Small Cap Value Report (Fri 26 July 2024) - JUP, STEM

Good morning from Paul, and with Graham making a Friday guest appearance too, thanks Graham!
(placeholder is up early because I'll be travelling early in the morning, disrupting my usual routine here a little)
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia.
Companies Reporting
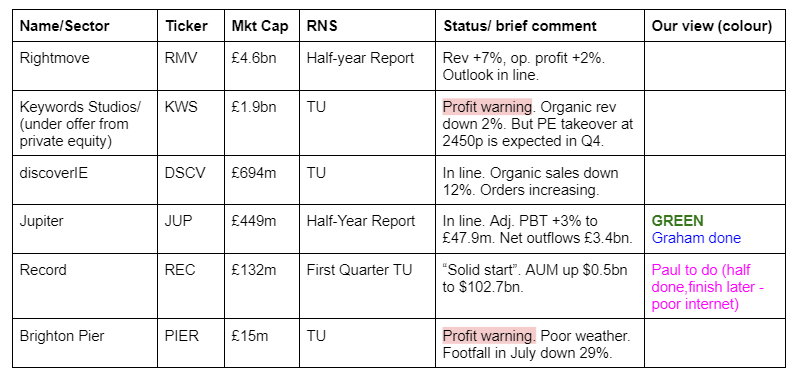
SThree (LON:STEM) - Notes from Graham's management meeting this week are available in a section below.
Summaries
Jupiter Fund Management (LON:JUP) - up 9% to 89.8p (£489m) - Half-Year Report - Graham - GREEN
H1 results are “in line with or, in some cases, ahead of our expectations”. Revenue declined, but cost control and higher interest income helped generate an improvement in PBT. I think management has achieved a lot over the past year, and this remains one of my favourite “value” financial stocks.
Jupiter Fund Management (LON:JUP)
Up 9% to 89.8p (£489m) - Half-Year Report - Graham - GREEN
A solid first half with reasons for cautious optimism
We last covered this stock in April, for the Q1 update, when I kept my positive stance on it.
Here are the key bullet points from today’s half-year report.
The financial results are “in line with or, in some cases, ahead of our expectations”.
AuM £51.3bn (June 2024), down slightly from £52.2bn (Dec 2023).
Net outflows £3.4bn.
H1 net revenue £173.7m (H1 last year: £181m)
H1 PBT £38.7m (H1 last year: £34.8m)
The last line sticks out to me: despite falling revenues, Jupiter has nevertheless posted an increase in pre-tax profits.
Jupiter’s CEO (appointed in late 2022) was one of the catalysts that I hoped would lead to positive change here. So far, so good. Here are some of his comments on the half-year results:
"Jupiter delivered a solid financial performance during the first half of the year… Our underlying profit before tax increased by 3%, supported by a continuous focus on cost management which saw total operating costs continue to fall. I believe we have a business and a structure which positions us well for success given our work to date to right-size our business, invest in strategic growth drivers, and bring in highly regarded investment talent.
There are reasons to be cautiously optimistic. Our underlying outflows were small at just £0.2bn and we saw an increase in gross flows to £7.5bn…
As we look forward, like other market participants, we are beginning to see early signs of client sentiment shifting more favourably in the UK…
Flows: the company is eager to point out that “underlying” net outflows were only £0.2bn, if you look past two major sources of outflows. One of these involves Jupiter staff leaving to set up their own fund management company. The other saw the management of an investment trust changing hands.
While I agree that these events are one-off and lumpy in nature, the staff departures are arguably a symptom of Jupiter’s overall malaise.So I wouldn’t be too quick to treat the £0.2bn outflow figure for H1 as being representative of Jupiter’s “real” net outflow.
I also think it’s worth pointing out that the trend isn’t currently positive. Underlying inflows in Q1 were followed by underlying outflows in Q2. But it wouldn’t require a huge change in sentiment for this to turn positive again (I think underlying outflows were £0.5 billion in Q2).
Cost control: administrative expenses reduced by £3m to £129m. Staff compensation increased but other costs decreased. And in another example of positive change from CEO Matthew Beesley, I see that the total number of Jupiter funds is going to reduce further by the end of the year.
Interest income: another boost to profits came from finance income, which shot up from £1m to £4m.
Exceptional items: reduced from £12m to £9m. The only exceptional item is the amortisation of an acquisition. The results are clean.
Graham’s view
Perhaps I got too positive on this one, too early (I’ve been positive on it for nearly two years). But I’m glad I’ve stuck with it recently, as management’s cost-cutting and simplification plans are bearing fruit.
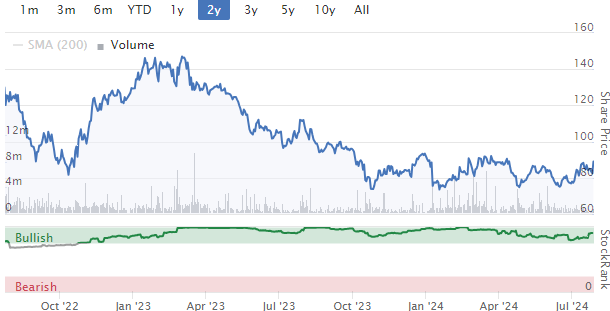
Quantitatively it’s a dream stock, except for the lack of share price momentum:
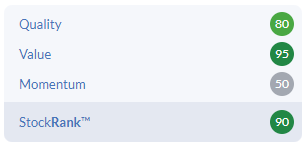
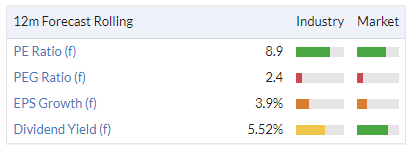
It’s trading at a high single-digit earnings multiple, offering a good yield:
Investors currently get £105 of AuM per £1m invested in Jupiter stock (based on June 2024 AuM).
That’s not quite as depressed as it was in April (£120) but still very cheap compared to some of Jupiter’s peers and of course compared to historic levels.
Times have changed, and maybe the historic valuations given to active fund managers will never be seen again? After all, there is ongoing downward pressure on fee margins, and Jupiter can’t escape that (it will earn c. 66 basis points on AuM this year, vs. 70 basis points last year).
But I think companies such as these, if they are managed well, should still be able to pump out decent numbers and cash flow for their investors, for some time yet. Perhaps this is the financial equivalent of a tobacco stock?
SThree (LON:STEM)
410.5p (£554m) - Management Meeting - Graham - GREEN
I had the chance to speak with Timo Lehne, CEO and Andy Beach, CFO of the science-focused recruiter SThree, earlier this week.
We covered their interim results in this report on Tuesday.
With so many company announcements being made in the last few days, I didn’t get a chance to type up my notes for you. So here they are now.
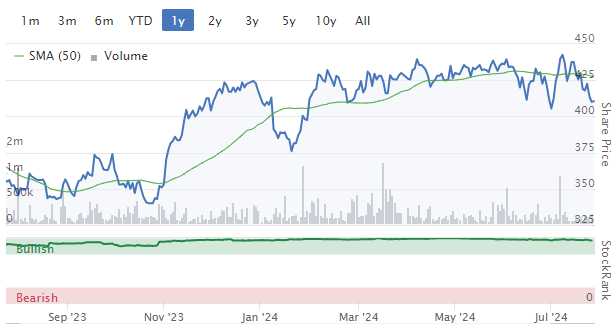
1-year chart:
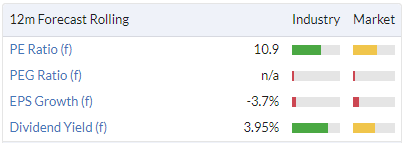
Value metrics:
Q1. How do developments in AI impact hiring currently?
A. There are a lot of conversations around AI. In the short-term, its impact may be overestimated. In the long-term, it may be underestimated. Many tech jobs make a reference to AI but they are not “real” AI roles, they just interact with AI in some way.
Q2. SThree’s net fees have declined 7% like-for-like, but the economies in which SThree operates (such as Germany, Netherlands, USA) are not particularly weak right now. What explains the disconnect between strong economies and weak net fees?
A. This is the most extreme disconnect we have seen in recent years between the economy and net fee growth. It’s the first time we’ve had both low unemployment and soft staffing. We think the reason is uncertainty about the future: companies may have been cautious about investing with several major elections coming up this year. Companies may also have been concerned about how the Ukraine conflict would impact them. Inflation has also been a problem. However, in countries such as Germany, Netherlands, UK and Japan, SThree’s decline in net fees has been softer than its peers. In the US, SThree’s decline in net fees was second-best, for the reason that SThree’s US business is more focused on Life Sciences.
Q3. Life Sciences has been declining ever since Covid. How important is this category to the future of SThree now that it’s a smaller percentage of net fees (17%) and why is it still declining several years after the Covid boom?
A. Life Sciences is still a sector that we back, it’s still very important to us. It has now returned to a level that is similar to where it was pre-Covid, so this is a normalisation after the boom. SThree is ready for it to rebound whenever it picks up again. Watch out for new activity from US pharmaceutical companies..
Q4. Has recent weakness in demand been purely corporate-driven, or is it also a factor that candidates have been reluctant to change jobs?
A. SThree’s focus on Contract recruitment means that this is not really a factor. But candidates are still willing to change jobs, SThree has not seen any change.
Q5. With the growth in net cash (£90m), is there a point at which the company has too much cash and is SThree approaching that point where it needs to reduce the cash balance?
A. While the company has a large cash balance, much of it is needed for business as usual. £15-20m is needed to fund growth in contractors. In total, the company needs about £60m for business as usual and to fund its growth. The company’s cash needs tend to be countercyclical. But yes, the company does consider what it might do with its excess cash. When the Technology Improvement Programme is completed, that could be a good time to look at M&A as acquired companies would benefit from the efficiencies delivered by that programme. The Board also considers the potential for a return of capital, either in the form of a buyback or special dividend.
Q6. SThree has an average market share of 3% (from 0.1% to 6%) across its regions and has suggested that it can increase market share. But the recruitment sector tends to be very fragmented. Is it realistic to grow market share and what is a realistic objective?
A. Absolutely, SThree can grow market share. We have plans with targets for 2029/2030 that we will discuss soon. And we do think we are undervalued. SThree is a uniquely positioned house of brands, offering flexible talent to employers, and with an automated back office and invoicing system in an outdated, analog industry.
Graham’s view - I appreciated the chance to speak with management here, and I hope that my notes do justice to the conversation. It certainly helped to improve my understanding of my favourite recruitment stock. I should try to cover the sector a little more frequently, so that we can compare and contrast SThree versus its listed peers.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

49 comments
https://news.sky.com/story/bui...
This doesn’t look good for SIG (LON:SHI) Rumour of an equity raise and we all know that sky news always seems to get these stories right.
As it is the weekend I thought I would share one of my silly musings. Whenever I see a stock rated above as Graham - Green(e) I start to wonder if it might be a (Brighton) Rock solid investment?!
Groannnnnnnnn Sparkler ! You’re not one of The Comedians he wrote about in 1966?
I'm possibly the contrarian on Cavendish Financial (LON:CAV) but for me there are 4 re-rating drivers for the shares in the next 6-12 months, so I'm banking on not just the increase in deal/M&A/IPO volumes. So my buying thesis is that I don't need the IPO market to improve, just one of the four drivers to come true, and some of them are much more certain than the IPO volume pick-up possibility.
(I hold in the Boon Fund)
Hi Boon
Cavendish Financial (LON:CAV)
Personal opinion , but when the dividends paid out to shareholders are not even close to the bonuses paid to all employees (especially on a year of losses) then there is no investment case. I believe this is a company for the board and the employees. I cannot see this being a £100m+ market cap company as originally thought and after going through the results.
The day of the results contributor laurie expressed his opinion on the enormous bonuses as well.
I hope I am wrong and good luck to all shareholders.
All the best
Its true that bonuses at Cavendish Financial (LON:CAV) are more than dividends.
But this will be true of all similar firms to Cavendish. Peel Hunt, Numis (when they were still listed), Finncap and Cenkos before the merger.
Also to many financial services companies. I can think of investment banks, fund managers, etc.
If what you say is true, that all companies that pay more bonuses than dividends are lousy investments...
How can it be that many of them exist as companies, year after year, maybe decades?
And are you saying that in all the time that Finncap, Cenkos, Peel Hunt, Numis, etc have been listed.... that it has not been possible to make money by being a shareholder?
I can see why you might have this as one of your core investing principles. Especially when it comes to non-financial / normal-economy companies. But in the financial services space, big bonuses are a part of the compensation structure. We can debate whether it is bad or not, but it has not been ruinous to many financial services companies.
Therefore, perhaps there is an exception to the rule?
I have been refreshing my portfolio and had some cash to invest. It really does feel like small caps might be on the up. Many quality companies breaking out from base.
Ed has demonstrated that buying high SR companies increases the chances of making a good return, as does buying super stocks. Therefore, I did a very simple search for companies between £50m and £1b with a stock rank over 90 and a style of SuperStock. In my case I excluded financials.
The result was a screen of 37 excellent small cap companies. So simple.
Personally. I then like to look for companies that have recently retested a breakout from a significant base or are retesting significant resistance.
The result is that I’ve just opened positions in Character (LON:CCT) IG Design (LON:IGR) & Smiths News (LON:SNWS)
Note, I am currently sitting on a terrace in sunny La Gomera so it may be that the feel good factor has got the better of me but I’m getting very positive small cap vibes today.
Lucky you Revs8, thanks for the interesting post. Off topic but my wife and I know La Gomera quite well, we stayed there to watch the Yorkshire Rows housewives set off on their successful Talisker Whiskey Atlantic Challenge, we knew one of them and that was some challenge.
Amazing challenge. I believe La Gomera is a popular trans Atlantic starting point. Even Christopher Columbus set off from here! It’s a very lovely place for year round warm weather.
There is a feeling that UK small caps may have reached an inflection point, no doubt helped by the prospects of a rate cut, both here and in the USA and Europe. I would like to think that this is the case after more than two awful years for UK stocks and in particular small caps.
Here's hoping!
small caps ar inflection point
It is not only Small Caps that are making the headlines, Big boys are entering the ring too. Lloyds and the rest of the banking sectors are riding high and are at an inflection point too.
I should add that I’ve just checked out Character (LON:CCT) IG Design (LON:IGR) andSmiths News (LON:SNWS) on Paul’s summary sheet and they are all green.
Just published the Creightons (LON:CRL) full year 2024 results presentation given on Wednesday 24th July 2024. The reinstated dividend has inspired confidence. Here, they give details of the year gone and their strategy video & podcast.
Given the amount of column inches given over to Jupiter Fund Management (LON:JUP) what does the community think of MAN Group Man (LON:EMG) who released their HY results today in terms of their AUM and their flows in or out. Before buying some a few weeks ago I noted from some report or other (probably ED) on Polar Capital Holdings (LON:POLR) that only Man (LON:EMG) had better inflows than Polar and that the two were first and second in the rankings. I think todays report consolidates that view.
I hold both MAN , Polar and Jupiter
I like Man (LON:EMG) and I hold. I will admit that it is an area where I don’t have as much analytical confidence as some others but the performance here seems more than just sound and I am a little surprised that is has not attracted much attention. The earnings are sharply up , as you note there is a good rise in AUM and the p/e at 8 and a yield at 5.77% leaves very little more to desire. Major institutional shareholders have around 20% of the company and I would imagine they would have it on a buy list
Man (LON:EMG) is outside the market cap limited for the SCVR but it looks interesting on an initial glance. Thanks for flagging. I'm interested in why the share price is relatively high now versus historically whereas other fund managers are currently trading lower than historic performance.
Can't find that comment about better inflows. It may have been Graham?
Does that include Tatton Asset Management (LON:TAM) ? Their AuM was up 27%, in April, 2024?
I hold Tatton Asset Management (LON:TAM) and Polar Capital Holdings (LON:POLR)
Not looked at Man (LON:EMG) before.
Brighton Pier (LON:PIER) are now charging a quid just to walk on Brighton Pier from this May (i read too annual passes are £95 a pop - that's a lot of walking on the pier, although i think you do some rides thrown in), nevermind to do any of the activities and for the food.Doesn't seem much but is almost an extra fiver for a family of 4 down for the day and i'd think some people just like to go on and have a look before considering buying any of the overpriced food or arcades.Perhaps a good sign of the profit warning to come, if you were interested in the shares.Although admittedly it must need a fair whack of maintenance as unfortunately the other burnt down pier has just been left as is.
I had a quick rummage through Brighton Pier (LON:PIER) - and wonder if they might be very close (or on course) to breach bank covenants on their loans, given the profit warning.
Their FY results did state that they could survive a -45% lower EBITDA for FY Dec24, compared to management expectations, before covenants were breached. But management expectations are not provided.
Given the high fixed cost nature of the Brighton Pier business... I'd hazard a guess that even a modest fall in revenues would have outsized impact on the EBITDA.
Surprised it only fell -15% on Friday, given this increased covenant breach risk!
Graham, thanks for writing up your interview with SThree (LON:STEM. I think you asked some very poignant questions. Where I would have probed further - and I blame myself for not priming you with the question - would be on the trend for gross margins on new business and extensions. Typically in a downturn this gets pressured and, the longer and more often individual assignments are extended, the more margin tends to be sacrificed. The answer would have pointed to the current state of the tension between rare skills and employer demand, which I assume to be a more balanced currently, as well as giving clues about future profits as new agreements and extensions replace old.
Management at STEM love to make completely unfounded claims about their “unique” qualities, when they are just a bigger version of more profitable specialist boutiques up and down the land. Most of whom scoff at STEM’s offering. The reason they have a small presence in the UK is because they got chased out by superior competitors. Clearly they are better ingrained in DACH. Nevertheless, the new, automated back office system is interesting. I owned a specialist boutique, turnover £50m and I wrote a back office system to handle all contract administration and contractor payment needs. When I sold the business to a global (formerly listed) firm, I was shocked to find an entire building full of clerks and bookkeepers performing what my simple database application and one operator could handle, albeit on a larger scale. The inefficiency was gob-smacking! If STEM’s new back office works as well as they hope this will be a nice boost to operating margins and make M&A more earnings accretive.
On the topic of growing the market share, they will not achieve it organically. As you said yourself, the market is too fragmented and top consultants always depart to set up in competition, limiting growth. But an acquisition-led approach becomes more viable with a state of the art back office. That is only in accounting terms, however. Recruitment M&A is difficult because the purchase of an established brand is often the trigger for that brand’s superstars to seek to make it on their own. STEM’s reputation is not stellar within the industry and I can imagine that, if I had sold to them, there would have been immediate collateral damage. Indeed, having sold to a business with a better cultural fit, still half of the big hitters were gone within 3 years. Inorganic growth will be challenging.
However, unless market dominance is your aim, that is not necessarily a problem when the industries you supply see wages rising by nearly 10% every year and you have the option of migrating focus into the high growth areas as they emerge.
For all that this is a slightly critical analysis, STEM is my third largest UK holding, simply because I understand the business and market very well. And remain a firm believer in the structural drivers of the company’s success.
I am a holder of Sthree (stem). between you and Graham , you have produced something helpful and valuable. This Bulletin Board (hope I've used the right words!) at its best
Good article Graham but my comment is " If it is perhaps we should give up smoking "!*
Very funny John!
James Latham (LON:LTHM) - Don't want to temp fate but this has been steadily recovering for a while now - is there anything we should be aware of going on... (I hold)
James Latham (LON:LTHM) think it is just a general rise in the building supply sector, due to Labour's building plans. I hold. Others such as Alumasc (LON:ALU) and Eurocell (LON:ECEL) have had similar gains recently.
Some positive news on Cavendish Financial (LON:CAV): https://news.sky.com/story/min...
Has anyone worked out what a 'rough ballpark' is for the % fees the likes of Cavendish Financial (LON:CAV) make on IPOs?
This IPO might be relatively small but it's also a further sign that the IPO market is starting to get going again.
IPO advisory fees are disclosed in the prospectus so you can work it out exactly on each IPO.
Thanks Brookside. I was wondering if someone had worked out an average percentage to use as a ballpark template for future contracts. Maybe I'll have a go at some point!
I seem to remember that Yiannos holds Cavendish Financial (LON:CAV). I imagine he will have studied the numbers in great depth. He may be able to help.
Hi Ben
Exited my Cavendish Financial (LON:CAV) position on the day/next day the results were out. I have posted it on the day and the reasons behind it.
All the best
Benhazz
I sold half of my Cavendish Financial (LON:CAV) holding on the day of their underwhelming Results, hoping that the share price would drop more than it has so far, to give chance to buy that dip.
I’m looking to buy again on clear signs that the current better sentiment towards UK small company shares leads to Cavendish Financial (LON:CAV) winning a lot of new business via IPO’s, fund raisings etc. fwiw I think there’s big share price upside potential if that happens. Good chance that it will?
Centaue and share options
Not sure share options are meant to work like this .
Managenent crustallise 800k of share options in the LTIP
Then immediateky are “forced” by tax rules to sell 350k of those to cover their tax lisbility .
I guess given the price drop this week they took the opportunity to crystslise their options at a very low price, thereby locking in the tax liability .
Just a bit of a by product of an LTIP is 350k shares hitting the market In a relative thin market is a bit more downward pressure for a day or so .
All in all I take it as positivish though im no fan of options with s zero value strike price as open to such abuse in pocket filling mindest management which we occasionaly come across .
planetx
Not sure share options are meant to work like this .
Managenent crustallise 800k of share options in the LTIP
Then immediateky are “forced” by tax rules to sell 350k of those to cover their tax lisbility .
the answer here is a simple yes - its almost a standard that where someone is granted shares that a fixed % is sold immediately so that funds are crystalised - for salaried employees this is often even dealt with in the payslips so that the empoyee might not need to do anything - the are taxed on value of shares granted and then enough are sold so that that tax is settled.
Note by doing it immediately it normally avoids/limits any capital gains complications that would be present be selling ata later date.
If soemone woes 100k tax on receiving 200k of shares should we expect they have 100k saved up - the naswer is no.
Just a bit of a by product of an LTIP is 350k shares hitting the market In a relative thin market is a bit more downward pressure for a day or so
Thats just the collatoral damage that cant be avoided - do opportunities like this not provide good opportunities perhaps to nible investors like us?
I suspect there quite a few canny investors who for example have topped up on card factory in the 90's recently due to external selling and they may have made a quick 15-20%.
External selling like card factory by a current shareholder is different but agree both throw up opportunity albeit one is market force driven and the other is not .
Anyway if it throws up opportunty for the nimble them lets take advantage and i had a good old nibble yesterday .
Nimble is too flattering in my case planetx but your initial post got me researching, we've nibbled too.
Taylor Maritime Investments (LON:TMIP) good q1 statement lovely quarter dividends and will have 100% control of its other shipping investment so cost savings to be made.
Morning Paul,
Acquisition by Knights group (LON:KGH) , on a debt free ,cash basis. Looks a decent deal to my untrained eye?
Regards
Has Jupiter Fund Management (LON:JUP) quietly halved its dividend (3.2p vs 6.3p)?
Hi Doctor Dave, Jupiter Fund Management (LON:JUP) have a RNS of their half year results out and in it there is the following line " In line with our capital allocation policy, we announce an ordinary dividend of 3.2p per share"
Jupiter Fund Management (LON:JUP)
They changed their dividend allocation policy in October 22 so it's not progressive any more but is based on eps. Given their relatively poor performance that equates to a cut, but means they're not paying out cash they can't afford.
I hold.
timarr
Jupiter Fund Management (LON:JUP)
Another way of looking at this is there is a sizable beat versus forecast as far as I can see:-
EPS forecast (per stock report) 9.97p - at 6 months 6.6p.
Dividend forecast (per stock report ) 4.95p - at 6 months 3.2p.
A.
(I hold)
re: Jupiter Fund Management (LON:JUP)
thanks for clarifying this timarr, I didn't go into the dividend in detail in my article but yes there is a dividend cut vs. prior years. Still not a bad yield and the consensus number for the year on the StockReport (4.95p) looks very low compared to what is possible.
Generally an active asset manager will trade at between 2 & 3% of AUM in a takeover situation - so in this instance Jupiter Fund Management (LON:JUP) between 2 & 3 times the current market cap. There does seem to be a lot of value on offer even if AuM stays the same - it should be highly operationally geared for any inflows.
Jupiter Fund Management (LON:JUP) feels like a bit of a mixed bag update this morning although I think the share price has gone up reflecting costs being lower and profits maybe a bit better than we expected? The commentary does sound like there is a good chance of a beat at year end.
What I am less happy about is the continued outflows especially the £2.4bn from strategies managed by the value desk. Does anyone know what the total AuM of the 'value desk' is? I am assuming, but not sure, this is all related to the funds managed by Ben Whitmore who is leaving and at the start of FY24 he managed c.£10bn so this is quite a significant withdrawal if that's the case. Would welcome Graham's views on the value funds situation especially!
Of course if they can actually stop net outflows then this share should be decent!
I think it says that the value team now manage £6.3bn
re: Jupiter Fund Management (LON:JUP)
Tortoise, I presume you've done this, but check the numbers Jupiter gives for underlying flows. They say that excluding the Value desk and Chrysalis, net outflows in H1 were negative £0.2 billion. I believe they are putting all Ben Whitmore-related flows into the non-underlying category. But of course they will not want to name Mr. Whitmore in their report! Just my two cents. G
Thanks Graham and thanks for your write-up. I agree by value they probably mean the Ben Whitmore related funds.
£2.4bn out of what was £10bn* at the start of the year is a big chunk to lose. It was inevitable they would get some outflows with a star manager leaving but given he hasn't even left yet this feels like it's going badly so far. I don't think this necessarily changes the investment case and it is good they are trading in line with (and above some) expectations, but it does demonstrate Jupiter Fund Management (LON:JUP) is still dealing with significant changes. I will be happier when "underlying" flows became positive!
*At the start of the year they said: 'Ben Whitmore, the current manager of the Jupiter UK Special Situations Fund (AUM £2.1bn), Jupiter Income Trust (AUM £1.6bn), Jupiter Global Value Unit Trust (AUM £1.0bn) and Jupiter Global Value
SICAV (AUM £0.5bn), and segregated mandates with a further £4.8bn of AUM...'
Eenergy (LON:EAAS) - "Activity building after period of strategic change" - link to new research note: https://www.equitydevelopment....
eEnergy’s H1 update confirms that trading remains in line with expectations with momentum building at the start H2’24.
As previously reported, H1 started slowly as a result of weak market conditions and balance sheet constraints, which were resolved by the sale of the Energy Management (EM) division in Q1. Encouragingly, market conditions have improved and full year revenue guidance has been maintained at £25-26m. We make no changes to our underlying forecasts or fair value of 13p/ share.
In our view, recent months have been transformative for eEnergy, positioning the Group to capture the significant market opportunity that exists across Solar and LED lighting, in particular.
eEnergy now has the balance sheet strength to tender for much larger contracts, which we expect to drive long term growth. Trading is encouraging at the start of H2, and the Group continues to invest in the executive team with Nick Clark recently joining in the new role of Chief Operating Officer.
First comment!