Small Cap Value Report (Fri 27 Oct 2023) - RWI, FA., SFE, KETL, XPP

Good morning from Paul!
I'm pushed for time today, as I have to drive from Bournemouth to Brighton this afternoon for a (not dirty) weekend away - I'm doing more UK mini-breaks with mother, brother, nieces & nephews, etc, in AirBnB's. Doesn't look like we'll be basking in the sun on Brighton Pier (LON:PIER) - more likely trying to avoid being swept overboard in gale-force winds! I'll also attempt to record the weekend podcast early too, so let's crack on!
This weekend's podcast has landed early! Here's the web link. It's also available on the main podcast services. A more positive tone this week, and some comments about market doldrums & keeping your pecker up!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Summaries
Renewi (LON:RWI) - down 18% to 540p y’day (£434m) - No takeover bid - Paul - AMBER
Investment giant Macquarie had previously (28 Sept) announced that it was minded to offer 775p for this waste recycling group, but that management had rejected its approach. It updated yesterday that, due to continuing rejections from Renewi management it won't now be bidding for the company. The share price has now fallen to 30% below Macquarie's indicated price, so management have some explaining to do, as to why they rebuffed what struck me as a fair deal that would have allowed shareholders to exit with a decent premium.
Fireangel Safety Technology (LON:FA.) - Recommended takeover bid at 7.4p
What a turn up for the books here! Shareholders are bailed out by a trade buyer from Singapore (already holding 17.5%) which has announced a 7.4p cash takeover offer, recommended by management. This is a cracking premium of 252%, which I imagine shareholders will gratefully accept, since this serial under-performer and diluter looked to be heading towards zero. Bear in mind it peaked at c.300p in 2015.
Safestyle UK (LON:SFE) - suspended.
Another serial under-performer that looked to be heading to zero. No white knight has been found here, not even Pat Butcher's mob are interested in the equity! Shares are now suspended, and it confirms this morning that there's unlikely to be any return for shareholders. That's that then.
Strix (LON:KETL) - down 3% to 57p (£121m) - Corporate Update - Paul - RED
CFO sudden departure concerns me. I review the other points that concern me - excessive bank debt, covenant relaxation required, awful balance sheet with negative NTAV, lots of cash wasted on dubious acquisitions and capex, and a close connection with China. Good luck to holders, but it's definitely not one I would want to go near.
XP Power (LON:XPP) - up 9% to 1094p (£216m) - Q3 Trading Update - Paul - RED
Market is relieved at some signs of things stabilising/improving at this troubled company. It's taking self-help measures to tackle excessive debt, but talks with the bank on covenants have not yet been finalised. Sounds like there's a hint about a possible placing too? So I'm steering clear until the finances have been repaired.
Paul’s Section:
Renewi (LON:RWI)
Down 18% to 540p y’day (£434m) - No takeover bid - Paul - AMBER
Renewi plc (LSE: RWI), the leading international waste-to-product company…
Investment giant Macquarie announced on 28 Sept 2023 that it had proposed a cash takeover at 775p to Renewi, but Renewi management rejected this approach as undervaluing the company.
It seems that Renewi management have continued to rebuff Macquarie’s approaches, so they announced yesterday that they’re not now intending to bid for Renewi, causing an 18% drop in share price. It sounds like they might have been prepared to pay more than 775p too -
Macquarie confirms that, following multiple attempts to engage with Renewi's Board, including a revised proposal, all of which were rejected, it does not feel it is in an informed position to make an offer for Renewi.
So here we are with the share price now back down to 540p, or 30% below the price Macquarie initially indicated.
Paul’s opinion - I thought 775p was a good offer for Renewi - a highly indebted company with rather patchy performance, and very low margins.
Maybe shareholders need to quiz management about what they plan to do, to create equivalent or better shareholder value, since the share price is now a long way below the proposed offer.
We were discussing in the reader comments yesterday, as to what approach to take when shares shoot up on a takeover approach. I sometimes like selling half immediately, to hedge my bets. That’s particularly the case when it’s not actually an agreed bid (as in this case), just a suitor wanting to bid, which has been rebuffed by RWI management.
Do we have any RWI holders in the house? If so, what’s your view? Did you bank any profits after the 28 Sept announcement of the bid approach? Are you happy for the company to remain independent, or annoyed that management rejected the bid premium?
I wonder if bid approach(es) might resurface? It’s an unusual business, there’s nothing on the UK market similar to Renewi that I’ve seen anyway. And a previous waste recycling company, Augean, was taken out by a bidder, so this type of company does seem attractive to buyers.
Strix (LON:KETL)
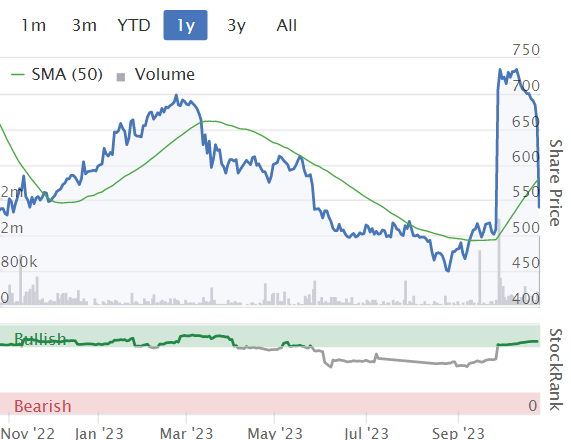
Down 3% to 57p (£121m) - Corporate Update - Paul - RED
Strix Group Plc (AIM:KETL), the AIM quoted global leader in the design, manufacture and supply of kettle safety controls and other complementary water temperature management components, announces a corporate update covering the planned CFO retirement and leverage ratio covenant relaxation.
This is odd. It says above that the CFO’s retirement is “planned”. Then it says this contradictory phrase -
Strix announces that after over twelve years with the business, Raudres Wong, Chief Financial Officer ("CFO") has advised the Board of her intention to retire as CFO, effective immediately.
If it was planned, then surely she would have previously advised of her intention to retire? I’ve done a quick search of the last few RNSs, and I cannot find any reference to the CFO planning to retire. Can I ask if any shareholders here were aware that the CFO was intending to retire, and whether this had been previously announced, as I might have missed it? So far (at 08:26) only a 3% drop in share price suggests this has not caused a panic amongst shareholders.
A NED has taken over as CFO temporarily whilst they look for a replacement. Again, not something that happens when a departure is planned - when it’s done the other way around - the replacement is found, then the incumbent does a handover period, then retires.
Why does this matter? I don’t like an abrupt departure of a CFO, because it can be a sign that something’s wrong (or Wong, in this case!)
She is thanked, and provides her own pleasant quote, wishing the company well.
Debt covenant - is relaxed, for Sept 2023, which seems strange as that’s retrospective. It does however reinforce what we already knew - that Strix has taken on too much bank debt (used to fund divis, heavy capex, and dubious acquisitions) . It confirms again today that debt reduction is a priority. Yet it’s still paying (reduced) divis. I think divis should be stopped altogether (and usually are), at any company which is struggling with excessive debt. I’m surprised the bank let it pay divis at all, considering a covenant relaxation was necessary. The H1 divi is 0.9p, down from 2.75p LY H1.
Paul’s opinion - I don’t like this share. I’ve raised concerns about its accounts in the past, and generally I avoid anything with close connections to China, due to the terrible history of China stocks on AIM back in c.2015 (almost all of them turned out to be frauds). Remember Camkids, and Naibu (whose Directors disappeared). There’s still stuff about Chinese frauds in our archive here. I put a blanket view of “I wouldn’t buy any of them” in my reports here, which turned out to be a very good move! The discounts to net cash, and super-low PERs did suck in some investors though, but the trouble was that none of the figures were real! There’s a fascinating article I wrote here in Feb 2014 about Chinese frauds, and also interesting that back then we were worrying a lot about the Chinese real estate boom bursting, which is a similar concern to the present day.
I’m not saying Strix is necessarily fraudulent. It passes two of my “probably genuine” rules, (1) it’s been listed for a long time, since Aug 2017, and (2) it’s paid decent divis over the years. I just don’t like a lot of exposure to China.
Also my concerns over its accounts are that there doesn’t seem much genuine cashflow, once finance costs and capitalised development spend are taken into account.
The balance sheet is heavily negative NTAV, with way too much debt.
Overall then, why would I want to get involved, when I can take my pick for higher quality, more soundly financed companies on cheap ratings? We’re spoiled for choice at the moment, so we don’t have to guess, or take any unnecessary risks at all.
Strix ran up the debt making a series of peculiar acquisitions, and heavy capex, which I don’t think have added value.
If I’m not 100% happy with the accounts, then I decline to invest, which is my view here. Good luck to holders, let’s hope it works out for you.
Looking back at our previous notes, I’ve viewed it as RED (due to high debt, and the accounts), whereas Graham is more lenient at AMBER, so it depends who is writing the report on the day.
I’m going to stick with my RED view, mainly due to the excessive bank debt, signs of stress with a covenant relaxation being required, that big divis are now a thing of the past, and that I think management have wasted a lot of cash on acquisitions and capex, funded by debt. So it’s definitely not for me. What looks like an abrupt CFO departure today, is another reason to steer clear for me. Obviously I’m happy to correct that if it transpires that the company had previously mentioned the CFO departure.
XP Power (LON:XPP)
Up 9% to 1094p (£216m) - Q3 Trading Update - Paul - RED
XP Power, one of the world's leading developers and manufacturers of critical power control components to the electronics industry, is today issuing a trading update covering the third quarter, and October to date, as well as detailing the significant actions being undertaken to reduce costs and preserve cash.
This previously looked a really good company, but it took on too much debt (which we warned about in Jan 2023), and got embroiled in an expensive $40m legal case.
The bigger bombshell happened on 2 Oct 2023, when it warned on profit, and flagged a potential bank covenant breach, causing shares to collapse from c.2400p to below 800p at one point.
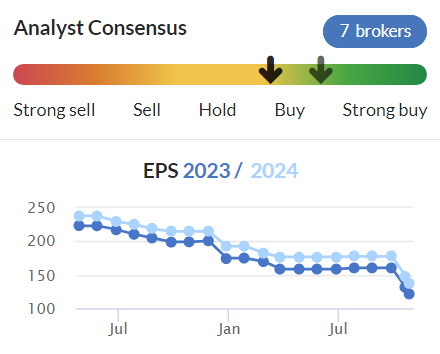
There’s been a modest recovery in recent weeks, and as you can see, the market has reacted positively to its Q3 update today.
It sounds as if trading has at least stabilised -
Revenue in the third quarter was £75.1m (2022: £79.4m) with operating profit slightly ahead of our prior expectation due to a better outturn in September. Trading in October has been at least in line with our expectation. Our full year expectations are unchanged.
Although this is the context for today’s in line update -
Other points -
Cost reduction & cash preservation measures taken, £8010m benefit for FY 12/2024.
Inventories being reduced by £10-20m over the next 2 years, to free up more cash.
Other measures to preserve cash, such as no divis, minimum capex, etc.
Bank talks ongoing, and are they hinting at a placing here I wonder? -
The Group is also in advanced and constructive discussions with its lending banks regarding future covenant requirements and other near-term actions to strengthen the balance sheet. These discussions are proceeding as planned and we will provide a further update shortly.
Paul’s opinion - it’s had a nice bounce from the recent disastrous lows, but it’s clear that XPP is not out of the woods yet. So personally, I won’t be investing due to the risk of dilution in a discounted placing perhaps. Given the ongoing financial risk, it has to remain at RED for the time being. Once funding talks are resolved, and the position is clearer, then I’m happy to look at it again with fresh eyes. The purpose of our RED view is to flag up risk. You can make your own minds up whether you are happy or not to take that risk.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

86 comments
I hold Renewi (LON:RWI) and didn't sell because I expected a second bid. The bid came but management rejected that too, so they really have their work cut out to show they were right .....
Normally I sell straight away as I did with SCS (LON:SCS). Greed got the better of me with Renewi (LON:RWI).
TU for Zotefoams (LON:ZTF) due out w/c 6 Nov. CFO says if there had been any material change from August update they would have informed the market. Like you I wonder at the continuing price erosion and hope I'm right to keep holding. Just part of the general malaise and people getting spooked? Tis Halloween after all!
Thanks for the date, my response to the CEO would be, is a 30% lower SP not a material change that you would want to reassure the market on. I hope you are right, I'll keep holding for sure but I'll be ready on 6th November just incase.
Bit late as was busy yesterday.But have a good weekend in Brighton Paul.A mate just moved down there last year up towards the outskirts almost overlooking Brighton FC and the south downs.Lovelier area than i thought.. as i had only visited Brighton in summer before when the beaches were packed with burnt 'tourists' and the town clogged up with foreign language students!!
Personally i'm just waiting for Powell to finally admit defeat re : the 'soft landing' thesis and say the big R word.Do i dare say that could be near the 'bottom' for the US market.. which irrespective of Bailey has to give us a little boost over here surely.....?Just perhaps!I'm hoping the US will then start seeing the end of the business cycle and be more willing to buy the 9/10 of the indices that aren't the previous 'Magnificient 7'.
'History seems to support the idea that a soft landing for the economy is
very challenging to pull off. Since the 1950s, each period of U.S.
disinflation driven by Fed policy tightening has coincided with a U.S.
recession, according to Deutsche Bank.'
Positives :
If the U.S. does slip into a recession sometime during what’s left of 2023 or in early 2024, there’s no reason for investors to panic.
First off, historically speaking, recessions don’t last very long . The average duration of a U.S. recession since World War II is just 11.1 months. The Covid-19 recession in early 2020 lasted just two months.'
https://www.forbes.com/advisor...
I'm no expert on the US markets, although do follow general commentary still and they definitely seem super jittery with even the big, global tech names selling off recently and don't seem to know what to do anymore!So some certainty could definitely help imo.
Argentex (LON:AGFX) I don't think it's been mentioned here, but are people aware that this is now the 2nd time Argentex have spooked the market in a rather bizarre way - both times with no real explanation!
The last time was back in 2021. Harry Adams was previously the joint ceo with Carl Jani - they were the 2 founding partners. I believe they both had a similar stake in the business. Carl Jani was off work for some time, due to covid according to the company. He then returned to work in May and by August he had left the company. Argentex said that Jani was retiring from work due to covid related health concerns. And if I remember correctly, there was a contractual agreement in place for Jani to sell Harry Adams his stake in the company.
This may not be that odd at face value. However Jani was I believe a young man, so retirement did seem rather odd especially without Jani ever speaking up about it. The even odder part was the agreement to sell his stake to Adams, which if I remember correctly was at a significant discount to the actual SP (perhaps between 10 - 20%). This created a strange overhang on the shares for a while.
It always bothered me, why would Jani sell his stake for under market value. And also if Argentex was as good as it seemed, why wouldn't he want to hold his stake as a silent partner. The situation seemed extremely odd, and only briefly glazed over and never properly explained. Now we have a similar departure concerning Adams, the whole thing just doesn't stack up. It may be that Argentex are just not very good at communicating with the market. I'm not saying there is something untoward going on, but it certainly doesn't feel like a comfortable hold imo.
hi MetalMaid
Argentex (LON:AGFX)
'The even odder part was the agreement to sell his stake to Adams'
I don't think Jani sold his shares to Harry Adams.
If I remember correctly they were sold via a bookbuild because of the heavy volume and hence the discounted price. This is fairly standard practice in such circumstances.
Snazzy
Ok thanks for that clarification. I would still wonder why he decided to sell his entire stake at under market value. It seems he wanted a very quick exit, but why? You would think that if he believed in the company he would have kept a silent stake. And why was this not explained properly to the market. And now we have a 2nd strange CEO departure - that's 2 CEO's gone in less than 3 years - both times without proper explanation - and Jani dumping his stake is alarming imo. You think its standard practice, I think its very odd. I have no conclusions, just thought it would be worth mentioning for those that were not aware of the recent history.
Argentex (LON:AGFX)
'You think its standard practice, I think its very odd'
I meant that a bookbuild sale would be fairly standard practice where a large stake needs to find buyers (and hence a discounted price as the process is effectively a quasi auction).
As for selling his entire holding, no that's not standard practice although more likely to happen where there has been a sudden departure and a falling out (as seemed the likely case at Argentex).
Snazzy
Yep sorry Snazzy, I meant the whole episode seemed rather odd, and not standard practice as to how it all transpired, and also how it was subsequently communicated.
I take on board what you are saying about the bookbuild sale, many thanks for clearing that up. And I am sure you are right that in such circumstances this is not unusual.
I remember thinking at the time that the stock price seemed very cheap. And here was Jani wanting out, and fast, and willing to eat a fairly large discounted price. It just made me question why he was not wanting to hold any position. Tbh, I kind of forgot about it all. But then yesterday its 2nd ceo departure in just over 2 years - and again no real explanation. I don't think anybody really knows what's going on with this company, because imo they never properly inform / communicate with the market.
Btw, just to add. I wouldn't find this that odd if it was a poor performing / struggling business. But for some time now, Argentex have been sitting on what appears to be a very strong balance sheet, with loads of cash. They have also been posting very good top line growth within a difficult economic backdrop. Not the circumstances you would usually see the founder ousted. Perhaps its just a boardroom coup. It will be really interesting to see how this all transpires. I for one will watch from the sides, as all the uncertainty makes it uninvestable for me for the time being.
Half of that cash is clients money.
Argentex (LON:AGFX) - Jani didn't sell all his shares to Harry Adams, just some of them. I seem to remember that management and Pacific / the Beckwith's also took them at c80p. It was a discount but Jani probably just wanted out. I got the feeling that he was the brains and Adams the salesman, but I might be wrong. The other oddity is the fact that LLP profits take a sizeable haircut every year, as the founders take a big chunk of the distribution. That should have been changed at IPO as it left a bad taste!
Yep 80p was what I remember. I think the stock was trading at around 95p - £1. Very good point about the LLP structure.
Reference the post by Ben Hazzard yesterday about Renold (LON:RNO) and the spread of over 6% I think the key point is that very early in the Trading Day eg 8.02am spreads are wider. On 20th October I sold 50,000 Shares in Renold at 12.18pm and the spread was 4%.
Recently I monitored the spread on Smiths News (LON:SNWS) over a 6 hour periodand it varied between 2.4p and 0.6p. You have to watch the Market Makers because they are very clever particularly on small caps.
Hi Portugull, interesting observation and not something I'd ever noticed actually. Market makers taking advantage of anyone who's desperate at the open sounds about right though!
Smaller Cap spreads will alter throughout the day depending on a number of factors. obviously news, demand, and market makers balancing their books amongst others . For example 8.00am spreads can be 7-8% and reduce to less than 1% during the day. Even then you don't know the exact spread until you try to trade, for the less experienced I would suggest you try some 'dummy' trades on stocks you hold to get an idea of the way things work. Unless I saw an opportunity for a quick trade I would never buy at the open, you are asking to have your trousers pulled down. For longer term trades this is not so important, but it is worth knowing how things work.
I’ve looked at Renewi (LON:RWI) a little. I stopped looking as I believe making a good sustainable economic return across its businesses could be v hard. For example recycling is very energy and labour intensive and that’s really just to extract a single element at a time….so for foreseeable future large scale ‘commercial’ recycling of metals etc is likely to require subsidies (explicit or implicit). I know they do many things but this is an issue I think they’ll run into in many business areas. Recycling (laudable etc) has good vibes but bad economics.
The thing to look at is the big energy to waste operators, the newest plans are very smart in terms of what can be done automated, with a few folks on back end conveyors only.
I went with the local school (parent helper) and it was a wow this is a seriously clever bit of German technology you have installed. They basically say put everything in your black bin, we can separate it better than you can with several bins.
Tommy
York and North Yorkshire (thalia.co.uk)
The good news is that Paul has already done his weekend podcast, so there is a silver lining in every pitch-black depressing cloud!
Hi All,
I know that SCVR doesn’t cover mining stocks but can anyone shed some light on Metals Exploration (LON:MTL)? MTL has an incredible Stock Rank of 100, Quality 93, QM 98 and QV 99. Their website is very informative - wonderful, but am I missing something? MTL has the same volatility as most sucker stocks. I have a very small holding and its sits in a folder called ‘Impulsive Punts’! I am keen to find out if this share deserves to treated with more respect. If so I might buy some more.
Many thanks
Metals Exploration (LON:MTL) is being promoted on a tip site. I don't do resources or mining so can't really help.
I'd want to know what the all-in-sustaining cost per ounce of gold is and the expected life of its mine. Is Metals Exploration pumping money towards finding new deposits, it doesn't pay a dividend so it must be doing something with profits. At least it has more than 7 employees, perhaps you might like to take a punt on it Pat and treat it as a learning curve on gold miners. You may think the share price is cheap right now but the 5-year performance doesn't agree. Politics often come into gold mining and may cast a shadow on it, I hold Anglo Asian Mining (LON:AAZ) which is looking a better propostion, but there's the politics.
Stock ranks don't work well on miners. Metals Exploration (LON:MTL) is nearing end of life, this makes it a fairly speculative proposition, and could do very well or very badly. DYOR strongly recommended.
Junior miiners on the London Market are the fastest way to burn money. You have to be a trader really.
Zotefoams (LON:ZTF) down a decent chunk today on no news, someone happy to ditch 82k worth at 268p. Last update on Aug 8th they closed at 375p, a 40% upside to that sell price today. For a decent quality company with manageable debt this seems an excessive decline, even in the current bear market. I'm tempted to add but with an update maybe overdue I'd hate to be on the end of another profit warning. PE down at 13 now with long term support levels around the 250p mark if it falls that low. Anyone have any bear case thoughts at this price?
The way this market is I'd wait for the TU and top up then if it's decent. It may cost you but that's insurance.
Buying now is risky. If trading has deteriorated along side increasing interest rates that debt wouldn't look as manageable. See XP Power (LON:XPP)
Edited to add XPP was mentioned to show what happens when debt gets out of control, I don't think there's as much risk of this with ZTF so it's not a straight comparison, more an extreme example.
When is the next TU expected anyone?
Last year it was 13th October. So a few weeks earlier. But no official date provided on their website. Thanks Doug - I think the debt looks very manageable based on previous data, but who knows moving forward, that's always the mystery. I'm going to hold tight for now but if it dips to 250p resistance line I'll be adding another 20-30% to my holding.
Going back to 21 the ZTF TU was into November though so hard to be confident on timing.
I think the debt is manageable too.....as long as trading and cash collection hold up.
The idea of paying more after reassuring newsflow is a sound one . . . . . if the contains unwelcome details you might also get to buy as it marks down (perhaps if the news didn't warrant the decline). I currently don't hold but conscious its not far off its 2022 lows and only lower than those once in the last 5 years for a month in March/April 2020
Returning to subject of SCS. I am in Belgium and we have made several purchases at PoltronySofa and are very satisfied customers. It does seem that SCS is a good fit for them to enter the UK market. I would be surprised if it does not go through.
Despite this, I sold my holding yesterday. After the gruelling last few weeks, it was nice to take a profit and in the knowledge that I would be extremely disappointed to be holding if the deal was to fall through. Short term gain at a likely small cost (small premium and dividend) against the risk (even if low) of extreme pain.
Of course if another bidder does emerge I shall be very annoyed but this is the price of operating in the market.
Yes, I had been planning to hold SCS to get the div, and the possibility of a better offer. Looking at Renewi's chart this morning made me reconsider! Not worth taking the risk. I'm still left with profits well above my current portfolia average.
I sold my holding in SCS (LON:SCS) today following a very similar rationale to BrusselsLad. In addition, I have a number of small and mid cap stocks on my watchlist, to add to or start positions in, that are at significant recent lows. Of course the market could continue to decline but I believe that there is probably a reasonable chance for a year end rally. After that who knows what 2024 will bring. I hold my individual shares in an ISA and use my DC pension to collectively create more of an all-weather style portfolio which has helped me, at least so far, to manage this protracted period of uncertainty .
Who knows, the share price of SCS (LON:SCS) may be over 300 pence in 2024, as they were 2 years ago. Especially if there is that mooted rising tide carrying all boats upward:-). A takeover would certainly kill the suspense so good luck to the entrepreneur. I hold.
Don’t despair even those holding much larger Mk caps Natwest (LON:NWG) are having a bad day/month, mentioned today as trending as the number one on the viewed list here, with plenty of great/ sage advice given here over the past weeks and just talking about the market you know you are not alone, I removed my initial fears, reviewed the figures and topped up first thing for the 10% divi. GL
There is a huge amount of gloom and despondency out there re stocks and it is great to see the mutual support being provided on this forum.
We can’t be far off ‘maximum pessimism’, if indeed we are not already there. Although I have lived through many market cycles, I was not actively involved in the stock market until relatively recently. Hence, I would be really interested to hear from ‘old hands’ here which are the sectors that will see the fastest share price appreciation once this market turns.
I concur and see the markets too irrationally low atm. Everything getting punished. Breadth indicators suggests so.
Instead of picking or topping up individual shares to add at this time, I've put some money into the FTSE250 etf. As I think we'll see a good recovery across the board. Vanguard FTSE 250 UCITS ETF GBP Dis (LON:VMIG) was my pick. Drip feeding in purchases, and will be getting close to 10% of my portfolio soon, and hopefully 15% or 20% end state
Hi Boon,
Would be good to Vanguard FTSE 250 UCITS ETF GBP Dis (LON:VMID recover! I have held since June 2016 with dividends reinvested from January 2019. I am a small amount in profit at c. 5% (mainly down to dividends taken as income rather than reinvested in the early days of my holding) but over nearly 7 1/2 years that is a pretty paltry return.
Strix (LON:KETL) , unhappy holder wondering if the debt covenant relaxation and CFO departure are linked? The CFO would have signed off the most recent acquisition and has now lost her head. Presumably the outgoing CFO will be dumping her shares which will lead to further short term pressure on the SP.
Strix (LON:KETL) isn't a Chinese fraud. It's a long-established IoM business. They had a fair bit of debt at IPO but paid it off quite quickly. They are pretty protective of their patents but do do most of their manufacturing in China. Their problem is that they have been over-ambitious, building a new manufacturing plant in China at the same time as aggressively acquiring a number of companies.
The CFO has gone for a very early retirement I think. I'd seen absolutely nothing before this so it does seem to have been planned very rapidly.
I suspect it won't be long before the CEO suddenly finds he's been planning his own retirement for a while.
Re: Strix (LON:KETL) - Over-expansion is a pretty serious, and dangerous, misdemeanour for an executive team. (No position)
It sounds like we all have many investment tales of woe, which can be absolutely soul destroying at times. But, as a lot of you have mentioned on here, it is good to 'talk' and to understand you're not alone during this very frustrating (and painful) period.
I would like to offer one glimmer of positive news though. After reading Roland's excellent SIF Portfolio reports over the years, I decided a couple of years ago that I would put aside a (decent) chunk of my investment cash and be an absolute 'slave' to his rules base approach (well, my own stock picking skills were pretty woeful!!). Clearly with a the portfolio of c.15 shares, there have still been some real 'dogs' over the last year or two but, there have also been some 'heroes' which have contributed to a 5%+ portfolio growth over the last 12-months and 0% YTD (not bad against all the red we are witnessing).
So my conclusion? I'm not sure I have an earth shattering statement that will change the world, other than maybe to attempt different mini strategies within your overall investment strategy - I guess that's called diversification!
And finally, thank you Roland for shining a light on your very interesting stock-picking strategy - I would definitely recommend it!
Cheers all - I'm sure the bear will retreat back into the woods soon...!
Hi Chris I'm not sure any old diversification plan has worked or will work. I did that and all that seems to have happened is that my portfolios have caught the Devil by the tail.
Hi Chris, It is all a bit painful- but seen this over many years and it will turn- and when it does could be fast. When is the question and there are well known global issues which may stall the recovery in markets- particularly smaller company markets. Looking at the latest stats from the Investment Association looks like a large % of the August inflow of £354 went into tracker funds.
Hi Chris1011
Agree with you on Roland's SIF portfolio approach - it is a shame he is not officially running it and posting it on the Stockopedia site anymore (at least I think that is what he said). I am considering adopting it in future as my stock picking skills are also pretty woeful! I have been running a 'fantasy' SIF portfolio based on Roland's screening approach since the beginning of 2023. I follow the rules rigorously and my approach lacks some of the in-depth analysis that Roland carries out on the stocks that the screen identifies. In last few months quite a few stocks have hit the 25% stop loss criteria and have been 'sold' - perhaps indicative of the bear market small/medium cap stocks are suffering. Consequently my version of SIF portfolio is down c. 0.8% YTD which I guess isn't too bad!. Interestingly for comparison Ed Croft's NAPs portfolio for 2023 (another rules based approach) including costs and dividends is down 2.4% YTD though without a very large special dividend from Capricorn Energy (LON:CNE) this would be down by 5.6% YTD.
Renewi (LON:RWI)
In answer to your question, Paul, I owned and sold the lot for £7.25 on the day of the initial offer. I would buy back in as it’s a rare name in an attractive space. But with the withdrawal of Macquarie’s offer in the low £8s I think that sets an upper bound for other offers - which may never transpire! So I’d be looking for an entry below £5, as I don’t think the price today reflects the troublesome economic conditions in Northern Europe.
Hi Paul & BnB - don’t hold Renewi (LON:RWI) but did hold Augean. The difference on the latter was that it had a virtual monopoly on landfill sites and could therefore dictate pricing which provided good downside protection to the shares.
Does Renewi (LON:RWI) have any similar moat to its business case?
Does Renewi (LON:RWI) have any similar moat to its business case?
Not of the type enjoyed by Augean. But where the latter’s monopoly existed in opposition to the drivers of the circular economy, Renewi’s business is favoured by regulation and the direction of policy. It is also a very rare asset - a listed (almost) pure-play recycling company. Debt is too high for complete comfort though.
Thanks - am wary of high debt unless it is really well covered, with minuscule risk of covenant breach but will take a “renewed” look at Renewi (LON:RWI) (sorry, I couldn’t resist!)
As with BnB I sold all Renewi (LON:RWI) when the offer landed but am not tempted to buy back in. I also held Finsbury Food (LON:FIF) and also sold when the offer landed (I thought the offer was low but needed the money) but here I am very tempted to buy back in,
AIM up today!! None of my stocks rising though...
But as Ed Croft has observed over time, a buy signal on the AIM is when it crosses the 120d moving average. It's well below that at the moment.
Yep, no buy signal yet. Santa Rally maybe not so far away?!
'Cost of children crisis’: UK parents on coping with half-term on a shoestring
https://www.theguardian.com/ed...
Crisis, crisis, everything is a crisis these days. 'Coping'? I went out and played with my mates when I was a kid. Nowadays it's a crisis if you can't afford to taken them to Disney.
That's because kids are used to expensive items like PlayStation, fancy clothes, shoes and big holidays courtesy of our government printing money over the last 14 years. All that cheap money loaded households up with so much debt which now has to be paid for at high rates!
I'm sorry but there's a real lack of empathy being shown here. I'm sure you've both read the article. If you have and still feel this is people crying wolf then that's shame. The big difference between the uk we live in now compared to the 'good ole days' is that there's far less central govt support available now. For instance, try getting a cavity filled at the dentist for less than £150 now.
There are major economic disparities in the UK. Wealth between the poorest and reasonably well off is wide. £30k a year is now considered to be less than an average wage and isn't enough for people to live on. The amount of disposable income than most people have is very little after tax, NI, and bills are paid. If you have a family to look after what's left doesn't go very far if you have childcare costs. Schools look for parents to make contributions to be able to afford to run some events, otherwise they don't happen. Those of us on here who can afford to invest and pay for a platform such as Stocko are in fortunate positions.
If you honestly believe increased central government involvement in family life is a good thing I think you have learnt nothing from history
Will leave it there
That's simplifying what I was saying. I'm saying that the safety nets that used to exist have decreased significantly, whilst costs across the board have risen significantly. Childcare, for instance, is so expensive that some parents are better off not working rather than take their child to a nursery. Some nurseries now struggles to attract children because of the cost. That's a stark contrast to where we were a few years ago.
I'm simply suggesting there's a need for some context, rather than making a snarky comment and looking down on what people do now. Us investors complaining about how difficult it is to navigate this market, in comparison to what some working families are struggling with requires some perspective. And it's so easy to revert to stereotype and say they need to stop buying videogame consoles or going on holidays. Plus, even if you wanted to be selfish in your approach - if other people didn't spend where would we be with our investments?
could not agree with you more.
I'm not sensing that any of this thread is relevant to UK small caps. Maybe one to move to Twitter?
Sorry Paul, I agree with you but I find the initial posting and response to be short-sighted, lacking in empathy and saw some lazy reversion to stereotypes. And yet some of the people being scoffed at are those very same likely buying at Greggs (LON:GRG) Frasers (LON:FRAS) , thereby making money for those of us who hold them.
Unbelievable - school a adminstrator bleating about the " cost of a shower" and the one off extra cost of replacing (very clearly) warn out trainers. I am sorry but get 6 hours part time work done for one weekend or get some decent trainers off ebay or gumtree or charity shop and stop bleating. Ridiculous when peeps over pimp tough times. I have sympathy for those not able to go out and earn extra but normal peeps over bleating like this really doesnt help the cause sorry to say (hmmm is she a union officer in disguise?). djack its not lack of empathy here - its a clearly ridiculous self pity article from soemone who has not evidenced thaey cant just do some overtime when there are more important things than a pair of worn out trainers . The most obvious clue this is a left wing rant is that she says "we are having to dip in savings" then the next line says "we are in overdraft" - if you have savings left why are you using an overddaft. My annoyance here is perhaps more at teh guardian than this person - i suspect if they are honest the guardian has made them look like a total whinger when they may not be ? - am i too cynical?
Possibly. your comments might be valid but we don't have context on what actions someone has taken. Maybe the article is poorly written but I wouldn't dismiss the view as being down to an undercover unionist. I've been to different parts of the UK this years and there are some clear economic disparities between cities.
I am not dismissing the consensus view - i am dismissing the article moaning without saying why that person couldnt have done 3 hours extra work or whether what was being presenteed is really what it is. Its clear the guardian and unions love to push false naratives in this regard - nowt against the person involved but imho the article is terribly put together and comes across as a biased rant. I live in the most deprived part of the uk and i am well aware how tough it is to the extent that some peeps need food banks to get buy - i am not denying its tough for many peeps particualrly now with household costs and inflation being what they are.
And each month I donate £cash to the Foodbank so I concur life is hard and I am very grateful and sometimes I moan too
Tommy
In real terms, wages are no better for low-to middle income earners are not much better than ten years ago.
Agreed and i would say times are probably tougher than 10 years ago with high inflation - high food/energy costs - at least 10 years ago we didnt have those issues on top.
What do you think of REIT's prospects? I was reading today's RNS's and this came on my radar:
M7 Regional E-Warehouse REIT plc
Proposal to De-list from IPSX
https://www.londonstockexchang...
Q3 2023 BUSINESS UPDATE
https://www.londonstockexchang...
i think they had to refinance their loans now at 7.31% instead of 3.85%
they are de-listing as a REIT and going private?
how sustainable are REITs which many people use for investment income?
Are there any REITS that represent value - many have been battered this year!
For me personally, easier ways to make money. Still too much uncertainty about rates and let's face it - everyone got the whole rates cycle wrong. Higher for longer does nothing to help this sector even if gearing is low enough to ensure survival.
Ben - Property companies are very much out of favour until the interest rate cycle turns. I hold quite a few and they have been very poor performers in the last year. I wouldn't touch the company you mention as Loan To Value is too high.
Avoid anything with LTV > 30-35%, have loans that need refinancing in the short-term or that have Revolving Credit Facilities, would be my tip. I'd also avoid anything but the best companies as these are really bombed out share price wise anyway. No point buying the worst highest risk companies when the best are on record discounts. Those with fixed rate debt at c3% and a long maturity debt are best. Its quite a specialist sector; industrial, self storage and alternatives seem to be best at the moment. Offices, high street retail, pubs and shopping centres worst for obvious reasons.
My top real estate picks would be TR Property Investment Trust (LON:TRY) - for an investment trust with a good record, Value and Indexed Property Income Trust (LON:VIP) which announced today and is well run, a dividend hero and with an exit planned in a few years, Londonmetric Property (LON:LMP) for a quality bigger company and Tritax Big Box REIT (LON:BBOX) for logistics sheds. They are all down a lot so best to await the charts reversing.
Assura (LON:AGR) and Primary Health Properties (LON:PHP) are both interesting as well holding about 10% each of the UKs GPs surgeries, but their LTVs are a bit too high, and have some rights issue risk, albeit they have their interest fixed at c3% for a few years yet.
I hold all of these, but keep real estate weighting between 5-10% of my portfolio.
If you're interested in the property sector, but don't want to pick shares yourself, you could consider TR Property Investment Trust (LON:TRY) . They own a broad range of investments, including logistics, office, self-storage and student accommodation. The also own offices, but seemingly in attractive places where occupancy is good. Many of the reits they invest in are at substantial discounts.
Or alternatively, why not the Premier Miton Pan European Property Share Fund, a unit trust. According to the Premier website, it has returned 60% over the last 10 years.
TRY's comparison, i.e. it's NAV, is up 35% over 10 years, according to numbers i gleaned from AJ Bell.
Your are starting with a 10% discount with TRY but the numbers suggest you are getting the better manager with Premier.
Declaration: i know the manager of the Premier Fund, hence why i know it exists, and how successful it has been.
HI Chris - surely holding property in a UT goes against all of the warnings that have come to light recently - and historically.
When forced redemptions cannot be met on property the fund gets gated - this is not uncommon in turbulent times as the fund manager cannot exit property positions quick enough to pay out redemptions.
I appreciate the current prices might be good and it could have a good track record (Ive not checked it), but I would prefer to hold my property in an IT or directly so I can always get a price and exit.
Re: Why not Premier Miton Pan European Property Share Fund, a unit trust?
An open-end fund structure for property and land (and other illiquid assets)? We've seen that go wrong before. If it owns just shares, fair enough, but otherwise I suggest folk stick with REITs and its closed-end fund structure.
I would suggest looking at Palace Capital (LON:PCA) trading substantially below NAV (share price 218:nav 295ish), minimal bank debt, £0.1m at last update, will have bought back 20% of it shares on completion of the current share purchase programme and yields 6.5%.
Serial astute small cap investors Peter Gyllenhammer and Christopher Mills (Harwood Capital) have significant holdings. A lot to like if you ask me. I hold.
Alternatively put your faith in Marcus Phayre-Mudge who has managed TR Property Investment Trust (LON:TRY) since 2011. TR Property Investment Trust (LON:TRY) invests in property through equities and direct investment. Its been around a very long time. Currently trades at a 11% discount to NAV and yields in excess of 6%. Held in my daughter's ISA.
Yes, agree jonno that TR Property Investment Trust (LON:TRY) is good. Worth mentioning its on a double discount. 11% discount to NAV, but the portfolio holdings are on massive discounts as well. Of course, this reflects that real estate values are still falling but these could bottom out sometime in 2024 I suspect.
if you're looking for a REIT at a good discount, consider Regional REIT (LON:RGL) - looks like a double-digit divi is quite achievable, and has a 0.38 price to tangible book value.
You need to pick carefully but definitely some REIT bargains out there - stick to those where the underlying assets are performing well and seeing strong demand, and with modest, long-term debt. If you focus on the better quality ones you're essentially getting a 7-8% inflation linked yield while waiting for the valuations to recover. My top picks are Tritax EuroBox (LON:EBOX) on a near 50% discount, Supermarket Income REIT (LON:SUPR) and £SHED I would also highlight Schroder Real Estate Investment Trust (LON:SREI) as they very smartly fixed their debt a couple of years at a very cheap rate for well over a decade.
Personally would look for REITs where this a shortage of supply for the particular area they are invested
Two that might be worth a look and which I hold are
THRLTarget Healthcare Reit (LON:THRL) there is no shortage of old people and they own modern energy efficient homes unlike a lot of the existing stock
PRS Reit (LON:PRSR) Build for rent housing REIT which there will be a shortage of supply for the foreseeable future
Both been affected by rising rates but seem to have stabilised and offer good long term fundamentals
I'm just looking at all the comments yesterday in reply to Lefty's post on it being difficult at the moment. I'm also finding it tough, I feel like my portfolio is being slashed by a thousand ~-0.8% drops at the moments.
So reading the comments on here yesterday really helped. Thank you to everyone who contributed.
For me its just focusing on the fundamentals of the companies and ignoring the share price for now. I've also appreciated the dividends and reinvesting them, so far very few of my companies have reduced or even held dividends which is leading to nice increases YOY.
If somebody is making money in this market then they are in a minority. Only really possible through trading. The screenshot above is a reflection of the state of the market, not any reflection on Stockopedia.
Investing is simple but not easy, said Buffett. Simple part is buying quality companies and holding them over the long run. Hard part is putting up with the losses along the way.
Good to talk Carvalio, I feel much better today.
Sometimes if you are confident in the fundamentals of the companies you own you are best not looking a lot of long term holding of shares is phycology was never put better than Benjamin Graham and his discussion of Mr Market in his book the intelligent investor
https://www.amazon.co.uk/Intel...
Sometimes you can appear to be wrong for a long period of time before it comes right