Small Cap Value Report (Fri 28 April 2023) - NUM, TUNE, EXR, CGS, WAND, GETB, ZOO, CTA, TPX, MER

Good morning from just Paul today!
Today's report is now finished, at 13:20
Tune in for tomorrow's next thrilling podcast instalment!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
A crazily long to do list today, but I've already done 2, just need to type up my notes - I'll focus on quick comments, to get through as many as I can -
Update at 11:38 - good progress so far, lots has turned blue, on the to do! I'll have to leave some of the smaller things, and hope to get up 2 or 3 more sections on the larger market caps below.
Good, most of today's list got done, please remember we can rarely cover everything. I've deleted a couple of micro caps from the list that don't look very interesting.
Quick comments:
Numis (LON:NUM) - recommended cash bid at 350p (incl 11p divis) - Paul - GREEN
Checking our archive here, Graham has reported positively on this investment bank/broker, marking it GREEN on 3 April, 7 Feb, and 8 Dec. Graham pointed out the short term headwinds from the weak IPO market, but good recovery potential, strong asset backing, and decent yield from Numis shares.
It’s surprising to me that Deutsche Bank is doing this £410m cash bid, given it has widely publicised problems of its own.
This is a recommended cash bid, at 339p + 11p in divis, total 350p. That’s a very nice premium of 72%, so nobody can complain about that. Investors can use the proceeds to buy another cheap broker, and get more of it, which itself might then be bid for.
The takeover bids are rolling in at the moment, which does reinforce the point that private markets & acquirers are valuing some UK shares more highly than the public market does. I think this augurs well for UK markets, and a wider recovery as more people realise that the UK small caps space is (selectively) full of bargains - but also plenty of junk too though! - which is my view.
ENGAGE XR Holdings (LON:EXR) - up 18% y’day to 3.85p (£20m) - Paul - RED
I took a look at this software company focused on the metaverse (creating visual software for headsets). Q1 2023 TU says in line with expectations, and revenue up 40% on LY. Big name clients. VR concert with Fatboy Slim. Lenovo headsets coming. E10.8m cash end March 2023, after surprisingly well-supported placing in Feb 2023 (it was getting close to running out of cash, so this saved the company I would say). No 2022 accounts published yet, but FY 12/2022 TU looked grim: E3.9m revenues, E(5.8)m EBITDA loss!
Paul’s opinion - looks grim to me. There must be any number of companies in this space, selling a product for less than the cost of developing it, so what’s the point?! The product demo I watched online looked really weak & gimmicky in my view. The heavy cash burn suggests it might be back for more cash in 2024. Hence the risk is investors will see it as a jaded concept, and the share price melts away to dust. Why get involved, when the chances of commercial success seem to distant, if at all? I've been in the UK small caps market for over 25 years, and have noticed that this type of share hardly ever succeeds. Even if they do, it's years, and numerous fundraisings later. They're best avoided, apart from where a commercial tipping point has been reached, where profitability and self-sustaining cashflows have been reached. EXR is nowhere near that point.
Castings (LON:CGS) - up 3% to 379p (£165m) - Paul - GREEN
Ahead of market expectations TU for FY 3/2023.
Strong demand, due to high build rates by heavy truck manufacturers (70% of CGS’s revenues derived from this sector). Some production inefficiencies in H2, but now largely resolved. Input costs (raw materials & energy) successfully recovered from clients. Balance sheet here is superb, last reported as NTAV £125m. Neutral cashflow, after special divi payment, and increased working capital. Outlook sounds positive from buoyant customer demand.
Paul’s opinion - lovely figures: PER 12.5x, yield 4.7%, great balance sheet. Pricing power proven. V high StockRank. BUT - main products (turbocharger housings) likely to be phased out with electrification? So big question is what alternative products can Castings focus on longer-term, and will these be a lucrative niche too? Still, in the meantime, it’s a thumbs up from me.
WANdisco (LON:WAND) (I hold) - suspended - Paul - RED
Update today reiterates that the entire fraud was apparently just one rogue employee. Obviously that sounds ludicrous, but that’s what we’re being told.
Hoping to lift suspension of the shares. New CFO started on 11 April. New CEO being sought. No mention of solvency or cash position, which was flagged by the company as a concern when the fraud news first broke.
Paul’s view - is not printable. Any recovery from this share would be good, as I’ve already mentally written it down to zero. Likely outcome? If it comes back from suspension I would work on the basis that it might resume trading at maybe 90% down? Because the valuation rested entirely on the positive contract announcements, which were made up. The big lesson here remains - don’t believe the trading updates from jam tomorrow companies until the numbers are audited, and the cash is in the bank. Especially when management has a track record of being overly-promotional, with false dawns before. I see my losses here as the market charging me a fee to re-learn these lessons!
Getbusy (LON:GETB) - up 2% to 66p (£33m) - AGM Statement - Paul - AMBER
In line with exps for FY 12/2023, “high level of confidence” of achieving exps. Good visibility, as it’s a recurring revenues business. ARR now £20.5m, up 17% on a year earlier, at constant currency. Positive noises made about customer acquisition, average revenues per user, and reduced customer churn.
Liquidity looks OK, with £2.7m cash, plus unused borrowing facility of £2m.
Guidance FY 12/2023: revenue £21.1m, adj EBITDA £0.7m - unchanged EBITDA from FY 12/2022, and it turns into a £(0.7)m loss before tax.
Paul’s opinion - it looks OK, but still seems sub-scale, isn’t profitable, and growth isn’t rapid enough to get me excited. Hence shares look uninspiring, unless it can really turbocharge the growth, which isn’t happening yet. Also I find generally this type of business usually seem to find things to spend additional revenues on, usually increased sales & marketing (as is happening here), so the operational gearing often turns out to be an illusion. But it’s chicken & egg - they can’t get the growth, without first spending more on sales & marketing. That said, investors like recurring revenues businesses, and tend to value them quite highly. The fundamentals don't justify a higher valuation right now.
Zoo Digital (LON:ZOO) - down 9% to 166p (£148m) - Paul - AMBER
Has done a placing at a 13.5% discount (160p), issuing 7.8m new shares (89.8m existing, so 8.7% enlargement), to raise £12.5m before fees. There’s also a very small £0.5m retail offer to existing retail investors, through BookBuild.
Purpose - proposed acquisition of a Japanese company later this year.
Trading update - FY 3/2023: revenues $90m+ (up 28%, almost all organic), adj EBITDA $12m+ (up c.44%). Cash of $11.8m. Revenue is well short of expectations (of $99m), due to major customer delays. But as it’s a low gross margin business, that doesn’t seem to have done much damage to profits.
Paul’s view - it’s a mild profit warning, obscured by the fundraise news. Annoying that the fundraise is at a 13.5% discount. Also raising more equity reinforces that this has not historically been a profitable or cash generative business. FY 3/2023 seems to be its breakthrough year, where it is forecast to make c.£7.1m adj PBT.
We’ve commented positively on the great newsflow from ZOO during 2022, but I’m less keen on it after this profit miss, and dilution from the placing. Still, it’s a good story, although I think the current valuation (PER 30x FY 3/2023, and 21x FY 3/2024) looks fully priced for the time being. Gross margin of only 32% indicates this is a competitive area, lacking pricing power. Although that’s arguably offset by the structural growth opportunities from streaming TV services globally.
I’ll shift from green to amber, to reflect dilution & the mild profit miss.
CT Automotive (LON:CTA) - 43p (£22m before fundraising) - Paul - RED
I’ve only mentioned this automotive parts supplier once here, on 9 Dec 2022, to warn people away from it, after a profit warning took it down 16% to 102p, and leaving it indicating an $11m loss for FY 12/2022. Bear in mind this company only listed in Feb 2022, so it’s been a disaster. Also net debt looked worryingly high when I reviewed it in Dec 2022.
Problems seem to have been caused by semiconductor shortages, supply chain bottlenecks, input cost inflation. However, I wonder if there might be recovery potential here? It operates in a variety of low-cost countries, including China, but might see more demand for reshoring in e.g. the USA market (I think it has a factory in Mexico). Volex recently noted this factor is helping demand from its Mexican factory. Also as we’re seeing from CGS today, production of vehicles is now recovering, so demand for components should also logically be recovering.
The fundraising CTA announced this week dilutes existing shares by 45% (including the Exec Chairman who will still own 27% after the fundraise), at a hefty discount - priced at 34p. This raises £7.7m before costs.
Paul’s opinion - obviously a nasty situation, now with dilution, but I’ll keep an eye on it, as there’s a possible recovery story here at some point. I need to see the full 2022 numbers, which haven’t been published yet. Maybe this fundraise was essential to persuade the auditors to sign off the going concern note in the 2022 figures?
Tpximpact Holdings (LON:TPX) - up 66% to 53p (£49m) - Paul - RED
An announcement today about big contract wins with UK central Govt has put a rocket under this troubled IT group, adding £20m to its market cap.
The deals are worth up to £77m over 4 years, with the Dept for Education, and Land Registry.
It certainly reinforces TPX’s credibility to win contracts of this size with Govt. But it also makes me wonder what the terms are? It won them in a competitive tender, and there’s always the risk that a financially troubled group like TPX, which has stretched its banking arrangements, might be tempted to bid for work at less than ideal terms. We don’t know.
I reported here on 31 March 2023 how its bank had waived the covenants that were breached on that day - a very close shave.
Paul’s opinion - I hope TPX uses this contract win euphoria to get an equity fundraise away, which it needs to become financially stable enough. The Sept 2022 balance sheet is very weak, with NTAV negative at £(16)m, with £20m of long-term bank borrowings sticking out like a sore thumb. I’d want to see that at least halved, with a £10m+ placing, before considering this share safe enough to invest in. In the meantime, it’s making progress, but still very high dilution/solvency risk.
Mears (LON:MER) - up 6% to 222p (£245m) - Paul - GREEN
I last looked at this provider of maintenance & repair services for housing here on 8 Dec 2022, concluding that the trading update and outlook both looked good, awarding it a coveted SCVR thumbs up!
Mears manages & maintains about 450k affordable houses in the UK - so it’s an outsourcing group for this sector.
What’s the latest? Today we get FY 12/2022 results, another positive trading outlook comment, and a £20m share buyback.
Adj PBT is £35.2m, up 37% on LY. Thin margins though, as this profit is generated from £960m revenues.
Delighted to see average daily net cash of £43m disclosed - this is far more useful than the period end day’s snapshot (which was £100m net cash at end Dec 2022).
Nice divis here, at 10.5p for 2022 in total (2021: 8.0p).
Adj EPS is 24.5p (2021: 18.2p), so the PER is 9.1x - still good value I’d say.
Order book healthy at £2.9bn, about 3-years revenues.
Balance sheet looks OK, neither strong nor weak, in my view.
Outlook - positive start to 2023, in line with expectations.
Paul’s opinion - positive, this gets a thumbs up. I wouldn’t expect this type of business to ever attract a massive PER, but 9.1x looks too stingy. So it’s not difficult to imagine say 20-50% upside on the share price, in a more healthy stock market, and you get paid decent divis whilst you wait.
Paul’s Section:
Focusrite (LON:TUNE)
451p
Market cap £267m
Shareholders have had a horrible time here. This share seems to have suffered that nightmare double whammy of seeing forecasts fall, combined with a growth company high PER rating turning into a value company lower PER. Combine those two, and they’re a powerful force on the way up, but unfortunately on the way down too. As you can see -
Here’s the share price since listing -
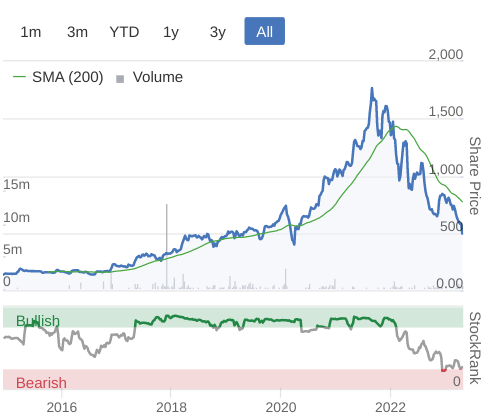
I never would have predicted such a big sell-off, although it was clearly overvalued at the peak.
In fact, I called this one wrong when last looking at it here on 14 March, giving it a GREEN opinion at 665p, thinking it was reasonably priced on a fwd PER of 15x. Nobody knows what will happen with short-term market sentiment though, including me! We're really just looking at the company fundamentals here.
Turns out the market disagrees, with it now down another 32% in the last c.6 weeks to 451p.
So I looked at its recent interim results last night, asking myself, has it overshot on the downside now?
Here are my notes from the interims -
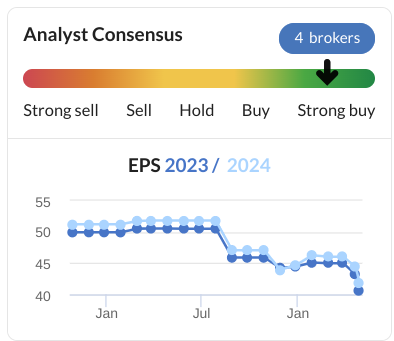
Broker forecasts have reduced to c.40p EPS (down, but hardly a disaster - but could they drop further, now the earnings trend seems to be downwards?). This is still double the pre-pandemic level of EPS, so this is not a broken business.
Founder, Philip Dudderidge, still owns 33% - the owners eye, but not too dominant, in my view.
The well-known Buffetology Fund (which has had a difficult time, like many of us), is a notable major shareholder with c.10-12% - could they be a potential seller, to meet redemptions, which might depress the share price?
StockRank is low, at only 27.
Last reported on 14 March 2023, with in line H1 TU, and FY 8/2023 also guided in line. Although broker forecasts have been falling, so it’s not really in line! -
Interim results to 2/2023 -
11 brands now (musical instruments, speakers, and the core products are boxes to digitise sound, used also by podcasters)
“Content creation” division hit by surplus inventories, and having to clear old stock to make way for new improved product launches - I think this could be the problem - we’ve covered this point before actually here - that TUNE’s core products have a limited lifespan, and have to be constantly updated to remain competitive. This involves considerably capitalised R&D, and means that I question whether the business is as high quality as we previously thought?
H1 revenue £86.2m, down from £92.9m a year earlier. This is flattered by acquisition & forex. The organic revenues from core products (Focusrite and Novation brands) are down a hefty 19%.
H1 adj diluted EPS is 18.0p (H1 LY: 26.2p) - so c.40p broker consensus looks realistic for the full year, given new product launches should give things a boost.
H1 divi very small at 2.1p
It’s moved from net cash of £18.0m, to net debt of £13.2m - due to funding acquisitions. This is not a problem level of debt, so not a concern at all to me.
Audio reproduction division did well, so there’s a portfolio effect here of strength in some areas mitigating weakness elsewhere, which I see as positive obviously.
Current trading - “remained solid”, with the outlook sounding quite positive, although it’s not that clearly explained, so somewhat ambiguous I’d say.
Capitalised development spend is high, at £4.3m in H1, so £8.6m annualised. This renders EBITDA meaningless of course.
China risk - this sounds quite alarming, in that the commentary reinforces just how dependent TUNE is on manufacturing and components from China, which of course could be calamitous as relations deteriorate between the West, and China. That said, who isn’t dependent on China? If war breaks out over Taiwan, then we’re all in a mess, regardless of what we’re invested in.
Balance sheet - dominated by £84m intangibles, from multiple acquisitions. However, there’s no need to panic, as the NTAV is still positive, at £26.6m - which is adequate, rather than strong. Working capital looks healthy. Overall, at the current level of profitability, the balance sheet is fine, not a worry.
Cashflow statement - again the capitalised R&D stands out as a big number, at £4.3m in H1. Also there was a big reduction in payables, which could do with querying if anyone talks to management. We can also see that it borrowed the money to make acquisitions.
Paul’s opinion - not a great deal has changed since I last looked at TUNE a few weeks ago. So I see the 32% fall in share price since then as overdone.
A much more appealing fwd PER of 11.1x per the StockReport is interesting value for what remains a decent quality business (see the high quality scores on the StockReport).
I think it’s come into buying range for value investors, and the newsflow hasn’t been particularly bad, hence I’m happy to give it a thumbs up. It’s the sort of thing where, if I had spare cash, I’d probably be nibbling at it for a small starter size position, and then wait to see how things develop. But as always, each to their own. I can see why some investors don’t like buying into a falling price, as things often overshoot on the downside. So watching and waiting is also a sensible strategy, although that can often mean we miss the bottom, and miss out on takeover bids too. A bid looks unlikely here, since it would need the approval of the founder, with a bid-blocking 32% stake.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

54 comments
Hostmore (LON:MORE) very late results on Friday afternoon they look better than expected.
On the subject of WANdisco (LON:WAND) I just cannot believe the story.
The Fraud Squad need to be all over this case. When it is really hard to believe it is often fraud and I think this case has a long way to go. Lets hope the truth will out.
...is it possible to introduce a "subject" field into this, please?
https://www.voxmarkets.co.uk/a...
Richard Crow is always worth a listen IMO. He discusses his holdings and general investing strategy.
interesting. thank you
@CTO in the headline.. I don't see it. Do you mean @CTA?
yes sorry, I spotted that a moment ago & corrected it! Apologies for any confusion.
It looks like I don't get to buy Zoo Digital (LON:ZOO) shares in the Retail Offer since I hold shares in Hargreaves Lansdown and iDealing, which are not on the list.
https://bookbuild.live/deals/K2QE3Q/authorised-intermediaries…
Why not use an Open Offer as normal?
I urge those in a similar position to contact their broker, asking them to register:
"Intermediaries wishing to participate in the Retail Offer on behalf of underlying clients, should register at www.bookbuild.live or support@bookbuild.live "
Thanks for the list. And yes this route is extra complicated and excludes some retail investors for no good reason
Appears to be 2 very large government contract wins at TPXImpact announced.
Looked a basket case previously but the wins over 2 and 4 years appear to be almost the same as the entire 2023 revenues.
Large debt but trading was in line in March. Should see upgrades. Trading update/guidance probably in next week.
James Fisher And Sons (LON:FSJ) FY numbers out this morning.
Roland previously commented "I think the foundations are being put in place for a turnaround. I’d be interested to learn more here, as I think there are some attractive elements to this business".
These results read to to me like the turnaround is beginning to bear fruit, under a new CEO. Pity there doesn't seem to be any new broker notes. It was quite a downfall for this longstanding business.
Does anyone else see green shoots? I Hold.
James Fisher And Sons (LON:FSJ) I agree and hold also. New management Cockburn (Chairman ex Aggreko and Serco) and Vernet (CEO ex Smiths Group) have great track records and are highly regarded. A sprawling, under-managed business ripe for restructure and they've started well with disposals and asset sales to reduce gearing. They slightly front-run the results with their refi announcement on Wednesday but they're trading better than expected overall with the defence business in contract cycle low. There are some high quality businesses in here from submersibles for the SBS, to diesel tankers and bubble curtains for wind farms in all of which they have strong positions. A lot of work to do but green shoots indeed.
I took a starter position in James Fisher And Sons (LON:FSJ) on news of the credit facility being agreed.
Things seem to be stabilising from what I can see (I'm certainly no sector expert). Has all the ingredients you'd look for in a turnaround, low share count, debt reducing, simplifying business, new CEO. Lots of work to do but there's a multibagger possibility here if things work out.
James Fisher And Sons (LON:FSJ) FY 22 Results (I hold). No more big surprises. always good. Results a little under expectations but broadly in line.
I agree that the turnaround is now well underway. It's the case that the rot sets in before things go south. And also the case that that a lot of the heavy lifting to turn things around has to happen before it shows in the results. Management is rightly being cautious, but in amongst all the detail on the hard work underway - the chairman commented:
'the business has performed well during the first quarter of 2023 with revenue and profit above our internal Budget and well ahead of the prior year.'
Too early for that to be reflected in any forecasts yet, but the potential for an upgrade is there already?
A recent press release on the Fisher Website - Subtech has signed a second vessel to longterm charter this season. A very significant commitment to increased capacity in the North Sea.
The markets in which Fisher operates are now growing strongly again and likely to continue while at the same time the energy price has fallen sharply from its peak, reduced freight and logistics costs, supply constraints and inflation falling are all likely to contribute to a tailwind for future results.
Net debt was stable at the balance sheet date - but since then £20m has been received for the sale of Swordfish and a futher £2.4m agreed for the sale of Mersey Fisher together with delayed receipts at JFD. There is always an increase in funding needed during H1 as the off-shore season gets underway - with current performance continued through a successful season there is potential for debt to start falling fast towards the end of the year.
The shareprice remains very depressed over understandable debt concerns, but revenue remains high and the company has avoided sellings its crown jewels or increasing the share-count. Not without risk still but the prospect for 3x or 4x multiple and more in the longer term is starting to emerge?
Finally starting to look good to me,
cheers
Mark
WANdisco (LON:WAND) - Who would want to be on the other side of the trade if it goes down 90% on relisting? I've always wondered who takes this kind of risk knowing a possible zero may be on the cards. Speculators with lots of spare money to burn?
Well - As Paul said - I just don't understand how this can be put down to just one rogue employee - surely the CEO an CFO would have honed in on this - not just to put out the press releases but also to congratulate the guy for his efforts - or not.... And where are the Fraud Squad ? Sounds to me far worse than Pat Val and even rogue trader Nick Leeson
The fact that a lot of well heeled investors were supporting Wand time and again with fresh money is an example of a lesson the market taught me in the dot con boom.
There is more money looking for a good investment than good investments looking for more money.
Another little observation of life while working behind a bar in my twenties and watching people winning a jackpot on the bandits, was that they invariably put it all back in the machine apart from a round of drinks. Winners are playing with someone else's money.
I agree with everything Paul says about ENGAGE XR Holdings (LON:EXR) - yet I hold it, having bought in around the current price, after the March 2023 placing. This is a stock that will need more financing and the most likely case is that it will go to zero. So apart from the reason that I am a mug for a wild punt, why do I own it?
1). The placing in March raised €10m and this should be enough cash until end 2024 - Finncap is forecasting end 2024 cash of €4.9m. So there is some room for error. If I view the stock as an option, it is a 2-year option for something to happen. Also there were no warrants in the placing - so no built-in dilution on the upside.
2). The placing took part in the “VR winter” - so there must be some serious investors who think it is not wasted money. The key backer of Engage XR is HTC. They also stumped up more money in this round (although less than I would have liked and were diluted). HTC is a possible exit in the future.
3). The Engage platform does show some momentum (revs up 40% in Q1). The number of clients on Engage (including household names) rose to 190 (Dec 2022) from 23 (June 2020). While true many clients will only be using it as small trials to ensure they are not missing out, it does show momentum.
4). David Whelan, the CEO, started the company in 2014 with his wife on the back of a €1,000 loan. Management are used to working on a shoestring (if needed) and has skin in the game.
5). The FatboySlim concert performed recently on Engage got good reviews. This could create opportunity - as well as the risk of lost focus.
6). I became a bit more bullish about the market in March and thought my portfolio was too defensive. So I was looking for a couple of stocks that could show upside in a bull market.
7). ENGAGE XR Holdings (LON:EXR) recently announced it was delisting from Euronext - now AIM is the only listing. This announcement seemed to coincide with the stock falling to the low 3s and below the 4p placing price. Maybe a buying opportunity with “forced” sellers?
8) Finncap does have a 25p price target - although I would take that with a large pinch of salt .
9) I calculate that the company has raised around €30m from investors to date - so more than the current market cap
I agree this stock is high risk and the law of averages mean these stocks will likely go to zero. Sizing is important. DYOR.
The WAN saga reminded me about Revolution Beauty (LON:REVB), so I had a quick look at them this morning.
Revolution said they expected their long delayed final results and interims to be released by the end of April. 7 hours to go! I don't hold directly but I do indirectly via Boo. Can't see the aspiration of month end being met, but you never know, maybe they'll put a rabbit out the hat.
Have taken an opening position in Premier Miton (LON:PMI) in my daughter's ISA at a shade under 90p. Fund managers have been sold off, understandably so, particularly where they have bias towards UK shares. Given the dire sentiment to UK small and mid caps, the former being an area where Premier Miton (LON:PMI) has good representation, it seems like a good time to buy.
Premier Miton (LON:PMI) as with most fund managers are cash rich and pay a handsome dividend at the current price. Fund managers will be beneficiaries when the market turns, just have to be patient. Given its small size relative to its peer group I suspect that it is also a potential bid target.
Polar Capital Holdings (LON:POLR) is also held in the family portfolios.
To paraphrase the psychology of one of the great investors, Howard Marks of Oaktree Capital, sentiment in the stock market swings between the extremes of hopeless and flawless. That fact coupled with his view that the most important determinant of returns is not what you buy but the price you pay makes Premier Miton (LON:PMI) in my opinion, a sound buy at the current price. Of course it may always get cheaper, if it does and nothing changes dramatically in terms of the company I will likely add.
Just my thoughts.
Premier Miton (LON:PMI) Looks good with strong divi but heavy dilution of share base in evidence though - 50% over 6 years
Colin, most of that was from when Premier bought Miton.
Ahh! That explains it. Thanks. I wish I could figure out how to plot Market Cap V Time instead of share price
When looking at fund managers I like to take a close look at the underlying funds, especially their bigger funds. I have to say Premier Miton are rather uninspiring - they don't have a particularly distinctive offering (lots of seemingly identical UK equity income funds) and 3y and 5y performance rankings not great (mostly 3rd of 4th quartile). It is an incredibly crowded market with hundreds of other funds all competing for business, so you really need to be delivering top quartile returns if you want to attract meangiful inflows. I guess it is cheap, so probably does offer value, but can't really get excited about it.
I am more positive on Polar as they have a much more specialist focus (technology, healthcare, insurance, etc) so that would be my pick if I wanted to invest in the sector. However, I generally favour the alternative fund managers with institutional clients, such as Intermediate Capital (LON:ICP) and £GHE
I do think fund managers are great to buy during downturns because:
I have played Cenkos Securities (LON:CNKS) in this way - buying when share price is near NAV and selling when I feel it's reached it's peak in the cycle and then waiting again (sometimes 2+ years) for it to get near NAV again.
I have about a quarter of my portfolio in fund managers right now in Cenkos Securities (LON:CNKS) finnCap (LON:FCAP) Polar Capital Holdings (LON:POLR) City of London Investment (LON:CLIG)
I am a bit surprised Polar Capital Holdings (LON:POLR) hasn't bounced more strongly given the improved performance in NASDAQ this year and the group's heavy weighting to US tech.
Agree with all that - fund managers give a geared play on equity markets. I'd just note that Cenkos and Finncap are brokers not fund managers so quite different business models, although I suppose they would also benefit from a rise in markets.
On Polar, the key thing is to look at their main global technology fund (which I think makes up around a third of AUM so will always be a key driver) - performance is nothing special over 1,3 or 5y - mostly 3rd quartile over these periods and well behind the ishares tech ETF. If we do see a further rebound in tech stocks then not sure the Polar fund will be the one to gather the inflows. For that reason I'm staying on the sidelines with that one too.
Croma Security
Security division is set to be sold off before end of this financial year .
Management buyout and the company already reporting seperately in its accounts .
Directorate changes are happening past few weeks .
I think announcement relatively imminent .
This would leave Croma with a cash pile circa 4-5 million plus a decent business with its its security stores making circa 1 million a year plus stuffed with the freeholds .
Looks a decent bet , even if the sale didn’t go through its still a good little business .
Micro cap but 7 million valuation is pretty low now I topped up at 48p this morning as price has been drifting down with no support or interest .
Re Croma. We also hold planetx, I agree with your observation, we'll add a few more too.
Investing is sometimes like travelling around the Monopoly board and landing on Chance. Several weeks ago one of my holdings Morgan Advanced Materials announced a major cyber attack..down went the share price. Today I landed on Chance again and the card read "Takeover bid for Numis".
Surely it’s definitely Community Chest!
Alphawave IP (LON:AWE) Alphawave Semi, a global leader in high-speed connectivity for the world's technology infrastructure, has published its preliminary results for the year ended 31 December 2022, a small $6.5m profit (MKt cap £835m). There is also a Q1 23 trading update, $100m of order bookings in Q1. Shares to be suspended for a short period due to delayed audit of FY22 accounts. I would really appreciate if you could have a look at this sometime.
Until there are evidenced revenues/cashflows (not more "bookings") from identifiable companies that are not related parties (Verisilicon, CPP, other Dai/Sutardja family related entities, John Lofton Holt's Achronix etc) it will be an uphill battle to forget what happened to Alphawave IP (LON:AWE) in Sept 2021!
What happened to Alphawave IP (LON:AWE) in Sept 2021 out of interest?
https://www.ft.com/content/1a5...
But there are evidenced revenues, cashflows and profits - very little of which is Verisilcon based if you look more closely.
To be fair "bookings" which is contracted revenue btw, is an industry standard metric but I don't think most investors actually realise what "bookings" are defined as......they assume it is some flaky half handshake type revenue - it isn't! The company has stated this before but it falls on deaf ears. We can also see this effect evidenced if we look back to bookings from previous quarters into actual revenues with an average lag of around 6 months.
Nonetheless clearly Alphawave IP (LON:AWE) has an investor perception problem, not helped by the short attack in 2021, but I doubt that perception is going to change for another year or so. I think investors find the story too difficult so I expect this will gyrate between current bounds until the numbers drop into EPS, at which point I suspect the licensing effect lightbulb will go off and the shares will materially re-rate. Until then I don't see it getting much joy.
There are indeed, but recognisable names are hard to come by - there are alliances with the likes of Intel's foundry, and comments like "10 of the top 20 semiconductor...." but it is difficult to find blue chip names in the order book (non-disclosure may be industry standard, but doesn't chnage matters), or industry players who are willing to give a plublic thumbs-up to their product offering. Makes it very difficult to analyse their strategic position and value-added?
Yes but you could say that about many in the semi conductor industry, it is highly secretive in that respect. The problem is that with Alphawave IP (LON:AWE) people are looking for reasons to validate the short attack, which was highly effective but in reality based on very little. So until perception changes they can't get away from that and the only thing that will change perception is free cashflow and EPS numbers. In reality that's next years numbers if the business case is valid. So in my opinion at least, I see little change in the range trade until then. It is not helped by the absurdly low liquidity either.
Btw if you want to analyse their strategic position the Capital Markets day presentations on their website from a few months back are helpful.
Yes, been there & done that.
As someone who used to meet Acorn & ARM management regularly I've got some familiarity with the industry.
It's not what Alphawave say about themselves that I'm primarily interested in, it is what competitors and customers say about them - and on that front it really is difficult to uncover much (blank looks and shrugs, often).
It is quite a niche area, and quite difficult to find perspectives from sources other than the company itself.
It's an interesting situation, but not an easy proposition to get to grips with from outside the industry.
I don't disagree that investors appear to be finding it very hard to understand & validate the Alphawave IP (LON:AWE) business and that's why I don't think it goes anywhere until next year (assuming they continue in-line with their business plan).
All I can say is that the business is now large enough, having spent the IPO proceeds on acquisitions, that given the number of employees if the revenues aren't genuine then the business would be bust in an instant as the cost base would be too heavy. Add to that the very heavy founder share buys and anecdotally that adds up to guiding me towards the story being one of genuine increasing revenues and profitability.
If that is indeed the case and the $350m revenue for this year goes to $500m next year (40% growth rate) and with corresponding margin increase to 40% (per CFO in capital markets day) then this share will appear very cheap indeed. Given the licence model it will probably trade on 25-30* so share price could happily treble or more.
Am I buying now - probably not because investors don't like it. Trades up to 120p and back again. If it dips a bit I might well buy some, wait for the rise towards the top of the channel and sell and then repeat over the next few months. Otherwise I'll wait till next year
Alphawave IP (LON:AWE)
Add to that the very heavy founder share buys
Needs to be put into context with the approx £300m the 3 founders and Mr Sutardja collectively trousered at the admission to AIM.
LON:AWE is down nearly 13% as I write. Wondering if its a Wandisco led-reaction - trust in tech is in very short supply or a reaction to the (comprehensive IMO) update. Alphawave is growing very fast, huge jump in headcount, cash surplus now a small debt so there's no lack of ambition. It would be good to have a second opinion on the update.
Hi Berksbee - this happens on every update. They trade around 100p then drift upwards to 120p before quarterly updates. Then people start trotting out the same negatives and it drops back. Repeat cycle.
In my opinion nothing will change for another year or eighteen months. This year is somewhat irrelevant ($350m revenue and $87m ebitda) as they are integrating some big purchases. Next year at expected $500m revenue and 40% ebitda margins or $200m is the key catalyst. If they broadly hit that then I suspect Alphawave IP (LON:AWE) will materially re-rate but I don't see the market giving them any credence until then personally, just more of the same trading pattern.
EDIT : To put it into context look at the liquidity : £2m worth of shares has sent an £800m market cap company's price down 14%. There is f*** all liquidity in the UK market apart from in a handful of large cap stocks. It's probably good for traders as you get relatively large and fairly predictable swings but if you are a longer term investor it is a basket case.
Sutardja has made a remarkable series of large investments in Alphawave IP (LON:AWE) .
Yes - he has, and for that reason I'd argue the likelihood of fraud, which seems to persistently be mooted for some unknown reason, is actually pretty low. You don't own as many shares in a company and buy that many more if you know the walls will come crashing down. I think it is clear he believes in the long term business at least.
Brave Bison (LON:BBSN) results appeared positive yet the market saw fit to sell off. CEO comments suggest headwinds exist in 2023 but I think that is stating the obvious. I topped up yesterday and may add more as I believe management are on the right track.
Positive buy broker comments but they haven’t upgraded their guidance figures, strange.
Alfa Financial Software Holdings (LON:ALFA) strong TU update this morning. 'We have seen excellent revenue growth in the first quarter across all revenue streams with total revenue of GBP27.0m up 20% on this time last year (2022: GBP22.5m). ......The revenue performance in Q1 is tracking ahead of our expectations by approximately GBP1m. Most of that increase will benefit operating profit performance.'
and backed by a very cash-rich balance sheet and major investors.
Great news for Numis (LON:NUM) shareholders... I have a somewhat out of date view of Deutsche but ignoring that, the stock volatility, the price to book etc I think it's a very interesting move. Despite media rhetoric and the failure to win a few recent listings I see this as quite the vote of confidence for UK equities. The market is cheap relative to most others....and there could be a fund raising bonanza round the corner as corporates look to replace debt with equity. Expertise in small / mid cap is very helpful here as venture funding dries up.
It's a stunning premium... at a guess the price must reflect all sorts of staff lock-ins etc needed and therefore "their" earnout is tied into the equity...but that's just a guess. Thinking aloud - maybe it's possible to roll the cash into DB stock and avoid paying tax....have to hold 3 years say. Otherwise they just take the cash and walk round the corner... leaving DB with not a lot...having just paid 2x book. It does make Barclays (LON:BARC) look very cheap....(I don't own, but have in the past) ... and the obvious smaller comp Peel Hunt (LON:PEEL) .
Anyway good news for dear old sleepy cheap UK.
Well done to Graham who has consistently said there is value in UK brokers (and asset managers) and Numis (LON:NUM) in particular.
Deutsche Bank throwing me a lifebelt over my Numis (LON:NUM) investment, will have less to write off if the offer goes through. Same lesson learned over again.
Edit: I couldn't understand how three quarters of the CEO's 2 million-pound remuneration comes from performance, perhaps Deutsche Bank sees this as one reason for the very low share price. Get rid of this and the company might flourish? Anyway, I have sold my share.
Hey-ho Silver
Pleased to see Castings on your long list Paul, good luck getting through that lot! You last did a quick comment on Castings Nov 22 and we did get a few shares while they were on offer, it's now our 3rd biggest holding by value. Pleased and relieved to read this morning's TU with the above expectations forecast.
Morning JASVFS,
Yup a nice update from Castings (LON:CGS) - I've reviewed it above in the quick comments section. My view remains green thumb!
Regards, Paul.