Small Cap Value Report (Fri 29 Jan 2021) - BOO, CARD, BMY, DLAR, XPD, NCYT, SLP

Good morning, it's Paul & Jack here with the SCVR for Friday.
It's catch-up day today, thankfully the RNS is fairly quiet, as it usually is on Fridays.
Timing - Today's report is now finished.
Agenda -
Boohoo (LON:BOO) (I hold) - in exclusive negotiations to buy remaining Arcadia brands.
Card Factory (LON:CARD) - Banks extend covenant waiver by only 1 month. Clearly needs a refinancing. High risk.
Bloomsbury Publishing (LON:BMY) - Well ahead trading update
De La Rue (LON:DLAR) - positive trading update from yesterday
Xpediator (LON:XPD) - positive trading update
.
Jack's section:
Novacyt Sa (LON:NCYT) (I hold) - FY update
Sylvania Platinum (LON:SLP) (I hold) - Q2 update
Boohoo (LON:BOO)
(I hold)
Thanks to reader Alex, who flagged to me last night press reports (initially from Sky, who are usually reliable) that Boohoo (LON:BOO) (I hold) looks set to pick up the other Arcadia brands not already sold - Burton, Dorothy Perkins, and Wallis. A price of c.£25m is mooted. If that goes ahead, in addition to Debenhams BOO would by then have a total of 13 brands. Remarkable stuff.
As I've been saying a lot recently, the ambition of BOO's management is awe-inspiring. They want to build the best eCommerce business on the planet, and I remain of the view that this share should be a core, long-term holding. It's very much GARP at the moment too, with a forward PER below 30 by my calculations.
I've no idea what the short term share price will do, as it's a very volatile share. I see market gyrations as nothing more than background noise. It's the long-term that matters, and I'm very confident that my analysis on BOO is correct.
BOO has just confirmed the press articles, saying -
boohoo group plc
COMMENT RE: MEDIA SPECULATION
boohoo group plc (the "Group"), a leading online fashion group, notes recent media commentary. The Group confirms that it is in exclusive discussions with the Administrators of Arcadia over the acquisition of the Dorothy Perkins, Wallis and Burton (excluding HIIT) brands. These discussions may or may not result in agreement of a transaction. A further announcement will be made when appropriate.
[Paul: my bolding, as usual]
.
Card Factory (LON:CARD)
I previously liked this greetings card & sundries retailer, but it went into the covid crisis with too much debt, hence it went onto my avoid list a while ago, due to weak finances/balance sheet.
As reported here on 15 Jan 2021, the company indicated it would breach banking covenants, and I concluded that an equity fundraising is only a matter of time.
Earlier, I flagged the weak finances here in July 2020, concluding that I wouldn't buy until it's refinanced properly.
The need for an equity refinancing is very much reinforced with an update today -
Banking syndicate has waived covenants from 31 Jan 2021 to 28 Feb 2021.
"Subject to certain conditions" - we're not told what these are.
We remain in constructive discussions with our banks, and have agreed a process to continue to explore a range of potential solutions, with scope for further extensions to the waivers as this process continues.
A further update will be provided in due course.
My opinion - not a good situation. Extending the covenant waivers by only a month, tells me that the banks see this as a problem, and want a solution. What could that mean? A sale of the business possibly? Asset disposals, if there's anything saleable? More likely, a long overdue equity fundraising.
The company is in a weak position, so who knows if there would be much investor appetite for an equity fundraising? I'd be worried that it might have to be done at a big discount. Existing shareholders are in a potentially weak position, so I'll continue to give this share a wide berth.
Conclusion - uninvestable until a big placing has been done, to greatly reduce the bank debt. Why would anyone want to buy/hold before that is done? Historically it's been a good, cash generative business, making high margins, just overloaded with debt & paying imprudently high dividends. Has it missed the boat with online greetings cards?
I'd be happy to take a fresh look at the share, once it's refinanced properly, and if there's a more convincing strategy to grow its online business. As I mentioned here ages ago, there's an obvious, and large gap in the market for some kind of automatic greetings card service online, to send out scheduled cards to customers' loved ones, direct to the recipient, without having to faff about with buying cards & stamps.
.
.
Bloomsbury Publishing (LON:BMY)
Bloomsbury Publishing Plc (LSE: BMY), the leading independent publisher, today gives a pre-year end trading update for the 12 months ending 28 February 2021.
Trading ahead of expectations
This looks really good, and great clarity providing a footnote to quantify market expectations, thank you for this -
Bloomsbury is pleased to announce that revenue is expected to be ahead and profit well ahead of market expectations* for the year ending 28 February 2021.
* The Board considers that the consensus market expectation for the year ending 28 February 2021 is currently revenue of £161.8 million and profit before taxation and highlighted items of £12.1 million.
Consumer division doing well - best sellers are listed.
Academic & professional "continues to make good progress..."
Digital is in demand from academic institutions in lockdown.
Diary date - June 2021 for preliminary results FY 02/2021
My opinion - well done to shareholders, this should be a good day for you.
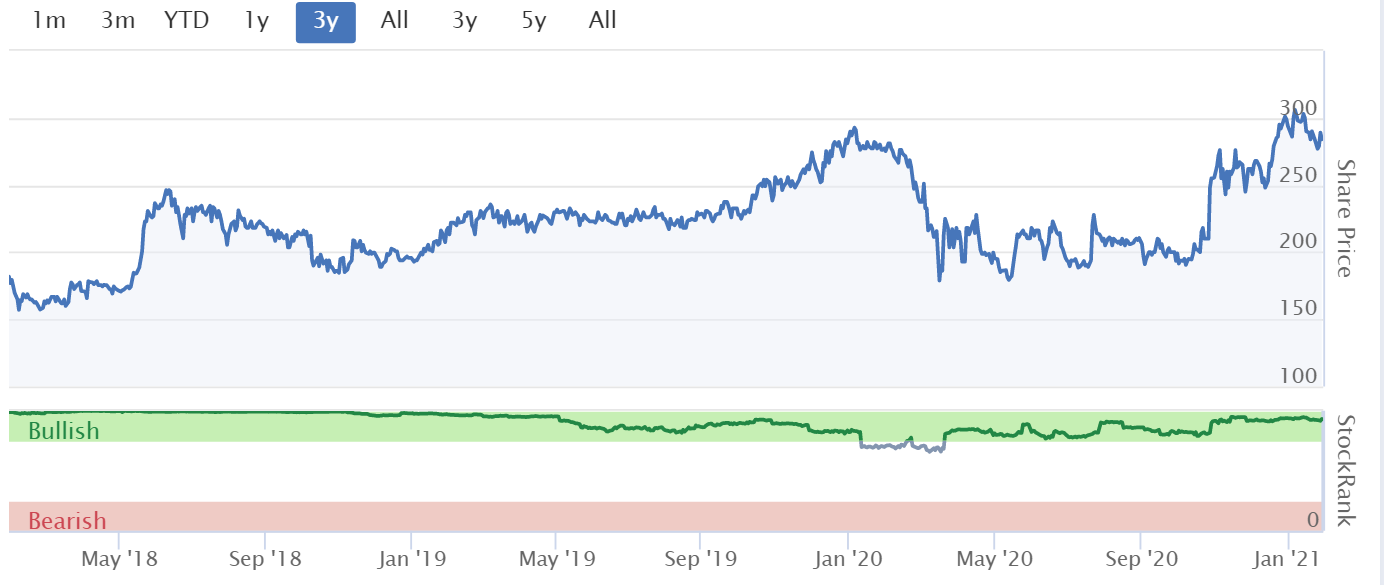
The share price has already surged from flattish around 200p last year, to nearly 300p now, so the question is how much is the good performance already in the price? We're about to find out!
I can't find any broker research, but based on this update, and previous results, it looks as if FY 02/2021 might come in around 15p EPS, suggesting a PER in the high teens, which looks priced about right to me. Note the consistently very high StockRank (green line below). You get a c.3% dividend yield too.
.
.
De La Rue (LON:DLAR)
166p - mkt cap £324m
Trading Statement (from yesterday)
To refresh memories, here are my notes from 30 Nov 2020, on publication of the interim results to 26 Sept 2020. The key issue is to adjust for the £15m p.a. cash outflow required to service the pension deficit recovery. That’s highly material to the valuation, and remember this cash outflow is not accounted for on the P&L. Hence a low PER is absolutely correct. If you ignore the pension deficit, then it means you’re materially over-valuing the shares.
De La Rue plc (LSE: DLAR) ("De La Rue" or the "Company") today announces a trading update for financial year 2020/21 starting 29 March 2020, and developments in its polymer banknote strategy.
Positive trading, ahead of expectations -
The Company has seen positive trading in this financial year, with good progress on the implementation of its Turnaround Plan. As a result, the Board's expectations for adjusted operating profit for the financial year 2020/21 are in the range of £36 million to £37 million, compared with current market expectations of approximately £34 million.(1)
(1). Market expectations are based on the average of published notes from Investec and Numis Securities.
Both Investec and Numis are unfriendly to private investors, excluding us from seeing their research. Thanks a bunch guys. Maybe DLAR should appoint a new joint broker, someone like Finncap, N+1, or Liberum, who do publish good quality research on Research Tree which we can look at.
It’s so ridiculous to stop PIs getting hold of research, since we create the liquidity & set the share price! There’s no regulatory reason for this, since other brokers do publish research, that’s just an excuse to keep the city club nice and cosy, so that PIs are disadvantaged. It’s not good enough. Fair enough if the research is genuinely private, but it’s not. Analysts generally are given privileged access and information from the companies, which is not given to PIs. Not a level playing field at all. As one AIM CEO once said to me, “The broker’s forecasts are really the company’s forecasts”.
Summarising the rest of the update -
- Covid impact has been effectively mitigated
- Outperformance has come mainly from the currency division
- Authentication division - pandemic has caused some delays to securing contracts
- Capacity for polymer production capacity to more than double, with expansion of Bolton facility, operational before end Dec 2021, and create 70 new jobs
- Increasing “investment” in polymer, not clear if opex or capex, or mixture, by £5m, due to customer demand
- Diary date - 26 May 2021, for FY 03/2021 results
My opinion - sounds good. I like the stuff about customer demand. I like investing in companies which are scaling up capacity due to strong demand, as their shares often do well later.
How to value DLAR shares? It’s probably heading for about 13p EPS this year and 15p next year (maybe more?) IF there were no pension deficit, then I would probably be happy with a PER of about 20 as a reasonable price. That implies a share price of 300p (vs current price of 166p). With 195m shares in issue, that’s a valuation of £585m.
What should we take off for the cash outflows into the pension? It’s a £15m p.a. cash drain, so maybe I would discount that to say £200-250m negative valuation? Take that off my £585m valuation of the business, and I get to £335-385m, or 172p-197p per share price target for me personally.
At 166p per share that’s not exciting enough upside to make me want to buy now.
The opportunity here would be;
1) If the business beats performance, since that would all flow through to equity, with the pension cash outflows remaining the same. Hence you could view the pension scheme as providing some fairly low risk leverage to the upside.
2) If the pension scheme assumptions turn out to be better, making it a smaller problem.
Risks are obviously just the reverse of the above 2 points.
Overall, quite interesting, and I’ll keep it high up on my watchlist.
.
Xpediator (LON:XPD)
44p (up 20% at 10:36) - mkt cap £62m
Xpediator (AIM: XPD), a leading provider of freight management services across the UK and Central and Eastern Europe…
This looks really good -
… is pleased to confirm the Group expects to deliver profits for the year ended 31 December 2020, significantly ahead of market expectations. Following higher than anticipated demand for its services in the UK and Europe during November and throughout December 2020, the Group now expects to report adjusted profit before tax of approximately £7.2 million for the year ended 31 December 2020, a 40% increase over the prior year (2019: £5.15 million).
- High demand for freight forwarding & warehouse/logistics, outweighed challenges from covid
- Strong trading in Nov & Dec 2020, helped by various factors, including Brexit stockpiling
- Fuel & toll card business, Affinity, improved as road traffic volumes recovered
- Romanian pallet distribution (“Pall-Ex”) also strong, and above pre-covid levels
- Disposal of ESWD, previously announced, will eliminate £0.35m annualised losses
- Diary date - April 2021 for FY 12/2020 results.
Brexit - sounds quite relaxed about this issue, which has interesting read-across. Confirms my view that this is probably a temporary, fixable problem -
In 2021, as widely reported, transport volumes into Europe have been lower from the outset of the year due to the administrative changes caused by Brexit. In essence, there has been an increase in administration and it is taking time for businesses and customs officials to adjust. For Xpediator, as anticipated this is an opportunity to increase administrative support to our clients to enable them to manage the new environment which in time will settle down.
Outlook - sounds positive -
2021 has begun well across the Group during which we expect to benefit from the permanent £0.5m of cost reductions made in 2020, the first full year of revenues from the Nidd Transport acquired in October and the ongoing uplift in demand for our services across the Group."
My opinion - this sector doesn’t interest me at all. That said, I’m really impressed with today’s update from XPD. So its shares might be worth a closer look, if you want to invest in a haulage group.
I’d probably be more interested in looking at Wincanton (LON:WIN) or Compass (LON:CPG) Clipper Logistics (LON:CLG) than something this small, as their shares are more liquid.
.
Jack's section
Novacyt (LON:NCYT)
Share price: 992.5p (-7%)
Shares in issue: 70,626,248
Market cap: £701m
(I hold)
There has been a long silence from this Aim-listed diagnostics company, and that gap has been filled with daily speculation regarding the nature of these results. Their release was always going to cause some trading action, one way or the other.
One of the key challenges for Novacyt Sa (LON:NCYT) , which has grown so quickly, is managing expectations.
Shares are down today, but the fact remains that NCYT has worked its way into a great position in a market that has been totally transformed by Covid. Just how long Covid testing lasts, and what more normal diagnostics trading looks like on a 2-3 year view is an essential part of the value equation here.
That future is uncertain and it’s hard to have a strong view on it at this moment. I do suspect there’s a chance we are underestimating how long testing will be around, but I’m no expert. Who is? Hence the dilemma re. NCYT valuation.
What’s more concrete is that for now Novacyt is a testing cash cow, generating fantastic year-on-year sales, margin, and profit growth as its PCR (and soon other) tests are deployed in the frontline against Covid.
Beyond that, how management allocates the capital generated from its Covid testing windfall will be an important driver (or destroyer) of value.
This is a key risk going forwards and is far from a slam dunk. Management has hinted at a transformational M&A strategy and, while the company has done an excellent job over the past year, that is still a very different strategy to what has generated their success so far, and one fraught with execution risk.
Given the above uncertainties, I can understand why the market might apply a steep (and forever shifting) discount rate to Novacyt. Ultimately though share price performance will track earnings - and if you think the outlook is good here, then you should be able to hold through short term volatility.
Still, the shares are down this morning, so let’s take a look at the full year statement.
The picture is of sequential progress, with H2 figures trumping the transformational first half across the board. Just how many more periods there are like this is important to the valuation.
Highlights:
- FY Revenue increased by over 20x to €311.6m (£277.0m) compared to €13.1m (£11.5m) for the full year of 2019,
- H2 Revenue of €239.2m (£213.7m) compared to €72.4m (£63.3m) in H1 2020
- Gross margin above 80%,
- EBITDA profitability for the full year above €210m (£187m), with H2 2020 EBITDA above €161m (£143m) compared to €49.4m (£43m) in H1 2020,
- The Company's cash position at 31 December 2020 was €101m (£91.8m), compared to €1.8m (£1.6m) at 31 December 2019 and €19.7m (£18.0m) at 30 June 2020. This follows significant investment working capital to meet product demand and the paydown of all outstanding debt,
- Investment in pipeline of next generation COVID-19 tests and acquisition of IT-IS International.
Business clearly continued to accelerate during the second half of the year, driven by the global commercialisation of NCYT's COVID-19 product portfolio ‘and has resulted in the rapid transformation of Novacyt into a leading European integrated molecular diagnostic player.’
NCYT has expanded its global presence, with the UK, Middle East, Germany and US being its four largest revenue generating markets. It has secured significant contracts with national governments, including two with the Department for Health and Social Care in the UK (DHSC), as well as with other national non-government organisations, for the supply of its COVID-19 products.
And for now at least this is high-demand, high-quality business with conversion of EBITDA to free cash flow before acquisitions to be close to 80%.
Holders are still waiting for DHSC contract announcements. In the meantime, Novacyt has diversified its revenue base with the introduction of ten new products and has hired 124 people, with significant increases across manufacturing, sales and R&D operations.
More senior hires have also been made: James McCarthy was appointed as CFO ‘to support the Company as it enters its next stage of growth,’ while Anthony Dyer has taken on a new role as Chief Corporate Development Officer to focus on organic growth and acquisitions. Guillermo Raimondo is now the Chief Commercial Officer and was most recently Executive Vice President Global Marketing & Sales at Siemens Healthineers, ‘responsible for $4bn of global revenues’.
Full year results are expected in April 2021.
Conclusion
Demand for NCYT’s COVID-19 product portfolio remains strong and the directors believe this will remain the case ‘throughout most of 2021, with continued conversion of new opportunities, including a number of planned product launches, and the expansion of the Company's VersaLab™ service to support private sector testing of infectious diseases, initially focused on COVID-19.’
So on that note, I would pencil in one or two more ‘gold rush’ periods before considering a gradual normalisation across 2022 as the base case. Discussions to extend NCYT’s DHSC contract are ongoing, and a development here would clearly be price sensitive. So I would expect further short term volatility going forward.
The question really is of intrinsic valuation, and what is priced in at NCYT.
My current view is that the market remains overly optimistic regarding the Covid timeline and is attaching too short a lifespan to testing demand. I’m simply basing that on Hofstadter’s Law. This notes the tendency to by overly optimistic in the face of complex tasks:
It always takes longer than you expect, even when you take into account Hofstadter's Law.
It’s something I’ve found applies quite often.
If Novacyt can win the already flagged DHSC contracts, and then evolve its testing away from large contracts to smaller and more frequent transactions across various geographies to a private client base, that could be a promising mix.
Organically, Novacyt will continue to invest in its commercial infrastructure to deliver new products, a revamped R&D pipeline, and establish a direct sales force in key markets in the US and across Europe. It is also open to acquisitions.
I sympathize with NCYT management - the group’s remarkable transformation has attracted a certain level of expectation.
But there is also no denying that material aspects of the investment case make it quite ‘binary’ - DHSC contract news flow, the commercial lifespan of Covid testing products, the types of companies NCYT looks to acquire, and the prices it offers for them. All of these things are material uncertainties weighing on the share price.
It’s a very hard stock to value for those reasons.
I continue to think what NCYT has so far achieved is impressive - £200m revenue in half a year, with more to come. But there’s no doubt this is firmly in the ’high risk’ category given the wide range of possible trading outcomes over the next 12-24 months.
Sylvania Platinum (LON:SLP)
Share price: 103p (-1.9%)
Shares in issue: 272,533,615
Market cap: £280.7m
(I hold)
There’s a Liberum broker note out there (available on Research Tree) which proposes that the price of Rhodium - one of the platinum group metals (PGMs) Sylvania Platinum (LON:SLP) produces - might increase from $20,000/oz to $100,000/oz, while SLP’s current share price implies just $4,000/oz.
Now I didn’t get the chance to properly dig into that note, but that spread of potential rhodium prices is useful to bear in mind. It’s a key input into the valuation of SLP and suggests potentially material upside if EV demand and the rest really does make the rhodium price pop. That cuts both ways of course - if spot prices go down, then so will Sylvania’s profitability.
SLP isn’t really a miner, although it does have some exploration assets in South Africa’s Bushveld Igneous Complex, where its operations are located. Most of its production comes from extraction of PGMs from chrome dumps and arisings.
The group’s earnings are heavily dependent on PGM spot prices, therefore so are brokers’ forecasts.
Nevertheless, SLP’s forecast valuation metrics remain striking, even with the share more than doubling over the past year.

These are quarterly figures referencing quarter-on-quarter progress.
- Sylvania Dump Operations (SDO) declared 18,363 4E PGM ounces in Q2 (Q1: 17,972 ounces);
- SDO recorded $43.7m net revenue for the quarter (Q1: $41.5m);
- Group cash costs increased 3% in ZAR from ZAR11,818/ounce ($699/ounce) to ZAR12,153/ounce ($780/ounce)
- EBITDA of $29.1m (Q1: $28.8m);
- Net profit of $20.3m (Q1: $20.1m);
- Cash balance of $67.1m (Q1: $60.9m) after payment of dividends, royalties and income tax.
Perhaps holders are looking for a little more growth in these figures, but even if you assume no growth beyond these levels, you still get FY net profit of around $81m (£59.3m). Divide that by the shares in issue and you get an FY21 EPS estimate of 21.7p per share, which gives a forecast PE of 4.7x.
So that’s still quite cheap - and note brokers are forecasting comfortably higher EPS than this.
Opportunities include:
- Ongoing circuit optimisation at the new Lannex mill and spiral upgrade will improve processing efficiencies and profitability;
- Mooinooi chrome proprietary processing modifications and optimisation project remains on track to commission during Q3; and
Conclusion
The Group remains debt free and continues to maintain strong cash reserves to allow for maintenance and growth capex. This includes not just its dump operations, but also upgrading its exploration assets.
SLP remains on track to achieve its target production of approximately 70,000 ounces of PGMs for the year. Financially the company continues to benefit from the stronger PGM basket price in recent months. There is also the expected ‘windfall dividend’, which is set to be decided in February.
Meanwhile, SLP has multiple operational opportunities. The Mooinooi chrome proprietary processing modifications and optimisation project should improve chrome recovery efficiency and is expected to be commissioned towards the end of Q3 FY2021.
The proposed MF2 expansion project at the Lesedi Plant to construct a new secondary milling and flotation module to improve the upgrading and recovery of PGMs has commenced and is scheduled to commission towards the end of FY2021.
What’s more, the company's ‘specific fine chrome recovery research and test work initiative,’ started in late 2019, has identified a circuit configuration and technology that enables the recovery of previously uneconomical dumps.
This could enable the Company to re-treat low PGM grade tailings resources and extend the operational life of PGM operations at selected sites.
And SLP also has exploration assets:
- Volspruit Platinum Opportunity - Detail design for the Permitting Applications has been completed and specialist work for updating the EIA and Water Use License will commence during Q3. The final test work report is expected during H2 FY2021.
- Northern Limb Projects - Specialist consultants have completed initial studies and identified specific higher-grade portions that could be attractive for shallow, low risk open cast extraction and PGM processing. A concept level mining study for the project has been scoped and will start during Q3 and continue until late 2022.
- Grasvally - The sale of Grasvally to Forward Africa Mining for ZAR115m is still ongoing.
It’s steady as she goes operationally and the shares continue to look cheap across all forecast metrics. But, as ever, the big driver here are the PGM spot prices. If these continue to go up, SLP should do well but if the increases are unsustainable then there could always be a share price correction.
I can't believe it's Friday, this week has absolutely flown by, in a blur of RNSs and US market craziness. Fascinating times, but there are so many signs of financial mania, let alone exuberance about, that it's becoming rather worrying. Let's hope when the bubbles burst, they don't take down the good stuff with them.
Have a relaxing weekend!
Best wishes, Paul & Jack.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

138 comments
As a Card Factory (LON:CARD) holder, I find myself in a constant state of indecision about it. It was therefore, a very useful exercise to follow the link to the presentation and I would recommend anyone in a similar state to do so, albeit that it was some months back. https://webcasting.brrmedia.co...
I was impressed by the transparency and the sheer volume of factual, research-based information being shared. These chaps seem to have their finger to the pulse and, although they acknowledge the general slide of the sector over time, appear to be prepared to think laterally while not wasting what they have gained historically.
Now we have a vaccine rollout, giving some hope to the possibility that safer high street footfall will rise as Spring arrives, particularly for the largest card buying demographic, it would seem odd to write this company off. I find the fact that they print 75% of their cards reassuring.
Paperchase, a modest competitor has gone but that would seem to be an advantage to Card Factory (LON:CARD) rather than an arbiter of doom. Time will tell, but I propose to hold.
Very useful Tango, I share your indecision and like your analysis. Will listen to the webcast. One thing I am certain of is no Moonpig for me, even at half the price.
I think the problem with all this market frenzy is that we all know these companies will end up being priced at their true value, which is likely to be closer to the value ascribed to them by the shorters than their current prices.
While the shorters will have had a fright the ultimate losers will be the innocent (arguably also greedy / dumb / uneducated in markets) that are joining the party late.
Yes and no.
Don't forget the shorts have to buy the shares back to give to their original owners, and even when they've bought 100% of the company stock (for GME, other situations are different), they're still not finished buying.
In theory this whole thing could unwind and only the shorts lose. Not going to happen in practise, granted, but being the greatest fool is always a risk at the top.
Presumably if shorters borrowed 150% of stock to short there won't be enough shares around for them to close positions. o dear. No doubt thats too simplistic. Is it possible to borrow more shares than exist? As I have said before this was a mechanism designed to protect peoples investment, not to help sharks move in and create carnage. As usual good intentions end up getting abused by lack of control of regulators. Now its left to individual brokers to lay down the rules it seems. IGG the latest to ban purchasing shares in certain stock of their choice.
Just received this from IG by email:
“Due to the recent extreme volatility, and in order to prioritise the service we give our existing clients, we are not allowing any new positions to be opened on the US stocks GameStop and AMC Entertainment.
These restrictions apply to all IG accounts, and will be reviewed regularly. You will still be able to close any open positions that you have in these stocks. Any orders that you have already placed on these two stocks will remain.
In addition, if you have any spread betting or CFD positions open on either stock, please be aware that the margin required to keep them open will increase to that listed below from 4pm (UK time) on Monday 1 February. Please ensure that you have enough money on your account to cover the margin requirement.
Stock New margin
AMC Entertainment Holdings Inc 100%
GameStop Corp 100%”
Funnily enough my youngest son also bought Gamestop about 2 weeks ago. No idea on what basis. Anyway he was chuffed that has now wiped out all his losses in one go. I thinks a great way for the younger generation to get into trading . I think many of these guys and girls on Etoro are buying stock following 'super investors' who have their own pie charts depicting their success rate. I think they know it is nonsnsense and a bit of fun, and most of all a kick up the backside to the establishment . How exactly is it possible that hedge fund can borrow 150% of a companies stock? They deserve all the losses they get. Shorting has been around forever but I thought the idea was to 'hedge', not make rampant profits by clubbing together in packs and destroy a company by gross manipulation.
How is it possible that a stock can turnover its whole issued capital several times a week? Once you've worked that out, it's not much of a stretch to work out how you borrow more than the float.
HI
My third post
in two years watching and learning , so many educated posts.
Loving this
Re Gamestop.my son of 25 years has bought.
It started out as him wanting to make money, but has developed into he does not care if he loses the 1K invested.
Why because he explained to me ,this is the small guy fighting back.
He explained to me how Robinhood is now toast, and how the market makers are trying to manage/manulipate the system.
There is so much anger out there in relation to the banks and 2008.
The motivation is pay back
I am sorry ,if as an old man |I am unable to post this correctly
(New Post) Where but this is part of the new democracy.
Protest vote
We the people know/believe we are getting shafted
Who to blame?
Hence Brexit
Hence Donald Trump
I personally hope, as explained to me ,the Pi can destroy the establishment.
And the implications re investments and short sellers are?
Best wishes
I think the danger here is that people believe the hype they are being fed , sometimes the hype may have basis in fact but i suspect alot of the time it may partly be the kinda of crapola that trump would get in his head as being real life when its anything but.
I suspect very few of these moral crusaders will nag around if they lose money more than once or twice.
I was randomly watching a you tube video last night with one of these guys telling the whole world that it was clear market manipulation directly brought on by the hedge funds with their inside buddies just because some companies decide stop people opening new trades whilst they let them close out what they had.
Does what he is saying have an basis in reality - probably not unless some evidence can be provided to back up this assertion. Much more likely the dealing companies are protecting themselves risk wise and possibly even protecting their customers. Perhaps this could have created a false market temporarily which helped the hedge companies - but i simply don't believe the conspirecy theory until i see some evidence. It woul make sense for the SEC to look into this as there is an element of logic that allowing closure of positions freely that are mostly sells without allowing opening positions to be taken that are mostly buys does seem slightly open to abuse.
Perhaps by the time your son gets to 50 he will realise it is a dog eats dog world and that aint ever gonna change and also sometimes what you see and here may be a pile of baloney.
I don't really know the detail ref Robin Hood but it would be bizarre if they as a low cost upstart that has helped bring trading to the masses are then brought down by the masses incorrectly thinking the company is siding with the hedgies to screw them over. Sounds like an episode of Robin hood got mixed up with stargate (used to love their altrenate reality time travelling episodes)
Hey ho if nothing else the real Robin Hood Society has gained a legion of new fans - their twitter followers have gone up 100 fold in 24 hours or so (update another 50% overnight) . Perhaps that indicates the level of saviness of your average 25 year old internet share dealing freedom figter.
Well at least as proper capitalists (gotta laugh) the Robin Hood Society are making the most of their new found fame - their latest tweet welcomes their new friends then is straight onto the amazon us link so these new friends can spend their money on some nice Robin Hood related goodies - well one kindle book anyway.
I don't really know the detail ref Robin Hood but it would be bizarre if they as a low cost upstart that has helped bring trading to the masses are then brought down by the masses incorrectly thinking the company is siding with the hedgies to screw them over.
It's because the masses don't have a clue about how markets really work. They're the 21st century version of young software developers who are lost without an API.
A lot of them are trading using derivatives - effectively borrowing money. Robinhood has to be able to make those trades good if the traders can't. To do that it needs to have sufficient funds at hand and it ran out.
People need to go do their own research rather than posting stupid conspiracy theories.
I'm all in favour of people being allowed to do whatever they want with their own money, no matter how crazy. But when they start doing it with someone else's money there's trouble lurking around the corner.
timarr
And the final position on this is that GameStop is still worth the same as an underlying investment - far, far less than the mcap. (Perhaps if they are sharp they can do a placing at an absurdly inflated price and use it to reinvent themselve, but that's unlikely). The people who got this started will be long gone, but the unfortunates who were persuaded by their rhetoric to join the game late, often with leverage, are going to end up out of pocket. And while many may be saying they don't care if they lose it, many will, or can't really afford it and have no idea what's inevitably going to happen.
I don't know much about $GME but I did read they were planning to close some store and concrete more online sales.
" GameStop revealed it plans to close over 1,000 stores by the end of the fiscal year, which ends on April 1, 2021."
Yes I did think they maybe able to a placing but I doubt it but who knows, maybe the PIs will lap them up.
A lot of these problems have been caused by the shorters themselves, by over shorting and in order for them to close their shorts, they had to buy the shares that they had borrowed, thus further increasing the share price.
I think some of rules on shorting should change. But hedge funds will probably change anyway as they have been caught with their pants down. I gather they are now studying social media sites to see what is happening.
But hedge funds will probably change anyway as they have been caught with their pants down. I gather they are now studying social media sites to see what is happening.
I wouldnt even necessarily say they have been caught with their pants down - they just probably do the maths and take the risk - it has to be occupational hazzard that eventually they will take a hard beating somewhere - thats the game of shorting. Its easy to say they should have seen it coming with hindsight - being blunt if anyone had posted here on monday saying there is mass grouping against the hedge funds where we are going to take this loss making useless business and turn it into a $20 billion bemoth that will destroy the hedgies and we can make some great profit too - i would have laughed at them and thought they were mad :) .
Well I don't think they have been stung like this before. Sure shorts can go wrong but I don't remember anything like this.
I heard they disregarded the information and thought the PIs could not move the market, looks like they got the maths all wrong and had to close their positions at huge losses.
Stopping platforms trading certain shares, I think is wrong, that is manipulating the market, there probably will an investigation into that. Even that did not stop some of these shares from soaring again on Friday.
The danger now is this could escalator into something much bigger.
Stopping platforms trading certain shares, I think is wrong, that is manipulating the market, there probably will an investigation into that. Even that did not stop some of these shares from soaring again on Friday.
was it not the platforms themselves that stopped the trading presumably to (a) either protect themselves (b) protect their customers (c) market turmoil dicated they didnt have access to normal hedging or ability to buy underlying equities in which case they simply can't offer something they don't have for sale. I would suspect any platform will always as part of their t&c's make it clear they are under no obligation to take any future trade that is requested - therefore i would default to this story being a made up conspiracy theory and nowt else unless i see some evidence of foul play. The swings were so wild in gamespot i am almost surprised anyone was able to do any trading if the platforms were simply trying to maintain a neutral ish book which i am guessing can't have been easy.
On associated thought here though is could ab event like this cause a company like plus to take a hit big enough to materially affect their market cap.? The fact they have material profits/losses on trades naturally makes me wander if they could ever be caught with their pants down taking one side of the book?
Not sure, I read that they were warned but yes also I read that had to raise money to fund all the trading.
But if investors are buying then they should have funds? Maybe they have lent all the cash out?
Perhaps if they are sharp they can do a placing at an absurdly inflated price and use it to reinvent themselve, but that's unlikely
No professional investor is going to put cash in at these inflated prices but with so much dumb money about if they tried to get a placing away at (say) an 80% discount to the insane price they might get some takers. Why not try - they're effectively bust anyway?
Buying with leverage though ... well, I wonder. Individual losses will ultimately be capped by personal bankruptcy but the platforms are exposed to a very unusual set of risks. I wonder about Plus500 (LON:PLUS) and their lack of hedging - how exposed are they? And I look at the Ig Group (LON:IGG) takeover of tastytrade and wonder where the bodies are buried?
Still, many of the people involved will learn valuable lessons. I have a framed Marconi certificate I look at before I buy anything. Caveat emptor.
timarr
"Why not try - they're effectively bust anyway"
Roaring Kitty doesn't agree. Look at the date before anyone claims it's a response to the last couple of weeks.
100%+ short interest in GameStock stock (GME) – fundamental & technical deep value analysis - YouTube
Roaring Kitty doesn't agree. Look at the date before anyone claims it's a response to the last couple of weeks.
Well, he might be talking his own book there ...
Whatever it's worth, it ain't $22 billion.
timarr
It sure ain't worth $22Bn, but it's not 'effectively bust' either according to the video.
It sure ain't worth $22Bn, but it's not 'effectively bust' either according to the video.
According to the video.timarr
Well, all we can say is, he's put up more data about the position and why he's long than you have saying they're effectively bankrupt :)
I imagine he has significantly more motivation to do so :-)
timarr
"And I look at the Ig Group (LON:IGG) takeover of tastytrade and wonder where the bodies are buried?"
Its worth remembering that Ig Group (LON:IGG) s core leveraged products (CFD's & spreadbets) are currently not permitted in the US.
Operationally, the US business being acquired by Ig Group (LON:IGG) appears low risk on the basis that it is classed as an 'agency only broker'. This is evidenced by its low regulatory capital requirement : 'as at 31 December 2020, tastytrade had a regulatory capital requirement of $500k.'
So Elizabeth Warren has written to the SEC about Gamestop et al. Its a long letter and very much written with the 'little guy' at heart and painting the big boys as greedy manipulators.
https://twitter.com/SenWarren/...
See page 5 in particular.
What steps will the SEC take to ensure that prices better reflect the fundamentals?
How can this possibly work? and what would the ramifications be. From my perspective pretty much the entire US stock market is over priced. If this becomes a thing there could it become a thing here? If so who the hell decides what price reflects the fundamentals?
Like her or not she has got clout now.
Just pondering over another glass of wine (I hold)
:)
Communist style stock markets? Govt sets the fair price... everyone gets 1 Tesla share a week...
Hi I use Interactive Investor competitive price wise but dreadful platform layout like something from the 1980's.
Oh dear, and I'm about to be moved from the Share Center to Interactive Investor. Perhaps ii will adopt the best parts of SC tp replace the bits that worry you clarea. As always, living in hope, Silver
IKBR - fast, liquid and cheap but need to play with for some time. Use it for US shares with dollar account. If a chartist then use Tradeview graphically brilliant and gives a synopsis of all the strategies. End of the day its a full time job and then some.
Hello Paul. Thank you for your superb coverage, your incredible stamina and patience, among so many other things. You, and the reader comments you stimulate, are compulsive daily reading for me. I am interested to see the Boohoo (LON:BOO) brand expansion plans today. Given your previous history in retail clothing (and clearly your continued interest in it) would you be prepared to comment on not just the quantity of brands they plan to take from Arcadia but also the quality of these brands versus the ones that £ASOS is planning to take. My first thoughts are that £ASOS are getting the quality - though I would like to be proven wrong as a holder of Boohoo (LON:BOO), my largest holding, but no £ASOS. Thanks in anticipation.
My own, not Paul, view was different. When I realised they would bid for Arcadia brands, I hoped they wouldn't include TopShop etc. I saw it as too big, and likely too expensive, to be a good profit opportunity. These brands are niche, aimed older; they would benefit from a lot of refurbishment but visibility and awareness in the target market is already there and doesn't need to be created from scratch; and it looks as if they will be cheap enough to warrant a bet. They might be tired, but seem a good fit for the Debenhams demographic.
ASOS already had a major interest in Topshop through their website, so are in a better position to pay up (better idea of how to make money from them and don't want to lose the business).
Paul I know it is not about a small uk company but i am very interested to hear your thoughts on Gamestop if you have time? I think these young people sitting in their front rooms are asking some interesting questions and frankly that "^£& bleating about how unfair it was from his ivory tower just incensed me!!
Saw an amusing tweet about it yesterday along the lines of "Oh no the wrong sort of people are manipulating the market"
Unclear whether that statement refers to the Robinhood Redditors, the short hedge funds, the trading platforms, or the clearing houses!
im having same problems with ig -2 days of constant outages
also try plus 500 which by the ay is very cheap and benefits from all this volatility
I moved to IG from IWeb but they are also experiencing an outage today.
Same here, I have decide to slowly close my account as I exit and move to Spreadex.
ive heard from friends that interactive broker is good
But do they have an ISA?
I looked at their reviews and they were pretty mixed.
If your a trader the IBKR great for US. Don't know yet about UK - need to buy shares in both and sell at same time and check the spreads etc. ISA is not trading so go to AJBell or numerous trusts and forget about it.
ISA is just wrapper so you don’t pay any capital gains or dividend tax, so I don’t understand your comments. You don’t have to bother about tax forms either.
Trusts?
Can anyone recommend a trading platform?
I've run out of patience with IG - third day in a row it's completely unusable.
Yes I was just about to post IG down again, every time the US markets open it crashes. I lost some orders as well on Wednesday, they said do them again, but it's too late the prices had recovered.
HL was also down one day as well. People moan about HL but they are a lot better than IG recently.
Thing is, I now don't dare trust a trade even if it is up, what if it crashes and I need to exit?
So much volatility, and so little chance to do anything about it.
Maybe time to short IGG?! (not a recommendation, said in jest not seriousness).
However, in seriousness, I just checked their Twitter feed. And it is a feed.....
IGG 910p what 8 days ago... 750p at the close.
A 17.6% drop.
I think its fair to say that I and fellow shareholders are well p1ssed off with IGG today.
Also... I seem to remember that Ig Group (LON:IGG) does not hedge all its risks from being the counterparty to CFDs and spreadbets? Can anyone confirm?
So it's probably exposed to GameStop and other volatility this week.
I thought we had established that IG Group (LON:IGG) DO hedge their SB positions (although I could be wrong) - it is know that Plus500 (LON:PLUS) do not always do so.
FWIW - IG would not let me short $GME earlier in the week and if they had lots of uncovered longs there would have been no reason for them to not allow shorts.
If you can get to MyIG / dashboard, try opening your account with the "Use old platform" option - it seems to work much better,
Just checked again - I can get in using old platform, but not if I use the new platform.
Can't even get in. Where is the Old Platform option, not seen that?
Here in the drop down :-
Sorry - forget it - it wont pull up a deal ticket, no open positions at the moment so cant check if they can be closed.
Thanks but I don't have that option, only Open new platform, there is no down arrow on the right on my screen. I have only had my account for about 2 weeks.
It is working again now.
100% agree with the sentiment. I have the exact same situation. To think I was considering buying shares in them £IG.!!!
We need to vote with our feet.
But go where? In the UK there are limited choices, even the more expensive platforms are having problems.
I'm surprised that some people are reporting problems with IG. It's been working perfectly for me in recent days. Although I have been simultaneously logged in to my account on 3 computers, so maybe I'm hogging their bandwidth lol!
Paul, most of the problems are between 2.30 - 3.30 GMT, after the US markets open, at other times it works ok.
Last 3 days it has been the same, other platforms were having issues on Wednesday as well.
Even my limited US orders were all cancelled which was very annoying.
As a new user I’m not at all impressed. Try phoning them up doubt you will get through in under an hour.
herbie,
I think you need to be careful that you and Paul are not talking at cross purposes i.e. Paul may be using the spreadbetting platform and you may be using the sharedealing platform? As I mentioned elsewhere on a recent thread, the IG share dealing platform is garbage and the customer service even worse. They can't even do basic stuff like pay dividends on time because they're not a real broker and need to use Citigroup as a sub-custodian to do the groundwork for them.
I'm about to move from IG to Schwab for US dealing and will move my ISA to another broker in the new tax year.
All the best, Si
Yes I’m using the share dealing or ISA platform however the whole site was down, so it does matter which platform I’m trying to use.
It is working fine but after the US markets open you just get error messages when you try to do anything.
I have only just started using IG so I don’t know if this is just this week or happens often, I did not have a problem last week.
I was using the spreadbetting platform.
Speculation, not fact time.
If Paul’s has been fine and some of us smaller investors have been having issues, it might be they’ve prioritised bigger players and throttled those who deal in hundreds and low thousands over those who deal in significant sums.
Makes sense if that is what happened but they need to be careful, how do whales eat if there are no schools of little fish? Also worth saying, we might only be seeing the symptom, the cause might be some bottleneck outside of IG’s control.
Yesterday on £IG site there was a warning about shares like $GME and $AMC that the margins could be increased to 100%.
IG did send me an email on Wednesday saying the problems was because of an US broker.
If this continues I will moving elsewhere. I only have a small account with £IG.
Just read this "Charles Schwab cited "heightened trading volume and volatility across our entire industry" and "challenges with online functionality" at times."
So it is not just £IG that is having problems.
No idea whether they are suitable for your needs but the recent Cmc Markets (LON:CMCX) interim results state:
"At CMC our goal is to constantly provide a superior and unrivalled online trading experience for our clients and through this period of market uncertainty we have provided a CFD platform with 99.97% uptime. We look to lead with quality and in the period have been able to on-board a record number of high quality clients and deliver significant growth across all of our key businesses."
£CMCX seems to be working very well, I use their platform and have had no trouble.They also had good IT performance early 2020 when IG and other spread betters suffered. I may be biased though as I am long the stock!
CMC Markets (LON:CMCX) seems pretty good platform, but I can't see anything about ISAs, do they have them?
Spreadex worked fine today when Ig was down.
As a random, I know that Graham (don't talk about the EX) was a long term holder and did a lot of stuff on here and his own website on this thoughts on Ig Group (LON:IGG) Cmc Markets (LON:CMCX) and Plus500 (LON:PLUS) including hedging strategies.
I no longer hold, having watched it go up and down three times this year and obviously being me did not sell on any of the peaks or anywhere near. I finally sold (about £8.10 from memory) with a small gain and the dividend (reinvested) so failed on my Buy High, Sell Low, Buy back Higher, Sell even Lower strategy. But right now with the trading issues and the purchase I am happy to be on the sidelines and wait to see what happens.
And maybe I can buy back at <£7???
Tommy
&IGG I cannot understand why IG have no customer service on these occasions. They didn't anwer the phone, Tweet or chat for an hour or two after the site fell over.
With thanks again to alibx11, who posted the link on ADVFN, this looks like it may help Boohoo (LON:BOO) be more efficient operationally, provided there is a smooth implementation...
https://www.retailtimes.co.uk/...
Thank you Jack for the great note.
Whilst you mention the Cash balance of USD67.1m, up by $6m in Q2 after payment of Dividends (5.9m), Tax for HY of 15.1m plus Cap Ex and Share buybacks, another important number is Contracted Assets of circa USD60m that is almost as good as Cash and has grown by USD32.1m in the last 6 months, reflecting the growth of the business following shut down last April/May.
Whilst the PE is just over 4, if it is adjusted for Cash and near Cash items it is a lot lower.
Due to the growing supply deficit, higher environmental standards etc the case for Rhodium is clearly to the upside.
£MARS "confirms that it has today received an unsolicited non-binding proposal from Platinum Equity Advisors, LLC ("Platinum") regarding a possible cash offer for the entire issued, and to be issued, share capital of Marston's".
No longer holding these. Sold when the current lockdown was announced. Could not understand why the price was so firm. There is a lesson there!
Intriguing indeed - had me confused with SLP for a moment - so much buzz here today about Platinum - but seriously having read the RNS theres no indication of how much money is on the table - yet surely a figure must have been mentioned - why is it not being given ? And what would these guys do with MARS - combine it with GreeneKing or what...?
Marston's (LON:MARS) Yes its rather strange to be honest. It seems to have escaped the notice of many. RNS released late morning. Friday, red day, brokers all struggling. I cannot think they have offered just a few pence above the current price so I have taken a punt hoping the offer will be 120p or something...or a friendly bidder will pop up.
The Americans trying to buy up our cheap British assets. The price is only up 10% today which may well indicate Mr Market is dubious the bid will succeed.
Paul: "I’d probably be more interested in looking at Wincanton (LON:WIN) or Compass (LON:CPG) than something this small.."
Perhaps you meant to refer to Clipper Logistics (LON:CLG) instead of Compass.
cmpeckham,
Yes, thanks, you're right, I put in the wrong ticker. Will correct it now. Thanks for flagging!
Regards, Paul.
A comparison of Wincanton (LON:WIN) (I sold) with Clipper Logistics (LON:CLG) (I hold) and if I was really cheeky Dx (group) (LON:DX.) (I hold) might make interesting reading Paul but only if you feel inclined. Some outstanding commentary coming from you and Jack in these volatile times which I for one really appreciate.
Hi Chris,
I think we've got enough work on our plates without you dreaming up additional projects for us to do lol! ;-D
Best wishes, Paul.
Couldn't argue with that Paul. In any case on reading through them just now, there are enough past discussions on that transport trio to form a view, without adding more. Have a great weekend and wrap up if you are taking Paddy for a stroll on the prom.
Sylvania Platinum (LON:SLP) Jack thanks for your insights on Sylvania. With regard to:
“It’s a key input into the valuation of SLP and suggests potentially material upside if EV demand and the rest really does make the rhodium price pop. That cuts both ways of course - if spot prices go down, then so will Sylvania’s profitability.”
I have read the note quite carefully (Sylvania Platinum (LON:SLP) is my fourth largest holding) and unless I have misunderstood, Liberium’s bullishness on the Rhodium price (and therefore the outlook for Sylvania) is not directly to do with EV production but that ICE cars are currently much more profitable that EV’s, that there is a shortage of Rhodium. Rhodium is used in catalytic converters and that therefore:
- car manufacturers will want to go on producing ICE vehicles while they can/there is a market for them, which will be for along time (there are a 101 EV charging points in Sub Saharan Africa 76 of which are in South Africa. France has 13,341 for example http://www.electromaps.com/en/... ).
- this will lead to increased demand for Rh, which will lead to price increases in Rh. Demand already exceeds supply.
- because Rh is “relatively” small proportion of the overall cost of the vehicle Rh would have to increase to $100,000 before it caused them to switch to making EV’s (I find this argument weak)
- because there is a general world move to increase the severity of emission controls, we will see an increase in demand for rhodium.
The note covers a lot ground (it runs to 26 pages) and many of the bear cases for Rh price, which I won’t repeat here but the note is available at
https://www.research-tree.com/...
They further note that the projections for SLP is based on a $4,000 Rhodium price. Current price is $20,000.
I remain convinced that Sylvania is undervalued and that its Stockrank of 99 is completely justified.
regards
Michael
Thanks for the summary Michael, very useful. I hope to give the note a proper read this weekend.
Best,
Jack
Thanks Michael - really useful PoV. Sylvania Platinum (LON:SLP) is now my biggest individual (stock) holding at circa 8%. At 4 times this year's predicted earnings and with almost 50% in the bag, I will certainly continue to hold.
Boohoo (LON:BOO) I hold. I liked this from the FT article this morning:
“Sir Philip acquired Arcadia for £850m in 2002, a year when Asos’s revenues were just £4.1m and Boohoo did not yet exist.”
As a quick lighthearted aside, I read the following in the additional information section of a holding RNS yesterday PM:
Threadneedle Asset Management Limited is wholly owned by TC Financing Limited, which is itself wholly owned by Threadneedle Asset Management Holdings Limited, which is itself wholly owned by TAM UK Holdings Limited, which is itself wholly owned by Threadneedle Holdings Limited, which is itself wholly owned by Threadneedle Asset Management Holdings SARL, which is itself wholly owned by Ameriprise International Holdings GmbH, which is itself wholly owned by Threadneedle Asset Management Oversight Limited, which is itself wholly owned by TAM UK International Holdings Limited, which is itself wholly owned by Ameriprise Financial, Inc.
Not much to make me smile at the moment but the above did the trick.
All the best, Si
Nothing suspicious about a Russian doll company structure is there?
I guess you can have a partly recursive holding structure too.
I remember the South Korean chaebols had some interesting recursive structures but I think the regulators there have been making them unwind those into something that is at least hierarchical.
No doubt some accountant somewhere thought it would be a good tax wheeze.
Good Morning Paul
Bloomsbury Publishing (LON:BMY) I am interested in the comment you have made regarding Bloomsbury today, but from a wider angle;
The share price has already surged from flattish around 200p last year, to nearly 300p now, so the question is how much is the good performance already in the price? We're about to find out!
A number of my holdings have reported excellent trading updates/results/figures this week. ( £AAF £SLP £NCYT £BXP Hargreaves Services (LON:HSP) ) and yet with the exception of Bloomsbury Pub (I Hold too) prices have fallen on the day - in the case of Novacyt, dramatically!
So my questions/observations are
1. Clearly the market is aware of this information before announcements are made
2. Although I try to follow these companies where can I find such information ahead of RNS announcements?
3. If the market in general has knowledge of trading info ahead of RNS announcements doesn't that put the small retail investor at a major disadvantage?
share similar concerns but the Mkt is crazy and has been for some time. Did you note that for example yesterday morning first thing £CWR - CERES was down almost 20% - but ended the day down just 4%. Yet there was no RNS news. With Bloomsbury Publishing (LON:BMY) I'm sure there will be pundits who are disappointed with a mere 5% growth from this company - but hey - as I write, Its up over 7% (I hold both)
Yes the share price has gone up from around 200p, but it is only back to where it was a year ago, when it was around 300p, despite the predicted results being well ahead of the forecasts. Yes some is already in the price but seems the 200p was a bargain and no reason why the shares went down so much, but that's what happened to many shares last year.
Sylvania Platinum (LON:SLP) shares had already gone up around x3 so no surprise there was some profit taking, I sold quite a few of mine.
Novacyt SA (LON:NCYT) I also hold but it's about the future which seems uncertain, 2020 no doubt was a bumper year for them, can they grow still?
A lot is already in the prices, so unless the results are better than expected, you can expect some pullbacks.
It can be a good time to top up.
Hi Norfolk,
I don't think it is so much a case of the market having knowledge of unpublished trading, but rather having expectations based on general economic news, updates from competitors or downstream customers etc.
For example, in proper context I do agree that the Sylvania Platinum (LON:SLP) (I hold) update was good, but the share price has been up aggressively recently, largely I think on the back of the high commodity prices. Against this background it's easy to see why some might think a 1% increase in profit is a bit disappointing.
Bloomsbury Publishing (LON:BMY) on the other hand (I had been looking at recently - curses) were able to tell us that they will deliver "profit well ahead of market expectations*"
Incidentally on those market expectations - I do agree with Paul that it is good to see yet another company telling us what those expectations are.
However it would be useful if they could also explain what they thing "well ahead" actually means. I do understand they don't want to declare a number prematurely; but I cannot see why more companies don't adopt the formula of "profits no less than" or "in the range of".
Hi Gromley
Thank you for taking the time to reply. I am relatively new to all of this (been investing 7 months) and learning all the time.
Do you or anyone else out there have an opinion on Research Tree? I am Assuming this is a subscription service. I will need to check it out.
Whilst on I have to say the detail and depth of info provided by both Paul and Jack on these shares today, and indeed every day, is quite simply gold dust!
It is the opposite of Norfolk'n'Good!!
Thank you Norfolk!
I remember we used to have a possible relative of yours here as a subscriber, called Norfolk & Chance which I found an amusing username. Do you know him?! ;-)
Regards, Paul.
Err Paul evrywun knose evrywun round ear.......
Depends if you are 'long' or a trader. A trader will see shares pumped up on close of the day before or during the day and then drop after the announcement. You day or intraday trade or you just buy what you think is good and forget about it. Most accounts won't let you day trade without 20k and the keys to your house so they can sue you if you get a bit carried away. Going long with Stocko to support the fundamentals is probably good and dip in regularly to fine tune. Otherwise 7am watch the RNS, decide your plan, trade then come back in the afternoon before close. Then dive into the US till 9.30pm. Don't forget to eat and drink lots of water.
Card Factory (LON:CARD)
very frustrating situation here - i think card has good enough business model that they should not really be in the position they are right now. It's not good they they they and the ?ankers can't come up with an amicable solution - not sure if the bankers are being ?ankers or the company is makings its own problems here by they way they have approached things now or in the past ref financing issues. As Paul says until this situation is sorted its easy to imagine there being an extra 50%+ shares in issue this time next week with those shares being issued at 20p or less - much easier to wait till the dust settles here.
Can't see there would be much take up of any offer, not if as I understand it Moonpig, are floating next month.
Re Card Factory (LON:CARD) - I agree but draw a different conclusion (which is what makes a market). CARD was a great business that paid out too much (vs debt control and online devel). However, I think it is still a great potential business - just now at 1/5 of price it was 2 years ago. It has only crumbled due to i) Covid and only then ii) debt.
The 2 questions are thus
i) is there a STILL a profitable long term business or has COVID structurally changed the market to online cards, no cards or cards bought via supermarkets. My belief is that physical card buying will largely return albeit with the legendary 5 years change wrought in a single year ie in 12M time the physical card market will be say 20% smaller than it was pre-Covid. (In fact 20% decline would be >10 years change based on the 1% value decline pa CARD claimed pre-COVID for physical cards). CARD would still be by far the biggest and most profitable player in physical cards, generating huge cash operationally. Store competitor Paperchase is closing 20% of stores; Clintons must be in trouble again (as it was operationally poor pre-Covid); and independents will suffer when business support is reduced.
Two of its 3 biggest structural costs are leases and staff costs (inc turnover costs). From other companies, leases will likely be 30-50% lower in 2 years and maybe based on turnover at next renewal; estate has a 2.5yr ave lease length I think. A lot of ex hospitality workers (lots of young/female staff) will now happily take steady min wage jobs in CARD and not jump ship after 6months which was a costly problem before.
Online CARD has historically weak but they are still clear no 3 with arguably the most powerful brand - especially with the older, mass market, yet-to-convert to digital people. Also, historically, CARD online was underwhelming and the interim strategic presentation was more of the same. However, a new MD will no doubt be much more aggressive about online and the new website (introduced this year) is far better than the old and they have largely given up on the Getting Personal gifting brand (good news IMHO). They need to advertise and drive trial of card factory online once lockdown ends (as this will also help drive traffic back to stores - indeed this effect is likely to be greater short term !!)
I am clearly convinced there is a very profitable business still visible here
ii) Now financing - The real long term debt is only £144Mn acc to Stocko (ie excluding profitable store leases as Paul points out) To fund a significant debt reduction/rescheduling AND marketing spend to build digital and get people back into its stores, CARD has to raise maybe £50Mn. So yes a raise of £50Mn (from say 200Mn new shares at say 25p) is likely and has been on the cards (geddit!) for some time. However, I want to be in this as this looks a great buy-in price.
Forget about special or even ordinary dividends for a couple of years! But if you can accept that then I would welcome the chance to buy CARD at 25p/share in a few weeks as in 2-3 years I think they could be worth x2-3 this. Not hard to see it at 75p-100p in Jan 23. I don't trade so if it spikes down a bit short term post raise, that's life.
The lack of movement in the share price today suggests others are making a similar calculations. In addition, a bid from PE also can't be ruled out at these prices since they must like to normal operational cash flow characteristics and could focus on shrinking profitably, ditching low margin expansion into supermarkets and international expansion.
Personally I can still a role for a card and party ingredients (balloons) store in the local high street in a way I cannot for most clothing/ hardware stores.
My real fear is that as a small shareholder I am shut out of any low ball refinancing. (I hold).
I have been converted to £CARD online offering, over the past year it has got heavily into personalisation and increased the range.
They are much cheaper than Moonpig and Funky Pigeon and the DO NOT charge for postage.
The last positive advantage is that you can also buy cheap and cheerful (but good quality) cards for everyday uses, unlike the other two and we bought about 70 really good Christmas cards from them at very low prices.
I can only guess that they are not marketing their online offering widely and properly, if they did, they could easily beat the competition.
Re Card Factory (LON:CARD) and online sales. Both Funky Pigeon and Moonpig invested heavily in Marketing (including TV) years ago to build scale at which point heavily automated online cards become much more profitable. Card Factory (LON:CARD) faced the innovator's dilemma and got trapped not willing to risk cannibalising their hugely profitably stores and so had under-invested online site.
Upgrade in P12M and now playing catchup. I agree on pricing....but investor feel they are too cheap. They need to price up and put money into Marketing. The DNA of the company was cheap cards from secondary locations whereas Moonpig and Funky Pigeon were financially engineered from the start.
The new CEO starts March 1st and comes from a stores background (good) including Clintons CEO in 2011-12 (Takeover and rationalisation opportunity??). If he is smart he will hire a brilliant online Marketing bod as part of his no doubt organizational transformation plan.
I think the new CEO/new strategy (together with summer stores re-opening) will be the catalyst for a CARDS re-rating (by then financially solid after the expected equity raise).
Here's hoping.
25p certainly looks better than 35p.
I'm not sure I'd want to pay 35 hoping for the chance of 25.
Happy to wait.
As long as humans are disorganised, procrastinators, and forget about birthdays until the day itself, there will always be a market for Card Factory (LON:CARD) to sell high margin cards and gifts on high streets.
There are no viable online disruptors for an immediate £2 birthday card delivery. Until drone deliveries take off.
A sensible practical and PR move from Boohoo (LON:BOO), donating 750k to help children trying to learn from home...
https://www.dailymail.co.uk/ne...
Link posted by alibx11 on ADVFN.
piworld interview with Andy Brough and Tim Steer, discussing Tim's book: The Signs Were There. A tremendous easy to read book on accounting red flags. Here, they discuss some of the key elements of accounting manipulation, which should make you run in the opposite direction. Artfully, they take a dry subject and add some personality and humour so one learns and enjoys it! Video & podcast.
Separately, today Novacyt Sa (LON:NCYT) & Bloomsbury Publishing (LON:BMY) both update the market. They were covered/tipped by Richard Leonard in his 2020 round-up here at 13m50s & 15m39s . Or more Novacyt Sa (LON:NCYT) detail at 34m12s here (Andy Brough and Richard Leonard interview).
Thanks Tamzin. Richard Leonard is certainly on a roll. Redde Northgate, Reach, Polar Capital and Bloomsbury. Get him back again quick!!!
Thank you Tamzin for your superb collection of interviews. I can honestly say that I have enjoyed viewing/listening to every one of them.
Hearing the thoughts of all of your guests (including Paul) has always been very interesting and has certainly helped point me in the direction of some good investments. It's refreshing and appreciated that you allow your guests to speak without unnecessary interrupting.
Thanks Tamzin. Your interviews are very informative and has pointed me to some very good investments too.
Thanks Tamzin - I really enjoyed this piworld interview with Andy Brough and Tim Steers. Bought Tim's book a few weeks back which includes several of my more disastrous investments (before I joined Stockopedia). Check those balance sheets!
Angle (LON:AGL) Extract from an RCS this morning regarding an extended European trial programme on lung cancer.
ANGLE plc (AIM:AGL OTCQX:ANPCY), a world-leading liquid biopsy company, is pleased to announce the publication of a five year programme of work undertaken by the CANCER-ID Consortium to establish the performance and technical capabilities of five circulating tumour cell (CTC) isolation platforms, in which key advantages of the Parsortix® system were identified. The CANCER-ID consortium is supported by Europe's Innovative Medicines Initiative (IMI) and is a Europe-wide Public-Private-Partnership aimed at the establishment of standard protocols for, and clinical validation of, blood-based biomarkers in order to drive wide adoption of liquid biopsy in clinical practice and pharma services.
The research has shown that Parsortix performance was robust, with mean cell capture rates of 71% (EpCAM high cell line) and 67% (EpCAM low cell line). In comparison, the leading FDA approved antibody-based CTC system was unable to enrich EpCAM low cells. Parsortix was comparable to the leading antibody-based system with respect to time required for sample processing, staining and cell identification and was considerably faster than some other systems. The use of Transfix® blood collection tubes, utilised with Parsortix in this study, provided for 5 days' blood stability enhancing the practicability of sample management.
Paul, I would appreciate your thoughts on Supply@ME Capital - £SYME. It strikes me as an interesting platform for the current climate (finance tied to inventories) and they released an RNS today on global plans. Might be too much of a moonshot though.
Jack - I would be careful of Supply@me Capital (LON:SYME) they talk a great game but revenues whenever I look are almost non existent - I think risk way outweighs reward here
Good morning one_eyed_jack,
I've had a quick look at the StockReport for Supply@me Capital (LON:SYME) and note;
Shares suspended on 21 Jan 2021, due to non publication of accounts for y/e 31 Dec 2019! That's ridiculously late.
£167m mkt cap, is based on the new, acquired business. That's not included in the accounts published today, as they pre-date the RTO.
2019 accounts out today.
This is what happened to Imaginatik! I remember that company, always promising jam tomorrow. We saw them present at FinnCap years ago, nice American man who ran it, I think? Turned into a cash shell on sale of Imaginatik.
It then bought Supply@ME (an Italian company) in a reverse takeover - an innovative fintech "platform" to provide finance from inventories. That was in March 2020, so the 2019 accounts are now irrelevant for the cash shell, pre-reverse takeover
Valuation on re-floating through reverse takeover was £227.5m
Interim results also published today, 6m to 30 June 2020 - seem to show very little activity on the P&L.
There are various other RNS announcements, talking about funding, etc.
I'll wait to see what the future accounts are like, as there's not enough to go on for me to form a view at this stage.
I'm not excited about the concept though. The reason that funding inventories through lending is not popular, is because historically the lenders end up with a lot of bad debts - when companies default on the debt repayments, and the lender tries to repossess the inventories pledged as security, more often than not, they don't exist! So it's in reality unsecured, high risk lending.
Just because it's done on a high tech "platform" doesn't change the fundamental concept that lending against inventories is generally a really bad idea.
So not something that would interest me, but am happy to look at the first set of proper figures for the enlarged group in the future.
Regards, Paul.
Thanks for the first look Paul. I guess the question is have they managed to do something interesting to reduce the lending risk, or as you say, have they just digitalised a weak business model. I've got a small holding, but just enough to make it worth digging a little further.
Shareprophets have them down as complete crooks and a massive sell/short. Tread carefully. I'd probably join them if they weren't suspended for non-posting of 2019 accounts.............!!!!!!!
I'd never invest in a company with such a stupid name!
A couple of late comers have crashed in:
BigDish (LON:DISH) H1 rev nil. Confident funding "more than adequate to stretch the funding runway beyond the end of the second quarter of 2020". 2020?
Gutted there's no Zak Mir BS this time to quote for you.
Supply@Me Capital (LON:SYME) H1(Sept) loss £2.1m. "Exploring potential joint business alliances with Internet-of-things vendors... to develop a unique 'Internet of Inventory' tracking and monitoring product to enhance its offer."
It really needs to get green crypto bio-graphene anti-covid CRISPR accelerators in there.
I'm short
Morning Paul, great update from ncyt today particularly the H2 weighting of figures. I know this is in the Stockopedia staff investment club. What are the thoughts on it going forward from here. Thanks.
Buy a good parachute.
Positive Q2 update from Sylvania Platinum (LON:SLP), with net revenue up 5% to $43.7m and net profit up 1% to $20.3m compared to Q1. Performing strongly despite the challenges posed by the South African lockdown (I hold).
Paul - Grateful for a view on RNS Novacyt today
Many thanks
I don't have any views or insights on Novacyt, as not a sector I've ever covered, apart from occasional brief comments. I suppose the key question is whether it's a one-off bonanza from its successful covid testing product, or the start of something big?
The numbers in today's trading update are stunning, as expected.
Valuation of the shares hinges mainly on how the future pans out, once the covid testing boom has passed. I can't add any insights to that, your guess is probably a lot better than mine!
I've just messaged Jack, to ask if he would comment more usefully on it.
Regards, Paul.
Novacyt Sa (LON:NCYT) Thanks Paul and I hope Jack can find the time.
I hold Novacyt (6th largest holding but fortunately playing with casinos money). The big question for me (and I think the market) with Novacyt is whether the company has a sustainable business model. The bulls will tell you that testing will always be required etc etc and the bears that it is a one trick pony and that it has already pulled its rabbit out of the hat/crossed the finish line or whatever the metaphor is.
The stock is 38% up in two months before the last three days decline to £9.50 (and in hindsight I should have taken some more money of the table at the £11/£12 level but with hindsight all investments are profitable). It excites a lot of passion on Twitter and Leon Boros, who was in it (but not sure whether he is now) made a comment this morning on the update and he gets dumped on (which of course is absurd). His comment was simply that the update has come in at the lower end of Numis’ range and did the statement “...extend this phase of the contract....” refer to (using LB’s words) “the £100m extension to phase 1 or the much larger Phase 2?” Personally I believe it relates to phase 1. If it related to phase 2, that would have been material and they would have had to announce it and the stock price would have popped this morning. The decline comes from the uncertainty.
My opinion? I have none at the moment (I am afraid I am not a RNS junky and don’t get up at 7 to read them) but unless the company can grow in to one with revenue and income visibility, I will be happy when I can exit, as personally I much prefer companies like Treatt (LON:TET) Somero Enterprises Inc (LON:SOM) Xp Power (LON:XPP) and dare I say Boohoo (LON:BOO), only the latter do I currently hold but Novacyt Sa (LON:NCYT) has been good to me, so not yet ready to exit!
Apologies for the slightly wafflely post.
Regards
Michael
PS If you have read Bill Gates’ latest memo, it certainly gives the impression that the likes of Novacyt Sa (LON:NCYT) have an important place in the future so that we can avoid the next pandemic causing the same economic and social carnage that this one has.
the one forecast i can see for 2023 is Revenues decline to £97m, Net profit to £30m but for 2022 they have net cash 390m (no estimate for 2023 but can assume 415m). If they used their cash to buy in shares the market cap would fall to 215m which puts the remaining business on 7* PE.
Re Novacyt Sa (LON:NCYT), the cash flow generation looks prodigious. In the RNS management says cash flow should equate to 80% of EBITDA going forward. IF they can annualise H2's EBITDA that would be £280m EBITDA for 2021, and £224m cash inflow, against an EV at the mo of £614m (SP of £10). Looks appealing. I hold.
@grumpy5 thats broadly my conclusion too. I also hold. Even if we assume H2 20 is peak earnings and does come off a bit, its trading on <3x EV/EBITDA. As soon as company can give some guidance on FY21 and beyond you would expect that multiple to double at least in relatively short order.
I think there's a strong hint in today's RNS from Novacyt that the DHSC is about to extend its contract with Novacyt to supply test kits to the NHS:
"In addition, the Company continues to support the DHSC and the NHS following the deployment of its rapid PCR testing system, for the contract with the DHSC, announced on 29 September 2020, and the Company is in active discussions with the DHSC to extend this phase of the contract. Novacyt's PROmate™, a new product to improve the workflow efficiency when used with the Company's q16/q32 instruments successfully completed an in-service validation conducted by Test and Trace's Technology Validation Group (TVG), with the TVG concluding the performance of the PROmate™ aligns with the acceptable standard for point-of-care (rapid testing)."
Hi pka
I suspect it refers to phase one but the phrasing is ambiguous. Why use “extend this phase of the contract” when they could have said “the Company is in active discussions with the DHSC to extend phase 1 of the contract.” or ”the Company is in active discussions with the DHSC to extend phase 1 of the contract with commencement of phase 2 of the contract”.
Regards
Michael
Hi MichaelFBS,
I suspect that Novacyt's statement refers mainly to an extension of phase 1, but that they think there's a good chance of getting a contract from DHSC for phase 2. From what I've read, some NHS Covid testing staff at smaller hospitals have found the procedure for using Novacyt's Q16 and Q32 instruments quite complicated and have therefore been reluctant to use it. That's why the recent release by Novacyt of its Promate product is important, because it simplifies and shortens those procedures. There's some information about it here:
https://novacytinsider.com/promate-revealed/
I think Promate greatly increases the probability of Phase 2 of the DHSS contract going ahead.
Reading the Novacyt Sa (LON:NCYT) RNS my thought was they were being careful about shouting about all the money they are making while they are engaged in negotiations on pricing with the DHSC.
I continue to hold.
true. It’s going to be a balancing act. GM generally does not boast and makes simple statements. Generally their RNS’s factual and no waffle
Thank you so much for this, will read with this.
As an aside I have always been a little wary of Novacyt Insider and as to whether was part of a ramping exercise on Twitter.
Regards
Michael.
I agree that the Novacyt Insider website is something of a ramping exercise, but the articles seem to me to be very well informed about the company's activities and a useful source of information.
On Novacyt Sa (LON:NCYT) (I hold) the problem the market perceives is what happens if those cashflows are temporary? In extremis say cashflows are 2021: £224m and 2022: £246m and 2023: £271m and then goes to zero, discounted back at 8%, this gives market cap of £633m. Not far off Friday’s close.
I had the same issue with Anglo Asian Mining (LON:AAZ) where the market could not see beyond a particular mine’s useful life being three years and therefore awarded the company a very low PE (this is proving to be wrong, all but tediously slowly).
I fully except that my investment in Novacyt is closer to speculating than investing but IMO the market is seeing an end to Covid and testing much sooner than will be the case. For example I think a negative COVID test (vaccinated or not) is going to be required to travel, for example, for a very long time until the efficacy of the vaccines over time is proved.
Regards
Michael
Hi MichaelFBS, you wrote:
"On Novacyt Sa (LON:NCYT) (I hold) the problem the market perceives is what happens if those cashflows are temporary? In extremis say cashflows are 2021: £224m and 2022: £246m and 2023: £271m and then goes to zero, discounted back at 8%, this gives market cap of £633m. Not far off Friday’s close."
Even if one makes that very pessimistic (in my opinion) assumption, Novacyt (which I also hold) would have £741m cash by 2024. It could use that cash to buy a number of profitable businesses to give it ongoing cash flows. And Novacyt has said that it is planning to do just that, in order to diversify its business into related diagnostic areas. So it seems to me that its current share price is far too low.
I think the main reason for the £NCYT sell-off on Friday was the lack of any forecast at all for 2021 and the fact that talks are still ongoing for phase 2 of the DHSC contract, the first phase of which (according to my maths) ended mid-January. I also hold and hope that there is a contract extension announcement soon to put some spring back in the price. I have to say that I was disappointed that the 2020 revenues were not a bit higher than they turned out.
Another possible reason for the Novacyt sell-off on Friday was the announcement of the effectiveness of another Covid vaccine (Johnson and Johnson's).
My morning smallcap tweet:
Bloomsbury Publishing (LON:BMY) Myhealthchecked (LON:MHC) Xpediator (LON:XPD) Tricorn (LON:TCN) OPG Power Ventures (LON:OPG) Novacyt SA (LON:NCYT) Impact Healthcare REIT (LON:IHR) Various Eateries (LON:VARE) Tirupati Graphite (LON:TGR) Card Factory (LON:CARD) Next Fifteen Communications (LON:NFC), Inspired Energy (LON:INSE), Inspecs (LON:SPEC), Pelatro (LON:PTRO)
Bloomsbury Publishing (BMY) guides FY(Feb) rev ahead and profit well ahead of market expectations of £161.8m and £12.1m resp. Cites strong trading in the Consumer division. [SP=284 Cap=232m]
MyHealthChecked (MHC) £3m placing at 1.75p, 15% discount, to launch the products into the retail sector and develop new products. [SP=2.17 Cap=11m]
Xpediator (XPD) guides FY(Dec) adj pretax c.£7.2m up 40%, significantly ahead of market expectations. "2021 transport volumes into Europe have been lower from the outset of the year due to the administrative changes caused by Brexit...For Xpediator, as anticipated this is an opportunity to increase administrative support to our clients to enable them to manage the new environment which in time will settle down." [SP=36.65 Cap=52m]
Tricorn (TCN) Q1 update "demand levels from a number of customers continue to increase providing additional availability in the UK from the Group's invoice discounting facility. Has drawn another £1.8m. Cash at hand only £0.7m. Co returning to more normal levels of production. Re the inter-company imbalance of approximately £1m - £0.7m cannot be justified and will be written off . [SP=7.33 Cap=4m]
OPG Power Ventures (OPG) in line and will resume divs. [SP=14.72 Cap=59m]
Novacyt (NCYT) guides FY(Dec) rev €311.6 up over 20x and EBITDA above €210m. Cash €101m. Outlook: strong start, difficult to provide a clear forecast but mgmt "believe demand for the Company's COVID-19 product portfolio will remain strong throughout most of 2021, with continued conversion of new opportunities, including a number of planned product launches, and the expansion of the Company's VersaLab™ service" [SP=1070 Cap=860m]
Impact Healthcare REIT (IHR) NAV 109.58p/sh cf Sept 109.06p. Property val up 5% in the Q. Targets 2021 div 6.41 up 2%. [SP=111 Cap=354m]
Various Eateries (VARE) holding off signing up to any new leases, withdrawing guidance. Gets £2.5m interim payment under its Business Interruption Insurance. [SP=70 Cap=62m]
Tirupati Graphite (TGR) wins first commercial contract, to provide mineral processing technology development services, from Optiva Resources. No £££ but success fee in shares and warrants. [SP=76.44 Cap=57m]
Card Factory (CARD) banks give waivers in respect of anticipated covenant breaches, to end Feb. Constructive discussions. [SP=36 Cap=123m]
Next Fifteen Communications (NFC) Q4(Jan) rev up 9%, ahead of management expectations so guides FY ahead of market expectations. [SP=600 Cap=546m]
In line: Inspired Energy (LON:INSE) Inspecs (LON:SPEC) Pelatro (LON:PTRO)
Tricorn (LON:TCN), Re the inter-company imbalance of approximately £1m - £0.7m cannot be justified and will be written off . [SP=7.33 Cap=4m]
How can this be?! Careless would be an under statement.
Xpediator (LON:XPD), Trading update for this small cap looks promising. The Group expects to deliver profits for the year ended 31 December 2020, significantly ahead of market expectations. Following higher than anticipated demand for its services in the UK and Europe during November and throughout December 2020, the Group now expects to report adjusted profit before tax of approximately £7.2 million for the year ended 31 December 2020, a 40% increase over the prior year (2019: £5.15 million)..
A Brexit comment was also made.