Small Cap Value Report (Fri 29 July 2022) - FOXT, MMAG, WIL, AML, ELCO

Good morning! Just Paul here, as it's a Friday. Today's report is now finished. Have a fab weekend in the sun :-)
Graham and I shortly have a Zoom with Begbies Traynor (LON:BEG) to discuss the accounting treatment of deemed remuneration, we'll report back if any developments!
By the way, many thanks for the positive feedback earlier this week, re covering more companies here, with some smaller additional comments. We've taken that on board & will keep doing more of the same! (on top of our usual deeper dives on 3-5 companies reporting each day). We managed 12 companies yesterday, which I think is a new record.
Agenda -
Paul's Section:
Foxtons (LON:FOXT) - I've had a good rummage through its interim accounts, and like what I see. The shares look priced about right for now, but cost-savings have already been made, and lettings books are being acquired, so profits should be rising from here. Plus an experienced new CEO is joining in September, seemingly with a remit to focus the business more on profitability. This share could be quite good I reckon. FOXT shares are not obviously under-priced though, so upside depends on improved performance.
Aston Martin Lagonda Global Holdings (LON:AML) - This company's shares are paying us a fleeting visit, before they disappear into the sunset once the latest fundraising is done. Definitely not a value, share, with heavy losses in today's interim numbers. However, deep pocketed backers (Mercedes-Benz, and the Saudi sovereign wealth fund) are cornerstones for a big fundraise, to tackle excessive debt, and provide development capital. Once the fundraise has completed, I think there might be a speculative, long-term appeal to this share, if AML can scale up to become a profitable business, like Ferrari.
Musicmagpie (LON:MMAG) 44p (£48m) [No section below] - just a very quick look at its H1 (to May 2022) results. In a word - poor. An adj PBT of £4.0m in H1 LY, turned into a £(0.7)m loss this time. Costs were roughly flat, but a sharply lower gross margin caused the profit to vanish. I'm surprised that banks have agreed a new 3-year £30m RCF. Net debt is currently £3.3m. Outlook - adj EBITDA in line with its expectations (not stated). Balance sheet looks adequate. It’s a (very) low margin recycler of consumer electronics.
It’s yet another recent float that took advantage of the pandemic boom to float at an excessive valuation, on a short-term profit bonanza. Profit has since largely evaporated. So it’s not for me. It's not cheap either, latest Edison forecast is only 1.4p & 1.0p EPS for 2022 & 2023. I'd say it needs to more than halve again in price, to be more sensibly priced.
Wilmington (LON:WIL) 272p (£240m) [No section below] - noteworthy for strong momentum, in both earnings forecasts, and share price. FY 6/2022 TU (trading update) came out 2 days ago. Profit (adj PBT) ahead of expectations, at £20.7m (up 38% vs LY). Impressive increase in net cash, now £20.5m - previous heavy debt has been cleared. Growth is organic.
My view - patchy historic performance, but WIL seems to be doing really well now - in a busy sector (risk & compliance markets). I like the look of this share, and the valuation still looks reasonable. So a thumbs up from me.
Eleco (LON:ELCO) 70.6p (£59m) [No section below] - I like this company, but concluded here in May, with its in line TU, that the shares were much too expensive, given the outlook for falling profits. This is due to transitioning from up-front licence fees, to SaaS. Fine, I get how that works, but why would I want to sit & wait for profits to start rising in 2024? And pay up-front for that yet-to-happen profit growth? The latest update, 2 days ago, is again in line with expectations. It notes “increasing inflationary pressure on salaries” - a worrying headwind for the whole IT sector, since most costs are salaries. What capacity does it have to raise selling prices, in long-term contracts? (RPI or CPI plus, I hope). That's a key question to ask mgt. It still looks too expensive to me.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section:
Foxtons (LON:FOXT)
43.6p (up 5% y’day at 13:01)
Market cap £138m
This London-centred estate agents/lettings business cropped up on Friday when I interviewed renowned investor Richard Crow (“CockneyRebel”). He reckons there could be a decent turnaround under new management, in due course.
Foxtons Group plc (the "Company" or "Foxtons"), London's leading estate agent, today announces its financial results for the half year ended 30 June 2022.
Here are my notes -
Commentary is all about a turnaround, e.g. “tightening grip on costs”
New CEO from Chestertons, is joining in Sept.
3 acquisitions of lettings companies - I like the focus on lettings, long-term, recurring, good margin business. More acquisitions are planned - good, providing they don’t overpay. Obvious synergies from stripping out duplicated costs, I imagine.
H1 revenues £65.1m (up 3% on H1 LY)
Revenue split - lettings up 20%, property sales down 17% (in line with expectations).
LY H1 comparative benefited from buyers rushing to meet June 2021 stamp duty deadline (smaller competitor M Winkworth (LON:WINK) said the same recently, I recall).
Profit before tax (PBT) was £4.3m in H1
Adj operating profit of £6.2m is not a reliable number for me for valuation purposes, because financing charges are material, at £1m per half year, and the adjustments of £0.9m are mainly restructuring, which is pretty much ongoing at Foxtons.
Cost savings made, annualised will save £3.0m - that’s quite material to profits, although I do wonder whether any harm will be done to customer service? Are people made redundant previously just sitting around doing nothing? There’s usually a knock-on effect from cost reductions - would be worth asking mgt about this.
Lettings are now 69% of “contribution” (i.e. profit before central costs) - so FOXT should be seen as a more stable, lettings business primarily now. Not a boom/bust sales business, as it was historically.
Adj EPS 1.1p in H1 - this might be suppressed a bit by a £0.7m deferred tax charge, which I would be happy to ignore.
Bottlenecks in conveyancing & surveying (not enough people doing those jobs) impacting whole sector, with offer to completion now 96 days (23% up on pre-pandemic).
Outlook/guidance for FY 12/2022 is “at least in line with market expectations” (but I can’t see a footnote saying what expectations are).
Singers to the rescue (many thanks!), with a helpful one page summary. It’s forecasting 2.4p EPS for FY 12/2022, rising to 3.2p in 2023, and 3.8p in 2024. The analyst Greg Poulton says there’s potential upside on those numbers from acquiring more lettings books.
Valuation - it’s expensive on current year estimates, at a PER of 18.2 - in a sector that doesn’t generally command PERs much higher than low teens, if they’re lucky.
The 2023 PER drops to 13.6, which looks about right to me.
Therefore the bull case for Foxtons shares really rests on it managing to significantly beat forecasts, which might be quite tough, given that the 2023 forecast profit margin (PBT divided by revenue) is already quite robust at 10%. How much scope is there to increase that, in a competitive market, without damaging service and therefore sow the seeds of decline?
Balance sheet - is strange, as it’s dominated by huge intangible assets, partially offset by large deferred tax. I would delete those entries to create something that makes a bit more sense! It seems daft that FOXT has a historic “brand” asset of £99m sitting in fixed assets. This complicates the accounts - they should get rid of it, which I think would also get rid of deferred tax, which just confuses nearly everyone, and serves no real world purpose that I can see.
That takes NAV from £124m to my adjusted NTAV of £15.8m, which looks OK.
I was worried that FOXT might be locked into expensive pre-pandemic leases, but that doesn’t look a major issue, as RoU assets are £42.2m, and lease liabilities are £46.9m, a deficit of only £4.7m, suggesting that most leased properties earn their keep, in terms of being profitable at a site by site level.
Note that net cash is reducing sequentially each 6 months, due to the cost of acquisitions, but is still healthy at £11.7m, so there’s scope for more acquisitions without dilution.
Anyway, this is taking too long, so in a nutshell: the balance sheet is OK.
Client cash of £113m is held off balance sheet (see note 14). Note that FOXT keeps the interest income - so now interest rates have on savings accounts have risen to maybe 1-2%, that’s a £1-2m benefit to the future P&L & cashflow, potentially more if interest rates keep rising. That’s quite material actually, so is an important hidden upside on this share.
Cashflow statement - is heavily distorted by the IFRS 16 entries re leases. So cash generation is not anything like the £9.7m “cash generated by operations”, because further down there’s £5.9m costs re lease liabilities! This is another example of how IFRS 16 has made cashflow statements highly misleading for multi-site companies with leased properties. We should start a petition to have IFRS 16 abolished - it’s created huge problems in understanding accounts, and solved no problems! All that was needed was a more detailed disclosure re leases in a note to the accounts, not to wreck the balance sheet & cashflow statements with meaningless entries! IFRS 16 and pension scheme accounting drive me up the wall, as they’re so obviously unfit for purpose, yet nothing gets done to remedy this ludicrous situation.
Anyway, here in the real world, Foxtons is cash generative, and is essentially using its cashflows to make acquisitions, plus paying modest, but increasing divis (forecast yield for FY 12/2022 is 1.7%, rising to 2.4% next year). I would question why pay divis, when the strategy is to expand by acquisition? That’s a conundrum for the new CEO. I would cancel the divis, and focus on growth, in his shoes. But he’ll have to balance up what shareholders want, and what is in the company’s best interests. That depends on the economics of acquisitions, something I need to look into more closely. If they can bolt on lettings books, and make cost synergies, at attractive prices, then that makes more sense that paying out divis. Although FOXT could safely take on some debt, given that more revenues are now recurring? So the company has plenty of fairly safe options, which I like.
My opinion - Foxtons has had a mixed reputation in the past , for being too aggressive, slap-dash, cocky, too expensive, inefficient, etc - are examples of what I've heard about the business (e.g. from a landlord that I rented a London flat from, years ago). Do some googling! However, now that the business is morphing more into lettings, rather than aggressive sales tactics, it looks to be a much better business. I like the look of this share.
Valuation looks about right to me, based on these numbers and forecasts. However, if the incoming CEO is able to drive profits sustainably higher, then there could be good upside on this share.
Note that the share count has risen to 316m, from 276m pre-pandemic, due to a fundraise to prop up the business during the pandemic. With hindsight, they didn't really need to do that fundraise in April 2020 - I've checked the end 2019 balance sheet, and it was fine, with no bank debt, and plenty of cash. Although it's easy to forget the state of fear & paralysis the whole world got into in the spring of 2020. Also, FOXT actually managed to raise cash at a small premium, at 38.4p, fairly similar to the current share price, so it didn't cause any serious damage. Plus I would never criticise anyone for being too prudent in a crisis.
As a turnaround, I would say that there’s actually not that much wrong with the business to start with! But clearly the Chairman thinks it can be made more efficient, under a new CEO.
Overall, I can’t see anything wrong with this share, and who knows, there could be nice upside if the new CEO does deliver improved performance.
So a cautious thumbs up from me.
.
Aston Martin Lagonda Global Holdings (LON:AML)
474p
Market cap £553m (+ substantial dilution imminent)
I love Aston Martins, so thought I’d check out the accounts, given that it’s briefly within our sub-£700m market cap range. It won’t be after the dilutive fundraising underway.
The interim figures are dire, with heavy losses, and a broken balance sheet with way too much debt, and NTAV negative at about a billion quid!
However, 2 things intrigue me about this share -
- It’s a trophy asset, and attracts deep pocketed financial backers, and
- Brand value & future potential could be huge, if the business can scale up.
Both Mercedes-Benz, and the Saudis, are big backers. A group called Atlas Consortium put forward a big refinancing package, which AML’s Board unanimously turned down, in favour of a deal cornerstoned by the Saudis, who seem to be getting cheap new shares at 335p.
There’s then going to be a big Rights Issue to raise £575m.
This is going to substantially de-risk the balance sheet, and provide cash for business development - making this share investable for the first time, in my view.
The interim numbers themselves are awful, as I would expect from Aston Martin.
H1 2022 saw revenues of £542m, an operating loss of £(73m), and after gigantic finance charges of £221m, a loss before tax of £(293)m.
The outlook is more upbeat, with supply chain/logistics problems set to ease FY 12/2022 guidance reaffirmed, and demand strong.
Financial target is £2bn revenue, and £500m adj EBITDA by 2024/25.
Given that capex & depreciation are huge for car makers, then EBITDA means nothing.
My opinion - based on the numbers, AML isn’t really a viable business, as it has proved multiple times in the past. However, with 2 very deep-pocketed financial backers now, its future seems much more stable.
I’ll have to wait and see how things look after the fundraising completes, and some of the debt is paid down.
AML looks sub-scale currently, but if it can grow, then that could be transformative. For example, Ferrari is about 4 times the size of AML in revenue terms, but is strongly profitable, and valued by NASDAQ at £42bn.
Therefore, I wouldn’t be blinded by the historically poor numbers at AML.
AML certainly isn’t a value share, but I can see a (speculative) long-term opportunity here, for more adventurous investors, now that it's being properly refinanced.
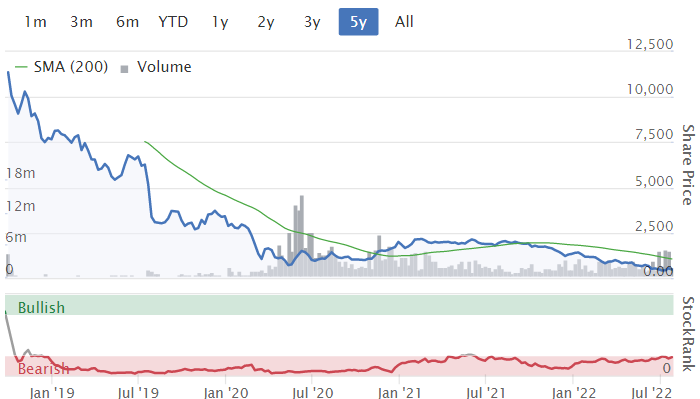
A disastrous 2018 float, even before the pandemic struck -
.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

19 comments
As a holder of Unbound (LON:UBG) I had an example of their total incompetence this week when I received a Marketing Email from them which related to a Special Offer valid for 2 days only.
The dates were Tuesday and Wednesday 24th and 25th July BUT the correct dates in the Calendar are 26th and 27th July. No doubt this caused much confusion but when they cannot get the simple things right it gives me as a Shareholder little confidence that they know what they are doing. A right royal shambles.
I took a small trading position in Foxtons (LON:FOXT) recently and sold for a modest profit yesterday. I don't have Paul or Graham's analytical skills but I generally found the results a little underwhelming. This together with its somewhat chequered history, alluded to by Paul prompted the sale.
My preferred company in this space, which I hold is Belvoir (LON:BLV) where I very much like the management team lead by Dorian Gonsalves.
Hi jonno,
We really like Belvoir (LON:BLV) here too! There's loads of stuff about it in our archive - "Discussion" tab on any company's StockReport brings up what we & others have written about it.
I like the fact that FOXT is now skewing more towards lettings. I was really impressed with how BLV sailed through the pandemic, riding a stream of recurring revenues that were not impacted much by the lockdowns, etc.
Also, I think lettings businesses probably have good inflation protection (with a lag maybe) as rents rise.
I wonder if Foxtons culture is as well suited to the hard graft of managing rental properties though? That's very different to a sell, sell, sell type of culture!
Regards, Paul.
Sigmaroc (LON:SRC) - Why are Stocko's metrics so awful for a company that seems to be doing well. Muted market reaction today.
I think Sigmaroc (LON:SRC) is a perfect example of risk vs reward and when to buy-in.
I was a previous holder and was looking forward to their developing buy & build strategy continuing and ongoing excellent results..................BUT
The market and sentiment moved against them and as everything sold off no matter how good the story was they started to move downwards - probably because a general fear of a recession being particularly painful for construction companies and also therefore raw material suppliers.
That sentiment has continued and their SP is not far off being 50% down. I got out a while back, but nor before taking a bit of a bath.
The positive is that so far they have continued to deliver and have managed the inflation issues well. But I suspect that IF we do have a looming recession they may again drop further. For me the question is about WHEN might be a good time to get back in - I am currently trying to protect some capital and I believe we could have a further sharp decline after the summer, so whilst I see them as being at a good price today, I am hopeful that I may get them at a better price in the autumn. If not I won't chase as there are bound to be other equally good stories/opportunities out there.
If people can shut themselves off from short/medium term noise and can sleep comfortably with prices dropping 50% knowing that they will come back then holding on is fine. I have done this in a few holdings, but it is painful. Others I have bailed out on - not quite worked out what makes me choose option A vs B, but might need to work on this.
Interesting presentation on Meet the Company just now from Trackwise Designs (LON:TWD) (I hold). Graham wrote yesterday that it's uninvestable and Paul changed his mind about it being a speculative punt.
New CFO did say he's intending to buy more shares now not in a closed period. They say they don't expect to have to do another fund raise and feel that share price has fallen more than it should have. Not for widow's and orphans but possibly a great recovery situation for the brave or foolish. Not sure which of those 2 I am. Probably both.
Thanks Roger, I'll take a look at the webinar from £TWD over the weekend.
Just so people don't go on a wild goose chase, the correct name is: Investor Meet Company, not "meet the company".
Shoe Zone (LON:SHOE) spending up to £1mil at a max price of £2. (I hold)
This is good news - luckily I've doubled up on (LON:SHOE) and was wondering whether to take some profits, or indeed move the money elsewhere given that the valuation is looking fairly full. This will help make my decision - whilst the initial buy back appears to be small, I can see this accelerating. I note some big buys from directors last year, which locked in a circa 6.5% div, more share buy backs will certainly be beneficial to them.
Foxtons (LON:FOXT) (I hold)
For anyone following the story, here is the company's response to my question on why rental profitability has increased so much year on year.
And my comment from yesterday for completeness:
https://www.stockopedia.com/co...
"The recent rise in interest has had a negligible impact on higher lettings revenue.
Key drivers there about rental prices were:
On deposits we need to match to tenancy lengths whilst making an allowance for a % that will activate their break clause and terminate tenancies early. For that reason, deposits are cascaded across various term lengths – from overnight upwards. Having a portion of money on very low duration terms skews the interest % downwards."
---
There is £113m of client monies on the books, where all interest accrues to the company. I'm not sure I understand how this only has a negligible impact. Even an average interest rate of 1% on the current balance would result in c£1m of relatively risk-free income flowing straight into pre-tax profits.
Hi abtan,
Yes I spotted note 14 too, with FOXT receiving interest on client monies of over £100m. Potentially interesting, especially if interest rates keep rising. Probably best to see it as a cherry on top, rather than a core reason to invest.
Regards, Paul.
Foxtons (LON:FOXT)
The interest income certainly is a nice additional earner.
More of my enthusiasm actually comes from the growing rental revenue.
The below shows how revenue/let (£) has evolved over the last few years (+ what I hope is a conservative estimate for H2.)
I'd certainly be interested in seeing a more granular breakdown here, for example, what proportion of this increase came from short term lets.
Shearwater (LON:SWG) results look good. Decent profit, cash rich and winning customers alongside high retention rates.
The company seems to start to be getting some momentum now. Happy with the results and happy to keep holding
Shearwater (LON:SWG)
Shearwater (LON:SWG) results look good. Decent profit, cash rich and winning customers alongside high retention rates.
Got to laugh at this company - net loss for year of £0.3 miliion and the company board thinks they are going great guns - not sure what planet the board reside on. Last year they at least managed to sneak into profit. Worst of all is there no mention in the headlines that they have lost money this year - first appearance of "loss" is the text if the text confiming there is a loss for the year on the profit and loss .
Very pleasantly surprised by the confident trading update from Sigmaroc (LON:SRC) which I hold. I have to admit to fearing that the senseless conflict in Ukraine would upset the apple cart, but on the basis of this morning's announcement #SRC appears to be in fine fettle. albeit one needs to see the interims scheduled for 12 September.
#BREE interims earlier in the week suggested that #SRC may be coping better than my expectations, but today's update far exceeded them.
"Strong first half of 2022, demonstrating the effectiveness of the Group's diversified model;
- H1 revenue of £248m, up 18% over 2021 on an adjusted like-for-like basis;
- H1 underlying EBITDA of £48m, up 6% over 2021;
- Underlying EPS over 3.6p, up approximately 35% over the prior period;
- Continued good cash generation, with leverage within the Group's target range;
- Diversified market profile and good demand leave the Group well placed to deliver the Board's expectations"
Max Vermorken, CEO of SigmaRoc, commented:
"To state the obvious this was a first half unlike any other, yet the Group performed extremely well. Input cost increases were managed and further cost reduction initiatives were implemented. We closed H1 2022 with a strong performance and remain encouraged by the demand outlook in all segments for the months ahead. Our focus remains squarely on developing our Group in terms of products and geography and we remain very confident in delivering good financial and strategic progress both in the current year and over the medium term."
A cynic might think the Thinksmart (LON:TSL) board may be in line for jolly wind-up bonuses that would have soared if Block had kept rising instead of halving from its March level.
So they had the opportunity to sell shares in Block earlier this year but waited until they halved in price to sell. Fantastic. £TSL