Small Cap Value Report (Fri 29 Sept 2023) - SAGA, XLM, EAAS, EBQ, FUTR, SYME, CAV, VCP

Good morning from Paul & Graham!
All done for today, and the week! Have a lovely weekend :-)
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
A deluge of new reports today, but mostly uninspiring companies I have to say (EDIT: actually, some of them are OK!) -
Summaries
Saga (LON:SAGA) - 121p (£171m) - Interim Results - Paul - AMBER/GREEN
Signs of life at this insurance/holidays group for the over 50's. Interim results are flat vs LY, but the outlook is more interesting, saying ahead of expectations for FY 1/2024. Also it confirms there is plenty of cash & a facility available to repay the May 2024 bond in full. Useful amount of de-gearing has already happened. I think risk:reward here has improved, so it might be worth a fresh look.
XLMedia (LON:XLM) - down 5% to 8.75p (£23m) - Interim Results - Paul - AMBER/RED
Online marketing company that looks cheap superficially, but the investment case doesn't stand up to my scrutiny. In particular, the weak balance sheet, with some nasty liabilities falling due, makes any shareholder returns unlikely I think. Horrible sector, where profits are often not sustainable.
Eenergy (LON:EAAS) - 5.8p (£20m) - 12-month Interim Results - Paul - RED
This energy consultant achieves a breakthrough into profit. However, the balance sheet raises big concerns, due to a ballooning receivables book, and mounting bank debt. Looks quite precarious to me, so I'll be avoiding this one.
Ebiquity (LON:EBQ) - down 6.5% to 43p (£59m) - Interim Results (“broadly in line”) - Graham - AMBER
This media investment analysis group says that it is only trading “broadly in line”. The global advertising market remains “cautious and risk averse”, although EBQ hopes to help clients spend more efficiently in these conditions. This is not a bad consultancy in my view.
Future (LON:FUTR) - up 16% to 827p (£986m) - Full year trading update - Paul - AMBER/GREEN
Shares in this publishing/marketing group have shot up 16% today, despite its trading update only being in line. I think that's because the valuation arguably overshot on the downside, and it now looks cheap. Although the weak, heavily indebted balance sheet is far from ideal. Overall, I quite like it!
Supply@Me Capital (LON:SYME) - down 5% to 0.1p (£61m) - Half-Year Report (“broadly in line”) - Graham - RED
This fintech platform has generated a tiny sliver of revenue in H1 (£0.1m) and so it remains loss-making. The balance sheet doesn’t offer much comfort with no cash, loans from an Italian bank and a working facility offered by its own CEO. I doubt this will end well.
Cavendish Financial (LON:CAV) - 7.9p (unchanged) (£29m) - AGM Trading Statement - Graham - GREEN
finnCap and Cenkos are no more; they've been replaced by a company called "Cavendish". Cenkos staff have had to move office and the Cenkos listing has been cancelled. Market conditions remain very quiet but I think this combined group should do well if conditions ever improve.
Victoria (LON:VCP) - up 2% to 537p (£618m) - AGM Statement - Paul - AMBER/RED
Victoria PLC (LSE: VCP), the international designers, manufacturers and distributors of innovative flooring…
We briefly mentioned this controversial share in Monday’s SCVR, when a condemnatory article in the FT highlighted an audit report qualified over uncertainty in a small subsidiary’s accounts, and a rather worrying comment from the auditor that VCP’s management had limited its scope. This caused a sharp spike down in share price as low as c.400p, but it closed the day almost fully recovered, so a nifty trade there for anyone who moved fast.
As I expected, VCP has issued a firm rebuttal of the allegations, emphasising it’s only a tiny subsidiary, and very small amount of money, and proper financial controls are now in place.
It also says some fairly upbeat stuff about trading being in line, £20m of efficiency savings being in the pipeline, and an H2 weighting expected for this year. Demand generally stable. Margins improving due to lower input costs and efficiency gains.
Paul’s opinion - I remain troubled by the negative NTAV balance sheet, and excessive debt, so it’s not for me. [no section below]
Paul's Section:
Saga (LON:SAGA)
121p (£171m) - Interim Results - Paul - AMBER/GREEN
Insurance & travel group targeting the over-50’s. I got a bit obsessed with this share previously, spending far too much time on its potential for a post-covid recovery, which seemed to repeatedly be deferred, and has been lacklustre so far.
So we switched from GREEN to AMBER in April 2023, and AMBER again in June 2023 (when it annoyed us by putting out an ambiguous TU that turned out to be a disguised mild profit warning).
The headline P&L numbers don’t look very exciting, with modest underlying profit, and huge adjustments again between underlying and statutory profit -
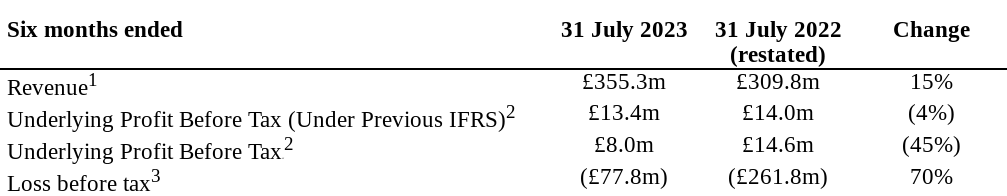
Outlook comments are a lot more interesting though -
"Overall, I am pleased with the progress made in the year to date. Looking ahead to the full year, we are keeping tight control of our costs and are confident that we will deliver significant double-digit growth in revenue and underlying profit that is ahead of market estimates, and repay the May 2024 bond when it falls due. This, alongside our continued focus on debt reduction, leaves us well placed as we position Saga for long-term sustainable growth."
I cannot find any broker notes, so don’t know how much it expects to exceed market estimates by, for FY 1/2024.
Last year SAGA reported £21.5m in underlying PBT, and is now saying it can achieve a double digit increase, implying something upwards of £24m u/l PBT this year - rather vague.
As you can see below, the Stockopedia graphs show that consensus forecasts have come down a lot from original expectations, but have pretty much stabilised this year. Are we now over the worst? It’s starting to look a little more encouraging.

Bond repayment in 2024 doesn’t look a problem, with Sir Roger helping out -
The Group expects to meet the £150m bond repayment due in May 2024 through a combination of Available Cash4 resources and drawdown of the loan facility with Roger De Haan. To provide additional financial flexibility following repayment of the bond, the Group has agreed a £35m increase to the facility, taking the total to £85m, and an extension to the expiry date, to 31 December 2025.
As I’ve always said, bear in mind that most of SAGA’s heavy debt burden is the ship loans. Total net debt is £657m, but £438m of that relates to the two owned nearly-new cruise ships, which have a book value of £597m - so the ship debt is more than fully asset backed.
Remaining “adjusted net debt” is £222m, which is too high I think, but not dangerously so.
Therefore I think these numbers are starting to vindicate my view on SAGA’s debt position as not being a crisis, more something that can be managed down over time. Sir Roger’s financial support (not cheap, at 10% pa, or 18% in an unlikely event it’s used for anything other than bond repayment) has proven key, although given that SAGA already has £181m cash on hand, that’s more than enough to cover the £150m May 2024 bond repayment. So I think his £85m loan facility is providing ample headroom, rather than being essential.
Balance sheet - is large, and complicated, and has negative NTAV. So the finances are weak, but improving I think.
The benefit all flows to equity remember, so the high level of gearing here could create nice upside for equity holders, as debt & perceived risk recede.
In the meantime, the 2026 bond is still seen as risky by the bond market, with a price of about 76. That gives a very nice return to maturity actually, so could be worth a fresh look for bond investors, as it seems as if risk is receding somewhat.
Paul’s opinion - I’ve only focused on the key points here, there’s loads more detail in the interim results.
Overall, it seems to me that things are at long last moving in the right direction. I see risk having reduced a lot, with travel now performing better, and some deleveraging now in evidence. The insurance division has been problematic, but in a way it’s encouraging that it says the sale of the underwriting division was pulled (after terms agreed) because they think they can get a better price at some point in the future.
Downside risk would obviously be, as with all travel-related shares, another pandemic erupting.
I can’t say I’m massively keen on SAGA, but that could just be emotional, as it disappointed so often from 2021 to earlier in 2023, that I just lost interest in it. Many other investors probably have the same emotions, which could possibly be providing an opportunity now that it does actually seem to be turning the corner - cheap due to investor apathy maybe?
I’ll give it some more thought, but (Roland and Graham may disagree with me here!) I’m going to tentatively go up from AMBER, to AMBER/GREEN. It has just put out an ahead of expectations update, after all, so this isn’t just wishful thinking.
Terrible long-term share price performance -
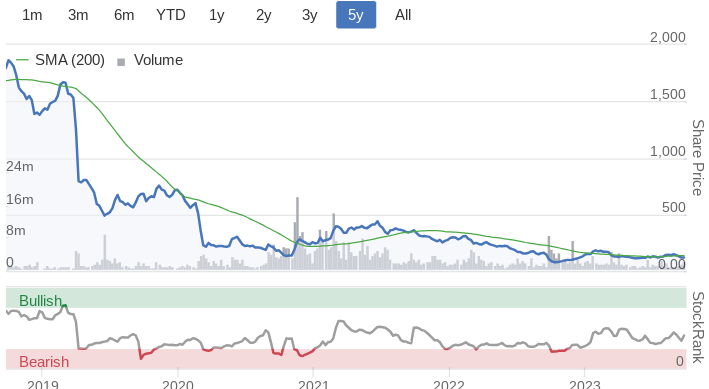
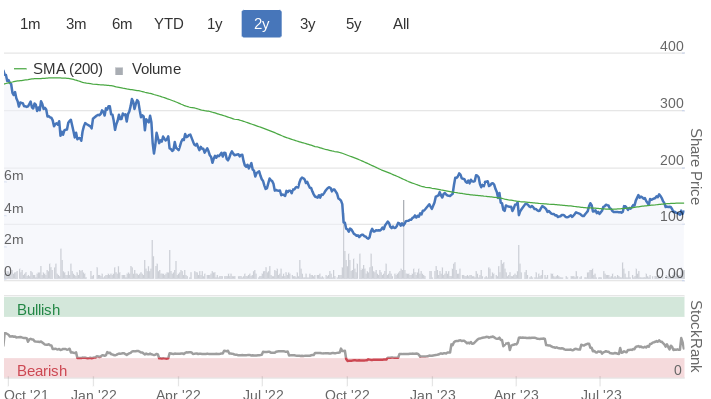
But is it now forming a base, since the bad news has stopped, and a more positive update this week? -
XLMedia (LON:XLM)
Down 5% to 8.75p (£23m) - Interim Results - Paul - AMBER/RED
Both Candish (new name for Finncap + Cenkos merger) and several readers, seemed to think this online marketing company looks cheap. It has retrenched, and now mainly runs websites to find punters for gambling & sports websites.
XLM shares peaked at just over 200p in 2018, and it’s been downhill ever since, now over 95% down from the peak. It paid decent divis between 2014-19, but nothing since.
Companies in this sector nearly always seem to go wrong, whilst looking cheap all the way down. That’s because they find a lucrative way of exploiting online ads, which is not sustainable, and after a while the cash machine is switched off by e.g. Google or Facebook etc, changing the rules in some way. Hence I think shares in smaller online marketing companies fail the first, and simplest test for investments - are profits sustainable? Often they’re not.
Key numbers for H1 -
Revenue down 33% to $28.8m
Operating profit of $6.0m benefits from a $4.0m impairment reversal, which obviously has to come off, reducing real operating profit to $2.0m (down 58%).
Balance sheet - looks weak. NAV of $105m includes $113m intangible assets, so NTAV is negative by about $8m. Creditors includes nearly $8m in deferred consideration, so that would use up all the $7.3m cash pile.
Since the half-year end it has raised $4.0m from the sale of some domains, so that helps. So there could be other hidden value within intangible assets, possibly?
Cash generation - EBITDA looks meaningless, because it capitalises a lot of costs into intangibles. In prior periods cash generation was quite good, but that seems to have dried up in H1 2023, and the previous tax credits have turned into a $2.77m cash outflow for income tax, which absorbs nearly all the cash generated in H1. Seems odd. The commentary says this relates to previously underpaid taxes from 2016-20, which doesn’t inspire confidence.
So overall, not a cash generative business any more, it seems.
The commentary also says XLM is exploring the option of setting up a bank borrowing facility, which reinforces me worry that cash generation, and liabilities payable could now be problematic.
Outlook - key points are these -
Actions to reduce the Group's cost base during the period will provide further benefit in H2.
As a result, the Group expects full year adjusted EBITDA to be broadly in line with management expectations.
As noted previously, the Group's performance will continue to benefit from period revenue spikes resulting from new online sports betting state launches in the US, however the timing, number and scale of launches will vary significantly.
Paul’s opinion - as is often the case, once we start digging into the detail, an amazingly cheap PER (the StockReport shows this as only 3.6x) is cheap for good reasons.
I see XLM as a shrinking business, that’s now struggling to generate cash, and has more liabilities than current assets, with tax arrears liabilities and deferred consideration creditors looking potentially onerous. Hence divis seem very unlikely.
Maybe new management will be able to lick the company into shape, I don’t know.
For me though, this sector is a no-no, and I can’t see anything positive in these numbers, so on balance I think AMBER/RED best reflects my view of things at this point in time. Who knows what the future holds though? It could get better or worse, I have no view on that.
Eenergy (LON:EAAS)
5.8p (£20m) - 12-month Interim Results - Paul - RED
eEnergy (AIM: EAAS), the net zero energy services provider…
It’s reporting a 12-month interim period, because the year end has been changed from 30 June to 31 Dec 2023, thus creating a one-off 18-month period.
Readers discussed this share yesterday, and seemed to think it might look interesting, so I’ve had a look at the figures -
Impressive revenue growth up 50% to £33.2m
Adj PBT up 34% to £2.7m - this number looks inflated to me, as it ignores costs like £0.5m share options which it claims are exceptional, but happened in both years!
Statutory PBT of £1.1m looks a more realistic performance measure to me, and is much improved from a £(2.2)m loss last year..
Note finance costs have shot up, at £1,050k
There is no historic track record of profitability, it’s been growing fast, and this seems to be the breakthrough year into (modest) profit.
Balance sheet - this is the problem area. I very much dislike this sector, of energy consultants. The pattern is often that they report good profits, but ever-increasing receivables, bank debt, and eventually even insolvency when they fail to collect in the receivables. I can’t remain the company name, but that happened a few years ago for a share that we discussed here a lot. It always looked cheap, but profit never turned into cash, and it eventually went bust.
Unfortunately EAAS reminds me of those numbers. Its balance sheet is weak, with NAV of £24.1m containing £28.8m intangible assets, thus NTAV is negative at £(4.75)m.
There’s also a bloated receivables book of £22.9m, which looks huge compared with £33.2m annual revenues - that’s about 3-times what it would normally be. Hence the excess raises questions over whether it will be paid by customers, or disputed? Also it requires bank borrowings to finance this bloated receivables book. There’s £7.75m of borrowings, and only £1.3m of cash, so the financing position looks weak to me.
Cashflow - is negative, because all the profit is sucked into receivables, this year and last year.
Paul’s opinion - I think this might need an equity fundraise. Being cynical, maybe that’s why they’ve recently hired Equity Development, to drum up some interest in the shares before a placing? All too often private investors are the cannon fodder to pump up a share price, in advance of fundraisings (often at discounts).
The key thing is that I’ve dodged a lot of bullets over the years by bargepoling all shares which build up excessive receivables books, because they nearly always end in disaster. I learned this the hard way, by incurring a heavy loss on Accident Exchange (very similar business model and numbers to Anexo (LON:ANX) now).
For this key reason, I’m not prepared to give Eenergy the benefit of the doubt. It may operate in a fashionable area, but for me cash is king, and that ballooning receivables book tells me that it has a bad business model, and has significant financial risk.
Sorry about that. I expect the readers who asked me to look at this one are probably now wishing they hadn’t!
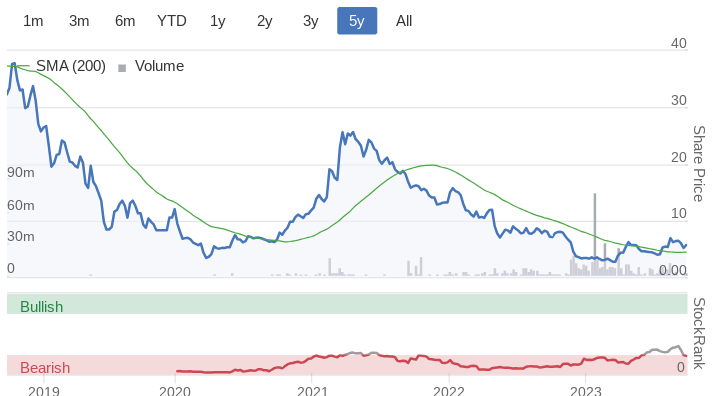
A very poor share price performance, and low StockRank are further negatives -
Future (LON:FUTR)
Up 16% to 827p (£986m) - Full year trading update - Paul - AMBER/GREEN
Future plc (LSE: FUTR; "Future" or "the Group"), the global platform for specialist media, today provides an update on its performance for the year ending 30 September 2023.
It’s only in line with expectations, so why is the share price up 16%?
Adjusted operating profit is expected to be in line with the Board's expectations1, delivering a resilient performance despite continued macroeconomic volatility impacting our sector.
1 Company compiled consensus for adjusted operating profit is £254.1m
Wow, that’s a huge number, adj operating profit of £254.1m, for a market cap of £986m. What’s the catch I wonder?
The rest of the announcement is quite brief, so here it is (as usual I add the bolding) -
Audience numbers have stabilised in the second-half and the Group has had positive month-on-month momentum in the final quarter.
However, overall trading conditions remained mixed, with challenges in consumer spending and the digital advertising market. As a result, Advertising and Affiliates product trends are broadly in-line with the first-half, as expected, despite a robust Prime Day in July.
Go.Compare (price comparison) revenue has accelerated in the second half, reflecting favourable market volumes with consumers looking for value.
Magazine revenue has remained resilient.
Foreign exchange has been a headwind in the second half, given currency movements in the period.
Interim results - for H1 3/2023 - I’ve had a look through these (published on 18 May 2023) for context. Key numbers -
Revenue flat at £405m
H1 adj operating profit of £130.3m, down 3% on H1 LY. Hence today’s guidance for £254.1m implies a small step back to £123.8m H2 adj operating profit, hardly a disaster, and given tough macro, could be seen as quite resilient I’d say.
Adj diluted EPS of 71.2p in H1 (down 12%)
Lots of adjustments, but the main item is amortisation on acquisitions, which is fine to adjust out - that’s what almost everyone does, and is generally accepted by almost everyone!
Lots of debt - net bank debt was £391m at 3/2023, but huge facilities of £900m, so tons of headroom. Bear in mind that operating profit numbers above won’t include the considerable finance costs of the borrowings.
Outlook was cautious, guiding towards lower end of expectations (this is back in May 2023, remember).
Balance sheet - as I suspected, a really low PER often points towards a weak balance sheet. This is pretty grim from my value investor point of view. How does £1.66bn in intangible assets strike you?! Although to be fair, given the nature of the publishing businesses, a lot of its subsidiaries do have intangible value that could be realised in a sale.
NAV is £1,057m. If I write off intangibles completely, and the (I assume) associated £122m deferred tax, then my adjusted NTAV comes out at negative £(481)m. That’s obviously not ideal, but I think it can be justified, given that the acquisition goodwill is for decent, cash-generating but asset-light online businesses. For this reason, I’m not having a fit over the negative balance sheet.
Bank debt is rather too high for my comfort, at £391m net debt (about a third of the market cap). So the business is heavily reliant on its bank facilities. I’d prefer to see it hold fire on any more acquisitions, and pay down some debt.
Valuation - the StockReport shows consensus EPS for FY 9/2023 of 140p, which ties in with the 71.2p in H1. Today’s higher share price of 827p is a PER of 5.9x - that strikes me as an attractive price.
Even if we very crudely adjust for the debt, of about half the market cap, then the PER would rise to about 9x (a bit less actually, as finance costs should be stripped out, if we’re stripping out the debt, but I’m only working out a ballpark figure here).
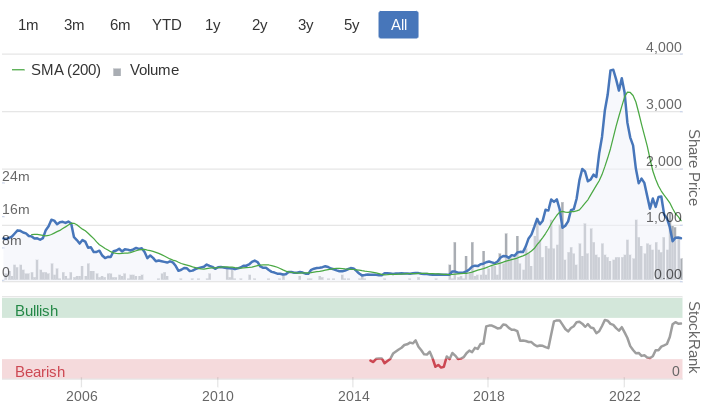
Looking at the historic share price chart, this company has commanded a seriously big price premium in the past, but looks like it’s now maybe overshot on the downside, and is priced like a value share - probably because investors may be worried about macro, and the debt burden?
Paul’s opinion – I was expecting to be cautious or even negative about FUTR, but having worked through the numbers with an open mind, I’m actually quite positive on this. It seems to be trading resiliently, and arguably the share price might have overshot on the downside perhaps? Therefore I’ll go with AMBER/GREEN - it’s worth you taking a look, and doing your own more detailed research, please remember we only have time to do quick reviews here. Let me know what you think!
Time to jump on the rollercoaster again maybe, if you have the stomach for it!?
Graham’s Section:
Ebiquity (LON:EBQ)
Share price: 43p (-6.5%)
Market cap: £59 million
A “broadly in line” outlook statement has rattled confidence here:
Ebiquity plc ("Ebiquity" or the "Group"), a world leader in media investment analysis, announces interim results for the six months ended 30 June 2023 ("H1 2023").
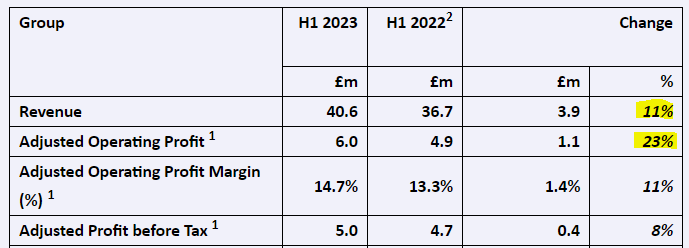
The company’s H1 financial highlights do look encouraging to me: revenues up 11% and adjusted operating profit up 23%:
I last looked at this one in February, when financial momentum also seemed to be very positive.
However, it’s important to be aware that the numbers here are complicated by the adjustments. For example, Ebiquity’s full-year results for 2022 showed an adjusted operating profit of £9.3 million, but an actual operating loss of £5.9m.
Often this happens when a balance sheet is stuffed with intangibles (e.g. as a result of acquisitions), and the value of these intangibles needs to be written down over time.
At Ebiquity, the balance sheet is worth £45m but this includes £53m of goodwill and other intangibles; strip them out and tangible worth is negative.
For the latest H1 period, thankfully I see that Ebiquity’s unadjusted earnings are at least positive (operating profit £2.4m, PBT £1.4m).
Net debt has increased from £9m (December 2022) to £15m (June 2023). One of the major reasons for this is a negative cash flow from operations in H1; checking the footnotes, I see that Ebiquity made a very large (£16m) payment relating to a 2020 acquisition. Of this £6m was paid in cash and £10 in the form of new shares.
This neatly explains why net debt is up and also why the share count is now around 140m (up from 120 million in December 2022).
The company says that this large payment is twice the amount expected at the time of the acquisition - “reflecting its strong performance”. So not necessarily bad news! Future cash flow performance could be much better, unhindered by these acquisition payments.
Outlook
We get the phrase “broadly in line”, implying that trends are slightly below expectations. This explains today’s share price fall:
A small number of large clients have recently reduced budgets, however, the business continues to trade broadly in line with expectations for 2023.
Additionally there is “some uncertainty for 2024” due to macro conditions, although “our business has historically been significantly less sensitive to weak conditions in the advertising market as our clients often look to us to help even more with improving marketing efficiency in such an environment”.
The view that Ebiquity can help companies make their media investments more efficiently in challenging economic conditions is repeated again in the CEO’s statements.
Clients are blue-chip and include the likes of GM, J&J, Danone and Disney.
Graham’s view
I continue to have a positive impression of this company. As I said before, it’s not really my style to invest in “consultancy” type businesses. However, as far as consultancy businesses go, this one has some attractions:
International diversification (significant revenues from Continental Europe and further contributions from North America/APAC)
Blue-chip clients
Good momentum in revenues and earnings.
Against that, you have the empty balance sheet and the significant adjustments being made to the accounts - par for the course when dealing with an acquisitive consultancy.
I’ll keep my neutral stance, albeit with a slightly more favourable view than I have for most companies in this sector.
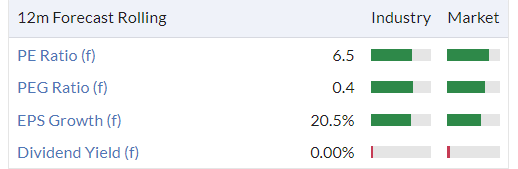
Quantitatively, there are signs of cheapness - but I would argue that cheapness is not hard to justify. Remember that earnings forecasts (and therefore forward P/E ratios) most often use the optimistic adjusted figures:
Supply@Me Capital (LON:SYME)
Share price: 0.1p (-5%)
Market cap: £61m
SYME, the fintech business which provides an innovative fintech platform (the "Platform") for use by manufacturing and trading companies to access Inventory Monetisation© ("IM") solutions enabling their businesses to generate cashflow, announces its unaudited results for the six months ended 30 June 2023 ("H1 2023")...
I don’t think I’ve studied this one before. Browsing its website, I see that the idea is to allow companies to put their inventory on a blockchain; they can sell the inventory in exchange for digital tokens, and then buy the inventory back when a customer in the real world wants to buy it.
To someone like myself, who failed to get on board the crypto train and who still doesn’t get it, this sounds like it is probably a waste of time. But let’s see if it works out.
Note that businesses on the platform won’t sell their inventory directly to SYME; a separate entity will take care of that, which has been sold to former directors of SYME.
Speaking of which, there are significant related party transactions. Let me try to explain:
Regarding the sale of that subsidiary to former directors, the £2m amount due from that sale has not yet been paid to SYME. The CEO (through his own company) has assumed the obligation to repay it to SYME.
Separately, the CEO has also offered to lend £3.5m to the company in a working capital facility.
So if I’m reading it right, SYME could find itself in a position where it is both owed money by its CEO, and it has borrowed money from its CEO, at the same time.
It’s always important to be aware when these sorts of transactions are happening, as they can lead to complications (not always good ones for the minority shareholders!).
Financial performance: H1 highlights show revenues of £0.1m (last year: nil). It sounds like they are still very much in the preparatory stage, before a full launch.
Operating loss is £2.3m (last year: £2.1m operating loss).
Looking ahead:
With the completion of inaugural IMs, the Group now expects to start to build a demonstrable track record of revenue generation as it scales delivery of new IM transactions.
They have a “pipeline” (inventory to be monetised) of £404.5m.
CEO comments:
The past six months have been productive for SYME, with our team working tirelessly on several key development workstreams. I am delighted with the progress we have made. We've started to build our track record on IMs which have unlocked a significant increase in engagement and interest in the SYME Platform, both in our core markets and further afield. Our pipeline is strong and the experience we have gained continues to streamline the onboarding process.
Balance sheet: the company has almost zero cash in hand, and has borrowed €1m from an Italian bank. Net assets are negative (minus £2m).
Graham’s view
I don’t see how to avoid giving this stock the thumbs down. It is effectively pre-revenue, and therefore it is still at a very speculative stage of development. The balance sheet is in the red, and the web of related party transactions are another hurdle when it comes to having any confidence in the outlook for private investors here.
I also don’t believe in this technology; others do and that’s fine.
So this one is getting the thumbs down from me; I feel safe in my belief that the risk:reward here is very poor. Hopefully this one can be the exceptional early-stage company that succeeds, rather than the typical story of high hopes and subsequent failure.

Cavendish Financial (LON:CAV)
7.9p (unchanged) (£29m) - AGM Trading Statement - Graham - GREEN
The combination of investment banks finnCap and Cenkos now has the unfamiliar name “Cavendish Financial”. The merger completed earlier this month, creating a business with nearly 200 staff and 220 quoted clients - making it a heavy hitter in the markets we cover here.
Staff have moved offices, trading has moved to a single platform, and there is “substantial progress” with IT integration.
I share their belief that the synergies should be significant and that the combined group should be stronger than the sum of its parts. In difficult market conditions, I think it makes sense for companies in this sector to consolidate and create a stronger group that should hopefully be very profitable in the next bull market.
Speaking of market conditions:
Trading across the City has been quiet during the Summer, but since merger completion the Group has already announced a number of significant transactions which will close in the coming months including acting as sole adviser to Round Hill Royalty Fund Limited on its offer from Concord Cadence Limited, fundraisings for Haydale Graphene PLC and Shield Therapeutics plc and obtaining key regulatory clearances for the equity financing of Allergy Therapeutics by ZQ Capital and Southern Fox.
Graham’s view
As of March 2023, finnCap had tangible equity of £12.5m.
As of December 2022, Cenkos has equity of £22m.
The combination now has a market cap of £29m (there are 362 million shares outstanding, at about 8p each).
I am waiting to see a financial statement from Cavendish but I’ll tentatively give it the thumbs up on the basis that it will be in an excellent competitive position in the next bull market (if there is another bull market!) and there is a good chance that the market cap is offering a discount to tangible equity.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

68 comments
Good news - for anyone interested, I'm now up-to-date with my podcast weekend summaries, it's been BOGOF weekend, with Episode 38 on Saturday, and Episode 39 today (Sunday).
Mystery shares are -
Spectra Systems (LON:SPSY) - Monday's SCVR, 25 Sept
Wilmington (LON:WIL) - also Monday 25 Sept SCVR
Redde Northgate (LON:REDD) - Tuesday 26 Sept SCVR.
My summary spreadsheet is also now up-to-date, very useful quick reference too I use it a lot myself, so happy to share it with Stocko subscribers.
Best wishes from Gozo!
Paul.
hi graham its not if there if there is another bull market but there will definitely be one otherwise as the private said in dads army were all doomed so buy the good biscuits while they are still on offer.
Future (LON:FUTR) (I hold)
Hi Paul
Thanks for your commentary here.
I hold and have been buying since May this year. Out of all the shares that I track it's one of the few where I see serious upside and I don't quite understand the rationale for the market cap being so low.
That gives me an EV of £1.4b (after today's rise)
A
Hi Paul,
I can't recall exactly where I saw the article but it stated that Future (LON:FUTR) share price was under pressure recently because AI was going to remove Future's moat.
Have a great weekend. Andy
Can confirm this - price drop was pretty much immediately after ChatGPT was rolled out IIRC, and thoughts were that AI would eat it for lunch. Not sure that's really playing out so far given AI is still rather generalised and not always up to date.
Interesting as they have been doing share buybacks and oscillated up and down a little since indeed.Personally, I do definitely see a distinct moat in their brands (whether the intangibles are worth what is stated on the balance sheet - i've no idea).However, if you like, trust and subscribe to a certain perhaps niche, hobby magazine or online publisher and willing to pay for the privilege, you aren't likely to switch to an AI written brand easily in my opinion.They are communities built around a trusted premium brand.
UK economy grew faster than estimated since Covid
The latest figures from the ONS indicated that the UK's economy has grown by 1.8% since the pandemic started, whereas the previous estimate was a 0.2% contraction.
One wonders if they know what 2+2 equals. -4?
Baffling. Oh, by the way, forget the gloom, we’re the best.
Apologies for being off-topic, but I think it's worth Stockopedia members having a look at the latest Lex Fridman podcast if they haven't yet seen it. Mark Zuckerberg has taken a lot of flak over his Metaverse vision, but the tech is now getting there.
Thus far, avatar-based demonstrations have been cartoonish and have consequently been dismissed as frivolous and a technological dead-end, so this is a key moment in the development of VR and in my view will, over time, have profound implications for many of the companies we invest in.
Impressive as it is, bear in mind that you are seeing this in 2D, whereas Lex and Mark are seeing each other in full 3D, a fundamentally more powerful experience. Lex’s reaction says it all, and throughout the interview he can’t stop commenting how blown away by it he is.
If you haven't time to watch the full episode, just go to 57:49 for their final thoughts.
I heard him talking about this during the Walter isaacson interview - think he was 'scanned' for several hours for his avatar. Look forward to watching it
Saga (LON:SAGA)
It always surprises me why this dull but complex and deeply disappointing share provokes so much emotion and divisive commentary on here.
Surely there are much simpler, safer and more rewarding opportunities to invest research time on?
Just my opinion for what it's worth.
Snazzy
Saga (LON:SAGA)
must admit i am a bit belligerent when it comes to this share so aplogies if i keep trotting out the same old crapola thats starts of the same cycle of arguments. In my defence i read the updates and have been hoping for that signs that profits would start creeping back up towards the £100 mill per year mark ) or certainly over the £50 mill per year mark that would provide much needed safety net ref 2026 bond - but no sign of that happening any time soon - saga definitely has possibilites to double and some from where it is. As you say though other safer options and i suspect a few have been burned here buying at higher prices by the possibility that the company would be churning out better numbers than they are doing.
Hi Snazzytime,
Saga (LON:SAGA)
It always surprises me why this dull but complex and deeply disappointing share provokes so much emotion and divisive commentary on here.
I read your comment, and expected to find a big slanging match below over SAGA in the reader comments. But far from it! What I actually found were some excellent varying viewpoints on the share, explaining why they held differing views, which is exactly what we want here - well reasoned debate.
You are right though that SAGA is quite complicated to research, but sometimes those are the more interesting situations, where valuations can be wildly wrong sometimes, thus providing potential opportunities.
I don't have a particularly strong view either way on SAGA, but given today's positive update, I'm leaning slightly towards the positive side now, after being neutral earlier this year. We just adapt to the changing facts & figures.
Regards, Paul.
Re Supply@Me Capital (LON:SYME) , there's a note buried in the interims that might call into question the wisdom of relying on the CEO's funding promises (via his vehicle TAG) :
.."On 30 June 2023, the Company issued a draw down notice to TAG under the amended TAG Unsecured Working Facility for the full GBP800,000 available. As at 30 June 2023, no funds had been received from TAG in respect of this facility, however subsequent to 30 June 2023, and prior to the release of these unaudited condensed consolidated interim financial statements [Ed.: maybe only a few days ago?] , TAG had provided GBP245,000 of the GBP800,000 that had been drawn down by the Company..."
And it's at least possible that that £ 245K only came in thanks to an odd transaction with another 'connected' company.
AIUI
Supreme (LON:SUP) Evil on a tear.
A small director purchase has just gone through over at XP Factory (LON:XPF) . Just under 30k, not huge but a show of support from the COO. (I hold)
Indeed, nice uptick as well today
Hi Ben,
Yes it's interesting how Director buys seem to be triggering waves of private investor buys at the moment. Although it looks as if the surges can be quite brief. We saw that with On Beach group (LON:OTB) for example. I reckon a lot of traders are banking 10-20% gains as quickly as possible.
Regards, Paul.
I have asked for it to be possible to set an alert for Director trading. Please add your weight to this request if you agree.
I have asked for it to be possible to set an alert for Director trading. Please add your weight to this request if you agree.
This works very well on Sharepad, so it should not be impossible
I have asked for it to be possible to set an alert for Director trading. Please add your weight to this request if you agree.
This works very well on Sharepad, so it should not be impossible
Indeed - and on AJ Bell as well: Directors dealing | AJ Bell
I'm hopeful that the On Beach group (LON:OTB) selling is done for now, as it has retraced back to re-test the supply/demand zone indicated here with the blue box. Optimistic that we'll see it push, medium term target for me is 140p.
I (X) Net Zero (LON:IX.) I know investment companies are not touched on very often here but the near doubling in NAV announced today and the large discount to NAV (I make NAV After tax provision about £1.10) look very appealing, albeit with much of the portfolio in one stock. I just wondered if any readers had any thoughts on it ?
Saga (LON:SAGA)
the fact Saga have to rely on the largese of Sir Roger and they need to formally confirm that (presumably to keep peps they owe "content" to the market kinda confirms to me this is a straight red flag. The other one is the distressed 2026 bond only trading at 79 - its trading at that level as there is risk albeit modest that bondholders may not get their money back. If bondholders are at modest risk the risk of equity placing must be above modest. It doesnt need much to go wrong for shareholdsers to be screwed over ala Revolution Bars - steady trickle down in price which panics the market and curent shareholders and then diluteds to oblivion to keep the lights on. I am not predicting that shareholders will be diluted to oblivion here - just that personally for me finding the spare 250 mill by 2026 on top of the ship repayments they need to make and catchup ref deferred debt payments they didnt make previously is to me much less plain sailing then Paul seems to think if we are saying they will do that with no dilution - we all know what happens with lkowly price and impending refinancing that appears over the horizon the market doesnt like it. If profits were £50 mill plus per year perhaps no biggie - but current management have managed to not deliver decent profits despite the current environment for cruising being good and companies like Hiscox saying the insurance outlook is fine and Dandy. If holders of debt rate this as red flag ref bond prices i dont see how sharholders can do anything other than red flag it either - thats just my opinion here reality is it may not be an issue on balance of probabilities Paul's opposite not a problem standpoint may be right in some respects i probably rate chances of them managing to limp on without dsoingh rights issue above 50% but not by much!
Saga (LON:SAGA)
We are in a cyclical trough for insurance though at an industry level - the insurance market is generally very good at re-pricing but there is a lag which is what we are seeing now. So assuming they know how to run an insurance business then in next couple of years you should see a big upswing in insurance profitability. If you combine that with the current trajectory on cruise and travel then you could quite happily see well north of £50m p/a free cash flow.
In reality I’m not sure I share your view on the Chairman loan facility as a red flag. They could have avoided this through the sale of the insurance business but felt it was wrong time in the market cycle (they had agreed a price so deal was there). They are correct in my view not to sell. Secondly they have enough cash to cover the bond repayment if required but a facility is beneficial to ensure sufficient working capital. At 10% why go anywhere else? You’re not going to get a much better rate and you have far greater control and flexibility.
Bonds at circa 80p aren’t a massive red flag either. They are pricing in around 15% yield per annum which isn’t pricing in a particularly high probability of default. Remember yields up prices down so when interest rates rose from 0% to 5% that created quite a big fall in price to get to the same risk premium.
All in all I think it depends on whether an investor believes they are in good control of the insurance division or not. If you do then £50m group profits should be easily achievable as the repricing lag unwinds.
Saga (LON:SAGA)
I dont necessarily disagree with your assessment that the loan from Roger is a good thing , its deffo a good thing if it keeps them out of a hole financing wise - the reality is though its entirely at his discretion whether it continues to exists and without it tougher choices would need to be made as you have agreeed . Any company that is reliant on third party generosity like this really is under the kosh somewhat.
I was looking for some confidence ref insurance bounceback and there was none - Hiscox have great outlook. Insurance did well previuously so why have they have got it so wrong when others are managing to make decent money again doing the same - underwriting hopefully may bounce back but without them providing any confidence they will strat making the money they probably shoudl do why should we be more confident than them.
Bonds at circa 80p aren’t a massive red flag either. They are pricing in around 15% yield per annum which isn’t pricing in a particularly high probability of default. Remember yields up prices down so when interest rates rose from 0% to 5% that created quite a big fall in price to get to the same risk premium.
It doesnt have to be high probability of debt to be red flag for shareholders - minor % chance is probably enough as shareholers are normally shafted in advance so that bondholders are settled - would you not agree ? - so the reality is bondholders could be fine but at the expense of dilution - for this very reason i see nil floor below which the shareprice could go - unfortuantely the lower the shareprice the harder it is to raise tehn money from shareholders easily.
My thoughts here are not really aimed at experienced investors here they can pay their money and take their chance - just that saga has already halved from 250p to 125p and could easily halve again. Some companies have decent floor on shareprice if they have sound balance sheet there is none of that here with the debt - arguments of those more positive than me seem to be - yeah it could happen like that but wont.
I don't think you can infer a company's prospects from bond prices all the time (it is a useful indicator, I agree, but not the only indicator) - due to the big increases in interest rates since they were issued.
An extreme example is the Austrian 100-yr bond.
Currently trading at 62. Back in 2019, issued at Par or slightly above I believe.
Does this suggest that the Austrian government is a worse credit rating at the moment than Saga (LON:SAGA) ?
No - because there are many other factors, including the coupon rate of the bond, as well as the duration, etc.
------
I also think that looking at only historic insurance profits, from the past 1-2 years, is not the right way to evaluate most insurance companies. There has been a massive shock to their business model (on the claims side). Better to rely more on projections going forwards, as well as further back historical trends (2017-2019) for some guidance.
------
Finally, while cruise bookings are still all rosy at the moment, this is one of the most expensive type of holidays one can take. Granted, their target market (older, affluent) are less likely to be impacted by economic shocks. But travel is not all rosy at the moment; there are signs of wobbles going into Q4.
Saga (LON:SAGA)
Better to rely more on projections going forwards, as well as further back historical trends (2017-2019) for some guidance.
thats the problem here their outlook is exactly the oposite of rosy here !- here are their comments not exactly gushing with confidence. Ok they expect better operating ratio in second half from underwriting - but underwriting was loss making (£18 mill worse overall than prior year comparative) - we should loody well hope things would improve from the poor h1 underwriting - they could have said will return to former levels of profits and they didnt - simply that it would be better than iss poor.
Insurance remains challenging as motor broking continues to weigh on earnings, however, plans are underway to re-develop aspects of our operation which will somewhat mitigate this. As a result, full year Insurance Broking profitability, on a written basis, is expected to be lower than the prior year. Repricing of the Insurance Underwriting motor book from mid-2022 onwards is starting to more fully benefit insurance revenues, and this is expected to lead to an improved gross combined operating ratio in the second half of 2023/24.
Can retail investors buy the 2026 Bond via Hargreaves? Saga (LON:SAGA)
Yes retail investors can buy but I seem to remember it’s only available in size in £100k nominal clips.
As far as I can see the Saga bond is not one of the 150 or so that Hargreaves list for online trading, but they do say you can call them and they will try to buy on the open market.
**Corporate bonds**
You can buy bonds such as the the Saga (LON:SAGA) 2026 bond mentioned by Paul at both HL and A J Bell according to their websites - you have to deal by phone in both cases:
https://www.hl.co.uk/shares/co...
https://www.ajbell.co.uk/our-s...
However I am confused. The bonds don't seem to be listed on the London Stock Exchange site which is surely the definitive source? Could more experienced investors share where they find this information? Even on those bonds that are listed, such as the ones issued by Sage on the page linked above, the individual results page has no useful information - price, yield to maturity, recent trades. It only states the code of the security, the coupon and maturity date.
Also, I can't see bonds in the Stockopedia database so they cannot be tracked as part of a Stockopedia portfolio, is that correct?
EDIT I have found this interview by Paul with Paul Hawkins which answers the question. Paul (H) says that the info isn't published online, you have to dig:
Q10. Finding information about bonds - is difficult. You said previously people should just google it, but I struggled to find much info. Hargreaves Lansdowne’s website lists some info on bonds, but only a fairly small number. Where can we find more detailed info?
A10. You’ve highlighted that there is a gap in the market. Stockbrokers try to avoid this area, over fear of regulatory problems. Ask your broker to speak to Winterfloods, Peel Hunt, or Canaccord, they may well have lists of available bonds. It does require some digging, to get lists of bonds, but the brokers do have them.
Listed on Deutsche Borse not LSE and I think min size is £100k nominal (about £80k cash) From having tried to buy some a while back. Might be wrong on size tho.
Thanks David for the info on Saga (LON:SAGA) bonds, much appreciated!
Saga (LON:SAGA)
But travel is not all rosy at the moment; there are signs of wobbles going into Q4.
To defend the company their outlook is rosy to the extent that even if things slow down they are so well ahead of last year that i dont see any reason to worry - reality is their target market is mostly living it large with pension triple lock and decent savings rates on their cash - i know most older peeps seem more than ever want to make the most of life - deffo noticed a changed since covid that the older peeps seem less spendthritht than they were pre covid - probably rightly so too
Booked revenue at 24 September 2023 was £43.3m for the full year, 52% higher than at the same point last year, representing a load factor of 85% and per diem of £285. Bookings reflect a significant increase in the number of first-time buyers following the decision to offer more shorter seven-day cruises.
· At the same date, the booked load factor for 2024/25 was 30% with revenue and guests 40% and 31% higher, when compared to the same time last year.
I have traded some corproate bonds as a retail investor, but frequently the dealing spread is utterly penal, making gilts better value after you've paid the bid/offer spread!
Fair point, Q4 looks in the bag for Saga (LON:SAGA) with load factor at 85% already booked.
Next year still in play at only 30%... but encouraging that its materially ahead YoY at this early stage.
You can infer an awful lot from the so-called "credit spread" - it gets very technical as you sometimes need to option-adjust & allow for variable maturity/call dates, but in simple terms it is the additional yield you get over and above a gilt of the same maturity.
The YAS page on a Bloomberg terminal will calcuate all manner of credit spreads for you - the z spread, the oas spread, the spread to the swap curve etc etc. The UK convention is a gilt spread whereas overseas it is often to a swap curve.
However, just to confuse things further, the credit spread isn't just about compensation for the the risk of default. It can be argued the credit spread (to the gilt curve) also incorporates the illiquidity premium - i.e. you are also compensated for holding something less liquid than a gilt.
Corporate bond fund managers will deal on the credit spread, and they will compare credit spreads between issuers in the same industry and relative to the average spread for the rating band at that maturity point on the curve.
All very difficult to do without Bloomberg. And as the trading is all OTC (i.e. usually not on exchange) the trading data is hard to come by and it can be quite difficult for even the pros to observe a smooth credit spread history. Now that there are electronic platforms like Market Axess things have probably improved a bit.
The credit spread is absolutely the way to judge the credit markets view of the company and the spread to Government is the consistent and ever present number to use. The spread chart shows a significant recovery since peak in Sep/Oct 22. However, it still reflects an enormous amount of caution that bondholders perceive. Realistically, when a spread is in excess of G+500 it starts trading on cash price. The story here is really a refinancing one. The debt paydown is a misnomer as it is amortisation. The De Hahn facility was clearly enforced by the RCF banks. There is comfort to be drawn in my view that he is providing this facility, as if he doesn't his equity is at huge risk. I suspect they will seek to issue a new bond in the coming 12 months as all of a sudden the 2026 maturity comes into view. Pure Gym issued a bond with a 10% coupon this week, this suggests (all things being equal) that SAGA 5.5% 26 is trading too cheap to its rating.
nb, comparisons to the Australian 100yr is not the right way to look. The effect of duration renders this comparison pointless. You have to compare apples with apples.
I own the 5.5% 2026 and tried to buy more last year. It has since rallied. I believe it is a far better risk than the equity due to the sentiments above about a potential equity raise. Achieving a 14% return (assuming par redemption) is a return I think offers equity like return for risk in the best part of this capital structure.
Hi Paul,
I think you should pay me a modest commission for the SAGA bond that I suggested to you a couple of years ago!
Sounds like it was a good idea!
Monthly DD to ZANE?
Only teasing, love Paul. :-)
I believe you can and when they drop below 50 then it’s game over for shareholders as the bond holders become the new owners.
Keep watching Saga’s bonds and if they trade below that 50 price mark forget the existing shareholders.
The Austrian 100 year bond is not a good example of comparison with any corporate bond. It cannot be compared at all actually.
As benchmark rates rose by 4-5 whole basis points recently then it’s obvious that the price of any bond with so much high duration (100 year!) will fall massively compared with that of a 5-10 year duration.
There was a US bond trader (unfortunately he passed away last year) that he made billions in these bonds that traded below 50. He just bought all the distressed bond holders, on companies that he thought they still had a future, and effectively became the main shareholder in the restructuring process. However the shareholders were left with nothing or almost nothing.
Thanks
on SAGA its worth noting that people absolutely love the product and come back for more and more, I think that is demonstrated in load factors and forward bookings. I think in the long run provided it can slowly increase prices it will do well.
I loaded up on defence shares generally this year. The argument that the world is becoming a more dangerous place seems unfortunately to be true and that requires a more defence minded response. Simples! Equally when a leading Saudi minister says he doesn't care what the markets say the price of oil is up, it is likely to go up and that is what we have seen. I made a small turn but sold far too early. I annoy myself when I try to over complicate things!!
MS International (LON:MSI) announces a first production and supply contract with the US Navy for their gun mounts. This first contract is for $23.5Mill. and follows on from the maintenance contract announced at the start of September.
Post the 7am rns MS International (LON:MSI) have announced a large US navy order and commentary from BoD seems more optimistic than I’ve ever heard - usually super understated.
Momentum looks good. Nice to see on a friday
Yes indeed, that's encouraging news from MS International (LON:MSI) (I hold) re the order from US military.
This share is very interesting, I reviewed it here quite recently, looking at the various divisions, each of which seem to operate in interesting, but unrelated niches.
The newsflow on orders (step changes as they say) is very encouraging. Also a delayed order from last year should boost this year's numbers. So I reckon we could see blow-out results from MSI smashing forecasts for FY 4/2024.
The owner/manager Directors have been running this company for decades, so must be thinking about a retirement sale. That can be a lucrative time for outside investors, since management are super-motivated to maximise the value of the company in advance of selling it.
So yes MSI is very much a thumbs up, GREEN share for me, hence why I bought some earlier this year on the basis of the strong newsflow. Although there was a hiccup with the contract delay, but that doesn't matter if you take a medium-term view.
Regards, Paul.
Agreed Paul - I suspect there will be some blow out earnings this year and they should be sustained next given the order book now building. Surprised it hasn’t moved more but this is a long term holding for me so patience required
Great to see discussion of MS International (LON:MSI) amongst holders here. I'm still coming to terms with it! (long term holder and its currently my largest holding by some way).
The contract announcement this morning appears to be for the Mark 88 mount, not the whole system (Mark 38 mod4 GWS). It appears that the USN is breaking the system down into separate elements for contracting. Which might help to explain the relatively large size of the support contract announced last month? The mount does not include the Electro Optical Sensor (EOS) package which is off mount. I expect a separate contract for that - though whether MSI rns it is a separate question? Probably also doesn't include the Northrop Grumman Mark 48 cannon which is likely free-issued to MSI Defence Systems US at Rock Hill.
There is a separate US DoD announcement of the contract upon which the MSI rns is based https://www.defense.gov/News/C... and good to see in that the funding commitment from the US Coastguard - which helps to widen the rollout and future appeal of the MSI System?
Directors selling up? Apparently the board was asked about succession planning at the recent AGM. They commented that they were very fit and keen to get on with the job (I'm paraphrasing). Not planning to go anywhere soon.
Separate but unrelated divisions? Yes viewed today. The history reveals strong connections. iifc - Mining Supplies International - now MS International - was founded on the Doncaster site in the early 60's to forge large steel arms for the National Coal Board (the forging division). It soon expanded into large structures, particularly the lift and conveyor external superstructures and when the mines shut down diversified into petrol station superstructures (superstructure division) which is also based on the Doncaster site. The large lifts and conveyors used large electric motors and to secure supplies MSI bought Lawrence Scott, a well known international producer of large generators and motors based in Norwich. Sometime in the late 60's or 70's I don't exactly remember. When the mining business disappeared Lawrence Scott was disposed of - but MSI retained the defence division which made a range of mounts, searchlights and antennas on the old Norwich airfield site. Became renamed MSI Defence and when BMARC failed it took on the integration and support for the Naval small calibre cannon as well as its mounts. Which leaves the Branding division. Which arrived by acquiring the Nederlands based business Petrol Sign BV to complement the Superstructures move into the European forecourt business by offering a complete refurbishment and rebranding package. Hopefully not an unhelpful diversion into the historical links between the divisions?
BTW - although the defence division is rightly the primary attraction right now the investment over recent years into both the Forging and Superstructures businesses has generated much higher margin and growing operations that look well placed for growth into the future. In H1 23 these two divisions contributed 17p eps whilst defence and branding contributed nothing. After the £2m loss in branding in H2 - I imagine that similar management attention has been in place there. And if it can be resuscitated I am sure it will be. But history suggests that they will have no problem taking difficult decisions if needed. I hope it can be resuscitated - as it has the potential to be a high growth high margin business complementing the superstructures division.
I have found that forecasting results with MSI is a fools game. Generally one division or another slips on a banana skin, But I'm not happy without at least a stake in the ground. At least so I can see where I went wrong. Gossip is that the delayed contract (held up by a signature in Whitehall apparently - my guess would be at UK Export Finance or Treasury, which is pretty busy with UK defence exports nowadays ) has just been delivered to the customer country (thought to be Ukraine) . On that basis I could see 40p eps in H1 and depending upon how the USN contracts and two large Air Defence contracts announced play out - it could be 50-60p in H2. Unlike many defence contractors MSI don't tend to take profits as contracts progress but on delivery. Which makes the revenue and profit prone to extreme volatility.
Anyway if you haven't already guessed it, MSI would be my specialist subject in any quiz round! So I'll stop before I outstay my welcome, if I haven't already,
cheers
Mark
Legend
MS International (LON:MSI) Thanks Mark - really interesting post. Fascinating history and explanation of how the business works.
Hi Mark
Your comment circles nicely back to our discussion on Boon’s thread. We both agreed there was enjoyment to be had in joining our contrasting investments on their corporate journeys. And your obvious detailed engagement with MSI bears witness to that approach. Without the slightest interest in MSI as an investment, I still found your description and analysis very informative and entertaining. Good luck with the investment.
Thankyou. That was most illuminating.
Superb analysis and explanation of MS International (LON:MSI) thank you Mark! So interesting to learn the history.
Thank you for taking the time to jot all that down - you really should paste that across to a topic in the Discussion section so subscribers not here today can benefit as well.
Personal group (LON:PGH) interim results look pretty good to me, despite share price weakness of late possibly due to concerns about the impact of the loss of the Royal Mail contract. 10% interim dividend sums up the results I think as its the first increase for a few year post the Covid-19 cut. It looks like the insurance business is doing fine with nearly £30m of annualised income. IFRS 17 doesn't appear to have much of an impact here. Any thoughts?
Going back 10 -ish years, I know from personal experience the Royal Mail contract was a huge cash-cow. There was a massive workforce who were suited to the low cost insurance and where the managers were actively helping Personal group (LON:PGH) to allow time for the sales process to happen. If you go to the head office , outside you will see a statue of their lead sales man who ran the account. The margins were very fat on this insurance.
Apologies that should have been Royal Mail! Now corrected above.
Yeah, I am worried about the loss of Royal Mail. They've spotlighted/featured Royal Mail as one of their highlight clients over the years, and so even without intricate knowledge, it is clear that it is a big part of the Personal group (LON:PGH) business.
Obviously, there's a nice glide path; those insurance premiums aren't going to stop overnight post-transition.
Hostmore (LON:MORE) headlines look most encouraging . Concerns re equity raise should ease and with a successful H2 put to bed. This paves the way for a recovery back to mid 20s. For once an FD exit wasn’t a negative catalyst so relief all round. I hold.
Well done to Richard Staveley at Rockwood Strategic (LON:RKW) who bought a holding in Hostmore (LON:MORE) earlier this year. I hope his holdings in M&C Saatchi (LON:SAA) Pressure Technologies (LON:PRES) and Flowtech Fluidpower (LON:FLO) all of which I hold turnaround.
Galliford Try Holdings (LON:GFRD) one of my larger holdings also owned by the astute Mr Staveley is on a tear and should, so logic dictates, be a beneficiary of the recent sewage and raac concrete debacles.
Morning RDHOWARTH,
Are we looking at the same numbers?! On a quick early glance, I thought the figures from Hostmore (LON:MORE) look grim - a big deterioration in trading in H1, LFLs nowhere near enough to offset wage & cost inflation, debt looking dangerously high, and a stated need to refinance its facilities in Q1 2024.
Yet a lot of upbeat commentary, which doesn't seem to connect with the figures at all.
I think this looks really precarious actually. Very high risk of a dilutive discounted placing in my opinion. Why take the risk?
Regards, Paul.
Note sure I agree on that one Paul though recognise I could also be wrong.
the H1 numbers not very good but it’s the Forward look that has me intrigued. They expect to pay off debt and return to shareholder distributions and had a better net debt position than expected. That feels like they know something about cash flow that’s not directly in the H1 numbers.
The £9m of annualised cost reduction combined with an H2 lfl of +2% says they should be back nicely in profit.
To be fair I’ve only skim read the rns but it raised enough interest on the current outlook for me to think about a weekend rummage in the numbers. Need to see if they are doing a meeting too.
Hostmore
Looks dire to me .
No cash
Losing money
Debt
Horrible track record recently
A business model that is always 1-0 down as they are saddled with a license payment straight off the bat to brand owners
Flawed business model as they don’t actually own any brand value
And a no doubt highly paid turnaround team milking it in a last ditch effort .
Good riddance to bad rubbish no idea why anyone other than an out and out gambler would invest in such dross
What’s more food is dated and pretty bad too .
Bonkers in my mind to consider this .
Richard Staveley taking a punt clearly has hopes for turnaround plan and he will have a 3 year timeline plus importantly will be a beneficiary when they need to raise money or even delist .
Richard Staveley taking a punt clearly has hopes for turnaround plan
I think even Amanda would struggle with this one and she knows how to turnaround a sinking ship!!!
Whilst many of your comments are true I’m less sure they are relevant. Todays statement provides plenty of NEW information - which provides clues to a pathway to a sustainable free cash flow. A sustainable free cash flow will be great for the equity value - and add materially to current share price. When a share is down 90 % this is crucial - not rants about historic business weakness.
I guess we agree to disagree - I will come back next week with more analysis but I trust these guys to sort this one out - and believe they aren’t full of fluff. I’d focus on H2 commentary which is half way complete rather than H1 historic nos that contain all the additional costs.
Apol I am actually on holiday …
Others may have picked up on this, micro-cap builder Inland Homes (LON:INL) due to be delisted on October 4th after a lengthy suspension. Having held on during the run-down to suspension, rather than being an anti-climax it feels more like a death in the family. Other than this it promises to be a sunny Friday here in Wiltshire.