Small Cap Value Report (Fri 3 July 2020) - MANO, CMCX, NUM, TRAK, TAST, RBN

Good morning, it's Paul here with Friday's SCVR.
No preamble today, as I was too tired last night to put anything together. Let's see what the 7am RNS brings.
Police forces are apparently on a New Year's Eve footing for "Super Saturday" tomorrow's pubs opening day. It's obviously going to be carnage, and no doubt we'll have Priti Patel & other Govt ministers chastising us on Monday for the bad behaviour of a hooligan anti-social minority (about 20% of the UK population I would guess! And growing every year, it seems).
Estimated timings - should be mostly done by 1pm, but I want to cover a few stragglers left over from earlier this week, after lunch. So final finish time c.4pm.
Update at 17:56 - today's report is now finished.
Running through the list, there's hardly anything of interest today. Looking at the reader requests today;
.
Manolete Partners (LON:MANO)
546p (up 7% ) - mkt cap £237.8m
Final Results - I've not come across this company before. It floated in Dec 2018, and seems to be involved in litigation financing. Graham outsourced coverage of it to subscriber abtan who wrote an interesting piece on it here on 21 Nov 2019. Reading that piece, it's clear that this share is not of interest to me, and I'm not interested in ploughing through loads of details on individual cases in order to work out what the shares might be worth.
Having a quick skim of the results today FY 03/2020, the headline numbers look good - adjusted (for IPO costs) PBT up 40% to £9.5m.
Final divi doubled to 3p (a very low yield though). Outlook statements reads positively.
My main worry with this sector (as some readers have commented on below) is that short sellers attacked another, larger, litigation funding company, Burford Capital (LON:BUR) and the share price has never recovered - currently sitting at about 500p, still about 75% down from its peak. I remember listening to the conference call from Burford when it was fighting the shorting attack, and it struck me how many potential problems there are with estimating the outcomes of cases, realised/unrealised profits, selling fractions of cases just before the year end to establish a higher book value, etc. It sounded an absolute minefield. The more information Burford provided, the more questions it seemed to stimulate.
According to the StockReport, Burford seems to currently sit at a Price to Tang.Book of about 1, which seems a sensible valuation to me. The equivalent metric for Manolete is 7.2. The latest balance sheet as at 31 Mar 2020 only has net assets of £34.9m, a P/NTAV of a very high 6.8 times. Looking at the list of its RNSs, I don't see anything that suggests it has done a placing since the year end, so the balance sheet would still be similar now.
Clearly the business is being valued on a multiple of earnings, and net assets are largely being ignored. Whereas the short sellers smashed up that valuation basis for Burford, and hauled it down to a P/NTAV of only 1. What's to stop them doing the same thing with Manolete?
My opinion - good luck with it, but this is not a sector I would want to invest in, given what happened to Burford.
.
Another reader request was;
Cmc Markets (LON:CMCX)
CMC is doing very well at the moment, up another 17% today. That takes the market cap close to £1bn, well over my usual cut-off of around £400m-ish. Larger rival Ig Group (LON:IGG) has also been doing well this year - these companies thrive on market volatility., Although bear in mind when markets calm down, then client trading activity can be expected to reduce back down again. Also some clients will have blown up their accounts, so new ones might be needed to replace them.
That said, today's update is very strong indeed - Q1 TY is better than H1 LY! Also it says;
The Board is confident that, even in the event that more normalised client trading activity returns, with the strong underlying performance of the business, 2021 net operating income will exceed the upper end of current market consensus1.
There's a very helpful footnote (all companies should do this) saying;
1 As at 2 July 2020, the Group compiled Full Year 2021 consensus is as follows:
· Net operating income of £245.9 million, ranging from £239.1 million to £255.5 million
· Profit Before Tax of £85.2 million, ranging from £75.8 million to £93.5 million
My opinion - neutral. The price looks about right to me, on the basis that this could be an unusually profitable year, due to the exceptional circumstances. It's a good point to remember for next time there's a major market panic - when everything plunges, we should buy the spread betting companies, as they benefit from market turmoil.
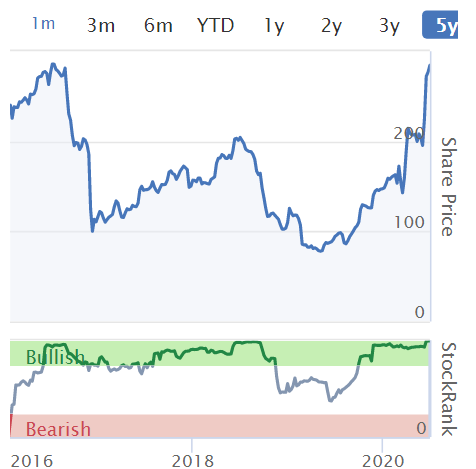
The 5-year chart below shows that it's only got back to where it started, with long periods of disappointment in between. Hence it's maybe worth bearing that in mind, before getting too excited about current strong trading? Every now and then regulatory issues surface with this sector, another point to bear in mind.
.
.
Numis (LON:NUM)
317p (up 2% today) - mkt cap £336m
Reports strong trading in Q3 (Apr, May, June 2020) - Q3 revenue "materially ahead" of Q1 & Q2.
Investment Banking benefited from an increase in capital markets transaction volumes which more than offset the decline in M&A deals and absence of IPOs. In addition average deal fees were significantly higher during the quarter as we completed capital raisings for some of our larger corporate clients such as ASOS, Beazley, Ocado, and Unite.
That's great, and I think we'll continue to see many more fundraisings this year, as companies repair their balance sheets, often under pressure from banks, who want to reduce their own risk. Although as the economy improves, then fundraising deals are likely to go back down again, in 2021 maybe? Hence IPOs and M&A will need to recover to replace the bonanza of fees from fundraisings.
Outlook comments are positive;
However, we currently have a good pipeline of transactions, and we expect revenue and profits for the second half will be ahead of the first half.
A general moan about old school brokers
Something really needs to be done about the profligate fees that brokers & various other advisers charge for fundraisings. It's money for old rope. Let's hope future financial reform sweeps away this cosy closed shop. What we need is a quicker, less complicated, and cheaper way for listed companies to raise fresh funding. The technology for quick, cheap, electronic fundraisings, has been around for 2 decades, but vested interests have successfully managed to stop any progress being made. I can feel a letter to Dominic Cummings coming on.
Numis produces excellent research on companies, but does its best to make sure that private investors don't get to see it. Whereas many other brokers make their research available on Research Tree, so there's no regulatory problem here at all.
Numis also seems to see it as their job to actively block private investors from having contact with companies, excluding them from company meetings, etc.. This is scandalous in my view, and needs to be challenged. The way I see it, if analysts are in any way guided by the company itself (e.g. chatting through & agreeing assumptions with the CFO), then it should be a requirement that such research is made widely available to everyone, not restricted to a select few important people - i.e. the broker's clients.
Peel Hunt & Shore Capital are a couple of other old school brokers that do the same thing. It's such a pity because Peel Hunt's research is fantastic. I really miss it, since circulation was tightened up after MiFiD I seem to recall.
The strength of these brokers is in their relationships with institutions, so they're good at raising money from the select few, whilst private investors often don't get a look in. When I meet companies, I always emphasise that they need a broker which sees the value of engaging with private investors. After all, we create the liquidity, and set the share price, with smaller caps.
.
Trakm8 Holdings (LON:TRAK)
21.1p (up 24% today) - mkt cap £10.6m
An impressive contract win announced today - 2 years minimum term, with a "major UK food retailer".
... utilises Trakm8's market leading algorithm to optimise home deliveries. There will be some initial customer funded engineering integration activity in advance of product going live later in the year.
No financial details are given.
I like the sound of this. One of my concerns with TRAK is that it seems low down the value chain, not making any profits from a sector where e.g. competitor Quartix Holdings (LON:QTX) produces fine profit margins & cashflows.
However, if TRAK's algorithm saves companies money by better planning routes for their lorries, then I can see that would be a valuable service.
Can someone explain why a Director was allowed to buy £50k-worth of shares just before this price sensitive news was announced? (see RNS yesterday, showing his purchases of shares on 30 June, and 1 July).
My opinion - TRAK has a very poor track record, and a lousy balance sheet with too much debt. Therefore it will need to do a significant placing at some stage, to fix the balance sheet. However, the market cap is now low, so if it does manage to get some excitement going again, with more contract wins, then that could boost the share price and allow it to do a fundraising without excessive dilution.
I'd like more information on the contract values, sales pipeline, etc. Otherwise it's just a complete punt.
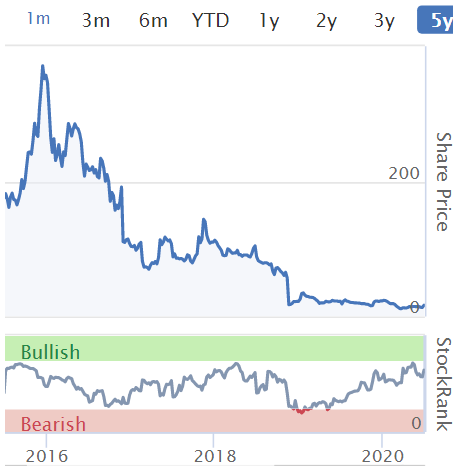
The 5-year chart shows just how bad things have been from the frothy highs when it seemed to be doing well. Could this provide an opportunity though, of a multibagger, if business starts doing well again? Unfortunately, my Tardis is out of service at the moment, so I'm not able to report from the future how things turned out!
.
.
Tasty (LON:TAST)
2.85p (unchanged) - mkt cap £4.0m
This is a chain of casual dining restaurants, mostly called Wildwood, but also some called DimT.
It's just issued an announcement, which I am reviewing because of the read-across to the wider sector.
Statement re: Redundancies - today it says;
Further to the Company's announcement on 26 June 2020 regarding the phased opening of a limited number of sites over the next few weeks, given the anticipated drop in footfall due to the continuing restrictions imposed as a result of COVID-19, the Board has come to the difficult decision that staff numbers need to be reduced accordingly.
Consequently, some 284 staff members (representing approximately 32 per cent. of the total workforce) have been made redundant across our restaurants and Head Office. Clearly, this decision has been very difficult for everyone involved and throughout this process our priority has been to support those that have been affected.
What a pity. However, I think this it the thin end of the wedge, given that the furlough scheme has really just deferred mass redundancies in the hospitality sector.
What isn't clear from Tasty's announcement above, is whether it is permanently closing any sites, or plans to re-open all of them, in time? So I'm pondering whether the sites that do re-open are going to be running leaner on staffing (which would be bound to cause customer service problems), or if there are just going to be fewer sites trading?
Some kind of restructuring sounds inevitable;
The board of directors is exploring ways to minimise costs and to strengthen the balance sheet including investigating the possibility of new debt and / or equity capital and also discussing terms with landlords and trade creditors. Further announcements will be made as and when appropriate.
My opinion - I'm emotionally attached to this business, as I really like all the lovely waitresses in its Bournemouth site, and I would visit at least twice per week, using the 50% off food discount available on the BigDish app (in which I have a shareholding). The food is quite good, and excellent value for money with the 50% off.
However, we can't let emotions get involved when it comes to shares. I've not bought any shares, because I don't see this being a viable business on its current property leasing arrangements. I think the company needs to do a pre-pack administration, to jettison all the lease liabilities. Then do deal with landlords on minimal, or even rent-free arrangements, to enable it to continue trading. Another possible restructuring would be a CVA, combined with an equity fundraising.
I cannot imagine that anyone would be interested in an equity fundraising without some form of restructuring of the leases.
At just £4m market cap, there also has to be a big question mark over whether it makes sense to remain listed?
I really hope the lovely Bournemouth staff will be OK, and look forward to seeing them soon, and having garlic prawns on toast (which are gorgeous!) and a pizza. The menu is very bread-based. Talking of which, I think to survive on lower staffing levels, restaurants need to shrink the menu options right down, to a few of the best sellers. There's far too much choice in most restaurants I think, which is more confusing than helpful. Also, instead of cooking everything fresh, much more will need to be pre-prepared centrally, and quickly/simply cooked. Most people won't know the difference anyway, and some things improve when frozen (e.g. marinated dishes like curry, etc).
As for TAST shares, sorry but I wouldn't touch them at this stage. If it does a pre-pack administration though, as recently done by Quiz (LON:QUIZ) for example, then it's a whole fresh start, with no lease liabilities pulling things down. If that happens, then I might consider TAST shares.
In the meantime, I'm very sorry so many staff are losing their jobs, and hope they find alternative work soon. The rest of the economy is undoubtedly going to have to digest large numbers of unemployed from the hospitality sector. Although as sector expert Mark Brumby, of Langton Capital, points out - if a restaurant or bar goes bust, then what is the most likely outcome for that site? Answer: the landlord just rents it out to a new operator, who inherits the fixtures & fittings, and re-opens as a bar or restaurant. S(he) solidiers on for a year, discovers that it's not viable, and also goes bust. Then the landlord re-lets it to another restaurant/bar operator, etc.. For this reason, it could take years for over-capacity to permanently leave the hospitality sector.
.
Robinson (LON:RBN)
105p - mkt cap £17.5m
Robinson plc ("Robinson" or the "Group" stock code: RBN), the custom manufacturer of plastic and paperboard packaging based in Chesterfield...
It has a 31 Dec 2020 year end.
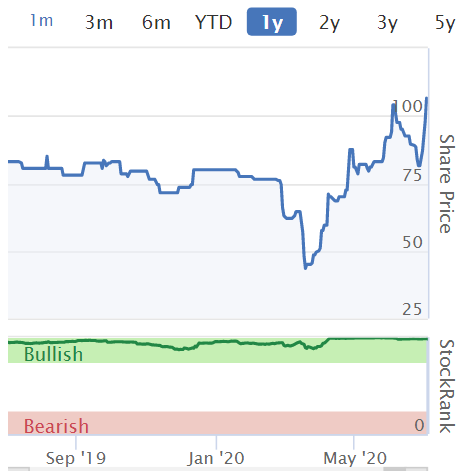
This packaging micro cap has not only recouped all its market crash share price, but is hitting a new 12-month high;
.
.
It issued a reassuring AGM update on Tuesday this week, key points for H1 2020;
Revenues - up 5% in H1 vs LY, despite challenging market conditions - this is impressive, but I suppose a lot of its products are essentials, sold through supermarkets, so demand would have continued despite covid
Margins have "maintained momentum" of H2 2019 (presumably that means they've risen?), operating costs static, consequent increase in operating profit - sounds good
Net debt down from £7m to £6m in 6 months, despite spending £2m on capex - suggesting good underlying cash generation of c.£3m in H1
Sale of surplus properties - delayed by at least 6 months, due to covid
Outlook - uncertain, but confident business can prosper
Dividends - final divi was cancelled in March. Reinstated now with a 3.5p first interim divi (same as 2018 final divi). This is very significant, in the signal it sends, but also the size of the divi is alone a 3.3% yield.
My opinion - I'm impressed. I won't be buying any myself, because it's too illiquid. Which does beg the question, why is it listed? But for those that do hold this share, well done, as the company seems to be performing well.
.
I thinki I'll leave it there for today, and this week.
Enjoy the weekend, but remember, don't have any fun, it's not allowed.
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

82 comments
Hi Paul
I am both honoured by my previous Manolete Partners (LON:MANO) commentary mention in this SCVR, and yet hurt that it put you off investigating further :)
Since your post I have, however, been in touch with the company and decided to sell my holding.
I found their response unsatisfactory and quite rude given that I have emailed them before (and received polite responses) and was baffled that I was being castigated for not signing off with my full name (which was essentially my email address + my first name clearly wasn't enough) and my position.
A snippet:
"I am not spending my valuable time conversing with someone who hasn’t the decency to properly introduce themselves."
As I'm always a very small shareholder, I would never be offended if an IR team chose not to respond to me, but I certainly wasn't pleased with that response, especially given that I have had no problems emailing in the past. In the end my decision to sell was therefore an emotional one.
For anyone interested, my initial email to them is below (with their responses in bold and CAPS).
Subject: FY20 Follow-Up Questions
"Hi (names of people being emailed)
Thank you for the results last week.
I'm going to jump straight into some follow-up questions:
1 - # CASES
Can I confirm the number of live cases at the end of FY20?
There were 84 cases at the end of FY19 (excluding cartel)
- less 54 completed cases
+ plus 141 new cases,
therefore I was expecting 171 live cases.
However, you have indicated 152 live cases at the end of March 2020 (and >200 cases at the end of June 2020).
What am I missing?
READ THE PRESS RELEASE 201 [Abtan: I don't know what this means]
2 - GROSS PROCEEDS PER CASE
FY19 £9.3m gross proceeds from 35 completed cases, so £265k per case.
This seems high in comparison to both:
a) the FY20 vintage of £188k per case (or MANO gain of £79k per case)
b) the FY19 vintage of £94k per case (or MANO gain of £34k per case)
Could you provide some more insight around the £265k figure? It is much higher than the other 2 figures highlighted.
Additionally, the below slide indicates £100k gross proceeds per case in FY20 (£76m gross cash generated/75 completed cases, from FY18/19/20 vintages).
Based on the total proceeds per case per vintage above (£188k and £94k respectively) that implies a very large skew of cash inflows from cases pre-FY20
Is there any rationale for this? I thought cash collections were relatively prompt. but this implies they actually might take several years.
IT ALL DEPENDS ON THE MIX OF CASES IN A PARTICULAR PERIOD
3 - 2016 VINTAGE
In the 2016 vintage why has the Manolete gain dropped from £2,995k to £2,979k?
This is now the 2nd time 100% completed prior year figures have changed retrospectively.
Is this an adjustment we can expect repeatedly going forward?
OBVIOUSLY SMALL ADJUSTMENTS OCCUR IF WE RECEIVE EXTRA INCOME ON A CASE WHERE WE HAVE PROVIDED BEFORE OR VICE VERSA
4 - AVERAGE LENGTH OF CASES
Average case duration is stated as 12 months.
Based on the list of large cases you have helpfully published over the last 12 months, it appears as though many large cases appear to take longer to complete.
So is the 12 month average simply the middle of 2 extremes, whereby lots of smaller cases settle within months, whereas the larger cases take several years?
IT IS THE ARITHMETIC MEAN OF ALL CLOSED CASES
5 - CASH GENERATION
Is there any concern that cash generated from completed cases in FY20 (£7.6m) is lower than FY19 (£8.3m)?
NO. AGAIN IT IS JUST THE MIX IN ANY ONE 12 MONTH PERIOD.
Thank you in advance for your responses
My first name"
The case for Tasty (LON:TAST)
- Tidied up by of offloading expensive underperforming sites
- Improved menus and marketing a lot
- Improved terms and training of staff compared to few years ago (prompted by minimum wage and Brexit considerations)
- Pre death of High St c.3 years ago this was a clear build, ramp sales and punt to private equity game
- Since then they've clearly decided that they want to be one of the last guys standing and have taken action accordingly (see above)
- They've got a lot of experience running restaurants (going back in the family with likes of Wimpey and some other US influenced chain that I've forgotten the name of...and then running thro to some recent pizza/pasta style places flipped to PE some years back)
- There was quite a lot of fat to trim from the pre death of the High Street Tasty. They've done it quite well with the help of dilutive equity raises. There's a but of admin expense that I have never been able to work out and management wont tell me more (I've met once and spoken to a couple of times). I was digging as I felt it could probably be cut out....I even felt there was possibly even as element of sort of gamesmanship (leverage for negotiations eg rent or a little bit more room for when needed). I'm far from certain about this but I felt it was there and that it could swing from loss making to profitable on it even though general conditions were a bit dire.
- They could have taken the business private in last couple of years. The equity they can raise on public markets isn't the reason to stay there as its piddling amount given valuation. The founders are likely wealthy enough that they can take private (de-list for peanuts) and fund...and probably make more money for themselves doing that. But they have persevered...that's positive for shareholders...but why they doing this?
- My guess is that its a combo of ego and proof that they can and know what they are doing when others don't (see Jamie etc).
- I thought this path seemed to be playing out quite well...at least until the Covid bomb hit
I thought the above made for a compelling option like risk-reward.
Issues
- Covid19 blew the bleeding doors off
- [Add in any other points re High St dead here and anything else negative here...I know, there are problems!]
Anyway, I've got a wheelbarrow load of shares in Tasty. Obvs its like confetti at this price. i was up on my penny punt until the pesky Covid came....I don't know how this turns out...but the owners are canny lads...a bit scary frankly in an old fashioned East End sort of vibe :) ...they most surely know the game they play and how to play it hard => I've got a hunch that if anyone is going to pull off a High St miracle its these guys.
Clearly my wheelbarrow may just be fuel for a flame out.
Exciting
If the above madness entices you....be aware that you stand to lose whatever you risk. Not a safe situation!
Ciao for now
All very good, but none of it matters. All that matters is getting out of the lease liabilities, hence TAST is uninvestable unless/until it does a CVA or pre-pack.
Thanks for your patronage and first level thinking.
Anyway, back to analysis rather than flippancy...pre covid Tasty (LON:TAST) had gotten themselves in a position whereby they had a good fighting chance and my points above paint a quick picture of that.
I acknowledge Tasty (LON:TAST) is high risk. That risk has increased due covid but perhaps also has the chance of resolution due to combination of general acute risks that all in the economy must now share, govt support (loans, probably extended furlough for sector, ability to conduct radical surgery due to circumstances which relates to shared risk thing, long forbearance on leases and/or direct support to 'high st' from govt). There's a chance covid is more a speeding of resolution for Tasty and in that perverse sense more opportunity than risk.
The situation would be improved by reductions in lease payments...but again surgery has been done getting rid of expensive trophy locations that don't fit the brand (eg they are a Kettering moderate income family brand not Canary Wharf or fancy Cobham brand).
IM(very flawed)O the dial on survival is about more than just leases and is how much can they get back to revenue and op cash flow like end of 2019 whilst reducing and stalling costs. Obvs leases are part of that (and provisions illustrate that there is some stress from it). But so are the points I make in first post and they relate to the ability to optimally manage leases too (not the CEO is a commercial real estate lawyer so add that to the owners who have personal and family restaurant operating heritage). I believe there is some flex in non wage operating costs that can come through too (they stepped up a few years back and I haven't been able to get a good explanation for what happened and whether it sustains...quite cagey).
This is not a strong recommendation from me in anyway. DYOR. This is a tiny option like holding for me and I don't do lots of work on it as the circumstances are not there to make it a significant holding and I know from experience that the company are going to be cagey and not that forthcoming.
Analysis or banalysis...you guys decide.
(PS note the following post balance sheet event from 7 Jan... "dim t More London site was assigned for a gross consideration of £2m and on 8 January 2020 the Group repaid the outstanding bank loan of £1.7m"...so another non optimal give brand focus site offloaded)
More waffle. You don't know what you're talking about.
Rents have to drastically come down. Nothing else matters. That can only be done by a pre-pack or a CVA. I've been saying this for years, and I'm right.
@mogomojoz.
I think you should put your money where your mouth is and buy a lot more shares. I also think you should stop spending your hard earned money at McDonalds and KFC.
Follow Paul Scott's lead and eat at Tasty. He seems to be doing more to support the share price than you.
Having spent 35 years practising civil litigation, for plaintiffs and defendants, I would not invest a penny in companies such as Burford. The risk of such an investment is immeasurable, in my opinion.
who would be a commercial landlord in this day and age? Pre-pack and bugger the landlord seems to be the order of the day.
Yup, it's really grim for landlords owning retail sites. There again, they've made hay for decades, so of all the people to feel sorry for right now, commercial landlords are bottom of the list for me!
"...if a restaurant or bar goes bust, then what is the most likely outcome for that site? Answer: the landlord just rents it out to a new operator."
I couldn't agree more. There is a site near me - three or four different bars in the last five years I think.
Hey Paul,
In response to your broker moan what every company should commit to is providing freely available research that is as professional as the brokers, sometimes more so, which PIs can see and comes from a properly regulated firm.
The flip side to this is that it’s not just a broker problem. PLCs also need to start treating PIs as investors who matter. Too many of them never actually look at their registers below the top FMs, others do but either don’t care or think it’s too difficult, which it isn’t, while others, often the less experienced ones, believe everything their brokers tell them! Many smaller companies don’t correlate their (usually low) trading volumes with the investor audience that is actually most relevant, which is PIs. Bottom line is that, regardless of size or liquidity, there is no acceptable reason why PIs should bot have access to the same type of information as FMs!
All that said, I have sympathy for good houses like Shore, PH, Numis etc who hold onto their best sales people and therefore their ability to raise capital efficiently: because they pay well they need to raise revenue from getting investors to pay for research. MiFID II made their model harder.
What a company really needs is one good broker and Equity Development (this isn’t the BBC so I don’t have to name the competition!). Certainly not two brokers doing the same thing.
Hannah
Quiz (LON:QUIZ) are up 40% today on no obvious news. High volume. Someone has spotted Paul's repeated comments about the benefit to shareholders from a pre-pack.
(Maybe it's Paul doing the buying).
Quiz (LON:QUIZ) has done what ALL retailers need to do - get rid of the lease liabilities.
Then re-negotiate drastically lower rents, or even rent-frees.
BUT in 2021, things could change for the better again, who knows?
Now now Mr Scott! I can see that you decided to call me a clueless idiot at 3am in the morning after being on the pop. Very naughty.
Obvs, you might be right..but if we judge it all on where the price ends up and its higher than now then I have top ragging rights over you and will be king for a day!
Thanks for your input anyway...first level thinking is often correct ;)
Your mojo
xxx
Following on from yesterday’s discussion on shopping centres:
In England, for the two-week period since non-essential retail opened on 15 June, footfall in our centres was 60% of the level achieved in the equivalent period last year and like-for-like store sales were 80% of the level achieved last year. Over the same two-week period, average transaction values were up 22% compared with last year.
https://www.investegate.co.uk/...
Trakm8 Holdings (LON:TRAK)
"Can someone explain why a Director was allowed to buy £50k-worth of shares just before this price sensitive news was announced?"
I had exactly the same thought when I saw the rns today
"Trakm8 Holdings (LON:TRAK)
"Can someone explain why a Director was allowed to buy £50k-worth of shares just before this price sensitive news was announced?"
I had exactly the same thought when I saw the rns today"
A curious one indeed.
He bought after the results release, it's common for Directors to do that (as they come out of the closed period.
As a NED perhaps he didn't have any direct visibility of these contract negotiations?
However, he is the CEO of Microlise a partner and investor in Trakm8 Holdings (LON:TRAK)
Microlise "support 14 of the UK’s 15 largest retailers" so it makes it a little less credible that he would not have known about a contract with "a major UK food retailer".
Some explanation required I agree.
Interesting comments re Numis (LON:NUM) and £CMCX. One alternative to these is £JIM. It has been reporting increased trading volumes during the pandemic volatility but doesn’t have the same regulatory risk. It also does considerable business processing trades on other companies’ behalf, including it seems for the increasingly busy PrimaryBid. With a SR of 93 and a dividend of over 5%, albeit Cmc Markets (LON:CMCX) is on a SR of 99.
Disclosure: Long JIM
Intreresting to hear your views on Numis! I had an email back from them last week to explain that they do not let private investors access their web resources. I had tried to get a logon to access their Z-score analysis of investment trusts - but all I got was a polite, no.
Similarly Winterflood have an extensive interest in investment trusts and run an annual investment trust conference / seminar. Again, an attempt as a private investor to gain access is met with a polite no by reply.
Could it be that they simply dont want the administrative hassle of dealing with the 'anoraks'?
Perhaps SIGNet and Mello could make appeals on our collective behalfs?
I think the top brokers, like Numis, Peel Hunt, etc just see themselves as above the riff-raff. We're of no interest to them, because they make plenty of money from institutions. Hence they don't need to get involved with pond life like us. Sad but true.
Although to be fair to Peel Hunt, when they acted recently jointly with FinnCap (who are excellent towards PIs) to raise money for Revolution Bars (LON:RBG) the brokers included a very large Open Offer, so that existing PIs got a decent slug of the 20p fundraising shares. That was superb I thought. We can but hope that this might be an improving trend.
Numis are highly regarded in the City. Just had a chat with my broker, who rates them highly. But he confirmed they're not even remotely interested in private investors. That wouldn't matter if they were just doing their own thing, but it disadvantages us, by denying us access to research & company meetings. Hence they're actively harming our interests, and contributing towards a playing field that is far from level. We need to campaign about this sort of thing, by lobbying MPs, etc. Otherwise nothing will ever change.
Well said Paul, your comments about brokers are spot on.
They charge excessive fees for what could be done more efficiently & fairly via an electronic auction.
The Invest Like The Best podcast episode #144, with Bill Gurley, covers similar issues with American IPOs & is a very good listen, via the Player FM app.
https://player.fm/series/2394923/242835039
Interesting article relating to travel in the Guardian - essentially travellers can't get insurance to cover Covid-19 related matters. So if you get locked down, as in Leicester, and can't travel or if you get ill overseas then you're on your own.
https://www.theguardian.com/mo...
Still, didn't seem to put off Stanley Johnson ...
timarr
I guess insurance is only a concern for those of us who lack the foresight to be wealthy enough to not have to bother.
There were a couple of comments here on Wednesday regarding the 161p bid announced for Cello Health (LON:CLL)
The price has now moved a little above that - I can sell at 161.84p and trades between 162 and 163 have gone through. This suggests a possibility of a counterbid.
The inequitable nature of taxes grows with each passing year of Govt.
Entrepreneur Relief at 10% CGT on disposals, has been reduced from a lifetime allowance of £10m to £1m . Yet Investor Relief is available for up to £10m at 10% as long as you are not a Director or Employee of a non listed company (includes AIM), and hold for 2-3 years.
So all the work and risk you do and make does not make a contribution equal to someone who may have spare cash, and is prepared to take a risk.
Trident
The inequitable nature of taxes grows with each passing year of Govt.
So all the work and risk you do and make does not make a contribution equal to someone who may have spare cash, and is prepared to take a risk.
I think thats the thing with taxes - everyone will have their own version of injustice.
The investor with £10 mill spare and a nearly unlimited choice of countries in which to invest its will possibly dictate that if they don't have a tempting rate of tax they will take their money elsewhere.
So is it really fair comparison you make if one is actually a fair rate and the other is needs must to maximise the tax take.
Perhaps the bod who does a lifetimes hard manual graft for a basic living wage and its paying 32% marginal rate on their earnings would say anyone who can get a low rate of tax on the first million should be thankfully and not complaining about the rate of tax they pay on the rest by comparing it to an artificially low rate - as on a pretty much like for like basis they are subsidising that entrepreneur on that first mill of low tax. Obviously that entrepreneur may be able to leave the country before paying and therefore perhaps pay nothing - so perhaps the hard grafter shouldnt complain either.
I may be one of the few who thinks or tax system is reasonably fair overall - i would say it is perhaps a little too fair to the really well off who can plan accordingly ref taxes. My one gripe about our system is that we let companies extract cash out of the uk (or out and back in) without paying their fair share too easily ref vat and corporation tax by claiming grants and other sham *like transactions (*legal sham) . Facebook really should be paying 19% tax and 20% vat on 90% of their revenue (est 10% running costs) earnt from uk based customers - the reality is they are probably paying almost nil vat and probably less than 10% corporation tax. For uber still not to be classed as a transport company for vat purposes is true government muppetry on an epic scale! (that phrase is so good it deserved repeating today)
Might interest some. A Tweet from Grant Shapps today
https://twitter.com/grantshapp...
Regards
Howard
With reference to Manolete Partners (LON:MANO) I used to own these, but the spread was very wide and I struggled to sell, so they appear to be an Illiquid share to hold.
Langton's daily email mentions that • A former head of the civil service has told the FT that a wealth tax is now possible to pay for Covid spending.
I don't have the FT. Was anything more specific said?
It was Gus O'Donnell speaking at an event at the IFS to launch research into a wealth tax.
I'm not sure how much insight he has into current plans beyond the obvious point that the Treasury will be looking at any and all taxation opportunities. He acknowledged there would be some practical difficulties in implementation.
A YouGov poll found that 61% of the public support a wealth tax on individuals with assets worth more that £750k. So most people favour taxes being paid by people richer than they themselves are.
When I lived in Sweden, my girlfriend's father ran a pretty successful balcony awning company (Swedes love a good balcony awning). One day I was moaning about the 30% base tax rate, and he explained he paid a 60% tax rate. I was horrified. He shrugged and said:
"Society is not free."
True.
And neither, it seems, is government muppetry on an epic scale!
I think everyone favours people richer than them paying the taxes!
The Absolute Return Letter this month spoke about income v wealth taxes and (I cant remember exactly) but I think said people are more concerned re income inequality rather than wealth inequality, which certainly aligns more with UK taxes. Although we do sort of have a wealth tax (or at least on gains - CGT).
Another thing to consider is once one is living off ones accumulated wealth a 1% wealth tax is actually c25% of the safe drawdown rate (4%) and this would be in addition to income tax / CGT.
My personal feeling is wealth tax should be dealt with by making IHT unavoidable, but currently is too easy to avoid if one is wealthy. Things like still allowing the 7 year rule re gifting for IHT make it far to easy to avoid. I've always felt that we should move IHT to the receiver and make it unavoidable (linked to nationality/residence?). The Non-Domicile rule is also mad - I know someone who claims it from his father even though he's never been to the country!
IHT is not easy to avoid unless you give assets away and survive without the money for seven years. My view is that IHT should be scrapped or merged with CGT when the assets are sold.
Yes, I always said to clients that IHT is both the easiest and most difficult tax to avoid. Easy because you can just give it away and difficult because no one wants to give it away - unless, of course, you have many millions to spare.
Yes, I always said to clients that IHT is both the easiest and most difficult tax to avoid.
The OTS IHT review from last year covered this:
In its first report the OTS highlighted the fact that very few people are currently within the scope of Inheritance Tax, with fewerthan 25,000 estates being liable each year. This is less than 5% of all deaths, even though ten times as many estates need to complete and submit forms.
https://www.gov.uk/government/...
There are 11 recommendations, perhaps the most important one for investors was the one that suggested that BPR IHT relief on AIM shares should be reviewed. It didn't go as far as definitely recommending it be removed but it did rather pointedly note that the original purpose of BPR was to stop family businesses being broken up to deal with IHT.
If they do decide to address IHT - and it really goes against Conservative Party instincts - then tidying up the use of BPR on AIM shares looks likely. I really can't imagine a Tory PM taxing ISAs although it's probably inevitable with a future Labour administration - although even then I would be very surprised if that was retrospective.
Overall they'd obviously like to go after the big internet companies but that'll be difficult while seeking a trade deal with the Trump administration. If he loses in November then it's more probable, I'd have thought, the Democrats are more likely to look at regulation and raising taxes and will need international support to make that work.
The other thing investors should dwell on is that governments are inclined to tax things that can't get away - so buildings, utilities and most people. Taxing higher earners relatively less is more about pragmatism than ideology - although multiple studies show that less dispersion in wealth creates a happier society. The World's Happiest Country report has the five relatively high taxing Nordic countries in the top seven along with Switzerland and the Netherlands.
timarr
Hi John,
Writing is not my forte and you've saved me the effort! Excellent points IMO.
I think everyone favours people richer than them paying the taxes!
Making IHT unavoidable... and stopping the trust scams. I know of someone whose kids got grants for Uni because there income was/is so low but has multiple (5) large houses!
Also (and I think I'm going off topic here) had a chat with someone who works in and end of life care home. She is incensed with people slagging the government off when they themselves were in part responsible/misguided. Examples:
Bed blocking in hospitals so they (the children) can avoid care home fees and get the inheritance.
Not recognising that many people in these homes don't want to go to hospital - they sign up for it.
Not recognising that many couples - don't want to be separated - whatever the circumstances.
There - had my rant whilst jumping up and down in agreement with you!
Hi JohnMM1969,
AIUI, in Spain tax on an inheritance is paid by the inheritors, according to their own tax situation.
So the affluent (merit, marriage etc) receive less than their poor fellow-beneficiaries (who may , 'tis true, ' be feckless; but may also be impoverished 'creatives' or religious/charity/socially motivated folk). And for the latter, the inheritance would make more of a difference/be more 'levelling'.
ATB
The IFS presentation is here:
https://www.ifs.org.uk/publications/14916
I have read the FT article - nothing specific or definite, just speculation at the current time. A think tank is in the process of undertaking a detailed, wide ranging review on the effects of introducing a wealth tax (can't recall the name of the body) in terms of tax take, inequality etc, which present its results to government. My read is that some sort of wealth tax will be introduced, but it will be a long way down the road....
While the iron is hot and everyone is worried about high gov. spending - 15% levy on all ISAs
Eh? What on the capital value of an ISA?
Pensions and homes would be excluded - all hypothetical.
Investors in Manolete Partners (LON:MANO) should be aware that the company has implemented an accounting change that could materially hit its StockRank and lead to the sort of misinformed analysis that has been levelled at other litigation financers. From page 42 of the 2020 Annual Report:
This is a technical accounting issue that I would recommend investors familiarise themselves with in relation to litigation financers such as Burford Capital (LON:BUR) , Litigation Capital Management (LON:LIT) and Manolete Partners (LON:MANO) , although it also applies to a number of private equity and multi-asset managers (e.g. KKR & Co in the US). The point is perhaps best illustrated by comparing MANO’s cashflow statement in its 2019 Annual Report (page 42) with the revised presentation in the 2020 AR (page 41).
Note that in 2019, MANO’s investment in cases of £2.405m was treated as an investment activity and formed no part of operating cashflow. Net cash generated from operating activities for that year was positive, at 955K.
In 2020 however, investment in cases has been moved from the investing activities section to the operating activities section, and 2019’s cashflow has been restated. As a consequence, 2019’s operating cashflow is now showing as negative.
This accounting change brings Manolete Partners (LON:MANO) into line with Burford Capital (LON:BUR) and Litigation Capital Management (LON:LIT) , and I think it should now be obvious that litigation finance companies are unlikely to be showing much in the way of positive operating cashflow when they are recycling cash receipts from concluded cases into new cases. Furthermore, any equity raise or increased borrowing to finance investment growth will axiomatically negatively impact operating cashflow.
So, a company working under such an accounting regime could be tremendously profitable and hugely cash generative, but could well appear as a complete dog as far as Stocko’s algorithms are concerned, since operating cashflow is a key component of the Quality and Value metrics.
Apologies for the lengthy comment, but I’ve attempted to make this point in fewer words in the past and it’s fallen on deaf ears.
Pleasure to read [and re-read] such an informative comment. Well done, sir.
A quick read of the cash flow statement under both bases shows that the issue with these companies is that almost all of their profits are ‘fair value movements’ (accounting profits not actual cash). So the key question is whether or not those fair value accounting profits convert to actual cash over time. Track record of the industry looks questionable on that front so buyer beware in my view. PE ratios etc are meaningless for companies where cash conversion is low.
Luthrin,
I think they should too.
The restated 2019 Cash Flow Statement shows a negative £1,897,000 at the operating level, adding back the "Investment in Cases" restores this to a positive £550,000 - hardly a meaningful figure in the context of a claimed 2019 Operating Profit of £7,212,000.
The 2020 figures are even more revealing. Adding back the "Investment in Cases" figure produces a negative operating cash flow of £4,177,000, in the context of a claimed Operating Profit of £9,804,000.
That may well be true; but on the above evidence Manolete Partners isn't one of them.
Bonitabeach
No position.
This reflects the rate of £mano 's growth. They work on relatively short cases which on average recycle capital in a year but the capital receipts are then reinvested in growing the portfolio. They are very clear that their capital inflows cover their operating costs despite ramping up their human infrastructure last year.
Isnt this an example of a company that has to manage a 'pipeline' of contracts. It incurs expense to manage the cases and then there is or isn't a pay off in the future (their latest case had proceeds of around half the carrying value of the claim). Its not that different from other contracting style businesses.
This leads to revenue and cost recognition issues. The only reliable number is the cash flow.
To be fair the "latest case" is not typical of the portfolio, it was £MANO trying to be clever by taking a different style of opportunity which was supposedly going to multibag and it didn't come off. I suspect they will have learnt to stick to their knitting.
"The knitting" is boring, simple and short duration insolvency disputes where there is a specific market opportunity - even more so for the next two or three year in this time of Covid.
I do agree that a valuation of 7 times NAV might be pushing the envelope a little though.
I don't think it is fair to compare it with contractors, the margins are far better for MANO.
its the cost of running a pipeline that is similar to a contractor and then of valuing the WIP. They are increasing debt which tells you something is going on.
Finals and appointment of a joint broker from Manolete Partners (LON:MANO) today. The results look strong. Is a placing imminent?
De La Rue (LON:DLAR) . Applied for more than my entitlement in the open offer and just wondering when I will know how many I will recieve and when they will become tradeable?
The timetable in the prospectus sad
New Ordinary Shares credited to CREST stock accounts (uncertificated Shareholders only)
as soon as practicable after 8:00 a.m. on 7 July 2020
Thank you
Don't forget that if you applied from a nominee a/c you will not get the proportion announced by the company because you are lumped together with others as one shareholder. If others within your nominee do not apply then you will get a higher % than that announced.
Just published piworlds webinar from yesterday, here. David Thornton Editor of Growth Company Investor discusses small caps, with his current tips including Venture Life (LON:VLG), Accrol Group (LON:ACRL), Codemasters Group (LON:CDM) (helpful to timarr above?), AFH Financial (LON:AFHP), Victoria (LON:VCP). Plus some great audience questions. And a special offer on Growth Company Investor. Enjoy.
(Or as a podcast here).
Codemasters Group (LON:CDM) (helpful to timarr above?)
Hi Tamzin
It was really interesting. I recommend it (and all of your other webinars) to the assembled masses. Keep up the good work!
timarr
Any time to look at Manolete Partners (LON:MANO)? It seems to be an interesting COVID proof company in the legal services sector.
Thanks,
Jim
Codemasters (LON:CDM) are releasing a trading update today also. can you provide your view on them Paul?
Codemasters (LON:CDM) are releasing a trading update today also. can you provide your view on them Paul?
Are they? Can't see it. It would be surprising, they only released their results 3 weeks ago.
timarr
Here's a link to Codemasters Group (LON:CDM) FY20 results presenation from last week, which was very helpful.
Cmc Markets (LON:CMCX) markets continue growth. With FY21 Q1 number already above FY20 half-year. I've pencilled in 20% growth for the year. PBT should exceed £120m. Valuations look north of 400p. (see valuation model).
(i hold a long position).
DYOR)
BSV
Cmc Markets (LON:CMCX)
With FY21 Q1 number already above FY20 half-year. I've pencilled in 20% growth for the year. PBT should exceed £120m. Valuations look north of 400p. (see valuation model).
I hold quite a lot of these too but it's clearly a volatility play and has benefited a lot from the pandemic. It was undervalued to start with, mind, but there's the ever present possibility of more regulation or a tax raid by impecunious governments or a hedging problem (as Graham has alluded to in the past).
Not that I'm selling, but I don't think we can just assume this will carry on going up forever.
timarr
Hi Timarr,
Q1 results are good. Its just a valuation model with some assumptions built-in. I'm not implying this will or will not happen. Just what the valuation might look might if it did.
BSV
It will be interesting to see how the Robinhood platform pans out in the UK. I suspect that it may act as a feeder for both CMC Markets (LON:CMCX) and IG Group (LON:IGG).
I am heavily in CMX peers IGG +51% and PLUS500 +26%.
I am getting sleepless nights about my exit strategy on PLUS500. It has a habit of violently correcting (taking off the table my dreams as it plummets back to earth Icarus like).
I strongly agree with the comments about risks with hedging or one bad news release citing new regulation and puff, 25% gone in seconds.
TBH, my cortisol levels will be easier once I take my money and run.
Can anyone tell how much a little bit longer to hang in for?
I am getting sleepless nights about my exit strategy on PLUS500. It has a habit of violently correcting (taking off the table my dreams as it plummets back to earth Icarus like).
With Plus500 (LON:PLUS) it's always worth keeping an eye on director sales and purchases, the timing of which seem to be a good indicator of future share price moves.
In terms of quality as vouched for by hedging policy I think it's reasonable to say that Ig Group (LON:IGG) followed by Cmc Markets (LON:CMCX) followed by Plus500 (LON:PLUS) would be the hierarchy in descending order. The latter's hedging policy - or lack of it - exposes shareholders to much more uncertainty. Their last trading update saw profits wiped out by customers all betting the right way. Obviously that can go the other way too, but I like a bit more certainty and a lot more sleep than they can offer.
As an aside - and nothing specifically to do with PLUS - I don't invest in Israeli tech firms any more as the corporate culture seems to be quite narrowly focused on self-interest.
Anyway, good luck with the wax and feathers.
timarr
Hi, I'm sorry for being a bit slow but could you add a bit of info to explain you valuation model graph.
I would agree with every word of timarr's comment on your valuation of CMC Markets (LON:CMCX) . Also:
- It's good to get different views but I'm not sure it's a good idea to post your valuation without an explanation of how you derived it. At worst it could mislead some people because often, minor changes in these models can have major changes on the valuation.
- It sounds like your model is some kind of 2 stage growth model with no terminal valuation. If so, 7% ongoing growth is way too high. No business can continue to grow earnings faster than global GDP for ever.
- 7% growth is probably too high for the medium term, never mind the long term as these business models have struggled to grow during the good times when volatility is low.
I wouldn't criticise you for posting, but I think that if you are posting these models as you have done a few times, you should substantiate them, otherwise it becomes meaningless and potentially worse.
Hi CMpeckham, dfs12,
For £CMCX the main assumptions are in the title.
The model provides valuations historic and future at NAV (actually TNAV), PE (15) and EPV, as a range;
I find it very useful to graphically see share price mapped against valuations to decide when to buy and sell shares. I hope some on this website also find it useful.
Kind regards,
BSV
Excellent thanks. I'm not familiar with earnings power value but that's probably just ignorance on my part!
Excellent thanks. I'm not familiar with earnings power value but that's probably just ignorance on my part!
I would stay ignorant if I were you. EPV is nonsense unless you know the future, of course. The idea that a company just sails on in some ideal constant state is totally ridiculous.
All the best, Si
Thanks for stating your assumptions regarding CMC Markets (LON:CMCX) . That means that others can take a view of how reasonable these are e.g. a PE ratio of 24 (I'm rather sceptical on that). This could be discussed for ever but I think there are a few important points here:
- You say your "growth" assumption is for revenue growth. But, revenue isn't a key input for any of your chosen valuation measures. Earnings and assets are.
- Revenue growth is one thing, but it's meaningless if profits are declining. If you look at the average forecast for earnings, it shows a 22% DECLINE this year and a 27% decline for the year after that.
- You say that EPV is your central and preferred valuation method, but you don't state the key assumptions behind that. In particular EPV is sensitive to the chosen discount rate (the WACC in the original version) so really you should state that.
Anyway thanks for sharing and good luck.
Hi Cmpeckham et al,
I like the discussion this created and hope people find this as useful as I do.
The best definition for EPV I can find is Earnings power value (EPV) is a technique for valuing stocks by making assumptions about the sustainability of current earnings and the cost of capital but not future growth. Earnings power value (EPV) is derived by dividing a company's adjusted earnings by its weighted average cost of capital (WACC).
I prefer EPV as does not need to take into account future growth.
For Cmc Markets (LON:CMCX) EPV, I've used WACC of 15%.
I ignore forecast from brokers and do my own research. I think you'll find forecasts will change soon and be upgraded.
Likewise good luck for the future
Kind regards,
BSV
I prefer EPV as does not need to take into account future growth.
That may be the case but it makes all kinds of other ridiculous assumptions about the future that make it worthless IMHO. It's just a fudge of an equally pointless analysis method - Discounted Cash Flow (DCF). It assumes that the future operations of a company will look exactly like the past, which as we find out on the SCVR at regular intervals, is a ridiculous assertion on which to base an investment decision.
I looked at EPV when doing a trial of Sharepad a few years ago. If you use it as a valuation method you'd never buy anything as the EPV is almost always way lower than the current share price. Here's an article explaining it's use by Phil Oakley:
https://www.sharescope.co.uk/p...
All the best, Si
Correction PE is set at 24
BSV
Hi Paul, any chance of a quick opinion on Cmc Markets (LON:CMCX) today's update seems pretty upbeat? Thank you.
My morning smallcap tweet: Will Foot fit SHOE?
Shoe Zone (LON:SHOE) Fastjet (LON:FJET) Amigo Holdings (LON:AMGO) Capital & Regional (LON:CAL) £CTAE Trakm8 Holdings (LON:TRAK) Numis (LON:NUM) Arena Events (LON:ARE) Manolete Partners (LON:MANO), Aptitude Software (LON:APTD)
Shoe Zone (SHOE) FD scarpers. He is thanked and new one appointed - Peter Foot.
Farcejet (FJET) co will continue to have sufficient resources to meet its operational needs until the end of Aug."If flight operations do not restart to sustainable levels by the beginning of September or the Company is unable to access hard currency from the Reserve Bank of Zimbabwe through repayment against the Company's historical legacy loans, it will cease to be a going concern."
Amigo (AMGO) agrees with FCA to handle all complaints within 8 weeks by Oct. Compensation & handling cost is expected to be substantially higher than the estimate of at least £35m. Cash at hand £136m.
Capital & Regional (CAL) received or expect to imminently receive 34% of rent due in June. Several of the non payers have engaged with us regarding payments now stores are trading. Cash at hand £81m, over a year's rev. Paused commitments to the proposed Hemel Hempstead Leisure project.
Catenae Innovation (CTAE) has finalised the development of a new product 'Onsite ID', a generic multi-document digital wallet. Dev was slowed during dev of the headline-grabbing, er possibly world-beating, covid tracking app.
Trakm8 (TRAK) as trailed in Apr, wins 2 year fleet optimisation contract with a major UK food retailer that had been expected in March. No £££.
Numis (NUM) Q3 rev materially ahead of each of the first two Qs. Guides H2 rev and and profits up on H1.
Arena Events (ARE) FY (15 months) rev up 36% (19% in comparable last 12 months) and adj EPS -3 (+3.7). Passes div. Outlook extremely challenging.
Manolete Partners (MANO) FY(March) dil EPS up 70% to 17p. Final div 3p (1.49p). Outlook "With a far greater number of cases (and generally larger cases) either recently completed or in progress, the outlook for further increased material cash generation from the portfolio appears very encouraging."
In line: Aptitude Software (LON:APTD)
Morning Paul I know Graham normally is more the man for financials but any chance of a look at Numis (LON:NUM) trading update looks decent revenue up good pipeline in place looks like they have made hay with recent round of fund raisings. Caution on second half same as virtually everyone but they do look well placed at the moment.
Thanks Andy
Too tired? How about the 7.5 hour trading day that's being mooted?
Good morning RISK....
The preamble within the SCVR is 'a bonus' that Paul & Graham kindly provide .... this is over and above their primary role of commenting on the daily small cap RNS's.
Cheers JD2