Small Cap Value Report (Fri 3 May 2024) - W7L, AGFX, FLK, AGL, MIRI, TRN, MORE

Good morning from Paul, near the end of another super-busy week!
We've now covered 440 unique companies in the SCVRs in the 4-months to date. Not long hopefully until we exceed last year's 609, now we're also covering some interesting-looking mid caps too. Someone queried why I'm also mentioning nano caps lately? It's because my new mid-morning movers section picks up some of the interesting news from nano caps. Also, it helps avoid banana skins when they're junk companies that need to raise fresh equity, as many are, but trying to ramp up their share prices with spurious good news releases. It gets something into the archive for quick future reference too.
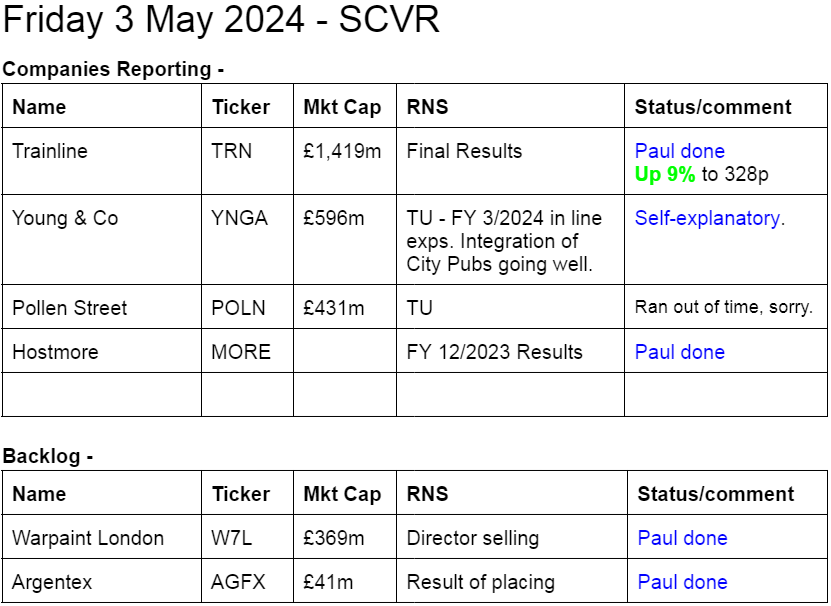
I had a late surge, and did some more work yesterday afternoon, covering everything on the list (13 companies), even if only a brief comment in the colourful list at the top. Even if it's only a brief comment, I do have a proper look through the numbers for each company, although I don't have time to read all the commentary if it's a full set of results - hence the need to always do your own, more detailed research - it's not just a slogan or a disclaimer - time constraints mean our reviews are necessarily superficial.
Also remember we're only flagging relevant facts, figures, and forecasts. I see some people on advfn were personally attacking me over Concurrent Technologies (LON:CNC) but didn't actually say which facts I had flagged up that were wrong (hint: none of them were wrong!). They just had a different, more bullish opinion, which is absolutely fine. My review was neutral, and flagged up both the positives and some negatives, which is surely the right thing to do, and then let readers decide what weight you give to each factor.
List of companies reporting
Other mid-morning movers (with news)
Fletcher King (LON:FLK) - up 26% to 44p (£4.5m) - Trading Update - Paul - No colour
A strikingly good update from this tiny firm of chartered surveyors & asset managers. No idea why it’s listed, but it’s been on AIM for donkey’s years, which cannot be a good use of cash costs. So de-listing risk must be high, which is why I can’t really give it a traffic light colour.
Trading has gone from being subdued when last reported, to buoyant in H2. It made £50k PBT in H1, but for FY 4/2024 it now says this (below), which looks rather good - are they saying £400-600k, or £600-800k PBT? It seems ambiguous to me, but maybe I’m being a bit thick? -
The Company reported a profit before taxation of £192,000 for the year ended 30 April 2023. Overall, it now expects to report profit before taxation for the year ended 30 April 2024 that is likely to be in the range of two to three times higher than last year.
Paul’s view - I like the look of this. It’s got a nice balance sheet too, with net cash of £2.6m at 31/10/2023, and hardly any creditors, so that’s proper, surplus cash I would say, supporting half the market cap.
Pity shares are so illiquid though - I just got a quote for a small scrap, and they wanted 2p over the offer price. So I would need about 5 years of divis just to recoup the bid/offer spread! That together with de-listing risk, means it’s probably uninvestable. Might be one to keep on the watch list though, in case a clumsy seller ever smashes the price down to exit in future? Looks a nice little business, but absolutely no point in it having an AIM listing.
Angle (LON:AGL) - up 15% to 15.75p (£41m) - Agreement with AstraZeneca - Paul - RED
An eye-catching RNS, saying it’s done a deal with giant AstraZeneca to develop a prostate cancer detection system for use in studies. Trouble is, the deal is only worth £550k to Angle, and is long-term in nature, when I think the share price is telling us that investors want some jam today, and not more of the heavy cash burn for many years that AGL has so far inflicted on investors -
"This is further validation of ANGLE's Parsortix system which shows potential for long-term large-scale revenues in bringing innovative new cancer drugs to the market. We anticipate that success in this first phase of assay development may lead to much larger contracts for use of the assay in clinical trials."
Cash was £22.2m at 30/6/2023, and it said the cash runway lasts until Q1 2025, despite cost-cutting.
Paul’s view - Angle technology sounds great, but as with so many innovative medical things, it takes an eternity of heavy losses to get anywhere - Angle has been listed on AIM for 20 years, and has got nowhere in commercial success, just year after year of heavy losses, along with never-ending exciting sounding technical development announcements, like the one today. It might be great technology, but the begging bowl is almost certainly going to come out again later this year. As we’ve seen with other struggling minnows, the investor appetite for pouring in more & more cash is very weak, and often brutal in the discount demanded. Why get involved? It’s a pure punt at the moment, with a very large risk of considerable dilution, so for me it has to be RED until it’s properly refinanced (again). Stuff like this should not be listed on the stock market.
Mirriad Advertising (LON:MIRI) - down 41% to 1.275p (£6m before, £12m after placing) - Discounted placing - Paul - No colour.
Another placing from this cash burner. It will double the share count from 489m to c.978m, with the new shares being issued at 1.25p (a c.45% discount) to last night’s close. This raises £6.1m (before costs of probably a few hundred k). Retail offer through REX (a new platform) will be open until 11am on 7 May, hoping to raise £0.55m extra.
Paul’s view - I last looked at this in-game advertising company on 8/4/2024, concluding it was too high risk, but seemed to have interesting potential. With the coffers now being topped up, it should be able to last well into 2025 I imagine. So it’s moved up my list of possible reckless punts (where I usually wait for a refinancing to happen, as in this case). I’m tempted to have a small dabble, with money I can afford to lose. It’s just a punt though, as the track record has been dire.
Summaries of main sections
Warpaint London (LON:W7L) - 478p (pre-market) £369m - Director Selling - Paul - GREEN
Substantial Director selling in a secondary placing. Providing the price isn't at a discount, then I'm not concerned by this, because owner/managers retain a huge 43% of the business after this selling, and agree a 12-month lock-in. UPDATE: the price is at a discount of 6% at 450p, and the amount was raised from 6m share to 7m shares. So I'm a little perturbed by this morning's update. Institutional demand can't have been that strong, if they required a 6% discount to take the shares away.
Argentex (LON:AGFX) - 35.9p (pre-market) £41m - Result of Placing - Paul - AMBER
Looks like the take up of its placing might have undershot the target.
Trainline (LON:TRN) - up 7% to 322p (£1.51bn) - Final Results FY 2/2024 - Paul - AMBER
I have a quick look through the FY 2/2024 results. It doesn't really float my boat, being pricey on a PER basis, having a negative balance sheet, and spending too much on buybacks that are helping to mop up very generous management share options. On the upside, EBITDA margin is improving, which combined with revenue growth and opportunities in European markets, does mean nice profit growth. Could be a bid target maybe?
Hostmore (LON:MORE) - suspended - FY 12/2023 Results - Paul - RED
Late 2023 accounts don't impress me, it's still a very sick business. Debt reduction has come from stretching working capital, not from underlying trading. Very weak balance sheet, totally dependent on bank borrowings, but a 1-year extension to end 2025 does give breathing space. Will the reverse takeover of US brand owner save the day? Combining two highly geared businesses will surely make one larger highly geared business? There are considerable risks here, including the "material uncertainty" going concern, so it has to be RED from me until the waters become clearer and the cokes more fizzy!
Paul’s Section:
Warpaint London (LON:W7L)
478p (pre-market) £369m - Director Selling - Paul - GREEN
Announced just after the market close yesterday, Shore Capital is doing a secondary placing of Director shares, totalling 6m shares (c.£22m, 7.8% of the company). There are currently 77.3m shares in issue.
PLANNED: Sam Bazini (CEO) - Before: 19.45m shares (25.2%), Selling: 3m shares, After: 16.45m (21.3% of the company).
ACTUAL RESULT: Sam Bazini (CEO) - Before: 19.45m shares (25.2%), Selling: 3.5m shares, After: 15.95m (20.6% of the company).
The numbers for Eoin Macleod (MD) are identical.
Lock-up (ie agreed no more selling) for 12 months afterwards, which I like to see, this is good.
Paul’s opinion - substantial Director selling is never positive, as the people who know the business best want to sell. The question is, how bad is it? In my view, the founders each dropping from 25.2% to 20.6% is fine, I don’t have any quibble with this, because they retain enormous personal stakes in the business.
We’ll have a short wait to find out the price, which will be the best indicator of how much genuine institutional demand there was. Hopefully nil discount. UPDATE: unfortunately there is a 6% price discount, at 450p. That doesn't tie in with the broker stating there was strong institutional demand. If that had been true, the shares could have been placed at market price, with no discount needed.
It’s bound to slightly take the edge off the bull case, but you can’t blame owner/managers for wanting to enjoy a bit of the wealth they’ve created, and a combined 41.2% remaining holding is more than enough. Top-slicing after a very strong rise in the share price is sensible, especially when their shares probably make up the overwhelming majority of their personal wealth, I imagine.
Hence I’m happy to stay at GREEN, providing there isn’t a large discount on the price when announced shortly. Let us know your views, especially if you hold this share personally.
UPDATE: results of the placing of Directors shares is a little concerning. The price is 450p - if there was such strong demand as the broker claims, why did they agree a 6% discount? That doesn't stack up with the claims it was over-subscribed (of course it would be if they're being offered a 6% price discount). 7m shares were sold instead of the planned 6m.
Overall, I think 450p is probably now the benchmark for what W7L shares are currently worth, so I'd expect to see the market price fall to near the Director selling price. However, any wobble on this news might be quickly forgotten if/when the next "trading ahead of expectations" update comes out!
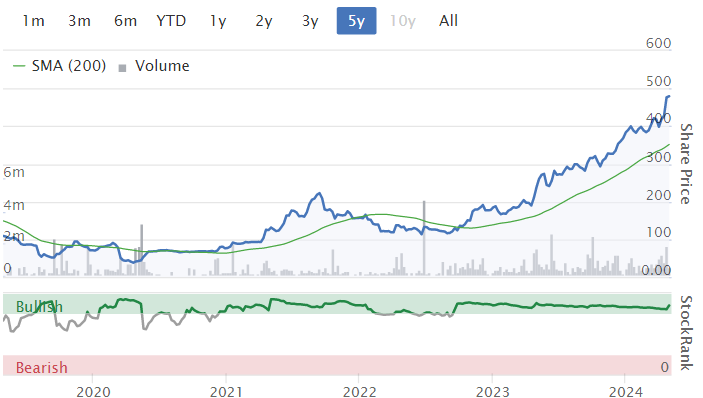
A nice success for many readers, and the SCVR, as we were all over this one early in the 4-bagging bull run that started in 2022 -
Argentex (LON:AGFX)
35.9p (pre-market) £41m - Result of Placing - Paul - AMBER
I speculated in yesterday’s SCVR whether any institutional investors might pull out of the placing at 45p per share, given that the market price undershot, ending up at 36p on yesterday’s results & downbeat outlook.
Sure enough, it looks like the placing has undershot, with only 7.2m shares at 45p being taken up (£3.2m). the original announcement said 11.3m shares (but that might have included an open offer?)
I don’t suppose there would be much take up of the retail offer if the share price remains below 45p, since people could buy in the open market at a lower price.
Paul’s opinion - clearly not good news, but AGFX has a sound balance sheet, so I was surprised it needed to do a placing at all. It does make me wonder if management might be expecting much worse trading in future, and want to get some cash in the bank ahead of that?
AGFX is either a cheap turnaround, or a disaster in progress. It’s not obvious to me which is the case, so I’ll remain on the fence with AMBER.
Trainline (LON:TRN)
Up 7% to 322p (£1.51bn) - Final Results FY 2/2024 - Paul - AMBER
Results for the twelve months ended 29 February 2024
Strong growth from Europe's most downloaded rail app
A 7% share price rise on results day is usually a good reason to investigate, although this might just be a rebound after recent falls maybe? I think a reader here mentioned the other day that recent falls could have been due to fears of possible railway nationalisation in the UK in future?
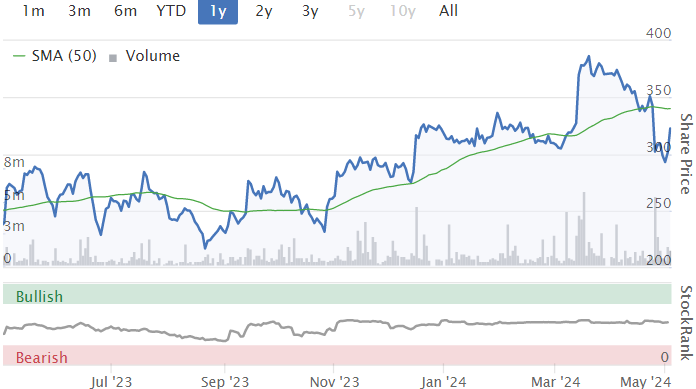
The news BUZZ feature on Stockopedia under the “NEWS” tab for every company is really handy, as it gives a one-line quick view of results. For Trainline, today BUZZ says - “Trainline rises as labour worries subside, sees strong forecast”. I find these snippets are usually accurate, so definitely useful as a shortcut.
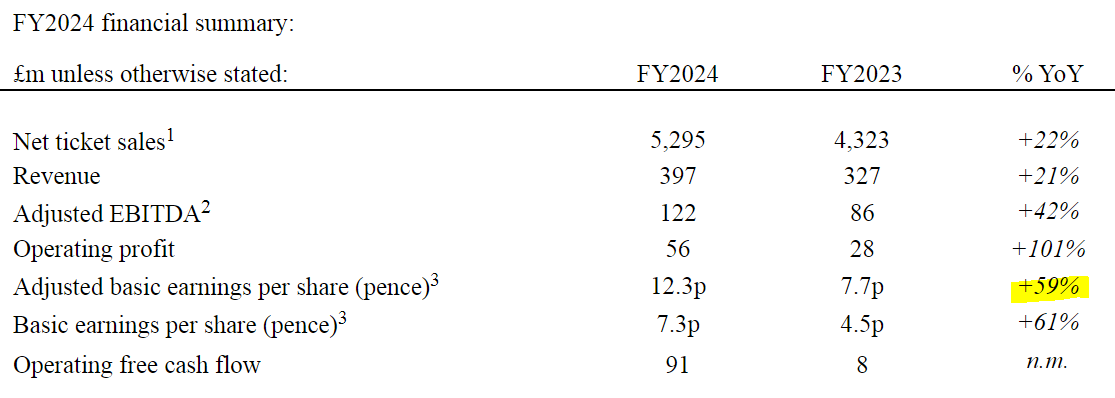
Nice highlights table below, with excellent growth in most metrics (I’ve highlighted the only one I’m interested in) - giving a PER of 26.2x - seems very pricey, but maybe not so if strong growth is continuing, rather than just a one-off rebound from lockdowns ending & travel normalising?
Guidance - why couldn’t they work out the figures, and give us a profit number? Instead we get this -
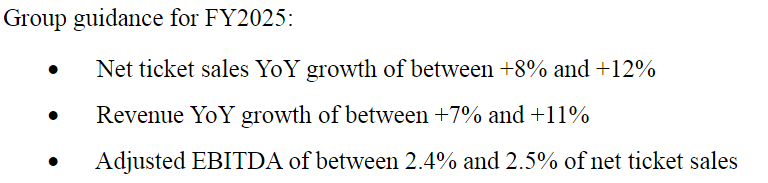
I make that net ticket sales of £5.82bn (mid point of range), and hence adj EBITDA of c.£143m (middle of range again). That’s up 17% on FY 2/2024 actual - good, but not madly exciting for a share rated on 26x.
Previous guidance was adj EBITDA range of 2.15% to 2.25%, so the new range is usefully higher.
New share buyback of £75m announced.
CEO comment sounds interesting -
"New entrant carrier competition is revolutionising rail in Europe as more customers benefit from greater choice, lower prices and the opportunity to choose greener travel. We are becoming the aggregator of choice in the UK and internationally and are delivering strong growth, particularly in those markets liberalising fastest such as Spain.
Reconciliation between adj EBITDA and PBT is an eye-opener. Very big rewards for management here -
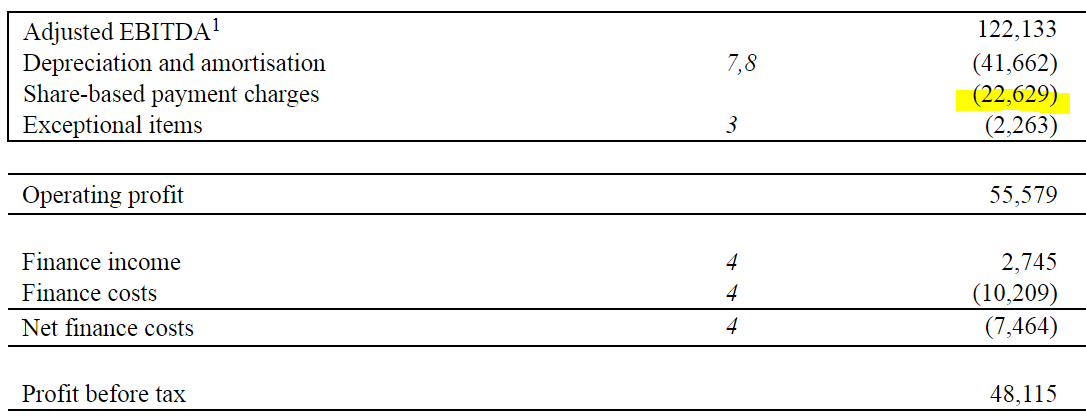
Balance sheet - not great. NAV is £312m, but taking off £489m intangible assets gives us negative NTAV of £(177)m. So there’s literally nothing in asset backing here. That may not matter, if it’s generating plenty of cash and doing buybacks using cashflows. But if something unexpected were to go wrong, then there's no asset backing to catch any share price fall.
Cashflow statement - note that of the £121m post-tax cashflow, almost a third (£37m)was spent on capitalising (presumably IT development spending) into intangible assets. Taking off other real world costs lower down the cashflow (interest costs, lease liabilities, etc) I arrive at £71m free cashflow. Not bad. It used roughly half of that for share buybacks (which you could argue are not doing a lot more than mopping up management share options). The balance was a £35m increase in the cash pile. No divis paid - there should be!
Broker notes - nothing available.
Paul’s opinion - just a quick review as always, but I don’t see enough to get me excited about the valuation or the upside potential. Also there’s no balance sheet support, and buybacks are significantly offset by generous share options issued. There aren’t any dividends, which is not great. Which does make me wonder if the business is primarily run for management’s benefit? Don’t shoot the messenger, I’m only pointing out relevant facts.
Has anyone got a more bullish view, to explain the upside potential maybe? I suppose it might be along the lines of gaining market share in Europe, and having an established market position that might be difficult to dislodge, especially in the UK, and making decent cashflows.
Also, IT businesses like this can attract remarkably high takeover multiples from the private markets, usually based on a multiple of EBITDA. Valuing TRN on say 15x EBITDA would give a £2.1bn valuation, enough for a 40% bid premium above the current share price. We know that US private equity funds are all over UK mid caps, so maybe this might be a target, who knows?
Hostmore (LON:MORE)
Suspended - FY 12/2023 Results - Paul - RED
Hostmore plc ("Hostmore" or the "Company" and, together with its subsidiaries, the "Group"), the hospitality business focused on 'TGI Fridays' and 'Fridays and Go', is pleased to announce its audited annual results for the 52 week period ended 31 December 2023 ("FY23").
Shares should come back from temporary suspension, given late accounts have now been published.
The commentary tries very hard to put a positive spin on these results and outlook, but there are still major problems here. I think the turnaround implemented by management has made a little progress, but has mainly succeeded in staving off collapse, rather than fixing the business.
That’s reflected in a “material uncertainty” going concern statement, reminding us that this is still very high risk.
Bank - a key point is the bank’s given it more breathing space, extending the vital borrowing facilities to end 2025 (1/1/2026). Net bank debt has come down, from £31.3m end H1, to £25.1m end H2. Although the cashflow statement shows that’s been achieved from stretching other creditors, and squeezing receivables too. There’s no underlying cash generation.
EBITDA on the old (sensible) basis has almost vanished, from £11.3m in 2022, to only £1.6m in 2023.
LBT was £25.5m in 2023, after more write-offs.
Balance sheet is really bad, which is likely to eventually need an equity raise to fix it.
Current trading - poor, with LFL revenues down 7% vs Q1 2022, blamed on weak demand. That’s not sustainable long-term, since costs (esp wages) will be rising considerably. Although cost cutting means it has been able to report an improving trend on EBITDA compared with last year, and within Q1 itself - which does strike me as clutching at straws (to drink the disappointingly flat coke maybe!?)
Paul’s opinion - this business is clearly still on life support (the bank facility). I don’t see a convincing turnaround here at all so far, and the shares still look very high risk.
I haven’t touched on the deal to do a reverse takeover of the US brand owner, which could be a lifeline, but that means taking on even more debt. So I think it is too complicated for me to want to spend time digging into the detail of that deal.
Good luck to any holders here. You’ve either got a zero, or a recovery trade, I just don’t know which yet!
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

88 comments
It wasn't the most recent podcast, but I'm sure I heard Paul mention something about Topps Tiles (LON:TPT) Topps Tiles, so I just wanted to flag up that the Zeus analysts have done an audio report on it, which you might like to hear https://zeuscapital.co.uk/log-...
**Bank Holiday Weekend Offer**
For the whole of this long weekend any investor buying a ticket for the *Mello2024* event will be given the bonus of being able to bring a friend or family member completely free of charge. Worth getting a friend to join with you and halving the cost maybe...
Will end at market open on Tuesday as it is a bank holiday weekend so plenty of time to connect
Mello2024 investor conference takes place on the 22nd and 23rd May and Stockopedia will be there plus Paul Scott and all the BASH regulars. Do come and join us....another six companies added to the list today and another six to be announced on Monday.
We want to keep this important face to face engagement with companies going and it has been tough since Covid as many directors just want to do webinars as their only token offering to investors. If you want to ask private questions or check out body language it is impossible on webinars and investors need to network with each other too.
Please support us and encourage companies/ management teams you are in contact with to come along to Mello2024 in Chiswick on 22nd or 23rd May
Mello2024 – Mello Events
If you have never been to one of our two day conferences before then clearly you are missing a great opportunity to engage with management teams and also network with hundreds of likeminded investors so we are offering virgin tickets at just £30 for either of the days so that you can see what it is all about.....a big discount from £99.00 and if you do not agree having spent the day with us I will give you an annual pass to our virtual shows on top. I just want investors engaging with all these quality smaller companies. This offer is only if you have never attended before so please be fair to all those who pay much more.... Simply enter the code NEW2MELLO24 BUY NOW: https://www.tickettailor.com/events/melloeventslimited/1201351
Full info on this thread Stockopedia | Mello2024 conference...22nd and 23rd May | By carmensfella
Tracsis (LON:TRCS) H124 presentation given last week by management together with a helpful Q&A video & podcast. They're always very open. All eyes on the USA which could be a game changer over time. For now, a H2 weighting. The obvious question about Labour taking the railways under public ownership. They see this as a positive. To date investing to provide the infrastructure to scale. Highly cash generative.
Ingenta (LON:ING) results meeting on Tuesday has just been cancelled as the results have been delayed. No reason given but it does seem a bit late in the day to be postponing a results announcement? I have no position.
For those bemused/frustrated by the Card Factory (LON:CARD) share price performance, it’s possible the cause might not only fall at the door of Teleios (real or just perceived overhang). I noted a relatively detailed, but bearish, substack write up on Twitter - it shouldn’t be hard to find but the core thrust of its stance to my reading centred on the threat of price competition.
On first reading, I dismissed it as a malevolent article written by someone with an agenda. There’s no way I’d walk far to buy a cheaper card from my favourite Card Factory shop where the average selling price is already only just over £1.
But looking more at the competition angle (main reference being to a company that has about 60 (and expanding) stores currently in the UK, Cards Direct), I realise I had a blind spot because none of those stores are near me. And said company has just posted its latest accounts at Companies House - it’s profitable and balance sheet seems sound - so a more worthy adversary perhaps than Clintons ever was.
Thanks for highlighting. Cards Direct have a relatively tiny number of stores, so can't see it being a huge threat unless they start expanding very aggressively. As you say, I can't believe card buyers are particularly sensitive to prices - can't imagine people will shop around to find something 10-20p cheaper, especially as Card Factory already very cheap.
And let's not forget that Card Factory (LON:CARD) design and print their own cards. Nice vertical for cost control and flexibility to respond to price competition. Long and strong
Agree it’s likely not a major threat, yet. But it’s the sort of thing that can just nibble away and gradually undermine growth, a bit like it seems Likewise (LON:LIKE) is doing to Headlam (LON:HEAD) - not sure if it’s the best analogy but it’s the first to spring to mind.
To be honest, I posted it mainly because I know how easy it is when the price is not moving as you expect to contrive all sorts of reasons why the price is wrong, and if you hold on things will fix themselves. Better I think to know as many of the things you’re up against to understand why the price is what it is. In this case Teleios seems to be most regularly cited as a drag, but no holdings changes are being disclosed so at some point things have to point to something else.
Smiths News (LON:SNWS)
as a non-expert could anyone please explain why the ROCE is so high on the stockopedia rankings?
thanks
Smiths News (LON:SNWS) - it’s a good question and I’ve wondered it. I may be reading this wrong but isn’t it in terminal decline as people move away from papers/magazines etc and IIRC even its management admitted this?
This is in the summary in the NAPs post:
"Smiths News has done an excellent job of creating efficiencies and improving margins over the last few years, to mitigate the impact of the structural decline of sales volumes in the UK’s newspaper and magazine market. As a result of the changes it has made, which included the disposal of loss-making assets, it has managed to turn a profit in each of the last 3 years.
Despite a notable lack of forward-looking growth, the company looks exceptionally cheap on a variety of valuation metrics. A price to free cash flow of 3.8 and prices to sales of just 0.11, imply that there could be a unique value opportunity at play. Furthermore, a forward dividend yield of 7.94% might provide an added incentive for income investors."
l don't know why the ROCE is so high.
Is that craft beer or cask beer?
Both.
I see, not familiar with craft beer in pubs.
I see, not familiar with craft beer in pubs
Several microbreweries here with their own outlets and a specialist craft beer “shop” with a good array of craft beers on tap. The main brewery here is Vocation (just down the road) which is too big to be called “craft” nowadays, but still a lovely choice of ales, whether cask or keg. And they sell delicious guest beers in their main outlet, from chocolate stouts to raspberry sours.
Gosh, i’m beginning to realise why we get so many beer tours!
Ah, BnB, I know where you are now. I had imagined somewhere posh like Ripon, Thirsk, Skipton or Malton.
As a Friday afternoon aside, Sowerby Bridge has a good range of pubs with good beer comfortably < £4 per pint.
Richard
Ah, BnB, I know where you are now. I had imagined somewhere posh like Ripon, Thirsk, Skipton or Malton.
As a Friday afternoon aside, Sowerby Bridge has a good range of pubs with good beer comfortably < £4 per pint.
Alternative beats posh any day of the week. To your aside, Sowerby Bridge is surprisingly good for food but the vibe is too ‘fax for us hippies in the upper valley.
Wetherspoons (The Barrel Vault) at St Pancras has an incredible array of craft beers from microbreweries sold by the can for drink in or take away at very reasonable prices if anyone ever fancies a sneaky one on the train. Digressing away from shares here but it is late on Friday and the bank holiday awaits us!
Berkshire Hathaway (NYQ:BRK.A) AGM tomorrow - first meeting without the legend, Charlie Munger. Always a must view for Warren Buffett fans, like myself. Charlie Munger will be sadly missed for his no-nonsense talking and enjoyment of See's Candies peanut brittle and Coke throughout the meeting.
Only one Saturday evening a year!
I kind of hope Warren looks to his right and asks "What do you think Charlie" and then proffers up some wit to tip his hat to the great man. Always a must watch for me.
Dear Paul
Could you review Zoo Digital last February you seemed quite keen at two pounds last month at thirty pence you seemed negative wondering where your view is going with the price at 55p is it still a bad company or is it the good company from last year?
Assuming that you haven't seen Paul's reply to you this morning, on yesterday's report?
I have not though I see my question has been red flagged which is odd stock up again today so I guess the market at least is making a judgement call
Voting machine / weighing machine springs to mind...
Zoo Digital (LON:ZOO) was a great bottom recovery trade.I was thinking about buying in around 20pish level as it has no debt i think.Shame i didn't!Canaccord were selling down a fair quantity for a good while though and Liontrust bought 5% .Similar to Frontier Developments (LON:FDEV) 's nice recovery from near the £1ish mark.Nice to see the market 'allowing'/being more accomodative/'risk on' on these potential bottom fishing recovery plays more lately.I don't totally like the game of how low can he/she go........!The nerves can't handle it.
Interesting observations on drinking. My small town in Yorkshire, and which is very pretty and tourist-friendly, is packed every weekend with from-out-of-town beer drinking parties. You can hardly move in the many craft beer-focused pubs* and locals retreat to a couple of joints that are hidden away from the weekend beer trail.
* I witnessed one group being ejected for ordering “17 pints of Carling please “ The look of disgust on the barman’s face was a picture!
Yes, there are always exceptions. I've thought for some time that tourist-focussed market towns are "hotspots". But how much trade do these outlets do during the week? I said the wet trade is now down to 2 evenings a week - maybe 2 days a week in your hotspot. Is that enough?
Is that craft beer or cask beer?
Yes some areas will that get sort of trade. But isolated pubs rarely do.
Food more profit, you have to be busy pub, just to sell drinks, many of those have about 12 different cask beers on.
Years ago many pubs had really low rents, much lower than a house, l knew people who were tenants. Some were only open in the evenings, may just sell a few beers. I think rent and rates were based on turnover.
Another factor, that l forgot to mention is the drinking culture at work, when l started work, it was almost encouraged, people regularly drank at lunchtime, one company even had a bar with cheap drinks, now is frowned upon or maybe even banned. Anyway too expensive now.
https://www.independent.co.uk/...
Personally I've no issue with director selling at Warpaint London (LON:W7L) - they've taken the price from 80p to £4.80, at some point they need to realise that gain, buy themselves a Ferrari and a yacht :D They're not getting any younger and the company is still growing strongly.
Well done Sam and Eoin, keep it up.
If Hostmore (LON:MORE) [I hold] is now considered boring Paul then I'm breathing a sigh of relief! :o)
Mercifully the delayed results publication was of short duration. Hostmore is perhaps becoming more complex given the reverse takeover, which a navvy like me might consider to be digging the hole deeper, but shy bairns git nowt so I'd rather see the company doing something radical than die of inaction. The CEO keeps buying shares, and I'll be interested to read your results analysis and any comments you might have on the strategy of world domination please. Possibly controlling the brand allows control of the format so a refresh might be hoped for if Julie McEwan can keep the lights on long enough.
Thumbs up to a piece today on Pollen Street (LON:POLN). Stocko correctly highlights that it's newly listed - this is technically correct but a little misleading.
Essentially it converted from a closed end IT into a commercial company, as part of it's evolution and growth. It's *effectively* always been listed, and is profitable and dividend paying.
You can find the historic financials and all the broker notes at Research Tree.
It's a pity but I guess a lot of folks will instantly move on when confronted with no financials + "recently been listed" on the Stocko page. You'd be missing out though.
Today's TA appears positive, with AUM up to £4.4b (£4.2b) and performance in line. There's a share buy back running but some director selling of late.
Perfectly understandable if Paul would prefer to leave this one to Graham as this is more his area but equally I'm sure we'd appreciate Paul's (and others) thoughts.
You seem to be 'having a go' here at Stocko, and even at Paul, Your knowledge is valuable but the tone could be better. Stocko can never be perfect but it never seeks to be 'misleading' I'm sure.
A 'manners monitor' in play.....from my perspective I am grateful for Mark's candour and knowledge on POLN.
Sorry Snowdrop but in no way and I was "having a go" at either Stocko or Paul. I think Stockopedia is brilliant (in my own case genuinely transformational), but it has the occasional flaw, which in this case is probably very difficult to solve. I was just pointing out one such issue as it arises. Nothing more.
As for the remark about Paul, I was just reflecting the common knowledge on this board - and something that Paul has referenced a few time times here and in his brilliant Podcast, that Graham often takes the lead on the banks and financials as this is a sector he likes to contribute on.
I was actually trying to stimulate a discussion and provoke some curiosity to look more deeply at something that could be an intetesting avenue for research. Sorry if the tone was not pitch perfect for you, it genuinely was not meant!
Paul if you were offended I'll buy you a beer or three at Mello!
Paul if you were offended I'll buy you a beer or three at Mello!
Can I take you up on that Mark (even though I wasn't offended! ;-)
Thanks for the additional colour on the background on Pollen Street (LON:POLN) . In those circumstances the data would naturally just show it as a new listing, I can't see any way around that, so it's not really an error.
I haven't got time to look at it today, due to a 240-mile drive in the offing, to visit family up north this afternoon/evening. But it did catch my eye with a "quite interesting" conclusion here on 21 Mar 2024.
I am a bit lost Snowdrop ... the tone seems perfectly okay to me and Mark's comment will be of value to someone.
Morning all,
Seplat Energy (LON:SEPL) is one of my largest holdings and thus I try to track everything related to it very closely. Yesterday afternoon Reuters put out a news article stating that a meeting is taking place today that could result in a quick resolution of the Exxon Mobil (NYQ:XOM) deal, closing it within the next two weeks - https://www.reuters.com/market...
If this is indeed successful, the 1.3billion acquisition will result in a significant increase in oil production, likely over 150%. This will have a demonstrable impact on both profits and therefore dividends/sp. There have been false dawns in the past, and there have been previous indications the deal will be resolved and then it has not happened, however, a lot of parties are losing out from the deal not being resolved and the Nigerian government has recently been very public about wanting a "quick" resolution.
The SP is up nearly 25% YTD, so there is decent momentum behind the stock and some buyers have already stepped in, likely in anticipation of the deal being completed, although this rise does not by any stretch reflect the potential upside should the deal go ahead. There is of course a small risk that the deal could fall through, although that looks increasingly unlikely as a lot of Nigerian government officials will likely benefit financially from its completion.
For many, as a Nigerian company, Seplat Energy (LON:SEPL) will be un-investable. However, the risk/reward seems strong. Especially as geopolitically the country in quite stable at the moment - please DYOR
HSS Hire (LON:HSS) - results look decent on initial view. I feel that the market is not really absorbing the transformation story and the debt is a concern. However, very nice dividend and well covered - seems to be a very decent recovery play on interest rates coming down? Would welcome any more erudite views.
I was thinking to myself before logging on this morning just how much output there's been on the SCVR lately and you note 'We've now covered 440 unique companies in the SCVRs in the 4-months to date. Not long hopefully until we exceed last year's 609'.
Incredible work from you and Graham!
I'm someone with a full-time job so this blog is critical for giving me ideas and keeping on top of what's happening across the market. Thank you very much for all your efforts :)
How lovely thank you Tortoise Investor!
We've played around with the format a lot, trying out new ideas. I'm happy with the way we've got it running now,. As Ed commented to me the other day, the beauty of this format is that you can quickly skim the SCVRs for things of interest, using the summaries, and colour-coding. That's the idea really, that hopefully readers who are busy can spend as little as 5 -10 minutes skimming the summaries & movers sections, to find anything that might be of interest.
We're now enjoying it a lot more too, now the reader comments have improved and are much move civil, it makes it a pleasure to interact, rather than a source of aggravation!
All good, happy days! Now we just need some nicer weather :-)
I spoke to Sam at last years Mello. One of my questions was "will you sell down your share holding". He was a non commital no. I think we have to remember they have accumulated wealth. They have every right to take it when they feel there is a reason be it share price or personal. Also when you ask them questions of course they can't be totally open because they might destroy share value before they have taken advantage. Example Teleios and Card Factory. So all in all I would suggest this is a share price valuation sale, it has gone up over 4 times since late 2022. Of course that has captured a lot of future growth and taken any personal risk out of it for Sam and his partner. I would have handled it exactly the same way had I been smart enough to build such a good company. Still holding
Which company Camtab?
Warpaint London (LON:W7L)
Sorry Kevin. Yes as Cancun correctly says Warpaint.
Young & Co's Brewery (LON:YNGN)
Youngs have released a short update saying that trading is in line with expectations and full year results will be announced in June to allow auditors to accommodate the recent acquisition of the City Pub Group. The voting shares trade at around 960p and the non voting shares at 620p or thereabouts. The only difference is the latter doesn't get to vote at the AGM. They are both entitled to the same dividend and both trade at a substantial discount to NAV of around 1250p
The non voting shares trade at a PE of around 10 and yield of 3% or thereabouts and at half book value. For a high quality operator that is lamentable, but the British pub will be about long after the current sorry episode in UK equities is forgotten.
Crackers, but that in large part that is the state of the UK small and to a lesser extent mid cap market.
Very patient holder.
Yes, Jonno. I hold Fuller Smith & Turner (LON:FSTA) and it is a similar story there, with a big discount to NAV and decent yield. Unlike a number of pub groups (e.g. Marstons, Mitchells & Butlers) they have modest debt too. Very cheap imo.
Young & Co's Brewery (LON:YNGN) ' the British pub will be about long after the current sorry episode in UK equities is forgotten.'
Well, some of them. I'd guess about 75% .
The evening wet trade is down to just 2 days a week. The student market is looking weak and I have personal knowledge of a student "activity" pub which offered games etc., a bit like an XP Factory (LON:XPF) site, which has just gone bust. I suspect some students have woken up to what student debt really means for the rest of their lives. A lot of bartenders are twiddling their thumbs a lot of the time while the electricity meter spins round. On the food side, the average bill for me and my wife for a pub meal and one round of drinks is £50 - we have agreed that although we can afford it we don't like spending that much for what is usually mediocre fare, and we eat out 50% less often than pre-lockdown habits. Then there's the new minimum wage structure. The pub trade is being squeezed between lower sales and higher costs. There will always be exceptions, and maybe Youngs is one of them, but I wouldn't count on the book value as a support - a lot of pubs aren't worth anything like the figure in the books . I'm basically a property guy and when I see people saying that stressed businesses are OK because they have a lot of property I have to point out that valuations for specialised properties (pubs, car showrooms, etc.) are always done using the profits method. No profits = a revaluation based on an alternative use, usually less because of conversion costs, and if the LPA has a community facilities policy it's very hard (sometimes impossible) to get change of use for pubs. There's a derelict one near me (rural area) which failed as a pub years ago and nobody is even allowed to live there as their home unless they reopen it as a pub which would be a ridiculous thing to do. Sorry to be so bearish.
Young & Co's Brewery (LON:YNGA) / XP Factory (LON:XPF) - As someone who is probably a little younger than most on this site (35) and probably with a lot less disposable income (I just decided to sell my house and invest it all instead), I have really noticed the food and drink industry becoming less accessible to me and my young family. My friends are all repeating the same message, most of us have a husband/wife income of 60k-100k, so we are far from being on the breadline, but with one or two young kids each, we can't justify going out for 5-6 beers and food when you can get 18 cans of premium lager for 15quid and sit in someone's garden for free and throw some food on the BBQ. Food prices have gone up a lot in both supermarkets and restaurants, however alcohol has gone up in pubs but not so much in the supermarkets - at least that is how it feels.
An additional note, I recently returned to my old University for a charity football match up in Lancaster. I was gobsmacked by how empty the campus bars were and just generally the attitude towards alcohol and drinking. 15 years ago every student was a borderline alcoholic and in the bar every day, these days I just don't think that is an accessible lifestyle due to cost and thus students just aren't paying up. Plus if you pay 9k a year, you can't afford to mess up your degree by being hungover in every lecture. The issues at Revolution Bars (LON:RBG) only emphasise this. With so many cheap high quality companies on offer, I just don't see any value in the hospitality sector... I certainly can't see any growth prospects.
Interesting.
Personally i don't know why you have to have a meal when going to the pub. That was very rare in years gone by.
In a sense pubs have shot themselves in the foot by making it expected that you only go if you have food as well. Not surprisingly people can't afford this but could afford a couple of pints.
I think there are many factors involved, drink driving law, stopped some people going to pub and drinking, prices in supermarkets far cheaper, you are talking about 1/4 of the price, l can buy cans for around £1, in the pub it is around £4-5. More people drink wine now. Margins on food were higher than beer. The only wet pubs now are towns or cities, even some of those do some food. Pubs have turned into restaurants. I used to go a lot to pubs, beer was relatively cheap, now l consider it expensive. Partly due to Scottish chancellors and alcohol tax escalator. Also the beer quality, because of lower turnover, is generally not so good. Why pay £5 for a pint if it is not very good. If it is bad, l will take it back, but that can cause problems. The other issue is staff, many pubs can't get staff.
I know lots of people who used to go to pubs but rarely go now. Many pubs are closing down.
A gin and tonic from the supermarket would work out about a pound, it's £9 from my local and £7 a pint.
City centre pubs also suffer from commuter syndrome so WFH with only TWT in the office, possibly followed by a couple of pints in the pub, often leaves many pubs closing well before 11pm. Forget any thought of a late night lock-in.
Makes you wonder why the Tube runs all night at weekends.
Young & Co's Brewery (LON:YNGN) - Thanks for this Jonny - I have held the voting shares for many years and not thought this through. Just looked at the Stocko info - of major shareholders of both classes. Of course the family/directors hold voting but a number of insistitutional holders are in either or indeed in both categories . Maybe I should sell voting and buy non-voting. I'll need to do some more research and appreciate more community comments.
Hi bohenie
I believe that Nick Train's Finsbury Growth & Income Trust (LON:FGT) holds the non voting shares, although the Trusts performance has been that great of late. He also holds Fullers I believe.
It was Andrew Hollingsworth of Holland Advisors who alerted me to the significant price disparity between the voting and non voting shares quite sometime ago. Andrew runs an open ended fund and has given presentations at the physical Mello event in Chiswick. He holds the non voting shares in his fund, which has performed very well.
All the best
Warpaint London (LON:W7L) price has not dropped much, around 475p to buy, was hoping to top up at around 450p.
Transense
Paul commented relatively negatively few days ago as a previous holder burnt fingers
I countered poditively as a newish holder pumping my dross
Good article on progressive research with MD / chairman and Dowgate young buck Lawrence Hulse .
https://progressive-research.c...
don’t think that link works but sure you guys can find it .
If they can’t sell the shit out of that translogic tyre monitiring system they need a kick up the ass .
Hi planetx,
I've got to challenge you on this -
"Paul commented relatively negatively few days ago as a previous holder burnt fingers"
Possibly intended as a semi-joke (I sometimes can't tell with you!). Just to set the record straight, I did not burn any fingers on Transense Technologies (LON:TRT) . Actually I researched it jointly with a couple of mates who had come up with the idea, which I thought looked interesting. We had a zoom with management, so went into a fair bit of detail. That was in mid-2021, when the share price was about 85p. There must have been some good news at the time, as it was rising nicely (but then peaked at c.120p in Nov 2021, before beginning a descent to a low of c.52p in Aug 2022).
I only held a small position for a little while, but after talking to management decided it only had limited upside. The main takeaway was that they were running the legacy business (with a contract or patent that was due to expire in about 2030) for cash, and stripping out costs, whilst trying out a couple of other blue sky projects. They don't seem to have paid any divis with the cashflow from legacy contract. Although it looks as if the share count has reduced, so some buybacks possibly.
I see since 2021 revenue has roughly doubled, and there have been small but rising profits in 2022-now. So on balance this has signs of life, and it might be worth me taking a fresh look. I quite like blue sky projects that can self-fund the growth ideas from some kind of legacy income stream.
So maybe it's time for me to have a fresh look on a quiet day?
Thanks for flagging the idea, albeit in your customarily quirky way.
Regards, Paul.
Four directors of Transense Technologies (LON:TRT) made coordinated purchases of a trivial number of shares yesterday, around 4000 in total. Is it really so illiquid that this was all they could get or was it a weak attempt to lift the share price? It’s a bit higher today.
Transense Technologies (LON:TRT) They bought over 40,000 at around £1 on 30th April.
Chairman owns circa 270,000 shares that he has bought in the market with his cold hard cash .
New MD Ryan has started buying but told me as he is generally in a position of holding confidential info it is incredibly rare they get the chance to buy .
The day after the recent RNS they all bought in the market at circs 2 pound , It was at 91p week before
These are signs of a good management not expecting too much of a free lunch at shareholders expense .
Transense Technologies (LON:TRT) Thanks but why are you replying to me? l think you should replying to FREng.
Why did they buy at £2? The price was around 107p.
That was a typo !
think I’m replying to you this time
Rushing round a bit this morning so my usual inaccurate postings are even more woefully unstructured .
OK, no problem.
Apologies. Reading RNS on an iPhone through varifocals.
LOL, I know exactly the problem.
My perspective on Transense Technologies (LON:TRT) (I hold) is different though. Bridgestone found they could exploit their earlier technology globally and TRT have exploited that to gain enough funding to invest in and develop their newer technologies until 2030. Not many AIM companies have that luxury, especially those with a £16M M/Cap. And, to me, the new technologies might have a similar potential, possibly bigger. Apart from the cash, the Bridgestone deal is also perfect PR as a means of demonstrating their technical acumen in the real world.
It is hard to look at growth rates and PEG rations, its all about developing the technology and finding a customer who can put it to transformative use. To me it is a buy and put in the drawer situation but with an outside chance of explosive success. Or possibly a takeover by a company who wants the IP. If I had to predict, I expect it to be in the range 50% 10 bagger to 50% -1 bagger! Good odds but not for widows and orphans
I might also try to go and visit their operation. The whole vibe of the recent investor presentation felt positive. Management determined to invest and make it work, not just suck up as much salary and other remuneration from investors as they could.
Paul
If your interested I think that the MD and chairman would be available for a discussion with you .
Apologies if my customary way prodded you
I do like the look of what’s happening here and I understand the translogic application that’s a very commercial product .
The history of the company being sort of run by scientists as opposed to commercial beings is a good read across to many AIM companies , lots of lessons to learn here and quite interesting
Share price took a big leap this morning so might have missed the good entry point of week ago (91p)
Another nice trading update from Pollen Street (LON:POLN) which I hold - fund raising for the alternative asset manager continues to perform well. "Total AuM increased to £4.4 billion as at 31 March 2024 and Fee-paying AuM at £3.4 billion." Lindsey McMurray the CEO gave a good presentation recently - she looks a hands on and capable leader and has a large stake herself.
On Argentex (LON:AGFX) its interesting to see that the placing was still effectively underwritten by Pacific Investments and the directors added as well. It seems that management have misjudged the mood. Everyone else looked the other way by the looks of things! I no longer hold and thankfully sold out at about 116p (but still at a 10% loss), as I lost confidence in the magement team about a year ago. I would note that Pacific Investments are certainly not fools and have a good historical record, so they either see continued opportunity / maybe this was the only way they could see in saving their large investment. It looks like Harwood have not been interested though. Not sure that I have the confidence to go back in ..it will take a long time to regain investor confidence in their business model!
Why would Harwood be interested, they have just reduced their holding?
They can now buy at 36p..
Perhaps a little early to say Harwood haven't been interested, we will need to await holdings RNS following admitting of trading of the new shares. The Director and Pacific allocations are revealed due to the party interest of Henry Beckwith, but stripping those out leaves an amount suspiciously close to the 10% of Gresham's holding (if they were trying to avoid dilution). As I said, will need to await the TR1s for confirmation.
mighunter - yes, agreed on Argentex (LON:AGFX), the RNS only announces 78% take-up of the placing for related parties, so other significant holders may have avoided dilution and added a few. Clearly they have not backed-up the truck though! Pacific Investements are the only really big supporter.
Pollen Street (LON:POLN) satement looks really interesting, especially when CVC, listed in Amsterdam recently, CVC NA, trades on nearly 10% of AuM. What is non-fee paying AuM though, should we include that in calcs?
My morning smallcap tweet: Poverty of expectations
Physiomics (LON:PYC) Graft Polymer (UK) (LON:GPL) Polarean Imaging (LON:POLX) Angle (LON:AGL) Tekmar (LON:TGP) Fletcher King (LON:FLK) Time Out (LON:TMO) Hostmore (LON:MORE) Roadside Real Estate (LON:ROAD)
◄Physiomics (PYC)► warns FY-June rev only £600k-650k due to several large contracts taking longer to sign. [SP=1.4 Cap=2m]
◄Graft Polymer (GPL)► as mooted, gets shot of Slovenia entity for a nominal consideration. [SP=0.15 Cap=m]
◄Polarean Imaging (POLX)► sells upgraded hyperpolariser to Cincinnati Children's Hospital to replace the research polariser. No $$$. [SP=3.67 Cap=8m]. I hold.
◄Angle (AGL)► £550k order to develop a Parsortix-based Androgen Receptor (AR) detection assay for use in prostate cancer studies. [SP=13.62 Cap=35m]. I hold.
◄Tekmar (TGP)► sells loss-making Subsea Innovation Ltd for £1.9m. TGP retains premises worth £2.8m. A paltry £27k up-front. Will be broadly EBITDA neutral for FY24. [SP=9.15 Cap=12m]
◄Fletcher King (FLK)► guides FY-Apr rev materially higher than management expectations with pretax 2-3x higher than FY23. [SP=33 Cap=4m]
◄Time Out (TMO)► takes misuse of the word curation to the next level - 'editorial curation' of outlets in the new Time Out Market Porto. [SP=50 Cap=170m]
◄Hostmore (MORE)► delayed FY-Dec out so should be unsuspended. Q1 LFL rev down 7% but EBITDA £0.3m (-£2.9m). [SP=20.9 Cap=25m]
◄Roadside Real Estate (ROAD)► Cambridge Sleep Sciences stake sale and acquisition of rights: some rigmarole with Cambridge Sound Technologies. ROAD has received the £7.5m for the Cambridge Sleep Sciences stake. [SP=8.2 Cap=12m]
So, Mr Contrarian, Polarean Imaging (LON:POLX) and Physiomics (LON:PYC) both in the RNS today then, chalk and cheese when looking at the 10-year graphs. I bought into Physiomics in 2017 and sold out the same year, pleased about that as the graph is similar to the descent of a small plane that has lost engine power at height, and despite the efforts of the pilot there is only one ending. Polarean Imaging has a quite different graph, I hold but am reminded of a note I left to self the other day:
Hostmore (LON:MORE) (I hold still ) Thank you for getting the results out ahead of the weekend, relieving concerns that something unwelcome had happened. I haven't read the whole disclosure but can't find an immediate new negative. Obviously negative LFL are a problem.... but any concerns re financing are helped by the extension of the facility to 1.1.26. This gives time to cement the deal that remerges the brand internationally... which would seem a worthy idea although both businesses face challenges. For Hostmore (LON:MORE) I think it reduces some risk in exchange for the upside of recapturing all the value lost...what do I mean? well the re-rating of the combination offers lower potential but still significant. It does mean if you plan to hold you should probably average down, at some point. The most pressing risk is quite clearly continuing tough trading conditions. I can't offer any ray of sunshine here....and just hope the consumer hangs in there. At least they have their eyes open to the challenge and aren't betting on a major uplift in consumer sentiment. Getting the basics right will surely help....hot burgers, fizzy coke and friendly staff please.
Results of placing from Warpaint London (LON:W7L) just announced. 'The Placing was substantially oversubscribed and was very strongly supported by both existing and a large number of new institutional investors. Accordingly, to aid allocations, the Sellers agreed to upsize the Placing from 6 million ordinary shares to 7 million ordinary shares during the accelerated bookbuild.' - they got this away at 450p which is just over 5% below current sp - a good result. I think any drop in sp will be short lived and see this as net positive. Directors still holding substantial chunk of shares and they deserve to enjoy some of the fruits of their labour given the stellar performance of company and sp.
Morning Huwster,
That sounds like a PR release! Clearly it's not a net positive, when the founders sell a lump at a discount.
W7L shares recently peaked at 490p, so Directors dumping 7m shares at 450p is not a good result in my opinion. This shows they clearly wanted to sell (and were not responding to institutional demand). The institutions wanted a 6% instant profit in order to buy the shares at 450p.
I think this might put a cap on the share price at c.450p, since Directors were clearly keen to sell at that price.
Fantastic company though, so I'm still GREEN. Let's just not try to dress up a negative as a positive.
P.
Morning Paul, I see your point but on the other hand existing and new investors putting money in now (after such as good rise) clearly expect share price appreciation above 450p otherwise why would they bother - unless they are planning on dumping right away. If the directors tried to sell these shares in the open market I'm guessing the price would be far lower. Maybe net positive was too bullish - I hold after all :-) - but also don't view this as particularly negative either - more neutral I would say IMHO.
Fair comment, that sounds more measured, I agree it's probably neutral rather than negative for W7L :-)
Warpaint London (LON:W7L) Why do Shore Capital (and multiple other brokers) treat shareholders as stupid? If I own a significant % of a company that I run, why should I give a fig about poor institutions who are keen to buy shares?
In reality, the founders fancied selling some shares and getting some cash. Selling 15% of their holdings, later increased a tad, doesn't seem wildly significant.
They retain very substantial stakes in the business. And are slightly less able to do whatever they like, regardless of other shareholders - having dropped from a combined stake of just over 50% to 41%.
Also removed uncertainty around future selling by directors who are now locked in for 12 months - that would be a bigger concern for me - risk of them continuing to dump shares.
Paul, Warpaint London (LON:W7L) Were they spooked by the possibility of an early election and big change in tax? I think there is a very high probability this is the last time they will be able to keep so much of their respective £15.75m.
Ooh that's a good point Funnymoney, that Warpaint London (LON:W7L) management might be crystallising some capital gains before the uncertainty of an incoming Labour Govt (which might hike CGT and other taxes possibly?), I hadn't thought of that, thanks for flagging.
Warpaint London (LON:W7L)
Completely agree. In my business-building days the first tax news I ever looked for on a budget or change of administration was anything relating to disposal of holdings, esp CGT and entrepreneur’s relief.
I agree, that's quite likely to be the reason. They will be paying only 10% tax on their gains. Business Asset Disposal Relief is an easy target for Labour, not much extra revenue but a nice political gesture (in their eyes). I wouldn't be surprised if other director sales pop up where there are big gains to be crystallised. https://www.gov.uk/business-as...
Business Asset Disposal Relief is an easy target for Labour
I have close contact with the Labour Party through my community work. And, frankly, I think Labour are more likely to increase the relief than to reduce it. This is a Blairite, centrist shadow cabinet, which has ousted huge swathes of left wing activists. Apologies if this is straying onto political ground. Hopefully this still count as economics.
Warpaint London (LON:W7L)
Reply to BnB - Directors' decisions to sell are based on their perception of the future, and that of their advisers. Fears of future tax rises may be mistaken but it's what the directors and their advisers think that matters, not anyone else.
Warpaint London (LON:W7L) director selling - while I agree with the sentiment regarding a change of government, Business Asset Disposal Relief is now subject to a £1m lifetime allowance, so the current rate of tax on most of the gain will be 20%
Warpaint London (LON:W7L) Looks like it was at a 6% discount and both directors threw in an extra half-million shares each due to the institutional demand.