Small Cap Value Report (Fri 3 Nov 2023) - SCE, CURY, WIX

Good morning, it's just Paul today, as it's Friday.
All done for today, and the week! Podcast tomorrow :-) Have a lovely weekend all!
Brief market comments
The bounce is on! Is it going to be another bear market rally, or the start of a new bull market? Who knows, it depends on whether people buy or sell.
Although it does seem to me that this week might be a turning point, as peak interest rates appear to be in, and markets look forwards. So who knows, but my money remains fully invested, as I think small caps are offering some tremendous value right now, for patient holders.
Yes there are lots of profit warnings happening, and likely. There are also loads of takeover bids too. So I think these seem excellent conditions for investors who can tolerate the odd disappointment, and who think medium/long term (and of course who pick our shares carefully).
Managing my portfolio
Nobody forces us to sell anything, if we're ungeared. So if I don't like the market price of a share I hold, then I ignore the market price as being unsatisfactory. What's wrong with holding? Especially if there's a divi to look forward to every 6 months.
A few years ago, I decided that staring at profit & loss figures every day was clouding my judgement. So I removed the columns in my spreadsheet showing the original cost, and the running profit/loss on each position. I found this greatly helped my decision-making. Instead of worrying about positions in the red, and gratefully selling them if they got back to breakeven, instead I focused on the fundamentals of each company, and the prospects. Is it decent value at the current price, with a reasonable outlook & balance sheet, and hence worth holding? If so, then my decision is to remain a holder, and my original buying price is totally irrelevant. That's something worth thinking about. Equally, if the fundamentals have gone wrong, and I don't like the value/prospects for the company any more, then it should be sold - and again, my buying price is irrelevant. It's easier to sell a duff share if you don't look at your P&L on it.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
A nice leisurely morning is in prospect, instead of the usual frenzy trying to take everything in, and then decide what to prioritise. I'll be able to manage all 3 of these by myself -
Summaries
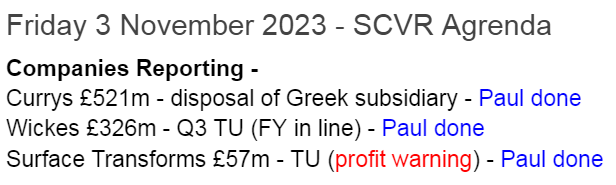
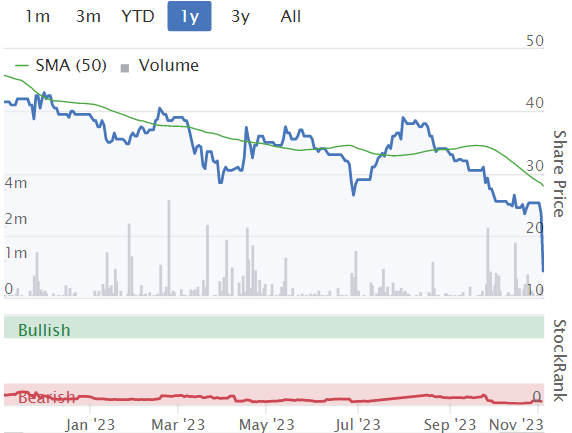
Surface Transforms (LON:SCE) - 23.5p (y’day) £57m - Trading Update (profit warning) - Paul - RED
It's another profit warning unfortunately, bad luck to holders. Production delays (again) mean FY 12/2023 revenue forecast of £13.0m becomes only £8.6m. Should be sorted by Q1 2024 (they say), but that leaves an obvious need for more funding - dilution coming, at any unknown price, means I haven't got any choice than to move to RED for now. Pity, as I like the company's longer-term prospects.
Currys (LON:CURY) - up 4% to 48p (£544m) - Proposed Disposal - Paul - RED
Proposed disposal of its Greek business takes some pressure off its stretched balance sheet. However, on reacquainting myself with the numbers, I remain of the view that this is a risky share, with some big nasties on its balance sheet, which could trip it up if we go into a recession.
Wickes (LON:WIX) - up 1% to 133p (£341m) - Q3 Trading Update - Paul - AMBER/GREEN
An in line with expectations update for Q3. Valuation looks about right, but I'm leaning towards a more positive view now, due to the c.8% dividend yield (and buybacks) and sound balance sheet. Although I'm assuming we're not heading into a nasty recession. If we do, then it could clobber WIX's profits and put paid to the generous divis, but wouldn't risk insolvency (unlike Currys).
Paul’s Section:
Surface Transforms (LON:SCE)
23.5p (y’day) £57m - Trading Update (profit warning) - Paul - RED
Surface Transforms (AIM:SCE), manufacturer of carbon fibre reinforced ceramic brake disc materials provides the following trading update for the ten months to 31 October 2023 and revised outlook for the 2023 financial year.
We’ve covered this speculative share 5 times this year, usually AMBER, but on 2 occasions when Roland covered it, he’s more sceptical, with RED or AMBER/RED. Re-reading our previous notes, the common themes this year have been -
Great news on order intake, with big multi-year projects contracted - so demand is very strong.
Production delays as it struggles to gear up to actually make products on a greater scale.
Clearly needs another fundraise, in our opinion.
Today’s update is more of the same, I’m afraid.
Sales are accelerating, but below budget.
Production line - technical problems are constraining output.
Remedial action being taken (sounds pretty basic stuff - eg. training, maintenance of machines, new COO).
Reduced guidance for FY 12/2023 - sales now expected to be £8.6m (£6.3m already achieved by end Oct 2023). That’s quite a big miss, with the StockReport showing £13.0m consensus forecast for revenues.
On the positive side, it expects to reach target production by Q1 2024. Will shareholders see this as an annoying, but temporary/fixable problem? Or a more serious disappointment? I don’t know yet, as the market hasn’t opened yet (writing this at 07:55).
Outlook - it remains upbeat, “very positive” for 2024-2027.
Production capacity is being greatly increased (once they’ve solved the technical problems) -
The Company remains on course to have capacity equivalent to £50m sales per year run rate in 2024 and for £75m sales run rate in 2025. Additionally the Company is well advanced with its plans for the next phase aimed at progressively providing £150m of sales capacity by 2027.
Financing - this is the bit that is more important to me. I can forgive technical problems, assuming they’re not disastrous. The way I read this, another equity raise is inevitable, even if it succeeds in getting a capex loan -
To finance its capital expenditure plans, the Company is in advanced discussions on a £13m capital expenditure loan that would be released as new capacity is expended in 2024 and 2025 but cannot be used for working capital purposes. The outcome of these discussions is not certain but is expected to conclude before the end of 2023. Success in securing the loan will enable the Company to finish installing the current capacity build to £75m as well as commencing the next stage of the capacity build towards £150m sales capacity; however there remains the need to finance the working capital of the significant sales increase over the next few years.
Paul’s opinion - my feeling is that, with this type of share, you have to expect commercialisation to take longer, and encounter problems along the way. The main thing is they’ve got a huge order book. Fulfilling that, for a company that’s almost a startup (in terms of production) is bound to be difficult.
Yet again, a promising UK growth company is under-financed, it’s the same depressing story. Personally I’d be tempted to have a flutter on this share, but not whilst it is so obviously in need of more financing, as we have no way of knowing if that can be raised on reasonable terms or not. Why sit there waiting to be diluted? The profit warning, and higher dilution risk means I’ve got no choice than to move from amber to RED for now. Pity, as it’s a very promising company, it just needs to get the finances properly sorted out.
EDIT at 08:13 - Oh blimey, I've just seen the early share price - heavily whacked, down 41% at 08:14, 13.0p bid, 15.0p offer. Bad luck to holders. Let us know how you see it. Are you tempted to add, sell out, or hope to weather the storm? I suppose it depends on your position size too.
Currys (LON:CURY)
Up 4% to 48p (£544m) - Proposed Disposal - Paul - RED
An agreement to dispose of its Greek operations (Kotsovolos - Greeks do seem to love the letter “o” don’t they!) has been reached.
The enterprise value is £175m, so this is material to the group’s £544m market cap.
The logic is -
The Disposal will simplify the Group's structure enabling it to focus on its larger markets of the UK & Ireland and Nordics, while simultaneously strengthening Currys' balance sheet, increasing flexibility to invest and grow the business and improve shareholder returns.
Sounds sensible to me.
The disposal valuation is 6x adj EBITDA, which doesn’t look a generous price, there again this is a rather unattractive sector (low margin retailing of other companies’ products). CURY says this valuation is greater than its own, so it makes sense on that basis.
Net cash from the disposal is expected to be £156m. Uses of the cash -
In the short term, the Board intends to use the proceeds to reduce net debt and then at the appropriate time, following peak trading, enter into discussions with pension trustees regarding the potential to reduce the pension fund's accounting net deficit and required future contributions. Reducing indebtedness may also provide, at the appropriate time, the Group with greater flexibility to invest to grow the business, after which Currys will also explore the potential to return any surplus capital to Shareholders
Given its stretched balance sheet, I don’t think CURY should be paying any divis at all, so I would treat its forecast 4.4% yield as not being something you can rely on. Indeed the last divi was passed, after poor free cashflow was reported for FY 4/2023, see my review here on 6 July 2023 for more of the gory detail. That includes £50m cash required by the pension fund this year, rising to £78m pa for the next 3 years - they’re hoping to negotiate this down.
Paul’s opinion - CURY shares look high risk, if you delve into the detail, in particular its dreadful balance sheet, which last reported had negative NTAV of £(728)m. Maybe it can keep the plates spinning (or maybe the Greeks will keep all the plates, to smash after dinner?!), but the business is completely dependent on trade creditors extending a huge £2.0bn funding for working capital. In times of higher interest rates, companies are less willing to offer generous payment terms like this. Although maybe Currys is too big for the manufacturers to say no to?
There’s also an issue with negative lease entries, implying plenty of loss-making stores.
It could all be fine, but there are very considerable risks with this share, that’s why it looks cheap on a PER basis. So I'm not trying to predict what the outcome will be, as I don't know. Just flagging up the risks.
I’d be looking at much better funded retailers, with positive balance sheets, if I wanted to invest in this sector (worth considering now that real incomes have started modestly rising again).
CURY is far too risky for me, so it has to remain at RED, although we’ll look at the figures with fresh eyes next time it reports. The Greek disposal should boost the balance sheet a bit, but of course it means losing profits from that division too, and we won't see the revised balance sheet until the full year end in April 2024.
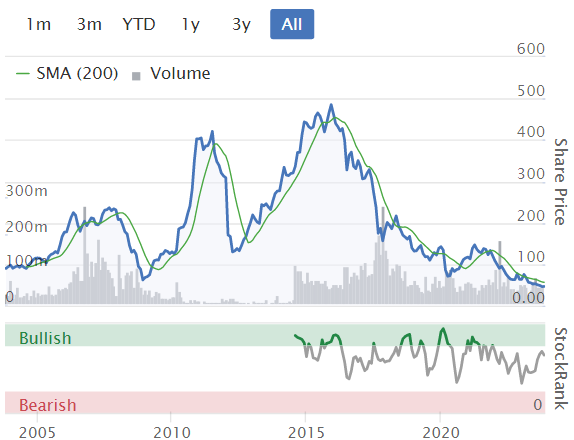
I think there are much better risk:reward opportunities in the market than CURY, but I don’t know how the shares will do. With a peak in 2015, this looks more than just a blip! More like a business that seems to be in structural decline. Maybe one for traders, hoping for a quick bounce perhaps? With a tiny c.1% profit margin, I could see this company bouncing between small profits, and small losses in future. Above all, they have to hope the trade creditors don’t get cold feet and start demanding cash on delivery, as that would instantly kill the business. As could a recession, if we get one - a balance sheet as stretched as CURY's doesn't have any fat in it for a rainy day.
Wickes (LON:WIX)
Up 1% to 133p (£341m) - Q3 Trading Update - Paul - AMBER/GREEN
This looks straightforward, it’s in line with expectations -
Wickes Group plc - Trading Update for the 13 weeks to 30 September 2023
Balanced business model continues to deliver; on track to meet full year expectations
Year-to-date revenues are basically flat against last year, on a LFL (like-for-like) basis.
Given that this lags well behind inflation, that’s not a good outcome on sales, so there must be offsetting margin improvements (lower freight costs, etc).
I don’t find the company’s splitting “core” and “DIFM” revenues is of any use. Sales are sales, to me.
Customers are taking longer to commit to bigger ticket purchases, and there have been some delays from an IT glitch.
Guidance is confirmed - and helpfully it's clearly specified in numbers -
Based on trading to the end of October, we remain comfortable with current market consensus for FY2023 adjusted PBT of £45.3-49.0m
That’s a small profit margin,only about 3%, given that forecast revenues are £1.57bn.
Also it doesn’t tie in with the StockReport’s consensus forecast, which seems to have got higher earnings forecasts from Thomson Reuters.
There’s nothing available on Research Tree.
If I take £47m adj PBT as the mid-point of the FY 12/2023 provided today by Wickes, then take off 25% corporation tax, I get PAT of £35.3m. Dividing that by 257m shares in issue, gives 13.7p EPS, a PER of 9.7x.
Whereas the StockReport says 23.5p, giving a PER of 5.6x, which looks wrong to me.
Ah it’s coming back to me now, this is the one where the 1 January year end has confused Thomson Reuters (not difficult!) and it’s therefore putting the forecasts into the wrong years.
Checking back my more detailed notes here on 15 Sept 2023, with the interim results, I covered this point of incorrect broker consensus figures back then too.
Paul’s opinion - nothing has really changed since my last review c.7 weeks ago.
Dividend yield and buybacks are generous, and affordable given the strong balance sheet, but with such a wafer thin profit margin, it wouldn’t take much of an economic downturn to wipe out profits, and take the dividend down with it.
I thought the price was up with events at 147p, and went AMBER on 15 Sept.
Given that it’s now cheaper, at 133p, then it’s a bit more attractive, especially as the fundamentals haven’t changed - same full year guidance as before.
Overall, if you have to own Wickes or Currys, I would say Wickes is a vastly safer investment proposition. There’s not enough here to excite me though, and I think it’s probably priced about right. So I’ll stick with amber. Or maybe I should be a bit more positive, given the 8.2% (hopefully sustainable) dividend yield, and the high StockRank of 89?
OK, yes let’s go up a little to AMBER/GREEN! I’m basing that on my assumption that the economy isn’t heading into a deep recession of course. If it does, then all bets could be off.
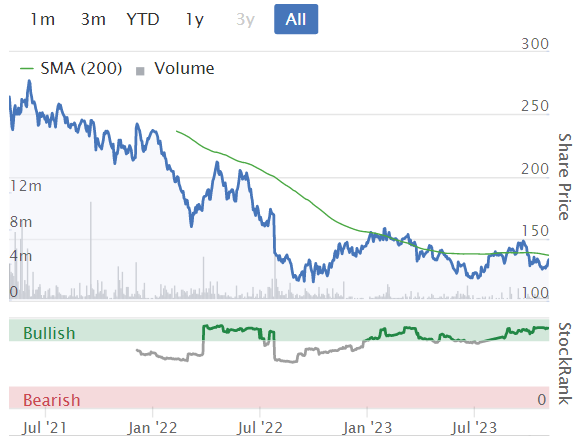
Note that the share count has barely changed since it listed, so theoretically there's nothing to stop the share price regaining previous highs -
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

67 comments
Paul’s optimistic cry of ‘The bounce is on! Is it going to be another bear market rally, or the start of a new bull market? Who knows, it depends on whether people buy or sell’ has prompted a deeper look into my spreadsheets. With help from Edmund Shing, (hi Edmund!) with his Rule of 72 Predictor by which means I can use the Past to see the Future in so far things remain in the area of normality. So to discover how many years it will take for my efforts in equity investment to double the value of the portfolios I maintain I used the annualised growth of the past 5 years. Covid occupied a central part of this term of course but I guess this should count as being within the area of normality today. Backing up the annualised growth is the inclusion of all dividends and the addition of spare cash which ends with a prediction of 18 years to double the current amount in the portfolios. It is hard to reconcile the resultant pessimism with Paul’s optimism; Friday’s upward skip surely follows the adage that one swallow doesn’t make a summer. Here’s how Word sees the trend in my portfolios for this year to date.
Going back to the calculator the past 3 years predicts a doubling in the portfolios in 17 years’ time, and in both cases the gain is bound to be nullified by inflation? Will compounding come to the rescue? In my own case, at age now of 79 I simply won’t be around. All this means that it’s high time to put all I have learned from members comments, the SCVR, and the Stock Reports to better use than previously.
Silver
A good day for Gold
Probably on the back of interest rate rises are done.
But don't trust the market. Horse racing must be more predictable than this stuff.
Currys (LON:CURY) "The enterprise value is £175m, so this is material to the group’s £544m market cap"
Made me sit up ! ...looks cheap ,should read £1.75bn LOL !
WRONG!
No, sorry you're completely wrong there, I don't make mistakes like that!
I was talking about the EV of the Greek subsidiary that is being sold. Not the group EV.
Maybe query the numbers, rather than incorrectly trying to correct me, in future? I pride myself on my numbers. How often are they wrong? Hardly ever. And immediately corrected on the (very rare) occasions they are wrong.
Big soz , scan read your article after looking at Stocko report stating £1.85bn EV ..been a long day -have a nice weekend
Thanks SaarfLondon!
You're one of my favourites, glad we got this sorted :-)
Best wishes, Paul.
Big LOL -You are MY favourite - Pauly Pilot
Just want to say ladies and gents thanks for some brilliant posts this week compared to the car crash that is advfn bulletin boards there's some real top table posters here who comment every day on Stocko , in my opinion that is worth the subscription alone.
Haven't seen Timarr about recently who is generally mustard on the macro but hopefully he's lurking somewhere around.
Have a relaxing weekend folks maybe the sunlight is starting to chink through after an awful 18 months , i've been trading 25 years plus and don't remember all asset classes getting beat up at once as has happened last year and a half, even in gfc bonds boomed to cushion part of the pain.
Hopefully the good times may be about to start to roll again.
Andy
Last 25 years interest and mortgage rates have not increased by 5%!
Withdrawals and redemptions (from stocks to bonds) have been the driving force in this market.
As for the majority of the small caps in the UK one can easily understand that they are mostly listed poxy companies (NOT ALL).
Nice post and I agree. Great place to come and take the temperature, learn something new and share the pain.
Reference the post by Mark Carter on Diageo (LON:DGE) I listened to a Podcast by Nick Train to Investors Chronicle last night and Mr Train is a big fan of the Company. A hold for ever type of Share.
This weeks Top of the Pops & Top of the Flops (excl. total junk)
Some much better looking potential early trend reversals showing up now. Theres loads but a few here
A very powerful move up on the S&P this week up 6% (weekly bars) Has the look of short covering as was the case in October also. Will see where it finishes.....tend to see a selloff on Friday last couple of weeks
This week Top of the Pops includes mostly junk companies that have bounced from their lows.
Top of the Flops companies (excluding 5-6 of them) will probably not be listed in 3-4 years!
Certainly a lot of speculative stuff up this week yiannos.
International Personal Finance (LON:IPF) are launching a 12 Per Cent. Notes due 12 December 2027. I hold the Ordinary shares and will consider buying some bonds. The risk in the short term from a capital point of view is what will they be valued by the market. Given BoE rates seem to have stabilised 12% looks OK. Interested in any other views on this.
A few £100k director buys going through at Eurocell recently. Good to see.
I spotted that too.
This is the risk I think with the strategy by Equals (LON:EQLS) and why I sold. If both have no interest it makes equals look weak and raises questions of why now? Are they seeing softening of busines or some other headwind coming into view? . It wouldn't surprise me if the company leaked the story to Betaville, it was quite a detailed RNS to knock up in 90 minutes or so.
"Statement of intention not to make an offer for Equals Group plc
Fleetcor notes the announcement made by Equals Group on 1 November 2023 in response to market speculation.
Fleetcor confirms that it has been contacted by Equals Group to assess whether it wishes to make an offer for the entire issued and to be issued share capital of Equals Group. Fleetcor announces that it does not intend to make such an offer for Equals Group.
This is a statement to which Rule 2.8 of the Takeover Code applies.
Fleetcor and any person(s) acting in concert with it reserves the right to make or participate in an offer for Equals Group (and/or take any other actions which would otherwise be restricted under Rule 2.8 of the Code) within the six months following the date of this announcement:"
On Surface Transforms (LON:SCE) - I'm a suffering shareholder here :) Bought in around 34p, but luckily as a more speculative bet, was less than 3% of the Boon Fund.
I seem to be going in too early to these zero-to-something revenue businesses. There was Oxford Biodynamics (LON:OBD) (from 30p down to 11p and now up to 35p) and hopefully SCE does the same.
It is frustrating because it seems like management do not have the expertise for manufacturing, and they have belatedly hired an COO.
I posted a few weeks ago I think that I thought an equity fundraising was unlikely, as they would have proven Unit Economics, proven capacity, and firm contracts. That they could then access bank lending.
It turns out I was only half right; banks aren't as lenient as they are before. And SCE has dropped very strong hints on raising cash.
I think they will probably delay that until end of Q4, early Q1. So that they can show monthly ramp-up in volumes, to re-assure new equity investors that there is a credible (profitable) run-rate.
But if they fail to resolve their issues and the run-rate is still low, it will definitely be an equity emergency raise at a discount.
It is now a much smaller percentage of my portfolio, so I am going to mull it over the weekend on next steps.
(I hold in the Boon Fund)
The advantages of a well diversified portfolio; even a couple of zeros will not destroy your portfolio and your life time savings and hard work.
Exactly. My portfolio performance today, even with a -30% for SCE, is still better than the FTSE all-share benchmark.
Risk sizing is always the unsung hero, but it helps when more of the risky clangers are in the smaller holdings.
LARGE CAP QUALITY. I surmised a few days ago that there are some large cap quality growth stocks that are low in terms of relative pricing. I'll start with Diageo (LON:DGE, and maybe on Monday I'll look at something else. Taking yearly snapshots, the current PE is 18.7. This is in the lowest quintile of its valuations. The lowest was in Nov 2014, at 18.4. The highest valuation was in Nov 2021 at an eye-watering 27.8.
Over a decade the shares have risen 60%, which is admittedly no great shakes. The Footsie has risen 10% during the same period, which is pretty rubbish.
I think many owners of Diageo (LON:DGE) are scratching their heads trying to work out the read-across from the recent Remy Cointreau SA (EPA:RCO) results.
They slashed guidance blaming a sharp fall in US demand.
So make sure you are comfortable with the "E" before you worry about the "P" bit....
150 looks good to me..... shorts need to get out of the way now.... enjoy the rally folks
150 looks good to me..... shorts need to get out of the way now.... enjoy the rally folks
Wasn’t the rally yesterday? Agree it’s a helpful number but futures not reacting hard to the print. Bigger reaction is in the 10yr, which looks a tad overdone. Guess we need a few more like that before Jay acquiesces but political pressure will build soon with only a year to go.
Maybe but 150 is goldilocks isn't it ? and im more interested in shape than index levels... with bombed out stocks rallying as perceived rate victims can enjoy the pause.
eg. Russell +2.49%
Maybe but 150 is goldilocks isn't it ?
Yes. I’m reading the reaction as: First derivative up = no recession, second derivative down = rates have peaked
Re Surface Transforms
By my reckoning this company has been going about 20 odd years broadly making the same product. One for very patient shareholders?
Never held or likely to hold.
Paul said "The bounce is on! Is it going to be another bear market rally, or the start of a new bull market? Who knows, it depends on whether people buy or sell."
I was listening to Paul Hill this morning and he is of the opinion that acquisitive companies sense that now is the time to be investing, before PI's realise that company valuations are too low. M&A activity is clearly on the rise signalling we may have reached the bottom.
It's a convincing hypothesis, but as Paul S observed, it depends on what people do.
I've been going through my portfolio and although there has been a good bounce, very few holdings are showing signs of increased volumes. So at the moment I'm quite cautious.
Does anyone know what is happening with Cavendish Financial (LON:CAV) shares are 18% on no news, also were yesterday.
I’m a small investor and have found Stockopedia has improved my performance. However this year I bought some good shares and have shares that are growing and meeting all the criteria but share price down 20-30%. So holding on in hope.
but you cannot expect straight line growth?
you are looking at the change in a year (a bad year with war and interest rate hikes) rather than long term?
I really enjoyed this article. I felt under a lot of pressure to sell some shares that have not performed as well as expected. However, if they are still a quality company and paying dividends then why do it ?
Exactly!
I had missed Currys (LON:CURY) becoming a small cap. That happened fast. It doesn't look good to me, but there is a lot of company for your money, even looking at the EV. It could turn out well if enough of its competitors were to close down before it does. I don't hold.
There is much truth in what Paul says about book values skewing our approach. I suspect we are all guilty, and in my case it is usually stubborness & dented pride that makes me reluctant to sell things.
However, as it is a quiet day I thought I would make the case for holding on to your "losers".
1. Capital losses are extremely useful.
One of the major advantages of single stock investing over funds/trackers is that you have much greater control over your CGT situation. You can choose when to recognise your losses and offset gains to minimise your CGT bill - especially if you have a spouse or gains on property etc. Yes, I've heard "Don't let the tax tail wag the investment dog", and frankly in many scenarios it is terrible advice.
2. Bombed out shares have "option value".
The upside can be immense, whereas you've already taken the loss so there is an assymetry of risk (often exacerbated by others dumping their small holdings). Cleaning them out because you don't want messy small holdings is often a mistake - anyone who has held on to Centrica (LON:CNA) in recent years will vouch for this.
3. Book values don't reflect dividend income
My spreadsheet has a separate column to show cumulative income over the holding period. I have many holdings where the P&L looks anaemic until you take into account divis & special divis. Legal & General (LON:LGEN) is a good example. Just make sure you hold these in your ISA/SIPP. Stockopedia subscribers are very poorly served here as all the charts are price only, rather than total return - and it makes an immense difference (as anyone who is familiar with Bloomberg's TRA functionality will attest). Dividend compounding matters over any multi-year horizon.
4. Reversion to mean
This may not be a popular opinion...but none of us are clairvoyant geniuses and there is a lot management don't know, let alone investors. If you've just experienced some bad luck with a share (as opposed to a fundamental fault with the company/management coming to light) then it makes little sense to sell because of some arbitrary stop-loss...you will have to re-invest the proceeds in another company. Are you jumping off one sinking ship (where the management have at least started to plug the hole) onto another where the management have yet to even spot the rocks?
These arguments of course run contrary to much of what you will read - how to deal with profit warnings etc, and I do like to play devil's advocate, so take with a pinch of salt.
Good point, particularly the last one. Since Frances Dalton first noted that tall parents tend to have shorter children, and short parents have taller children, the idea that things tend to move from extreme values to more average ones over time, has been extensively studied, but is still not well understood. It suggests that managers, if they want to have a good track record, should take over at failing teams/institutions, since , without doing anything, performance is likely to improve back towards the average. If you take over at the best performing place, it is likely to do less well over time. Of course, there are many other factors at play which influence performance but regression to the mean is a poweful one which influences many aspects of life and the world. It is a useful lens to bring to bear on stock and share price performance.
Well.....today has served up a perfect example.
Terry Smith sold his Estee Lauder Companies (NYQ:EL) after profit warnings (to be fair, before the most recent one...) and opened up a position in Fortinet (NSQ:FTNT) which has just warned...
I used some of my horrendous losses eg Patisserie Valerie and some Woodford duffers against capital gains on BTL. But losses in an ISAs and SIPPs are a total loss
Arix Bioscience (LON:ARIX) Final thoughts on this bid by RTW Biotech Opportunities (LON:RTW) . It would appear that Acacia Research(hold 25.52%) pushed for this deal. Quite how it is allowed that they get cash and the rest of shareholders shares- which are now worth about £1.28 not £1.43 is a mystery to me. Given the cash and listed part of Arix was worth about £1.24 looks like the best interest of the majority Arix shareholders have been ignored in this transaction. I am told Acacia were not "natural investors" in Acacia- they are part of Starboard Value an activist fund. They bought the holding from the distressed Woodford funds.
It is also suggested that the unlisted part of the portfolio was hard to sell at the valuation, and a substantial discount had to be taken. Begs the question who other that Acacia would have asked them to sell at a large discount. Arix could have sold the quoted part of the portfolio, returned that and the cash to shareholders and slowly wound up the unlisted portfolio. Other listed funds have and are doing this.
I did not imagine the strategic review the board undertook would end up with such a poor deal for the majority of shareholders. Lesson learnt, though not quite sure what that is !
I will hold in the hope terms will be improved, but not with any conviction. RTW have done a good deal it would seem so maybe the new shares will perform better than Arix did- Biotech is an interesting area at the moment.
I don’t hold but am watching for Arix Bioscience (LON:ARIX) to drop sub 110p
What has occurred here is that RTW have priced the deal against their NAV and not their share price which is also at a discount. So when you combine the assets it is not NAV dilutive for RTW which I understand.
Whether that is a good deal for Arix Bioscience (LON:ARIX) shareholders is another matter but clearly driven by Acacias desire to exit and perhaps a threat to dump stock if a deal not agreed within a certain timeframe.
But I’m with Mojo on this in that the assets are probably more likely to generate stronger returns in the long run under RTW Biotech Opportunities (LON:RTW) ownership. So if there are exiting holders I’d probably pick some up around the 110p mark. Doesn’t currently look like it will drift that far but we will see
davidjhill I would agree with you that ARIX could be a cheap way in now- doing the maths looks 10% cheaper than buying RTW. . I am already fully weighted in ARIX so not sure I will be buying more. I am still researching RTW- I had put on a watch list as it happens a few months back.
PEEL HUNT agree https://citywire.com/investmen...
Update on Arix Bioscience (LON:ARIX) Takeover panel say this is not a takeover bid. It is an acquisition of Assets so outside of the Takeover rules !.
MS International (LON:MSI)
http://newsfile.refinitiv.com/...
Half way down this RNS is reference to a Grant of Phantom Award to director Roger Lane-Smith of 100,000 shares that will only vest if ownership of the company changes in the next 10 years. Considering the ages of the board is this a sign they are starting to consider an exit plan?
For me MS International (LON:MSI) almost certainly get bought out at some stage but hopefully not too soon as I see material upside opportunity.
the main fly in the ointment of a sale is the conglomerate nature of the business. Either they need to sell businesses separately or a new owner would likely buy for the defence business and divest most of the rest.
Anyway for now lots of opportunity and when the directors who are notoriously quiet and understated say they are seeing a step change I tend to believe them. Fingers crossed anyway.
He will be 86 in 10 years time !
Buffett is much older…….
Maybe it's the Coke (cola)
Exactly!
Wickes (LON:WIX) reports on Q3 today and remains in line with forecasts. I did hold this previously but sold out at 150p as more and more householders' DIY budgets are getting squeezed by mortgage costs so the risk for this share feels to the downside especially for a p/e at 9 when you can still get a lot of other retailers for less than this.
The stockopedia site continues to have last year's data for FY23 - I have raised this via the green button previously but it's a data problem on the supplier side I believe so unfortunately the stockrank and p/e data isn't accurate.
I've raised this problem several times, with no correction, on this and 3 other companies, who all have a year end on 1st January. The whole company sheet is misleading with forecasts showing dates of previous years. What does it take to get some action on these ?
Yes I have raised this issue as well and was promised it would be sorted out soon, but that was about 9 weeks ago. Just because of the date on the results said 31st December. The figures are even on Stockopedia if you look at the accounts, can't understand why Stockopedia can't adjust them. They seem to totally rely on information from their provider. I really despair. I chased it up on 13th October but never got a response. Chased again.
Wickes (LON:WIX)
Wickes is an interest Stock. It has a third of its mcap in cash. It’s on a single digit p/e with a substantial covered yield and doing their first buyback.Housing market is weak, rates are high, consumer will be squeezed-which bit is new news? There is a reason that the share price has halved in the last year-this is all old news. Does that mean this is the bottom-of course not. No one has a crystal ball but RMI is clearly not going to end. If I can’t move I may do home improvements, our housing stock is old and needs constant work, all my builder friends are still relentlessly busy. I’m not saying Wickes is the one to own, I have been buying several housebuilders recently.
I have been trading/investing in this sector for 34years. I have never seen the housebuilders looking so cheap but with such strong balance sheets. These are interest rate plays where you are being paid to own them in my view. At the most extreme level is Crest Nicholson Holdings (LON:CRST), it is trading at less than 0.5 NAV. If I was offered a £1m house for £500k and get paid a yield, I’d think I’d have a good chance of making money. No housebuilder trades at 0.5NAV through the cycle and stays independent. Clearly you can disbelieve NAVs but this is a very different sector nowadays. The managements are all rewarded very differently and will focus on returns.
I could drone on, cyclicals are meant to look at their most expensive at the bottom. I could make a case for several of them now. I have been buying Crest Nicholson Holdings (LON:CRST), Berkeley group (LON:BKG), Vistry (LON:VTY), Bellway (LON:BWY) for the last month. We live on an island, we need more houses, strong balance sheets, oligopoly, I expect political help in the run up to the election and rates are peaking. If your personal balance sheet can ride out the cycle then I’d expect to be handsomely rewarded.
Thanks for your thoughts about housebuilders MH1. I also do not understand why they are so cheap but I wonder if some investors are concerned about your scenario of being offered a £1M house for £500,000. Do you think falling house prices may help explain why shorter term investors may be wary of the sector, despite the much stronger balance sheets? My preference is for M J Gleeson (LON:GLE) because they build affordable houses and perhaps may benefit (or be least harmed) by policies which Labour may introduce if elected next year.
I’d say this is the nature of cyclicals especially one’s perceived to be to be tied into the interest rate cycles. Vistry which is more liquid is moving its whole business to partnership housing( more affordable) is already committed to giving circa 35-40% of its mcap back in the next 3yrs.
In the worst case scenario you see dividends cut but it’s likely to be because land is trading at distressed valuations and they’re augmenting their land banks and if you believe in management then that’s the right capital allocation decision.
I could just as easily ask why were people paying 2x NAV for Persimmon at the top? That was the same Thing in reverse. Rising rates, a long way from asset backed protection on valuation.
Fund managers generally are not paid to take risk. They don’t have any great insight and even if they did they couldn’t express it because they are tied to benchmarks. My whole career was spent exposed to them, you really don’t need to worry about what they know usually. They are exposed to fund flows and justifying themselves to trustees etc every three months.
Time will tell, this is what makes a market:)
Pretty much at the bottom of the GFC Persimmon announced it was going to pay the equivalent of its market cap in dividends over 5 years. Are we in a similar place?
Portfolio rebalance if anyone Intereted .
Had a good review of what I’m sat on yesterday and action points
Avingtrans - looks like there’s a lot of stock in the market and price at bottom of range .
Add at 372 to increase to a maximum holding (done already )
Trifast - like the recovery story carry on building a stake but no rush as this is a long recovery play (not rushing )
Wynnstay - so solid with dividend and asset backing start Mg to recover , imcrease to 2/3 position (had reduced to 1/2) . Buy in ISA / pension as good dividend . ( caught some at 392 )
Georgia Capital - increase if in low 900s as it’s dropped a bit , Bank of Georgia very strong and it’s underpinned by owning 20% of BoG. (Caught sone at 930)
Bloomsbury - increase on weakness / bottom of trading range
Holders - keep selling down (painful)
Equals - top slice 5% yesterday
Can’t find anything with sufficient conviction to add and a lot of the stuff I was considering has already started a bounce .
I will throw one trend into the pot - decoupling ? Ironically the fiscal situation is not the same in Europe / US /China / UK … the UK has seemingly been in the worst situation for a whole host of reasons But .. Is the inflation trend as strong in Europe as it is in US ? Perhaps not - the post Covid economy harmonised global trends although China was in first and out last. Maybe economies diverge more next year and this becomes a positive driver not negative for UK … since the starting point is so attractive. Maybe all we need to do is stop shooting ourselves in the foot - I know I’m dreaming ? But .. I’m saying there is a chance
Paul, your comment "gratefully selling them if they got back to breakeven,"
I'm sure we've all been there Paul, I certainly have. Been underwater so long on some that breaking even is like getting your head above the surface and the feeling of relief after a dive as you fill your lungs. I've missed out on a few that have gone on way past break even. So I must think would I buy them rather than looking at the green grass over the fence.
I'm with Paul... we got oversold short term and its ripe for a bounce... I tend to think of the market as a bit of a bully during difficult times, searching out weakness which it punishes...the pace of recovery was pretty explosive yesterday...if this follows through, after negotiating the non farm payrolls today then the shorts are going to have to cover. The inversion has obviously unravelled significantly but it still potentially has some way to go...and so a concern for me, would be the rally has been driven off a rally in bonds. This suggests there is still a decent sensitivity to inflation and higher for longer will continue to exert pressure on long bonds. This trend has not been a friend of the value investor ( which I include small cap) which is behaving more cyclical at the moment. Rightly or wrongly. The prospects for more weakness in CPI in Q1 next year is possibly more positive than I thought.
So I'm comfortable investing even against a backdrop of expecting more weakness and uncertainty mainly because the longer this all goes on, the recovery will be spectacular. I think we are all on the same page here, focussing on which are the best companies and accepting, even these will miss numbers from time to time. It feels like the profit warnings will continue into Q1 next year and ...I hope the recession arrives soon so we can move on ...
Im not sure how everyone else feels but Im a little short of new trends emerging into next year... energy transition is in disarray...ISM weak...China weak... Oil and Gas feels ok to me... Nuclear build good.... it does leave me feeling boring divi stocks will do well for a while until a more positive earnings cycle unfolds. Ironically its all the profit warnings that reset the deck for this to happen... some rough water to sail through but reasons to be positive too... at the end of the day a lot of worry already in the price.
You make an excellent point regarding short positions. I'd imagine a lot of the upside has now passed and a good number will be looking to jump ship with profit in hand before it's too late.
Short term : Defence, Oil and Gold?
Medium term: Back to the cyclicals? Housebuilders, Brickmakers, etc followed by Fund managers as those who develop FOMO pile back in? And personally like the prospect for REITs as seen in the bounce yesterday. Happy to take the divis while we wait for the capital growth as long term interest rates come down. Good article by Edmund on this at the weekend I thought.
Germany seems to be leading EU lower and Canada is a little out of step with US so maybe we have to pick our markets as well as our shares?
Yep agreed re portfolios
No book price and consider if you were a Martian and came down to earth with no memory of the day before.
Is the portfolio in front of you the best one would create?
And if you sell a stock, remember it’s a piece of paper, it has no feelings, it won’t resent you selling it!
Agreed Scotty
Indeed hopefully the war on inflation may now be 'largely' over.
According to economic forecasts, CPI in Europe, the UK & US should all migrate to below 2.5% by the end of 2024.