Small Cap Value Report (Fri 30 June 2023) - BOTB, GLE, COST, DPP, ANP, REC, LTHM, VARE

Good morning from Paul, and happy half-year's eve! The card manufacturers are missing a trick not making cards for today, and half-year's day tomorrow!
Today's report is now finished. Podcasts tomorrow!
Half-year comments
This weekend I'm hoping to do a half year review of my 2023 watchlist ideas, which have done quite well in a lousy small caps market. Here's an overview -
Top 20 main value/GARP ideas - as of last night, 14 were up YTD, 6 down, average +6%, vs AIM All Share down 10% YTD, which is a creditable 16% out-performance. One takeover bid out of 20 shares, Best Of The Best (LON:BOTB), a 32% gain. I forgot to put Warpaint London (LON:W7L) on the list too, which is up 48% YTD, so if I'd remembered, the overall gain would have been higher.
Hence it does seem that value/GARP small caps have been a relatively safe haven in a difficult market so far this year. Although we could see it as more bumping along slightly above the bottom, given that 2022 was really bad for UK small caps. The recovery will happen, it always does, we just don't know when! Plus no doubt we'll see more upside from takeover bids, which help demonstrate that the market is cheap right now. This spreadsheet tracks performance with live prices.
"Runners up" - 12 more value/GARP ideas for 2023 - 7 up (not the drink!) and 5 down. Average is also +6%, also 16% out-performance against the AIM All Share index. Boosted nicely by the car dealers, with a + 56% gain on Lookers (LON:LOOK) (which I've banked in the market, due to deal risk worry), and also a nice +28% from VTU.
Cyclicals (Reach, Eurocell, and Headlam) are the 3 worst performers so far (Reach also got embroiled in renewed phone hacking legal action from Prince Harry). Here's the spreadsheet for this selection of 12 shares (same spreadsheet as above, but a different tab).
A lot of the above shares also pay divis, so the total return is higher than +6%.
How has my own, real world portfolio done? I got lucky with the 200% premium takeover bid for Seraphine in January, which was by far my largest position at the start of the year. So that's heavily skewed things into a large % gain YTD. However, I'm 23% down from my peak at the end of February 2023, which already takes into account the big imminent loss in WANdisco (LON:WAND) when it returns to trading shortly (a stupid decision to buy something highly speculative, where the trading updates turned out to be fraudulently mis-stated - not really something you can anticipate). Also, I'm still about 30% down from my all-time-high in mid to late 2021. So plenty of work to do, to get things back on track in the next bull market, but I'm confident it will happen, in time.
NB. I'm only referring to continuing activities, which is my ungeared portfolio. I've excluded the highly volatile performance from my geared portfolio, because I've closed it down, so in accounting parlance that is a discontinued activity! And life is much simpler and less stressful as a result, so there's an intangible benefit there [which I promise not to capitalise!]
Just thought you might find the above interesting.
Rather boring companies reporting today, so I'll probably try to pick off a few of the backlog items that are more interesting -
Quick Comments
Best Of The Best (LON:BOTB) (I hold)
530p (£44m) - Update on Mandatory Recommended Cash Offer of 535p - Paul
Globe Invest (Tedi Sagi) announced yesterday that it won’t be increasing the cash bid any higher than 535p. It’s been buying in the market, increasing from 29.9% to 38.7%. EDIT: RNS just out today saying Globe has increased further to 42.25%. Together with management irrevocable undertaking shares, the total was 58.75% yesterday, now up to 62.3%, so it's a done deal I'd say.
The “Mandatory” wording relates to Takeover Panel rules, where if anyone goes over 30% they usually have to make (ie. mandatory) a takeover bid, unless they’ve previously received a whitewash agreement allowing them to go over 30% (which first requires a 50% vote of independent shareholders).
An example of this has coincidentally been announced this morning at another company - shareholders at tinyBuild (LON:TBLD) (I hold - just a punt yesterday) have voted against a whitewash arrangement to allow its founder to increase his stake.
Paul’s opinion - a desperately disappointing end for small shareholders in BOTB, with the company being sold at an undervaluation to Tedi Sagi, despite a strong trading update earlier this year, and broker forecasts revised upwards, and a lowish PER. Although management had already effectively cashed out a while ago, c.£70m banked mostly at a price of £24/share! So their remaining holdings were only worth barely more than 10% of what they’ve already banked, so perhaps it just wasn’t worth the hassle for them to carry on running the business (after over 20 years), when they’ve got £70m burning a hole in their back pockets? So I can see why this deal makes sense for management, but it’s a big disappointment for outside shareholders. Still, BOTB shares have delivered a 30% YTD rise, which is not to be sniffed at. Previously, BOTB shares did a 30-bagger move roughly, from £1 to a peak of £30, so the opportunity was there for investors to bank a big profit too. I certainly don't bear a grudge, this has been one of my best ever investments, banking profits well below the £30 peak on the way up, but still a substantial gain.
Since the 535p deal now is almost certainly going ahead, with very little chance of any further upside, it might make sense to sell in the market, if there’s something more interesting to invest in (that’s what I’ve done, selling most of mine). Or hold out for the last few pence, whichever you prefer. Deal risk looks low to me.
MJ GLEESON (LON:GLE)
358p (pre market) £209m - Sale of portfolio of homes - Paul - GREEN
Many thanks to Ben Hazzard for flagging in the reader comments the RNS from this low-price housebuilder, which I hadn’t spotted.
This is extremely interesting, and could be a trigger for housebuilder shares to recover possibly? I say that because selling big parcels of houses to institutional investors (build to rent) could enable housebuilders to up their production and sales, despite a slowdown in demand from individual households (due to macro, higher mortgages cost, etc) -
MJ Gleeson plc ("Gleeson" or the "Company") is pleased to announce that it has entered into a contract with global investment firm Carlyle (NASDAQ: CG) and Gatehouse Investment Management, a market leading single-family housing investment manager, for the sale of 288 homes across multiple developments, of which up to 66 homes are expected to be completed in the financial year ending 30 June 2023 ("FY2023") with the balance in FY2024.
Consideration for the sale totals £50.4m payable in cash upon completion of each home, save for a small retention. The proceeds will be reinvested into the business for working capital purposes. This transaction strengthens Gleeson Homes' forward order book and allows the business to expedite the opening of new sites.
The Company will issue its next scheduled trading update, in respect of the year ending 30 June 2023, on 7 July 2023 and expects to confirm that it will deliver results for FY2023 in line with expectations.
Paul’s opinion - this looks quite exciting to me. If I had any spare cash, I’d be a buyer of GLE after this news. It also sounds potentially good for the country, to see institutions buying up new houses, then if it happens at increased scale, this could improve the supply of good quality rental properties, which is badly needed.
Bear in mind also the imminent reforms to unlock infrastructure investment from insurance companies, pension funds, etc, is there the potential for a boom in housebuilding, not linked to mortgage rates? This type of thing could be a gamechanger, and a nice catalyst for renewed interest in housebuilder shares. So thumbs up from me, and for the sector, which is cheap right now I think. Although if house prices fall a lot, then all bets could be off. So some risk for sure.
EDIT: Many thanks to Liberum, with an update note available on Research Tree. This says that today's deal represents 4% of sales volumes for FY 6/2023 (ending today!), and a whopping 12% of forecast volumes for the new financial year, FY 6/2024. So this deal looks highly significant. The only query I have, is what volume discount the buyers have negotiated? There's a danger that margins might take a hit, chasing volume, who knows?
Liberum also says the average sale price of £175k is 4% below the average. Also there will be no selling costs (compared with selling houses individually - e.g. marketing, commissions, etc), which helps offset the price discount. Carlyle (the buyer) is a huge operation, with plenty of experience in buy to rent, so maybe there could be more similar deals for GLE, and other housebuilders?
Could this be the time to buy? Or are we going to see another leg down, if macro conditions worsen? Answers on a postcard please! Do remember though that this time, housebuilders have bulletproof balance sheets, with net cash. Very different to previous recessions, where they were loaded up with debt. That makes risk:reward a lot more favourable this time around, although as always, timing the exact low is pure guesswork.
Costain (LON:COST)
Up 2% to 46p (£128m) - Reduced pension contributions - Paul - AMBER/GREEN
Good news for shareholders - the minimum deficit recovery payments by Costain into its pension fund are to drop from £12m pa to only £3.3m pa.+ CPI inflation, from now, July 2023. There is a total funding deficit of £25m, so this payment plan looks very reasonable.
There is a potential sting in the tail though, in that if divis paid exceed pension contributions, a top-up is required. That does look an issue, based on the forecast divis. So if people want good divis, then the pension contributions would be a fair bit higher than £3.3m, so maybe keep the bunting tucked away for the time being!
The StockReport shows 1.63p divis forecast for FY 12/2023. With 277m shares in issue, that would cost £4.5m, which is well within the total expected pension contributions this year (a split year) of £7.4m.
However, looking at FY 12/2024, forecast divis are much higher, at 3.17p, costing £8.8m. That's way above the minimum of £3.3m, so if my numbers are correct, those divis in 2024 would trigger an additional £5.5m payment into the pension scheme, taking the total to £8.8m.
Contributions stop if funding reaches 101% (currently 97%).
Paul’s opinion - there are quite a few moving parts here, but it’s clearly a positive that the minimum level of pension deficit recovery payments has dropped such a lot. Management might decide to postpone dividend increases, and instead prioritise acquisitions, or internal investment, so as not to trigger larger pension payments. They’ve got a variety of options anyway.
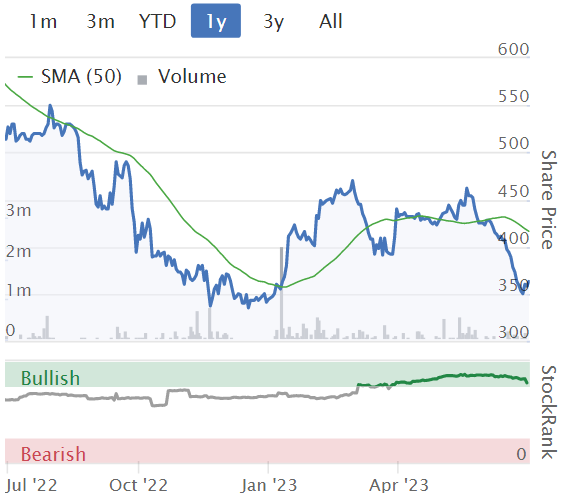
Looking back at my previous notes, I’m not keen on this low margin contracting sector. Although COST has the best balance sheet in the sector that I’ve looked at. Ultra-low PER of 4.1x has obvious appeal, and we had in line updates on both 11 May, and 9 June. Something went wrong with a contract building the A66, which wasn’t very well explained on 9 June, so that worries me.
Overall, COST shares look superficially very cheap, now they’ve dropped a lot recently into value territory. Although bear in mind the negative points above. Let’s split the difference and call it AMBER/GREEN.
DP Poland (LON:DPP)
Up 2% to 7.85p (£56m) - FY 12/2022 Results - Paul - RED
Some quite good KPIs, but the bottom line is yet another hefty loss chalked up - DPP has been listed on AIM for 13 years, and it’s never made a profit! It operates the Dominos Pizza franchise in Poland - where they love pizza, so there’s masses of home-grown, much cheaper competition.
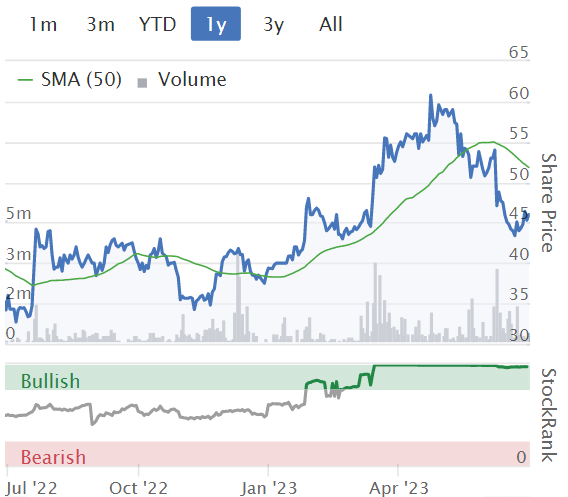
Look at how the share count at DPP has soared (712m now, 129m in 2016), as it’s diced with death numerous times, being bailed out with repeated placings. Why investors keep pouring money down the drain here, I cannot fathom.
It made an acquisition of another chain, not long ago.
Revenue £36m (up 20%)
Loss before tax is flat vs LY at £(4.3)m
Outlook - doesn’t say anything of note, other than that “some food costs dropping in Q2 2023” should help improve profitability (ie. reduce losses).
Balance sheet - is weak, with NTAV of around zero. Small net debt position.
Looks like another refinancing is only a matter of time, probably dressed up to say it’s for another small acquisition.
NB note 27 shows that loan notes of 7.5m Euros are payable by DPP on 31 Dec 2024. It doesn’t have the cash to pay those, so a refinancing will definitely be needed.
Paul's opinion - I wouldn’t go near this share. It’s a lousy business, and valued at a totally irrational £56m. Moreover, the clock is ticking for repayment of a 7.5m Euro loan note at end 2024, so it will need to raise more cash, or convert that loan into equity maybe, if the lender agrees? Either way, this share looks deeply unattractive. RED.
Hopefully this section is helpful to anyone, to put you off buying DPP shares if you read a puff piece about it somewhere else. This is why we cover rubbish companies as well as good companies - so you can look up our notes, and save time having to find all the things that are wrong with it!
Anpario (LON:ANP)
200p (£48m) - AGM Statement (y’day) - Paul - AMBER
Anpario plc, the independent manufacturer of natural sustainable animal feed additives for health, nutrition and biosecurity…
Says that trading continues in line with expectations, but look how much they’ve reduced expectations in recent months - EPS forecasts more than halved! -

ANP says that farmers are cost-cutting, so demand for speciality feeds has reduced. It sees no immediate improvement, but is hoping for a better H2.
ANP itself has been cost-cutting too, to benefit H2 2023, and 2024.
Improved efficiency from automating production.
Gross margins are improving as lower raw material costs are coming through.
H1 results due out 13 Sept 2023.
Paul’s opinion - I’ve not been keen on this company before, as performance did not justify its premium rating. On the upside, shares have fallen a lot, and I previously mused on 22 March that at 214p the shares might be coming into buying range.
A 225p tender offer for 17% of the shares was announced on 8 June, putting the surplus cash to good use. That could mean future upside on EPS, if trading recovers.
The hope for an improved H2 mentioned today seems to be backed up with sensible reasons, although it sounds like interims are likely to look poor, so why get involved now, and probably take another hit when interims are published?
Overall, it all just seems a bit lacklustre. ANP seems to have a fairly high margin niche, and profit might recover back to previous £3-6m pa range in time. But what then? To engage my interest, I’d want to see its products generate sizeable compound growth, and become a mainstream proposition. It’s easy to see how that could make this share a multibagger. Trouble is, it just hasn’t happened, and doesn’t look likely to happen at this stage anyway.
So ANP can only really be seen as a value share at the moment, on a PER of maybe 10x.
If earnings recover back to previous levels of say 15-20p EPS (raise that by 17% due to the tender, so 17-23p forecast, hence 170-230p target share price.
By coincidence, it’s plumb in the middle currently at 200p. So ANP looks priced about right. Hence I’ll stay AMBER. I’ll keep an eye on it though, as any acceleration in growth, eg big new contracts, would be a potential buying opportunity in future.
A big de-rating here, as the growth trend conked out -
Record (LON:REC)
Unch 93.5p (£186m) - Final Results - Paul - AMBER/GREEN
Record plc, the specialist currency and asset manager, today announces its audited results for the year ended 31 March 2023 ("FY-23").
I’m not familiar with this share, but wanted to flag it to you for further research because the shares are close to a multi-year high, and results reported today look excellent.
Profit before tax (PBT) up 34% to £14.6m
Notional assets under management (read the footnote 1!) are huge at $88bn
Divis raised 25% to 4.5p total = 4.8% yield, pretty good. On top of this, it also seems to pay smallish special divis each year too, taking the 2023 yield up to 5.5%
Basic EPS up 32% to 5.95 = PER 15.7x - the StockReport shows consensus forecast of 6.01p, so it’s a whisker below.
Outlook comments from the outgoing Chairman (founder? It’s his name over the door!) are very interesting, looking at the macro picture, and implying maybe we’ll end up going back into a QE, low interest rate environment from political necessity? Maybe this is why US markets are showing apparently irrational strength? (although it’s narrow leadership) -
Outlook
In contrast with the optimistic tone with which I feel I can talk about Record, I see many serious and deep challenges ahead for the global economy in general, and for the developed West in particular.
Across the board, Western governments have arguably over-extended themselves both in the scope and scale of public expenditure, and in their method of financing this expenditure - namely through debt. Much of this debt is, in practice, monetary financing via "Quantitative Easing". Central banks, and their sponsoring governments, may find this financing becoming increasingly onerous as short rates rise. The same issue has already hit some regional banks in the US, and may hit more. This monetary dislocation is running concurrently with very low or zero productivity growth in much of the global economy. It remains to be seen whether Western democracies can find policies to re-establish low-inflation growth.
Record is not immune from these challenges, but structurally we are positioned to be nimble and adaptable to client demand as it develops and changes. While cost pressures (particularly labour costs) will undoubtedly impact the business, the current pace of growth and change should allow the revenue to grow sufficiently to more than compensate for the cost-base growth.
I leave the business in good health; vibrant, enthusiastic and looking for new opportunities. I couldn't have wished for more.
In addition, the CEO has his own outlook section (below), and seems to like analogies that don’t actually say very much -
Outlook
The next phase of our development of Record is to reap some of the rewards of our modernisation and diversification. The soil has been fertilised over the last few years, and the new plants well heeled in. For quite some time they have been putting down roots and like any young tree more has been going on under the surface than on the top.
As was clear at our Capital Markets day recently, the next phase should see some new revenue from our diversifying strands at RAM and Record Digital as well as continued work to scale our currency business. This continues our theme of diversification and modernisation, while our recent promotions carries on our theme of succession planning for the long-term future. We will continue to keep a close watch on costs but drive forward with our three‑year plan.
Balance sheet - looks OK with about £27m of NTAV.
Paul’s opinion - neutral, as I don’t know anything much about the company or its business model. However, the figures look impressive, both these latest results, and the historic track record. Could be worth you doing some research on it. So let’s go AMBER/GREEN to reflect that.
Forex related businesses seem to be having a bonanza at the moment, and Record is no exception. So the vital question is whether this is sustainable? Also risk management is critical at this type of business I would imagine.
James Latham (LON:LTHM)
1,239p (£249m) - FY 3/2023 Results - Paul - AMBER/GREEN
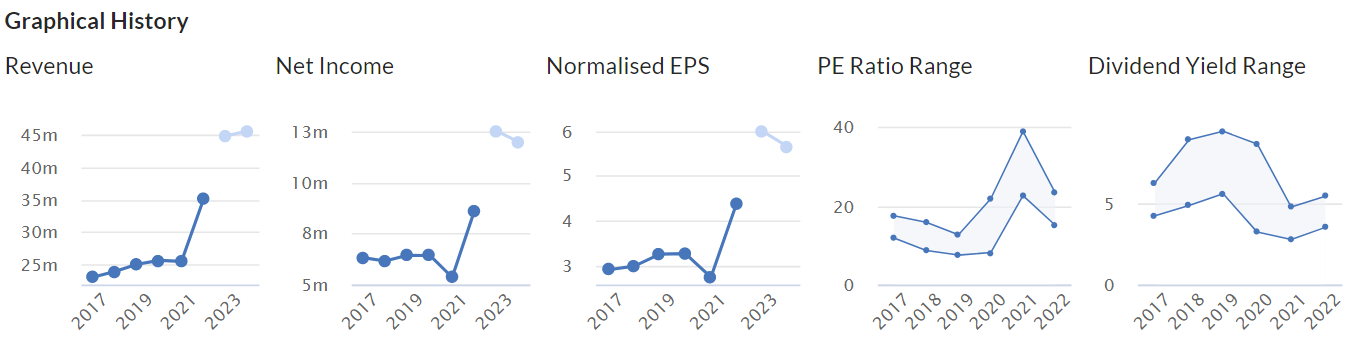
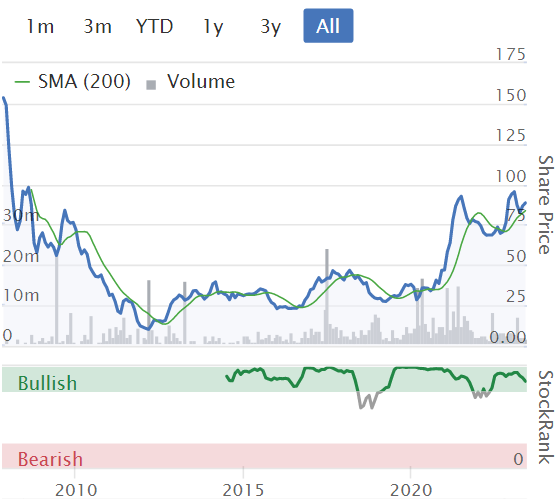
Lathams distributes a wide range of timber products. It’s had an absolute bonanza during the pandemic, with profits soaring -
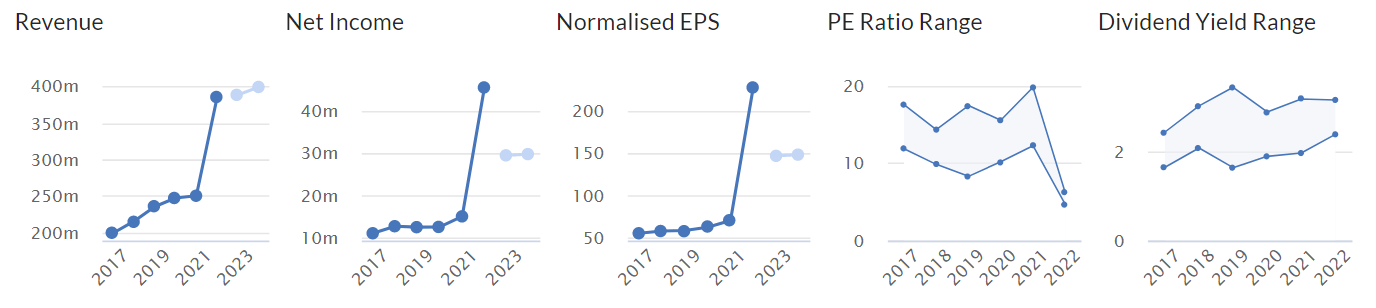
Pre-pandemic it made a fairly consistent operating profit margin of around 7%. That shot up to around 15% in FY 3/2022, combined with much higher revenues, from higher unit prices, and the pandemic DIY boom, saw PBT soar to £58m last year.
This year it’s come down a bit, but PBT still highly impressive at £44.5m, based on an operating margin achieved of 10.7%, about half way back to normal (7%) from the peak (15%).
EPS numbers are 180p FY 3/2023, and 229p FY 3/2022.
PER is 6.9x on the latest number - cheap? Not really, because earnings seem likely to fall further, as things normalise.
Valuation - I’ll have a stab at valuing this share, because I don’t want to value it on super-normal profits generated from one-off supply chain chaos caused by the lockdowns. Also I can't find any broker forecasts.
The big question is to what extent will revenues and higher margins be maintained? Who knows? These things tend to revert to the mean though, and often shortages are followed by gluts. So anything could happen.
We could work out a range of scenarios. I think my base case for valuing the shares would be to ignore current trading, and assume the operating margin returns to c.7% in time. Revenue might fall too, as supply and competition normalise, so say 20% off revenue gets us to £326m, at 7% is £23m operating profit. PBT would be higher than op profit, since it has a big cash pile, earning interest now, so I’ll say £2m net finance income, hence £25m PBT. Take off 25% tax, and I make that earnings of £19m, divided by 20.2m shares = 94p per share. Hence the 1,239p share price works out at a PER of 13.2x my forecast future normalised EPS. That seems reasonable, and is a similar rating I remember in the past for this share.
Balance sheet - is stunning! I always say that for this company, and every time it gets better still. NAV is now up to £196m, with only £2m intangible assets, so £194m NTAV! That’s incredible.
Net cash is £62m, which doesn’t look window-dressed (ie exaggerated) to me, because creditors are low. Net working capital is a remarkable £155m! So Lathams could easily pay a large special dividend if it wanted to, but owner/managers are super-conservative here, only paying small 8p special divis this year & last year.
Cashflow - is better than last year, as the previous working capital build-up has flattened off now.
Dividends are very well covered, so the company could easily afford to pay out far more, it doesn’t need to hoard all that cash to such an extent.
Note the pension scheme is a drain of £4.4m on cashflow this year, and £3.4m last year.
Outlook - sounds mixed. This bit worries me a little -
We have a concern that the market in Europe is quiet, and this could cause manufacturers to export cheaper product to the UK market, and negatively affect product values…
The board is therefore very aware that the results for the last two years have been exceptional, and far beyond the profits earned before the start of the COVID-19 pandemic. The board's challenge is to navigate the business towards what is a more normal and realistic profit achievement which takes into account the market conditions we are operating in and the inflationary overhead pressures that all companies are facing.
Straight talking there, which is commendable.
Paul’s opinion - I think it looks reasonably valued, even on my basis of making quite cautious assumptions. As management confirm, the last 2 years have been “exceptional”, and investors should keep that front of our minds, so don’t make the mistake of valuing this share on probably unrepeatable high profits.
There’s also the magnificent balance sheet to take into account.
The consensus forecast for FY 3/2024 of 148p looks much too high, so I would expect to see that come down. My 94p estimate is far more realistic, and valuation still stacks up at that level too.
Overall then, I’ll go AMBER/GREEN.
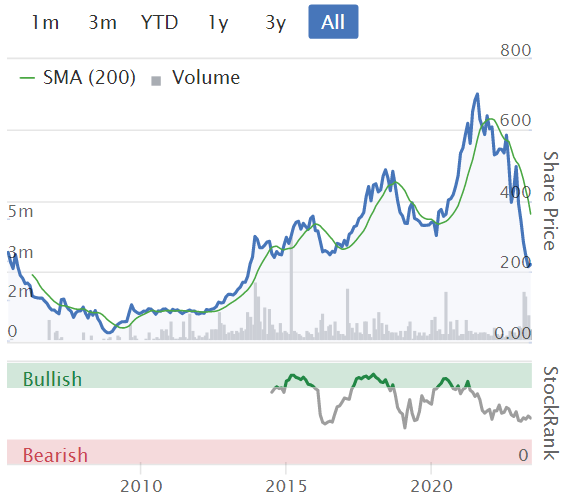
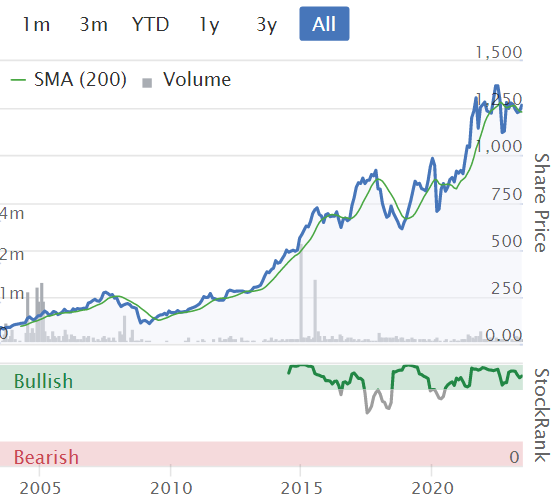
An amazing long-term chart (with divis on top), but I'd rather buy on a dip, not near the highs -
Various Eateries (LON:VARE)
32p (£28m) - Interim Results - Paul - RED
A small, but expanding chain of bars & restaurants, main brands being Coppa Club, and Noci.
Horrible H1 figures, this is really struggling now. Has spent most of its cash pile on expensive fit-outs of new sites.
Profit warning - EBITDA margins “significantly lower” than previously expected.
Paul’s view - I’m struggling to see any attraction to this share, almost at any price. Hospitality sector is really grim at the moment. Given that VARE spends big on swanky fit-outs, those sites should be highly profitable when they're new. But it still can't make a profit, so I think the concept is actually quite flawed.
It's probably going to need another fundraise, to keep funding the fit-outs for new sites, unless it can do deals for large reverse premiums from landlords.
2 main shareholders - Hugh Osmond (47%), who hasn't demonstrated yet that he can work his magic on this company. And Canaccord with 24%. They might decide to take it private, since there's little point in it being AIM listed with such a small free float, in terrible market conditions. so I'd say delisting risk could be high.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

65 comments
I know we don't normally cover small O&G exploration companies, but was wondering why Orcadian Energy (LON:ORCA) jumped up by 52% today.
52% isn't a lot when you are down 98% but it would be good to know. I only keep the stock in my PF as a reminder to never invest in small explorers.......again!!!!
Best Of The Best (LON:BOTB) Looks a done deal, Slater have sold their 8%.
Don't know if other have seen this but if you want a laugh at the expense of RBG Holdings (LON:RBGP) this is funny. Who would employ these absolute clowns to represent them.
https://www.rollonfriday.com/n...
Hi Wolf,
Great link, that was very amusing. Also, one of the click-through links is an even funnier (shorter) article - https://www.rollonfriday.com/f...
Have a lovely weekend!
Regards, Paul.
The housebuilders look cheap. I think Crest Nicholson Holdings (LON:CRST) are trading at 0.57 of their tangible assets and don't have net debt. Unless house prices fall dramatically, which I can't see happening due to the demand for housing - this must be a bargain. I can see rates peaking at 6% at the end of this year and perhaps we will see price declines of circa 10% overall? I realise that they are at the high end of the market and in the South East, so perhaps they might be impacted more by a recession? Anyone else have an opinion on the housing market?
Hi bsharman,
Not so much a thought on the housing market but I too feel in the long term the housebuilders are worth a go at current levels. I have been pound cost averaging in and will just sit back and enjoy the decent dividends waiting for the cycle to turn again in their favour. Richard
Housebuilders. I agree . All housebuilders are good value looking in 2-3 years time. A new element is the entry of the big boys into the rental market. Legal and General and Lloyds are acquiring a large parcel of housing stacks for rental. This is positive for the market. The housing market relative to earning is still high and I expect it to adjust (if inflation is 10% and average house growth is 0%) , it means 10% drop without anyone noticing it!
I am picking up gradually regardless the price going up or down. I expect there will be a headline news in the next few months saying: transactions are down, mortgage approvals are down, and average price down will follow. that is when I buy more!
Springfield Properties (LON:SPR) also looking spicy at the current levels!
Any chance you can give a view on the delayed Concurrent Tech results Paul. Good company (IMO) experiencing difficult conditions largely as a result of the challenges of sourcing following Covid, War etc. But they do offer some visibility in their results as they quote order intake which is up at £31.5m (£25.2m, 2021). I know 2021 is rather bemusing but reflects the delay in getting these results out. New CFO has clearly gone into the numbers with some vigour, not incorrectly when the net result is to reduce basic EPS from 3.84p to 1.35p!! Over capitalising development costs seems to be the issue (or at least as given by the Company). A stock on a high multiple (over 20 times a few weeks back) is obviously going to get pummelled with these results but my gut says they are coming into interest area. If anyone else has an interest in this stock would love to hear from you. I have been a holder but sold out a while back for transparency sake.
Hi Camtab,
I looked at Concurrent Technologies (LON:CNC) in a fair bit of detail just 11 days ago here.
So I wasn't planning on revisiting it today, given that it doesn't seem like much has changed, and the share price has barely moved.
I've got a couple of hours left, so wanted to look at James Latham (LON:LTHM) as a higher priority.
Sorry about that, but you've already covered the main points in your post!
Regards, Paul.
Fair do's!! Apologies I missed your recent update I will take a look. If anyone else has my interest Cenkos on Research Tree have issued a good paper today (but note it is non independent under FSA COBS).
Thanks Paul, Very much looking forward to your thoughts on James Latham. Richard
My preference is for Galliford Try Holdings (LON:GFRD) over Costain (LON:COST) . This is a discussion that I have had with Boon, whom I have a lot of time for. I believe that he holds Costain (LON:COST) .
Both are low margin construction businesses, but the former has new management under CEO, Bill Hocking who has done a commendable job to-date in terms of risk management and only tendering for work where the risk/reward is favourable. It has no debt or pension concerns and has recently been awarded £26m in settlement of a long standing litigation case, part of which is to be used to pay a 12p special dividend. Excluding the special dividend the current yield is around 4.5%.
It has two main divisions, construction where the work is focussed mainly on public sector infrastructure, schools, prisons, roads etc and water infrastructure where it has expertise in maintenance, design and build etc. The latter really piqued my interest given the public outcry over sewage contamination of water courses etc. From memory the split is 60;40 or thereabouts.
It also has some nascent activity in build to rent and commercial building refit to meet the new energy standards.
Galliford Try Holdings (LON:GFRD) has cash close to its market cap, but this is somewhat illusory as most is client's money paid in advance, still one presumes it can earn interest on what is a significant sum. It trades on a much higher PE than Costain (LON:COST, however it appears to me that the reasons for doing so are self evident. Finally Richard Staveley, manager of Rockwood Strategic (LON:RKW) has a significant holding as I believe does Gervais Williams at Premier Miton (LON:PMI) No one gets it right all the time, but it is I would suggest an endorsement of the investment case.
I hold and have added recently on the 'sewage' debacle.
The AIM index and why I'm 30% down. A bit of a quandary here, it won't go up until people invest and there's no point in investing until it 's reached the bottom.
How do you know when its reached the bottom?
Ah, that's easy. Each time the index hits a new low it's reached the bottom....
Mortgage applications steady despite rate rises, says Nationwide
https://www.bbc.co.uk/news/bus...
Amused by Mr Contrarian's "beautifully varnished finger".
RNS justifies the Options awarded earlier this week by Revolution Beauty (LON:REVB) that were deemed dreadful behaviour by Graham here on Wed.
I would be very careful if you are thinking about an investment in Costain. They are cheap for a reason. They have shown some remarkable ineptitude and I understand National Highways have taken £1bn to £2bn of funding away from them in the last year. Yes they could turn it around but they need to sharpen up significantly. I would prefer CRH who have (had) 4 cement making sites in Ukraine and are a much better run business.
I work within the Construction industry, and other than when I have been given share options as part of Employer schemes, I do not invest in it. I currently hold nothing!
Cashflow is Queen and King, and several companies do pay what appear good dividends and there is the ability to buy the trend and make money, but when you look at Carrillion, or ROK, a lot of what was very obvious signs later on. Balfour Beatty (LON:BBY) was hit massively a few years back within issues in the UK business and the CEO fell on his sword, the company survived.
The thing to ask right now is how many contracts were bid when, and what if any of the have inflationary clauses, especially within the big value contracts that are currently on site. Typically if they have an inflationary clause they only have once a year triggers (anniversary) to incorporate, and linked to CPI, not construction products and labour costs, so when typically on a low single figure margin overall what has been the impact or what is the impact.
With Costain (LON:COST) either go through the RNS's or use your search engine of choice and put in National Highways/Costain. This is one part of the Costain business and stated as a lower margin, but as an investor I would be asking what is the read across is this isolated or a wider.
Good Luck
Tommy!
Thanks for this heads up Camtab! I didn't know about the National Highways overall picture (presume the A66 was part of that) so will do a bit more digging.
I think the investment case rests for Costain (LON:COST) on whether they can successfully grow their "consulting" side of the business, rather than just the "build" side. And insert themselves as the people to manage umbrella contracts for complex delivery programmes (I'm sure that's not the technical industry term, but hopefully conveys what I'm trying to mean!)
If they manage to move the revenue mix shift and margins grow, then that 4-5x PE will be slow.
On the pension contribution and dividend announcement today... I don't think the matching criteria is too much of an issue, for now. At 11p EPS and say a conservative 3x div cover is targeted in this case (some to reserves, some to pension contributions) then that's still a 3.67p dividend, yielding c7.5% to 8.0%. More than adequate for value / dividend investors.
(I hold in the Boon Fund)
Yes but , 3.67p dividend means they have to match that in pension contributions.
I do not expect that high dividend. Perhaps 2p maximum.
Hence why I say that the minimum div cover ratio that is probably possible at Costain (LON:COST) is 3x div cover (to account for paying out 1x to the pension).
And even at 3x cover, its likely to still be able to pay 3.67p dividend, a 7.5% to 8% yield.
Surely they haven’t made an announcement that they have arranged to pay less pension contributions and then pay a dividend that will have to pay more contributions on what they have agreed.
Other than that , a very very good value share that should have been trading at a higher price but with minimal growth potentials.
Hi Cantab
I totally agree with you re Costain. I spoke to owner of major contractor recently and he told me some disturbing information. He was not aware I was a shareholder but I immediately sold my holding, at a loss.
This is not investment advise just sharing information I received privately He said that since the collapse of Corillion that banks are extremely cautious about contractors.
This man's company does not have any buisness dealings with Costain.
DYOR
TOM
Trackwise Designs (LON:TWD) Amazing what's happened here, it looked to have real potential a few years ago. Total wipe out.
"The Company's cash runway is expected to extend at least into July 2023" is one of the more ridiculous statements this week.
On another subject, inflation data from EU today-
"...data indicated that inflationary pressures in the Euro Area had cooled down in June. The latest CPI report revealed that headline inflation eased more than anticipated, reaching 5.5%, the lowest level since January 2022. However, the core rate remained persistently high. Among the largest economies in the Eurozone, inflation slowed in France, Italy, and Spain, but accelerated in Germany. These figures align with the expectation that the ECB is likely to continue raising rates in the coming months. In other economic news, German unemployment rose more than expected in June. Elsewhere, weak data on China's factory activity has sparked hopes for increased policy stimulus in the world's second-largest economy."
Yes very sad. I am fairly sure the trouble started when the founder, Johnson, didn't raise enough cash in the first placing to fund the new factory. Reason I think that he was reluctant for his own holding to be diluted too much. A real shame because now I doubt if he's going to have much left even if the company does survive.
Someone's going to make a killing picking this tech up for peanuts I think.
As well as being half years Eve today is also the last day of the Holy month of Pride. Last chance to get out there and enjoy the flags.
No greater sacrifice for any company than putting a multicoloured background over their normal logo. Well done all.
Dear Mr Wolf, you need your own column. Please can I ask the floor to second the motion?
Very kind of you to say TEIN. Not many takers tho, so my "Trade like an idiot" column will have to wait for another day
i must say, it does grate seeing companies 'change' their logos for a week or a month - it's completely performative behaviour!
instead, refusing to conduct business in countries or states that are e.g anti-LGBT+ would be an actual stance but ofc we know that won't happen!
anyway, politics rant over - back to the usual daily reading of reports and financial statements ;-)
Being a cynic, is this not a useful way to increase your order book by approx. 100m / 50m for Barratt Developments (LON:BDEV) / MJ GLEESON (LON:GLE) respectively.
It is telling that BDEV stated the asset (cost) value & not the sale value & being pedantic, if 195 are still in due diligence, then they sold 409 homes!! But you know, need to show the order book not falling of a cliff!
I hold MJ GLEESON (LON:GLE) so I shall not criticise!
I missed it, but still not sure.
Barratt Developments (LON:BDEV) say 168m sale on 100m cost - that is well above their existing gross margin of 20-25%.
If bulk sales are higher margin, may well be game changer
Where do private housebuilders stop being so and become contractors for social housing?
MJ GLEESON (LON:GLE) sell at the value end of the new homes market, so when they sell property in bulk to social/ private landlords then unless they replenish supply they simultaneously reduce the number of (more) affordable homes for private buyers. I know this is an over/ very simplistic observation and bordering on political/ social observation (so in danger of breaking one of my rules here), and accepting the builders will do what they must if demand from private buyers is suppressed (I noticed recently Gleeson have a lot of deals on individual properties/ sites).
It occurs to me that Gleeson and Barratt Developments (LON:BDEV) will have been selective on which properties, available now and later, to make available to this sort of sale, and so will have covered their own backs at what seem like reasonable retail prices per property. Every shopkeeper likes a big order, you can't blame them for that, and as mentioned by others there will be economies of scale on the deal anyway.
[I hold MJ Gleeson]
Angle (LON:AGL) I never owned this, but could anybody who does please tell me why after FDA it tanked. Trying to work out if Renalytix (LON:RENX) could do the same. Appears unlikely given the state of the chart, but who knows in this market?
Hi Funnymoney
I think that the simple answer may be found in the adage that a great idea is not the same as a great business and the smart money probably bought the rumour and sold the news the moment the FDA announcement caused a surge of excitement.
The reality is that Angle (LON:AGL) has been a jam tomorrow, cash burn for years and converting the opportunity will be expensive and difficult with no certainty of any benefits accruing to shareholders, especially those who got in early and then got regularly diluted along the way. The moment there is any sign of a profitable future, the opportunity might be snatched away by an opportunistic takeover bid.
When I began investing, it was always in these types of story stocks with some great potential future that might solve fundamental problems (and I sincerely wish Angle (LON:AGL) the very best because their technology looks fantastic with a genuine potential to improve lives (I speak as somebody who would have benefited from their technology had it been widely available).
But as my investing knowledge has grown, especially since discovering Stockopedia, I have realised that it's usually complete folly to invest / gamble on lottery ticket shares. In fact when I first started my Stocko subscription, I reviewed my portfolio through its lens and sold out of all of the junk stocks I held. Angle (LON:AGL) was amongst them - at that time (December 2016) it had a Stock Rank of 4 and was classified as a Sucker Stock. Its share price is currently a third of what it was even at that point in time (and that's the nominal price, not allowing for dilution - the share count in December 2016 was around 60 million and today it's more like 260 million!)
Since then I have utilised the Stock Ranks to steer me away from any of the "losing styles" and the results have been game changing for me (138% time-weighted return versus 2% for the FTSE all share over the same period).
Angle (LON:AGL) is a really wonderful example of the pitfalls that await many small private investors at the start of their investing journeys and it amply illustrates our human bias towards narrative, the dilution risks of investing in early stage companies and the risks of competing against the smart money.
Around the same time that I started my Stockopedia subscription, I became aware of a company also in the healthcare space - Bioventix (LON:BVXP) which also had a good story but was already profitable, had a Stock Rank of 90 and lots of other great metrics clearly visible through the lens of Stocko (Quality rank of 97 at that time) and it was one of the first things I put into my portfolio in place of the junk that I had thrown out. The share price has tripled since then and it's a great illustration of the power of Stockopedia.
Renalytix (LON:RENX) currently has a Stock Rank of 7 and is classified as a Sucker Stock so the best interpretation of that is to say that on average, it has a higher chance of losing you money in the long run than something with a decent ranking.
Thanks for that and completely agree . Renalytix (LON:RENX) is a micro-position for me. Currently in the money. Although management have been promising FDA for years (which was a major negative), they have been quite good at getting the insurance company side of things sorted out while they have been waiting. For better or worse, it is a Chris Mills/Harwood stock who took part in the fund raising at 90p in Jan/Feb 2023. It also is AI based which I thought might help it catch a bid in the present market.
Like you, 95% of my stocks have good rankings. I tend to focus on low price/sales plus high relative strength or in a bull market very high eps/fcst eps and high relative strength. I don't have the staying power to hold on to value stocks which are not in an uptrend.
John
I too use Stockranks for most of my investing (having read What Works on Wall Street and used Company Refs) but still decided AGL was worth a punt. Maybe in a couple of years it will hit SR99 and be a High Flyer and you can join the party 8-)
I don't follow either particularly closely (I have a small holding in Renalytix (LON:RENX) ) but the perception in the market is Angle management are very poor and completely deluded about the quality of their product. This sector is also completely out of favour as institutions are very reluctant to keep investing into fund raises since the world changed (interest rates went up). For what its worth I'm going to run my small position in RENX but they will need cash very soon. But I've decided to ignore this as the opportunity is so huge and all it takes is one institution to back the raise. Most UK institutions have sold out but there are still a few that own. I think the cash needed is more likely to come from a US institution. They last raised cash through a private placing with a US institution and I suspect the same thing will happen again... especially as they finally have this FDA approval. We knew it was coming "end of Q2".. why did they leave it to the last day! I've had sleepless nights! So annoying but a relief today as they would have to raise cash without the approval (if it had been delayed).
Feta
“but the perception in the market is Angle management are very poor and completely deluded about the quality of their product.”
I have seen these views expressed on a certain BB and disagree. Getting FDA approval was no mean feat in itself. The board has recently been strengthened by 4 new recruits with considerable medical experience to boost commercial progress. I doubt they would join a company with little prospects.
You only have to read a few of the independent research papers published or look at trial results to see the product works.
I hope you're right on AGL JimMcLad, As you say Commercial progress is key. All eyes on their future revenue forecasts.
Funnymoney
I admit from a pure investment perspective I bought in too soon. Alternatively, I should have sold after FDA for a large profit and bought back in today! Many PIs expected that getting FDA approval would open the floodgates immediately to multiple orders. In the medical arena things don’t happen that quickly (unless rules are bent to produce vaccines quickly).
Market conditions haven’t helped and contributed to the forced selling by 2 IIs – the second being Baillie Gifford who held AGL in a small caps fund they were forced to close recently.
The SP is also being held down by the possibility of a fundraise next year though funds could be obtained from non-dilutive sources.
Regarding the announcement this morning by MJ GLEESON (LON:GLE) , I'm not sure how much of a game changer this is in context. They were guiding to deliver between 1,650 and 1,850 homes in FY2023 at their half year results statement back in February and today's announcement is for the sale of 66 homes in FY2023 with the balance of 222 homes in FY2024. So whilst this gives a little welcome certainty, one imagines the margins are lower (each unit is being sold for £175,000 approx.) and in context, the actual numbers are not hugely significant to their annual build volumes. Further, this may already have been factored in to their guidance back in February - it's not clear if this institutional sale is additional to what they were expecting but in any case the numbers are within the margin of error of their guidance anyway.
On its own not a game changer, but could be if we start to see more of this. Carlyle have billions of AUM so if they (and other institution s) decide to start increasing exposure then could potentially see a lot of money - from an institutional investor point of view residential looks an attractive asset class given strongly rising rents and resilient income streams.
Johnsmith68 makes some good points re MJ GLEESON (LON:GLE). In addition I would like to see the small print of the contract before rushing to buy. Who bears the risk of a fall in house prices? Is the sales value linked to a house price index, for example? What get out clauses may there be? Also, the institutional buyers may be more picky about quality of finish than the average retil house buyer, bringing additional costs to satisfy the contract.
If I held (which I did previously) I would get more comfort from the in line with expectations statement.
Richard
I'd also add what build standard have they agreed - Built to the latest Part L efficiency standard or to Future Home 2025, both come with complete different materials and labour costs meaning Gleeson's margins will get squeezed. From an investment perspective you'd want the house built to the best possible standard as its a selling point - lower energy bills, greener tech etc.
In relation to the Part L Building regulation change, any house which foundation has been excavated and poured with concrete, then signed off by the NHBC before June 14th will not have to be built to the Part L regulations.
No doubt Gleesons, as have other housebuilders will most likely have already put in the foundation for the majority of these plots to minimise the uplift in cost which is estimated to be upto £4k/plot.
Morning Paul,
Further to your point on MJ GLEESON (LON:GLE) about investments in housing possibly being a catalyst for sparking interest housebuilder shares, did you also see this news this am....
June 30 - Britain's largest housebuilder
Barratt Developments BDEV.L on Friday said it had agreed to
sell 604 homes to Citra Living Properties, a subsidiary of
Lloyds Banking Group LLOY.L for 168.4 million pounds ($212.57
million) in cash.
Interesting times for housebuilders.
Andy2205
I'm 30% down since 21 too, a trouble shared etc.
I see on my computer screen that WANdisco (LON:WAND) is getting a plug because Paul mentioned it. Just in case anyone is thinking of doubling down on this turd that the city are busy polishing for its relisting can I say that after most of my life working in IT I tried to warn that I saw no value in it long before it crashed and burnt. The management worked hard to keep it flying with all sorts of claims that they alone held the key to handling masses of data generated by all sorts of businesses but most of the IT world (think Visa, Amazon, and everybody else on the internet) managed very well without their help. Their only real income was from a limited number of users of an obscure database system called Hadoop who wanted to migrate their data while the system was live to new systems "in the cloud".
Money will be raised, remember there is more money looking for a good investment than good investments looking for money, a new CEO will take over the ship, get paid well till the money runs out and it will die, supposedly a victim of the state of the economy. Don't join the mugs throwing good money after bad.
I see on my computer screen that WANdisco (LON:WAND) is getting a plug because Paul mentioned it.
Getting a plug? Sorry, what does that refer to?
Many of us also thought WAND was a pile of junk - I wrote many consistently bearish articles about it here, over many years. Then in mid-2022 a series of game-changing order bookings trading updates came out, which is what persuaded me it might be genuine. Who could have possibly imagined that the updates & bookings were completely fraudulent? The market cap rose to almost £1bn, and the major shareholder list was a who's who of big name investors, including renowned investor Richard Griffith, it was his largest holding. So it fooled much greater minds & wallets than mine.
At least holders will salvage something. I've heard rumours of the placing price, but don't want to reveal it as it would breach a confidence, not something I do - sources must always be protected.
Sorry Paul, no offence to you intended or implied. The plug I was referring to was the "Securities mentioned " panel on the right hand side of the screen which at the time of writing only showed WAND for all to see. I hope that clears up any misunderstanding.
Oh I see, thanks Samsgrandad! I misunderstood, and thought you were suggesting I was talking up WAND (whereas as you might imagine, my views are best not put down in writing, to avoid turning the air blue!!!)
Thanks for clarifying :-)
Best wishes, Paul.
My morning smallcap tweet: Shitshape and balls-up fashion
Trackwise Designs (LON:TWD) World Chess (LON:CHSS) Renalytix (LON:RENX) Streaks Gaming (LON:STK) Kropz (LON:KRPZ) Loopup (LON:LOOP) Tpximpact Holdings (LON:TPX) Revolution Beauty (LON:REVB) Leeds (LON:LDSG) Seeing Machines (LON:SEE) Induction Healthcare (LON:INHC) Costain (LON:COST) Narf Industries (LON:NARF) ITM Power (LON:ITM) Quantum Blockchain Technologies (LON:QBT)
◄Trackwise Designs (TWD)► guides FY-Dec22 pretax loss £7.74m (£1.98m). It will miss end June accounts deadline so will be suspended on July 3. Blames "intense demands upon the entire management team in dealing both with the impact of the EV OEM dispute and working to secure new business". Cash is expected to extend at least into July. But that's next week! Expects to know if it gets supplier nomination for OEM B in the very immediate future and will then make decision on raising funds. [SP=NA Cap=NA]
◄World Chess (CHSS)► €1.2m+ sponsorship by ITcom Domains. It will become the official sponsor of Armageddon, replacing the previous sponsor The Four Horsemen. [SP=8.15 Cap=64m]
◄Renalytix (RENX)► FDA approves KidneyIntelX.dkd prognostic test to guide care management for adults with type 2 diabetes and early-stage chronic (diabetic) kidney disease. [SP=76.8 Cap=98m]
◄Streaks Gaming (STK)► launches its second flagship product called "Streaks Social". It will "allow influencers to better connect and monetize (sic) their existing fans through the automatic creation of an AI Avatar". [SP=2.57 Cap=10m]
◄Kropz (KRPZ)► will miss end June accounts deadline so will be suspended on July 3. Trading - sold 33k tonnes of phosphate concentrate in June. [SP=3.48 Cap=32m]
◄LoopUp (LOOP)► gets FY-Dec accounts out. Extra £13.5m goodwill impairment compared to prelims. Bank facilities extended by a yeatr to Sep 24. [SP=2.08 Cap=4m]
◄TPXimpact (TPX)► agrees reset of the covenant terms applicable to its £30m revolving credit facility with HSBC; "provides renewed stability". [SP=37.5 Cap=35m]
◄Revolution Beauty (REVB)► gives boohoo the beautifully varnished finger again. [SP=27.5 Cap=85m]
◄Leeds Group (LDSG)► discovers that stock at subsidiary (Hemmers-Itex Textil Import Export) at 31 May was overvalued by £408k. Blames a programming error. [SP=11 Cap=3m]
◄Seeing Machines (SEE)► CEO gets 10m options and vesting of another 15m extended to 2026. Bemoans share price. [SP=5.45 Cap=226m]
◄Induction Healthcare (INHC)► trading - sounds in line. Sells Switch, a directory app, for an undisclosed sum. Internal promotions to CEO and CFO. [SP=22.59 Cap=20m]
◄Costain (COST)► new contribution plan to pension scheme cuts payments to £3.3m PA from £12m. [SP=45.3 Cap=125m]
◄Narf Industries (NARF)► expects audit and unsuspension no later than 14 July. [SP=0.8 Cap=15m]
◄ITM Power (ITM)► MEP30 electrolyser stack gets UKCA accreditation (UK version of CE mark). [SP=73.02 Cap=453m]
◄Quantum Blockchain Technologies (QBT)► last-minute FY accounts out, avoiding suspension. [SP=1.63 Cap=17m]
Varnished finger LOL
Positive results from Record (LON:REC) this morning, the specialist currency and asset manager. I'd be interested in any comments on this one. Neil Record steps down from the Board today, but seems to have transitioned the management team well. Diversification of revenue streams seems to be working well with strong revenue growth and AUM of US$88bn (up 6%) in choppy markets. I hold.
Record (LON:REC) Nice to see a special dividend too.
This is reassuring
Record is not immune from these challenges, but structurally we are positioned to be nimble and adaptable to client demand as it develops and changes. While cost pressures (particularly labour costs) will undoubtedly impact the business, the current pace of growth and change should allow the revenue to grow sufficiently to more than compensate for the cost-base growth.
Less sure about this!
The next phase of our development of Record is to reap some of the rewards of our modernisation and diversification. The soil has been fertilised over the last few years, and the new plants well heeled in. For quite some time they have been putting down roots and like any young tree more has been going on under the surface than on the top.
Oh dear. Who thought this was a good idea?
The next phase of our development of Record is to reap some of the rewards of our modernisation and diversification. The soil has been fertilised over the last few years, and the new plants well heeled in. For quite some time they have been putting down roots and like any young tree more has been going on under the surface than on the top.
I see that Record (LON:REC) have also released their PDF annual report today. Good! Why can't all companies do the same? Speaking as an ex-auditor, there is really no excuse for releasing 2 or 3 weeks later as many companies do. The annual results announcement is audited...the document should be ready!
Paul,
Thanks so much for a wonderful and engaging first half-year of commentary. Your comment "Also, I'm still about 30% down from my all-time-high in mid to late 2021" is so reassuring, if disappointing for you, as it mirrors my own performance. As said by others before, private investor investing tends to be a solitary activity, so hearing about the downside performance of others provides support that, perhaps, we are not an outlier.
Thanks for your half year comments Paul - very helpful for me. I too am about 30% down from the high so it will be difficult to get back there.
Trading update included withing the MJ GLEESON (LON:GLE) RNS this morning. RNS outlines the sale of a portfolio of home but also states:
The Company will issue its next scheduled trading update, in respect of the year ending 30 June 2023, on 7 July 2023 and expects to confirm that it will deliver results for FY2023 in line with expectations.
Brilliant, thanks for flagging this Ben Hazzard!
It's a really interesting announcement from MJ GLEESON (LON:GLE), and bullish I think for its shares (which were too cheap already in my view). So I've rushed out a quick comment on it above.
Best wishes, Paul.
News from Barratt this morning also.
Barratt Developments PLC ("Barratt") today announces the agreed future sale of
604 ((1)) homes to Citra Living Properties (No. 1) Limited ("Citra"), a wholly
owned subsidiary of Lloyds Banking Group plc ("Lloyds") for total cash
consideration of £168.4m ((1) (2)).
Well done Paul - lovely to have your analysis vindicated in this way.