Small Cap Value Report (Fri 31 May 2024) - JD., DPP. Brief: CMO, AFRN.

Good morning from Paul!
I'll leave it there for today, and the week.
Didn't buy Warpaint? - really insightful article here from Ed, delving into a new study on momentum. Very topical as we enter a new bull market. I've also always had problems buying shares in an up-trend, and where valuation looks stretched. I've missed loads of good investments in this way, sitting on the sidelines complaining about a stretched valuation whilst it gradually multibags! So there's a lot I need to learn about just paying up for the best companies, and not letting the value investor in me block that path. Although there's also the point that this strategy could result in over-paying for stretched shares, right at the top.
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Companies Reporting
Summaries
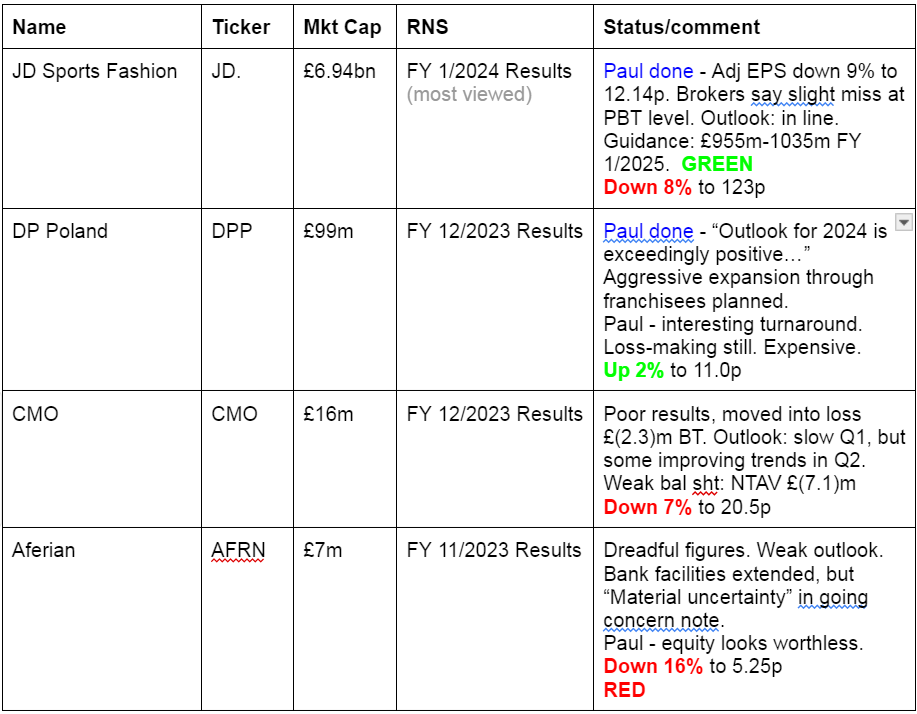
JD Sports Fashion (LON:JD.) - down 11% to 118p (at 08:47) £6.18bn - FY 1/2024 Results - Paul - GREEN
A slight miss at PBT level. Outlook is unchanged for FY 1/2025. I don't understand why the market has dropped this 11% today. Looks a quality company to me, which has self-funded terrific growth in the last 6 years, despite the pandemic & tough macro. Seems too cheap on a PER c.10x.
DP Poland (LON:DPP) - up 2% to 11.0p (£101m) - FY 12/2023 Results - Paul - AMBER
Some exciting bull points here in an interesting turnaround, but the valuation seems way too high to me.
Paul’s Section:
JD Sports Fashion (LON:JD.)
Down 11% to 118p (at 08:47) £6.18bn - FY 1/2024 Results - Paul - GREEN
JD Sports Fashion Plc (the 'Group'), the leading global retailer of sports, fashion and outdoor brands, today announces its full year unaudited results for the 53 weeks ended 3 February 2024.
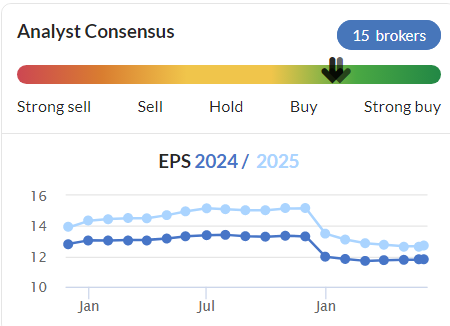
My initial skim of the results & outlook led me to believe the figures and outlook were in line. So why have the shares dropped 11% this morning? To start with, I’ve got conflicting information on whether the FY 1/2024 results are slightly ahead of expectations (12.14p adj EPS actual, vs 11.8p consensus shown on the StockReport, suggesting a 3% beat), or below expectations (as a couple of brokers suggest)?
In a morning summary note, Winterfloods says the figures are a small miss at PBT level, and notes a small cut in the dividend. Full year divis are actually up from 0.8p LY, to 0.9p this year, but I note the split has changed, so that the final divi was 0.67p LY, and is 0.6p this year. Divis are not material here anyway, as the yield is under 1%, since cashflows are mainly being applied to organic (new stores) and acquisitive growth.
Another broker says PBT at £917m was slightly below expectations of £923m, so overall it looks like a slight miss at PBT level, but nothing to get steamed up about. The -11% share price move this morning seems an over-reaction, but is really only giving up the gains in the 3 days prior to this results release. Maybe traders bought in anticipation of stronger numbers & outlook, and exited this morning? Who knows!
In any case I am encouraged when companies I like become cheaper, providing nothing significant has gone wrong, which it hasn’t here.
JD is a big business these days, and international. Some key numbers for FY 1/2024 -
Revenue £10,542m
Adj PBT £917m (down 8%)
Adj EPS 12.14p (down 9%)
LFL store revenue growth of 3.8% is below peak inflation, but similar to where inflation is now running.
Wages costs in particular are flagged - with £70m extra, in addition to minimum/living wage increases. Total operating costs rose 5.1%, a bit ahead of LFL store revenue growth, so margins have been pinched slightly, but are still good I think.
Overall, I see those figures as respectable, given that we’ve been in a tough consumer macro environment, with cost pressures too.
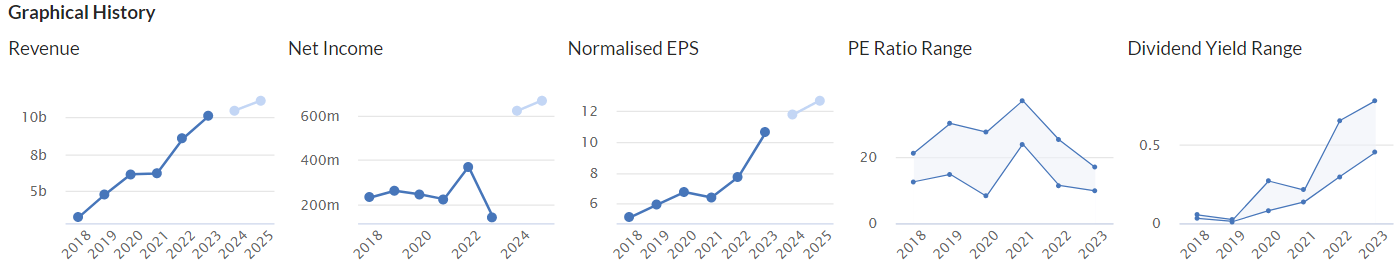
Note that JD issued a profit warning, which I covered here on 4/1/2024, which took it down 23% on the day to 119p, causing me to highlight that it looked good value. Things didn’t get any worse, with an in line update on 28/3/2024, hence I remained GREEN here, due to the value, and the good long-term track record of rising profits & EPS. Although note the shares have gone nowhere in the last 5 years, since it’s seen a PER de-rating at the same time as rising EPS, which is unusual. EPS has doubled in the last 5 years, but shares have gone nowhere. Could that be an opportunity, or is the market now telling us it’s a mature business, struggling to generate organic profit growth from existing stores? Could the new stores, and multiple acquisitions of other companies be concealing a deteriorating underlying business maybe? That could be what sceptics think possibly?
Outlook - sounds fine to me in the circumstances -
"We have started the new financial year with Q1 in line with our expectations in a volatile market and we are on track to deliver our profit guidance for the full year. Looking further ahead, we have a strong business model and a clear strategy to deliver long-term growth and value creation for our shareholders."
…and maintaining full year profit before tax and adjusting items guidance of £955m-£1,035m. This includes a c.£55m annual increase, announced at our March update, from the accounting policy change to include amortisation of acquired intangibles as an adjusting item from FY25 onwards.
Balance sheet - has £1,032m net cash (excl lease liabilities).
NAV is £2,868m, less intangible assets of £1,429m, giving NTAV of £1,439m, or about 23% of the market cap. So some asset support here, but it’s mainly an earnings & cashflow company, as is usual in this sector.
There's only been modest dilution in the last 6 years, from 4,866m shares to 5,183m, so JD got through the pandemic, and expanded the business 3-fold in revenue, and more than doubled EPS over this period, almost all self-funded from its own cashflows. That is very impressive you know.
As flagged here before, the only unusual large item on the balance sheet is £810m non-current liabilities called “Put and call option liabilities”. That’s a big number, and seems to relate to acquisitions, buying out minority interests. There’s more detail in note 6, I don’t want to get bogged down in it though. My inkling is that this £810m balance sheet liability sounds like deferred consideration, so I’d net it off against cash, bringing the group to a net cash position of £222m, which is fine.
Acquisition - a large acquisition is in progress (announced 23/4/2024) of Hibbett Inc (NASDAQ listed), for £878m, subject to regulatory and shareholder approval. Expected to complete in H2 of (calendar presumably) 2024. So that could give a catalyst for increased forecasts if it goes through. They’re taking on debt to part-fund it though. My initial worry is that a low-PER UK share buying something on NASDAQ (presumably expensive) could destroy shareholder value. However, a quick look at Hibbett’s StockReport (via my US Stockopedia subscription) shows it is actually modestly valued at a similar PER to JD (even with the bid premium included), and solidly asset-backed too. Just on a quick review, this looks a nice bolt-on deal, with 1,169 stores in 36 US states.
The USA is already JD’s largest market, so will grow further if Hibbett is acquired.
Paul’s opinion - JD is a very ambitious growth company, but it’s priced as a value share, on a forward PER of only about 10x. We don’t have to worry about debt, as the balance sheet looks adequate.
My main reservation is that JD’s business model is to provide trendy showrooms for other companies’ brands. So JD doesn’t have any control over product. What if brands decide to sell direct, and scoop up the retail margin for themselves? I’ve been saying that for years, but it’s still a concern to me. Or maybe JD is too big to be ignored or squeezed by the big brands? I don’t know, what do readers think?
As for the brands, I see Nike (NYQ:NKE) shares have been weak , doing a round trip back down to where they were pre-pandemic, and rated highly still on a PER of 23.7x.
adidas AG (ETR:ADS) in Germany shares have been recovering since Oct 2022, but are still below pre-pandemic share price. That’s on a fwd PER of 48x. So there’s clearly a large valuation gap between the brands (highly valued) and the retailers (lowly valued), which makes sense to me, to some extent. Although maybe the retailers could be too cheap now? If the Hibbett deal happens, I reckon that would add about £1.4bn additional revenues to JD, and £75m post tax earnings. That’s before synergies too, presumably the greater group buying power could squeeze higher margins out of the big brands?
Overall, JD does appeal to me, as a value/GARP share. It’s roughly tripled revenues in the last 6 years, from acquisitions and openings loads of new sites too. PER of 10x does seem oddly cheap. Hence I’m sticking at GREEN. Maybe there are issues I’ve not spotted, so it definitely needs readers to do a much more detailed research process yourselves, as with everything. However, superficially I think it looks well worth a closer look.
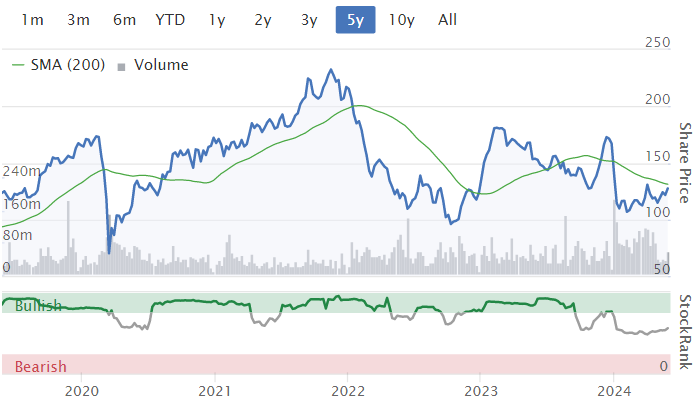
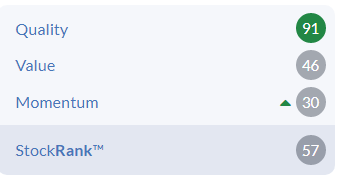
Note the StockRank system has fallen out of love with JD shares, previously highly rated it now only gets a middling score -
DP Poland (LON:DPP)
Up 2% to 11.0p (£101m) - FY 12/2023 Results - Paul - AMBER
DP Poland, the operator of pizza stores and restaurants across Poland and Croatia, announces its audited results for the year ended 31 December 2023.
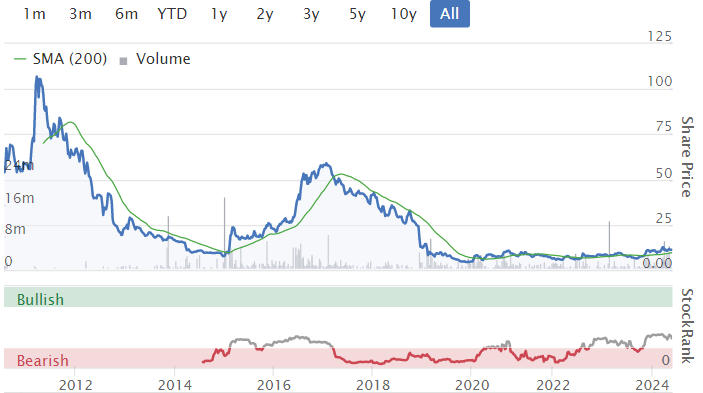
Terrible historical track record of losses every year, multiple fundraises, and shareholder value destruction -
Turnaround - this is the interesting bit. New management seem to have convinced everyone that they’re turning it around, and can create a successful business by switching to a franchising model. This got very credible backing in a Mar 2024 fundraising of c.£20m, enough to resolve its previously weak balance sheet, and fund future expansion. A key positive point is that half the money raised came from the UK Dominos operation, Domino's Pizza (LON:DOM) - this is clearly a superb endorsement of DPP’s turnaround potential.
When the facts change, we change our view, so I was happy to switch from red in 2023, to AMBER on 28/3/2024 when this game-changing fundraise was announced. Graham agreed on 29/4/204 on a trading update showing that it’s approaching profitability.
2023 Results - are poor, and to my mind would only justify a valuation of close to nothing -
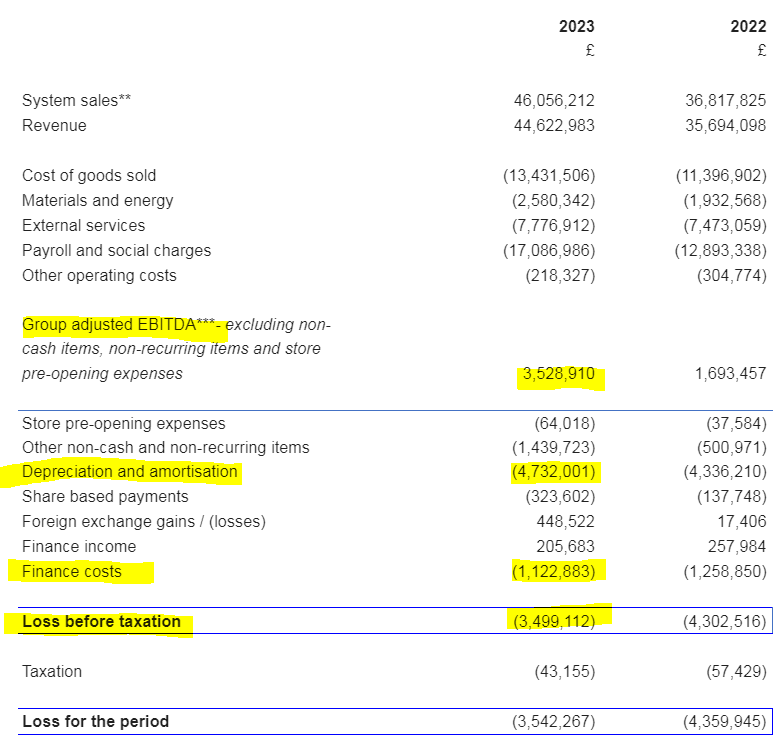
EBITDA is positive, but it’s less than the depreciation charge (although that’s distorted by IFRS 16). If we’re kind, then I would see the above as being c.£(2)m loss before tax, having accepted the £1.44m non-cash & non-recurring items.
Balance sheet - was weak at 31/12/2023 with negative NTAV of £(3.0)m, but that has since been comprehensively repaired with the c.£20m equity fundraise in Mar 2024. So NTAV should now be positive, possibly about £15m, if we allow for some more losses in early 2024. Its finances are sorted now I think, so I don’t have any remaining balance sheet concerns.
Outlook - this is what almost all of the market cap relies on. At £101m market cap, and with no historical profits at all, DPP absolutely has to move into significant profits, and demonstrate the ability to strongly grow those profits. It’s very unusual for a business in the hospitality sector that has been a long-term serial loss-maker, to suddenly become a terrific, profitable growth company, but it can happen occasionally when economies of scale kick in, and a brand becomes well-liked by customers.
New management are also highly regarded, several sector experts have told me, so that could be a key catalyst, well it already has been, given the mkt cap has soared, and they got a big fundraise away, including £10m from UK Dominos.
Very strong LFL store sales growth so far in 2024, this is very impressive - as it needs to be -
Looking to 2024, our strong growth has continued, with LFL sales up 19.9% year to end of April. Supported by our recent fundraise, we aim to open 45-50 new stores, upgrade 25-30 stores, and transition to a franchise model. I'm excited about our future and our team's potential to continue delivering."
Although note that it mentions high inflation in 2023 of 11.4% (Poland) and 8.4% (Croatia). I’ve checked the latest figures, and these have come right down, to 2.5% in Poland and 3.3% in Croatia (year to April 2024). Therefore the +19.9% LFL sales growth so far in 2024 is almost all genuine, real terms growth. Very good!
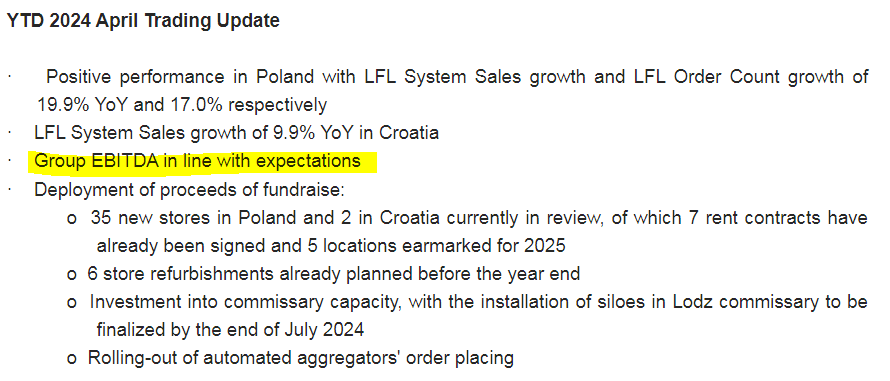
Current trading is in line -
Forecasts - thanks to Singers for an update today, as follows -
FY 12/2024 - adj PBT £0.7m, adj EPS 0.1p
FY 12/2025 - adj PBT £2.9m, adj EPS 0.2p
FY 12/2026 - adj PBT £4.6m, adj EPS 0.4p
Let’s be very generous and put it on 20x forecast 2026 EPS, that would be a share price of 8.0p.
Slight problem here, the share price is already well above that, at 11.0p.
So bulls must be hoping not only that DPP can move into profit, but that it can smash these forecasts.
Paul’s opinion - it’s a turnaround, no arguments there, but from basket case, to something that might reach breakeven shortly. It's difficult to get excited about that.
However, the forecast upside is already more than fully baked into the share price today. So where’s my upside, if I decide to buy at 11p?
Also, the franchise side of things is an aspiration. Franchising only works if there’s a really big profit margin, which can be shared between the brand owner, and the franchisee. Since DPP’s own stores generate very little site level profit at the moment, why would anyone want to set up a franchised store that’s unlikely to make them much (if any) profit after fees? Also, franchise operations can be a handful to manage, as the operators have autonomy, and might start doing things the main company may not like.
Overall then, I like the beginnings of a turnaround, and it should be good if DPP can (after many years) finally deliver a maiden profit (slightly above breakeven). Does that make it a business worth £101m though? Not by a long shot, in my opinion. To me, this share is worth maybe £20-30m market cap. Hence the £101m market cap is way above my perception of value, based on the existing forecasts. So where’s my upside going to come from? Unless it delivers stellar trading updates, there’s a considerable risk here that the shares might slowly drift back down. So at the moment, I think risk:reward seems weak. I’ll stick at AMBER though, as it’s now well-funded, but shares would have to more than halve for me to even consider investing here. Good luck to bulls, I hope the company delivers forecast-busting results!
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

57 comments
Paul, another enjoyable podcast, and forgot to say thanks for highlighting the potential in Surface Transforms (LON:SCE) the previous week, up over 30% in a week will pay for Stocko and ZANE direct debit for the next year, what is not to like.
Just FYI, this weekend's podcast "mystery share" is JD Sports Fashion (LON:JD.)
Many thanks to The Phoenix and Sutters for the updates.
Just goes to show the collective knowledge available on Stockopedia.
Not sure what if anything is going on at ME International (LON:MEGP), probably nothing just the gyrations of a capricious market. It has been on a tear of late along with a few other small caps in the portfolio, Galliford Try Holdings (LON:GFRD) and Bloomsbury Publishing (LON:BMY) for example.
ME International (LON:MEGP) up again today on significant volume. No of significant newsflow, at least not in the public domain. My best guess is that trading is going well and the share price is playing catch up. Still inexpensive on a forward PE of 12.3 falling to 11.3 for FY 25 and respective yields of 4.5% and 4.9%, or thereabouts with a cash rich balance sheet.
Makes a change to see UK small caps make up some ground after a grim 2 years. When rates star to decline, whenever that is, UK small caps as a cohort, will in my view be off to the proverbial races and not before time. In the interim I will continue to collect the dividends from shares such as the above and sit on my hands.
Hi Jonno the Naked Trader announced he had topped up his position in his blog yesterday so might be a few following him in but equally would have expected that effect first thing not end of day. Schroders are big supporters also so they could be topping up maybe all will become clear at some point next week.
ME International (LON:MEGP) is due to give a H1 trading update next week
Thanks, Paul. JD Sports looks really interesting here. I will take a further look. Certainly seems very cheap.
While checking today's mortgage lending figures, I came across this, which helps support the narrative of money returning to the market:
In April, UK non-financial businesses – PNFCs and public corporations – repaid, on net, £1.1bn in loans to banks and building societies.
The net flow of sterling money – known as M4ex – was £10.3bn in April.
This was mainly driven by households’ holdings of money, which increased by £8.4bn, the highest flow since September 2022.
Within the increase in households’ holdings of money, households deposited an additional £11.7bn into ISAs, the highest since records began in April 1999.
The flow of sterling net lending to private sector companies and households (M4Lex) decreased to £1.2bn throughout the month.
This was mainly driven by a decrease in net lending to non-intermediate other financial corporations (NIOFCs) to a flow of -£1.0bn from £9.8bn in March.
https://theintermediary.co.uk/...
JD Sports Fashion (LON:JD.) for anyone interested in the sportswear retail industry in general or the Hibbett acquisition in particular, this is a fun read:
https://open.substack.com/pub/...Re: warpaint and buying at or close to 52wk highs
I find the fee structure in the UK makes it quite difficult to do this based on the potential losses involved due mostly to dealing fees - they just make momentum investing much more risky. I moved to the US a few years ago and dealing fees practically don’t exist here because about 5/6 years ago the brokers decided they were going to make most of their money off the options traders (presumably to lower entry barriers for retail investors)
For example, in the UK if I want to invest £1k in something, on the purchase I have to factor in the spread (0.5-1% for argument’s sake), the dealing fee £10-12 and the stamp (0.5%). So I’m already up to 2.7% in the red before I’ve got going.
Then let’s add in some risk management, so a 15% cushion in the form of a stop loss just in case I’ve got it wrong.
And then when I sell, another £10-12 to my broker/dealer.
So in total, what could be a 15% loss from a risk mgmt perspective ends up more like closer to a 19% loss after fees, tax and spread.
Make a few moves like that which go against you (and then in true Sod’s Law fashion make another push up after bottoming out just under your stop loss) and those losses start to mount up.
By contrast, in the US, my costs are the spread and what I’m willing to lose before I sell. If I get it wrong I’ve only lost what I was willing to accept losing. If I get it right, but have just timed it wrong I can buy back in at no cost (all I lose is my option to deduct losses from my income at year end if I buy back within 30days of taking the loss). The whole system is FAR more forgiving and provides much more room for error and it makes momentum investing WAY easier
So for those UK investors who find it hard to buy good companies close to the top, I do sympathise - our dealing costs suck
TL;DR - UK broker/dealer fee structures are a massive pain and make momentum investing a much harder prospect than in the fee-free environment of the US. I’ve got a lot of sympathy for UK investors who find it hard to buy near the (current) top
I agree with you, but Trading 212 has solved this problem in the UK really. Zero dealing fees and make most of their money off of the CFD arm. In my opnion, they'll soon be the largest investment platform in the UK if other platforms do not cut their fees.
Wish they did ISAs
They do?
They have offered a stocks and shares ISA for years now.
I agree on Trading 212, the only downside is the lack of coverage. You can't trade a lot of small caps and the ones you can the spreads are hard to stomach. But for your average trader who wants to buy mag7 and the companies they are familiar with it does a fine job.
I am sure there are examples missing, but I have always been able to find every stock discussed here on Trading 212. And the spread is just the market spread you'll get on any platform.
Paul, you’re far from the only one who will struggle with buying a share on a high. It’s a big psychology Hurdle to get over. Keep up the hard work.
Ah, JD, a company I sold years ago as I thought I had made enough money. D'oh.
I think two companies are worth mentioning here: JD and Frasers (LON:FRAS), which has a large stake by Mike Ashley. It is (or at least was) Artemis Alpha's largest holding. The fund manager made a good case for it, too. Check out InvestorMeetCompany if you're interested on hearing the manager's thoughts.
Both companies form a duopoly in sportswear. Frasers has large economies of scale and has plenty of room for expansion in Europe and luxury brands seems to the be gist of the argument. Both companies have a good track record, they're cheap, and look like they have expansion potential ahead of them.
I chose FRAS for my ISA model portfolio shortly before ISA season. Up 12% so far over a couple of months, so looking good so far. Alas, I don't have any shares in my real portfolio. It's tough making a decision sometimes.
JD Sports Fashion (LON:JD.) Nike (NYQ:NKE) Foot Locker (NYQ:FL) (FL still has circa 70% of shoe sales being Nike i think - trying to diversify there).
Nike having cut wholesale supply to many retailers in favor of a direct to consumer approach has had to backtrack and come back to the retail stores as customers didn't switch as they wanted and the company was left with a bunch of inventory.I found this tidbit too post Nike management strategy volte-face'Apparel retailer Hibbett, on the other hand, has even expanded its relationship with Nike by launching a joint loyalty program in late October.'Seems consumers like to still shop athletic shoes in store and with a well known retail brand too.
yes I'd just assume when it comes to shoes / trainers customers want to try them on and walk around to see how they fit, feel and look, but maybe I'm wrong having never bought any clothing / footwear online ever. I hold JD Sports Fashion (LON:JD.) so very much appreciate your write up Paul, another point that may be holding the SP back is Peter Cowgill stepping down as CEO in 2022 ? having turned the business round since 2004
Sharon Daly, Non-exec Director at Warpaint London (LON:W7L) must have read Ed's article - she just purchased 4,080 ordinary shares at a price of 490p per share.
Hi Paul, can I ask if the morning broker summary you get is something available to us plankton?
Hi WoSS,
Hi Paul, can I ask if the morning broker summary you get is something available to us plankton?
Plankton - love it, I might have to borrow that for future reports here!
The answer is sadly not, as I only get a broker summary report as a favour from a mate in the City, on the strict understanding it's not forwarded anywhere (got to protect sources). And to be honest, we're so swamped with info from the RNS, I don't generally have much time to look at it.
Regards, Paul.
Thanks Paul. No problem, back into the sea I go.
Watch out for the whales
Watches of Switzerland (LON:WOSG) , currently 407.80p
I've been tempted by the possibility of high rewards for shareholders if the company’s turnaround strategy is successful. However, Graham recently noted potential risk factors on 16 May 2024:
Retailing risk: exposed to consumer sentiment generally, with the ongoing cost of expensive leasehold properties.
Watch market risk: the value of luxury watches has been extraordinarily volatile in recent years, as we’ve discussed previously.
Financial risk: WOSG has borrowed to fund its recent US-based acquisition.
But Graham was inclined to believe that these risk factors are priced in. Chart signal suggest an upside move towards 500p, although fair values according to my broker site is over 730p.
I have taken a position today.
Watches of Switzerland (LON:WOSG)
Swiss Watch Exports Post Surprise Jump After US Revival
Monthly Swiss watch exports posted a surprise gain in April as a revival in demand for premium and luxury timepieces in the US and Japan offset continued weakness from China.
Shipments rose 4.5% by value to 2.1 billion Swiss francs ($2.3 billion) in April from a year earlier, the Federation of the Swiss Watch Industry said Thursday. The increase follows a sharp drop the month before. They were helped by an 11.6% jump in exports to the US, the biggest market for Swiss watches, which reversed a fall suffered in March.
April Swiss Watch Exports
US 11.6%
China -7.5
HongKong 0.2
Japan 13.6
Singapore12.5
UK 4.6
https://archive.ph/mEQQt
As a holder of Watches of Switzerland (LON:WOSG) , with my largest unrealised loss, I am staying on the sidelines until mortgage rates fall and house prices rise, making funding available for premium watches and jewellery.
Like JD Sports Fashion (LON:JD.) they are focussed on growth through acquisition and stores.
A move to start paying dividends would bring a larger pool of investors to this company but I don't see that happening any time soon.
Talking about Warpaint London (LON:W7L) and their multibagging turnaround in the last few years.On the other side of the pond mind, but astonishinging for a tired, oversexualised, scandalised old brand, Abercrombie & Fitch Co (NYQ:ANF) 's new ceo has totally turned around their brand and image.The share price keeps reaching new heights, which for a clothing brand has made more than a few people i know sell out, as they obviously assumed the sales growth would slow at some point (which admittedly it must sometime??).One after a nice ride up to only $60 and a a few even attempt to short the share at this level.Nevermind NVIDIA (NSQ:NVDA) multibagging, preppy clothes must have even beat the top notch AI chips performance.
I used to buy ANF clothing at uni until the quality started slipping because (I suspect) they were trying to improve margins.
However, my wife started buying their stuff in the last year or so (which for me is an indicator the stock might be worth a look) and I’ll admit they’ve had a resurgence. To your point, the new CEO has really done a job on the place - which is no mean feat because the brand really suffered at the hands of that grossly plastic-surgery’d sexpest they used to have at the helm
I concur with Paul and believe that at the current price JD Sports Fashion (LON:JD.) reflects good value.
The 1st Quarter results are only slightly down on 2023's excellent 1st Quarter and have not been helped by the extreme wet weather.
JD Sports is still in an expansionary phase and is definitely being assisted by the increasing number of Women and Girls participating in Sport, which simply increases their number of customers. Together with the Athletic Leisure trend whereby people wear sports clothes socially and wear trainers more frequently because they are more comfortable than formal shoes I think that JD has some useful tailwinds.
JD should also be helped by the forthcoming European Football Championships and the summer Olympics and I think the share price will make some headway in the remainder of the year.
The main thing that would worry me about £JD is a potential change in youth fashion/tastes, away from very expensive branded sprotsware. Obviously this has been a big trend over the past decade or so and clearly a big driver in JD's success. I haven't looked into this in detail, but my sense is the next generation have realised it's all a bit a rip-off and looking for better value - see the rise in second hand clothing companies. This would also explain some of the weakness in Nike and Adidas. I am certainly no expert on fashion trends, so might be talking rubbish and would be interested to hear others views.
JD
I think it’s going to struggle
The move is to upcycled and recycled
I’m seeing this all the time
We had a young designer call in to use our warehouse for a photoshoot , he takes old knackered garments repairs them , cuts them up , and prints on them .
I heard Route 1 and chain of skate type shops stopped selling new clothing and now are reselling vintage
Think the writing is on the wall for JD and your investing into a falling tide .
And you can’t out swim a falling tide .
So bbig Eurovision style “nil points” for me though may well swing upwards mid term but long term I’ve got them as dead man walking .
That’s the bear case but I’m in bad mood Friday mode .
Which country? Its a big World out there, and JD is a global company based in little old Bury. I spend the majority of my life outside of Europe, and I see a lot of those JD bags everywhere i travel.
I teach in a large secondary school filled with students in the majority from low earning families. One thing I can guarantee is most of these kids wouldn't be seen dead in second hand or upcycled clothes. For contrast, my wife and I have started to get some second hand stuff off vinted and Ebay lately and a lot of our friends do too. One of my main reasons for investing in JD Sports Fashion (LON:JD.) is because I see on a daily basis how important clothes and fashion are to young people, and the trend is still very much sports apparel. I know a lot of the parents of these kids are going to be feeling a slightly better off with minimum wage rises and reducing energy bills and the Olympics and Euros will only drive sales further. I can't speak for the US, but these days more than ever, in the social media driven world we live in, trends tend to ignore geographical barriers, so I'd expect much of the same over the pond.
@I really cant see that happening. Trainers will always be something that people want, whatever age. It's not confined to youth. Key issues for Nike (NYQ:NKE) and adidas AG (ETR:ADS) is which ones are being bought? At the moment in the UK people want Adidas Originals. Give it a year and it will be something else. So as long JD Sports Fashion (LON:JD.) stock what people want I can't see interest in trainers waning to the extent that it severely impacts their business.
(Posted this to the wrong post. it was fin reply to Bouden54's Comment about JD's risks)
Agree there will always be demand for trainers. It's just whether there'll always be such a strong demand for the very expensive branded sportsware that JD specialise in - perhaps there'll be a move to better value options, which would probably be good for Frasers.
Regarding JD Sports Fashion (LON:JD.) being up earlier in week, Dick's Sporting Goods (NYQ:DKS) SP is up 17pc this week, after reporting good quarterly results. Dick's Sporting Goods (NYQ:DKS) has a market cap of $18.5bn, so more than double that of JD Sports Fashion (LON:JD.) . As Paul pointed out, USA is very important to JD and I hoped that Dick's results would be a good read across, sadly not from the press release today.
I'm very new to all this and fascinated. I read the momentum article yesterday and a surprising number of the shares I've bought which also happen to carry high stockrank, high vm rank seem to exhibit those kind of smooth trending curves (by eyeball only I will admit but there were easily discernible trends). The problem is that as Paul Scotts comment above says although there's also the point that this strategy could result in over-paying for stretched shares, right at the top. I've had a couple of those already (I hope they recover). At the moment my wins seems to be outdoing my losses though which is nice. My big loser thus far seems to be Phoenix group (LON:PHNX) which i bought ages ago as a dividend stock and sat on. The dividends have made up the losses but am seriously contemplating taking the hit and running as the money could be more usefully used elsewhere. I'm concerned that if they drop the dividend I'll see further falls.
I made the decision this week to offload some of my income shares based on the view that if this truly is a bull market I can make more from some of the shares that will gain from the current conditions.
I therefore sold out of my long-term Legal & General (LON:LGEN) & M&G (LON:MNG) holdings to start to buy into some of these earlish movers. The capital gain in both of the sellers had been miniscule, but I had appreciated the dividends, but I think we could be in for some good upside over the next few months so felt comfortable and if I want to buy back later I am sure I can.
Good luck in your decision.
Yep did that. I got trapped in Phoenix. I had both M&G (LON:MNG) and Legal & General (LON:LGEN) and offloaded them for the same reasons (at a profit and having had lots of dividends thank goodness). Serabi Gold (LON:SRB) and Metals Exploration (LON:MTL) are currently doing me proud. My portfolios performance is already improving. A very good luck to you sir!
Woah - hold your horses everyone! What you are essentially doing is saying "now is the moment to become momentum/growth investors". That may well be true and I personally agree that the market has an increased risk appetite right now. This looks logical when considering a) the value on offer in UK equities, b) plenty of takeover activity and c) a potential downward trend in interest rates.
However, those dull and boring income stocks are giving you a degree of balance to your portfolios. True, they aren't very exciting but they will offer comfort if and when the market turns. By all means increase exposure to higher risk equities if you think the time is right, but switching the whole lot is a bit like going 'all in' at the casino.
Personally I am tilted towards growth/small cap but I certainly wouldn't bet the entire house on them and especially not mining stocks (or as I like to call them, 'holes in the ground backed by a whim and a prayer!' )
I am in agreement I hold about 40% in the likes of Phonex Holdings (PNK:PXHI) and Legal & General (LON:LGEN) I treat them like bond proxies but they pay a higher yield and I expect minimal capital appreciation.
I'm the same now, lost a fortune in the recent bear market on hope/hype/potential stocks, lost about 70% of my portfolio f in two years...
Come back a bit this year, I'm about 60% in things like Phoenix group (LON:PHNX) easyJet (LON:EZJ) PayPoint (LON:PAY) and a few others/40% in growth businesses now, tough lesson that one.
It does mean it will take a lot longer to build it back up again but safety first!
It’s interesting to note the improvement in share price of a couple of hydrogen related stocks ( ITM Power (LON:ITM) and AFC Energy (LON:AFC) ), where I have small positions, since the announcement of the general election. I base the assumption that the share price rise is attributable to Labours more positive attitude to the green transition than the Conservative position of late. Ceres Power Holdings (LON:CWR) is also showing signs of recovery.
Apart from the obvious house building and related industries, which could benefit from changes in planning rules, I was wondering if there are any other sectors that are likely to benefit from a Labour government.
AFC Energy (LON:AFC) doesn't have a product that works. The CEO has announced the first sale each year for the last 4 years and then the order is subsequently cancelled by the 'customer'. Total bargepole territory.
Coming to the FTSE 250 index, Alpha Group International, Brunner Investment Trust, Liontrust Asset Management and XPS Pensions Group are likely to be added, along with Ocado Group and St. James's Place.
Regarding Liontrust, Coatsworth said, “Liontrust used to be a staple of the FTSE 250, but briefly disappeared after a run of bad luck for the share price, when interest rates started to go up, a big acquisition didn’t work out, and it suffered widespread outflows from various funds.
“The asset manager has enjoyed enough of a recovery in its share price this year to put the stock in line for promotion back into the FTSE 250 index.”
https://www.euronews.com/busin...
That attempt to acquire GAM was a massive misstep and wasted a lot of management time which could’ve been focussed on retaining AuM in a depressed market. I’m still peeved they went so hard on that purchase
Yes I'd spotted that one too - this could potentially mean further to go in the current upward momentum for this share since all the relevant index tracker funds that track the FTSE250 (and/ or the FTSE350) will be forced to buy into Liontrust Asset Management (LON:LIO) once it's in the index again...
Filtronic
Rather generous incentive package for new CEO with circa 5 million shares at strike price of 17p with reasonably easy hurdles .
At least shows he’s a good negotiator as opposed to the remuneration committee .
At least they weren’t zero value ones which is a total wind up .
I’m sure he’s worth it .
Not a great fan of options scheme weighted in favour of the CEO and Directors, the whole workforce needs to be incentivised, its the whole team that deliver results
My morning smallcap tweet: The letter of the flaw
Petrofac (LON:PFC) Revolution Bars (LON:RBG) SEEEN (LON:SEEN) Oxford Cannabinoid Technologies Holdings (LON:OCTP) World Chess (LON:CHSS) Galliford Try Holdings (LON:GFRD)
◄Petrofac (PFC)► FY-Dec accounts out at last. Shares should be unsuspended. The auditors have disclaimed their audit opinion for the financial statements. Everything hinges on a financial restructuring. [SP=10.5 Cap=55m]
◄Revolution Bars (RBG)► formal sale process over, proceeds to its restructure plan. [SP=1.2 Cap=5m]
◄SEEEN (SEEN)► £763k placing & subscription at 3p, an 8% discount, to to accelerate sales etc. Also £315k conditional loan notes. [SP=3.5 Cap=3m]
◄Oxford Cannabinoid Technologies (OCTP)► decides against a Matched Bargain Facility after the cancellation of listing because it's "not practicable in the short term". Tough titties. [SP=0.18 Cap=2m]
◄World Chess (CHSS)► yet another trivial RNS - launches new and revamped interface for FIDE Online Arena. You can now start a game with one click. Just the sort of thing those short attention-span chess players want. [SP=3 Cap=24m]
◄Galliford Try (GFRD)► wins 2 contracts worth £101m [SP=258.3 Cap=265m]. I hold.
Every time I read anything about World Chess (LON:CHSS) I can't help but mentally adding
'in a show with everything but Yul Brynner'
Siam's gonna be the witness, to the ultimate test of cerebral fitness.
Interesting to see thst the most viewed stocks are all from the article on price momentum Ed wrote yesterday (which was great btw)
Momentum plays a large. part in my investment choices these days.