Small Cap Value Report (Fri 4 Aug 2023) - XPF, CARR, CPI

Good morning from Paul!
It's quiet for news today, so I'm hoping to finish late morning, and enjoy my last day on holiday here in Blakeney, Norfolk.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £1bn. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk.
XP Factory (LON:XPF) (I hold)
17p (pre market) £30m - Trading Update & y/end change - Paul - AMBER/GREEN
Year end is changing from 31 December to 31 March. I can see the logic for this - creating better visibility of full year results, not having to faff about with stocktakes & other year end procedures at the peak trading time of year, and making the audit and tax computations easier. So I think this is a logical move, and there’s nothing suspicious about it. Although investors do have to remember a year end change, so you don't start misinterpreting growth rates for the 15-month changeover year.
In terms of trading, the crux is that it’s in line with expectations for H1- strong Jan-Apr 2023, but “a little softer” in May & June (blaming rail strikes & hot weather).
Current trading in July was “significantly ahead” of May & June, which reassures me that there isn’t a deeper problem.
Full year expectations - in line.
Some short-term caution -
We are mindful of the pressures on consumers and on our cost base which bring an element of short term caution but we remain optimistic for the future of both our businesses and for the 2023 outturn."
Broker update - Singers has today confirmed its existing forecasts, which are £42.6m revenues (up 87% on FY 12/2022 actual), Adj EBITDA (pre-IFRS 16) £5.5m, and aPBT £1.1m. Remember that some of the sites are franchised, so the site level revenues overall would be higher than this, so quite a decent-sized business is being built here, rapidly.
Forecast £1.1m aPBT for FY 12/2023 is not a huge profit, but most of the sites were only opened in autumn 2022, in the dash for growth with the Boom Battle Bars acquisition. Hence sites should gradually mature. From this point onwards, we should see an operationally geared increase in profits, as new sites are added to a mostly fixed (and quite high) central overhead. Therefore I think the basic concepts of Escape Hunt, and Boom Battle Bars have now been proven, and the investment case for this share is that it's just a roll-out of new sites, each one adding to profitability (hopefully). Less risky through franchisees, but better control in the company-owned sites.
Cash is £3.6m at end June 2023, but we’re not told if this is gross or net. I think that's enough, but not ample. If management want to expand faster, then I think a fundraise would be needed. Although bear in mind that new sites are plentiful, and available on superb terms - with large landlord cash contributions towards fit-outs. The other option would be to use some debt for new sites, but that might not be easy to arrange in the current macro environnment. There is a small existing debt facility for fit-outs. With established sites now producing good cashflows, there's no imperative to raise money anyway, in my view. It would be a choice, for faster expansion, not to keep the lights on. I don't want to be diluted, so I would prefer them not to raise fresh equity at anything like the current share price.
New sites are being progressed with 6 in total happening this year, a much slower pace than 2022, but still good expansion. There must have been some teething problems from the extremely rapid expansion last year, so a more moderate expansion this year seems sensible to me. Dubai sounds interesting, has just recently opened, and has “so far traded exceptionally well”.
Paul’s opinion - this sounds a solid performance, but the short-term caution makes me move from GREEN to AMBER/GREEN. It’s a long-term holding of mine, because I’m impressed with the site economics, and the extremely rapid expansion in 2022 has transformed the scale of the business. Experiential leisure is very popular with customers, so this is an interesting niche to invest in, I think.
XPF is now profitable, and that’s after a large depreciation charge, so it should be nicely cash generative, enabling it to self-fund further expansion (albeit at a slower pace than the break-neck expansion of 2022).
I don’t think there are any other pure play experiential leisure shares available to us on the UK market, other than Brighton Pier (LON:PIER) which is small and niche (they can't do a roll-out of new piers!). Whereas XPF has 2 proven brands (Escape Hunt and Boom Battle Bars) which seem to work well at site level. Therefore it’s now just a case of rolling out more sites. I'm investing here because I think in say 3-5 years, this should be a much bigger business, the two formats are already proven (not speculative), hence it's just a question of trusting management to execute well in expanding the number of sites. If it works, then I'm hopeful for a multibagger. Plenty of competition from boring, generic bars, is likely to fall by the wayside I think, in current tough macro conditions.
There is competition of course, with experiential leisure bars popping up in other formats too.
It’s pointless looking at historic numbers for XPF, because so many new sites were opened late in 2022. So the figures prior to 2023 are not of any relevance.
I think the cash position looks a little tight, which means the rate of expansion is probably limited by available cash, although note that property deals mean the bulk of the site fit-out cost is paid by the landlords. That’s how it managed to open so many new sites last year with limited cash. Management made it look easy, but opening so many new sites so fast must have been an incredible amount of work - we now know management can handle rapid site expansion, when it was previously just an aspiration. That gives me confidence.
For growth investors I think this is a very interesting situation. Visiting the sites is fun, but remember that peak trading is Thu, Fri, Sat nights, so they might appear quiet at other times.
For now, the valuation looks about right to me, with a higher rating likely once the next bull market starts.
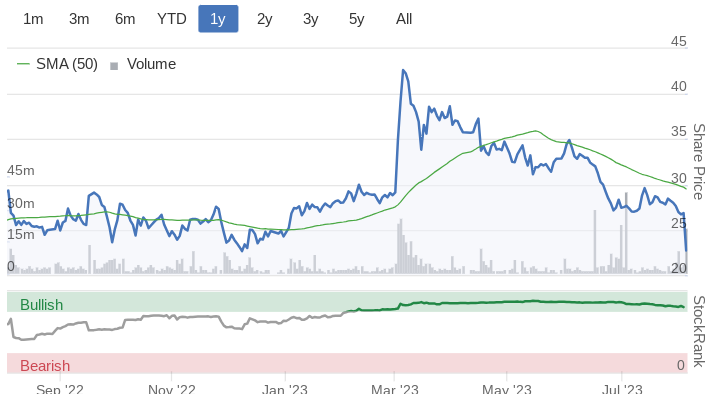
Note that the share count has increased considerably, to fund the acquisition of Boom Battle Bars, which was done at 30p. Now the acquisition has been done, and rapid expansion of new sites achieved, it strikes me as odd that shares can now be bought at almost half price! It just shows how market sentiment for small caps has plunged in the last 2 years or so - creating lots of buying opportunities I think -
Carr's (LON:CARR)
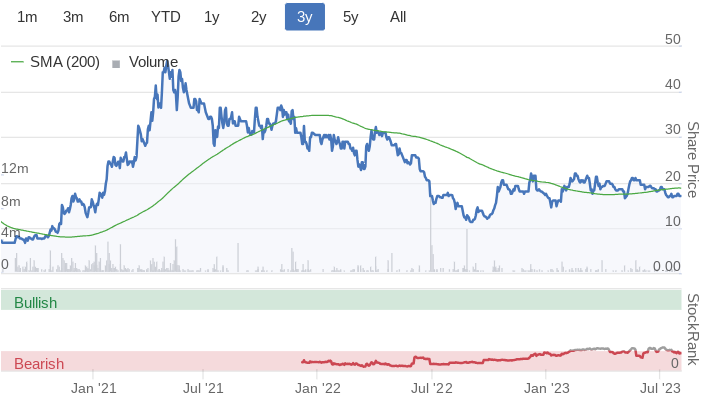
Down 11% to 128.5p (£121m) - Trading Update - Paul - AMBER
Carr's (CARR.L), the Agriculture and Engineering Group, announces a trading update in respect of the financial year ending 2 September 2023.
Background - this share was suspended earlier this year, due to a technical problem relating to the audit of a subsidiary, and an FCA investigation into the previous auditor’s work. It came back from suspension on 29 March 2023. All a bit messy.
Graham looked at Carr’s interim results here on 2 May 2023, noting a small profit warning, and wasn’t keen, viewing it as AMBER.
Carr’s moved from net debt into net cash, after a significant disposal during H1.
Today’s update - is a profit warning.
At the interim results (published 2 May 2023), the outlook section guided c.£10m aPBT (adjusted profit before tax) for FY 8/2023.
Today it lowers aPBT guidance by £2m (20%) to c.£8m.
That’s not great coming right at the end of the financial year, where guidance should have been pointing to a secure number that it could meet. Taken together with all the audit problems, this seems another indicator that financial controls are not what they should be. It’s so important that companies budget prudently, and hit their forecasts. Posting a miss at the end of the year is unimpressive.
What’s gone wrong?
- Speciality agricultural division - it blames drought in the USA, and higher costs in the UK, and a “delayed recovery” in markets.
- Higher costs relating to the disposed Agricultural Supplies division - this sounds a one-off, so fairly harmless.
The engineering division is trading well, and its order book provides confidence.
Net cash position, but no figure provided.
Paul’s opinion - rather underwhelming, but not a disaster, I’d say.
This share had a big re-rating about 10 years ago, but has since gone sideways. So the only attraction has been divis, which are OK, but nothing special, at a yield of just under 4%.
Value metrics are unimpressive, apart from price to tangible book, which is strong (the lower, the better) at 1.47.
It all just looks a bit flat. I think to buy or hold here, you would need to have some insights about the company’s future performance, and believe that it’s set up to grow profits from the current rather lacklustre level. If any subscribers are bullish, please do leave a comment explaining why, as there might be something good here that I've missed.
I can’t see anything wrong with this share as such, but also can’t see much obvious upside either, from a quick review only, so I’ll stick with AMBER.

Capita (LON:CPI)
Down 13% to 23.4p (£397m) - Half Year Results - Paul - AMBER
This is a large, complex group, that was in financial trouble, but has since drastically de-geared. I recall looking at it here in early March 2023, concluding that it looked a good turnaround around 35p/share. Unfortunately, since then the price has continued drifting down, with an extra lurch today (shedding £60m in market cap this morning alone), to currently sit at 23.4p. So it hasn't worked so far - is it still an opportunity, or a can of worms?
It looks like I briefly held a tiny position in CPI, which from memory was just a tiny spread bet, that didn’t last long. So no current holding, for disclosure, as required.
I don’t want to spend too long on this, so just a few notes from my skim-reading of H1 results today -
Adj revenue up 6% to £1.4bn, so a substantial business (not sure why they adjust revenue?)
Adj PBT £33.1m (up 34%)
Reported PBT negative at £(67.9)m - so there’s a very large different between adjusted and reported numbers, this is a key area to focus on if you research it deeper.
Net debt (excluding leases) continues to fall, at £166m (down from £289m a year earlier) - so as mentioned before here, Capita looks financially stable now.
Cyber incident - this seems to have spooked the market today, judging by the news summaries, with expected costs (net of insurance receipts) at a hefty £20-25m. See the reader comments below for some highly critical reaction to this (the incident itself had already been disclosed, but I’m not sure about the costs). Could this be the type of problem where costs, and even compensation, could escalate? It seems a considerable risk.
FY 12/2023 expectations are unchanged, the company says, and on track for improved financial performance they say.
It looks like net debt should fall further after more disposals complete.
Borrowing facilities extended.
Pension deficit - this looks complicated, so needs more work. It’s saying there’s an accounting surplus, but seems to have paid a whopping £30.6m deficit contributions in H1, if I’m reading that correctly?
Balance sheet - is pretty horrible actually. NAV of £247m includes almost £600m in intangible assets, so NTAV heavily negative at c.£(353)m - I think this rules it out for me. I don’t understand why I was sanguine about the balance sheet back in March? Possibly because management had won me over in the webinar at the time. More scepticism required I think!
There’s a huge deficit on working capital, with current assets of £774m being dwarfed by current liabilities of £1,442m. So it seems Capita needs large up-front payments from its customers to keep operating, which is a form of hidden debt really (see the £606m in deferred income creditor).
Paul’s opinion - as you’ve probably gathered, I’m a bit underwhelmed by this. That could just be emotional though, in that the share price has been so weak, and a negative market reaction today. Could it be a buying opportunity? I’m not sure, and this clearly needs a lot more work, to investigate the remaining disposals, the pension scheme, how serious the cybersecurity breach is? So I’d view this as a special situation, needing much more work, that could go either way. So I’ll just say AMBER for now.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

35 comments
To round off the week, I've updated my summary spreadsheet here.
My podcast was recorded last night, just one this weekend, available here, and through all good (and some bad) podcasting services.
Mystery shares for Stockopedia subscribers (best ideas from the week's news, for you to investigate more closely) are -
SCS (LON:SCS) - in line update, very cheap I think. Compare the balance sheet with DFS!
TT electronics (LON:TTG) - one of Graham's but I think it looks interesting too.
Facilities by ADF (LON:ADF) - almost a mystery share. Down due to external factors, could be a nice recovery for 2024 if strikes resolved in Hollywood perhaps? Might have to be patient.
Also one that I forgot to mention in my podcast, is Devolver Digital (LON:DEVO) - which I think could be an interesting mystery trade, to watch & wait for it to stop falling. The cash backing interests me.
Hope you're enjoying the weekend! See you bright and early tomorrow morning :-)
Regards, Paul.
Directors buying. The engineering businesses should command a higher rating and don't fit well with the agricultural business and could be opportunity sold. New CEO not really indicated plans as yet.
Coops: I assume you are writing about Carr's (LON:CARR) . It helps if you say so!
Paul - Reader request - as we near the weekend, as one of your regular podcast listeners, can I ask for a 5min ramble in that on 'your research process' outside of the published financials (and personal visits focused on consumer entertainment hubs!).
How do you actually DO your DYOR? I have been hit on some shares recently where the inevitably historic financials looked good (or at least understandably bad) .....but then suddenly weren't, presented perhaps by new Mgt! I feel we may be near a 'things can't get much worse so they must get better' moment on some cyclical UK shares.
I feel a need to 'do' something to continue to believe, as I must as a small cap investor, that I have an edge vs the institutions.
I therefore find myself, for example, trying to become an expert on brick manufacture and import/substitution costs (hello Ibstock (LON:IBST) !) and housebuilding projections. Do you pore over such govt statistics? Would this be windmill-tilting vs fund managers who are presumably full time paid to do this sort of thing vs my odd hours here and there.
Obviously, I'd welcome thoughts from any other subscribers.
Hi Zipmanpeter, Stocko has a vast archive of how to DYOR, if you have a search for Edward Croft, Mark Simpson or Meagan Boxall who all have excellent articles on strategies etc.
Also the 'Discuss' & 'learn' buttons to the left of the screen are useful with articles & blogs from other users.
Do Your Own Research has different meaning to different people. I am terrible at fine combing the report or the results of any company with going through the numbers. I do however, read the CEO report in some details. On the other hand I read or scan the business pages of The Telegraph, FT and The Times. I read IC and watch CNBC. Essentially I read the news and the commentary from various sources and make my mind up .
I read the tips and the brokers rating to take advantage to do the opposite if I disagree with their recommendations.
And most of all, I really read all the Stocko community comments here. Some contributors in these pages are so knowledgeable that I think they should be fund manager!
Thank you all for your comments and may it continue!
Many are a hell of a lot better qualified than so many fund managers !!!
I've been in XP Factory (LON:XPF) for about 3 years, they have always delivered in targets in a very tough period. I think at some point it should re rate over the 30p placing price. Richard isn't a rampy CEO, so far he has set achievable targets and hit all of them
Totally agree with Paul that I hope they don't raise at this price, the only reason I can see them doing it is to buy flip out, I can't remember when the exclusive option expires, can't be long. Hopefully they wont
I'm putting off looking at Capita (LON:CPI) next, which looks complicated. So let's put up some holiday snaps I took this week in Norfolk!
1. Sunset last night in Blakeney Quay, nearly the highest tide in the lunar cycle, which has engulfed nearly all of the car park. So we found a vantage point, and were hoping to see some SUVs floating nose-down into the North Sea, but sadly not -
2. Day trip to Sandringham, you can see the late Queen's country house in the background. More a large country house than a palace. Stunning, meticulously maintained, huge park-like grounds, well worth the visit! Pleasant & helpful guides in every room in the house, and no "clipboard nazis" thank goodness! (I usually, and frequently get into spats with that type).
3. A very large photo of a charming nearby village called Wells-next-the-sea.
4. Marshes near high tide, caught some super cloud reflections in the water.
great pics, enjoy your column, the analysis is easy to understand and great for a novice like me keep up the good work, thanks
Superb pictures - such a lovely part of the world. So much to do up there but if it is raining I can highly recommend visiting Holkham Hall. If you want to spoil your Mum then the Blakeney Hotel is superb for food. I hope you enjoy it whatever you decide to do!
I'm on the Costa Brava, stunning
You should have spoiled your uva arf to dinner at Galton Blackiston’s Morston Hall restaurant, it really is up there with the best of them
Capita (LON:CPI) results were poor in my view. Even worse, the outgoing CEO spins everything positively and has lost credibility.
Apologies - I am probably biased as my pension data was leaked, despite previous reassurances that it hadn't been, at which point I sold my small holding luckily at a profit. Anyway here are some of the spins.....
"Acceleration in financial performance" - really? They made an increased loss and reduced adjusted operating profit.
"less than 0.1% of the Group’s server estate" - on the cyber attack but included millions of pensioner details, so the cyber criminals must have targeted the most interesting bit of the server estate!
"Funding position transformed" - Pre-IFRS 16 net financial debt1 was £166.2m (31 December 2022: £84.9m) reflecting the free cash outflow and additional pension deficit payments of £15.6m triggered by prior-year Portfolio disposals.
previously announced £15-20m of cyber-attack costs now £20-25m with nothing provided for claims - see note 16.
Talk of dividends now off the radar - not surprising as there is no free cash flow.
Anyway, things won't change here until a new CEO is honest about the problems in my view. Will the new CEO find more problems and kitchen sink the full-year results? Best way forward is to split Capita into 2 separate companies (public sector and private sector) and re-brand in my opinion as Capita itself is a tarnished unloved brand.
DYOR, but just my take on things based on my experiences of Capital over the last 6 months or so!
All good and fair points. Naturally for a business in transition that has off loaded many businesses you have to look at adjusted numbers and HOPE they become the reported over time. If you have no faith in that then of course it's a no. I thought adjusted growth actually showed some momentum with 6% Revenue growth - 43% operating profit and 10% EBITDA. FCF as stated was a negative. A significant target is margins.. and I think this echoes the Serco (LON:SRP) strategy which was also stop start for a year or two.
The cyber breach is more difficult and I guess we need some decent evidence this is not going to bite again before its investable. I will review the webcast for any snippets.
Brand Architekts (LON:BAR) it doesn't look as though you've looked at this one for a while. Trading update issued back on 20 July. I've been alerted to this one and it looks interesting with proactive momentum: the resolution of legal dispute, continued international roll out of products ; one of their products "skinny tan" is rated highly by my 17 year old daughter. Also have a look at the two year SP chart showing a nice top left to bottom right trend. Looks very interesting! Would appreciate your thoughts Paul on a quiet day. Many thanks!
Thanks Bristolian.
I've followed the story at Brand Architekts (LON:BAR) for a few years, but there's not been anything of interest to motivate me to take a fresh look. I seem to recall newsflow and figures have been lacklustre, at best. Next time it reports, we can discuss it then - as always, I'm more than happy to take a fresh look at anything, if the facts & figures have improved.
Regards, Paul.
Morning All,
Looking at Mears (LON:MER) forecasts for 2024, profits and earnings are shown to fall?
Anybody as to any reason why?
Thanks.
Anyone one else having a problem with the folios on Stockopedia. I added a transaction today, price was 604p, but it timings that by 100, don't know if this is a one off or not. I put in the price as 6.04 but that that shows as 6.04p which is incorrect.
Report by the green button. I had this in the past with one share and it took a little while to fix as it was the pull through data from thee supplier that was the issue.
they do keep you updated tough!
Tommy
I have reported it, still waiting for an answer. Looks like a one off. Had some weird problems on folios in the past.
Capita (LON:CPI) has been on watch list status for me...after a rather successful disposal programme last year.... it looked like it was cleaning up the balance sheet...and analysts were expecting a return to growth and better margins....net net much improved FCF. FCF is the magic when it comes to turnaround...it reduces debt, supports dividends and buybacks...so if you have a very cheap stock with low margins it can be become quite exciting.
The trouble is just as things were looking up in February and the shares rallied massively from below 30 to above 40.... we had the market wobble and then more importantly, Capita (LON:CPI) had its own issues with a pretty bad cyber attack. The shares promptly retraced all gains.
Todays numbers are a bit of a mixed bag...in line apparently although the cyber attack and other adjustments mean positive FCF is a forecast not been witnessed. The revenue growth however was ok and guidance and order book all look ok. Further smallish disposals in H2 should reduce debt a little more. The hit from cyber is relatively painful...and obviously mistakes on large contracts can have a disproportionate impact on the market cap ( since it's so low). So the FCF hit of £50m is taken badly today.... compared to a positive outlook for the full year.
The shares are getting hit hard this morning. Maybe the investor call helps.. I think they probably got a little unlucky with the cyber attack ... and as they put that behind them.... a refocus on underlying growth and performance if supported with better FCF .... should see the shares do better. No rush for now, but into the year end maybe of interest on the expectation of full year results without landmines.
I think they probably got a little unlucky with the cyber attack
You don’t get unlucky with cyber vulnerabilities. You get found out.
Capita (LON:CPI)
I think they probably got a little unlucky with the cyber attack
Capita are now faced with two potential additional costs - the fine from the ICO, which could amount to £17.5m and consquential damages claims from any of the parties affected by the data breach - and there are a lot of them.With a lot of cyber-security incidents investors reasonably take a view that the company in question isn't really a specialist in the area but that's not true with outsourcers like Capita. This is core business, and they should be on top of it - it'll be interesting to see if the ICO report sheds any light on what happened, but given that customer data has been exfiltrated, it probably won't make pretty reading.
timarr
As it is a quiet news Friday :-)
timarr,
I always enjoy and usually learn from your posts. I am not sure I have come across the word exfiltrate before. Presumably one has to infiltrate before one can exfiltrate?
Hi Helvellyn
I am not sure I have come across the word exfiltrate before. Presumably one has to infiltrate
before one can exfiltrate?
Ack, that's the day job talking, jargon all the way I'm afraid.
Exflitration in this context is a form of data breach where the attacker manages to extract data from the target's system. That's what's happened with Capita, which means that personal data has been exposed.
One thing to be wary of is that the initial reaction to institute checks - many breached companies offer a year's identity fraud protection, for instance. Of course, the criminals know this, so they'll often sit on the data for twelve months or more before attempting to use it.
Basically - if you know your data has been breached make sure you've changed all critical passwords, and regularly check your credit record. In this case "names, dates of birth, marital status, addresses, postcodes, salaries, email addresses, and employment details and history" were lost, which is a pretty good start to identity theft.
Even the best companies can get breached, unfortunately, but most breaches are from low-hanging fruit. Outsourcers like Capita are data honeypots, so the hackers will be all over them.
timarr
Ack, that's the day job talking, jargon all the way I'm afraid.
Exflitration in this context is a form of data breach where the attacker manages to extract data from the target's system. That's what's happened with Capita, which means that personal data has been exposed.
My ex day job :-)
I always have a problem with this because it probably means all that precious data sitting there was not encrypted at rest. It's no good an attacker downloading a large database if it's encrypted with a 256-bit key unless they have access to a bloody powerful computer, preferably optical, to brute force decryption.
I realise using encryption properly makes even legitimate use inconvenient i.e. proper per-use user verification, but the mind boggles why a proper security hierarchy is so rarely implemented in this day and age to protect important data. Of course, economically proper security makes no sense and this is the real issue for a company looking at its operating overheads i.e. it's like any insurance, you don't need it, until suddenly one day you do! As such, it's only natural for dumb company management to cut corners. Companies like Capita, and their security advisors, deserve all they get. It's just unfortunate for the rest of us whose data they hold with such scant regard.
All the best, Si
My guess would be if this is a problem for say Capita (LON:CPI) it could be much worse for small asset managers, stock brokers etc where IT budgets are even more stretched.
My daughter in law has her pension plan manag ed by Capita and as a result of her experience in trying to resolve it all she nows refers to them as Crapita! Says it all from her perspective as a client!
While all quite here, I glanced at the news on Stocko.
It’s full of companies buying back their shares. In today’s case mainly banks ,(Barclays,Virgin money), IG, Bellway, Rit,Spirent, etc.
This is all good news for the future earnings and tells me : 1. the companies think it’s the best way to spend their cash
2. when the market recovers it turbocharges the speed of recovery in share prices.
I have my portfolio set up for news, and this year two-thirds of all RNSs are for one or other of them buying back shares. As these are all UK-listed, it does mean the available public company universe is slowly contracting, but I feel sure that one day the UK will turn higher, simply as a contrarian trade.
First half figures from Morgan Advanced Materials (LON:MGAM) this morning (I hold).The company was hit hard by a cyber attack that depressed first half profits but has used it as an opportunity to upgrade its software. On current trading it reports robust demand and no further changes in full year adjusted profits. Its on a prospective PE for 2024 of 8.2. The London market seems littered with companies selling high quality products and expertise at low ratings. If ratings do not improve I think there will be a spate of takeovers.
My morning smallcap tweet: Cuttings
Parity (LON:PTY) Carr's (LON:CARR) Home Reit (LON:HOME) Argo Blockchain (LON:ARB) Ilika (LON:IKA) Kibo Energy (LON:KIBO), £XFP
◄Parity (PTY)► warns H1-June rev down 10% due to weak mkt. "With market conditions not expected to improve in the near term and a key client signalling a shift towards a more global supply chain, Parity is prioritising resources to exploit its strengths and opportunity within the public sector." Cuts staff in private sector biz. [SP=3 Cap=3m]
◄Carr's (CARR)► warns FY-Sept adj pretax only c.£8m. "Expectations for August 2023, historically a strong trading month, have now been moderated by delayed recovery in our markets." Also "Following the strategic disposal of the Agricultural Supplies division, completed in October 2022, the Group has incurred higher central costs in the course of concluding the transitional services agreement, now expected to complete before the end of calendar 2023." [SP=142 Cap=134m]
◄Home REIT (HOME)► sells 40 properties for £4.8m (39% of cost) which had limited prospects for income and capital return given the required capex. [SP=38.05 Cap=301m]
◄Argo Blockchain (ARB)► mined 11% fewer Bitcoins in July than June due to "greater downtime at Helios from weather-related curtailment and onsite construction". [SP=10.02 Cap=68m]
◄Ilika (IKA)► the serial disappointer signs a 10 yr manufacturing licence and royalty agreement with Cirtec Medical for Stereax range of products. Exclusivity for Cirtec in medical device use. "Ilika will now focus on advanced technology development and IP licensing in support of Cirtec's manufacturing and commercialisation activities." Despite this good news rev guidance for the next few years is unchanged. [SP=45 Cap=72m]
◄Kibo Energy (KIBO)► extends long-stop date for JV announced in July due to delay to necessary funds. [SP=0.05 Cap=2m]
In line: XFP
Positive trading update from XP Factory (LON:XPF) . Revenue up 131% and outlook sounds good:
“Notwithstanding the ongoing rhetoric of the cost of living crisis and rising interest rates, trading in July was significantly ahead of May and June and early indications are positive for August. Looking further out, the Company is experiencing record levels of corporate and group bookings for H2 2023, which together with July's performance helps underpin the board's confidence in a full year performance in line with market expectations. “
Hoping for some thoughts from Paul on the XP Factory (LON:XPF) trading update as he holds. The revenue and EBITDA figures look very good. Like for like sales growth is more modest but still positive.
Usually when a company changes year end there are concerns that the company is trying to hide something by delaying the year end and making comparatives more difficult to assess. In this case the change looks completely sensible, giving the market time to assess the Christmas peak trading period and allowing the accountants a quieter period for their year end accounting work.
I hold and am looking forward to good share price growth as and when the revenue growth starts to generate meaningful profits and cashflows.