Small Cap Value Report (Fri 4 June 2021) - SAL, POLX, CREO, TUNG, CDGP

Good morning, it's Paul and Jack here, with Friday's SCVR.
I'm getting my 2nd AstraZeneca jab this afternoon, so am looking forward to that. The NHS App is very good, I downloaded it onto my phone last night, it keeps a record of your jabs, which could be useful in future to prove you've been vaccinated (for travel, etc), so you might want to look at downloading it yourself, if you haven't already done so.
Timing - we're making good progress, so should all be done by 1pm official finish time, or earlier. Today's report is now finished.
Agenda -
Paul's Section:
Spaceandpeople (LON:SAL) (I hold) - too small for the SCVR, at only £3m mkt cap, but seeing as I've looked at its 2020 results out this morning anyway, might as well post my brief notes. It's a speculative punt, but has survived the lockdown, and sounds like there is some potential here, with (previously announced) new contracts. High risk warning.
Polarean Imaging (LON:POLX) (I hold) - highly speculative, but several shrewd friends tell me this MRI scanning company looks to have interesting potential. High risk warning on this one, so won't appeal to most readers.
Creo Medical (LON:CREO) - another highly speculative jam tomorrow medical devices company, issuing results for FY 12/2020. Prodigious cash burn. I've got no idea how to assess companies like this, so am neutral.
Tungsten (LON:TUNG) - some signs of life here, in today's year end update for FY 04/2021.
Jack's Section:
Chapel Down (OFEX:CDGP) - perennially loss-making, cash-burning UK wine producer. Disposal of non-core beer business and a strong performance in ecommerce and direct to consumer are positives, as is the strong market position, but there's still plenty to be done to show that this can become a sustainably profitable business for investors.
Paul’s Section
Spaceandpeople (LON:SAL)
(I hold)
* High risk, extremely small *
14.25p - mkt cap £3.0m
Only a tiny position, which got through to my Spreadex account due to a clerical error. It’s too small for the SCVR, at only £3m mkt cap, but seeing as I've looked at its announcement today anyway, might as well quickly post my notes below.
FY 12/2020 results, out this morning.
It’s still in business, and has survived the pandemic, thanks to taxpayer-backed loans.
New CEO, Nancy Cullen - I think it’s too early to judge her, because the pandemic hit & stalled the business soon after she stepped up.
Loss of £(2.1)m before non-recurring charges, £(3.6)m statutory loss - a seriously bad year, due to retail lockdowns
Balance sheet weak at NTAV of £(2.2)m, so don’t be surprised if it needs to do a placing at some stage. Are the receivables collectable?
Cost-cutting done
Outlook - promising, maybe? Talks of a “vastly strengthened portfolio” (of shopping centre clients) in the UK, and “an improved long-term contract with ECE in Germany”.
My opinion - high risk, a speculative punt. However, the £3m mkt cap gives plenty of upside, if the new venues (e.g. former INTU shopping centres) do generate decent returns. I seem to have bought a tiny position in this at 6.9p, thinking it would either go bust, de-list, or recover. It’s doubled so far, so it’s tempting to run the thing, and see what happens on re-opening. Or maybe sell half, and run the rest for free?
I like the concept of pop-up retailing, and SAL tends to do better in retailing recessions (but not when they’re completely shut of course!) as there’s more demand from landlords for its pop-up shops & kiosks when their other revenue streams are under pressure, as they are now, as never before.
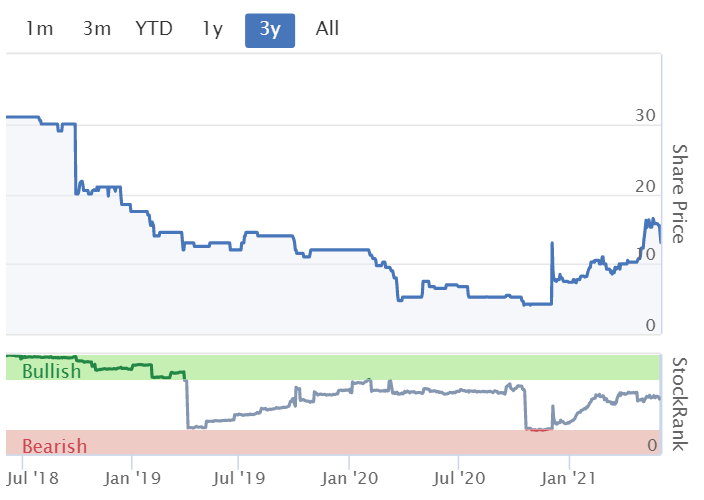
NB.Be careful with the StockRank here, as with many nano caps, there's not reliable broker coverage - only 1 broker reporting here, and what looks like incredible 2021 forecast earnings.
.
Polarean Imaging (LON:POLX)
(I hold)
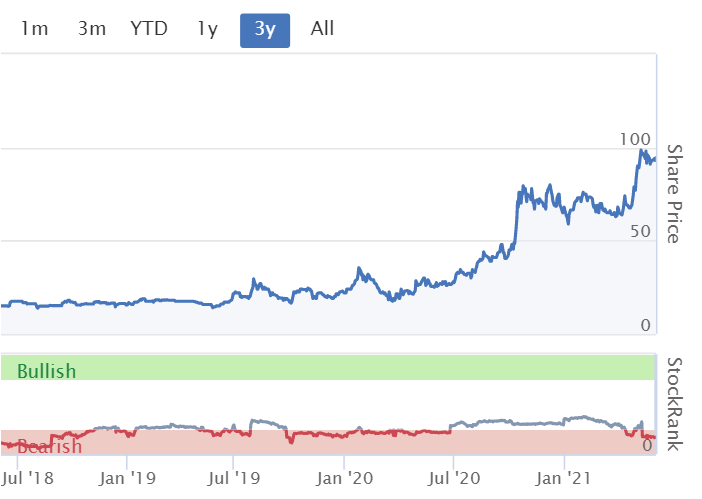
93p (pre market open) - mkt cap £197m
* Highly Speculative *
It’s a bull market, so everyone likes the occasional punt! Several of my shrewd HNW investor friends have flagged Polarean to me, as being something they think has potential, so I picked up a few on the basis that these investors’ previous ideas have generally done very well.
What does it do? It’s found a way of making MRI lung scans more detailed & useful, using Xenon gas. This is completely outside my area of expertise, so I’m not offering any view on whether the product is likely to work or not, that’s up to readers to research for yourselves.
My notes from this morning’s FY 12/2020 results -
- Date set for approval in USA is 5 Oct 2021 - a reasonable timescale
- Mgt background looks impressive - see video of recent presentation on InvestorMeetCompany
- Revenues only $1m - product is just being sold in small numbers to research facilities (e.g. top universities) to assess it
- Gross profit of $710k - a high percentage, so if product is approved & rolled out, then company could become profitable, at what level, I have no idea
- Operating loss of $6.6m in FY 12/2020
- Balance sheet was weak at NAV $8.7m, however£27m raised post year end, so is fine now - looks fully funded for (hopefully) product launch later in 2021, or early 2022?
- Impressive cornerstone investors backed recent £27m fundraise, including Bracco Imaging - a >E1bn revenues Italian healthcare group, active in diagnostic imaging - so I’m impressed they’ve invested in Polarean, and must have checked out the technology. Also, Amati AIM VCT invested, and other institutions.
My opinion - this is a complete punt for me. I’m just flagging it up here for people to do your own research, if you like speculative things, as shrewd investors tell me it could be the real deal. Obviously this type of share is high risk, because if the approvals don’t happen, and/or the product is found to not work as hoped, then the share price would collapse by a very high percentage. Hence personally, I always limit my position size to an amount I could afford to lose. I’m just hoping that POLX isn’t BOLX!
.
Creo Medical (LON:CREO)
208p (down 1% at 09:44) - mkt cap £329m
* Highly speculative *
Jumping from one loss-making jam tomorrow medical devices company above, to another, more extreme one here. For useful background, see Roland's recent article about CREO here.
Results for FY 12/2020 are out today.
I rarely cover things like this, and no HNW investors have told me they like this share, I’ll let you know if that changes!
Revenues £9.4m (up from a negligible £13k in 2019)
Massive losses of £(20.7)m after tax (because tax credits can be seen as part of earnings for loss-making companies like this, so I use PAT not PBT for such situations) in 2020, and £(15.9)m in 2019
Balance sheet - all that matters at cash burning companies is: how much cash is left, and how long will it last? Creo had £45.1m cash. No net cash figure is given in the commentary, but I see the balance sheet has liabilities called ”Interest bearing liabilities”, which sounds like debt to me, of £4.0m + £6.54m. There’s also “Non interest bearing loans” of £1.79m. Net all that off, and it looks like net cash of £32.8m
Cashflow statement - shows £(16.3)m operating cash outflow, plus a further £20.6m cash outflow for an acquisition. Therefore, if we assume it’s not going to make any more acquisitions, then the net cash pile of £32.8m looks roughly enough to last until the end of 2022 - no immediate cash worries then.
My opinion - neutral. The valuation of the company is entirely based on hopes for the products it is launching. I can’t assess that, so can’t take this any further. It’s the sort of share where you would need to do in-depth research on the products, and would need specialist sector knowledge to be able to judge their chances of commercial success.
For most private investors, buying shares like this is just gambling, so it doesn’t interest me. There's always the risk of further fundraises, and dilution. Note that the share count has roughly doubled from 2017 to now.
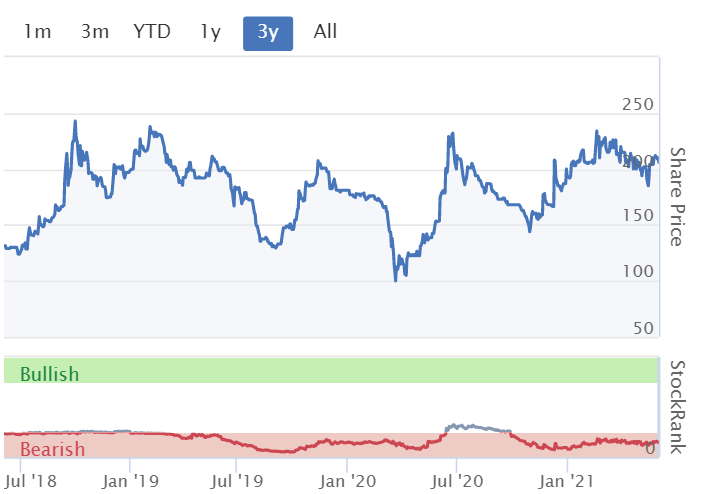
The Stockopedia computers snort with derision at jam tomorrow shares, and they're usually right to do so, because such a high proportion of jam tomorrow shares turn out to be awful investments. So the StockRank is predictably low, at just 16 - a useful warning to us.
.
Tungsten (LON:TUNG)
34.5p (up c.5% at 11:28) - mkt cap £43m
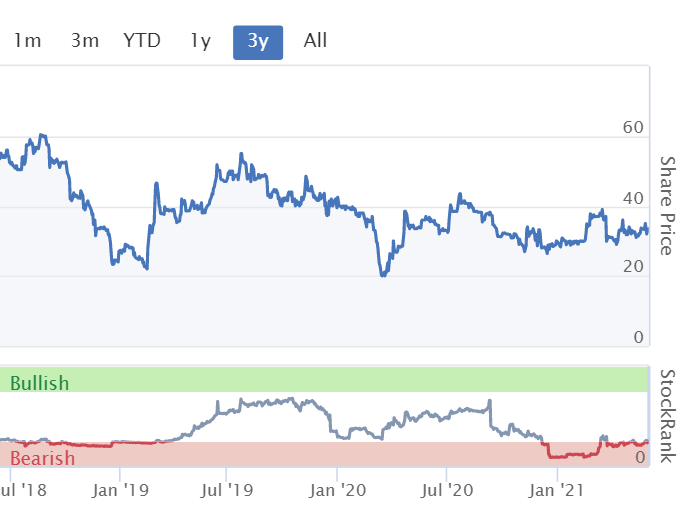
I last looked at Tungsten (an accounting software company) here on 24 March, when the shares fell 19% on news of a major client loss. I pointed out that Tungsten has a very poor long-term track record, and also needs a fundraising due to its weak balance sheet (NTAV negative at £(10)m)
Positive news came out on 13 April 2021, of a new customer win - an impressive client name too, NTT (European division), a “leading global technology services company”. It’s Japanese headquartered, and google says it’s the 4th largest telecoms company in the world, in terms of revenue, and the 5th largest publicly traded company in Japan, after Toyota, Misubishi, Honda, and Japan Post. Hence a really impressive client win. I didn’t focus on this announcement at the time, but it looks important, not least as a reference customer to help win other new clients.
Trading Update - today
Tungsten Corporation plc (AIM: TUNG), a leading provider of digital financial management products and software solutions, today issues a trading update ahead of the announcement of its full-year results for the year ended 30 April 2021.
Trading is recovering after covid impact
“Strong momentum in new sales”, and “recovering transaction volumes” towards the end of FY 04/2021
Large client wins: 8 (up on 6 last year)
Revenue essentially flat vs LY, c.£36m
93% of revenue is repeatable/recurring - giving good visibility for future
Adj EBITDA in line with guidance - but doesn’t remind us what guidance is, distinctly unhelpful
Net cash is £2.1m - running tight in my view, so high likelihood of a placing at some stage, but the horrendous cash burn of the past has stopped due to cost cutting
Current trading shows a rebound in transaction volumes after falls last year
Outlook -
"Our current sales conversion rate and increasing year-on-year transaction volumes across the business, particularly in Europe and North America, gives us cautious optimism for FY22 delivery. The solid sales pipeline and an additional £1.0 million of investment in tech development and compliance functions in FY22 will provide us with a strong platform for future growth."
My opinion - not a basket case any more, and the NTT Europe contract win does seem impressive. I think a further fundraising is likely, but if it raised a top-up of say £4m, that’s only 10% dilution, so not necessarily a major worry.
I thought Proactis was hopeless, and Tungsten reminds me of it. However, someone saw value in Proactis, and bid for it, at a large premium. Which I think shows that recurring revenues at software companies are valued highly by acquirers. Hence there’s a possibility someone might bid for Tungsten, as I’ve mentioned before here. I’m tempted to have a little dabble.
.
.
Jack’s section
Chapel Down (LON:CDGP)
Share price: 59.5p (unchanged)
Shares in issue: 162,600,159
Market cap: £96.7m
Chapel Down (OFEX:CDGP) is a bit of a rarity: a UK winemaker. It’s a nice business to look at, but whether or not that makes it a good investment is an entirely different question. Liquidity is an issue, with a 496bps spread and an average of about £11,500 worth of stock trading hands.
While revenue has gone up, the group has struggled to turn a profit, with total operating expenses moving up more or less in line with revenue. This has resulted in precious little for shareholders to shout about over the years.

The group also reliably burns cash.

Whenever I see consistently negative free cash flow, I like to check the Net Debt and Average Shares lines in the Balance Sheet section of the Financial Summary. Cash to fund operations has to be coming from somewhere, and this brings with it important implications for historic and potential shareholder dilution and debt levels.

Of course, this year Chapel has had Covid to contend with too. While the weather might be perking up now, and a 25 acre vineyard in the heart of Kent sounds like a nice place to be, on trade demand must have suffered greatly in recent months.
I’m rooting for this UK vineyard, but I can’t say it’s winning me over at first glance as a potential investment.
Final results
Wine & spirits
- Wine and Spirits revenues on a continuing basis up 32% to £13.294m
- Wines and Spirits gross profit on a continuing basis up 31% at £5.149m
- Adjusted EBITDA for Chapel Down Wines and Spirits was up 76% at £1.608m
- Wine sales volumes up 38% despite losing a third of on-trade business over lockdowns,
- Direct to consumer (D2C) volumes were up 467%, offsetting reduced hospitality and retail volumes. D2C has grown from just 4% of Chapel’s trade in 2019 to 18% today.
- The 2020 harvest was ‘excellent… in both quality and quantity’
Beer & cider
- Beer and Cider was badly affected by the lockdowns, with sales down 52% to £2.265m
- Gross profit fell 68% at £0.451m. The group experienced ‘heavy discounting and intense competition’ here.
- Adjusted EBITDA was a loss of -£1.629m (2019: loss of -£1.776m).
Adjusted EBITDA for the group was a loss of -£0.021m (2019: loss of -£1.236m).
The loss before tax however, was a much larger -£7.860m (2019: loss of -£4.285m) due to the £6.677m of exceptional costs associated with the disposal of Curious Drinks Limited which completed on 23 April 2021.
This strikes me as a good move - beer is fiercely competitive, full of operators that have been doing it literally for centuries.
I imagine this was a huge and costly distraction for management of a company that has established a strong market position as a winemaker.
And the team says its core wine business is now in much better shape, with ‘a great deal of excitement around English wine’. Chapel has used this restructuring as an opportunity ‘to transform sales towards e-commerce’.
A 32 % increase in turnover at its continuing operations to £13.294m is promising, as is the 31% increase in gross profit to £5.149m. Plus the group says its 2020 harvest is its third highest ever.
Chapel is going to invest in further capacity and equipment over the next 2-3 years. More detail here would be nice but this, alongside the direct-to-consumer and ecommerce growth (ecommerce grew by some 467% in the year, albeit presumably from a low base) and the disposal of Curious, could mark the beginnings of a more intriguing investment case moving forwards.
Risks remain. Chapel Down’s fortunes will forever be tied to the notoriously fickle British weather. The group raises concerns about the availability of labour and Brexit, which has not had an impact so far, could always complicate the shorter term picture.
Conclusion
This is more interesting than I had initially imagined but I do remain wary.
The crucial changes are in the level of profitability, the disposal of Curious Brewery, and the strong performance in e-commerce and direct to consumer.
With the furloughing of staff and management’s decision to reduce spend over lockdown, we might not be able to count on the margin improvement as a permanent feature.
The disposal is more promising.
The combined business made a loss before tax of -£7.860m, with the Wines and Spirits delivering a profit before tax of £0.955m and Curious Drinks recording a loss before tax of -£8.815m (including the £6.677m exceptional write-down of net assets).
There’s a strong wine and spirits brand here, and Chapel already exports to the US, Norway, Latvia, Hong Kong, Japan, New Zealand and China.
Given the track record this is not one I would invest in just yet - but I would monitor performance post-disposal of the brewery and keep an eye on its growing ecommerce and D2C businesses to see if they can continue to grow post-lockdown. It could lead to a more sustainably profitable business.
Meanwhile, revenue growth has been encouraging and Chapel Down has built up a strong market position in the UK over the past 20 years or so.

Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

35 comments
Tungsten was or indeed is my short of the year. This is based entirely on its history of blindingly bad decision making, its presence in a market littered with dead bodies and its ability to hire incompetent management and waste shareholders' money. But that is history and we all know what Henry Ford said about that. Good luck if you believe and make me duly surprised. My last sale in 2015 was at £1.45 and I confess to having made a reasonable profit entirely through luck rather than judgement. I guess the Stocko quality ranking is a laggard?
I'm not much of a wine drinker but today's comments are making me want to buy a bottle of Chapel Down's wine :)
Dear Paul
I own shares in Brickability (Brickability (LON:BRCK)), having purchased a holding shortly after its flotation in August 2019. Part of the attraction was that the Directors bought shares in the issue which is unusual. Having met management at the time of the impending float, I was impressed by their knowledge of the industry, the robust financial controls in place and also by their wish to expand the business through acquisitions but with very strict payment criteria.
I mention this because you have quite correctly referred to the large share disposals by several Directors alongside the recent acquisition of Taylor Maxwell, so I wanted to put their part share sales into context. My understanding, incidentally, is that over thirty new institutional shareholders have come on board, in addition to existing holders who either retained (ie diluted) or increased their holdings. The acquisition is immediately earnings enhancing, resulting is anticipated double digit percentage earnings growth in each of the next two years following the company’s March 2021 year-end. Cenkos is the broker and, if you are interested, you will find a detailed note on Brickability on the ResearchTree website.
Kind regards
Phillip
Thank you, Phillip, for writing about Brickability (LON:BRCK) . I have been very pleased with the way it has kept going up over the six months since I bought it - my first purchase. The Stocko metrics were good, I liked how the management came over in the results presentation on their website, and I thought building would be part of the Covid recovery. It does not get a lot of discussion on the site, so your in-depth knowledge has been reassuring. I will look out the Research Tree note you mention.
Regards,
Indie
Hi Paul and Jack,
great article as always.
But Paul, I wanted to take issue with you regarding your excellent recent piworld video with Tamzin.
While you are of course entirely correct in mentioning that the SMXX FTSE Smallcap index has gained 27% year to date, I would like to point out one thing.
this is not an investable index! I would love to be able to buy an ETF of the FTSE SmallCap ex ITs, but one doesn't exist.
When I look at UK small-cap investable benchmarks, I tend to look at well-managed UK smallcap investment trusts such as Blackrock Throgmorton Trust (LON:THRG) , Standard Life Uk Smaller Companies Trust (LON:SLS) and Montanaro Uk Smaller Companies Investment Trust (LON:MTU) .
The average performance of these 3 YTD is under 12%! So a big difference to the SMXX...
(maybe just trying to justify my own paltry YTD portfolio performance, which has not been as good as yours - so far!)..
Tx Edmund
On Tungsten (LON:TUNG)
I wish there was a way of filtering out companies as a few years ago I thought I knew better (despite advice from PS) and made a fairly _massive_ loss and any mention of that name makes me feel pain.
I still believe there is a good business in there somewhere and wish current holders the best of luck but no-one has found that business since well before OB10 was turned into TUNG - over 10 years now.
On Chapel Down (OFEX:CDGP)
You may not like the wines but a lot of people do. The decanter World Wine award is (I think) the largest in the UK and is widely published in Europe, US. It also has a far east correspondent.
They have leased / bought a lot of land in the area and are expanding
They are also starting up an "upmarket brand" called Kits Coty and yes it is rather expensive but pretty good - esp the chardonnay.
In a way it is a play on global warming as the land there will become prime wine country in the future and champagne may become too hot for good champagne
(I hold and do enjoy the 30% discount)
Paul, thanks for your comments on £CREO. One important point I would make is that they did £9m revenue last year but they have already issued a TU stating they are ahead of next FY revenue guidance of £20m. So clearly something is going well as they already know they have more than doubled revenue YOY.
Hi Paul
Thanks for drawing our attention to Polarean Imaging (LON:POLX), as you say a very interesting company, and a reasonable prospect. But . . . a market cap of 200 million for what is currently a start-up? Is there really enough upside? Surely Spaceandpeople (LON:SAL) must be a better bet, even if does have to raise more money.
£polx I looked at the house broker forecast which was based on what appeared to be very low machine sales and the risk reward was not worth it. If you ignore that forecast and listen to the guy running the company he says that he doesn't see why every hospital would not have a machine. If that's true then the upside is immense. I'm still put off by the broker though.
Polx (I hold) have a leading position in the technology they have developed and there is no comparable device providing the same level of detail in imaging with the the same safety profile.
Other alternative uses were suggested by the CEO for medical drug development trials and how costs could be significantly cut.
There are barriers to entry as they have a plethora of patents but also as it is a drug device combo then any new similar product for the medical market will need to go through the lengthy period of Pre clinical and Phase1, 2, 3 etc trials before it can reach market so not an easy task.
I expect in the next 2-5 years they may get taken over probably by Bracco who have a shareholding but also one of their people sitting on the management team who previously sold his own company to Bracco - Jonathan Allis of Blue Earth Diagnostics ( a Bracco company) and he is still the Executive Chairman there. Very strong signs in my view of what may happen in future. Good luck all.
I share your enthusiasm with POLX. They are an impressive outfit serving a very important and under-served area of medicine. Have done my own DD they appear to have an extremely high chance of obtaining FDA approval at which point they will be in a position to offer clinicians something that nobody else has been able to do - accurately assess lung function in a quantitative manner.
In a peer-reviewed study, their drug-device combination has just been found to identify lung damage as a result of Covid that no other diagnostic approach was able to detect. Not only is this topical due to Covid, but pulmonary conditions are a major health concern globally and represent a huge need for reliable diagnostic technology.
I see this as a multi-bagger and hold.
Hi Jack,
Thanks for the update on Chapel Down (OFEX:CDGP)
A friend invited me to visit their vineyard a few years ago, and it's a lovely setting, with a good restaurant there too.
As for the wines themselves, I've not tried them recently, but was unimpressed last time. They seemed to me below average, compared with French or Chilean supermarket wines, and at least double the price. So other than the novelty of trying an English wine, I cannot see why anyone would repeat purchase them. Although taste is a very personal thing. Tiny revenues, after many years trying, seems to confirm my view. Sure there are limitations on the production from acreage, and vines taking x years to mature, etc, but I remember they said additional grapes can be bought in from nearby farms, if the demand is there, which it clearly isn't, to any meaningful level.
Looks like diversifications haven't worked either.
No divis have ever been paid, so apart from the shareholder discount on (not very good, overpriced) wine, what's in it for shareholders? Nothing.
Yet this share is still valued at a £96m market cap. That looks ludicrous to me. It should probably be written down to whatever the secondhand value of the land/vines would be, which as it's on a P/TBV of 3, suggests the shares might really only have an underlying value of a third of the current level.
Would be interesting to hear if any readers love the wines? I would only ever invest in a wine maker, if the product was stunningly good, and lots of other people thought so too. That just doesn't seem to be the case with Chapeldown. Good luck to them though, but not a credible investment, in my opinion.
Regards, Paul.
Paul Re Chapel Down (OFEX:CDGP)
The industry seems to think it is worthy of awards https://blog.chapeldown.com/ch...
For the second year running we are delighted to have been awarded 2 Platinum medals at the Decanter World Wine Awards.
Out of 16,518 wines judged from 56 countries, just 178 from 24 countries were awarded a Platinum medal. First deemed ‘Gold’ in the first weeks of judging, these wines were re-tasted by panels made up of Regional and Co-Chairs, awarding Platinum medals to the best wines.
As you say with share valuation DYOR - we don't all come up with the same conclusion from the same data !
however, Without wanting to sound too flippant, where those awards : "best English wine" with an entrants list of 1?
exaggerated for effect, but you get what I'm suggesting i hope.
16,518 wines judged from 56 countries
Being proud of what we can do is not fashionable, but I think we can can hold our head up here.
I've never had any problem with the quality of the better British wines, but in general you pay more for a similar quality that you do from many other countries. A lot of that is down to climate, and the ability to produce good wines on a regular basis. Of course, that may well be changing with global warming and incerasing expericence.
Winemaking? An old saying: ''How to make a small fortune running a vineyard?...start with a big fortune'' ;-)
I am happy to say that I very much enjoy many of the £CDGP wines, not all, but they cater to number of different preferences. The roster of awards also shows that they are being taken more seriously in the wine world. As a holder of over 2000 shares I get to receive a significant discount to the retail price. I am long past the point where the discounts have paid for all of my still very modest shareholding! Shareholder benefits are usually not a consideration when buying but this one very much works for me.
The beer and cider business would I believe have worked too, but for the pandemic. It’s original rationale was to provide a steadier source of cash flow to a wine business that had modest acreage and size to support the “down” years of crop failure. But there have been several years now of excellent harvests, and with greatly increased acreage combined with increased stocking to cover the down years, the wine business can probably now prosper on its own. But getting bigger is still a more reliable way to go and today’s fund raising will ensure that they can put the exit cost of the beer venture behind them while continuing to expand.
While I wait for them to grow the share price I can enjoy sipping a fine glass of sparkling wine.
Paul,
I have also been to the restaurant, it was very good. Although it was a few years ago now i remember we had a bottle of their Flint, which i enjoyed, however if Chapel Down relied on me for revenue they would have closed years ago.
Richard
Re Chapel Down (OFEX:CDGP) Jancis Robinson has generally been supportive, eg saying in 2019
“I am delighted for the success of British wine-makers, Chapel Down in the USA. Their award winning Three Graces has a good balance, is well made, and overall a very good effort; It’s no surprise that it won the Chairman’s trophy. Chapel Down are showing no doubt that the quality of the wine produced from vineyards in England is better than it has ever been.”
I wouldn’t ask her about small cap account numbers but I will always take her word on wines.
Yes, I thought Chapeldown wines were overpriced, compared to overseas wines. Wasn’t impressed enough to buy again.
I have been a shareholder for many years and enjoy the shareholder discount on wines. the Fizz is excellent and in my view better than the cheaper champagne brands so with the shareholder discount is Good value.
I agree that the still and red wines are mediocre in my view. As for the company this is all about building a brand and they have some real heavyweights on the board and as shareholders. I have enjoyed the journey so far and think there is further to go.
regards
mark.
"I’m just hoping that POLX isn’t BOLX" Paul, you made me spill my coffee... this is the content I'm here for!
Bloomsbury Publishing (LON:BMY) has issued an RNS Reach this morning announcing a presentation to investors on 14/6. You can find it here:
https://www.londonstockexchange.com/news-article/BMY/investor-results-presentation/15004039
or here:
https://investegate.co.uk/bloomsburypublishing--bmy-/rns/investor-results-presentation/202106040700047577A/
all you will find on Stocko is "This news story has no text". Why?
I used to own Spaceandpeople (LON:SAL) but sold out recently at lower levels than now. Reading today’s statement what struck me was the lack of caveats around the Going Concern statement - which (if directors and auditors are correct in their assessment) is reassuring for a company whose share price implies a high risk of bankruptcy. I am definitely questioning my wisdom in selling out previously.
Second Paul on the NHS app. Link to it on Apple App Store:
https://apps.apple.com/gb/app/...
Angle (LON:AGL) a world-leading liquid biopsy company, confirms that it has completed the work required to answer questions raised by FDA in its Additional Information Request and that a comprehensive response has been submitted to FDA as planned
You got there before me Jim McLad. Just to put a bit more meat on the bones, here is my bit.
Just a reminder for Angle (LON:AGL) fans, after perhaps some profit taking by some trading the stock yesterday.
‘The company confirms today that it has completed the work required to answer questions raised by FDA in its Additional Information Request and that a comprehensive response has been submitted to FDA as planned.’
On the 29th April, Finncap had a note out raising their price target to 165p pre FDA rising to ‘at least 220p on receiving FDA clearance’.
The company adds ‘In line with industry best practice ANGLE does not intend to provide any further updates on communication with FDA regarding the submission whilst the regulatory process is as expected. ANGLE continues to anticipate a regulatory decision from FDA during H2 CY 2021’.
Any views on Creo Medical (LON:CREO)?
Horrendous
Good morning, Bluesky. What is? The weather? We arent mind readers?
ridavies,
No mine reading required. Creo Medical (LON:CREO) results
BSV
Jubilee Metals (LON:JLP) has even more to offer. Yesterday + 255kt of tailings; today +944kt of tailings. What are they going to report on Monday? I can hardly wait!
The price Jubilee Metals (LON:JLP) are paying for access to the 944kt of tailings is linked to the PGM spot price at the start of each month which limits their upside potential / downside risk.
My morning smallcap tweet:
GYG (LON:GYG) Supply@Me Capital (LON:SYME) Sportech (LON:SPO) Tungsten (LON:TUNG) VR Education Holdings (LON:VRE) Manx Financial (LON:MFX) Spaceandpeople (LON:SAL)
GYG (GYG) PUSU offer deadline extended to 2 July. [SP=85.89 Cap=40m]
Supply@ME Capital (SYME) delays FY20 accounts pending new funding. Going concern a concern is it? [SP=0.42 Cap=144m]. I'm short.
Sportech (SPO) proposes move to AIM listing. [SP=29 Cap=55m]
Tungsten (TUNG) guides FY(Apr) rev (excl wound down Tungsten Network Finance) down 1% but up 1% at const FX. Adj EBITDA in line. "For March and April FY21 the combined transaction volumes increased by 9% versus the same period in FY20. This trajectory has continued into FY22." [SP=32.01 Cap=40m]
VR Education (VRE) new clients and Facebook has renewed its enterprise account and doubled the number of user licenses. No £££. [SP=16.5 Cap=43m]
Manx Financial (MFX) FCA approval to enter SME debt mgmt mkt "on behalf of those lenders who do not wish to manage the process for themselves." [SP=7.8 Cap=9m]
SpaceandPeople (SAL) FY(Dec). No current trading figs. States wrong FY at top. [SP=14.01 Cap=3m]