Small Cap Value Report (Fri 4 Nov 2022) - DFS, NWOR, RCH, PMP, FOUR

Good morning from Paul!
Today's report is now finished, thank you as always for tuning in, and adding your comments, which remain of a very high standard & tone - not always difficult in a bear market, when everyone's suffering. The next thrilling instalment of my podcast will go up tomorrow, summarising this week's SCVRs! Have a lovely weekend everyone, we survived another week!
Agenda
CEO interviews - I've done two this week!
Cerillion (LON:CER) - audio is here, written summary is here. A very good company, shares have multibagged, and the CEO explains why performance has soared in the last 2 years. Shares are expensive, but for good reason it seems.
UP Global Sourcing Holdings (LON:UPGS) - audio is here, written summary is here. This one is particularly interesting for wider read-across re supply chains. With some surprising revelations, which could be quite bullish for seeing inflation come down, and possibly some shares doing better than we might think, as supply chains normalise.
Moving on to today's news -
DFS Furniture (LON:DFS) - as you would expect for a furniture retailer, it's seeing more difficult conditions this year. Although today's update says the last 2 months have improved from a weak spring/summer. It's too early to call that a trend though. Profit guidance is for the middle of its published range. H2 weighting expected in FY 6/2023. Share buybacks funded by bank debt continue, which is madness given the macro picture. It remains uninvestable to me, due to the terrible balance sheet, so I see this share as high risk in the current environment. If I'm going to hold consumer-facing stocks through this recession, they need to have bulletproof balance sheets. And some might reasonably ask, why hold them at all?
National World (LON:NWOR) and Reach (LON:RCH) - [no section below] as subscribers have commented below, a bizarre situation emerged here last night, where small newspaper group National World (formed from the wreckage of Johnston Press) with its market cap of £54m, has announced it is considering launching a takeover bid for large newspaper group Reach, market cap £328m.
Clearly that doesn’t make sense, unless NWOR can explain how it intends to fund such a deal. If it’s a cash deal, then where is the cash going to come from? A huge equity raise, and/or debt? NWOR does have heavyweight, experienced management, so presumably they wouldn’t have made an announcement unless they’ve lined up some funding?
There’s also the issue of RCH’s gigantic pension schemes. Presumably the trustees would need to be onside, to sign off a takeover, and why would they do that, when the status quo is working fine, with RCH’s still prodigious cashflows servicing the pension schemes cashflow requirements. Hence at this stage, it all looks a bit far-fetched to me, but I’ll watch developments. [no section below]
Portmeirion (LON:PMP) - many thanks to eagle-eyed subscriber illiswilgig, who spotted an in line with expectations trading update buried within an RNS yesterday about a design partnership. I think this is reassuring, and PMP shares strike me as good value now. Thumbs up from me. Whilst obviously conscious that we seem to be entering a recession, so 2023 could be a tougher year.
4imprint (LON:FOUR) [no section below] - I flagged up this company's strong performance here in August, when some simple calculations showed that it was probably heading to smash existing forecasts. Sure enough, a strong update today has brought more broker upgrades. This company is just so impressive, with an amazing multi-bagging long term track record. The latest upgrade (it reports in US dollars) becomes 217p in sterling, so at 3,820p/share, a PER of 17.6 doesn't look expensive. Providing of course there's not a deep or extended recession in its core US market - there's always the risk that we might be buying at peak earnings. But for long-term holders, prepared to ignore short term considerations, this share looks a lovely thing to hold forever maybe.
Paul’s Section:
DFS Furniture (LON:DFS)
129p (up 4% at 08:48)
Market cap £311m
DFS Furniture PLC ("the Company" or "the Group"), provides an update on trading in advance of its Annual General Meeting later today.
The current financial year is FY 6/2023.
This is the story so far -
5 July 2022 - CFO leaving, but sounded amicable. Trading update (my review here) sounded upbeat, with FY 6/2022 results set to be in the “upper half of the range” of forecasts. Supply chain easing.
15 Sept 2022 - Preliminary results (I reviewed here), as expected (profit of £60.3m, well down on LY £109.2m). Demand “softened markedly” from April to Sept 2022. Profit guidance for FY 6/2023 provided £20-54m range. High balance sheet risk, with negative NTAV of £(265)m, bank debt large & rising, and being used to fund a reckless share buyback. So uninvestable to me.
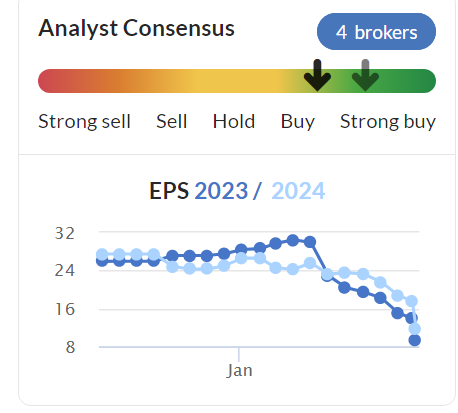
Note that in recent months, brokers have been deeply slashing earnings forecasts, as I would expect in a consumer downturn -
.
Today’s update
Very clear as usual (DFS stands out for giving really transparent profit guidance, I wish the same could be said of most other companies) -
Since early September we have observed a more positive trend, with Group order volumes growing relative to FY22 and also relative to the pre pandemic FY19 financial year. We have also seen continued evidence of positive market share gains from the latest Barclays / CACI market data. Our overall performance is in line with our mid case scenario (c.£36m PBT) for the full year. We would expect profits to be weighted towards the second half given the order intake profile we have seen year to date, our made to order business model and revenue being recognised on the delivery of orders to customers.
Whilst the macroeconomic outlook is uncertain and inflationary pressures remain high, we remain focussed on executing our strategy to lead furniture retailing in the digital age. Our business has proven to be resilient, and given our inherent strengths, we are well positioned to maintain our trend of market share gains across the economic cycle.
That’s not too bad, but remember forecasts have already been slashed.
I don’t know if we can call better order intake in Sept & Oct a “trend”. Given the macro picture, it could just be a bit of a bounce from poor trading over the summer?
H2 weighting for profit - suggests that interim results are probably going to look weak, so I wouldn’t want to be holding when those are published.
What’s missing from this update - I’d like more detail on the backlog of orders. Remember that supply chain problems meant delivery times extended for furniture retailers last year, which flattered their cash balances temporarily. Also, if they’re now catching up with deliveries, then that would flatter performance for a while, meaning that we could be seeing a time lag before lower orders translate into lower revenues.
Also we’re not told what the liquidity position is. DFS was getting near the top of its overdraft facility when last reported.
Share buybacks - this madness is continuing, funded by bank borrowings.
My opinion - I wouldn’t touch this share, given the terrible, geared balance sheet. Pity, as it’s quite a good business. Also, as mentioned by Andy Gossage of UP Global Sourcing Holdings (LON:UPGS) in my interview yesterday (transcript here, see point 7), freight rates from the Far East are plummeting, which should be a big benefit for furniture vendors.
Given the risks, I think the market cap looks way too high still. There’s a big risk that divis & buybacks might have to stop, due to the impending recession, and it could even be forced to raise fresh equity to prop up its extremely weak balance sheet. I cannot understand why the market just ignores these risks.
The Chairman is leaving today (previously announced we’re told), and the CFO left for a better job at B&M European Value Retail SA (LON:BME) earlier this year. Maybe they can see the same financial storm clouds gathering that I’ve been warning about for a long time here?
It will be interesting to see what happens with insolvent MADE.com - DFS must be one of the front-runners to grab the brand from the administrator, probably for not much money, but that depends who else is interested.
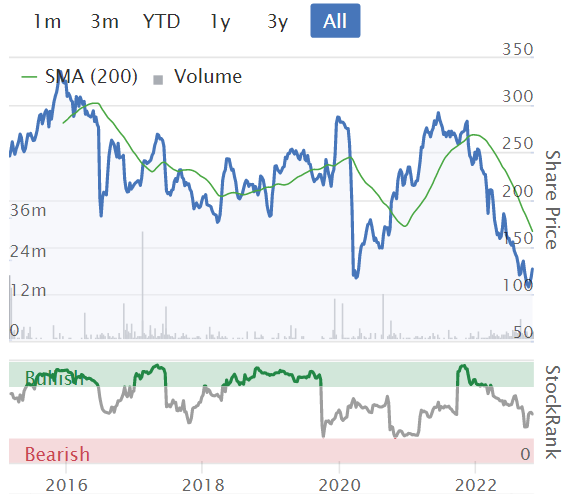
There is a recorded webinar from 26 Sept 2022 on InvestorMeetCompany, which I'll watch later to see if there's anything I've missed.
.
Portmeirion (LON:PMP)
310p
Market cap £43m
Many thanks to one of our stalwart subscribers here, illiswilgig, who spotted a trading update buried in an RNS yesterday from PMP about a design partnership. I’m ashamed to admit that I briefly started reading the same announcement when it came through on my email, but quickly dismissed it as not being of interest. Just shows, we should always read the whole announcement to the end, in case there’s something buried in it!
This really shouldn’t happen. People who write RNSs should always include “Trading Update” somewhere in the title, even if the main purpose of the update is something else.
Anyway, this is what PMP said yesterday -
As we continue through our key seasonal trading period, Group sales remain robust and further to our interim announcement on 15 September 2022 trading for the months of September and October have been in line with management expectations.
That’s good because H2 is the main period when most of every year’s profits are made. So there’s now a much stronger likelihood that PMP should meet (lowered in Sept ‘22) forecasts for FY 12/2022.
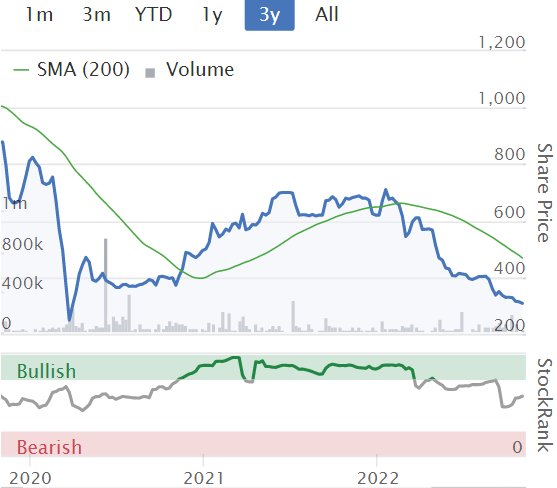
Valuation - both Panmures & Singers left their forecasts unchanged this week, in update notes (thanks for those). The average is 44.8p, the same as Stockopedia’s 44.9p broker consensus figure. At 310p per share, that means a FY 12/2022 PER of only 6.9.
That seems a very gloomy valuation, but perhaps people are reluctant to buy the shares, since demand could deteriorate if we get this 2-year recession that the Bank of England is cheerfully predicting & helping to cause.
My opinion - I continue to believe that PMP is well-managed, and has a decent strategy, to expand through new products. It’s selling a lot online now, has a strong balance sheet, and energy costs are hedged into Q1 2024, so hopefully things might be improved by then.
I think the current price could be a decent long-term entry point, with the proviso that a bad, and extended recession, could clobber its earnings in 2023. That’s the trouble with almost everything at the moment, isn’t it. Overall then, I'm tempted to start nibbling at this share.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

54 comments
Crestchic
Sone almighty trades just been logged , around 2.7 million GBP at around 252p .
Hard to figure out if these are buys or sells or a combination of both .
That’s about 4% of the company and it is not very liquid so cannot all be sells or buys .
Maybe a couple of institutions are buying or selling .
Hopefully an RNS or two will reveal all early next week.
My money is Harwood will be buying sone of these just can’t see them selling .
Bit weird really it dropped very briefly into the late 240s
Good entry point I think I did add some myself but not those huge trades .
Any guesses ?
A whole lot of FOMO exaggerating market movement today, I suspect. Investors holding defensive cash positions pushing to get back on the boat ... but it's still probably just another bear market rally.
There's probably a lot of sentiment that all the interest rate rise expectations (short term and medium term) has peaked.
However, forecast earnings still haven't been slashed enough. Always lags behind. Plus companies always leave it later than sooner to do profit warnings... and many companies have reporting Q4 coming up, or their seasonal high in Nov-Dec... so while current trading might be already missing market expectations, they might be adopting a wait and see approach of a hail mary. Because who loves to be the CEO or CFO that releases a profit warning, and causes the share price to tank 30%?
Today's strong rally is a dead cat bounce in my view.
Wish I could disagree with you.
Thanks for the UPGS interview Paul - very interesting. I'm a long-term holder of UPGS. They have a fantastic management team led by Simon Showman. What I particularly like is their strategy of buying brands out of administration. As far as I understand it, Salter is the only brand they actually paid more than a nominal price for. Progress, Petra, Beldray and Kleeneze all purchased for virtually nothing and re-launched.
Reach (LON:RCH) of course smaller companies can take over larger companies - the most famous example being RBS's audacious bid for NatWest at the start of the 2000s. Not quite sure how this works - presumably they need investors to come on board to back the management of the smaller company and provide the necessary funding.
Reach (LON:RCH) Do not see it as necessarily a big problem. For investors it is merely a choice of who do you want running the company existing management or Montgomery ? Montgomery knows the business well, not only that that but Vijay is his FD and he is the ex FD of RCH (Though he is resigning ). NWOR would bring some cash and another cash generating business with no pension fund. Could be win win, reduction in overheads and more cash generation to allay any fears over the pension fund deficit, and according to The Times there is a possibility of Gannet being involved too.
Very interesting.
Crestchic
Bit of downward pressure on Crestchic .
Seems to be a consistent seller with low buying .
Plenty available to buy at 254 level (low for last few months ) and hard to sell indicating market has plenty of stock so may drop a bit more .
If this drops into the 240s it’s probably a good entry point for anyone that “missed the boat” think it will bounce of those levels very sharply.
Just a note as it’s one I follow closely
Good Morning
Value Opportunity?
I just realised that the market capitalisation of Bank of Georgia (LON:BGEO) has eased to over £1bn
This is of interest to me as a holder of Georgia Capital (LON:CGEO) as it’s market capitalisation is only £281m
The possible opportunity is that this very well run and prudent private equity company, in terms of it valuations and business growth record (eg see Edison report of May 31st 2022) has a 19.9% holding in Bank of Georgia (LON:BGEO) (ie worth approximately £200m. As of May this represented just 18.2% of Georgia Capital (LON:CGEO) assets. This would appear to suggest that one can buy the remaining 81.8% of assets the company holds for £81m!
I hesitate to use the term mis-pricing, but I’m struggling to find the enormous mistake that I surely must have made in my analysis in making this case. Any illumination would be most welcome.
Update
I posted the above comment under unloved share Georgia Capital (LON:CGEO) a couple of days ago. Since then the Bank of Georgia (LON:BGEO) share price has gone up significantly so that now the relevant valuation for Bank of Georgia (LON:BGEO) is £1.15bn and so Georgia Capital (LON:CGEO) holding of Bank of Georgia (LON:BGEO) is now worth £229m ...this then leaves the remaining assets (which remember in May 2022 were in the region of 80% of the company's assets being priced in at just £52m.
Agree on those points Georgia Capital tends to lag Bank of Georgia .
Both shares do jump around a bit with only a week or so Bank Of Georgia sub £20 .
Spread is also quite large on Georgia capital so it’s more of a long term play and the value will come out .
Not the easiest share to understand and it is relatively unknown .
I raised it about a year ago as a “special situation” and agree with your summation but market doesn’t seem to want to wake up so it’s a tuck away and forget and ”trust your analysis” situation .
Looks well run , and bank of Georgia current valuation is a solid foundation .
Bank of Georgia up another 4% today !
Agreed re not the easiest to understand…and it’s only been around four years since spinning assets out of £BGEO. However it’s recent sale of its water business appears to have proved its model and valuation.
As you say I will just tuck away.
directors of Georgia Capital have been selling recently- you would have to wonder why?
The last director sale was on 15 sept at 7.07 gbp (only 60k of his 774k holding ) , bank of Georgia at this date around 2100
Now Georgia cap 628 and bank Georgia 2380
So this seems to highlight
- director sold 7% ish of his shares at a great price timed that well
Given the 12.5 % decline in Georgia cap and the 10% increase in bank Georgia (assuming it holds) then do the maths looks a good entry point now .
Clearly the non bank of Georgia investments are vulnerable but it’s under half NAV , and the bulk of the NAV is the bank of Georgia .
I’ve topped up a bit today .
I purchased a further 5000 shares yesterday for the same reason. They now hold 20.5% of Bank of Georgia and their NAV is up to 1904p. Aside from Bank of Georgia , their other investments have defensive qualities with good potential
To be precise two Directors have sold a total of 120K shares in Georgia Capital (LON:CGEO) during the last year.
The main seller (100K) still has 750K shares and presumably will get more from remuneration if the company continues to be successful. Overall this does not seem an unreasonable level of sales to me.
Just to add to the valuation mix, Bank of Georgia (LON:BGEO) pays out in the region of £18m dividend pa (approximately 8%) to Georgia Capital (LON:CGEO) at present.
Positive announcement from Sigmaroc (LON:SRC) It has been granted a UK patent for its Alphabloc modular wall system.
"The Alfabloc is an interconnecting precast concrete walling system produced in the UK, Ireland, Benelux and Scandinavia. Each free-standing section can be interlocked to form a continuous wall of heights up to 6 meters. In this way the Alfabloc system was used at for example Heathrow Airport, nuclear facilities and numerous construction and industrial applications."
The more I get to know about Sigmaroc (LON:SRC) the more I become convinced that it is far from a "run of the mill aggregates provider" I attended the evening presentation for retail investors held in London a few weeks ago and was impressed with the innovation and entrepreneurial approach, such as the development and marketing of 'Greenbloc', its low carbon building block which is cement free and offered as an alternative to the ordinary portland cement equivalent. The technology behind 'Greenbloc' is not new, but Sigmaroc (LON:SRC) have invested in developing it and are now starting to reap the benefit.
The recent agreement with ArcelorMittal for the production of 'net zero lime' for use in steel production is a further example of the company's innovative approach
A few further findings from the retail investor presentation, none earth shattering, but all positive in my view:
I hold and added at 40p. I think that once the economic clouds start to lift Sigmaroc (LON:SRC) will prove to be a good investment, but in the meantime, it is a matter of trusting management and remaining patient. It was good to see buying by directors after the recent trading update.
Hopefully my assessment is not misplaced!
Is that the bear market over then ?
Yes truegent IMHO it was over a couple of weeks ago.
I hope you're right !
Paul/Graham.
If possible, could you give your thoughts on the DFS Furniture (LON:DFS) trading statement. They are guiding for PBT of £36m, which is well ahead of the Stockpedia forecast of profit after tax of £18.4m. Even allowing for 25/30% tax , they should be making £25/27m for the year, which is also ahead of the FY24 estimate
I am in SCS (LON:SCS) which I know has the thumbs up from Paul but a view on DFS Furniture (LON:DFS) would be good for a read across.
National World NWOR .
What a surprise and strange position .
It has been my worst investment of the year in terms of performance but I just figured it is illiquid and unloved .
Pretty hard to see it being able to gobble up a company 6 times bigger and it feels an opportunistic albeit ballsy move by David Montgomery who obviously knows reach very well .
At least at a minimum it might increase interest in National world as a share as there are literally only ever a handful of trades a day and on my fag packet it is far too cheap.
Be fascinating to watch this unwind if Montgomery does have a serious tilt at Reach it will be a literal David v Goliath .
Sadly I sold around 30% of my holding right at the bottom of their slide at circa 15p when I made the move to sell all non AiM shares and hold only AIM due to IHT benefit (still hold bulk in pension) . Could have timed that better but it was a general down day when I switched and I redeployed into Belvoir at 190, vertu at 42, Hargreaves at 313 - so out of the crying pan into the frying pan maybe.
I do wonder if Montgomery has seen some large pension surplus that will help fund this, anyway at the moment it is just a bit bizarre that someone can do an RNS saying “we’re thinking about doing something “
Response from Reach (LON:RCH) late last night:
Reach plc ("Reach" or the "Company")
Response to statement by National World plc ("National World")
The Board of Reach notes the announcement by National World that it is considering a possible offer for the entire issued and to be issued share capital of the Company. The Board of Reach confirms that it has not received an approach from National World.
The Board will issue a further statement if and when appropriate. In the meantime, Reach shareholders are strongly advised to take no action.
i really enjoyed the recent discussion and listening to the interview on corporate bonds - it added a lot of value to me as someone who knows next to nothing about bonds. But, did anyone find corporate bonds you can trade in at lower values that looked attractive?! All the ones I come across seem to be traded in £100ks! Sadly my portfolio is "only" in the low £10ks.
Been trying to figure this part out myself recently as I'm thinking of splashing into some bonds and locking in some reasonable rates. I am coming to the conclusion that some EFT bonds might be the best bet where I can spread the risk over many companies. If anyone knows better though I am open to understand more
The one problem with an ETF or Fund is it isn't a bond. In a bond...as long as the co doesn't go bust, you get your money back. 7% might prove to be a disappointing return which you have locked into....but I can live with only making 7%. A bond fund however could do better or worse depending on how far interest rates and bond yields move. To avoid a capital loss you may have to hold until rate expectations and therefore yields fall. You don't have this issue in a bond and can just lock in. The banks are retail friendly...and the prefs which are quoted on London. Getting a list of these isn't so easy... but im looking at Gen Accident... or Aviva...lots of Insurance companies use them.
Yes that is absolutely true. If rates keep rising then you'll probably suffer a capital loss on a bond fund whereas a single bond will mature at par with no ultimate loss. On the other hand, if rates fall over the next few years then bond fund should make strong capital returns as well as the income, so you'll probably do better in a bond fund in that situation.
On the preference shares, these are perfectly good instruments, but don't have the seniority of investment grade bonds so a bit riskier. I personally stick with investment grade bonds to diversify my equity risk.
Would you mind letting us know what bonds you are presently holding?
As mentioned in another post below, I stick with ETFs for investment grade bonds - I mention the 2 I currently hold.
you can (sort of) through a platform called wisealpha.
I have (a small amount of money) with them.
This is what it looks like
I got some of
on the basis that they probably are not going to go under before jan 23 and they are senior secured. (sorry if the pics are a bit small)
Hi Andrew, thought you might want to read this regarding the matalan bond.
https://www.drapersonline.com/...
thanks
It looks like I will now find out what "senior secured" actually means when things go wrong.
I share your pain. I’ve identified a few opportunities in bonds but can’t get HL to add them to their tradeable list. I’ve therefore gone for fixed dividend preference shares instead. Typically paying around 7.5%. I have a list of 17 that are available on HL. Let me know if you want me to publish the list.
Graham, if you wouldn't mind, that would be really useful. Thanks
Here is the list that I have…
Apologies in advance, I use my phone to publish and the tickers don’t produce a link for some reason.
£GACA 7.85%
£SANB 7.68%
£GACB 7.76%
£AV.B 7.48%
£STAB 7.51%
£STAC 7.48%
£RSAB 7.56%
£BWSA 7.29%
£LLPC 7.26%
£AV.A 7.29%
£LLPD 7.38%
£ELLA 6.87%
£NWBD 6.99%
£NTEA 6.61%
£BWRA 6.36%
£BP.B 5.42%
£LLPE 6.47%
Yields shown are based on closing prices in market last night.
These preference shares sit lower in the capital structure than bonds and for most of them payments aren't compulsory.
Thanks Graham, much appreciated.
£GACA looks nice with an ex div 1 Dec @ 4.4p
As others have pointed out, buying individual bonds is nigh on impossible for private investors so I have been buying ETFs - iShares have very broad range of bond ETFs covering pretty much every asset class and region. They also offer currency hedged versions if you don't want FX exposure.
For bonds I am only really interested in highly rated, investment grade in order to provide some ballast against my riskier equity exposure. Nothing wrong with high yield bonds, but they tend to perform like equities so wouldn't give me the diversification I need. As someone pointed out here a couple of days ago, there are some good fixed income investment trusts but these are mainly focused on high yield bonds.
As for bond funds (OEICs) - well I'm really not convinced managers add any value (at least in the highly rated parts of the bond market where I'm interested) so prefer to stick to passive ETFs
In case anyone interested I hold these iShares - LQGH (US corporate bond, GBP hedged) and ISXF (UK corporate bond ex financials). These both provide a nice amount of duration (around 7 years) so means they should get a nice boost if yields start to fall as I expect. Shorter dated bonds are lower risk and are really more like cash but you won't get much benefit from falling yields.
Hi I concur with your thoughts but one thing I have never managed to get to the bottom of with ETF's is that as far as I am aware the don't come under the financial services compensation scheme if they go bust but does anyone know if they fall under a European equivalent ?
The other thing that has become apparent during my research into ETF's is to avoid investing into any that are US domiciled as you could have tax issues if you hold them with the US equivalent of HMRC calling on you.
Regards Andy
No, ETFs are investment vehicles so wouldn't come under the compensation scheme - I guess if you want absolute safety then hold cash in a bank account. On the other point, I've never heard of ETFs being US domiciled - the ones I've looked at tend to be domiciled in Ireland or Luxembourg.
Thanks Bouden no issues with taking risk I just wondered if they fell under an EU equivalent , you are spot on re Ireland and Luxembourg but there are the odd US listed one's link below explains a bit more.
https://en.swissquote.lu/inter...
I think you want short duration. Interest rates are rising which means bond prices fall. The fall is approximately magnified by the duration. Therefore, you want short 1 or 2 year duration. Next year when rates start falling you want long duration.
Longer dated yields can move completely independently of the overnight bank rate - so yes the bank rate is likely to keep rising for now , but longer yields are set by the market and forward looking - they will start to fall in anticipation of future rate cuts - so you can easily have a situation where the bank rate rises but long yields fall. Indeed, this is very much what I expect to happen so personally want long duration.
Unless one is buying high yield corporate bonds... why not just stick the cash in a fixed savings account, at 4.5%-5% interesr, with similar risk profile as holding govt gilts? Won't be tradeable of course. But I'd prefer to do that than pay the high bid-ask spread of investment grade corporate bonds even if they're yielding 6-8% over 5 years.
Because with bonds you can make a capital gain if yields fall, on top of the income. Plus if you invest in investment grade corporate bonds, you get an extra 2-3% credit spread.
Morgan Advanced Materials (LON:MGAM) solid update from this manufacturer of bearings, ceramics and carbons many of which are being used in renewables so a decent growth market IMHO.
Group revenue up 10.5% To end of Q3, with full year expected to be 7-9% above previous guidance.
Stocko matrix likes this company sitting on a low P.E. I think in the medium term with the 4.5% divi, it's a decent buy and hold share at todays depressed S.P.
(I hold)
One thing that I find encouraging about Morgan Advanced Materials is that the proportion of their sales to UK customers is low, at from fallible memory less than 10%, with the rest distributed over many countries. If our BoE governor is to be believed in terms of our recession longevity that is reassuring.
Morgan Advanced Materials (LON:MGAM) follow Weir (LON:WEIR) earlier this week trading well. All these stocks seem quite we'll placed to me...esp if China relaxes from covid zero. Morgan Advanced Materials (LON:MGAM) is pretty cheap, not the highest quality but trading well. I liked the look of Weir (LON:WEIR) mainly because it feeds directly into the mining space at good margins and the maintenance business is excellent. It comes at quite a premium to say Morgan though. Obviously power rationing with European customers is something to take into consideration this winter but as a group Industrials are showing form. See article written by Roland a few days ago.
Interesting what you about the China relaxing Covid zero policy, if this happens I do see a decent boost for many companies, but RS (LON:RS1) I know not a small cap, would get a decent boost, and bought yesterday on the dip likely due to the RNS ON a leave of absence for the CEO. RS appears to be a very well run company, with a solid update yesterday, and anyone who has used them knows the products are excellent.
Of course recession fears are the problem, but I'm trying to drip feed into the market over the next year and look beyond the immediate tails of woe. Trying to pick out the companies which will still be good quality then, is the problem, so for me a track record of growth in revenue, profits and a decent margin are the key, along with a dividend to help temper the inevitable short term losses.
I was flummoxed for a minute not realising Electros had changed its name. I haven't looked at it for some time, a little all things to all men for me at the moment. I think I want exposure to companies supporting drilling for the black stuff or these grubby metals we are going to need so much of which might be picking up as china open despite obvious gloom from BOE yesterday.
For what's its worth I thought Bailey was talking his own book and everyone lapped it up. Paint a gloomy picture and hopefully the bond market lets us off with lower yields ....and less rate rises. Maybe I'm seeing stuff that isn't there but .... u never know.
I partly agree but partly...
...business activity is partly based on confidence in the future.
If the future is bright and sunny, you tend to got out and have fun and spend
If the future is dark and gloomy, you tend to stay in and huddle over a cup of tea
Mr Bailey has forecast dark and gloomy. People will change their behavior based on his statements. Unlike the weather, that change in behavior can cause a reduction in economic activity all by itself. If this was a time where there was a lot of irrational exuberance, I would understand he is acting as the adult in the room.
But I have not noticed much sunny optimism recently, so currently think Mr Bailey is just a bit tone-deaf on public comms.