Small Cap Value Report (Fri 4 Oct 2019) - GRG, SCS

Hi, it's Paul here, with Friday's SCVR.
I'm starting early (writing this on Thurs evening) because am meeting my stockbroker for a boozy lunch in the city on Friday. Hence I want to get this out of the way, so as not to short-change my readers here.
ZANE afternoon tea at Claridges
Before we start though, I just wanted to report back about my charity auction for afternoon tea with me at Claridges last week.
Ken & Cheryl (readers here for several years) very kindly sent me a gift, of a voucher for afternoon tea for two at Claridges. I thought let's raise a bit of money for the Zimbabwe charity that I visited earlier this year, ZANE. So I invited bids for subscribers here to join me.
A subscriber here, called Sanjay, submitted the highest bid, and we met up to enjoy afternoon tea & had a terrific discussion about shares, property, economics, you name it! It was a really enjoyable meet up - he set the agenda. We're meeting up again to have another session, on balance sheets, which I'm happy to do in return for another generous donation to ZANE from Sanjay.
We now have quite a few Stockopedia subscribers who have engaged with ZANE, and are making regular donations. I'm so pleased about that. No matter how bad my portfolio gets, I always put it into the perspective of the terrible poverty I saw in Zimbabwe earlier this year. People there somehow managed to just get on with life, despite living in often appalling conditions.
I know that many subscribers already have your own charities that you generously support. My trip to Zimbabwe (at my own expense) to see ZANE's activities for myself, and meet virtually all its highly dedicated team there, means that I've done the operational due diligence for you on ZANE, much in the same way that I try to assist you with due diligence on shares, in these reports. Therefore, subscribers can donate to ZANE knowing that its work really is saving & improving lives on a day-to-day basis. I can't stop thinking about my trip to Zimbabwe, it's on my mind all the time, hence why I'm trying to raise bits & bobs for ZANE whenever I can.
Consumer confidence
Every now and then, I check out the GFK consumer confidence stats. The latest report for Sept 2019 is here.
As you can see below, people actually feel fine about their personal finances, and for big ticket purchases. But there's a crushingly negative perception on the overall economic outlook - hardly surprising when we've been told on a daily basis by news outlets, for the last 3 years, that Brexit will make the roof fall in.
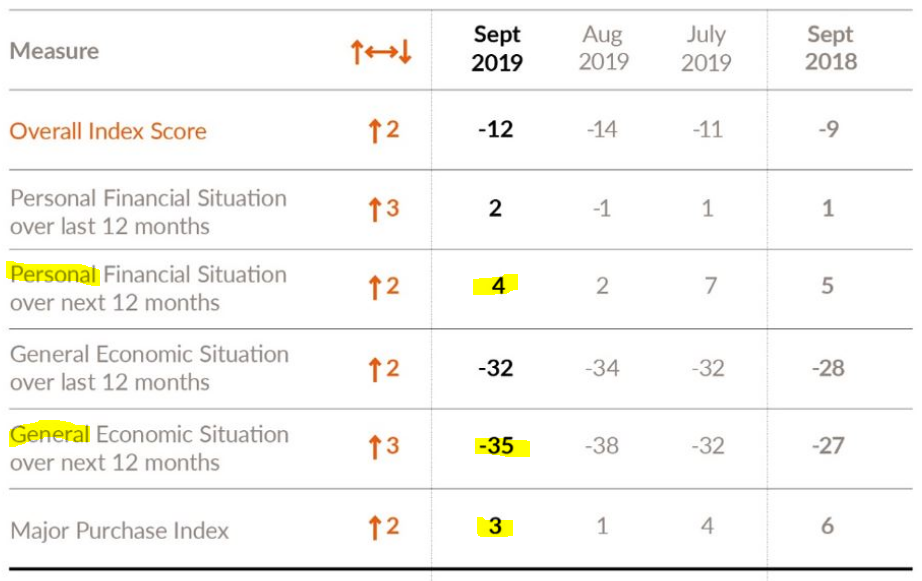
The figures haven't changed much from a year ago.
We've got full employment, and wages are rising well above inflation. So if you take the Brexit factor out of the equation, things would be pretty good.
The EU has a history of doing last minute compromise deals. So if the same thing happens with Brexit this month, then an optimist might see the possibility of a big stock market rally in bombed out shares, if/when some kind of fudge is agreed near the end of October. Who knows? My hunch is that this is the most likely outcome, hence why I remain invested in cheap small caps.
Greggs (LON:GRG)
Is still delivering fantastic LFL sales growth, as its recent trading update shows;
· Company-managed shop like-for-like sales up 7.4% for the 13 weeks to 28 September 2019
· Total sales for the nine months to 28 September 2019 up 13.9% and company-managed shop like-for-like sales up 9.4%
Despite a bit of a slowdown in the growth rate, it's still astonishingly good. Evidence that High Streets are still alive & kicking, for shops that offer a decent product, at an attractive price?
The PER of 20 looks challenging though, despite the strong growth.
I wouldn't pay a PER of 20 for anything operating in the High Street.
SCS (LON:SCS)
Share price: 221p
No. shares: 40.0m
Market cap: £88.4m
ScS, one of the UK's largest retailers of upholstered furniture and floorings, is pleased to announce its Preliminary Results for the 52 weeks ended 27 July 2019.
This lower-priced retailer of sofas has been an unlikely survivor of the carnage in the retail sector in recent years.
There's a lack of broker coverage available to me, but the reported (adjusted) EPS seems to have come in ahead of expectations;
Underlying earnings per share of 30.3p (2018: 26.8p), an increase of 13.1%
That's a PER of only 7.3 - although the question arises, why would it be higher, given the state of everything?
Current trading - this is quite bad;
Whilst it is still very early in the new financial year, the Group has had a more challenging start to FY20, with like-for-like order intake falling 7.6% for the period from 28 July 2019 to 29 September 2019. On a two year basis, like-for-like order intake was down 3.0%. The period has been impacted by the record temperatures seen over the key August bank holiday weekend and the increased political and economic uncertainty that the UK is currently facing.
Balance sheet & cashflow statement - both look excellent. Therefore I see no solvency risk here at all. It's tremendously stronger financially than larger competitor DFS.
Going concern note - is robust. SCS learned the hard way that when credit dries up, it can be catastrophic (it went bust in the last recession). However, the balance sheet now is loaded with cash, so this should not be an issue, even in another recession.
Going concern
The Group generates strong cash flows, reflecting the negative working capital requirements of the business model. In addition, the Group has a committed £12.0m revolving credit facility in place.
The Group's forecasts and projections show that the Group has adequate resources to continue in operational existence for the foreseeable future.
Having considered the Group's current trading and cash flow generation including severe but plausible stress testing scenarios, the Directors have concluded that it is appropriate to prepare the Group Financial statements on a going concern basis.
The comment about "severe but plausible stress testing scenarios" is important, and is a much stronger statement than the one from Ted Baker yesterday.
My opinion - it's cheap, it pays a great divi, and has a strong balance sheet.
It's your call, on whether you want to invest in something like this, right now?
Looking at SCS's website, I have to say that the products look tons better than when I last looked. Great value too. This raises the question of whether sofas really are big ticket items any more?
This is irrelevant really, but personally I like to get a good 15 years out of things like sofas. The old fashioned style of a 3-piece suite (a settee and 2 arm chairs) seems to have given way to something more flexible. So when I last updated my settees in about 2002, I picked 2 different sized settees, and a large pouffe (no laughter at the back please!) for about £1,750. That ensemble could probably be replaced now, for about half the price, from ScS, yet our incomes have risen quite a lot since 2002, making settees almost disposable for people who let children leap all over them, and make a mess with food droppings (and pets).
Bearing this in mind, I'm warming to ScS, as a company which might be more recession-proof than I imagined?
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

20 comments
Really enjoyed having a previous afternoon tea in Claridges. Quality of food and service very good. Can't say the same thing about the Ritz. My wife thought this would be a good photo opportunity and experience. Had to wear tie (borrowed from hotel). Served by a sullen waiter. Choice of cakes , I thought average. Cost was ridiculous.
Long time ago also had afternoon tea at The Lanesborough Hotel. Was excellent. Don't know what its like now.
Try the Tea House Theatre in Vauxhall Pleasure Gardens.
All I can say is that Cheryl & Ken, who paid for afternoon tea at Claridges, are such lovely people! As indeed is Sanjay, who happily donated to ZANE, to spend 2 hours with me, talking about shares, what a nutter LOL!!! :-D
Re SCS (LON:SCS) ...
I like it a lot. Really well run business. I sold on the prelims though after owning for 3 years. Nice return (appreciation and dividends) but should have been better however the management are making missteps in terms of capital use and showing a kind strategic passivity...waiting for Godot...
https://www.stockopedia.com/content/scs-waiting-for-godot-la-z-boy-edit-518151/
IMO it'll probably be okay from here and if they communicate some strategic clarity re cash pile, 50% ownership by PE and future direction it will head up above 300p...
...but the time for greater clarity was at least 12 months ago and the exit from House of Fraser for the last call for timeliness. Today there is no sign they have clear plan other than to spruce up stores and continue to be smart sofa traders. This is passive in a ruthless world and so is much higher risk than it appears given SCS doesn't have a clear top line growth path...but is a great business making loads of cash and can really take charge of its own bottom-line if it chooses to. As I say in my linked note I think the experienced CEO is scarred from 2008 experience so just wants to play safe, have bullet proof balance sheet and look to play only once things have gone through a verifiable trauma....in way he wants to do what the Sun Partners private equity did with him.
Strategically, it looks like they flirted with a new path to posher customer base with the sofa.com interest (they stepped aside and left Magic Mike to pick it up). It fits in that it wouldn't have cannibalised their current business (just like HoF didn't)...but HoF was really low capital commitment whereas sofa.com would be relatively intensive with both cash and management time going on it. Is it the right thing to do?
The sales stutter is worrying. Flooring is rather unexplained....yet they are investing more...is that to hold ground or make more ground. Note, it has been a great success over the last 5 years but perhaps against competitors that have been going nowhere fast. New store opens have really slowed down (I love their discipline on how and where they will open new). They acknowledge they have some old poorly located stores that don't work well but can only close when lease ends or they can pass to someone else (Reading is recent example...I went in and was dreadful and not surprised it has closed)...
There's a danger that sales hit a rough patch whereby external and internal factors push against them. If their H1 2020 results show a revenue decline somewhere near their 2 month 7% LFL decline the price will fall precipitously ...say 50p from here.
I love SCS as a trading business but I think they've put themselves in danger of the doghouse by not paying attention to capital management from shareholder perspective
(As a topical aside management say they experienced a Brexit vote bounce with their customer base (Brexit voters outside the south east to be simplistic)...are we seeing a Brexit stasis hiatus? Probably not, just like the symmetry.)
Paul
In the short term, whether there’s a Brexit transition deal matters quite a lot to share prices, so your comment that the EU has a history of last minute compromise is important. Can you think of some examples where this has and hasn’t happened?
... so your comment that the EU has a history of last minute compromise is important. Can you think of some examples where this has and hasn’t happened?
EU compromise tends to happen on internal negotiations, as with Greece, where failure puts the European project at risk. Tends not to happen in external negotiations where the EU is nearly always the bigger party and where they take the view that they can walk away in the knowledge the other party will come back to the table.
Here - who knows?
timarr
I agree - the EU is historically unwilling to compromise on matters of principle - as seen by the EU secretariat. Essentially because it has to hold together 27 or however many it is diverse states and the only mechanism for doing so is by invoking principles such as the integrity of the single market. Also, current proposals get it about 99% of what it wants anyway. So I don't see compromise by the EU riding to the rescue of any long positions on the market (such as mine).
To my mind any compromise, if there is one, has to come from some of the other parties involved. The DUP has compromised, but the Irish government has not, and nor have the group of rebel Tories. Both these have to retreat a bit if there is to be any agreement, and neither has any incentive to do so. On the face of it the current balance of forces will force the government to request yet another extension, which the EU will grant again, and which is almost certainly the worst of all possible worlds for everyone.
I also largely agree though I would think the worst of all possible worlds would be to leave with no agreement (though its a near thing). This is of course a strong possibility surely ? A further extension would be not possible with the current government, I would imagine. It does seem to me that the Tories have nowhere to go and will be blamed in any outcome. This is important for investors because it increases ( though not ensures given the febrile nature of UK politics) the likelihood of a left wing government whereas to get post Brexit success the UK needs to move economically and possibly socially to the right.
I think it's pretty clear that the EU thinks it has done enough compromising. May and the EU worked out a deal over 2+ years, which was very difficult and required compromise on both sides. Not a great deal, but then there isn't an an obvious one. Johnson started his negotiations by essentially telling the EU that the thing they had negotiated and which they see as critical to both peace and the economy on the island of Ireland, had to be scrapped. His current (half released) plan apart from being a mess, requires the whole issue to be revisted every 4 years with an effective veto from the DUP. That's not a deal that Ireland or the EU are likely to accept, and you have to ask if Johnson really wants them to.
A reply on Brexit mostly from investment perspective.
Best guess is another extension and then General Election with high chance of big Tory majority. Then likelihood of a no deal outcome.
BUT commentators seem to be missing the obvious: there’s no such thing as a no deal outcome. Whether the UK leaves with or without a deal, either way the next stage is the same. I.e trade and other negotiations probably over several years. Negotiations to go better, with European negotiators in better mind frame (and U.K. focus share prices to do better) if the UK doesn’t crash out?
UK market has way underperformed since Brexit vote. So Brexit perhaps largely priced in to UK focus shares. Some big FTSE shares are on very low PEs and unusually big dividends with some of those Companies still confident they can increase these dividends. Upside for these could be large post the U.K. leaving, but if £ strengthens, dollar earners to do less well. And that upside hope could be knocked for 6 by bigger problems.
e.g China/US trade war, along with clear signs of Worldwide slowdown? And worst case scenario a repeat of 2008 with debt so high and limited weapons left to tackle it.
Completely irrelevant but worth a mention. Perhaps the vote in 2016 vote would have gone the other way but for one of the many wrong scare stories. When George Osborne wrongly warned that house prices would crash, I’ve wondered ever since how many younger voters so keen to get on the housing ladder, decided to switch from remain to out?
If you look at Howard Marks on YouTube he references the creeping inevitability of rising interest rates, and that they need to rise in order for the FED to have any leverage when and if the next downturn comes.
Compare and contrast with a President who actively promotes a low interest environment. Of course he has been kiboshed before by higher interest rates (when he couldn't service his commercial debt) , and dare we say it, perhaps by his poor business ventures, and he prefers loose money.
But his inventiveness turned to tariffs, as a trade weapon, and with the world trade perhaps slowing down as a consequence, he has got an environment where the FED decides not to increment interest rates.
Might it be that perversely what he desires will be his undoing, economically?
Morning Paul
Thanks for the commentary on SCS (LON:SCS) . I am a holder and continue to hold.
A few additional things I picked up from the investor's call might be of interest to you or other holders:
EBITDA is £20m.
50% of customers pay by cash/credit card. Need to pay a deposit, then finalise payment 8 weeks later, a few days before delivery.
50% take finance option and SCS is paid this from financing company 2 days after customer receives order.
Supplier is paid, on average, 45 days after delivery (the end of the month after delivery).
There are loads of other little gems in the presentation published a few days ago (link here for any interested).
Cautiously optimistic holder.
A
I might have thought £ZTF's warning yesterday could be relevant. If sales of foam rubber in Europe have fallen badly, how much longer before that happens here? I had thought furniture makers such as SCS (LON:SCS) were one of the big markets for their foam rubber. I don't hold, but think it is one to watch.
Zotefoams (LON:ZTF) 's products are used in a wide range of applications, but to the best of my knowledge I don't think soft furnishing is one of those applications so I would be cautious to assume any read across at all from Zotefoams (LON:ZTF) to SCS (LON:SCS) at all.
That said Zotefoam's slow down I would say is symptomatic of the wider economy anyway, although it would certainly be interesting to have a better understanding of which sectors in particular have given the biggest impact.
Thank you Gromley re Zotefoams (LON:ZTF) markets - note to myself, do more research.
It wasn't unreasonable to speculate ST (and to be fair, it took me a while to understand the scope of what Zotefoams (LON:ZTF) does & I'm not sure I could describe it in a single sentence).
It is one of the qualities I really like about the Stocko community that people will offer up thoughts that might be really useful or might be wide of the mark and can be corrected in a (usually) civilised fashion.
If everyone was to only post when they were sure they are correct then we'd miss out only a host of useful stuff I think.
Gromley,
Hats off to you, for your excellent contributions this week (and over a long time before that). You and many other subscribers here really add considerable value.
It's a team sport, this investing business.
The market has really knocked the stuffing out of me in the last 18 months. I enjoy analysing results & trading updates, it's like trying to do a puzzle. However, I've really lost my confidence, and feel that I'm not at all good at managing a portfolio.
So think I'll try to stick to analysis of balance sheets & cashflows, and hopefully add some useful commentary.
Regards, Paul.
Hi Paul
I don't think you have ever positioned yourself as a defensive investor. The small cap tide has definitely turned against us all for the time being, so sitting on the sidelines doing your analysis seems a very sensible strategy.
So how about congratulating yourself on cutting your cloth appropriately, for the moment. Opportunities will come along and you will spot them.
Jon
This is a really interesting and honest admission Paul. The thing is I doubt any of us have had a perfect portfolio and all of us invest based on bias, preference and interests. I've had some stocks go completely belly up, and some have been rocket ships. The great thing is it all adds to the experience and understanding we have of the marketplace and our own measures for selecting equities, bonds, funds, etc.
The great thing here at Stockopedia is the information and the community add yet more knowledge, insight & support, which in the long run will help make us better investors. So chin up, lick those wounds and back in the game! (and the analysis of balance sheets and cashflows is super useful - thanks)
They serve tea in wine glasses at Claridge's do they?