Small Cap Value Report (Fri 4 Sept 2020) - ZEG, SQZ, REDD, RNWH, CTG

Good morning, Jack here.
With news that Apple is now worth more than the entire FTSE 100, perhaps it’s not surprising to see a sharp pullback in US and China tech shares overnight.
Around $150bn has been wiped from the company’s market cap - an entire Unilever up in smoke - down 8%, with Amazon and others down c4%. The fall has to be placed in context - US equity markets have rallied by more than 50% since March as institutional money flowed back into big tech. The correction looks to have spread to China too. It’s not surprising to see some profit taking given equity market performances since March/April.
As we head into Q3 of a frankly astonishing year I’ve been doing some thinking (dangerous, I know).
Mostly I just look for small, well-run companies that can become much bigger in time - but recent events have been so significant that they might trigger some fundamental changes in market dynamics. So I’ve been grappling with slightly more macro considerations.
Maybe a better way of saying it is certain trends are becoming more entrenched: currency debasement; big tech and the High Street demise; increased data and IT support as more people work from home; the possibility of increased fiscal spending, etc.
Out of everything, maybe the most important dynamic is zero/negative interest rate environment monetary policies. QE has exploded recently. Central banks are regularly sending out tidal waves of cash. Everything between the Great Financial Crash up until the start of 2020 looks like child’s play compared to the post-COVID binge witnessed over the past few months.
This is a powerful driver of gold and silver. I want more portfolio exposure to these metals because I personally think spot prices there have further to run. Then there are other long term growth markets. Other metals such as palladium and copper might be worth a look.
Software and IT - Computacenter is hitting all-time highs as business booms. Gaming is a huge and maturing global industry. The UK punches above its weight here with several listed plays, although valuation remains a concern.
And then putting thematic thinking to one side, there are some attractive bottom-up valuations in UK equities. UPGS has trebled since March and so has Gear4Music. There are solid operators out there that still have yet to recover, such as Headlam, covered by Paul yesterday.
Very serious risks remain of course and with close to 0% interest rates there is precious little cushion.
What I don’t know is much greater than what I know - but I continue to believe a strategy of investing in small companies with good management, healthy balance sheets, reasonable valuations, and strong growth prospects will do well in the long term.
Zegona Communications (LON:ZEG)
Share price: 112p (unchanged)
No. shares: 219.0m
Market cap: £245.25m
Zegona Communications (LON:ZEG) is focused on a ‘Buy-Fix-Sell’ strategy within the European Telecomms market. Its first move was the acquisition of Telecable in the Asturias region of Spain, which completed on 14 August 2015. Following the sale of Telecable to Euskaltel on 26 July 2017, Zegona acquired a 15% ownership in Euskaltel. Since then the group has taken its interest in Euskaltel to 21.44%, making it the group’s largest shareholder.
Directors want to turn this into a £1-3bn enterprise value company. Right now though it seems as though ZEG is more an activist investor with one core holding. An unusual state of affairs. I looked at Sigmaroc recently which is running a ‘buy and build’ operation in construction assets. What struck me there is that to hop onto this kind of strategy early on, you need to have a favourable view of the management team.
It seems like the main men at Zegona are Eamonn O’Hare - chairman and CEO, formerly CFO of Virgin Media and the UK division of Tesco, and Robert Samuelson - founder and COO, also formerly of Virgin Media. So, two ex Virgin Media executives.
Perhaps they can cause some damage. I might investigate this team in more detail later - for now, you can see more on this part of ZEG’s investor relations site if it piques your interest.
Another thing stands out with ZEG - given its main source of income is a minority stake in another company, it looks like the group reports its share of this profit using the equity accounting method. This means no revenue (but if you want, you could probably just multiply Euskaltel’s revenue by ZEG’s stake in that company to come up with an indicative figure).

From the group’s 2019 annual report:
In March 2020, Euskaltel published its 2020-2025 Business Plan setting out its key strategic initiatives and its ambition to double the size of its customer base and grow revenues to over €1.2bn and EBITDA to over €470m by 2025. The plan details the actions being taken to grow in its existing core regions, to expand using the Virgin brand to offer high value services to customers across Spain, and to continue to drive operational efficiencies through a single integrated organisation.
ZEG’s 21.3% interest would equate to €255.6m (£228m) of revenue and c€100m (£89m) of EBITDA by 2025. Given ZEG’s £245m market cap, that makes it worth investigating. Spanish telecomms is not a market I know though, and these companies can often come saddled with debt, so I’d personally take a much closer look at Euskaltel too if possible.
Euskaltel (MCE:EKT) is the leading converged telecommunications provider in the North of Spain, with a network covering 2.3 million households. It’s publicly traded and has a market cap of £1.23bn (meaning ZEG shares trade at a slight discount to its 21.3% stake: £245m vs. c£262m) and €668m of revenue. ZEG itself calculates its underlying net asset value to be £1.23 per share.
As expected, EKT has more than its market cap in net debt (c£1.29bn) but has stable cash generation.
That to one side for now, the community’s been buying:

And Zegona itself has been buying back shares, so let’s look at today’s interim results.
Interim results for the six months ended 30 June 2020
There are a lot of words before you start getting to the actual numbers. Some sifting is required…
Record profitability - €91.8 million Q2 EBITDA within EKT's traditional business; record customer growth; limited COVID 19 impact; third consecutive quarter of year-on-year revenue increases.
Ah, Euskaltel operating cash flow up 10% to €50.9m, that feels a little more concrete. The accounting value of the investment appears to be down though, so mixed I'd say.
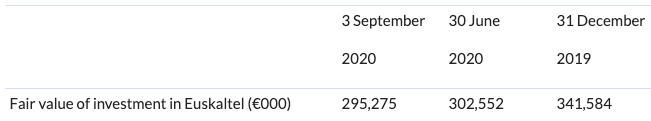
It appears as though ZEG is pushing a turnaround in EKT’s operations which is still at an early stage so there’s just not an awful lot to go on right now.
As for Zegona itself, for the period:
- Profit fell from €33.7m to €7.1m due to a change in the reporting of its EKT investment as a result of its increasing influence
- The fair value of Zegona's investment in Euskaltel was €302.6m at 30 June 2020 (2019: €303.6m).
In terms of outlook:
In addition to supporting Euskaltel's performance improvement through its representation on the Euskaltel board, Zegona continues to see many attractive investment opportunities both in Spain and the wider European TMT market.
There seems to be a punchy management incentive that entitles the team to 15% of the growth in value of Zegona across various calculation periods, ‘provided that ordinary shareholders achieve a 5% Preferred Return in each Calculation Period.’ I would want to look at this more closely. This target was not met in the first calculation period and so no value was received by management.
Conclusion
An interesting company that looks to be helmed by an experienced team that has worked together before. A lot of whether ZEG is a good investment depends on a closer look at Euskaltel.
There is also the accounting - it’s not the standard profile of an operating company. Note 6 to the results seems to have more of a breakdown and I’ll take a closer when I can but for now suffice to say the way the StockRanks and other metrics are set up might not necessarily reflect the changes in value at ZEG, which are primarily driven by its 21.44% stake in a £1.23bn Spanish telecomm business.
That kind of situation can create opportunities though, as there is greater scope for a mismatch between market price and intrinsic valuation. Is that happening here? I’m not sure yet! The company is buying back shares. Directors are also net buyers over the past couple of years.
Still too early to tell for me, though, especially given the declining fair value of investment in EKT and underlying asset value at ZEG.
Serica Energy (LON:SQZ)
Share price: 111.8p (unchanged)
No. shares: 267.6m
Market cap: £297.58m
A very quick update here, just to tell the market that Serica Energy (LON:SQZ) has been offered a new operating licence covering four UK North sea blocks.
I’ve had a quick look at this oil and gas (mainly gas) operator before and it seems like it could be a solid pick. So much here depends on the macro outlook for gas of course but that’s why it’s worth flagging.
Some metals are rallying - will oil and gas rebound at some point too? Or are the dynamics just too different given the ongoing social drive towards a green, renewable future?
I have no exposure to the Oil & Gas sector right now and am curious to hear other people’s views on this part of the market.
I’m quite happy on the sidelines for now but if I had to be picking stocks here to look at more closely, I would probably be looking at SQZ and £JSE. SQZ has a c£100m net cash position but there may be decommissioning liabilities to read up on. Interim results are out next Thursday so that should provide some guidance.
As I said though, happy to sit out for now.
Redde Northgate (LON:REDD)
Share price: 205p (+7.33%)
No. shares: 246m
Market cap: £470m
Venturing out into mid cap territory here but I can see Jonno, Yellowstone et al talking about this modestly valued contrarian play. Redde Northgate (LON:REDD) does have a fair amount of debt but looks cheap on both a PE and EV/EBITDA basis.

There’s also that 8.75% dividend yield - I’ve had a quick check through historic RNS announcements and it seems as though it has yet to make a final decision on whether this payment will go through.
Given the group’s net debt and today’s acquisition (see below), perhaps the divi will be canceled. If you’re ever going to, you might as well now while everyone else is doing it. The vehicle hiring business (sorry, I mean integrated mobility solutions and automotive services provision) is fairly capital intensive:

Net debt has been rising so perhaps cash might be better used paying down some debt.

Mind you the group’s net assets and sales have also been increasing, and then there is the Redde Northgate merger back in February, which results in greater scale and, presumably, synergies.
A combined Redde Northgate might have a few more growth levers at its disposal. Plus if the resulting group can survive a multi-month social lockdown with a net debt balance sheet, that’s probably about as bad as it can get (famous last words?) - so the fact that it is surviving has to go in its favour.
Anyway, the actual news today is the acquisition of certain Nationwide Accident Repair Services assets alongside a trading update, so let’s take a look.
Acquisition of business and assets
Trading
- Sequential month-on-month improvements
- ‘Excellent’ progress in integrating Redde and Northgate since merger
- Strong cash inflows and increased headroom on bank facilities from £234m at end April to £291m at end August
Sounds good to me, particularly for a stock on a forecast FY21 PE of c6.7x.
A quick look at the financial health scores show that even with the net debt, REDD is in a reasonably solid condition:

Liquidity ratios are quite low - but if it’s within historic norms then that’s probably just the business model. If the current ratio is declining over time, then that probably warrants a closer look.
Returns on capital are reasonably healthy for such an asset-heavy operation, and ROE is boosted by the debt, while an operating margin of close to 10% is actually quite good.
Acquisition
Nationwide ‘is the UK’s largest wholly and the largest independent accident repair company in Europe’. It’s also a strategic partner to many UK insurers.
REDD will take on 77 of the 102 bodyshop sites from administrators in an acquisition it expects to be immediately earnings enhancing. It’s paying an initial cash consideration of £11m plus a deferred £5m payment contingent on retention of certain business.
It looks like a potentially good bit of opportunistic business, with flexibility over which sites it continues to run and increased service, maintenance, and repair capabilities in the UK. Group CEO Martin Ward also says the move should open up new markets for REDD.
Conclusion
Above in the preamble I touched on the idea of stocks out there that have been hammered but that will be eventual winners in their respective markets. Rerating opportunities, essentially.
Perhaps REDD can be added to that list.

In general I am trying to steer clear of net debt positions but REDD’s operations are recovering, its liquidity headroom is improving, this recent acquisition looks quite sharp, and even before that there were probably enhanced growth prospects as a result of the significant merger and scale economies.
I’d like to know what’s happening with that dividend. Ultimately though, given the low valuation, synergy opportunities, and improving growth prospects, this is one turnaround opportunity I’d like to take a closer look at.
Even after the recent modest share price recovery it trades at a discount to tangible book and with a bit of earnings growth and multiple expansion you could quite quickly be looking at a sizable return.
Renew (LON:RNWH)
Share price: 465p (+9.54%)
No. shares: 246m
Market cap: £612.5m
Renew Holdings (LON:RNWH) is a holding company that owns a mix of construction and engineering subsidiaries. This is actually an area I’ve been looking at in case we do see higher levels of infrastructure spending in future.
What I immediately like about Renew is a steady improvement in operating margin over many years:

Revenue has also grown very steadily at a 5y compound annual growth rate (CAGR) of 5.25%. That margin improvement means that net profit has grown at a much higher CAGR of 34% over the same period though.

The group appears cash generative, but construction is cyclical and times have been good recently. RNWH has a £32m net debt position - in contrast, I’ve written about BILN before here, which has a stronger balance sheet and net cash position. At first glance the latter is smaller, on a cheaper valuation, and looks to be more conservatively run from a financial health perspective.
RNWH can justify a higher multiple with superior trading of course.
On this note the group says that:
‘Trading... has been strong and consequently the Board expects the Group's full year results to be materially ahead of current market expectations with adjusted operating profit forecast to be between £39m-£40m. This improved forecast result is reflective of our defensive qualities, resilience and the implementation of numerous mitigation measures that have proven to be extremely effective in responding to the challenges of Covid-19.
The group’s rail, infrastructure, and environmental markets have been resilient and a majority of its activities were designated ‘critical’ by the government through lockdown.
The integration of Carnell, acquired in January 2020, is complete and trading here is in line with expectations.
Ah - cash generation ‘continues to be very strong and we anticipate reporting a net cash position at the year end, ahead of market expectations.’ That’s good. The CEO also sounds familiar...

Just a joke of course, Paul is away today but he’s not moonlighting as the chief exec of a £300m construction company.
Conclusion
I don’t know Renew in any detail. The reputation of its subsidiaries, the revenue splits, exposure to various parts of the economy.
It does sound like quite a lot of its business is in more resilient, protected parts of the market. In terms of trading, the company has turned in an excellent performance over the past five years. If the world doesn’t end, I don’t see why this trend wouldn’t continue.
And despite this continued execution, capped off by today's ‘materially ahead’ update, the group’s PE ratio has been falling and dividend yield increasing:

That said the group has quite a lot of goodwill on the balance sheet (£100m or so) and if you go on FY19 numbers, it has a negative net tangible asset value of c-£22m. By comparison, BILN has NTAV of about £28m and is around ten times smaller.
If only you could separate the trading entity from the balance sheet… Still, the swing to net cash is encouraging and if RNWH can continue to build up a cushion there then it looks like one to keep on the watch list. If you can stomach the risk and are banking on a strengthened balance sheet in future, then there could be some good upside - but there's also safer bets to make.
Christie (LON:CTG)
Share price: 74.5p (+7.96%)
No. shares: 26.5m
Market cap: £18.3m
Christie (LON:CTG) is a professional business services group with 42 offices across the UK and Europe, catering to specialist markets in the hospitality, leisure, healthcare, education, and retail sectors.
It’s tiny - a sub-£20m market cap with low liquidity. The valuation looks attractive but that aside, Christie’s StockReport flags up a couple of warning signs. Just scrolling down the screen these are:
- Very poor relative strength,
- Low Financial Health scores (F and Z Scores to the right),
- Declining operating margins over time (in the ‘Profitability’ box of the Financial Summary),
- It’s a micro cap with a tiny free float (see the Trading Information box below).

To balance it out, some positives:
- Subscribers point out this is one of Lord Lee’s stocks (see him on the register here)
- The valuation is modest, even after earnings forecast reductions (but note the final dividend has been withdrawn, leaving a yield of about 1.7%)
- Christie does generate particularly good returns on capital over time - between 20%-50%.
- Revenue has been steadily increasing and the group’s compound growth rates are steady if unspectacular - but that’s probably good for a 6.3x forecast PE ratio.

So my first take is mixed. Maybe Christie is a well run business - but does that make it a good investment? The shares are down nearly 50% on their 52w highs, so there could at least be a rerating opportunity if CTG can recover operationally.
True, it has a focus on professional services to hospitality and leisure but there’s always the chance the fall has been overdone given the recent wild market.
Bear in mind these are delayed results for the year to 31 December 2019, before companies had to react to COVID-19 and the associated lockdown.
Highlights:
- Revenue +2.6% to £78m,
- Operating profit +41.3% to £5.8m
- Earnings per share +36.2% t 15.3p
- ‘Strong cash generation in the year and ended year with a healthy cash balance’ - that’s encouraging
These look like good results to me, an expectations beat. A shame, then, that they’re so historic - a lot’s happened since December 2019. The operating profit was boosted by a £1.5m gain on the sale and leaseback of offices in Milton Keynes. Strip that out and underlying operating profit looks to be £4.3m (+4.9%).
I can imagine this is a well run business with a possible rerating opportunity somewhere down the line, but is there better organic growth potential elsewhere?
Regarding COVID, chairman and CEO David Rugg comments:
‘The Covid-19 pandemic has since caused us to re-assess our plans and expectations for 2020. The steps taken across the group in recent months has put the Group in position for the recovery that is now underway. Each of our services remain in demand. We therefore view our future with cautious optimism.’
That could be a lot worse. CTG also says:
Our transaction pipeline which had been stalled is now flowing again. We are experiencing a return of known investors and a healthy flow of new buyers. These include private equity buyers looking for good businesses which have faced Covid-19 disruption, private buyers looking to relocate to country and coastal locations and even entrepreneurs utilising 'bounce back' loans to acquire additional trading units.
Conclusion
I hope CTG will see a return of more favourable market conditions over the next two years. There are early signs this is happening, in which case today’s share price could be a good entry point and a decent way to play a normalising economy.
It did well to increase its cash balance from £4.7m to £9.8m in FY19 but then COVID came along and disrupted what looked like some promising trading momentum.
With a fair wind perhaps this stock could rerate from today’s lows. For now the momentum is very poor, but micro caps can jump in value quickly.
I wouldn’t bet against a sudden rerating at some point. In its own words ‘In the absence of any resurgence of the pandemic we should return to profitable UK trading in aggregate in 2021. We therefore view our future with cautious optimism.’ Perhaps one to keep tabs on should momentum comprehensively turn but I’m personally waiting for more proof of recovering trade.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

44 comments
Hi & thanks for the update Holland Smith & id be surprised if most readers of this report dont want it. Although id prefer to see it here as it’s all in one place, do you need a code fix by Stockopedia, if so id post your request in todays or tomorrow’s SCVR as Jack is writing it and get engagement to an update on a fix (or not) .
Your efforts are very much appreciated
J
A tour de force Jack!
Regarding your comment:
"I have no exposure to the Oil & Gas sector right now and am curious to hear other people’s views on this part of the market".
Hello Jack, it is good to see you back again writing for SCVR and also to see that Ed has added your picture next to Paul on the homepage.
My investment style is akin to yours, ie,. I too, look for high quality companies which are undervalued and which have a tailwind behind them, aka good momentum. Likewise, with the exception of Centamin and Polymetal international I also prefer to go fishing in the AIM & FTSE Fledgling markets for small cap shares and watch them grow over time.
Also like you, I don't hold any shares in the Oil & Gas sector. Last month I was reading a technical paper which stated that the world typically uses around 100 million barrels of oil per day (before the coronavirus). However, due to global warming issues and the fact that the human race needs to go green with the uptake of renewable energy, it has been predicted that over the next decade or so, fossil fuel consumption will drop to around 70 million barrels of oil per day by the transport and the petrochemical industry. In my opinion, the market for oil and gas will become a diminishing industry that can only shrink over time. It is forecast that many smaller oil and gas companies will go out of business leaving only the larger players in the market. Furthermore, we have already got the easy stuff out of the ground, there is plenty of oil and gas still in the ground but this will become increasingly more costly to extract over time and as the price of renewable energy drops, we may end up in a position were the remaining oil stays in the ground due to economics. My opinion is that I don't see the point in investing in a shrinking industry with diminishing returns but that is only my opinion.
Redde Northgate (LON:REDD)
Jack - One thing to factor in to the debt though with these guys is that the debt itself is backed by physical assets (ie vans). So it's a little bit like a Next where they appear to have £3bn of debt but it is all related to the finance book.
As long as the second hand value of vehicles remains relatively robust then you should really take physical assets off the debt position to give yourself a better picture. Of course the risk is that 2nd hand prices plunge and those asset values are no longer strong enough to cover the debt taken out to buy them so some sort of haircut applied appears sensible.
Nonetheless I hold and think they have strong recovery potential especially as they are likely to be making hay with current 2nd hand values rocketing.
I think the vertical integration strategy is probably quite a good one ultimately though will take time to shine through, as it will add several layers of diversification to earnings and leave the group less exposed to economic downturns which should smooth earnings. Todays acquisition looks like management have taken advantage opportunistically to accelerate that strategy. Earnings enhancing is great to see.
I haven't been able to open Stocko for 2 days as I go to the .co.uk not .com. I assumed that the site was down again!
The morning read is not the same without you! :)
Welcome back MR C
Ed or Jack, ....the site has had some problems recently, i keep getting server error....and clearly a lot of us readers very much appreciate Mr C & Holland smith contributions, so i only think it right you update on where you are fixing Holland Smiths code issue, or if you are to fix it.
Your site updates were virtually non existent on twitter when the site was down, Ed may have been on his yacht, but come on, not good enough i'd say....
Paul, perhaps you can prompt on this as it's such a help for all of us.
Ok, it's now obvious to me that my news daily output should become an email blast as I believe some people really value the work behind it. It is slowly climbing its way to my number one priority, but there’s still a couple of paid freelanced projects currently preoccupying my time. Bear with me, I will be back soon!
Ten Multibaggers with 10 Bagger Potential - Creightons
Creightons information added.
https://www.stockopedia.com/co...
BSV
hi BSV - the links to the analysis are quite useful reading and so red flags are harsh. Might I suggest you change the header - I think you get flagged down because it sounds quite rampy even though that doesn't appear to be the intention at all.
Thanks, David,
I've been lucky enough to pick up stock I've wanted to own for some time and want to share information on the long term potential with others.
I don't mind the red flags.
BSV
Hi BSV, also think you've produced a useful write up. Also agree the header might get you marked down. I own CRL (in @ circa 45p) and topped up yesterday. Thought the PIworld presentation excellent and surprised we're not seen more of an uptick given the results. Then again it can take a while for the market to react to smaller Company news.
Thank you Berksbee,
Always nice to know its useful to others too.
BSV
Redde Northgate (LON:REDD) Redde Northgate was covered by Richard Leonard here, at 42.50 and 49.10. RL explains this well it's at turnaround story no. 1 which will be executed by new management including Martin Ward who knows the industry inside out Avril Palmer (who is a legend by the way, she started her career at Northgate).
But you also gotta factor in the company's business model, a part of which is to buy it's fleet new and shift its older vehicles onto the 2nd hand market.
That 2nd hand market has exploded because of covid. Fleets aren't selling into it due to delays in vehicle production of new units and demand for 2nd hand vehicles are through the roof coz every small business now need to deliver.
So you have the turnaround of a mis-managed company by a new top notch management team, plus the demand for vehicle rentals going up due to covid and demand for 2nd hand fleet... etc. etc.
Excellent buy at these levels. I hold.
Nice to see mention of some resource stocks on here Jack! It’s an area I’ve just started getting involved in over the past couple of years, and it’s difficult to get hold of non-spivvy coverage. Jadestone (JSE) is a good call given the quality of it’s assets, cash generation and very sensible management.
Attended a presentation given by Paul Blakely, CEO of Jadestone Energy (LON:JSE), about 18 months ago and he clearly outlined what he wanted to do. That included getting to a point where the company could pay a dividend in a reasonable time frame. He came across as genuine and professional. He seems to be delivering on his goals. It's not a company I'm invested in but it's definitely on my radar.
More broadly, we now seem to be in a period of constant change. Where well-established businesses can be destroyed very quickly. In that environment, a low-cost oil producer can look very attractive. There are still some two billion internal combustion engines on the road. And oil is used in a variety of industrial processes. Long-term and, in my view, oil is finished. But I suspect many industries and business models will also be gone by then.
Hi Jack
Re your comment re metals, Sylvania Platinum results coming up on 8th Sept. Appears to be very attractive company (despite being SA based), loads of cash, riding the wave of Platinum, Palladium and Rhodium prices and yet having a Current year PE of less than four - would be interested in your view next week.
had lunch yesterday at Chez Bruce in Wandsworth and it was packed . The owner,Bruce Poole told me that bookings had been phenomenal since opening a week ago,and the same applied to sister restaurants in Chiswick and Kew. He intended to squeeze a few more tables in to all the restaurants whilst still trying to comply with social distancing rules.
Creightons (LON:CRL) FY20 results presentation, has been published here. As alwasy, a great presentation by Bernard Johnson, Group MD, Paul Forster, Gp Finance and Commercial Director, and Pippa Clark, Global Marketing Director & Deputy MD. A superb insight to the personal care sector, and retail. Paul covered CRL in Wednesday's SCVR.
Results season is upon us, over the next few weeks we have results webinars for you to attend, as follows, you can register for them all here.
Property Franchise (LON:TPFG) on 9th September, 2pm.
Aquis Exchange (LON:AQX) on 11th September, 11.30am.
Somero Enterprises Inc (LON:SOM) on 14th September, 3.30pm.
Litigation Capital Management (LON:LIT) ON 23rd September, 9.30am.
Sumo (LON:SUMO), Thursday 8th October, 1pm.
Next week, we return with a piworld interview/webinar, with Castleford Tiger, who was cited by Andy Brough, of Schroders, for his encyclopaedic knowledge of Dart Group. We will be catching up with CT's views on Dart (LON:DTG), or should we now say Jet2! And learn more about his highly successful investing style. This is on Thursday 10th September, 1pm.
Two weeks later we have a piworld interview/webinar with Cockney Rebel, who has a name for making money in small caps, with a knack for perfect timing. With an AAR of 30%+, we will hopefully learn something about how he achieves that. This is on Thursday 24th September, 1pm.
To repeat you can register for all the webinars, company and interviews, here.
Morning Tamsin, just like to say that love the podcast version of PIWorld, perfect for a long Sunday bike ride.
Morning Jack, If you get time I would appreciate you looking at LON:CTG. Profits up 41%, P/E of less than 4 if I have done my sums correctly. Definitely looks small and value. I hold.
Interesting, good spot - I used to be much more closely involved in Leisure and remember Christie well so will take a look
Thanks - a very thoughtful write up. Only thing to add is the spread has tended to be quite modest in my experience.
I bought Christie (LON:CTG) Back in 2012 and looking back it actually didn’t do that bad for me with a 11.8% CAGR in the four years I owned it. I sold at 85.5p in 2016 because it seemed a bit aimless as an investment and the stock price has not gone anywhere in the last 20 years.
That said I could be missing something as I think Lord Lee is still a fan!
Morning Jack
Interesting acquisition by Redd Northgate. Looks a good fit, also a positive trading update. It was one of Richard Leonard's picks in the recent PI World interview. Do you have a view?
All the best
I would be interested in any thoughts you have on this too. Current trading looked particularly encouraging
Just having a look now actually
Agreed. Spanish business has much better margins than the UK and I wonder if in part that is down to them having the sort of repair network Redde has just bought for a good price by the look of it....I think the PE guy paid well over 30mn for it not that long ago. Trading was better than I had thought likely . They talk re divvie at results in a couple pf weeks.....used to yield around 9%. decent discount to NAV as well. HAving hire, insurance and repair under one roof wd seem to make sense?
Must say i am missing the Hollandsmith & MR C early morning updates and now i’m reading the news on twitter (which does have mr c?)
Have they gone for good? I must have missed the memo.
Have they gone from Stocko?
Does anyone know if MrContrarian and HollandSmith have disappeared forever? It would be a great shame if they have.
I think this might have something to do with it (from the SCVR on the 27th Aug)
HollandSmithAug 27, 2020
Hello Stockopedia, seems like the HTML function in your comment box is now disabled as im getting the message "Oops - you forgot to enter any text for this page!"
Im guessing this might not be online yet after yesterdays outage?
Could you please enable this feature?
I so hope HollandSmith and Mr Contrarian have not suddenly gone, because their daily updates on their own are worth the Stockopedia subscription, with the wealth of other information and facts and figures then in for free. And the SCVR is also worth the subscription, but it lacks something big first thing without HollandSmith’s and Mr Contrarian’s updates.
Ray Dalio, the founder of Bridgewater Associates, released a 30-minute video in 2013, explaining his template of the economy and how central banks and government should manage a deleveraging like the Great Recession and its after-effects.
I found it very useful to understand what is happening now.
Link included below
;feature=emb_title&ab_channel=PrinciplesbyRayDalioThanks Bluesky, I've seen that one before but it's always worth another watch at just 30mins... The fact it's still getting shared online seven years later says something.
Dalio has been posting articles recently on linkedin too, don't know if you've seen:
https://www.linkedin.com/pulse/implications-hitting-hard-0-interest-rate-floor-ray-dalio/
Thanks, Jack
I'm having a read now.
BSV
Hi Jack - thanks for this.
It would be interesting to hear what you and Paul think about portfolio strategies that diversify away from companies that get the majority of their revenues from the UK, and even to the high growth potential of frontier markets. IMHO, the UK outlook looks bleak after the Tories/UKIP shot the country in both of its own feet with Brexit, the implications of which are likely to be grim for many years to come. Covid has added lead to a sinking ship. I know (us) Brits like to be patriotic and I am sure you are more comfortable covering UK-focused companies, but there must be diamonds in the rough elsewhere. For example, what about companies like Asa International (LON:ASAI) - which focus on microloans to women across Frontier economies... something totally different, and sounding like a charity a bit, but operating in some of the fastest growing economies in the world, where demographics will keep powering growth and demand for financial services for a long time.
Anyway - just some thoughts.
Freedom sure is grim.
Retireyoung I could not agree more. There is an interesting take on the chaos To come in the haulage Industry (who voted overwhelmingly to leave - I know you could not make this up) in the FT today.
I have a 25% exposure to gold (via £PHAU and Anglo Asian Mining (LON:AAZ)), cash of about 10% . My next seven largest holdings (So my top 10) are Boohoo (LON:BOO) Avacta (LON:AVCT) Sylvania Platinum (LON:SLP) $GAW Ergomed (LON:ERGO) Avon Rubber (LON:AVON) and Bioventix (LON:BVXP) make up 43% of my portfolio.
Off the top of my head these look reasonably underexposed to the UK - thank god.
Regard
Michael
An option is also to invest overseas it certainly widens your choices dramatically.
Good morning Jack,
I completely agree and feel there is a stronger case now for 80% of portfolio's should be in cheap global/S&P500 trackers, with 15% in small caps with high potential growth and 5% in gold ETF?
long way down.. ..