Small Cap Value Report (Fri 5 April 2024) - PINE, STCM, XSG, RUA

Good morning from Paul!
Last day of the tax year today.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Only 3 companies reporting today, so I'll be able to cover all of them, plus a couple of backlog items too, hopefully. That's assuming the RNS hasn't malfunctioned again - sometimes a second wave of announcements come through about 07:30.
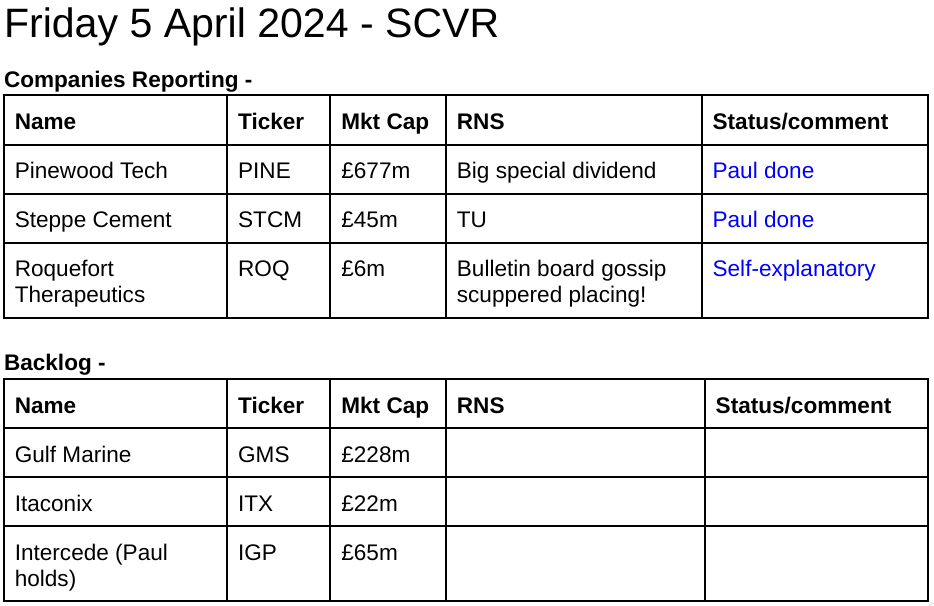
Other mid-morning movers (with news) -
Xeros Technology (LON:XSG) - down 14% to 1.6p (£4m) - conditional fundraising at 1.5p. I was quite surprised that this company is still going, after many years of commercial failure and heavy cash burn. Heavy dilution, with this latest fundraise almost tripling the share count. It’s the washing machine project with beads. Share count c.1m in 2017, c.600m after latest raise.Just passed its 10-year anniversary on AIM.
Rua Life Sciences (LON:RUA) - up 16% to 12.75p (£8m) - Business Update - Paul - AMBER
RUA Life Sciences (AIM: RUA), the holding company of a group of medical device businesses focused on the exploitation of the world's leading long-term implantable biostable polymer (Elast-Eon™), today provides an update on trading for the financial year ending 31 March 2024 and developments since the successful fundraise in December 2023. [at 11p]
Made up H1 shortfall in H2, with FY 3/2024 revenues in line exps at £2.2m. Gross margin will exceed expectations (not stated). Operating costs £200k below expectations at £3.4m. Cash position of £4.0m - about half the market cap, interesting!
Possible large order? - “succeeded in securing the initial development stages of a significant contract with a global enterprise. This contract represents a major milestone on the route to doubling revenues for the contract manufacturing division once fully operational. Initial development work under this contract has commenced, with an initial purchase order valued at £100,000 already received.”
Paul’s view - this heart valve materials technology sounded vaguely familiar, and it turns out this company used to be called Aortech, which I remember from old. Several generations of investors have become excited, then disappointed, with its failure to commercialise what sounds like interesting technology. It floated on AIM in 1997, amazingly! I wonder how much the listing costs, and Directors fees have been over the past 27 years?
It’s making some positive-sounding noises today, so who knows, maybe it’s making some commercial progress at long last? The recently raised cash pile means that we don’t have to worry about solvency for the time being, with maybe 2 years’ cash in the bank? There does seem to be something interesting hear, but people have been saying the same thing for the last 27 years.
Summaries of main sections -
Pinewood Technologies (LON:PINE) - up 1% to 39.1p (£680m) - Return of £358m to shareholders - Paul - AMBER
Having demerged its main business (car dealers, formerly called Pendragon), it's now proceeding to pay a large, planned special dividend with the cash proceeds. A 1 for 20 share consolidation is the next step. This leaves a SaaS software business, which looks good (see Zeus note for details), but I question the valuation, which is looking rather full perhaps?
Steppe Cement (LON:STCM) - down 7% to 19p (£42m) - 1.5p/share cash return, Q1 2024 TU - Paul - AMBER/RED
A convoluted corporate structure involving several countries make it difficult to pay divis, so it's structured a proposed 1.5p cash return as a capital reduction/distribution. The Q1 2024 trading update doesn't give any details on profits, so is largely useless, and there are no broker forecasts. 2023 results have not yet been published, and H1 results were poor, at only breakeven. Unsurprisingly therefore I'm leaning towards a negative view.
Paul’s Section:
Pinewood Technologies (LON:PINE)
Up 1% to 39.1p (£680m) - Return of £358m to shareholders - Paul - AMBER
Formerly the Pendragon car dealership group, it sold the main operations to Lithia (NYSE:LAD) for cash, with 24.5p per share (£358m) to be paid out to PINE shareholders as a special dividend.
A share consolidation will also happen, on a 1 new for 20 old basis, so the share price will rebase upwards, for a smaller number of shares in issue (Old: 1,742.3m, New: 87.1m).
I’m assuming that when the 24.5p special divi is paid on 7 May (for those holding shares on 22 April), then the share price would gap down to 14.6p. Then it would gap up to 292p when the 1 for 20 consolidation occurs. Hopefully those figures are correct.
I make that a £254m market cap for the Pinewood software business post de-merger, which seems a lot, considering it was little more than an afterthought when part of Pendragon.
We need pro forma numbers and forecasts, which Zeus helpfully provide via Research Tree. Forecast adj PBT is £8.5m for FY 12/2024, rising to £12.1m and £15.4m in the following two years. There are good reasons provided for the forecast growth, eg expansion into the US market, in a JV with Lithia. Also Pinewood can now sell to other car dealers who might have seen it as a competitor (when part of Pendragon).
Paul’s opinion - based purely on a quick review, I think we’re being asked to pay too much for future growth that hasn’t happened yet, so it doesn’t interest me at this stage.
The demerger strategy has clearly worked well, with the idea being that a standalone software business would attract a higher rating than was attributed whilst it was part of a car dealership group. That seems to have gone well -
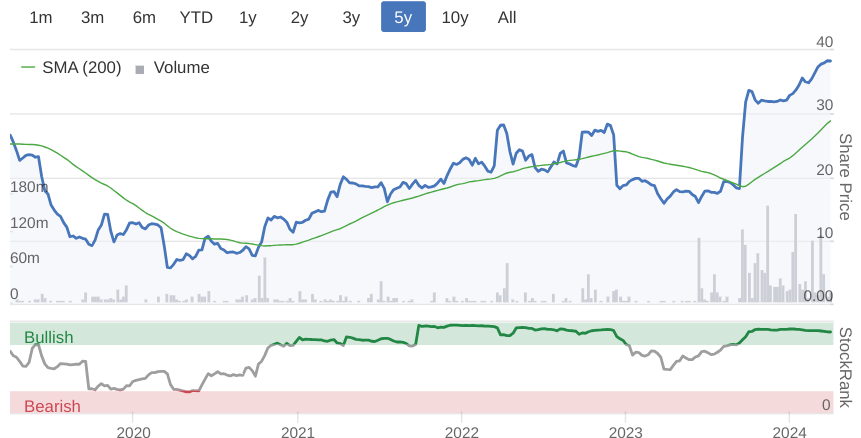
I can’t remember the exact details, but there was some kind of scandal which left Pendragon looking really dicey when it hit the lows of c.6p, which is why the share price crashed before the pandemic hit. Still, it’s been a superb recovery since, so a very good outcome for holders.
Steppe Cement (LON:STCM)
Down 7% to 19p (£42m) - 1.5p/share cash return, Q1 2024 TU - Paul - AMBER/RED
This producer of cement in Kazakhstan is calling an EGM to authorise a reduction in capital to allow payment of 1.5p per share as a capital return to shareholders. More detail is provided as to why this method is being used, which is more tax efficient than paying divis which could be subject to taxation in multiple countries, due to its complicated corporate structure, which seems to involve Malaysia and the Netherlands, as well as Kazakhstan.
I would normally give anything like this a wide berth, but STCM has a history of being profitable, and generous with divis - something that’s quite rare for overseas companies that usually list on AIM primarily to fleece gullible UK investors. So anything that pays generous divis stands out from the pack of AIM junk.
Various problems were encountered and reported in 2023, but we still haven’t had the financial results. A year-end trading update on 12/1/2024 wasn’t much use, unless you have your own forecast spreadsheet that you can plug the selective numbers into.
H1 2023 results were poor, with a breakeven overall result, down from a $12m H1 PBT in 2022.
Q1 2024 trading update - is similar to previous updates, in that it provides detailed information on production and pricing, but not the number we actually need - has it made any profit?! Given that the variables seem to be worse than 2023, and it only reached breakeven in H1 2023, then I’m assuming this means it’s now loss-making?
Paul’s opinion - this might be of interest to special situation investors. The continuing desire to pay divis is the only saving grace really - if it wasn’t for that, I’d be red on this share. However, previously high profits, and a track record of paying shareholders, means I’ll hold back from going fully red. The lack of proper information on profitability, no broker forecasts, and what seems likely to be a loss-making Q1 of 2024, means I’ll go with AMBER/RED.
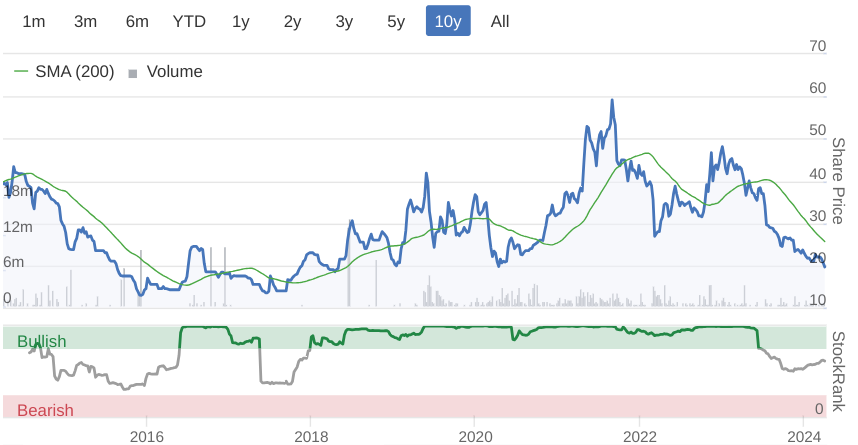
Ten year track record (chart below) is volatile - but at least it's got a 10-year track record! - in fact it's been UK listed nearly 19 years -
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

93 comments
"We need pro forma numbers and forecasts, which Zeus helpfully provide via Research Tree. Forecast adj PBT is £8.5m for FY 12/2024, rising to £12.1m and £15.4m in the following two years. There are good reasons provided for the forecast growth, eg expansion into the US market, in a JV with Lithia. Also Pinewood can now sell to other car dealers who might have seen it as a competitor (when part of Pendragon).
Paul’s opinion - based purely on a quick review, I think we’re being asked to pay too much for future growth that hasn’t happened yet, so it doesn’t interest me at this stage."
--------------
Just one point on the valuation of Pinewood Technologies (LON:PINE) [I hold] the North American JV provides significant potential upside to forecasts provided by Zeus as they state in the narrative of their note.
Hargreaves Services (LON:HSP)
H1 interim dividend is due to be paid on 11th April but I've just spotted that Interactive Investor paid my dividend yesterday, one week early.
I've never come across this before.
Not sure if this a company or broker mistake.
Have all holders been paid early?
Snazzy
I got the Hargreaves Services (LON:HSP) dividend as well, on IG platform.
Stocko have it as paid yesterday.
hi Rusty2
Hargreaves Services (LON:HSP) dividend payment date on the interim results RNS was 11th April and remains the same date on both Sharepad and dividenddata.co.uk
Rather bizarre that Stocko are the only ones in the know!
Snazzy
Hargreaves Services (LON:HSP) went ex divi 21/3, so 4/4 looks right for payment, that was the same number of days as last year.
Fair point although their RNS clearly stated 11th April.
Sounds like a company error then but at least it's in the investors' favour.
Hargreaves Services (LON:HSP) Looks as if Stocko got the right date from here:
https://www.hsgplc.co.uk/inves...
Hi Snazzytime
Hargreaves Lansdown paid mine yesterday, too
Volex (LON:VLX) share price weakness looks like a massive buying opportunity to me. Happens every year in lieu of a Q3 update and every time they issue full year results either "in line" or "ahead " of exps.
Hi Joshwood,
Volex (LON:VLX) is now about 10% of my portfolio, it was much more earlier in the year. Needless to say I think Mr Market as is often the case has misread the runes and overshot on the downside.
Nat Rothschild holds 25% of the equity and although not a founder/owner like Paul Young at Kitwave (LON:KITW) , Simon Showman Ultimate Products (LON:ULTP) or Philip Meeson Jet2 (LON:JET2) , all of which I hold, I regard him in the same mould. Irrespective of his wealth he has never sold a share and I am happy to remain invested alongside him. I intend to post my thoughts over the weekend.
All the best
Hi Jonno,
I agree. he hasn't put a foot wrong since he joined the company.
Where will you be posting your thoughts? looking forward to reading them!
Hi joshwood
I suspect that it will be a new post on Stockopedia. I will need to revisit my notes etc. Please be aware that whatever I say are my views only and as a holder I am likely to be biased and that like all investors I am from time to time wrong.
All the best
Anyone know why Kenmare Resources (LON:KMR) stockrank has dropped so low recently - high 80s to late 50s now ?
Had a quick look Kenmare Resources (LON:KMR) the 2023 results are out now and Stocko will have updated their ranks based on those, profits are down on 2022, so quality has fallen quite a bit.
Kenmare Resources (LON:KMR) - (I hold) This is one of those specialist shares where you need to look behind the figures - which Stocko use for the rankings. Well worth visiting their website.
I'm just answering why the rankings are down on Stockopedia.
Similar happened with Gulf Keystone Petroleum (LON:GKP) on the 22nd March. Dropped from a 91 SR to a 25 SR...has had a slight improvement since. Had it on my watchlist and the numbers looked ok (prior to March 22nd). Not looking so good now with the updated numbers.
Again they published the 23 results which have a loss.
No dividend either.
Nice to see a fairly chunky purchase by the FD of Luceco (LON:LUCE) today (I hold). It feels like there’s some nice momentum behind this one at the moment.
Good £60kish - not chump change!
ShareSoc - thinking of buying the membership. I have read through all the features list etc. But wanted to hear from real live experiences - what is the one thing you find most useful about your ShareSoc membership?
why this bulletin board of course!
They do get involved when shareholders are being treated badly by companies. They can have some interesting presentations. They are the sole voice standing up for small shareholders. I am a member.
I'm a member. I don't buy in for any personal benefit, but because it's important that there's someone standing up for small shareholders, and because I believe the guys who founded it are people of immense integrity who genuinely do the best for the rest of us.
Yes, that’s why I joined Sharesoc too.
They have helped investors in Woodford.
They have also attempted to genuine ownership of shares held via a nominee, as in most platforms and brokers accounts. Currently most shares are actually owned by nominee accounts , who , if you obey all their rules will let you pretend you actually own your shares. Do not think there has been much progress made as yet.
hi tic_tac_toe
It should be live now but isn't.
Still waiting for Vox markets to start the show.
Looks like timekeeping isn't their usp.
Snazzy
I have been waiting as well on YouTube. Can’t see anything on this on their website.
No idea. I just went to their YT page and the Live section. It may be things the new link https://www.youtube.com/live/z...
Not on the newsreel this morning but saw this in today's Telegraph reBabcock International (LON:BAB) . Couldn't link but here's the cut n paste of the majority of it
Mini-nukes to be built in Hartlepool under multimillion-pound proposal
Engineering group Babcock wins funding to build small modular reactors in Teesside
Hartlepool could host a fleet of mini-nuclear reactors within a decade after the Government awarded a multimillion-pound grant to engineering group Babcock to explore the project’s feasibility.
X-Energy and Cavendish Nuclear, which is owned by FTSE-250 group Babcock, have won funding from the Future Nuclear Enabling Fund to progress plans to build new mini-nukes in Teesside.
The companies are developing advanced nuclear power plants known as small modular reactors (SMRs). The hope is that these mini-nukes could be partly built in factories and constructed in large numbers of locations, providing cheaper green energy than larger nuclear sites.
Advertisement
X-Energy and Cavendish Nuclear want to build a 12-reactor nuclear plant in the North East. Mick Gornall, managing director of Cavendish Nuclear, said the goal ultimately is to develop “a fleet” of such reactors, which the company calls Xe-100s.
He said: “A fleet of Xe-100s can complement renewables by providing constant or flexible power and produce steam to decarbonise industry and manufacture hydrogen and synthetic transport fuels.
“Deployment in the UK will create thousands of high-quality, long-term jobs across the country.”
Lucky Hartlepool. Have to say I would not want to be resident near one of these sites. Unless they are going to have military style security I think we are in danger of creating more potential terrorist targets, never mind the accidents that have happened around the world at nuclear plants (few but catastrophic). Putting these near populated areas seems a high stakes gamble. Perhaps a good location would be underutilised military bases? I'm sure we still have a bundle of those, many in relatively low density population areas.
Maybe a slightly paranoid gut reaction there, sevenccc. The kit may be built in Hartlepool but I doubt they will be handling nuclear materials on Teeside.
Fuelling the units will likely be done after installation ... on-site.
Volex (LON:VLX) (I hold) should benefit as they manufacture high speed cables for data centers:
"AI Demand for Data Centers Vastly Underestimated, CoreWeave Says
The world is “grossly” underestimating how much the demand for artificial intelligence is going to expand the global market for data centers over the next five years, according to the co-founder of the cloud-computing unicorn CoreWeave."
Source: Bloomberg
https://www.bloomberg.com/news...
A subscription site but three free article views per month I believe.
It's been archived on HERE unlocked.
Auto, yes I was reading something similar on this subject, apparently by 2030 data centres in Ireland will be consuming 30% of the country's electricity supply, that's a lot of energy consumption and a lot of data storage.......
How best to play this theme?
How best to play this theme?
Buy a bundle of cloud and data centre stocks two years ago.
More constructively, new avenues do keep appearing. The most recent is to have invested in memory, esp. HBM, semiconductors. Decent gains in the last couple of months. Or, as you intimate, buy picks and shovels: cables, cooling, electrical suppliers. Volex looks underappreciated but is being held back by the poor outlook for Tesla.
Alphawave IP (LON:AWE) is a provider of connectivity solutions in data centres (I hold).
Buy picks and shovels:
Softcat (LON:SCT) , in their recent 1 results:
During the period, there was growing interest from customers in engaging with generative-AI ("Gen-AI") and the possibilities it offers, over time, to transform their operations. We have been able to offer advice and support via workshops, webinars, podcasts and one-to-one meetings, and these interactions mean we are well-placed to help our customers assess their readiness for adoption as use cases and products start to come to market. In many situations, customers are discovering through their interactions with us that they first need to make improvements to their foundational data governance and management for Gen-AI as more and more use cases are established.
While it is still very early days, we are already beginning to see the all-encompassing impact the broader AI opportunity will have across both infrastructure and applications. The early-stage adoption of tools such as Microsoft Copilot will increase steadily over the medium term, but Gen-AI and large language models are just one aspect of AI that will drive both volume and innovation in IT over the coming decades.
As a reseller, they should also benefit from upgrades of replacement/upgrade of pandemic driven kit. I hold.
Agreed. I bought Bytes Technology (LON:BYIT) on recent CEO-dodgy-trading-related weakness. Off 5% since and looking decent value to me.
Yes, Bytes does look good value but I am waiting for the outcome of the company's committee investigating the CEO-dodgy-dealing episode before buying back the shares I recently sold.
Oddly enough data center REITs were one of Jim Chanos's favorite shorts before he shut up shop.I think his argument was that they're commoditised and very competitive, ie. Microsoft, Amazon, etc.. take all the spoils.
'Chanos, 66, last year took out large short positions against data center real estate investment trusts (REIT) including Digital Realty, with a prediction that cloud providers would take their business.'
https://www.datacenterdynamics...
Where is the extra electricity going to come from?
Nukes in Hartlepool?
only 3million people in ireland so a 30% increase not as much vs uk population
Ireland's population hasn't been 3m since about 1960. It's over 5m now., and rising. The mass emigration of young people is a thing of the past.
Digital 9 Infrastructure (LON:DGI9) was in theory a good way to play this data centre and data traffic theme. It had three main investements (Verne - data centres; Aqua Comms - undersea cables and Arqiva -UK digital transmission). But it has been a complete disaster - as it became overlevered and doubts about the true value of the assets. The Verne business got sold off last month to reduce the debt pile (DGI9 could still theoretically benefit from an earn-out on Verne). The rest of the businesses (bar Arqiva) are now up for sale as DGI9 is in a managed wind down.
One lesson from DGI9 is that being in the right theme is useless if the price is not right.
I have this week bought into DGI9. It is a punt on the remaining assets being worth more than the now significant reduced RCF (following the Verne sale).
There is some interesting information on Digital 9 Infrastructure (LON:DGI9) (I hold) on this thread https://www.stockopedia.com/co...
Indeed. Microsoft (NSQ:MSFT) moved the US market when they announced their $100 billion data center, 'Stargate', spend recently, that could lauch as soon as 2028 apparently.
Does anyone have the link for today's 9.30 Vox Markets live interview with Cockney Rebel?
Thanks
Snazzy
Is this Live now?
Supposed to be, but not started for some reason...
I can’t use this link and a search of YouTube shows nothing for today with Cockney Rebel
Vox/YouTube
The CR video is now up (with apols. for lateness):
https://www.voxmarkets.co.uk/a...
The other link given by tic-tac-toe is Our Graham:
CR:
Snazzy. Goto youtube and search for Vox Markets. It will come up there. Alternatively goto Vox markets website. Link will be there too. Will be listening in myself!
No sign of it when I checked a few mins ago.
Did it go ahead?
Happy Friday all!
NAHL (LON:NAH) rumour swirling around yesterday after Betaville posted about the possible disposal of their Critical Care division for an estimated £40m (mkt cap is £30m). Nothing from the company yet though...
IMO it would make sense for them to do that now, as the other part of the business, Consumer Legal Services, is now maturing and cashflow positive, meaning it can stand alone or be disposed of separately. Back of the envelope, that's worth c.£25-30m at least, so I think there's value here.
Best wishes, M.
Wow! NAHL (LON:NAH) up 20% in early trading!
A sharp move down on the S&P500 last night in a roller coaster day. Initially went up strongly and then moved from 5,258 to the rising trend support level of 5,147 (down c2% intraday) ahead of jobs data today. This was the largest down candlestick for a long-time. Could be a bumpy couple of days if it falls any further, as suport levels below this are 4,600 (-11%) and 4,100 (-20%). Ouch!
Given the vertical ascent of the S&P500 for 6 months driven the Mag-7 (now Fab 4) its likely to be even more dramatic on a correction in my view (i.e. up the stairs down the escalator). I get the feeling that this run is coming to an end (before we get to the summer) given concerns over whether the Fed will be able to reduce rates, gold soaring and the 10-yr having moved from 3.8% to 4.3% this year. The market is hinting to the Fed that rate cuts are not yet needed in the US given the strength of their economy driven by Biden's deficit spending.
This is something to watch closely as UK shares will also be heavily impacted if this corrects.
I've reduced US exposure by half already; might clip a bit more. Have had a superb run, so won't be complaining.
I didn't have as much in as I wanted before the steep increase so not reducing my holding at this stage in the US. I have money sitting earning 5% while I wait for the correction (I hope) but so so difficult to know when to add. Will drip it in with each decline if it happens of course.
Well said. However, as UK share didn’t go up in tandem it probably would not fall so much.
I stay fully invested in UK shares and collect dividends.
Or typically UK go down and then not go back up.
Corrections in the US tend to be shorter than the UK.
Sentiment index rolling over too....
Topvest, I agree with the observation but I think you meant "take the stairs up, and the elevator down", depicting gradual upward progress followed by a sharp correction.
Crude suddenly spiked on the news of Iran saying it will retaliate after Israel attacking Iran's consulate in Syria the indices immediately were sold en masse.Crude is at a price where it cold really hurt inflation numbers again.If crude supply isn't affected, i don't see how it will affect Nvidia chip numbers, Microsoft software sales though etc.. The risk free asset, Invesco QQQ Trust Series 1 (NMQ:QQQ) , is still safe for now!
My morning smallcap tweet: One Steppe Beyond
Steppe Cement (LON:STCM) Global Ports Holding (LON:GPH) Pinewood Technologies (LON:PINE) Roquefort Therapeutics (LON:ROQ) Supply@Me Capital (LON:SYME) Alliance Pharma (LON:APH)
◄Steppe Cement (STCM)► Q1 cement sale vol down 18% and rev down 23%. Transportation costs have increased significantly and shipments to the southern region of Kazakhstan result in low margins. Will return 1.5p/sh to holders. [SP=20.95 Cap=46m]
◄Global Ports Holding (GPH)► 51% owned JV awarded preferred bidder status for a 15-year concession to operate Casablanca's new cruise terminal. Flowery prose about Morocco follows. I've been and I must say the diarrhoea is amazing. [SP=207 Cap=158m]
◄Pinewood Technologies (PINE)► details of 24.5p special div. [SP=38.97 Cap=668m]
◄Roquefort Therapeutics (ROQ)► re SP fall and speculation about a placing - co was in talks about a fundraise but "in response to incorrect bulletin board comments regarding a speculative placing price and resulting unusual share price movements" will not proceed. [SP=4.5 Cap=6m]
◄Supply@ Me Capital (SYME)► Biz update. White-label IM business line contracts signing delayed. Something to do with cheese. Also "continues to make solid progress in structuring a security token framework with the CH Trading Hub" and has secured a commitment of $5 million from the asset manager. [SP=0.04 Cap=21m]
◄Alliance Pharma (APH)► FY results delayed to 23 Apr due to "volume of work" for the auditors. [SP=38.4 Cap=208m]
Love Mr. C's commentary on Global Ports! Superb!
Moroccan version is notable, but perhaps not so enduring and instantaneous as that from Egypt.
In my experience the Karachi version is world beating.
Anyone with IG or other Flexi-ISA providers can deposit an amount into their ISA that they'd like to roll over today and withdraw it tomorrow.
For example, if you've only deposited £10k so far but want to carry the remaining £10k over, you'd need to deposit £10k today. Tomorrow you can then withdraw that £10k and you'll be able to replenish it anytime within the 24/25 tax year, plus your new £20k allowance.
Why don't all ISA providers offer this?
Very good info Michael and very good question, Viz (nothing to do with a certain magazine of same name are you?)
I am pretty sure Hargreaves Lansdown don't allow this but I am going to find out this morning and will report back.
I've finally heard....and they don't! You were right Michael
The term for allowing withdrawals from an ISA provided they are returned within the same tax year is 'flexible ISA'.
ISA providers don't all provide flexible ISAs as they want to use the cash sitting uninvested in accounts to make money. I think this is poor. Disappointingly the largest execution-only provider in the UK Hargreaves Lansdown does not offer a flexible ISA.
At least HL pay some interest on cash unlike IG.
If you take the money out you have put it in a cash ISA?
Rusty2 - no you can just take it out and spend it. FlexiISA rules allow you to withdraw any amount from your ISA in a tax year and pay it back in again in the same tax year.
OK I did not realise that. But what is the point, why put it in at start of the ISA year? If you not going to invest it in shares?. I get over 5% on instant access account at the moment. I'm not rushing to put it in an ISA at the moment I still have cash in there.
Rusty2, the point is you can put it in at the end of the tax year, temporarily so as not to lose your allowance.
Example I might have £20k in my bank today that I'm going to need to spend in 2 weeks time. I'm expecting to have loads of money in 9 mths from now. I put the £20k in my ISA today and use my allowance. Next week, new tax year I take out the £20k, In 9 mths time I can pay £20k in plus my 2024/25 allowance of £20k.
Several sources say "If your ISA is ‘flexible’, you can take out cash then put it back in during the same tax year without reducing your current year’s allowance.."
So you saying that is incorrect?
In the guidance in gov.uk this is what they say:
"A flexible ISA is an ISA whose terms and conditions allow the investor to replace, in whole or in part, cash they have withdrawn, without the replacement counting towards their annual subscription limit. No changes are needed to the application form, but should be within terms and conditions.
Where a withdrawal is made, any subsequent subscriptions in the same tax year that would otherwise count towards the subscription limit will do so only to the to the extent that previously withdrawn amounts have been fully replaced."
My quote was from gov.uk as well. But others are now putting the amount in last tax year and then taking out this tax year.See the post I was replying to.
Either the gov.uk site is not up to date, quite possible or they are incorrect.
If this is the case, then you just keep moving the £20k each tax year, then fill the ISAs later when funds allow.
My ISA allowance was filled last year, so this did not apply to me.
I wonder if I transfer cash from my share ISA with HL, which is not flexible, to a flexible one at IG, what I can then do with the funds?
I wouldn't expect the gov.uk guidance to be wrong. The way I read it is you can any withdraw any amount from a flexible ISA in this tax year and repay it back within the same year without affecting the allowance. So say if you had £40,000 in one stocks and shares ISA arsing from whatever previous years contributions , you could for example take out all £40,000 this tax year and pay back in up to £60,000 later in this tax year, but can't wait until the next tax year to put it back in.
As regards crossing over tax years I think the important point is that with a flexible ISA you can max out this years ISA allowance even if you know you want the money temporarily for something else next tax year but may to be able to pay that and more back in in that year. Yyou don't have to wait until after you need to spend the money just because you'll be paying in more than £20,000 altogether next tax year; as long as it's not more than £20,000 plus the withdrawal you'll be ok.
Somebody can correct me if I'm wrong. Could always check with HMRC if you needed to do something like this.
I think I see what you are saying. So if I transfer all my ISA cash to IG flexible ISA, then I can take it all out and invest it in non ISAs, as long as I pay it back this tax year. This seems to rather defeat the point of ISAs.
They could but they have to be "Flexible ISA". Suspect that decision not to is based on cost of changing their systems v increase in profitability. I have ISAs with ii and Barclays. ii is not Flexi, Barclays is Flexi but in all other aspects are sh*te and has been since they changed name to Smart (I don't think so) Investor.
I don't understand why anyone should want to place £10k in this back end of a tax-year ISA and place £30k in the new tax year ISA unless it will be with a differing provider.
Presumably if you had short term liquidity needs I guess ?
Silver Moon. As one example, someone has £10k today but needs to spend it very soon. Later on in the year he is retiring and expecting to get a very substantial tax free lump sum from his pension.
It’s brilliant. I saved up three years of ISA allowance which would have been totally lost. Borrowing and depositing the money for a couple of days at the end of the tax year, and withdrawing it in the new tax year. Repeating this until I could afford to take up all the allowance myself, which I couldn’t before.
Flexible ISAs
My understanding is that you must repay any monies within the same tax year.
This is the case on a cash ISA I hold and was planning to take out some funds, temporarily, but as I say, must deposit them back in the same tax year
Pom, are you saying that you have rolled up 3 years (lets say 3x20k) contributions by only depositing say £1k each year then £57k in arrears? That isn't how I understand the ISARULES. Alternatively you borrowed 20k year one, 40k year 2, 60k year 3 (assuming allowance was the same for each year) at the end of each tax year for a couple of days? If it's the latter, I'm curious about the lender. Banks in my experience, only lend money when you don't need it.
That's correct Samsgrandad. But someone might have a business and possibly borrow from directors loan account each year, for a few days.