Small Cap Value Report (Fri 5 Jan 2024) - NXT, CKN, RBG

Good morning from Paul!
All done for today!
Please note I've added permanent links to my spreadsheets & podcasts in the explanatory notes below, which some readers might find helpful.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Live prices tracking spreadsheet for Paul & Graham's 2024 share ideas (2 separate tabs at bottom),
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs) - search on any podcast provider for "Paul Scott small caps", or web link here.
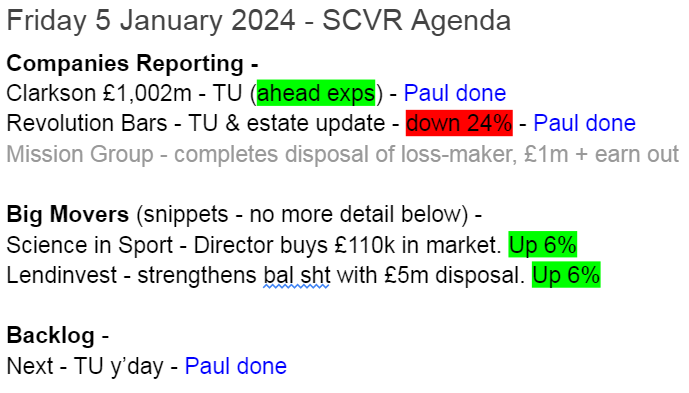
Quiet again today -
Summaries
Next (LON:NXT) - Up 6% y’day 8550p (£10.9bn) - Trading Statement - Paul - AMBER/GREEN
As usual, Next delivers the goods, with ahead of expectations peak trading. 2.3% increase in PBT guidance for FY 1/2024, to £905m, a staggering 19% PBT profit margin. Macro comments are encouraging - buoyant outlook for consumers, and no further selling price rises. Although some risks, eg Suez Canal may cause delays. Shares look fully priced for now maybe?
Clarkson (LON:CKN) - up 9% to 3555p (at 08:59) £1.09bn - Trading Update [ahead exps] - Paul - GREEN
Another positive update from this shipping broker. Broker upgrades leave valuation still looking reasonable at 12x PER (pre-market rise today), despite a strong recent rebound in share price in late 2023. I have no sector knowledge, hence no idea what the future holds, but I'm viewing the performance, and valuation as of today positively.
Revolution Bars (LON:RBG) - Down 22% to 4.25p (£10m) - Trading & Estate Update - Paul - AMBER/RED
Reports OK peak period trading (4 weeks to 31 Dec 2023), with LFL sales up 9%. However, H1 (Jul-Dec) is still negative. No mention of performance vs mkt exps, so I assume in line (broker leaves forecast unchanged). This is a high risk special situation, and I think it could go either way. 8 loss-making sites being closed, could result in an exceptional cash cost to exit the leases I wonder?
Paul’s Section:
Next (LON:NXT)
Up 6% y’day 8550p (£10.9bn) - Trading Statement - Paul - AMBER/GREEN
Strong performance in Nov & Dec 2023 means that this fashion retail leader once again raises guidance - PBT for FY 1/2024 is upped by £20m to £905m (only +4% vs LY though, so limited profit growth).
Note this is a 19% PBT profit margin - astonishingly high, demonstrating yet again that it’s the sector leader.
EPS guidance is 570p, so the PER is 15x - up with events I’d say.
Sales growth came almost entirely from online (up 7.7% H2 to date), with retail flat vs LY. Note there was logistics disruption online LY, giving a boost to this year's comparative.
Cash generation - £100m more “surplus cash” than expected in FY 1/2024.
Net debt at 1/2024 expected to be c.£700m (fixed rate corporate bonds [3.0% to 4.4%] totalling £800m, repayable 2025-28), down £97m in the year.
Remember Next also has a large store card receivables book of £1.26bn (Jul 2023), which more than covers this net debt, so overall its financial position is very good & safe.
Outlook for FY 1/2025 (bear in mind guidance is usually set prudently at the start of each year) -
Sales forecast up 6.0% vs LY (2.5% organic, 3.5% acquisitions like Joules, Fat Face & [partial] Reiss)
PBT guidance - up 5% on FY 1/24.
Macro comments are the main reason to read Next’s announcements, here are some key points -
On the face of it, the consumer environment looks more benign than it has for a number of years, albeit there are some significant uncertainties.
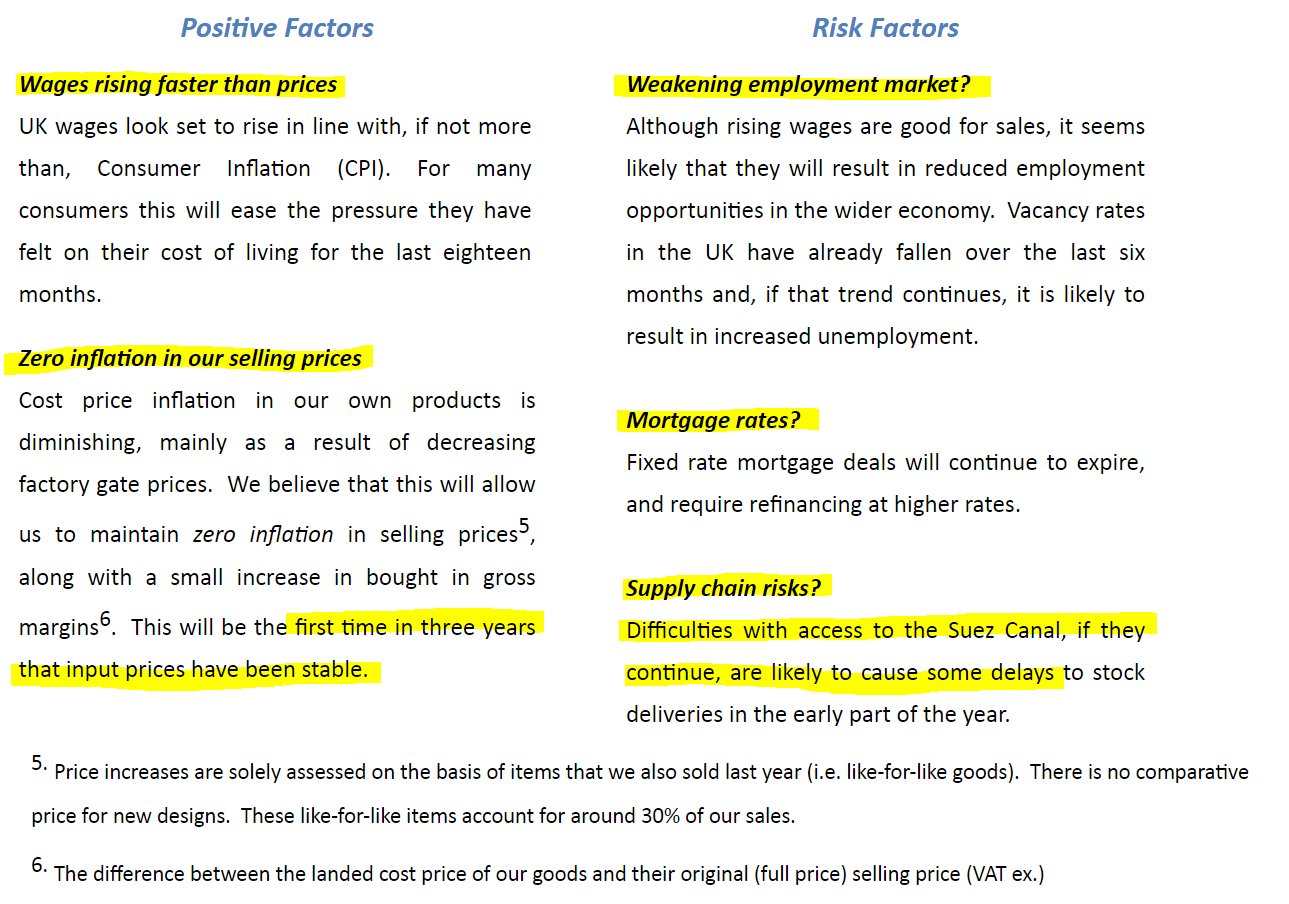
Readers flagged this point below, where NEXT rightly condemns EBITDA! Music to my ears of course, well done NEXT! We need the rest of the city to fall into line behind NEXT, in ditching the absurd focus on often misleading EBITDA figures. Or just give us both! Real profits, and EBITDA, what's wrong with that?
EBITDA?
We will, of course, be including the depreciation and amortisation of other assets with a limited life. For clarity, we will not be joining the companies that quote 'EBITDA' as a key measure of success. Capital spent on assets or technology that decline in value, and ultimately require replacement, must be accounted for in any reasonable assessment of financial performance.
Paul’s opinion - as regulars know, I’ve been a long-term fan of NEXT as by far the best operator in its field, and also brilliant in its communications to investors. Hence its statements are always essential reading (and reporting here) for me.
Everything NEXT has said confirms my positive outlook for retail, hospitality, and consumer spending generally, which is reassuring given how NEXT has vastly more knowledge, data, and experience than me! Hence I'm always guided by its reporting, even though it can sometimes be too cautious.
Shares hit a new all-time high yesterday, and I can see why. However, for me, the PER of 15x FY 1/2024 earnings is high enough, given that profit growth is fairly sedate now, and boosted by share buybacks.
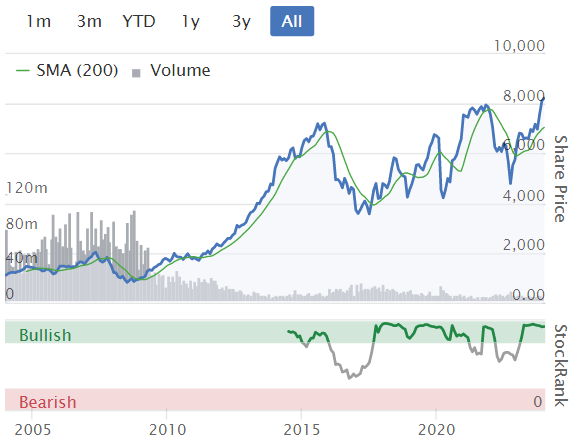
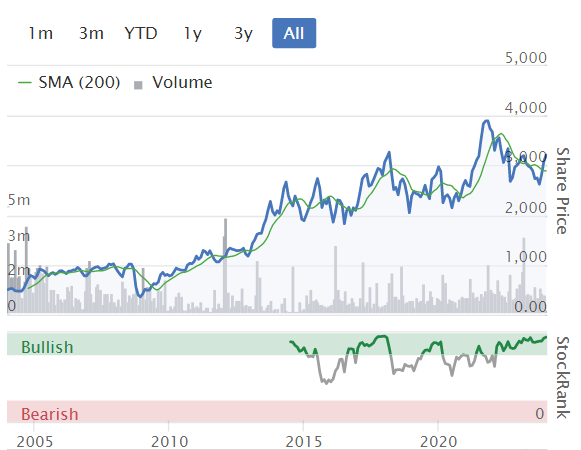
You can see from the long-term chart below, that the best time to buy NEXT shares is when some kind of minor disappointment has occurred, or the market does a general panic sell-off. They always rebound, given time, as nothing seems to be able to knock NEXT off track for very long.
Hence I’ve given it a mildly positive view of AMBER/GREEN - great company, but price probably up with events for the time being maybe?
Clarkson (LON:CKN)
Up 9% to 3555p (at 08:59) £1.09bn - Trading Update [ahead exps] - Paul - GREEN
Clarkson PLC, the world's leading provider of integrated shipping services, today announces that following strong trading throughout the final quarter, particularly from the Broking division, results for the year ending 31 December 2023, are now anticipated to be ahead of current market expectations.
Clarksons' underlying profit before tax, subject to audit, is now expected to be not less than £108m.
Clarksons' results will be reported on 4 March 2024.
It’s good to have revised guidance, but why can’t they mention what the previous guidance was? This is a problem with many companies' announcements. Instead we have to search for that info, which Liberum has provided in an update note this morning, many thanks.
Liberum raises PBT forecast by 5%, but points out it was already at the top end. So I’m guessing that means other brokers might be putting through a larger % rise. Ah yes, here we are - Liberum says consensus was £100.5m, so “not less than £108m” PBT is a c.8% rise in guidance today. Good stuff, although the share price has been very strong in the everything rally of Nov-Dec 2023, so we need to see good performance - as we saw yesterday with JD Sports Fashion (LON:JD.) , any under-performance is brutally punished after a bull run in share prices.
Valuation - normalised EPS forecast is upped from 251p to 266p. That gives a PER of 12.3x - which is lower than I had imagined (Edit: will need to be revised up after this morning's 9% share price rise, I wrote this pre-8 am).
Forecast for FY 12/2024 is almost flat, and then a small 3% rise for FY 12/2025 - so it looks as if Liberum is not forecasting any structural growth, although it’s impossible to say what results will be even 1-2 years in the future, nobody knows. So I see broker forecasts as just a best guess, and nothing more.
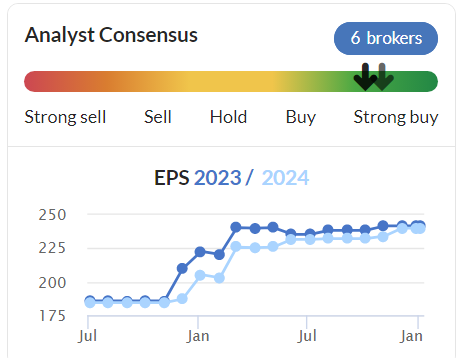
As you can see below, CKN is in a lovely pattern of raising earnings forecasts, with today’s out-performance coming on top of some big previous increases - proving the point that sometimes companies which out-perform continue to out-perform, hence the importance of momentum statistics -
Paul’s opinion - checking my previous notes, we’ve liked CKN before, but pointed out on 6/3/2023 review of FY 12/2022 results that a vast provision for staff bonuses stands out like a sore thumb on its balance sheet, so make sure you check out that issue when considering this share.
Liberum notes this point in its forecasts, where net cash of £373m becomes £113m after taking into account accrued staff bonuses! So if you use Enterprise Value, you very much need to adjust for this, as it's material to the valuation. The costs are expensed through the P&L though, so earnings numbers should be fine to rely on.
Other than that, this share looks very good. Although I don’t understand anything about its sector, so have no idea what the future holds, that’s for you to figure out!
We’ve tended to be amber in the past, due to lack of sector knowledge, but I think we have to move up to GREEN on today’s latest upgrade, and what seems a reasonable PER valuation too. Remember that's just a view of the facts, figures, and forecasts on today's date. We're not trying to predict the future.
Good long-term share price appreciation, plus a reliable 3% yield on top -
Revolution Bars (LON:RBG)
Down 22% to 4.25p (£10m) - Trading & Estate Update - Paul - AMBER/RED
(for the avoidance of doubt I do not currently hold this share personally)
Revolution Bars Group plc, a leading operator of premium bars and beautiful gastro pubs, trading mainly under the Revolution, Revolución de Cuba and Peach Pubs brands…
We’ve regarded RBG here as a risky special situation for some time now, covering it 3 times in 2023, each time emphasising the high risk from a bizarre management decision to max out the overdraft to buy Peach Pubs.
SCVR here on 26/7/2023 at 5.85p, I concluded that RBG shares are a “Special situation, only for risk-takers”. Amber.
SCVR here on 18/10/2023 at 3.2p, I flagged the material uncertainty going concern statement, and concluded, “This could go either way, for risk-takers only. Best avoided for most investors I think”. Amber/Red.
I wanted to get those facts in, as sometimes reader comments seem to mistakenly imagine that I’ve been a perma-bull on this share, which is not correct.
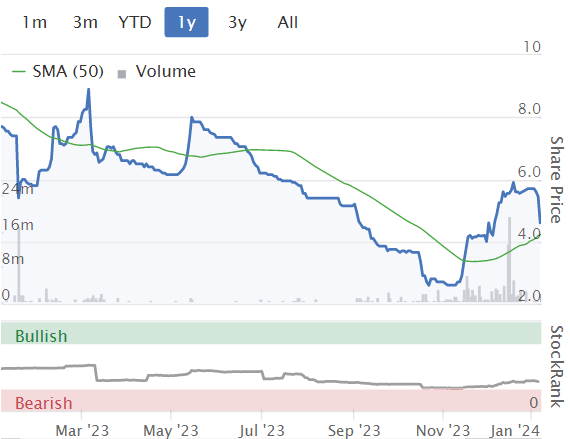
On to today’s news - the market’s initial reaction is negative, with the price now (09:53) down 21% to 4.3p, but only 2.2m shares (£95k) printed so far. That’s despite the company saying it has “traded positively” over the seasonal peak festive period.
My summary -
Peak period (4 weeks to 31 Dec 2023) - LFL sales up 9% vs LY - pretty good I think, but it needs to be at this sort of level to absorb additional costs.
Best festive period since 2019.
The core chain is still dragging down the average (as mentioned before).
Smaller brands, Rev de Cuba, and Peach Pubs “performed well”, but no figures given.
H1 (July-Dec 2023) revenues are LFL down -2.8%, but improving trend as was last reported at -5.5% on 18/10/2023.
Nothing is said about performance vs market expectations today, although Cavendish updates us today leaving forecasts unchanged until a more detailed update is issued near end Jan 2024.
Wage rises - a big sector headwind, as we know, because wages are about 35% of revenues -
…the prospect of the statutory 10.8% increase in the national living wage in April 2024 increases the challenge.
Site closures - 8 bars out of 67 (excl. Peach Pubs) are being closed, to stem the losses. Negotiations underway at 5, no indication of terms (likely to be an exceptional cash cost, as I'm guessing that disposals may well require RBG to fund the new tenant with a reverse premium and a rent-free period).
Net debt - all-important, as this is a major risk, although the bank has been remarkably accommodating in 2023 (see SCVR 18/10/2023 for more info). At 4/1/2024 net bank debt was £18.3m, down from £23.2m at 15/10/2023. Although just after New Years will likely be a seasonal high for cash. Remember though that RBG has a large depreciation charge, so with close to a capex freeze in place now, it should be cash generative - hence why I think the bank is giving it time.
Customers - once again, RBG says its young customers are being disproportionately squeezed on incomes, which I personally question. I suspect they’re spending money on other things, and at competitors which offer a broader experience (eg the boom in experiential leisure such as XP Factory (LON:XPF) [I hold]). Recent press reports also indicate that younger people are less keen on alcohol overall, and are just drinking less (unlike the over-50s).
Paul’s opinion - no change. I still see this as a high risk special situation, which could go either way. The bank debt remains uncomfortably high, but the only covenant is a minimum liquidity one.
I’m worried that the core format is now tired, although the fit-outs were refreshed quite recently with refurbs. Although it’s noticeable from my sample of 1, the Bournemouth site, how quickly customers have trashed the place after its refurb about 2 years ago. There’s really an ongoing need for maintenance capex, which is what Loungers (LON:LGRS) does, rather than letting sites gradually deteriorate in between major refurbs.
Staff at Bournemouth joked to me about the last refurb, saying “We were meant to get a video wall, but all we got was that bloody shark thing!” (pointing to a jaws-like model stuck onto the wall) - because the budget had to be curtailed.
Equity is really difficult to value. It could end up worth nothing, or very little (if another emergency placing is needed, although no indications that is likely). There again, someone might come along and bid for RBG (if a larger group, they wouldn’t need to repay the bank debt), with the aim of refreshing or changing the format. It's chicken feed £10m, to get a chain of gastro pubs, and at least some decent bars.
Consumer spending is likely to rise well in 2024, with real incomes set to rise sharply, that could help improve trading, but there again a big hit is coming with living wage rising c.10% in April 2024.
Overall, I don’t have a strong view either way.
Since it is undoubtedly higher risk, I think sticking with AMBER/RED makes sense. Again to emphasise, this is a special situation for risk-takers only, so would not have any place in a regular portfolio. My only interest here is for relatively short term trades, when it gets oversold. It's not something I'm interested in holding longer-term at all.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

92 comments
The clothes are amazing quality but crazy expensive. I have quite a few second hand items of theirs and they still cost 30quid a pop on eBay/vinted. Often you are looking to pay 2-3 times that brand new. I must note I have zero interest in fashion or brands The clothes are just super comfortable and fit fantastically. I have been tempted to buy into Lululemon Athletica (NSQ:LULU) but it's PE is just ridiculous for a luxury sportswear company.
What would we do without Stockapeda its staff and subscribers?
Happy new year all
That's a blast from the past. Hi-Tec used to be listed in the UK - I had some shares in the 1990s when I first started work and investing. Per wikipedia:
In 1988, the company was floated on the London Stock Exchange.[3] Frank van Wezel bought the company back in 2000. It was privately held through 2013.[3]
They used to be big in white badmington trainers....or was it squash!
There seems to be quite a few companies in the past few days where big institutional sellers (maybe forced in some cases) are having their holdings bought out. Zotefoams (LON:ZTF) , ME International (LON:MEGP), Gooch & Housego (LON:GHH) and Made Tech (LON:MTEC) spring to mind but there are likely more. We are then seeing the share prises rise as the overhang has been cleared. Hopefully this is a positive sign going forward for the markets generally, the added liquidity has to be particularly good news for companies like CMC Markets (LON:CMCX) and IG group (LON:IGG) . I'd like to keep a closer eye on any companies where there has been long term selling from institutions pushing down or limiting the SP to take advantage quickly if an overhang is cleared. The only one that springs to mind for me is Card Factory (LON:CARD) where Tellios have been selling significantly but over time into the market. Any others spring to mind?
Liquidity is very poor and spreads wide. Yesterday I got a price to sell some Cavendish Financial (LON:CAV) , the quoted spread was 12.41 to 13p, sell price I got was only 12p and it was around 3pm not near closing time. I'm seeing quite a few prices, outside the quoted spreads, in the last few weeks or no online trading.
If these large sales are not filled, then then share price, will fall significantly. It may explain why ME International (LON:MEGP) share price has fallen so much recently.
Totally agree Rusty, liquidity and spreads have been shocking and I'm not typically trading large amounts, low 5 digits max. Those trading higher values it must be close to impossible. Here's hoping it improves moving forwards into 2024 and beyond. My comment wasn't stating it's good at the moment, just that if the big boys can get the wheels turning again then retail should hopefully follow, improving liquidity.
Huge volume of 4.5m+ so far in Made Tech (LON:MTEC) . SP up > 15%. £60m revenue, £16m cap, £8m cash. Management hold 43%.
I managed to make some money in Made Tech in the run up early last year, but it's somewhat worrying that administrative expenses seem to be rising at the same rate as gross profit.
Hi David. Mainly on valuation grounds following reasonable interims which contained an in-line outlook. There are so many opportunities in the current market but this just looked too cheap. I like founder led businesses and directors have been buying lately too.
A big thank you to Paul and Graham for sharing the Google sheets, a very generous thing to do. I am a very big user of Google sheets and have all sorts of data. I would also like to commend Paul on his podcasts, 52 was excellent. Keep it coming as you do it, don't get slick by editing it, I love the little asides. Happy and successful new year everyone.
I second that, I love Paul's burps as well.
Hi Orval,
The unusual sounds that Paul usually makes at least once per podcast are 'hiccups' rather than burps.
I have known Paul for 11 years now, and I believe that I have now finally solved the mystery of his obligatory trademark 'hiccup'. It turns out that it is all down to his enthusiasm and excitement for what he does, as we all know he is so passionate about investing in UK small caps, and this causes his 'hiccups'
I will copy / paste here straight from a credible medial site -
Hiccups are repeated spasms or sudden movements of the diaphragm that you can't control. The diaphragm is the muscle that separates your chest from your stomach area and plays an important role in breathing. A spasm in your diaphragm causes your vocal cords to suddenly close, producing a "hic" sound. Eating a large meal, drinking alcoholic or carbonated beverages, or getting excited suddenly may cause hiccups.
Best regards
Neville
Thanks for clarifying that Neville, hiccups they are then. The podcasts really bring the text to life, its hard to tell how enthusiastic Paul is about a share in the weekday reports, but you can tell by the tone of Pauls voice on the podcasts how keen he is on a particular share. Now I know its hiccups brought on by Paul getting excited, I will pay particular note to which share Paul is talking about at the time ;-)
Anyhow, look forward to the weekly podcast, perhaps I really am a boring old man, but its my weekly highlight.
You are right Orval, we must pay particular note to which shares Paul is talking about at the time of his 'hiccups'
I also look forward to Pauls weekly podcast, and maybe I am a boring old man as well at only 58 years old !, but its also a weekly highlight for me.
Paul and Stockopedia and the community here have brought much life and colour to an otherwise lonely interest / activity
Thanks to all for your kind, and very amusing comments above! :-D
Sometimes an "unproductive" cough Paul.
My wife, a background listener who believes you have "an attractive voice", has occasionally noted modest concern.
Zotefoams (LON:ZTF) have issued an alteration to yesterdays RNS re BGF Investments shareholding.
They have added around 3% to their existing holding.
Replacement Holding(s) in Company - 12:47:39 05 Jan 2024 - ZTF News article | London Stock Exchange
Re: Revolution Bars
The key question that Revolution Bars has never fully answered is why it thought it could compete with small privately owned bar owners which make up a significant part of the market. As far as I am aware, all standalone quoted bar companies going back as far as Luminar have failed to meet expectations. There is a reason for everything.
I have known a couple of small private bar owners and seen first-hand the effort required to keep ahead of the market. Rebranding and fitting out every 2 years is commonplace not only to keep the place attractive but to rebrand and keep the offering fresh. I think originally Revolution said 5- 7 years for its re-fitting program?
No real surprise here for me that this share is where it is
Very out of favour Harwood 'biotech' share Trellus Health (LON:TRLS) doing an Angle (LON:AGL) today.I actually had a look at the investormeet presentation yesterday, as its so out of favour and found the management was so impressive on the call and with a decent cash runway (so they say).So decided to buy a punt for a bit of fun this morning and could not get a quote for anything over £500 exactly.Yet no volume seemed to be going through.If it's someone knowing something, i find that very unfair as usual.I would have thought there would have been a huge amount of shares to mop up as the share price is totally on the floor!
And also the preferential treatment some clients obviously get with smallcap marketmakers as trades go to no trade to fill their orders.Even with Nvidia racing ahead, you could always get filled!This sort of stuff does put me off these kind of companies shares.
Hi StrawberryDreams, I share you frustrations at times. In these micro caps the market makers are protected by the NMS (normal market size) which is often tiny value wise... and the very wide spreads. The market makers recognise the dangers of getting short these bombed out stocks as they can become unbuyable and squeezed. When they start seeing demand they can call the price up and show liquidity much higher up. In the case of TRLS I see retail punters were prepared to buy above 7p (about 300k shares). My advice is to perhaps ring the broker and leave with a market maker with a limit, I get this is very uncommercial if you are only looking to buy £500 worth as extra charges kick in.
I bought TRLS on the way down (I'm averaging about 5.75p) but I had noticed it had gone very quiet and there was not a lot of supply. The last penny or 2 falls have been on small volume. I think worth a punt here though, tiny market cap means it doesn't take a lot of good news to get them going. All about position size which I see you recognise. Good luck!
This month marks the 20th anniversary of my opening an account with Hargreaves Lansdown who are still my only stock broker.
Encouraged by Paul Scott`s comments on subscribers performance in 2023 here is my own review.
2023 was a tough year for my portfolio which got off to a bad start. In January I sold Hostmore (LON:MORE) at 11p for a loss of £13.6k. A big mistake on my part due to poor research and bad position size.
I lost £5.4k (74%) on iEnergizer (LON:IBPO^E23) which delisted. I had only held the share for 7 weeks. Cruel luck. I learnt a good lesson to avoid any share with a dominant shareholder.
Then on 22 May I sold Polymetal before it delisted at a loss of £14.9k on just 1,000 shares. I had held these shares since November 2020.
My solitary big winner for the year was Burford Capital (LON:BUR) up 81%. From a low of 547p on 20 March Burford hit 1343p on 8 September. The SP then fell to £10 but on the 27 December it rose 223p in one day a gain of £20k for what is my biggest position. Burford rescued my year as I ended up 4.5%.
My key theme for 2024 is to use a stop loss to avoid damaging losses and to reduce my positions from 29 currently to 15/20 maximum. In conclusion over the New Year I read a quote attributed to Albert Einstein who said "learn from yesterday, live for today, hope for tomorrow". I thought this was very appropriate not only in life but for investors!
Huge thanks to the Stockopedia team for all their work in 2023. I wouldn`t be without it.
I've been on a few of Robbie Burns seminars his screen/buy strategies are so straight forward and simple that you thinking he's holding his real secrets back (he's not) but when it comes to money management he is an absolute master at keeping losses to a minimum.
Most what he covers at the beginners seminars is outlined in his books but the 10% that isn't is pure gold, plus like Paul he's an awesome speaker hence why he's desperately trying to get rid of his audience at 10pm plus at the live seminars.
But his screen on Stocko is average at best.
But the Guru screen is nothing like his actual trading. It is not his screen.Very few on that screen he actually owns. So I would not take any notice of screen. His buy success rate is actually pretty high and he cuts the losers very early. Not sure you could do a quarterly screen that would work for Robbie Burns.
I see that Guru screen excludes AIM stocks, some his best stocks last year, were on the AIM, such as Yu (LON:YU.) Good Energy (LON:GOOD) MS International (LON:MSI) and Knights group (LON:KGH).
The screen doesn't really match his style he will have 5-6 stringent rules, examples being no large debt, chart not in a firm downtrend , he normally will review a share in 5-10 minutes, check strength on level 2, look at the chart and be out if it drops 5 or 10% in short order from his entry. He mainly trades mid caps these days do to his portfolio being larger.
I would guess his strike rate is north of 60% but as I say in my personal opinion his biggest strength is ditching duds before they start to run into losses past double digits sounds easy but super hard to do in practice.
Generally need at least 20 holdings across different sectors to have reasonable diversification. My guess is that you are under diversified.
I was noodling around some of my holdings today to check my convictions and I was really surprised to notice that Games Workshop (LON:GAW) qualifies for the Benjamin Graham Deep Value Checklist. It's not a share that ever looks especially cheap so given the well documented quality on offer and the Amazon tie-up now into the final 12 months "creative guidelines" negotiation stage, I'm thinking this looks as compelling as it has done for some time.
I was pleased to note too that a recent addition of mine, Nexteq (LON:NXQ) also qualifies for the Benjamin Graham Deep Value Checklist.
For those who followed Ed's recent multi baggers webinars, it's interesting to note that Nexteq (LON:NXQ) also passes 7 of the 8 criteria for the 2x2x2 framework screen, 9 of the 13 tests for the Multibaggers: Master Checklist screen and 19 of the 22 tests for the Multibaggers: Extreme Criteria at Breakout screen. With founder Nick Jarmany (now the Non-Executive Deputy Chair) holding almost 17% it also adheres to the founder led attribute of many multi baggers.
I was looking at Nexteq (LON:NXQ) yesterday funnily enough and noticed the same thing re 2x2x2 checklist as well as passing most flags on other screens. Also has a bit of a bowl quality to the chart.
Out of interest why did you add it to your portfolio? This is a company I do not know at all so have to do some research on it
Hi David ,
On Nexteq (LON:NXQ) this should have been trading about 130p- a small upside (about 25%) BUT cannot qualify as a multi bagger.
2018 revenues are about the same as now so unless they increase them I cannot see this breaking the bank.
All the best
Yeah - that's the bit I want to understand better Yiannos
Is there something that means Nexteq (LON:NXQ) has the ability to start delivering strong revenue growth and margin expansion, thus capable of achieving a material re-rating or am I just staring at a business that is broadly a bit undervalued in a sea of equally undervalued assets.
the company passes a lot of screening tests but what's the forward narrative and why.......
Probably the market sees no growth potential as its revenues basically gone nowhere from 2018. Still Nexteq (LON:NXQ) is a good company with a good balance sheet but not for me.
Thanks
I had a good look at Nexteq recently. I am not sure I can vouch for just how strong the forward narrative is, but I suspect the company would point to a number of factors positive for growth. One would be recent product development, including the addition of turnkey cabinent solutions to provide a more integrated package for Quixant and strengthen the overall sales appeal. Another would be the targetting of relatively new sectors for Densitron, including now having a reasonable footing in broadcast and opportunities in medical. The scaling of sports betting across the US as more states embrace legalisation would probably be touted as another tailwind. Broker Cavendish I believe have made a point about the level of integration to customers' products bringing high switching costs, and that then supporting opportunities for upselling and expansion into higher margin contracts.
As I say, I am not sure this makes for a strong forward narrative, but I marked Nexteq as one to keep a close eye on to see if evidence of these mooted tailwinds gaining traction starts to emerge.
David, re @Nexteq (I hold) have a look at PI World video of the last results which should hopefully give you a better understanding of why there is growth potential, link here: https://www.piworld.co.uk/company-videos/nexteq-nqx-h1-2023-results-presentation-september-23/
Thanks all for input on Nexteq (LON:NXQ) - very helpful
Big volume in Gooch & Housego (LON:GHH) Starting to see a lot of volume spikes now.
Gooch Housego
Well spotted huge sales around 7.5 million pounds worth of the company , maybe 6% .
Interestingly price heading north of anything so there is a buyer for sure .
Looks like Octopus have continued to sell down they seem to be exiting a few positions recently
Be interesting who has picked these up my guess is Jonno has overdone the Christmas sherry and could be him
Wasn’t me that’s for sure
Gooch & Housego (LON:GHH)
I wish planetX!
I do like the look of Gooch and Housego, but am currently fully invested. I know that Stuart Widdowson at Odyssean Investment Trust (LON:OIT), which I hold has a reasonable position, but not sure whether he has been in the market recently.
I am partial to a good sherry but more so a nice port especially with stilton, walnuts and biscuits to finish the Christmas fayre.
Best wishes for healthy and happy New Year and of course successful investing in 2024.
c8m ME International (LON:MEGP) traded at the open this morning at 119p maybe there’s a programme trade around…
Sorry a bit behind the curve obviously, been out all morning!
Friday - Another day of yo-yo up and down pricing. Today Bioventix (LON:BVXP) down over 3% for no apparent reason - or maybe its cos according to Stocko info page - it pays no dividend ?
Stocko prices go on the last trade, so if it is a sell, it will show a fall. According to my platform Bioventix (LON:BVXP) has not moved today. 2 of my biggest gainers according to Stocko, have not moved either.
I do find Stocko. prices annoying and misleading.
Google shows live prices.
I have live prices on my platform. This is not about live prices. This is about showing the last trade price, which will show big movements on stocks with wide spreads. If I look my folio on Stocko. a lot of the prices are misleading.
Thanks Rusty and others - you are right - but why is the Stock info page showing nil yield - depending on which page you view - Come on Stocko - please get this sorted
It will be because their data provider has not supplied the information. The dividend is for the coming year not the past one, I think.
I'd ignore 3% moves on smallcaps. You'll find investing more relaxing if you say to yourself "It's just noise".
RM group and Rockwood
Rockwood just increased by over 1% by my fag packet a 600k buy .
It’s one of their biggest holdings plus they are active on the board / actively engaging with management and are almost certainly in possession of knowledge not available to the market so opens a few questions on when aggressive buying by a major shareholder whose team have a board seat leans towards insider trading .
Despite RM issues and debt you have to say the sector is pretty recession proof .
I only have a small position since before Christmas and have already jumped in and out a few times so it is definitely something I have no conviction in .
Increased a touch today just for fun as clearly it is unfolding and to be honest thr Rockwood strategy to unlock the value with disposals and restructuring just looks a case of execution and the value looks to be there .
I see £JD still getting some interest on the most viewed list - there was a good article in the Times this morning (behind a paywall so not given the link) that basically said there could be a few underlying issues - in particular increased competition from the likes of Sports Direct who are starting to strike deals with the big brands, plus a number of smaller high street rivals. They also note that the brands themselves are increasingly selling direct.
I personally have a slight concern that the whole trend for young people shelling out on ultra-expensive sportswear might be starting to fade - after all fashion moves in cycles and perhaps the next generation aren't keen on paying £250 for a pair of trainers.
So perhaps the days of booming growth are over and maybe the share price is actually fairly priced now? I was tempted to take a small position but on reflection decided against it.
I thought the kids were against fast fashion & buying quality stuff that doesn't get thrown away. Are there any young people here?
But I can see Athleisure winding down soon enough - makes me wonder why I bought - although I don't know how long I'll keep it.
I do find retail tends to get over reactions up & down on a single update, but sales/profits tend to be a lot steadier over longer timeframes
FWIW, I buy cheap stuff and don't throw it away!
The big new trend seems to be for 'pre-loved' clothes - loads of start-ups in this area. That certainly wouldn't be good for the likes of JD but I guess good for the planet!
Pre-loved - sounds like fancy talk for 2nd hand!
Wonder if anyone will be interested in my wedding suit - only worn once!
But one of the reasons I own PayPoint (LON:PAY) - get the vinted business!
My birthday suit won't get many bids ....
JD
Something has to be bought as new in the first place to be available as good condition second hand. Probably not much difference between bod buying 1 new top that lasts 2 years if they can sell half price after 1year. If same bod can sell at half price after 1 year they will probably buy new every 2year as its the same cost. No reason JD couldnt have a nearly new area if that made them sufficient wonga.
I watched an interview with the Lululemon athleisure and yoga wear founder Lululemon Athletica (NSQ:LULU) , who wished he had not been persuaded to diversify and sell any of his shares a while back.Also as he loves the sportswear business so much and is involved in some other smaller ones now.I can't see athleisure going anywhere soon.
Working from home has permanently changed dress codes, to some degree.
Certainly could be & maybe JD Sports Fashion (LON:JD.) don't stock Lululemon is the problem - hard to say as always - are Nike/Adidas losing share to a new competitor or is it soft market
My cousin in US is a fashionista (and rich) & the whole family are fitness freaks - she and her daughters swear by Lululemon & even her husband became a convert because of the quality/comfort.
Leggings seem to have made quite the comeback, although my knowledge of fashion is not really something anyone should rely on - it even worse than my knowledge of shares!
Just looked at Lululemon, they seem quite a controversial company. Just put their name in google. Maybe too niche for the UK market?
Hi Bouden,
Very expensive trainers have been 'in' fashion for over 50 consecutive years now. Over 40 years ago I remember begging my parents for the latest pair of Nike - think they were about £50 at the time! Given you could buy a 4 bed house in the south east for less than £50k at the time, £50 was a lot of money.
Safe to say think the days of Dunlop green flash are well and truly over!
One strand of current fashion is for retro trainers eg Stan Smith so would not be surprised if Dunlop Green flash included
I can't believe you can still buy Hi-Tec Silver Shadows new. I reckon Hi-Tec's been making them for 50 years now.
A mere 42 years, apparently!
"The Hi-Tec Silver Shadow was launched in 1981 to conquer the running category ..."
https://www.hi-tec.co.uk/pages...
That’s brought back a memory, I was issued these trainers on joining the RAF in 87!!
Hi-Tec basketball shoes - i used to be the bees knees ... dang !
.
There was an interesting pitch on Dragon~’s den last night, 3 young guys setup a website selling second hand reconditioned quality clothes/footwear..they’re blowing the doors off in terms of turnover, the founder was spurred on by the fact that his sister got £400 trainers for Xmas but they only cost £100 on the second hand market. Definitely a growing slice of the mkt.
Some better volume in ME International (LON:MEGP) this morning. 11x usual.
Looks like there are several large trades at 119p including one at £9m. I don't hold but am watching with interest.
Hoping that's the seller done!!
Wolf, out of interest what's your process for spotting the high volume trades? Is there some kind of filter you use that highlights volume discrepancy to norm or something similar?
Ben, I look for at least 5 x 30 or 60 day average volume.
You can use ADVFN or IG or some of the others tho have to manually put details in. I use Sharepad which does it automatically so can filter the whole market.
Heres todays volume leaders
Thanks Wolf, would be interesting to know if Stocko could add something like this as would be handy to not have to go through the faff of keying it all in on advfn.
Agree Phoenix, surely wouldnt be all that difficult to add.
Hope you had a good Xmas/New year mate.
Hi Wolf just checking and there was a big (ish) volume day also on 15th Dec, I met Andy Brough of Shcroders last summer and this was one of his fave stocks when he was holding court.
Thanks for the heads up today fingers crossed something might be afoot.
Andy
Sorry, but which stock are you talking about?
Thanks Wolf of Small Street - just added this as a column into my sharepad set up. Very useful. Richard
Was about to post a similar comment! I really like ME International (LON:MEGP) and have held previously. Quite pleased buying back in at 118-120p but it’s early days.
ME International (LON:MEGP) This is something I have held since the summer of 2022 and have watched it deliver some great returns, although the last few months has seen some steady selling and continuous SP drop. However, it remains a firm favourite in terms of its fundamentals - its Nov TU showed a minor blip in its feed.me division, but this is a tiny part of its overall profits.
To this end, with a great dividend, strong cash, no debt and excellent ROCE and other fundamentals I am a keen holder and used today as my day to top up again. The large 7m+ purchase this morning (not me for clarity) will hopefully signal a change in perceptions as we move towards the Feb results.
My YE review showed me that I have way too many holdings - and that I need to get more conviction in my best holdings. I think I have a fear of holding too many real £££ in any single company and this means I have a huge PF of many 1-2% holdings. Hopefully today is the first step in trying to rebalance things and get a much smaller portfolio of more strongly held conviction stocks. A WIP but I want to get to half the number of holdings by the middle of the year.
Good luck to all.
Supreme (LON:SUP) . Nice bit of business for Supreme - the CEO is moving things forward nicely
#Supreme plc (AIM: SUP) , a leading manufacturer, supplier and brand owner of fast-moving consumer products is delighted to announce the acquisition out of administration of the trade and assets of FoodIQ UK Holdings Limited ("Food IQ"), the protein manufacturer, for consideration of GBP175,000.
Principally, the acquisition provides Supreme with access to a purpose-built, state-of-the-art, accredited, automated contract manufacturing facility that opened only 18 months ago and cost almost GBP1.2m to build'
Revolution Bars (LON:RBG) updating lacking much meaningful info, although reduction in debt positive, 9% L4L for 4 weeks over Xmas + nye positive but compared to last year when we had lots of train strikes maybe not that impressive.
Revolution Bars (LON:RBG)
My opinion is that Reduction in debt is meaningless also as they are not saying anything about payables. Also increase in sales sounds meaningless as well if you consider the rate of inflation and as you have rightly said the train strikes last year.
All the best
Agree they need to say something about their cost base + with the. Was that they are closing sites not sure the announcement was worth doing if they are giving a full update in a few weeks. Having thought about revs more today I do think there needs to be some changes made and hoofully the new large shareholder will implement positive change
Supreme (LON:SUP) - nice little bolt-on of a nearly new manufacturing facility at a fraction of its original cost. It will assist in increasing their Sports Nutrition & Wellness division capacity by c40%. Not a big deal, but shows their entrepeneurial ability in picking up assets on the cheap out of administration. Ultimate Products (LON:ULTP) also have a similar mindset and pounce on consumer brands in administration.
My morning smallcap tweet: Letting the air out if the week
Revolution Bars (LON:RBG) Minoan (LON:MIN) Woodbois (LON:WBI) Supreme (LON:SUP)
◄Revolution Bars (RBG)► LFL rev up 9% from 4 to 31 Dec. H1 LFL -2.8%. Calls time on 8 less profitable (ie lossmaking) bars. "You say you want a Revolution." Well not if you live in Derby. [SP=5.53 Cap=13m]
◄Minoan (MIN)► extends options which were granted in lieu of remuneration. Project at Cavo Sidero: "moving ahead...on the basis of the existing contract and associated documentation whilst it pursues further commercial discussions and negotiations with more hotel operators, financial and other types of partner". [SP=0.69 Cap=6m]
◄Woodbois (WBI)► CEO resigns, but will continue to provide advisory support. Exec chmn takes on both roles. Claims it's to "enhance decision-making processes and improve operational efficiency". Board wasn't run properly if that's the case. Also "reinforcing the reporting of and competitive capital allocations to its distinct profit centres" to improve financial management and accountability. [SP=0.9 Cap=33m]
◄Supreme (SUP)► buys out of administration of the trade and assets of FoodIQ UK, the protein manufacturer, for £175k. Co gets "access to a purpose-built, state-of-the-art, accredited, automated contract manufacturing facility that opened only 18 months ago and cost almost £1.2m to build". Will increase co's "wellness manufacturing capacity". You can manufacture wellness now? I'll take ten.
Love the reference to Derby!
The weird thing about the Revolution in Derby is the bar Nextdoor is a Revolution De Cuba! Presumably that one is staying open?
Minoan (LON:MIN) - I'm struggling to comprehend that they are still trying to find a partner after all these years. They only seem to keep going to preserve the lifestyle of the directors. I got burnt by them years ago.
Thankfully I've since learnt to avoid these types of jam tomorrow companies, mainly due to the excellent insight & analysis on offer here.
Good morning Paul et al, I have a suggestion, is it possible for someone at HQ before they turn off the lights on a Friday night to put or or two place holders on the SCVR home page to enable readers to discuss the previous week or (I'm sure I’m not the only saddo to research over the w/e) review the weeks going on and the weekend press? In the whirlwind of Monday mornings often things get lost whereas during the weeknd there is more time to focus. I’m not suggesting any more work for Paul, Graham or Roland, just a place for readers/subscribers to post. Thanks!
I don't think they turn off the lights on a Friday night, as they probably never came in to use them.
Excellent proposal Ox’
Also think it is a good proposal - maybe the placeholder can be linked with the weekly podcast?
The only thing I would say is I think it's in everyone's gift to create a discussion post - though I appreciate there is some gravitas to it being titled as a small cap value report and sitting in the relevant UK blogs section.
I think neat tool would be a notification system whereby you're informed if someone responds to your post. I think this would be an equally good way in helping to keep the conversation going / deepen research. Quite often I've gone back to historic stock reports (either from during the week or way before) and felt compelled to reply to a subscriber's really helpful post but thought there might not be much value if no one else is bothering to look so far back.
Jacxx
I have asked for this (via the contact button) but for some reason it doesn’t seem to be a priority, though I would have thought it would greatly increase engagement and also allow discussions between members to be ongoing.
I have also asked if one could received email notifications, as one does for the SCVR, for regular columns such as Mark Simpson or Edmund Shing, but again this does not seem something that seems to have gained much traction.
I struggle to see any downside with either of the above and cannot imagine that they would be difficult to implement.
Regards
Michael.