Small Cap Value Report (Fri 7 July 2023) - PODP, WAND, GLE, HTG

Good morning from Paul!
I'm going to start with a few quick comments, then move on to reviewing a big mover from yesterday, Hunting (LON:HTG) which we flagged here in Dec 2022, as a potentially interesting turnaround.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £1bn. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk.
WANdisco (LON:WAND) (Paul holds)
Suspended at 1310p - Fundraise & unsuspension - Paul - RED
This is the fraud that I got caught on earlier this year, where it turned out that all the incredibly bullish trading updates with massive new order bookings, had been fabricated. I took them at face value unfortunately, even though with hindsight the claims being made by the CEO looked far-fetched (and he was dripping with deceitful body language signals when I met him shortly before the fraud was exposed). Let's hope deep-pocketed US investors haul him into the courts.
I don’t want to waste time picking over the bones of it, but shareholders are at least going to salvage a little scrap of value.
A fundraise of $30m has been done, but at 50p, a 96% discount to the (artificial) share price when it was suspended on news of the fraud being revealed.
It will certainly be interesting to see what the share price does once it resumes trading, scheduled for 25 July.
MJ GLEESON (LON:GLE)
385p (pre market) £225m - Trading Update & Capital Markets Day - Paul - GREEN
Gleeson is a starter homes housebuilder in the Midlands and North.
Background -
Bear points - Shares in housebuilders have been under pressure of late, due to understandable investor concerns about the impact that much higher interest rates are bound to have on sentiment & affordability for new house purchasers.
Housebuilders are also having to bear the cost of cladding remediation (post Grenfell tragedy), and a corporation tax surcharge.
Bull points - valuations are cheap, and in some cases, eg GLE, market caps are now below NTAV, so very strong asset-backing (indicating the market expects asset values to decline).
Forecasts across the sector have already come down a lot, as have share prices, so is the bad news now priced-in?
Balance sheets across the sector are bulletproof, with little to no debt.
The UK’s structural shortage of housing, congested planning system, NIMBYs, onerous environmental considerations, plus little bank financing available for housebuilding SMEs, mean a very favourable demand:supply situation is likely to endure, possibly forever, for the bigger housebuilders.
The latest additional bull point, which I think could be highly significant for GLE, given its relatively small size, and that it builds affordable starter homes, is major institutions now wanting to bulk buy houses for rental. Such a deal was recently announced by GLE, which the broker expects to constitute 12% of revenues in FY 6/2024. Does this plug any gap in demand, and even give the prospect that production could be stepped up, at lower risk, with homes pre-sold to institutional buyers?
Today’s update - starts with 3 positive headlines -
MJ Gleeson plc (GLE.L), the low-cost housebuilder and land promoter, today provides an update for the year ended 30 June 2023 ("FY2023").

My summary -
Completed sales of 1,723 homes in FY 6/2023 (down 14% on FY 6/2022)
Of that, 115 were bulk deals with institutions - so without this element, unit sales would have been down 20%
Average selling price up 11% to only £186k (still very affordable)
Shift in demand - fewer first time buyers (down from 71% to 50%), and more over 55’s.
Restructuring completed - simplified operations, annual savings of £3.2m from now on.
Forward order book is stronger than 30 June 2022 and 30 Dec 2022.
Land available at “sensible prices”
Pipeline is 17,375 plots owned, or purchased subject to planning permission - looks ample at 10-years’ worth (at current sale rate).
Outlook comments defy the investor gloom, and I think confirms my view that focusing on the entry level part of the housebuilding market is likely to be relatively resilient -
Looking ahead, whilst the Board believes that demand from first-time buyers will continue at the levels seen through the last few months, it anticipates that interest from other value-driven buyers will increase as purchasers look to take advantage of Gleeson's more affordable price points and high quality.
Gleeson Land - also has a substantial pipeline, potentially for 17,831 plots, very similar to GLE’s own pipeline. I don’t quite see the point of this division. If land holdings are good, why doesn’t GLE just build on them too, instead of selling them on?
Outlook for this division sounds OK -
Whilst planning delays and economic uncertainty are causing some larger housebuilders to hesitate in completing land purchases, mid-size and regional housebuilders remain active buyers of high-quality consented land.
Cash - is down, but not a concern, as they’re building/buying tangible assets with cash, not burning it -
The Group ended the year with cash balances of £5.2m and no debt (30 June 2022: £33.8m cash and no debt). This was a pleasing outcome given the significant investment during the period in bringing forward a higher proportion of new homes starts.
Overall, as mentioned in the first headline, FY 6/2023 trading is in line with (lowered) expectations -
The Board expects the results for FY2023 to be in line with market expectations.
Capital Markets Day is today, and has this stated purpose -
…will set out a roadmap to significantly scale the Company's operations over the long term.
That’s great, but sometimes CMDs can be designed to drum up demand for a placing. Given the strong balance sheet, I would much rather GLE used a little debt, secured on its properties & land, rather than dilute shareholders when the shares are too cheap.
Presentation slides will be on the company’s website, so I look forward to seeing those when available.
Full year results are due out on 14 Sept 2023, so I’ll be sure to focus on those.
Paul’s opinion - this remains one of my favourite 2023 watchlist shares, and is up 11% YTD (year-to-date) despite the big deterioration in macro & sentiment.
Today’s in line update, and perky outlook further reinforce my positive view of this share.
Obviously the main downside risk is macro, so housebuilders won’t interest anyone with a gloomy view of the future for house prices, interest rates, etc.
I think it’s a good buying opportunity, for patient investors, who don’t get spooked by short-term share price weakness. Or investors who are happy to drip feed money into decent companies.
Pod Point group (LON:PODP)
Down 11% y’day to 64p (£99m) - Directorate Change - Paul - RED
Pod Point, one of the UK's market leading providers of Electric Vehicle ("EV") charging solutions…
It’s not just any old Director resigning, it’s the founder CEO, who has been running Podpoint since founding it in 2009. He’s stepping down with immediate effect. So clearly things can’t be going well.
A NED, Andy Palmer, has been appointed interim CEO,
… to enhance operational performance and deliver sustained shareholder value for the group.
Paul’s opinion - I reviewed PODP here in Nov 2022, coming away with a very negative impression, of a fashionable-themed IPO, which doesn’t have a viable business model at this stage (if it ever will?). Historically it has just burned cash, mainly selling low margin individual home charging units for EVs.
The only positive about PODP is the cash pile. It had £73m NTAV at Dec 2022, including £74m cash. But it guided that cash burn was expected to be substantial in 2023, reducing cash to £50m by year end. Bear in mind that deferred income (a creditor that measures how much cash has been paid up-front by customers) was £21m at Dec 2022), so I would deduct that figure off the cash pile, to arrive at a clean cash figure.
It seems to me the cash is simply being squandered, so the wide-eyed visionary type of founder CEO departing, strikes me as good news, in that a more sensible, less profligate strategy might be adopted by new management.
Bottom line, I don’t see anything attractive about this share to date, but the cash pile gives them options to re-mould the business into something that might become commercially viable after a restructure. We need to see some evidence of that first. Building the charging infrastructure for EVs is a noble aim, but subsidising this is the job of Govt. So why would I want to own shares in a company that generates heavy losses installing EV chargers?
PODP shares look the type of thing that’s probably going to continue trending down, tracking the reducing cash pile. With the occasional speculative spike up on positive news announcements (giving trapped instis a good opportunity to sell into the spike). So I think private investors are likely to be subjected to a PR effort, to induce us into being the buyers (lambs to the slaughter) to help the instis exit from their poor investment. I won't be participating in that game, for sure! So it's a thumbs down. RED.
Hunting (LON:HTG)
249p (up c.22% y’day) £410m - Trading Update & CMD - Paul - GREEN
We should have covered this yesterday, as it was a big positive mover on a trading update, so I’m prioritising looking at it today, to see if the move was justified.
Background - to get me up to speed, I’ve looked at our notes here - we’ve covered HTG three times in the last year, as follows -
25 Aug 2022 - 256p - Breakeven H1 results. Upbeat outlook - strong order book, macro tailwinds. Superb bal sht & reasonable divi yield. Paul - worth a closer look. AMBER (due to my lack of sector knowledge).
15 Dec 2022 - 269p - Good TU, raises guidance to $85-90m EBITDA (prev. $80m). Graham - GREEN.
30 May 2023 - up 15% to 232p - Major order, and guidance raised again. Very strong bal sht. Looks interesting as a turnaround. Paul - AMBER.
Here’s the latest news, from yesterday -
Hunting PLC (LSE:HTG), the global engineering group, today issues a trading update, ahead of its Half Year Results to be released on Thursday 24 August 2023.
The current financial year is FY 12/2023, so H1 is 6-months to 30 June 2023.
Key points -
H1 ahead of mgt expectations.
Strength in most international markets.
Both revenue & operating profit head of targets set at start of 2023.
H1 guidance: EBITDA $48-50m
Order book has grown in H1, $530-550m at end June 2023 (31 Dec 2022: $473m)
Net debt guidance: $51-52m at end June 2023, expected to be paid off in H2.
Capital Markets Day to present strategy to (usually institutional or HNW) investors: 13 Sept 2023. Hopefully they will also engage with private investors too somehow, even if it’s just publishing the slide deck. Ah yes, here we are, good stuff -
Hunting's management will provide a live presentation via the Investor Meet Company platform on 24 August, commencing at 3:30pm (UK). The presentation is open to all existing and potential shareholders.

This all looks impressive. Clearly the group is on a roll.
"The outlook for 2023 continues to be strongly positive, with 2024 revenue visibility also improving due to the orders secured during the period."
Broker update - many thanks to Zeus for its number-crunching.
Note that EBITDA is an inflated number, I tend to much prefer adj PBT, with the latest Zeus forecasts showing the big difference -
FY 12/2023: Adj PBT $56.3m (based on EBITDA $96.8m) - adj EPS $0.257 = 20.2p = PER 12.3x
FY 12/2024: Adj PBT $83.6m (based on EBITDA $124.8m) - adj EPS $0.382 = 30.0p = PER 8.3x
Forecast divi is about 8p for 2023, and just over 10p for 2024, so a yield of 3.2%, rising to 4.0% in 2024, and importantly these divis are comfortably covered by earnings, and easily affordable from its strong balance sheet. So the dividend paying capacity (more important than the actual yield, in my view) is very good.
Although do bear in mind its main markets are energy-related (oil services), so can be very cyclical, and I suppose probably vulnerable to long-term redundancy, when we eventually curtail or even stop burning fossil fuels. Maybe there's growth in other sectors, like offshore wind?
That could mean a permanently low PER, as maybe some investors might want to avoid the oil sector?
Balance sheet - is amazingly strong. NAV of $846m, less intangible assets of $191m, gives NTAV of $655m, or £516m. That’s 26% above the market cap of £410m, which seems an anomaly. This hidden store of arguably excess mainly working capital could be attractive to a financial buyer, who could load the business up with some debt, and cut back on its rather high inventories and receivables, possibly?
There are no dominant shareholders, so that increases the possibility of a takeover approach, I imagine. So this could easily become a takeover target I reckon - nice potential upside possibly?
Paul’s opinion - looks positive to me - guidance keeps being increased, orders are up, the PER still looks reasonable, and the balance sheet is bulletproof. Nice, well covered divis too. Plenty to like here.
On the downside, I think you would have to properly understand the sector, and cyclicality, which is not my area.
Plus it looks a possible takeover bid candidate too, maybe from an international buyer?
Hence overall risk:reward, just on a quick review of the numbers, seems good to me.
Quite a nice looking chart. StockRank is upper medium at 63, but should improve as improved quality scores feed through from the move back into significant profits -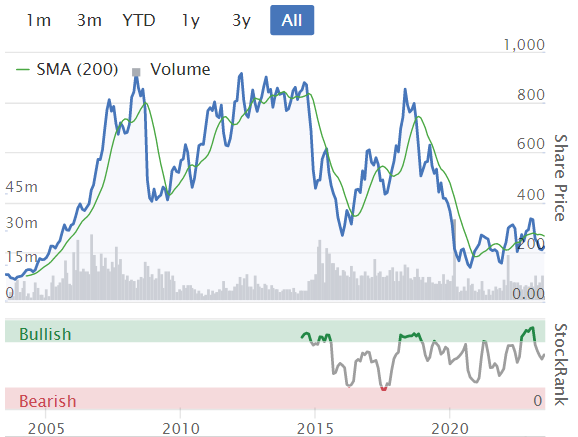
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

55 comments
Thanks as usual Paul for your interesting podcast . Find it very hard to understand though how you managed to find , what you describe as an intelligent 25 years old, who does not realise you can earn interest on savings .
I asked my 14 year old grandson did he know what interest was, and he thought I was losing the plot !! When I explained why, he said “ that woman must be a plonker “ :) I agree
I am surprised that there has been no comment here on the 24% collapse in the price of Alfa Financial Software Holdings (LON:ALFA) following the withdrawal of the buyout offer by EQT at 208p.
At the time of the offer it was described as “irrevocable” , it would seem that in the City this means something different to what it would seem to normally imply.
Osb (LON:OSB)
I've just had time to look more closely at the wording and realise that the share price reaction appears to be even more strange than I thought.
IFRS 9 means the bank has to recognise revenue evenly over the expected life of the mortgage. Most mortgages will be 20+ years. Osb (LON:OSB) now think customers will spend an average of just 5 months on the reversionary yield over the life of the mortgage. Given a lot of these mortgages will fix for 5 years then in reality they are saying on average it's 5 weeks each time they reach the end of their initial term.
That means the £160-£180m charge should apply over the average duration of the entire loan book which will probably be well north of 10 years.
So in essence this announcement is saying that cash profits are being hit by maybe £15m p/a
Given net profit is expected at £423m p/a this is a 3.5% reduction in annual profits so a 28% fall in the share price appears to be utterly bonkers and an enormous over reaction.
The size of the charge is due to the accounting recognition taken upfront but actually spread over many years. Wouldn't surprise me to see this reverse as interest rates peak and landlords wait it out to re-fix.
As a negative management have done an appalling job on explaining this in terms their investors understand and why they put it out after hours is beyond me. I plan on contacting them for an explanation.
Unfortunately can't find any research to confirm my understanding but wow - now on a PE of 3 !!!!
I don’t think you realise how the market works in this sector- their underwriting abilities are not to be trusted anymore and this is why the price collapsed.
Hunting (LON:HTG) : One of the reasons I invested is that they say they are seeking out other markets for the longer term rather than concentrating on just oil exploration.
The trading update said:
Hunting's Advanced Manufacturing businesses are also seeing good growth in both energy and non-oil and gas markets.
The Group has made good progress in its strategy to position itself in the
supply chain for energy transition markets. The strategic alliance with Jiuli, announced in June, enables Hunting to deliver key technologies and products to clients in the geothermal and carbon capture sectors, which management believes will lead to strong sales in the short to medium term.
Fingers crossed for a successful pivot.
It was also covered in Mark's article on Extreme Value Investing: Screening for Net Nets on April 12 - an interesting read which says "Hunting is finally expected to be profitable again in 2023."
MJ Gleeson (GLE) Just a quick point on house prices the current market reminds me of the early 70's where real house prices fell significantly but because of the very high rates of inflation we had back then they pretty much stayed the same in nominal terms.
I just read the annual report from the Halifax who claim house prices have fallen by a average of 2.6% over the past year. after two years of 10% inflation that amounts to a significant fall in real terms even though in nominal terms they haven't moved much.
Myself I think they have much further to fall the enormous increase in house prices over the past 20 years has largely been driven by Interest rates falling ton close to zero and mortgages that used to be calculated on 3 times the largest income of a couple plus the smaller to up to 5 times the smaller now we are starting to see that reverse.
If you look at the very long term rise in house prices they were still going up during periods of 'normal' interest rates, so population growth and lack of supply ( the same thing ) must be included in reasons for increase.
House price adjustment will happen as you said it.
Inflation of 5% over the next three years with 5% in house prices over the same period equals to 30% drop which I guess is what we expect.
But you are missing wage inflation over that 20 years which is significant. If wages double over 20 years then house prices can double on the same basis. The 4-5* earnings is actually more normal than the previous 3* which was quite UK specific so that’s not going to change dramatically either.
Then factor the large proportion of homes owned outright and people’s price anchoring. What you’ll see is a big drop in supply (has already started in the higher echelon brackets).
Also Expect stamp duty to be targeted for a big drop in coming budgets to generate demand.
Also factor in what it costs to build a new home, it has massively risen labour rates are up, they wont fall, bricks remain key and until energy drastically falls bricks won't be sold at a loss, many other materials are up and are globally set eg copper for wiring, plastics are costly pipes etc. House builders wont sell at a loss. The population is going through the roof where do 200 000 new people go every year ? I suspect we will have a lull and stagnant market, something will have to give on new homes. If there are no new homes hopefully prices remain steady. I'm a landlord having sold two properties but I retain two. Plainly Gov policy is to make landlords feel much pain, its working, I think the Gov is happy to see rentals becoming corporate, but why ?
Pod Point group (LON:PODP) Am I the only one who sees LON:POOP?
Hunting (LON:HTG) i have held Hunting previously in 2020 for around 6 months purely as a net net play, so i know a little bit about the company.
my personal opinion is the business is run far too much for the benefit of the senior management. As an example in 2022 the renumeration committee set the CEO's annual bonus target based on achieving a 1% return on capital employed and $1.9 million in "adjusted" pre tax profit. The targets were un-suprisingly hit, but for which the CEO was paid $1.5 million in annual bonus. The CFO received roughly half a million. Going back over the annual reports, you'll see a similar pattern year on year, where senior management are massively over compensated for achieving nothing in real economic value.
i struck me as a business whose cash ends up either in the warehouse yard or in the pockets of the senior management. After a cash outflow of $38mill this year the management still saw fit to purchase $7million in treasury shares to award themselves for future bonuses.
Not sure if anyone has a different take on the company?
Practices seen far too often and no PI voting powers to speak of.
agreed, i also think a focus on EBITDA as a performance metric for a business which is so capital intensive should also be a red flag to watch out for. As well as reports and accounts which are far too complicated for such a simple business.
Capital (LON:CAPD) (I hold). Are establishing a dominant position in the photon assay market via their majority holding in MSALABS (over 80%). News release today.
Its not a share covered by Paul & co., so I was wondering if there are any mining experts in here who can add further insight for me? My analysis is as follows:
Majority of current revenue comes from deploying and operating mining rigs. Growing and profitable but capital intensive.
Fast growing deployment of Chrysos photon assay technology (via MSALABS) that is set to replace traditional techniques (not just for gold but other metals also) (they are not a unique supplier but are now the largest in the market). Currently accounts for circa 10% of revenue but growing at a steady rate. It strikes me that there is a significant moat here. Once deployed a mining company is unlikely to switch supplier. I can’t get sight of the licensing arrangement with Chrysos.
Chrysos do license direct to large mines and other labs but MSALABS are now the largest supplier and possibly have a deployment advantage in their tie up with Capital (LON:CAPD).
Capital (LON:CAPD) have a price target of between £1.50 and £1.80 according to 5 brokers.
The share price chart shows a rising channel. Current share price is in the lower end of this. There is a potential cup and handle formation that would Also give a price target in the region of £1.50. (Just speculation not the point of me writing this).
The recent long term incentive for the current directors is clearly linked to TSR which I approve of.
On a negative note the 2 founders recently sold a chunk of shares, however they still own over 10% of the company and may simply be realising cash as they get older.
I’m thinking of increasing my holding so any further information, particularly on the photon assay technology rollout would be appreciated.
WANdisco (LON:WAND) - what a saga, Paul - looks like us little people will find our holding valued at circa 5% of the last, admittedly false price - and meantime even the new management and their advisors at a loss to understand that they need an AGM to agree the new share listing, with a belated RNS earlier this week. Meantime how many months - or years will we have to wait for the fraudsters to be brought to court and indeed the auditors to be held to account.
A buying opportunity?
The market is falling partly because there is intense competition for our cash. The 5 year gild is priced at 85 p which means you get a 100 p in five years and on top of that you get a pay out every year, yield of 5% tax free too. With some investment grade corporate bonds you get 7%.
This has made the equities less attractive. The big money has gone for fixed rate and there is less demand for equities.
For retail investors( who can not participate in the fixed income easily,) this is not a bad thing. we can buy good companies much cheaper than before.
Hi Lucky Dip,
Yes absolutely, I agree - as you say, fixed interest looks very attractive right now (especially if higher interest rates are temporary, and start falling again next year & after).
So I totally agree that equities should be cheaper. Things that were priced on PERs in the twenties (or even above) in the last 15 years of zero interest rates should now be much lower. That's why we challenge high PERs every times we find them, in these SCVRs - are those premium ratings still justified now?
Before 2008, I remember you could buy quite good companies on PERs of about 12. We should be resetting our expectations for shares back to that sort of level, only venturing above it when a company is demonstrating exceptional growth.
Some commentators are saying that higher interest rates won't stick, because Govts cannot afford to service their huge debts in a permanently higher interest rate environment. So maybe we could see a return to QE and zero interest rates at some point in the future? That would be incredibly positive for equities of course, and horrible for fixed interest (if the maturities are medium or long term).
Lots to ponder!
Regards, Paul.
Things that were priced on PERs in the twenties (or even above) in the last 15 years of zero interest rates should now be much lower.
I think that holds true for the UK stock market in these times of international neglect. But it's important to recognise the changing nature of the constituents that make up the market, especially in the US. Once overwhelmed by oil and industrial giants, the S&P500 is now a tech index, dominated by companies with astonishing cashflow generation and the very highest quality of earnings (margins, returns etc). It is entirely sensible that valuations should have fallen since 2021, but equally reasonable that, even with interest rates back at 2007 levels, valuations should settle at a materially higher level than in the days before FAANG etc. As an example, Nvidia, which I'm sure almost everyone on Stocko agrees is expensive, is actually cheaper today, relative to its most recent growth forecasts, than at any time in many years!
In other words, the valuation gap between UK and US isn't just about neglect. It's a market of stacks not a stock market, and the ones in the US are simply superior businesses on a vastly greater scale in a much more dynamic economy. That isn't to ignore the value opportunities here or to denigrate all UK companies - I own a good number. But I am relieved to have taken an internationally diversified approach.
Hi BnB
With reference to your final point .....
But I am relieved to have taken an internationally diversified approach.
Just this morning I compares FTSE All share vs S&P 500, Nasdaq Composite, DAX & CAC 40, for one year then five year. I could have used other indices such as Netherlands, Sweden, Itsaly etc, but these major ones illustrate some points about diversification across markets.
For several years I avoided investing into US or European sharers because of concerns about FX costs on top of trading costs. Thankfully I put these concerns aside and simply seek out great companies across multiple indices. Firstly, researching these great companies wherever they are (restricting myself to what my platform (Hargreaves) supports) is incredibly stimulating I find. Secondly as you note it provides a powerful diversification of economies, currencies, sector strengths (e.g. US tech, European fashion for example). Finally, in my experiences, it helps a portfolio to weather the ebbs and flows of both global but also local market volatility.
One year here ....
Five year here ....
Regards
Howard
Publication of results for FY23 from Creightons (LON:CRL) today. (I hold.) I think it is in line with their previous guidance, about six months ago, perhaps better rather than worse. Interesting and mixed picture. I have continued to hold because demand at their end of the market should hold up in recession, and management has impressed me here. Both are borne out - vigorous action has been taken to cut costs and maintain cash flow, and sales of own branded goods have been strong, or at least have risen in line with inflation. This is about half the business. Their acquisition of Emma Hardie has been justified, I was a bit sceptical at the time. The other half of the business - private label and contract sales, historically the larger part of this business - has been weak. There is a lesson for me here - strong brands properly managed survive. The other negative point is that they are in what is necessarily a competitive business, and net margin is not that great. Operational leverage is not what you want in a recession. I will continue to hold - at a price to sales of 0.35 there is room for a higher share price.
Management has been good at Creightons (LON:CRL) previously but I think their capability has come into question with the expensive acquisitions, the way they were structured (having had to pay out for falling short of share price), and their cost and price controls during an inflationary environment. They also have variable cost debt which is not great right now (albeit only cost them £111k in interest in most recent financial year)
It is good to see H2 is looking better but op margin is still only at 4.4% and revenue has fallen - never a good thing in an inflationary environment. Doubling H2 EPS would give about 2.6p so I think a good entry point might be below 30p which this has just hit this morning but I am a bit nervous about the falling revenue.
Also, what do others think about the balance sheet? Cash on hand isn't great.
Margin was an average of 4.4% for H2 - which was a significant improvement on H1. So the exit rate likely better than 4.4%. Gross margin is up. Revenue has fallen from contract manufacturing, presumably their competitors are choosing not to pass on price increases and are seeing margin erosion. To counter this their branded sales are up significantly and they're investing in new markets both domestically and internationally. They seem to have put a lot of store in sun cream, we'll see how that pans out for them I guess. Their net cash is -£1.2m, not exactly massive given they reduced this by £900k over the previous 12 months and the one off cost for the Emma Hardie purchase was £300k, again not a massive figure and shows that actually cash generation is better than it appears. So, the variable rate debt issue and the margin issue are likely not that big a problem.
Expensive on last year's earnings figures and the lack of outlook statement / current trading is a worry. I'm long.
To be fair to them on outlook Creightons (LON:CRL) never issue that. Sometimes they say some words about outlook on any investor presentation - I haven't seen that they are doing one this year? I wonder if Tamzin has something lined up as they've been on PIWorld a few times in the past
MJ GLEESON (LON:GLE) Morning all. You’ve given me an excuse to make my first comment, But firstly I must add my appreciation for the detailed updates, podcasts and general discussion on the small cap forum, this section is worth the subscription alone IMO. My simple point Paul is you have listed this as RED, is that correct as the narrative suggests otherwise. Thanks in advance.
Good morning G Ellis, and thank you for your kind comments! And welcome to Stockopedia too, as it's your first post! :-)
Yes, you're quite right, I mistakenly coded MJ GLEESON (LON:GLE) as RED, when I meant GREEN, since corrected. Apologies for the typo.
Regards, Paul.
Paul, you have MJ GLEESON (LON:GLE) marked as “red”, which I assume is a mistake from your commentary?
Thanks MattH! I've no idea how that happened, I've corrected it now. I'm firmly GREEN on MJ GLEESON (LON:GLE) - many thanks for pointing out my mistake. My excuse is that I've got family staying with me this week, and have got 3 people chatting & making breakfast in the same room with me right now!
Medica (LON:MGP)
That's it folks, takeover completed and so listing cancelled this morning.
I bought in January 2020 and have received a total return of 43.67% - not bad since the FTSE SmallCap Index, of which MGP was a part, is fractionally lower now than then. Like others I thought the bid was a bit low but no-one else came with a better offer.
This post is to thank those of you who were around at that time for the lead. There was a competition then - homepage at https://www.stockopedia.com/ch... The following year another https://www.stockopedia.com/ch... but both now result in :
The 'erase the past' brigade are active here in Stocko despite Ed calling it a tremendous resource:
One feature it gave was a table of shares entered by most popular with the ability to select subscriber, non-subscriber or all. I selected subscriber (non-subscribers tended to go for mining/oil stocks of less than 1p) and after some research selected a couple of shares from the top of the table to buy. MGP was one - the other? - Volex (LON:VLX) bought at 161.8 and 278 as I write, after almost 500 in the small cap tech bubble of Sept. 21.
Thank you.
I've held on to Medica (LON:MGP) just in case there would be a higher bid. As the takeover is now complete, when will the monies be credited to my account? I could use the money for some more purchases!
Medica (LON:MGP)
The money has to be despatched within 14 days of the effective date (yesterday).
The money has to be despatched within 14 days of the effective date (yesterday).
This is correct and when it arrives I was looking to put some of the money to work elsewhere in the healthcare sector. Is anyone else keeping tabs on the situation at EMIS (LON:EMIS) ? The share price is in the same range as it was prior to the £19 offer from United Healthcare and so it seems the market is saying the deal is 100% off, and yet the CMA final judgment is due in October. It seems something of an asymmetric bet at this point i.e. 50% upside if the deal goes ahead with maybe a 10% downside on news of the deal not going ahead. Something of a special situation to ponder...
I agree and purchased some EMIS (LON:EMIS) recently using the exact same reasoning.
RE: Medica (LON:MGP, EMIS (LON:EMIS)
Yes, in exactly the same situation. I held onto Medica in the hope of a possible counterbid but sold EMIS because the price looked full.
I think EMIS is interesting, but I suspect that if the bid fell through then in the current market the share price would drop again. Given the rise in interest rates since the bid I wouldn't be surprised if the bidder walked away if given the chance - e.g. CMA condistions triggering a break clause.
On the other hand, if it's approved then you're looking at a 40% rise. Given that there don't look like any issues in the underlying business that's probably a decent risk / reward - basically anything bought now is likely to fall next week, anyway ...
timarr
I think EMIS is interesting, but I suspect that if the bid fell through then in the current market the share price would drop again. Given the rise in interest rates since the bid I wouldn't be surprised if the bidder walked away if given the chance - e.g. CMA conditions triggering a break clause.
Yes, agreed, but I'm surprised the purchaser hasn't walked away already given the extended period of the CMA investigation. The acquisition is very small for the acquirer and so I'm not sure that an increase in interest rates would have that much effect on their decision given they have $30bn in cash with Net debt/EBITDA < 1.
On the other hand, if it's approved then you're looking at a 40% rise. Given that there don't look like any issues in the underlying business that's probably a decent risk / reward - basically anything bought now is likely to fall next week, anyway ...
OK, I'm being thick here. What's happening next week? Fed meeting? I'm not expecting the proceeds from Medica (LON:MGP) to hit my account next week necessarily, so that's not really a problem and any news prior to October is only likely to be bad, so there's no rush. Besides, I quite like lower share prices when I have cash to invest :)
All the best, Si
You're not being thick. I merely meant that everything is falling so that what looks cheap today will be cheaper tomorrow.
And yes, you're right. EMIS isn't a major purchase for the acquirer.
timarr
That's it folks, takeover completed and so listing cancelled this morning.
I bought in January 2020 and have received a total return of 43.67% - not bad since the FTSE SmallCap Index, of which MGP was a part, is fractionally lower now than then. Like others I thought the bid was a bit low but no-one else came with a better offer.
I first bought in January 2019 and added more in 2020 for a total return just over 90%. I'm more than happy with that and feel whichever valuation multiple you use that the 212p offer was fair. It's a good company but not a top, top quality one, so a take out at 20x FY23 EPS estimate is a decent result IMO. It's a pretty good time to receive the funds to re-invest in some good cheap companies too.
All the best, Si
Osb (LON:OSB) rather bizarre over reaction here this morning to last nights trading statement. It’s low volume so I can only think it’s retail investor piling out who don’t understand the implications.
In essence they are taking a circa £160m non cash charge to p&l. But actually this is an up front hit to something that impacts the expected cash flow evenly over the entire life of the loan book which will be 5 or so years in Osb (LON:OSB) case. So it’s really lowering future years forecasts by about £30m per year. that’s about a 5-7% impact so a 17% fall looks way overdone.
The rest of the trading statement was ahead of forecasts. Costs down more than forecast and NIM up more than forecast and flat to last year over H2.
So this is a bank on a cost income ratio in the 30%s trading below its own capital value with an EPS of circa 100p now on a PE of 3 paying something like a 10% dividend….and it still falls 17%! It really only deals with professionals and the LTV is really quite low.
The volume is mostly bots trading, very little in the way of real shares changing hands from my observations.
I think at least a 10-15% drop is warranted, but markets always tend to over react so not at all surprised to see it down around 20% now. It's not just the significant hit to the loan book, it also raises question marks over their ability to model future cash flow, and out of hours trading updates never look good. That said it was already very cheap and even cheaper now.
Now down 26%, looks like an over reaction. We will see, I hold. With rates now so high, no surprise that customers are switching quickly, when their fixed rate mortgagee finishes.
It's probably very naive of me but I hadn't realised Osb (LON:OSB) baked in such large expectations of customers sitting on the reversion/variable rate. I agree with what others say that you would think their modelling would predict customer behaviour on this front in light of the rate of interest rate increases and the projections going forward.
Side note, but with the level of government intervention these days (not intended as a political comment) you'd think banning or curtailing banks' ability to put customers on variable rates must be under the spot light. I can see the argument for requiring the bank to automatically port a customer to a lower rate at the end of a fix (perhaps linked to the current fixed rate offerings) rather than just leaving them on the much more expensive variable rate. In today's favoured terminology it's difficult to see that as anything other than a "windfall".
Banks already have to give enhanced notice of expiry of fixed terms, but I could totally see someone looking at low hanging fruit for fixes to the cost of living crisis/surging mortgage payment costs to go for something like this. Clearly, such a move would be bad for OSB and co. Or perhaps I'm just spouting nonsense...
I’m astounded at the drop but I guess that’s the state of the market at the moment with such low levels of liquidity. People just sell indiscriminately and it craters the price.
The reality is that the reversionary period baked into their models is now just 5 months so that’s unlikely to change much lower. I suspect in 6-12 months we are going to see a large swing the other way because rates will be peaking and landlords will be waiting for a drop in prices before fixing when existing deals expire.
It really is bizarre that an effective 5% change in forecasts has led to a 27% drop in market cap. This really is a horrid market, particularly in the Uk alas. Better off elsewhere. I am considering quitting investing in UK companies and moving abroad as the market is fundamentally not working. Very very dislocated.
I agree that the out of hours announcement was a stupid thing to do but it doesn’t throw into question their modelling. Models change as people evolve to macro events and this one is notoriously difficult to predict accurately.
Has anyone else been caught by last night’s announcement from OSB? Brutal market reaction this morning. Hopefully, this will be a one-off profits hit, but the market will want to know if anything else is lurking. This was such a market darling as well. Ouch.
RE: Osb (LON:OSB)
But who could have anticipated that a huge rise in interest rates would lead to customers remortgaging off exorbitant standard rates more quickly?
timarr
It’s not as simple as that. If you are remortgaging a series of properties you may well stay on a higher reversionary rate if you believe interest rates are peaking or coming down. Most professionals will look to time it so there is always a reversionary period. You just have to work out what it is and when anything changes meaningfully you adjust the model.
The IFRS rules though are that when you adjust the model you take the hit for all future years immediately in the p&l. Hence the headline number isn’t the real number or a drop in cash profits and it looks like investors haven’t understood that.
Even so, that still looks like a big adjustment to my untrained eye. A victim of even higher for even longer, perhaps?
Osb (LON:OSB) Spotted it last night and sold first thing this morning for 10% hit. Very disappointing when companies put out these out of hour announcement, which just creates a sense of panic. It looks like their modelling was completely out, but it seems blindingly obvious that borrowers would look to refinance their mortgages rather than pay the sky high reversionary rate (which is what they had seemed to be assuming in their models). Just gives a sense that they're not on top of things so will stay away for now until things settle.
Hi Paul, if it's a light day today, would there be any chance you could have a quick glance at Quiz (LON:QUIZ) ? I know its small, but there are a few holders on here and your view is always appreciated. Many Thanks Andy
For those interested in WANdisco (LON:WAND) the new Ceo did a very interesting interview last year, well worth a listen. https://podcasts.google.com/fe...
Trying to stay positive (!) I have recently realised how lucky we are to have as our UK registry Companies House. It's easy to criticise them but I had to carry out research into a German company (Fackelmann GmbH who are continually increasing their holding inPROCOOK (LON:PROC) , and another company registered in the Cayman islands. On the German registry you have to jump through hoops to get any information and there is a charge to see balance sheets. The Cayman registry charges US$36.59 for Company Details, US$60.98 for Director Details, and US$60.98 for a Detailed Search. The registry website says all they provide are: Company Name and Number, Place and Date of Incorporation, Type of Company, Status, Registered office and Address. Any other information and or documents must be requested from the Company's Registered Office! Just think how easy it is to do basic research on a company registered at Companies House - and it's mostly free.
My morning smallcap tweet: Are you being swerved?
Creightons (LON:CRL) MGC Pharmaceuticals (LON:MXC) Quadrise (LON:QED) Aptamer (LON:APTA) Capital (LON:CAPD), 1Spatial (LON:SPA)
◄Creightons (CRL)► FY-Mar rev down 4%. Pretax down 80%. There was no trading stmt since H2 in Dec. Biz returned to to profitability and positive cashflow in H2. No current trading. [SP=31.1 Cap=21m]
◄MGC Pharmaceuticals (MXC)► another $1m from AMC Pharma for ArtemiC. [SP=0.23 Cap=8m]
◄Quadrise (QED)► £1m placing and £2.25m OO at 1.25p, a 34% discount, to keep the lights on. [SP=1.71 Cap=24m]
◄Aptamer (APTA)► £507k contract wins, included in the pipeline set out in recent RNS. Still needs further funding in the short-term. [SP=4.47 Cap=3m]
◄Capital (CAPD)► positive operational and financial developments in majority-owned co MSALABS. Also $10m placing means CAPD's holding up from 77.8% to 81.8%. [SP=94.12 Cap=182m]
In line: SPA