Small Cap Value Report (Fri 8 Jan 2021) - RCH, TRMR, DPP, SCS, SBRY, CCT, PETS, MARS

Good morning, it's Paul here with the SCVR for Friday.
Timing - today's report is now finished.
Agenda -
Reach (LON:RCH) - Trading Update
Tremor International (LON:TRMR) - Trading statement
Dp Poland (LON:DPP) - Reverse takeover & share dealings re-commence
Scs (LON:SCS) - Very significant major shareholder announced!
J Sainsbury (LON:SBRY) - trading update
Character (LON:CCT) - Freehold property disposal
Pets At Home (LON:PETS) - Good trading update
Marston's (LON:MARS) - Q1 update
.
Reach (LON:RCH)
Share price: 224p (up 28% at 08:45)
No. shares: 312.1m
Market cap: £699m
Reach plc, formerly Trinity Mirror plc, is a national and regional news publisher. The Company is engaged in producing and distributing content through newspapers and associated digital platforms.
[Source: StockReport synopsis]
Good news this morning with a positive update for FY 12/2020 -
Reach plc ("Reach", the Company") today announces that it expects underlying operating profit for 2020 to be ahead of market expectations, in the range of £130 to £135 million, following a record digital revenue performance.
This new £130-135m range is ahead of existing consensus expectations for u/l operating profit of £124.3m . So about 5-9% increase above expectations, coming right at the year end, is very good.
Digital revenue grew by 24.9% in Q4, up from 13.4% in Q3. Print circulation sales were down 11.7% in Q4, an improvement on the 12.6% decline in Q3. These trends contributed to an improved total revenue decline in Q4 of 10.2%, compared with the 14.8% decline in Q3.
That's a good acceleration in digital revenues in Q4, which were +16.2% for the 5 months to 22 Nov 2020, which I covered here on the 27 Nov 2020 trading update.
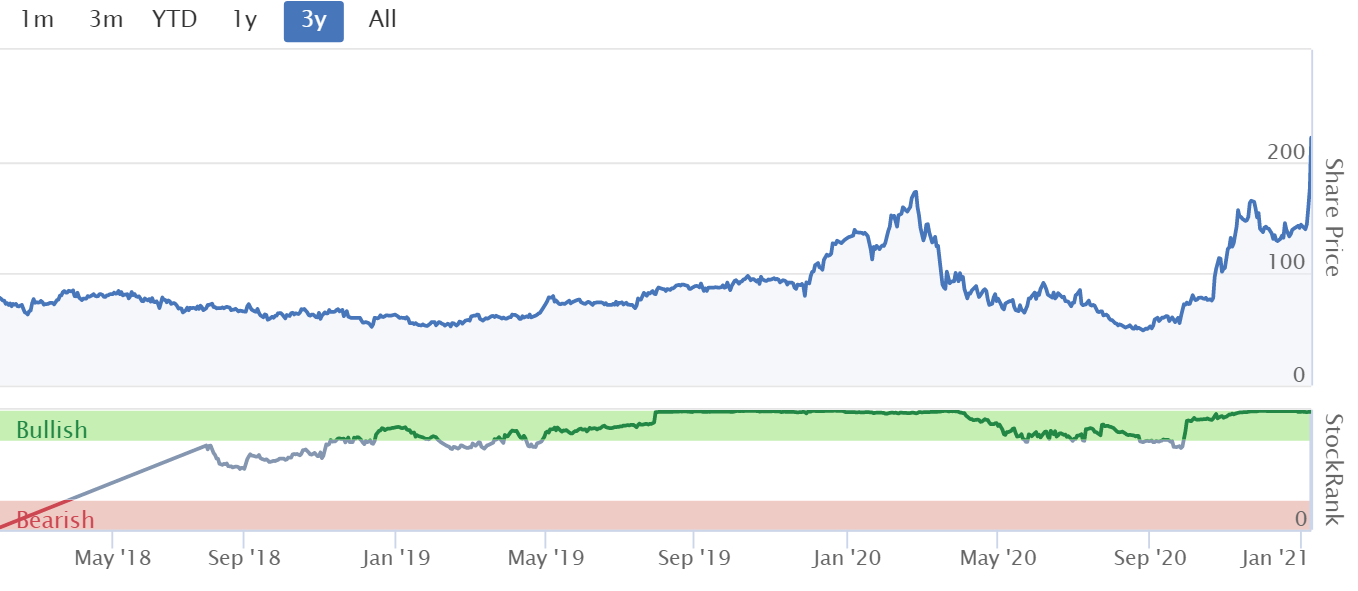
Although overall revenues are still falling fast, reinforcing the fact that the main business (newspapers) looks moribund long-term. There's been a surge of investor interest in the digital side of the business in the last year, as you can see from the share price.
Digital strategy - is to persuade customers to sign up (now at an impressive 5m customer registrations), which enables Reach to track user activity on its website, and thereby better target advertising.
Pension deficit - is not mentioned today.
Its giant pension scheme liabilities are a major worry, and highly material to the share's valuation.
In the most recent annual report for 2019, the actuarial deficits totalled £701.7m - an enormous liability. Remember that deficit recovery payments are based on this figure, not the much smaller accounting deficit. From page 113 this is the breakdown of that £701.7m total deficit -

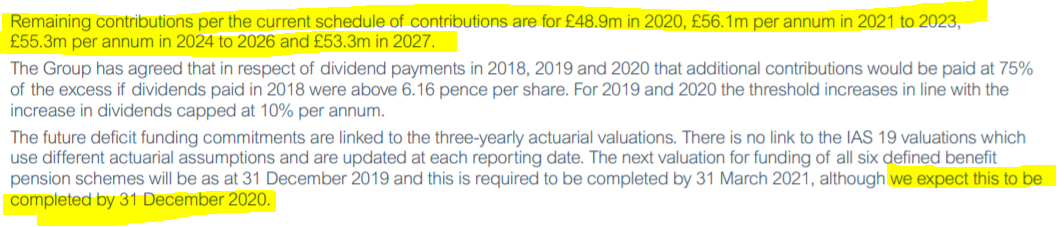
From the same page we are also reminded that huge cash payments are ongoing into the pension schemes. The latest three yearly pension scheme actuarial valuation sounds as if it's imminent, which is crucial information. Ultra low interest rates are likely to have swollen the liabilities, but investment returns may have boosted assets. The problem is that the deficit is the difference between two multi-billion numbers, so can be very volatile. I'd want to see this latest pension scheme information before buying any shares in Reach, because the numbers are so highly material.
The downside risk is that, once no more cost-cutting can be done, then the pension schemes could swallow up all future profits before long.
.
My opinion - this share is very difficult to assess, because we don't have full information about the digital side of the business. Where is the profit coming from? Newspapers or websites? I can't value the share without that information.
The bull case, about Reach morphing into a major digital advertising platform does sound very interesting. I'd like to see much more specific figures on this before buying into the story. Hopefully forthcoming 2020 results might give us more detailed information. It needs to split out profitability between the declining print business, and the growing digital business. Without that information, valuation is just guesswork.
I'll go through the 2020 results in detail when they're issued.
The increased 2020 profit expectations reported today is clearly good news. How much of that is down to cost-cutting, and how much to digital growth? We're not told.
Share price up 28% at 08:46 today seems a tad overdone to me. But we are in a bull market! If market sentiment detaches from fundamentals, and just rates it as a mini Google or Facebook, then the sky's the limit. So I can see the speculative appeal of this share.
.
.
EDIT: See Research Tree for an interesting update note from N+1 Singer. The forecast section is interesting, as it shows the split between print & digital revenues (but not the profit split unfortunately). What it shows is that rising digital revenues don't manage to fully offset falling print revenues in 2021 & 2022. Therefore overall group revenues fall in the forecasts.
This results in adj operating profit forecast to move like this;
2020: £131.6m
2021: £133.0m
2022: £135.1m
Hence not much movement in profitability at all, despite increasing digital revenues. EPS is static at around 33-34p EPS over the next 2 years forecasts.
So you could argue that digital growth is just offsetting print decline, leaving no overall change. It's difficult for me to get excited about that. Especially as the enterprise value (including actuarial pension deficit) is well over £1bn now.
Tremor International (LON:TRMR)
Share price: 439p (up 17% at 09:01)
No. shares: 133.3m
Market cap: £585.2m
Tremor International Ltd (AIM: TRMR), a global leader in video advertising technologies, provides an update on trading for the year ended 31 December 2020.
Tremor ended 2020 with a flourish. How about the following for outstanding clarity - giving us the previous guidance, and new guidance, with specific figures. If only all trading updates were presented in this format, for all companies, life would be so much easier -
The Company's record revenue and profit growth in the second half of 2020 continued through to the year-end, with trading in the month of December at a record high and materially exceeding the Company's expectations.
Therefore, Tremor expects trading for the year ended 31 December 2020 to be ahead of the ranges outlined in its most recent trading statement on 30 November. These were revenues, net revenue* and Adjusted EBITDA in the ranges of $390-400 million, $171-175 million and $50-52 million respectively.
Tremor now expects to report revenues of $404-408 million, net revenues of $179-181 million and Adjusted EBITDA of $58-60 million for the year ended 31 December 2020.
In addition, the Company had net cash at 31 December 2020 of c. $96 million (30 June 2020: $78 million).
This trading performance demonstrates a 72% growth in revenues for Q4 2020 compared to Q4 2019 and 50% growth in the second half of 2020, compared to H2 2019…
A growth table shows stunning growth in “PMPs” (whatever that is), and in 2 other categories, all showing >100% revenue growth.
Outlook comments sound very positive too -
The board and management of Tremor believe that the growth demonstrated in the second half of 2020 is set to continue through 2021, despite the ongoing uncertainty and impacts relating to the COVID-19 pandemic. It is clear that Tremor's strategy to focus on video, data and Connected TV - which is complemented by its end-to-end technology platform and broadened geographic footprint - is coming into fruition. The business is now fully integrated and set to deliver sustained growth.
My opinion - these figures look fantastic. This is not a sector I understand, so am neutral on this share.
My main concern is whether these fabulous figures are sustainable or not? We’ve seen in the past how, in this type of business, big profits can be made, but then just as quickly disappear, when things like Google algorithms are changed in some way.
Therefore I think investors need to properly research how the company specifically makes money, and consider whether that is sustainable or not. It’s no good asking companies themselves, it’s much better to get some kind of third party, sector expert views from outside the investing community.
Director selling is something to watch too, which has been substantial at this company.
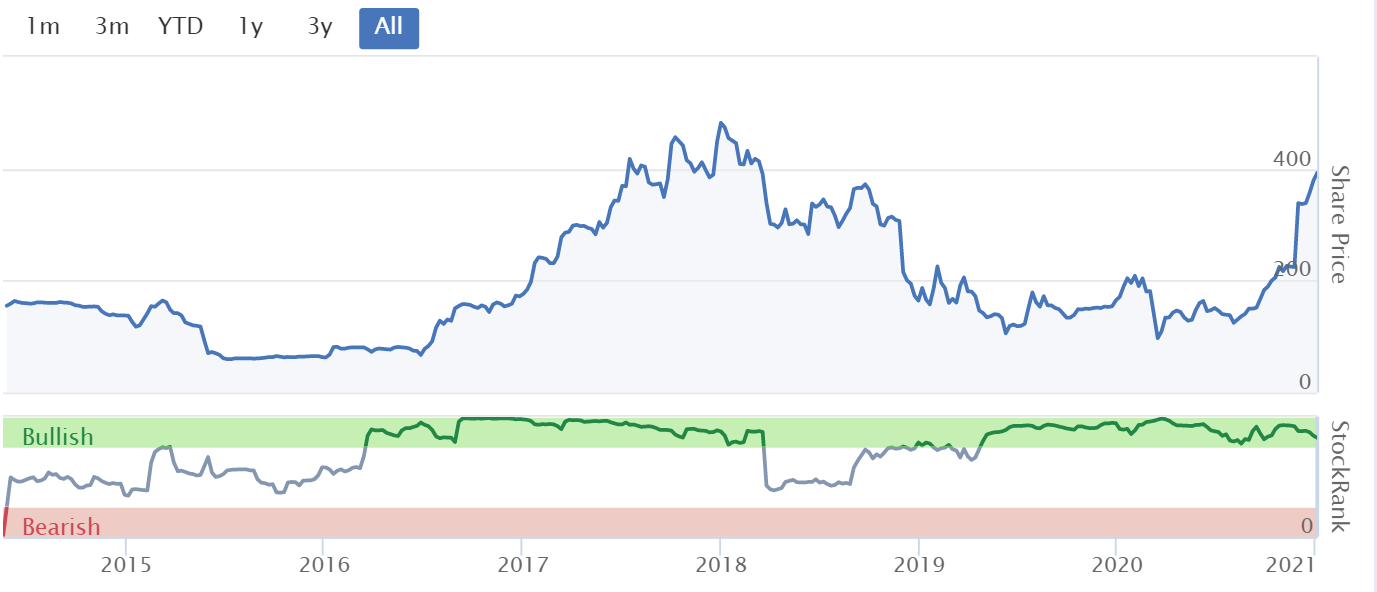
Overall, I’m happy to pass on this share, as I don’t properly understand it. As the chart shows, the company's track record is mixed. It might be the type of boom & bust company where it could make sense to top slice some profits & run the rest for free?
With a big cash pile, dividends should be back on the agenda.
.
.
Dp Poland (LON:DPP)
10p - shares resumed trading today
Hopes that this company could replicate the success of Dominoes Pizza, but in Poland, didn't work. So instead of admitting defeat, after many years trying, and racking up heavy losses, a creative solution has been found.
DP Poland is being combined with another Polish pizza chain, called Dominium, almost doubling the number of stores.
I'm not convinced that merging a basket case with another business, even a good one, will result in a good combined business. Therefore it's of no interest to me.
If the combined group does manage to achieve profitability, then at least it will have plenty of tax losses from DPP to utilise, assuming they have a similar corporation tax system in Poland to the UK system.
.
Scs (LON:SCS)
205p - mkt cap £78m
(I hold)
A lot of my shrewd investor friends are in this stock, which attracted me to buy some last year too, after doing my own research of course.
This week, a not only shrewd, but omnipotent investor joined our ranks ... God!
The Church Commissioners for England have just announced a new 3.0% disclosable holding in ScS.
A nice soft ScS settee is certainly more comfortable than a wooden church pew. Maybe that was in the back of the Commissioners minds?
More seriously though, I'm not concerned about the latest lockdown, because ScS quickly recouped lost sales last time, and also sells online. Plus the lead times from ordering to delivery are enough to mean it continues generating sales (recorded at time of delivery to the customer, I understand) even though showrooms might be closed.
It still looks cheap, and has a super balance sheet, because it sits on customer cash deposits for a while, before having to pay its suppliers. Hence very favourable working capital cycle, and it didn't need to raise any fresh equity during 2020, unlike larger competitor DFS which paid for its weak balance sheet by having to dilute shareholders almost 20% during the crisis.
These things matter, because we cannot assume covid-19 is a one-off. Something similar might happen again. Hence companies need to repair their balance sheets, and keep much higher levels of cash reserves than might have been the case pre-covid.
Business models are not as strong as we thought, and in vulnerable sectors like travel/leisure, retailing, and hospitality, nobody can assume any more that revenues will flow uninterrupted forever. That means a sea change in attitudes is needed. Instead of clamouring for resumption of divis, shareholders should probably be encouraging companies with weak balance sheets to retain more cash, to reduce balance sheet risk in future.
.
J Sainsbury (LON:SBRY)
242p - mkt cap £5.4bn
Just a quick comment, so I can close another tab on my browser, left open from earlier this week.
Mkt cap of £5.4bn seems very modest, for such a huge business. I do wonder if it might become a bid target, e.g. for an overseas bidder that wants a ready-made, large UK outlet for its own products? I don't mean replacing the existing products, but finding a bit of space in SBRYs stores for complementary products, sold at high margins. That could make sense maybe.
Things that stand out from SBRY's Q3 update published yesterday, are;
Strong Xmas sales, LFL up 9.3% (excl. fuel)
Argos also did well, up 8.4%
Digital sales now 44% of the group total - that's a massive amount, which would have been unthinkable a few years ago. I wonder if many people might continue shopping online, having been initially forced to do it due to lockdowns?
Business rates relief - I'm still scratching my head over this, in that SBRY voluntarily handed back the business rates relief, which was not required. Tesco was the first to do this, IIRC, but SBRY followed shortly afterwards, I recall, maybe even the next day. This is hugely material to profits -
We now expect, after forgoing business rates relief of £410 million, to report underlying profit before tax (UPBT) of at least £330 million in the financial year to March 2021 (financial year to March 2020: £586 million)
Put another way, UPBT would have been at least £740m, but SBRY gave up over half of that voluntarily, £410m, as a gift back to the taxpayer. I find that absolutely remarkable. The cynic in me says there must be more to it than just doing the right thing, as the associated PR benefit. Some readers suggested that the Govt might have made it clear a windfall tax would be imposed if they didn't surrender the taxpayer support over business rates. That does sound credible to me.
Wafer thin profit margins - it's a business generating revenue of nearly £30bn, so the £330m profit margin is tiny in percentage terms. That's worth pointing out to anti-capitalist family members, which I often do!
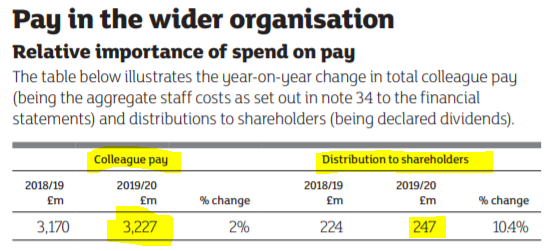
As an aside, I thought it would be interesting to work out how much SBRY pays its staff, and compare that with shareholder payouts. Happily, this information is already provided in the 2019 Annual Report - as follows -
.
As you can see, staff pay was over 13 times the amount paid to shareholders. Again, worth pointing out to anti-capitalists. That said, I do feel a lot more needs to be done to rein in executive greed, so pay at the top end is very much a big issue.
My opinion - I wouldn't normally be interested in supermarkets, but maybe it's time for a fresh look? Covid seems to have been a double-edged thing - extra sales, but increased costs.
.
Character (LON:CCT)
421p - mkt cap £90m
A favourable, albeit not financially material announcement came out yesterday.
CCT has sold an overspill warehouse for £3.5m. Book value was £1.44m, so there's a worthwhile profit on disposal, and a boost to cash reserves, and balance sheet overall NAV.
I think it also suggests that the accounting generally at CCT is probably quite conservative.
.
Pets At Home (LON:PETS)
446p (up 7% at 13:07) - mkt cap £2.24bn
I like to look at as many retailing trading updates as I can, at this time of year, as it's my sector specialism & can give insights into other areas in small caps.
This update is for FY 03/2021 to date.
Trading has been excellent recently -
... momentum has accelerated across all channels during our third quarter, with "high-teens" Group LFL sales growth during December.
Classed as "essential" hence can continue trading through current lockdown.
Profit guidance raised -
... we now anticipate full-year underlying pre-tax profit, including the previously announced repayment of business rates relief of £28.9m, to be at least £77m2
2. In our H1 FY21 results on 24 November 2020, we anticipated FY21 Group underlying pre-tax profit on a post-IFRS16 basis to be £93.5m including business rates relief. On 4 December 2020, we announced our intention to repay the £28.9m of rates relief received
That works out as raising guidance from £64.6m previously, to "at least" £77.0m now - impressive.
My opinion - the share price has doubled in recent months, so it's on a punchy valuation that reflects strong performance, in my view. Too expensive now at 446p, in my opinion.
.
Marston's (LON:MARS)
79p (up 6%, at 13:27) - mkt cap £500m
Q1 Update
This is another pubs group, following on from similar-sized Mitchells & Butlers (LON:MAB) yesterday. MAB said that its cash burn would deplete cash reserves rapidly in the coming months, and that it was exploring equity fundraising. The Telegraph helpfully pointed out that MAB is lucky to have 2 very wealthy major shareholders backing it, likely to be supportive.
MARS is in a better position. Oct-Dec 2020 trading was obviously "materially disrupted" with covid restrictions, and all its pubs are now closed.
Expects re-opening to occur in March 2021, at the earliest. Some of the previous restrictions may remain on re-opening.
JV with Carlsberg gave it a £233m cash injection, impeccably timed!
Liquidity looks fine - plenty of headroom, so it is implied that it should not need to do a placing.
CEO implores the Govt to extent business rates relief, and VAT cut.
My opinion - neutral, as I haven't done enough research to form a view either way. Given its superior liquidity position, I would gravitate towards MARS ahead of MAB (which needs more equity raised).
.
That's it from me today, and for the week.
Have a lovely weekend, as best you can.
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

120 comments
Sorry Abtan, wrote a message but not sure why only the first line was posted !?
Funding Circle Holdings (LON:FCH) let’s just say I’m highly sceptical...
Abtan
It’s a Euro debt fund so note that this was the case for all Borrowers in Europe (from UK, Spain, Germany to even likes of Latvia).
You are trying to analyse the situation in hindsight when the threat was very real at the time !
From a UK perspective, the CLBILS schemes were announced but who would actually qualify (would PE businesses be eligible for example!?) and how the scheme was to be administered was not really determined until mid summer. UK banks were speaking to the government on a daily basis to try and figure out the ‘rules’ and how they could implement the policy efficiently / effectively.
There was a massive backlog of firefighting work to complete at UK banks, so only the most critical of cases would be seen to (a bit like the NHS currently !). Reach (LON:RCH) may have had plans for investment or to build a working capital buffer that required cash, so would have been prudent to take advantage of available liquidity whilst it was there.
A CFO who did not draw down an RCF and then faced some sort of emergency liquidity requirement would not be in a job for very long !
I’d probably ask the opposite question ? Why wouldn’t you fully draw down all available liquidity, squeeze debtors and creditors where you can, reduce Capex spend to preserve cash in June last year ?
To quibble about the pocket change of a bit of extra interest is akin to trying to pick up pennies in front of steamroller!
All the best with Reach (LON:RCH). Been on my watchlist for a long time...so will continue to follow with interest.
Reach (LON:RCH)
Thanks Nicobos.
"You are trying to analyse the situation in hindsight when the threat was very real at the time !"
This is a fair point and there may be some subconscious truth in this.
"how the scheme was to be administered was not really determined until mid summer"
I didn't realise that discussions on the administration of CLBILS loans continued past June 31st (ie at the end of Reach's H1). I thought - clearly incorrectly - that everything was clear as of March/April when the schemes were launched. I know the US had issues with their own covid loan programmes (particularly PPP), but I didn't really read about many issues over here.
"I’d probably ask the opposite question ? Why wouldn’t you fully draw down all available liquidity, squeeze debtors and creditors where you can, reduce Capex spend to preserve cash in June last year ?"
I completely agree with this, though if I may, I'd like to add one question - if you expect to lose £60-80m in annualised free cash flow overnight (and that's after funding £50m into your pension), are you really making £60-80m of annualised cash flow in the first place?
For what it's worth, I am probably being too pedantic and missing out on a golden opportunity. As a company that I've only recently looked into I'm sure there are logical explanations for the phenomenal increase in cash generation from 2018 to 2019, and presumably into 2020, even after paying the c.£20m deferred consideration for the Express and Star.
I don't hold, but look forward to seeing future updates.
A
Funding Circle Holdings (LON:FCH) (no position)
Hi Nicobos
On a completely separate note to our previous discussion, I wondered whether you might have any thoughts on Funding Circle Holdings (LON:FCH) in the current environment.
I was expecting them to be a big winner in 2020 with all the government backed loans flowing around in their key markets, but came away repeatedly disappointed.
I've no idea if you have any experience with them, but given your background any thoughts would be much appreciated.
Cheers
A
I was actually very impressed at the speed which the government acted to put various schemes in place to shore up the system. Get the press release out, work out the detail later (a bit like Brexit!
slightly off the subject sell all facebook google twitter stock a storm is coming.The clamping down of free speech is a very dangerous game to play.Americans and some uk users are jumping on other platforms fast.
Google? People won't want to stop making Google searches. It wasn't Trump's prime platform.
I don’t think the majority of people would argue against blocking the tweets of a very dangerous lunatic whose followers are easily led astray.
So how come the Iranian and Chinese governments get accounts?
How come the leaders of public disorder over the summer weren't banned?
"first they came for".....
So how come the Iranian and Chinese governments get accounts?
How come the leaders of public disorder over the summer weren't banned?
If they're fomenting public dissent, violent disorder and disseminating verifiable lies under the guise of officially mandated authority then they should be banned too. But the social media networks are acting in their own best interests, as you'd expect, they're public companies.
They're going to be regulated anyway unless they start to moderate content properly. Claiming that they're open platforms and therefore not responsible for what's posted can't really be justified any more and that will drive up their costs and erode their margins. Which perhaps is a reason for selling, but probably not one to worry about immediately.
But the "first they came for ..." quote is from Martin Niemöller's lament about his and his fellow Germans' failure to defend their democracy from the Nazis. It's about standing up to authoritarianism, rather than defending some absolute version of free speech. There's only one side in America trying to deny pluralism at the moment so the quote could equally be well be used to defend the social media companies as condemn them. Bit late in the day, mind.
Free speech is not, in any case, absolute - in particular sedition, incitement and hate speech would normally be excluded under the harm principle. If the social media networks actually started moderating on that basis they'd be performing a societal good - and probably seriously reducing their traffic.
timarr
Reach (LON:RCH) doing a little more digging on this today and what's interesting is that digital is now around 25% of overall revenues and effectively at an inflection point. ie the drop in revenues from print next year is expected to be offset by the additional revenues in digital and starts to overtake it in YE 2022 - ie overall group revenue should be growing again. The increase in digital doesn't really increase Opex either so margins improve. That's important as it now means that cost cutting is no longer required to maintain and grow EPS of 33/34p.
Given the growing net cash pile and FCF yield of around 17% coupled with an expected increase in group revenue then servicing the pension gap doesn't seem remotely like a stretch, so a 6* PE is looking very stingy indeed to me. Indeed if the digital strategy continues on Q4 trajectory or even upwards then estimates will need revising upwards as analysts only appear to be factoring in 18-19% digital growth next year vs 24% in Q4. Similarly print is expected to decline 7%.
Free cash generated pre Pension is around £260m over this year and next. That demonstrates the highly cash generative nature of the business and clearly shows any pension servicing should be comfortable.
Hello Paul,
I too would like to thank you for a week of superb SCVRs. The effort you put in is truly "above and beyond the call of duty" and enormously appreciated.
Have a great weekend,
Steve
Paul - just want to say a big thank you for your mammoth efforts this week. SVCR is compelling reading every day.
The number of companies you have covered this week in such tremendous detail is simply awesome, what a great start to the new year......
Thanks again - Pete
This news below sounds great. may the markets re-rally!
https://www.cnbc.com/2021/01/08/pfizer-biontech-vaccine-appears-effective-against-mutation-in-new-strains.html
Having worked as CFO in retail, leisure and distribution sectors, the only reason To currently invest in J Sainsbury (LON:SBRY) would be due to takeover speculation noted above. I use them for home deliveries and, whilst the delivery people are nearly all great (very good recruitment approach, in my area of London at least), the fulfilment % achieved is unbelievably poor- my own subjective assessment is that circa 15% of my orders aren’t delivered, including items on promotion, a cardinal sin in retail. Justin King tackled JS’s poor availability many years back, but they have been getting worse for a couple of years now (and, no, I’m not talking about COVID shortages of loo roll, for example). Some of it, I believe, must be down to poor in-store picking discipline, but as this ought to be easily controlled, I struggle to understand why.
Until I saw such an improvement in such a basic retail measure, I wouldn’t touch them.
I've had similar experiences of J Sainsbury (LON:SBRY) home delivery. I bought some wine on promotion last December only to find they charged me full price.
I think this is in breach of consumer law and made that point to Sainsbury who simply stated it was in their T's and C's. So I tweeted this point to various (in)famous short-sellers and bought shares in Tesco (LON:TSCO) instead. The 51p special dividend due to be paid in the spring makes them a much more attractive investment IMO.
Have a great weekend
cheers
Francis
Re: Scs (LON:SCS) Finally, that old hymn they used to make us sing at school makes sense: "I am the Lord of the dance setee."
I'll get me coat.
Maybe they thought it was a chairity
Anyone here hold Bushveld Minerals (LON:BMN) ? It looks very interesting but I know little about the sector and haven't come across any decent research online. If someone could point me in the right direction it would be greatly appreciated. Thank you!
Bushveld Minerals (LON:BMN) is covered in here:
https://s3.amazonaws.com/asset...
Yes, it's good to see BMN in the top 20, although, having been invested in BMN for a number of years, I think the bear points are a bit overstated, particularly the ones concerning vanadium prices and potential future dilution. BMN's business model has a built in hedge on V prices as it sells to the steel sector where there are few alternatives when it comes to steel strengthening, so demand stands up very well if/when prices spike. At the same time it is a key figure in the emerging energy storage sector, which is much more price sensitive, but it has - uniquely - developed a V leasing option which greatly (30 or 40%) reduces the capital cost of Vanadium Redox Flow Batteries. And best of all, the quality of it's primary V resources put it in the bottom quartile in terms of production costs, meaning that when prices are low they are profitable when most of their competitors are not. As regards dilution I see that as very low risk as they are fully funded to double their production capacity and are generating cash already - as the commodity super cycle is just getting started.
Excellent video. There was another one previously in same series. GL
Bushveld Minerals (LON:BMN) - not sure u got IC / FT - but here we go :
https://www.investorschronicle...
https://www.investorschronicle...
Also check out the very active bulletin boards - I usually go to LSE, advfn are filled with nutters.
Joshwood there is some excellent research online. Try https://www.thebushveldperspec... for a start. It's a resource put together by some (invested) PIs, many of whom populate the LondonSouthEast chat board, which is one of the best informed around. #BMN also has a good following on twitter. Good luck with your research!
Paul, ...."That's worth pointing out to anti-capitalist family members, which I often do!".....I can do a good line in "capitalist Pig" t-shirts if you like. They make excellent Christmas presents!
I dont know if this should be a concern or not tbh but there does seem to be a fair amount of short interest in J Sainsbury (LON:SBRY) which I find quite interesting https://shorttracker.co.uk/com...
Short positions now increased J Sainsbury (LON:SBRY) on the 7th Jan to 9.4%. Interesting given their results this week.
Short positions now increased J Sainsbury (LON:SBRY) on the 7th Jan to 9.4%. Interesting given their results this week.
I think you need to be careful interpreting short positions as a particularly bearish signal. Some of these positions may just be some kind of hedge e.g. Blackrock have a 3% short position but also a 5% long position.
I'm also a bit worried about the accuracy of the information on shorttracker.co.uk - it shows Carillion as the 6th largest short position with no changes in individual short positions since the end of 2017! I don't know about you, but when I see something like that, it makes me wonder about the validity/accuracy of the other information present.
All the best, Si
In a market were beta to upside is expected a previously relatively high rising but growth limited defensive can be a good short to help you leverage more long whoosh /cyclical into your book if you run a high gross long and short portfolio (ie so you’re always committed decent amount both sides)
In a market were beta to upside is expected a previously relatively high rising but growth limited defensive can be a good short to help you leverage more long whoosh /cyclical into your book if you run a high gross long and short portfolio (ie so you’re always committed decent amount both sides)
Thanks. Even if this kind of stuff is way above my paygrade. My main concern would be the accuracy of the shorttracker website, particularly given that it does not declare short positions under 0.5%. You only need half a dozen of those and it could quickly make the data shown to all intents and purposes meaningless. I gave up referencing the website years ago as I didn't really trust it was telling me the whole picture.
All the best, Si
Reach (LON:RCH) - Snippet from Shares Magazine:
ANALYST VIEWS
Numis analyst Gareth Davies called Reach’s update a ‘very encouraging statement’ and pushed the stock’s target price to 240p from 210p, pointing to its ‘very strong digital revenue momentum, with strong drop-through to profits.’
He also highlighted the five million online customer registrations and said it was a key part of the firm’s Customer Value Strategy, which enables Reach to ‘use enhanced data and insights to drive new product innovations and to grow revenue through more targeted brand opportunities and commercial partnerships.’
Analysts at N+1 Singer said Reach now generates a 17% 2021 free cash flow yield on their forecasts, well ahead of the 3-7% generated by its global peers, ‘with room to accommodate pension payments, the resumption of a cash dividend, and a steady level of reinvestment back into the business.’
I can’t link you to the article, but if you are interested in fundamental research, may I point you to the latest quarterly newsletter on the highly respected gmo.com website? It’s worth ten minutes of your time.....
Very interesting GI, thanks.
Reach (LON:RCH) discussed by Richard Leonard (and Andy Brough) here, at 21m15s, back in October 2020.
Mr Leonard hits the bullseye on both Reach (LON:RCH) and Tremor International (LON:TRMR) in the same interview . His other daytime job is an oracle whose choices I have not heeded with much regret!!!
Great news r.e. Reach. Another great example of how technology is tricking down to more "boring" traditional companies and enabling them to increase their competitiveness.
We have a saying in my company - many businesses now are IT companies, a lot of them just haven't realised it yet.
If you're selling something intangible, you're almost certainly an IT company and if you're not investing in your IT infrastructure, machine learning, and AI capabilities you're going to get left behind.
Banking, Insurance, retail, media. Hell even our local council is investing in software to make bin collection routes more effective and efficient.
Having written this, I should probably investigate the "picks and shovels" companies some more, Amazon, Microsoft, Google, Cisco, Adobe, Intel, etc
piworld have just published an interview with Andrew Hollingworth. Andrew reflects on 2020; value v growth; his investment approach; running a fund during CV19, and how he dealt with a large drawdown managing other people's money. What went well, and badly, and opportunities for 2021.
Tremendous honesty, and a real sense of some aspects of fund management. This is a goodie. Video & podcast.
Moving on to today's news. Tremor International (LON:TRMR) have made a fantastic turnaround from Q2, when CV19 hit them really hard. Upgrades today for both 20 and 21. 21 EPSf up 31%. finnCap note cites all in the sector are experiencing strong growth. Andy Brough mentioned TRMR in his interview here at 15m45s, back in September. It's up >100% since. finnCap TP 800 (from 500). Granted based on US valuations of competitors. Here's their H1 results presentation (September 20), but we eagerly await H2. But today, very clear guidance given.
Mpac (LON:MPAC) overview by Castleford Tiger, here 11mins in, back in September.
RE: Reach (LON:RCH)
I hold 3% or pf
I was looking at adverting spend in relation to £TTD recently as Tobias Carlisle described the valuation of that company as the most egregious (and it might be!) of all the US tech companies.
My pennyworth on Reach (LON:RCH) is that one shouldn't lose sight of the addressable market. UK advertising spend reached £23.6 bn in 2018 (https://www.adassoc.org.uk/res...) and global advertisinng is currently predicted to be $633bn by 2024 (https://www.statista.com/stati...)
£FB revenues are estimated to be in access of $100bn by 2024 Wpp (LON:WPP) (an agency I know) has revenues of £11bn. I think there is a reasonable possibility that Reach could increase its ad revenue quite significantly.
Stocko computer likes it and a fc pe sub 6 I think it is certainly a stock that is worthy of consideration and sometimes pension deficits have not been a barrier to success for other companies though I accept that the Reach's pension is an enormous.
As an aside looking at the Stock report the F score is 7 (good) and the Z score is 1.1 (ditress). Are these telling a conflicting story or is it completely possible for a company to have a good F score and a bad Z score and both be telling us something about the company.
Thx
Michael
Michael, I have noticed that some shares do have a high F score but according to the Altman Z score, they are nearly bankrupt, so I think you do need to take both into account.
Prophotonix (LON:PPIX)is the worst on my screen.
Something to watch out for if screening for high F scores.
Someone on Stockopedia, did write an article about high F score shares and this was pointed out to them.
Prophotonix (LON:PPIX) Prophotonix
Herbie47, I regularly undertake fundamental screen checks using p/e, net gearing, stock, quality rank and Prophontix comes top off the list so like yourself I am confused that when looking at the Bankruptcy risk it is severe however looking at the balance sheet, cash net debt etc. looks to be in a comfortable position. There is little on the discussion board so I would really appreciate anybody's informed views who can provide or interpret better than me. If Paul could find the time to comment or analyse it would be very much appreciated.
Sorry I don't know anything about Prophotonix (LON:PPIX). Looking into it the Altman low score is to do with:
"Do reinvested earnings make up a significant portion of the assets?"
It is a US company but listed in the UK.
It is under £10m mcap, so doubt Paul will want to spend much time on it.
I am also sometimes puzzled by the Z Score - for example, SP shows the score for SCS (LON:SCS) as 0.74. I don't imagine anyone thinks it is a candidate for shorting. In the case of Prophotonix (LON:PPIX), I had a look some time back - it looked to me like a business which has its problems, but a long way off bankruptcy. So why is the Z Score so useful? I feel that, like most of these ratios, it just flags up where further delving might be useful, but doesn't tell you more than that.
Agreed - new CEO is doing a fantastic job around digital. I know everyone keeps banging on about pensions and the death of print but I really think they are missing the point and have been saying that for ages now. Good to see the market finally starting to re-price this stock.
It is a fantastic cash machine and pays down its pension deficit and still generates £60-70m additional cash each year. That really shouldn't be overlooked when a stock is trading at £550m market cap with £60-100m of net cash on its balance sheet already. A PE of 5 is miserly for that business in my view.
The only thing that I felt was missing previously was the digital strategy not growing quite quickly enough. It felt a bit sluggish, not quite thought out. Under the new CEO it has been re-energised and his experience in digital will, I think, make a huge difference. Over half way to the 10m digital subscribers already is impressive and the growth moving into the mid 20%s is what is required.
Anyway, I think if you focus too heavily on the pension then the only time you'll enter this stock is when it is almost fully valued. I've been a holder from 60p based on the cash generation potential alone (ignoring digital) so I'm probably biased.
Reach (LON:RCH)
Hi David
I came to a similar conclusion as yourself; annual pension payments have been set for the next 6 years and the company is still able to generate very healthy levels of cash - it looks like a good cash cow at the current price.
However, I don't think that I personally will invest because it's too difficult to see how profitable a Digital-only entity would be.
Even in the annual report I can't even tell what is included in Cost of Sales - is it physical paper, or editorial content, both, etc...?
Digital is growing, which is great, but it's also coming from a small base.
A couple of other points from the Half Year report that put me off:
It's one that I'll keep an eye on in case I have missed something; for now I will watch from the sides.
Cheers
A
Glad to see that the new management at Reach (LON:RCH) have maintained the traditional pattern for quarterly trading updates (even in a bonkers year).
Q1 : In line
Q2 : In line
Q3 : In line
Q4 : Ahead.
A bit of poetic license from me, there in relation to Q2 & Q3 (this year) , but they do always seem to hold something back for a pleasant Q4 surprise.
I haven't drilled back down through my notes, but cannot immediately work out how far ' ahead' this actually but superficially it looks like more than 20%, but I would have thought that would be materially or significantly ahead rather than just ahead?
Has anyone else got a view at this stage?
Reach currently list the consensus EPS at around 31p (consistent with the Stocko figure) so it will interesting to see any updates.
It seems very likely to me that this over-performance will mostly convert to cash, although there will be exceptional cash out flow relating to the (previously announced) cost reductions ahead of original plan.
200p+ per share is beginning to get a bit into nose bleed territory for me, but then I remain quite sceptical about the digital business.
Something (else) for me to think about over the weekend.
Reach (LON:RCH) Abtan, a quick response on point 2: they would have drawn down £25m on the credit facility as this is what all sensible companies / CFOs did under the first 3 months of Covid.
Best to draw as cash in case the Bank cancels your facilities when you many need them the most !
Always a good area to focus on though. Reminds me of hindsight investing in PatVal Patisserie Holdings (LON:CAKE) where some spotted that the Company was not making any interest on deposits despite allegedly having £20m of cash on deposits with banks,
We all know how that ended...
in PatVal Patisserie Holdings (LON:CAKE) where some spotted that the Company was not making any interest on deposits despite allegedly having £20m of cash on deposits with banks,
We all know how that ended...
As an aside this is still partly rumbling on.
Ref Patisserie - the liquidators (FRP !) are suing Grant Thornton for £200 mill - i would guess though even if they won the full sum asked for none of that would probably end up with shareholders?
https://www.eveningexpress.co.uk/news/business/patisserie-valerie-liquidators-file-200m-lawsuit-against-auditor-grant-thornton/
Reach (LON:RCH) (no position)
Hi Nicobas
Thanks for the comment.
I'm not sure that is entirely correct.
If the company is doing as well as it's implying it is, then the bank will never not extend it credit facilities, especially in the current environment where CLBILS loans up to £200m are 80% backed by the government.
Note that voluntarily paid £0.6m in finance costs even when they have net cash.
Something just doesn't add up.
Incidentally it's precisely because of Patisserie Holdings (LON:CAKE) (never held a position) that I take more notice of these things.
Cheers
A
Reach (LON:RCH) trust me...this is the reason.
I work for a debt fund (which holds debt & equity positions) and we told EVERY one of our portfolio companies to FULLY draw on their Bank RCFs in March 2020. So did every private equity sponsor I know.
You forget that there was a scramble for liquidity and a lot of uncertainty. Because of the lower capital weighting (for banks) of undrawn vs drawn facilities, there was no certainty that the banks had enough liquidity to fulfil their obligations. Doesn’t matter if you were a good borrower or not, banks were swamped and cash is king.
Remember you go insolvent due to running out of cash, not because of a lack of profit. This was the first time in my career, I’ve seen borrowers bust through their cash flow cover covenants (cash to debt service) long before their leverage test (net or gross debt to ebitda).
Everyone was withholding payments and trying to preserve liquidity so their was a massive systematic cash crunch. Reach (LON:RCH) for example may give advertisers 30-60 days to pay (I don’t know if this is the case but just an example), what if their clients withhold payment and Reach (LON:RCH) has to pay staff etc.
Paying £600k finance costs is sweet FA compared to the certainty of survival and no equity dilution for shareholders (Via an emergency equity fund raise).
I’ll add to that. Nearly every company I’m aware of maxed out their credit lines back in March/ April even when it seemed to be somewhat pointless or unnecessary - the fear of another 2008 style credit crunch was real and has led to the situation today where many companies have huge amounts of both cash and debt on balance sheets.
Most credit facilities also have graduated terms as well - eg first £20m overdraft at 2%, next £20m at 4%, next £20m at 4.5%. There will be significantly higher financing charges on most balance sheets this year than strictly necessary. I had thought this might be a major bull point for banks during 2021...
Reach (LON:RCH)
Hi Nicobos
Thanks for the input.
I must admit that I still don't get it.
Credit drawdowns in March/April I get (as you have indicated - I don't disagree with this) but why have the credit drawn at the end of June (i.e. the end of H1) when the CLBILS scheme exists?
I'm genuinely interested to know why your debt fund, for example, thinks that liquidity could be an issue when the backer of current loans is the UK government, who take on 80% of the risk?
If there was any risk for £RCH , then I imagine, funds would easily be available in days, not weeks or months.
A
Reach (LON:RCH)
abtan
I'm not sure that is entirely correct.
If the company is doing as well as it's implying it is, then the bank will never not extend it credit facilities, especially in the current environment where CLBILS loans up to £200m are 80% backed by the government.
I would totally disagree with your line of thinking here as you have added the word "never"- presuming any financial institution will "always" in the future do something that is discretionary on their part is fraught with risk. Infact i would go so far as saying any presumption in that regard is somewhat risky - even if practicably speaking its seen as low likelyhood that the renewal wo';t be rubber stamped.
If we look back to the 2008 recession the housebuilders were doing fine and dandy up to 2017 just before the credit crises hit and many of the knock on consequences were made significantly worse by banks simply refusing replacement financing needed to complete ongoing projects which forced the housebuilders into an overnight shutting of much of its in progress work - ok you may say that in the meantime trading had turned much worse - but i would never presume anything when you are the one going cap in hand to another. Another example would albeit alomng slighty different lines would be Northern Rock where they kinda presumed their funding taps would be rolled over indefinately - i think it was the removal of the funding taps that caused their failure rather than any lack of trading. So i think the words "never not help" and banks should not really be used in the same sentance :)
Hi Rmillaree
Fair point on my use of "never" - you're correct, this was probably the wrong word to use, even if it is very likely that a "supposedly" highly cash generative business would not struggle to access debt facilities.
As an aside I think the 2020 situation is very different to the 2007 one.
As I understand it the loans issued today are 80% covered by the UK government. So the bank is effectively only taking on the risk of 20% of the loan.
For example, if someone wanted a £100k mortgage pre-2019, the bank would have needed to bear the risk of creating £100k loan on their balance sheet.
Today for the same mortgage, the bank's risk is only £20k, yet they are still able to reap the benefits of the full £100k mortgage.
I'm happy to be corrected, but I thought this was the point of the CBILS and CLBILS schemes launched in 2020 - to get as much cheap credit into the economy as quickly as possible without credit institutions having to worry about risk levels.
A
A break above 230p next resistance would be 300p.
PS I should have added, it is extraordiary that these figures imply that Facebook will capture $1 in every six spent on advertising. Is that right?
I totally agree with you on Reach but in a way whilst very good to understand these issues, the market has known about them for a while and priced them accordingly. So when they announce outperformance the market responds or at least it does in its current mindset (25%)!! I attribute such a rise to the digital story because story stocks have been big all year. When will fundamentals return to the market, how long is a piece of string and was that a pig that just flew past my window?? When Govts stop messing with the markets is I believe the answer.
Hi Camtab, I actually know..... How long is a piece of string?
It's twice as long as it is from the end to the middle!!!
You tell me how long it is from the end to the middle and I can tell how long the piece of string is !!
Good luck with your pink porcelain aviators flying past your window!!
FYI, I hold £RCH
Thanks Logic, most helpful. I am with you incidentally on Reach, a holder that is.
HI Paul,
Thanks for covering Reach. In respects of the pension deficit, If the total deficit was £701M in 2016, just to clarify the now quoted £209M is the remainder to pay off to remove the deficit?
Reach included this in their latest interims a few months ago:
Reach expect the pension deficit to be removed before or in 2027, obviously any revolution could affect this.
As always thanks for your terrific write ups and happy new year to you and all the Stockopedia community.
Phil
thanks Phil, Would pension deficit payments come out pre or post profit numbers? So would the reported £130m profit already have these costs baked in?
Pension deficit recovery payments are not included in profit numbers. They go through the cashflow statement. In other words, once you take into account finance charges, and tax, a significant part of Reach's cashflow ends up servicing the pension deficit.
thanks paul, much appreciated.
Hi Paul, whereabouts do these final salary pension contributions get accounted for anywhere in the stockopedia cashflow statement? Or does one need to rely on digging into the annual report to account for it?
Phil,
There are 2 methods of accounting for pension deficits;
1) Accounting deficit - which is what you'e focused on. This is often much smaller than the,
2) Actuarial deficit - far more important, because these 3-yearly calculations determine what the company has to pay in deficit recovery payments. Hence why I highlighted the massive, c.£700m actuarial deficit, because this matters a lot more than the smaller accounting deficit.
I think with Reach, a lot of shareholders don't realise how gigantic the actuarial deficit is, hence a much bigger problem than it appears from the accounts. You have to dig into the note 20 at the back of the 2019 Annual Report to see the full horror of its pension liabilities!
Regards, Paul.
Good points. But bear in mind many trustees now will have a higher long-term target of moving to essentially a buy-out/buy-in liability (even higher than the on-going actuarial liability) to enable them to near fully de-risk. This would typically be a very long-term aspiration, over perhaps a couple of decades, but will be a clear direction of travel. It means that in practice if gains start to emerge (eg from equity outperformance) this allows them to take a further incremental step to move out of risk assets and into matching assets.
That said, I've no idea what the Reach schemes are aiming to do!
Hi Paul,
That's brilliant, thanks for taking the time to come back to me
Sainsbury argos shut 128ish? of their stand alone argos stores end of q2 perminatly so like for like sales moved to other argos stores in sainsbury at xmas while customers were told to shop and pick up argos stuff at same time. Also refunds have been discounted at times in argos still only at sis in lockdown or not at all see website. There are a few tricks being used to improve margin, click and collect pick up only from stores, much better use of staff with the closures to elsewhere and food counters closed, its like argos has moved on 5years because of covid to more digtal and at times it was digtial transactions only.
Morning Paul,
The article by John Arthers hit my inbox this morning 'Ponzi-Stage Stocks Are Stable. Just Don't Cough' - sorry not sure how to share the link for all.
Edit- try this https://www.bloomberg.com/opin...
I would be interested in getting your and readers views about the headiness of the US markets in particular. To my mind, the piece makes a compelling argument to consider shorting Wall Street, perhaps not today but fairly soon.
I'm well aware of the dangers of 'betting against the market' but the body of evidence in the US , if not the UK, seems to be growing.
Good weekend all.
In a similar vein I recommend this recent piece from GMO founder, and (in)famous value investor, Jeremy Grantham: https://www.gmo.com/europe/res...
Personally I am very sympathetic to the view that US Growth stocks are in bubble territory. $TSLA in particular is one of the most egregious examples than I can recall of a stock which has completely and utterly divorced from reality
For UK investors there is obviously some comfort in the 'relative' value on offer following multi-year Brexit headwinds. But I worry that that won't count for much (at least in the short term) if Wall Street catches a cold...
<wrong reply to link used>
Reach (LON:RCH) - like Paul I am an accountant but for better or worse carried on with it all my life (I did enjoy it and had a fair sized practice). Despite that, I am frankly more interested in where a company may be heading than what the figures necessarily show at present. I think this is one where you are either excited by what is happening or you are not. It was a company with seemingly no long term future and is transforming itself to hopefully have a great future. I am influenced by the fact that my son is very much involved in digital matters. The possibilities are endless and the pension scheme could become insignificant in comparison.
Now then, I am not saying anyone should rush into it. I started buying below 100p when tipped by Richard Leonard and it was one of my biggest holdings. I then thought it had got ahead of itself when it went up to over 170p on results not long ago and when it dropped back on the same day I got out just below 150p. I then bought back in around the mid 130's. I see it is now over 200p so I have a decision to make on whether I think the price will hold up or fall back so I have no idea whether I will still hold it at lunch time!! Whatever, I think it could be very good in the longer term although perhaps once again it may be ahead of itself! I don't think that really helps anyone but best of luck to those who hold!!
Reach (LON:RCH) - to elaborate, they have around 160 regional newspapers. Neither the journalism nor the web sites are great but they exist so they can be improved if they have a mind to do so. If you search for local news it is most likely you will be directed to a web site owned by Reach and no one else.
Over time, it seems obvious that there will be less and less people buying newspapers and more going straight to a web site. Publishers seem very happy to have readers move online. I used to pay £2.50 a week for the Sunday Telegraph and then saw an offer whereby for around £75 per annum I could have the Daily and Sunday Telegraph online. So 7 papers a week for not much than half the cost of one Sunday paper. They even threw in 6 bottles of not particularly good wine! Of course, I am now inundated with things to buy and competitions to enter but it is clear where they think the future money is.
For Reach to have 5 million people signed up towards a target of 10 million by the end of 2022 is very good. It is easy to have a great website that no one is interested in. It is hard to have a web site attracting millions of visitors. That is why I believe the company has great potential.
I apologise in advance as this wont be of interest to many but does your digital Telegraph subscription include access to their Crosswords?
I also have a digital sub to the Telegraph App but no access to Crosswords.
I have had a look and it seems like you have to pay £36 a year for access to all their crosswords and puzzles. It did say that with the normal subscription you could access one puzzle a day free but I couldn't immediately see how to do so. You can have a free trial.
My experience of crosswords is limited to the Daily Mail crossword in the pub. Means of transport, 3 letters - well it can be car, bus or van so you can't fill it in immediately!
doublelutz
Thank you for taking the time to do that. It would seem that the Telegraph's famed Cryptic Crossword is its jewel in the crown when it is worth just half of all the other content put together !!!
To the point where, when we're not in lockdown, when I work from home I take breakfast at Sainsbury's and buy the Telegraph. I do the cryptic over breakfast, look at the business section later (If I don't do it online) and the rest of the paper becomes pet cage liner.
It's a cab.
TREMOR Great results from the depths of despair to profit, other holders out there what do you think as to the likely fortunes of TRMR ?
Well one broker has today increased its target price to 800p. The huge discount to it's American listed peers is intriguing. People on other boards highlighting that they hired a US based investor relations manager so are predicting that is a sign of a US listing.
I sold half my holding at the start of covid at 174p and forgot to buy back so not sure my opinion has any merit!
£TRMR
Tremor makes the knees tremble!?
Like Tremor International (LON:TRMR) a lot though was a buyer around 100p along with mojo. Rates at less than half US valuations. Everyone likes to point out that it has a less than glorious past as to the reason why it should trade at such a discount. I think that is unconscious negative historic bias at work personally and you have to look through to what the company is now. It is US based (may have headquarters in Israel but is run out of the US and the CEO is there). It is not the old business - It is a new management team and CEO, that CEO has a history of making money selling businesses in this space. They acquired 2 other similar sized businesses to assemble this end to end platform so is really 3 businesses merged into one and properly integrated. It is focused in the right areas of digital marketing and the revenue fruits are starting to bear. I haven't sold a single share since I bought them at 70-100p which given the profit they've generated is unlike me. I usually top slice.
For me they are a global business run out of the US so the UK markets are probably not the optimal place for them to exist anymore but that's just my perspective.
Ad tech is a growth market, CV19 will accelerate this.
Do you see them listing in the US?
I mean why the hell anyone like this lists on the UK is beyond me.... if they were US listed, no one would be asking these sorts of questions... the investment checklist would be: 'Ad tech? - Y/N : Y = BUY and BUY BIG'
lol - I agree; and we've had that debate on here a few times as they have moved into strong profitability. Not sure what the metrics are now but I think US peers are still something like 3-5* the comparative valuation of Tremor International (LON:TRMR) so there is a discrepancy. That doesn't mean the US peers are valued correctly of course.
In this case I am surprised Tremor International (LON:TRMR) haven't gone US listed : they are really a US business now with senior execs in US and client base heavily focused there so it wouldn't surprise me. What I would say is that the CEO has a track record of building and selling businesses so I wouldn't be at all surprised if they get bought. A US business could probably buy it at twice the price and still call it earnings enhancing and the CEO would still look like a genius to shareholders if he got us 900p say!
All of the exact same arguments were made for the preceeding entity Taptica. Could list in the US, cheap compared with peers (the trade desk commonly cited), good cashflow, growing adtech market etc etc. Then one day the profits disappeared for reasons I still don't quite understand, share price bombed, and it was all swept up under the merger and the following name change. I don't know whether it would happen again or not, but I am particularly cautious about this company, and this sector in general.
Tremor International (LON:TRMR) I used own Tremor buying from 385p in December 17 and then agressively 12 times all the way down to 100p in June 2019 and I would almost certainly still own it if I had not sold at 82p in March meltdown. I would be sitting on a 6 figure 100% profit.
I tried to get back in in December after the initial pop but the very next day the CEO dumped 700,000 shares. This company in the form of Taptica as it was known was always one for shenanigans and I decided I did not need to be invested in a company where the management does something like than without giving a reason.
Dispassionately it does seem to have turned a corner and could at a stretch be compared with the likes of The Trade Desk (I hold) and which trades on a forward PE of 154 or 1,861 Price/FCF (take you pick)! But I don't trust the management.
Would I hold here yes. Would I buy: probably not though the management or not it is tempting! I will keep it under watch!
On the whole Google algo thing they don't as far as I understand it rely on this.
My scriblings on the company which maybe out of date are at
https://investing4value.wordpr...
and
https://investing4value.wordpr...
Regards
Michael
Thanks Michael - I have come to the conclusion that as an investor there are some shares that for whatever reason I'm just consistently unlucky on. Superdry (LON:SDRY) is one of those for me and maybe Tremor International (LON:TRMR) is one of those for you. It's bl**dy annoying though isn't it :) Every time I have traded Superdry (LON:SDRY) it has lost me money only to then merrily reverse and stick its proverbial up at me so it is now on my "never trade" list.
Ditto Superdry (LON:SDRY) - all my purchases have hit stop loss and then they bounced hard.
I'm not going to look at buying them again until they manage to ditch the retail estate. I can't believe that the old CEO thought "stack 'em high, sell 'em cheap" was ever going to work for a brand based on quality and design appeal. I don't agree with Dunkerton's politics but he did the right thing ousting Euan whatshisface.
Thanks David.
Yes I know what you mean. Tremore was even more annoying as I spent a long time analysing it and came to the conclusion that it was sound and why I bough the share all the way down to 100p.
I sold Tremor International (LON:TRMR) on March 19 along with most of my pf (you can read about my meltdown at https://investing4value.wordpr...) but did not buy back as I started to rebuild my portfolio, which was silly as I had from March 30th to Sept 20th to get back in at a reasonable price. Oh well. I am nogoing to chae it from here but if I can crunch the figures I may divert a little of my investment in TTD into Tremor.
Positive update from £PMI. Most asset managers should do well, if the near term future, especially for UK equities plays out as many anticipate? Premier Miton (LON:PMI) should continue to benefit from the increase in scale of the merger of Premier and Miton, the integration of which is now complete.
Like Polar Capital Holdings (LON:POLR), Premier Miton (LON:PMI) is cash rich with a handsome dividend yield, even after the recent share price rise. I hold both.
Hi Paul and others,
Ig Design (LON:IGR) : (IG Design Group) New Long Term Incentive Scheme
This appears to be almost a misallocation of shareholders money in my view. The Remuneration Committee, chaired by Elaine Bond, has awarded participants to share, in total, in up to 12.5 per cent. of the value created for investors (the "VCS Pool"). This pool takes a base price for the shares of £4.50 (the shares were over £7 last December but have been low this year due to the Covid crisis, the justification for using a low price) as opposed to yesterdays closing price of £6.10, thus already allocating 12.5% of £154m (the difference in market value at £4.50 per share compared to todays price of £6.10 per share) = £19.25m . So without doing anything the members of the incentive scheme have been given £19.25m. Recipients named are Paul Fineman (value of allocation today = £3.37m), Giles Willits (today = £2.4m) and Lance Burn ( today = £1.44m), which represent 37.5% of the pool.
I am sure all the recipients, including those unnamed, are hard workers and highly skilled, a credit to themselves and the company. However incentive schemes based on falsely low share prices seem immoral to me. Am I being unfair or should we be making a fuss over this? Perhaps I'm being a bit naive.
My opinion is that the scheme should be re-written and the role of Elaine Bond reviewed. I would be interested in others views.
Regards, Peter
Peter
I am not a shareholder in £IGR - but I fully agree, in principle, that these schemes are generally excessive and should be resisted and that many remuneration committees are too weak.
While I fully agree that private shareholders should state their objections, these schemes only get changed, in reality, when the institutions object. For example, I am a shareholder in Sensyne Health (LON:SENS) which had its own remuneration scandal shortly after IPO, this led, following strong objections from the institutions, to the Chairman and the Senior Independent Director (also head of the remuneration committee) leaving the board and the founder/CEO working for a nominal salary for FY20.
I agree with you Peter. I've just had a look, and it seems disgraceful. I assume they have discussed it with their major shareholders, but if not they are taking a risk. I sold all my shares in IGR a couple of weeks ago, and this certainly hasn't made me regret my decision.
For what it's worth, I've just sold my Reach (LON:RCH) shares at a gain on the day of 24.4%. The price was starting to decline from a 27.7% gain. I may well buy the shares back later on today if the price continues to decline.
Thanks for highlighting Peter.
I had Ig Design (LON:IGR) on my watchlist but have just removed them. As a PI all we are realistically able to do is avoid companies where their governance structures fail to live up to expectations. The worry is that this sort of behaviour gets ingrained into the company culture
Best, Steve
Is it me just being silly or can I not see a report?
It takes time to write. Patience.
Ah its coming through now, I saw nothing at all earlier.... normally up pre this time, wasn't a gripe bud, more of a question mark moment in my head, hope you have a great day pal.
The report is there you may need to refresh your screen.
Information for new subscribers here:
I start writing these reports at 7am most days (but sometimes have a lie-in, if it's a slow news day), and publish each section as it's written (which typically takes at least an hour per section to create). So the report gradually appears, section by section, throughout the morning. The official finish time is 1pm, but I often continue into the afternoon if there's interesting stuff to write about.
This is freelance work for me, as I have lots of other things to do too. It's not a full-time job. Hence timing of reports is not necessarily consistent. If I'm too busy to spend much time on it, then Jack helps out.
Regards, Paul.
Hi Paul, would be interested in your thoughts on Reach (LON:RCH) which i think you and Jack have commented on before. The TS reads pretty well. Digital growth of 24.9% in Q4 pretty impressive and they are already half way to their 10m customer registrations target. This has already been raised once and it wouldnt be surprising to see it raised again if momentum continues. They have also done a very good job of taking costs out over the last few years and they comment that this has enabled them to develop a more efficient operation model. thank you
re £RCH I won't comment on their actual financials, but:
When I have encountered a website that identified itself as a Reach one, it has immediately bombarded me with adverts - to the point that the content was unusable and instantly annoying - more annoying than my desire to read whatever content they were offering; I closed the page without reading and won't consciously return.
As a business model, I just can't see how this sort of 'mugging' approach will be sustainable for the future (I suspect people are much more fickle than they might like/need) so I am not inclined to give credence to them as an investment case.
Ultimately the numbers will talk for themselves so I have a hat ready for being eaten...
I use Adblock so I don’t see any adverts. If adverts are annoying you youmay want to try using it, it is free.
Thanks herbie47, I can never stay more than 3 seconds on any of their websites, the ads irritate me too much.
indeed, I have it on my desktop but haven't yet set it up on my phone - thanks for the reminder :)
however, if everyone who looks at their pages does this - I suspect this will mean that their revenues will collapse as the links won't be loaded - so either way I think as a business model it is flawed.
Reach (LON:RCH) Interesting point, I’m not sure how it works, I thought it was based on how many visits to the site, that generated advertising revenue. Some sites usually American don’t like adblockers and won’t let you access it unless you unblock them.
I have sold my Reach (LON:RCH) shares this morning.
Worth trying the Brave browser. It's my go-to option for viewing news feeds (eg Google News) as it blocks all pop-up ads by default. Reach sites too. Daily Mail will still have their irritating embedded news videos start to play but it's easy to kill them with a single click.
Chrome is still a more functional browser for other sites I think, but I always found AdBlocker troublesome and lots of news outlets won't let you view until you disable it.
Presumably though if you block the ads they don't make any money!
Yes but I’m not interested in them, they are better off targeting people who may want to buy their products.
Here is one view: https://medium.com/bobs-economics/adblockers-do-they-really-cause-websites-to-lose-money-an-economist-explains-646de980e283
Some sites insist you turn the Adblock off but I rarely do, too much hassle, I just go elsewhere.
I don’t usually watch TV ads either.
Yep, their (Reach (LON:RCH) ) websites perform appalling to the point of unusability on a year old, quad core i7, with 32Gb ram on 55mb broadband connection. I don’t know how people with old hardware on poor links cope.
I never have any problems with Reach (LON:RCH) sites and I have old hardware.
Same for me - old hardware and no problem
Just tried the Derby Telegraph for the first time in over a year - it is actually much better now in terms of performance.
Horrible layout though.
Don't forget the constant offers to subscribe too!
I have a similar beef with recruitment agencies and their scatter-gun business models - I've taken delight in being able to refuse them hiring business in the past based on a personal blacklist from being spammed.
Any business model that relies on treating its customers/users as mugs to be milked/annoyed I think should be a red flag for investors.
I'm wondering if Google are about to throw a spanner in the works with their proposals to disable tracking cookies. Comment this morning on BBC news that "Google's Privacy Sandbox proposals will potentially have a very significant impact on publishers like newspapers, and the digital advertising market. But there are also privacy concerns to consider," said Andrea Coscelli, chief executive of the CMA.
I've enjoyed the ride so far but have now decided to take the cash whilst it's on the table.
It would be interested to also know the margins they are working on with the digital side of the business, it should in theory be a far more leaner business model driving stronger margins than the traditional papers. I personally think as the digital side grows, coupled with reducing ongoing costs could really turbo charge their bottom line. Paul makes a very good point about pensions though, a real thorn in the side for the future.
As Paul comments on Reach (LON:RCH) it is difficult to understand the specific business units. I was previously long Reach (LON:RCH) but got stopped out when they drifted off. Regretting not buying back in, but part of me has been questioning the bull-case because of the lack of clarity on figures (and also the big pension liabilities). It does sound very interesting but it's too easy to chase the story and then suddenly find it is without substance.
If we get more clarity on the figures I maybe tempted, but having now missed a 30% uplift over the last few days I may not be as tempted as I was before. At some point it really needs to provide clarity on this "monetisation" concept - especially as others have highlighted bombarding people with adverts is not really how to go about it.
Great company but am happy to sell 50% of my shareholding at these prices and effectively own the balance for nothing . Agree the major pension liability is a possible problem for the future but I am still positive long term .
Hmm...didn't think of that - just flogged the lot!
My morning smallcap tweet:
SIMEC Atlantis Energy (LON:SAE) EQTEC (LON:EQT) SIGNATURE AVIAT (LON:SIG) ADES International Holding (LON:ADES) Immedia (LON:IME) Malvern International (LON:MLVN) Petards (LON:PEG) Gulf Marine Services (LON:GMS) Tremor International (LON:TRMR) Reach (LON:RCH)
SIMEC Atlantis Energy (SAE) CEO resigns to become adviser. He is thanked. [SP=22.2 Cap=110m]
EQTEC (EQT) MoU with Nobilis Pro Energy of Greece for development of Nobilis's existing pipeline of opportunities in Thessalia and Central Greece and for the proposed delivery of these and further advanced gasification projects. [SP=2.55 Cap=179m]
Signature Aviation (SIG) bid approach from Carlyle Investment Management. [SP=423.88 Cap=3518m]
ADES (ADES) CFO scarpers. He is thanked. [SP=9.95 Cap=413m]
Immedia (IME) £3m placing at 25p, an 18% discount, to keep the lights on. 1:1 warrants at a very generous 35p strike. [SP=30.5 Cap=8m]
Malvern (MLVN) £380k of loans while it waits for £900k debtor to pay in Q1. Outlook: "Overall demand for our education products remains largely unaffected. Further growth in the University Pathway division is predicted for September 2021 and we are currently expecting the Summer programmes to go ahead for language centres and Malvern Juniors." [SP=0.14 Cap=2m]
Petards (PEG) one of several companies saying in last 24h that they don't know why SP went mad yesterday. [SP=18.9 Cap=11m]
Gulf Marine Services (GMS) wins long-term contract for the GMS Evolution. Backlog $220m (firm and options), of which $101m will be executed in 2021. [SP=5.98 Cap=21m]
Tremor (TRMR) guides FY(Dec) rev $404-408m, ahead of Nov guidance of $390-400m. Also adj EBITDA of $58-60m cf $50-52m. [SP=375 Cap=500m]
Reach (RCH) guides FY(Dec) U/L profit £130 to £135m, ahead of market expectations. Q4 rev down 10% cf Q3 down 15%. [SP=158.16 Cap=494m]
Thanks Mr.C - Petards (LON:PEG) has in fact increased every day for about a week - and now more or less doubled in price. A tiddler of course, but bearing in mind its business profile , maybe surprising it has not taken off before now. Another share of note in this respect - Accsys Technologies (LON:AXS) which is proceeding with its new facility near Hull and the BP refinery.
On another subject - Any thoughts on why Randall & Quilter Investment Holdings (LON:RQIH) has appointed Barclays as joint broker ?
Maybe they want to be seen as one of the Big Boys now...? (I hold all three)