Small Cap Value Report (Fri 8 Mar 2024) - SRT, MTW, KINO, JUST

Good morning from Paul!
I've got to prepare for an introductory call with mgt of Property Franchise (LON:TPFG) a little later, which I thought would be useful as one of our favourites, Belvoir, is absorbed within TPFG today. So if anyone can think of anything intelligent-sounding that I can ask them, please do leave a comment below! I'll ask them to continue with the small shareholder communications that Belvoir excelled at (coming to conferences, doing presentations on Mello, etc)
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Paul's 2023 share ideas, with live prices.
New SCVR summary spreadsheet from July 2023 to date, updated at weekends (very useful quick reference tool, search for ticker using CTRL+F). Hover over cell for pop-up notes.
Frozen SCVR summary spreadsheet for calendar 2023.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Quiet for news today, so I'll do a couple of backlog items too -
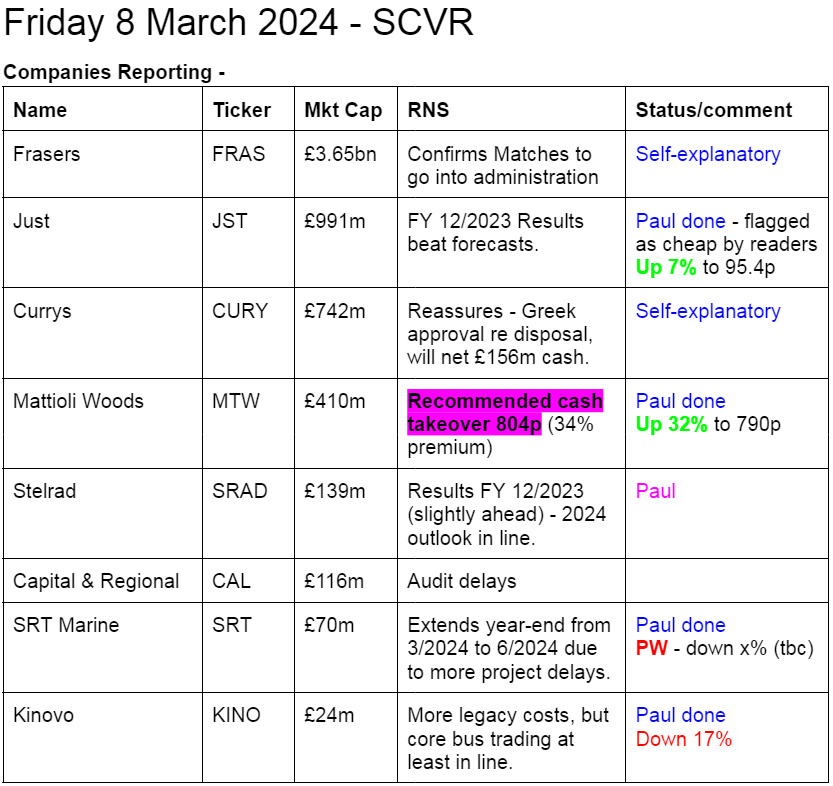
Quick comments on movers with news
Just (LON:JUST) - up 12% to 99.5p (£1033m) - Results FY 12/2023 - Paul - no view - too complicated! So I’ll mark it as AMBER.
Very interesting reader comments today on this specialist financial services group, focused on the retirement income market.
The attraction of this share seems to be -
- Strong results out today: 27.9p u/l EPS actual vs 26.6p broker consensus (upwardly revised several times in 2023)
- Big discount to NTAV (claims it has 224p NTAV/share) vs 99.5p current share price.
Not so good points are -
- Modest divis, but it says will “grow over time”
- Govt consulting on ground rents may affect JUST’s £176m portfolio
- Balance sheet NAV is a small difference between huge assets, and huge liabilities
- Complicated accounts.
Paul’s view - I don’t usually review banks or insurance type businesses, as it requires specialist expertise to properly analyse them, which I don’t have.
Another reason I avoid personally investing in these sectors, is that unforeseen world events can cause shocks to the system, with outside investors never really knowing what huge contractual assets or liabilities could become problematic. Look at any bank’s balance sheet at the gigantic numbers called “derivatives”, and any number of future horrors could be lurking in there. The key lesson from the 2008 crisis is that big financial organisations think they’re managing risk, but some unforeseen event can quickly cripple them - which applies to insurance companies too. Look at the debacle with the autumn 2022 mini budget, where derivatives forced pension funds to start panic selling due to margin calls on their contracts that were supposed to manage risk.
Anyway, sorry if this sounds weak, but I don’t want to give any opinion on this share, as it’s way outside my area of expertise.
Summaries of main sections
SRT Marine Systems (LON:SRT) - 31.6p (pre-market) £70m - Change of Year End & Update - Paul - BLACK (profit warning), on fundamentals RED
Misses forecasts for FY 3/2024, so it's extending the year to a 15-month period to 30 June 2024. Yet another, in a long track record of big disappointments. Shares look impossible to value, due to wide range of potential outcomes.
Mattioli Woods (LON:MTW) - up 32% to 790p (£410m) - Recommended cash takeover - Paul - PINK (takeover)
Not a particularly generous bid, at a 34% premium. It will be interesting to see if the mainly institutional shareholder base will welcome a liquidity event, or push for a higher price? Yet another example of the stock market undervaluing UK shares compared with private markets.
Kinovo (LON:KINO) - down 17% to 39p (£24m) - Update on Discontinued Operations - Paul - RED
More cost over-runs for its discontinued operation are announced today, but also reassurance that the core business is trading well, "at least in line". I think a recovery trade is possible here, but for me there's too much risk of dilution, due to its weak balance sheet. So I continue to flag the risk, with RED, but I don't know what's likely to happen with the share price, it could be a recovery candidate possibly?
Paul’s Section:
SRT Marine Systems (LON:SRT)
31.6p (pre-market) £70m - Change of Year End & Update - Paul - BLACK (profit warning), on fundamentals RED
SRT Marine Systems plc ('SRT'), the AIM-quoted developer and supplier of maritime surveillance systems and navigation safety products hereby provides a business update and notification of a change in financial reporting date...
I think this update has been heavily PR’d, but there’s no getting away from the fact that it’s a profit warning. Key points -
Delays in project deliveries (blamed on Govt bureaucracy, and even Ramadan &EID!) will miss 31 March year end cut-off, slipping into Q1 2025.
No problem, they’re just changing the year end, extending it by 3 months to 30 June 2024 (so a 15-month one-off period).
It says this is necessary because poor FY 3/2024 results would mean SRT failing financial checks from key potential customers (no details provided).
Cash is said to be strong, after a £10.5m fundraise in Dec 2023, but no figure provided for current cash or net cash (remember it has gross debt too, of £9.6m at Sept 2023).
15-month forecast revenue is the same as previous 12-month forecasts - so effectively a reduction. H1 was £5.5m revenues, so £70.9m FY forecast looks like fantasy to me.
Paul’s opinion - checking back, the forecasts for FY 3/2024 showed a gigantic H2 weighting, which looked unrealistic from the start. SRT once again demonstrates that it has little to no visibility over revenues.
What’s the betting it will need yet another placing at some stage? Fairly high, I would say.
I imagine the market is likely to take a dim view of today’s latest disappointment. Maybe SRT would be better off as part of a private group?
I went up from red (after lousy H1 figures) to amber/red (after 21/12/2023 fundraise, which included £7m from a “strategic investor”). However, today’s profit warning means I have to go back to RED.
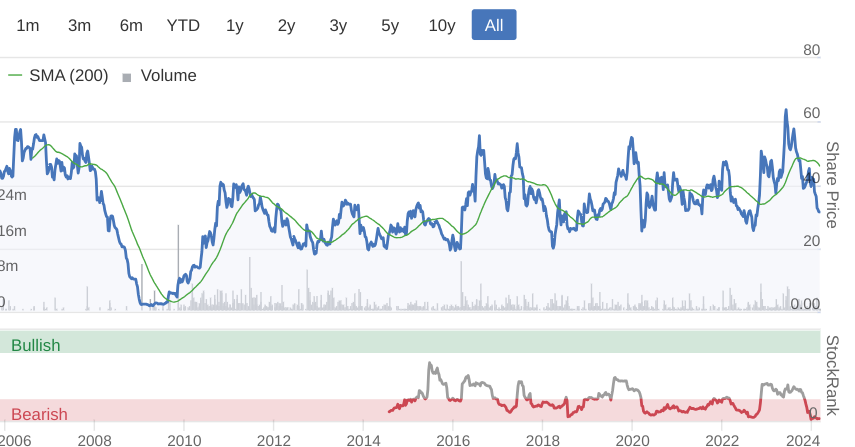
I see a pattern emerging over the last 18 years -
Mattioli Woods (LON:MTW)
Up 32% to 790p (£410m) - Recommended cash takeover - Paul - PINK (takeover)
Recommended unanimously by MTW’s Board.
Cash bid of 804p cash (£432m), plus divi already declared.
34% premium to last night’s close - so not particularly generous.
The bidder is a fund managed by recently floated Pollen Street (LON:POLN) which we’ve not yet looked at in the SCVRs.
Valuation - interestingly it doesn’t mention EBITDA, but instead bid price is 16.3x adj PER.
Irrevocables only 12.4% - so might be an uphill battle to get shareholders to agree this deal.
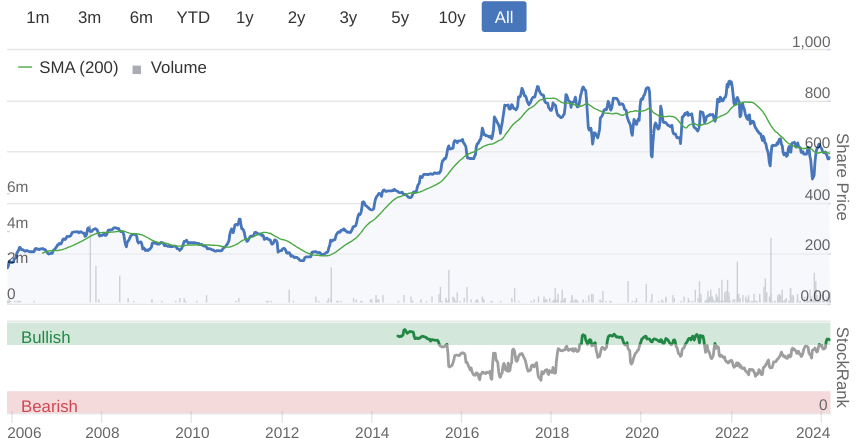
Paul’s view - looking at the chart below, this bid only takes the share price back to where it traded in 2017-2022. Arguably, it might recover back to that level (maybe beyond?) of its own accord in the next bull market.
Although institutions might welcome a liquidity event, freeing up cash to meet redemptions or make new investments, plus of course an instant boost to their performance statistics.
It’s yet another example that private buyers are valuing some UK shares at prices well above the public market, which is very exciting in my view, offering us opportunities to make money, if you can look beyond the short-term gloom (what is it about being greedy when others are fearful?).
MTW looks a decent company, and I’m not convinced this takeover approach is generous enough to succeed. The ideal scenario for holders would be if someone else comes along with a higher bid. I like the niche activities MTW has within its range of services, and I vaguely remember a management presentation a few years ago which impressed me.
Kinovo (LON:KINO)
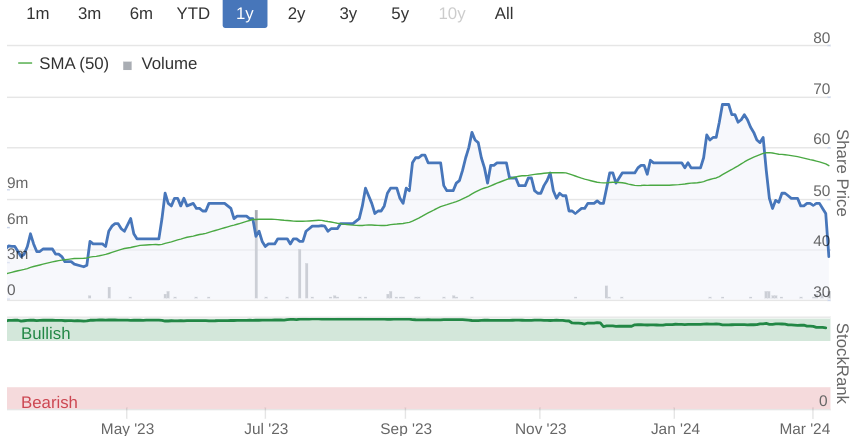
Down 17% to 39p (£24m) - Update on Discontinued Operations - Paul - RED
Kinovo plc (AIM:KINO), the specialist property services Group that delivers compliance and sustainability solutions, provides the following update on its discontinued operations.
I’ve only reviewed this once recently, here on 9/2/2024 (55p) - where I viewed it as red, because the expensive legacy issues and weak balance sheet seemed to present unattractive risk:reward. That’s even though the core, ongoing business, looks OK.
Today it says there will be another £2.9m costs to finish off the remaining disastrous projects of its incompetent former building division.
However on the plus side, we get an upbeat-sounding trading update for the core business -
The continuing business is performing strongly during the peak trading season and the Board continues to anticipate the outlook for the full year ending March 2024 to be at least in line with that provided on the 9 February.
Paul’s view - there could possibly be a risky recovery trade here, if the legacy issues can finally be shut down without any more additional costs.
However, having looked again at the last balance sheet, and adjusting it for more provisions since announced, I think it’s too weak for me to want to get involved. So I’d say dilution risk seems quite high, and it mentions continued support from HSBC today, which makes me nervous.
Good luck to anyone punting on KINO, but for me risk:reward still doesn’t stack up. I prefer situations where the upside is obviously tilting in my favour, without having to use hope, or guesswork, so I’ll stay at RED just to flag the higher risk here. Remember we’re not predicting the outcome with RED, as risky situations can occasionally produce lovely rebounds. It’s up to you to decide how you see risk:reward, and this one could go either way I think.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

58 comments
Just taking a look at IPOs since March 2020. Not a vintage crop putting it politely.
44 down more than 85%
Regtech and supply@me have the same bloke In charge, very impressive!
21 up 50%+
Of the 44 losers only 3 have positive free cash flow. Of the 21 winners 8 have positive FCF.
Volume leaders today. Have a good weekend all :)
We found similar in our 2021 study of IPOs:
"IPOs, on average, tend to rise after the initial float, reaching a high around six months later. Performance then begins to drop as interest wanes. The strong average performance figures after 1 year are largely driven by a small number of well-performing IPOs".
Full study is here: https://www.stockopedia.com/ac...
Peel Hunt (LON:PEEL) doing comparatively well and not selling off still of late inspite.I'm wondering if the market assumes it will get a part of the very potential Shein offering..?London Stock Exchange (LON:LSEG) was more enthusiastic recently than usual with regards to the actual LSE stock listing business.
Supply@Me Capital (LON:SYME) was a UK meme share and very popular on a UK bulletin board to be fair.
Someone tried to tell us: https://www.stockopedia.com/co...
Paul, It will be good to read a summary of your call with the management of Property Franchise (LON:TPFG) which I hold. There is a new note from Canaccord out today, Big and Better, which is available on Research Tree.
SRT I'm not sure what I find funnier: another contract delay or Paul writing "down x% (tbc)".
Some big volume in GB (LON:GBG) this morning. Might be highest ever daily volume looking at it.
Thank you Mr Wolf. I do wish stocko had this function. I have bought into GB (LON:GBG) thinking news of a bid may have leaked. The sp hasn’t moved much yet
No worries roger. Its probably just a transfer between institutions around 260p. Price looks to have been moved down in the past week to get this away. Big trade just under 7million, lots of holders with 7m+ holdings.
Why do you think GB (LON:GBG) might be bid for? £665m cap vs. Fcst revenue of £279m and a PSR of 2.4
What's the attraction to a bidder?
It's purely a punt and doubtless Wolf is correct in his assessment
It has been touted as a possible target for some time and there was what I would describe as 'false' bid 2 orb 3 years back when they changed their advisors in very rapid order to the same ones that advised on the Ideagen takeover by HG Capital. I use the term 'false' as the bidder at the time was responding to rumour that caused the price to spike and went in at what many considered to be an opportunist level and would not budge to higher levels and then withdrew without putting in any sort of a fight. There is some relevance here in that GBG's chairman, Richard Longdon, was at the time of that bid the IDEA chairman when it was sold. Richard has experience of selling well.
.
Roger
I have found the ADVFN app useful for near real time information. It's free and the data stays visible on screen after a burst of updating. inter-day graphs and trades are available as well as news. I find it a useful supplement to Stockopedia.
Property Franchise (LON:TPFG) been keen to buy some of the these but price keeps rising and waiting for a better entry point! I'm wondering if we might see a bit of a pullback if the now ex-Belvoir shareholders decide to sell up?
Just (LON:JUST) - its very cheap versus book value. I have held in the past. The problem with the business model is poor cash flow generation, hence the very low dividend. Worth another look though on the back of these results. The equity release product didn't help, other than hedging retirement annuities, as it was cash out on day 1 and no cash back for 20-30 years!
Just (LON:JUST) while quite possibly too big for the SCVR I like boring shares that help me sleep at night
Just Groups results today reassure with adjusted operating profit +5% ahead of expectations & a total 2.08p dividend
I see that RBC have set a price target of 115p
*with apologies for the delay in posting this, I wrote it pre 8am but for some reason it never uploaded
Hi AstonGirl,
It does seem an utterly bizarre price target - 50% discount to TNAV
Topvest,
The previous business model was somewhat ill considered as it was upfront cash hungry and not capital generative. The current management have spent a few years changing that around significantly. The business now generates capital, cash flow and profits and is not particularly sensitive to rates or house prices. The dividend needs to grow for sure but the discount to a growing NAV appears arbitrary at best to me. I’d imagine someone will buy them well north of 150p if it persists given the business now generates own funds.
Yes I hear some of the big US asset managers are keen to enter the UK pension space to take advantage of all the schemes now looking to offload their pension liabilities. Just would provide a good platform to enter this market.
SRT Marine Systems (LON:SRT) should consider a new logo
“Lost at sea”.
Probably deserves a more nautical theme as you say Harry. Well it is Friday :)
Done in Copilot in a couple of minutes:). My money is on Nvidia taking the number one spot by MC before too long.
SRT Marine Systems (LON:SRT) Wolfie To be honest how are they still allowed to be listed after so many years of daylight robbery?
And the likes of many many others.
Time permitting I will prepare next week a list of small cap companies that need to be addressed by the LSE along with the different brokers that keep pumping money into them in discounted placings.
Look at Kinovo (LON:KINO) announcement today! Obviously they do know the cost of these legacy issues and the need of a placing-just keep hiding it at the expense of innocent and probably new investors.
SRT. The ultimate ‘jam tomorrow’ company. I once asked Simon Tucker if they would be better off as part of a larger group. Halma for example. Smaller companies represent a big risk to governments spending large sums on critical IT infrastructure projects. They might not be around when a wheel falls off. I remember talking to Marlborough Stirling about this very issue which, was what lay behind their takeover by United Utilities all those years ago. Time to think about it again.
SRT. It's an interesting point. I know, for example, that big oil companies would much rather deal with companies that have ISO9001 certification. If not, managers have to ask lots of questions, which understandably they'd rather not deal with.
Maybe it's the same idea here. As part of a larger group they may be automatically certified, gone through maybe security checks or whatever, making the whole process much smoother.
As an interesting counter to all the negative sentiment here around SRT Marine Systems (LON:SRT) (I hold) their broker note is available from Cavendish who suggest that their financial situation could rapidly and dramatically improve once agreements are in place as they have large quantities of ready to ship kit just waiting to be released.
As with Beeks Financial Cloud (LON:BKS) (I hold) these sort of systems are complex, take many years to develop and have to go through a miriad of regulatory hurdles but once put in place are hugely sticks and come with signifcant annual recurring revenues and upgrades.
@SRT Political risks impossible to quantify.
Just (LON:JUST) - results today ( just under the £1 billion market cap so in the SCVR universe). Looks like a big hit - does anyone understand why they seem so cheap? PE ratio is 3ish
Just (LON:JUST) results were tremendous in my view
Roll up roll up - buy £1 coins for 40p here ;-) seems ridiculous to me that with a TNAV of 225p they trade at 95p but there we go.
Historically the company traded lowly because (a) it was too exposed to house price equity and (b) to interest rates and (c) was not generating own capital
Now it doesn’t have that exposure, generates its own capital, is growing its dividend at 15% (from a low base) and is exposed to a strong market sector that is highly cash generative.
Quite why it trades so far below NAV is beyond me. It’s not like peers trade at anything like that discount so hopefully it will narrow soon…… I hold.
Thanks davidjhill, that sounds very interesting, I'll try to have a look at Just (LON:JUST) later this morning.
Best wishes, Paul.
hi Paul - thanks. And I don't find it at all wishy washy that you conclude it's outside of your area of expertise....... if only other commentators would do the same at times - we can't all be an expert on everything and being honest when not is an important trait in investing I think.
Just (LON:JUST) results looks good and very cheap. What may put some off is the low dividend - most life insurers are paying 8-9% yields. My understanding is that Just are taking on lots of new business (annuities and pension scheme liabilities) - this does not immediately generate any cash but should do in future years.
Stocko has the NAV at 113p?
Stocko doesn't seem very reliable for insurance companies (probably confused by the complex accounting) - the FY report today says tangible net assets per share is 224p.
Given they target the retirement market, they must press just about every hot button in the FCA’s offices.
No more than any other regulated financial business
Hi David- reading the comments here all v interesting but just how does JUST make their money nowadays. The website has loads of jargon - as you would expect - and I can understand the comment that FCA must be all over them. On the plus side - whilst there are plenty of complaints about coys such as StJames and HL I never hear any comment good or bad about JUST. Look forward comments from Paul - but suspect at the end of the day its just too complicated financial manoeuvring for me.
How they make money is actually pretty simple - they get paid to take on a long-term pension liability, and invest the proceeds in a bunch of long-term assets (mainly bonds but also some property related assets and other alternatives). Over time they expect the gains on these assets to exceed the pension liabilities.
Just (LON:JUST). If the company believes it can make enough money from investing the payment to cover the pension liabilities, why don't the large companies offloading their pension schemes simply do the same. Why do they offload it to Just? Is it to get the liabilities "off the books" (eg Reach (LON:RCH)? Thanks...
Just (LON:JUST)
If the company believes it can make enough money from investing the payment to cover the pension liabilities, why don't the large companies offloading their pension schemes simply do the same.
I have to presume Just only take on the companies that are well enough funded that they liabilities can be hedged/insured with very high level of certainty with no cost to them - or a cost that is paid for by company transferring scheme to them.
I also presume schemes like Reach (insert classic line from that Whitesnake song) are not in a position where liabilities can be fully hedged as there is not enough safety net in surplus of scheme assets over liabilities or there is no surplus.
Look at Premier foods they had surplus of £765 mill on the balance sheet at last year end and they still need to sort our the detail to preaumably pass over thr scheme to someone else - or have it fully insured. At least they have confirmed that day is soon approaching. I have not seen any proof positive that Reach are heading in that direction - and the fact they still have chunky payments to make to fund the scheme kinda says where they are as of now - IMHO (others will surely disagree)
Similar to Phoenix group (LON:PHNX) if you know them bohenie.
It’s like a pension run off business but Bouden is a reasonable explanation.
Does a leopard change its spots? It may be a buy right now but don't stay too long! I don't hold because I pulled out 23 months ago struggling to do that at 93 pence after buying at 69 pence in September 2018, my selling price so, so similar to that of today.
Triple Point Social Housing REIT (LON:SOHO) FY23 results:
Maintaining dividend (10%) which is covered on a run rate basis (90% cover for the year) and expect to return to progressive divi in due course. No real update on Parasol and MySpace except that they are expected to pay increasing rents over time, but no other issues with registered providers and a useful update on the top 10 in respect of their regulatory positions. Expect further strong rental growth.
Don’t expect the election to have any impact on the model, demand strong etc. Not planning any further disposals in current market, not any further new developments. Happy to take 10% divi here!
Mattioli Woods (LON:MTW) another one goes…Pollen Steet buying for 804p/share
Sold out of this a few years ago - when the price was around 800p -
Well done, but how much value does this comment contribute to the community ?
That is a punchy premium on assets of £15Bio.
My morning smallcap tweet: The long and grinding road
Kinovo (LON:KINO) Sutton Harbour (LON:SUH) Petrofac (LON:PFC) SRT Marine Systems (LON:SRT), Stelrad (LON:SRAD)
◄Kinovo (KINO)► cost to complete all the DCB discontinued projects up £2.9m from £5.72m previously estimated. Blames a number of unforeseen and legacy issues arising from poor quality workmanship. [SP=46.38 Cap=29m]
◄Sutton Harbour (SUH)► borrows another £450k from BDSL and extends repayment to May 2025. [SP=10 Cap=14m]
◄Petrofac (PFC)► wins three year $200m contract. [SP=23.26 Cap=121m]. I'm short.
◄SRT Marine Systems (SRT)► extends FY end by 3 months to June to ensure its YE financial ratios meet certain minima. The minima are set by a foreign gov't for companies bidding in one particular jurisdiction. 'Prudently' guides FY (15 months) rev same as guided for previous FY-Mar due to possible/probable project delays. So a warning then. [SP=31.51 Cap=70m]. I hold.
In line: SRAD
Interesting piece by John Authers on UK PLC
"The small companies sector, despite much-ballyhooed projects to build it up, has dwindled to what Absolute Strategy’s Ian Harnett calls an irrelevance. Institutions need to take huge stakes in them to make any difference to their overall performance. This dynamic impedes capital from staying in the country, and particularly from going to the kind of growing companies that might most buoy the economy:"
https://www.bloomberg.com/opin...
Good for private investors... less institutional competition should mean better chance of better than index returns by stockpicking.
However, liquidity suffers massively....