Small Cap Value Report (Fri 8 Sep 2023) - G4M, SUP, HARL, MORE, CRW, CRN, HEAD

Good morning from Paul & Graham!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £1bn. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk.
Summaries
Gear4music (HOLDINGS) (LON:G4M) - 87.5p (pre market) £18m - AGM Trading Update - Paul - AMBER
A reassuring update, reiterates full year expectations. Focusing on profit over growth now. £10.0m forecast EBITDA is a nonsense number, due to large capitalised development spending (although this is being reduced). So only £1.4m adj PBT is forecast for FY 3/2024, which isn’t enough to get me excited.
Supreme (LON:SUP) - 114p (pre market) £134m - Times article - Paul - AMBER
An interesting article in today’s Times newspaper flags that Supreme a company connected with Supreme's CEO has donated £350k to the Conservative Party. Supreme’s vaping products are criticised for being colourful and with scents which may appeal to children. Personally I’m worried about vaping, as it seems to be a new way of creating the scourge of nicotine addiction. Other views are available. Shares look good value, and the big political donation might help deter any action to curtail vaping! [no section below]
Harland & Wolff group (LON:HARL) - down 13% to 13.25p (£23m) - H1 Results - Paul - RED
Absolutely horrendous H1 figures - revenue of £25.5m, loss before tax of £(31.5)m, which includes a huge £13.8m in finance costs. Losses blamed on increased headcount in advance of big contracts. Huge order book of £1bn over 7 years. Balance sheet is one of the worst I’ve ever seen, with NTAV negative at £(92)m. Current assets £25m, current liabilities £142m! This is a crazy capital structure, where the business is funded entirely with large loans. It’s doubling down too, with “advanced negotiations” for a new £200m facility. Paul’s opinion - this share could easily go to zero, with big dilution or insolvency. Super high risk, but with equity valued at only £23m, there is leverage here for a speculative spike up - purely for gamblers. On fundamentals, I would deploy my bargepole for this share. [no section below].
Hostmore (LON:MORE) - unch 15.75p (£19m) - Resignation of CFO - Paul - RED
We’ve reviewed this TGI Fridays restaurant chain 3 times in 2023, concluding RED every time, flagging in particular the high risk of a profit warning, excessive debt, high risk of a discounted fundraise (or insolvency). See SCVRs on 10/1/2023, 10/3/2023, and 7/6/2023 for more details.
The company put out a bullish-sounding presentation earlier this year, which caused a spike in share price from 14p to 24p, when they said it could generate £10m pa in cashflow and pay off bank debt in 2 years. In retrospect, I think that’s probably pie-in-the-sky.
Put all that together with the abrupt resignation today of the CFO, and my hunch is that things could be going badly wrong here. A further downturn in sales would probably be terminal, because of the operational gearing in the restaurant sector. Hence I want to reiterate my worries about insolvency or a highly dilutive placing here. Very high risk, and I’m not touching this one again unless it’s properly refinanced with fresh equity. What price would that be at? 1p? 2p? It could be anything. I imagine existing equity could get all but wiped out here, if the downside scenario plays out. Why take that risk? We can get out, but the institutions can’t.
Craneware (LON:CRW) - 1530p (£543m/$678m) - Final Results (Tuesday) - Graham - AMBER
I provide the notes from my call with management of this software group selling into the US healthcare market. It helped me understand their views on a range of issues and hopefully it will help you, too! I have a positive impression of the business; stock might be fairly valued.
Cairn Homes (LON:CRN) - 94.4p (£636m/€742m) - H1 Results to June 2023 - Graham - GREEN
Excellent news from this Irish housebuilder as full-year guidance is upgraded. A very large H2 weighting is expected which should unwind the inventory position and reduce net debt. The large buyback programme expands to €75m at what I believe is an attractive valuation.
Headlam (LON:HEAD) - 227p (£183m) - Interim Results - Paul - AMBER/GREEN
I have a good rummage through the H1 results below, following a profit warning in July. H1 profit came in 65% below last year, due to gross margins weakening, and higher costs. An immensely strong balance sheet with c.£100m of freeholds, and modest net debt, makes this very securely financed. Current trading still sounds a bit soft, but medium term there are good reasons to expect a nice recovery in earnings. I'm tempted!
Paul’s Section:
Gear4music (HOLDINGS) (LON:G4M)
87.5p (£18m) - AGM Trading Update - Paul - AMBER
Gear4music (Holdings) plc, ('Gear4music' or 'the Group') (LSE: G4M), the UK's largest retailer of musical instruments and music equipment…
Trading is in line -
"We are pleased to report that trading during the financial year to date has been in line with the Board's expectations.
* Gear4music believes that consensus market expectations for the year ending 31 March 2024 prior to release of this announcement were revenues of £161.2 million and EBITDA of £10.0 million.
Prioritising profitability ahead of growth, so cost control and gross margin.
“Significant cost efficiencies” in software development unit - note that G4M capitalises a lot of development expenditure (£5.3m in FY 3/2023), which is why EBITDA is meaningless here, as it completely ignores these substantial costs. I’m glad savings have been made here, as the costs previously seemed excessive.
Secondhand system has launched well, in the UK and more recently in Europe too.
“Well prepared” for seasonal trading peak upcoming.
Paul’s opinion - the problem here is that £10.0m EBITDA only becomes £1.4m adj PBT (see Progressive note, 20 June 2023). Lots of revenues, of £161m, but hardly anything in profit. What’s going to change to improve that? I’m struggling to think of anything big.
The last accounts (which I reviewed in detail here) showed a very welcome and large fall in bank borrowings, so I think this share is relatively safe. It’s also got freehold property assets.
The original bull case with G4M, which caused 2 huge bull runs, since dissipated, was that rapid growth and improving margins (as it scaled up) would result in the profit margin rising from miniscule, to something more like c.5% - which on large revenues, would make it highly profitable. At this stage, I just don’t see that as being a likely outcome any time soon.
Therefore I don’t think I can get above AMBER (down from amber/green last time) for the time being, but I’ll keep an eye on developments.
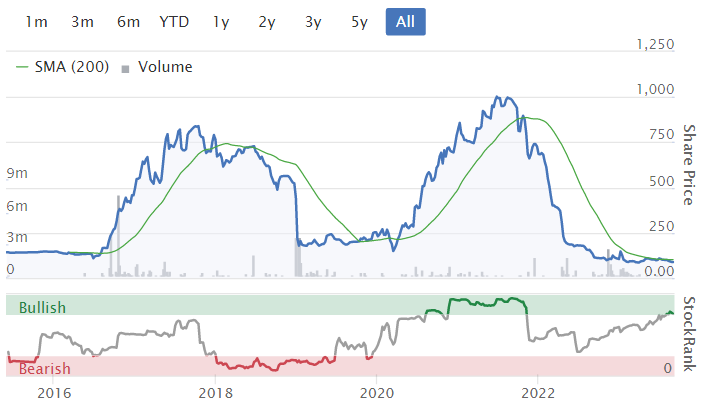
Two fantastic bull runs (the trick is clearly to sell, when it stops rising) -
Headlam (LON:HEAD)
227p (£183m) - Interim Results - Paul - AMBER/GREEN
Headlam Group plc (LSE: HEAD), the UK's leading floorcoverings distributor, today announces its results in respect of the first six months of the year to 30 June 2023…
Slightly ambiguous wording there, it’s H1 of FY 12/2023.
It’s nice to see a headline below that is realistic about profits being down, instead of trying to cover it up (e.g. Beeks Financial Cloud (LON:BKS) this week [I hold]) -
Revenue growth and good cash generation; profits lower due to macro and industry headwinds
If you recall, HEAD issued a profit warning on 27 July 2023 - see my notes here. This said that H1 would see revenues of £332m (up 2.5%), and a sharp fall in underlying PBT from £17m in H1 LY, to only £6m in H1 2023.
Interestingly, and encouragingly I think, the share price spiked down, but almost immediately recovered, and has been edging up a little since. Is this a sign that the bad news is now priced-in, I wonder? That could be bullish, not just for this share, but for other cyclical shares too perhaps?
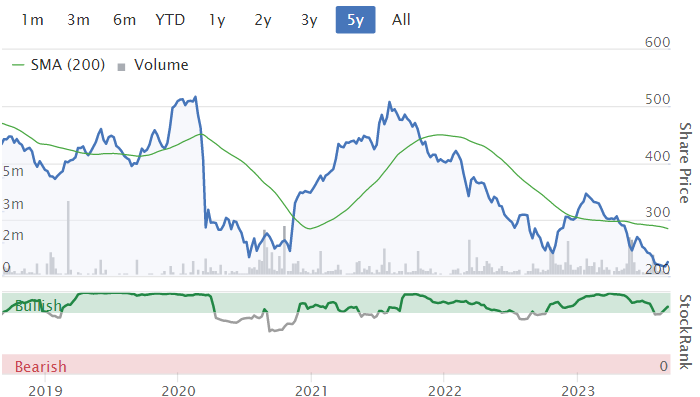
Note that the share price of HEAD is actually lower than the low at the worst point in the pandemic. The share count has actually fallen too, due to buybacks. So this is looking very cheap compared with historic norms. Which does of course raise the question as to whether something fundamental might be going wrong at HEAD - the obvious one being increased competition from Likewise (LON:LIKE) (led by HEAD’s former CEO)?
Right, on to the actual numbers for H1, which I would expect to be the same as the TU in July.
Revenue up 2.5% to £331.8m - yes that’s as expected.
Underlying PBT also in line at £6.0m (down 65%)
Operating profit (underlying) is £8.2m (H1 LY: £17.9m)
Why is profit down so much? -
…principally impacted by the macro and industry headwinds of lower residential trading volumes and high operating cost inflation
This is despite cost-cutting, profit still fell significantly -
Efficiency and mitigating actions contributed £5.0 million of benefit in the first half, expected to build in H2
It provides a profit bridge from H1 operating profit LY, to this year -

Actually, I’m going to challenge this bridge, as I don’t find it very convincing. A key reason for the drop in profits is that gross margin was lower, at 31.5% H1 TY, vs 33.7% H1 LY. That caused a £7.3m fall in gross profit, but it’s not mentioned at all in the table above.
So the way I see it, I’ll ignore the table above, and instead my conclusions are that profits fell due to -
Lower gross margin (£7.3m impact), and
Increased admin/distribution costs (£5.6m impact)
It doesn’t precisely reconcile to the £9.7m drop in operating profit, but it’s roughly in the right ballpark.
Finance costs more than doubled, up from £1.0m to £2.2m. Note 4 shows that there was no interest income in H1, suggesting it’s in a negative cash position throughout the period. That’s confirmed by bank interest payable in H1 being £1.0m, versus £0.2m in H1 LY. So definitely a deterioration in the cash/debt position. Maybe there's a credit interest offset against the bank borrowings?
The lower gross margin concerns me, because that is indicative of increased competitive pressure.
Having said all that, in a tough macro environment, I wouldn’t expect profits to be static. As long as it’s not loss-making, then a lean period now might just be a blip, who can say?
Interim dividend is reduced, but still worth having at 4.0p (LY H1: 6.2p). A key feature of HEAD shares is the generous divis historically, and importantly it is so financially strong that its dividend paying capacity remains good. So once this soft patch has passed, I think divis could resume an upward trajectory.
Balance sheet - this is fantastic! NAV of £219.9m, only £21.3m is intangible assets. So NTAV is £199m - about half of which is freehold property. The market cap is £183m, so this share is more than entirely backed by tangible net assets - a real sleep soundly share to hold - ideal when you’re anticipating, and waiting for a recovery in trading.
There’s a £3.3m pension deficit showing as a liability.
Cashflow statement - is actually improved, because of normalised working capital movements. H1 TY also saw £3.7m spent on an acquisition, quite hefty capex of £9.7m in H1 - is this is the roll-out of trade counters perhaps? £5.2m was spent on share buybacks, and £9.0m in dividends in H1 - hefty shareholder returns, but probably not sustainable at that level for now?
There was a large drawdown of bank borrowings of £60.0m, offset partly by repayment of £23.2m borrowings, so it looks like the company has adjusted its cash/debt position there to give it more headroom I’d say. Not a concern though, as the levels are comfortable - net bank debt of £19.6m at June 2023, albeit considerably worse than £1.8m net cash at Dec 2022. Hence why I think the big shareholder returns probably need to be reined in for now.
Current trading - “broadly in line with expectations” for July & August, but mitigated with cost savings, so -
...management's expectations for the full year are unchanged
That sounds OK. No sign of any green shoots at the moment, and with house building set to slow down markedly, I would say the macro factors are probably not going Headlam’s way any time soon.
Therefore I’m wary that it might deliver another profit warning. Is that a worry though, given the market reacted so stoically to the recent profit warning?
Outlook - I find this reassuring -
Looking ahead, the ongoing macroeconomic and industry headwinds are likely to prevail into 2024, with suppressed residential consumer spending continuing. However, the medium-term market outlook is strong; annual volumes are currently around 20% lower than in 2019 and we expect volumes to improve significantly over the coming years.
This, combined with the increasing benefits as the strategic initiatives mature, provides opportunities for material profit improvement over the medium term including as a consequence of high operational gearing. Furthermore, the cash requirement, albeit relatively modest, from the strategic initiatives is anticipated to reduce, providing a further boost to cash generation.
Strange that they think they have high operational gearing. It’s a low margin business, so surely operational gearing is quite modest? Maybe they mean that the bulk of the overheads are fixed costs, which makes sense.
Paul’s opinion - I’ve viewed HEAD as AMBER the last couple of times, as tougher trading became apparent. However, on being reminded of the tremendous balance sheet strength, and the upbeat medium-term outlook, and the share price resilience to the last profit warning, I’m seeing signs here we might be over the worst. So I’m warming again to HEAD as a recovery trade for the medium term. There’s probably more upside than downside, hence I’m tempted to dip my toe back in with a small position here, when funds permit. With the intention of buying more if it continues falling.
Recent comments from the Bank of England, that it sees inflation falling, and interest rates now being at or near the peak, suggests to me that buyers might be starting to nibble at cyclical companies like this again. When the bull market starts, it can surprise everyone at its speed, and often anticipates improved fundamentals - if we sit and wait for confirmation of an economic recovery, we’ll probably miss a good part of the next bull market. Hence I’m definitely warming to the idea of putting some money to work on shares like this, and Eurocell (LON:ECEL) (£100k Director buy there this week too), even though the figures look rather poor at the moment. They both have nice strong balance sheets, which means short term share price falls are not a concern.
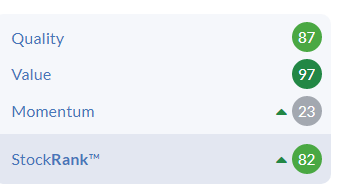
Stockopedia likes the value and quality, but obviously not momentum -
Graham’s Section:
Craneware (LON:CRW)
Share price: 1530p
Market cap: £543m ($678m)
This software group (serving US-based healthcare providers) issued full-year results on Tuesday.
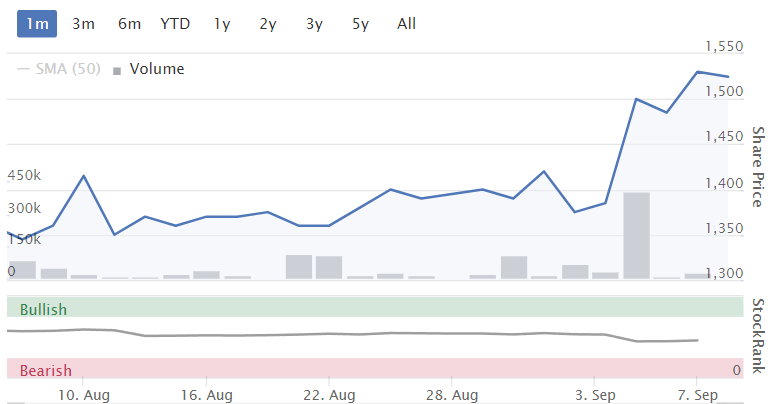
The share price reacted positively:
I had been up all night with a fever, causing me to miss the SCVR on Tuesday, but I had a conference call arranged with Craneware management shortly after 10am. So I did get the chance to speak with CEO Keith Neilson and CFO Craig Preston.
Before getting into the contents of the call, let me remind you of the headlines from Craneware’s full-year results.
Revenues +5% to $174m
Annual recurring revenue nearly equals total revenues.
Adj. EBITDA +6% to $54.9m
PBT $13.1m (unchanged on the prior year)
For a more detailed review, see Roland’s fine article earlier this week.
Cash - $78m of cash offset by $83m of total borrowings ($75m long-term, $8m short-term).
Interestingly, the Craneware balance sheet includes $51m of cash representing “amounts held on behalf of customers”. So it’s perhaps more reasonable to treat the company as having $27m of its own cash, offset by $83m of total borrowings. That leaves a net debt position of $56m.
Operational highlights - the company has migrated customers onto its new “Trisus” platform, where it can offer a wide range of services. Craneware is even generating some revenues from third parties who add their own applications to the Trisus platform. Customer retention has been maintained at over 90%.
Outlook statement:
COVID-19 public health emergency in the US formally declared over in May 2023, providing a more supportive market backdrop at the end of the year and into Q1 FY24
Continued post-period sales momentum and a growing pipeline of opportunities
Well positioned for FY24 and beyond with balance sheet strength, high levels of ARR and early signs of increasing customer confidence.
My call with management
It was just a brief 15-minute call but I got to ask a few questions which I thought would be helpful for myself and for readers. I have paraphrased the answers below based on my notes - these are not direct quotes from management!
Q1. I asked them to break down in plain English what their software achieves for their customers. Specifically the difference between “digitisation” (this is not what they do) and “digitalisation” (this IS what they do!).
A1. Keith Neilson explained that “digitisation” is simply the recording of individual transactions in a digital format, whereas what Craneware does - digitalisation - is taking all of the data from individual transactions and using it to look for improvements in business processes. Craneware’s solutions can look at the back end of a hospital and help find ways to do things better, with potentially billions of dollars of savings (healthcare spending is enormous!).
Q2. I asked if the demand for Craneware’s products was driven largely by regulations (such as 340B) or if it was largely optional for customers to sign up.
A2. It’s a mix of both. Firstly, there are reporting standards which hospitals have to comply with. You get large amounts of customer data which have to interact and comply with these standards. And then you have the money-saving insights and improvements that are made possible by the software.
Additionally, under the subscription model, the vast quantity of data is constantly being updated over time (i.e. it’s not just an instant piece of analysis - hospitals can see how their processes are changing over time). With high customer retention of 90%+, most customers get to see these long-term benefits.
Q3. With inflation so high over the past year, investors have a different perception of what is an attractive level of revenue growth. Has Craneware’s 5% revenue growth been driven by pricing increases or by additional customers and product sales? And how does the company intend to manage inflation in future?
A3. Craneware has been keeping its pricing flat, so the revenue growth it achieved over the past year is from additional customers and additional product sales.
Its customers have had to deal with very high wage inflation and would have been very unhappy to see rising software costs on top of that. However, US inflation has fallen to only 3% and so they are back to more normal conditions now. The prices of individual Craneware products can contractually be increased. But the company would prefer to grow by developing new software and increasing the value of existing software, rather than increasing its prices.
Q4. Given that the company’s balance sheet includes customer-owned cash (due to one of the company’s roles as an intermediary in the transfer of cash), there is a net debt position. How does the company see this position evolving in the future?
A4. Firstly, the customer-owned cash is a good thing for the company. It can be offset against customer invoices, so it reduces the risk of bad debt. It is also interest bearing, and the company is looking for ways to improve its cash management in order to reduce its net net finance expense (the amount of interest the company paid this year doubled from $3m to $6.5m).
The customer-owned cash is high-volume, staying for a short period of time but being constantly replenished.
As for the overall net debt position, the company is comfortable with the amount of debt it’s carrying but may seek to pay some of it down early. It has confidence thanks to its high levels of ARR/repeat revenues.
Graham’s view
Many thanks to Alma PR and to Craneware for the chat - it definitely improved my understanding of the company and hopefully the above notes have given you an extra insight into it, too!
Roland did a fine job reviewing the full-year results earlier this week, and I have little to add to my previous comments on this stock - if you treat it as a “SaaS” stock, you can argue that it’s cheap. If you look at it through conventional metrics, it seems fully priced. But it’s always nice to find a successful founder-led business.

Cairn Homes (LON:CRN)
Share price: 94.4p (-2%)
Market cap: £636m/€742m
Shout-out to JASVFS in the comments who requested this one. The Irish housebuilder issued half-year results yesterday. I previously covered their H1 trading update in July.
Please note that the stock is dual-listed both on LSE and on Euronext Dublin.
In addition to the results for the six months to June, we also get an update on the order book, with a current snapshot. Business is booming:
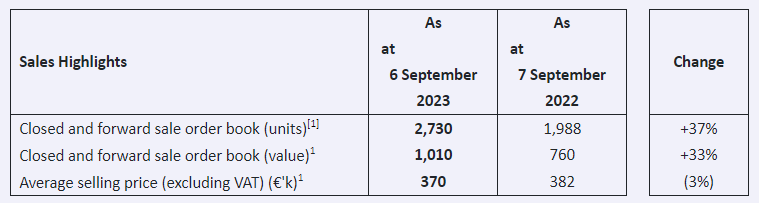
(Note: Cairn says that sales of multifamily units drove a higher ASP last year.)
And here’s an excerpt from the H1 results table.
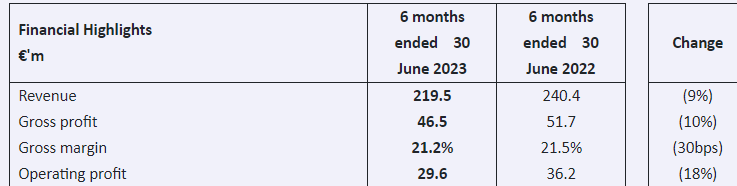
Gross margin at 21% is as expected.
The year-on-year fall in H1 may not look too encouraging, but there’s a significant H2 weighting in store. Previous guidance suggested full-year revenues of €650 million and operating profit of €105-110m.
In fact, this guidance has been upgraded: they are now expecting revenues of over €675 million (at an unchanged gross margin) and operating profit of €110-115m.
The company’s construction work-in-progress (“WIP”, an important component of its inventories) has jumped by €80m over six months, and is expected to unwind fully in H2 as deals close. So WIP will fall back to around €340 million.
Because of the temporary increase in WIP, net debt increased to almost €230 million by the end of H1, but is expected to fall back to €130 million as the WIP converts back into cash.
Share buyback - one of the key reasons I gave this share a positive review was its buyback programme.
I don’t automatically give companies with buybacks the green light. But if their stock is rated at a modest valuation and they are able to devote substantial amounts of cash to buying back their own shares, then this can do wonders for EPS growth (of course profits cannot suddenly shrink, or it won’t work!).
Cairn has announced a €35m increase to the €40m buyback programme announced in March. So it’s now a €75m programme - 10% of the current market cap.
€25m has been spent so far, with another €50m to be done.
Shares outstanding have fallen from a high of 770 million a few years ago, to just 670 million now.
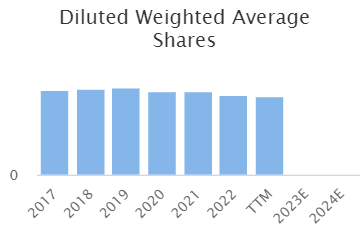
If they were able to keep buying at the current share price (€1.10), the remaining buyback programme would reduce the share count by another 45 million. So maybe there will only be about 625 - 630 million shares left?
Remember that this is the valuation at which they are buying:
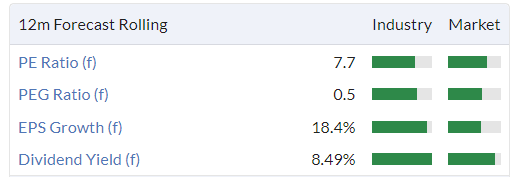
The balance sheet shows equity of €733 million (around the same as the current market cap) and moderate leverage. Total assets are over €1.13 billion, financed by gross borrowings of over €300 million. The lenders are a banking syndicate with security over all of Cairn’s assets.
Graham’s view
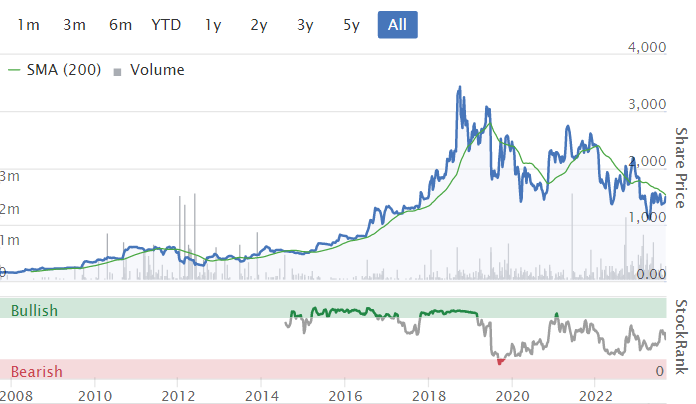
No reason to change my view on this one: I was positive in July at 99p. The share price is now 94p even though they have upgraded their guidance!
The macro picture remains very supportive, due to the housing shortage conditions. Desperate conditions in rentals do, I think, have a spillover effect into the buying market.
Cairn has achieved a lot in a short period of time, and they say that they are making “progress towards a c. 15% return on equity target as we exit 2024”.
Existing ROE already looks OK and so based on the valuation and the buyback activity, I remain positive on this one.

Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

62 comments
Perhaps Gear4music might be on another 'tear'.It had sold down again but the market seemed to like the update and hasn't been sold off on above average volume again.All any investors/traders need now is all 30% gain traders to be out and a good report in a month or 2 time wouldn't hurt either.Market share not bad and founder has shares.So unlikely to try to totally destroy the equity??
I'm long despite the current margins and playing for at least a return to the £2 mark with inflation decreasing (hopefully) over the next x years.Bring it on (fingers doubly crossed).
Paul, thanks for the shout out in your weekend podcast. Here’s hoping for more takeovers in the portfolio. As a side-note, I thought you might like to know that Belvoir is pronounced “Beaver”. The name derives from Belvoir Castle near Grantham.
I enjoyed your “rant” (as you called it) against Just Stop Oil. You might be amused to learn that my sister is a prominent figure in the “organisation” and regularly features in televised stunts - usually followed by protracted court appearances, and surprisingly lenient treatment from the judiciary, who perhaps see the big picture. I do find their level of comprehension of the issues around energy generation astoundingly naive and only informed by some very narrow, highly tendentious sources. But it’s also important to recognise that they are motivated by a desire to stop the galloping pace of climate change, and at least they are making a stand, often at considerable personal risk, for, as they see it, the benefit of every future generation. So, while despairing at their naivety, I am conscious of my own deficiencies in this regard and full of admiration for their courage and conviction.
I think the company name is pronounced Bel-vwar, contrary to the Castle.
Not by locals I’ll bet. It’s a Grantham company.
Yeap it's beaver .... and in a slightly related point to your post, I'm off on a stag do shortly and we are putting the stag in a Just Stop Oil T-Shirt, potentially chaining him to a lamp post somewhere too but will refrain from supergluing him to the road...hmmm. We are also trying out Boom Battle Bar too!
When Belvoir Castle was built it was pronounced Bel-vwar as Westway001 has corrected stated.
Belvoir is French for "Beautiful View". However centuries ago, the locals for one reason or another, struggled to pronounce the French word Belvoir ie, "Bel-vwar" when the castle was built and so they just pronounced it Beaver Castle because it was easier to say.
David.
Game set and match to Burford Capital (LON:BUR) today as the Judge rules against Argentina.
Shares temporarily suspended pending an RNS from Burford I guess on Monday.
My biggest holding despite me selling in August 2019 after the Muddy Waters Report which caused the SP to collapse.
Huge thanks to some of the Stockopedia subscribers including Donald Pond, Maddox and abtan to name but 3 who have been brilliant in keeping me informed with their deep understanding of very complex issues.
Burford Capital (LON:BUR)
Hi Portugull
That's awfully kind of you to say; I'm not sure that I've added that much over the years and I don't even remember the last time I posted about Burford. Nonetheless, many thanks for the kind words.
---
As for today's announcement, I didn't really think much has changed since the last announcement a few months ago as the total damages awarded was always going to be between two very large numbers.
It's of course nice that this has now been set at the higher end of the scale, but why there's been such a drastic upward share price movement today seems strange, as I would have expected it to be 2 months ago instead.
---
Looking at what could go wrong (sorry!), there's still the possibility of an appeal.
From the Burford RNS today I couldn't quite understand what bond Argentina would need to pay if they did appeal. Is it the fully $16b? Surely not.
On the positive side, I calculate that:
I imagine some of this would go to Burford employees (I still don't trust their employee rewards system), but there should be a nice sum leftover for the company/shareholders and therefore I shouldn't quibble too much about getting less than I would hope for of a very large number.
Another few important points (for me at least):
Cheers
A
I notice Burford Capital (LON:BUR) have been suspended on the Aim, no doubt due to this: https://www.stockopedia.com/sh...
But they are still trading on the US market, currently up 18%.
Nice to see Aim actually beating the FTSE indeces today. Long may it continue.
Probably due to Burford Capital (LON:BUR), one of it's largest stocks.
I know it is not reporting today, but I notice that Plexus Plexus Holdings (LON:POS) is down 11% now, has anyone seen any news related to this?
Shares that have a parabolic spike up like that will nearly have some quite strong reversals/pullbacks. I’d be amazed if it didn’t have a big percentage drop after the last few days.
Markets feel primed here. Don't know how everyone else is seeing it? but I'm starting to see some encouraging price moves, sellers look all sold out and although there's not exactly a stampede of buyers it's looking a bit better.
I've been trading almost everything, more shorter term than usual, for over a year but now looking to hold things a little longer as we head towards the best part of the year. There's good looking prices all over the place, just need a catalyst.
I've dusted down my wallet last 3 weeks and spent some cash, tricky part is narrowing the selection down to a reasonable number. Could probably buy 30+ shares which look good for a 50%+ uplift. Always downside risk of course so will see how it plays out, I'm already in decent profit this year so sacrificing 10% wouldn't be the end of the world.
P.s I have had a temperature this week, so may be delirious!
re: Cairn Homes (LON:CRN)
Hi JASVFS, thank you for your comments - Cairn Homes was one of the reasons I wanted to help Paul with the backlog today, as I'm really impressed with the results at Cairn and I saw your comment! So I was glad to be able to update the SCVR with my view today. I'm also puzzled that the stock is down compared to when I covered it last, with guidance being upgraded since then. G
Cairn Homes (LON:CRN)
I'm also puzzled that the stock is down compared to when I covered it last, with guidance being upgraded since then.
Also puzzled. Only thing I can think of is that because the net asset backing is lower than UK peers and they're carrying debt, if you only take a superficial look it's perhaps less impressive. I suppose there's also a question of whether Ireland has dodged the downturn or simply delayed it.
But really, it looks like excellent value.
timarr
A note about Cairn Homes (LON:CRN) in case it's useful: director Shane Doherty sold ~£400k worth of shares back in April. The reason given as "dispoal of shares to settle a tax liability arising on the vesting of shares. Company secretary Tara Grimley sold around £57k of shares for the same stated reason.
Make of that what you will.
Better stock up. This is no laughing matter!
It’s all shits and giggles until someone giggles and…
re Hostmore (LON:MORE) latest news flow.
The fact the outgoing CFO is staying 6 months to ensure a smooth transition is slightly positive. Whilst this could be the forerunner of a fund raise I'm less sure the existing holders would require such a large discount. We will see but assuming they are supportive any raise could just as easily be done around these levels. Why? well most investors are down 90% anyway..... and the upside is already substantial just to return the business to previous operating levels. The wording of the announcement suggests a somewhat orderly exit because if the outgoing CFO was a scapegoat for another downturn in fortune...normally I would expect him to be straight out of the door. We will see but since down here the money is pretty much already lost I won't be doing anything now....and added around these levels earlier this year. Clearly the market has taken the dump it view today which is perfectly understandable.
With a number of comments on Supreme (LON:SUP) here this morning the following slide from the most recent presentation may be helpful:
You can listen to the CEO discuss this from 22 mins 25 secs in here:
Supreme (LON:SUP)
"supreme now conducts third party testing?
does that mean that they have previously being selling stuff they didnt know were safe or compliant?
No it means they don't do the testing themselves now. But you knew that's what it meant, didn't you?
Supreme (LON:SUP)
Paul writes that "...today’s Times newspaper flags that Supreme has donated £350k to the Conservative Party". Well, Supreme (LON:SUP) hasn't. I can only read the first few lines of the article before it goes behind the paywall but the headline "Tories accept £350,000 donation from vape firm" is at best totally misleading. They say the donation came from Supreme 8 Ltd. This is a private company owned by the CEO of Supreme plc:
It is described as:
So it is not directly a "vape firm" although it looks as if it is a vehicle to hold Sandy Chadha's shares in the plc.
It looks like this is the press' latest bogey - the other day we had the Mail headline "Could Britain be next to ban vapes?" while the article that followed was about banning disposable vapes.
News nowadays is all about clicks. And the best way to get clicks is to try and trigger some kind of outrage/controversy in the reader.
Precisely. A lot of news is no longer balanced. It’s aimed to trigger extreme reaction even if that means taking an outlier and using it as an example/case study.
Politicians pick up on it and express outrage / faux concern etc to garner votes. And the bandwagon rolls on.
It’s all very polarising - not just on the topic of vaping but in general. It’s a tactic used to provoke the “villagers and pitchforks” response. Needs to be addressed
Hi sharw,
Thanks for pointing out this technicality about how Supreme's CEO paid the money to the Conservatives. I would suggest it amounts to exactly the same thing, but we do need to get the detail right, so I'll amend the article accordingly.
Whatever the details are, I think it's fair to say that there is a lot of concern about vaping, and the nicotine addiction it causes. This need to be at least considered by Supreme (LON:SUP) investors as a potential business risk.
Regards, Paul.
Aha!
Thank you Graham for your notes on Craneware (LON:CRW) - it has helped me get a better perspective on the company. One on my watch list.
You're very welcome, ST! G.
I notice Kitwave (LON:KITW) has lost more than 10% of its value in the last two trading sessions. Does anyone know of any reason for this? Sector rotation, broker sell note etc. (I hold)
Dmdefurey it's a nice business, but sending out the wives to sell £3m shares won't help. Year end is October, this years growth is v good. Looking forward to next year forecasts are flat, tho obviously room for upgrades.
Next news probably November? unless theyre ahead of forecasts, so traders will have moved on for now. How will food price inflation slowing effect them? A decent chunk of debt but free cashflow is good. Wonder if '24 will be a consolidation year ather than chasing growth?
Its close to the 200d moving average so if it's going to bounce it'll be soon I'd imagine. Im always suspicious of £1m+ director sales so that has taken the shine off it for me....tho they did sell millions at 150p and shares still doubled.
Just my opinion so could be well off the mark.
Thanks for your thoughts, Wolf of Small Street. I think it's the recent director (wives) selling that's taken the shine off the shares for the time being. Other than that though, Kitwave (LON:KITW) looks like a fundamentally solid business and I'm happy to continue holding (might even add to my position) at these prices.
Hi dmdefurey, for Kitwave (LON:KITW) (I hold) the reported volumes are very low recently (but I think large trades have delayed reporting) and have picked up a bit today, striking a bit of hope that the falls could be largely over. Like WoSS below I like the strong free cash flow. It doesn't look like Paul Young has sold any more shares so I take some comfort from that and will be adding at these levels and lower. Fingers crossed!
Positive price reaction at Restaurant (LON:RTN) following Ken Hanna's (group chairman) decision to not seek re-election at the next AGM. Looks like activist shareholders Oasis Management and Irenic Capital having been pushing for the move, having only been in the position as chairman since January 2022.
In other news, we have a new IPO in Tribe Technology (LON:TRYB) which enters our small cap universe, with a £22.2m market cap. The Company is a developer and manufacturer of autonomous mining equipment and targeting the $2.2billion global surface drilling market.
Round Hill Music Royalty Fund (LON:RHM) deserves a mention this morning? Bid at 67% premium (valuing them at c USD 470m ) from Alchemy Copyrights it has put a light under Hipgnosis Songs Fund (LON:SONG) +10% at 88.5p. Many ‘alternative ‘ investment funds coming under more scrutiny as discounts to NAV remain high.
Re Supreme (LON:SUP), sold out recently after the recent price uptick, still made a loss though. It's a great business and I am sure the price is only as low because of this adverse sentiment about risks of vaping. In Scotland, the local administration 23-24 programme announced this week says: "The Programme for Government outlined a commitment to take action to reduce vaping among non-smokers and young people and to tackle the environmental impact of single-use vapes, including consulting on a proposal to ban their sale and other appropriate measures." and with a similarly socialist UK government on the horizon, it is now too risky for me.
Same here Bronstein - sold at a loss earlier this week but comfortable with that as I see dark clouds on the horizon in the vaping industry so cut my losses.
Supreme (LON:SUP) I don't like public companies donating to political parties so as a holder I'm unhappy about that. So far as vaping is concerned the consensus seems to be that as long as there are people for whom the alternative would be tobacco there is a case to be made, but clearly any attempt to target children is very worrying. I have a recollection of the CEO saying in a presentation that they had lobied for a ban on disposable vapes but until such a ban is in place they would continue to supply them. I hope that recollection is correct. But whether it is or not, the last Annual Report says (p.27) 'Revenue for Vaping was £76.1 million (FY22: £43.6 million), growth of 75%..... Aside from acquisitions, the category reported organic growth of £19.7 million, arising from the launch of a range of disposable vapes' so the business is heavily reliant on these things - vaping as a whole is nearly half total turnover. I have searched the AR and other documents for 'children' and found nothing but 'under-age' returned this, in the Risks section of the AR (p.41) '.... there are no long-term health studies of the effect of vaping on users. .....The environmental impact of disposable single-use vaping products (which have seen significant growth in 2022/23) and the risks of under-age vaping have recently drawn particular attention, with speculation that these may be areas of focus for new or increased regulation. Regulation of the vaping market in the UK may change in the future which could threaten the future of the industry. Mitigating factors: As a member of the UK Vaping Association, the Group remains alive to any upcoming changes or considered changes to regulation going on in the UK and across the world. The Board expects that there would be a sufficient notice period for any material changes to legislation, which would give the Group enough time to adapt accordingly. The Group’s vaping product portfolio includes e-liquids, including its market-leading 88Vape product, making the Group well positioned to mitigate in the event of any restrictions on single-use vaping products. The UK Department of Health and Social Care’s programme, recently announced in April 2023, of new measures to help the government meet its ambition of being smokefree by 2030, appeared to reflect a continuation of the UK Government’s support for vaping; the scheme included the provision of free vape starter kits to smokers.'
Conclusion - Some years ago I decided that it's up to the State to make moral judgements about business, not me, and anyway if I were to make ethics a fundamental ground for investment decisions there would be hardly anything I could invest in because all business consume resources, create waste, use energy, and often have adverse effects on somebody - the production of cadmium for EV batteries is an example of that. I still have a very high regard for the management of this business, profits are likely to increase, but this issue is probably going to keep the P/E depressed, no chance of re-rating. I see the Stocko frecast dividend yield is 4.99% and I think that's potty, it would be over 80% above the current yield of 2.7%
Actually I think dividend yield forecast is about right for Supreme (LON:SUP) They moved to a %age of earnings which is why the 2.7% last year was a low outlier. Historically they pay about 5%
Supreme "An interesting article in today’s Times newspaper flags that Supreme has donated £350k to the Conservative Party. ...the big political donation might help deter any action to curtail vaping!"
If so, there's a word for this. It's "corruption".
The problem is that it’s just another political football that in reality isn’t going to yield very much. It’s a bandwagon to jump on.
Do you want people smoking or vaping? The latter is preferable (obv none of the above is better but that’s never going to happen)
Should disposables be phased out/banned - almost certainly. Will that impact Supreme (LON:SUP)? Yes - probably medium term positively.
Is the underage vaping really a major problem or is it a great way for politicians to make a splash with headline grabbing faux shock and concern. it’s a tiny proportion and most of those that do vape switch from smoking. But throw in a couple of well placed media publicity stories and the public will think every teenager on the street is doing it!! Great way of political point scoring.
should vaping be regulated better to prevent underage users getting easy access anyway - of course.
Would this negatively impact Supreme (LON:SUP) ? No barely at all - they’ve been calling for better regulation well before the current media attention.
Working within education, in a deprived area of the midlands, I can assure you that vaping is a massive issue within schools and amongst children. If anything the statistics being quoted in the media are way short of reality. Easily half of the students in our context aged 15-16 vape socially and the increase has been exponential over the last two years. There is also a misconception that children only use disposable vapes, which whilst true in most instances, is becoming less of the norm. Disposable vapes are a gateway to non-disposable vapes, which are now becoming more common with children. The increase that I have seen in vaping first hand with parents and students has been so significant that I can't see anything other than another above expectations beat when Supreme (LON:SUP) releases its next trading update.
I heard a great put-down to a lad vaping:
"You might think you look hard, but you smell like a strawberry muffin...."
trouble at t'mill?
I sold my Ashtead Technology Holdings (LON:AT.) on results day, results were excellent and I usually sell too early anyway but they're forecasting growth to moderate in H2. Coupled with the UKs mad windfall tax on the North Sea, Siemens turbine problems and what seems to be soaring costs in the offshore industry I think it's something worth at least keeping an eye on.
Very much worth keeping an eye on, but the demand from clients generally in the renewables subsea area is only increasing, month-by-month. I work in the industry, and there's never been anything like this before. We work globally, with particular emphasis at the moment on the UK and northern Europe. Transmission system operators (National Grid, SSE and their European equivalents) have huge amounts of subsea projects already consented / nearly consented for at least the next decade, and are planning for the 2035-2045 period now. I know a lot less about the oil & gas markets but it seems they're ticking up again.
What I don't know about Ashtead Technology Holdings (LON:AT.) is what their particular markets are, or who their direct client base is. For example, from a quick scan of the website, they say they do surveying & robotics services, which should be in high demand (regardless of this particular offshore wind auction, taxes, or any problems Siemens has with its turbines) for the next decade or two.
Two areas to research (if anyone was interested) would be:
Cheers, Happy Friday
Chris
Hi Chris,
Great to have some industry specific comments and pointers, appreciated.
H
Thanks Chris, very helpful.
Seen there's a 2GW subsea cable from Peterhead to Drax power station in Yorkshire given the go ahead a couple of weeks ago. You anything to do with this?
Nearly but no. This is one of the Eastern Greenlink projects - there will be four of them in total. See this handy little drawing with the four big green lines up the eastern side:
The Holistic Network Design shows the current interconnector plan for the UK, but this is goin to be revised and added to as more projects have been / will be given the go-ahead by Ofgem.
I would be very interested to hear your views on Orsted A/S (CPH:ORSTED) , it seems like they are facing pretty big headwinds (geddit !) in the US, but have quite a few UK offshore installations.
I would agree with your view on vaping but if I was Supreme (LON:SUP) I would be keeping my head down and not particularly want the headline (despite all publicity, good publicity etc) plus to be seen contributing to a toxic Tory govt not a good look imo
Not a small cap but Computacenter (LON:CCC) half year report looks good. Sound confident, 19th consecutive year eps growth forecast, nice cash inflow. Margins seem to be holding up OK. Gaining market share.
Probably expect eps forecasts to be nudged up now as Q3 started well.
Jefferies raised target from £27 to £33 (buy) this morning.
Not a bad looking chart either... here on the weekly;
Strong breakout from the recent downwards trend, nice stop loss position below the recent lows, and MACD crossing over.
I've taken a few this morning. If they get close to the £33 target, the Risk:Reward is decent.
I agree, don't see why it wouldn't be back up to at least previous highs at some point in next few months, which would be over 30% upside on this mornings price.
I've gone through the Computacenter (LON:CCC) RNS briefly and almost gave up....just so many tables of figures. Thankfully they've done some of the work for us in the investor presentation on their website where they state constant currency revenue growth is 22.5% (although still not clear if that includes or excludes the acquisitions).
But for all of those big top line numbers, Jefferies are only upgrading by c2% for FY24 onwards.
Technology Sourcing is 77.2% of revenue, and the US dominates, which focuses the mind a little. There was a massive inventory unwind - for instance a reduction of 62.5% (!) in the UK, although a more reasonable c. 20% overall.
Accounts are restated to reflect they are an agent on software sales, so that is a big shift in the top line and the cost of goods sold. Yes, they've restated the prior period, but also admitted going any further back before 2021 is too painful to calculate, so it clouds the picture when looking at long term revenue progression.
Yes it is all good, but I suspect much of the share price reaction is clawing back the drift of recent months as doubts are dispelled, rather than a reflection of vastly improved prospects?
Perhaps some of the language used is over-exuberant given good but modest growth. But that is my sole criticism. CCC has one of the great mid-cap growth records in the UK market - 19 years of adj EPS growth. I have compared the company with domestic rivals many times over the past few tears but found nothing to rival them. I shall continue to hold and keep as a top five investment.
.
P.S. i earnestly hope CCC will continue to encourage cheers not tears.
Good morning Paul and Graham, Cairn Homes yesterday upgraded forecasts with their (to me) excellent H1 results. It didn't make your long list for analysis so I'd be grateful if either of you have time to comment on those figures. We hold and added yesterday, as did Cairn Homes extending their buy back, there was clearly plenty of selling though and we could have bought cheaper at times yesterday. I'm puzzled at the muted reaction or did I miss something? You covered it favourably Graham on the 5th July.
Graham, regarding Cairn Homes (LON:CRN) , I did ask last time you covered them about any potential issues with regard to MICA. I have copied my previous comment to save retyping......
......Do you think there is a danger of the Gov down south imposing some sort of surcharge on builders to help fund the compensation for those affected by the Mica scandal? Similar to the UK gov's stance on the cladding issue. I believe the bill is circa 2.7 billion Euro, far from insubstantial.
It's a subject I am only vaguely aware of, but thought you may be better placed to answer.
For those unfamiliar with it, thousands of homes in Ireland have been found to contain bricks with more than the maximum permitted amount of a substance called Mica, which has the minor drawback of absorbing water, something which has fairly obvious repercussions for bricks and houses. There are now homes all over Ireland, mainly County Donegal, that have cracked brickwork that can not be repaired and that surveyors have said will need to be torn down and rebuilt.
More details, in case any one is interested...
https://en.wikipedia.org/wiki/...
Hi Jeremy, sorry I missed you last time. There is a concrete levy of 5% that came into force this month. It is called the "Defective Concrete Products Levy" and it is supposed to help fund mica redress (but I don't know if the funds raised will be ringfenced for that purpose). In any case, that is how the situation has been resolved for the time being. G
Thanks for getting back to me on that Graham. I wonder how much the levy will raise and, as you say, if it will be ring fenced and used for Mica redress or will it be swallowed up by other Government departments.
Interesting to see an improvement in retail fund sales in July.