Small Cap Value Report (Fri 9 Aug 2024) - Main: KLR, SEE Movers: BEZ, ROO, HIK

Good morning from Paul! In case you missed it, I added some extra sections to yesterday's report in the afternoon/evening, and we're off to a flying start this morning with 5 backlog sections.
I'm finishing promptly today, to meet Phil Hanson for lunch, as a thank you for his excellent spreadsheet which measured the performance of our traffic lights system here in the SCVR. It clearly shows that GREENs do best, with AMBER/GREEN and AMBER not far behind (so do look at all 3), whilst considerable under-performance is shown in particular by REDs. Whereas AMBER/REDs also under-perform, but within it, there are some big winners - so that category is a bit of a lucky dip, where every now and then a poor/risky company suddenly shoots up when it sorts itself out, eg McBride (LON:MCB) . So there are opportunities throughout, but statistically you skew the odds more in your favour with GREENs - which is what we hoped would happen, so it's great to have data from Phil which proves it works!
Latest figures as of last night -
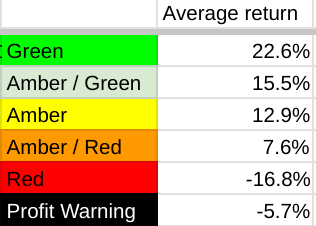
It would be interesting to see if combining our traffic lights with the StockRanks produces a better result still.
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia.
Companies Reporting
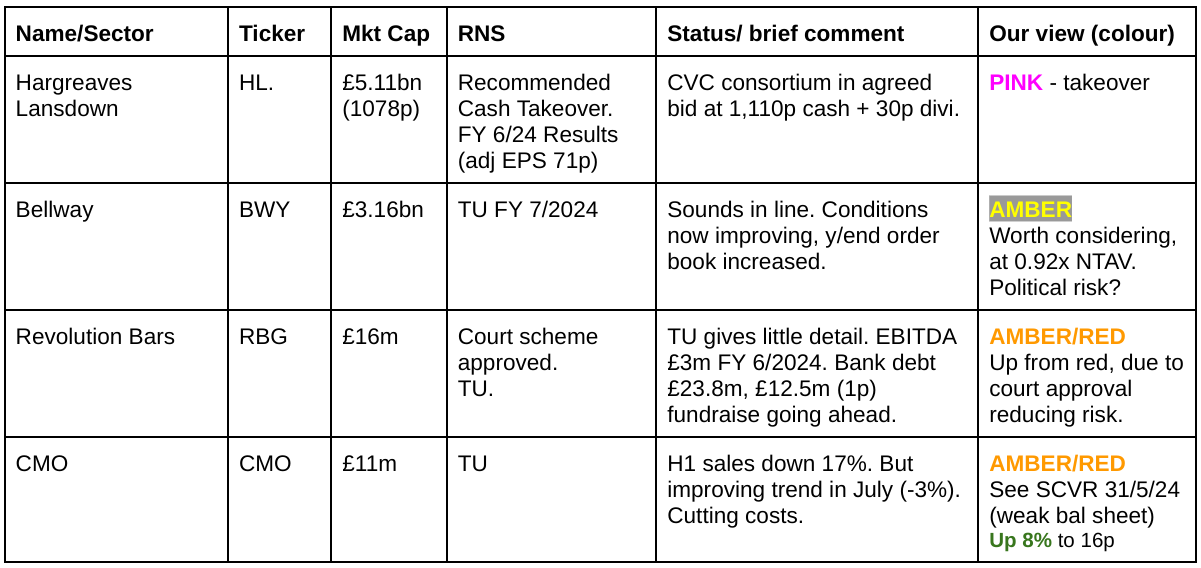
Summaries
Keller (LON:KLR) - 1,582p (£1.16bn) - Interim Results - Paul - AMBER/GREEN
Superb H1 results, and FY estimates raised. Looks a remarkable turnaround in the last year which we've flagged here before, several times. Still looks good value on a fwd PER of c.8x, despite shares having doubled. Is this improved performance sustainable though?
Seeing Machines (LON:SEE) - Up 3% to 4.82p y’day (£200m) - Q4 KPIs - Paul - AMBER/GREEN
Strong growth, driven by EU legislation requiring fitment on new cars. However, this update drops the Q3 wording of reassuring on FY 6/2024 performance, which arouses suspicion. No broker notes available. I like the story, but am a little wary given the changed wording of this Q4 TU.
Paul's Section:
Firstly some interesting movers from yesterday (with news)
Beazley (LON:BEZ) - up 11% to 706p (£4.56bn) - Results FY 6/2024 - Paul - AMBER/GREEN
A striking 11% rise in share price yesterday, in a positive reaction to record H1 profits, up 99% to $729m.
Strong NTAV/share of 483p ($4bn).
Positive comments & outlook, eg -
“When faced with the world's largest ever IT outage, Beazley's approach to underwriting cyber risk was tested and proved to be highly resilient. We see opportunities in the remainder of the year and are confident in delivering on our high single digit growth guidance. We are also pleased to confirm that we have improved our undiscounted combined ratio guidance for the full year to around 80%."
High StockRank of 89. Strikingly cheap fwd PER of 6.0x.
Looks interesting - worth a closer look.
Deliveroo (LON:ROO) - up 10% to 141p (£2.42bn) - H1 Results - Paul - AMBER
Positive market reaction rising 10%, on positive H1 results & outlook.
I reviewed this here on 18/4/2024, coming away pleasantly surprised.
It’s a turnaround year, but the H1 profits are tiny for a £2.4bn market cap company -

Net cash of £662m.
Outlook sounds positive -
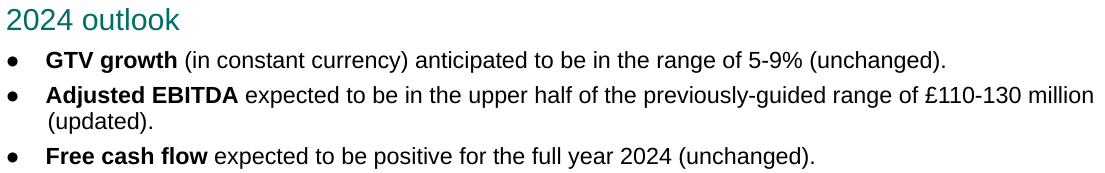
Paul’s view - very difficult to value, as it’s only really trading around breakeven. Who knows what the future holds? Strong balance sheet with surplus cash, of which £150m is ear-marked for further buybacks.
Hikma Pharmaceuticals (LON:HIK) - up 8% to 1,992p (£4.42bn) - Half-year Report - Paul - AMBER/GREEN
Underlying H1 results show flat operating profit vs H1 LY at $402m.
Good outlook -
“The outlook for 2024 remains strong and we are pleased to upgrade Group revenue and profit guidance:
Group core operating profit of $700 million to $730 million, up from $660 million to $700 million”
Has almost $1bn net financial debt.
NTAV $1.2bn.
Paul’s view - valuation metrics look quite attractive, so shares look worthy of a closer inspection.
Main Sections:
Keller (LON:KLR)
1,582p (£1.16bn) - Interim Results - Paul - AMBER/GREEN
This is an interesting one! It’s done some big moves over the last 20 years, but in an overall sideways move until Oct 2023 - where I’ve cut off the chart -
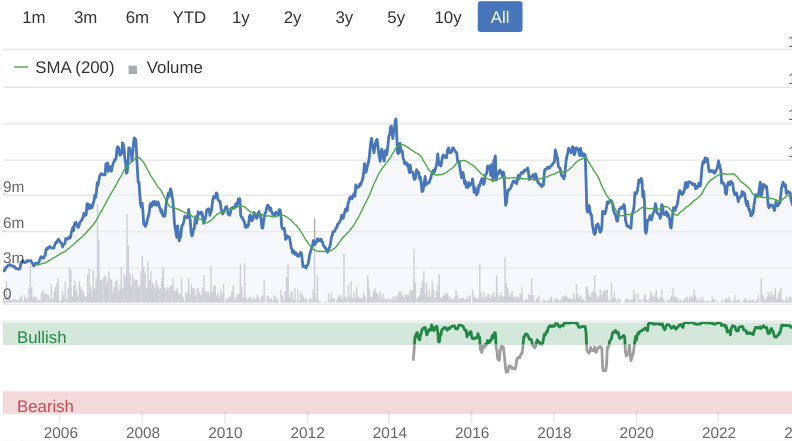
Now look what’s happened in the last year - it’s doubled!
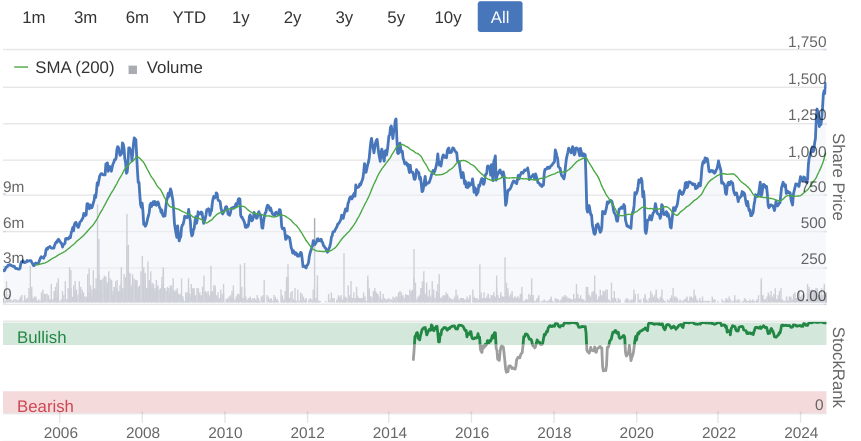
I’m pleased to say we did spot something interesting happening here, as follows -
23/10/2023 - AMBER - Keller - up 15% to 771p - TU materially ahead. Graham thinks it's low quality, but cheap. Paul is more positive on Keller.
17/01/2024 - AMBER/GREEN - up 3% to 853p - ahead exps. Very low PER, and 5% yield. Balance sheet just about OK, but fair bit of debt. Interesting!
05/03/2024 - AMBER/GREEN - up 7% to 935p - FY 12/2023 Results - good numbers - underlying dil EPS up 53% to 154p (PER 6.1x). Net bank debt down 33% to £146m. Total divis for year up 20% to 45.2p (yield 4.8%). Confident outlook. Modest pension deficit payments to end in Aug 2024. Balance sheet NTAV c.£400m, looks OK overall, although gross bank debt seems higher than I would like. Paul’s view - I like it.
15/05/2024 - AMBER/GREEN - up 16% to £13.18 (£958m) - AGM TU - excellent update says 2024 will be materially ahead of the Board’s previous expectations. Balance sheet also appears to be strong with a very low leverage multiple.
Keller Group plc ('Keller' or the 'Group'), the world's largest geotechnical specialist contractor, announces its results for the half year ended 30 June 2024.
Things are going well -
“Outstanding H1 performance; expectations for FY 2024 materially increased”
Some really impressive highlights numbers here, in particular a big improvement in operating margin, and a large reduction in debt -
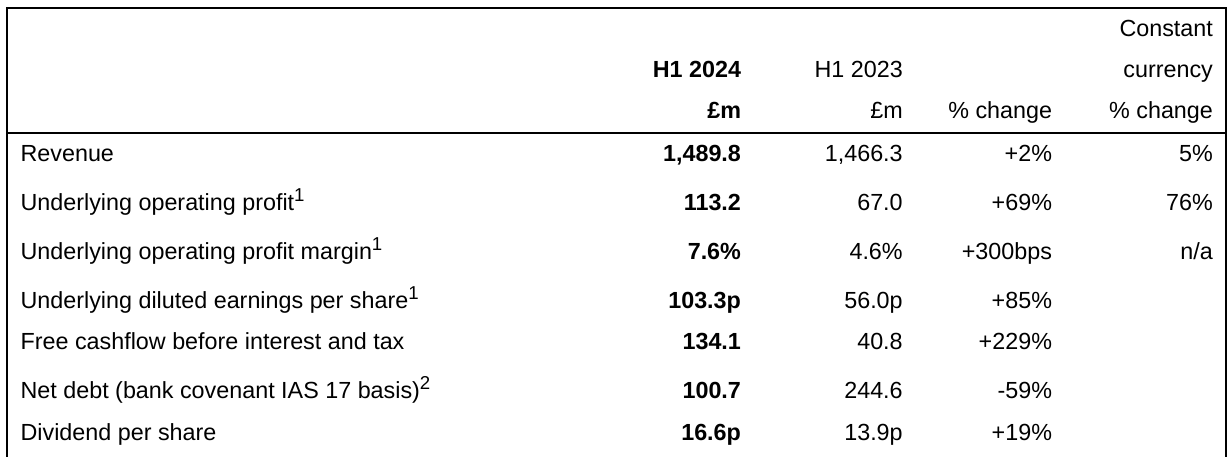
Outlook -
“Board's expectations for full year 2024 materially increased, underpinned by our record order book of £1.6bn”
“We maintained our focus on sustainable markets and attractive projects and the results reflect both the strength of the Group's presence in the buoyant North American market and our continuous groupwide emphasis on improving project execution and delivery.
The current macroeconomic environment presents opportunities, particularly in North America, albeit there are challenges in some of our other markets. The strength of the Group's performance, together with the quality of our record £1.6bn order book, provides us with increased confidence in the outlook for the rest of this year. As a consequence, the Board now anticipates that the Group's performance for the full year will be materially ahead of current market expectations1. This performance will have a modest weighting towards the first half given beneficial tailwinds in the period."
1 Analyst consensus underlying operating profit for FY 2024: £178m; range: £176m - £179m.”
Broker update - there’s a really helpful detailed note from Panmure Liberum, which significantly raises estimates, as follows -
FY 12/2024 adj fully diluted EPS, old: 156p, new: 186p
FY 12/2025 adj fully diluted EPS, old: 161p, new: 191p.
Those are big increases, and PL hints there could be more upside on these raised numbers.
If it’s heading towards say 200p EPS, then the current PER is only about 8x 2025 estimates.
As you can see, nearly all the H1 profit came from the high margin N.American business -
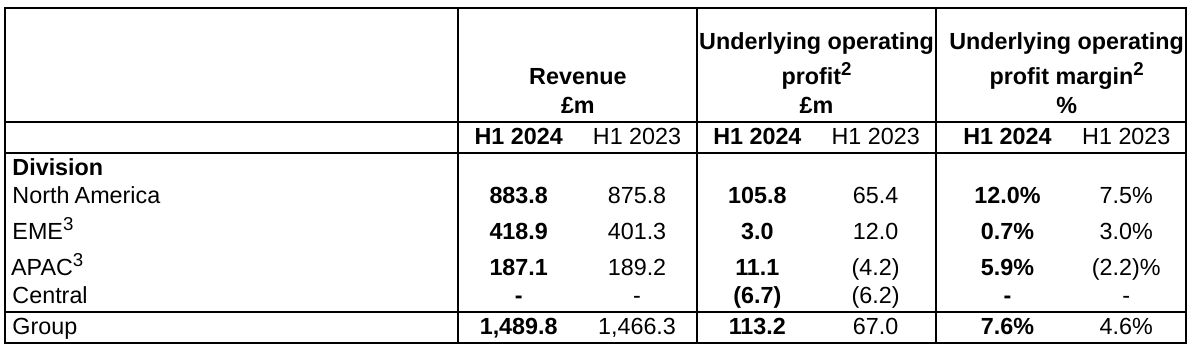
Balance sheet - looks fairly strong, although I note receivables are extremely high at £797m - something to query with management if they do a webinar.
Cashflow statement - all looks good to me.
Paul’s opinion - we’ve been moderately positive on Keller since autumn 2023.
These H1 numbers and outlook show a remarkable improvement in performance, driven by its higher margin N.American business. How sustainable is this, and how has a transformational improvement in performance occurred?
Based on these numbers, and a forward PER of only 8x, I suspect this share’s bull run could continue.
It’s already risen a lot, so I’m happy sticking with a positive view at AMBER/GREEN.
Seeing Machines (LON:SEE)
Up 3% to 4.82p y’day (£200m) - Q4 KPIs - Paul - AMBER/GREEN
Seeing Machines Limited (AIM: SEE, "Seeing Machines" or the "Company"), the advanced computer vision technology company that designs AI-powered operator monitoring systems to improve transport safety, publishes its quarterly Key Performance Indicators ("KPIs") for the quarter ended 30 June 2024.
I better understand the investment story here, after having a briefing with management earlier this year. This eye-tracking technology has been around for years, with SEE being a leading provider of just a handful of competitors globally. Uptake is now rapidly growing because of EU legislation requiring this being fitted to new cars. SEE doesn’t make the products itself now, it’s just an IP business, charging a relatively modest per unit royalty. Rapid growth means it should move into profit & cash generation quite soon, after years of losses. Mgt seem confident they can reach profits without needing any more equity raises.
Recent quarters show a strongly improving growth trend -
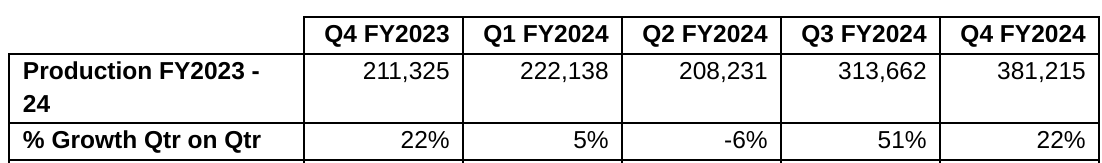
It recently received a $16.5m licence fee from Caterpillar.
The above seems good, but it doesn’t say how trading is going versus expectations.
Outlook -
“Paul McGlone, CEO of Seeing Machines, said: "We have maintained growth of over 100% in the number of cars on road featuring our technology from 12 months ago, despite the quarter-on-quarter volatility experienced during the year. Regulations are now in place so we are confident that these figures will continue to grow for existing Automotive programs and as new programs start production.
"Similarly in Aftermarket, the new regulation in Europe will require more commercial vehicle OEMs to seek After Manufacture fitment for our Guardian technology, underpinned by successful homologation (regulatory approval) with our Northern Ireland customer, Wrightbus, as announced on 30 July 2024. With Guardian Generation 2 stock sold we are now focused on Guardian Generation 3, initially with European commercial vehicle OEMs, then all customers across existing markets in Europe, The Americas and Asia Pacific."
Paul’s opinion - I don’t have enough information as to whether these KPIs are as expected, or above or below, since SEE doesn’t directly tell us, and I don’t have any broker notes available. This looks a bit suspicious, as the previous Q3 update did specifically say that SEE was on track to meet FY 6/2024 expectations. That wording has been dropped from this latest Q4 update, which is bound to make investors suspicious that performance might have fallen short of expectations for FY 6/2024.
I’ve been AMBER/GREEN here twice previously in 2024, so will stick at that level, although I’m a little nervous, so will probably hold back on buying any shares personally until we have more clarity on how 2024 has panned out. There does seem a good growth opportunity here, driven by legislation requiring the use of this safety technology. Shares are currently tricky to value, as it is still loss-making, so the valuation depends entirely on future growth and profitability, which is tricky to estimate at this stage.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

71 comments
Hill & Smith (LON:HILS) interim 2024 analyst presentation from yesterday video & podcast.
Thanks Tamzin - the numbers look ok, but SP down 5% today. I must be missing something!
HILS Analyst estimates still look good.
Q Score is 99. This is definitely a high-quality share.
Here's why it sometimes pays to listen to fund managers ...
One of their divisions is "Galanizing Services". Now, this sounds like the most deathly dull business there is in a cyclical industry. Sounds terrible, right? Well, it turns out that transporting steel is pretty expensive, so you want to do as little of this as possible. This gives the division something of a moat. There's usually not enough business for two players. So if you can out-compete someone, you can usually earn decent returns. This is what HILS is doing.
Over 10 years its share price has gone from 564p to 2040p. Not bad for a company that sends everyone to sleep just listening to them.
It seems to me like a company that flies under everyone's radar and they miss quite a good opportunity. (I don't own any shares, however).
The company was covered in one of Paul Hills videos, where he was talking to two lady fund managers in the small-cap sector. Alas I can't remember the video now, so if someone's got a link, I'd be grateful.
Possibly Georgina Brittain from JP Morgan small cap growth and income - JUGI - they hold HILS
Thanks for all the interesting replies - lots of food for thought! It's reassuring to know I'm on the right track, though I admit it’ll be tough to stick to this new approach without missing the thrill of trading. Maybe I might just allow myself to keep 10% of my funds for some trading excitement. Have a great weekend, everyone!
For any holders of Zotefoams (LON:ZTF) - I contacted management to question the partnership with Refresco, specifically whether they had rights to any of the IP of Rezorce as part of the partnership. I also asked about market trials and if they will announce the start of the trial via RNS. The response from the CFO, Gary McGrath, is below:
Hi Ben, thanks for your message. Apologies for the delayed response. The week we announce our results includes a roadshow where Ronan and I are in the City morning to evening and are fully occupied the whole week. It means we fall behind on emails and have to find time in the evening or the following week to play catch up. You were not singled out as someone not to respond to, rest assured!
Refresco are the largest beverage packager in the world. They are owned by KKR and have a number of sustainability targets like many. They service supermarkets like Tesco who are demanding of them developments in sustainability. This opportunity provides them therefore with obvious benefits around sustainability as well as increased revenue opportunity. There are no financial agreements in place and they have no rights to any of the IP. They would become a customer of the product, process it into carton form and fill it with juice, and sell.
We will absolutely inform shareholders of milestones in this, the most likely next one being the market trial.
I hope this answers your questions. Take care. Gary
Always good to receive a personal response from the CFO and I am happy to hear that despite partnerships with Refresco, Shincell and Censco they still retain 100% of the IP.
Ben,
I appreciate you taking the time to share, thanks.
Thanks for sharing this ... I have not yet heard back from them. They announce that Refresco are a "joint development partner" when in fact they are a future customer. Really not quite the same thing is it? Language matters and this is pretty sloppy, leading to obvious confusion.
Now that we understand the relationship with Refresco is as potential customer, we can secure a better understanding of why they have appointed Mazzone and Co. to find a strategic partner to roll ReZorce out.
Not sure I agree with that comment on sloppy wording James re Zotefoams (LON:ZTF) . I suspect both Refresco and Zotefoams regard each other as partners in bringing this innovation to market. The trial is presumably exclusively through Refresco as it is relatively small volume 150,000 units. On packs of 12 or 24 that's probably half a day's production.
I would expect someone like Refresco to get 6 months exclusivity on first products to market if the trials go as expected. Or category exclusivity or geographic or similar. Maybe not a financial JV but definitely a development partner IMO.
For Zotefoams (LON:ZTF) I think it is a great strategic move to have a major producer as a partner. Especially when you've got Tetrapak to compete with.
I'm more concerned with the length of time this is taking. I thought we'd have had the trial run in Q2. Appreciate the summer not the ideal time for trials when production lines need to be running or available to run at max capacity if the sunshines. Fingers crossed this turns out well.....
I would have thought that they will need to perform production trials and maybe product stability studies for what they put into the cartons hence the co-development. This takes time if they need to get data on leachables and extra tables.
Extractables
Hi Archer
I'd have expected those tests to have been conducted on pilot scale plant in either their or Refresco's R&D labs. This test should be to confirm the materials run through the line efficiently and don't present any issues through the supply chain. Perhaps I'm imaging they are further along the process.... You only have to look at the history of Britvic to see where these things can go wrong. Two examples that made the news - Still Tango had to be withdrawn after the bottles started to suffer fermentation and expand, Robinsons Fruit Shoot changed the Cap and ended up off sale for over 6 months. The profit warning that followed almost halved the share price. (Another missed opportunity!)
But that is weighted towards the larger mcaps, if you exclude them, what are the results like?
The UK markets have not faired so well.
Planning to Do More of Nothing
I've been reflecting on my investing habits and gradually realizing that my urge to constantly tweak my portfolio might not be the best strategy. Instead of feeling compelled to buy or sell stocks every day, I'm considering a shift towards a more patient and thoughtful approach. My aim is to focus on buying from my watchlist only when the timing is right and selling at a decent profit without getting caught up in greed. This would mean resisting the temptation to hold out for higher gains and instead, taking a more measured approach.
I believe that by curbing the impulse to be constantly active in the market, I can achieve better long-term results and free up time for other pursuits beyond share dealing. That said, I'm not sure how easy it will be to stick to this plan, as the thrill of trading can be pretty addictive!
I share your sentiments. From a couple of years ago I decided that a more buy-and-hold approach would be better. It seems to have been paying dividends. I'm tempted to say buy and never sell, but that might be overly strict.
One thing that can help is to make the determination not to sell. It doesn't mean you will succeed, but it does help. Also, resolve to not look at the markets for a week. If you manage that, then try a month.
Some people can't go on holiday without checking on the markets, although I've never had that problem.
Mark,
I try now to do the same. This dates to my Covid meltdown in March 19th 2020 when I timed the bottom to perfection. The trouble is I was selling not buying. I ended the year up 0.6% but if I had done nothing the portfolio woudl have been up 36%.
It was a painful lesson, the scars of which I have still not fully recovered from.
Regards
Michael
Sound advice Turbo, even tho it is easier said than done, I'm trying to adopt the same mindset
Hi turbo,
I too am trying to adopt a more patient and thoughtful approach which, on the whole, seems to be working. However, there is a difficult balance between keeping a regular watch on the markets for stocks to add to your watchlist whilst at the same time resisting the opportunity to dive in & out of the market. Not easy, I wish you well.
I can empathise with your message. However, knowing when to sell does matter. Really good article on timing the market by “Don’t let the tail wag the dog“. Worth reading if you haven’t already.
Good idea turbo but one i find impossible to adopt. I'm currently wondering what the best strategy would have been in the event that Russia launches a nuclear attack on Kiev. Gold perhaps?
Certainly not crypto, I think, because of the power requirements and the likely problem liquidating the investment when required.
I hold lots of stocks long-term (eg still have Gear4music (HOLDINGS) (LON:G4M) but tend to trade at the margin - adding when something looks to be good value, trimming if it shoots up.
Share dealing costs add up and quickly eat into profits substantially too, which stops me from trying to trade US stocks, although i probably could get better forex rates if i abandoned hargreaves!
I realised this farily re3ently similarly and just shut off the screens on days like the recent US high Vix sell off after buying a couple things i liked, as i reckoned it would rebound.I like to try keep up with events but now trying to make more of a routine that involves reading limited things, looking at indices and prices at certain times and then clocking off.Try to systemise my daily market interest like scvr tries to systemise stockpicking, as there's so much market information around nowadays (too much for human brains to handle sometimes i think).It is hard to keep an active interest and not get 'too spooked' or too enthusiastic around normal volatility and question why too much if something falls or rises intraday.The weather is finally decent too!Not sure how long that will last......
I agree Hargreaves Lansdown (LON:HL.) are too expensive for US shares. I use IG group (LON:IGG) now, only costs are 0.5% forex, spreads are very tight, usually less than 0.2%, no stamp duty of course. So often cheaper than dealing UK shares.
I completely concur with your approach. I was looking back at some old investment platform statements yesterday from 2018-2022 as I was doing some shredding.
I was trading in and out of shares two or three times a week, with very little understanding of what I was buying, often following the crowd.
Since 2022, when I retired, I have done very, very little. Simply maintaining a core portfolio of ETFs and then buying into quality UK small and mid caps and holding for between 12 and 18 months, using moving averages as my catalyst to buy or sell. I dread to think how much money - and emotion - I wasted over those four years.
I think your approach misses one point .
If you buy a part of a business you are a shareholder .
Before you buy part of a comoany you need to understand the business, its valuarion, and know why you ate buying it .
Too many people invest to to buy and sell shatre.
if you think of it as buying and sellimg businesses you have taken the time to understand by definition you will buy less and hold better for longer .
Took me a good while to get this mindset and the jumping in and out mehtality and trading of shares is very different to investing in businesses mentality .
The longer you hold you then develop great in deoth knowledge of your companies and i find you know the correct times to buy and sell based on company performance not mr markets opinion.
Few of mine ate down a bit this past week dedpite being on olan and performimg well so ive been buyimg these companies, i probably know more about these than any analysts or mr market himsrelf .
I just want to thank all the cool heads this week who said to not panic sell. Hearing experience like this really helps in times of turmoil. I bought some shares on the pull back that I had my eye on and they're up already. I think a few years ago I might have panic sold and lost out on some gains.
Tan Delta Systems (LON:TAND) I hold a small position
This is a bit of a tidler for SCVR and Stocko ranks it as a sucker stock. Nevertheless it's an interesting company based in Sheffield, because of its IP and the markets it addresses.
Mr C mentioned the RNS this morning about an agreement with a global engine manufacturer to develop a new product. I'm inclined to believe it's a marine engine maker as this market was mentioned in the recent trading update:
- a leading, large ship engine manufacturer with approximately 15,000 engines in the field, each with at least 10 cylinders, and each cylinder requiring a sensor;
The same trading update also said it had opportunities with:
- a significant global oil major who is promoting our sensors to their customers and has provided an initial sales pipeline forecast of £8.0m across 15 projects, over the next 2 years; and
· a global logistics company with a fleet of critical conveyor gearboxes with a potential initial requirement valued at nearly £3.0m.
The key word here is "Global" imo. Why are "Global" enterprises even entertaining such a tiny company? The answer is because the products they can provide are seriously impressive. Essentially, the sensors TAND produces monitor liquids in motors and gearboxes. This enables the operator of those assets to know when it is time to replace the oil in a gearbox or engine for example, rather than using a rule of thumb. This saves waste by eliminating unnecessary oil changes or breakdowns caused by failure to replace in time.
In case studies published by the company the result of using their sensors has reduced costs by up to and 80% in a wide variety of industries and achieved an impressive payback timescale. See https://www.tandeltasystems.co....
The company only listed a year ago so there isn't much of a track record but I think it has a lot of promise and is well worth watching to see if the opportunities with some very big names develop into material contracts.
as all my stocks are held with Hargreaves Lansdown (LON:HL.) is there anything that should concern me with the company being taken over? Interesting to see no mention of the deal in their daily news roundup on the app…
Hargreaves Lansdown (LON:HL.) - mildly disappointing to see this go private, despite holding and making a profit.
Db47 - I had the same concerns when Charles Stanley were taken out by Raymond James. For what its worth, I just follow the accounts of Charles Stanley on Companies House to make sure that things are not going pear shaped, when they issue annual financial statements. I'm sure that you have nothing much to worry about for a long time, if ever, with Hargreaves Lansdown.
thanks topvest, agreed think it’s a shame really that Hargreaves and co have sold out, and as I understand any holders of Hargreaves Lansdown (LON:HL.) within an ISA / SIPP won’t be privy to the private equity shares, I suppose time will tell whether that’s a bad thing or not… what are you going to do ? as I hold Hargreaves Lansdown (LON:HL.) too in the trading account…
there’s an article in Investors Chronicle today here’s a quote :
‘The interesting part will be how private equity decides to shape the business. Though now rendered irrelevant as far investors are concerned, exponentially rising costs has been a frequent source of discontent between the board and its largest shareholders, as the company tried to modernise its offering in the face of stiff competition from the likes of AJ Bell (AJB) and the Abrdn (ABDN)-owned Interactive Investor. The consortium said "a substantial transformation" was required at Hargreaves Lansdown to help promote "savings and investing in society".
"Further investment by [the consortium] in the technology platform is expected to improve operational resilience, enhance capacity in systems, and deliver significant scalability and operating leverage in its cost base going forward," the buyer added.’
So this too should allay any fears of a diminishing service from Hargreaves Lansdown (LON:HL.) and I can’t see they can raise already high charges in such a competitive market (here’s hoping !)
All the best, congrats on realising a profit !
Will the tech platform investment improve HL’s back office functions? I’m not sure Hargreaves Lansdown (LON:HL.) ’s quality customer service reputation is justified - I recently exercised my SIPP 25% tax free cash drawdown at both HL & II., due to concern about a change of rules in the October budget. The latter took 48 hours, HL tell me they are still working on early July applications…….OK they have more customers, but they charge a lot more.
Trader Jack, I agree with your doubts about HL’s service reputation. They used to be prompt in answering the phone and dealing with issues with a better understanding of the customer. They have now caught the same disease as most other financial platforms led by legal and compliance cultures. Long wait times on telephone calls, identification requirements and restrictions on dealing have caught on. I was unable to add to Doric Nimrod Two, a position I already held because they were and still are short an information document from the issuer whereas I could buy the stock in my AJ Bell and II accounts. They were very slow in handling a transfer of my ISA from another platform. Lately, I have noticed that they pay dividends later than other platforms. I hope the PE owners can address these issues but I fear a rise in costs and more streamlining. Getting ready to move.
Wow, Paul, the Green ones have done really well.
I guess for those wanting to buy quality shares to hold for a long time, it's worth following Buffett's advice: "If you aren't willing to hold a share for 10 years, don't even think about holding it for 10 minutes."
I think in some respects it's both easier and harder than you think.
I saw a video on YT from 9 years ago, with Harry Nimmo, who has (had) a formidable record running Abrdn UK Smaller Companies Growth Trust (LON:AUSC). He's retired now, I think. Here were his share tips: Ted Baker, Workspace, and EMIS.
Ted Baker. Those shares were listed in 1997 at £1. The fund actually bought in at that time. They were worth £24.50 at the time of the broadcast. Wow. But the shares were suspended in 2022, and taken over at 110p. Very much a case of up hill and down dale.
Worskpace. Has gone nowhere for 10 years. Was worth 603p, recently 613p.
EMIS. Price as about 720p 10 yrs ago. They were taken over in 2023 at 1925p.
So that's one reasonable hit out of 3. Very hard game.
But maybe not as hard as you think. Starting around 2010 I held a couple of shares on behalf of my mum. The shares were AstraZeneca (LON:AZN) and Unilever (LON:ULVR) . How did they do? AZN is up 277%, compared with the ASX of +66%. ULVR is up 125% compared with ASX of +46%. Which puts my mum in the genius stock-picker category.
So perhaps the secret, if there's any, is to hold good quality companies at reasonable prices, an hold. There's nothing flashy about AZN and ULVR. No-one is going to think that ULVR is going to shoot the lights out.
Sane, sensible, good quality. Decent returns on capital, limited debt, reasonable divvies, reasonable size, with at least some room to grow. Nothing flashy here.
For those interested, I discovered WisdomTree UK Quality Dividend Growth ETF recently. Their top 10 holdings are III 70, ANTO 68, RELX 97, AZN 87, EXPN 83, ULVR 70, FERG 92, GSK 87, RIO 86, DGE 81. The numbers are the quality scores I noted down at the time. Obviously I'm not recommending anything, just throwing it out there for your consideration.
Thanks, Mark. I used your comment to start a thread on WisdomTree UK Quality Div Growth UCITS ETF GBP (LON:UGRW) for the archive and to attract other comments.
Keller seems to be getting some significant work from Saudi Arabia's NEOM project which is a multi-year trillion dollar ground breaking project to build a completely new city of the future in the western desert of Saudi Arabia . This is an important flagship (in the desert ?) project initiated by Mohammed bin Sultan - the de facto ruler of Saudi Arabai. See the Wikipeida entry for more detail. Track record and the ability to handle large scale projects are more important than price in this situation.
Profits from Middle Eastern work are often substantial but problems can arise sometimes due to local culture and anticipation being different to European or American cultures.
I have held Keller for several years (since 2018) in numerous family holdings since it seemed a leader in its area and seen it (hopefully) by now sort itself out after several years of poor performance after earlier expansion in several overseas territories where (my impression and opinion) control was not what it should be.
Interestingly Keller gets a long rating on 9 Stockopedia screens which is very unusual. BTW This and the progress it has made in sorting itself out, improving margins and ROI etc is far more important in my view than buying Keller for its possible profits in the NEOM project which should be taken cautiously as just icing on the cake.
I too bought Keller (LON:KLR) in July 2018 (think it was one of Ed’s NAPs selections) at around £10 only to run out of patience in January 2023 selling for a c. 25% loss. Having held for 4.1/2 years with no sign of improvement seemed a reasonable decision to move on. However, perhaps the buy and hold strategy is the way to go as the share price has doubled since I sold. Personally I struggle to identify which poor performing stocks to hang onto and which to divest. Consequently there are perhaps a few too many ‘dogs’ left in my portfolio!!
Interesting, The NEOM project has been scaled back significantly so sustainability of Kelley’s revenues/profits if derived from that’s source is questionable.
thanks Paul for going back to Keller, have a great weekend
Good luck to patient holders of Hikma Pharmaceuticals (LON:HIK). I bought earlier in the year but tired of it range trading between 1800p and 2000p so sold in May.
Looking at the graph for Mortgage Advice Bureau (Holdings) (LON:MAB1) I am hoping that my patience here will be rewarded in Q4, which will start to see the unwind of 2 year fixes taken out after the mini budget as well as borrowers moving off their 5 year fixes on pre-covid rates.
Profits for the year are forecast to rise 50% which should be supported by further interest rate cuts and buyers returning to the market; the 3.3% yield helps while I wait.
This week has certainly given us "interesting times" and like Paul I took the opportunity to buy a couple of stocks off my watch list (Filtronic (LON:FTC) together with building sector plays Brickability (LON:BRCK) and Kinovo (LON:KINO)) plus top up some holdings. Yesterday's acquisitions by Genuit (LON:GEN) look a good fit so will look to add.
Fully invested now, so time to relax and enjoy the warm weather.
Hikma Pharmaceuticals (LON:HIK) has been a fairly volatile share for its average market cap but has always recovered.I remember wishing i had bought it when it was around 900p a few years ago, but i was still involved in buying pre revenue mining shares... Oh for a time machine!I guess it's a quality company of enough size to generally tilt longer term recovery odds in its favour.
Regarding Beazley (LON:BEZ) , I used to be a holder and still rate the company. It did, however, have a dip in fortunes when the insurance cycle dipped. I would compare the company with Conduit Holdings (LON:CRE) . The latter may carry more reinsurance risk, but it is cheaper, growing faster, and carries a higher yield, I think. Downsides are that it is a young business and sits in a higher risk part of the market. I hold Conduit Holdings (LON:CRE), but not Beazley (LON:BEZ) at the moment.
Other views welcome.......
Good shout; and thanks for flagging. In the Lloyds / (re)insurance P&C space, I hold Beazley (LON:BEZ) and Lancashire Holdings (LON:LRE) currently - not really investigated Conduit Holdings before.
I think you've accurately flagged the risks associated with it; I'd add another in that it seems to have an exceptionally conservative investment portfolio - a good thing, ordinarily, but in this space it implies that it's not willing to go down the risk spectrum in order to search for more yield - possibly because of the solvency implications if it did so. I might investigate its interim results in a bit more detail, and look at its year end FCR, to try and understand this a bit better.
The other point which you've flagged is when the insurance cycle will turn - we're definitely seeing signs of it being towards the top of the market in certain lines with both BEZ and Conduit mentioning slight rate softening in certain lines. The theory goes that the better the quality of underwriting, the more easily companies can ride out these dips... but that perhaps explains the exceptionally low P/E ratio.
Partly due to the insurance cycle, I'm contemplating perhaps taking some money off the table (especially on Beazley, where I've held since the 150p's).... but equally, I'm also contemplating adding more just because "they look cheap"...
Thanks for the reply. I'm mulling Beazley (LON:BEZ) , it does look good value...perhaps more liquid than Conduit Holdings (LON:CRE) . The Conduit Holdings (LON:CRE) Finance Director is ex Lancashire Holdings (LON:LRE) , I believe. Conduit looks better value than Lancashire, I think.
Kirkie - I would agree that the insurance cycle is at or near the top-end of the cycle. I always hold a few of these insurers. For what its worth Beazley (LON:BEZ) are my favourite, then Conduit Holdings (LON:CRE) and then Lancashire Holdings (LON:LRE) . Hiscox (LON:HSX) is also very good but didn't get in at the right time. I would concur that its not necessarily a good point in the cycle to buy these, unless buying relatively short-term. They may go up further short-term. I hold longer term, but have top-sliced Beazley (LON:BEZ). Best point to buy is when the cycle is recovering....about when Conduit Holdings (LON:CRE) listed...they are a very clever bunch and when they get sold it will be a clear sign that things are definitely toppy!
I have been a holder of Beazley (LON:BEZ) for a while now and previously held it a decade ago so I have followed it for a while. The thing about these insurers is that they, rather ghoulishly, prosper from disaster provided they know how to manage the risk. The rates typically turn up sharply after a disaster and slide as the memory of disasters start to fade. So I am afraid that I see disasters as generally good for business. Beazley has been a pioneer in cyber security cover and the repeated problems in this area should keep rates high, with “climate change” fire, floods and hurricanes (even if they have no connection to climate change) maintaining a high rate of concern.
As an example of declining risk, over the years fatal air crashes have declined markedly (thank goodness) and as a result the premium rates have much lower margins.
So this can be a lumpy business but Beazley has a track record that shows, over the long term, that it can manage the risks it takes on and take advantage of richer premium rates when they emerge.
,
I sold Conduit Holdings (LON:CRE) because I was worried they were exposed to hurricane risks especially as they are based in Bermuda. Was I being too hasty?
A lot of the reinsurers seem to be based in Bermuda - both Lancashire Holdings (LON:LRE) and Hiscox (LON:HSX) are based there in addition to Conduit Holdings (LON:CRE) . I don't think the company location is related to where they insure risks - I think it's more of a corporate tax thing, or maybe now a critical mass thing (easier to find staff where other insurers are based?).
Most of the staff won't be in Bermuda, that is just a tax haven. Hiscox (LON:HSX) is a Lloyds underwriter, so based mainly in London. Most staff will be based in London or UK, believe Lancashire Holdings (LON:LRE) also. I would not class Hiscox (LON:HSX) as a reinsurer, they underwrite a lot of direct business. Not sure about Conduit Holdings (LON:CRE) not familiar with them.
Risks will be worldwide although they will have more exposure in some areas. Most of risks are international in Lloyds, not UK based.
For those not familiar with Conduit Holdings (LON:CRE) i recommend watching the Investor Meet Company archive on this company, starting with Neil Eckerts introduction (autumn 2023 i think) to the company and its history and then follow up with the various results presentations since. It also helps if you know a little about industry and the way it works and phraseology used.
I hold Beazley (LON:BEZ) since 2013 and Conduit Holdings (LON:CRE) since 2023 after watching the IMC webinar and scrutinising HY23 results.
and yes the hard rate market is now moderating which is why picking your risk is so important
It's tax that's the only reason. And probably staff are not based there either
Conduit replied to exactly this question in their results presentation. They said that there is a surprisingly low correlation between number of hurricanes and claims. It’s where the hurricane hits that matters…..
Paul you gave Getech an Amber in March but questioned why it's listed, it's almost embarrassing to ask on Stockopedia but does adding 10 or 20,000 shares to an already large almost wipe-out holding make any sense? The placing and retail offer is at 2p. We are steadily going Green but still have a few dogs at the bottom of our portfolio to feed or shoot. I like what this company does but it's always struggled to gain traction.
Going Green :-)
Edit: I think the clincher for myself will be those that pay a dividend so that should reduce the numbers in the Green List. Happy hunting over this weekend peeps. p.s. It was good to read that Hargreaves Lansdown (LON:HL.) is being bought by CVC Income for £11.10 plus 30 pence per share held. I hold.
Hargreaves Lansdown (LON:HL.) Agrees To Takeover By CVC-Led Consortium at a 5.8% premium. A little disappointing for shareholders. They have been in discussions for a while and have finally agreed. (I hold)
Hi Paul.
I don’t have any data but my checklist is now very simple. SR over 80, super stock and green or amber green on your list.
That produces plenty of quality companies from which I can add my own personal bias. Early days but results look good so far.
I don’t have any data but my checklist is now very simple. SR over 80, super stock and green or amber green on your list.
Can you post a list of companies? tia
Hi eParo. I’m on my phone and not sure if I can post a link to a screen but here is a screen shot of my selection criteria. I’ve used SR of 90 to get 43 excellent companies. I have to search Paul’s list manually.
I personally look for companies that have an excellent trend but have pulled back recently due to overselling/profit taking but each to their own.
I own several companies in the list.
Rev8
Thank you for sharing this. Very interesting.
I have created with one tweek with StockRank >= 90.
This throws up about 67 UK companies but screen for the US and you 398!
Regards
Michael
Most Superstocks are over 80 SR. You would have missed out on some big winners, if you limit your selection to just SuperStocks, such as CMC Markets (LON:CMCX).
Hi Rusty. There are always fish that get away but in my opinion it is more important to avoid the big losses. As shown by Ed’s analysis limiting to high SR and super stocks increases the chance of picking winners and having an overall winning portfolio. Now adding Paul’s analysis seems to increase odds even further. It’s the principal reason that I use Stockopedia. I can’t do this analysis myself (who can?).
As Munger said "Fish where the fish are"
My morning smallcap tweet: Loan alone
Kazera Global (LON:KZG) Getech (LON:GTC) Revolution Bars (LON:RBG) Kinovo (LON:KINO) Oncimmune Holdings (LON:ONC) CMO (LON:CMO) Tan Delta Systems (LON:TAND)
◄Kazera Global (KZG)► gets £500k total shareholder loans to fund the cash element of the consideration payable to Tectonic Gold. [SP=0.41 Cap=4m]
◄GETECH (GTC)► £1.5m placing and £0.2m retail offer at 2p, an 11% premium, "to deliver further progress on sustainable growth" etc. [SP=1.89 Cap=1m]
◄Revolution Bars (RBG)► Restructuring Plan approved by court. Guides FY-June EBITDA c.£3m. Expects to publish FY results in Oct.
Don't forget your shareholder specials when dining: lame duck with lemon, baked-in disappointment and take-away mugs. [SP=1.17 Cap=5m]
◄Kinovo (KINO)► wins contracts worth £5.3m over 5 years from the National Housing Maintenance Forum framework. [SP=70.97 Cap=45m]
◄Oncimmune (ONC)► wins $1.5m ImmunoINSIGHTS contract. [SP=9.55 Cap=7m]
◄CMO (CMO)► improving sales trend and positive momentum through Q2 and July. Q2 LFL down 12.8% vs 21.3% for Q1. [SP=14.8 Cap=11m]
◄Tan Delta Systems (TAND)► wins £200k non-exclusive new product development agreement with a global engine OEM. To be booked this FY. [SP=15.5 Cap=11m]
Enjoy your lunch and thank Phil from the rest of us. Black/Green (fundamentals) is the one I always look out for..
Ever thought why Warren Buffett & many other smart fund managers say 'invest for the long term'?
Well, despite delivering a compound 10.3% pa return over the past 98 years and increasing 73% of time - the S&P500 index has nonetheless still fallen in 26 of those years by an average -13.4%?
Basically saying if you have time horizons of 5 years or more, then you'll be pretty unlucky (ceteris paribus) to lose money over that period.
Sadly not many of us will make 97 years longevity and have to hope don’t need cash during a down cycle. Be interesting to see an equivalent set of data for the FTSE100. I note that S&P 500 had best day for two years yesterday (Source. FT) yet UK markets still pretty static. Seems our markets plunge when US falls and don’t recover when the US bounces back. Lack of technology stock exposure perhaps?
10.3% pa return from S&P 500 is fairly sobering reading... I am only slightly above that. Maybe I should give up on UK small caps and stick everything in a S&P500 tracker?!
A lot of the the S&P500 is driven by a few of the companies. We all know their names: MSFT, GOOG, AAPL etc.
But here's the problem If you go back to like 2014, AAPL was on a ridiculous value of below 14. Amazing to think about now, isn't it? This wasn't a fluke, there were plenty others in that position. So obvious in hindsight!
Now AAPL is on a PE of 32.
It's worth reminding ourselves that MSFT took 13 years from its 1999 share high to get back to that level.
Big Tech looks invulnerable right now. But remember, the more invulnerable it looks, the greater the risk it has.
Never easy, is it?
I started investing properly in 2012 and I would be considerably richer now if I had put all of my money in to a combination of Berkshire Hathaway (NYQ:BRK.B) and an S&P Tracker, rather than fannying around in small caps. I ams sure that there are a few (Paul?) who can outperform the S&P on a regular basis, but I think it is a bit like Frenchmen and love making; 90% of Frenchmen think they are above average lovers.
I have not yet bitten the bullet and moved all of my money to an S&P tracker but 32% of my money is in Berkshire and S&P and most 85% of my wealth is in property.
Regards
Michael
Have a look at Investor AB listed on the Stockholm market. They have a similar family holding company structure to Berkshire Hathaway and a similar philosophy, but with a focus on industrials, rather than insurance.
Investor AB holds strategic stakes and often voting control in some well-known large cap companies including ABB, Astra Zeneca, Atlas Copco, Ericsson, Husqvarna, NASDAQ, SAAB and Electrolux. They also have a private equity arm called Patricia Industries which invests in medical tech and consumables, and they own a small stake - circa 10% I think - in Swedish fund manager, EQT.
Investor AB was set up in 1916 by the Swedish Wallenberg Family, who are the richest industrial family in Europe. Market Cap is just over £69 billion. There are two classes of shares with the A shares carrying the votes. The Wallenberg family own 49.22% of the A class shares.
They form 20% of my portfolio and 40% of our family holdings where we have held the company for over 20 years.
They have compounded capital over the past 10 years at 16% pa including a 2% dividend. They have delivered double the returns of Berkshire Hathaway over the past 10 years, although the family also hold Berkshire Hathaway (I don't). Berkshire Hathaway and Investor AB are buy and forget and sleep well at night investments.
Finally, you can hold them in a UK SIPP or ISA as they have a crest certificate.
Investor - Home (investorab.com)
Agreed ....but there are always exceptions to every rule, Japan (until very recently) / UK AIM index !