Small Cap Value Report (Fri 9 Feb 2024) - SEE, SUS, KINO, ALU, VLG

Good morning from Paul!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
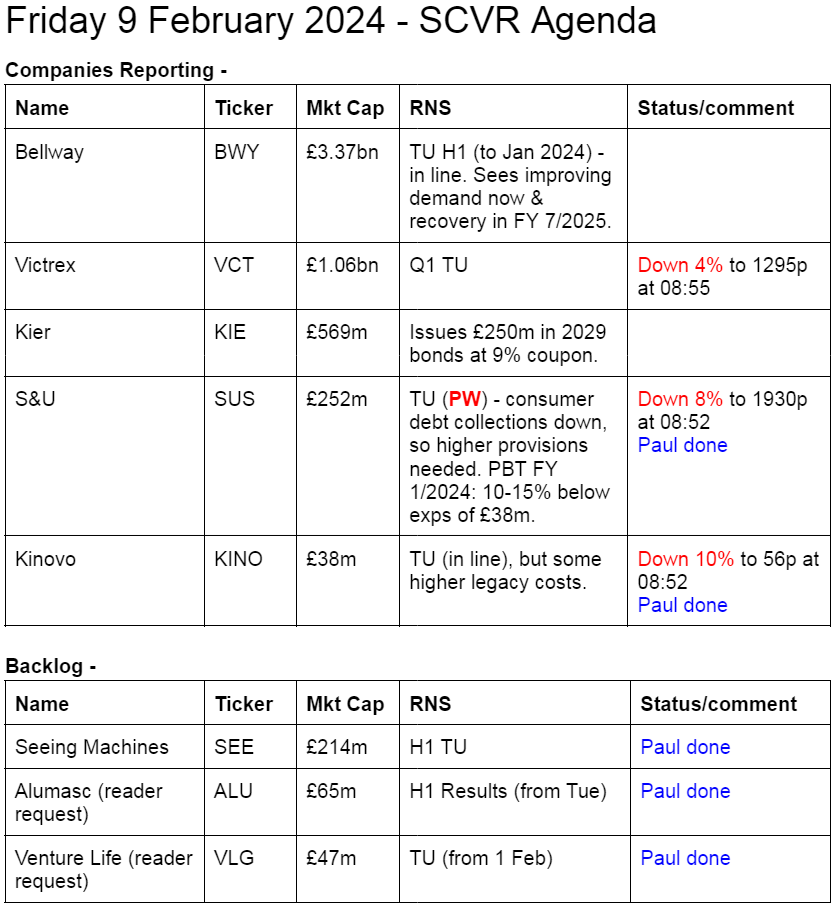
Other mid-morning movers -
Sondrel (Holdings) (LON:SND) - down 22% to 9.5p - the pump & dump continues to unravel? It’s almost out of cash, so needs to get a fundraising done, pronto.
Summaries
Seeing Machines (LON:SEE) - down 2% y’day to 5.15p (£214m) - H1 Trading Update - Paul - RED
A trading update yesterday misleads us over the cash position, by ignoring the $40m convertible 2026 loan. So it actually has a growing net debt position. Will need another fundraise late in 2024 I reckon. Then it has the timebomb of the 2026 convertible repayment to think about. On the upside, revenues are growing, and it thinks cashflow breakeven is possible in Jun 2025. That's not good enough risk:reward for me, so I'm sticking at RED.
S&U (LON:SUS) - down 8% to 1,937p (£235m) - Trading Update [profit warning] - Paul - BLACK (PW flag) - AMBER on fundamentals
This specialist lender for car financing, and property bridging loans, mentions tough conditions requiring a higher bad debt provision. This has knocked back FY 1/2024 profit guidance by 10-15%. It's not a disaster, and I find the valuation metrics attractive, so I'm viewing this moderately positively overall. Although there are regulatory worries, and we can't be sure how quickly consumers recover from the cost of living crisis.
Kinovo (LON:KINO) - down 10% to 55.5p (£35m) - Trading Update [in line, pre-exceptionals] - Paul - RED
My first review of this niche property services business. It initially looked quite good, until the sizeable legacy issues (re a former building division) are considered. Costs and delays have increased legacy provisions to a level which I think makes the already weak balance sheet look precarious. So high risk of a dilutive placing, I suspect. Why get involved, when it's not even particularly cheap for the core business?
Alumasc (LON:ALU) - 179p (£65m) - Interim Results - Paul - GREEN
Readers asked me to look at recent in line H1 results. I'm glad they did, as this looks a smashing value share. I think it's too cheap, with upside on future earnings and a possible re-rating onto a less mean PER. Thumbs up from me, but as always, this is just on a quick review, so you need to do your own more in-depth digging.
Venture Life (LON:VLG) - 37p (£47m) - Trading Update - Paul - AMBER
A bit vague in places, so I need to see the full year numbers before forming a firm judgement. But at best I'm lukewarm on a quick review.
Paul's Section:
Seeing Machines (LON:SEE)
Down 2% y’day to 5.15p (£214m) - H1 Trading Update - Paul - RED
Seeing Machines Limited (AIM: SEE, "Seeing Machines" or the "Company"), the advanced computer vision technology company that designs AI-powered operator monitoring systems to improve transport safety, provides a trading update for the six months to 31 December 2023 ("H1 2024") and quarterly Key Performance Indicators ("KPIs") for the quarter ended 31 December 2023.
H1 revenue of $25.6m, up 5% reported, or 28% up excluding some prior year one-offs.
ARR up 22% to $14.5m - doesn’t seem a lot, considering SEE has been trying to commercialise its tech for about 20 years.
Cash of $22.2m at end Dec 2023, and $13.9m cash burn in H1. So another cash fundraise looks to be on the horizon I’d say - probably mid to late calendar 2024?
Graham and I regard the updates from SEE as being misleading, because it only reports gross cash. Checking the last balance sheet at 30 Jun 2023, there was a $40.3m loan within non-current liabilities. This forms part of a $47.5m convertible loan note from Magna International, maturing in Oct 2026 (see note 21 in the last Annual Report). Conversion price is 11p, so with shares in the open market less than half that level, presumably the holder would prefer to be repaid in cash in Oct 2026, rather than convert. So that looks like a ticking timebomb. Magna is a large Canadian car parts manufacturer - so this is an impressive strategic investment in SEE, but I do worry about how it may ultimately hand control to Magna, if SEE is not able to repay it in 2026. Plus SEE has already burned through over half of the cash it received from Magna.
Looking ahead, the growing industry demand for fatigue and distraction solutions to support enhanced transport safety, combined with our market leadership position, production pipeline, proprietary AI technology and balance sheet strength, leave us well positioned to meet FY2024 expectations and cash break even run rate during FY2025."
For a start, it doesn’t have a strong balance sheet. NTAV will probably be down to about $7m by Dec 2023 (I’ve estimated this as $21m NTAV at June 2023, less $13.9m cash burn in H1 to Dec 2024). It’s also has net debt of about $(18)m at Dec 2023 - being $22.2m gross cash, less the $40.3m convertible loan disclosed at June 2023.
So clearly the 8 Feb 2024 trading update which doesn’t mention the convertible loan at all, is highly misleading.
Upside potential - there is lots of detail in the TU about deals with car manufacturers. It says these total lifetime value of $366m. What’s the lifetime though? Revenue was $58m last year, which resulted in a $(15.6)m loss before tax. So on a c.50% gross margin, it looks like breakeven revenue would need to be about 53% higher, at $88m pa. That’s just to breakeven remember, let alone make any profits or cashflows to repay the convertible loan.
Paul’s opinion - revenue growth is happening, and the contract wins sound impressive. Yet SEE remains loss-making and cash-burning. There’s a financing timbomb, well 2 actually - the existing cash pile could run low, or out, in about a year. Plus it has to work out how to repay the convertible loan to Magna in 2026. Dilution in the past has been excessive, with now c.4.16 billion shares in issue!
Overall then I think the £214m market cap is looking optimistic, and doesn’t give me an attractive risk:reward. Hence I’ll stick at RED, because of the weak balance sheet with substantial debt, depleting cash reserves, and inadequate growth rate to transform the numbers. By the time SEE is actually making a decent profit, we might be seeing driverless cars coming onto the market, so it may not have a particularly long lifetime for this driver alertness product - over 20 years to commercialise it, then obsolete after a few more years maybe?
SEE would make a good case study in why it's best to avoid blue sky projects - they take many years to reach commercialisation, require numerous rounds of equity financing, and spend most of the time overvalued due to overly optimistic hype. SCE is another good example of it taking an eternity to reach commercialisation, and the value being destroyed due to repeated delays & equity dilution.
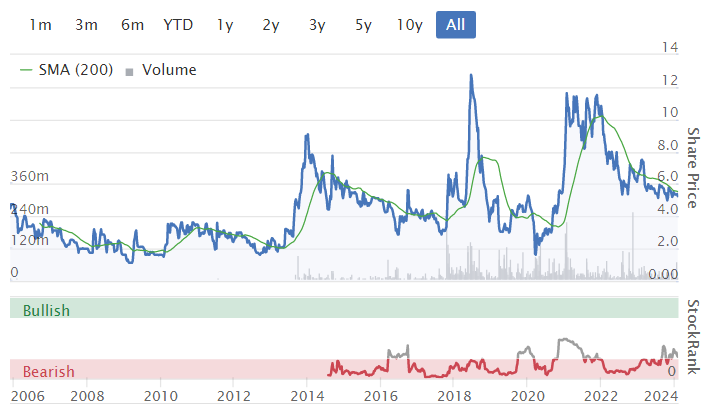
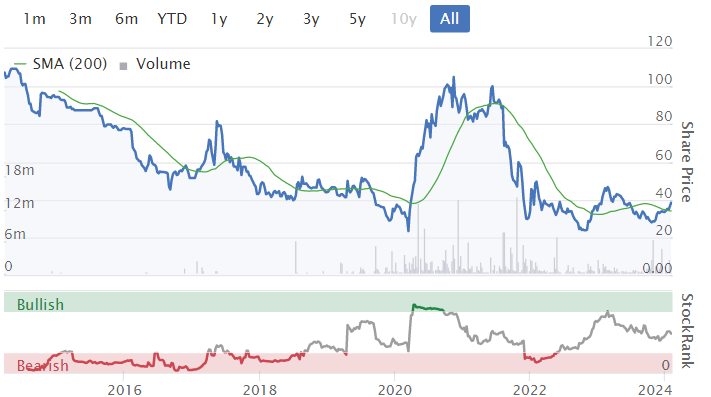
Here's SEE over its 20 year period as a listed company -
S&U (LON:SUS)
Down 8% to 1,937p (£235m) - Trading Update [profit warning] - Paul - BLACK (PW flag) - AMBER on fundamentals
S&U PLC, the specialist Motor and Property Finance financier, today issues its trading update for the period from its statement of 12th December 2023 to the Group year end on 31st January 2024. S&U's full year results will be announced on 9th April 2024.
My summary of today’s update -
Profits impacted by these factors -
…poor consumer confidence, continuing high interest rates, cost of living pressures and regulation…
Significant drop in collections from customers -
…live monthly repayments at Advantage for the second half of the year were 90% of due (H1 23: 94%).
Increased bad debt provisions required.
Profit warning - new guidance for FY 1/2024 - this is crystal clear, and not a disaster -
Thus, our group profit before tax for the year ended 31 January 2024 is likely to finish between 10% and 15% below consensus expectations of c£38m.
It sees these problems as temporary -
Nonetheless, we expect a solid rebound; hence our continued funding investment in both businesses of £15m during the period…
In the meantime, the decline in collections referred to above is reflected in a percentage of due 4% lower than Advantage's habitual 94%. This may be partly seasonal and is expected to partly recover in the coming months. The actual levels of bad debts and voluntary terminations remain within budget.
Discussions with FCA have “deepened”, and some process changes made, not clear what financial impact this will have.
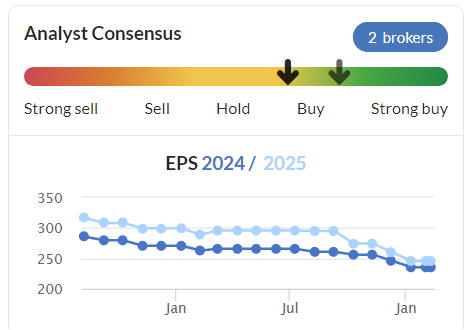
As you can see below, forecasts were already on a steadily declining trend, with another drop flagged today - which will update on this graph next week probably -
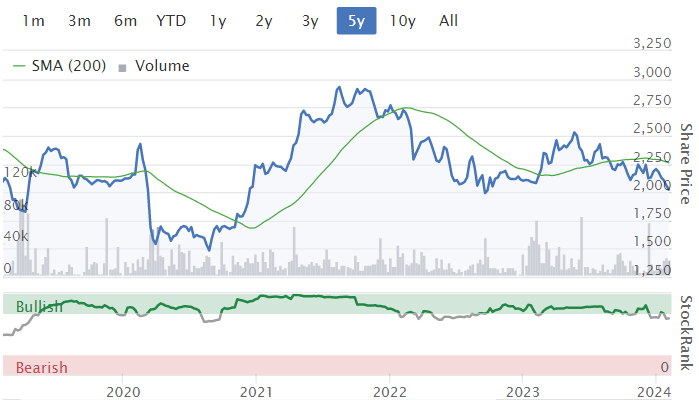
All of which has been reflected in a softer share price since the peak at end 2021, plus of course a wider bear market in small caps over the last 2 years -
SUS also does property bridge loans, secured on properties. There’s a nice summary here of progress -
Thus again, the watchwords for Aspen are ambition tempered by caution. Net receivables now stand at just over £130m (2023: £114m) as the business achieved its budgeted annual gross lending target of £144m, and has also just achieved an impressive historical milestone of £500m of gross lending. Collections have been slower in the period, as refinancing and sale processes take longer. This followed an excellent performance for the year as a whole, when repayments (excluding retentions) at £126m were more than 50% up on 2022/23. Hence loan book quality remains good. Of 167 loans, the number of loans beyond term is 15 (December 23: 16).
Funding - again, self-explanatory. SUS borrows in bulk, and then lends in smaller, higher interest cost deals, that’s its business model.
Group borrowing now stands at £224m against £192m last year. Group funding facilities of £280m provide comfortable headroom for the sustainable growth path expected over the next two years. However, these funds come at an increased and not readily transferable cost, and the past year has seen interest payable by the Group rise to £15.1m from £7.5m last year.
Dividends - a slight cut to the 2nd interim divi, from 38p LY, to 35p this time. Nothing to worry about there. Yield is about 7%, and looks reliable (and growing) - great for income seekers.
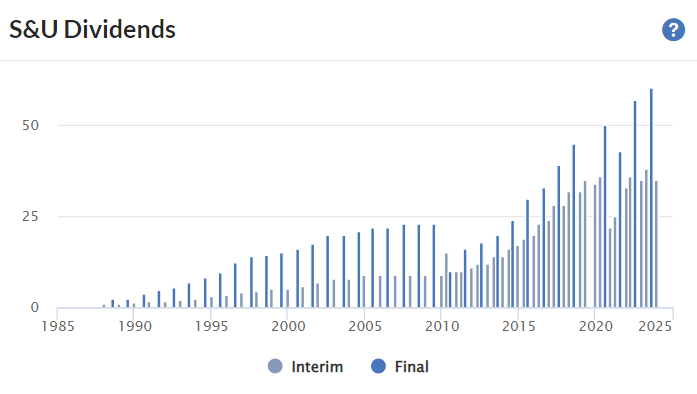
The long-term track record on divis is remarkable - note the change c.2010 to paying 3 divis per year, instead of 2, which needs to be taken into account -
Chairman’s words are nicely down-to-earth I think - as you usually find at owner-managed businesses - it’s controlled by the Coombs family -
Commenting on the Group's performance and outlook, Anthony Coombs, S&U Chairman, said: "Faced with an array of challenges ranging from weak consumer confidence, cost of living pressures, funding costs and regulatory activity, 2023 has not been a vintage year for either S&U or the specialist financial services sector. Given the underlying strength, resilience and expertise of our Group, I fully expect a resumption of S&U's habitual and robust profit growth in the years to come."
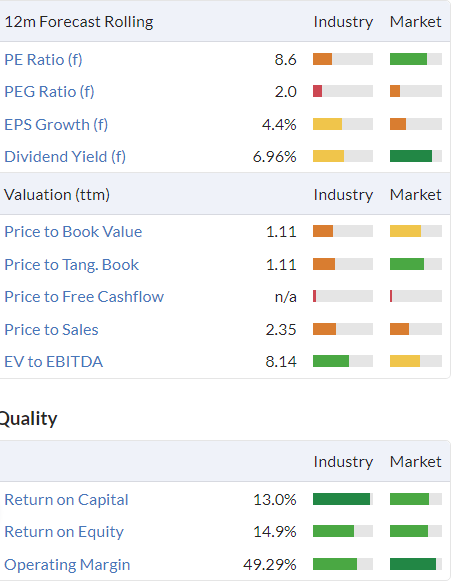
Valuation - some very attractive metrics here, and note it’s close to being fully NTAV backed, giving a lot of downside protection. Although note these figures will change a bit when the data updates with the latest broker changes today -
Paul’s opinion - Graham usually covers this one, and has written positively about it a lot in the past. Although I see he went down from green to amber on 12 Dec 2023, being spooked by the Skilled Person Review, and the more bearish language from the Chairman.
There are such attractive valuation measures here, and an excellent long-term track record from prudent owner-managers. This really makes SUS stand out. I think a lot of "challenger" type lenders come a cropper in recessions, because they take on risky loans in order to grow fast. Whereas SUS has been in this game for decades, and seems a prudent operator. Hence why I think it's worth a look, even though this might be seen as a really bad point in the cycle to look at lenders of any type, in particular specialist lenders, when defaults are rising.
It’s not really a sector I would want to invest in though, especially at a time of apparently increasing stress on consumer budgets (but that could rapidly change from April 2024).
We can’t get away from a softer patch of trading at the moment, and this is a profit warning, but it doesn’t strike me as a serious or ominous profit warning today. Could it warn on profits again is a key question? Maybe, maybe not, who knows?
Downturns can also shake out flaky competition, giving more market share to better run, more established companies like SUS.
EDIT: I totally forgot to mention the current controversy over mis-selling of car finance. Some readers have picked up on this, and are discussing it below in the comments. It would have been helpful for SUS to have said something about this today, which it didn't. Hmmm, maybe I should leave it at AMBER after all, which was Graham's last view. Yes, I think I'll do that, so editing the original from amber/green, just to be on the safe side. We can always go back up again at a later date.
Kinovo (LON:KINO)
Down 10% to 55.5p (£35m) - Trading Update [in line, pre-exceptionals] - Paul - RED
Our SCVR coverage of this share stopped in late 2021, as Jack used to cover it, and must have moved on to his job in the city around that time.
So I’ll take a look with fresh eyes today, as it looks quite interesting - what seems a near death experience in 2022, and it’s 6-bagged since those low!
What does Kinovo do?
Kinovo plc (AIM:KINO), the specialist property services Group that delivers compliance and sustainability solutions, provides the following trading update.
It floated in Mar 2015.
Reviewing recent RNSs -
1/9/2023 - KINO announced it had received an indicative possible offer at 56p cash from Rx3 Holdings, owned by Tim Scott (linked to 29.6% shareholder I think) . Mgt said they would not recommend such a bid, after consulting other shareholders.
5/9/2023 - HSBC has renewed borrowing facilities to 31/5/2024, removing material uncertainty in last going concern statement.
19/9/2023 - Rx3 Holdings issues a statement saying it will not be bidding. Unusually it also airs some dirty linen in public -
Rx3 remains concerned over the unresolved and hence open-ended issues that persist with regard to the DCB projects that the Company has stated that it believes will be finalised by the end of 2025 at a cost of £18m with £14m expected to be recovered from clients and subcontractors.
Having not been permitted access to perform due diligence, nor having received a response from the Company seeking to clarify or counter any of the points made in the Rx3 Announcement, this has heightened Rx3's concern and resulted in it deciding not to proceed with any offer. Rx3 will continue to seek further clarity as to the contractual position and the Company's financial exposure regarding the DCB projects.
Clearly then, this share is complicated, and I’m already starting to lose interest, due to the size of the liabilities mentioned above by Rx3. That’s obviously what caused the share price to collapse in 2022. What happens if it can't recover £14m from third parties?
28/11/2023 - Interim results look OK. Revs £30.3m (up 2%), adj PBT £2.6m (up 25%), notes H2 weighting to profits. Outlook in line with FY exps. Weak balance sheet with what look like stretched creditors. NTAV is negative at £(3.4)m.
Trading update today - starts off positively -
The continuing business continues to perform well with particularly strong margins reflecting the mix of works and continued effects of management's implementation of the strategic repositioning.
Discontinued operations - this is the problematic contracts from its former construction division, called DCB Kent. There have been some delays & increased costs -
As a result of these delays, the total net costs incurred have increased to £7.1 million as at 31 December 2023 including additional procurement, warranty and remedial costs. Kinovo are seeking to recover some of the additional costs incurred through claims and recoveries, but the total pre-tax net cost to complete is therefore expected to be a material increase from the previous estimate of £5.72 million.
That looks very onerous in the context of its weak balance sheet and modest cash position & bank facilities. I don’t have enough detail to properly assess this, but my inkling is that KINO seems to be in a precarious financial position, and could well need to do a placing, to bolster its balance sheet.
Outlook - tries to reassure us, and to be fair, the core business does look fairly decent -
Without accounting for additional works crystalising from Kinovo's pipeline as the Group enters its peak trading season, revenues for the year ending 31 March 2024 for continuing operations are expected to be approximately £65 million (FY23: £62.7 million), reflecting a different revenue mix of projects contracted to date, with electrical services continuing to perform strongly. Adjusted EBITDA is expected to be significantly ahead of last year (FY23: £5.5 million) and not less than £6.2 million, being in line with management expectations. This demonstrates the Board's continued confidence in the strength and resilience of the continuing business and its significant growth potential. Cash balances will reflect the aforementioned costs incurred and the outcome of any potential recoveries from the DCB projects, supplemented by cash generation from the continuing business.
The good news is that adj EBITDA of £6.2m mostly turns into adj PBT - Canaccord (many thanks) has put out a note today, with £5.8m adj PBT forecast.
Paul’s opinion - the core business looks fairly decent, but not something that’s ever likely to attract a PER of more than about 10, given the sector.
Forecast adj EPS is 6.9p gives a PER of 8.0x, but it comes with all the baggage of these large disputed old building contracts, and a weak balance sheet that doesn’t (I think) have the capacity to pay out the cash needed to close off the disputes.
So shareholders are left hoping that the core business can over time generate the cash to settle historic problems, and that the bank will remain supportive - with a bank renewal to just May 2024 recently not inspiring much confidence, as it looks like a stopgap.
The UK small caps market is awash with value opportunities at the moment, where we can buy good businesses on modest valuations, and with strong balance sheets. So why get involved in something complicated, problematic, and inadequately financed like KINO?
Personally I’ll be keeping clear, and flagging the high risk with a RED view for now. It might well survive and prosper, but even if it does, I can’t see that much upside on the existing share price. So at this stage, I think risk:reward seems poor, which is pretty much what the potential bidder said when they pulled out.
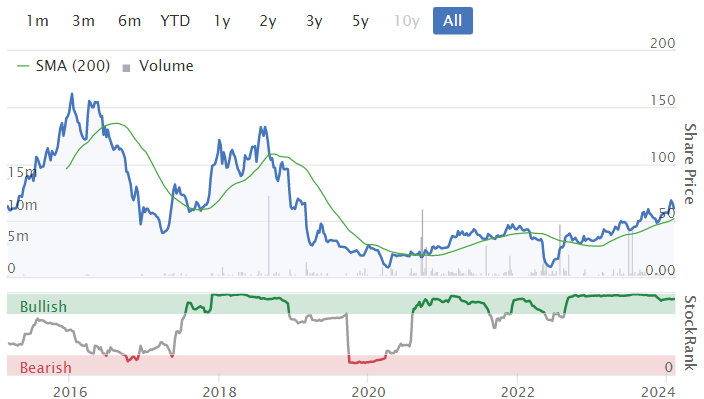
That said, the stock market seems to be looking through the problems -
Alumasc (LON:ALU)
179p (£65m) - Interim Results - Paul - GREEN
This came up as a reader request recently. We’re not an on demand service of course, but we try to accommodate reader requests, if people spot something interesting and flag it up to us with good reasons.
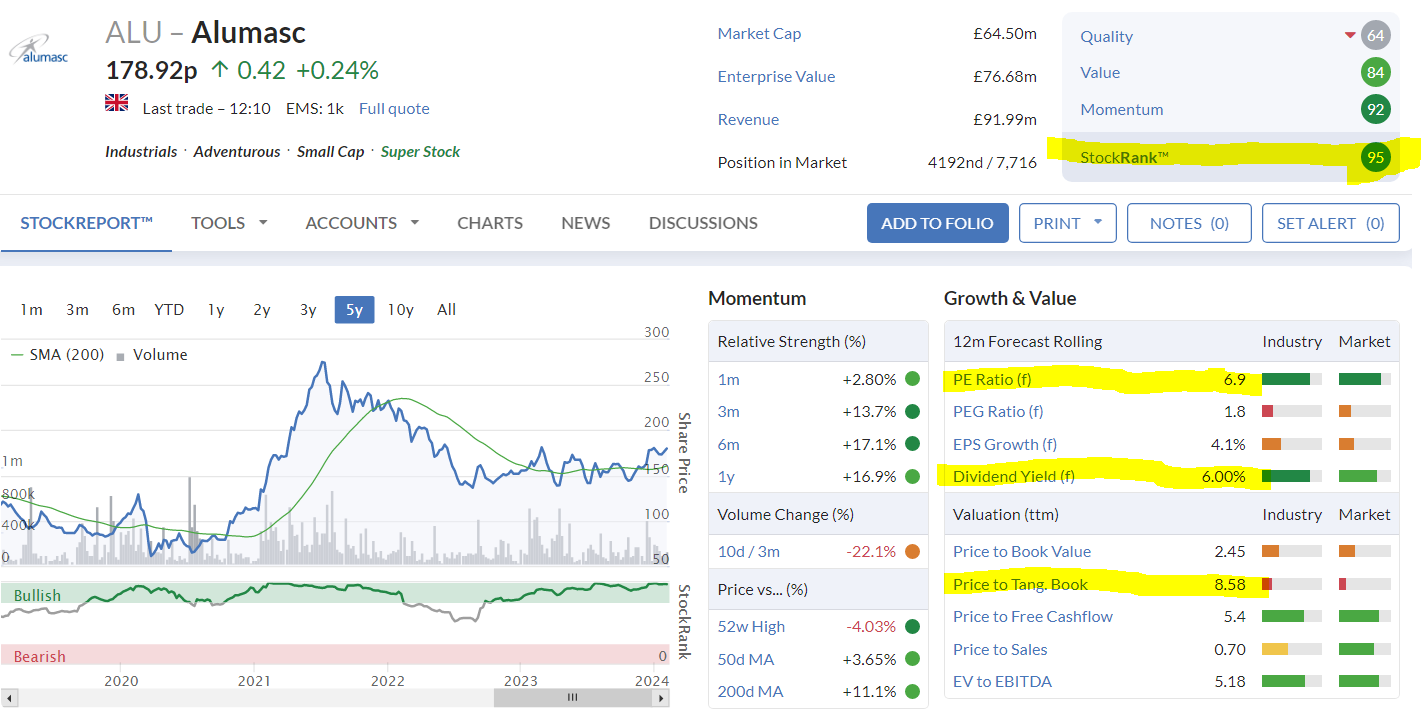
The quickest of glances at the StockReport has immediately caught my eye, with some attractive key numbers below that I’ve highlighted -
Also, I like the building products sector, as having potential for a recovery, with some attractively low valuations still available in places.
This came out on Tuesday 6 Feb 2024 -
Alumasc (ALU.L) the sustainable building products, systems and solutions Group today announces results for the six months ended 31 December 2023.
The CEO’s summary seems impressive given tough macro -
"We are very pleased to report an encouraging first half in which we continued to outperform our underlying construction markets. As expected, UK sales were resilient in a challenging environment; and coupled with strong overseas sales, Group revenue and underlying profit before tax grew by 6% and 12% respectively. We have again demonstrated the resilience of our business model with its multi-markets exposure.
Outlook also sounds fine -
"The Board remains confident in achieving full year expectations, despite the expected continuation of UK demand headwinds and the further delay of a significant export contract in Hong Kong."
Broker forecasts have been edging up recently too -
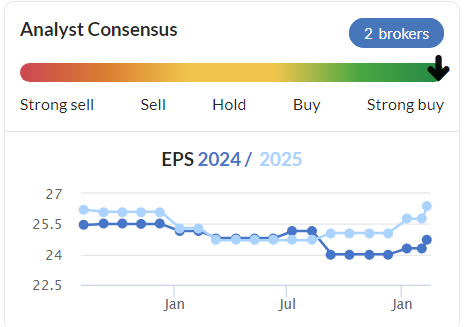
H1 figures -
Revenue up 6.4% to £47.8m
Good underlying operating margin of 14.1%, indicating pricing power.
Underlying PBT up 12.4% to £6.3m - remember that’s just for a half year.
Adjustments look smallish, since statutory PBT is £5.6m
Underlying EPS 13.0p in H1
Net bank debt looks fine at £7.4m (after spending £6.5m on an acquisition)
Broker update - thanks to Cavendish, who update us, expecting 25.1p adj EPS, for a PER of 7.1x, which strikes me as a modest valuation, with upside potential on both the earnings, and the rating.
Balance sheet is OK, but not strong. NTAV is about £8m.
There’s cash of £7.2m, and bank debt of £14.6m, so net debt of £7.4m - not excessive.
Note the pension deficit of £4.8m, which seems to be a cash drain of about £0.6m pa, down from £1.0m last year. So I’d say valuation of the shares needs a small downward adjustment to reflect this liability, but it’s nowhere near a dealbreaker.
Cashflow looks fine to me.
Paul’s opinion - on the quickest of reviews, I think this looks a smashing value share.
Thumbs up from me. Thanks to the readers who badgered me into looking at it!
Venture Life (LON:VLG)
37p (£47m) - Trading Update - Paul - AMBER
Venture Life (AIM: VLG), a leader in developing, manufacturing and commercialising products for the self-care market, announces a trading update for the year ended 31 December 2023 ("FY23"). The Company expects to publish its results for FY23 in early April 2024.
FY 12/2023 revenue is c.£51m, up 16% helped by an acquisition (+5% on a LFL basis)
EBITDA in line with expectations (no figure given)
Normalised inventories improved operating cash generation to £9.5m (up 70%)
Gearing reduced to 1.25x EBITDA (1.1x post year end)
Price rises will raise margins in 2024.
The commentary is all a bit vague and mostly fact-free.
Looking back H1 results were nothing to write home about, and finance costs stand out as heavy, tipping it into a statutory loss before tax of £(1.3)m for H1.
The balance sheet at June 2023 was weak, with NTAV of £(2)m.
Bank debt was excessive, at £16.9m gross, less £3.7m cash = £13.2m net debt at June 2023. That’s too much gearing,although it sounds as if the position might have improved in H2.
Cavendish has put out a recent update (many thanks). Note that the large £11.6m adj EBITDA only turns into £2.5m adj PBT. So I would need to see the full published accounts to see how all the numbers fit together, there’s not enough information in today’s update.
Paul’s opinion - VLG strikes me as unremarkable. It seems a hotch-potch of small-selling branded personal care products. There’s been a lot of dilution over the years, and its track record hasn’t been very good.
Directors bailed out at the right time, banking millions at 90p in Nov 2020.
Overall then, I’m a bit sceptical, but will grudgingly go with AMBER.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

147 comments
Yes the discussion on SCVR is excellent. You really don't need to apologise. You were called an idiot for saying the SCVR is quite useful and that was pretty rude. Not sure abusing the customers should be a core concept at Stockopedia.
Doctor Dave, It seemed like an off the cuff remark and not meant maliciously, so I will let it pass - this time. I may withdraw my "likes" for this topic in the future though.
Appreciate your thoughts. Thanks.
If anyone from Stockopedia is out of bed and concerned about the value of the Stockopedia brand they may wish to do some redacting and deleting on this thread this morning.
This might help achieve the stated objective to "preserve the quality of the comments section" .
Exactly the opposite should happen-all these posts should be left for everyone to read. Same person asking for quality of this section the other day abuses innocent subscribers at 3 o’clock in the morning.
Another day another evening another morning (whatever).
Another 24 hours of mocking subscribers from the same person.
This is the main reason I have cancelled my subscription and to be honest I do not understand why the management of stockopedia accepts this behaviour by one of their employees. No other workplace would accept or encourage this bullying and abusive behaviour. Calling subscribers idiots, gamblers and fools anonymous!
The funny side of things is that the same person has asked contributors on many different occasions NOT to turn this forum into ADVFN or X.
Thanks
Gutted to see you leave Yiannos1... I have learnt a lot from your perspectives, insights and experience... are you active on Twitter / X or any other forums at all please? Please excuse the question if it offends ...
I have an account on X (not active anywhere else) but I do not post anything-just for my own educational purposes I follow some clever people.
There are so many parts to Stockopedia. I hope you will consider staying for the parts you like and find useful.
Yes you are absolutely correct on this one but at the same time this forum and the morning report is also a part of this service
Can you imagine calling one of the customers in your workplace a fool or an idiot and in a very nasty way as well?
It’s embarrassing for the whole stockopedia team and the effort they are doing to provide a better service.
A quick post on AIM VCTs which are an interesting way to get 30% tax relief, tax free dividends outside an ISA and tax free capital gains once you have exhausted ISAs and SIPPs. You have to be willing to hold long term on higher risk portfolios and suffer a bit of a share price discount to NAV building. However, obviously, its a better time to invest than 2 years ago on AIM particularly when the VCT manager has a good long-term track record.
I put some money into Unicorn AIM VCT (LON:UAV) today. Despite the bombed out share price they only opened the VCT offer yesterday (although the prospectus has been out for a few weeks), raised the full amount by 3pm yesterday and are over half way through the over-allotment facility when I applied this morning. I was very surprised there was such a fast take-up given the pain of UK small-cap markets.
This is not about the individual purchase, but more about it underlining that there is still strong demand for AIM micro-cap venture new issues with the right tax incentives in place. Encouraging I thought, so I thought I would share.
All we need now is abolishing stamp duty on UK share purchases and a UK ISA. The LSE market needs a helping hand.
There are a few AIM VCTs out there to choose from such as Baronsmead Venture Trust (LON:BVT) , Amati AIM VCT (LON:AMAT) , Hargreave Hale Aim Vct (LON:HHV) and Octopus AIM VCT (LON:OOA) - all have reasonable records over the medium term, but are down about 50% on a couple of years ago. I hold the first two.
Unicorn Aim VCT is a long term holding and I seem to recall that all its offers are well over subscibed. In fairness the offer is very small (15 million initial with 5 million over) and existing holders will hoover this up without too much effort.
Its proved to be one of those companies which distributes nearly all profit as income. Dividends paid between 1st October 2018 and 31st December 2023 total 71.5 pence per share and hence it will be popular within a tax exempt VCT structure.
I didnt take up the offer though I would suspect that it will be an attractive entry point.
I have a few VCTs, anyone know why their prices have dropped so much?
Hi topvest,
thanks for posting on VCTs. From your experience, what is the liquidity like ? And can an investor typically buy outside of the fund raising period ?
fyi - I found the following podcast from Feb-22 very useful re VCTs.
https://tinyurl.com/bdhkvkau
My notes....
# VCTs started in 1994.
# Government effort to increase investment in early stage businesses.
# Purpose is to provide capital to early stage growth trusts.
# After some early setbacks, VCTs in the main have provided some decent returns for shareholders.
# 30% income tax relief but investors must hold VCTs for a minimum of 5 years.
# All returns are tax free. I think I heard most of the returns are in the form of dividends but please check & revert if I have this wrong.
# GBP 5bn in VCTs as of February 2022. By my calcs, this has fallen to approx 2bn now.
# Most VCTs invest in typically 30 to 60 early stage companies.
# Octopus is the biggest provider.
# Most VCT providers offer a buyback option (usually 5% discount to NAV).
# Investors need to think of VCTs as long-term investments as the VCT market is not very liquid.
# Last 3 minutes handles the issue of market liquidity. Conclusion is they are long-term investments (people generally hold VCTs for at least 5 years) and issuers do provide the option to sell at typically a 5% discount.
I did a bit of research on VCTs at the time of the podcast and concluded some basic facts: AIC web site says there are 8 VCT sectors containing 27 trusts with a combined mkt cap of 2.1bn as of today....VCT AIM Quoted (7 trusts / 769m total mkt cap)
VCT Generalist (10 trusts / 1145m total mkt cap)
VCT Generalist Pre Qualifying (2 trusts / 65m total mkt cap)
VCT Specialist: Environmental (3 trusts / 85m total mkt cap)
VCT Specialist: Healthcare & Biotechnology (2 trusts / 18m mkt cap)
VCT Specialist: Media, Leisure & Events (1 trust / 5m mkt cap)
VCT Specialist: Technology (1 trust / 7m mkt cap)
VCT Specialist: Technology Pre Qualifying (1 trust / 18m mkt cap)
I have no idea why there are 3 sectors with 1 trust in each! Makes no sense, maybe there were more once upon a time but there you go. Anyway, let's focus on 2 trusts....
Octopus Titan VCT which is the largest trust by mkt cap in the VCT Generalist sector. 1.142bn mkt cap, 9% discount and 6% yield. Top 10 accounts for approx 75% of the total trust. Cazoo is one of the holdings. Chart looks similar to that of many of the smaller company charts.... SP has sold off over the last 12 months and discount has widened. Interesting it has underperformed the sector average over every time period. Jam tomorrow ? Maybe. But it has paid regular dividends over the years so must be doing something right.
https://tinyurl.com/3fyyfdsr
https://tinyurl.com/4femjknz
Unicorn AIM VCT which is in the VCT AIM Quoted sector. 187m mkt cap, 12% discount and 5% yield. 186m mkt cap, 12% discount and 5% yield. Top 10 accounts for approx 45% of the total trust. Some recognizable names....Tracsis, Anpario, Avingtrans, Tristel, Cohort. Has outperformed the sector average over the years. Again, chart looks similar to what we have seen happen in the smaller cap / private equity markets.
https://tinyurl.com/y785szex
https://tinyurl.com/2mr95fhw
My conclusion at the time was VCTs are high risk, potential high return, not for widows or orphans! Lots of early stage, high risk businesses but they are grouped together so if one fails then an investor's cash is not completely done. The risk is spread.
Thoughts welcome.
SSB
Re Seeing Machines (LON:SEE) becoming obsolete. Even if you're correct in thinking that self-driving cars are coming any time soon (I don't), SEE also provide Occupant Monitoring.
So, if your self-driving car is taking you to the cinema and you happen to have a stroke along the way, do you still want to go to the cinema, or would you rather be taken to the hospital instead?
This tech is also of course relevant anywhere where a machine/robot needs to understand what a human is doing.
For those interested, this is still relevant:
https://stream.brrmedia.co.uk/...
Seeing Machines (LON:SEE) are becoming the opposite of obsolete as you say Joe91. Plus they will be in every aircraft, boat, train, tram, lorry/HGV as well as cars....... Global automative regulations are mandating this tech so it will be the mainstream for at least the next 15 years particularly given length of car manufacturing model cycles. There are only a couple of players in this industry that have either the credibility (which includes long term research and proof of consistency) or longevity required. Seeing Machines (LON:SEE) has circa 70% market share I believe.
I think the finances are also misunderstood. Cash outflow second half should be no more than $5m and positive mid next year. The only real question I have on the finance is the convertible but Im almost certain I've asked that question before of mgmt and it isn't an issue. The new CFO was buying large quantities and spent a lot of money - he wasn't doing that to hand the company over as Paul suggests.
That all said I suspect the share price is unlikely to go anywhere over the coming months as the real catalyst for this is next year, so buying now I suspect is dead money that could be used better elsewhere for now until the mood music changes.
Hi david,
Thanks for your additional points on Seeing Machines (LON:SEE)
I'd just urge you not to shoot the messenger! Since the company did not mention the substantial convertible loan at all in its latest update, and claims to have net cash (when it actually has net debt), I was correct to flag this as an issue, which readers can then investigate & interpret themselves. Pretty shocking though that the company tries to present itself as having net cash, are you not concerned about that misrepresentation of the facts?
Regards, Paul.
Hi Paul - Haha, definitely not shooting the messenger. Love your work as you know. It’s very valuable and you do a fantastic job at getting analysis out so never any complaints from me :-)
Re Seeing Machines (LON:SEE) I don’t think they’ve ever represented themselves as net cash. They’ve pretty consistently said they have a cash balance sufficient to move into run rate cash flow positive next year and expect not to need any additional funding. The management presentations I’ve attended they seem pretty genuine and down to earth - I could be wrong of course but I don’t think there is any “wool pulling” here.
They brought in a well regarded new CFO a year ago and he has bought a lot of shares since, as has the NED. That doesn’t suggest to me that they see any risk around the convertible. I confess though that whilst I’ve asked the question to mgmt about it previously I can’t quite remember the answer, though at the time I was comfortable so I do need to revisit that to check.
Personally, I don’t think they are going anywhere much share price wise in the next few months because the catalyst for any re-rate is really 2025 onwards, but I do think this is a business that will be several times larger in a few years time. Would it surprise me if they raised a bit of cash, no, but I doubt it’s material in dilution terms and probably from an OEM partner. So I think your assessment is a little harsh but I don’t disagree with the sentiment that it’s probably not yet the time to be buying.
Sorry David, that is not true.
SEE has convertible debt on its balance sheet.
That is not a matter of opinion it's fact.
Not averse to an untruth yourself though Paul, claiming that tech mandated by the EU, (and soon NHTSA?) is soon to be obsolete.
Weird move on Journeo (LON:JNEO) today. Not sure who they upset to get kicked 11%
Did I miss something?
Journeo (LON:JNEO) is small and crowded with PIs...ergo it may perform Somero Enterprises (LON:SOM) levels of mystifying share price moves once any initial surprise is digested. Not a forecast, just an observation
Well it certainly had a demystifying move today :-)
Trading is good as I understand it and they are pretty lowly rated but hey ho. I’m in this for the growth over the next few years so no biggie just wondered if I’d missed a new Labour policy announcement banning all digital displays ;)
Journeo (LON:JNEO)
I hold.
An educated guess is that the share price weakness is due to Downing Strategic Micro-Cap Investment Trust (LON:DSM) selling down its holding, which has gone from 6.62% just before Christmas to 2.52% currently.
Downing Strategic Micro-Cap Investment Trust (LON:DSM) is in wind down and is to start returning cash to shareholders in the near future. Below is an extract from the announcement by Downing Strategic Micro-Cap Investment Trust (LON:DSM) released on 2nd February.
Indicative returns for Shareholders and estimated timescales
In the absence of unforeseen circumstances and subject to the market conditions, the Board, in consultation with the Investment Manager, is currently estimating that the Managed Wind-Down could be completed within 2 years. Further, the Board believes, in consultation with the Investment Manager, that within the first six months of 2024 up to, or exceeding, 50 per cent. of the Company’s NAV could be returned to Shareholders in cash (assuming current bids for certain of the Company’s investments complete by then) with more value remaining in the NAV of the residual portfolio to be realised through the process of complete wind-down.
I haven't caught up with the comments today...I wonder if we're all jollier?
I've got a hypothesis: The angst and bickering goes up when prices go up and becomes particularly so as things get frothy. I'm thinking back to prior times when we all (or some inc me) get a bit uppity. Whereas when we are wrapped in a miserable bearish fug the urge to beef is lower?
A longitudinal behavioural study for someone :)
I'd hazard a guess that the feeling of missing out or not doing as well as someone else (often people more vocal when going well for them) turns the temperature up. Or I may be speaking nonsense
Bloomsbury Publishing (LON:BMY)
As this is one of my largest holdings I thought that I would throw my tuppence worth into the mix and re-post my earlier views, off course I could be wrong and end up with the proverbial egg on my face. Also I am undoubtedly biased.
"Morning Abtan
I hold Bloomsbury. It is a top 5 holding in a relatively concentrated portfolio of 27 UK small caps.
My view is that the company is likely to issue a further ahead update prior to the release of its prelims in May due the strength of its fantasy and science fiction book list . I posted my reasons for this on 10th January, see below.
Just my view and somewhat speculative. The company also has £39m of cash looking for a home.
"Morning Paul
What a gargantuan effort. Very well done.
I hold a number of the shares mentioned; Volex (LON:VLX) ME International (LON:MEGP) Bloomsbury Publishing (LON:BMY) Porvair (LON:PRV) and will explore the others in your selection for possible investment.
Volex (LON:VLX) and Bloomsbury Publishing (LON:BMY) are in my top three and I would not be surprised to see a further ahead statement from the latter before the finals in May. Reasons:
Further down the line the Harry Potter books are being made into a television series by Warner Bros Discovery.
Just my thoughts and I am often wrong.
All the best"
Great article by John Authers today about passive investing , indexing , the rise of the magnificent 7 , and the NO return of active managers.
Another opinion about the US markets worth reading.
Agreed, a very interesting article and I'm not entirely sure how worried one should be by it ! Although he has to produce a 'piece' every day so a fair bit of his work is contrived, he does come out with some good stuff IMO.
I haven't seen any commentary on DS Smith (LON:SMDS) and the Mondi merger proposal. Have I missed it?
Bought DS Smith last week having read a Roland piece on solid Companies providing decent yielding dividends. (circa 5% for DS Smith)
DS Smith (LON:SMDS) and Mondi (LON:MNDI)
Not seen much commentary yet but will post if I do - as neither are small caps (both in FTSE100) Roland's article is the best place to post: https://www.stockopedia.com/co...
DS Smith (LON:SMDS) At this point there is no proposal, just a discussion between the two companies.
Does anyone know what the forecasts are for Avingtrans (LON:AVG) ? Stocko has them at c2p FY24, when Paul last reviewed in June i think they were 24p. Looking at the broker forecast graphic they collapsed somewhere inbetween. Surely they can't be correct? Thanks
Hi cabarrow
Avingtrans (LON:AVG) is one of my top 3 holdings, the others being Volex (LON:VLX) and Bloomsbury Publishing (LON:BMY)
The reason for the sharp decline in EPS at Avingtrans (LON:AVG) relates to the investment required to scale its medical division (Adaptix and Magnetica) .
According to house broker Cavendish the nascent medical division has net assets of £9.5mn but will record an operating loss of £6.9mn for the year to 31 May 2024 and a further loss £6.4mn the following year. These losses will be covered by forecast annual operating profit £12mn and £13.3mn, respectively, from the group’s energy division.
As a result of this investment Avingtrans (LON:AVG) pre-tax profit is estimated to decline from £9mn to £2.3mn in the new financial year. However assuming Avingtrans (LON:AVG) is successful in commercialising its portable X-ray scanner (adaptix) and portable helium free MRI device (Magnetica) the capital return will be substantial.
The management at Avingtrans (LON:AVG) have proven themselves to be adept and astute and I am happy to remain invested.
For holders of Supreme (LON:SUP) the chart signals look very encouraging.
(I hold)
Is there anyone else who is just a bit queasy about the way we have to spring up and protect people from making ill informed decisions? If people signed an agreement to pay a certain amount per month then should we spend time to show up that they could have paid less. It may seem a bit hard to remind people that they are free to choose, but increasingly it seems that any stupidity is rewarded by recompense. The high interest bond scandal highlighted the fact that people appear to have no internal check on claims that are ludicrous and part with excessive amounts of savings.
There is a clear (and missed) opportunity for the FCA to act as a guardian against fraud, and certainly to punish quickly and with force, the high interest bond sellers should have been a moment for the FCA, without any delay, to come down on them like a ton of bricks. The SEC functions this way, as Elizabeth Holmes and Sam Bankman-Fried can attest, but there should I think be some level of personal responsibility not to be an idiot in making what are your payment or investment decisions. Am I being too hard?
Its about not robbing your customers blind - if one goes in car showroom and the seller come up with an apr of 8% - i would not expect to find out that the apr could have been 4% and the other 4% is the salemans commission. Everyone is aware there is a kickback cut whatever but if the person selling the car makes up whatever rate suits them and pockets the different without telling you its akin to theft imho.
So why is American Express able to advertise a credit card with 113.1 APR. Different products suit different people.
with american express you are dealing directly with the finance company - you know they are trying to get away with as much as they can charge and you know what youa re willing to pay.
when you have just spent 20k on nice new or nearly new shiny car and have agreed the deal on which the garage has earned their bit - in the absence of information to the contrary you would expect that the finance company interest rate is being driven by the finance company and not the saleman wouldnt you ? - you wouldnt expect that the car salesman is just making up then highest figure they think they can get away with to get extra profit on top ? you arent dealing with them you are dealing with the finance company - if they are acting as representative of finance company thats hould obviously be flagged up.
In that reagrd its nowt by shyster practice if thats whats gone on and ity wasnt disclosed.
Now if they said they had sign saying "finance rates quoted are completely at the discretion of the car saleman and rates quoted might be double rates available independently" then that would all be fair above board and transparent.
One of the isues here is that there is probably limited options ref financing cars if you want to deal with company other than recommended finance company. I wouldnt say they have you over a barrel as you could jhust get personal loan - but presumably its defaul option of their one finance provider.
Thanksfully the FCA seem top agree with me on this point - surprised anyone would think its not shady practice.
I guess it's a bit of a challenge. Often car dealerships offer finance for a nice profit and to aid the sale rather than be competitive and treat customers fairly.
So far in my adult life I've owned about 5 cars. I've been fortunate enough to be able to buy 4 of them outright with cash. The 5th one which I also bought from a dealer I financed with a loan from Nationwide. This was back in 1999 and I don't remember the exact interest rate however it certainly wasn't a rip off. For anyone with half decent credit I would recommend doing the same and getting a loan from a bank/building society. If you are buying a car on impulse/urgent need then you are vulnerable to the sales pitch/offer of the car salesman.
When I bought my last car the salesman tried to sell me a finance deal, my response was, why should I do that, why pay you interest.
I appreciate I've been fortunate to be able to buy my cars outright. However bear in mind I always by 2nd hand and I wouldn't go near one of these personal lease/contract finance plans, too much small print.
Agree with this. I have bought many cars myself and have always gone to my bank first to get a personal loan as it’s way cheaper. But if people decide to get a loan via the car seller then that is their decision.
in the real world many peeps arent financially literate and kinda trust the garage is getting the best rate available - or that the rate is waht the rate is for their provider. ok they know the rate they are quoted and could walk away but they probably most certainly think that the rate being charged is fair rate based on their "credit" - not a fictitious maxed out rate the salesman thinks the punter will stomach. Thats simply wrong on every level from honest and integrity - etc.
Hopefully very few lender/seller combos work like this but i think its great if they are getting their comeuppance if they have acted in such a manner
Do they also think that the supermarket they choose to shop at sell all their products cheaper than any where else? What about car insurance, do they take the first quote they get and presume that is the same price from all other insurers?
providing finance is rightly a regulated activity - I think the fca rightly believe there should be transparency whether you are getting a finance quote from finance company or not. Clearly in these examples the salesman is simply making numbers up as they see fit without telling customer this is the case - in all practical purposes they are acting as finance provider setting rates made up out of thin air but not making that clear to the customer who thinks they are dealing with finance company - it’s so easy to see this is not transparent or right . Finance regulated - non regulated shopping has no relevance - who on earth gets a car insurance quote from the car salesman with salesman making up insurance quotes they fancy that doesn’t happen. This point is as basic as salesman not advising they are actually ones giving finance quotes when customer thinks quote is from finance company - if it’s not a direct lie it might as well be.
I couldn't agree more. Anyone who signed an agreement made a decision that the rate offered was acceptable to them, otherwise why sign. What is within that rate is irrelevant. It seems that those who don't shop around and/or read the small print are compensated for their stupidity.
Cerillion (LON:CER) - there's the highest volume with Cerillion today since 2020
We like Cerillion (LON:CER) here at the SCVR
Cerillion (LON:CER) Me too, Louis Hall doing a great job, I've held it since I started and treat it as a benchmark when assessing other similar companies
I know Paul mentioned their last results here fairly recently.Any Alphawave IP (LON:AWE) holders (i hold a small position from the technological advice of someone else not on here - perhaps unwise but i'm wont to a punt or two still) and company and tech experts here?I seem to remember there were a few.
It was up 9% yesterday and up another %4 today after a bit of a dismal run?I was trying to find any small mention of Arm Holdings (NSQ:ARM) in their RNS s and materials.I think they use some ARM chips and say they are partnered (whatever that means), as i was wondering if the current admittedly smaller current interest could be related?Any much more educated opinions?I do see they welcomed Arm's IPO a while back on their website.. for whatever that's worth!!
I held for a while but decided to move on (probably too early) when they breached a financial covenant and whilst successfully negotiating with their bank, from memory only received a 9 month stay of execution plus they also parted with their FD in the recent past . For me the descriptions in the recent RNS of why operating profits have disappeared don’t seem solid and it started to look more and more a jam tomorrow company. Out of interest shorting on this company was running at around 4% but is now down to 1% so that could be a positive going forward,
SUS What is it they actually do?
They have part of their description as "Advantage Finance focuses on the non-prime section". "Discussions with FCA have 'deepened'.” Oh dear, that doesn't sound good.
I have learned through bitter experience never to invest in companies that I consider bottom-feeders.£S&U
Oh dear, that doesn't sound good.
Agreed - being frank i found the previous update was a huge red flag. They confirmed that along with others in the industry they had appointed a "skilled person". To me that prior announcemnet kinda suggested their processes werent fit for purpose before that appointment. That was idle speculation on my part at the time but the fact discussions have deepened suggests to me the processes they had in place were not sufficient to pass review by skilled person. Dont know the exact process of when the skilled person comes it but surely they should have been in position that skilled person would come in and go thats great confirm that to fca and fca would agree. Perhaps others would argue its an unnecessary distraction from making money if not 100% necessary. But i would like to think pukka listed companies like this would be well on the right side of the line. Perhaps one complciation here is that perhaps teh FCA might do nothing forever then go back retrospectively and kick up a fuss - generally though i like the fcat that ten fca are taking these companies to task for shody practices like salemen inventing their own APR's that maximise their bonus (S&U clearly dont do that)
XLM – Xlmedia.
What happened to this? Yesterday on backlog to do, now disappeared...
Good job subscription price has just increased by 25%......
Personally glad they're not wasting time on companies like XLMedia (LON:XLM) - a clear basket case and much prefer they focus on good quality companies.
Looks like you need the help, so will agree.
Hi Bouden54,
I agree that XLMedia (LON:XLM) is a hopeless case , but if a reader wants to know the opinion of the writers on a particular share he should be allowed to.
Yes readers of course readers should be free to request, but would be helpful if they at least give a brief summary of why it might be interesting, not just "can you look at this?"
XLMedia (LON:XLM)
I wouldnt say this sahre is dead and buried - i think they expect profits will turn up in 2024 as things stand - whether we should believe them in that regard ....
There are too many companies to cover. XLMedia (LON:XLM) has been a dog of a company over the years. I’d much rather they cover other companies that are worth the effort than cover this one again.
ofc no one wants to see the subscription rise, but that’s life. It’s up to you whether you think it is worth renewing or not.
Fair enough that no one wants a subscription price increase, but wasn't it only a year or two ago since the last one? I'm still happy to pay of course because the price is still minimal compared to the amounts I spend trading. However, if one were to compare with its main rival which offers US and EU coverage for getting on now to be almost the same price, it may result in a few jumping ship, assuming one does not have the luxury of subscribing to both.
I do find SCVR quite useful, but my main interest is to do my own research and the screens, mini-charts and main charts are essential for that. I wonder if the price increase is to fund extra analysts to expand coverage, which for some is the main draw for subscribing, but for others like myself, it is nice to have, but not end of the world if not.
Well it’s their business so they can charge what ever price they like. I’m sure some will leave but probably not enough that the 25% increase will be detrimental to them.
.
Filtronic
Price up again another 15%
As my old FD used to say “it’s a good problem to have”
Has become my largest holding and feels a bit frothy .
No idea what to do really, sit and hold and let it run .
Or trim
Or sell
In the end sold 7% of my holding as trying to get a bit of cash in the bank for this years other projects .
Looks like it’s going to run further but playing a bit safe with a top slice
I don’t particularly like to see these mad rushes into shares but at least I’m on the right side of the fence .
Same boat with Filtronic (LON:FTC) it was only about 2/3 weeks ago I said I would have to trim as it's now hugely overweight. Spent all morning contemplating, but as a newbie investor 12 years ago, I held a concentrated portfolio with Google/Microsoft/Amazon/Apple and thought I was a genius jumping out with circa 200% gains. Deployed my cash in rubbish jam tomorrow shares. Over this period I'm now about 15% up not including dividends, but if I had sat and done sweet FA, I'd be smoking a fat large cigar...
Always tricky, and it's an answer that one can only know with hindsight.
I am reminded about the advice that Monhish Pabrai gives: if you have a good company that you think will continue to grow for a long time then don't sell when the price is frothy, only when the valuation is egregiously high.
It might be worth considering how much of your portfolio it is. I have a share that is over 10% of my portfolio. I'd probably still keep it if it became 20% of my portfolio, or more.OTOH, you don't want to end up with a situation like James Fisher And Sons (LON:FSJ) which was over 2000p in 2019 and now 288p. Or Creightons (LON:CRL, which went from 4.25p 20 years ago to ~130p in 2021 then back down to 18p. Or ASOS (LON:ASC) from 12p 20 years ago to 7500p in 2018 and now 371p. And so on, and so forth.
Best of luck with whatever you decide.
When it doubles, sell half.
Yes Filtronic (LON:FTC) is a dilema. I have only held for 3 weeks and am up 50%. I think the market is responding to the LEO Satellite potential. Filtronic are operationally geared and I recall that Richard Stavely (Rockwood) in a recent Vox interview thinks there will be a lot of new contract announcements over the next 12 months.
I am with the "when it doubles, sell half and let them run", brigade
“When it doubles sell half”
I’m not a fan of that strategy.
Letting winners run is I believe historically a better strategy
I generally set a max holding level of 20% of my portfolio in one company, so when a value goes over this I tend to slice to bring back to the max holding level
It even works the other way, eg Avingtrans is a max holding but it’s declined to be below my max level , so I’ll actually buy to take back up to a max holding
This seems to work quite well, I had Hargreaves as a max holding then it dropped 20% so I was topping up to max level . It’s now recovered so I’ve sold some this week to take it down to max level .
Ultimateky comes down to knowing your companies inside out and having confidence in them .
I’ even rank my confidence levels every week in a company I have top holding , if a level starts sliding I’ll think about doing something
Eg right now
Avingtans 8/10
Hargreaves 9/10
Equals 7/10
Georgia capital 8/10
Bloomsbury 10/10
Transense 7/10
Filtronic I’m on 8/10 right now
Titon 5/10
Transense 6/10
SDG 6/10
Trifast 4/10 (reduced)
Pennant 5/10 (low on liquidity)
Anyway not sure if anyone else does stuff like that , I’m very much company and “rising tide sector “ focussed as opposed to pure fundamentals which don’t tell the full story .
I like that thinking, to have a mental thought re: how much confidence you have in the company on a weekly basis, might use that.
I too am not a fan of sell half and run half as this used to be a tool I'd deploy sometimes as it was my mother-in-law's modus operandi. That said, she would be selling sending share certs in post etc... so in this day and age I think you need to move with the times. Invariably, any stock that I have cut on a 100% gain I no longer own as I've sold to buy on another idea.
Even Superdry (LON:SDRY) I banked my profits within a week the remainder got sold, the dip on Card Factory (LON:CARD) to 90 was too good not to take it (having missed the first time round).
In terms of positioning, I have:
Filtronic 27%
Pendragon 12%
Shoe 15%
Beeks 10%
Carr 8%
Nexteq 6%
Vietnam Opp Fund 6%
I do mess about with other stocks in the family's ISA's but these are my holdings.
*edit Pendragon (LON:PDG) is an arbitrage position which I expect to have cash back in a few weeks.
I think Shoe Zone (LON:SHOE) may be my coffee can stock, my divis yield around 26%.
Going back on when to sell, I do remember a Minervi tactic to sell going into results, which I'm warming too. I can book the profits, then buy back in if I still like the investment case.
Filtronic (LON:FTC) has momentum for sure - this is being compounded by a resurgence for all things “semi conductor”
But for a perennial disappointer a 2 year fwd rating of close to 40* just looks very rich. I.e it doesn’t just have to meet expectations it needs to smash them! Can it grow into that rating over several years - for sure, but does it represent good value here………definitely not for me. Its track record is way too spotty for me to have confidence in its ability to consistently beat expectations.
But whilst a stock has that momentum it’s a good wave to ride. If I hit one of these I will try and ride the wave but keep raising my mental stop loss upwards - eg falling below 50 day MA etc. It solves the sell half on a double approach which is a little crude for my liking and allows you to ride the momentum until it stops.
Sold a slice at 39. Crazy action which I’m not sure where it has come from. Comfortably happy with this and have some dry powder left for an inevitable drop.
Hi planetx, very interesting! I can really see the value of that provided it doesn’t encourage you to overtrade. Do you keep a record of your opinions to see how they change over time or is it just a quick reflection for the week then bin it? Asking for a friend! ;)
Re £Alu - business is clearly on something on a roll have dumped installing stuff a couple of years ago in favour of a focus on products under 3 divisions. I really like the focus on water management as I think climate change is going to make water a hot topic over the next 10 years, both saving it and managing worsening storms . Their acquisition in this area that has just gone through therefore makes sense and looked OK.
However, as a business I worry about how far/how fast it can grow in size (since it sells through specifiers which are relationship intensive) plus how reliant/optimistic it is on sales to global 'airports' - it has had one very big contract with Hong Kong which distorts results a bit.
Like a lot of smaller building supplies companies I think it would be a tasty morsel for a bigger player like £MSKL (once that company gets it debt back under control) who could 'buy' a lot of niche products and contacts quickly and to them cheaply and then roll into their bigger systems. But if that does not happen, there is a decent divi and some growth prospects as a standalone.
The current situation on building is so bad that it almost must get better in 12-18months AND the political winds will have changed. Labour are promising to build to bulldoze 'NIMBY' opposition and change dysfunctional Planning to build new homes (for its young voter base) and the (aged) conservative base that stopped or slowed it will be less able to resist.
I think building supply companies are interesting as a class (home builder less so since they will be easier to tax and gave a LOT of money to the Conservatives which means Labour will not mind hurting them......even if some of them are now donating (aka bribing!) Labour now instead. Building is very political.
Yes Zipmanpeter I agree that building can be political and I think Alumasc's positioning in water management and other sustainable building products gives it good green credentials, for what that is worth. I like conservatively run serial acquirers so Alumasc's slow but careful accretive acquisition policy combined with organic growth is quite appealing to me. Its Timloc building products section is one of the strongest parts of the company and at a recent presentation, management said they hope to bring all parts of the company up to the same standard. It occurs to me that struggling Titon might make a nice acquisition for Timloc to get to work on.
The article suggests that the Magma money will be converted into cash however my understanding is that Seeing Machines (LON:SEE) gets to choose how it will be converted (Cash or Stock).
Quite a hoo-ha on the SCVR yesterday over Sondrel (Holdings) (LON:SND) , eclipsed the recent Plexus Holdings (LON:POS) speculation? Paul. S is right to say that Sondrel isn't for widows or orphans but having a short life looking forwards I don't care. I didn't sell my holding yesterday although perhaps I should have because when I doubled up this morning I could have quadrupled -up! After all, this about the AIM casino...
News from Waterstones, the bookshops, this morning. They have had problems with the implementation of a new IT system but this part should be a good read across for Bloomsbury Publishing (LON:BMY)
Despite the setback, full-year sales jumped 13% to £452.5m, up from £399.8m, as “footfall and sales continue to recover post pandemic”.
Waterstones said it had benefited from the “increased popularity of both reading and physical bookshops, supported notably by social media and positive press coverage”.
Full Retail Gazette story Waterstones profits plummet after IT trouble - Retail Gazette
I hear that Sarah J. Maas books are selling like hotcakes. Here's an RNS reporting on 1 February:
"Bloomsbury, the leading independent publisher, is
pleased to announce that Sarah J. Maas' latest novel, House of Flame and
Shadow, which was launched on 30 January 2024, has reached Number 1 globally
on Amazon."
BMY has a fwd PE of less than 15. BMY should be storming it when they next report. I hold.
Mark Carter,
Whichever Top Selling Fiction Book List you use the Sarah J. Maas novels feature very strongly. This is from Publishers Weekly and she has 3 in the top 10 and the numbers for her latest publication are very impressive.
Publishers Weekly Bestseller Lists
Bloomsbury usually have a Trading Update in March.
Bloomsbury Publishing (LON:BMY) has just his an all time high today, if it closes above 482p then there should be no resistance level and we could see a decent gain as we move towards earnings. The previous update on December 7th guided Revenue comfortably ahead and profit materially ahead of expectations but this only moved the SP a couple of percent.
An article in the guardian (Https://www.theguardian.com/books/2024/feb/07/house-of-flame-and-shadow-by-sarah-j-maas-races-to-the-top-of-bestseller-chart) yesterday emphasises the success of Sarah J Maas.
At the time of the update on 7th December Sarah J Maas had two titles in the top 20 Amazon chart for a number of weeks. Since the release of the new book, an additional 5 of her historical titles have moved back into the top 20. As of last week she has 8 of the top 20 books in the top 20.
The growth of the fantasy romance novels as a genre is huge and this is being reflected in the number of people buying her older books. Sarah J Mass is contracted for a number of other releases (I think 6) with Bloomsbury.
Of all the stocks I hold, this is my second largest holding and probably the one I have the most conviction about over the next 6-12 months, not expecting fireworks but I think there is another 20% upside in that period.
Bloomsbury Publishing (LON:BMY)
"As of last week she has 8 of the top 20 books in the top 20. "
Remarkably this week it is 9 of the top 20 most sold fiction books on amazon.com.
https://www.amazon.com/charts/...
A
Might use my Bloomsbury Publishing (LON:BMY) shareholder discount of 35% to find out what it’s all about.
We get a discount?
Yes!
“For investors with 1 or more Bloomsbury shares (including if held directly or via a nominee), we offer a special discount of 35% (off RRP) on all books published (print only) by Bloomsbury. To take advantage of this benefit please fill in the form below and we will send you a discount code. You may use this code when you place your order and check out your basket for books on the Bloomsbury websites.”
https://www.bloomsbury-ir.co.u...
Awesome, thanks Indie!
Wow and drat! I’ve already bought this year’s Reed’s Western Almanac!
Good morning all, I too would love to see a breakdown of ALUMASC #ALU,. Also why is XPF up 10%
This may be of interest to anyone holding shares in car finance related stocks....Martin Lewis shares car finance compensation update: ‘I’ve never seen anything like it’ (msn.com)
S&U (LON:SUS)
I might be wrong but do not believe that SUS sold these types of products. My understanding was the FCA investigation is into some car finance lenders that had ‘discretionary commission arrangements’ with brokers. There is no doubt this will impact the sector overall, but I don’t think this is SUS’s practice
You're right: from the Advantage Finance (S&U's subsidiary) website:
"Advantage Finance can confirm that it has never used any form of Discretionary Commission Arrangement and has never allowed the broker to influence the interest rate for any potential customer. Therefore, this action being taken by the FCA does not apply to Advantage Finance and any of its past business."
So they are one of the few lenders totally insulated from the noise around discretionary commissions. There are obviously other pressures, but if you're being optimistic, it must be nice to not have that potential explosion hanging over you.
I emailed Secure Trust Bank (LON:STB) last nigh (I hold) to ask if they were aware of any potential claims regarding this mis-selling issue.
whatmore1951
Isn’t it a MUST to read Company trading updates and Results updates etc?
The answer to your email to Secure Trust Bank (LON:STB) was in their last trading statement. I’ve copied the relevant section from it below. If there’s something in addition to that about potential claims that you have asked then can you please post what it was.
Here’s the relevant bit from the trading update:-
“Regulatory initiatives - Vehicle Finance
We note the FCA's recent announcement about discretionary motor finance
commissions. We operated some discretionary commission arrangements until
2017. From 2014 to 2017, a mid-single digit proportion of our new vehicle
finance loans included such arrangements. The FCA plans to set out its next
steps in Q3 2024, when the implications for the industry should become
clearer. We will provide further information to the market on these
developments as appropriate.
Separately, during H2 2023 we engaged in formal discussions with the FCA about
our collections processes, procedures and policies in Vehicle Finance. This
follows the FCA's review of Borrowers in Financial Difficulty (BiFD) across
the industry. We have engaged external support to assist us with this review
and, where necessary, are enhancing our approach. We currently expect the
review to conclude by the end of H1 2024.”
I posted this last night so I imagine most folk will not have seen it.
Avon Protection (LON:AVON) I spent the afternoon (yesterday) on the capital markets webcast and was quite impressed. I think when they get margins up and ROIC to 17% this could be a very high quality business with significant recurring revenues.
I was very impressed by the moat, the leadership (experienced, intelligent fanatics with big shareholding’s), the product development paths that are open (some R&D will be customer funded!) and the fact that since Jos Slater and Rich Cashin arrived they have replaced 40% of the top 150 leaders in the business to drive significant culture change and a winning approach. Previous management must have been completely asleep at the wheel on how to run productive factories with continuous improvement.
However, having blurted all that out, I can’t determine whether it is cheap enough to buy at the moment or whether it might take off now…
On reflection, they are a year or so into a 2-3 year plan so there is time to watch for progress. I would say that Jos and Rich are not the kind to take prisoners if the ball gets dropped, operationally speaking of course, performance will be improved -end of!!
I too watched the Avon Protection (LON:AVON) CMD, and concur with your views.
Though I have to say I think their target of 5% revenue CAGR looks very cautious to me. They are giving themselves a big cushion there, and are the sort of management who will not want to disappoint. Defence spending is heading upwards globally, and I know at least one British Army unit that wants Team Wendy helmets (I know of another that already has them). The dip yesterday afternoon seemed entirely irrational, so bought into it.
The dip in Avon Protection (LON:AVON) was both rational and irrational in my view.
It was bought heavily into the CMD as certain commentators kept bigging it up. Therefore sell the news kicked in.
It is also pretty pricey on a trailing basis so you have to believe in the execution to be buying at this level. I am still sat somewhat on the fence. I wasn’t going to chase it at 1000p and I missed the dip to 800p which is roughly where I think I am a buyer on balance so will be patient and see if there is a retrace.
I can’t quite believeAvon Protection (LON:AVON) is on a PER of 30+ whereas MS International (LON:MSI) looks like it’s on about 10. Is the former going to outperform the latter by that much??? Seems like a valuation dislocation to me
Well David I own MS International (LON:MSI) also, and one should point out that it is not 100% a defence company. It warrants a slight conglomerate discount. It is ripe to be broken up if the ageing board decide to bale out.
S&U (LON:SUS)
Like, I believe, many investors, I find selling much harder than buying - it's something I'm trying to improve.
I've been a long term fan of S&U - ticks a lot of boxes for my, especially the family / management shareholding. But I sold following the TU on 12 December on the more cautious outlook, but especially on the news of a "more formal interaction" with the FCA and appointment of a skilled person. I had been bitten badly by Jarvis Securities (LON:JIM) in a similar situation - and felt there was little downside in exiting, and I might avoid a deteriorating situation.
That deterioration has come this morning - the interaction has "deepened" to the extent they have had to make changes to processes, albeit "precautionary". Also a profit warning & modest dividend cut. I'm a bit surprised the shares are only down 10%.
One thing that seemed common to Jarvis Securities (LON:JIM) & S&U (LON:SUS) was the proprietorial management &, I suspect, a belief that they were doing things correctly. Maybe without input from more dispassionate observers?
One of the problems with the FCA rule book is that it provides a framework which you interpret as best can, often it’s not easy. Some years ago, I found myself in a difficult situation over the interpretation of a rule so l phoned them. The response was: “We are your regulator. We are not here to advise..”
Pathetic response, no wonder the UK stock market is declining. Sloping shouders a clear sign of power, without responsibility
I had a similar experience. Their response was " You don't ask a policeman how not to break the law" That was so he;lpful.
Yes I work in a different field with similar characteristics. The government response to queries is traditionally "Read the funding rules" but of course, if they were clear then I wouldn't have been asking the Q.
Also it is the government with carries out or commissions the resulting compliance audit so they must know what they are expecting...
I firmly believe the current FCA management believe the Consumer Duty fair vale is different to how it actually reads on paper. So when this management moves on the next bunch will interpret or apply the rules differently. For example back when the FSA was first launched it said it believed general insurance did not need regulating. Wrong certain parts did..... but now we have a regulator with a hammer and nails........
All 8 shares of Simon Thompson's Bargain Shares 2024 get a 5-10% boost in the first few minutes of trading:
Anexo (LON:ANX), Triple Point Energy Transition (LON:TENT), Naked Wines (LON:WINE), Alpha Real Trust (LON:ARTL), Eenergy (LON:EAAS), B.P. Marsh & Partners (LON:BPM), Nexteq (LON:NXQ), Oxford Metrics (LON:OMG).
Just let anyone knows that it's no news, just a once a year shot, so if you are a lucky holder, it might be a good chance to sell these days, specially some of these are very illiquid.
They usually rise before he publishes the tips. I suspect a scandal is not far away.
They usually rise before he publishes the tips. I suspect a scandal is not far away.
That is quite a serious allegation. Do you have any evidence or is it just a feeling? I did some research a couple of years ago around the IC Alpha small company tips. As far as I could tell the increased trading activity on the half dozen or so tips I looked at started during the day the tip was published, almost immediately after the Alpha email notification was sent to subscribers. The uplift in prices tended to be rapid and occured within a few minutes. I couldn't find even the faintest suspicion that the tip had leaked ahead of publication.
I agree with you and that was not very nice accusing a very nice and honest person without any valid reason. He is not even allowed to invest in the stocks he covers; unlike some others.
"They usually rise before he publishes the tips. I suspect a scandal is not far away."
When making these type of comments its worth remembering that Simon Thompson and IC have a lot of reputation at stake. Why would they risk destroying a valuable brand?
Does any one know if there is a way to quickly find stocks which qualify for the most long screens on here?
Is this what you're thinking of? Screen of Screens
Perfect thank you
anyone know how to determine the date each company qualified for the screen
Not sure how useful that would be, its possible but quite tedious.
The screen works as follows: "It picks stocks that are appearing most frequently across all the 'Guru Screens' tracked by Stockopedia - be they quality, value, momentum, growth or income (excluding short-selling strategies). A stock must be appearing on at least four strategies before it can qualify for the Screen of Screens."
On any shares' Stockreport, just below the chart is displayed the number of screens passed. For example, Kenmare Resources (LON:KMR) has a value of 10 (You can display each of these screens by clicking on the left and arrow buttons in the box below this figure). Then go to the the "display" drop down menu button on the Stockreport(next to "add to folio" button, and randomly select an old report date to display. Take a note of the number of screens passed in the report. You are looking for when it first increased to 4 or higher from 3 or lower, 4 or higher is when it would qualify for the screen. Keep looking through the reports, earlier or later as required.
Ta. In the old version it had the date the share qualified for a particular screen. Really found that useful.
Thanks to Paul who reviewed the System1 (LON:SYS1) trading update recently and noted that it is worth a closer look.
…..I do recall that it has been investing in a new Ad platform of some kind for several years, so if that is now paying off, there could be further upside perhaps? Looks interesting, I think it’s worth you taking a closer look.
A +13% System1 (LON:SYS1) share price jump yesterday followed an intriguing Capital Markets video presentation. The CEO made a confident start stating that System 1 are only, “Scratching the surface of the opportunity”.
SYS1 have seen substantial sales growth in the US with their “Test Your Ad” offering which uses facial emotional responses to predict an advert’s effectiveness. New clients wins from the likes of Pfizer, M&S, Tesco, easyJet and Toyota give confidence.
During the presentation they illustrated the operational gearing effect of their 85% GM, such that if sales doubled their EBITDA (and PBT) would quadruple. After a number of false starts and a new internally promoted CEO, it looks like they are in a sweet spot. I hold and doubled my position this morning.
www.youtube.com/watch?v=sAD_IrOkDF4
I'm a big fan of System1 (LON:SYS1) and now held three times through the years (currently hold).
I also work in marketing, so have first hand experience and knowledge of the problem they are trying to solve with Test Your Ad.
They really should rebrand themselves as an AI tool. Because other companies are - its using big data, on emotional responses to ads that they've collected over decades. And then using AI to understand new ad videos. And score them for emotional response. More accurately it is ML/DS, but everything can go under the AI umbrella now it looks like.
The hidden value, IMO, is all the client relationships they are building. This is a product used by senior people - CMOs, VPs, Directors. As they are the ones involved in the production and storyboarding of expensive video campaigns. They are also the purse-holders to spend on consulting works. I wouldn't be surprised if they see a surge in consulting work in the next few years, based on all the new clients they can cross sell consulting to.
I really need to do a proper write-up on System1 when I can, given that I have more intricate knowledge of what their TYA service is solving for and the marketing industry. Will come soon, either on Stocko or Substack.
(I hold in the Boon Fund)
System1 (LON:SYS1)
Hi Boon
It looks fascinating and I must admit that the only thing stopping me investigating further is the seemingly poor cash generation. If this meaningfully swings upwards, as the company has strongly implied it will, I'll take a closer look.
There was an interesting presentation made this week (available on the IMC platform) where a comment was made on competitors in the US.
I know you're in the industry - have you come across any other company that might offer a similar product in the UK?
Thanks
A
abtan,
DragonFly AI is the one closest to what they're doing IMO.
Shutterstock are also offering solutions here (albeit slightly different, in Images not in Videos).
There was one more company, I can't remember the name, in the UK. Part of a much larger MarTech provider. Hmm. It'll come back to be at some point.
The elephant in the room, is if Google develops something. They have visibility on lots of video ads. They know all the responses by consumers to their ads (quant not qual though). They have an incentive to offer a tool to their advertisers, so they make better ads = more ROI for advertisers = more ad spending with Google. And they have lots of $$ and lots of engineers to throw at problems. Maybe Meta might do something too.
System1 (LON:SYS1)
Perfect, thank you very much for sharing your insights.
A
Boon,
That is a really good point about System1 (LON:SYS1) selling itself to senior managers.
I used to be a Sales Director and their Ad Testing would be a great, “foot in the door” to new clients. Because of their huge gross margins and the low variable cost of their automated Ad testing platform Sys1 could afford to offer the 1st Ad test at half price, or even FOC to gain a prestigious new client. If things go well, then high price consultancy would almost certainly follow.
On reflection I recalled an allusion to this strategy in their Capital Markets presentation so I word searched “price” in the automated YouTube text and the CEO hinted at this approach saying….
….”We're actually learning we have more flexibility over price than we originally thought”.
The management team struck me as unusually confident in achieving substantial sales growth. Why else would the CFO finish with a slide “illustrating” that if their sales double, EBITDA would quadruple. Perhaps at last they have cracked their own secret sauce?
Totally - you nailed it on the "foot in the door". And as you probably knew as a Sales Director, the onboarding process of new vendors is so painful in many large corporates, that when there is a need for consultancy/external work, the first port of call is always existing suppliers, rather than try to onboard a new supplier.
I would take the bullishness in their slides with a grain of salt. After all, it wasn't too long ago that System1 (LON:SYS1) were saying something about being a billion dollar market cap company...
Granted, it is a different CEO now. But culture is harder to change. This is after a company in the marketing sector after all. And marketers are experts at spin...
I decided to bank some gains on Fri and sold about half.
(I hold in the Boon Fund)
Boon,
System1 (LON:SYS1) could yet become a $1B company, but not under the leadership of the original CEO/Founder.. I see that he has now been side-lined and a more scaleable approach is being adopted. The CEO change and exceptional GM% reminds me of the Games Workshop (LON:GAW) scenario, (I hold}.
I topped up on Friday so I may have brought some of your top sliced SYS1 holding. At the end of the day, we both think SYS1 has got growth potential but it’s a difference in perspective that makes a market.
Thanks for sharing yours. Ian
Thanks iwright7 - System1 (LON:SYS1). The Capital Markets presentation is interesting and provides lots of information. I've been watching them for a while, and remember the old BrainJuicer business that promised a lot but never really went anywhere. I don't think it scaled particularly well, relying on a lot of consultancy. The business seems much better structured and managed now and is obviously growing strongly. It appears they have dealt with the scalability issue too. What's particularly striking is the potential for growth, they have a $20bn addressable market. Ad Pre-testing and Innovation seem to be the niches they are most competitive in, which represents $14bn on its own. Current revenue £26.2m (TTM figure taken from Stocko) so they have a fraction of a percent of market share (0 .23%). If they gain 5% of Pre-Testing and Innovation that is still 21 times up from where they are now. I think they'll do better than that given the US market penetration they have. I have some Silver Bullet Data Services (LON:SBDS) but decided to buy a small quantity of this after watching the link you posted.
Good luck with your new position. Despite a high PE you (we) sometimes have to pay front up for growth.
Barclays (LON:BARC) agrees to buy Tesco (LON:TSCO) 's retail bank for £600m, representing a 37.5% discount to net tangible assets.
https://www.londonstockexchang...
Implying perhaps that maybe there's NOT actually too much upside in the UK's other retail banks either?
But that 37.5% discount to NTA is not including the Tesco Bank name. Which it looks like they are licensing separately in an initial 10 year agreement.
So if you think that a brand name has some value/equity, then this benchmark transaction suggests that similar banks should be valued at better than 37.5% discount to NTA.
eg Metro Bank Holdings (LON:MTRO) at 70% discount to NTA probably way undervalued.
Good morning both Pauls, absolutely agree with Paul H, Paul S is my go to first thing every morning. Thank you for all the time and effort you put in. As a newbie, your selflessness (Bit of a mouthful) in helping people like me navigate the minefield, that is stocks and shares, is invaluable. Keep up the good work.
Morning to all the writers and editors. A superb range of coverage this week and the refinements to the presentation really do work. Additionally. I like the way you join in the discussion board itself, Paul, and don’t stay aloof during the day. Please accept my appreciation and best wishes for a relaxing weekend.
My morning smallcap tweet: Car lender S&U collides with economic reality
S&U (LON:SUS) Renalytix (LON:RENX) Hemogenyx Pharmaceuticals (LON:HEMO), Kinovo (LON:KINO)
◄S&U (SUS)► warns FY-Jan pretax 10% to 15% below consensus expectations of c.£38m. Loan advances motor finance 7% lower as more applications rejected. Uptick in lending activity in secured property bridging business. Increased bad debt provision. Does not mention the Martin Lewis programme this week encouraing more PCP mis-selling claims. [SP=2060 Cap=250m]
◄Renalytix (RENX)► US Medicare and Medicaid draft Local Coverage Determination for KidneyIntelX and kidneyintelX.dkd testing. It specifies when the tests are reasonable and necessary. [SP=10 Cap=26m]
◄Hemogenyx Pharmaceuticals (HEMO)► FDA has lifted the clinical hold on the Investigational New Drug application for HEMO-CAR-T for the treatment of acute myeloid leukemia. [SP=4 Cap=47m]
In line: KINO
Morning Paul
Just wanted to quickly say a MASSIVE thanks for all your hard work, superb daily commentaries & marvellous weekly podcasts
To me, you do a terrific job and go way beyond what anyone would humanly expect.
You're a top bloke.
Thank you Paul, that's a nice way to start the day! :-)
Absolutely agree Paul H. I've been meaning to find the right moment to say this but not only is his analysis fantastic but It's clear to anyone who is a regular reader of the daily SCVR and listener of the weekly podcast, is that Paul S us passionate about what he does, he cares about his work, he is genuine, he is witty, he is personable and he is not afraid to admit he was wrong. I'm sure I've missed out other traits, but in essence all of those things make him unique in the world of stock commentators/analysts in my eyes. Many people will say well he does what he's paid for, but no, he goes above and beyond. He continues to work and provide his thoughts when he's on holiday and on the weekend. Bris.
Thanks Bristolian! Good grief, what's happened this morning, is it something in the water causing an outbreak of positive sentiments?! Whatever it is, I like it :-)
“Just wanted to quickly say a MASSIVE thanks for all your hard work, superb daily commentaries & marvellous weekly podcasts
To me, you do a terrific job and go way beyond what anyone would humanly expect.
You're a top bloke.”
I don’t know Paul personally so cannot vouch for him being a top bloke, although I am sure he is. I agree that he does provide an exceptional service to the Stocko reader like myself and he is my go to morning read.
He is however prone to a “hissy fit” every now and then where his comments are less considered as in his criticism regarding the Good Energy (LON:GOOD) posts yesterday. I initiated the comment regarding selling on a stop loss (manual) following the reversal in sp momentum towards the 120MA. The use of a manual stop loss, the importance of momentum and the use of the 120MA as an inflexion point are all learnings from Stockopedia.
I still believe my post was a valuable addition to yesterday’s discussion but the fact that so much criticism arose from it makes me less inclined to want to contribute in the future.
He is however prone to a “hissy fit” every now and then
So what ? are we not allowed to have hissy fits nowadays ? - when Paul throw a hissy fit he tends to get challenged - as does everyone on here who throws a hissy fit around here . Facts are hissy fits are a fact of life end of.
I still believe my post was a valuable addition to yesterday’s discussion but the fact that so much criticism arose from it makes me less inclined to want to contribute in the future.
Please carry on with your posts in the manner you have done - certain topics will polarise opinion end of - 70% of peeps might agree with you but 30% of peeps will say you are talking nonsense - that doesnt mean your comments are not valuable and appreciated - in bulletin boards everyone needs to suck up the negative press unfortunately.
Paul raised a valid point that unless someone is adding something ref news or similar the bulletin board simply wouldnt work if everyone was posting sold out stop loss every time they have traded with adding something useful. The good news is that whilst there is a small element of that that goes in here its pretty rare so i dont think its a bit biggie (imho) thats not to say Paul is wrong for asking for useful comment - albeit perhaps the way the point was raised might niot have been appreciated by some.
To be fair I think your original post just said "stop loss triggered. Sold on sentiment" and didn't expand on the 120MA, importance of momentum (etc.) I definitely don't think you should feel less inclined to contribute - rather feel encouraged to share more context / learnings so other readers gain more insight.
Hello SCI20, I was interested in your comment yesterday 'sold on sentiment'. As a stop-loss was triggered, selling would seem to be a hard-headed, predetermined decision of the type we're encouraged to make as the way of winners. With the technical analysis you've described here, it would seem even more to be unsentimental. If you don't mind me asking, where did the sentiment come in? Interested in your thought process, if you're happy to share.
Hi Indie, my equity funds (largely UK) are held within my pension and therefore I have adopted a buy and hold strategy. The never ending bear market and geopolitical events have resulted in far too many of these holdings showing losses of 25% to 60%. I have pivoted towards a more agile approach with a keen eye on momentum and less attachment to the investment and a more pragmatic approach to price.
I do not use automatic stop losses but review my holding if the price falls by 20%. At this juncture I review the story behind the stock and the prevailing sentiment. With the news of Labour rowing back on its Green Energy policy and the general realisation that green energy is not a short or even medium term solution I decided to sell Good Energy. I feel positive about this decision as I have acted dispassionately and decisively. The price may well bounce back but I have the reassurance that a 20% loss does not become a 50% loss.
Thanks, SCI20, most interesting and helpful.
Yesterday I just flagged a series of pointless reader comments, briefly announcing their trades, or stops being hit, with no supporting detail or insights, as clutter which wastes everyone's time. I totally stand by that valid comment, which needed to be said as a reminder, in order to preserve the quality of the comments section.
Please don't take offence or misinterpret a valid criticism, just take it on board. Before posting anything, I always ask myself, "are other people going to find this useful & interesting?". If the answer is no, then (usually!) I hit delete.
Anyway, I've made my point, and won't say any more on this.
Regards, Paul.
It was your opinion that it was pointless. It was my opinion that highlighting negative momentum was a very valid one to make. Since I pay for the privilege of accessing the SCVR I am imo entitled to my view.
What I want to know is how on earth does he get through such a volume of work?
Hopefully just strong coffee and alcohol!
I think yes to the alcohol!