Small Cap Value Report (Fri 9 June 2023) - MEGP, MIDW, SHOE, NWF, COST, SFOR, WAND

Good morning from Paul!
Today's report is now finished.
I was very impressed with Megan's webinar earlier this week. If you missed it, this is well worth a listen over the weekend - some useful insights, with high quality stocks tending to perform better in market downturns. (Note: it's silent at the start, then starts properly at about 3m 25s)
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk.
Quick Comments
To round off the week -
S4 Capital (LON:SFOR) - down 5% to 123p (£708m) - AGM TU - Paul - RED
Sir Martin Sorrell’s rapidly growing digital marketing group. I reviewed it here on 11 May 2023, concluding that the weak, greared balance sheet, and huge adjustments to turn a statutory loss into a profit, put me off.
It’s difficult to work out what this waffly update, full of buzzwords, is actually saying today. The market doesn’t like it anyway, with shares down 5%.
Paul’s opinion - same as last time - the accounts look horrible, and the style of today’s update puts me off further. I wouldn’t bet against Sir Martin, given his amazing track record.
Costain (LON:COST) - up 3% to 48.7p (£134m) - Update re A66 Project - Paul - AMBER
I’ve read this 3 times, and am still struggling. Costain’s involvement in a road project, the A66, is coming to an end, but no details are provided as to why. It denies that this will hit the order book, as press reports have apparently claimed. The most important bit says -
The Board remains confident of delivering full year results in line with its expectations.
Paul’s opinion - not a sector I invest in (low margin contractors). But the value metrics are looking superb now, a fwd PER of only 4.3x, 5% dividend yield, and a strong balance sheet, with shares at a discount to NTAV. See SCVR from 11 May 2023 for a review, where I concluded positively about this share. It’s dropped about 20% on the rumours/news about this problem project, so might be worth a fresh look, if you do invest in this sector. Although clearly the A66 news is bound to unsettle investors, as often we see that an initial problem can escalate into a series of profit warnings. For that reason, I think it’s best if I play it safe and await developments, so AMBER for now.
WANdisco (LON:WAND) - suspended - update - Paul (I hold) - RED
This jam tomorrow company turned out to be a giant fraud, at least the order book & supposed contract wins were. So I've mentally written off my investment here. However, an update today gives a glimmer of hope - shares should come back from suspension on 30 June - likely to gap down maybe 80-90%, I imagine. A little more detail on the false orders, which were with 8 supposed customers. Trying to raise $30m, which looks like it's been well supported by shareholders, although no indication on what price new money will be raised at. Change of name planned, probably a good idea in the circumstances!
Backlog items -
Midwich (LON:MIDW)
Up 3% to 465p yesterday
Market cap £480m (based on 103.3m enlarged share capital)
This growing distributor of audio-visual equipment caught my eye here on 9 May 2023, with an in line, confident AGM statement combined with quite modest valuation, drew me to view the share positively at 446p.
Earlier this week it announced a £50m placing, to fund acquisitions and reduce debt (rather confusingly worded, I felt).
The placing has now been done, at 425p, which is only a 5.6% discount. This has been well received by the market, with the price closing yesterday up 3% to 465p, a healthy premium for those who participated in the placing, and also a small PrimaryBid retail offer, which raised £1.25m.
Paul’s opinion - I’m mentioning this fundraise because it says to me that decent companies which are raising money for sensible expansion plans, not to avoid bankruptcy, are able to get a deal done on sensible terms. A 5.6% discount is fine, if the money is going to be used for good quality, reasonably priced acquisitions. Midwich says there are 6 more possible acquisitions currently in due diligence (i.e. detailed, confidential inspection of the business & accounts, where an outline deal has already been informally agreed).
The main acquisition target, is a Canadian company called SFM. The price being paid is 7x adj EBIT (operating profit) for 2022, but with 2023 revenues expected to be “materially ahead”.
This sounds impressive -
The Acquisition and M&A Pipeline combined is expected to be materially earnings accretive in the first full year of ownership, including the impact of the Fundraise and before synergies
There’s obviously execution risk with doing lots of acquisitions, but as far as I can tell, Midwich seems to be growing strongly with an acquisitive strategy that doesn’t seem to involve excessive dilution, relative to the growth being achieved. It had 80m shares in issue in 2017, which will have risen to 103.3m after this latest fund raise. Yet EPS has more than doubled over that period - demonstrating that (so far anyway) the acquisitions have added value. Dilution is good, if it’s used to buy good companies at a lower rating than the acquirer's own shares, and where there are synergies on top of that.
Midwich is looking like an increasingly interesting company, which might be worth you taking a closer look at. I’ve not done any detailed work on it, as always, because I have to cover hundreds of companies here. Potentially interesting is my conclusion, so I’ll remain GREEN on it.
ME International (LON:MEGP)
158p
Market cap £599m
We’ve been raving here about MEGP shares for some time. Checking the archive, I did a thorough review of the FY 10/2022 results here on 1 March 2023, concluding that I liked everything about this share, giving it a firm thumbs up.
Previously on 7 June 2022, I concluded that it was a highly attractive buying opportunity at 70.6p. It’s more than doubled since then - very impressive in a nasty bear market for small caps.
Management tried to take it private in Jan 2022 for 75p cash per share, which was declined by outside shareholders, but it was a clear message that management saw good times ahead.
That’s the background, so I’m starting off with a very positive impression of this share. Let’s see if that stands up to scrutiny of the latest update for H1, which was published a week ago, on 1 June 2023.
ME Group International plc (LON: MEGP), the instant-service equipment group, announces an update on the Group's trading for the six months ended 30 April 2023 (the "Period").
Company’s headline says -
Strong H1 performance across all business areas and operating markets, with increased full year outlook for 2023
The Company is pleased to announce that during the Period, Group revenue was up by more than 24% and profit before tax was up by more than 35% compared with the six months ended 31 April 2022 ("H1 2022"), driven by a strong performance across all of the Group's key business areas and its 19 operating markets.
Photobooths - revenue up 25%. Strong demand for photo ID. Focusing R&D on photobooth innovation, including biometrics - “should be the norm by 2025”. Anti-spoofing patented.
Laundry - “continued to perform very strongly”, revenue up 36%. Rolling out a new App.
Other smaller divisions also trading well.
Outlook - nice clear guidance here for FY 10/2023 -
As a consequence of this strong trading performance in H1 2023, the Board is pleased to increase its outlook for the current financial year, ahead of previous expectations, with revenue between £300 million and £320 million, EBITDA between £100 million and £110 million and profit before tax between £64 million and £67 million.
This compares favourably with the guidance provided on 1 March 2023, which said -
* The Group's compiled analysts' consensus forecast for the financial year ended 31 October 2023 shows revenue of £284.8m, EBITDA of £91.1m and profit before tax of £58.5m. [1 March 2023 RNS]
That’s a 12% increase in PBT guidance, if we take the mid-point of the new range of £64-67m.
Broker updates - many thanks to both Canaccord and Finncap, for publishing notes via Research Tree, it’s so helpful. Canaccord seems to have anticipated strong performance, and already had £62m adj PBT pencilled in, but has raised that by £2.0m to £64.0m, noting that there’s a good chance actual results could come in ahead of this new forecast.
Equivalent EPS (adj and diluted) is raised from 12.7p to 13.1p.
At 158p per share, that’s a PER of 12.1x, which looks good value still, despite the share price having doubled in the last year.
Paul’s opinion - remains very positive, so I’m happy to maintain my thumbs up/GREEN view of this share. As always, the one thing I cannot do is predict the future. So you have to do the deeper research, to form a view on what the future might hold. All I do is review the facts, figures and forecasts as they are today. On that basis, this share looks excellent to me.
I particularly like that this share is no longer a one trick pony of photobooths. The laundry business is significant too, and the other growth areas sound promising, including the food/juice vending machines. As it’s operated booths for so many years, there must be immense experience & know-how within MEGP, which is hidden value I think.
Downside risks? I suppose the main risk is if some technical development makes photobooths redundant. People have been worrying about that for many years, but MEGP seems to have successfully innovated, and stayed ahead of the curve. The biometric comments in today’s update particularly intrigues me. If any readers have looked into this in more detail, then please do share your views in the comments. As always, my stuff is just an introductory review, not an in depth analysis of the products, markets, or competition.
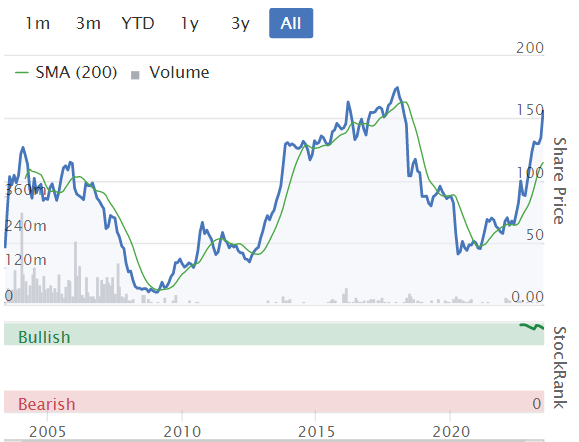
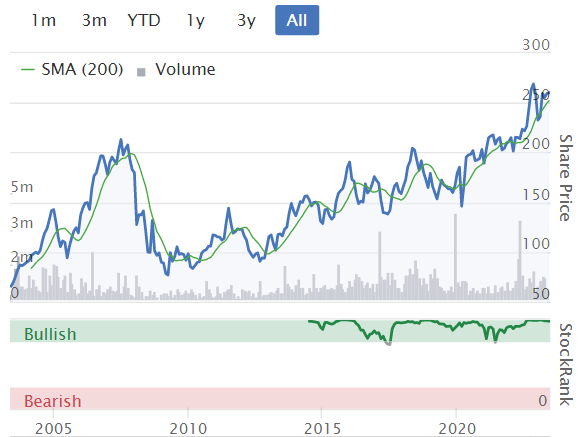
MEGP (formerly Photo-Me) shares have been quite a rollercoaster in the past -
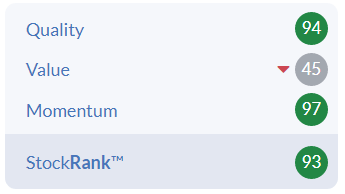
A very strong StockRank further encourages me -
Today's News
Shoe Zone (LON:SHOE)
Up 11% to 233p (at 09:31)
Market cap £108m
This cheap shoes retailer had been a star performer, but shares wobbled on publication of disappointing interim results & only in line FY 9/2023 expectations, which I reviewed here on 16 May 2023.
I think the share price had risen to c.250p based on expectations from investors that the company would continue a run of beating market expectations, hence why in line wasn’t really good enough to support a continuing rising share price.
Investors who stuck with it have been rewarded today, with an ahead of expectations update -
Shoe Zone is pleased to announce that since the publication of its Interim results on 16 May 2023, trading has exceeded expectations due to particularly strong recent trading through May and early June. This is a combination of strong early demand for summer products and lower container rates contributing to improved margins.
As a result, the Company now expects adjusted1 profit before tax for the financial year ending 2 October 2023 to be not less than £10.5m.
1 Adjusted to exclude the profit on the sale of freehold property and foreign exchange revaluations.
I can’t find what previous guidance from SHOE was, so am referring to a note from Zeus (many thanks) dated 16 May 2023. This shows underlying PBT of £8.5m for FY 10/2023. So today’s update looks to be a c.24% increase in profit expectations - excellent news!
By my calculations that would be EPS of 16.8p (previously 13.5p).
Paul’s opinion - all is forgiven! This is a much better performance, than was previously indicated, and it’s good to see better margins coming through from lower container freight costs.
Based on the much improved profit outlook, I’m happy to go back to GREEN now (previously AMBER after the disappointing outlook comments last time).
Expect a decent share price rise today (I haven't looked at the live price yet!).
EDIT: it's up 11% at 09:31, which looks justified to me.
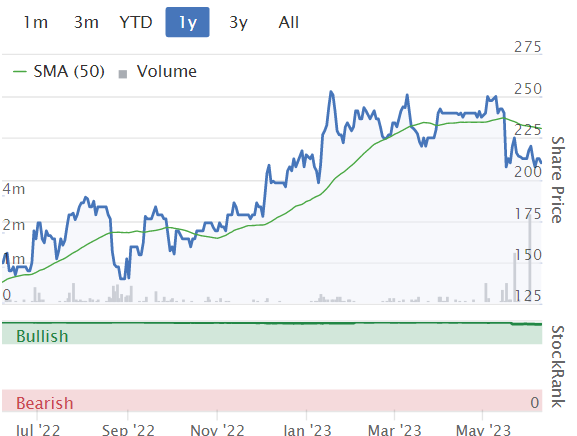
Also note that the StockRank is jammed on maximum!
NWF (LON:NWF)
Up 7% to 275p
Market cap £136m
Trading Update & Renewed Banking facilities
NWF Group plc ('NWF' the 'Company' or the 'Group'), the specialist distributor of fuel, food and feed across the UK, today provides a trading update for the year ended 31 May 2023 ("FY23"), together with details of its renewed banking facilities.
Reading through my previous notes here, we’ve been positive (green) on NWF for some time, noting in the SCVR for 1 Feb 2023 that it looked like a beat against expectations was coming, given record H1 (Nov 2022) figures, and a very confident outlook.
Sure enough, the next update on 9 Mar 2023 was ”significantly ahead”, with profit guidance raised from £12.3m to £17.5m.
My only worry is whether the booming profits are sustainable, given that competitor Wynnstay (LON:WYN) had reported a bumper one-off boom year, due to the knock-on effects of the energy crisis, causing selling prices to rise substantially, but maybe not sustainably?
Looking at today’s update, things are still looking very good - it’s another guidance raise -
As set out in the trading update of 9 March 2023, the Group delivered strong performances from all businesses in the first half. Pleasingly, this positive momentum has been sustained through the second half and consequently, FY23 headline profit before tax is now anticipated to be ahead of the current market expectation1 and in excess of £19.0 million2.
1. Company compiled consensus headline PBT of £17.5 million; information for investors including analyst consensus forecasts, can be found on the Group's website at www.nwf.co.uk
2. Stated before amortisation of acquired intangibles and the net finance cost of the Group's defined benefit scheme
Acquisitions - Sweetfuels (bought for £10m) is performing strongly. More acquisitions are planned, the strategy being to consolidate a fragmented market - I like that approach, and it should be quite low risk, in that management will know what they’re buying (i.e. not branching out into unknown areas).
Bank facilities renewed -
The Group has completed the renewal of its banking facilities with NatWest Group for a three year term on competitive rates, with an option to extend by two years. The facilities of £61 million comprise an invoice discounting facility of £50 million, a revolving credit facility of £10 million and an overdraft of £1 million, with a further £20 million accordion available to support the development strategy of the Group.
Net cash was £1.2m at the last accounts (interims at 30 Nov 2022).
Today we’re told net cash at 31 May 2023 year-end date is higher than expected, but not provided with a number, which I would have liked -
Net cash at the year-end is also higher than previous expectations as a result of the stronger trading result, ongoing disciplined cash management across the Group and some positive working capital movements.
Balance sheet - I’ve looked at the last balance sheet, and it’s OK. Although it reports net cash on the last balance sheet date, both receivables and payables within working capital are large (both over £100m), so I imagine there would be quite large intra-month swings in cash/debt, depending on when suppliers are paid, and also the timing of customers paying invoices. Hence why borrowing facilities would be needed.
What we really need is the average daily net cash/debt figure. All companies should report that figure as best practice.
Note there’s a pension deficit of £10.5m, so you would need to check that out properly, I haven’t got time right now, as a webinar is about to start!
Paul’s opinion - based on another ahead of expectations update today, and a still-reasonable valuation, I maintain my positive view of NWF shares. But as usual, I’ve no idea what will happen in the future, in particular whether the big jump in earnings over the last 2 years is sustainable, or a boost from the energy crisis? That’s the key area to research if you’re digging deeper on this share.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

28 comments
My son has worked for Midwich for 8 years. They are busy and are a very forward thinking company and look after their workforce well. Always a good sign for me. Save on a lot of recruitment costs
Personally I am not convinced. They are moving away from specialist to more of a broadstream distributor- but not of the size of Ingram for example. I do buy from AV distis, but not Midwich.
I always enjoy listening to your podcast Paul, especially your market musings . Did not really appreciate your comment though that mortgage rates should be lower and saving rates reduced, as savers can afford it . Well tell that to the many retired people who rely on savings income and have been subsidising bloody mortgage rates since 2008 !!!
Hi Caper4,
Yes that's a fair point re interest rates, and savers having subsidised borrowers for the last 15 years, point taken!
I suppose my main criticism is the speed of interest rate rises. Also the randomness of fixed rates ending on mortgages, which will allow some people to ride out this period, when others will be thrown into crisis.
Regards, Paul.
The mystery share for this weekend's podcast is RWS Holdings (LON:RWS)
The mystery share in this weekend's podcast is RWS Holdings (LON:RWS)
Costain (LON:COST)
I would do a quick search on "Costain" and "National Highways" what used to be Highways Agency/Highways England. This obviously gets all yesterday's articles, but if you go back a little bit as well gives a wider story.
Firstly, the A66 is currently in Development Consent Order (Planning Approval) stage, so due to start next year subject to Secretary of State approval. Costain is one of four Contractors involved, so there is also Balfour Beatty (LON:BBY) , Kier (LON:KIE) and Keltbray stated as winning work packages. So it is part of the £1.3bn not all of it, then spread over say 3-5 years and think typical construction margins. So is probably a small hit to this years revenue and profit as it is early stages right now and loss of future workbook for 2024-28.
I think that the bigger part is there was a similar announcement in May regarding the cancellation of the M62 central barrier project, and from memory I think that the top two managers of the Highways Division left the company at the same time.
Obviously Highways is one branch of Costain, so there are other parts of the business that will continue through this, I don't know the percentages of turnover/margin that come out of Highways.
I do not hold.
Tommy
In the late update yesterday by Costain (LON:COST) they confirmed:
"this project was included in our preferred bidder book and therefore this decision has no impact on the Group's order book"
Order book is defined as: revenue from contracts which are partially or fully unsatisfied and probable revenue from water frameworks included at allocated volume.
Costain reports on future visibility in three ways.
Secured Revenues for FY[x]: these are contracts where there is locked-in agreement for the works to be done in the financial year. I take this as more or less in the bank.
Order Book: contracts have been signed, but typically as projects are multi-year, timing of revenue could be delayed. But it is past the bidding stage. Of course, projects could be cancelled.
Preferred Bidder: this is the stage before Order Book. Costain is selected for the project (or part of the consortium), and detailed negotiations are started on final scope, pricing, specifications, delivery, etc. At this stage there is also no "competition", but the wet ink is not on the contracts yet either.
Looks like the A66 project fell in the last category.
At 31 Dec 2022, the status of all three were >£1bn Secured Revenue FY23, £2.8bn Order Book, £1.6bn Preferred Bidder Book.
------------
Now, this update also included the statement that the order book is broadly unchanged at £2.8bn from Dec22. On the surface, worrying. As it suggests that future growth might plateau, given the order book has not grown.
BUT.... digging in the FY report, Costain states that not all the high-margin, high-growth consultancy work can be reflected in this framework (Secured>OrderBook>Preferred) so we are not given visibility into whether this segment of the business is growing in H1.
FY results confirmed to still be in line with expectations though.
Therefore, I am puzzled why the shares are still down c10%. That gap should close. I would have bought more today but I'm maxed out on my current position size here, given gains since buying.
(I hold in the Boon Fund)
WANdisco (LON:WAND) wasn't a particularly flattering name even before their negligence / fraud was known about.
Anyway on a quiet Friday afternoon I thought it would be a good opportunity to thank you Paul, Graham and occasionally Roland for the views on various companies - it has been very good recently. I also watched a few of Eds videos recently on the Stockopedia youtube site, which are well worth a watch for anyone that hasnt seen them.
Thanks for sharing Megan's webinar, just finished listening and thought it was very good. I have updated my screens, which has given some shares to have a further look at.
Thanks for watching - glad you enjoyed it!
Very annoying that Safestay (LON:SSTY) decides to release FY results at 11am. And on a Friday too. One suspects some bad news buried?
Initial skim seems to be OK. And looks like a profit upgrade for FY23 coming, as first four months of trading already "significantly ahead of budget" and management outlook for the rest of the year is positive on all the key trading indicators.
(i hold in the Boon Fund)
Safestay (LON:SSTY) i assumed 11am results rather than 7am was more suited to their target customer and latest check out time.
the outlook commentary seems very positive and confident to increase prices and occupancy in a growing market which will allow debt to fall further.
dusc. i hold and have bgt more this morning
Safestay (LON:SSTY) (I hold)
Thanks Boon, I completely missed that!
Here are some thoughts that I jotted down as I was going through today's report.
I view all of the below as positives.
"from 1 January 2023, we have allocated 3% of total revenues in order to maintain these high standards in our hostels."
----
By my own calculations Net Assets currently = £19.1m vs the current market cap of £19.2m
This includes all Cash, Debt and Property, including the Elephant and Castle hostel where there is an option to buy back the property.
A possible risk here could be that some of the valuations are from 2021, though it's not concerning enough to make me want to sell.
---
I've modelled out various occupancy rates (73%-79% vs 77.3% in 2019) and bed rates (£23.70 - £24.00 vs £23.62 in 2022) for 2023 and I believe cash generation should come in somewhere between £2.3m and £3.6m.
Note that this included a £1m/year CBILs payment that will conclude in 3 years.
Based on this - and the material asset-backing - the current £19m market cap seems too low.
Happy holder for now.
A
hi JASVFS I'm also a holder of Steppe Cement (LON:STCM), I'll share my off the cuff thoughts
- impressed with their cost controls, given local inflation
- this combined with sensible capex gives a good impression of management
- there are no mention of future divis, or of intended divi policy, I wonder if they may cut the divi to reduce debt given the 20% interest rate
- it remains super cheap but probably deservedly so given the political instability, increasing cost of debt, potential for a deterioration in $ exchange rate, and cyclicality
this is only a very small holding for me and I'll continue to hold for now.
Shoe Zone (LON:SHOE) rather surprising update so soon after the interims. I do find a bit conflicting. HY only £1.5m and update at least £10.5m. Last year was £3.1m and at least £8.5m, trading update end of June.
I did sell over half my shares after the interims at around todays level.
I held Shoe Zone throughout, even the interims I pointed out that there would be a lot of selling given the gains that holders have made. What I thought was ignored by sellers was the interim update effectively told holders that the news should only get better as prices were coming down and they were actively looking at ways to be more efficient throughout their estates. What with a large family holding and continuos ways of improving EPS via share buybacks etc, this is almost starting to look like a coffee can share.
Nice ahead of expectations update from NWF (LON:NWF) cash and profit ahead of expectations.
Morning carvalio!
Thanks for flagging NWF (LON:NWF) ahead of expectations, I'll look at that one next, as we like to prioritise companies reporting ahead or below expectations.
Regards, Paul.
I hold NWF (LON:NWF) but it's another frustrating one when it comes to broker research. Nothing recent on Research Tree, yet the Stockreport says 3 brokers cover it. I do think the market for UK small caps could pretty much get changed overnight by some consistency in broker report availability. Argh!
Thanks for looking into it Paul. Have a good weekend.
Have never understood the attractions of NWF. It operates in three very competitive markets, with margins to match, of which two have long term structural problems.
I used to buy my heating oil from NWF but now choose a local competitor who consistently beat them on price by an appreciable margin and provide an equivalent service.
Perhaps you can indeed make a silk purse out of a sow's ear...
I don't suppose you fancy getting your foot into some wet cement this morning Paul? You were neutral and gave Steppe and Amber on the 14th April. It has/is maintaining dividends and there's lots of capex which should help going forward but with KZT interest rates at 20% their caution on loan rates seems timely! It's not a big holding of ours so no problem if you're busy again, I'll reread their results and try to understand them.
Hi JASVFS,
Sorry I didn't get round to looking at Steppe Cement (LON:STCM) and I'm not sure I could add any value by commenting on it, as mentioned last time, it's a bit of a special situation.
The market clearly doesn't believe the divis are sustainable, which is what an 18.2% forecast yield is telling us. Its track record on divi payments has been very good, so there might be a (risky) opportunity here perhaps?
It's not one I would take on personally, as I don't normally buy anything overseas listed on AIM (apart from Somero Enterprises (LON:SOM) )
Good luck with it!
Regards, Paul.
Good morning Paul, thanks for reviewing ME International (LON:MEGP). I'm a wee bit short of time this morning but a couple of thoughts I can quickly communicate:
I look forward to reading other subscriber comments. [I hold]
TEIN
Thanks Paul and Tein, also worth noting it’s highly cash generative showing net cash of £34M in last set of accounts.
For my small town thoughts on ME International (LON:MEGP) they have installed washing machines / dryers at the local garage, and other than the occasional youth sitting in the largest machine when it is raining, they seem to have a reasonable amount of use when looking when I drive past. The machines different sizes, with the largest able to wash a super-king duvet, which given the local dry cleaner Johnson Service (LON:JSG) has now shut which used to do a reasonable trade on duvet cleaning I figure there is a reasonable demand for these. Which for a "middle class rural market town" you kind of think that every house has a washing machine therefore what demand?
But guess there is always, machine broken waiting for a delivery, the outlaws have just been got to throw everything through, duvet needs doing, and washing the kit for the local football/cricket/netball team stuff there is a demand.
You learn every day.
Tommy
I hold in Mum's ISA (aka SIPP)
Tommy, have you tried switching the machine on with said youth in the drum?