Small Cap Value Report (Friday 1 April 2022) - QUIZ, RBGP, RNWH

Good morning! It's Paul & Jack here with the last SCVR for this week.
Agenda -
Paul's Section:
Quiz (LON:QUIZ) - a positive trading update for FY 3/2022, moving back into a (small) profit, which compares favourably with a forecast £(2.9)m loss (from Panmures). Sound balance sheet. Looks to be getting back on track, and market cap of £18m seems stingy, even after today's c.36% rise.
Renew Holdings (LON:RNWH) - a reassuring H1 update today, everything is in line with exps. Renew has an excellent long-term track record, and is worth considering, on a reasonable forward PER of 12.4
Jack's Section:
Rbg Holdings (LON:RBGP) - a higher tax rate means fairly pedestrian earnings per share growth despite encouraging progress on revenue, EBITDA, and profit before tax. The valuation is undemanding and the strategy and growth potential are there, so I’m happy to hold with the 4-5% dividend.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section:
Quiz (LON:QUIZ) (I hold)
14.5p (up 36% at 08:54)
Market cap £18m
QUIZ, the omni-channel fashion brand, is pleased to provide a trading update for the financial year ended 31 March 2022 ("FY 2022").
Some good news, which is welcome in a very difficult market for small caps. Consumer discretionary shares, especially smaller ones, have been absolutely destroyed in the last 6 months, as inflation begins to squeeze household incomes (and looks set to get worse). That said, there comes a point where everyone likely to sell probably has done, and valuations become irresistibly low for all those people holding cash.
What makes QUIZ attractive to me is -
- Its specialism of special occasionwear is now booming, given all the pent-up demand from delayed weddings, parties, etc.
- Store portfolio completely restructured through a CVA, with all stores now on cheap turnover rents
- Decent balance sheet with net cash, and very low lease liabilities (2 year leases typically)
- Greatly reduced competition in physical stores
- Well-known brand
- Successful online operations
- Family-owned & run, experienced management
- Very low valuation, with the City having given up on it
Trading Update for FY 3/2022 -
Positive sales momentum has continued into Q4 (Jan-Mar 2022)
All sales channels doing well (stores, online, concessions [stores within a third party’s store])
Like-for-like (LFL) sales now “broadly consistent” with pre-pandemic (FY 3/2019)
FY 3/2022 revenues ahead of expectations, at £78m
Gross margin good - Q4 back up to pre-pandemic level (was 60.7% in FY 3/2019 - high for the sector)
Guidance: EBITDA at least £4.3m, and PBT at least £0.5m
Net cash £4.2m at 30 March 2022 (gross cash £5.6m, bank debt of £1.4m)
Bank facility has no covenants, and due for renewal in Sept 2022 (which should be a formality I reckon, as it was renewed without a hitch previously during the pandemic)
Results - due out in July 2022
Valuation - the last broker note I have is from Panmures, Dec 2021. It pencilled in £74.0m revenues, and PBT of £(2.9)m loss for FY 3/2022.
Therefore today’s company guidance of £78.0m revenues and a profit of £0.5m is a significant beat, especially on profit.
My opinion - this is pleasing. Remember that this year was badly impacted by the pandemic in the first 2 months, April & May. That’s offset by Govt support measures, especially business rates.
It’s good to see the business return to a modest profit. Historically QUIZ was highly profitable, but ran into problems with product pre-pandemic, causing profits to crash. Let’s hope the business is back on track now. With much lower rents, following the restructuring through a CVA, its stores should be decently profitable going forwards. Although other costs, eg. wages & utilities will be higher.
As I’ve said before, QUIZ is not the best in class, but the valuation looks far too low, for a business that could be getting back to making decent profits again. There’s growth coming through from international, and new concessions too.
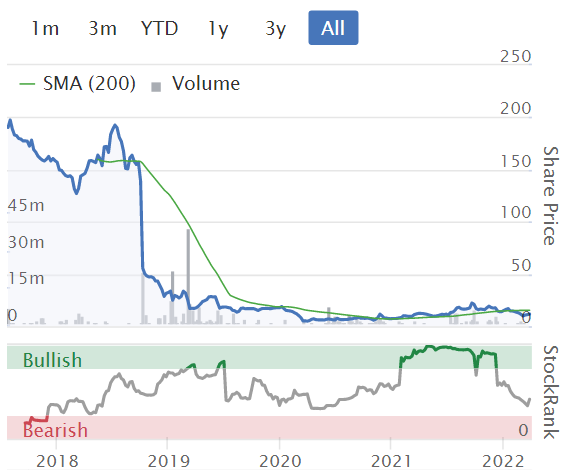
The long-term track record is awful, but bear in mind the share count hasn't changed (no dilution), so in theory the share price could multibag from here, if previous levels of high profitability are regained (it was making c.£8m p.a. profit in 2017 & 2018). Maybe let's not run before we can walk!
.
.
Renew Holdings (LON:RNWH)
689p (up 1% at 10:02)
Market cap £544m
Renew (AIM: RNWH), the leading Engineering Services Group supporting the maintenance and renewal of critical UK infrastructure, today provides an update on trading for the six months ended 31 March 2022.
This sounds reassuring -
The Board is pleased to confirm that trading for the first half of the year is in-line with management's expectations. The Group's order book continues to be underpinned by long-term framework positions and is expected to be in-line with that reported at our AGM in January.
We continue to successfully manage the industry-wide material shortages and inflation challenges effectively, without any material impact on trading.
Net debt and cash generation are also in line with expectations.
The Board remains confident of the Group's prospects in the second half of the year.
That all sounds fine. Mears noted yesterday that most of its contracts have built-in inflation uplifts, so I think it would have been useful for RNWH to give us a bit more information about how its contracts are structured. Probably the best type of contracts in an inflationary world are cost-plus type contracts. We need to ask management more about this issue, e.g. on webinars - i.e. what is the mechanism for them to pass on higher costs, and is there any delay?
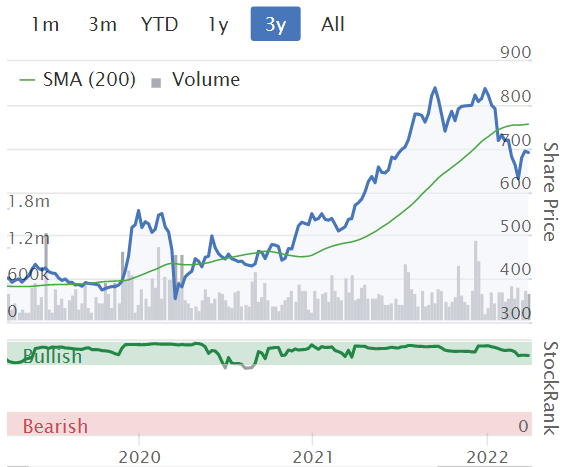
Renew has a decent StockRank -

.
The growth & value stats below look middling. A PER of 12.4 is good value I think, but this sector tends not to attract high valuation multiples, due to the risk of contracts going wrong.
I’ve highlighted the Price To Tangible Book field - if you see a “n/a” here, it means NTAV is negative - which is an amber warning to check the balance sheet, which is probably weak.
In the past I’ve had concerns with RNWH’s weak balance sheet, but it hasn’t stopped the company performing well, so having a lean balance sheet is not necessarily a deal-breaker, but it does increase the risk of something potentially going wrong.

.
My opinion - RNWH has an excellent long-term track record. Providing it can manage cost increases, then it might be a reasonable place to park some money.
.
 .
Jack’s section
Rbg Holdings (LON:RBGP)
Share price: 114.9p (+2.13%)
Shares in issue: 95,331,236
Market cap: £109.5m
(I hold)
This is a professional services group which has been busy buying high margin, niche businesses, as part of its strategy to build a larger and more diversified enterprise that relies less on its Rosenblatt contentious law division.
Now, RBG reports across the following:
RBG Legal Services - includes Rosenblatt, a UK leader in dispute resolution, and Memery Crystal, which offers legal services in a broader range of areas such as corporate, tax & wealth structuring and employment.
Lionfish - finances litigation matters run by other solicitors in return for a significant return on the outcome of those cases.
Convex Capital - specialist sell-side corporate finance boutique based in Manchester focused on helping smaller businesses realise their value through sales to large corporates.
Results:
- Group revenue (including gains from litigation assets) up 86.7% to £47.2m,
- Group organic revenue (excluding Memery Crystal) up 19.6% to £26.8m,
- Gains on litigation assets up 84.5% to £5.2m
- Adjusted EBITDA up 91% to £13.8m,
- Adjusted profit before tax up 111.7% to £10.1m,
- Adjusted free cash flow generation was £5.3 million (2020: £5.1 million)
- Net debt of £14.2 million (2020: net cash of £3.5 million) reflecting new £10 million term facility to fund the acquisition of Memery Crystal (of which £1 million has already been repaid)
- Total dividend paid to shareholders in respect of the 2021 financial year was 5 pence per share (2020: 3 pence per share), reflecting the Board's confidence in the Group's continued prospects
Earnings per share are not included in the headline results. Further down the report we see basic and diluted EPS up from 7.29p to 7.63p (+4.7%), which looks rather pedestrian given the revenue, EBITDA, and profit growth.
RBG paid significantly more tax this year, 21.3% compared to 13.1%, meaning profit before tax rose by 24.6%, whereas profit after tax was up by just 12.7%.
RBG Legal Services - Post-MC acquisition, legal services revenue is up 56.3% to £32.6m, with revenue now more evenly split across Dispute Resolution (35.8%), Corporate (35.3%) and Real Estate (28.9%). The integration of Rosenblatt and Memery Crystal support functions is now largely complete and has led to a sustained improvement in EBITDA margin to 27%, expected to rise towards 35% over the medium-term.
Average revenue per fee earner of £347,000 has fallen from £425,800, reflecting the enlarged workforce. Total staff has grown from 73 to 193, of which 137 are fee earners (2020: 43).
Total Lockup was 109 days (2020: 99) of which Debtor Days were 59 days (2020: 47, Rosenblatt only).
Lionfish - Successfully realised litigation asset sales in five cases, proceeds totalling £3.1m. Cash investment of £1.8m in 10 cases, with a full commitment of £10.5m (if funded through to trial over the next 2-3 years). First case successfully completed, delivering a return of 2x money invested as per strategy.
Convex Capital - a much stronger performance, as previously flagged. Completed 14 deals, generating revenue of £9.4m (2020: 2 deals, £1.6m) and generated EBITDA of £4.2m (2020: loss of £0.9m).
Post-period end, Convex Capital has completed two further deals, delivering revenue of £1.7m and has a pipeline of 20 deals, with six going through due diligence.
M&A
In line with our strategy, we continue to assess M&A opportunities to diversify the business and grow our service offering to clients. Our ambition is to create a broad, high-quality, high margin professional services group. As such, we focus on high-margin, specialist companies which can also create opportunities for cross-referrals. However, we will only do deals at the right price and with the right deal structure.
There’s a new EIP announced today, as well as a couple of growth share schemes. One part that sticks out is that the CFO has been granted 1,000,000 nil-cost options over ordinary shares which will vest over two years ‘and be subject to no further conditions other than for Robert Parker to remain employed by the Group’.
Turning up for work is hardly a stretch target, but the group does add this is ‘awarded in recognition of his three years' service with no prior equity allocation’.
Conclusion
There’s a lot to digest here, so I’ll wrap it up for now and if anybody spots additional talking points, leave a comment. There’s a presentation soon on investormeetcompany, at 10:30 I believe.
The main disappointment is the earnings per share figure, so it’s up to the group to generate per share value in the upcoming periods. RBG does have a clear, differentiated growth strategy to achieve this though.
In our core professional services businesses, we want to capitalise on the areas that offer the highest returns for shareholders, such as our high margin legal services businesses. Furthermore, we will use the Group's expertise to maximise the potential returns by selectively investing in contingent asset classes such as litigation.
All subsidiaries are growing, so the direction of travel is positive. There’s no guarantee that will continue - there rarely is - but the valuation remains undemanding (with an FY21 dividend yield of 4.4%), so I’m minded to hold as the company sounds out acquisitions and builds momentum across its high margin businesses.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

57 comments
I have just watched the Rbg Holdings (LON:RBGP) presentation on investor meet company. Several positives but also as commented below some perceived negatives, one being the issue of 1,000,000 nil cost options to the CFO. Rbg Holdings (LON:RBGP) is however a people business and I suppose there is a difficult balance to be struck between keeping the best people, but not doing so to the detriment of shareholders. Having said that the company has to date always fronted up and you have to hand to Nicola Foulston, she takes no prisoners.
On balance I am happy to hold as I think that the management team led by Nicola Foulston who holds 12% of the equity, are competent and ambitious. There is also a potentially attractive dividend going forward with a stated intention of paying out up to 60% of earnings.
As mentioned earlier it is my preferred way to access the litigation finance arena, as the breadth of Rbg Holdings (LON:RBGP) activities de-risks the former.
The CFO can always be replaced. They're not indispensable.
Onthemarket (LON:OTMP) really interesting anomaly highlighted today in one analyst note that Boomin is about to complete a £20m funding round with a valuation of £150m!! It has 8k advertisers compared to Onthemarket (LON:OTMP) and is loss making whereas Onthemarket (LON:OTMP) is profitable with net cash.
Currently Onthemarket (LON:OTMP) sits on a valuation of just £69m and must be far more valuable than Boomin.
Just goes to show there appears to be materially more value to a company in the private equity space than there is as a listed company, which is supposed to be the opposite!
Atalaya Mining: ATYM
I wonder what the story is behind Yanguu Copper selling its 22% stake via a secondary placing at a 20% discount to yesterday’s market price. Good to see the share price has bounced back somewhat but I’m curious to understand what caused the forced sale. ATYM management sounded very upbeat during a recent InvestorNeetCompany presentation so it looks like the issue was with Yanggu
Atalaya Mining (LON:ATYM)
"Creditors to Yanggu Xiangguang Copper Co., one of China’s biggest copper smelters, have stopped providing more loans over concerns about its ability to repay"
https://www.bloomberg.com/news...
AAhhh Jamboreebop..makes sense...thanks for this!
Brilliant info, thank you
What a great chance to top up on a down with ATYM today. Yanguu must need the cash....but with copper prices high that's bad news for them I think.
Is acquiring professional services firms really a sustainable business model? I know accountants who worked at Tenon - it went bust! Imagine that, a firm of accountants going bust! Bought too many firms and after a lock in period the key people leave and so do clients, who then rejoin the accountants/lawyers they trust and like. SP rise in the short term as EPS grows etc... but fundamentally a flawed strategy as I see it. Fine to trade but not a coffee can stock and not one you want to hold when the music stops.
Thanks for write up on Rbg Holdings (LON:RBGP) Jack. Decided to sell out this morning - nothing drastically wrong just a bit underwhelmed by results (as I think you were!) and slight concern over the large bonus for CFO. Always slightly wary of investing in legal companies as there will always be mismatch between who takes the profit - the lawyers or the shareholders - I think we all know the answer to that.
I do see attractions in litigation finance but would prefer to invest in one of the dedicated funders Burford Capital (LON:BUR) Litigation Capital Management (LON:LIT) or Manolete Partners (LON:MANO) whereas for RBG it's just a small part of their business.
Rbg Holdings #RBGP holders might be interested in also reading the second RNS released this morning which details the latest Executive Incentive Plan
In particular, this gem caught my eye regarding the CFO, “1 April 2022, granted 1,000,000 nil-cost options over ordinary shares..to Robert Parker,Chief Financial Officer..will vest over two years and be subject to no further conditions other than for Robert Parker to remain employed”
So that is a 1.2 million pound bonus with no conditions just for doing the company the honour of not doing a runner.
He must be an incredible CFO, I must admit I did once say to my chairman that our then FD (who was excellent) was and I quote "worth his weight in gold"
Seems RBG are taking this literally (would be true if he weight 22kg) but I exagerate for effect.
Yet more shareholder theft by a top team at a public company enriching themselves with no due regard for their actual role which is to create value for shareholders and not for themselves.
Total disgrace, companies like this should be put on an investment black list, totally morally bankrupt thieves.
“1 April 2022, granted 1,000,000 nil-cost options over ordinary shares..to Robert Parker,Chief Financial Officer..will vest over two years and be subject to no further conditions other than for Robert Parker to remain employed”
- it is April fools day ????
1m shares in Rbg Holdings (LON:RBGP) is over 1% of the issued share capital. I am flabbergasted. I haven't looked at their annual report to see his remuneration, but this stinks.
I was looking further into Rbg Holdings (LON:RBGP) as a potential investment, but will now avoid it like the plague.
That is a disgrace. I'd love to see this put to a shareholder vote. I would question the CEO, Chairman and Non-Exec who chairs the remuneration committee and ask them if they felt this was in the best interests of the shareholder or simply getting another crony onto the fat-cat gravy-train which will later allow them to also issue similar packages to themselves.
Completely uninvestable.
Worth noting that the award covers a 5 year period (recognising his work over past 3 years and vesting in 2 years), so if that assumption correct works out at 200k options per year and not wildly excessive.
Its not bad and lets face it, there's a lot of people who have not been so well remunerated over the last 3 years as he has, I bet. I never received GBP200k of Share Options a year.
I'll consider dipping my toes into Rbg Holdings (LON:RBGP) in two years time, the SP has been slipping since around this time last year so must give it time to be turning around guided by you-know-who. As of now I don't hold.
What, he doesn't even have to be a director of Rbg Holdings (LON:RBGP)?
And 'recognising his work over past 3 years'! Will he be paying his housekeeper/nanny/gardener a super bonus to recognising their work over past 3 years?
RGB Holdings (LON: RBGP).
At the IMC today I asked Nicola Fulston about the rationale behind the entirely non-performance related EIP.
The answer was that Robert Parker (easily confused with Peter Parker (AKA Spiderman)) has not received bonus or shares for the last 3 years as it has not been possible without causing an accounting issue. The 1,000,000 nil cost shares which vest in 2 years time actually cover 3 historic years and 2 future years so 5 years in total. I may not have explained this very well but it made sense. Watch the IMC recording for clarity.
I owns shares in #RBGP.
Still a wind up .
And still a gravy train for directors / senior employees at the expense of shareholders .
Really annoys me that it is accepted practice and that the investment community is willing to turn a blind eye .
Red flag now , there are better companies out there that don’t do this so just don’t waste time on companies that do this .
You will never guess what just happened .
My FD just walked in and said that she is happy to stay at the company but I need to pay her 400k cash in 2 years time on top of her current package .
I thanked her for her commitment to the cause and of course signed her up because that’s no problem .
Oh hang on, I’m the owner of the company and that’s 400k of my profits, so I told her to do one .
Cip Merchant Capital (LON:CIP) has gone unconditional at 54% . Can anyone point me towards what impact that has on the minority. The bidder got a good discount to NAV and I'm assuming that there will be some sort of liquidation and distribution.
Personal Group (LON:PGH) full year results webinar today (1.4.22) at 12 noon. Deborah Frost, Chief Executive and Sarah Mace, CFO will present followed by a live Q&A. (Following results on Tuesday).
Results showed revenue of £74.5m with EBITDA of £6.1m in line. A final dividend of 5.3p. 1.21m of the UK workforce have access to one or more of the Group's services.
Outlook: continued strong trading in line with expectations. Including a five year contract with Sage for Sage Employee benefits. They've also signed Dame Kelly Holmes as the Groups Chief Wellbeing Ambassador for 2022.
Favourable market dynamics with employers needing to offer enticing benefit packages. They should be able to share good insights on the overall labour market.
Join us at 12 noon: https://bit.ly/piw_webinar
Positive results from Rbg Holdings (LON:RBGP) . The company remains my personal choice in the litigation services arena given its performance resulting from its breadth of services and management team. The latter communicate regularly with retail investors appearing on Mello and Investor Meet Company. There is a presentation at 10.30 this morning on the latter by Nicola Foulston, CEO.
https://www.investormeetcompan...
Still trying to get my head around the new Executive Incentive Plan & Growth Share Schemes that were also announced this morning.
Jack i am aware that Rbg Holdings (LON:RBGP) was your pick at one of the stock slams and wonder if you have any thoughts on the results.
All the best
Rbg Holdings (LON:RBGP) final results (I hold). Results look fine but tax charge has doubled so final post tax result appears to be a relatively small increase perhaps affected by the acquisition costs of Memery Crystal. Hope Nicola will explain all, including the new incentive schemes (1 million nil-cost options to the CFO) at the Investor Meet Company presentation this morning.
Opened my mailbox this morning to find a news release from £AGL then came back down to earth. Not the much anticipated FDA announcement, just another very important piece of research from Switzerland which demonstrates the formation of CTCs and CTC clusters can be disrupted and hence slow the spread of cancer.
https://www.stockopedia.com/share-prices/angle-LON:AGL/news/rcs-angle-plc-identifying-drug-targets-in-cancer-metastasis-urn:newsml:reuters.com:20220401:nRSA8579Ga
Quiz (LON:QUIZ) good update
https://www.investegate.co.uk/quiz-plc--quiz-/rns/trading-update/202204010700088621G/
Should start a price recovery hopefully
Yes Paul would love your views on Quiz (LON:QUIZ) trading update today (i hold). All reads well to me as revenue and profit ahead of market guidance. Seems like they have managed supply chain issues well and are benefitting from events being back. Cant understand why this is valued so low, hopefully this update will turn the tide (i can at least dream!)
Quiz (LON:QUIZ)
Its hard to work out what is going on here - stocky numbers seem all over the place with the earnings being donwgraded on the computer today (April fool?) but the net profit figures was showing up as being £0.8 mill expected which is higher than todays update suggest we should expect . I am not convinced the stockopdia numbers are reliable with regard to that £0.8 mill being expectation prior to today.
What is much more positive is that Paul commented in January that expectations per december note he had were £74 mill turnover and loss of £2.9 mill - so things seems to have materially improved compared to those numbers mentioned in december - so based on that i am taking this as a positive update .
Probably what matters more is what the expectations are for next year which one would hope would show further progress?. Would be comforting if we got some broker updates suggesting next year would be back to solid level of profits.
Overall the lack of any bad news at all today is probably the most pleasing thing , i was slightly worried that then prior update was a bit sketchy - to me at present although the balance sheet is not terrible there are some chunky liabilities that were concerning when there was no proof that company was not still making losses. Thankfully todays news that they are back to profits is very pleasing.
Trading on an EV to EBITDA of sub 3 which looks too low.
On the surface a slightly disappointing bid for Randall & Quilter Investment Holdings (LON:RQIH) this morning, which I seem to have held forever. 175p a share, a 20% premium. What's a bit odd is the way the offer notice emphasises the £100 million in new equity funding to R&Q - which is very nice and all that, but not really relevant to shareholders you'd have thought.
However, hidden in the offer is a £100 million pre-emptive fund raise in the event the offer doesn't go through to fix a recently recognised impairment which will breach their financial convenants. They have pre-emptive waivers in place with their banks, which suggests that the problem isn't entirely fictitious.
At 175p that will be a CAGR of 13% (including dividends) over a decade so I shouldn't complain. There is a bit of feeling of open season on UK financial stocks at the moment, though.
timarr
RQIH has been gradually moving across the Atlantic for a number of years. It didn’t smell right to me and so I dumped my holding a couple of years back when they had their last ‘mates rates’ cash raise. Not at all sorry to see them go. The company certainly didn’t seem to be run for the nest interests of all the shareholders, just a few insiders imho of course.
Randall & Quilter Investment Holdings (LON:RQIH) management trying to steal the company away on the cheap. How convenient that they’ve all of a sudden found that the business needs $100m of equity funding. They will probably get there in the end but I expect large shareholders (Slater and Phoenix) to go into bat and demand a far better price. The CFO of Randall & Quilter Investment Holdings (LON:RQIH) was buying shares only a few months back at 170p and so trying to steal the company for 175p is a bit of an insult.
Sorry to see you go
Thanks.
How do I subscribe?
April fool
Congrats - Special allocations for Stocko subscribers? primary bid wont let me play cos I am not uk resident
Brilliant as ever Mr C! I have subscribed
Not using Numis? They seem to have the bandwidth.
April 1st
Richard
Re Mr Contrarian. You have got to be spot on.............. And if so, he's caught a few.
Many thanks, Mr C for all your hard work in the grey light of dawn. And what a good day to choose for your IPO! :-)
ESET intercepted your worldgreynews link MR C. Something about a trojan white rabbit? :)
April Fool ?
A word of caution re the worldgreynews link as it triggers my antivirus. It tried to download some potentially dangerous software in the background (not a virus).
Any virus would still be safer than Mr Cs IPO tho…
Fair point.
April 1st?
What is this outdated IPO nonscense??? Surely a SPAC!
Am I too late to secure the NFT?
An excellent post for this day of the year. Thought for a moment you were really sodding off...
...all of that work just to make us smile?
Thank you
I will certainly be investing and urge others to do so too. Remember to tell Sid.