Small Cap Value Report (Friday 7 June 2024) - BWNG, CCR. Brief: BWY, TPFG, SRT, CFYN, SYS.

Good morning from Paul!
I got up early today to finish my half-written section on N Brown (LON:BWNG) from yesterday, but haven't quite finished it yet. I'm 90% done now, so that should be up a little later this morning. EDIT at 08:49 - now published below.
Thanks very much to Ed for a superb webinar last night. I jotted down some key points which chime with ideas I've independently had, after mulling over the consequences of the last 2 years' bear market. If you didn't attend last night, then make sure you watch the recording, it was full of incredibly useful reminders (which we all need from time to time), but also some great insights too from the data. I was delighted that Ed highlighted Graham & my stock-picking successes in 2023 and 2024, where we've trounced the markets, and the various automated systems!
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
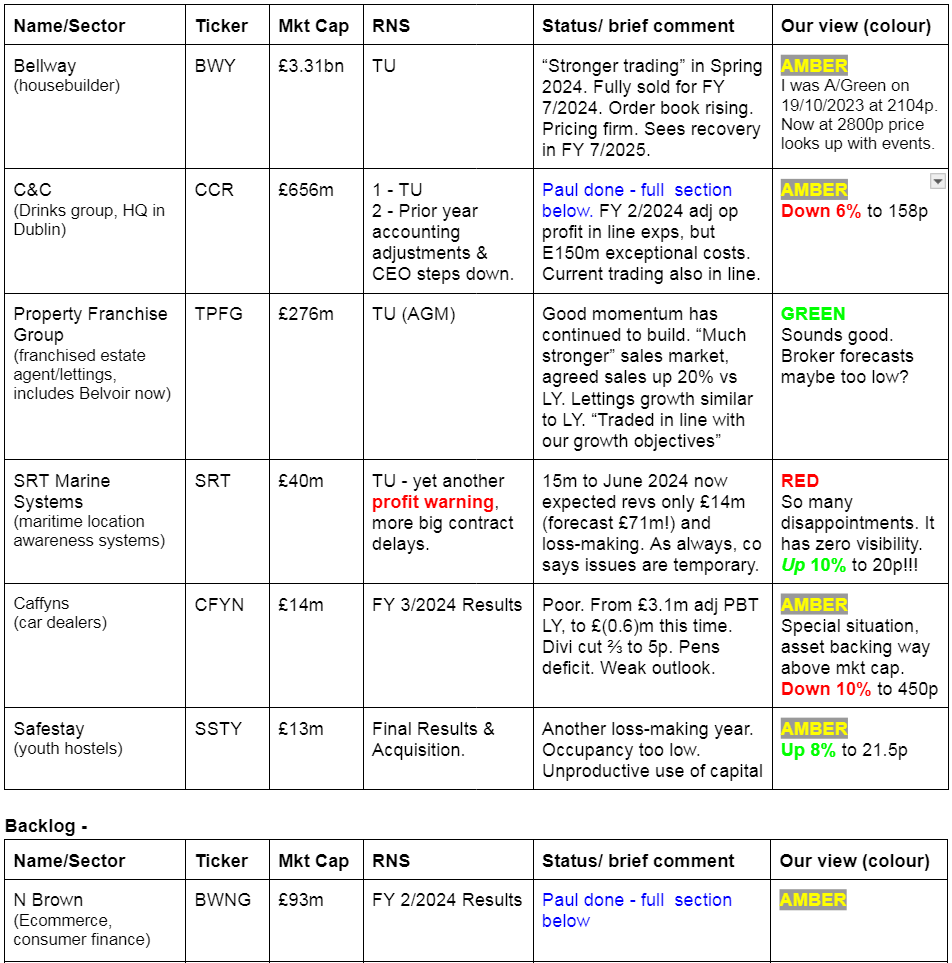
Companies Reporting
Other mid-morning movers (with news)
SysGroup (LON:SYS) - down 6% to 33p (£17m pre-fundraise) - Placing & Retail Offer - Paul - AMBER
SysGroup (AIM:SYS) the technology partner for delivery and management of cloud, data and security to power Artificial Intelligence ("AI") and Machine Learning ("ML") transformation…
This is noteworthy for a good reason. My antennae were previously picking up signs that rampy RNSs looked likely to be followed by a fundraise to repair its weak balance sheet (negative NTAV of £(7)m), hence I flagged SYS as AMBER/RED here on both 30/4/2024 and 29/5/2024. That’s exactly what has happened, with an equity fundraise announced last night.
What’s good about it then? It’s a big fundraise relative to the market cap at £11m gross. Huge discount? No - a very impressively small discount of about 6%, with the new funds being raised at 33p. Maybe appetite for small cap fundraisings is returning?
33.2m new shares are being issued in the placing/subscription, which increases the share count from 51.5m to 84.7m, an enlargement of a hefty 64%.
There’s also a small £0.5m open offer, which I’ve not included in the figures above, as we don’t know what (if any) take up there will be.
However, it’s a proper refinancing that fully resolves my balance sheet concerns, hence I’m happy to move up to AMBER.
It’s interesting to see that a micro cap refinancing has been so well supported, so SYS must be telling a compelling story to investors keen to jump onto the AI bandwagon?! Now it’s refinanced, this might turn into an interesting punt, who knows? SYS is a proper business, that has credible rising revenues, and only small losses. Now it has cash in the bank too, I wouldn’t try to stop anyone who wanted to have a little punt on this. As we go into a new bull market, stuff like this can re-rate nicely once animal spirits return. Hence why I think this is actually quite a good time for risk-tolerant punters to be looking at more speculative ideas, selectively, and providing the company is properly funded, which SYS now is.
Summaries
N Brown (LON:BWNG) - up 34% to 20p (£93m) - FY 2/2024 Results - Paul - AMBER
I get properly stuck into the detail below, and overall found this better than I expected (especially balance sheet, liquidity, and cashflow, which all look improved). Trouble is, there are also plenty of negatives and risks. Huge discount to NTAV might prove a lucrative trade, or a value trap, who knows?! I'll sit on the fence for now.
C&C (LON:CCR) - down 9% to 155p (£600m) - Trading Update - Paul - AMBER
Reveals accounting problems in previous years' accounts, which are not a big deal in my opinion. CEO has fallen on his sword though, as he was CFO when the problem numbers happened. Current trading is in line. Debt has come down a fair bit. All in all it's just a middling, unremarkable, low margin cider maker. I can't see why anyone would want to invest in this really, when there are better & cheaper companies available elsewhere.
Paul’s Section:
N Brown (LON:BWNG)
Up 34% to 20p yesterday (£93m) - FY 2/2024 Results - Paul - AMBER
A strange business, that sells items online (eg clothing, homewares) and tries to generate profit from offering high cost instalment payment terms (with high rates of customer defaults). Its brands include Jacamo, Simply Be, and JD Williams.
The free float is small, with Lord Alliance & family having a controlling stake, and Frasers (LON:FRAS) owning 20%.
Sentiment towards this share has collapsed in the long-term, but the 34% bounce yesterday in a positive market reaction to FY 2/2024 results compels me to take a look at it, unfortunately.
Headlines sound encouraging -
Adjusted EBITDA above market expectations and return to profit
Strong balance sheet and liquidity
Revenues are substantial at £601m, down 10% on the 52-week comparable.
Revenues are split 63% for products, and 37% for financial services (interest charged to customers)
Adj EBITDA is down 13% to £47.6m, but ahead of market expectations -
3 The market consensus for FY24 Adjusted EBITDA is £44.7m as at 5 June 2024.
Adj PBT is up 171% to £13.3m
Statutory PBT is £5.3m, so the massive write-offs it had last year are much smaller this time.
Adj EPS is 1.65p (LY: 1.81p), but it’s so close to zero (hence volatile) that I don’t think it makes sense to use PER as a valuation measure, but for completeness it’s 10.3x.
Adj net debt is down 21% to £236m
Dividends - stopped in 2020 and not resumed.
The reason why adj PBT rose, when adj EBITDA fell, is mainly due a much lower depreciation & amortisation charge of £20.7m, compared with £35.7m last year. So the higher adj PBT is not due to improved trading, just a lower non-cash charge for depreciation - helped by big write-offs in last year’s accounts.
It looks as if the accounts were kitchen-sinked last year, with only £7.5m of adjustments this year (FY 2/2024).
Remember it had a large cost related to litigation with Allianz, which went against BWNG, costing £26m last year.
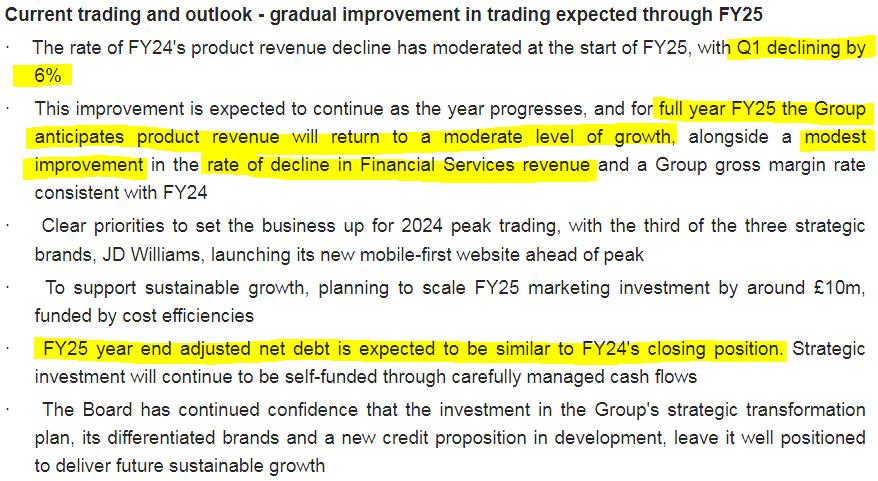
Outlook - not madly exciting - this doesn’t suggest to me that we can expect any step change (up or down) in BWNG’s future performance -
Broker forecasts - many thanks to Shore Capital for an update note yesterday. It’s forecasting flat revenues and EBITDA for FY 2/2025, which turns into £12.2m adj PBT or 1.9p adj EPS. That’s a painfully thin 2% PBT margin on £601m revenues, which increases the risk that there could be wide variances between actual & forecast. A wide range of possible outcomes. Hence why I’m reluctant to value this share on a PER multiple. Low margins like this don’t leave any scope for a repeat of previous legal & regulatory problems, which have been substantial costs. Low margins, and high risks, is not a good business model.
Balance sheet - as always, is large and complicated. NAV is large at £379m, about 4x the market cap.
Software - note that BWNG capitalises £20m pa of what it calls “software”, of which £15.4m is internal IT spending (disclosed in note 10). This needs to come off EBITDA to make that figure more meaningful. A criticism levelled at BWNG is that it uses outdated and inefficient legacy IT, which is very costly to maintain. Capitalising £20m pa in software & IT spending does seem excessive to me, so I think that argument holds water.
The depreciation charge was slightly lower than the additions, at £17.3m in FY 2/2024. This seems to be the source of the large overall drop in depreciation, since amortisation of software charge was much higher at £30.6m last year (FY 2/2023). Note that year ends slip slightly into the first few days of March each year, but I refer to them as Feb year ends. Total intangible assets were £60.9m at FY 2/2024. So deducting this £60.9m from NAV gets to NTAV of a huge £318m - that’s more than 3x the market cap of £93m. This does seem an excessive discount to NTAV, so clearly the market is implying that because BWNG doesn’t generate any significant return from its large assets, and doesn’t pay any divis, then this discount is justified.
It makes me wonder if the best way to create shareholder value might simply be to shut down the operating business, and let the customer receivables book run off. Providing shutdown costs were not too huge, then this would create more shareholder value than continuing with a business that ties up £318m of assets, but generates little to no actual return for shareholders.
Fixed assets total £47m (see note 11), and includes £33.5m “Land and buildings” which is usually freehold, although I can’t find any mention of freeholds in this RNS, or the last annual report. It would be interesting to find out what this property is, if it’s freehold (very likely I’d say), and what its market value now is. It’s probably the headquarters.
Pension scheme - had a £17.1m accounting surplus, down a little from £20.0m last year.
All of the above is really just a sideshow. The biggest numbers by far on the balance sheet relate to its customer instalments receivables book, which is huge - it’s £517m gross, less a £73m allowance for expected credit losses, giving £444m net receivable. Other debtors and prepayments are £25m, taking the balance sheet total receivables to £469m.
The big problem is, how do we know that the £73m bad debt allowance is enough? What if it’s wildly out, and far more customers default? Why is BWNG sending goods to so many customers who are going to default on the payments, how does that make sense?
Note that the annual P&L charge for bad debts was a huge £106m in FY 2/2024, albeit down from an even larger £122m last year. For me, this business model just doesn’t make sense. Surely BWNG needs to use better credit scoring methods to largely eliminate orders from customers who can’t, or maybe even have no intention of paying? There seems a major problem with the business model here, and maybe quality of management too?
As we saw with S&U yesterday (another sub-prime lender), it only takes fairly small changes to the bad debt provisions to clobber profits. BWNG doesn’t have much profit to start with, so the risk of a big write-off to the receivables book is clearly something the market is worried about. Also regulatory risk. High cost credit is an area that regulators have been all over, and look at the legal mess BWNG got into with Allianz, which turned out to be very costly to settle. Could more regulatory credit-related liabilities emerge in future maybe? PPI hasn't gone away yet either (see below).
Cash was a healthy £65m at 2/3/2024, up from £35.5m a year earlier.
The middle section of the balance sheet is incredibly good, with £617m current assets, and only £72m current liabilities, so a colossal £545m net current assets.
However, the bank borrowings are also substantial at £302m gross, which is in the non-current liabilities section of the balance sheet. Net off the £65m cash pile, and net financial debt (excl leases) is £236m, down a useful 21% from last year.
Liquidity looks fine, as note 15 explains the facility limit is £400m, and has been extended to Dec 2026.
Covenants look unusual and we’re not given specific details -
The key covenants applicable to the Securitisation facility include three-month average default, return and collection ratios, and a net interest margin ratio on the total and eligible pool. Throughout the reporting period all covenants have been complied with.
There’s also an undrawn RCF & overdraft totalling £87m, to Dec 2026.
Overall then this looks a business in good order, and not financially distressed.
Provisions include £9.2m marked as “other litigation” (see note 18). This relates to ongoing PPI claims. I would have expected this historic matter to be dwindling, but the provision was actually increased by £2.5m in the year.
At least the big litigation with Allianz seems to have been settled now, with only a £0.2m balance sheet provision remaining.
Cashflow statement - looks remarkably strong at £92.2m (up hugely from only £6.3m LY), helped by inventories and receivables coming down by a combined £56m, whilst trade payables only fell by £7.5m, so there’s a £48.5m positive cashflow there from working capital.
Capex of £23.2m is nearly all capitalised IT, hence why EBITDA is a nonsense number. Interest costs were £15.4m. There was a £7.7m positive move from forex forward contracts.
Put that lot altogether, and BWNG was able to reduce its bank debt by £31.4m, and increase its cash pile by £29.7m to £65.2m.
This looks very good, and I’m sure the bank will be a lot happier seeing the borrowings coming down.
However, the shrinking debtor book is what’s driving a lot of this, which means lower revenues from interest charged to customers in future.
Paul’s opinion - the main (only?!) attraction to BWNG shares is the large discount to NTAV, which does seem excessive - NTAV is £318m, market cap is £93m. However, since BWNG doesn’t actually generate any meaningful returns from all those assets, then a large discount is reasonable, surely? Shutting the business down and putting the receivables into run-off looks by far the best way to generate shareholder value. I wonder if that has been considered?
Years ago BWNG was a decently profitable, dividend paying business. Can it get back to that? I can’t see any reason to anticipate that. Product revenues are declining, and so is the customer receivables book. It has a feel of managed decline, not a growth business.
However, decline is not necessarily bad. As I highlight above, the cash generation has been highly impressive, due to the loan book shrinking. I would argue that shrinking the business, and hence releasing all that cash unproductively tied up in receivables, is the best way to create shareholder value. Imagine if it say halved the receivables book, enabling it to pay off most of the debt. It could then start paying divis again. Much stricter lending criteria are needed to shrink the ludicrous >£100m pa write offs when non-paying customer receivables are sold to debt collectors at a discount.
Overall, at this market cap, I think there are credible bull and bear cases, and it’s very difficult to predict what will happen in future. It’s clearly a poor quality business, and if it didn’t exist nobody would invent it. That said it’s dirt cheap on an asset basis.
I’m much happier with the balance sheet and cashflows now than before, so even though it’s not something that I personally would invest in, I can see that with a bit of luck, there could be a nice trade here. Or something could go horribly wrong, like it did at competitor Studio Retail (which went bust when its accounts turned out to have a c.£100m black hole in them). That said, BWNG proved resilient in absorbing the substantial costs of its Allianz legal dispute. I genuinely can’t decide, so will sit on the fence with AMBER.
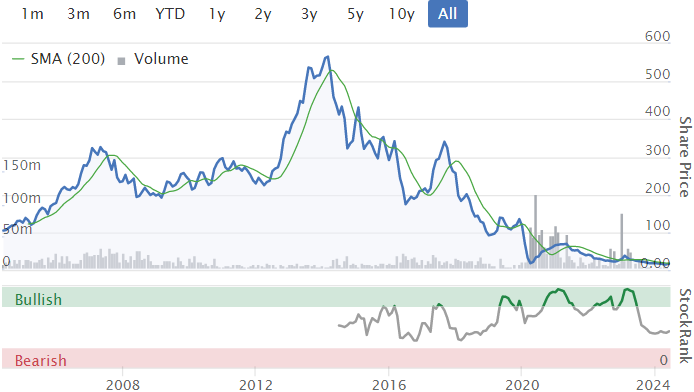
The long-term chart is telling us this is a business that has had its day. Still, that doesn't mean there won't be lucrative trades for short-term bounces along the way.
C&C (LON:CCR)
Down 9% to 155p (£600m) - Trading Update - Paul - AMBER
Its branded drinks seem to mainly be ciders, e.g. Blackthorn, Bulmers, Magners, and others listed here.
I’ve called it a trading update, but the title of the RNS is actually “Summary of FY2024 Unaudited Financial Performance”. What’s that then? It says this is not a preliminary results announcement, because it’s not yet been agreed with the auditors. The purpose of this announcement seems to be to help neutralise a second RNS this morning, revealing accounting problems that have arisen with historical results.
Actually, let’s do it the other way around, and I’ll look first at what the historical problems are, and whether they’re serious or not.
Prior Year Accounting Adjustments and Directorate Changes
Inventory and balance sheet items need to be adjusted.
No change to earnings for FY 2/2024, or future years.
This actually looks relatively minor - E5m total profit reduction spread over 3 years to FY 2/2023. Plus a €12m exceptional charge for “onerous apple contracts” (not heard that one before!) in FY 2/2023 which had been booked in H1 of FY 2/2024 I think.
More details here, again these sound fairly minor for a company valued at £600m (having lost £56m of its market cap in today’s 9% share price fall) -
“These adjustments relate principally to five items, inventory related matters at Clonmel (€10m charge), goods received not invoiced ("GRNI") (€3m credit), the timing of release of customer discount liabilities (€3m credit), change in accounting treatment of glassware (€1m charge) together with additional items (net €nil) over the three-year period in question.2
CEO Patrick McMahon had been previously CFO when these accounting problems occurred, so he’s taken responsibility for it, and will step down as CEO. Chairman Ralph Findlay becomes interim CEO for an expected 12-18 months whilst a permanent successor CEO is sought.
Paul’s view - there doesn’t seem to be any indication of fraud, just sloppy accounting procedures & controls. Or possibly the failure to book an onerous contract provision for its apples might have been brushed under the carpet deliberately in order to hit profit targets? I’m just guessing there. I hope it’s not one of those situations where an apparently modest first reveal then deepens into something much more serious. Maybe that’s why today’s £56m market cap hit is over 3x the actual financial hit to the company?
Trading Update - summary of FY 2/2024 performance
7 June 2024 | C&C Group plc ('C&C' or the 'Group'), a leading, vertically integrated premium drinks company which manufactures, markets and distributes branded beer, cider, wine, spirits and soft drinks across the UK and Ireland issues a summary of unaudited financial performance in respect of the year ended 29 February 2024 (FY2024) following a delay in the preparation of the Group's Annual Report and Accounts for FY2024.
These numbers are unaudited, so audit adjustments could yet happen.
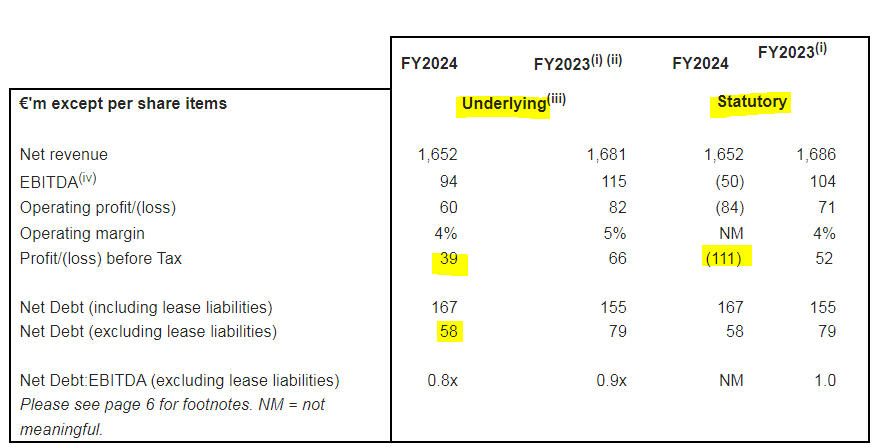
My comments on the above table -
Big revenues of €1,652m, but small underlying PBT of only €39m (down 41% on LY)
PBT margin is very low at 2.4%
Net debt excl leases looks modest at €58m - that’s well down from €107m reported at end H1.
Huge difference in the statutory figures, which show a €(111)m loss, that’s €150m lower than the adjusted numbers. This is mostly a goodwill write-off for UK (“crowded and competitive cider market”) brands, here’s a breakdown -
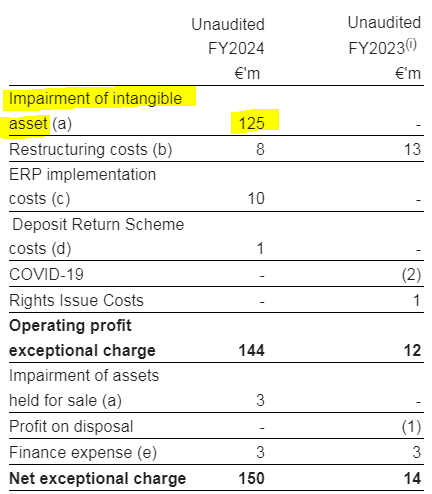
Importantly, it says these numbers are “in line with market expectations”
Claims to have a strong balance sheet, so I have to check now! At H1 its 31/8/2023 balance sheet only had €93m NTAV, which includes a €38m pension asset, so €55m excluding pensions. I would call that adequate, rather than strong.
There’s been some disruption caused by a new ERP system botch up, previously announced.
Dividends - a 3.97 Euro cents final divi is proposed, on top of a 1.9 cents interim paid in Dec 2023. That’s about 4.97p, so a yield of c.3.2% - not madly exciting. The share count seems to have reduced by about 2% recently thanks to buybacks, with another €15m buyback starting in Sept 2024.
“Commitment to return €150m to shareholders by end of FY27 remains unchanged.”
Current trading - is in line with expectations.
The football this summer is expected to help.
Paul’s opinion - not a company I know particularly well, but I’m left underwhelmed generally by this low margin business.
They’ve done a great job today in damage limitation, by rushing out draft FY 2/2024 results, and confirming trading is in line with expectations. The accounting errors (let’s be kind) are not significant overall, but obviously it raises a question mark over management competence and/or honesty. The CEO’s fallen on his sword, which is the right thing to do, people have to take responsibility for things that go wrong on their watch.
Overall C&C just seems a middling company. Fairly average PER and dividend yield. Operating in low margin, competitive markets. Adequate balance sheet, etc. I can’t see why anyone would get excited about the potential for this company/share. So it’s an AMBER from me. Why get involved?
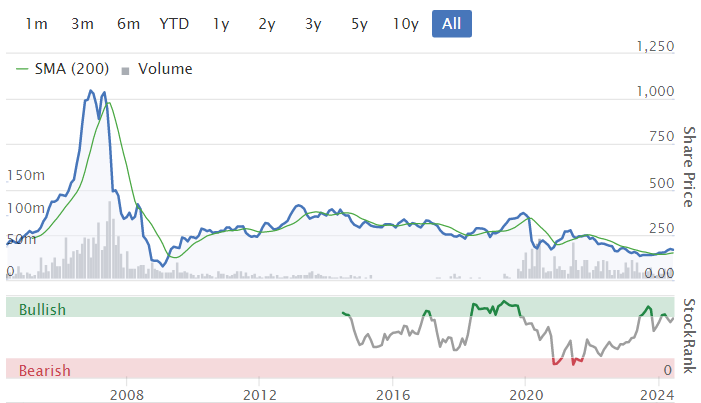
The long-term track record looks poor too - see chart below. Does anyone know what caused the boom & bust from 2005-7?
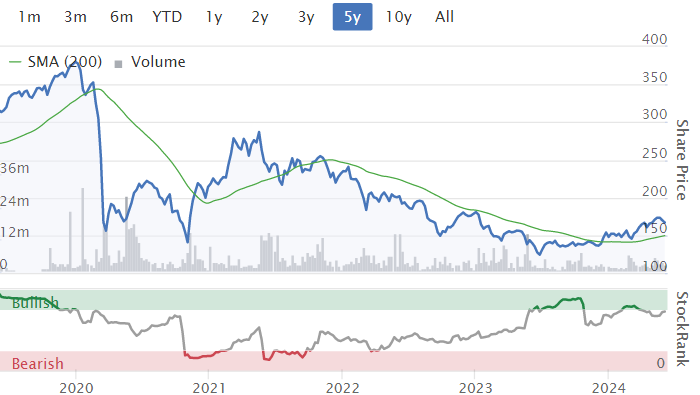
Zooming in to the last 5 years, it’s not really made any progress from the pandemic lows -
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

86 comments
Thank you Paul!
I've done another video!
The theme for this one, is whether our SCVR colour-coding system actually works - ie does it have any predictive ability? This data analysis by my friend Philip Hanson proves that it has delivered remarkably good results. So yes, it works very well!
Also some very interesting insights into how profit warnings have behaved subsequently, which challenges the conventional view that we should sell on the first profit warning. This data says yes, do that for the smallest companies, but larger companies profit warnings are often buying opportunities at the moment (mainly due to them receiving takeover bids).
The data covered is all SCVRs from July 2023 to end Feb 2024, and I run through a lot of the biggest gainers and fallers over that period.
This is about 40 minutes long - I hope you find it interesting.
https://www.loom.com/share/75e...
Here's a new spreadsheet, created kindly by Phil Hanson, which I haven't shared before, which shows how our colour-coding system in the SCVRs has worked very well, and I talk through this sheet on the video. You can open this using google sheets, save a copy locally for yourself, and then you can play around with the data to your heart's content!
Hi Paul
You mention you use an earnings surprise screen, would you be willing to share that screen
thanks
Hi alex,
Sure, I've done a video on the topic you requested, here -
https://www.loom.com/share/896...
Regards, Paul.
Trying out some new software called LOOM (a chrome plugin) for video screen sharing. This was intended as a test, but turned into a review of mine & Graham's 2024 share ideas lists.
Let me know what you think! Useful? This link below should enable you to watch the video -
https://www.loom.com/share/a9f...
EDIT: Here is the link to my top 20 2004 shares ideas spreadsheet, which is open to all to view. This link is in the explanatory notes above in every SCVR.
Big thumbs up from me
Excellent run through . Cheers Paul
Paul - Yes an excellent review of your colour coding sytem - A fantastic result to.
It struck me that there maybe an opportunity to create additional Alpha by combining Paul's etc positive (Green) assessment with a systematic (High Stockrank) score.
Ed mentioned in his last video that a systematic Sell rule could be companies with a SR <70. If we adopted the inverse of this rule and combined it with Paul's Green assessment, we would only buy Green companies with a SR >70.
My Excel skills are insufficient to attempt calculation, but maybe someone could look at this and see there is any benefit of combining man and machine?
Surge at Equals (LON:EQLS). Something leaked?
Have to wait for an update from sky news?!Maybe they've finally finalised their takeover.
Surge at Equals (LON:EQLS). Something leaked?
Caught my eye too, as a holder. A notable spike, but not associated with high volumes so it might just be an aberration.
Not one of mine, but a superb post on N Brown (LON:BWNG) and really interesting follow up from Edward. Always something to learn on Stocko, even if you don't own the stock under analysis.
Severfield (LON:SFR) under the cosh today - I wonder if thats reaction to the Indian election and the risk that infrastructure spending will be cut back and hit the likes of SFR which has a subsidy based there ?
Frp Advisory (LON:FRP) rather sharp pullback over last couple of weeks - they put out a very good trading update a couple of weeks ago and shot up, but now reversed all those gains. Looks tempting at these levels.
SRT Marine Systems (LON:SRT) I hold
I’m a long term investor in SRT. I sleep well at night despite inconsistent results. Why? Because SRT have some amazing technology which is why it is bidding for contracts that are of national importance to its potential customers.
Delays arise because of complexity and the slow nature of getting agreement from myriad government departments. Delays also occur because vested interests may seek to obstruct progress because they profit from not being regulated. That is a political reality which governments have to overcome.
I have been following SRT closely for 14 years or so. Contrary to what some people claim, SRT has not been selling systems for 20 years. It began life as a radio company. It sold its first system in 2015, to Bahrain. Since then it has delivered systems to the Philippines, Saudi Arabia (although they are officially referred to as a ME country), and a small project in Indonesia (again officially referenced as an Asian customer).
Today’s RNS, contains some clues as to irons in the fire. These are not piddling prospects but substantial contracts that have taken years of painstaking engagement with the customer to educate as to the capabilities of SRT’s offering and to build trust that SRT will not land the customer with a big bill and something that fails to deliver the expected benefits. I firmly believe the value of SRT’s IP underpins its share price regardless of current market valuation based largely on sentiment.
Many folk have been attracted to the story at any given moment and then bail out when it fails to deliver in the timeframe they expect. Today has seen such an event with short term investors panicking on the news that this year will show a loss. The initial SP drop has been undone by a more sanguine view of the facts. Looking beyond that short term time horizon, I believe faith will be rewarded. The old adage about only investing in what you understand is pertinent. Casual observation will not suffice. SRT is not running out of cash. I believe it has access to ample funds if required. Cash is coming in all the time, just not in huge numbers, but sufficient to keep the lights on until some substantial contracts are signed.
One only needs to look at the recruitment taking place to realise that SRT is not acting like a company that doesn’t expect to see material contracts going forward. It is not a dishonest company in my experience. It may be over-optimistic about timing but the contracts it is bidding for do not appear to be going to anyone else. That would be a real concern but customers who have an SRT system are pleased with it.
For anyone that wants to better understand SRT this article provides some history and more colour. It is over a year old so please remember that when reading it.
https://www.stockopedia.com/content/srt-on-the-cusp-962172?order=createdAt&sort=desc&mode=unthreaded
Interesting comments, "SRT is not running out of cash" and "cash is coming in all the time". If you mean that they regularly tap investors for more money to keep the lights on then I would agree. I counted at least six placings since 2014 and I probably missed one or two!
I think you might be provocatively misconstruing what I wrote. Cash is coming in from sales.
I love the market!!
Not at all. If Stockopedia is correct, free cash flow has been negative every year since 2018 and likely every year before that too. I am not trying to be provocative, just saying it how I see it. Incidentally, how do you actually know that this company has such valuable ip? Because Simon Tucker keeps on saying so? He may well be right and clearly there has to be something in it or they wouldn't get any orders at all. Mind you, he is still under investigation in the Philippines so who knows!
Both you and David Hill make some plausible points for the bull case and today's share price reaction also suggests shareholder support, so maybe you will be proved right in the end. Good luck.
Hi sparkler,
SRT Marine Systems (LON:SRT)
A jam tomorrow stock that has lost about 70% of its value the last year or so where at the same time most small cap stocks doubled.
Negative cash flow yields for years with revenues less than village corner shops.
Dilution after dilution and on top of that under investigation by a country that takes no s..t.
Good luck is an understatement.
All the best
Just to be clear though Sparkler - my views are made on the basis of risk/reward not necessarily whether I believe in the company long term or selling the bull points of the business. At 10p (and 16p) it was very obviously the wrong price for me and so it proved as it’s doubled intra-day as the market has realised the same and rather than being uninvestable presented a glorious market opportunity.
SRT Marine Systems (LON:SRT) has only been cash generative in one year of the last many I think and has certainly been a serial disappointer in terms of profits moving to the right. They’ve been quite canny in tapping investors though as placing have been done at much higher levels so dilution hasn’t been terrible.
But the IPR is clearly valuable - it has won a lot of business. I think the French Government gave one of the countries funding support expecting a French company to be awarded the contract and the Country in question STILL chose SRT Marine Systems (LON:SRT). That alone tells you the IPR is strong. But also the constantly increasing sales on the transponders and market leading position in that area gives you a similar perspective despite the losses.
I’m not sure why investors seem to think that you have to either have a trader mentality or be an investor in it only for the long term in sleep at night stocks. I’m certainly not. I pay attention to risk and reward and that might be short term or long term. In this case the next year for SRT Marine Systems (LON:SRT) is where it is all about. If those big contracts get going then really all that has happened is the massive profits due this year have moved into next and you’ll see a big re-rating. If that doesn’t happen it will start falling - when the share was at 15p I could see the drift to maybe 11 or 12p on bad/no positive news so my risk is 20% approx. Buying right now that risk is higher - circa 40%.
I’m not in love with the share - it is what it is. I recognise its faults and understand the drivers for potential upside so that makes it investable. It has IPR, it has material contracts (albeit moving), it has a long financing runway to absorb shocks and it operates in a good and growing market segment with (and excuse the pun) a bit of a moat. Given those dynamics why would I look a gift horse in the mouth if the market offers it to me? It’s all about relative value.
You started out saying it was a bargepole stock and I disagreed. There are lots of bargepole stocks out there but for me SRT Marine Systems (LON:SRT) isn’t one of them, for all the reasons Ive previously described. That doesn’t mean it goes up of course, nor that it succeeds in its aspirations. If the story isn’t playing out you move on, but if the risk/reward is good enough who cares whether it becomes a short term trade or long term investment - we don’t have to be single track investors.
Thanks for coming along Paul - appreciated the nod yesterday too - the webinar was good fun. For those interested, you can catch up with a replay here - https://event.webinarjam.com/l... - lots of StockRanks content.
I have a couple of slides from the webinar that the SCVR readers might find interesting in the deck.
I put a little Folio together to monitor the equal-weighted performance of Paul & Graham's watchlists. +24% year to date.
The watchlists had an average StockRank of 70 at the start of the year. As I always say, the value of research is higher the lower down the rankings one goes - high-quality research is what goes on here every day. It's cool to see that there have been only 4 losers year to date in the entire set - which is an impressive hit rate and validation of the attention given to the market scuttlebutt on a day-to-day basis.
One point to mention. The big winners year to date have been more "speculative" risk ratings - we expect those kinds of shares to move faster in risk on / bullish environments - but of course can correct quickly too if things pause/deteriorate! Worth pointing out, though, that there are quite a lot of lower risk shares in the set too. Plenty of "Balanced" risk ratings which have lower annual volatility.
Eneraqua Technologies (LON:ETP) No new news.Surprising moves yesterday and today.Sellers finally out?Has always had daily volume but not moved either way from around 40p for a long while.They do install green tech, so perhaps a Labour win might help them win more public sector business?Break out or false start?
June always seems to be the month where your best bet is to close the laptop and go away until July!
Leaving today for Tenby, forgot the laptop last year but not this time, you just cannot turn your back on the Stock Market!
Tenby is a wonderful distraction to be fair
Laugharne is worth a visit, only 25 mins away. Browns and the Ferryman deli plus the Castle, estuary to walk along and of course Dylan Thomas’s home. I live there.
Wandisco (LON:WAN2^G17) disgraced founder trying to list another shambles of a company called IntelliAM AI limited.
Of course it has to be called AI , otherwise how he can fool again innocent investors.
My issue is that why there are still brokers out there wiling to back this fraudster?
All the best
Well said yiannos1, although I don't think David Richards has actually been convicted of fraud (yet), there can't be many people who believe his preposterous excuses that a rogue salesman was responsible for the entire sales pipeline being completely bogus!
I went to a meeting just before WANdisco blew up, and found his body language most peculiar, constantly delivering deceit signals, per an excellent book on this called Spy The Lie, written by former CIA operatives. I must re-read it actually, to refresh my memory, highly recommended book for anyone who's not seen it.
There's no way I would go near any company he's involved with. How impertinent of him to come back so quickly, as if nothing had happened. The next sign of a new bull market will probably be Rob Terry making a comeback!
Regards, Paul.
Are the Police and/or FCA actually investigating this fraud - or will we have to wait until investigations into Patisserie Valerie are completed before they can find time - if ever ?
Probably forgotten about Patisserie Valerie. Mean while the ex directors continue to live off the cash from their exercised options at what were fraudulently generated share prices. No justice it seems as far as the FCA ,SFO or whatever regulatory body is failing to do there job properly!
The lengths we have to go to to invest in AIM companies sometimes!CIA training...!
Good spot yiannos1
You couldn't make it up!
For anyone interested, I came across this background article https://www.prolificnorth.co.u...
Snazzy
Just seen this photo
They are getting ready to bite some more investors these big white implants!
All the best Snazzy
Buy British
over the last year I sold half of my Tesco shares and bought Costco. A very profitable move. Yesterday I was about to repeat the exercise but I stopped. Tesco is a british institution now and offers a great deal of community services. It is also the largest employer of people with learning difficulties. I followed my good citizen duties and I am sticking with Tesco.
Tesco is big and does employ a lot of people but is probably the least 'patriotic' of them all. It has a deserved reputation for playing hard ball with farmers and suppliers in general. It gets its produce from any source that it can make the biggest return on - not necessarily British produce. It has been the most reluctant of the supermarkets to back and NFU suggested policy of highlighting home grown produce to its customers and has been the last to do so, in fact only implementing the policy in the last few weeks. Of course, its press release is a gushing piece saying how pleased they are to be implementing this policy for the benefit of their consumers - yeah right, they only implemented it when it eventually became apparent that their competitors were stealing a lead on them and they feared lost profits. Tesco itself can not be described as a good citizen.
I hear there's a lot of dodgy stuff goes on. Like, food manufacturers "rent" out shelf space. I presume that top-tier suppliers (like Unilever) aren't subject to this. I hear that milk is a loss-leader for Tesco. Also, they sell Heinz baked beans below cost.
I find that many supermarkets have some odd stocking choices. It seems that where Tesco leads, the others follow, which doesn't strike me as being particularly logical. Like, of late, I haven't been able to find Walls ice cream. It is unfathomable as to why.
There have been lots of other brands, too, that I really like, which have disappeared. Like Warburtons crumpets. Where did they go? I liked them. I somehow get the feeling that Tesco drops big popular brands just to prove who's in charge.
You can find Warburtons crumpets in Sainsburys.
Walls ice cream is sold in Booths.
Tesco are defintely in charge of the farmer supply chain but they are not in charge of the major FMCG brands. Quite the reverse actually. For global FMCG brands like Mars, Unilever, Mondelez, Nestle, they are in charge.
I never had the opportunity to enjoy that privilege as I supplied(for different employers over the years) meat, dairy, top fruit, soft fruit and field vegetables. I was very much in the agricultural camp and regularly took a spanking. Asda were the worst, followed closely by Tesco.
I am retired now and farming so I don't have to worry about my career.
Tesco (LON:TSCO)
I can get Warburton's products, including crumpets on my delivery orders.
I do find that there are anomalies where products disappear for a few months, that you have ordered forever, and then come back again with no idea why they went...
Top tier suppliers are very much a part of this Mark. I was doing some work many, many years ago helping the national account manager for Kimberly Clark on a Sainsbury’s job and all his attention was taken up by them taking Andrex off the shelves. Imagine the stress given the hundreds of millions invested in the mills.
Then there was Adam Lloyd of Lloyds chemists chucking Gillette out for a while, before it was bought by P&G.
A company I worked for at one early stage in my career actually paid £500k to get 12 four foot wide gondola ends in the Sainsbury Savacentres back in the day. (Interestingly, savacentres just spell checked as “scavengers”!, LOL)
Big retailers behave very aggressively with people’s livelihoods to get what they want and run training programmes on dissecting businesses -without anaesthetics!
My goodness there are some antics in the grocery industry! It certainly made work exciting!
I remember the MD coming back one day and saying he had left the buyer at T stamping her feet and in tears because he could not agree to the demands. So half the store estate went to a rival -who of course had to pay listing fees and a bigger discount because they were winning the business.
A never ending cycle of value destruction which drove sourcing from China and then retailers starting their own buying offices in the Far East.
My brother in law, a farmer, used to supply Tesco with potatoes. He stopped supplying them many years back, when they demanded 180 day payment terms!
He told them where to go, and got a contract with Waitrose instead, who are far more reasonable, and is still with them today
A couple of years ago, mum haplessly agreed to "HolidaySurfers", or some such nonsense. It was by a company in Canada. Toronto, specifically. I heard from some Canadian guy that, yeah, there's a lot of scam artists operating from Toronto.
Anyway, we contacted Tesco credit card, who refunded our money as a fraudulent charge with efficiency.
So I am more than happy to express my gratitude to Tesco and their team for their straightforward assistance. It is something that I won't forget.
I used to supply Tesco back in the day. They are complete bandits and dropped us like a hot potato when they managed to source cheaper product from Thailand. When they came back because their supplier had let them down, we were unable to respond as the factory capacity had been allocated to Aldi.
...and there is the rub.
As someone who spent 20 odd years running agribusiness companies supplying UK and European supermarkets, I can tell you German privately owned Aldi is a good deal more patriotic than Tesco will ever be. Aldi genuinely support British farmers and British agricultural and farmer-owned business.
Of course, I was scrupulously polite whatever my personal enjoyment of the situation. However, It is always better to be polite as you don't know if, in the future, you end up as the CEO of a company with a huge chunck of their turnover with Tesco and, when you arrive you find your old nemesis has, like you, been promoted.
Farming is just as tough BTW.
I have been a customer of Riverford Organics for more than. decade. Its founder Guy Singh Watson said that as a farmer in his earlier days he was hoping to supply a big supermarket. He had an invitation to talk to their buyer in London. He politely asked if he could meet on another day which was more convenient. He was told, " listen sonny, when we say jump, you jump" .
He founded Riverford to avoid ever having to deal with supermarkets again. It's now the biggest box scheme supplier in the UK and the quality and value is outstanding. It may not have been Tesco but it's not the first time I've heard of farmers being shafted by the big boys.
Property Franchise (LON:TPFG)
Confident AGM statement. I should have bought more when I added around 330p, but it is always the way. When shares go up you wish you had bought more and vice versa.
CFO to step down at the end of 2025, so plenty of notice and time to find a suitable replacement.
Exciting future with the integration of Belvoir and the recent substantial acquisition:
"The Guild and Fine & Country provide services to a total of 1,036 outlets, of which 65 are international outlets. In the year ended 31 December 2023, the Acquisition produced audited revenues of £13.2 million, audited EBITDA of £3.5 million and PBT of £3.3 million".
Difficult not to get carried away with confirmation bias, so message to self that nothing is guaranteed in investing. Having said that the future looks bright provided Gareth and his team successfully manage the integration of Belvoir and The Guild and Fine & Country.
Eneraqua Technologies (LON:ETP) moving up nicely. high risk. results were a few weeks ago trade receivables reduced, Big red from Paul last time.
Hi davidallen77,
Context for Eneraqua Technologies (LON:ETP) shares since listing - see chart below - it clearly wasn't the business that was sold to fund managers at IPO -
A slight blip upwards today is barely noticeable on the above chart.
Your post aroused my curiosity, to see if this might be a buying opportunity, so I've had a quick look at the FY 1/2024 results, announced on 23/5/2024 here. They're terrible! -
You're right that receivables have reduced, but are still way too high - something is clearly not right here -
Given their track record, I don't trust management, so am not interested in their outlook comments.
Good luck with it, maybe things can't get any worse?
Regards, Paul.
Maybe worth a look now, i will do some research.
In my opinion, IPO's should never be bought by PI's, as they tend to be IPO'd at max valuation and best timing.. 9 out 10 are lower within a couple of years.
Quite often they are Private Equity owned, then an IPO as a way out!
BEWARE. my experience (at 2 employers who were PE owned) is that they will cut costs/staff to the point where it is unsustainable medium term, to make the figures look great and get a good exit price via sale or IPO. Then a year or 2 down the line the problems emerge......
It happens time after time
many thanks Paul, I see Justin waite did a video on this one for watchlist yesterday, volume of over 2million in a month so a seller could be cleared, new FD to be annouced soon. Pi world interview in discussion tab I can't understand the ceo but old FD said we will be better this year, why no Investor meets interview.
Some thoughts on Safestay (LON:SSTY)'s very belated results (for FY Dec23) today. Coincidentally, I had also left a comment on yiannos' comment on Wed's thread.
There's quite a bit of freehold property (and also leasehold, if you want to include), showing quite an asset-rich balance sheet. Trading way below TNAV. Company states their NAV is 50p. At the last results, I had my own "Boon's adjusted" TNAV of 30p. Shares are currently 20p.
Despite being only a £13m market cap, its going to take me a few hours just to digest through and piece together the story from today's results...
(I hold in the Boon Fund)
Hi Boon,
All fair and valid comments.
I spotted that the revenues will easily be beaten for 2024 and 2025 estimates. If you take out the acquisition outflows they generate an amount that it’s too much for its £13.7m market cap.
They are trying to build something here with all these acquisitions and a price closer to the low 30’s can easily be achieved this year.
All the best
Fantastic W7L q1 trading update today
Warpaint London (LON:W7L) their Q1'24 TU was released on April 9th. Have they updated it again ?
They reiterated results from 24th April this am in an announcement about a conference they are presenting at, no new news!
Thank you, I had not read that RNS fully ;-))
Thank you Paul for catching up on nbrown...
Updates today from two 'bargepole' stocks as in "I wouldn't touch it with a bargepole!" The first is that serial pusher of revenues and profits to the right SRT Marine Systems (LON:SRT) which has found yet more excuses for delays this morning! The second is C&c (LON:CCRN) whose CEO is now resigning over matters relating to his watch as CFO. This being another company that seems to disappoint much more frequently than it pleases. Maybe we should start a 'bargepole of the year award' for a bit of fun. Any other candidates?
SRT.
"Whilst both our systems and transceivers businesses are
progressing very well within the strategic global maritime domain
awareness market, it is with considerable disappointment that it now
appears likely that new project revenue milestones in our systems
business which were expected to be completed in the current financial
period will move into the early part of the next financial year."
This company is constitutionally incapable of making any real money. I don't know what the deal is. I presume it's something along the lines they design something, sell it (eventually), and then it's back to square one again. It has produced no free cashflow for at least a decade. Utterly utterly univestible.
You see Sparkler - I take a completely contrarian view to you on SRT Marine Systems (LON:SRT). For me this mornings drop was a great opportunity. You could buy at 10 or 11p but in reality even back here at 16p this is a £35m market cap that has no funding concerns despite the ongoing delays, most of which are bureaucratic, and an IP rich business doing maybe £11m revenues.
So the play here is that at the 15p level you’ve probably got around 20% downside in the short term (ie next 12 months), but if the contracts that have shifted into the early part of the new year do indeed come in then I can see a trebling or quadrupling of the share price. Therefore the risk/reward for me on this now is very good indeed. Not quite a free option but not far off it.
Serial disappointers with IP rich products and plenty of funding can be a great place to make good returns if you time it half well and don’t fall in love with “the story”. Basically because you have lots of retail lemmings bailing out as they get disappointed and lose interest against a backdrop of relatively low liquidity. Then the same investors get FOMO as any good news filters through.
Edit : Lol - I see I’m not the only one that spotted that as price is now up on the day! I hope no one got suckered into selling at 9.5p. MMs having a field day.
I agree David. The large often governmental market is a tricky affair with many a slip between cup and lip! But IMO SRT have some important positives starting with there is a clear need for what they are trying to achieve and it is growing. They already have a market leading product in AIS and are bringing out a new updated product called NEXUS. But most importantly I have never seen any sense of dishonesty in the management team despite the many disappointments. I think the Phillipines thing is a political set up.
So given that base view they raised £10.5m in Jan and have a £16,5m facility. Financially they are fine for the next few years, in particular as much of the work is funded by Govt financing (which seems to be the cause of the delay). They have a potential (and this is really where one of the ?s arise) market of £559m with projects of £180m. Current market cap is £40m. We don't know the margins which is a problem for me and sparkler.
Typically i don't like large contract business and don't invest but the risk/reward ratio at 20p seems well weighted in my favour. So need for product, honest management team, cheap valuations. Ticks my boxes and I will go down with the ship if I am wrong.
Well good luck to you David. I admire your patience and strong nerve on this one. I have no axe to grind, having never held the shares myself, but occasionally I have been tempted given their supposedly strong position in what should be an attractive niche market. Like many, I can see the potential for this business to really take off one day but it hasn't managed to do so yet in the twenty or so years I have been watching it - now that is a long investment horizon!
Hence why one should never fall in love with a stock.
My point really was SRT Marine Systems (LON:SRT) is far from a Bargepole stock unless you wanted to sit in it for 5+ years waiting for jam to arrive. It just depends on your investing / trading timeframe.
My definition of bargepole is one where there are no consistent revenues, are loss making with low IPR and a rapidly disappearing runway. Or have management that prove untrustworthy with investors. SRT Marine Systems (LON:SRT) fits only one of those criteria imo which is the loss making part. That doesn’t mean one should necessarily buy and hold given the number of setbacks it has managed to endure over the years but it also presents some great opportunities for canny investing at times.
hi davidjhill,
SRT Marine Systems (LON:SRT)
That doesn’t mean one should necessarily buy and hold given the number of setbacks it has managed to endure over the years but it also presents some great opportunities for canny investing at times.
In essence this is a stock with appeal for contrarian traders. No bad thing but imho you need a trader's mentality to feel comfortable in getting involved (I don't).
If your bread and butter approach is buy and hold investing then it makes sense to give the likes of SRT Marine Systems (LON:SRT) a wide berth. You'll sleep much better.
Good luck to holders.
Snazzy
SRT Marine
Net Debt 10x Cashflow- FCF Negative- Interest Cover Negative- Net Profit Negative-Spread 11%- Piotroski 3- Share Dilution 10%-ROCE Negative-Net Gearing_ 61%- EBITDA Negative FCF to Sales Negative- Operating Margin Negative
Whats not to Like?
David, if you managed to grab a few at 10p that's surely got to be up there for trade of the month and it's only 7th Jun! One bagged in a few hours!
Extraordinary price action with SRT Marine Systems (LON:SRT) (I hold) this morning in response to a very lengthy RNS explaining reasons for the delays to their contracts.
Trying to train myself (perhaps AI would do better) to accurately predict the impact of an announcement on the share price and in this case had guestimated 20-40% down and mentally prepared to buy more if it went as far as -40% which it duely did, bottoming at -42.2% but I wasn't quick enough to buy (some did), and now it's up almost 10%. What a swing.
Just shows that one needs nerves of steel and to be able to think independently to avoid the vagaries of sentiment. Much of the recent fall has been anticipating this revenue miss but I'm evidently with the bull case that revenues will eventually materialise and their marine domain awareness systems will become essential and profitable installations.
Anyhow Simon Tucker doing a webinar on Monday so we'll see what he has to say.
Stockopedia Turd Awards - would be some good marketing for ED !
My morning smallcap tweet: Smallcaps weep
Caffyns (LON:CFYN) SRT Marine Systems (LON:SRT) Physiomics (LON:PYC) Property Franchise (LON:TPFG)
◄Caffyns (CFYN)► FY-Mar rev up 4%. U/L pretax -£566k (+£3.1m). FY div 7.5p (22.5p). Outlook - trading has remained challenging. Some manufacturers continuing their transition to new agency arrangements which may result in some short-term disruption to the market. EV demand weak. [SP=546 Cap=15m]
◄SRT Marine Systems (SRT)► warns FY-June rev £14m lower than expected due to contract completion administrative processes. Co "in a positive position to weather the project delays". [SP=18.2 Cap=41m]. I hold.
◄Physiomics (PYC)► wins £162k five month contract for its Virtual Tumour technology. [SP=1.35 Cap=2m]
◄The Property Franchise Group (TPFG)► AGM stmt - momentum has continued to build. "Our longstanding businesses have traded in line with our growth objectives." [SP=442.22 Cap=276m]. I hold.
Despite the recent bounce, UK equities (especially smallcaps) still look cheap compared to other geographical regions and historical averages.
UK market is cheap. No obvious catalyst for a large rise but it does mean it is low risk, unlikely to fall very much.
I did see on the webinar yesterday that a guy from Germany posted that the Germans were very much interested in UK stocks. He didn't elaborate, but it will be interesting to have heard his thoughts. So if there non-UK investors out there, I'm sure we'd all be interested in your opinions.
My insight into the European markets is virtually nil, but my general impression is that at least German and French stocks are not especially high, barring a a couple of hot sectors, perhaps. The first share I looked at, Volkswagon, is on a PE of 4. No-one is going to call that "stretched".
Plucking some other shares at random: Siemens 17 ( a little above average, but not outrageous), Total 8, ING 8. You can have a little look at others for yourself at Euro Stoxx 50: https://www.boerse-frankfurt.d...
Louis Vuitton is on a PE of 25, which is obviously a pretty high rating. But so are some high-quality UK stocks. EXPN on nearly 30, REL on 28, and so on.
So I don't think share valuation is a uniquely British thing.
I'm not even sure that the US markets don't offer any value. Sure, big tech is on sky-high value. So is a lot of other large caps. MCD (McDonalds) is on a PE of 22, WMT (Walmart) 29, (JNJ) Johnson & Johnson 22, and so on. But there is stuff lower down that's more reasonable. Like JACK (Jack in the Box) which in on a PE of 10. It's a fast-food chain, is expanding, so I assume everything is OK. Fast-food chains seem to be going to the wall in the US right now. But JACK is expanding, so maybe these failures are actually helping it. Whatever. The point is that I'm getting the impression that the market is concentrating heavily on the well-seasoned names, and kinda just ignoring everything else.
Totally agree and would like to add some more excellent growth stocks listed in the US that I believe have further upside potentials :
1. Aspen Aerogels (NYQ:ASPN)
2. Applovin (NSQ:APP)
3. TransMedics (NMQ:TMDX)
4. Shift4 Payments (NYQ:FOUR)
5. DraftKings (NSQ:DKNG)
6. On Holding AG (NYQ:ONON)
I struggle to find anything listed here with growth potentials as the above.
Still some opportunities but these are based on the outflow of money that has crashed prices and not on any growth visibility.
All the best
I’ve been a holder of Shift4 at times, and profitably. What makes me nervous is the fact that every payment stock I’ve held has eventually crashed and burned. What makes this one different?
Shift4 Payments (NYQ:FOUR)
Just Keeps growing its revenues and will have net cash in 2026.
ROE 31% EV/FCF 8.56X
FCF yield 12%
Revenues will double from current levels in 2026.
Interesting numbers for a growth company and I believe they have recently rejected a take over offer.
All the best
Hi Yiannos1. Where do you get your information in choosing the above stocks?
True, but I suspect they always will. From a global perspective the UK market (particularly small caps) is surely niche and essentially domestically driven.
I invest in UK small caps because I feel, living here, I have a better understanding of the market in which they operate that I do in other countries, but if I didn’t live here I wouldn’t touch the UK with a bargepole.
Very happy to hear that Michael Lynch, accused of USD 11 billion in fraud linked to the sale of his software firm Autonomy to Hewlett-Packard, was acquitted on all charges yesterday.
https://www.google.com/amp/s/w...
Its good to see that US justice can work. HP clearly did not do their DD properly, buyer beware rules!
I'd just like to say a big thanks for the Webinar on Thursday. A thanks for posting the link. Sometimes in the past the link has been left off in the webinar reminders, making it difficult to find the link.
I noticed that BA was mentioned, and I'd like to add my own little commentary on it. I bought it back in Nov 2021 on the back of its high stock rank. I'll continue to hold, and I'll explain a little why. The forward PE ratio looks a little high at 19.5. However, it P/FCF is 15.1, which is a FCFY (Free Cash Flow Yield) of 6.6% (the inverse of 15.1).
If you think you have a quality share (admittedly I think there's higher quality and growth prospects than BA), then I like to think of a hurdle rate for FCY of 1+rate of inflation. Given inflation at 3%, I want a FCFY of 4%. This is an idea I got from Terry Smith.
The free cashflow per share is 91.2p on a TTM basis, according to what's on Stockopedia. Even if you apply a more conservative cashflow of 80% (split the difference between 2022 and 2023) results, you still a FCFY of 5.7% (based on a share price of 1394p). It's till above the hurdle rate.
Analysts are expecting double-digit growth over the next couple of years, so it's all positive.
Perhaps a bit more qualitatively, I think the UK and Europe will need to double their expense expenditure. I'm basing that on the rate we spend on defence as a percentage of GDP. Whether that will happen is another matter, of course, but even the Labour have made positive noises on defence spending.
A lot of the really easy money has been made since Russia invaded Ukraine (although that's still an ongoing story, for sure, who knows where this will end up).
Perhaps I'd be more critical of the investment case if I were to consider BA today, but it seems like a fairly safe LTBH (long term buy and hold). I've seen posters who have held the shares for decades and have been very satisfied with its performance. It's not something that will shoot the lights out (figuratively rather than literally), but it should prove a nice steady plodder at least. It is also not economically sensitive. Governments are going to carry on spending on defence even if the rest of us are eating ze bugs.
That's my logic, anyway.
There are other good shares in the defence sector, which no doubt offer excellent opportunities, but I'll leave that as an exercise for the reader.
Where is the link to the webinar?
You may have to wait for it to be edited
Yes I would also like to see this; I seem to have missed out on it (sometimes I am choosy about watching but this would be one I would have liked to see).
Do you mean Boeing or BAE Systems? Presumably the latter!!! Sometimes a full stop can go a long way to help others identify what you mean - BA plus a . = BAE Systems (LON:BA.) if I have got it right.
Ed has posted a link to the replay above, but it's also permanently on the Stockopedia Academy here: https://www.stockopedia.com/ac...