Small Cap Value Report (Friday 8 April 2022) - JET2, VP., BOWL, SENS, RFX

Good morning! It's just Paul here today, as Jack's snowed under with other work. Today's report is now finished, have a lovely weekend!
Agenda -
Paul’s Section:
Jet2 (LON:JET2) - outside of our scope, as it’s £2.5bn market cap. So just a quick mention of what seems like an encouraging update today - which could have positive read-across to other travel company shares. It says that Feb & Mar 2022 saw load factor “approaching seasonal norms”. Summer 2022 bookings “are encouraging”, and close to pre-pandemic levels. Fuel costs are mostly hedged. In any case, I see that the oil price (whilst volatile) has come down from recent peaks.
My view - this could be a good time to buy travel shares, as strong demand returns, but share prices still look depressed. Could be a nice trade, for a (say) 20%+ sector bounce? That's it, no section below.
Vp (LON:VP.) - a positive trading update, ahead of expectations for FY 3/2022. This strikes me as a good business, and attractively priced, with a decent divi yield too. Looks good value. Worth considering.
Hollywood Bowl (LON:BOWL) - an excellent H1 (Oct-Mar) update, with very strong LFL revenues continuing, from pent-up demand - but how long will that last? Ahead of expectations for the full year, but we can't access any broker research, which seems an own-goal by the company. The recent big recovery in share price looks justified to me, this seems a good business, and it's expanding, on a valuation that still looks reasonable.
Sensyne Health (LON:SENS) - shares crash nearly 80% on news it's delisting, and fresh funding from lenders will involve massive dilution from lowered conversion price (and warrants). We rang the alarm bells here on 14 Jan, and 26 Jan, when the company announced it had run out of cash. It's since dropped over 90%. Anyway, that's it, de-listing means that we won't need to cover this crock again. It's worth studying situations like this, so you can spot the warning signs in future at other companies in terminal decline.
Ramsdens Holdings (LON:RFX) - a reassuring H1 trading update, with all 4 activities doing well. Liberum ups FY 9/2022 profit estimate by 19%. There should be a c.5% divi yield by next year. Sales of forex are expected to improve, as leisure travel returns. Looks OK overall, and priced about right for a sector that is always cheap.
StockSlam - sadly, the online StockSlam event is now on hold, due to a lack of new people prepared to do 3-minute pitches on shares of interest, it was felt that we couldn't just have the same speakers appearing time after time. Also, I think the organisers, Damian, and PIWorld, need a break. I'm hoping StockSlams return in the autumn, we might have to do some nagging!
Here's the video of this week's StockSlam, including my "pitch" for Beeks Financial Cloud (LON:BKS) (which readers here already know that I'm bullish on as a long-term core holding in my portfolio). Obviously not cheap now, and I'm hoping for a pullback so I can buy some more a bit cheaper.
Link to StockSlam recording for April 2022.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Vp (LON:VP.)
870p (yesterday’s close)
Market cap £349m
Vp plc, the equipment rental specialist, today provides a trading update for the period since the Interim Results were issued on 30 November 2021 (the 'period').
VP has a year end of 31 March 2022. It is an equipment hire group.
Positive update -
The Board is pleased to report that the Group has maintained its recovery in trading performance with our core markets of infrastructure, construction and housebuilding providing increasing levels of demand and we expect to report results for the full year, ahead of the Board's expectations.
Outlook - no signs of any recession worries here -
We are encouraged by the improvement in sentiment and performance experienced in the final quarter and look forward to a period of further progress in the new financial year.
Commenting on the Trading Update, Neil Stothard, Chief Executive of Vp, said: "Since our interim results in November, the Group has seen increased demand from our core markets as Covid restrictions have eased and we are pleased to say that overall performance is expected to be ahead of the Board's expectations. Additionally, we have made excellent progress with both our technology offering and with the introduction of more environmentally friendly equipment solutions for our customers."
"We look ahead with optimism, confident that we will continue to deliver excellent value growth for our shareholders."
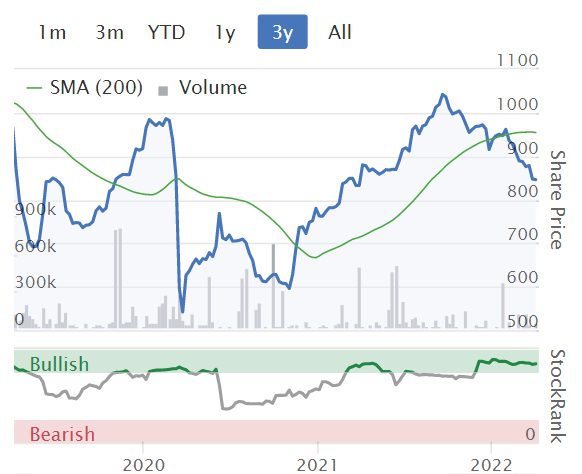
My opinion - I do wonder if the stock market (especially in small caps) might be over-reacting to inflation worries? VP’s update today reflects a buoyant economy, with full employment.
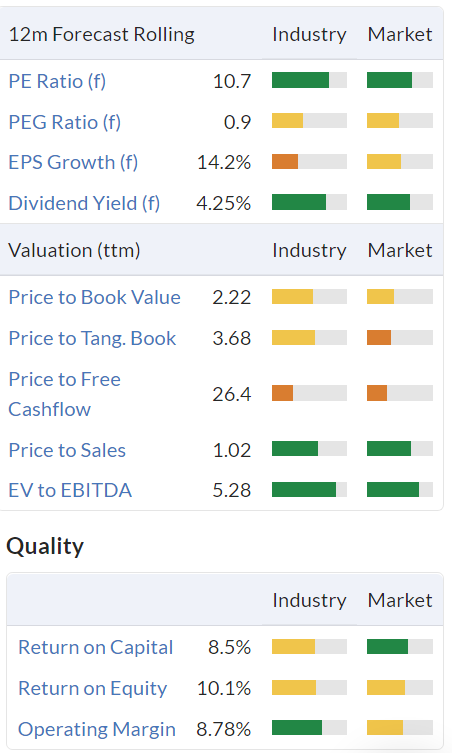
Valuation metrics below look pretty good value to me. After the recent dip in share price, VP seems worth considering. It strikes me as a decent company, well managed, with a fairly good long-term track record, and attractively priced right now, especially after today’s ahead of expectations update & buoyant-sounding outlook.
.
.
.
Hollywood Bowl (LON:BOWL)
280p (up 7% at 08:27)
Market cap £478m
Hollywood Bowl, the UK's largest ten-pin bowling operator, is pleased to announce a trading update for the six months ended 31 March 2022.
Preamble - I last looked at this share here in Oct 2021, when it published a strong trading statement for FY 9/2021. Pent-up demand had produced a positive H2. However, pandemic disruption meant that full year results for both FY 9/2020 and FY 9/2021 were barely above breakeven, helped considerably by Govt support measures.
The balance sheet was strengthened during the pandemic with a fundraising, which increased the share count from c.150m to 171m shares - not too much of an issue.
Note that the IFRS 16 lease entries are large, and show a net liability of £41.6m - this should largely disappear in future as sites become profitable again. Taking that into account, the balance sheet looks OK, with plenty of liquidity.
Today’s update - the prior year comparatives are meaningless, due to pandemic disruption. More importantly, the like-for-like (LFL) revenue growth compared with pre-pandemic is highly impressive, at +26.8% - this really matters, because there are a lot of cost headwinds (e.g. wages) these days. So +26.8% revenue growth is way more than needed to mop up cost increases, I reckon.
Although I suspect that rate of growth is probably due to pent-up demand, hence should probably be seen as a temporary bonanza.
As mentioned above, demand for holidays is returning, so could that see UK-based leisure attractions wane in popularity, as squeezed incomes require savings to be made elsewhere to fund a family holiday abroad? Who knows - every household has their own priorities, and behave differently.
Inflation & cost control - this is very interesting, especially the benefit of installing solar panels. Hedging of energy costs is a key issue right now, so we need to ask that question on company webinars.
I’d like to see more companies disclose what their % labour cost is. Actually, this is in the notes to Annual Reports, so we can easily find out that information ourselves -
Cost control remains a focus for the Group. Although not immune from inflationary pressures, centre level labour accounts for less than 20 per cent of sales and the Group has taken a number of mitigating actions including maintaining a simplified food menu introduced during the pandemic.
The main potential exposure is energy costs, which the Group has hedged out to the end of FY2024. Additionally, five solar panels installations were completed on centres during the period with five further planned during FY2022. The Group expects that by the end of FY2022, 15 centres will have installed solar panels that result in up to 33 per cent of the sites' required electricity being self-produced. We plan to roll out solar panels to more centres in FY2023 and beyond, subject to landlord consents.
Cash - was £30.0m (and no interest-bearing debt) at end Sep 2021. This has improved strongly, to net cash of £49.6m at end March 2022. Very impressive, especially as that’s obviously after taking into account cash outflows for capex - refurbs & new sites, and improvements like the solar panels.
Dividend to be reinstated. This should be quite good, because the company has plenty of capacity to pay generous divis, due to its hefty cash pile, and cash generative operations.
Full year guidance -
The Group anticipates that its full year performance will be ahead of current market expectations.
Broker updates - there’s nothing on Research Tree. It’s very frustrating when companies fail to ensure forecasts/research gets out to private investors - a big oversight.
Looking back at my notes from last autumn, I thought at the time that consensus of c.15p EPS looked light, and that something nearer to 20p this year, and maybe 17.5p thereafter (as pent-up demand waned) might be more appropriate.
With another really positive update today, that could be too conservative now maybe?
If we value the share on say 20p EPS (this year could be more), then the PER would be 14 - that’s not expensive, especially as the finances are sound, with plenty of net cash in the bank.
My opinion - I still like BOWL, despite a recent big recovery in share price after the mad panic sell off in early March. This rebound looks justified by strong fundamentals, in my view.
I’m not sure I could bring myself to buy now though, looking at this chart -
.

.
Sensyne Health (LON:SENS)
2.2p (down 78% at 10:16)
Market cap £3.6m
It’s around this time of the morning that I check out the top risers & fallers, to pick up news stories that I missed on my first sweep of the RNS.
Today’s top faller today, by far, is this massively loss-making AI company in the pharmaceuticals sector.
It came up previously on the top fallers list, so I covered it here on 14 Jan 2022, at 24p, warning that a price of 0p looked highly likely, concluding “ditch them at any price”, which on reflection probably crossed a line in terms of not giving advice, but the financial situation looked so bad that I felt compelled to warn in the strongest terms I dared.
Then again we looked at it here on 26 Jan 2022, after major shareholders extended an emergency loan to keep the lights on temporarily whilst a sale of the company was sought, concluding “Very dangerous, beware”, and “I wouldn’t touch this with a bargepole”.
Just to clarify, that wasn’t hyperbole, we would only use language like that if a company is a complete financial basket case, and about to go bust. Or rather where the probability of a 100% loss is extremely high. Sometimes companies do manage to rise from the near-dead, but it’s very rare in the worst cases like this, where a heavily loss-making company runs out of cash.
I’m making the above point not to sound smug, but to emphasise that when shares collapse, it’s predictable just from looking at the balance sheet, and cashflow. Companies don’t go bust due to losses, they go bust when they run out of cash.
Today’s Update has triggered a further 78% fall, so it must be grim.
- The founder/CEO has stepped down with immediate effect, to be replaced by Alex Snow, an “experienced entrepreneur” with relevant experience.
- The new CEO will conduct a restructuring, focusing on core activity, “with the support of the Noteholders” - so clearly the creditors are now in control of the situation.
- Cash - there’s only £1.5m left as of 6 April.
- Noteholder creditors have agreed to provide another £15m in new loans, to include 10p warrants, in tranches of £5m. Loan notes will be convertible into shares.
- Share capital being restructured.
- Cancel listing on AIM - this is the killer, so it’s game over for most people, who won’t want to hold shares in a private company. Although that is still possible.
- Waive requirement for a mandatory offer under the Takeover Code (because Noteholders will own most of the company if they convert into equity).
- Formal Sale Process announced in Nov 2021 has not worked so far, but “discussions remain ongoing with a small number of parties…”
This warning is very clear (that existing equity is now worth very little) -
Shareholders' attention is specifically drawn to the proposed term to cancel the Company's shares from trading on AIM and the highly dilutive impact of granting conversion rights to the Noteholders and the proposed change in exercise price of the warrants associated with the loan notes.
My opinion - it looks as if the company could survive. However, because it’s run out of cash, the new financial backers (lenders) have taken control, and existing equity now looks likely to be diluted away to virtually nothing.
The approvals will allow for the conversion price for the loan notes and the exercise price for the warrants to be set at a new nominal value for the ordinary shares of £0.008 per share.
This bit above seems to be saying that the new shares (if Noteholders convert) will be at 0.8p per share. The nominal value of the shares is being lowered to 0.8p, through the usual device of splitting into (worthless) "deferred shares". Therefore if we work on the basis that total noteholders end being owed £20m after the new loans have been drawn down, that would mean conversion into 2.5bn new shares. There are currently 166.2m shares in issue, so existing shareholders would go from owning 100% of the company, to owning about 6% of the company, massive dilution, assuming the noteholders do convert their loans into shares at some point.
At this stage, there’s little point in selling, if your shares are only worth a few quid - the dealing commission might even be more than they’re worth, for small shareholders.
As the company’s got fresh (loan) funding, it could survive in restructured form, and existing shareholders would then own a tiny proportion of a private company, which could conceivably survive, and a remote chance of it prospering maybe?
This situation is a reminder, that if you must punt on blue sky, jam tomorrow shares, that are burning cash at a prodigious rate, then it’s vital to ensure there’s enough cash in the bank to get to where the company needs to get to. Repeat rounds of funding really don’t work well on the AIM market, companies like this should stick to private ownership.
.
Ramsdens Holdings (LON:RFX)
182p (up 3% at 12:11)
Market cap £57m
Ramsdens Holdings PLC, the diversified financial services provider and retailer, announces a trading update for the interim period ended 31 March 2022 (the "Period").
H1 profit guidance -
During the Period, Ramsdens delivered a strong performance across each of its four segments. As a result of this, the Group expects to report H1 profit before tax of approximately £2m.
Brokers don’t give out half year guidance, so it’s not clear how this compares to market expectations. That the share price is up 3%, and the company describes its H1 performance as “strong”,and “very strong”, suggests that this is a bit better than expected.
Outlook - interesting comments here, especially the above-inflation pay award for staff. Reading between the lines, it seems to imply that higher wages can be taken in their stride -
"We are pleased with the Group's very strong performance during the Period, the first half of a financial year marked by the continued easing of restrictions and consumers' transition to normality.
Whilst being mindful of the impact of current macroeconomic events and well-publicised inflationary pressures, the Board is encouraged by the growing demand for Ramsdens' services and believes that the strong momentum reported today will continue over the coming months.
Demand for Ramsdens' foreign currency services in particular is expected to grow significantly as more people travel abroad this summer, and we are confident that the Group's ongoing strategic investment in its jewellery proposition will continue to deliver strong results both in store and online.
We have rewarded our staff with pay rises in excess of inflation, and I would also like to take this opportunity to publicly thank them for their dedication both to the business and to our customers over the last two challenging years.
We remain on track to open eight new stores in this financial year, and underpinned by our diversified model and well-invested proposition, look forward with confidence to the key summer trading period ahead."
That all sounds pretty good.
Broker update - many thanks to Liberum for providing us with an update today, much appreciated. Liberum analyst Shailesh Raikundlia has put through a chunky +19% increase to his FY 9/2022 forecast PBT, but no change to FY 9/2023 forecast.
I find it easiest to work on EPS forecasts, which are 14.8p this year, and 18.5p next year.
Shares are 182p now, so the PERs are 12.3 this year, and 9.8 next year - which looks about right for this sector, which always seems to trade on low multiples, due to the regulatory risk, and slip-ups which seem to occur from time to time.
Dividends - are forecast to be about half earnings, giving a c.5% yield by next year - the main attraction of owning shares in this sector.
My opinion - this looks like a smaller version of H & T (LON:HAT) - both companies are income shares, with the long term charts showing zig-zag sideways movements. Hence it seems to me that the time to buy is when they periodically sell-off, not when they’ve just put on an impressive share price spurt, as of now.
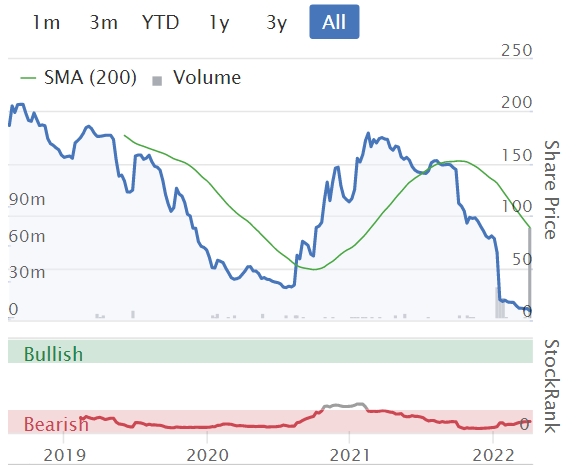
Here’s the RFX share price since it floated, obviously heavily disrupted by covid, like most shares.
It’s also paid out 19p in total divis since listing.
.

.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

45 comments
Cant get excited about jet2 as at Dec 2019 market cap was 2.5bn (and there are now more shares in issue as there were then). We are now also at 2.5bn mkt cap. Net debt position slightly better than then. The pent up demand argument is risky with all the talk about consumers have less spending power now compared to back in 2019. Better bets to be had elsewhere
Re Sensyne Health (LON:SENS) Early in my investing career I lost a small amount of money on $NTX.L - flat surface loudspeakers - anybody remember them? Later I lost a lot more on $TUNG.L . They vere valuable lessons. Never again will I invest in small loss-making companies that promise jam tomorrow but generate no cash or shareholder value.
Hollywood Bowl (LON:BOWL)
Ten Entertainment (LON:TEG)
What is interesting is that the bowl shareprice seems to be going great guns at present whilst for ten entertainment their main listed competitor the sharprice is going into reverse if anything - recent outperformance is 25% which is very noticeable and slightly frustrating potentially for holders of £teg (that will be me) Note ten also came out with a trading ahead of expectations update recently so there seems to be very little difference in how they are doing compared to prior expectations. I do know when i bought £teg that Bowl were seen more as the quality operator (teg were cheaper when i bought on pe ) so perhaps its simply the return of price premium for bowl - or perhaps they may have better operational gearing or prospects ? answers on a postcard please.
I think it's simply the case that Ten Entertainment (LON:TEG) is smaller, less liquid stock and therefore tends to always trade at a discount to Hollywood Bowl (LON:BOWL) I don't think there is much difference in terms of their quality metrics. You see a similar thing in the property/REIT space - the bigger funds such as Segro tend to trade at much bigger premiums to the smaller companies.
Does anyone know if something happened overnight in Media stocks?
I notice Bidstack (LON:BIDS) is down 17% but also Tremor International (LON:TRMR) down despite a good tie up announcement this morning. Seems to be sector related but I haven't seen anything on my radar tell me why.
Some reports in the US that advertising market is slowing, was on CNBC
Thanks Albert
Thanks Paul for the StockSlam link. Obviously Paul's is a star performance, other great pitches from those below with the stock and investment trusts mentioned:
Damian Cannon: Tinybuild Inc (LON:TBLD)
Charles Ford: Fireangel Safety Technology (LON:FA.)
Edmund Shing: Anglo Pacific (LON:APF)
Lilian Nandi: India Capital Growth Fund (LON:IGC)
D’Arcy Andrews: Purplebricks (LON:PURP)
Robert Cordon: Oakley Capital Investments (LON:OCI)
As paul mentions: Paul Scott: Beeks Financial Cloud (LON:BKS)
Dee O’Hare: Carr's (LON:CARR)
Shakti Tipathy: Gore Street Energy Storage Fund (LON:GSF)
Here again, the link for the video and podcast.
Also, do join us today for the Tracsis (LON:TRCS) H1 2022 webinar. Management will present followed by Q&A. The new US acquisition and US market scope sounds very exciting. Register here.
Finally, £IES announced 'a memorandum of understanding' with Hyosung, Korea, the large energy storage & renewable energy project developers, who will represent/sell IES products. Sounds big. Here's the PIWORLD interview from March: IES & the renewable energy landscape. Video.
Thanks Tamzin, I don't know about being a "star" performer. My portfolio has plummeted in the last 6 months, so I seem to have a reverse midas touch at the moment! Let's hope my luck changes :-)
Thanks for all your hard work in putting on the StockSlams, I think we took it for granted, so will miss them.
Best wishes, Paul.
Your time will come Paul, as will many others on this board.
Thanks Paul!
You'll go back to out perform soon, you always do. In the meantime you sharing your experiences help us all cope with the ups and downs of investing. And, we are all grateful for your amazing research and analysis, which is too easy to take for granted.
Argentex (LON:AGFX) (I hold) - Seen some recent gains (from year lows) so wanted to flag it in. Results out anytime, with this company performance benefiting from interest rate rises and currency fluctuations, which must be a theme for the coming year.
Reading across to Alpha fx, its time for Argentex to deliver a similar performance, and looking at the last set of results I do see these next results continuing the share price recovery. I maybe wrong, but worth a look IMO.
Path Investments (LON:DGI) - has arrived on LSE. full list, via a reverse today. An EV drive train technology business which looks more advanced than Saietta (LON:SED) but on a much, much reduced market cap of £34m v's £155! Also, there is a sodium battery business too, so an ESG champion in the making? According to Align Research its worth 1.192p precisely - all sounds quite compelling unless any EV experts out there can set me straight?
I'm not able to see anything about the Path Investments (LON:DGI) technology other than people being interviewed saying how great it is. Are there any details you can point us to?
I am intrigued given this appears to be defence technology making it's way into the commercial world but don't agree they are more advanced than £SED. DGI describe themselves as an R&D outfit so far, albeit with some promising partnerships.
Here's a link to the note; http://www.alignresearch.co.uk...
Spoke with a second hand car salesman yesterday. His market read is that cars have reached peak price and just starting to soften. He reckons people are paying full whack now but in 3 years the car value will be less than they've used to calculate lease payments and this will cause problems down the road so to speak....
Hi Paul, I do agree with you on the holiday rebound. Jet 2 up 4.4% but still posting losses. I suspect the term 'return to pre pandemic levels' is enough to get the share moving upwards. This COVID related staff shortage maybe a chance to buy on a dip. My picks would be EZJ (moves a lot in a day/week so not for the faint hearted) and OTB which I have been in and out of and making some small profits on (spread bets) since before Christmas. OTB seems at a good buy price now as recently been up at 250. Having read the Jet2 results I am now taking a medium term hold in these two companies.
Financially they don't look great, but this return to 'Pre pandemic levels' holiday narrative seems to be one of the only guaranteed good news stories for this year.
Could FerrexPo (FXPO) be a buy at current distressed levels? I know its in the conflict zone but the trading statement is very encouraging! Many expected production to be at a standstill!
https://investegate.co.uk/ferr...
Ferroxpo works from the middle of ukraine and the russians appear to be abandoning in favour of east ukraine. They still appear to be functioning well however the problem is access to sea ports. So no matter how " safe they can produce without access to the sea profit has to take a hit. Is this already built in to the share price??. But as rothschild said during napoleonic wars " buy to the sound of cannons ""
To what extent can they stockpile any product that can't be transported? If they can, then profits would surely only be deferred, not lost.
Historically they have shipped 50% of production via the barge/rail route through Europe. No reason they can't ship 100% via that route but they will need access to a European port for seaborne onward deliveries. That is what they are working on currently. That will cost a bit more in freight but given lack of global supply and price rises in Iron ore additional freight costs would be more than offset by price rises.
Estimates are that mine is operating at 70% of previous capacity which is surprisingly strong to be honest. I expected less.
It's an interesting one I agree. On the basis that it appears reasonably clear that Putin won't be able to take over the whole of Ukraine and given where these mines are situated in central Ukraine then it appears that on a medium term view Ferrexpo (LON:FXPO) appears phenomenal value at these distressed prices. Any ceasefire / agreement will also light a fire under them.
On the flip side prolonged war or a change in Russian strategy to target areas outside of the East/South would increase the risk and change the dynamic.
At present they are slightly lower on production and can only get goods out to Europe via barge and train. Not sure how much this will add to freight if they need to then ship from Europe. Only 50% of historic sales have gone the current route.
Nonetheless they have no debt and $160m net cash and at current ore prices are well capable of doing 100p eps if there is no deterioration in circumstance. So a PE of 1.8 and at the moment it appears the dividend is still expected.
My worry is, everywhere in the Ukraine is in range of a cruise missile, and any target seems to be a legitimate target in the Russians eyes...and I am afraid an iron ore producing manufacturing facility could be deemed as aiding to the war effort, with the added advantage of effecting western financial interests.
I want to stick it up Putin as much as everyone else, but would keep any investment small as its sadly still in a war zone, and could be wiped out, which I pray does not happen, but I think remains a possibility.
That's the risk you take Paul but generally the same applies to any resource stock, just different risks. Most miners are in jurisdictions where things can play out badly in the worst case scenario though.
If you want to minimise risk then you stick with the majors who have global diversification along with the lower rewards on offer, otherwise you accept the elevated risk.
In the case of Ferrexpo (LON:FXPO) you don't get to buy stock at a PE of sub 2 free of risk! Investors have to try and assess the risk and reward and factor that in. That decision should be very specific to an individual.
Every investor has a different tolerance and diversification. For example I wouldn't buy Ferrexpo (LON:FXPO) as my only stock in a portfolio but I might allow it to be a 1 or 2% allocation on the basis that over time it may treble or quadruple or more and add good alpha to the portfolio, but in an extreme scenario would only cost me 1% capital.
"Head I win, tails I don't lose much." - Mohnish Pabrai
I have small positions in £FXPO, £POG and £POLY. If two of them go bust and the other one 10 bags, I will personally be delighted.
Journeo (LON:JNEO) announced a new order worth 9m over three years today (which for a 9m cap company is pretty significant.) With the worst of COVID now over and higher fuel costs pushing people onto public transport I think the opportunity for this company to re-rate is big. Expanding beyond UK is still elusive but would also be a big game changer.
I am long on this and probably biased :-)
Hi Brookeda
Thanks for the heads up. I noticed Journeo (LON:JNEO) whilst browsing my lists yesterday but didn’t know enough about them. I’ve just gone and has a second look. This news has given me the conviction to invest.
I can only buy £500 at a time on AJBell so starting with a very modest investment. Do you know much about their other customers and potential growth?
I think this area of transport security and planning is going to grow massively. Forward PE looks very modest.
I would suggest if you haven't you have a look at their last trading statement from March which summarized how the management see the opportunities for the company. I think there was a collective shrug when these came out. I think there's been a big question mark around public transport since COVID and people working from home more etc.
If we assume fuel cost are going to remain high and there's no reason in the short term to believe they won't there's going to be a lot more move back to public transport in my opinion which could help.
On the downside for this stock its a very small cap, very illiquid and like other small companies it drifts down on no new news.
I haven't heard of Journeo (LON:JNEO) before, but then saw its logo on the StockReport - 21st Century. This share has been around for donkey's years, and it always looks cheap, but then something always goes wrong. The trouble seems to be lumpiness of orders, installing CCTV on buses & trains. I don't think it has any particular moat. That's why it only makes a profit every now and then, and doesn't pay divis. Why is it listed? Imagine what all the costs of listing have been since it floated in 2005!
I think investors would need to see something fundamentally change for the better at this company, to make it of interest. There have been false dawns in the past, when people get excited about a flurry of big orders, then it has always fizzled out again.
I wouldn't assume broker forecasts are going to be achieved either.
Sorry to be a misery! These minnows are usually best avoided, unless there's something really special happening re growth & innovation.
.
Actually Paul - that's not really quite accurate on Journeo (LON:JNEO)
You are right that it used to be C21 and there was an old management board that basically had a strategy of selling hardware and things went wrong. They then resigned and it got taken over by an experience pair who both bought large chunks of shares in the business. So they are owner/managers.
Since then - and in the last few years they have steadily been taking the company to connected security systems on public transport. So they have transitioned an old business with little value to a real business in the IoT space selling software (plus some hardware). They are really the leading experts in that space. They have also been steadily increasing revenues and orders over the last 3 years, clients appear sticky and like the products and are expanding.
Whilst I wouldn't necessarily say this is going to have a big enough market to multi-bag necessarily the momentum in the business should double the share price in my view. Remember it is now profitable and cash generative too.
Thanks david, sounds interesting, I'm taking another look at JNEO now.
It will be interesting to see if the new mgt/strategy at Journeo (LON:JNEO) is going to work or not.
Looking afresh at it, the FY 12/2021 results don't inspire, with only £0.6m u/l PBT.
Do we know how much of the £15.6m revenues are recurring? The commentary talks about monthly income from connected vehicles, but it looks small numbers compared with other companies offering software connecting to vehicles for other uses, e.g. telematics like Quartix Technologies (LON:QTX)
Balance sheet looks weak, with cash tight, and negative NTAV, so it's under-capitalised a bit I reckon.
Good announcement today, I see it's put a rocket under the share price - a £9m framework agreement, over 3 years. Although already included in budget, so I question whether landing an order that was already expected should have moved the share price up 37% today?!
"The contracted revenues under the Agreement were included in management's expectations of performance for the current financial year and add to the Company's strong order book, providing further future revenue visibility."
Getting myself up-to-speed on it, this does look a bit more interesting that I thought. So could be worth a punt. Have we seen management present anywhere, e.g. webinars? I'd be interested in attending a webinar, to learn more about mgt.
Thanks for flagging, potentially interesting! (although a long, and unremarkable history, as I pointed out above!). Maybe that could be about to change? If it hits the broker forecasts for 2022 & 2023, then I think it would justify a higher price.
Jack & I do like it when readers post comments here which flag up stuff which we might have missed, and you might have researched in depth, so thanks again for posting your thoughts on JNEO. I'll watch out for their next results/TUs, and report on them in future, now you've piqued my interest! :-)
Regards, Paul.
Thanks Paul
I'm not sure we have seen much from management. I recall a meeting with them I attended a couple of years ago which alerted me to the story but not much else. Nothing on IMC either. I think the business is at inflection point personally but todays rise has obviously removed some of the undervaluation.
There is a 6 mins video on proactive investors which I seem to not be able to link on here which is about a year old, but is a short summary of the challenges the company are looking to help support. This isn't a big holding of mine but something that could get more traction particularly if they can go on the back of government money to re-invest into public transport
Hi Brookeda
Thanks again for the heads up. I read the PI comments in SCVR looking for ideas and you've posted a good one here.
I followed your advice and read the March financial report. It makes for very impressive reading.
All companies like to tell us that their market is huge (and we all know there are many fish in the sea) but Journeo (LON:JNEO) seem to be getting noticed by a very sceptical/frugal industry. I particularly liked that Abellio London are funding their £0.5M investment through operational savings. A zero cost upgrade is going to result in a happy customer and more orders. Plus makes a great case study to show to prospective customers.
Just a few wins from their many opportunities will make a big difference to a company of such a small size. I suspect their next problem may be growing pains (small operator operating in a big market) but its a good problem to have.
It also looks to me that they have IP and "know how" that may form a moat. "Know how" is often underrated as IP but in reality is often the best way for small companies preventing others from overtaking them.
I've bought my small initial stake (thankfully, early this morning). I'll be doing more reading and keeping an eye out for dips in the price. Hopefully Paul and SCVR might keep an eye on it too.
On a side note it is good to see that good news can result in a share price break out. There is money looking for interesting companies. I looked up the price chart on investing.com and it doesn't look the same as the one Paul posted earlier which paints a very negative picture. Not sure why they are different.
Journeo (LON:JNEO) ( I hold)
Journeo has suffered from historical perceptions that it is simply a box shifter(CCTV). Whilst this was its historical business, the story has moved on somewhat. Firstly, camera and CCTV technology is now being used to monitor different aspects of the journey, for example potholes etc in the road that need fixing and can make the process more efficient. More importantly, it also means they have relationships across what is a very inert industry. I had a bad experience in an unlisted name in the same space that was always doing pilots but couldn't get across the line.
The cloud has opened up all sorts of opportunities that were previously dominated by 2 hardware manufacturers on board. Journeo is effectively a play on Smart Cities. The transport network is critical both in terms of giving and receiving information. There are big government grant programs in place from which they have been benefitting. They have a contract with Edinburgh who are very committed to the smart city concept. A lot has gone into tech and tech development since Russ Singleton became CEO. He is ambitious but building steadily. The orders are becoming greater in magnitude which is a great sign that the strategy is working including an increasing component of recurring revenues but I wonder if there may be a need for fresh working capital at some point.
It has some similarities with Tracsis in my view but is clearly miniscule in mcap terms. Liquidity has been an issue. I suspect this will change with the appointment recently of Cenkos as brokers.
Re Journeo (LON:JNEO) -
I looked up the price chart on investing.com and it doesn't look the same as the one Paul posted earlier which paints a very negative picture. Not sure why they are different.
Different timescales. I was talking about the long-term performance of the company, so showed a long-term chart.
It's always worth checking the X-axis when looking at all charts, just so you're clear what timeframe you're looking at.
P.
Cmc Markets (LON:CMCX) update reads well. After the mishaps with setting expectations last summer it looks like they are trying to put things right by under-promising and over-delivering. Results at top end of expectations and above Stockopedia forecasts. The development of the new UK retail platform appears near to completion with little damage to profit and loss and more international platforms set to come. The share price has dropped back to the levels seen at the start of the pandemic so there is plenty of scope to move up.
Agree, gains with IG recently are a good read across. Volatility on the increase will benefit these companies.
What’s your Twitter name?
@MrContrarian
MrContrarian I note you are no longer short Avacta does that mean you have changed your view r is it an ommission?
I closed Avacta (LON:AVCT) short a month ago at 42p. My position had become small and I wanted to withdraw the profit to use elsewhere. It's still a short, probably.
£cmcx - CMC markets. In line but top end of expectations. Happy enough with that, but what interests me is they say income (but not profit?) is now higher than pre pandemic. I'm hoping that this alongside the share buyback will push the share up to around the 300 mark in the next quarter. They seem to be making all the right noises about geographical expansion. We shall see.