Small Cap Value Report (Friday 9 July 2021) - COG, PMI, IKA, THS

Good morning, it's Paul & Jack here with the SCVR for Friday.
Timing - TBC
Disclaimer -
A friendly reminder that we don’t recommend any stocks. We aim to cover notable trading updates & results of the day and offer our opinions on them as possible candidates for further research if they pique your interest. We tend to stick to companies that have news out on the day, and market caps up to about £700m. We avoid the smallest, blue sky type companies, and a few specialist sectors (e.g. resources, pharma/biotech).
A central assumption is that readers then DYOR (do your own research) and discuss in the comments below. The comments, incidentally, sometimes add just as much value as the articles. We welcome all rational views, whether bull or bear!
It's helpful if you include the company name or ticker within reader comments, otherwise some readers may not be aware of what company you are commenting on.
Agenda -
Paul's Section:
Cambridge Cognition Holdings (LON:COG) (I hold) - yet another contract win. Looking good.
Ilika (LON:IKA) - you heard it here first! As I suggested a few days ago, this jam tomorrow battery technology company is doing another big placing. Makes complete sense, given the sky-high market cap.
To follow.
Jack's Section:
Premier Miton (LON:PMI) - the trend of strong performance from fund managers continues. Profitable, scalable, modestly valued & with a 6% forecast yield - but exposed to market sentiment should conditions turn.
Tharisa (LON:THS) - platinum group metals producer reports a record Q3 and the shares continue to look cheap; key concerns include the sustainability of current PGM prices and the risk of additional Covid disruption in South Africa
Paul’s Section
Cambridge Cognition Holdings (LON:COG)
(I hold)
165p (y’day’s closing price) - mkt cap £51m
Another one! Something significant seems to be going on here. In the past COG seemed a serial disappointer, but the more commercially focused strategy under newish CEO Matthew Stork, is clearly working.
2021 forecast revenues are already in the bag, with signed contracts, so any additional contract wins are icing on this delicious cake. High margins too, so operationally-geared cake.
I hope some readers are enjoying this cake as much as I am, but it’s terribly illiquid, so it can be difficult to impossible to buy. Hence when positive newsflow occurs, holders can sit back and enjoy watching prospective buyers bidding up the price, as happened when Best Of The Best (LON:BOTB) shot up when the newsflow was good (not so much these days though with that one, but I reckon it could do alright longer term, there have been bumps in the road before).
I wonder if £100m+ market cap could be on the cards, in a bull market, for COG? Am sitting tight - run the winners, as my latest read, The Art of Execution, urges us.
.
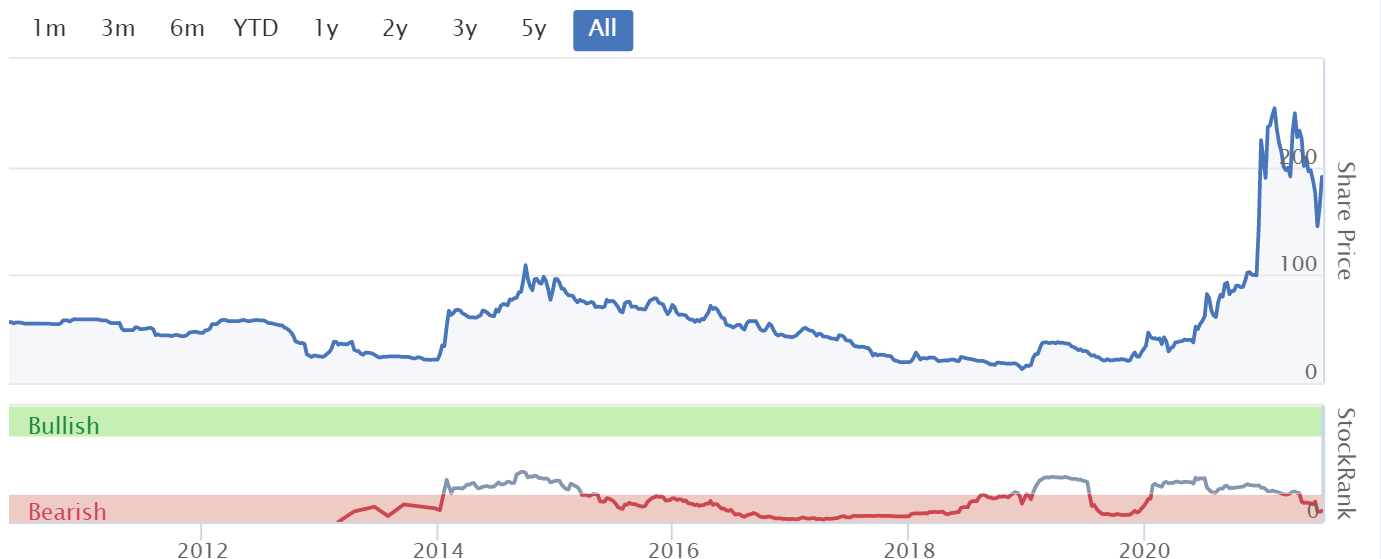
Ilika (LON:IKA)
151p (down 24%, at 09:35) - mkt cap £211m
Proposed Placing, Open Offer and Retail Offer
Ilika plc (AIM: IKA), the advanced solid-state battery company…
As suggested here a few days ago, it’s pleasing to see Ilika follow-up on my suggestion that they should take advantage of the sky-high market cap to do a big fundraising. Although they’ve baulked at my suggestion of £100m, and instead gone for a more modest £18m placing, a crushing 30% discount. But only 9.2% enlargement of the share capital. Sometimes deep discounts can attract “flippers”, who are motivated to bank profits fast - thus putting a lid on the share price, for as long as it takes buyers to absorb the overhang.
A 30% discount also confirms to me that the share price is inflated, probably by retail, speculative buying, and institutions aren’t generally convinced by the story. If they were, then the placing price would have been c.200p, not 140p.
A further £3.7m is being raised in an open offer.
On top of that, an additional £3.0m is being raised via Primary Bid - it’s nice to see that platform gaining traction. Roll up, you lucky people!
Directors are investing a paltry £15k, so it seems pretty obvious they’re in this for the remuneration & share options. Although some well-timed buys at 20p per share were made by Directors in 2018.
As you can probably tell, I don’t think much of this company, based on its lamentable track record. Who knows, it might be able to commercialise its battery technology at some point? The hefty market cap indicates that plenty of people believe the story. Unless you’re expert in battery technology, then this share is a total punt, not an investment, in my view.
.
.
Jack’s section
Premier Miton (LON:PMI)
Share price: 188.95p (+2.14%)
Shares in issue: 147,491,470
Market cap: £278.7m
Premier Miton’s an active fund manager offering a range of funds including actively managed equity, multi-asset and fixed income funds, and investment trusts. Other managers such as Polar Capital Holdings (LON:POLR) and Tatton Asset Management (LON:TAM) are having a great time right now in terms of performance and fund inflows. When the going is good, these are high quality, profitable, cash generative businesses with impressive scale benefits.
This is reflected in the StockRanks - of the three listed above, Polar has a QM Rank of 99 and Tatton’s on 98, while Premier is on 97. Fortunes can change though for fund managers, exposed as these companies are to market sentiment and investor confidence.
PMI Ranks:

For now, on a valuation basis, it looks like there is scope for PMI relative strength to continue assuming the market holds up and inflows are healthy.

We have just had a fantastic twelve months or so with the rebound from Covid lows, and conditions now feel trickier. Investors are having to be more discerning in picking winners.
This is a very brief update on what appears to be another quiet Friday. We’re entering the summer holiday months so light news days are to be expected for a little while.
Highlights:
- AuM up to an all-time high of £13.6bn from £12.6bn in Q2, marking the third successive quarter of positive net fund flow,
- Net inflows of £351m during the quarter
- Financial year to date net inflows of £710m (9 months to 30 June 2020: £615m net outflow)
During the Quarter, the group launched its Premier Miton European Sustainable Leaders Fund, which has attracted good investor interest since launch with AuM at the Period end of £60m. Another launch is planned for September 2021: the European equity income fund.
So Premier is expanding and diversifying its offering of actively managed funds. It also says its ‘business platform [is] capable of managing significantly higher levels of AuM’. So there’s scope for good, profitable growth here if the talent can attract further inflows.
Mike O'Shea, Chief Executive Officer, commented:
Since the beginning of the financial year, we have seen strong flows into our European and US equity funds. This has continued during the Quarter. In addition, we continue to see good flows into our top performing UK equity fund range. Our UK Multi Cap Income, UK Value Opportunities, UK Growth and UK Ethical funds all saw net inflows during the Period. I am also pleased to report that it was a good Quarter for our Diversified multi-asset fund range and for the fixed income bond funds.
Conclusion
It’s hard to pick any faults in today’s brief update, with AuM at record levels and new funds being launched. The valuation is undemanding and the StockRanks are picking up on favourable financial data. Fund managers are scalable, with great potential for operational gearing. Hence the rush for scale and M&A.
The obvious risk is if market sentiment turns, and potential outflows in the event of sustained underperformance. On that note the group’s funds all reported positive investment performance in Q3, although there were net outflows in its Multi-Asset and Investment trust funds.
That said, over a nine month period, total AuM has increased from £10.608bn to £13.612bn so it’s clearly a positive trend for now. There’s no denying the collective share price performance of fund managers in recent times - a very strong part of the market right now.
There’s a 6% forecast yield here to boot, so this ticks boxes across growth, value, quality, and income.
Tharisa (LON:THS)
Share price: 129.16p (+0.51%)
Shares in issue: 269,059,931
Market cap: £347.5m
(I hold)
Tharisa is a producer of Platinum Group Metal (PGMs) and Chrome concentrates from its mining operations in South Africa. Its open pit Tharisa mine has 14 years of open pit and 40 years underground mine life.
In terms of additional projects, there is the Vulcan chrome processing plant and Salene Chrome in Zimbabwe that the company is spending money on.
It is producing prodigious amounts of cash at current spot prices. Yet it trades on a forecast PE ratio of just 4x. So are the current results sustainable? That concern must in part explain the stock’s apparent cheapness.

There are always reasons behind a low multiple. In Tharisa’s case, it is exposure to PGM prices that can fall down as quickly as they shoot up, and the territories in which it operates. South Africa might introduce an export tax on chrome and Covid has made production tricky in the past. Even so, Tharisa is well placed to continue operating responsibly and in a socially distanced manner due to the open pit nature of its central asset.
The fact that the group’s parent company is based in Cyprus means Tharisa has a slightly unusual structure to it. Add to that the fact that commodity prices can be fickle and we can conclude that Tharisa is not for everyone.
But those with a higher risk tolerance or that specialise in commodity producers might be interested. This is an SIC holding - you can read the more in depth pitch here, which goes into more detail around the supply/demand dynamics of PGMs.
- Five million fatality free shifts (FFS)
- Record mining rates and tonnes processed; PGMs produced up 11.4% to 39 koz, Chrome Concentrates up 18.1% to 379.7m kt
- Average PGM basket price +138.8% to $3,804/oz
- Balance sheet strengthened with cash increasing to US$80.5m after US$10.8m interim dividend payment and capital expenditure on its Vulcan development
FY2021 guidance is maintained - that’s for 155 koz to 165 koz PGMs (6E basis) and 1.45 Mt to 1.55 Mt of chrome concentrates.
The average PGM basket price is up 15.6% quarter-on-quarter. It would be prudent to forecast a degree of reversion in Q4. The group says its basket price remained above US$3,000/oz ‘at the time of writing, despite the recent decline in the rhodium price’.
Stainless steel producers are operating at historic high levels, creating robust demand for ferrochrome, which bodes well for the current and future chrome ore price.
Sea borne logistics costs continued to trend upwards - this is from South Africa to China, so it sounds like this is an issue in many markets.
Net cash improved by c$13m despite paying $11m in dividends in the quarter and a significant amount on Vulcan capex. This project is set to finish in the coming quarter, in which case we might expect capex to reduce beyond that.
Phoevos Pouroulis, CEO of Tharisa, comments:
Operationally, the third quarter was one of the strongest in the Company's history, with record mining and processing rates, supported by strong PGM and chrome pricing… Revenues and margins continue to be healthy as the combination of our favourable PGM basket saw record prices, in addition to a steady increase in the pricing of our chrome concentrates.
These price increases are a direct result of the increase in demand for our critical metals as economies focus on rebuilding post the global pandemic. Moreover, given the rapid adoption of decarbonisation initiatives, we see these prices being sustainable for the foreseeable future.
Conclusion
At the half year mark, the group had produced 75.1 koz of PGMs and 730.7 kt of Chrome Concentrate for a profit before tax of $104.6m. Let’s book in another $60m of PBT for Q3 on account of the record basket price, and then another $40m in Q4 (somewhat below the $52m average of the first half). That yields an FY21 profit before tax of some $206.6m, or £150m, which would be a forecast PE ratio of just over 2x.
Or another way: Peel Hunt recently increased its FY21E EBITDA forecast by 71% to some $303m. Taking the current exchange rate, that’s £220m. Net cash in Q3 is $41.8m, up from $29.8m. Let’s assume that rate moderates (a lot) in Q4 and Tharisa ends the year with a round net cash figure of $50m - that would give an enterprise value of £304m, meaning the group would trade on an EV/EBITDA multiple of just 1.4x.
You can plug in any numbers you like of course - including more bearish projections as it’s possible that the group’s basket prices fall a long way - but even so, there are a lot of perfectly reasonable projections that conclude the group is undervalued. Given that, it would be good to see the group buy back shares at these levels. In fact, while the CEO is on the Major Shareholders list, there was actually quite a lot of director selling in the second half of 2020.
Let’s note that Rhodium, one of the key drivers here, has come down in price recently. So if that continues, it’s likely the Q3 performance will not be repeated on the same scale.

But Tharisa will remain profitable and cash generative barring a more serious decline in basket price. The key risk is ultimately the prices of the metals Tharisa produces. On that point the group comments:
The use of PGMs in the hydrogen economy has not been fully recognised… PGMs play a vital role not only in emission control in traditional drive engines but a major role in hydrogen fuel cells, the greening of the economy and PGMs continue to be a critical component of the changing drive train make-up. [The robust outlook is] evident in the demand for the precious metals in a number of growing diversified industries, while PGM production increases across the industry remain limited, therefore supporting stronger long-term prices
Covid is another concern. The group’s guidance is premised on the current level of economic activity being maintained, but South Africa is at an adjusted Alert Level 4 as Wave 3 reaches peak, and Tharisa has recorded an increase in active COVID-19 cases from prior waves. So that’s far from certain.
Risks aside, Tharisa’s growth projects remain on track. The construction of the proprietary Vulcan fine chrome recovery plant is on schedule for commissioning by year end and will add an additional 20% chrome to current production levels at low operating costs. The new development project in Zimbabwe, Salene Chrome, is also progressing well and is planned to be in production start-up before the end of the calendar year.
I don’t want to labour the point, but miners are risky and not for everyone. Many of the best long term investors leave this part of the market well alone. But if you do get involved, then the prospects at Tharisa look encouraging.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

53 comments
@Paul Scott it would be great to get your updates views on Tharisa given recent progress and Ukraine etc. Any chance of an update?
deleted wrong post.
Abtan
Thanks for your input, appreciated.
I don't think its a scam, but the audit doesn't really prevent that. All that says to me is that it verifies the judges are there on that day, they picked a location, and that the closest entry in the system has won prize - ie. they haven't allocated it to their friend who was miles off.
So in that sense, BOTB do not 'pick' the winners. If that Prash fella happened to successfully get it right 5 times in a row, the site would have no choice but to award him the 5 cars, no matter how implausible or fixed it sounds to everyone else.
Using a rough estimation if you played every week the expected win rate is 1 in 5000 weeks, or 1 in 2500 if you get your wife to play as well. So 3 in the current space of time and the Brandon Klayman example raises the possibility that people can raise their chances above the norm.
I don't think the audit would pick up a scenario where customers contacted judges, a provisional 'leak' of projected answer given, and multi-accounting used to bombard lots of entries around that spot. The audit would only care that the winner is the closest to what the judges say. So it's possible to have a situation where something passes an audit, but also is not legit.
To see two events of very large probability occurring is quite surprising; i just wouldn't be surprised at all if multi-accounting was in use. After all, it's not illegal, more entries make BOTB more money, I don't expect them to be very hard on it as most people won't do it.
I guess what I haven't been able to shake is how winners are reported. I would guess many people are like yourself, preferring to take the cash and not the car. Yet the winners videos all have the implication that the person has won the car.
The local press stuff is not persuasive to me. I've been a journo a long time ago, stories like these I suspect are already written. How else would a local rag know that someone has won? The stories all pretty much follow the same formula. Given one of the board members previous ties to News International this is no surprise.
I don't think press coverage is any indication of legitimacy. Recently Football Index was exposed as nothing more than a ponzi. But this had a load of features in respected publications, and people 'invested' as a result. The reason why those articles ran was because Football Index paid affiliate revenues for new business generated. The same kind of deal I think BOTB is doing with the Sun - a perfect target market.
So the biggest bugbear is the lack of any winner social media; I find the 'I don't have social media, so why should anyone else', not that good. To be sure not everyone has social media. It would be normal to Google one or two names and find nothing. But when that number goes to 15, 20, and they have nothing or virtually dormant accounts that is a bit suspicious.
I did find a previous winner with an active Facebook account, and very active - multiple posts per day, lots of photos. She posted the official BOTB video of the day she 'collected' the car - but since then, no mentions, no photos of it either. Prior to winning she re-posted BOTB communications like other winner videos, but that all stopped after she won. But you would think that winning would make her to have an even more favourable outlook on the company and enter/repost other competitions.
Combined with that other lifestyle winner who can post pictures of trainers but not of his £12,000 haul of electronics, I really sense that my suspicion of some kind of NDA is about right. But then again, much like the multi-accounting, is this illegal? Probably no, so as a shareholder it may not bother you.
Personally I think more regulation could come in. You could make an argument that for any gamble, punters should be given sufficient information of the probability of winning. For prize competitions online this could be as easy as a real-time counter of tickets sold; and/or a mandatory minimum prize payout ratio. So, there could be a cash top-up to bring that in line if the car is not sufficient.
For instance I regard some of those raffles trying to shift houses as a bit of a con. Omaze's charity structure means that most of the public won't criticise it: 80% of net proceeds go to charity. But I think a lot of us would know that net means that any number of large expenses could be thrown at it. Stuff like TV advertising must be running up the bills heavily, but all that gets paid before the charities get a cut.
The last set of results showed a large increase in turnover (amount of BOTB games played) yet also a bigger increase in profits - less tangible prizes given out per pound staked. Yet I bet virtually all players would have no idea whether implied value is getting better or worse. In fact it would be possible to drive down payout levels to very low levels (which then means profits are very high) and many players wouldn't have a clue.... they pay money every week, not really expecting to win, so are not very disappointed when they don't win, and still play again the next week.
With virtually all players losing, value is very diffcult to perceive. I think BOTB do a much better job than the competition here, with video content and consolation free bets.
But I guess for shareholders there must be some ambivalent feelings regarding this: increasing player fairness with regulations would be seen as a good thing by most of society but would be bad for BOTB business.
If these prize competitions become common, I think its inevitable that it'll happen as no doubt there will be more unscrupulous operators who wouldn't mind ripping people off.
Best Of The Best (LON:BOTB) (I hold)
Hi Snoo and any holders
I don't usually comment on a company unless there's an update or news, but I have snoozed recurring tabs in Chrome and this morning the following Alexa.com web traffic tab for BOTB popped up:
https://www.alexa.com/siteinfo...
The apparent rebound in July (which was after the last "warning" update) looks good, though for complete transparency:
Despite the above, the reason I bring it up is because I noticed a mention of "Omaze" in the Alexa results.
I've heard it mentioned on this site too as a competitor to BOTB so I've decided to check out their website. I have a few thoughts to share:
https://www.gamblingcommission...
As far as I can see there is no skill, judgement or knowledge required - punters just buy a ticket and hope they win.
There is actually a specific section for house raffles on the gambling commission website, but as per the screenshot above, the company specifically states that it is NOT a house raffle.
https://www.gamblingcommission...
4 . Finally Omaze is 100% not a charity, so it can never claim it is running its competitions as such. From the "Fundraising Regulator," which Omaze specifically mention on their website.
https://www.fundraisingregulat...
----
In conclusion, I'm not even sure how Omaze is allowed to do what they are doing in the UK.
With Best Of The Best (LON:BOTB) at least there is a discussion on whether it is skill-based - Omaze seems like it's a pure housing raffle (which it claims it isn't) or possibly a Prize Draw, which if it is, looks to be illegal.
It will be interesting to see how this one pans out. For the moment though, at least in my biased eyes, Omaze doesn't seem like a serious competitor to Best Of The Best (LON:BOTB) .
Cheers
A
Fine work Mr Holmes. I suggest Best Of The Best (LON:BOTB) shareholders put a discreet call in to the regulator! The regulator can’t claim Omaze are under the radar as they’ve been on a TV advertising blitz of late.
Gus.
Best Of The Best (LON:BOTB)
Thought I would have seen some pushback against my comments.
Looked into what I wrote a bit more on the weekend, so some other points.
Max entries per competition is 75. It was 150. It seems to me that an generous approximation of the odds of winning a competition if you buy maximum tickets is 1 in 5000. Thus the odds of winning 3 competitions comes out to 1.25 trillion.
For the Prash guy in practice it'll be less than that, as it may be safe to assume that he played in multiple weeks and didn't win, and also maybe also made multiple entries. But still on the face of it I think it leaves the odds beyond credibility. Combined with that Brandon guy (whose likely odds of winning so many competitions in that time must be around the same ballpark). I am quite unsatisfied with that considering these two cases are came in about the first 10-15 I looked at (only taking the unusual names).
Still haven't found any online presences of winners showing off their winnings. On the assumption that winners of cars suddenly turn into shrinking violets for fear of getting robbed, I looked at the other stuff. This guy won £12,000 worth of technology in April - he has posted some pictures of trainers he got, but not a hint of anything he supposedly has won. He is a bedroom DJ, with a Mixcloud, Instagram accounts but not Twitter?
I can only presume with the lack of reply the default position is that most people will agree that this doesn't look good, but will look the other way and give the company a pass on this. That is fine, but some of the plausible explanations for it I think are worthy of attention:
First case is whether it is possible to game the system by getting the judges general prediction in advance. If that could happen, naturally the odds increase. I don't view this as likely, although conversely I don't view the judges as high-profile enough. For instance if they paid for a current famous footballer or manager that would be really useful as he could front advertising campaigns as well.
The more likely case is whether there is multi-accounting going on. I have some experience in the industry and most female accounts are suspicious, basically only created on behalf of a male in order to take bets or use bonuses that the male account is banned from. Thus multi-accounting is disliked, because those multi-accounts ultimately take value away from the book. I don't think there is the same motivation to go after multi-accounters in the same way here, because they would actually make more money for the company rather than lose it.
Another point on the winners; using people's real names puts out a lot of information. In the case of Prash and his wife, we can see where they live and their jobs and also their address. There could be something missing - ie a very rich relative in the family, or multiple houses - but on the face of it these aren't rich people to the extent that their prizes would make up a substantial part of their net worth. Using Streetview on the residential address given shows that none of the prize cars seem to be in there. I believe the logical thing to do would be to actually take the cash.
It reminds me that I went on holiday with a housemate that played BOTB in its retail guise at an airport - he loved cars and was attracted by the actual car being there. Yet if he won, he couldn't have kept it. For one, he couldn't drive to work in it. Affording the insurance would also have been an issue. He would also have to park it on the street outside our house where it would stand out like a sore thumb. Or he would have to pay to keep it somewhere else. The opportunity cost of holding a car instead of cashing it in is thus incredibly high, as he could have used the money to make a deposit to buy a house. Or if he owned a house, make some other investments which dont have such a high maintenance cost.
I think the above is true for a good proportion who win competitions, who didn't give thought to the practicalities of owning. But the winners list implies that nobody takes the cash, and they are pictured with the car. Is that really credible? Maybe I've missed something here, but if your total net worth is under £50k, and you win a car in excess of that, it makes no sense to keep it given the cash alternatives on offer.
I do think the reasons for the non-acquisition by betting companies are a few: the valuation is too high, and the barriers to entry low (the bigger books could simply add a 'Competitions' tab on their site if so inclined) but also that they might not be able to run the competitions in the current guise without attractive adverse attention either from their userbase or the regulators. For instance it seems possible that BOTB could list a Boeing 737 as a prize, even if they had no way of getting one, because they get to choose what the prize is every week.
There seems to be two primary defences against wrong-doing, one is that everything must be above board because its a PLC. This didn't stop Patisserie Valerie being a fraud, even though prior to that it, it looked like a superb company outperforming the market which had director selling despite a bullish outlook.
Second as mentioned before is that it would be hard to keep a secret. But a much bigger competition (McDonalds Monopoly in the US) was a fraud for years before it was discovered.
FWIW like I said before I don't think there is necessarily wrong doing, but what I think is happening is that most people take the cash. In the case of that tech bundle link I posted above, the alternative is £10k and many people would already own most of the items in that bundle. The site gives people the cash under condition of making a video pretending you are taking the prizes and an NDA from talking about it.
That would seem to explain the lack of active Twitter accounts I've seen. After winning it may be that your acquaintances are quick to tag you in a conversation and ask about it, it may be better not to chance it and just not have Twitter for fear of letting something slip that breaches the NDA, or have the not good look of ignoring your acquaintances questions about the car. I do notice that the CEO at some point deleted his Twitter account; that many not mean anything on its own, but I would regard genuine winners social media as some of the best free advertising you could get - such as re-tweeting their interactions.
Why would they do this? I can think of a few reasons; if people suddenly realise that winning a car is more hassle than its worth, or that the cash prize is better value, the kind of 'impulse' element of playing goes, and if you are playing for cash, why not just play the lottery? Secondly there is a hard line in between prize competitions (no regulation) and lotteries (needs licence) so it makes sense to represent as as the former as much as you can.
Genuinely interested to know if I am alone on these concerns.
Best Of The Best (LON:BOTB) (I hold)
Hi Snoo
Thank you for all your posts. I meant to come back to them earlier, but then got side-tracked.
I'm in a bit of a rush so will bullet point some responses:
I like my practical car and have no need for another one. Also, I know nothing about cars.
Let's not forget that his parents run the GP surgery he works in (it's on their website). They are clearly not a poor family and I imagine they wouldn't be willing to risk going to jail for participating in a scam.
Also, they do disclose in the youtube video that he has won before.
Youtube Video
Here are 3:
https://cdn.botb.com/media/228...
https://cdn.botb.com/media/358...
https://cdn.botb.com/media/297...
Note that Wilkins Kennedy was incorporated under the name of Azets (as were several other subsidiary accountancy firms), hence the apparent difference in auditors in the 3 letters marked above, but it really is the same auditor.
I cannot imagine either the auditors (which look international) or the lawyers would let their reputations be tarnished over something as simple as a spot the ball competition.
This could of course be a very elaborate scam, but there's a lot of evidence implying that it is really just a spot the ball competition with quite significant cash prizes.
Cheers
A
”masterful inactivity” more or less the same as “benign neglect.”
Hi Pail.
You mentioned "The Art of Execution" yesterday and its advice to either sell completely or add on a large drop in the SP of any stock one holds. As a result I added more Jarvis Securities (LON:JIM) yesterday and today, at just under the mid-price... ...so thank you for that
I guess you should be applying this principal to Best Of The Best (LON:BOTB) ?
Don't know about the chances of Best Of The Best (LON:BOTB) as I missed the greatest opportunity whiles back but do hold Jarvis Securities (LON:JIM) and have added to that over the years. I feel there is a consensus that the SP has some way to fall over the next couple of working days.
Silver
Premier Miton (LON:PMI) good write up Jack. One thing I would add is that they appear to be a good 30% undervalued compared to peers sitting at PE of 10 vs 13-15 range for others. I suspect this is a remnant of "growth" scepticism when they merged but the last few trading updates appear to be dispelling.
Mind the illiquid gap though - I already hold but tried to buy 7000 the other day and couldn't get anywhere near. Even when I put 2000 in the best they could muster an offer on was 169 shares at the price !! I wasn't going to chase it so I didn't investigate much further but worth bearing in mind.
Premier Miton (LON:PMI) I had no problem on Friday buying a larger quantity via Barclays using the Quote and deal facility. Curious!
Here's the much awaited PIWORLD interview with the very popular Richard Leonard. His views on markets, where we're at in the economic cycles, and those companies which he's been buying. His new picks include Made.com (LON:MADE), Devro (LON:DVO), National World (LON:NWOR), Synthomer (LON:SYNT), Wickes (LON:WIX) He gives an update on Reach (LON:RCH), Polar Capital Holdings (LON:POLR), Redde Northgate (LON:REDD) and of course Novacyt Sa (LON:NCYT) He's pretty clear what he's buying and selling, so you can assume he holds anything here. It's purely educational, to understand some of his thinking. Please do your own research on any stocks mentioned. Video & podcast.
Forthcoming PIWORLD events:
Vertu Motors (LON:VTU) Investor Presentation. We're delighted Robert Forrester, CEO and Karen Anderson, CFO will present to investors followed by a Q&A. Tuesday 13th July, 4pm. Register here. This has taken a long time to come to fruition, so I hope there will be lots of interest.
Exploring the listed private capital opportunity - Part 2. Listed private capiatl gives all investeors access to high-performing private equity and credit instruments. Presenting will be BMO Global Asset Management, CVC Credit Partners & £OCI. We had Part 1 earlier this week, and the funds are impressive, all achieved annual IRR of over 15%, sometimes much more. Not a class I was familiar with and it was rather interesting. Monday 12th July, 2pm. Register here.
Accrol Group (LON:ACRL) full-year results webinar. Thursday 15th July, 1.15pm. As part of the Group's financial results roadshow, Dan Wright, Exec Chair and Gareth Jenkins, CEO will present FY results. We'll get an update on the integration of the new acquisition and how business is shaping up.
Sosandar (LON:SOS) full-year results webinar. Wednesday 21st July, 11am. Another company Paul knows very well. They seem to have navigated CV19 very well. It will be interesting to get an update on trading once lockdown is relieved, and the advertising world returns to normal pricing. Register here.
Tekmar (LON:TGP) (virtual) Capital Markets Day. Thursday 22nd July, 4pm. Tekmar a leading provider of technology and services for the global offshore energy markets, is hosting a virtual Capital Markets Day events for investors. The events will provide further information on the Company’s strategic plan, and how, by building on the strong foundations of the business today combined with a robust growth strategy and attractive market fundamentals, the Company intends to deliver on its ambition to double organic revenue within 5 years and improve the financial characteristics of the business more broadly. Register here.
Re Richard Leonard He's pretty clear what he's buying and selling, so you can assume he holds anything here. I think this should read everything? Keep up the good work Tamzin - your contribution to our investment knowledge and decision making is invaluable!
People are obviously going to own the shares they think are best, and want to talk about. What's the problem with that? I'd rather hear people talking about shares that they believe in, and have backed with real money, than not.
It's only ever a problem in my mind, if people talk up a share, whilst selling, or intending to sell. That's crossing a line, and people who do this get found out, because they contradict themselves I find.
Hi Tamzin,
It's great to see more and more interviews being published. The new branding looks good as well. Nice one :).
Hopefully you'll be able to get Mark Slater back at some point to talk about his investments. Certainly keen to hear his views on Best Of The Best (LON:BOTB) !
Cheers,
Tamsin, I'll await the Vertu Motors (LON:VTU) presentation with interest and sadly won't be able to make it live. I hold as looks like good value for all the reasons stated on SCVR previously. But one thing that does annoy me about Vertu Motors (LON:VTU) is it seems to waste a lot of money marketing multiple brands and I am finding its multiple online offering confused. With the Formula One adverts for example it is advertising both its Macklin Motors and Bristol Street Motors brands - surely that just undermines name recognition and means their marketing budget is not being put to best use? To improve their online offering I think they should try and focus on a single brand - ideally one that sounds a bit snappier than 'Bristol Street Motors' which always sounds like a single showroom in the backend of nowhere. It would be great if this marketing strategy and multiple brands strategy could be probed during the Q&A!
Seeing Machines (LON:SEE) (I hold) down c10%. Not sure why!
Xpediator (LON:XPD) and Reach (LON:RCH) have also been marked down today (I hold both) quite a lot on no news.
Suspect that if you did a screen for "shares that have more than doubled since jan 21" you would see quite a few of today's larger fallers.
Whether you sell out or buy the dip is (obvs) a matter of personal judgement.
I tend to go for what I call "masterful inactivity"
"masterful inactivity" Love that phrase - have it on my wall now!
Not that relevant but i served on the 'investment committee' of a sole-owned Co's pension scheme in the early 2000s. me, the owner, his mate (barclays stockbroker) and a couple of others.
Met every ~3 months. The owner basically refused to invest for about 18 months. Drove me mad - what is the point of an investment committee if we do not invest. Then he went for cos that were FCF positive and yielded > 2./5% and his mate liked. At the end of 36 months we were in the top 10% of uk equity based unit trusts and that performance persisted until ~06 when the Co was sold.
He started his first business around the early 70s and was always very keen on cash.
There was another 1y long period when he refused to invest. He also hardly ever sold.
That is why "masterful inactivity"
Reach (LON:RCH) is only down according to my platforms.
I've had a look at the top performers in my folios, most are only up and down 1% apart from Halfords (LON:HFD) which is down 4%.
There is bound to be some profit taking after a good run in the last year, I have just top sliced some of mine and sold Future (LON:FUTR).
Hi Paul - you mention Best Of The Best (LON:BOTB) which is an interesting one I think. The reasons for the recent falls seem fairly clear, but the big question is at what level are the concerns/uncertainties already 'in the price' and the risk/reward becomes favourable. There is no answer to this without a crystal ball of course, but to me it is looking attractive again at current valuation. Even in a scenario where growth is faltering a bit , it seems highly unlikely to not be growing at all (and even at this year current earnings its sitting on PE of 12 now - almost certain to reduce materially forward for next year even with slower growth - which hardly seems demanding). This looks quite likely to look cheaper again in 12 to 24 months than it does now (or for the price to have corrected upwards) unless there is a real nasty lurking in terms of growth disappearing completely or some regulatory 'black swan'. I seem to remember that in a recent interview with Tamzin (before the latest updates from BOTB) you'd said that if it went back down to 2000 you might go back. Here we are now 20% below that level even. What are you thoughts on it now given the updates we've had since this time and have your views on it changed much? Cheers, BIACS
Morning BIACS,
You mention Best Of The Best (LON:BOTB) (I hold). I can't make up my mind on this. Let's list the bull & bear points, to clarify my thinking!
Bull points-
Bear points -
Overall then, I'm probably more bullish than bearish, but only have a small position, and am not sure whether to increase it or not.
The facts have materially changed, so my previous view on valuation is obviously now no longer relevant. What do you guys think about BOTB?
Regards, Paul.
"Mgt blotted their copybook by selling substantial stake at £24, then warning on profits shortly afterwards"
Good write up. For me the above point alone was enough for me to sell all my shares at a loss.
I have top sliced this in the past (but not anywhere about 30 unfortunately) but it was still my biggest holding in March this year at about 15% so I have been hurt short term by this. I don't at this point see any reason to sell but I also don't want to add to something that's still a big holding as I think the upside still outweighs the downside at this level.
Clearly it seems that management have been surprised but the weakening dynamics but I think they have a track record of coming up with ways to build the brand. Since the announcement they seem to have teamed up with the Sun newspaper and Talksport so they are clearly trying new things to generate interest.
I would love them to invest in international expansion but for some reason it's never on the agenda and of course could we see the return of an interested bidder again.
Its all up in the air and no one can discount a profit warning on the horizon. For now I am holding and I'll wait when happens
"Only credible operator in its field (plenty of rubbish, me-too competitors)"
Best Of The Best (LON:BOTB) - I should say that this is coming from the position of not having played either, but Omaze definitely appears to be a credible competitor to BOTB. Based on what Ive seen, I think Id be more inclined to use Omaze if I were to do this type of thing.
What do you guys think about Best Of The Best (LON:BOTB) ?
Hi Paul
I agree with a lot of what you have said and as a holder I am in 2 minds on what the company's future looks like.
More short term, I'm actually not worried due the point made by BAICS. The company doesn't need to grow very much to make the share price look cheap again.
I also wonder if there will be a UK boost once everyone realises they have loads of holiday this year but can't go anywhere.
Additionally H2 is traditionally the larger period so when the inevitable slowdown came (as seen across the gambling industry right now) it's good that it was in H1.
Growth aside, I see that the company has already started decreasing their costs of sales/additional cash prizes, so profit margins should at the very least be maintained.
My only wish is that management start sharing more performance metrics. I don't understand the logic in not divulging information on something as simple as Marketing spend, or the lifetime value of a customer. I guess when management still own 50% of the company it's hard to get them to do anything.
I personally wish they had sold more of their holding, or at the very least, engage more with us PI's.
Cheers
A
Best Of The Best (LON:BOTB) - I saw that 888 Holdings (LON:888) mentioned the other day that "Since 17 May, when UK retail and leisure venues reopened, average daily revenues in the UK have, as expected, been approximately 20% lower than the year-to-date period before that." I guess this may have read across to BOTB and potentially help anyone who is trying to put a number on how much their revenue has dropped.
Hi Gwillis68
I hold 888 Holdings (LON:888) so I saw that -20% comment too.
"Since 17 May, when UK retail and leisure venues reopened, average daily revenues in the UK have, as expected, been approximately 20% lower than the year-to-date period before that."
2 things to add:
I think it's difficult to assume an exact correlation between the 2 companies, especially as 888 Holdings (LON:888) makes most of its money from online casinos, which entails someone taking time out to play, whereas Best Of The Best (LON:BOTB) is a 5 minute game that someone might only play once a week.
I'm sure lockdown has affected both negatively and it will be interesting to see the direction they take throughout the rest of the year as "normality" returns.
A
Thanks Paul - never held Best Of The Best (LON:BOTB) and kicked myself all the way up from about 200p! Have taken a keener interest recently given the pullback but like you I struggle to pull the trigger on buying now, though I suspect long term it will continue to be a rewarding share.
Broadly speaking my concern here is that I can see a short term drop in profitability post easing of restrictions which feels to me like maybe something in the region of 15-25%. Thus I struggle a bit with broker forecasts for them to increase EPS next year. If I conservatively strip 25% out of eps I come up with 110p for next year and I feel that number leaves me some margin for error. So personally I am looking for 1400-1500p as a buy at which point it should yield roughly 5% as well I think with room for special division around the 70p mark.
As you very rightly point out it is illiquid though so I can see a situation where there is a big share price overreaction if that short term eps drop does occur. Thus I think my own strategy will be to pick half my allocation up if I see the 1400p range and then wait to see what the outlook is confirmed as for next year and either average down if there is a big negative reaction or if valuation isn't too stretched.
Worth keeping an eye on Omaze though as they seem very active and their offering includes cars too.
For me Paul even if the company doesn't grow it pays a dividend, has a strong balance sheet and is very casg generative allowing it to pay out special dividends. I am happy to keep collecting and whilst the share price goes up and down happy with the income aspect.
IMO the main danger for Best Of The Best (LON:BOTB) is regulation.
Omaze in US for their car auctions seem to work differently. Each car has a specific end date for auction close. If the car is worth $100k and they have only sold $100k worth of tickets, then tough.
BOTB have a large pool of cars and there is one winner per week (and midweek). But the individual car does not have a specific end date, so they can choose the car where value of tickets sold is greater than the value of the car.
This seems to give them a good deal of flexibility how to run things. So rules such as giving away a specific car on a specific date would be bad for them.
Let me say one thing that seems suspicious to me. The vast majority of players I think would be males from the lower demographic bands who like showing off (why enter a competition for flash cars otherwise).
Yet trawling through the list of winners and Googling some even some of the more unusual names sees the same kind of pattern: a slick BOTB winning video featuring the happy winners published on their website, a collection of spammy news articles from their local press, but no social media profiles like Twitter accounts where you would think they would be celebrating or posting some non-publicity shots of the cars...I find that odd. For instance there is a double-barrelled video game creator who won who you would definitely think would be on Twitter, but he isn't.
Maybe it's just me, but can anyone find a Twitter account of someone who has won? It seems that hardly any of the winners do. Or are names changed to protect the winners, but if so why use real people?
Actually I found one:
Winner 459 was Prash Thurairatnam
He has a Twitter account here, albeit not very active. Photo is of the same guy. He has been active in the past year, but makes no mention at all of winning the car, when you think winning would be a big thing.
Looking back, in 2015 he actually won before, there was a video to it. No pictures of this amazing car though. Also his wife won a car in 2016 on BOTB - he didn't say much about that either.
Seems incredible luck for one household to win 3 cars!
When I was researching Best Of The Best (LON:BOTB) I played all their games and to be honest I cringed at the prospect of winning and featuring on their website, and certainly wouldn't post my winnings anywhere if I did win. Not least of which for security reasons, it is unwise to advertise recent big ticket purchases on social media and sports tracking apps etc (See thieves using Strava app to target high end bicycles). Also I don't use social media.
It's hard to imagine the scale of conspiracy that would be required, engaging all of the small press outlets over the country, using hundreds of stooges with false identities and back stories. It seems unlikely. I looked up approx 4-5 winners with "obscure" names and skimmed articles about them from The Herts Advertiser, Coventry Observer and the Doncaster Free Press, found one Linkedin profile (which matches the job description given in the video).
I find it more interesting to note how well BOTB have engaged the local press to further advertise their business.
At least two of those articles sign off with:-
"To see XXXX’s emotional reaction alongside a host of other lucky winners, head over to BOTB.com."
From their terms
=======
11. Winners' Personal Data
11.1 Acceptance of the prize by the Winner will mean they are required to have their photo and video taken by the Promoter for promotional purposes (Public Relations and Marketing), both immediately after their win and in the future for use in accordance with rule 6.2, unless prohibited by law.
11.2 By entering a Competition, you agree to the use of your name, address, and/or photograph or other likeness, as well as your appearance at publicity events without any additional compensation (save for reasonable travel expenses) and as required by the Promoter if you are declared a Winner.
======
I've only skimmed the articles so I can't tell if an interview has been conducted or whether they have taken notes from the videos but participation appears to be mandatory.
Best Of The Best (LON:BOTB) doesn't interest me as it encourages gambling without, I think, offering any part of the proceeds to charity. From the various threads over on PH it does appear there's loads of similar lotteries and draws - eg https://www.pistonheads.com/ga...
I imagine set-up/ development costs are light - the challenge is to build a recurring client base before the marketing budget is blown. Similar to many SaaS businesses in that respect?
TBH the teaming up with the media isn't of much interest to me considering that one of the directors has a past with News International.
Basically it's a paid advertorial where the article/comments are written already, then the paper gets a cut of the revenues generated when users click the links. That's pretty much what the 'teaming up' with the Sun is. I would think it would be standard practice to try and get a story of the winner featured in the local press, but not all local papers will carry it because it's not really news.
I just don't understand why the past winners seemingly have no social media. For that guy I mentioned, it just seems unnatural considering him and his wife have won a few hundred thousand quid of cars. It is unlikely to be security related, as the videos show where he works, and for his wife, their house and kid. Posting a few pictures of a car is nothing in comparison.
Another guy, Brandon Klayman, has a distinctive name but no social media despite running a digital marketing company! His acceptance video shows him saying he hasn't won anything, but he won an unnatural amount of competitions that month.
Best Of The Best (LON:BOTB)
I had a look at some of the recent you tube vidoes and i find it impossible to believe the winners shown were anything other than 100% pukka. Winners seemed normal bods and all the comments were nice ones that were happy for the winners. I actually came away from watching the you tube videos with the thought that the competitions are less scammy than i previously presumed was the case.
You can watch one very happy winner here.
https://www.youtube.com/watch?v=c-HOiQw8ueg
The videos Best Of The Best (LON:BOTB) make IMO try to make it look like they are off the cuff, but are pretty scripted.
For instance take a look at the video of that Prash guy in 2019. By this time he and his wife had already won a car each. The man comes in with a BOTB logo on the front and he pretends not to know - the guy even has to remind him of his name.... yet only a couple years before there were in a BOTB promo video together.
I don't think it is a scam, but I do think there is some bending of the truth. For instance, the videos imply the winner keeps the car... but I reckon most users might consider the cash to be better. If you lived in a working class or middle class area, parking a supercar on the street looks rather out of place, and for those that are younger, the insurance costs would be extremely high. The depreciation on most of the cars would mean that the car would be worth less than the cash alternative almost as soon as you drive it away.
Re LON:BOTB I wonder if 'the facts have materially changed' when it comes to operating performance? It seems pretty logical to me that as we were all 'released' and with Euro Football looming other 'normal' distractions of life would resume. You see that reflected positively in todays strong beat from Campari Group. However, what is not discounted in the share any longer is a return to the 'new' normal, something that will become easier under autumn/winter conditions and ping induced self-isolation. I suspect activity is already back up to its pandemic levels and look forward to the companies next report. What is less palatable is to close the 'formal sale process' for the business in February and then a month later see the family take £60m out of the company. The unabashed positive sentiment towards Mr Hindmarch and team will be forever dented if a return to usual trading conditions and cashflows is not forthcoming. As they still have 47% of the capita, I have taken the view to double my holding at £15 over the past week or so. Fingers crossed / ball spotted !
Premier Miton (LON:PMI)
Nice TU today - AUM up 8% for the quarter 2.8% of which is inflows. Seem to be finally making the merger with Miton work (which is how I hold) and new products proving their worth.
Stock report looks good and there is a Liberum Note on Research Tree raising TP to 210p
6% dividend looks good.
Phil
Would be interested in any comments from Open Orphan (LON:ORPH) from anyone, I hold - the RNS to me is fairly vague - no numbers unlike Cambridge Cognition Holdings (LON:COG) referred to above- which I don't hold.
It seems the RNS has been issued in response to the recent share price drop - it is up 8% as I speak but I would not be surprised if the numbers turn negative again.
FinnCap (house broker) reckons the contract is worth £3m. What I don't understand is that the Irish wizard in charge has been telling the hVivo facility has been fully booked for 2021 for some time.
There were some weasel words along the lines of 'we' re fully booked but just managed to slip this small contract into the schedule'
Beware of Irish blarney, or any blarney for that matter
£orph (I hold). I think Mr Friel's business has good value to unlock. I'm not sure his approach to presentations helps his cause.
My morning smallcap tweet:
Open Orphan (LON:ORPH) £DKN MJ Gleeson (LON:GLE) Bidstack (LON:BIDS) Cambridge Cognition Holdings (LON:COG) Chamberlin (LON:CMH) Senior (LON:SNR) Ilika (LON:IKA)
Open Orphan (ORPH) wins 'significant 'HRV & Influenza human challenge study contract. No £££. CO was "solidly EBITDA profitable in H1 2021 and we remain on target for a profitable and successful 2021." [SP=25 Cap=168m]
Dekel Agri-Vision (DKN) guides H1 significantly up on 2020's €15.4m rev, €1.9m EBITDA and €0.4m net profits. [SP=NA Cap=NA]
MJ Gleeson (GLE) guides FY(June) marginally ahead of market expectations and in line with 2019. [SP=870 Cap=507m]
Bidstack (BIDS) exclusive partnership with Belgrade-based Nordeus, best known for its flagship game, Top Eleven, the world's most successful mobile football management game. [SP=2 Cap=8m]
Cambridge Cognition (COG) £1m contract as the cognitive assessment partner for late phase cancer trial. [SP=163 Cap=51m]
Chamberlin (CMH) expects a return to profitability this FY as it recovers from BorgWarner contract loss. "We have already received considerable interest in our growing gym equipment range and now are preparing to launch a range of premium quality cast iron cookware for distribution across Europe." [SP=10.5 Cap=7m]
Senior (SNR) which recently rebuffed a 200p offer guides H1(June) rev down 13%, ahead of management expectations. Also expects FY slightly ahead of management expectations. [SP=160 Cap=671m]
Ilika (IKA) £24.7m placing and PrimaryBid offer at 140p, a nasty 30% discount, even though it's only 9% of capital. Needed to support the development of Ilika's solid-state electric vehicle pouch cells and to keep the lights on as it never make any money. [SP=200 Cap=278m]
In line: £
more good news from Cambridge Cognition Holdings (LON:COG) :
Cambridge Cognition Holdings Plc (AIM: COG), which develops and markets digital solutions to assess brain health, is pleased to announce that it has won a £1 million contract as the cognitive assessment partner for a late phase cancer trial. This is the second contract for a top ten pharmaceutical company with a strong pipeline of oncology products. The revenue from the contract is expected to be recognised over the next six years.
https://www.investegate.co.uk/...
Cambridge Cognition (LON;COG)
Another £1m contract, rev over 6 years.
Transforming from a struggling minnow into a more substantial player.
Revenue booked for years ahead, now profitable, throwing off cash, margins 81%, excellent products are winning numerous contracts and enhancing reputation.
New CEO of 2 years Matthew Stork is executing his strategy - well done.
Must now be ahead of expectations for this year.
Was lucky to make my first buys in April last year just under 22p as I saw the incredibly depressed share price and the much improving newsflow. Had been following for years.
Hoorah! These contract wins at Cambridge Cognition Holdings (LON:COG) are rolling in, I'm definitely right about this one - the company is much more commercial under Matthew Stork. Revenues over 6 years - so only a gentle increase in this year's forecast likely (which was already in the bag, due to existing order book).
What I particularly like, is that contracts are high margin, relying on decades of experience/data, and are a relatively small component of the total cost of drug trials. Once big pharmas get into the habit of using COG as part of the process (looks like that is underway, judging from stream of contract wins), it could lead to repeat revenues. Little in the way of competition, just some Australian outfit. Profitable now too, on a run-rate from Q4 2020 onwards.
I don't back any particular type of management, in terms of background or style, just looking for effective entrepreneurs. I think we have that here.
COG reminds me of Bioventix - specialised niche, with massive barriers to entry. £100m+ market cap looks possible in a bull market, in my opinion.
You only need the occasional big winner, and run it (resisting the temptation to bank profits, and ignoring market volatility), to mop up all the mistakes! I tend to have one big winner each year, and it's often the most unlikely candidate.
Regards, Paul.
Very pleased to see rapid growth at Cambridge Cognition Holdings (COG), the software company, but I wonder if the comparison with "early days" Bioventix is perhaps a little far stretched as Bioventix was profitable since its fairly early days on AIM and has a track record of re-investing its profits to good effect, hence the excellent ROCE. By contrast, COG is not yet profitable, although it did list its shares at about the same time as Bioventix. It may be worth spending a couple of hours doing due diligence on the internet if you are considering investing in COG, particularly visit the Cogstate web site as this Australian competitor's business appears to be a bit more developed than COG's but perhaps the growth being shown by both companies indicates that this is a good sector to be working in. There are also competitors in the US as you might expect.
£AGL More news on the brain cancer front this morning summarised by CEO.
"This is important new work by the world-leading Hamburg-Eppendorf cancer centre. Prof. Wikman and her team have demonstrated the utility of the Parsortix® system in isolating CTCs from cancer brain metastases and demonstrated superior CTC positivity rates than those seen in studies using other enrichment technologies. Cancer brain metastases cannot be accessed for tissue biopsy without highly invasive procedures and a liquid biopsy alternative would be of great benefit to patients to monitor and optimise treatment."
Morning, JimMcLad. Yes, to expand on your statement if I may, because this is a truly important system, not just for the company's success (which we are all interested in of course!) but for literally millions of cancer sufferers, now and in the future.
The Parsortix system developed and perfected by Angle (LON:AGL) continues to demonstrate its value as a major aid to supporting best practice cancer treatment in many areas. It is currently awaiting FDA clearance for use in breast cancer treatment, and its approval cannot come quickly enough for current and future patients.
Now Angle (LON:AGL) and its Parsortix system has shown considerable success in overcoming challenges associated with isolating CTCs from brain metastasis patients in three different cancer types in research form. University Medical Centre Hamburg-Eppendorf has published results of new work undertaken in patients with brain metastasis.
Liquid biopsy from peripheral blood is a particularly attractive solution in brain cancer because of the difficulty, medical complications and cost associated with taking a tissue biopsy from the brain. The characterisation of metastatic tumour cells can be crucial in helping to inform personalised treatment decisions, but, because of the serious risks involved, most patients with brain metastasis will never undergo a tissue biopsy unless undergoing surgical tumour resection.
In this albeit small study, patients with 1. primary breast cancer, 2. non-small cell lung cancer (NSCLC) and 3. melanoma with subsequent brain metastases were screened for CTCs using the Parsortix system. Successful identification results were between 2-3 times superior when compared to previous studies into cancer brain metastases which utilised other CTC enrichment technologies, including the leading antibody-based system.