Small Cap Value Report (Mon 1 Nov 2021) - SHOE, PIER, LOK

Good morning, it's Paul and Jack here, with the SCVR for Monday. Today's report is now finished.
Agenda -
Paul's section:
Shoe Zone (LON:SHOE) - trading update raises profit guidance again for FY 9/2021. I missed the update from 13 Oct, so cover both today. It looks an excellent recovery, although there is a question mark over undisclosed benefit from business rates relief, which will be substantial given SHOE operates from 410 sites. With net cash, and divis returning sooner than expected, this looks a credible, and good value recovery share. I also like the growth in online, and a change in strategy to make online sales "core" in the future. Thumbs up from me!
Jack's section:
Brighton Pier (LON:PIER) - eight university town bars, eight mini-golf sites in retail and leisure hubs, a pier in Brighton, and a theme park in North Yorkshire. This is an unusual combination of assets. Current trading looks understandably positive and the shares are up, but the company has disappointed before and this looks like a complex and costly enterprise to run. The shares are illiquid too, so it's high risk.
Lokn Store (LON:LOK) - strong results and although the shares look expensive, there is a long term growth opportunity here which can be realised via a relatively low risk strategy. Margins are already high but the company suggests these could improve further. It might be worth looking beyond the high earnings multiples but there's no doubt 33.5x forecast earnings feels pricey.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to cover trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section
Shoe Zone (LON:SHOE)
90.5p (pre market open) - mkt cap £45m
It’s called a “further” update, because this cheap shoes retailer had already given a year end trading update here on 13 Oct 2021. Unfortunately, that one slipped through the net here at the SCVR and we didn’t cover it, which is a great pity, as looking at it now, the previous update was strikingly good compared with previous gloomy utterances from the company.
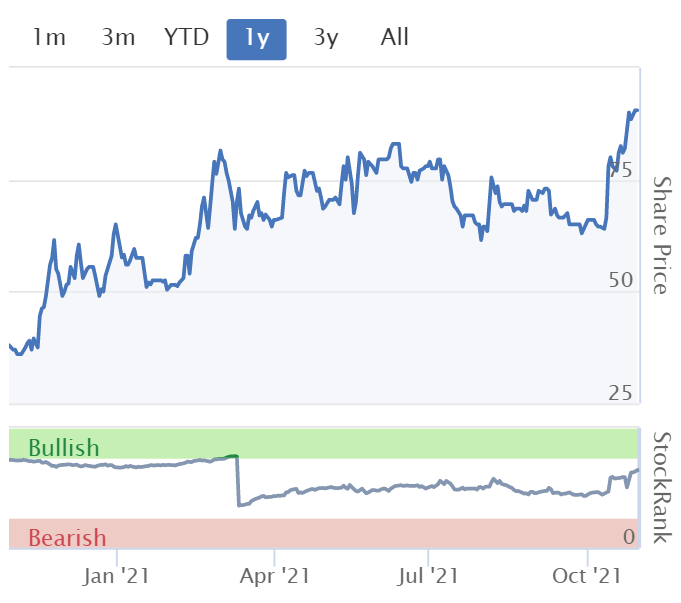
Note that the share price has been a stand out performer in the last year, something that would not have been at all obvious as likely to happen, a year ago. Being an importer of cheap, fairly bulky items (boxes of shoes) made in China, I would have thought that SHOE would be in the eye of the storm re supply chain costs/delays. That’s why I didn’t really give the company a second thought. What a mistake that was! There doesn’t seem to be any rhyme or reason with supply chain problems - some companies are getting slaughtered, other companies are taking it in their stride, with SHOE seemingly being in the latter camp. Hence why investing is particularly difficult at the moment, with companies splitting into winners & losers, on an unpredictable basis. That's why I’m increasingly looking through supply chain issues, as something short term, that should be resolved at some stage, hopefully in 2022. That’s clearly what the USA markets are thinking, and we tend to follow their lead, usually after we’ve had a panic sell-off in the UK, over potential problems that US investors largely ignore!
I’m increasingly seeing some good buying opportunities in UK small caps - I pointed out the illogical sell-off in Sanderson Design (LON:SDG) (I hold) on Friday when it lurched down to about 155p. Coincidentally the excellent David Thornton of Growth Company Investor also flagged the same buying opportunity just a couple of hours later, in the latest edition of GCI which was emailed out late morning. That seems to have driven a strong rebound in SDG on Friday, which seems fully justified by the recent good newsflow & figures, which both David and I simultaneously flagged up.
SHOE looks a good opportunity too, this is what it says today -
Today’s update - profit guidance has been raised again for FY 09/2021 -
...reported profit before tax is now expected to be in the range of £9.0m to £10.0m for the 52 weeks to 2 October 2021
This compares favourably with the previous guidance (13 Oct 2021) of
Profit before tax expected to be not less than £6.5m
That’s an increase in guidance of £2.5m to £3.5m.
Of this increase -
- Pensions - £1.5m is non-trading, relating to pension scheme contributions, which don’t need to go through the P&L, but seem to have been mistakenly budgeted for via the P&L, which does raise the question as to why SHOE’s finance department made this apparent mistake?
- Favourable forex has boosted profit by another £0.4m.
- The balance of about £0.6m to £1.6m of increased guidance must be down to improved trading.
That’s all clearly good news. Although we are not told the extent of taxpayer support in arriving at this decent level of profits. Business rates relief in particular will have been a large number, given that SHOE is trading from 410 sites, and therefore should have been disclosed as a material item, in my opinion. Without being told that number, we really can’t determine what the underlying level of profitability would be in future. The hope would be that if there are no further lockdowns, then increased profits from trading would offset the withdrawal of business rates relief in due course.
Previous trading update from 13 Oct 2021 -
I wish I’d spotted this at the time, but never mind, It reads very well.
Stand out items include a high gross margin of 61.3%, which is near the top of what retailers achieve.
Strong online growth, which has now grown to 25.7% of total revenues. There’s been a pivot towards online, with management now describing online growth as “core” - quite a big change in strategy.
Supply chain cost/delays had been offset through reducing the number of product ranges, thus reducing cost per unit - very impressive this has been absorbed. Although SHOE expects further supply chain cost/delays for a further 6 months.
Net cash of £14.2m, meaning dividends are expected to re-start sooner than expected - very positive. Although cash flattered by £2.5m due to temporary delays stock intake.
My opinion - this looks very good to me, and the market cap of only £45m looks too cheap. So a thumbs up from me. As management says, the business has emerged from the pandemic “a leaner, stronger, amore resilient business”.
EDIT at 08:24 - a note has just come through from Zeus, many thanks for that. They're penciling in £8.0m adj PBT for FY 09/2021, falling to £6.5m next year, despite revenues forecast to grow 31% to £155.9m next year FY 09/2022. Hence clearly I was right about the materiality of business rates relief withdrawal, that must be the main factor for forecast profits to fall, despite a big forecast increase in revenues.
Zeus's 10.4p EPS forecast for FY 09/2022 looks conservative though, and it's only just above half pre-pandemic peak earnings. With a rationalised cost base, and more online sales, I would hope SHOE should be able to achieve forecast-beating numbers in FY 09/2022 and beyond. Hence the forecast PER of about 9 is probably under-valuing the company's potential for further profit recovery, the way I look at things (i.e. the actual PER might turn out to be lower than 9, if earnings exceed these undemanding forecasts).
End of edit.
Jack’s section
Brighton Pier (LON:PIER)
Share price: 77p (+16.67%)
Shares in issue: 37,286,000
Market cap: £28.7m
Brighton Pier operates Brighton Palace Pier, eight bars, eight indoor mini-golf sites and, more recently, it has acquired the Lightwater Valley theme park in North Yorkshire. It’s an unusual assembly of leisure assets, making PIER somewhat unique in the listed space.
It’s an unusual portfolio of assets so I’m curious to know if lasting value can be built, particularly with its move into theme parks.
The group was previously Eclectic Bars, so it has been forced to move away from its historical business of nightclubs, has bought a pier in Brighton, opened some mini-golf sites, and has now acquired a theme park in Yorkshire. The bars are in university towns, while the mini-golf sites are in ‘high footfall retail and leisure centres’.
It doesn’t immediately sound like a highly efficient enterprise. It actually sounds like it must all be very hard to run well, although the vision is quite ambitious.
Merlin (since delisted) was attractive due to its high barriers to entry so there is logic to running these kinds of assets. But a theme park is a much different enterprise to a mini-golf bar; one large, more complicated site with rides that require a significant amount of upfront capex.
Group trade over lockdowns has been heavily impacted, of course, and at £29m market cap, this is a very small company with poor liquidity, so the risks are high.
The share price chart shows the company ran into trouble before Covid, and has since failed to recover to its IPO price.

To its credit though, shares in issue have stayed broadly the same, which is quite a feat.
The group wants to create ‘a growth company that operates across a diverse portfolio of leisure and entertainment assets in the UK’ targeting both organic and acquisitive growth. Longer term, it wants to act ‘as a consolidator within this sector.’
There could well be organic growth opportunities across the estate and you could potentially build something of enduring value with these more unusual, large assets. Brighton Pier, for example, was the fifth most popular free attraction in the UK prior to the pandemic, with over 4.9 million visitors in 2019, making it the UK's most visited landmark outside of London.
Nevertheless, there is also probably quite a high demand for capex and, operationally speaking, this seems like a complicated micro cap to run. Best of luck to management.
To end the year with the acquisition of Lightwater Valley has been particularly satisfying and a sign of how we have remained focussed on our stated aim to expand the Group by further acquisitions.
Both FY20 and FY21 have been heavily affected in differing ways by Covid, so comps are difficult. Nevertheless, here are the highlights:
- Revenue -40.3% to £13.5m,
- Profit before tax up from a loss of £9.5m to a profit of £4.2m,
- Basic and diluted earnings per share up from a loss of 25.5p to positive 11.5p,
- Group adjusted EBITDA more than doubled from £2.5m to £5.1m,
- Adjusted EPS up from a loss of 5.3p to positive 5.7p.
I would be wary of adjusted EBITDA for such an enterprise given the high demand for maintenance capex. Depreciation this year is £1.2m and, while capex was just £258k, in the prior year it was £1.6m which is likely more usual. So wear and tear is an ongoing business characteristic.
Furthermore, EBITDA this year was helped by some £5m of business interruption insurance income, £0.7m of COVID-related local authority grant income and £2.2m of furlough income which has offset staff costs. So adjusted EBITDA is fairly meaningless on an ongoing basis. I’m not sure that such government contributions should be included in ‘adjusted’ metrics.
Whilst the late-night bars were almost entirely closed throughout the whole 52-week financial period, the Pier and Golf divisions were able to reopen for trade during the key summer months of July to September 2020. This summer trading period contributed approximately £2m of earnings to the group, helped by the Eat Out to Help Out scheme.
Cash burn was reduced in the year and additional funding provided with help from suppliers, landlords, banks, and government.
Current trading sounds encouraging and the group comments:
With the easing of restrictions during summer 2021, the Group's diversified offering has been in prime position to capitalise on pent up demand for leisure experiences. With the Pier and Golf divisions both open, the addition of Lightwater Valley for the full 13 weeks and the Bars finally open for 10 weeks, total sales for the 13-week period to the end of September 2021 were £15.9 million. This is 145% over the same period in 2020, and 44% ahead of the same (pre-Covid) period in 2019 (or 30% ahead of 2019 if benefit from the temporary VAT concession is excluded). This strong summer 2021 trading performance, coupled with the benefits from VAT and rates relief, indicates that this year could be an exceptional opportunity for the Group to recover some of its lost earnings if it is able to continue trading without further restrictions.
Lightwater Valley - On 17 June 2021, PIER acquired the entire share capital of Lightwater Valley for £3.6m with a further £1.2m paid to clear Lightwater Valley's outstanding bank debt on the date of acquisition. Total cash outflow is therefore £4.8m.
The acquisition was funded from a £2.0m extension to the group's revolving credit facility and existing cash resources. The transaction was expected to be immediately earnings accretive post completion.
For its last full year of uninterrupted trading (year ended 28 February 2019), Lightwater Valley recorded sales of £5.1m, EBITDA of £1.1m and pre tax profits of £0.6m. The total fixed assets being acquired are stated in the balance sheet at £4.1m.
Conclusion
It’s hard to gauge what the group’s underlying prospects are from such a set of results. The group says current trading is exceeding expectations, with like-for-like sales up 81% on the same 13-week period of 2019. That’s very positive and probably explains today’s share price reaction.
FY profits have been helped hugely by government schemes and insurance income, so it’s hard to gauge how the enterprise trades on an ongoing basis (not really the company’s fault). The group’s broker, Cenkos, forecasts 11.9p of earnings per share for FY22 which, if achieved, makes the shares look cheap at present.
The balance sheet does not look particularly strong, with net tangible assets of £8.8m although cash has improved from £2.6m to £7.1m.
There’s a lot of risk here in terms of the lack of liquidity and forced move into other business lines which arguably require different skillsets to run. I’m concerned about how large the ongoing cost base might be as well, given the group’s acquisition ambitions.
The theme park is an interesting move but I suspect these are highly specialised assets, so I’m waiting for a longer period of undisrupted group trading and to see how Lightwater Valley performs before making any serious decision.
Shares have responded positively to the update, up around 16%, and current trading looks quite buoyant but I worry that the spread of businesses makes this a tricky and costly enterprise to manage. I also wonder, given the size of the group and its more unusual collection of assets, if there is a temptation to take it private at some point.
Lokn Store (LON:LOK)
Share price: 879p (+5.27%)
Shares in issue: 29,686,787
Market cap: £260.9m
This is a supplier of low cost, secure storage space, which is actually an attractive structural growth area.

The Self-Storage Association UK (SSA UK) Annual Industry Survey 2021 notes that public awareness of and demand for self-storage is increasing. Lok n’ Store opened its first self-storage centre in 1995 and has grown consistently over the last 26 years. Revenue has increased fairly steadily over time.

Today it operates 37 self-storage centres trading mainly in Southern England which generate strong profit margins, and it has a pipeline of 13 secured stores with additional opportunities beyond that.
But the shares do look expensive. It’s likely there’s quite steady growth to be had here, but you are paying up for it now.

Excellent trading, significant asset value growth, ambitious store opening programme and accelerated dividend policy
Highlights:
- Group revenue +21.3% to £21.9m,
- Adjusted EBITDA +23.2% to £11.89m,
- Operating profit +29% to £7.46m,
There’s been a strong year on year recovery, with total occupied space up from 5.9% to 35.3%, occupancy up from 69.6% to 85.8%, and pricing up by 8.7%.
As a result, cash available for distribution is up 33.3% to 28.4p and the annual dividend has been increased by 15.4% to 15p - the tenth annual dividend increase in a row. Cash inflow from operating activities before investing and financing activities was £12.2m, up 25.6%.

Adjusted net asset value per share has also increased by 31.6% to £7.31. The average cost of debt is just 1.54% and the loan to value ratio is a modest 21%.
Pipeline - the group says new ‘landmark’ stores will deliver further growth. £26.9m has been invested in new stores and the pipeline of 14 new units will take the group total to 51, adding 38% more trading space.
Management comments:
We have made significant progress on our new store pipeline, with two new stores opened in the period and one existing store acquired contributing to our net asset value per share growth of 31.6%. Three stores are currently under construction opening early 2022, and four more are soon to commence. This pipeline of new stores delivers 38% more space and will add further momentum to sales and earnings growth.
The group has cash balances of £9.1m (2020: £13.1m) and a £100m revolving credit facility, which should finance the current pipeline. Interest cover is more than 10 times against a covenant of 2.5 times. LTV based on net bank debt was 21.0% versus a bank covenant of 60%. Net debt is £56.3m (2020: £38.3m).
Conclusion
Very positive results, and the outlook is equally as encouraging. Occupancy increases point to further revenue growth and potential margin expansion if sustained, momentum is expected to continue, and the group has a sensible and relatively low risk growth strategy of prudently opening new landmark stores.
The UK self-storage market continues to grow but remains surprisingly under-developed relative to Australia and the US. When the industry first emerged over here, companies were predominantly single owner sites often located in industrial areas. Larger operators (managing ten or more sites), such as Lok'nStore, have recently been developing purpose-built stores in retail-facing locations offering customers a higher standard of product and service.
You would think that it would be relatively easy to go into this line of business, but the group says that barriers to entry include the difficulty in finding and securing suitable sites as well as gaining the appropriate planning consents. This, it says, is why larger operators now own or manage around a third of all facilities and hold a 45% of market share in terms of revenue and space.
Returns have been strong over the past few years for the likes of Lokn Store (LON:LOK) , Safestore Holdings (LON:SAFE) , and Big Yellow (LON:BYG) but given the market stats quoted by the company perhaps there is a longer term growth opportunity. No doubt the valuation looks quite demanding at these levels, but then again brokers have been upping their forecasts and the company sounds optimistic.

Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

52 comments
Seems the new Finance Director Terry Boot at Shoe Zone (LON:SHOE) is really working out well then.....
Thanks for the replies re: Simon Thompson/Investors Chronicle. Fully agree Stockopedia is the go to place for proper background and research! Was just thinking about maybe subscribing to IC for a few months, but maybe I'll give it a miss if the minimum subscription is 6 months.
turbo, Obviously the choice is yours and I'm not trying to sell an IC subscription but mine occurs every 3 months and comes to £34.37 for the digital mag plus £34.38 for the Alpha. The Alpha goes into a lot more detail and if it draws your attention to the Company then you can come across to Stocko and dig deeper. I find that these articles can be useful for triggering your investigation into the Company - much as happens here and with the Stock Slams. If I make more (and hopefully a lot more) than the costs then that's good enough for me.
Thanks for your reply GN100, will take a closer look :)
check your local library (or ask them to stock it) ours has a new copy each week.
You can normally find an IC subscription ofer for getting the first 4 or 6 weeks for free - just remember to cancel your DD before the 4 or 6 weeks is up. I've subscribed for a while (and more recently also to the Alpha bit), but am debating about giving it a rest and perhaps trying something else....................Sharepad, or another magazine.
Whilst Ive enjoyed the couple of years I find I fall behind with the weekly magazine and often find myself 2 or 3 weeks behind.
I don't think I have ever identified a specific stock to undertake further research on from IC, but I have had reinforcement of some of my holdings and have enjoyed the more general articles. Like others here I get a lot of info from this site and also a number of other subscriptions.
A cracking business which never seems to put a foot wrong. I hold.
Which stock are you referring to?
£LOK. I have to say that I find this utterly fascinating. And just can't really get my head around it. Here you have a business with an Enterprises Value of c. £300m and a Market Cap of c. £250m. It has a decent brand / track record but basically has big sheds for sub-let. No patent. No real magic sauce. Definitely no monopoly. On a stand alone basis it trades on Revenue, EBITDA and Net Income (pre-property value adjustment) multiples of roughly of 14x, 25x and 78x. Pre-expansion capex the business throws off FCF about £8m according to the Prelims, which are presumably somewhat inflation protected via the ability to push through incremental yearly price increases. But presumably not too much as clients do have some choice / price sensitivity. All in all it means a FCF yield of roughly only 3%, which explains why the Div Yield is less than 2%. Much of the net asset value expansion seems to have come from successive rounds of positive property re-valuation. Presumably this can always go two ways. Net Debt has been steadily rising as the site portfolio expands. Leverage is modest yes to Market Cap but not on a Net Debt/EBITDA Basis.I guess my question is who is the marginal buyer at this valuation and what is their investment thesis? It's clearly not a high yield income play? A warehouse property play? Someone betting on continued positive property re-valuation with some modest property portfolio growth attached? Is this seen as ultra-low risk and business cycle independent? As I say I'm genuinely fascinated by who looks at Lokn Store (LON:LOK) at current levels and goes, lovely, I will have me some of that. And ditto holders who have done well and choose to stay in
Ecr Minerals (LON:ECR) . I know we don't analyse resource companies here but in my opinion this RNS is disgraceful. The CEO died suddenly over the weekend at the age of 51, and all they can manage is a very brief RNS entitled "Directorate Change" in which we are told he was "a good CEO".
https://www.investegate.co.uk/...
Well the Ecr Minerals (LON:ECR) RNS did say a bit more.
Craig was a good CEO and a great friend and his loss will be felt by many. Our thoughts are with his family at this difficult time
posted in wrong thread
Trident Royalties (LON:TRR) Q3 2021 Activities Update today seems to be the reason behind the 20% uplift in the share price
https://www.stockopedia.com/sh...
Seems to have been a Simon Thompson tip more likely as the spike started after this was published (not much reaction from the initial RNS)
Like most Simon Thompson tips I'd assume he hasn't really wired into the numbers and operations...just spinning another speculative illiquid small stock looking for a nice bump on his performance spreadsheet.
I don't have a strong view of Trident Royalties (LON:TRR) . I've looked a bit and watched management present. Royalty companies can be great. But the risks and costs to starting up such a business are considerable. I don't like that Trident is so young and with very (imo) inexperienced management. A startup in this area from a seasoned greybeard is exciting and more worth the risk. In addition, I have not liked how the CEO has presented a lot around the share price and how it should go up as as the market cap of the biz increases the rating afforded to royalty businesses goes up due to the 'financing (g)arbitrage' double whammy whereby big royalty can capital raise less dilutive AND the valuation multiple afforded to royalty biz is much higher than small scale miner.
A beautifully circular argument....has truth for the winners in the space...but not everyone wins. Early stage royalty businesses have heightened negative optionality too in that they are more exposed to downside in anyone stream and that will disproportionately hit valuation that disables ability to build business.
Check out the CEOs bio (from their website - its not weighty:
"Adam Davidson has over 10 years of experience in the natural resources sector, most recently with Resource Capital Funds, a leading mining-focused private equity firm. Prior to RCF, Adam held positions with BMO Capital Markets in Metals & Mining Equity Research and with Orica Mining Services in Strategic Planning. He has extensive mining capital markets experience across a breadth of jurisdictions and commodities. Adam began his career with T. Rowe Price and also served in the U.S. Marine Corps.
Adam is a graduate of the Australian Institute of Company Directors and previously served as a Non-Executive Director of private gold producer RG Gold. He earned his MBA from the College of William & Mary and completed a post-graduate in Mining Studies from the University of Arizona."
It might work but the risks are gigantic. I think Anglo Pacific (LON:APF) is risky with downsides not fully appreciated (I'm waiting for an accident to consider a buy there)...but Trident is off the scale.
Hi Mojo,
I'd appreciate any of thoughts you'd care to share on Anglo Pacific (LON:APF) (I hold) downside.
It does seem something other than general market sentiment is holding down the share price at the moment - H1 was entirely underwhelming but Q3 earnings just came in at $23.6m, higher than H1 $22.2m - but the shareprice is down. It looking increasingly likely that Q4 will be even higher which will help to pay down debt well ahead of schedule and set them up for upcoming payments on upcoming royalties/streams incoa and piaui.
The cobalt stream is starting to look like a good buy at last but their coking coal royalty will disappear very quickly from next year onwards - and as yet their portfolio doesn't really have anything to replace it and move the shareprice on? Is this the main downside you see?
At the moment I'm looking for some upside on the FY results and FY22 predictions, collect the divis and then exit most of my holding,
cheers
Mark
Hi Mark
I'm not very informed on Anglo Pacific (LON:APF) so take my views with big pinch of scepticism. They are very much drive-by-banalysis.
So IMO reduce future returns from coal a lot (be simple and make zero and then add a little residual for some return). Note, the fact that the coal assets are held way below the recent battery metal acquisitions despite throwing off so much cash flow tells you that Anglo think its near used up as an asset for them....and I'm not on top of it but Q3 was a really nice surprise.
Thanks Mojo for taking the time - that's a very useful summary of Anglo Pacific (LON:APF) points - positive and negative. I think you've got it pretty much spot on - my views align with yours. Gives me plenty to think about.
I was not aware of the CEO's previous. He has not inspired me, though he did well with the Liorc Iron Ore and flipped it to buy into the Cobalt stream which was a bit slow at first but seems to be coming good now. Like you I wonder why he's leaving now when it seems that it might be coming together at last.Q3 came in as I anticipated - with current prices I expect Q4 to be higher.
With the golden goose tailing off in the next couple of years they do need another large stream/royalty to keep the cash rolling in, fund the dividends and pay for new acquisitions.
The good news is that the cash rolling in at the moment might just alllow them to fund another royalty/stream - the bad news is that there might not be a good enough deal available to them!
I agree with you there.
They may just strike lucky (again) as they have a development nickel mine 'Piaui' sitting in their portfolio - and a cheap option to raise the grr to ?4.25%? But even if everything goes according to plan - it won't come into production for a few years. So there could be a nasty gap.
I like the battery metal portfolio but don't think the numbers are great - unless they are really lucky with the prices in the next couple of years. I probably have too large a holding here, been holding on in the hope of a good exit point - still might happen but I will be watching carefully,
thanks again for the write-up,
cheers
Mark
"A startup in this area from a seasoned greybeard is exciting and more worth the risk"
I do think you are correct to sound a cautionary note. One should enter this trade with eyes fully open.
I would agree that 10 years experience is really not that that much, so he's still relatively new to the industry.
I have small stake in Trident Royalties (LON:TRR) mainly for the lithium exposure (around half of portfolio) which should have increased significantly since they purchased. The main risk is that very few of the assets are actually producing and still at the development stage, but for me worth a small punt.
Trident Royalties (LON:TRR) . That spike started at the same time as Simon Thompson's piece dropped into my in-box. I remember an interview with one of the Winterfloods executives and his comment was that the MMs read these articles at the same time as us, the stocks are almost always SETSqx so they merely mark up the price to take advantage of the article. Sure enough, the PI's take the bait and you can see the volume climb immediately after the article. Market forces in action really, supply and demand.
GN100, any thoughts on the quality of Simon Thompson's tips, wondering if a few months subscription might be worthwhile...
Have a look about and you may find a subscription offer for the IC. His tips are often pretty good but imo give poor price to buy at. Don’t try and follow the herd though for a quick 10% as you will likely fail.
A mixed bag, some good, some bad (a few total losses). Quality is pretty average. You are better off here.
Very bias in my opinion, very little about the negatives. There are no performance figures on his tips, only his annual bargain selection.
Agree, ST tends to only list the positive points (in a rather exaggerated way) as if he's trying to sell you something. I much prefer the balanced approach on here, where Paul and Jack weigh up both the bull and bear cases and readers can make up their own mind.
I discovered Paul and Stockopedia via Globo, which was one of Simon Thompson’s tips, he got into a real mess with that, he could not see any of the problems. Yes I quite agree he is like a salesman. When his tips go wrong he is always trying to make out there are not any problems.
turbo, as others have commented on this thread, a mixed bag. I would SUGGEST that if you bought his portfolio at around the beginning of the calendar year you may end up in profit, although it may be a long wait for some of them. One of the problems is, and this applies to most of the small-cap universe, to make a reasonable amount of money you have to often well exceed the EMS in your holding. If the share is illiquid then getting out can be a problem. As always there's no free lunch. Also, remember that ST is a journalist like any other, he has to produce an article for his editor and that is a tip. I think he is probably better at picking than some of his contemporaries. As has already been mentioned, I think you are better off here - no tips are given but the research is there for you to see and the collective wisdom of Stocko comes free with your sub. If I was to reduce to only one source of info it would be Stocko.
That spike started at the same time as Simon Thompson's piece dropped into my in-box
I have been looking into the effects of some of Simon Thompson's tips, in particular reported trades and the time of the tips. If it's not too much to ask, do you know the exact time that tip appeared in your inbox? Hrs:mins:seconds if possible?
It arrived in mine at 9:35. Presume is the same for everyone.
Thanks. The 9.35 time fits with the reported trades and does suggest that the ST tip was indeed responsible for the spike in price rather than it being a reaction to the trading update.
Some time ago I had a look at the effect of a Simon T tip. It was obvious that the minute the email hit inboxes there were a large number of people buying simply on the word 'buy' - they would not have had time to read anything about whatever the company was. I took the trades that were not a round number of shares - presumably £ specified - and found most of those numbers as sells later in the week as the price held in anticipation of those who did not pay the premium receiving the tip in the Friday magazine.
Good luck to them but not my style.
sharw Yes 0935 for me as well. You are quite right about the volume you can see how and when it grows on the one-day
chart.
FWIW I think it's insane to follow Simon Thompson tips and that the IC should not have this guy tipping speculative and speculatively priced micro caps to UK PIs. Very shoddy. He doesn't do good work...just cosmetic banalysis.
Bull market on and liquidity good and not throwing around much in the way of investment size...well you might tip toe thro his volatility and pick up a little return...tho still get hit with some fat tail downside in things.
Bull market and/or liquidity cools. Then even at small size you may find exit only available at chunky mark downs.
Bah humbug.
Re Brighton Pier (LON:PIER) I guess Jack is too polite to mention the elephant in the Chair called Luke Johnson with a 27% holding.
Re K3 Capital (LON:K3C) - looks good and under appreciated (perhaps a lot of info/change to parse). I added a comment here:
https://www.stockopedia.com/co...
Growth (organic and acquisition) plus margins means it still looks cheap imo (adjusting for margins and growth that is...there are many lower p/e stocks!) with a better mousetrap than other corporate advisory businesses driving growth and profits looking forward.
Another small but earnings enhancing acquisition in the UK announced by Water Intelligence (LON:WATR) this morning [I hold].
https://www.investegate.co.uk/water-intelligence--watr-/rns/acquisition-of-uk-based-wat-er-save-services-ltd/202111010700138176Q/
WH Ireland have upgraded again, based on this acquisition and the recent Q3 trading statement. Their numbers still look light to me.
Shoe Zone (LON:SHOE) Chunky director buys in May showed that the directors had faith in what was coming down the pipeline. Unfortunately as a result I'm overexposed so won't be buying more, but I was in there on Saturday with my kids. Impressed with the price and layout of the stores, didn't feel like a 'cheap' shop and a lot tidier than Clarks!
K3 Capital (LON:K3C) Final results ahead of expectations. Finncap have released a note this morning.
Game over re. the recent spat between Science (LON:SAG) and Tp (LON:TPG) with the announcement this morning that the incumbent CEO will be leaving following an extended notice period and the incumbent Science (LON:SAG) NED will take over as Executive Chairman pending appointment of new CEO. This follows the existing Chairman’s departure last week.
https://www.investegate.co.uk/....
Presumably at some future point Science (LON:SAG) will acquire the rest of the company that they don’t already own now they have de facto control.
Gus.
Thanks Gus. Am I wrong in thinking that there might be a relatively low risk trade to make here? On the (not certain) assumption that Science Group goes ahead and buys up the rest of TP Group, it will have to do so at 6.5p . Today's price of TP Group is about 4.9p, so you could be getting 30%-ish, if and when Science Group decides to complete the takeover.
The downsides I see are that (i) Science Group states it doesn't intend at any point to revisit the takeover, and the share price dwindles/declines (this could be offset by Science Group improving the TP Group business in the meantime); (ii) Science Group doesn't announce the takeover for a very long time, and your holding in TP Group suffers from opportunity cost and goes sideways/down; and (iii) Science Group gets to do the due diligence it originally wanted to do, and finds some awful gremlins in the accounts, and the share price tanks.
The 30% isn't massive but it's not to be sniffed at. It looks a decent risk/reward trade to me. The management of Science Group seem too proactive to do nothing. All things being equal (which they never are), they should either improve the business from their position as substantial shareholder and controlling party on the Board, and/or buy it.
Thanks, please tell me why I'm wrong.
Chris
Hi Chris.
Yes - interesting situation with Science (LON:SAG) / Tp (LON:TPG) . All the considerations you make are valid and no guarantees on anything in life but to my mind the risk reward looks reasonable. I think under TOP rules, Science (LON:SAG) are only required to pay at least the previous bid price if they revisit within a certain time period (6 months?) but after that they can rebid at a lower level. This said, the previous bid of 6.5p was made without the benefit of inside due diligence so presumably Science (LON:SAG) made some conservative assumptions. Unless there’s a horror show hidden in the books a lower price shouldn’t arise now Science (LON:SAG) have full access. One other consideration that comes through in the RNS is that Science (LON:SAG) have identified a lot of bid defence costs and fees from the previous aborted bid as well as expenses from buying out the old Board contracts and also some existing projects that are underwater. I could anticipate a fair bit of kitchen sinking in the coming months (not least part of the Science (LON:SAG) propaganda to demonstrate just how poor previous management were) that may well take the Tp (LON:TPG) share price lower giving an even better entry point/potential upside if a full bid comes through in due course. Over time I think Science (LON:SAG) will make Tp (LON:TPG) a better business, whether they buy them out or not, but it may not be a quick fix and there may some bumps along the way. Just a few thoughts, no advice intended.
Gus.
Yes, good point on the kitchen sinking, given the relative disdain from both parties throughout the process. It's hardly a buoyant market at the moment either, so this could easily drift down regardless.
Cheers.
Chris
Re Tp (LON:TPG) Science (LON:SAG) bid
according to my limited understanding SAG did not make an annoucement of a Firm Intention to Bid (rule 2.7 announcement) they only made a Possible Offer Annoucement - which had to be followed by a Firm Intention to Bid or Withdrawal of the possible offer within 28days under the 'put up or shut up' rules.
They chose to withdraw - so no offer period commenced - and are now subject to the 6 month period during which they 'shut up' and can't make an offer except under certain circumstances decleared in their withdrawal.
After that it seems like a fresh start? I am not sure that there are any rules on a price for an offer after the end of the 'shut up' period?
The mention of offer minimum price I can find in a quick skim of the taleover rules is
Rule 6.1 of the Code provides that if a bidder acquires an interest in shares in a target company:
• within a three-month period prior to the commencement of the offer period; or
• during the period (if any) between the commencement of the offer period and the
announcement of a firm intention to make an offer (a Rule 2.7 Announcement); or
• prior to the three-month period referred to above if the Panel is of the view that there are
circumstances which render it necessary to ensure that all shareholders in the target are
afforded equivalent treatment in accordance with General Principle 1;
then, except with the consent of the Panel, any subsequent offer by the bidder for target shares
must be on no less favourable terms.
It's not clear? Under point 3 the panel might be able to rule that the previous price bought in the market applied - but considering that SAG withdrew because of lack of due diligence maybe not?
I thought it was interesting that they stopped buying at 27% and didn't push up to 29.9% to improve their vote margin. Strikes me that SAG rarely do or don't do anything without a reason?
As I say I am not an expert - just based upon what I read. I decided to buy more SAG instead of TPG - that might turn out to be a missed opportunity.
cheers
Mark
Thanks Mark. That makes sense, and points towards Science Group waiting for 6 or more months before doing anything. And should they end up doing something, they could end up paying less than 6.5p, and, as Gus pointed out, playing down the short term prospects of TP Group in the meantime, by slagging off (in a non-libelous manner of course) previous management.
Re Science (LON:SAG), I believe Tp (LON:TPG) will need to raise new funds - Science (LON:SAG) has always said this is necessary. They do not have a past record of being generous in a takeover situation, and having removed the existing CEO and Chairman there is nothing in their way. As an existing shareholder, I shall be pleasantly surprised to see 6.5p for my small holding, but I doubt it.
I think the minimum offer amount is whatever is paid in the preceding 12 months rather than 6?
Directors are in a bit of a bind though as they are no longer unconnected parties and therefore will have to excuse themselves from any discussions around any offer they may make for the business. It will be the independent non execs that will probably have to opine on fairness of any offer.
Also, the directors are duty bound to look after shareholders best interests. Otherwise they risk a law suit against the individual directors. Would not be good for Science group if that happens as market would be unlikely to take it well.
As they only own 27% they need a lot more holders to accept a lower bid and why would they do that? The directors of Science group are now managing the business and they are duty bound to manage it properly. Given they own 27% they are also not incentivised to do anything else.
Vehicle Manufacturing and Supply
Some of you may know that one of my businesses is a vehicle leasing business. With regards to vehicle manufacturing and deliveries we received the following update from a large lease company which I thought may be insightful for those that are interested:
"Since the last update, the general situation unfortunately has not improved and remains extremely challenging for almost all of our key OEM partners. The general availability and now increasing costs of raw materials is impacting production in the automotive sector as well as many other industries globally.
The now high profile global shortage of semiconductors continues, and the backlogs in the critical parts supply chains in Europe means almost all OEM’s are advertising exaggerated lead times and uncertainty around future vehicle supply, challenges that will unfortunately be with us for some time.
There are some areas where we have seen more recent activity, so we can provide some more specific information on the following topics:
Specification changes:
More OEM’s are now being forced to remove specific features & options from vehicles, in order to maintain production volumes of different models.
These specification changes are now being updated on OEM’s websites at the point of announcement, to ensure customers can access the latest information, and make informed decisions. Encouragingly, OEMs are now more frequently making these changes as part of scheduled Model Year releases, therefore minimising the impact to orders already in build.
In almost all MY changes, reductions in the overall number of model derivatives and option combinations available are now common place as OEM’s simplify their model line ups, again to ensure production constraints are minimised.
Vehicle Pricing:
OEM’s are continuing to reduce new vehicle discounts. This started with reductions in the ‘high cost’ channels (e.g. daily rental and tactical) earlier this year, but increasingly, OEM’s now are reducing end user and now standard contract hire and lease terms.
Many now are unfortunately not offering price protection on outstanding quotes. Almost 2 years of lower than normal production volumes means increasing pressure to improve the profitability of the units OEM’s do manage to sell, so further discount reductions are expected this year and into the early part of 2022.
List price changes are common throughout the calendar year, though in the last 6 months we have seen higher than expected increases. As the cost of vehicle production continues to increase, the trend of steeper pricing changes is expected to continue in the short term.
LCV:
LCV (Light Commercial Vehicles) supply has been critical for many months now. Total production volumes for 2022 are being highlighted as a concern as many OEM’s are carrying full or almost full order banks into next year. Those that have spare allocation advise that these free build slots are filling quickly.
Again, model range simplification has helped some OEM’s improve lead times, though in general these are still considerably longer than passenger cars. OEM’s are currently reviewing order banks to identify orders that can potentially be removed or reprioritised by required date, to try and free up supply.
Aftersales:
OEM parts and supply chains issues are also of course impacting their aftersales and parts distribution networks across Europe. The OEM’s ability to deliver replacement parts out to their various markets quickly has been impacted, and unfortunately this means we are seeing extended downtime for certain vehicles awaiting replacement parts.
As we move towards 2022, it is becoming clear that for many OEM’s, profit will be a major driver underpinning sales strategies for next year. This will of course heavily influence which sales channels OEM’s are able to support with vehicle allocation. Low margin vehicle sales will almost certainly continue to be minimised where practical.
All OEM’s are very conscious of how vital it will be to continue to support their UK dealer network with dedicated vehicle allocation, as almost all dealers have had a very challenging last 18 months. Retail sales, due to their profitability, will continue to receive its own ring fenced vehicle allocation.
There are also expected to be further changes to the way dealers are targeted / remunerated, largely shaped by each OEM’s appetite to influence different sales volumes in the different channels.
Some more ‘positive’ news, some OEM’s are now faring better. Polestar and Tesla for example have very healthy stock position for Q4. Kia, Mazda and Hyundai are all offering reasonable lead times for almost all vehicle in their portfolio’s.
The summer factory shutdowns across Europe have all now been completed giving the OEM’s the time to complete essential servicing and retooling. This ensures these assembly plants can now operate at full capacity, as and when they have the parts supply and workforce to allow this.
The measures being taken by the OEM’s are now helping to slowly reduce average time taken to build vehicles, but the backlog of orders means this is not translated into lead time reductions…yet."
Recommended all cash offer for U And I (LON:UAI) from Land Securities acquisition vehicle at 149p/73% premium to Friday’s close.
https://www.investegate.co.uk/...
High premium to current price but well below historic pre-COVID highs (constant share count). 3.6% irrevocables from Directors and 32% Letters of Intent from institutional shareholders.
Gus.
U And I (LON:UAI)
Yep good result for holders here. Can’t really imagine there will be a bidding war here ? What do others think?
Probably not another offer but you never know. Just sold my holding for £1.485. Happy to take the money now for just half a pence under the offer.
Suggests there could be hidden value in these deeply discounted property companies. Perhaps could be a positive read across to the likes of Newriver Reit (LON:NRR) where a fair amount of the portfolio is earmarked for regeneration (mainly conversion to residential).