Small Cap Value Report (Mon 10 Feb 2020) - NMC, UPGS, BOOM, TND, VLX, LUCE, INTU

Good morning, it’s Paul here, with Monday's SCVR.
I hope that subscribers survived the weekend storms, without any harm to family, friends, or outbuildings.
Estimated timings today - I have a conference call with a company to prepare for & participate in, which is eating into my time this morning. I'm taking an early lunch break today too, to get out in the sunshine before it disappears (am trying to have a better work/life balance, exercising when I can - EDIT too late, it's started raining again lol!). Hence today's report will be mainly done by 1pm, but I'll carry on until c.4pm to finish off anything left dangling.
EDIT at 15:46 - I've covered as much as I can today, so today's report is now finished.
Being forced to stay indoors yesterday did at least allow me to get on top of the mountains of paperwork in my office, with what I call "speedy filing". This involves leaving large piles of paperwork untouched, for several years, whereupon it can simply be transferred directly into the recycling bin. Much more efficient than actual filing.
It's also useful thinking time, with my attention currently focused on;
China supply chains
We've discussed this before, but I noticed late last week that several shares which rely heavily on imports from China, began to drop sharply. A good example is Up Global Sourcing Holdings (LON:UPGS) which imports branded consumer goods, e.g. small domestic appliances, a lot of which come from China. Its business is bound to take at least a temporary hit from supply disruption. The market has anticipated this, with a sharp fall in share price recently, giving up all of the Boris bounce;
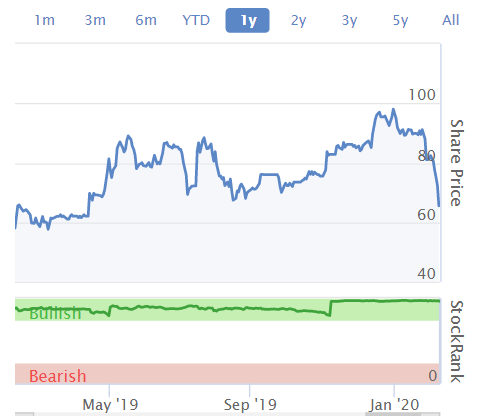
At what point does this become a buying opportunity? After all, with small caps, it only usually takes a handful of sellers to smash up a share price in times of uncertainty. If buyers are sitting on their hands due to that uncertainty, then sellers have nobody to sell to, hence the price is just marked down until bargain hunters emerge. This can create some marvellous opportunities.
As we know, catching falling knives can often be dangerous as there could be deeper underlying problems that the sellers know about, and the buyers don't. E.g. I got caught out with that on Mysale (LON:MYSL) shares in 2018, when the company's upbeat trading update turned out to be misleading, as much deeper problems were about to emerge. The seller(s) clearly knew that, but I didn't. Thankfully I twigged that something was wrong, and ditched my shares at a far smaller loss than would have been the case if I'd held.
Profit warnings which are due to a one-off, fixable problem, are my favourite type of profit warnings. It can often make sense to buy the dip, when a fundamentally strong company warns on profits in this way. Coronavirus & the supply chain problems it is creating, looks exactly that type of one-off hit type of situation. Although at this stage, we don't know how long it's going to have an impact, nor crucially if it's likely to spread outside of China on a large scale. If it does, then all bets are off.
Like many investors, I'm monitoring the data every day. There are lots of websites providing this data, although how reliable the data is, we don't know. The rate of growth is slowing, and numbers of cases have not yet reached into triple digits for any individual country outside China.
Here are the key questions to ask (not exhaustive, just what I could think of) when looking at companies that report supply chain problems from China (which I expect to see starting imminently, in trading updates);
- What is the level of inventories in the UK, and how long will these last? Just-in-time supply chains are not looking such a good idea right now
- If supplies from the Far East are being disrupted, then what alternative supply arrangements can be made, and how quickly (and at what increased cost)?
- How easy is it to cut costs (laying off staff, etc, if needs be)? Or are costs high, and fixed (worse case) - e.g. retailers, many of which import most of their goods from the Far East
- Crucially - how is the balance sheet structured? Running down inventories due to supply problems improves cashflow, but will the business be strong enough to be able to fund the re-stocking when it comes? This might involve having to pay cash up-front to alternative, new suppliers?
- Bank borrowings - how much spare capacity is there, and will the bank remain supportive? What are the bank covenants, and is there a risk of breaching them? In practice, in such a low interest rate environment, it's very unusual for banks to withdraw support from listed companies, but they can force companies into dilutive equity fundraisings. In wobbly situations, if banks see inventories run down, and short-term bank borrowings correspondingly reduced, could they be tempted to pull the plug in order to minimise their losses?
- On the flip side, could UK companies benefit from potential customers re-shoring production back to the UK? There could be winners from all this
- What would the financial impact of supply chain problems be? If inventories available for sale dry up, then will sales be lost permanently, or just deferred? What will the P&L hit be? Broker forecasts probably won't be reduced enough, so profit warnings could be multiple. Or, companies might adjust better than expected, we don't know at this stage.
- How aggressive or prudent are the accounts? Prudent CFOs always keep some excess provisions tucked away, which can be released to mop up the damage from unexpected problems. Aggressive companies don't have this luxury, or might even be tempted to start fraudulently mis-stating their accounts.
My view - even though the market is already pricing in these risks, I tend to find that shares still drop (often heavily) when anticipated problems are later announced. Giving a double downturn. For that reason, I'm keeping my powder dry, and watching carefully for trading updates that mention China. Expect a lot of them in the coming weeks.
It could also be the new "Brexit uncertainty" excuse, for businesses that need to find some reason other than "We're not very good at what we do" - which is often the underlying reason for under-performance!
Nmc Health (LON:NMC)
Share price: 760p (up 8.6% at 08:54)
No. shares: 208.7m
Market cap: £1,586.1m
Statement regarding possible offer
This share has been trashed by short sellers, who I imagine will probably be having kittens right now.
I'd expect to see a dash to cover short positions today, so a big bounce in the share price. Could be an interesting one for traders to jump onto?
Although approaches are said to be "highly preliminary", this announcement mentions the names of two potential bidders - KKR (a huge US outfit with about $148bn assets under management, according to google), and GK Investment Holding Group, whose website says they're based in Switzerland, and invest particularly in Africa and M.East. Publishing specific names, adds to the credibility that the bid interest might be real. I wonder if either company will comment on this?
There's a separate announcement which suggests that major shareholders have not been complying with disclosure requirements. This also contains a brief trading update, saying;
The Company's operations continue to perform strongly, and the Company expects to report full-year 2019 results in-line with management's expectations.
EDIT at 08:56 - quite a muted jump in the share price today. The value metrics shown on Stockopedia look dangerously low - e.g. a PER of 4.7 is not necessarily a good thing. It can be the market saying there's something wrong. In this case the problems seem to arise from high debt, and questions raised by shorters. Plus there's a bad smell around the major shareholder disclosures. I'm not tempted to take either a long or short position here, but it's a fascinating & topical situation, that's fun to watch from the sidelines.
Up Global Sourcing Holdings (LON:UPGS)
Share price: 61.4p (down c.6%, at 09:01 )
No. shares: 82.2m
Market cap: £50.5m
Trading update
As if by magic, UPGS has published an update - I wrote the above section before 7am, so wasn't aware an update was coming.
Ultimate Products, the owner, manager, designer and developer of an extensive range of value-focused consumer goods brands, announces the following trading update for the six months ended 31 January 2020 ("the period").
Today's update sounds reassuring to me;
Outlook
Given that the majority of the Group's manufacturing is based in China, the Board is closely monitoring developments with the coronavirus outbreak there. The extension of the Chinese New Year holiday by nine days to today (Monday 10 February) in the Group's main manufacturing areas is expected to cause production delays. As further information becomes available, we will continue to evaluate any short or long term impact on the Group's business and take all necessary action to mitigate any disruption. We have extensive experience of managing supply chain disruptions in China, including those caused by previous viral outbreaks.
The Board currently expects full year profitability for FY20 to be in line with market expectations.
Interim figures - this is just a snapshot, prior to the full figures being published (last year this was on 29 April).
Key points;
- H1 revenues up 2.8% to £67.7m
- Bank facilities extended to 2024. Funding headroom of £13.2m at 31 Jan 2020.
Balance sheet - I last reviewed it here on 9 Sep 2019, and found it satisfactory.
My opinion - I don't see any serious worries here, based on the update today, and a balance sheet that looks OK. Yes there is some bank debt, but it's comfortably covered by inventories & receivables.
It's too early to be certain, but the signs are that there's no reason to panic here, if you're a shareholder.
Update at 08:25 - I'm surprised to see that UPGS share price has dropped about 8% this morning, at 08:26, to 60p. Why are people selling, when a known factor is reported on in a reassuring way? Mind you, there are only 161k shares traded so far. It does make me wonder if some investors just don't anticipate seemingly obvious potential problems? It's getting to a level where I'll add it to my watch list.
Audioboom (LON:BOOM)
Share price: 247p (up 11% today, at 09:03)
No. shares: 14.0m
Market cap: £34.6m
Statement re media speculation and review of strategic options
This podcast company has put itself up for sale.
I don't see this as coming from a position of strength at all - it's had a financially dismal track record as a listed company, never turning a profit. Repeated fund raises have succeeded in growing the top line (up an impressive 91% in 2019), but it remains stubbornly loss-making. OK, plenty of growth companies burn cash, but after a certain length of time, investors just get bored with hearing the same story over & over again, every time it wants to raise more money.
I see that a major shareholder recently supplied a $4m loan. That reinforces my view that Audioboom has probably exhausted all opportunities to raise more funding from the stock market. Hence other options (if there are any available) need to be explored now.
As this looks to be an announcement forced on them by weakness, then I cannot see why the share price is actually up today.
The good news is that there are lots of PE/VC outfits with vast amounts of other peoples' money to spend, and typically they love tech companies. Although surely someone would have spotted BOOM by now, and bid for it, if they thought it was any good? There's always the chance that Raine Advisors might find a deep-pocketed optimist, prepared to buy into the story here.
This share is just a lottery ticket.
Tandem (LON:TND)
Share price: 190p (down 7%, at 09:33)
No. shares: 5.0m
Market cap: £9.5m
Trading update & board changes
Tandem Group plc (AIM: TND), designers, developers, distributors and retailers of sports, leisure and mobility equipment, announces a trading update ahead of its annual results for the year ended 31 December 2019 which are due to be announced in March 2020.
Here are my notes from this announcement;
- Revenues - up 15% in H2 vs LY, blames weather & macro for slower growth than H1
- FY 12/2019 revenues £38.8m (getting revenue back up to 2016 level, after declines in 2017 and 2018)
- "Strong year", profit before tax "expected to be well ahead of the prior year". (FY 12/2018 was £2,081k underlying, or £1,872k statutory PBT). Well ahead - what does that mean? 10%, 20%, who knows? There are apparently no broker forecasts - why not?
- Operating expenses up 11% on LY (which, assuming static gross margin %, would consume most of the 15% improvement in revenues)
- Cash generation strengthened balance sheet, but no figures given
- Pension/divis clarification - agreed with pension trustees that dividends won't exceed deficit contributions
- Additional (presumably this means increased p.a.) deficit recovery payments may be needed once 2019 triennial agreed
Outlook - 2020 has "started more slowly". Some major customers have stock left over from 2019, so not yet re-buying.
Coronavirus - this is important, as it has read-across to so many other companies that import from China;
The Coronavirus outbreak in the Far East appears to be a significant threat. A number of factories have not returned to work after Chinese New Year.
The restriction on travel imposed by the Chinese authorities is hindering the movement of raw materials and labour throughout China.
This has already delayed the production of orders and made it difficult for our QA/QC inspections to take place.
Further, the welfare of our staff is paramount and we will not put them at undue risk of infection until we have greater clarity of the situation.
This gives us virtually no ability to forecast. All we know is that there is a problem, but it's not known how big, or how long it will last.
There are two ways to look at this;
1) It makes the share uninvestable, as we cannot forecast with any accuracy
2) The share is already dirt cheap on valuation metrics (see below), and some temporary stock intake problems might present a buying opportunity.
Another key point to consider, is that valuing companies on a PER basis makes us short-sighted. When we're buying shares, we're not just buying this year's or next year's earnings. We're buying the company's future earnings, in perpetuity. So one bad year really doesn't matter, in the long term. In the short term though, it can be incredibly painful.
Therefore everyone has to make up their own minds, and different people handle things differently.
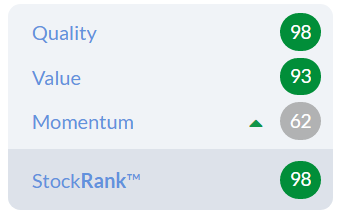
Tandem does look very cheap indeed, but I'll come on to the reasons why, in the next section after these graphics;
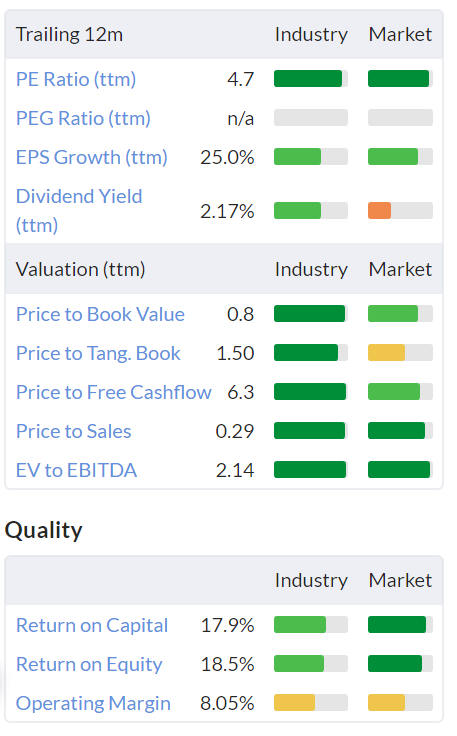
"ttm" means trailing twelve months, i.e. cobbled together from interim & final results, because there are no broker forecast figures available.
Balance sheet - this is important, as some investors mistakenly think Tandem has net cash. I reviewed the last balance sheet here on 1 Oct 2019. It actually had net debt of £2.0m, taking into account invoice discounting debt, and a mortgage on its freehold property. That's fine, as the freehold is in the books at £3.1m, so overall the position is sound.
This matters because the China disruption should not risk solvency of Tandem, given its sound balance sheet.
.
Board changes - oh dear, this is a dismal section of the announcement. It reads like one of those emails that you write when you're drunk, intending to delete it, but then mutter "Sod it!" under your breath, and hit the send button anyway. The next morning is usually then embarrassment & damage limitation!
The long-serving Non-Exec Chairman, Mervyn Keene, has decided to retire on 31 July 2020.
The long-serving CEO, Steve Grant, will become the new Chairman.
The group FD becomes the new CEO.
Musical chairs then, with no fresh blood other than a (yet to be secured) new CFO.
Chairman's rant - popcorn at the ready, let's see what he says!
When I was appointed Non-Executive Chairman the share price was 110.5p. Today as I announce my intention to step down the price is 205p per share. Despite this, it is disappointing that internet posters, who often hide behind absurd pseudonyms, continue to type inaccurate statements and offensive remarks.
There are an irritating few of these keyboard warriors who have no commercial experience but think that they could run the Group better.
He's been Chairman nearly 10 years, and the share price has doubled. Adding it up in my head, I reckon divis paid have totalled c.35p in that 10 years. So not a bad total return for shareholders, but not stellar either.
As for the internet trolls, we all know about the loonies on advfn & LSE bulletin boards ("many of them need to be sectioned!" as the Chairman of a different company quipped to me recently). They're best ignored, and it really isn't sensible for the Chairman of a listed company to be venting his spleen in an RNS about this issue. Also, on a technicality, if they're hiding behind absurd pseudonyms, then how does the Chairman actually know that they don't have any commercial experience?
People posting inaccurate things on bulletin boards is above all, a symptom of Tandem's extremely poor communications with shareholders. Directors of listed companies should (and most do) realise that part of their job is making sure that investors understand their business model, and to provide accurate facts & figures, and answer any queries from investors. Therefore, companies need to be an open book, and happy to communicate with their shareholders, who after all, own the business.
I've had a lot of feedback from Tandem shareholders that the Board are terrible at communicating with shareholders, and seem to view outside shareholders as a nuisance. The Chairman's comments below rather reinforce this perception. The outgoing Chairman doesn't seem to understand that part of his role, is to manage investor expectations, and communications. He wants us to just let them get on with it. That's not how it works with listed companies.
As I move on to other opportunities I know that, providing shareholders understand that we have a great team running the business and let them get on with it, all will benefit."
There should be no conflict between management running the business, and also having sensible communication with shareholders, such as;
- Results presentations & webinars each 6 months, open to private shareholders as well as institutions
- Occasional presentations at investor meetings/shows, to get the story out there
- Open days once a year, to show people round the facilities
- Broker research - get a house broker that puts research out to the PI community (ideally via Research Tree) - e.g. finncap, Liberum, or N+1 Singer
- Engage a financial PR firm, to introduce the company to more private investors, and to act as a point of contact for queries from investors, journalists, etc.
It's too small to interest institutions, so private investors are the market in Tandem shares - why hide away from us?! We create the (limited) liquidity, and set the share price.
No wonder the share is on a PER of about 4, and market liquidity is poor.
Directors put together only own 777k shares (15.5% of total shares), yet seem to treat the company as if they owned the whole thing! The petulant communications of the Chairman today, are indicative of an attitude that I've seen at some other small caps - usually ones where the founder still controls the business.
Perhaps the change in Chairman could be used as a refresh point, to adopt a better approach to handling investor relations? There's an opportunity here for the share to re-rate from a PER of 4, to a PER of 8 - doubling the share price potentially, if the new Chairman opens up the company to its investors. After all, what's the point in having a listing, if you're going to neglect outside shareholders?
On fundamentals, Tandem is a nice little company, profitable, and with sound finances.
Volex (LON:VLX)
Share price: 141p (up 3.7%, at 15:05)
No. shares: 149.9m
Market cap: £211.4m
Statement re situation in China
Volex, the global supplier of complex assemblies for performance critical applications and power products, today provides an update on the current situation in China.
This is what the company says in full;
As a result of the outbreak of Coronavirus in Wuhan, all major operations in China have been subject to an extended and mandatory closure over the Chinese New Year holiday period. The welfare of our employees continues to be the top priority for Volex. Over the past week we have been working closely with local government agencies in China to implement certain precautionary measures [Paul: such as?] to allow our employees to return to a safe work environment.
Volex has 14 manufacturing plants across the globe, four of which are in China. [Paul: What proportion of global production do these Chinese sites account for?]
Three facilities are located in Guangdong province, Southern China, approximately 1,000km from Wuhan and one facility is located in Jiang-Su province, Eastern China, approximately 600km from Wuhan. [Paul: which means what, exactly?]
As of today, one of our four sites in China has resumed operations at a reduced capacity. The other sites will follow once the necessary approvals are received from the Chinese authorities.
.
That's absolutely uesless! It doesn't tell us anything, just leaves questions unanswered, e.g.
- How much production has been lost?
- How quickly can it be recouped?
- "Reduced capacity" - what % reduction?
- What is the financial impact of all the above?
- Can other plants make up for lost production in China?
- Is this going to affect the company's ability to meet, beat, or miss market expectations?
Presumably, we are meant to surmise that Volex plants being 600-1000km away from Wuhan province means that the impact is less serious? If so, why not say so?
My view - this gives us nothing much to go on. I don't see any updated broker notes either.
The purpose of an announcement like this, should be to clarify the situation. Instead we've just been given bare, disjointed facts, with zero interpretation of those facts by the company.
Luceco (LON:LUCE)
This share has fallen sharply today, presumably on China supply concerns, it's down 14% today to 123p.
Unfortunately, there is no statement from the company as yet, so hopefully they'll be preparing one for release tomorrow?
As with the other companies I've looked at, the share price has fallen a lot, but it's only really giving back some of the recent gains. We're a long way from things actually looking cheap yet;
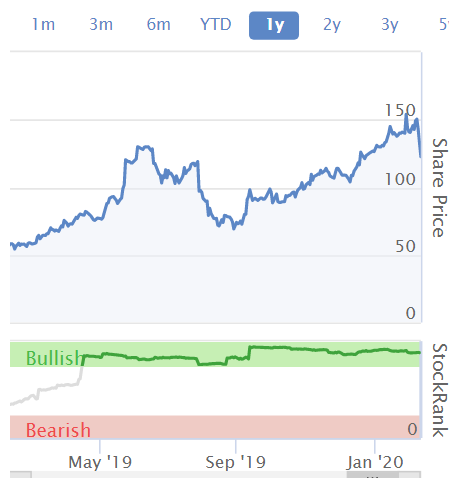
Maybe we should then be looking at China supply issues as having pricked a bubble, rather than (yet) making shares affected genuinely good value?
I'll report properly on this when the company issues a statement. Let's hope it actually contains some useful information, unlike the one from Volex.
Intu Properties (LON:INTU)
This is a crisis hit owner of major UK shopping centres.
We already knew it was trying to raise fresh equity, this is confirmed today;
Further to recent press speculation, intu properties plc ("intu", the "Company") confirms that it is engaged in constructive discussions with shareholders, including the Peel Group and others, and new investors including Link Real Estate Investment Trust and others, in relation to a proposed equity raise alongside intu's full year results at the end of February.
The share price has bounced 24% to 16.6p. The big risk here is that new equity might dilute old equity out of the picture.
Looking at the major shareholders list, Peel owns 27.3%, being the largest shareholder. Therefore if Peel is prepared to stand its corner in a fundraising, that could protect some value in the old equity, perhaps? i.e. Peel is incentivised to want new equity to be injected at a high share price, in order to limit the dilution of its existing stake.
It remains too risky for me.
That's me done for today, see you tomorrow!
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

37 comments
Tandem (LON:TND) - interesting that the outgoing C'man quotes the share price from the start of his tenure. He doesn't mention that prior to that he was CFO since 1993 when the price was c.£10.00 (does he believe that as CFO he has no input to the success of the company??)
Seems very incestuous management team.
Given the small number of employees (on lower wages) I wonder how much of the £10 million of the Pension liabilities are actually for the benefit of the directors themselves?
Brian Geary , who has a 10% stake in CRL since the days of sub 10p, has recently disclosed a > 3% stake. Probably the recent price rise was caused by others following his disclosure.
Thanks for another mammoth report Paul.
Very scathing attack there on £:TND, I hope the directors read and take note and what good investor relations should be and would build confidence in the management.. By them being so defensive and anti-shareholder relations is not going to encourage investment. Maybe the outgoing Chair lost his complete sense of purpose or is just a bad egg?
Hi wildshot,
I tried to be balanced with my report on Tandem (LON:TND) - yes their investor communications is terrible, but it's quite a nice little business, and looks cheap.
One shareholder complained to me about Director remuneration, so I today checked it to the last annual report, and found that actually it was OK in both 2018 & 2017, so I didn't criticise the company for that.
This situation does raise the point that reckless posts on bulletin boards clearly do real damage to company's perceptions of their small shareholders. A few noisy idiots can clearly taint the image of the whole private shareholder base. So maybe the silent & sensible majority need to take better control of wayward bulletin boards?
Regards, Paul.
P.S. In my experience, pretty much all small cap CEO & CFOs do read bulletin boards! And are often exasperated with what people write on them! That can result in either of these reactions;
1) Alienation, and they don't want to talk to any private investors (sounds like Tandem's Chairman has gone that way), or
2) Relief when a sensible & well-informed shareholder does ring them up to discuss the business.
re: Tandem (LON:TND) 110p to 205p +35p dividends over 10 years is a compound return of 8% PA, about the same as the FTSE All-share total return of the period and significantly less than the 11% compound annual return of the FTSE small-cap total return.
Most of the Tandem (LON:TND) return is due to a rise in the last year as more activist investors have bought in, unhappy at the level of management remuneration, in my opinion, this makes it doubly embarrassing for the outgoing chairman to hold up this average-to-poor return as a sign of success in an RNS.
As Graham has so eloquently written about before, Tandem (LON:TND) is clearly being run largely for the benefit of the Directors with disdain being shown towards shareholders who question them. As a consequence, regardless of its financial prospects, I regard it as uninvestable. It would be a small portfolio that only contained small companies that treated their shareholders with integrity, but I see no reason to hold shares where the Directors take salaries that are highly significant in the context of the company's pre-tax profit and distributions to shareholders. And who treat the position of PDMR as if only insiders are capable of running the company when they have made some absolutely howlers on the acquisition front. As shareholders we need to be able to trust the custodians of the companies that we invest in. I can see absolutely no reason to place any trust in the Directors of Tandem (LON:TND) .
Some thoughts on UP Global Sourcing Holdings (LON:UPGS) -> The big reveal happened this morning. Price down 7.5% to 59p at moment. Having travelled down from 100p at turn of year and 90p from T0 #Coronavirus.
Must have released a stinker rns then?
Well, on the negative side they announced that there will indeed be production disruption in China due to #Coronavirus. So any hopes of miracle news dashed! There must have been something more negative to add to sp woes?
Maybe muted revenue growth….H1 20 v H1 19 shows 2.8% growth to £67.7m (bit below 5% expected). Obvs much less exciting that H1 19 v H1 18 were the increase was a whopping 36%. Is this negative?…not in any objective sense.
Revenue result is reasonably positive standalone result and very positive in a valuation context. 1) Standalone its shows robust demand for its good during a period where some others struggled -> at least a partial win by not losing?!
Then 2) The mute 2.8% growth versus whopping 36% in prior period needs context. H1 18->H1 19 had new growth in Europe and a bounce-back in demand from established customers who had pulled horns in during 2018’s tough UK retail climate.
Orientation tricky but implicitly H1 19->H1 20 at 2.8% rev growth is effectively a bit more revenue growth and continued operational momentum than is credited by just basic arithmetic. No prizes from sceptics but if you believe the business is good then some solace.
3) Debt headroom of £13.2m implied approx £5m more trade financing being used YoY given that they renegotiated facilities up by £8m+ during period…that’s a positive as that means the forward order book is stronger than the same time last year.
Its early H2 20 for #UPGS and #Coronavirus will impact…but the start point to H2 20 implied in debt headroom disclosure is quite positive. Back in 2018 part of their pw problem was that the discount retailer channel was temporarily stuffed after a lot of growth.
This last TU suggests that there is no temporary growth indigestion coming from the massive European sales expansion and add that to an adjustment for the extent to which ongoing op momentum is a bit disguised by big bounce-back from 2018 => looks healthy.
At 7x p/e and 7% yield #UPGS is close to no brainer (if you believe in the durability of model and management). Current short term China woes may be good for the quick and adaptable UPGS if they can show customers superior op dynamic during tough time.
Paul: "When we're buying shares, we're not just buying this year's or next year's earnings. We're buying the company's future earnings, in perpetuity. So one bad year really doesn't matter, in the long term."
So true, and in fact it is much more true today than it was 20 or 30 years ago. That is because long term interest rates are dramatically lower today than back then. Future earnings have to be discounted at a long term interest rate to get a present value and hence a logical valuation. But if long term interest rates are close to zero, then you don't have to do much discounting of the future.
This is a major part of the reason why growth investing has outperformed - and value investing underperformed - over recent years. Growth shares have their big earnings in the future, so a growth share when valued on today's interest rates is logically worth a lot more than one valued on 1980s interest rates.
By the same token, a hit to this years earnings should be much less of an issue today than it was in 1980, because near term earnings are much less important to the valuation. So it would be logical for stock markets to react less to issues like the coronavirus than they would have done historically. Somehow though, if things get bad, I doubt there will be much logic involved.
Coronavirus figures have hit triple figures in Japan.
As far as I can tell, the WHO initial death rate estimate will have to be increased from the 2% figure. Deaths/Cases is already 2.25%, but that includes many recently diagnosed cases, where the result is not yet known.
Case numbers have been increasing by around 20 % a day, falling to around10% a day recently. That's the result with everything closed in China, although I suppose there is an incubation period. Quite a rate of compounding.
Some are talking this down and comparing with normal flu deaths. For something additional to flu deaths, with a higher death rate and a fast growth rate, I don't think this should be underestimated in such a way.
I think it's dangerous taking too many leaps. I know that as investors we are somewhat programmed to try and extrapolate but this is somewhat different.
This is a new virus and therefore death rates are actually statistically pretty meaningless currently. There could be far more cases of infection than are reported, as only those diagnosed are given and for that you have to have visited a doctor and been tested. It is quite likely that many people get it, recover at home or have mild symptoms but the reality is we don't know.
The fact that 2% of reported cases have resulted in death so far doesn't mean that this is the death rate either. It could potentially be higher but it could also be very materially lower. Much more likely to be the latter I'd say as very few deaths will occur undetected whilst many mild cases are likely to not be reported, but again that's only my hypothesis.
Since it is early in the viruses progression medical professionals will learn quite quickly how to treat in order to limit the death rate, even before any new drugs or vaccines are introduced and so death rates may well come down as this is better understood. Viruses like this do spread and quickly. The fact that the rate of new cases is stabilising just means that the Chinese in particular, appear to be doing a reasonable job of containing it so far.
Comparing this with Flu I agree is probably not correct as that is a well understood virus that has been around for a very long time and has affected hundreds of millions of people, but at least the comparison acts as a counter balance to the media frenzy that would otherwise ensue. "Killer Virus Spreads" was the headline in black bold letters a few days ago on one London paper! Nothing like bad news to sell content even if it does potentially induce fear and panic!
In reality the discovery of this virus is a serious event, one that should be treated with caution and should be contained as far as is possible. However, in my opinion the psychology of the crowd will be the more telling factor on stock prices.
David
Agreed that we don’t want panic and scaremongering headlines. But we don’t want complacency Or naïveté either.
40,000 cases is quite a large number. Certainly more than a handful. While, there may be unreported mild cases that mean the average death rate may be lower, that should not be a comfort to us as it has been clearly shown that those that are infected but display few or no symptoms can be contagious. The ski chalet “superspreader” may turn out to be unusual but it demonstrates that the infected are contagious even with few or no symptoms.
Furthermore, medics already are well aware how to treat viruses. They are unlikely to be able to improve the death rate in the absence of new medicines.
So, given the high number of cases, it seems unlikely that the death rate will turn out to be very materially lower than the 2% and note that this is orders of magnitude higher than for common flu.
Added to that is the concern over the incubation time. Sure, the range of about 2 - 10 days could change somewhat as more data becomes available but currently it does seem to be longer than for the other flu or respiratory viruses. That means infected people going about their business for longer and potentially infecting more people before they are diagnosed than with the other viruses. So more of the population may catch it for that reason.
The outlook does appear to be potentially very grim unless we are lucky in some way.
Yes I read that the cruiseliner in Japan cases have doubled in the last day to 136 with many elderly people. Also hearing many in China are awaiting testing. Also results are taking around 7 days in Bangkok which is the only test centre for many countries in that area, so there is quite a big lag from getting the symptoms and the results. Cases may well increase per day if testing is speeded up which is something China is trying to do.
In a similar vein I noticed that (from memory) the number of deaths on Saturday in China was reported at around 90 which struck me as being more than 10% of total deaths. I hope this simply represents more efficient reporting .
It was 89 on Saturday and 97 on Sunday, 108 on Monday. The total is now over 1,000 and cases over 40,000. Only about 4,000 have recovered. Who knows how accurate the Chinese figures are. The WHO has a team in China now so maybe things will become clearer.
Here is a link: https://www.worldometers.info/coronavirus/
Hi. For anyone interested in Volex. This video is from their investor roadshow last November after the half year report. Presented by the CFO Daren Morris. He highlights the progress and just how Volex is positioned around the world
https://www.youtube.com/watch?v=QJQufQboZfE
STRIX ( £Ketl) is down today over 4.0% and I wonder if this is China related with them having factories out there? Could be a buying opportunity at some point?
Jim
In the midst of all this spare a thought for the victims (other than financial). I am sure everyone does but it is too easy to forget those suffering in Hove as well as Hong Kong.
https://www.cdc.gov/coronaviru...
Of course, I'm sure everybody is thinking very much about the suffering of people affected by coronavirus. Plus worrying about how our own family & friends might be affected if this thing becomes a pandemic. That's a given.
Paul, thanks for starting the debate on what potential implications the coronavirus may have for our investments, as it doesn't appear to be under control as yet, and it seems to be taking the recent froth off the market, and in some cases more than that... I found this article this morning debating the same, in which the impact on certain companies (Apple, Starbucks), industries (carmakers, tourism), commodities, countries and the global economy are considered:
https://www.theguardian.com/news/2020/feb/10/will-the-coronavirus-outbreak-derail-the-global-economy
Thank you very much for this. Fascinating! We are already seeing sell-offs in many Asian dependent businesses, across all sectors. Laura Ashley Holdings (LON:ALY) is of course a retailer, Octagonal (LON:OCT) provides financial services, and Luceco (LON:LUCE) and Up Global Sourcing Holdings (LON:UPGS) are nominal manufacturers who will see their supply chains disrupted. Oil and resources are taking a hit too, as demand is speculated to fall. Anglo Pacific (LON:APF) is at a twelve month low. At least at this stage, opinions are far more important than facts, and these will guide the market rather than the reality of the situation. Quality companies will fall along with the rest, and we may be able to pick up some bargains.
I quite like the idea of "speedy filing".
If you have any other life hacks Paul - please let me know!
Watchstone (LON:WTG) we talked about this a couple of months back. I originally bought some on the hypothesis that I expected the cash backed value to be above 200p and with capital return could see a sub 1 year 30-50% return.
Todays announcement says the cash is 195p and they are returning 110p for now. Ingenie has been challenging but now selling at highest rate for years and since it is clear they are also looking to sell this business when they can get a decent return that at least bodes a little better. Not sure what value to attribute to the remaining business and the listing but I will go for a finger in the air 15p so perhaps a total asset value of 210p.
Feels like hypothesis continues to hold then. I will get a min of 110p in Q2 leaving me with a purchase price of 30p for a residual value of 100p. My anticipated annual return therefore now depends on when that discount narrows and by how much and whether a sale of ingenie happens anytime soon.
There is this 12 shareholder notice of possible intention to initiate proceedings. Given previous legal actions in this vein were dropped it feels fairly spurious/opportunistic to me, but we'll see.
Watchstone (LON:WTG)
Hi David
Just to add to your thoughts, I'm hoping for:
The current share price is currently 150p
I know that Ingenie burns through £5-6m per year, so I hope I'm being prudent with my estimate.
In the current uncertain climate Watchstone (LON:WTG) seems like a good cash substitute.
Fingers crossed we're not missing anything.
A
Whilst I am not looking to debate this too much, is it too obvious to comment that this virus may have a bigger impact on corporate profitability given post Saars there is more output from Chinese factories to the West and typically economic growth is not robust enough to stand a prolonged shut down? To me markets are not yet discounting this impact sufficiently i.e Asian markets seem a bit too much ‘ blue sky’ ?
Whilst I am not looking to debate this too much, is it too obvious to comment that this virus may have a bigger impact on corporate profitability given post Saars there is more output from Chinese factories to the West and typically economic growth is not robust enough to stand a prolonged shut down?
I heard Paul Krugman make this very point on the Today programme this morning. Back in 2002 when SARS happened China was in the early stages of it's great manufacturing growth and only accounted for 8% of world manufacturing, now it's more than 25%. He too thinks the effect is being underestimated.
I see he also wrote a piece for the New York Times: https://www.nytimes.com/2020/01/30/opinion/coronavirus-jobs.html
All the best, Si
Can I claim originality? Not a today programme listener and I profess to cancelling my subscriptions to NYT many years ago! Seriously, this does feel more serious than Saars but maybe someone who has better research than I can post a list of the most vulnerable companies. If this equals fewer Chinese tourists and Students maybe the backwash is more significant? Not trying to be alarmist, merely realistic
I have been thinking along the same lines. The Chinese workforce is now returning to work. The authorities must have been faced with a tough decision - do we extend the holiday period even longer and damage the economy further or let business resume and hope for the best i.e. hope that the epidemic doesn't get totally out of control as a result.
I am not surprised to see UP Global Sourcing Holdings (LON:UPGS) marked down - some of this I'd say is because people are invested in this as a growth stock, and a revenue increase of 2.8% is pretty mediocre, while the rest is due to the company stating that it is expecting disruption in China but it is unable to either quantify this at present or state any alternative arrangements.
Could you perhaps please cover the update from Tandem (LON:TND) too, Paul? On the one hand they state figures for the current financial year will be well above last year, but on the other hand they indicate that this year has got off to a slow start with the China virus affecting their QA.
Paul
I see Keith Ashfird Lord has taken a stage in Revolution bars for Buffetology Fund
I also have bought some shares on the return to 70p following the break out from the long term trading range. I held when it was in the 200p region, watched it ever since and this is the first time I thought it could possibly be a buy. We shall see. The only problem for me is that I buy shares using the internet rather than phoning a broker like Paul. I was restricted to 5,000 in a deal and then just 3,000. That made me worry about what would happen if I wanted to sell in a downturn and my intended holding was immediately scaled down. I know this is an issue with most small companies but to me it is something that points me in the direction of companies where it is easier to deal.
You are correct to be cautious. Sadly liquidity is an issue vastly underrated by most small cap investors as getting out can always coincide with the spread widening. As you can see from the large sake of HL shares by one of the founders even large caps can be hard to sell in volume.......
Hi Martin, that's not a new stake in Revolution Bars (LON:RBG) for the Buffetology Fund, he's held for a while, biggest shareholder I think.
He(Ashworth-Lord) has added to his stake in chain nightspot operator Revolution Bars from 16.9% of the shares to 19.6%.
The S de L Buffettology fund has grown so large that small companies have become of little consequence so in June Keith Ashworth-Lord announced that he would discontinue microcaps, defined as below £100m mcap. He held three. In December he sold the entire 16% holding in Driver (LON:DRV). The holding in Air Partner (LON:AIR) has been gradually reducing but with the third, Revolution Bars (LON:RBG) , where he sold down from 18.7% to 17% in July, the policy appears to have reversed with the recent purchase although note that the fund rules do not permit a holding above 20%.
Up Global Sourcing Holdings (LON:UPGS) trading update today for H1. Revenue up by 2.8% (£1.9m) on last year. (full year revenue growth expectations 5%).This seems a little disappointing but H1 last year saw a big increase in revenue of 20.8%.
China, they are monitoring but extension of new year to today is expected to cause disruption delays. They highlight they have extensive experience of dealing with supply chain disruptions in China, including previous virus outbreaks
Go on to give statement that full year profitability for the year will be in line with market expectations.
The trading statement seems a bit empty having to talk about licence renewal and bank facility extension rather than any progress on brand development or sales. It also needs a fairly good second half (revenue £57.5m last year to £61.3m) based on stockos fullyear expectations) to meet expectations which they may struggle with given China issues.
Maybe a wider sell-off, Volex and Luceco also sharply down.
Perhaps saving a profit warning up for a few months....to me it seems like if everything gets back running as normal today there may be little impact as the factories was on holiday anyway. Maybe there is an unknown factor for the virus with people travelling from their hometowns back to the factories?
I too am quite interested in this but admittedly this is no cheaper than it was 12 months ago.
Volex have issued an update re China situation, only 1 of 4 factories reopened.
There is a new broker note out from Equity development this morning (its free on their website and usually posted on the companies website).
The note reduces total year revenue estimate by 2.1% but keeps ebitda, pre tax profit and eps constant due to operational efficiencies. Also keeps its 100p price target. No further China news.