Small Cap Value Report (Mon 10 July 2023) - MSI, OTMP, TLY

Good morning from Paul & Graham!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £1bn. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk.
Paul’s Section:
Backlog Item -
MS International (LON:MSI) (Paul holds)
540p (£90m) - FY 4/2023 Results - Paul - GREEN
Full year results came out on 22 June, and I thought it looked an interesting company. However, I only drafted half a section at the time, and quickly got distracted with more companies to write about. So I’ve dredged it up, and finished off this section over the weekend. Also I should add that I’ve picked up a small position personally, mainly to motivate me to do more detailed research on it.
This is an unusual group, with 4 diverse divisions, each of which it says has a leading position in its specialist markets -
Defence: £32.4m revenues, £2.0m operating profit (LY: £30.2m, and £4.1 op pr)
Forgings: £23.3m revenues, £3.9m operating profit (LY: £16.5m, and £2.2m op pr)
Petrol station superstructures: £16.3m revenues, £2.1m operating profit (LY: £15.1m, and £1.1m op pr)
Corporate Branding: £12.4m revenues, £(2.7)m operating loss (LY: £13.0m, and £(1.3)m op loss)
The figures above are from note 1 in the FY 4/2023 results, which has no separate column for central costs. Therefore it seems the above profit numbers are stated after absorbing all the central costs of listing, which are substantial - e.g. the Directors overpay themselves, a common complaint from investors in MSI, withdrawing £2.1m (see note 3[b]), far too much for a company that has reported a drop in PBT from £6.0m LY, to £5.1m TY. However, this does show that the individual divisions would be more profitable if the profit numbers above excluded central costs. This could mean hidden value, say on disposal of any division that they decide is non-core, because an acquirer could strip out those heavy central costs.
Commenting on each division in turn -
Corporate Branding - loss-making this year and last year, so why is this still part of the group? There’s potential group upside from a turnaround or disposal of this loss-making division. This seems to be based in Netherlands, and does illuminated advertising displays, from what I can gather.
MSI Defence Systems - based in Norwich UK, and Rock Hill, S.Carolina USA. As you can see above, defence had a bad year, with profit halving, because a large contract was delayed slightly, and didn’t make the year end cut-off, we’re told. This is the most exciting part of the business though, in terms of orders & outlook. So the contract slippage that has harmed FY 4/2023 results, should correspondingly boost FY 4/2024 profits, setting the group up for an outperforming year this new year.
Defence products include a very impressive (see website for video) high-tech gun that detects and destroys drones (clearly a sweet spot right now). It also seems to make large guns for navies, and for tanks.
Forgings had a very good year, with profit almost doubling. This seems to be MSI-Forks, with factories in Doncaster UK, S.Carolina USA (sharing the same site as MSI Defence above), and Sao Paulo, Brazil. Its website shows a variety of forged (steel presumably) prongs for the front of forklift trucks. Sorry, fork arms, I think is the correct term. The website also shows a variety of other products such as rings & cylinders, shafts & spindles.
Superstructures division makes the canopies & other things for petrol stations, and this also almost doubled profit in FY 4/2023, making as much profit as the other 2 big divisions put together.
It seems to have subsidiaries in Doncaster UK, Krakow Poland, The Netherlands, Anderten Germany. The interesting aspect of this, is that the development of EV charging stations, opens up big opportunities for this division in future.
I’ve read the FY 4/2022 (NB last year’s) Annual Report, because this share intrigues me. A few points I noted down -
Directors are all getting on a bit! So succession planning, and potential value crystallisation of the group could provide nice upside for all shareholders.
Michael Bell (Exec Chairman) joined in 1972, rose to the Board in 1980.
Michael O’Connell (FD) joined the Board in 1985.
Nicholas Bell has probably not yet finished his trial period, being a recent Board joiner in 2013! ;-)
Their remuneration is excessive at £766k (Exec Chmn), £408 for the FD! And £357k for the other Exec Director. This did include bonuses, as FY 4/2022 was a good year, but it’s far too high for the size & profitability of the group, in my opinion (and other investors have also moaned about this).
They’ve loaded up with share options too, with 1.5m in issue at an average exercise price of just 94p. That’s just within the maximum acceptable limit of 10%, at 9.3% of the 16.2m shares in issue (ignoring shares held in treasury).
Directors are big shareholders too,
Bullish points -
- Eliminating the £2.7m losses at Corporate Branding would boost group profits significantly.
- Order book has almost doubled to £115m
- Upside from US Navy, which looks like it might be close to ordering MSI’s large naval gun.
- Positive outlook for the refuelling superstructures division due to EV charging roll-out.
- VSHORAD anti-drone system - order received for £54m, not clear if this is included in the £115m order book or not.
- Years of R&D now seems to be paying off with big orders -
- We perceive that we are achieving a significant, upward step change in the further development of the Company that will again bring additional rewards and success for the business. I look to the future with confidence.
- Therefore, together with the delayed order from last year likely to boost the current year, we can probably expect much stronger results for FY 4/2024 in due course. That could be bullish for the share price.
Takeover target? With some seemingly ground-breaking defence products attracting big orders, combined with ageing Directors with large personal shareholdings, this reminds me of Avesco, which we did very well on (5-bagger) a few years ago - with the end result being a bumper agreed sale of the company, after loss-making divisions were jettisoned or turned around, to maximise profits. MSI seems to me a somewhat similar type of situation - a rather off the radar company that contains some valuable parts, with ageing owner/managers likely to be seeking an exit.
Balance sheet - looks good. Note there is a pension deficit, with deficit recovery payments of £675k last year.
Bearish points? For balance, the main negatives seem to me -
- Not obviously cheap on historic numbers, so the investment case relies on the big order book growth translating into rising future profits.
- Excessive Director remuneration.
- Illiquid share, with wide published spread (although real prices are often well within the spread)
Paul’s opinion - it’s difficult to predict how this might pan out, as we don’t have any broker numbers. It’s one of those owner-managed companies where longstanding management, annoyingly, behave as if it were a private company, giving out little information to outside shareholders, and not having any forecasts issued by brokers.
Still, they’ll want to maximise the value of the company, and then sell it probably, when they retire.
The big new orders sound very exciting, and a high-tech system that shoots down drones, seems a very worthwhile, and non-lethal product.
I’d be interested in hearing from any readers who have looked into this company in more detail.
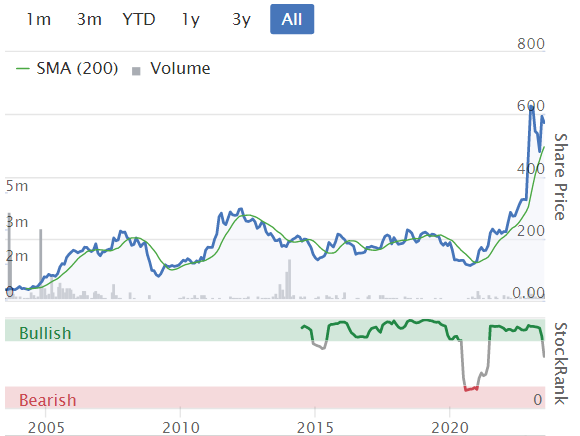
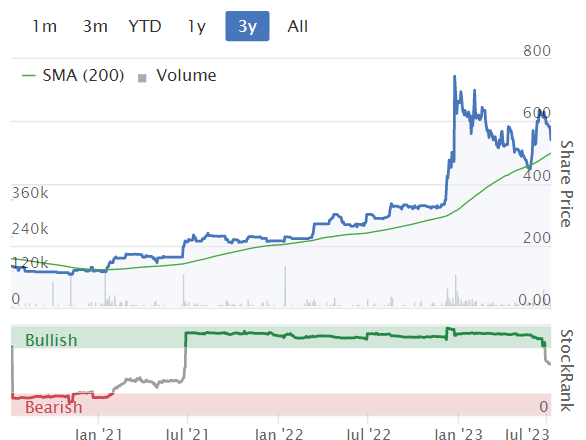
A sleepy share for many years, but investors have re-rated it (impressive, as this has been during a vicious small caps bear market) in the last 18 months, in response to much stronger newsflow -
OnTheMarket (LON:OTMP) (Paul holds)
Down 5% to 52p (£44m) - Audited Results FY 1/2023 - Paul - GREEN
OnTheMarket plc (AIM: OTMP), the technology-enabled property business which operates the onthemarket.com property portal, today announces its audited results for the year ended 31 January 2023.
Good reported figures here for FY 1/2023 -
Revenue up 14% to £34.4m
Adj operating profit up 59% to £4.3m
Statutory operating profit only breakeven, at £0.1m, so the key question is whether the £4.2m adjustments are sensible or not? (note 7)
Adjustments - I’ve highlighted the 2 biggest ones below (note 7) - it’s fine to adjust out £1.5m goodwill impairment. I’m unsure about the £1.375m “Agent recruitment charges” - this is share-based payments to estate agents, in return for them signing paying contracts. So you could argue it either way, as to whether that should be left in as a cost, or adjusted out. I can’t make up my mind.

Current trading - is in line with expectations.
Outlook - as I would expect, it says macro, higher interest rates, is having some negative impact on the housing market. It mentions that customer cancellations are higher than expected. H2 is expected to be more challenging that H1.
Despite that, it says both revenues and profit are expected to be higher in FY 1/2024 than FY 1/2023, which sounds counter-intuitive, given macro conditions. So my feeling is that the risk of a profit warning may be quite high here. Also the natural optimism & desire to talk things up all the time, of estate agents, is a background worry with shares in this sector!
The 2018 5-year lock-ins for agent shareholders ended in 2023, with most agents continuing to use the OTMP portal.
OnTheMarket Money - this is an interesting development, as it provides mortgage broking, thus could become a nice additional earner that would otherwise go to price comparison sites.
Good growth in new homes advertiser numbers, has mostly offset a decline in core agency customers (down 6%).
Website visits down 14%, which is disappointing - this metric needs to rise strongly, for OTMP to be a credible challenger to the dominant Rightmove.
Advertising spend of £8.6m (down from £10.6m LY) is substantial, and I’m really impressed that OTMP manages to absorb this heavy cost, and still be profitable. Most challenger companies in this sector burn cash like there’s no tomorrow, then end up going bust (e.g. Purplebricks). OTMP looks a rare exception, where it’s already a viable, profitable, cash rich company. So risk:reward looks good to me.
EBITDA - best ignored, as £4.5m costs were capitalised onto the balance sheet, including £2.3m staff costs.
Balance sheet - looks fine, including £11.3m cash (with no debt), up from £8.4m a year earlier. There is £4.0m of deferred income, which explains where some of the cash has come from (customers paying up-front). So no worries about funding, and the going concern statement is clean.
Share options are excessive at 10.2m, but they’re mostly underwater, so not a worry.
Paul’s opinion - I think this is a very interesting share, which is why I opened a small position myself, and spent a bit of time going through the numbers in detail this morning. It’s easy to buy into a cash-rich company like OTMP, when its share price is collapsing, because you don’t have to worry about it running out of cash. The increase in cash pile today reassures me very much.
Renowned investor Christopher Mills has said recently in interviews that the OTMP market cap perplexes him (in being so low, and continuing to fall). For what little it’s worth, I completely agree. This is a credible business, profitable, cash generative, self-funding heavy advertising spend and new product developments.
It gets in the obligatory reference to AI today! Imagine in a bull market how this share could re-rate upwards, if investors focus on its growth potential, and tech development? Meanwhile, the downside protection from profitable existing operations, and a healthy cash pile mean we don’t have to worry whilst we wait.
Subjectively, I think the newish CEO, Jason Tebb, is bringing new energy and a better strategy to OTMP. Plus most importantly, he’s protecting the cash pile, instead of blowing it on TV ads, which is the main risk I see. He recognises that he can’t compete with Rightmove or Zoopla on marketing spend, so instead is trying to develop useful tech tools so that agents (who part-own the business) will use it more, and become stickier clients.
Overall, I think £44m market cap is a bargain, so I’ll probably be adding to my position on weakness, to get ready for the next bull run.
We don’t have to worry about operational gearing, because in a downturn the substantial advertising budget could easily be cut.
Zeus has trimmed its forecasts for FY 1/2024 this morning, there’s a detailed note on Research Tree, so many thanks for that.
There’s probably not a catalyst to reverse the downward share price trend right now. However, I’m happy to hold this for the long-term, as I think it’s a really interesting challenger company, and shares look really cheap. I think risk:reward could be good here, for patient investors, and I’m in good company with the shrewd Christopher Mills!
A poor share price since listing, but the fundamentals have improved a lot over this period, with good growth, and a move into (adjusted) profit. Note there has been some dilution, with share count rising from c.60m to 80m now, a lot of which is issuing free shares to estate agents in return for 5-year paying contracts.
Totally (LON:TLY)
Down 25% to 12.75p (£25m) - Prelims FY 3/2023 - Paul - AMBER/RED
Totally plc (AIM: TLY), a leading provider of frontline healthcare services which increases access to quality healthcare across the UK and in Ireland by targeting the reduction of waiting lists and waiting times for patients, alongside corporate fitness and wellbeing services for corporate customers, is pleased to announce its preliminary results for the 12-month period ended 31 March 2023.
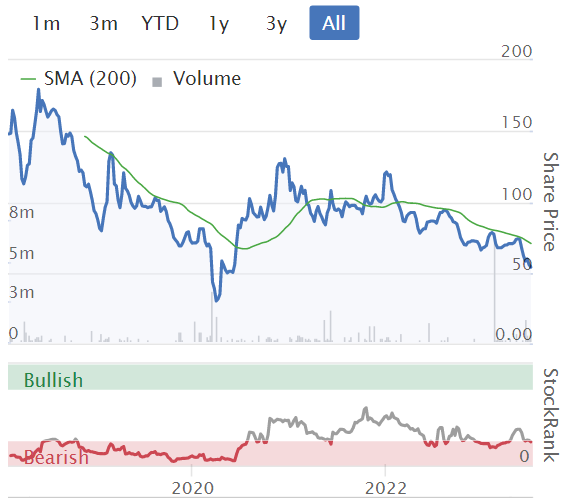
An unpleasant market reaction to these results today, down 25%, and a share price that’s now approaching previous all-time lows. This doesn’t reconcile at all with the upbeat comments I’ve heard from TLY’s CEO in fairly recent webinars - so I'm questioning whether I should be taking any notice of management commentary?

Outlook -
Post period update
The Board anticipates revenue in the year ahead to be lower than in the period to 31 March 2023. EBITDA is expected to be marginally below the period to 31 March 2023 reflecting improved margin driven by higher volumes in elective care, and the continued management and reduction of overhead spend. The Board are confident that the actions and strategy put in place over the past 12 months will ensure the Company remains in a strong position to continue to grow significantly over the coming years.
This doesn’t sound great either -
In line with our buy and build strategy, we remain acquisitive where opportunities enhance our ability to deliver increased shareholder returns and broaden services for commissioners.
In the year ahead, we will remain focused on making further progress with our growth strategy whilst ensuring we maintain the delivery of high-quality services and manage our costs.
We expect the coming year to be challenging as the NHS continues to operate in crisis and faces ever-increasing demand across all services.
The Board remains very confident in that the number of opportunities for the Company continue to grow and we are ready and prepared to further support the NHS as it continues to focus on the recovery and embedding of sustainable services able to cope with continuing higher levels of demand and the reduction of waiting times and waiting lists.
I thank all of our shareholders for their support during this challenging year. We will continue to focus on driving business growth, both within existing operations and through sensible acquisitions.
Balance sheet - looks stretched to me. NTAV is negative £(11)m, and I wouldn’t want to see it making any more acquisitions, unless funded by equity, which of course would mean dilution at a weak share price. So I think strategy is looking questionable now.
There’s negative working capital (current liabilities considerably exceed current assets). Most of the cash pile has been spent on acquisitions - a good use or not?
Paul’s opinion - are things as bad as the share price suggests?
It’s still reported profit growth, with PBT £1.8m, up from £1.3m.
The market cap of £25m seems paltry, so maybe this share could bounce, once it finds a floor? (nice and vague there!)
Very low margin public sector contracts don’t really interest me though, so it’s probably not something I would want to invest in. Although shares do look cheap now.
EDIT: Many thanks to Wolf of Small Street, who mentions in the comments below that broker forecasts for FY 3/2024 have been slashed by about half. So a nasty profit warning that the trading update seemed to attempt to gloss over. Very unimpressive, and sadly I think management now has little to no credibility.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

53 comments
"where did I say it is not generating cash?"
Here - "Especially when it generates little profit and no significant free cash flow."
Me - no position either way but I think if you're going to make a comment, you should be consistent with it.
Towards the end of the day Zoo Digital (LON:ZOO), which I hold, fell 7%. The results are expected tomorrow. I have a very nasty feeling that somebody knows something…and it isn’t me.
Some useful info here
https://constructuk.com/sp-glo...
"Key Findings:
Fastest decline in residential work for just over three yearsI
nput prices decrease for first time since January 2010
Supplier performance improves at quickest pace for 14 years 2009"
Future looking good this morning proposing £45 million buyback.Can't be many companies buying back shares in the market right now.Here's hoping new management is as skilled as the old guard.It was a market darling before inflation and to be honest hasn't had any major non inflation related issues so far like some other companies.It'll be interesting to see whether today's momentum continues as therecan't be an awful lot of choice for investing in uk listed consumer discretionary cyclicals right now that aren't burning cash.And i know how many 'geeks' there are who are really into a certain 'niche' subject and are willing to spend a premium on their hobby and how sticky it can be, as i am one.
Regarding MS International (LON:MSI) and an acquirer's ability to strip out bloated central costs, my suspicion is in fact an acquirer might instead have to add cost. I had experience of a company that at face value bears similarities to this business in terms of the general industry segment and age/longevity of service profile of the directors. Whilst an acquirer might well be able to strip out heavy director salaries, it's quite possible they'll find a bunch of other overheads that are missing and would need to be loaded in. The questions I would pose include:
- is there a middle management structure or has all decision making occurred at the very top (because they know the business inside out having worked there for years and might be very autocratic in decision making style owning a decent chunk of the company)?
- are the IT systems and risks/process controls well invested and up to date with latest regulations? I think the Annual Report contains a red flag in terms of the commercial business risks that are not mentioned, it reads as a plain vanilla job that pays lip service to the requirements - if that's the approach to the annual report, what approach is taken to everything else?
I could go on, but then I'd sound like I'm deramping. For me as an outsider, the business has a very high YDKWYDK ('you don't know what you don't know') score.
As mentioned by Illiswilgig in today's comments, it's impossible for users to tag shares which are mentioned here, the Stocko search engine can't find them, and nor can any other search engine because of the paywall. I think this is is a major weakness of Stocko. Part of the justification for the subscription is the views of knowledgeable people on the SCVR each day. I find myself having to bookmark discussions so that I can find them again and it's a time waster. I have flagged this to Stocko but I don't know if anything is being done about it. Does anyone else feel this is a weakness - if so can we make a joint approach to ask for something to be done about it?
This is the greatest weakness of Stocko! I find myself checking through whole days of comments just to find a particular discussion. I also have innumerable bookmarked links. Why Stocko can't utilise an effective SCVR-specific search tool is beyond me. I assume there has to be a technical reason for this and would welcome an explanation.
ECO Animal Health (LON:EAH) - just a reminder that we are hosting management this Wednesday (12 July) at 2.30pm for an investor presentation with Q&A - the sign-up link is here: https://www.equitydevelopment....
ECO Animal Health (LON:EAH) - "FY23 results ahead of expectations" (new research report here: https://www.equitydevelopment....)
ECO Animal Health Group reported revenue for the year to 31 March 2023 of £85.3m (+4%YoY) and adjusted EBITDA of £7.2m (+34%YoY), ahead of market expectations.
Revenue growth was led by S&SE Asia (+42%YoY) and LatAm (+15%YoY). Gross profitability improved from a 42.7% margin in FY22 to 45.0%, whilst the (adj.) EBITDA margin was also up from 6.6% in FY22 to 8.5%. The year closed with net cash of £21.7m, with cash from operations of £15.9m (FY22: £(0.5)m), in addition to which the Group retained £10m in undrawn £10m RCF.
ECO allocated the equivalent of 9.8% of revenue in R&D spend in FY23 (£8.34m). The Group reports that two late-stage development projects are to be submitted in FY24; we note the collaboration (from 2022) with Imperial College London, and Moredun Research Institute in Scotland. Our medium-term cashflow outlook indicates ample resources to maintain the level of investment for over a dozen major projects underway or planned, alongside a healthy c£22m cash balance. A well-planned and well-resourced R&D and product development programme – the fruits of which are not factored into near-term estimates – form the basis for additional revenue streams which we estimate could add >£70m by FY28. We expect the group to update on R&D progress and spend before the end of this financial year.
ITDA and adjustments were over £4m?
RE:OnTheMarket (LON:OTMP)
Share options are excessive at 10.2m, but they’re mostly underwater, so not a worry.
I would worry that the options will be re-priced tbh. There is plenty of precedent for companies doing that. I would sell immediately on an RNS detailing such a move because it shows you where the managements priorities are. Not that I'd touch this company with a bargepole anyway. Perhaps the StockReport misrepresents the value here, but there's too much red, and if you disregard the large adjustments, there's bugger all operating profit announced today. I don't care how shrewd someone is, everyone gets some investments wrong, but saying a company is cheap based on the market cap is ridiculous, we need more bones than that. Especially when it generates little profit and no significant free cash flow.
Re OTMP - the red on the StockReport is because it had a high cash burning, loss-making previous strategy under old management. That's no longer relevant, as the current strategy is protecting the cash pile (which rose), and operating profitably & it is generating cash, contrary to what you suggest.
Even if we disregard most of the adjustments, the goodwill write-off is perfectly allowable, so profitability is actually about £2m, not "bugger all", also reflected in the increased cash pile.
Anyway, it sounds like you've made up your mind, so we'll leave it there.
Re OTMP - the red on the StockReport is because it had a high cash burning, loss-making previous strategy under old management. That's no longer relevant, as the current strategy is protecting the cash pile (which rose), and operating profitably & it is generating cash, contrary to what you suggest.
Where did I say it is not generating cash? So basically, the hope is that new management can turn around a company with historically very poor fundamentals by spending less. There is a Buffett saying that rings pretty true in my experience:
"When a management with a reputation for brilliance tackles a business with a reputation for bad economics, it is the reputation of the business that remains intact."
I wish you well with the investment and hope the company can be turned around for everyone's sake. I just don't see the point in taking that risk so was surprised by your GREEN rating. I don't see why there should be a correlation between your position and the rating. I would have this as an AMBER at most. You even stated yourself there is a high risk of a profit warning.
I rated OnTheMarket (LON:OTMP) GREEN because -
It's profitable, and profits rose strongly today,
Big cash pile is about a quarter of the mkt cap, and rising, so no solvency or major dilution risk,
Outlook & current trading in line, obviously there's a possibility of a short-term profit miss due to macro factors,
I see multibagger potential at OTMP once a bull market resumes, as it's grown well in recent years, and achieved profitability, so risk:reward strikes me as good.
I like the focus on developing tech to make the platform more useful for estate agents, and the potential for incorporating a moneysupermarket type offering for mortgage broking fees.
Risk:reward strikes me as very good, at such a low market cap, and the company has made good progress in the 5 years or so I've been following it.
As regards my holding a position personally, that's obviously because I think it's good! It doesn't automatically get a GREEN just because I hold, which you seem to be suggesting.
If it were to warn on profit, then I'd have to go to AMBER.
With Knights group (LON:KGH) on the menu, interesting to see reports on bloomberg today that DWF (LON:DWF) are reportedly in discussions re a takeover- maybe the sector is in fact too cheap?
https://www.bloomberg.com/news...
Yep sounds like 100p a share incoming, which is a lovely boost.
I'm really interested in the RNS from Future (LON:FUTR) this morning. They have announced a share buyback programme of £45 million.
Board believes that the Share Buyback Programme will provide greater flexibility to achieve an optimal use of cash to deliver value for shareholders, whilst still maintaining a strong balance sheet.
I've not really looked at Future (LON:FUTR) before but I do think they have a strong set of brands including Go.Compare
Any thoughts on this business from fellow readers?
Future (LON:FUTR) I've held in the past and seriously thinking about getting back in on current valuation. The share price is down around 80% from its peak a couple of years ago - the company had delivered pretty phenomenal earnings growth over past few years but this has now gone into reverse.
The question is whether this is just a blip due to a weaker consumer (they are heavily reliant on advertising) or the start of a long time downward trend. The recent departure of the long serving CEO is probably also weighing on the share price.
Hasn't a lot of their growth come from acquisitions and not organic growth?
I think that Future (LON:FUTR) could be taken over by private equity - Go.Compare is their best asset surely. I'm not sure about the real value of paper based magazines however.
Yes, I think a fair chunk of growth has come from acquisitions, but they do seem to have been successful in buying up specialist publications and then consolidating them onto their platform - in turn driving increased readership and better advertising yields.
Looks like they've done particularly well in the technology space (gaming, digital cameras, etc) although they've probably taken that as far as they can and now trying to branch out into new areas, such as home and fashion - remains to be seen if they'll do as well in these areas.
GoCompare is a bit different from the rest of the business - not sure if this is their best asset? I don't think it's as profitable as some of the other parts, but not looked into that closely.
I was comparing the strength of Moneysupermarket.Com (LON:MONY) (which I hold) to the potential of go.compare, also I think one of the other comparison websites got taken over recently?
They are mainly a digital media company. They have focused on this area over the last few years where many paper based competitors have been slow to transition, so this is a strength of their portfolio. And yes paper based is dying rapidly, but at least future have recognised this for a long time and have aligned themselves correctly as the industry changes.
Re: the debt of Future (LON:FUTR) - They announced a share buyback of £45 million - perhaps they should have used the funds to pay down the debt?
I tend to agree, and this must have been well considered. But this does also suggest that they feel the debt is manageable and that the business must be materially undervalued in their opinion.
My main concern for future will be how AI plays out in their industry. It threatens cheaper alternative competitors that could seriously harm them. But I feel AI based media may be inferior and not trust worthy - so a differentiation over the quality and accuracy of content should mean they stay ahead of the data collection bot type competitors. They can also harness AI for better efficiency and better understanding of their niche markets (as many of their media content is quite niche and specialist). But I do think that this will be their biggest threat over the coming years.
Doesn't debt keep the vultures off? Just a thought.
Re Future (LON:FUTR) - the balance sheet looks horrible - £10m of NTAV and over £440m of net debt at last balance sheet date
But why would you value Future on NTAV - they are not a physical asset business! The book value is at a discount. This intangible value is actually their business and how they generate revenue. With some businesses it is hard to value or understand the value of their intangibles - it is often IP that could become redundant over night. With Future the intangibles is basically a collection of over 200 media brands - these are what generates the eyeballs and the advertising. Whether the business model can allow continued growth I do not know - but what I do know is that Future have some great assets that make them a shed load of money. The level of debt may be a concern, but the fact that these brands generate so much cash suggests they are well worth the current book value imo - this has also been a challenging economic period - and it not like they are swinging to losses, and its unlikely they will be forced sellers of any assets. Personally I think it is one of those cases where you should ignore the NTAV and focus on the undeniable strengths of the intangible assets which have been so productive for them over the years.
Is there time for a look at Argentex (LON:AGFX) today Paul?
Thanks,
Jim
Argentex (LON:AGFX) FWIW I have sold out this morning. Basis: profits already stalling (they said due to investment in future which if taken at face value may be ok) but now rev seems to be stalling and they would have to have a phenomenal H2 to make forecast of £70 million.
For the 12 months to end 2022, rev was £50.4 million. Q1 2023 rev was £12.7 million. So Q2 was £12.3. So actually going slightly backwards sequentially.
Shame - I like the company and the CEO. Will continue to monitor.
Probably not I'm afraid, as I'm going to have to dash for a flight shortly.
agfx I also did not like tone of TU which only mentioned revenue with no mention of margins, costs,profitability etc. Also too many director movements which is not normally a good sign.--Trimmed holding substantially today.
Is there time for a look at Argentex(LON:AGFX) today Paul?
Merely “in line with management expectations” when competitors seem to be doing extremely well. Little data on profitability. Revenues slowing. Management changes. Cheap for a reason and justifiably cheaper this morning.
Re Argentex (LON:AGFX) the singer note released today has 2023E revenue at £60m so H2 revenue of 35m.
Remember there has been a change of year end from March to December so H1 2023 now includes one seasonally stronger quarter (jan-mar) with the biggest quarter by revenue (sept-dec) now in H2
This is my understanding but I have to say the year end change confuses the comparables somewhat- all we have is the management assertion that they are inline with their expectations
Impax AM (LSE:IPX) anyone interested in their Q3 AUM update today can read new ED research note here, with unchanged FY23 estimates and fair value also held at £9/share : https://www.equitydevelopment....
Knights group (LON:KGH) an acquisitive law firm published its full year results today. All metrics appear to be good and this has previously been considered GREEN. I work in the legal services industry myself and hold as I think it's performing well and integrating newly acquired firms into its structure but would appreciate an update from Paul or Graham. Many thanks chaps.
Hi Bristolian I also hold a few and have worked in law. It does look cheap if it can generate some organic growth or at least sustain earnings. My, significant, reservation before holding more is the relatively poor fee earner satisfaction/reputation and also aggressive cash collection. Do you have any view on these?
Hi Drogon, I'll have a think on that and come back with some thoughts.
Totally (LON:TLY)
No numbers waffle-
"The Board anticipates revenue in the year ahead to be lower than in the period to 31 March 2023. EBITDA is expected to be marginally below the period to 31 March 2023 reflecting improved margin driven by higher volumes in elective care, and the continued management and reduction of overhead spend. The Board are confident that the actions and strategy put in place over the past 12 months will ensure the Company remains in a strong position to continue to grow significantly over the coming years."
Reality -
Dreadful
Thanks Wolfie, I didn't get time to look at TLY's forecasts, so grateful for you posting that. So sounds like TLY's commentary is glossing over a nasty profit warning. I think we can definitely say now that management are not reliable in terms of their outlook comments, which is what I questioned in the main article.
Any Broker notes ?
"I think we can definitely say now that management are not reliable in
terms of their outlook comments, which is what I questioned in the main
article".
Yes, there was a PW on 2/3, 4 weeks before the period end. The outcome then expected was given as:
EBITDA for the year to be c. £6.3 m. Yes, tick( Underlying 6.9 less 0.6 exceptional)
Cash at period end is expected to be c.£5.5 m. That did not say gross or net. Outcome £6.5m gross £4m net. Can't judge.
Company intends to maintain its dividend. No - slashed, and that, IMHO. is an idication of the new financial year not being as rosy as they thought in March.
I have just listened again to a podcast made by the CEO with Vox on the day of the PW https://www.voxmarkets.co.uk/m...
"Confident higher costs will unwind .... if had June yearend may not have to reduce figures..... prospects are amazing.....confirms maintained divdend....".
So that confirm's Paul's comment.
S&P was down slightly on the week. Q2 earning start this week I think.
Chart shows percentage of stocks above 200d moving average is OK at 64%. This is worth keeping an eye on occasionally as it was an early warning signal in 2021, peaking 8 months before the market.
Roughly, FTSE250 is 26%. AIM Allshare 30%. FTSE100 33%
UK Markets
FTSE 250 had another poor week. 36Up – 212 down on the week.
28 above 200 + 50d averages. Only 8 above 2x normal weekly volume
AIM All share continues to look weak.
Weekly chart -
117 Up – 452 Down
78 Above 200 + 50d averages. 23 above 2x normal weekly volume.
Retail sales of UK funds in May, June likely poor also. Need this to reverse really to have a sustained rally.
US Regional Banks. Stable for now but wouldnt take much to trigger another selloff.
China 50. Looking weak also
German DAX worst week since March.
US Homebuilders have been strong since October, just signs it may pullback this month. Nice uptrend tho.
US 10 year Treasury- Looked like it was rolling over a couple of months ago but is pushing up towards last years highs again. Something to watch
Hope everyone has a good week.
Thanks Wolfie can I ask where you get this info from is it free or paid for site ?
Regards Andy
Phoenix, You can get all the charts Ive posted here for free. Use either Tradingview, stockcharts or most will be on stockopedia charts too.
I have a list of charts I look at on Sunday evening as a weekly review type of thing. Started doing it a few years ago and found it very helpful to take a step back and look at things with no distractions at the weekend, helps give a sense of perpective. For me at least its easy to get caught up in day to day movements so this really helps. Hope it helps a few others too
Thanks Wolfie the bit I'm most interested in is the fund flows by asset class part how would one find that ?
Regards Andy
You'll find it here Andy -
https://www.theia.org/industry...
Thanks Wolfie keep the pearls coming.
ECO Animal Health (LON:EAH) FY results this morning and I would welcome your thoughts if you get time Paul and Graham
The share price has been rather weak of late so I was reassured by todays results which look to be ahead of the Stockopedia forecasts
Supported by 30% of its market cap in cash and a good pipeline of R&D new products I shall continue to hold (tho I’m not sure if could be called cheap in these torrid times)
Yes, would be good to see a write-up on ECO Animal Health (LON:EAH) . Market cap £66m with £22m cash albeit £18m in China. I look at the book value of £95m + the excess NPV on the intangibles NPV of £118m (note 12). Implies this is worth c£200m+ before any possible bid. Obviously a global pharma could eliminate the cost base. I re-purchased this in the last year as it looks very undervalued once the China pig market improves.
My morning smallcap tweet: First service
Deltex Medical (LON:DEMG) Hemogenyx Pharmaceuticals (LON:HEMO) RM Infrastructure Income (LON:RMII) WANdisco (LON:WAND) Tissue Regenix (LON:TRX) Ondo InsurTech (LON:ONDO) ITM Power (LON:ITM) Impax Asset Management (LON:IPX) Scancell Holdings (LON:SCLP) Non-Standard Finance (LON:NSF), Quartix Technologies (LON:QTX), Argentex (LON:AGFX)
◄Deltex Medical (DEMG)► UK and EU launch of its new next generation TrueVue System. Will spend 3 months testing in hospitals before co takes orders. [SP=1.1 Cap=9m]
◄Hemogenyx Pharmaceuticals (HEMO)► FDA puts product candidate Chimeric Antigen Receptor T-cells for the treatment of acute myeloid leukaemia on clinical hold. Cites manufacturing process problem to which HEMO has a fix. [SP=1.42 Cap=17m]
◄RM Infrastructure Income (RMII)► consultation concludes that co will not offer a partial exit opportunity because the co is already sub-scale. "Progress concerning a potential combination of the Company's assets with another suitable investment company or fund remains limited." Will ut forward proposals on future of co ASAP. [SP=67.5 Cap=80m]
◄WANdisco (WAND)► Tesco renews support and maintenance contract. $200k over 2 yrs. [SP=1310 Cap=9m]
◄Tissue Regenix (TRX)► 3 yr UK distribution agreement for OrthoPure XT, "the only available, non-human biologic graft for certain anterior cruciate ligament ('ACL') reconstruction procedures". [SP=50.02 Cap=36m]
◄Ondo InsurTech (ONDO)► Sweden's largest non-life insurer - sign new five-year contract to support LeakBot's rollout across the group. Opportunity is worth over £30m. [SP=18.65 Cap=14m]
◄ITM Power (ITM)► will open office and warehouse in Germany in Oct. [SP=67.56 Cap=416m]
◄Impax Asset Management (IPX)► AuM up 2.2% in June but down 1% in Q. [SP=529.63 Cap=702m]
◄Scancell (SCLP)► drug update. Co to focus on development of Company's two lead clinical assets SCIB1 and Modi-1. [SP=12.9 Cap=107m]
◄Non-Standard Finance (NSF)► assets disposed, nil for holders. Will de-list on Aug 8. [SP=0.05 Cap=m]
In line: QTX, AGFX
Good Morning Paul. Good to see your thoughts on MS International (LON:MSI) - I hold (My largest holding by some way). I think that there are a few holders around here, and there was some informed discussion in the SCVR on 22nd June, when the results came out but its not picked up by the stocko with no tag. So I will copy my post with thoughts from the day into a seperate message below)
cheers
Mark
My Thoughts from 22nd June on FY results..........
Link to the SCVR
illiswilgig Joined 2010 231 posts Jun 22, 2023In reply to davidjhill
MS International (LON:MSI) FY results (unaudited) to end April 23 (I hold)
MSI is certainly raising more interest here than I am used to over the years. It's my largest holding by quite some way so I want to get my head around the detail of the results as soon as I have time - and given the lack of information (quite normal) I may have to wait for the audited accounts and the AGM in August.
Before I start the usual disclaimers regarding MSI apply. This is a family controlled firm. Very old-school in its approach - more the lack of it - to its investors. The board are not shy in rewarding themselves and there is nothing that small investors can do about it. Has to be taken into account. Luckily the company has a much better approach to its customers than its investors. Perhaps that the right way around?
On the face of it 25p eps is well below my expectations. After the good H1 results I'd expected a minimum of 37p and more like mid to high 40's. Outcome from defence was always going to be hard to forecast. But in the end its a thumping loss from the branding division in H2 which has delivered the damage a -2.6m loss for the year. Ouch! Effectively around 15p pre-tax earnings which explains the divergance? There is always one division at MSI that delivers a surprise! Either up ordown. Thats the down one.
Forging and superstructures delivered £5.9m of operating profits - around 35p of pre-tax profits on their own. Though the fall in revenues and profits from the high water mark of H1 leaves some questions over the trend for the current year.
Seems defence did ok. A 2m profit on 32m revenue. But because of the lumpy nature of the deliveries and the arbitrary date of the accounts its not a helpful guide to the future only the past? On closer inspection it appears that 2.2m is down to profit recognised on a contract terminated in April 23. That's quite a profit on a terminated contract. Very curious. And without it - the company would be short of another 14p or so of pre-tax profits. But alls well that ends well? Just like that! Thats the upside surprise then.
More good news. The delay to the delivery of the anti-drone systems appears to have been resolved and they will shortly be delivered. To be honest. I'm amazed that they were ready to go. It normally takes upwards of a year for MSI to deliver systems from contract and these were ready to go in little more than 4 months. Outstanding. That's a lot of overtime. Gives some idea of the urgency of the contract as well I guess? All the more frustrating that they are still waiting to be delivered? Its work on top of the 'baseload' if such a thing can be envsioned - though its worth noting that the work load on spares, maintence, training, refurbishment and repair is building all the time. A 20% profit margin seems a reasonably finger in the air guesstimate on that basis - so something like £4m, 25p eps on top of the recent low level of profits?
Even more good news. A second order for £54m (bear in mind that Defence turned over £32m in the year excluding the anti-drone contract) has been received from an undisclosed customer. Not stated whether the same urgency applies. Though the size of the contract and the speed with which its arrived implies some urgency. There is some implication that the land-based anti-drone market it developing much faster than MSI's traditional Naval market. To anyone addicted to youtube/twitter videos of fpv drone loitering munitions from Ukraine this will not be a surprise? It does seem that MSI are in the right place at the right time with very good connections. Huge potential to play for.
And more. The order book now stands at £115m. Which is normally primarily in defence.
Yet more good news. The company continues to make progress with its US Navy contract - a framework contract which was previously held by BAe Systems but won this time around by MSI. It's sole source and will role their systems out across large parts of the US navy and coastguard. Technical assessments seem to be complete and the framework contract exists, commerical negotiations for the first order are soon to take place. This contract is enormous over several years - but probably its biggest effect will be providing a steadier work load and also in acting as sales/marketing for global customers.
I find it very difficult to express the long term prospects for the defence division and to attach a valuation to it. There is a transformation underway which looks to be quite extraordinary, though frustratingly lumpy and unpredictable. As yet the order book leads the profitability especially since the company has been investing in facilities in the UK and the US to support its rapid growth.
Despite the disappointment of these results - the current year looks set to be record breaking - given the roll over of the delayed deliveries in H1 and the new contract. So oodles more jam tomorrow? Possibly. But management is not given to optimistic statements - and the positive tone of the commentary is very unusual. Not a single comment about the usual caveats? And the massive increase in the dividend from 7.5p to 13p - seems to be a very clear signal of jam today as well as management expectations in the current year.
All very promising, but I'm going to have to wait until December for the next exciting installment. I am optimistic for another nice xmas pressy though?
cheers
Mark
3 Replies