Small Cap Value Report (Mon 10 Oct 2022) - RFX, BOWL, LINV, QTX, MADE, JOUL, BKS

Good morning from Paul & Graham!
Podcast - the summary for last week went up on Saturday, on podcast platforms, and here on my website. Last week's "mystery shares" (i.e. for Stockopedia readers only), which are my best ideas from the week, are;
Victorian Plumbing (LON:VIC) - see Thursday's report
Castings (LON:CGS) - see Friday's report, and
Wincanton (LON:WIN) - see Friday's report.
CEO Interviews - I enjoy doing audio interviews, and am planning on doing more. This week I've got 2 planned, both on Thursday, both are shares I hold personally this time (they're usually not), being -
Beeks Financial Cloud (LON:BKS) (reporting today)
XP Factory (LON:XPF)
So if readers here have any clever questions that you want to suggest, I'd be happy to hear them in the comments below. I would stress that my interviews are fairly high level, so trying to understand the businesses generally, not usually drilling down into minute detail. So I can't promise that I'll be able to ask your specific question (that's more suitable for the excellent webinar formats run by PIWorld, or IMC, and others), but it would be good to hear what topics you think are most interesting for me to ask about.
Agenda
Paul's Section:
Hollywood Bowl (LON:BOWL) - another positive trading update, ahead of expectations for FY 9/2022. Although I can't crunch the numbers accurately, because there's not enough information provided, and no broker notes available to me. The balance sheet is strong, with lots of net cash driving a self-funding roll-out of new sites. The dividend yield is now 5% and growing. So the fundamentals look great. Will the boom continue though? That's the big unknown, and the key to determining if the shares are cheap, as they seem, or just enjoying a boom that might fizzle out eventually?
Beeks Financial Cloud (LON:BKS) (I hold) - Results FY 6/2022. Just to let you know, I'm currently working on this section, it should be up between 1-2 pm. Update: see tomorrow's report, as this section missed today's cut-off.
Made.Com (LON:MADE) [no section below] - a quick update from last week. As previously reported, this heavily loss-making online furniture company is up for sale, in a last ditch attempt to avoid running out of cash & insolvency (it has previously said that it couldn't raise sufficient equity). The latest update says it has "begun discussions with a number of interested parties regarding the sale of the group". Timescale - non-binding indicative proposals are invited by mid-October, so this week & next week really. The Directors will review the proposals, and then start a second phase of discussions with a "select number of parties". Current plans require a cash injection of £45-70m over the next 18 months.
My view - MADE looks highly risky for existing equity. MADE failed to become viable during the pandemic, in perfect conditions - when everyone was shopping online, and its physical competitors' stores were closed. Trading has since collapsed, with huge losses this year, and cash rapidly dwindling. Shipping costs & supply chain costs became excessive, and should ease gradually in future, but will MADE still be around by then to benefit? Just because there are several parties interested, and going through the numbers, doesn't mean the equity is worth anything. Why would a buyer bail out existing shareholders, who have already declined to refinance the business? It's possible that somebody might see value here - there are press reports (maybe placed stories to talk up the price?) of private equity buyers sniffing around. Anyone holding this share is taking a massive risk of a 100% loss, in my opinion. Why take that risk, just on hope that a white knight might ride to the rescue, for a company that is close to insolvency? I'd say the probability is maybe c.90%+ that equity ends up worth nothing, and the business is bought out of administration for very little, leaving nothing for shareholders. I could be wrong, it's just educated guesswork at this stage, but I'm flagging extremely high risk, and that this share remains uninvestable. Anything could happen though, only insiders know what's going on. [no section below]
Joules (LON:JOUL) [no section below] - in a similar vein, but nowhere near as severe as MADE, JOUL is also on a tightrope needing to refinance. I need to set aside my incredulity at how previous JOUL management have managed to wreck a previously excellent business (whereas MADE was never a decent, profitable business). An update today says -
- Making good progress with turnaround plan
- Possible equity raise (as previously reported)
- Considering other options, including a CVA (not yet determined if necessary)
My view - it's still too risky for me, so I'm watching from the sidelines (as mentioned here before). CVAs don't necessarily involve wiping out existing shareholders, but I would expect a CVA to be done alongside an equity fundraise, and renegotiated (probably lower) bank facilities, it's often a package like that, which preserves some value in the existing shares. But it depends on how supportive existing shareholders are - especially the founder, who banked £12m in April 2021, part-selling at 232p. He remains the biggest shareholder at 21.7%. Will private investors be looked after in this process? Only insiders know, and there are a very wide range of possible outcomes here, ranging from OK, to a 0p wipe-out. So at this stage, this is impossible to value, and has to be seen as very high risk. For gamblers & optimists only at this stage, I'm afraid. Once again, I apologise for my previous misplaced bullishness on this share, I had no idea trading would deteriorate so badly, and the company would be run into the ground by incompetent management. [no section below]
Graham's Section:
Ramsdens Holdings (LON:RFX) (£62.5m) - an excellent pre-close trading update from this provider of pawnbroking, forex and other related financial services. Two of the four segments are above their pre-Covid levels. The forex segment is not quite there yet, but it is close. Pawnbroking is above pre-Covid levels and the momentum here looks excellent. The cost of living crisis may possibly hurt the demand for holiday money at some point, but conversely increases the demand for short-term credit. With many payday lenders having left the market and not been replaced, I can see the pawnbrokers having a very strong few years ahead of them.
Lendinvest (LON:LINV) (£104m) - this is an asset manager and an investor in the property space. Originally focused only on bridging loans, it now offers both development finance and buy-to-let products, and has an online platform for borrowers and lenders. This morning, the company has issued a nasty profit warning as it expects fewer growth opportunities in the buy-to-let category; it has needed to reprice products to shield itself and its investors from vulnerable property prices. The broker’s PBT forecast for the current year takes a huge cut. I’m nervous about this company’s prospects and would need a chunky discount to book value to get me interested here.
Quartix Technologies (LON:QTX) (£164m) (+3%) [no section below] - this telematics company provides a trading update in line with expectations for Q3. Annualised recurring revenue hits £26.9m, up by over 10% year-on-year. The subscription base is up 17% year-on-year. The company highlights growth in new subscriptions of 24%; I view this figure as the “second derivative” of growth and as being less important than the 17% growth in total subscriptions. The company expects more of the same in Q4. CEO Richard Lilwall is happy with the strong progress made in France: growth is led by Continental Europe, while the mature UK market continues to put in a solid performance. Growth in the US is slower. My view here is unchanged from July. I like the company but I’m not sure how to justify the valuation at 6x ARR and have concerns about price erosion for telematics technology. The forecast PE multiple is 30x. [no section below]
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section:
Hollywood Bowl (LON:BOWL)
205p (pre market open)
Market cap £352m
Hollywood Bowl Group, the UK's largest ten-pin bowling operator, today announces a trading update for the financial year ended 30 September 2022 (FY22).
Excellent operational and financial performance - investing in UK growth and international expansion
The Group has continued its excellent momentum following a record first half with another period of strong trading and further growth.
The boom in ten pin bowling continues. We reported here on 21 Sept 2022 impressive interim results from smaller competitor Ten Entertainment (LON:TEG) with forecasts also raised. TEG seemed to think that a step-change upwards in revenue & profit has happened, calling it a “new baseline”, but I don’t see how they can be so sure that it’s not just extended pent-up demand? Although we should recognise that the customer offer has improved, with better & refurbished sites, and additional games (not just bowling).
Some key numbers for FY 9/2022 -
Revenue £184.9m (well ahead of forecast £170m showing on the StockReport).
Like-for-like (LFL) revenue growth of 28.3% compared with pre-pandemic FY 9/2019 - this is a key number for all retail/hospitality businesses, and it needs to be strongly positive, to absorb 3-years worth of additional costs, which this is.
EBITDA (pre-IFRS 16, so a meaningful number) guided at £38.2m (up over 40% on pre-pandemic FY 9/2019) -
The Group expects to report EBITDA4 growth (pre IFRS-16) in excess of 40 per cent compared to FY19 (£38.2m), ahead of market expectations
Continuing to expand, with 2 new sites in the UK imminent, plus another 10 planned over the next 3 years.
Canadian acquisition is trading in line with expectations, and rapid expansion into new sites planned.
Net cash of £56m, plus undrawn £25m RCF - so tons of liquidity here, and little to no dilution/insolvency risk, in my view.
Balance sheet - when last reported as at 31 March 2022, looks fine to me. Although note there is a deficit on the lease entries, suggesting it has some under-performing sites. That would be a good question to ask management about, if they do a webinar - how many loss-making sites are there, how much do they lose, and what plans are there to exit or renegotiate on those leases?
For more detail, I reviewed BOWL’s interim results here in May 2022. Note that there was a £3m boost in H1 from temporarily reduced VAT.
Seasonality - checking the half year results table on Stockopedia here, there’s a strong H1 bias to profitability pre-pandemic, 2017-2019. H1 results this year seem to show EBITDA of £31.0m on the same basis as the FY 9/2022 guidance of £38.2m. So it seems that there’s a more pronounced H1 bias to profits this year.
Costs - “well insulated” from inflation. Electricity is hedged until end FY 9/2024. Solar panels being installed (we’re seeing this from quite a few companies now, pleasingly, and payback periods are now much shorter). Interestingly, food & drink is low, at <10% of overall costs, menus simplified, and labour costs are <20% of revenue at centre level. This sounds as if the position is pretty solid, nothing to be alarmed about re costs.
Dividends - a final divi of at least 7.5p is mentioned today. A 3p interim divis has already been paid, so 10.5p+ for the full year, a healthy (and growing) yield of about 5% - well worth having, in these inflationary times. Note also that in the past, BOWL has paid special divis, usually a similar size to the final divi. Plus it’s self-funding its own growth, and has accumulated a nice cash pile. So this is clearly a decently cash generative business.
Valuation - I can’t make sense of the profit numbers, because there are no broker forecasts available to me. So although BOWL says it’s ahead of expectations at EBITDA, I can’t see how that figure reconciles to the broker consensus net profit figure of £34.3m shown on the StockReport, there seems an anomaly between those numbers.
Therefore I think all we can do is assume that EPS might come in a bit ahead of the 21.9p broker consensus shown on the StockReport. If it’s say 23p, then the PER would be 8.9, which seems very good value.
My opinion - bowling companies are trading their socks off right now. If that level of demand continues, then the shares are really cheap.
But will demand, and hence profits, remain at elevated levels? Or are we seeing a continuing boost from pent-up demand? Who knows?
That’s it really, the investment case depends entirely on what you think is likely to happen in future. I don’t have any particularly strong view either way because this is an unknown factor, and nobody knows how the future will pan out.
As a value operator, it could be that BOWL is an affordable form of entertainment, which might do well in tight consumer spending times. This stood out for me -
The Group remained the lowest cost option of the major ten-pin bowling operators with a family of four able to bowl for under £22.
Hence on balance, I'm leaning towards seeing this share as attractive value. In more normal macro, and stock market conditions, this share would undoubtedly be considerably higher, based on these numbers.
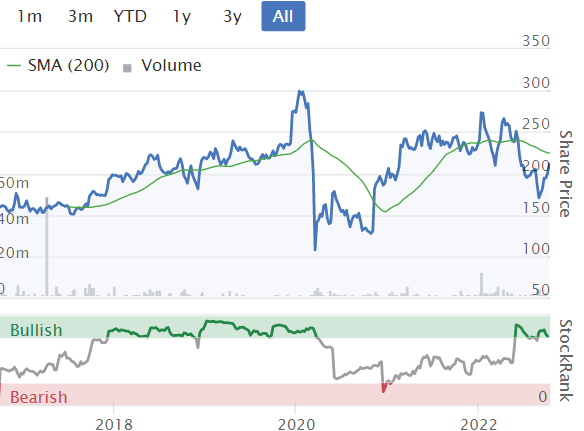
Note that the share price isn't a lot higher than when it floated in 2016. Yet the business is considerably bigger & more profitable now.
.
Graham’s Section:
Ramsdens Holdings (LON:RFX)
Share price: 197.5p (pre-market)
Market cap: £62.5m
This is “a diversified financial services provider and retailer” - it’s easy to think of it as a pawnbroker, but in reality it is diversified over a range of other products.
Forex has historically been a very important segment for it, and the good news this morning is that gross profit in this segment has “almost” recovered to pre-Covid levels. Gross profit for FY September 2022 comes in at £12.6m (the equivalent result for FY March 2020 was £13.1m).
The other segments sound like they are doing well, too:
- Jewellery retail revenue £26.2m (+40% vs. last year), much higher than pre-Covid levels.
- Pawnbroking loan book £8.6m (+41% vs. last year), above the pre-Covid loan book.
- Precious metal buying revenue £16m (+50% vs. last year).
So the growth vs. last year is stunning, and there is some growth vs. the last pre-Covid year, in two of the segments.
CEO comment:
"We are pleased with the Group's very strong performance during the year, which again reflects the resilience of our business model and the strength of our value-for-money reputation amongst customers.
We are particularly pleased with the strong rebound in our foreign currency segment, which has been a key driver behind our profit performance… we are in a good position to continue our positive momentum into the new financial year."
My view
It’s difficult to form an opinion on this in isolation to H & T (LON:HAT) (where I have no position currently but still have a positive view on the company).
This trading update is superb and, like H&T, it appears that Ramsdens is currently firing on all cylinders.
As I’ve already noted, this company is heavily weighted to forex. Maybe, if the cost-of-living crisis hits tourism, there could be less demand for holiday money? That’s one of the few vulnerabilities I can think of, and it does potentially affect the most profitable segment at the company..
That aside, I can think of little that is standing in the way of continued growth here.
The pawnbroking segment - which I view as the anchor for the jewellery retail and precious metals buying segments - is strong again, and this is attributed to:
customer spending habits returning following the easing of restrictions related to covid-19 and fewer alternative options for small sum short term credit.
That last bit caught my eye. As noted in The Guardian recently, payday lenders have been allowed to go bust (e.g. Wonga) but few new payday lenders have been allowed to operate. This creates a bigger market for unregulated, illegal lenders and also for regulated businesses such as pawnbrokers.
As a reminder, one of the best features of the pawnbroking loan is that if the customer walks away from it, they suffer few repercussions. They will not return home some day to find the bailiff knocking at their door. Even their credit score is unaffected. They lose the item but that is all. Regulators tend to worry about the rate and the amount of interest rate being charged but not about the format of the loan itself.
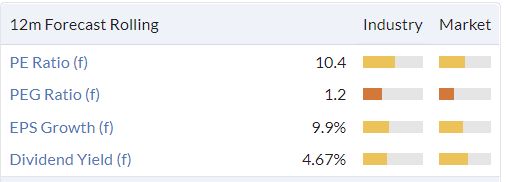
This share gets the thumbs up from me. Despite the growth momentum, it does not appear overly expensive, and ROCE/ROE should hopefully return to their previously high levels.

Lendinvest (LON:LINV)
Share price: 75p (-23%)
Market cap: £104m
This is another 2021 IPO. Down 60% so far:
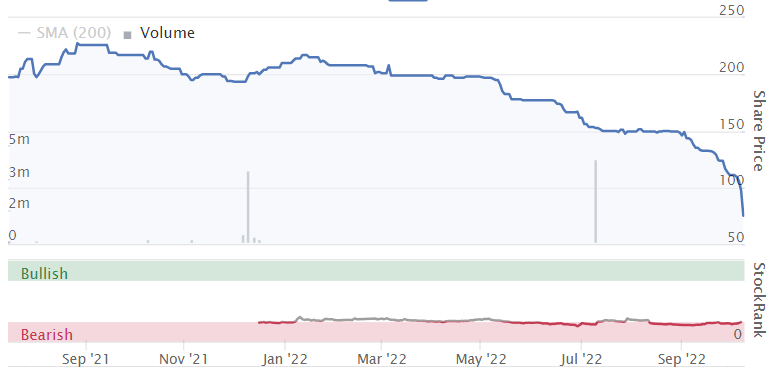
While the bear market we are going through is undoubtedly difficult, I also think we need to reflect on the glut of overpriced IPOs in 2021. I think we can safely conclude that there must have been a period of irrational exuberance, which allowed so many overpriced small-cap listings to hit the market around the same time.
Here’s a five-year chart of the AIM All-Share Index. We can hardly blame bankers and corporate issuers for selling stock to the public last year:

Let’s take a look at Lendinvest, which has not been covered in the SCVR before.
It describes itself as “a leading technology driven asset manager for UK property finance”.
On its website, you can apply to borrow for a range of purposes, all of which can be categorised as either bridging or development. The “bridging” category includes buy-to-let products.
It is also possible for individuals and institutions to use the website to invest in loans made by Lendinvest. Lendinvest uses its own balance sheet to invest, and is a manager of third-party assets.
Today’s update offers some optimism despite the challenges posed by rising interest rates. But there’s a profit warning later in the RNS.
"Looking ahead, we are acutely aware of the disruption in the UK mortgage market, which is affecting confidence and for the moment, applications for new mortgages have slowed across the market. Recent market dislocation has demonstrated the flexibility and speed to market capability of our platform. This provides us with a competitive edge, flexibility, and proven risk management capabilities, which in addition to the size of our addressable markets and our strong financial position, gives us confidence in our long-term prospects."
The growth figures for H1 - the period from March to September - look good, but of course markets are forward-looking and it’s the next six months which matter most. Deployed capital has reached £2.4 billion (up from £1.8 billion a year ago).
The company also reports “committed and deployed capital”, which apparently includes funds that the company could invest, but has not yet found a home for. There is a big discrepancy between this figure (£3.4 billion) and the amount that has actually been invested. It looks like this discrepancy was increased by recent agreements with Lloyds and JP Morgan.
More agreements on the way?
Investor appetite remains strong and we expect to complete a number of additional transactions in the second half of the current financial year.
Outlook
The profit warning is revealed down here.
Here's my summary of this section:
- The company has repriced products and “tightened our credit appetite” to protect returns given the likelihood of falling property prices.
- H1 growth was in line with expectations, but growth in Buy-to-Let in H2 is likely to be below expectations. The company has reduced its opex in anticipation of this.
- FY March 2023 PBT is probably going to be around the same level as last year.
I’ve found a note from finnCap, wherein they have today cut their PBT forecast for the current year by 31%, to just £14.2m.
The top-line revenue growth forecasts for this year and next year are cut by between 7% and 9%.
There appears to be very significant operational gearing; this is why the opex cuts are so important, to prevent the company from swinging even lower towards breakeven.
My view
I’ve dug out the March 2022 balance sheet. Lendinvest has net assets of £97.5 million, or about £90m after deducting intangibles.
Balance sheet leverage was as follows: the company was carrying loans and advances with an accounting value of £1.2 billion, and had outstanding borrowings of the same amount.
This leverage was reduced by a large securitisation in May. It has also raised new funds by issuing bonds. The company has been “selectively moving assets off the balance sheet”.
As there are quite a lot of moving parts, I’m unable to form a strong view on Lendinvest today. But I suspect that it should be trading at a discount to book value, given that higher rates are likely to pose a severe test for its remaining loan book. I’d also really like to see the new balance sheet for September 2022, after the dust has settled from all of the various events in H1.
We’ve also got the IPO problem: yes, the shares are down by more than 60%, so they are cheaper than they were before. But if I was to put my trading hat on, I would say that the share price momentum here is extremely negative, the company is issuing profit warnings, has a horrible economic outlook, a highly leveraged balance sheet with questionable values, and has still not found a floor after an overpriced IPO. It’s not clear to me that we have a solid underlying business to invest in here. But perhaps it will come good in time.

Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

46 comments
Hi Paul ,
Quiz plc had an update today but I haven’t seen it being covered in the small cap value morning report ( unless I am missing something ).
Are you still a holder of 2% of the company as you have previously stated?
Thanks
Yiannos
Hi Yiannos,
I had most of my small cap positions (including QUIZ) in a leveraged account with Spreadex (BIG mistake!) so this bear market has multiplied my losses on those positions by typically 4-5 times. I did downsize a lot of the positions in stages, but more recently (as mentioned here, and in my podcasts), I capitulated on lots of positions, due to mounting, geared losses.
So I'm not actually holding many of my previous positions any more, to protect what's left of my capital.
In that context, I did hold onto a smaller position in QUIZ at Spreadex until a month or two ago, but had a final clear out and that one had to go unfortunately. My view on the company's fundamentals is unchanged, I basically had to sell most positions, rather than actively wanting to sell them.
So as things stand now, no I don't hold any QUIZ any more. Pity, as I'm sure my analysis was right all along, but everything's getting beaten up in current markets.
The agreement I've always had with Stockopedia is that I have to disclose whether or not I hold each share, when I write about it. But in between reports, I'm free to buy or sell as I please. In practice, I transact very little, as I think longer term, but of course there was a complete mismatch between that investing stance, and using a geared account. Normally it worked well, but in a sustained bear market, it's been disastrous. Plus my hedging strategies last autumn went horribly wrong too. All a bit of a tale of woe. So going forwards, I'm not going to put long-term positions into geared accounts, but instead will focus on putting the long-term holds into the accounts where I own the shares outright. No more shooting for the moon, I think slow & steady is going to be the way forward for me.
Regards, Paul.
I do not think you should hold any positions ( short or long term ) in any geared account. This is a friendly advice (based on multiple clients I have seen in the past losing everything). Leverage is just gambling your money and hard work away. But I am sure you have realised this by now.
Thanks
Yiannos
Yes, you're completely right, I agree.
Note that the share price isn't a lot higher than when it floated in 2016. Yet the business is considerably bigger & more profitable now.
Worth remembering there have been at least two placings since 2016 (7.5m shares in April '20 and 13m more in March '21). I make that ~14% dilution. You need to take that into account when viewing the share price.
All the best, Si
Yes, good point Si.
Hollywood Bowl (LON:BOWL) had 150m shares in 2016, which has risen to 171m, about 14%, as you say. Not too bad actually, over a 6 year period that included the pandemic. But you're quite right, it needs to be taken into account when looking at the chart.
Thanks for flagging!
Regards, Paul.
https://www.youtube.com/watch?...thanks
Hi Paul, very grateful if you did manage to sumamrise your thoughts on friday's £JDW. Always appreciate this, and certainly, only if you felt you had the time. no stress.
Hi tic_tac_toe,
Yes, I do want to look at J D Wetherspoon (LON:JDW) but there are too many other things taking priority right now, hopefully we can cover it later this week.
I think it's a very interesting, unique business, due to its value for money offering.
Regards, Paul.
Hi Paul, thankyou for the podcast. Becoming my Monday morning go to. Given Beeks have said "We have the potential for considerable additional growth given the size of the sales pipeline, however these types of discussions will take time to flow through into contracts and revenues" I would be interested to hear their thoughts on how the pipeline is affected by the macro environment in particular the falling markets which clearly impact on investment companies profits.
Good question Camtab, I shall ask Beeks Financial Cloud (LON:BKS) in my interview on Thursday. Had something in mind already, but you're reinforced it, so thanks!
Sell it to The City. The latest episode with presentations by undergraduates from Sheffield, St Andrew’s & Cambridge Universities to Andy Brough, Schroders, Judith MacKenzie, Downing & Stephen English, Stellar Asset Management.
The stocks pitched are CPPGroup (LON:CPP) Norcros (LON:NXR) and Vector Capital (LON:VCAP)
These are impressive presentations for such young investors. The Fund Managers give great insight on additional things to look for. Since Schroders own 10% £CPP Andy gives his comments. A lot of fun & educational.
It’s long so perhaps take in sections. Video and podcast.
Separately, Eneraqua Technologies (LON:ETP) have announced interim results will be released tomorrow. Management will be giving a presentation followed by Q&A tomorrow 11th October at 12 noon. Register here to attend.
Does anyone know what is happening with Indivior (LON:INDV) today (I hold), figures look wrong ?
Does anyone know what is happening with Indivior (LON:INDV) today (I hold), figures look wrong ?
As a holder you should know about the 1 for 5 share consolidation.
Interactive Investor shows as price £0.00 in my account, and no messages... I obviously missed this one.
Large founder purchase of shares in Victorian Plumbing (LON:VIC) reported today.
Sold at the top and buying at the bottom. Another IPO failure for shareholders.
Unless you are a shareholder buying at the bottom ;)
Luceco (LON:LUCE) is up 15% at the moment. Was it tipped in one of the Sunday papers?
Yes - in Small Company Share Watch monthly tip sheet
Is that a worthwhile service?
Not read it, but I believe recent tips have included Reach (LON:RCH) and Tremor International (LON:TRMR) - not companies I'd want to own and both down very heavily this year, so track record a bit spotty. I personally think this is a much better resource.
I got a sample. It was from 2020. Tipped Reach at much higher levels than today and Joules at 105p.
Very few companies were not at much higher levels in 2020 !!
I use SCSW a lot, finding their selections interesting and useful, in conjunction with lots of other sources - such as Stocko of course. They have over the year done remarkably well with their selections with many multi baggers like SDI (LON:SDI) and Kape Technologies (LON:KAPE), but in the last year, the ones selected for their Portfolio have done poorly - like many other small company shares! Their best NAPs for 2022 were ME International (LON:MEGP) and £MNZS, their worst Joules (LON:JOUL)
If used carefully..
I have subscribed since '15 and the real performance of all their buy tips does comfortably beat the FTAS (like SimonT in the IC there is often a surge when published, I count from 2 days post publication). They do tip some losers - there is a v.big variation in returns.
I use it as a filter - their tips and F Score > 5 and SR > 60 and I start reading / looking for myself from that shorter list.
Is it worthwhile - not sure, I think the SNAPS portfolio type approach may be beating the SCSW GP3 - probably as it holds bigger companies.
SCSW's commentary on macro issues is a bit delphic, but pretty incisive .
#BKS announced both their final results and two contract wins of 2m over 3 years this morning. Revenue is now over 20m a year and continuing to grow strong. All of this is being reinvested in growing the company which showed 57% revenue growth last year.
I continue to be excited about this share and am happy to see little profit for now and the focus on growing the business. When customers are acquired they tend to be very sticky and increase business over time when they get comfortable with cloud computing . I could see this being a 40-50m revenue company in 3 years. I still think longer terms its a likely takeover target but hope it can grow substantially before that happens.
Beeks Financial Cloud (LON:BKS) (I hold)
Is their commentary misleading, or am I just misunderstanding? They say:
"Statutory Profit before tax decreased to £0.07m (2021: £1.26m) mainly as a result of the fact there was a one off write back of £1.99m due to the contingent consideration due to VMX Ltd in FY21 that was not paid."
But the fact that there was hardly any statutory profit in FY22 is plainly as a result of the ballooning share-based payments (546k FY21 vs 1661k FY22). The comparison to last year feels mostly irrelevant in view of this. Fundamentally, they made £400k more "underlying" profit for the year, but paid out >1000k more in share-based payments.
We assume we can expect more of the same in the coming years, given the number of options issued.
I know that I dislike the presentation in the commentary, but I'm unsure as to the extent to which this is a problem if they maintain their current growth.
Any opinions?
I think the share options is a good question for Paul to ask of the management when he talks to them.
I would also have at what stage would they see the investment they are putting in scaling allowing for some profitability.
Paul. Very good to see your "mystery shares" listed as you have. Please continue to do it. Others please like this comment if you agree.
Hi, thanks WarrantStar.
I appreciate not everyone has the time or inclination to listen to podcasts, so I thought it would be helpful to mention the best shares of the week (in my opinion only) as "mystery shares", and keep them exclusive for Stockopedia subscribers only. That seems only fair to me, because you're all paying for these reports here, so it seemed unfair to then give away free my best ideas to the internet! So that's why I'm doing it. At some stage maybe we'll put the podcasts behind the paywall, but that hasn't been discussed, everyone's busy on other things I think, so I just do my own thing & hope it works!
Getting back to your original point, yes I will post the podcast mystery shares here every Monday (and Friday). They're all in the SCVRs here for the week, so subscribers get to see our reviews before anyone else already.
Regards, Paul.
Hi Paul, thanks for your podcast and write ups. I thought I would let you know that the non Stockopedia subscription subscribers have been able to see your mystery shares this week as the top section of your write-up appears in the emails if you subscribe to them. Therefore, if you want them to stay hidden, it might be a good idea to put them at the end of your write-up.
Hi cazulas123,
Oh no, schoolboy error from me there, thanks for flagging it! I'll have to put the mystery shares right at the end in future.
Regards, Paul.
Intercede (LON:IGP) a helpful positive trading update and acquisition.
amazing SP response to Intercede (LON:IGP) acquisition. As they say, it is the IP that matters, not the revenue though that is useful. Commentary gives the imprerssion that they now have acquired the vital part of the jigsaw, the answer to a virgin's prayer. The SP rise shows that someone understands the value of this acquisition. More than I do!
Hi, my knowledge of IT security is way out of date, but nevertheless I'll give you my pennyworth. IT security splits into several product areas - authentication (knowing you are who you say you are), access control (allowing people to use your app, perhaps with a restricted view of data), security admin (as well as authentication management also making sure access control is up-to-date with people joining, leaving or changing organization roles) and fighting against all the people who wish to break into your system or just to break your system. Intercede (LON:IGP) operates at the top end of authentication - clever, difficult but complex. They recently announced they do access control as well with surprised me because I thought they had been doing it for ages. Its new acquisition operates at the bottom end of security - password management and things like that. In my view taking a complex product and making it easy to use is more difficult than making adding top end features to a simple product, and that is why Intercede (LON:IGP) has struggled to grow its market. The reservation I have of products that operate at the simple end of the market, is that the platform vendors (Microsoft, etc) are slowing creeping up adding features. I haven't bought McFee because I think Microsoft Defender is sufficient, for instance. I can't see Microsoft or others doing what Intercede (LON:IGP) does for a long time, but the major market for independent vendors I think is IT security admin. It is a huge challenge to make this easy to use, run across multiple platforms, doesn't open up security holes, and can be easily integrated into your apps.
I don't believe their is significant marketing synergy between Intercede (LON:IGP) products and Authlogics - the customers are too different. So I think Intercede (LON:IGP) have in their minds a long term strategy to develop products to manage authentication and access control for a wider set of business and this looks like what they mean by saying it is the IP that interests them. I wish them well. (I don't hold.)
While the Intercede (LON:IGP) management commentary says "trading in line", it looks like on constant currency basis they are poised to do maybe £12.2m FY22 revenues, which is higher than the £10.9m average broker forecast in Stocko.
Also, H2 should see higher reported GBP revenues, as their main revenue currency is USD. So assuming maybe a 12% FX benefit, that would mean close to £13m FY revenues. Quite a beat on £10.9m forecasts. Most of that beat will drop straight to the bottom-line (fixed costs mainly GBP), so profits should see +£1m boost from current forecasts, which is +1.7p extra EPS. Much more than the current 0.4p EPS in Stocko FY22 broker forecasts?
I also believe many AIM shares have been oversold; it was nuts that Intercede's market cap before today was £22m, and net cash (before acquisition) was £10m, almost half! I am kicking myself for not buying more, as I had my buy trigger at 37p, and the shares came close (39p ask) before today.
I'm still digesting today's acquisition, so don't have a view yet. But you can see that trading is going quite briskly; £2.2m positive cashflow in H1 demonstrates how reliable and solid the revenue flows are here at Intercede.
(I hold in the Boon Fund)
Bonhill
Lots going on there and looks like Christopher Mils and Richard Staveley maybe getting a boot up the backside of this crock of sh1t .
Announces formal sale process and a huge splash of retention bonuses if company is sold and options - so certainly management are now incentivised , of course at shareholder expense , to try to dump this dog of a company onto soneone . Might indeed suit a US buyer with dollars to deploy .
A rather self serving finance package from Rockwood which seems to include a 40k arrangement fee (even if only 200k is borrowed ) then 2% a month .
“Harwood
Capital LLP ("Harwood") to provide up to £800,000 in cash at a monthly
compound interest rate of 2% on funds drawn down, which will be capitalised
("Loan Facility"). The Loan Facility, which runs to 1 May 2023, has an
arrangement fee of 5%, may be drawn down in tranches of £200,000 and will be
used for working capital purposes. The Board does not anticipate that the
Company should need to draw down on part of the Loan Facility until February
2023 at the earliest.”
To be fair Rockwood seem exposed on this hence the sky high rates so presumably they are confident of a sale .
It does look cheap if you can sell off the assets piecemeal could end up with a nice cash shell, though who wants a cash shell at the moment . ?
nice start to the week in this trading update from Ashtead Technology Holdings (LON:AT.) (Ashtead Technology Holdings)
"Given the strong underlying performance, and supported by the continued positive market outlook and favourable exchange rates across its international business, the Board has increased confidence in the Group's trading outlook and now expects to materially outperform its previous expectations for the full year ending 31 December 2022."
Refreshingly upbeat given the gloomy prognostications almost everywhere else in the general market.
https://www.investegate.co.uk/...
Quiz
Interesting trading update which seems to be extremely positive with cash at 9 million . Sales up , Margin up .
But not a mention of profit ? Or the much substituted and much abused EBITDA .
Looks a cracking update but the total lack of profit mentions feels weird .
You could negatively say “turnover is vanity profit us sanity “
Or you can choose positively my old FD favourite “cash in the bank doesn’t lie”
Does look stunningly cheap and I used to hold, but I just don’t like the sector and I find the management of fashion companies like these generally very self serving so it’s not investable for me (sorry that’s a very broad brush swipe there on management ) .
Not weird - trading updates, even of FTSE 100 companies, will focus on revenues. They will then infer on impact on margins (either up or down) and guiding whether still within expectations etc.
Like most companies, at the half year trading update Quiz (LON:QUIZ) are unlikely to have decided what profit they want to report, or discussed adjustments with their auditors.
However, they did guide their house broker last week to increase the EPS forecast by 0.4p for this year and 1.1p for next year. Then today they announced "in-line" with market estimates. So it seems clear what the company's forecast EPS is, and it's a useful % increase this year and next.
Good point . Would have been nice if they had included that detail in the update .
Looks cheap but definitely not for me .
Morning all, I’m curious. As we come into earning season is there a quick way to sense check market beats vs estimates on Stockopedia or elsewhere? Thanks
End of year trading update from Ramsdens Holdings (LON:RFX) . They say the group expects to report annual profit before tax ahead of expectations but the update is lacking any meaningful financial information to be able to determine what this means. It goes on to say it will release the annual financial report in mid January. What they say appears good but the reporting seems a bit odd to me.