Small Cap Value Report (Mon 11 Dec 2023) - SNX, QTX, SCE

Good morning! It's just Paul here today, as Graham has a prior engagement.
Podcast - what with one thing and another, I didn't manage to muster any inspiration to record my weekly summary this weekend. We can't have a gap, so I'll record it late either today or tomorrow. Apologies for any inconvenience.
Mello Monday is from 17:00 tonight - with entertaining speakers, and terrific companies - I want to see 3 out of the 4 presentations.
Summaries
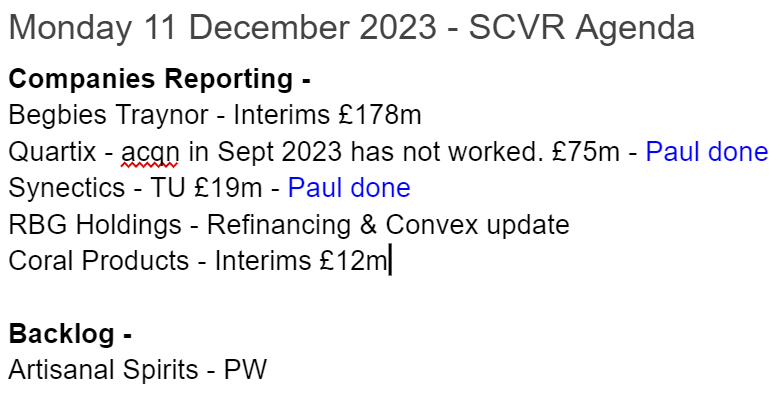
Synectics (LON:SNX) - 105p (pre-market) £19m - Trading Update (materially ahead) - Paul - GREEN
A positive trading update, and broker increases forecast EPS to 13.1p. Combined with a strong (net cash) balance sheet, reasonable divis, and a increased order book, this all looks attractive value to me. Not the most exciting company, but shares look cheap. So I think this looks a nice entry point. Stale bulls might sell into the liquidity, perhaps?
Quartix Technologies (LON:QTX) - Down 3% to 150p (£73m) - Konetik update - Paul - AMBER
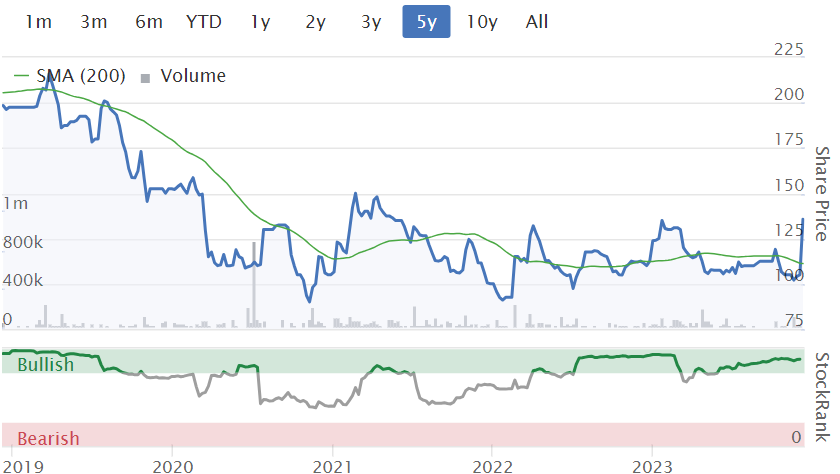
Founder Andy Walters is back in charge, and kicking ass! After a board room clear-out, today's update basically tells us that the acquisition made in Sept 2023 was no good. Are shares good value after a 9-year round trip back to where they started? No, not really, based on current forecasts, about 19x earnings (which have been in a downtrend since 2018). That said, I think a turnaround here looks possible, and you can't beat a founder, motivated with a 22% stake to sort out problems.
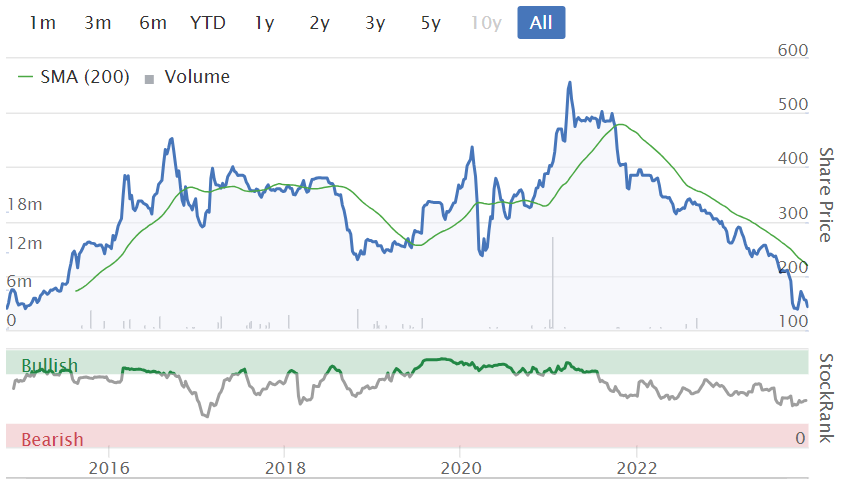
Surface Transforms (LON:SCE) - down 7% to 10.6p (£28m) - Result of Open Offer - Paul - AMBER/RED
The open offer has been well supported, with oversubscriptions meaning it raises £2.7m. This is conditional on the proposed £13m capex loan completing, which still hasn't yet happened. It's due "imminently" the company says. High risk, until the crucial loan is agreed.
Update: loan has been agreed, so the fundraising package should now go ahead.
Paul’s Section:
Synectics (LON:SNX)
105p (pre-market) £19m - Trading Update (materially ahead) - Paul - GREEN
Many thanks to gmtrader, who flags this materially ahead update in the reader comments below.
Synectics plc (AIM: SNX), a leader in advanced security and surveillance systems, provides an update on trading for the year ended 30 November 2023 ("FY 2023").
Good news here -
The Company expects results for FY 2023 to be materially ahead of market expectations, reflecting strong trading in the second half, particularly in the oil & gas market.
A resurgence in the oil & gas sector has been widely reported, as the Russian invasion of Ukraine refocuses the world on energy security, after a long period where environmental concerns had taken precedence, hence restricting new supplies that are now needed.
Outlook & order book - sounds good too -
Additionally, the Company ended FY 2023 with a strong order book, totalling £28.6 million (30 November 2022: £24.4 million) providing the Board with continued confidence for the year ending 30 November 2024.
The StockReport shows forecast revenues of c.£53m for FY 11/2024, so an order book of £28.6m at the start of the new year gives decent visibility.
Net cash - again, looks healthy -
Net cash at 30 November 2023 was £4.6 million (30 November 2022: £4.3 million) with undrawn bank facilities of £3.0 million.
Balance sheet - I’ve checked its last published accounts as at 31 May 2023, and confirm that SNX has a very healthy balance sheet, with NTAV of around £16m, including a robust working capital position. So it comfortably passes my balance sheet review, meaning shareholders shouldn’t have to worry about solvency or dilution.
Broker update - Shore Capital publishes an update today, many thanks for that. It increases adj PBT from £2.3m to £2.8m for FY 11/2023. This is 13.1p adj EPS (up from previous forecast of 10.9p). Shore leaves FY 11/2024 forecast unchanged, since it was already anticipating decent growth to 16.8p.
Paul’s opinion - at just 105p/share, this looks cheap to me. Synectics is not the most exciting company, and has been listed a long time. It has the occasional bull run (a large one, 6-bagging from 2008 to 2013), but then came all the way back down again. I’ve always seen the company as an also-ran in a large market, with little to differentiate it from the competition.
That said, it has strong finances, and pays reasonable divis. Not sure why the shares are listed, it doesn't seem to have done anything much with the listing.
Everything has its price, and this looks attractively cheap to me. Not something I’d want to hold forever though, but after a positive update today, and a share price at/near 20-year lows, I’d say risk:reward is probably as good as it’s likely to get, for maybe a 50% gain over the next year, would be my best guess, dependent on market conditions.
Quartix Technologies (LON:QTX)
Down 3% to 150p (£73m) - Konetik update - Paul - AMBER
This is an unusual announcement re the recent acquisition (15 Sep 20023) of Konetik. The founder, Andy Walters, returned to Quartix on 26 Sept, just after this acquisition was announced by former CEO Richard Lilwall. It’s now been decided that the acquisition was a dud (my interpretation), and attention is refocusing on the core business & strategy.
What’s the damage? £2.2m in cash was paid for Konetik, plus up to £1.2m in deferred payments linked to performance. Given that today we’re told performance has been weak at Konetik, then I’m assuming hopefully no further payments will be needed.
So the total damage is only about 3% of the market cap, not a disaster. It did use up most of the cash pile (£3.25m at 30 June 2023), but Quartix is a nicely cash generative business, so I’m sure this loss will be replenished. It does mean less in divis though, in the short term.
Paul’s opinion - I’m not too bothered about the failure of this recent acquisition, as it was fairly small. It’s better to take decisive action when a mistake is made, rather than drag it out.
The more interesting question is what happens to Quartix now that the founder is back in charge as Exec Chairman? He’s hit the ground running that’s for sure, with a sweep out of the board room. There was a profit warning on 6/10/2023. Refocusing strategy on the core activities seems very sensible.
Are Quartix shares cheap now, and worth revisiting?
They’re certainly cheap compared with the previous share price, but as we’ve consistently maintained here at the SCVRs in recent years, there was no convincing reason as to why QTX shares should be on a premium rating, because it hasn’t generated any earrings growth for years. So it’s been more a situation where an unjustified premium price has gradually come down to earth, the way I see things.
At 150p/share, the StockReport has a forward PER of 18.9x, hardly a bargain considering EPS has been in a downtrend since 2018.
What could make Quartix shares re-rate? Good news on the refocused strategy is what’s needed. Despite the lack of earnings growth, QTX still makes a very healthy PBT margin, and spews out cash, so it’s still a good business. It was making progress in France too, so if that opens the door to more international expansion, then maybe it could once again interest investors?
The trouble is, telematics is a crowded space, so to be more bullish on QTX I would need to do a lot more research, speak to people who use its products, etc.
In the meantime then, I’ll just have to sit on the fence with an AMBER view.
Note that there might possibly be an overhang, given that the 16% shareholder is a fund which apparently has been hit particularly hard with client redemptions.
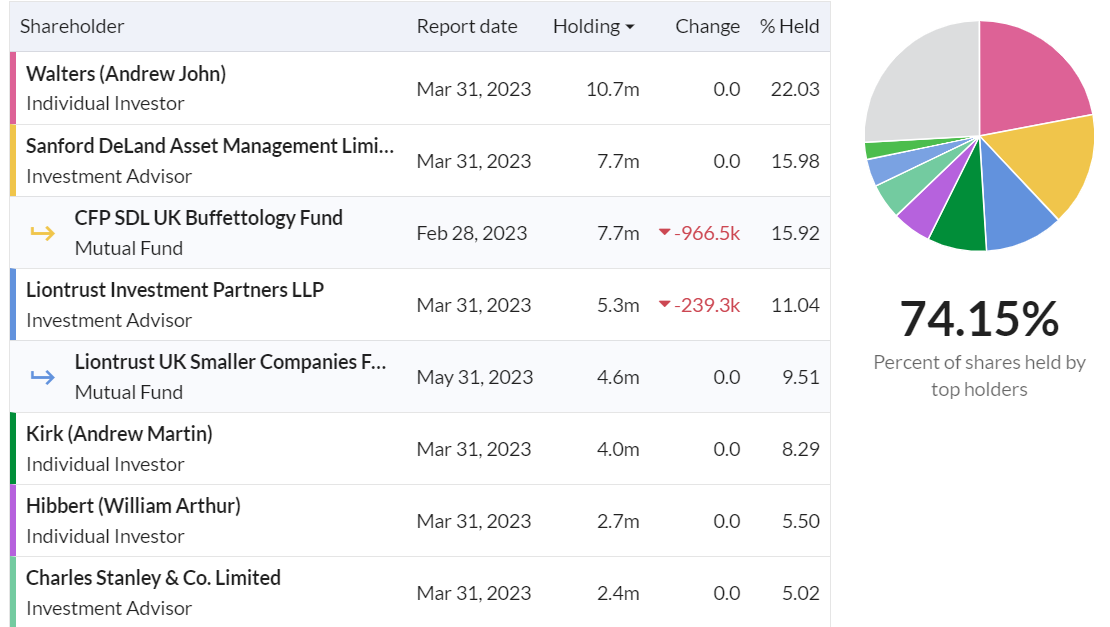
Shares have done a 9-year round trip to back where they started -
Surface Transforms (LON:SCE)
Down 7% to 10.6p (£28m) - Result of Open Offer - Paul - RED
Surface Transforms (AIM:SCE), manufacturers of carbon fibre reinforced ceramic automotive brake discs is pleased to announce that the Open Offer was significantly over-subscribed, raising gross proceeds of £2.7m.
Applications were received for 27,420,745 Open Offer Shares, representing a take-up of 137.1 per cent of the 20,000,000 available Open Offer Shares.
I went through the terms of the fundraising package here on 15/11/2023. It hinges on a £13m capex loan being agreed. Plus the formality of passing a vote at a GM. So I’ve looked for an update today on the £13m loan, all it says is -
…the £13.2m loan, described during the fund raising and still expected to conclude imminently…
We need more details on who is providing this loan, what the terms are, etc.? Without that information, I feel we’re too much in the dark to make this share investable. So for that reason, I’d rather wait until the loan deal is signed, and the money is in the bank.
Maybe the proposed lender is a connected party? I’d be surprised if SCE could borrow for capex from conventional lenders.
Anyway, fingers crossed the loan is agreed, as that would trigger release of the cash from the conditional placing and open offer. Good luck to holders.
Update: Conclusion of Loan Agreement
My wish has been granted! A further RNS came out at 11:34 saying -
Surface Transforms plc (AIM:SCE) manufacturer of carbon fibre reinforced ceramic automotive brake discs is pleased to announce that it has signed a £13.2m loan agreement with the Liverpool City Region Urban Development Fund which is part funded by the European Regional Development Fund (ERDF). The loan will contribute to the Company's forthcoming £44m investment programme.
The investment is supporting capital expenditure that will see the production capacity available in the Knowsley site rise from £50m sales capacity per year in 2024 to £150m sales capacity per year in 2027. The capacity increase is required to support the forecast substantial sales increase underpinned by the Company's current £390m* lifetime contract value and £300m prospective contract pipeline. The remainder of the £44m capital investment programme will be funded from free cash flow as the Company moves into profit, still expected during 2024.
Paul’s updated view - I think you would need to be a tremendous optimist to imagine that this is the last fundraise! However, assuming everything now completes, this buys management some time to see if they can fix production problems, and scale up. It certainly has not been anything near plain sailing so far. This share is a useful reminder that it’s all very well small companies winning large orders, but unless they’re outsourcing production, then scaling up manufacturing of complicated, cutting edge products, is not something we can just assume will be achieved. Things always take longer, and cost more than planned.
Should we shift from red to amber? I think we should move up a bit yes - because the main problem (running out of money) has been resolved, at least for the time being.
It’s got a huge order book, so there is clearly plenty of demand for the products, which I like.
SCE shares are still speculative of course, and it will probably need another fundraise. Also, its production problems could continue as it tries to scale up production.
So on balance I’ll go with AMBER/RED - ie still speculative and higher risk, but out of intensive care.
The share count will shortly go up from 241.7m, with 82.9m new placing shares, and 27.4m new open offer shares, new total = 352m. Shares have bounced to 12.5p in a relief rally, taking the market cap up to £44m at the time of writing.
The Stockopedia data gets updated when the new shares are formally issued, which is something to bear in mind over the next few weeks, as the old number will be shown until that point.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

95 comments
Begbies Traynor (LON:BEG) H124 analyst presentation including Q&A from this morning video & podcast. Revenue +13% to £65.9m operating margin 16.2%, aPTP +10% aEPS +4%. Interim dividend +8%. Cash £1.1m (£3m at FY23 reduction due to acquisitions). Confident of FY24 in line with expectations. Q3 trading update to be issued in February 2024.
No surprises here with Begbies Traynor (LON:BEG) as they'd signposted the results with a recent trading update.
The key investment decision here is whether their acquisitions just bring in revenue in the short-term, or they are a sustainable addition.
As they structure them with huge deferred consideration and earn-out payments. You can see this by the huge adjustments they make to PBT, EPS.
The underlying business as a whole, is highly profitable and cash generative. But if much of this value is sent out to third parties via earn-outs and deferred consideration, not much is left for Begbies shareholders!
Obviously, those external payments have a finite timetable, and so the hope is that once they drop out, then the Adjusted Earnings become the Statutory Earnings. However, with any "people" type businesses - there's always a risk of churn of employees, clients, projects, reputation, networks, etc.
I still think the core business is a nicely profitable and cash generative, and that their acquisition strategy is still sound, that their track record is good. But with the continued acquisitions it seems very much like a "jam tomorrow" business, perpetually.
It is a very good counter-cyclical play, as well as on the rising macro trend of more insolvencies and administrations (Jan is likely to be a massacre of retail and hospitality businesses, isn't it?)
Not a 10/10 bull on this, but still moderately positive on this holding. Not in a rush to sell or buy more at this time, will mull it over and digest the results in detail at a later time.
(I hold in the Boon Fund)
Bioventix (LON:BVXP) has been moving up recently on no news, any ideas, broker upgrades or share tips?
Future (LON:FUTR) sell off continues. 12mth rolling p/e now 4.4 and peg 0.2
Slater Investments just notified an interest of a bit over 5%.
Future (LON:FUTR) Is there something lurking behind the scenes?
Future (LON:FUTR) I think it's just a lot of panic selling after the recent broker downgrades. The US business obviously struggling, but the UK business and GoCompare doing fine and these parts by themselves worth significantly more than current market cap.
Future (LON:FUTR) (I hold)
Absolutely agree with the part on GoCo.
That business alone should be worth a fair chunk of Future's current £1b EV.
I estimate c.£640m, based on an estimated Net Profit of £32m and a x20 Net Profit multiple.
---
This implies the B2C and B2B business are only worth £360m, which doesn't make sense when the operating profit here looks like it is close to £200m.
I'm going to do some more work on the non-GoCo businesses so see if I'm missing something obvious as I don't understand the low valuation at all, even with the risks inherent within the areas that the company operates in.
A
Thanks would be interested to see your findings when you get round to it. I'd probably be a bit more prudent and value GoCo on a 14-15x multiple, which would cover around half the EV (and leave the rest of the business trading on an implied multiple of less than 3)
Future (LON:FUTR) (I hold)
Hi Bouden54
Sorry, I completely missed your comment.
I probably haven't researched the company enough yet, but I may as well share some thoughts whilst I'm here.
GoCo Multiple
You're right, a x15 PAT multiple for GoCo makes a lot of sense and wouldn't be unreasonable.
I actually used a range of x17 to x22, with the latter figure being the multiple that GoCo was acquired for a few years ago.
In the end I settled on x20 for ease and to make my point.
In any case, whether it's x15 or x20, GoCo - I would hope - is currently valued somewhere between 50% and 66% of Future's EV.
And then as you say, the rest of the business can't seriously be valued so cheaply, unless there's a good reason for it, such as a risk to its profits.
My thought process below:
---
Organic Traffic i.e. getting users in without paying for them
It was interesting seeing the below from the Capital Markets Day last year:
There doesn't seem to much paid advertising driving traffic to Future's websites, which gives me a degree of confidence that they will continue to reap the benefits of their naturally strong SEO.
I'm a big believer that large, well-known brands - like Moneysupermarket.Com (LON:MONY) -will continue to rank near the top of search results for their respective niches.
Advertising Revenues - getting paid for having so many users on their websites
There might be a risk targeting users with relevant digital ads, with Google set to follow Apple's privacy strategy and block 3rd party cookies.
Digital Ads are a chunky part of Future's revenues so I can understand why there might be caution, but I can't help but think that the larger niche websites will be more immune given:
Affiliate Income - getting paid by users buying something
Again, I don't see much risk here. There will always be users looking for the "best 40" TV" or the "best budget phone" and with that comes affiliate income.
---
So that leaves the macro risk...but I feel we're already in the middle of that.
I'm therefore left scratching my head at what else I might be missing. Are there other risks? Probably, there usually are! But certainly nothing obvious that comes to mind.
I'd be interested in hearing of any bear case I might not have thought of from anyone reading this.
Thanks
Thanks for that, very useful analysis. I'm with you, While the company has some issues to sort out, I don't see any major risks that would justify such a low rating - probably just a case of markets getting carried away on the downside when fear takes over.
I’ve subscribed to SCSW for around 20 years. It used to be very good but performance and the quality of their more recent tips has often been dire. Commentary tends to focus far more on the story and history than important financials.
I still subscribe because occasionally a tip really does appeal. E.g Good Energy (LON:GOOD) after their October tip this year was my first SCSW buy this year. It’s paid off already and with part profits taken.
Yes, The performance of their current and their 2 previous portfolios IS spectacular. BUT BUT a lot of subscribers don’t seem to have cottoned on to the fact that they can and do hindsight buy AND sometimes they buy a tip ahead of tipping it and sometimes over hyping it. E.g their first tip for Altitude (LON:ALT) was ahead of a big bullish plug that saw the share almost double before investors could buy it. And they are free to choose an optimum moment in any month to tell us in their next edition the price at which a portfolio holding was bought, sold or top sliced. If only we could all invest that way!
And more recent tips and portfolio buys have been very poor overall AND it’s interesting and well worth readers of this post checking this out here, there’s sometimes a big difference between their very bullish comment on a share in their portfolio and Paul Scott’s much more balanced analysis here.
e.g THG (LON:THG) (admittedly up to 85p from the 60p when it was bought for their portfolio in June). THG was a red for Paul and he commented “I wouldn’t go near this share at almost any price.”. OK so far the share price is higher but that’s because of regular bid rumours and an apparent bid once that came to nowt at 170p. It’s a very high risk gamble and I hold a few as a fun punt just in case there is a bid or other corporate action,
e.g Frontier Developments (LON:FDEV) bought for the SCSW portfolio in June at 510p and now just 120p. Paul gave it an AMBER that June. Graham has recently gone for green BUT that was after the share price had crashed.
e.g Musicmagpie (LON:MMAG) bought for their portfolio Dec 2022 at 24.5p and now just 11p. Paul Scott was negative in Dec22 at the time of that buy and had described Musicmagpie (LON:MMAG) as “uninvestable” earlier.
e.g Dr Martens (LON:DOCS) added to their portfolio at 152p in August this year and now just 93p. Paul had it as Amber/Red in November.
e.g McBride (LON:MCB) this month. Paul recently updated with AMBER rating.
I think Paul’s and Graham’s analysis here is way superior to most of the coverage in SCSW, but it’s the occasional very good one like Good Energy (LON:GOOD) that keeps me subscribing.
There are some spivvy tips in there for sure. They seem to concentrate on speculative growth stuff that has had a very tough 2 years. I'm thinking with interest rates rolling over their time (and outperformance) may come again.
THG there is no doubt in my mind that if they announce a break up this will perform very well. MM has refused so far though, continuing to ignore everyone. Have you noticed MM has bought some Kelso that is a fund pushing for THG to break up?! A bit weird.
To be fair, almost everyone in UK small caps has had a tough time since the market peak in mid-2021. We'll all be heroes when the market recovers!
That’s true Paul, and many good quality small cap shares have had a tough time, but I was pointing out that too many of the SCSW tips over the last couple of years were not good quality. There was (as explained with a few examples in my post) far better analysis on them from you than there was from SCSW. There were others in their portfolio that have done badly that you were wary about while SCSW was anything but!
Thanks ken, my cheque is in the post ;-)
Supreme (LON:SUP) I think was another tip that halved in price. I don't subscribe.
But did they not tip Yu (LON:YU.) ?
Yes Rusty2, SCSW did tip Yu (LON:YU.) and it’s one of their very successful tips. That’s why I still subscribe. They do also find some good ones.
The first thing I do with SCSW tips is to look at the Stockopedia stock page for that share, and then on to any comment on it here from Paul and Graham and other informed posters. It’s then, IF it looks worth checking out properly, that I move on to Company announcements and Results. As well as the figures I always look for hints in the commentary of possible problems ahead, and also for hints of a future “above expectations” update.
This month’s main tipMcBride (LON:MCB) fell at the first hurdle including just an Amber rating from Paul. And just reading their write up and seeing that they supplied supermarkets like Tesco was a put off anyway as the likes of Tesco can be ruthless with smaller suppliers. McBride (LON:MCB) might prove to be a successful tip but with so many quality small cap bargain shares available we can afford to be choosy.
Chapel Down (OFEX:CDGP)
Anyone had any experience of a stock moving from Aquis to AIM ?
Chapel Down moved late last week and is up around 15% in a few days. Since the move the liquidity is good, spread is reduced(currently less than 1%) and momentum is obviously good, I have a reasonable holding in this, around 4% of my porfolio, and would like to add but I feel i'm in unchartered waters. Any help welcome.
Helvellyn, I sold a third of of my holding in Chapel Down (OFEX:CDGP) after in moved to AIM. I had made a decent return since I bought in the early summer and whilst I feel confident long term I cannot see any major upside from current levels. I could well be wrong of course.
Re Chapel Down : I think Christmas period sales performance (shops, online and in bars/restaurants) will give us an insight as to how the marketing push is going.
As an owner of 2000 or more shares (approx £1000 at today's shareprice), I get 33% off their wine and have bought quite a few gift-boxed bottles in the last few weeks to give as presents, as well as a few bottles to drink over Christmas.
mjfgs.
Chapel Down (OFEX:CDGP)
There will probably be a FY trading update in the second half of January. Their PR machine has been working overtime this year, and IMO are producing some great stuff(I'm probably looking through rose tinted TBH, pun intended ;-)) ) From what i can gather sales wise my local Sainsburys doubled the shelf space for the 2 Sparkling wines in the autumn, due to increased demand so the manager tells me . Marks and Spencer (LON:MKS) keep running out of stock of one of the varieties which i'm not sure what to make of . Excess demand or poor stock control or poor supply chain, hopefully the former as Sainsbury TTBOMK never run out.
A good part of the Chapel Down (OFEX:CDGP) story is that having acquired over 1000 acres for growing the vines their current saleable wines are from just 750 acres, as it takes about three years to get wine from new planting. Part of building their size is to ensure that they can always supply from inventory, as it is notoriously hard to win back buyers if you have once had been unable to supply (as they almost had to in the poor weather years around 2013). Recent harvests have been spectacular - this years, a record, was especially large - so they are now able to expand their marketing with the confidence of supply. Since I enjoy several of their sparkling wines the shareholder discount makes the interim value of the shares a no-brained.
Stockopedia still thinks Chapel Down (OFEX:CDGP) are trading on Aquis! Not sure how long the platform will take to catch up/
Anyone buying Surface Transforms (LON:SCE) as they have just had the £13m loan approved? Long term possible they could (finally) do very well.
I am :)
Possibly because i've not been burned before on this one! But it's a classic one for me where I could be in the future if management continue to disappoint.
On paper this could be a multi-bagger - 60%+ gross margins on a £390m estimated order book and £300m more potential (key word here though is management estimates!! They believe this is what their order book is worth but it's not guaranteed). £100m-ish annual sales capacity. Would even a £1/share ultimate target be achievable I wonder? Certainly feels like risk/reward has tipped in the right balance but very "jam tomorrow"
Good Energy (LON:GOOD) I hold.
I note Small Company Share Watch have recommended taking part profits in Good Energy after a 138% gain since their feature on the company two months earlier. That is probably the reason for the 12% retrace this morning.
For traders that seems a sensible course of action but I will continue to hold a full unit - the medium term opportunity looks superb and the company has more than enough cash to fully exploit it.
I am surprised that the actions of subscribers of SCVR can shift the price by these amounts: Good Energy down over 10% and McBride up 15%. Surely the markets can’t be influenced by a niche monthly publication. Or can they?
Its not usually the actual buying or selling which moves the price - its the market makers who are aware of the tip/advice and move their prices accordingly
McBride (LON:MCB) was up 7% at opening on my platform, then buyers pushed up to +20%. Yes the market makers do mark tips up but then it's the market. Some fall back from the opening price.
Important to distinguish between SCSW and SCVR!
The discussion thread was about SCSW, a monthly publication. Last time I checked SCVR is a daily blog.
That's why I flagged it, as there seemed some confusion. Anyway, you sound like you know best.
Not at all Paul but you are addressing your comments to the wrong person. It was Monty9 :
I note Small Company Share Watch have recommended taking part profits in Good Energy after a 138% gain since their feature on the company two months earlier. That is probably the reason for the 12% retrace this morning.
Hi SC120,
My comments were addressing your post, which looks like it was a typo, that was all -

SCI20Joined 2019168 posts2:38 pmI am surprised that the actions of subscribers of SCVR can shift the price by these amounts: Good Energy down over 10% and McBride up 15%. Surely the markets can’t be influenced by a niche monthly publication. Or can they?
1ReplySC120.
Do you realise that this IS the daily SCVR “ blog” you seem a bit confused about? Have a look at the heading ahead of Paul and Graham’s analysis here; it’s “SMALL CAP VALUE REPORT (SCVR) MONDAY DECEMBER 11th 2023.”
Yes Ken I’m not yet at that stage where I forget where I am
I'm tempted to reply with a bit of banter, but won't! ;-)
You should have done. Always appreciate banter :)
It was Monty9 that created the original post re Sharewatch.
You wrote "I am surprised that the actions of subscribers of SCVR can shift the price by these amounts: Good Energy down over 10% and McBride up 15%"
Rusty2 thanks for picking this up. It was a typo on my behalf. It should have read SCSW! Apologies to all.
Glad we got that sorted! Ignore my reply a moment ago.
Peace and joy, and jingle bells are restored to all :-D
Cheers
Cornerstone FS (LON:CSFS)
Paul Scott mentioned this on the 4th December and after extensive research I believe it will be a multi bagger.
This was listed in 2021 at 61p and a market cap of £12.5m. Since it’s listing it has made numerous acquisitions and team hires hat helped improve its gross margin from 30% to 60%.
What the market is missing here is that all research available for future earnings are completely wrong and way too conservative (perhaps it is the new management tactics).
Shore Capital’s 2024 revenues are for 11.3m climbing to £16.5m by 2026.
BUT the last 3 years they have been growing by the 100% pa and as 2023 is expected to be about £9m these numbers are completely wrong. Also in 2026 PAT is expected to be £3.5m which is about 1/3 of the current market cap. I believe this figure can be achieved by 2024.
DYOR
Cornerstone FS (LON:CSFS) need to be a bit careful here as it has gone up considerably on the back of being mentioned by Vox Markets and also Paul Scott. Not much volume required to move it 20%.
The reality of the current upgrades though is that revenue per client has gone up considerably and room for growth in that metric is now more limited. The customer numbers can absolutely increase.
Nonetheless at todays price it is trading on next year forecast numbers of 15* And currently the market is not paying that kind of multiple for payment service providers so I think a chunk of growth above broker forecasts is now already in the price.
Over the medium term I agree it has good potential to be a multi bagger. I missed buying at 15p and I’m not going to chase at 22p until some of the froth comes out. It’s doubled in less than a month but is now in the territory of people buying on FOMO so I will wait. Maybe it will continue to rise persistently but a good chance it pulls back for a better entry imo.
As I said broker estimates are wrong-they are meant to generate revenues of about £6m in H2 2023and they are growing by the minute-their 2024 revenues of £11.5m according to Shore Capital will be easily beaten and with an improved operating margin (12%) this will be cheap even at 40p.
New CEO worked for Equals (LON:EQLS) for many years.
I tend to look (as you do!) forward 2-3 years-this might go back to 18-20p as you rightly say but I have no doubt it will be a multi bagger from current levels and a winner for 2024.
I don’t fundamentally disagree medium term but I think that whilst broker forecasts are ‘conservative’ they won’t smash by quite as much as the extrapolated trading update might suggest. Most payment services businesses are trading at not much more than 10 PER (which I do think is the wrong multiple btw) but nonetheless that doesn’t make Cornerstone FS (LON:CSFS) look tremendously cheap at current prices.
I’m watching - I think ultimately it could prove a big winner but a bit of froth in it at the moment as a couple of commentators have cottoned on so I’m looking for a pullback first but who knows whether I will get it.
I am talking about 2024 earnings estimates-H2 2023 looks like it will be about £6m; so this will automatically make 2024 about £12m with NO growth-BUT the company grows about 100% pa-Shore Capital have them for earnings of £11.3m for 2024!
They are generating free cash flows now and on an operating margin of about 15% and assume a very conservative growth of 50% (£18m revenues) this should be trading at about £30m market cap. I think it is very cheap but it is just my personal opinion.
I believe they will be re rating in the next financial year and in every trading update!
Thanks
I don't want to be associated with any of the over the top comments on Cornerstone FS (LON:CSFS) (I hold)
We merely spotted an ahead of exps update here, and you can do with that what you will. (I bought a few, it's not a crime. No intention to sell, we'll see what happens in 2024)
Worth a follow up for you bottom fishers-DGI Innovate - three Ex Tesla senior executives have take a 40% holding in the company ( I hold)
Interesting-I will appreciate if you have anything more to share with the community about DG Innovate (LON:DGI) and its products and/or future prospects.
Thanks
what is wrong with H&T today 6%down no news?
Shore's broker note today cut 24 & 25 EPS, as well as divi expectations
Yet again in a quandary whether to sell or continue to hold H & T (LON:HAT). Holding is in profit at about +75% so 'bird in the hand' etc and has hit my notional stop less for a Stockopedia rated balanced stock (15% from recent high). However, I have got it wrong with so many shares that have had a set back - held only to see further collapse, sold only to see a bounce back. Could H & T (LON:HAT) be one of Ed's multi baggers or will it continue to sink?
I'm a big fan of H & T (LON:HAT) but really don't think this is the sort of thing that could multi bag - would expect it to remain weak for time being but still good value on long term view
H & T (LON:HAT) Shore Capital have reduced earnings forecast by around 10% over next couple of years on higher costs (mainly due to the higher living wage). Still looks very cheap even after this adjustment.
I'd imagine this could hit quite a few other companies which rely on low paid staff (retailers, hospitality, etc) so might be worth keeping this in mind for potential earnings downgrades.
RBG
I used to detest this company due its its dick Turpin shareholder theft tactic of management issuing itself literally millions of free shares .
Rotten to the core that crowd of self serving white collar criminals masquerading as lawyers .
But just wonder if change is afoot .
Just noticed returning founder now chairman has actually recently parted with sone of his own pennies and bought shares like the rest of us have fo .
Seems to be a strong turnaround plan in place and two new major shareholders one who looks a potential acquirer .
I did used to hold many moons ago but lucky chucked my toys out the cot after the free shares handed out in the smash and grab robbery .
Might take a closer look looks a rebound trade which I generally don’t get involved with .
RBG Holdings (LON:RBGP) I was interested in your thoughts planetx. I have a small holding. The debt refi announced this morning was a positive, but the facility headroom seems to be very small £24.5m v debt of £22.6m at 8.12.23. You also have the overhang of ex CEO Nicola Foulston with 12% of the shares.
The Chairman’s recent shares purchase was minor but more relevantly, on rejoining the Board the Company agreed to pay him a total of £2.5 million in monthly instalments over a five-year period of restrictive covenant payments.
There are not insignificant risks with RBG and my personal preference would be Knights group (LON:KGH) , which is a larger more diverse growing legal practice which had a positive recent TU, but is equally cheap and has a much more manageable debt load.
Or you could avoid all debt (which is now significant with interest payments being so high) and in fact take the net cash position which you'll find with Keystone Law (LON:KEYS) where you'd get net cash at £11.3m & sig high ROE & ROCE over the last 5 years. A platform business and an early mover in this space. Revenue has grown at a 5yr CAGR of 22% with high profit margins. FCF conversion has been +97% over the previous five years. The CEO James Knight has plenty of skin in the game with a 28% stake.
Still reasonably priced considering how high the PE has been historically. There's no reason to think we can't carry on with a positive outlook stated in the interims in September of comfortably meeting market expectations and market conditions being in the groups favour with activity levels remaining strong. Talking my book of course.
@mginvestor on X
To be honest I wouidnt want to get too committed to RBG and I see it more as a rebound trade .
Not sure why I am even looking at it as I try to avoid, and am really bad at short term trades .
Really need a good poke in the eye for looking at this .
A lot of stocks bouncing up now from oversolds with quick gains as sone liquidity returns so bit of FOMO maybe .
Should know better really as it’s a dog shit company really with a proven track record of screwing over its shareholders
Need to give myself a good talking fo .
Thanks for the report Paul on Synectics (LON:SNX) The market certainly seems to think it is cheap as it is up 23% on open. Does the broker notes give a target price?
Eurocell (LON:ECEL) just moved into a top 90 Superstock. It's been a bit unloved of late, surprising to see.
Quite like ECEL and took a starter last week - "Bowl" on the (3 year) chart, new CEO, director buying (but they've been buying all the way down), decent yield, StockRank great & potential for that EPS to be wrong if mgns get back anywhere near normal (pre-COVID) - Plus, SFE and other smaller companies in the arena no longer around
I love it! It’s day will come.
Eurocell (LON:ECEL) along with Headlam (LON:HEAD) are my two preferred cyclical plays, they have the balance sheets to ride out the storm i believe and both have started to move off their multi year lows. With both, I believe it is a question of when not 'if' so patience required but nice dividends in the interim. Good luck fellow holders.
Eurocell (LON:ECEL)
It's been a bit unloved of late, surprising to see.
Its not alone - i hold Epwin £EPWN which is very similar sized/type entity in most respects and i think thats even more unloved than Eurocell based on the stocky genrated p/e figures. (Eurocell has i think historically had higher profits than Epwin so perhaps may have more bouncebackability with regard to profits going back to prior highs ?) and both epwin and eurocell are on racy ratings compared to Norcros (LON:NXR) another sector similar company. A very much unloved sector at present.
Hmmmm would epwin and eurocell be a nice to merge as equals and leverage cross selling and other efficiencies .
Good morning all.
TU from Synectics (LON:SNX) , brief but positive.
“The Company expects results for FY 2023 to be materially ahead of market
expectations, reflecting strong trading in the second half, particularly in
the oil & gas market.
Additionally, the Company ended FY 2023 with a strong order book, totalling
£28.6 million (30 November 2022: £24.4 million) providing the Board with
continued confidence for the year ending 30 November 2024. Net cash at 30
November 2023 was £4.6 million (30 November 2022: £4.3 million) with undrawn
bank facilities of £3.0 million.”