Small Cap Value Report (Mon 11 Mar 2024) - HEAD, LIKE, SRAD, ITV, ELM, RWA, RFX, MWE, TST, HERC, VANQ, SPA, NANO, LOOP

Good morning from Paul & Graham!
Today's report is now finished. As it's a big report today, to jump to any company section, just press CTRL+F and the ticker.
The Week Ahead - editorial & reader comments on larger caps, is up here - click here to read it.
Mello Monday is tonight at 17:00 - highlights include fund manager Chris Boxall, whose insights are always fascinating and enjoyable. Chris is a walking encyclopedia on small to mid caps, and isn't known for holding back his opinions on the things that matter! Highly recommended. I'm also looking forward to hearing from Galliford Try Holdings (LON:GFRD) which I wanted to cover last week, but it slipped through the net, so this might save me a job. GFRD's StockReport shows forecast earnings in an uptrend, and a 5.4% dividend yield, so a nice once for value investors.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Paul's 2023 share ideas, with live prices.
New SCVR summary spreadsheet from July 2023 to date, updated at weekends (very useful quick reference tool, search for ticker using CTRL+F). Hover over cell for pop-up notes.
Frozen SCVR summary spreadsheet for calendar 2023.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
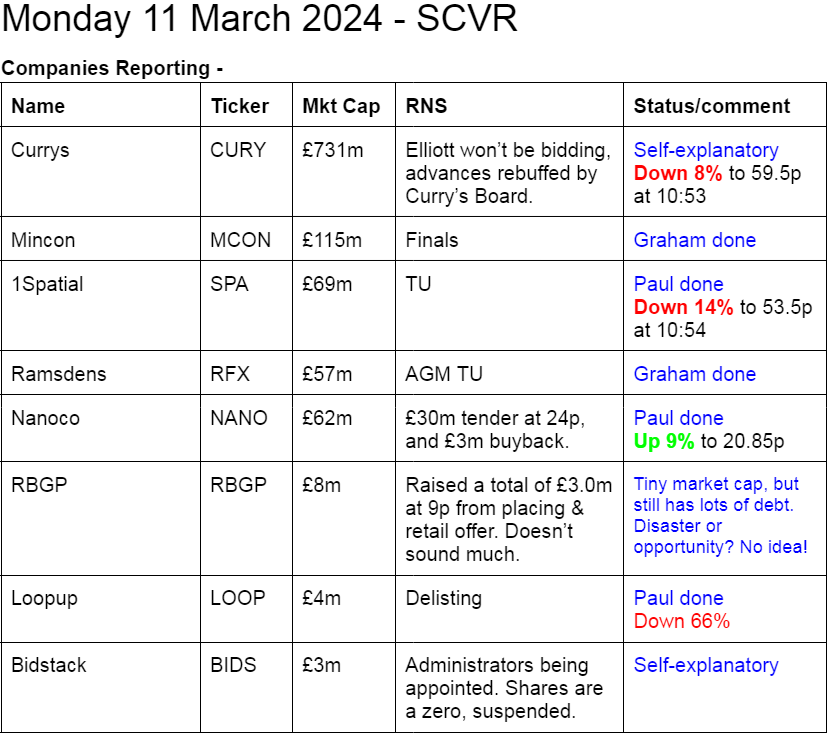
Companies Reporting
Our list should be up here just before 8am, then updated throughout the morning - please remember we can't usually cover everything! -
Other mid-morning movers (with news) -
MTI Wireless Edge (LON:MWE) - up 12% to 41p (£36m) on 2023 Results, and a (fairly small) extension of the share buybacks.
Additional info since posting the above:
FY 12/2023: Revs $45.6m, down 1.5% (up 2% CC). PBT up 12% to $4.8m. Net cash flat at $8.1m. Share buyback up from $200k to $700k, nearly 2% of the market cap. Strikingly high forecast dividend yield of 7.7%. Outlook: 2024 started well (in line). Increased pipelines in all 3 divisions. 2024: “another year of growth and increased returns for our shareholders”. Says benefiting from higher defence spending by clients. Paul’s view - a strange little group, but it’s been listed a long time, and has a good track record of paying generous divis, with a modest PER and sound balance sheet. Might be worth a closer look, if you’re prepared to invest in a micro cap based overseas. 2 dominant shareholders own 41% combined. Not sure why it’s listed anywhere, let alone in London?
Touchstar (LON:TST) - up 6% to 100p (£8m) on FY 12/2023 Trading Update - revs & profits “broadly in line”. But EPS will benefit from lower tax charge and lower share count from buybacks. “Confident” outlook for 2024, saying revenue & profits should go up. £3m net cash. Quite an interesting little company, I’ve followed it for years, but seems to be struggling to scale up significantly. Is it worth the listing costs? Could probably double profits if it went private.
Hercules Site Services (LON:HERC) - Up 9% to 32.5p on AGM Statement released at 09:22 - daft, as they should be pre-announced at 07:00, so everyone can react before the market opens at 08:00, instead of having to rush to interpret it whilst the shares are in live trading.
Vanquis Banking (LON:VANQ) - down 36% to 80p (£204m) - BLACK (2024 profit warning) - used to be called Provident Financial, it’s a sub-prime lender. In the FTSE 100 previously - today hitting a 34-year low! Graham reviewed it in Jan 2023 here. Disastrous share price performance. Trading update today is taken as a profit warning. FY 12/2023 results expected to be £25m adj PBT, same as 1/2/2024 TU. But FY 12/2024 now expecting profit “materially lower than market consensus expectations” (of £75m adj PBT). NOT involved in FCA review of motor finance commissions. But has received “significant levels of 3rd party complaint submissions”, so seems to be in the crosshairs for ambulance-chasing lawyers maybe? “Vast majority” of complaints rejected, but costs of dealing with them “likely to materially impact the Group’s profitability in 2024”. It’s now saying substantially below -
“Allowing for the factors described above, the Group expects to deliver adjusted PBT for 2024 which will be substantially lower than market consensus, resulting in a low single digit adjusted ROTE. “
Divis - 1p for 2023, and 1p planned for 2024. So that’s the 7% yield out the window.
Paul’s view - looks a mess, for special situation investors only I’d say.
Nanoco (LON:NANO) - up 8% to 20.7p (£67m) - Proposed Shareholder Return - Paul - AMBER
This is such an usual situation - a tiny tech company that ended up in litigation with Samsung, and won! This had been rumbling on for years, and you can see from the chart that this share became a gambling chip in 2022 on the amount of the award to NANO, which ended up disappointing.
NANO has now received £58.8m after costs. It’s returning £30m to shareholders in a tender offer at 24p, for up to 38.5% of the issued shares. Individual shareholders can opt to tender none, some, or all of their shares. I’d guess that uptake is likely to be very strong, particularly from institutions, as a liquidity event. There’s also going to be a £3m buyback.
It expects to have £23m net cash after the tender offer to “support” the remaining business, which sounds like more cash burn to me, this company's speciality!
There are 324.4m shares in issue, so if the full 38.5% are tendered (likely, in my opinion), then that will reduce to 199.5m shares outstanding. The buyback might retire another 14.4m shares (£3m at 20.8p current share price), giving a final reduced share count of c.185m. That implies a future, reduced market cap of c.£38m (at current 20.8p/share), for a group with net cash of £23m. That looks potentially interesting, but it depends how fast, and on what, the cash pile is going to be spent on?
Winning a large legal case against Samsung seems to be telling us this technology has value.
Could this be a cheap entry point into proven tech? Or, is this going to be another false dawn from a serial jam tomorrow cash burner? I have no idea, you decide! Could be a fun punt maybe, but needs a lot more careful research.
Loopup (LON:LOOP) - down 68% to 0.65p (£1.3m) - Trading Update & Delisting - Paul - GREY (delisting)
Not a surprise to SCVR readers, as we’ve been warning about the need to raise more cash for over 2 years, with increasing stridency - eg SCVRs -
- 15/2/2022 - needs another fundraising.
- 29/9/2022 - 5p placing done, not enough, needs more cash. Very high risk.
- 14/12/2022 - Uninvestable, could easily be a wipeout.
- 14/9/2023 - another fundraise (or delisting) practically certain, so best avoided. RED.
Today’s update is quite interesting, these are always worth reading when a company de-lists. It says being listed is not helpful for raising more money (hardly surprising, as they’ve repeatedly tapped investors for cash, and squandered it on a considerable scale, so we can all see how lousy the company & its management have been!)
Stripping out the substantial costs of a listing, and raising money privately, makes complete sense to me.
Trading - there’s good revenue growth in % terms, but the core business is admitted to still be at an early stage, £2.8m revenues in 2023 (and hefty losses).
Bank of Ireland are owed £6.0m (it wants half back funded from the proposed £9m equity fundraise), due Sept 2024, discussions being held to extend facilities include a requirement to delist and raise fresh funds after delisting. That’s an interesting point, that banks may encourage problem companies to delist.
LOOP intends to raise £9m privately, so dilution coming for existing shareholders, although interestingly it says fresh equity will be raised at 1.75p per share, “irrespective of any share price movement in the interim” (shares are currently 0.65p in the market). However, scrap that, as there’s a sting in the tail! -
… although the Directors may adjust this price depending on the investment offers which are presented to the Group as part of the proposed fundraising. There is no guarantee that the proposed fundraising will be concluded on the terms indicated, or at all.
It says raising £9m would not be possible on AIM. Too right! 4 private investors have indicated a total of £6.2m funding, again subject to delisting and refinancing the bank debt. So it looks as if LOOP could survive as a private company. Further funding would then be sought from private equity or venture capital - good, that’s the correct way to fund early stage, cash burning companies, not flogging shares to gullible punters on AIM.
Delisting requires a 75% shareholder vote, which should be a formality since a no vote would mean insolvency I imagine.
Anyway, that's almost certainly the end of LoopUp as a listed company.
Summaries of main sections
Ramsdens Holdings (LON:RFX) - up 7% to 192.5p (£59m) - AGM Trading Update - Graham - GREEN
We have an “in line” update from Ramsdens. There’s a standout performance from gold purchasing (gross profits up 20% YoY) and forex is doing well in advance of the key summer period. I remain a fan of RFX which appears unduly cheap at a current PER of about 8x.
Mincon (LON:MCON) - down 2% to 53p (£103m) - Final Results - Graham - AMBER
This Irish engineering group reports decent EBITDA (€21m) vs lowered expectations. I continue to like many aspects of Mincon but can’t take a positive stance until outstanding problems are resolved: the “Greenhammer” project, net debt and weak industry demand.
1Spatial (LON:SPA) - down 11% to 55p (£61m) - Trading Update - Paul - AMBER/GREEN
Bit of a muddled update today, which the market doesn't like. I run through the detail below, and am (just about!) keeping a moderately positive view, as I think this is an interesting company, in a potentially lucrative space. Even though the numbers don't particularly impress at this stage.
Paul’s Section:
Firstly, some shorter sections that I did over the weekend for backlog items -
Headlam (LON:HEAD)
193p (£156m) - FY 12/2023 Results - Paul - AMBER
(carpet & other floorcoverings distributor, UK market leader)
Quick review - 2023 results were poor. Revs down 1% to £657m, but underlying PBT down 70% to £11.0m (statutory PBT £7.1m, so adjs aren't huge). U/L EPS 11.0p (2022: 35.5p). Divi 10p (2022: 17.4p) - divis look unaffordable to me, given poor cashflow & quite heavy capex, resulting in a big rise in net debt. Bal Sht overall is good though, due to big freehold property, £200m NTAV is well above mkt cap of £151m.
Weak demand in 2024 so far. Expect medium term recovery. OK going concern statement.
Paul's view - disappointing. I'm wondering again whether poor performance is all cyclical, or might be hurt by increased competition from LIKE? Very difficult to value this share now, as no idea what normalised cyclical earnings will be? PBT margin is now under 2%. It says volumes are 20% below normal, so if that recovers, profits could shoot up. But will it recover, and if so, when? Note that staff costs were 14.2% of revenues in FY 12/2022 Annual Report, but 43% of gross profit. So it's being hit hard by higher employee costs in 2023, combined with soft demand. It employed 2,197 staff in 2022, costing avg £36.5k salary (excl employers NICs, etc).
Likewise (LON:LIKE)
18.8p (£46m) - Trading Update - Paul - AMBER
(Smaller, challenger flooring distributor, run by ex-CEO of HEAD - who has just sold c. £450k of shares the day before a TU - how is that allowed? Although the TU was OK). Confident of meeting 2024 market exps. Similar low profit margin to HEAD, but at least it's growing.
Overall, at this stage, I'm not convinced either HEAD or LIKE shares are attractive. It depends how an economic recovery might play out. An improving housing market should trigger improved demand for residential carpets, so who knows?
Stelrad (LON:SRAD)
112p (£142m) - Results FY 12/2023 - Paul - GREEN
Stelrad Group plc ("Stelrad" or "the Group" or "the Company", LSE: SRAD), a leading specialist manufacturer and distributor of steel panel and other designer radiators in the UK, Europe and Turkey, today announces its audited financial results for the year ended 31 December 2023.
A very quick skim of the results has left me with a positive impression. I think the building supplies sector is a good place to find cheap, cyclical recovery shares, and this one looks worth considering for that basket of shares.
Key numbers for FY 12/2023 -
Revenue down 3% to £308m
Adj PBT down 29% to £17.3m - a tough year, but not a disaster.
Adj EPS down 29% to 13.6p = PER 8.2x - could we be at or near low point of the cycle earnings maybe? So a low PER, on low point earnings, might turn out to be a good entry point, I’m wondering.
Value metrics look great - forward PER 7.4x, and forecast yield 7.0%.
Net debt initially looks too high at £60.4m (excl leases), albeit down 12% vs LY. As with all companies, we need to know the average daily net debt number.
Net debt is 1.47x EBITDA, which is arguably not alarming, depending on your view.
NTAV is OK at £50m, and this includes £31m freehold property, which is about half net debt, which I tend to offset against net debt, so overall I think the bal sht/debt position is probably OK.
Cashflow statement - impressive. Even in a subdued year, it managed to pay generous divis, fund capex, and reduce debt.
Outlook is in line, no change.
No broker research available - a basic mistake from the company, surely? Why would a small cap have Investec as their broker?
Biggest shareholder has 49.6% (had 80% pre-IPO, banked £70m from partial sale at IPO).
Floated Nov 2021 by Investec, now almost half the IPO price of 215p, at 112p.
Paul’s opinion - looks a nice cyclical recovery value share. Readers have previously told us that heat pumps require larger radiators, so we could be entering a period of growth for SRAD possibly?
ITV (LON:ITV)
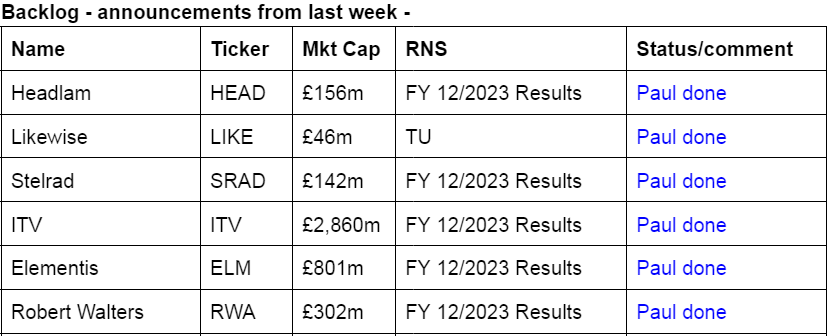
70.5p (£2.86bn) - FY 12/2023 Results - Paul - AMBER/GREEN
Large & complicated business, so I’ve only done a quick review of the numbers. Caught my eye when it announced £235m net proceeds from selling JV to BBC, and intends to spend the whole lot on share buybacks. This is on top of an already generous 6.8% forecast dividend yield. This is possible thanks to very impressive free cashflow, at £361m in 2023, which rose vs 2022 despite a fall in adj PBT (down 41% to 396m). Adj EPS down 41% to 7.8p in 2023. Mentions tough advertising market (but that could recover maybe?) High growth in streaming (so why did it sell Britbox?). Pension deficit has been cash-hungry, but it expects contributions to fall in 2024. Growth in advertising as economy rebounds? Many new Chinese electric car brands are about to land, I noticed one was sponsoring TV awards show last weekend on ITV.
Paul’s opinion - I’ve not done much research, but on an initial skim, this looks potentially interesting I think. Obviously you have to weigh up whether its core business is in slow structural decline, or could rebound? Worth a closer look I think, hence AMBER/GREEN.
Elementis (LON:ELM)
136p (£801m) - FY 12/2023 Results - Paul - AMBER
FY 12/2023 - adj EPS flat at 10.8c (8.4p) = PER 16.2x (forecast PER for 2024 is 14.0x)
Big reduction in debt from disposal, now down to 1.4x which looks manageable.
Divis being resumed. Outlook - good start to 2024. Macro uncertain. Self-help & growth programmes underway.
Paul’s opinion - looks like a moderate turnaround is underway, so there might be some upside, possibly? But for now, it looks priced about right to me, just on a very quick review.
Robert Walters (LON:RWA)
418p (£302m) - FY 12/2023 Results - Paul - AMBER
RWA describes its performance as “resilient”, which is not how I see a 63% drop in PBT to £20.8m (2022: £55.6m).
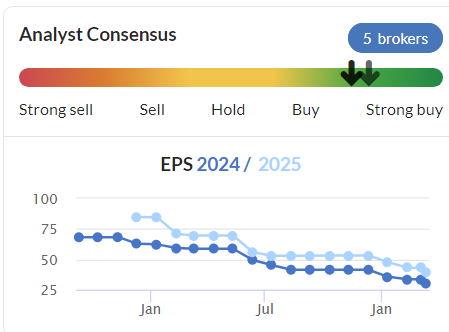
Forecasts have been stuck in a painful downtrend still -
Dividends - held at 23.5p total for the year (unch 2022) - healthy 5.6% yield.
That’s not quite covered by earnings, which were 20.1p in 2023.
Outlook - 2024 so far “remained muted”. Says it will “significantly strengthen our business”, details to come in the autumn (!) at a CMD.
This is interesting -
“Our collective experience trading through previous market cycles tells us that when conditions do improve, the inflection can be rapid, and we therefore have strong conviction in our decision to maintain our core consultant capacity, whilst sensibly managing our cost base.”
Balance sheet is healthy and ungeared. NTAV is £131m. Cash pile of £96m still healthy, but reducing, thanks to generous divis and £10m pa buybacks.
Paul’s opinion - poor results, no doubt about that. However, it’s a cyclical business, so sooner or later I imagine earnings should improve.
It’s well-financed, so could comfortably withstand another year or two of poor trading, if that were to happen.
Sooner or later, it should see a cyclical recovery, so I think for patient investors, EPS could get back to the 40-50p historical level (not much change in shares in issue in recent years), put that on a PER of say 12-15, and I would have a target price of 480-750p once economic conditions have improved. Is that enough upside on the current price of 418p though? I can’t say it massively excites me, as it might be a say 2 year wait to get there. Plus of course there’s always the chance conditions may not improve, and shares could lurch down again, nobody knows.
For me then, and for the moment, it’s just AMBER. Although I suspect we could be at or near the low point for earnings, so I probably should be more forward-looking and see the upside recovery potential.
1Spatial (LON:SPA)
Down 11% to 55p (£61m) - Trading Update - Paul - AMBER/GREEN
1Spatial, a global leader in Location Master Data Management ("LMDM") software and solutions, is pleased to provide an update on trading for the financial year ended 31 January 2024 ("FY2024").
The initial market reaction is negative, shares down 11% with someone hitting the bid repeatedly with 10k sales. Only 170k shares printed so far, and there could be bigger orders working in the background, so I tend not to take too much notice of the initial market reaction, which can sometimes be wrong.
Revenue growth looks modest - although is exactly in line with the broker consensus of £32.1m shown on the StockReport -
Total revenue for the year is expected to be no less than £32.1m (FY2023: £30.0m) with approximately 55% (FY2023: 50%) represented by recurring revenue. Within recurring revenues, software term licence revenue has increased by approximately 70% to £8.7m (FY23: £5.2m) with double digit growth across the UK, US and Australia.
Profitability - I was about to start a rant about EBITDA not being real profit, but it also mentions PBT below, but that sounds as if it has some one-off costs in it. Why not also mention adj PBT (which is my preferred measure, providing the adjs are reasonable)? Strange reporting here -
Despite the impact of inflationary cost increases, adjusted EBITDA is expected to be no less than £5.5m (FY2023: £5.0m) and reported profit before tax not less than £1.0m (FY2023: £1.0m), reflecting increased finance costs due to the high interest rate environment and certain exceptional charges relating to the restructuring.
Cash position - is down, and sounds tight, maybe that’s why someone is selling this morning - fears of a placing perhaps?
The Group's net cash was £1.1m at 31 January 2024 (£3.1m at 31 January 2023), reflecting the increased investment into the business, targeted restructuring activities and timing of certain working capital flows, which have reversed since year end.
Why didn’t they quantify the working capital flows, and give us the current cash position?
Maybe I should set up a consultancy business, to teach companies how to update the market properly? It feels like that’s what we’re doing here sometimes - picking up on their mistakes.
Outlook - this bit sounds good, but no numbers -
We ended the year with significant momentum, successfully closing a number of high value, multi-year contracts across all territories. These agreements provide a strong foundation for the sustained growth of our Enterprise operations in FY25…
With a healthy sales pipeline, strong order book and increased recurring revenues, the Board is confident that the progress made over the past year is set to continue.
Says it’s going to spend more on sales & marketing for new products.
Broker update - Equity Developments clear the fog a little with a brief update note today, which says that the £1.0m PBT is below its estimate of £1.8m. Not sure if I should mark this as a profit warning or not? I suppose it is a mild profit warning, so yes I'll flag it as BLACK.
Paul’s opinion - I was amber/green when I briefly reviewed SPA on 11/1/2024, but I think today’s update has dampened my thoughts on it. Also I’ve quickly reviewed the last H1 results, and see a fairly weak balance sheet. There’s only modest revenue growth in 2023, and no progress on profitability. Although often it’s better for smaller software companies to invest heavily in product development where they have the opportunity.
It’s a close call whether to drop down to just amber, but on balance I’ll stick with AMBER/GREEN on fundamentals despite this muddled update. The reason being that I like this space, and think there could be a long-term opportunity with this share perhaps?
Note that similar IQGeo (LON:IQG) has a very much bigger market cap, despite being not much larger in terms of revenues.
Graham’s Section:
Ramsdens Holdings (LON:RFX)
Share price: 192.5p (+7%)
Market cap: £59m
This “diversified financial services provider” issues an AGM update for the first five months of the financial year: from October to February inclusive.
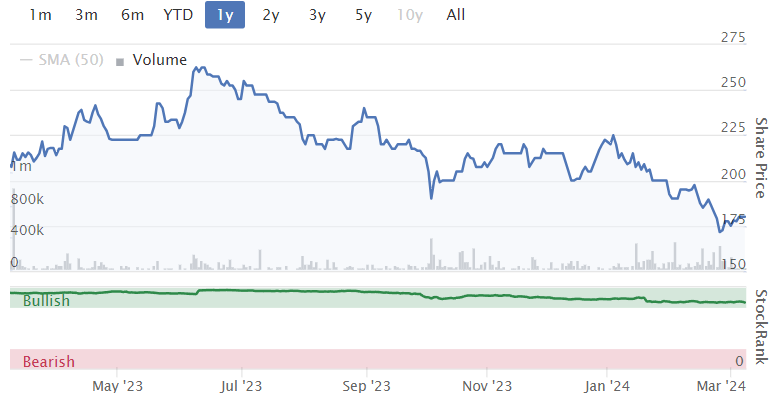
Trading is “strong and in line with the Board’s expectations”.
Bullet points for the four major Ramsdens services:
Foreign currency gross profit up c. 3% year-on-year.
Pawnbroking loan book up £0.4m in five months to £10.7m
Jewellery retail revenue “broadly flat” (slightly lower?) but with an improved mix (fewer premium watches), so jewellery gross profit is up c. 5% year-on-year.
Precious metals purchasing gross profits up c. 20% year-on-year.
The steady expansion of the store estate continues, with five new stores over the five months. Total estate now 167 stores.
Funding: £10m RCF with Virgin Money replaced by £15m RCF with Bank of Scotland, “on more attractive terms”.
Outlook: the Board is “highly confident in the Group’s continued growth prospects and its expectations for the current year”.
Estimates: Liberum estimates are for PBT of £10.5m this year (FY Sep 2024) rising to £10.9m next year. Some divisions are performing better than expected, and others worse, but the net result for headline numbers is no change.
Graham’s view
There’s no need to change my view on this one, as expressed in January. I said at the time that the company offered “net cash, a good yield, store expansion, and a proven business model at a cheap P/E multiple”. The share price is actually a little cheaper now than it was when I looked at it in January (192.5p today vs 205p then)
P/E and yield metrics as of last night:
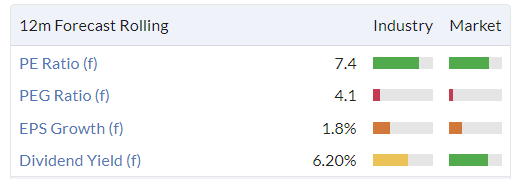
It’s important to bear in mind the factors at play here vs. something like H & T (LON:HAT). With Ramsdens, each of the four divisions makes an important contribution to gross profits. However, the biggest contributor is foreign currency (tied to tourist demand) and the second biggest is jewellery retailing.
In that sense, I would say that Ramsdens is the more optimistic investment: you are betting mostly on demand from tourists and jewellery buyers, rather than betting on demand from borrowers.
It’s also an optimistic investment in the sense that the company is making a gradual but large increase to its store portfolio, spreading out geographically.
But this morning’s rising share - in response to a merely “in line” trading update - suggests that investor expectations have been more on the pessimistic end of the spectrum.
Mincon (LON:MCON)
Share price: 53p (-2%)
Market cap: £103m / €121m
Mincon Group plc… the Irish engineering group specialising in the design, manufacture, sale and servicing of rock drilling tools and associated products, announces its results for the year ended 31 December 2023.
The table of financial highlights shows a tough year in 2023:
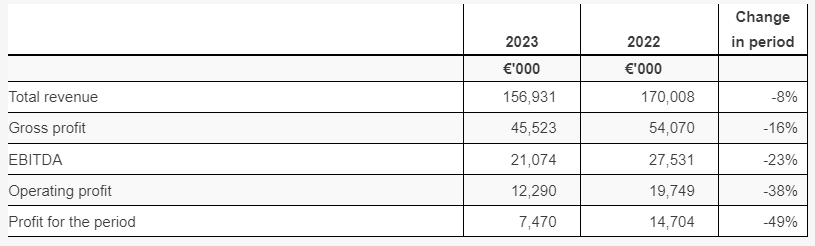
Please note we covered the full-year trading update last month which confirmed that full-year EBITDA would be “slightly ahead” of €20 million.
This followed a profit warning in October (the second and larger fall in the chart below).
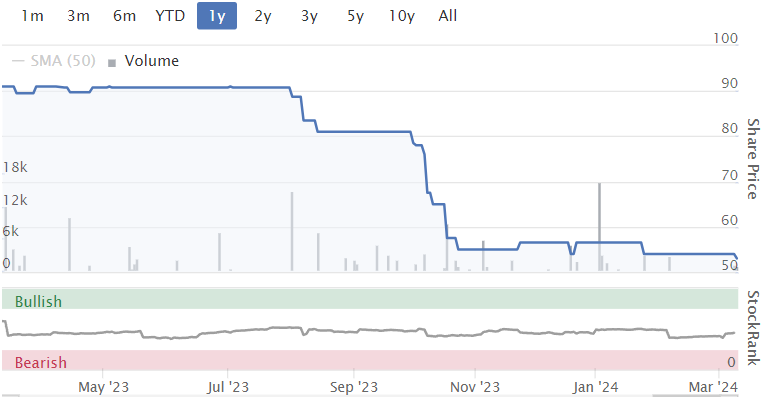
Estimates have been moving in one direction only:
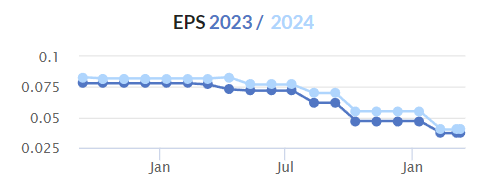
Turning back to today’s report, here are some of the key points.
Revenue contraction driven by disruption in the mining industry (mining-related revenues down 16%)
Other revenues similar to last year (water well/geothermal revenues up 3%, construction revenues down 2%)
Net debt reduces from €55m to 45m, using one of Mincon’s definitions of net debt that includes all liabilities.
A more generous interpretation of net debt would only include loans and borrowings. Calculating this myself, what I would call “financial net debt” has reduced from c. €26m to c. €20m. That being less than one year’s EBITDA, the company should be able to handle this much debt without too much difficulty.
And it’s worth mentioning that the company expensed €4m of R&D in 2023, and expects this to decrease in 2024.
Also, the company commissioned €10.5m of new capital equipment in 2023, but “this reflects a peak of investment in the near term, with capital equipment expected to be less than depreciation levels in 2024”.
These two factors both suggest that the cash flow performance in 2024 should be better than 2023, although of course many other variables will be at play.
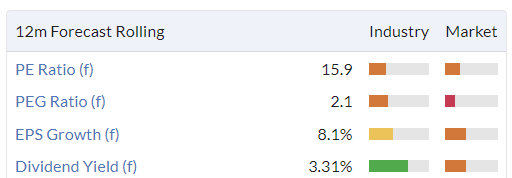
The dividend at Mincon has been unchanged for many years and remains unchanged this year. 2.1 cents per share, paid out in two equal instalments. It creates a modest yield at this valuation:
CEO comment
2023 has been a challenging year for Mincon in terms of revenue, profitability and ROCE. Revenue in H2 2023 was lower than expected due to a number of factors, notably a slower than expected recovery in mining revenues as customers ran down their inventories and the continuation of more muted conditions in exploration drilling, while we also experienced delays to anticipated commencements on some construction projects during the period.
Geographically, the main weaknesses were APAC (down 15%) and Africa (down 22%).
Greenhammer
This eagerly anticipated new product ran into problems in Australia last year. Maybe 2024 will be the year it finally succeeds? Here’s the update:
During the year, we continued our collaboration on the Greenhammer project with a major rig manufacturer and this is ready to start drilling on a copper mine in Arizona. We are confident that this approach will realise the potential that this product offers. Following this strategic decision, we elected to discontinue the previous testing on our own rig in Australia during the year.
Recent trading / outlook is positive although the company is clearly still challenged by current conditions:
…The subdued market environment in H2 of 2023 has continued into H1 2024 although we have begun to see some improvement in our order book. We are working hard to improve our competitiveness and input costs which together with potential improvement in the market environment gives us more confidence around performance in the second half of this year. We must also continue our work on delivering on the promise of our development projects. We also need to complete our root and branch review to put a stable base under the business to both deal with the challenges and realise the significant opportunities ahead.
Graham’s view
I’ve been neutral on this stock as it fights its way through various challenges.
Last October, I highlighted the five major challenges facing Mincon (supply chain, freight, Greenhammer, mining industry conditions, and net debt).
Let’s review progress again:
Supply chain: resolved.
Freight: resolved.
Greenhammer: still not resolved. Hoping for better progress this year.
Mining industry demand: not resolved as the market remains subdued. Some possible signs of green shoots but it’s too early to say for sure.
Net debt: while the current debt load looks manageable, I believe that the company could still earn decent ROE/ROCE without having a substantial net debt position (it did this before). Therefore I would like to see net debt reduce further, which I think is a goal that the company shares. Partially resolved.
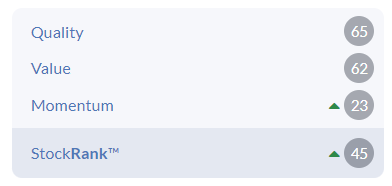
In conclusion, I think I need to remain neutral on this one. I still think it’s a better-than-average company and worth researching, but maybe it’s fully valued at this level? StockRanks are all grey:
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

54 comments
Paul. I'm blown away by both the number of stocks you got through here today and on the weekend's podcast.
I thought of you walking across Bournemouth with your triple choc pastry as I watched Grace Dent delve into Greggs offerings on Channel 5 last night.
Keep up the great work (and the steps).
How kind, thanks PoT! :-)
I missed that programme about Greggs last night, thanks for the reminder, I'll check it out on catchup.
1Spatial (LON:SPA)
Anyone interested in 1Spatial (LON:SPA) should watch this presentation by Paul Dooley of UK Power Networks. He explains why he is excited his company chose 1Streetworks and the potential of it. Both 1 Streetworks in the UK and NG9-1-1 in the US are high margin SaaS products which are starting to gain traction in the UK and USA.
I hold
SDSW23 UK Power Networks traffic management | 1Spatial
Join us for MelloMonday tonight, at 5pm. The programme for the evening is as follows:
5pm Fireside chat with Chris Boxall, Co-Founder and Director of Fundamental Asset Management
5:40pm Company presentation by Kinetiko Energy
6:10pm Company presentation by Galliford Try
6:40pm Introducing Clipper Automative and our Tax efficient investment show
7pm Company presentation by Taseko Mines
7:30pm BASH with Mark Simpson (PAY) and Kevin Taylor (RNO)
For more information, click here:MelloMonday 11th March 2024 – Mello Events
There are lots of interesting sessions and all annual pass holders and individual ticket holders will be sent a recording of the show within 48 hours of registering. For half price tickets, use code MMSTOCKO50. Buy Ticket for MelloMonday – MelloMonday, 11th March 2024 – Zoom, Mon 11 Mar 2024 5:00 PM - 9:00 PM (tickettailor.com)
Costain (LON:COST) Full Year 2023 Earnings Release tomorrow 12 March 2024 (I hold)
Paul did a quick summary on 10 Jan 2024:
"We gradually warmed to Costain in 2023, as the newsflow improved, turning green on 23/8/2023 due to cheap valuation, strong balance sheet, and improved forecasts. Although not a sector we like (low margin contracting).
Today it announces another “significant win” in the water sector.
Overall trading for FY 12/2023 is said to be in line. Net cash at year end is significantly above expectations, at £164m.
Paul’s opinion - looks quite interesting, PER only 5.4x. Note pension scheme (covered in our archive). Not my cup of tea, but providing they don’t screw up any big contracts, then it might be a share worth looking at. Small divis seem to be resuming this year."
Chart looks positive, hoping for some good news tomorrow.
1Spatial (LON:SPA) (I hold)has taken a beating today although I a reminded that it only takes the price back to where we were a month ago. Valuing growing SAAS companies is always hard as the recognition of new sales is dribbled into the results. I feel that SPA has right direction to continue consolidating and growing, it would be good to see them free of the debt obligations, and if the market was working properly it would be no problem but in the tremulous state of the UK market it is hard to get enough money for this stage of development.
I believe they are soundly managed, have a very strong competitive offering and as they bed down into being part of the infrastructure I anticipate that eventually they will rerate substantially. However I fear that they are exactly the kind of investment that London will have taken off its hands at an opportunistically cheap price by an overseas investor.
1Spatial (LON:SPA)
Can anyone please explain to me, in plain english, what this company actually does?
Michael Tee has helpful pointers above but let me try this example.
If you wish to dig up a road and expect the work to last a few days, SPA software will in just a few minutes give you a traffic management plan, so, where to put signage, which lanes to close, how to manage the one way street that intersects the works area, where to place which kind of traffic lights and so on. This is presented in an approved format for submission to the necessary authorities, council, fire, police ambulance etc. If subsequently a gas leak closes off a lane then the software can reconfigure the plan in a couple of minutes and keep the process moving. The USP for SPA is the huge amount of data required to be able to meet this planning.
Morning Paul.
Enjoying the weekend podcasts - thanks for doing these.
Just a quick point on Robert Walters (LON:RWA) - I seem to remember years ago you pointed out that recruiters were usually first to react to a bear market / recession but first to come out and start recovering (leading indicator) - I hold Gattaca (LON:GATC) and Robert Walters (LON:RWA)
Ultimate Products (LON:ULTP)
I saw Ultimate Products (LON:ULTP) at Mello last November and was very impressed with the presentation and the management team, the price then was I think 148p, the same as it it today. My view at the time was that the 'Elephant in the room' is China and this still remains the case. However China and the associated geo-political risk is an issue for many consumer orientated businesses, Warpaint London (LON:W7L) came to mind as I was pondering this issue. I don't know the extent to which the Warpaint sources products from China, but I would image a fair amount.
Back to Ultimate Products (LON:ULTP) that I researched over the weekend. I watched the presentation on the Equity Development website on the FY23 results and went through the prelim results, recent trading update and the various commentaries on Stockopedia.. My thoughts having done so and in no particular order are:
Ultimate Products (LON:ULTP) :
Despite the "China" risk and current problem to shipping posed by the ongoing military action in the Suez Canal there is a lot to like. I have therefore purchased an opening position at 148p. The funds were raised by selling my remaining holding in Howden Joinery (LON:HWDN) at 871p. The latter is an excellent company, but I consider that the share price is more than up with events.
As always these are just my views.
All the best
Deleted.Thumbsed up Jayman's post.(I still can't figure out how to delete an actual post, instead of just editing it.Have i forgot and being dumb?There must be a way.
SDG
Utterly pointless RNS saying they are developing an e commerce website for William Morris .
Beyond belief they are only just doing this .
Fancy having an e commerce website on that thing called the internet in 2024 how fantastic .
I’ll get my coat .
Maybe they are embracing direct sales which of course gives them ability to sell at a retail price not a distribution / manufacturers price so that’s high margin business at least .
It's potentially good news and the s/p has been low, so RNS to pep up the holders morale. I hold.
It was a useful RNS from Sanderson Design (LON:SDG) for me.
As you say further in your comment... less about having a website capability. But more about expanding into D2C.
Encouraging that they had one small trial, and it succeeded. Now rolling out to another brand. Implication is that they can probably roll this out to all their brands eventually.
What would be the ££ impact of having a fully scaled D2C distribution? That is the interesting question.
Looks like SDG now has potentially two growth engines. Licensing, and D2C.
My point was it goes without saying any brand in 2024 should already have this .
For they have left it too late the e com glory days have left so I actually think it’s not likely to do anything gamechanging .
I just found it cringeworthy .
Then again I’m having a bad day and everything is annoying me today .
I normally sing the praises or Lisa Montague and team .
Sanderson Design (LON:SDG)
I seem to recall from Paul's interview (could have been a webinar) that D2C was an ambition of Lisa's when she joined in 2019, though this was delayed due to the pandemic and supply chain issues (i.e. keep the cash saved to weather the storm.)
I'm not totally sure how I feel about D2C. It feels high risk compared to selling through known and trusted third-parties + licensing deals for more D2C friendly stuff (e.g. cushions, rugs etc.) Is there a risk that providing D2C cannibalises opportunities elsewhere?
hi planetx
Sanderson Design (LON:SDG)
Then again I’m having a bad day and everything is annoying me today
Hope your week improves planetx - the only way is up?
&ab_channel=YazzVEVOSnazzy
Sanderson Design (LON:SDG)
2019 revenues 113.5M.
2026 estimated revenues 117M.
I personally cannot see any upside in this one (unless someone buys it-probably not).
All the best
Sanderson Design (LON:SDG)
2026 estimated revenues 117M.
Do you have profit estimates for 2026?
I personally cannot see any upside in this one (unless someone buys it-probably not).
the upside is the clear trend in improving numbers since the lowpoint of 2019 - and if it continues the transition to licencing income being the main earner long term with hopefull;y ever increasing numbers in that regard (subject to natural variability - licence income can be lumpy) . Some have commentated on here that they think the brands alone (and with it the ability to generate licencing revenue) are worth more than the market cap , not sure if that is the case but one cant argue it could potentially be a lovely cash cow to an acquirer - or a bigger player who can leverage the brands better than Sanderson are doing (i am not knocking what the company is doing ref licence deals)
I feel they probably have mini headwinds this year - they had a real good year last year ref licence revenue and market conditions ref their customer base of wholesale aint brilliant at present (headwinds). So in some respects after real forward movement the last couple of years ref increaisng profits a year of flatness is no indication the company is going trending backwards even if they arent moving forward this year. I think any comparison to 2018 and previous is meaningless clearly the world has moved on from 2018.
On the flip side one can look at this company and perhaps argue they are still below 2018 ref profits - expectations for 2024 are pretty much flatline and heck they should be doing better than the p poor 2019 to 2022 period if they want to justify the market cap they have - never mind higher.
In some respects the proof of the pudding will be what they can acheive in 2024 2025 and 2026. Obviously it isnt really fair to expect them to exactly how well they will do now - one or two extra licences could easily add 10% or 20% to bottom line perhaps - if they deliver £10 mill 2025 and £11 mill 2026 (with further growth expected) * 15 p/e that would double the price = . So i think jury is out at present as no one knows what they will deliver going forward - but at pe of 8.2 with solid balance sheet and value of the brands its not expensive. Perhaps there is downside risk if the reality is licence sales has actually peaked and the market hasnt realised that yet - i havent seen any indication specifically that they arent confident ref licence income though.
Bidstack (LON:BIDS) Canadian Overseas Petroleum (LON:COPL) Loopup (LON:LOOP)
At least three less meaningless listings but the FCA should have tackled this issue earlier along with many more.
Agree Yiannos. Good riddance, hopefully more to follow.
Loopup (LON:LOOP) finishes with a flourish as the CEO Steve F claims they successfully survived the pandemic. Congratulations Steve, great job. Have you looked at your share price over the last 3 years? Revenue? Profitability? Please don't circulate your CV. We'll call you.
Loopup (LON:LOOP) Can someone clarify why going private has crashed the share price so much. I was under the impression that a de-listing was what really caused these big moves down - but to de-list would require 75% approval which under the shareholder register looks unlikely. I always thought that a 'take private' meant you get close to the market price - with the share price down 65% today I don't see how a take private would get the shareholders approval. What am I missing about this situation, I must have a flawed understanding of how these things work. If someone could clarify, it would be much appreciated.
(I do not hold Loopup but would like to better understand this downward move)
Metalmaid Taking Private has nothing to do with the price you get for selling a shared. It just means they will not be listed on any recognised market and will therefore be difficult to buy and sell any shares that holders retain. Probably on a matched bargain basis through an appointed intermediary but I'm not entirely clear on that.
Hence the decline in the sp today as holders try to get rid of the last of their shares and treat themselves to lunch with the proceeds. Slim pickings! Thanks again to Steve F for all his hard work and excellent leadership through the pandemic.
Many thanks for that. One more question - does taking private require a minimum certain percentage approval? And if so are we to believe that many of the larger holders have likely been secretly in prior discussion?
See the section "Process for Cancellation" in the RNS announcement today from Loopup (LON:LOOP) .
Generally requires 75% of shares to vote in favour.
The company, of course, in the prospectus, is probably going to offer the "stick" that if it does not receive the necessary votes, the only alternative is administration (and with no or little value for existing shareholders).
Rock and hard place.
Many thanks Boon, that's exactly what I wasn't understanding - and that now makes sense to me. cheers
Loopup (LON:LOOP)
I was under the impression that a de-listing was what really caused these big moves down
Yep that is the case here and the Turkeys will probably vote for themselves to be eaten come xmas day - so the reaction is standard for the merest sniff of delisting. I suspect the 4 potential investors here are holding all the cards if the investment is necessary and the alternative is simply to liquidate and start from scratch.
And I wouldn't be surprised if the new investors dilute current shareholders to oblivion. Lose - lose whichever way the dice fall.
Kinovo (LON:KINO)
Market Cap dropped circa £5m on Fridays (8th March) announcement of £1.5m extra costs for DCB.
Directors were buying in the market that day.
8 of 9 DCB projects expected to be finished by May 2024 with the core business looking good.
This share could re-rate once DCB projects are complete. Downside risk the final project incurs extra costs.
Downside on Kinovo (LON:KINO) also includes dilution risk, as the already weak balance sheet is building up larger creditors for provisions against the onerous historic problems. It said last week that most of the payments have been made, but it then mentioned continued support from HSBC, which worried more than reassured me.
Core business trading well though, so the upside case is that it trades its way out of the (large) historical problems. Downside case is that it has to dilute holders with a placing to strengthen balance sheet. Could go either way I think, so no strong opinion from me.
If there's another significant increase in the historical provisions, then I would be worried that the bank might lose patience (they hate that kind of thing), and demand an equity raise.
Orchestrated Director buying for smallish (CFO and COO) amounts doesn't reassure me, and their total holdings are also small.
I'm only flagging the risks, not predicting what will happen, it could all work out fine (or not), I don't know! Too much guesswork for my taste personally.
Regards, PAul.
Thanks for your comments Paul.
For anyone interested Kinovo (LON:KINO) are presenting "Update on DCB Discontinued Operation" on Investor Meet Company, tomorrow (12th) at 10am.
Not sure that the proposed potential (patriotic) £5000 maximum UK investments ISA is going to tempt Pension Funds who have shunned the UK for years, to invest more here!
What it has done has highlighted yet again how cheap so many UK shares are, and have been for so long now. Instead of bemoaning it why not take advantage as I have for a good while, by buying some of those big dividend paying undervalued UK shares and Investment Trusts, when they’ve looked particularly oversold.
It’s a fluke if we manage to buy right at the bottom but further falls if they look unjustified or during temporary market dips (e.g like at the height of the Truss/Kwarteng chaos in Autumn 2022 and then again when some fell heavily last Autumn) are average down or top up opportunities. Below are just a few of the current bargains I hold.
The big attraction is the extraordinarily big dividends while waiting patiently for the UK market to go on a sustained good run. Then the dividend yields will come down to more normal levels, NOT through (unlikely) dividend cuts but because of significant share price gains reducing the yields. AND 10% and more a year just from dividends is an acceptable return while these bargain buy opportunities persist.
So don’t just moan about how cheap a lot of UK shares are. Just take full advantage!
Here are some of mine:-
TP Icap (LON:TCAP)
Note. Final Results are this Tuesday.
There was an FT article on Saturday about the possible sale or ipo of Parameta Solutions. Claims apparently that it could be worth up to £1.5 million in an ipo…..and the market cap of TP Icap (LON:TCAP) is LESS at £1.4 billion. So far there’s no follow up to this today, beyond the share price up 7p as a result.
DIVIDEND YIELD is 6.8%. Big increase in final dividend last time from 5.5p to 7.9p. Interim also increased. Dividend policy is 50% of adjusted post tax earnings for year as a whole.
I bought right at the bottom at just £1.04p in July 2022. . A rare occasion of timing the buy at the exact oversold bottom. TP Icap (LON:TCAP) looks well worth checking out ahead of the Results in case they surprise on the upside.
Note share (at Friday’s close) is down 2% ytd, up 2% 1 year and down 31% over 5 Years. Peaked at £4.11 in Jan 2020.
Aviva (LON:AV.) 468p
Very good Results last week greeted with big initial share price gain that fell away to modest rise by the close. DIVIDEND INCREASED to 23.3p (ex 11th April and pay day 23rd May). AND future increases policy of mid single digits. Share has recovered from way oversold, but still cheap and with 7.5% dividend yield. I had a tiny post covid top up at only £2.50. Tiny because of my maximum in any one share rule AND my large holding was at a big loss then. But it shows that bravery buying when most are selling is a good Warren Buffett type tactic.
Legal & General (LON:LGEN) 249p.
Their Results last week fell a tad short of expectations. Reverse of what happened with AVIVA share price as initial double digit fall was mostly recovered by the close. Final dividend 14.63p (ex 25 April and pay day 6th June). “Continuing our progressive dividend policy.” 5% dividend increase for 2024. Dividend yield 8%. I luckily bought on an extreme dip to just 155p.
Abrdn (LON:ABDN) 152p.
Different to all the others covered in that performance has been dire and share price fall from £5 deserved. They’ve merrily bought back their shares for years starting at £5! So much for these buybacks rewarding their shareholders.
BUT! Now oversold? They’ve got assets way north of current market cap. And dividend is 9.6%. Final dividend of 7.3p (14.6p total) goes ex div on 14th March and pay day 13 April.
Is Abrdn (LON:ABDN) a possible bid target?
M&G (LON:MNG) 231p.
Recovered from crazy 177p low this time last year. Results March 21st. Has increased dividends up till now. Yield 8.5%.
Phoenix group (LON:PHNX) 510p.
Results 22nd March. Dividend 10.2%. Share is down 20% since this time last year for no obvious reason and fell to just 441p last October. So so so often those extreme falls are BUY opportunities….yet I know of folk who panic sold on that October 2023 share price fall just because of that fall instead of for investment reasons.
Liontrust Asset Management (LON:LIO) 681p.
Share price recovering from extreme lows but still a shadow of £25 peak in 2021. Ytd up 13% but down 37% 1 year. Failure of the proposed acquisition of GAM didn’t help. Stocko figures like Liontrust Asset Management (LON:LIO) with 98 for quality and 94 overall.
Chesnara (LON:CSN) 262p.
I’ve held for ages and it’s proved to be a poor investment. Ytd flat and down 8% 1 year. That’s despite 19 years of dividend increases and a 9% yield. Results are at the end of this month. Another potential bid candidate?
Polar Capital Holdings (LON:POLR) 442p.
At least it’s up from extreme low of 396p last October! Dividend yield is 10.5%. Results not until June. They’ve got some good performing funds and Trusts and share looks oversold. As with Liontrust Asset Management (LON:LIO) the Stockopedia figures like it with 98 for quality and 94 overall.
The huge dividends from all these shares are a BIG attraction while we wait patiently for the share prices to go on sustained good runs. Such high yields used to be a warning sign of unaffordable dividend or worse, but note again that dividends of the Companies in this post are often seeing increases. It reflects way undervalued shares and NOT a warning. . Hence why so many quality UK Companies are falling to (often foreign) bids.
Hi Ken,
A totally different view. These are all companies that are EX-growth!
I understand and share that some of these are probably 30-50% undervalued and the reason is their lack of growth.
Better opportunities elsewhere.
All the best
Yeah, I’m personally exiting the UK market completely.
I don’t see anything going for it. The city seems to be in a death spiral, vanguard etc are driving up “better market” prices
And it seems likely we are about to enter 4-5 years of a labour goverment
I’ve been moving to global markets for the past 6 months, and my goal is exit uk shares completely. I’m just not that good a share picker to spot the occasional one that goes against the trend, and there are many fantastic companies globally.
I am doing the same. Even my 'solid" stocks - one step forward 2 (or 3) steps back every day.
Hi yiannos
I wasn’t suggesting that the sort of value shares I covered in the post this morning were far better than growth shares. Some of the latter also look oversold (e.g Volex (LON:VLX) that I’ve held for around 2 years and has just flat lined overall since purchase. That PE of around 10 looks low for a growth share unless the market knows something I don’t yet.
I only hold a very few growth shares at present simply because there is usually little or no income and so dead money while waiting patiently for the upside, whereas for the shares I posted about this morning (and many similar examples) the dividend yields are providing big income while waiting and the dividends also fund new buys and top ups.
e.g current yields are good enough but at my buy prices TP Icap (LON:TCAP) is paying 13% a year even if no increase this year and Legal & General (LON:LGEN) (admittedly a “brave” as in Yes Minister buy) at what turned out to be the low at depth of the 2020 covid crash, is up 50% and unlike Volex (LON:VLX) has also returned nearly half my stake in dividends.
I try and go for a balanced portfolio with UK shares and also Investment Trusts to invest around the World and those Trusts also including some very big dividend payers. Charles Mitchell has started an excellent Investment Trust thread on Stockopedia that is now seeing increased interest and with a lot of Trusts covered by posters there.
You say there are far better opportunities. There could well be and it would be good if you could post on some of the ones you know about.
I have posted many times and the reasoning behind my recent picks.
Kier (LON:KIE)
iShares Bitcoin Trust (NMQ:IBIT) (sold 50%).
Ken, Fund managers do look cheap and I think we could see further consolidation in the sector. At the moment the yields are good. I boughtRecord (LON:REC) Impax Asset Management (LON:IPX) and Jupiter Fund Management (LON:JUP) a few months ago and hold POLR and TCAP.
Clearly these are not growth companies but I think in the case of Chesnara (LON:CSN) the city has lost the ability to properly price a company that has assured the market with an astonishingly sound dividend. If you were a pension manager that is looking to build up a a solid annual income you should forget the share price and tuck these away. If you never knew the share price you would never think of selling this! Why would you sell it?
Somehow the City gets embroiled into trying to breakdown the accounting for a clever buyer of declining assets and does not pick up on the only line which matters to an income enthusiast, dividends per share. Even dividend cover is going to vary and over more than a decade you just have to trust management that they have it right.
Hi Ken. Good post as ever - so good someone has copied it verbatim to the PHNX thread on ADVFN - at 16.35 by 'Apotheki'. If you weren't aware?
Thanks for letting me know Lincs. I’ve just replied appropriately there.
Thanks Lincs. I’ve just responded to him appropriately.
Morning Paul good news about your Mum. Being slightly pedantic but it could be the difference between success and failure. Heat Pumps (assuming their success will continue) are generally put into new builds. The advantage being you can put in under floor heating which will reduce demand for radiators. The large radiators are for those of us who decide to put heat pumps into older homes where raising the floor is expensive/a challenge.
Stelrad (LON:SRAD)
I think there is a growing market for replacement radiators. Many 1960s/70s houses like mine have old inefficient units and upgrading to new does improve heating and aesthetics too. Same must go for lots of much older properties that got their first central heating about that same time: lots of upgrade candidates methinks. Should provide a good solid market for Stelrad.
Re Stelrad (LON:SRAD) - the opportunity is not just replacement but also premiumisation and cost reduction. The total number of radiators they've sold is barely up in the last 5 years at just over 5Mn but they have increased contribution/radiator from £11.16 to £18.09. This reflects both moving production to newly invested and lower cost sites in Italy and Turkey and getting people to trade up - to ones related to decarbonisation (heat pump related) but also tall radiators, towel racks etc etc. Much of Europe is in a construction hole at the moment, especially the UK which is 45% of Stelrad revenue. If we saw a 20% increase in units sales (which does seem impossible) AND premiumisation AND scale/cost reductions, you start to see how their profitability could really motor in 1-2 years. They seem to be beating or acquiring western competitors but I guess the risk is a flood of Asian imports.
Was it just me who did a fist pump on the weekend when hearing that Paul's mum could walk again :)
Britbox - ITV (LON:ITV) (no position)
High growth in streaming (so why did it sell Britbox?).
Short answer. ITV didn't sell britbox (UK) which is being folded into ITVX at the end of April.
Has been widely mis-reported by the media. ITV sold its interest in Britbox International to BBC Studios ltd - the profitable international studio and distribution subsidiary of the Beeb.
Whether BBC Studios Ltd is getting a good deal is another matter? The BBC has a long history of profitable international distribution - Hopefully they know what they are getting into and it will prove to be a profitable business for them. In theory increased profits defray the cost of the Beeb to the licence payer and getting the rest of the world to contribute to running the Beeb seems a good thing to me? For ITV shareholders - they get a windfall and ITV gets to focus upon its ITVX streaming activity which also makes sense?
cheers
Mark
Ah OK, thanks Mark for clarifying that point over BritBox. I do recall it was the international bit in a JV with the BBC that ITV sold to the BBC. Didn't realise they had kept the UK bit, so pleased you pointed it out! Sorry for the inaccuracy/confusion.
Best wishes, Paul.
IMO it now opens up to a possible bid for the whole of ITV (LON:ITV) - now much simpler with two main divisions (Studios and TV channels). Or maybe the next step is a sale of one of the two parts, probably Studios (given the regulatory/government scrutiny if the TV channels were sold).
The investment thesis for ITV was always that it was undervalued compared to the sum of the parts. Especially Studios - rife speculation of the value it could get, especially during the COVID boom where streaming services were pouring money into commissioning content. That's now died down a bit, but its easy to image that the Studios business itself could be worth in the low billions, almost as much as the ITV market cap?
I used to hold in the Boon Fund but what made me sell out and keep out was (1) the weakness in Studios over the past year-ish, especially with the writers strike holding everything up. (2) TV advertising rates continue to be soft, and I don't see a catalyst to change that soon. It is a business with huge operational leverage - all the costs are fixed, every incremental £/ad spot falls to the bottom line.
One to watch today is GCM Resources (LON:GCM) 65% up so far today. Watch it fly.
My morning smallcap tweet: All dogs were cute puppies once
Bidstack (LON:BIDS) Loopup (LON:LOOP) Versarien (LON:VRS) EQTEC (LON:EQT) Currys (LON:CURY) Sanderson Design (LON:SDG) RC365 Holding (LON:RCGH) Aptamer (LON:APTA) Nanoco (LON:NANO) 1Spatial (LON:SPA) Journeo (LON:JNEO) Powerhouse Energy (LON:PHE) Gulf Marine Services (LON:GMS) Roquefort Therapeutics (LON:ROQ) AFC Energy (LON:AFC), Ramsdens Holdings (LON:RFX), Touchstar (LON:TST)
◄Bidstack (BIDS)► goes bust. [SP=0.22 Cap=3m]
◄LoopUp (LOOP)► proposes to de-list. Cites "ability of the Company to raise necessary funds within public versus private markets given the relatively early stage of development of the Group's fast-growing Multinational Cloud Telephony business". Trading in line. [SP=2.02 Cap=4m]
◄Versarien (VRS)► the slippery mess of a company will sell plant and equipment in South Korea for £604k. Possible license fees for patent use. AAC Cyroma and Total Carbide continue to be marketed for sale. [SP=0.1 Cap=1m]
◄EQTEC (EQT)► subscription form Verde delayed to 29 Mar at the latest. [SP=2.42 Cap=5m]
◄Currys (CURY)► Elliott Advisors will not make an offer "following multiple attempts to engage with Currys' Board, all of which were rejected". [SP=64.5 Cap=731m]
◄Sanderson Design (SDG)► to launch a direct-to-consumer collaboration with Morris & Co. Latter's wallpapers, fabrics and licensed products will be made available from a dedicated online shop serving customers in the UK, USA and other countries. [SP=104.5 Cap=76m]
◄RC365 (RCGH)► use of YouneeqAI's IP and Platform delayed because decided that its resources in the short term would be better deployed to Malaysia and Japan. The outstanding payment (3m shares) will be bussed around Oct 1. [SP=9 Cap=12m]
◄Aptamer (APTA)► after successful progress of work with Unilever the companies are drafting patent applications to protect these developments and downstream commercial applications. [SP=0.71 Cap=3m]
◄Nanoco (NANO)► to return up to £33m of the Samsung litigation proceeds via a £30m tender at 24p and £3m max buyback. [SP=19.19 Cap=62m]. I hold.
◄1Spatial (SPA)► guides FY-Jan rev £32.1m+. Adj EBITDA £5.5m+ and pretax flat at £1m+ "reflecting increased finance costs due to the high interest rate environment and certain exceptional charges relating to the restructuring". In line? Outlook confident. [SP=60.89 Cap=69m]
◄Journeo (JNEO)► wins orders worth £1.9m to supply and install important safety systems on existing buses for TfL. Installation in 2024 and support over 3-7 yrs. Co expects more orders during the year to upgrade more of the New Routemaster fleet. [SP=249 Cap=41m]. I hold.
◄Powerhouse Energy (PHE)► renegotiates agreement with Hydrogen Utopia for the development of a non-recyclable Waste Plastic to Hydrogen facility in Ireland. [SP=0.8 Cap=32m]
◄Gulf Marine Services (GMS)► wins the first of a two phase, four-year, contract for one of its vessels operating in the Middle East. [SP=17.55 Cap=177m]. I hold.
◄Roquefort Therapeutics (ROQ)► positive results for Midkine mRNA and STAT-6 siRNA programs. [SP=7.5 Cap=10m]
◄AFC Energy (AFC)► successful Factory Acceptance Test of its first state-of-the-art 30kW H-Power Generator. [SP=16.39 Cap=123m]
In line: RFX, TST
Great weekend podcast Paul.
Pleased to hear of your Mother’s progress in her recovery - as my octogenarian father quips with acuity, ageing isn’t for the feint-hearted.
Keep up the good work
Thanks TJ, much appreciated! :-)
Just to avoid clutter, can I suggest other subscribers could ignore or thumbs up, rather than adding other comments to this thread? That's not to undermine in any way a kind message, hope that's OK.