Small Cap Value Report (Mon 12 Dec 2022) - TLY, ARB, TSTL, CNIC, EXR, AGFX

Good morning from Paul & Graham!
This week should be interesting. We had snow yesterday, and then rail strikes kick in from tomorrow. So I imagine most of the country is likely to be in chaos. Here's our back garden in London yesterday - rather lovely, especially as it's so rare here. It normally looks the same, but without snow.
Podcast - went up on Saturday, covering loads of companies. The mystery shares (my best ideas of the week) will follow further down in a short section below. I've got to work out a better way of doing this, but I tend to make it up as a I go along, and structure follows later.
Mello Monday - it's the last show of the year, online today, starting at 5pm. Paul Hill is doing a presentation with some stock ideas, he's always brimming with interesting ideas, and has a fantastic personal investment track record, so well worth listening to. Also there are 3 company presentations.
Agenda
Paul's Section:
Totally (LON:TLY) [quick comment] - announces a big contract win, for £66m, over 5-8 years. Totally looks an interesting company I think - providing outsourced services for the NHS in specific areas (this latest contract is to operate urgent treatment centres, to relieve the pressure on A&E Depts, which sounds extremely useful). Although Totally has a good growth track record, it’s not made anything much in the way of profit - this seems low margin work, won in competitive tenders. If the company can raise margins, then the shares could become more interesting. EDIT: Thanks to StrollingMolby, who points out in the comments below that this is replacing existing contracts, and we're not told if it's on better, or worse terms. So impossible to tell if this is good news or not. (no section below)
Tristel (LON:TSTL) - an encouraging update from this niche medical disinfection products company. A decent H1 performance suggests that it might be heading for a full year beat against expectations. Cash is fine, with £10m on hand. Valuation is the tricky bit - it still looks over-priced to me.
CentralNic (LON:CNIC) - a positive trading update, the CFO steps up to become the new CEO, and it suggests share buybacks are on the cards - which seems a strange decision considering its weak balance sheet, and large gross debt. I've had another look through the last Q3 results, and am starting to get a bit more comfortable with the numbers.
ENGAGE XR Holdings (LON:EXR) [quick comment] - I’ve got to cover this, as it’s a top faller, down 46%. The short version is - don’t waste your time looking at it. Net cash was E4.9m at June 2022, it’s now expected to be down to only E1.9m at Dec 2022. A heavy EBITDA loss of almost E6m is expected for 2022, as orders have failed to come in as expected. So the cash burn means it’s only got enough to keep going for a few months in 2023. Costs are being cut, and another fundraise now looks inevitable. What discount will be demanded by anyone willing to put in fresh cash? Delisting also looks inevitable. I wouldn’t touch this with a bargepole. Going into a recession, jam tomorrow companies have to be fully funded, otherwise they're likely to fail. (no section below)
Graham's Section:
Argo Blockchain (LON:ARB) (£32m - suspended) - this looks like it might be reaching a conclusion. Its shares were suspended from trading on Friday, without explanation, on the same day that it issued its monthly operational update for November. The operational update was grim: mining margin reduced to 29% (a figure which doesn’t include the cost of mining machines) even as the company mined fewer bitcoins. More crucially, there is still no sign of financing, and without fresh funds, “Argo would become cash flow negative in the near term and would need to curtail or cease operations.” Funds are needed to cover its “present requirements”. This is crunch time: it should imminently announce either a deal, or that it is giving up and changing strategy (which will surely spell bad news for shareholders). While it’s impossible to know with any degree of certainty, I imagine that the likelihood of a total wipeout for the existing equity grows stronger for every day that passes without a deal announcement.
Argentex (LON:AGFX) (£148m) - this FX broker floated in June 2019 at 106p per share. Revenues have approximately doubled since then, but the company’s share price hasn’t, and valuation now looks far more reasonable to me. Furthermore, trading momentum is superb as the company again raises its expectations for the current period, in a short trading update. While not all of the factors behind its recent success are attributable to its own decision-making, I think that most of them are. It is now forecast to generate nearly £50m of revenues in FY 2023, with adjusted PBT of £10.7m.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul's Section:
Tristel (LON:TSTL)
360p (pre market open)
Market cap £170m
Trading Statement (AGM)
Tristel plc (AIM: TSTL), the manufacturer of infection prevention products, will hold its Annual General Meeting at 11am…
The current financial year is FY 6/2023.
H1 revenues expected to be £17m+ (up from £15m H1 LY)
Growth in all geographies.
Gross margin in line.
Cash position very healthy at £10m (with no debt) - I’ve always liked TSTL’s strong balance sheet, so shareholders never have to worry about liquidity, and it pays modest divis (yield just under 2%).
Update on North America -
"With respect to North America, we have made our first sales in the United States and Canada, and we are preparing the additional data requested by the FDA in September. We expect to submit it in March next year, meeting the FDA's deadline and facilitating a decision from the agency around our year-end in June. We remain confident of a successful outcome.
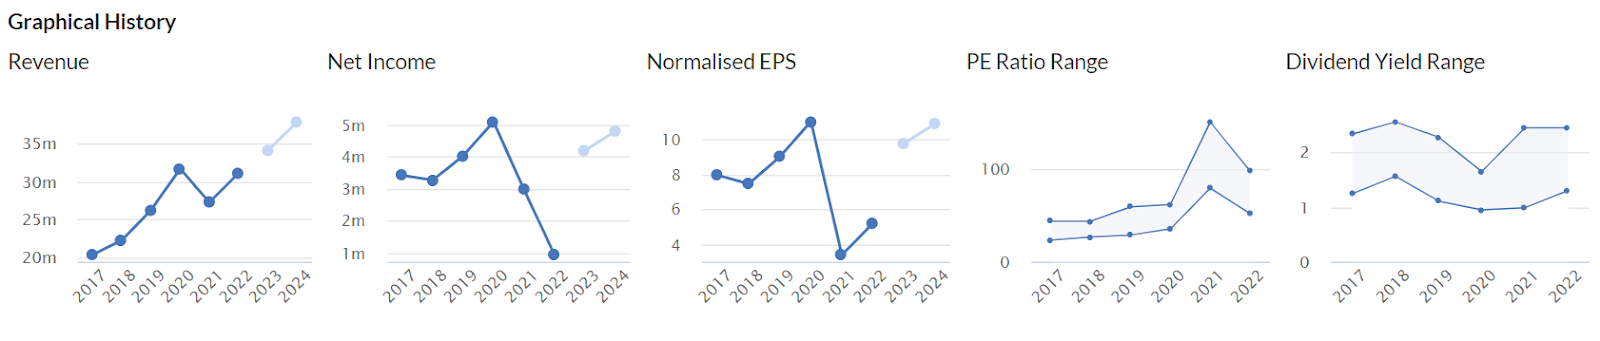
Broker update - Finncap issues a short update, thanks for that. Forecasts unchanged, but it points out that historically TSTL tends to have a small H2 weighting to revenues, which implies that it could beat existing forecast, which is £34.2m revenues, £6.0 PBT, and 10.7p EPS (higher than Stockopedia’s consensus of 9.75p). So it sounds like 11-12p might be a sensible guess for FY 6/2023, I reckon.At 360p (pre market open) that’s a PER of 30 times, on the most optimistic figure of 12p. Hardly a bargain - we’re being asked to pay up-front for considerable future growth.
My opinion - TSTL is a nice steady little company, generating modest long-term growth. It sells small amounts in lots of territories. So it perplexes me as to why investors think the long-awaited breakthrough into the large US market would be worth paying such a premium for? It’s notoriously difficult for overseas companies to break into the US, and it costs money to set up a sales network, promote the products, etc.
Shares remain significantly over-priced, in my opinion, for a company that looks sound, but not madly exciting.
Do these figures below justify the £170m market cap and high PER? I don’t think so.
Mystery Shares
These are my best ideas from the week's news, exclusively for Stockopedia subscribers, hence referred to as "mystery shares" in my free podcasts.
Last week's were -
Hargreaves Services (LON:HSP) - see Tuesday's SCVR here
Oxford Metrics (LON:OMG) - see Wednesday's SCVR here
MS International (LON:MSI) - also in Wed's report.
Obviously these are not recommendations, and I've no idea what the share prices will do. But they struck me as the most interesting value/GARP shares from the ones I reviewed in the week. Hence it might save you time, to flag up the best ideas in this way, if you're looking for new share ideas to research properly yourself (remember we only do quick reviews here, which are not necessarily comprehensive).
CentralNic (LON:CNIC)
136p (up 4% at 10:16)
Market cap £393m
Trading Update (leadership change, and share buyback)
CentralNic Group Plc (AIM: CNIC), the global internet software company that derives recurring revenue from marketplaces for Online Presence and Online Marketing services, is pleased to announce the appointment of Michael Riedl, currently Group CFO, as Group CEO with immediate effect. Michael succeeds Ben Crawford, who retires from the board today.
Trading update is positive -
…we are delighted to confirm that trading has remained robust since then and would now expect a full year outcome at least in line with the upper end of market expectations1. We will announce our Q4 trading update on 30th January 2023.
1 [1] Analysts forecasts as of 21 November 2022 are within a bandwidth between USD 701.0 million and USD 709.6 million for FY22 revenue and between USD 80.0 million and USD 84.1 million for FY22 EBITDA.
Checking back to the recent Q3 results, it made adj EBITDA of $62.0m, so today’s announcement implies c.$22m EBITDA in Q4, which looks a similar run rate to the 3 previous quarters (just under $21m per quarter, on average).
EBITDA of $62m for Q3-YTD turned into PBT of $21.0m, so a big difference there. The reasons for the difference are mainly quite a high finance charge (mostly debt interest), and a big amortisation charge. I’ve done some digging on this, note 14 of the 2021 Annual Report gives a breakdown of the amortisation charge, but it’s difficult to ascertain precisely what it relates to, and if this is related to acquisitions (in which case it can be disregarded), or internally capitalised costs (in which case it’s an important cost that needs to be taken into account).
Given this vagueness, I’ve checked to see if it’s capitalising a lot of internal costs, and the good news here is that no, it’s not. The 9-month cashflow statement shows only $0.6m of regular capex, and $3.6m of intangibles capitalised - i.e. not very much for the size of company.
Capital allocation - this is interesting, and sounds like a change of direction, to ease back on M&A activity, and instead focus on deleveraging and share buybacks -
The business is highly cash generative which has allowed the Company to successfully execute its M&A agenda and at the same time improve its net debt position. Having achieved these two objectives we now intend to launch a maiden share buyback before the year end with details to be communicated shortly.
Looking forward we will review our approach to cashflow deployment within the business and expect a greater focus on returns to shareholders versus M&A.
I think the reducing M&A, and deleveraging sound sensible options, but cannot see how share buybacks make sense whilst it has only recently refinanced its borrowings, which are substantial at $250m (gross) until Oct 2026, refinanced onto a lower interest rates (hedged with Swaps) recently.
My opinion - having spent a bit more time going through the numbers today, I’m getting a lot more comfortable with this share. Lots of acquisitions in the past have muddied the water, and made the accounts difficult to understand. However, it does look as if there’s a decent, cash generative business here.
I dislike the very weak balance sheet, with heavily negative NTAV. However it is a capital-light business model, in that there’s hardly any PPE (fixed assets), and also negligible inventories. Hence this type of business should be able to operate fine with little balance sheet strength. That said, I’m not keen on debt, which seems excessive. There again, the banks have happily refinanced it recently, with $250m facilities, at a lower interest rate, so they must be happy, and will presumably have gone through the numbers with a fine toothcomb.
Stockopedia is showing a forward PER of 8.3, possibly reflecting investor concern over high debt, a weak balance sheet, and accounts that are quite complex & hence difficult to understand. If they pause acquisitions for a while, I think that would be a good thing, so that we can see a clean set of numbers, without lots of adjustments.
Overall then, I’m not quite ready to give it a thumbs up, but am starting to lean in that direction, and think it looks a potentially interesting share that would be worth you spending some more time looking into. Could this be a GARP (growth at reasonable price) share? It's possible, the numbers do seem to be pointing towards that.
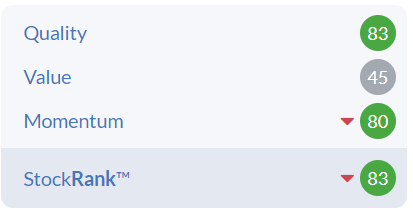
Stockopedia likes it, with a high StockRank -
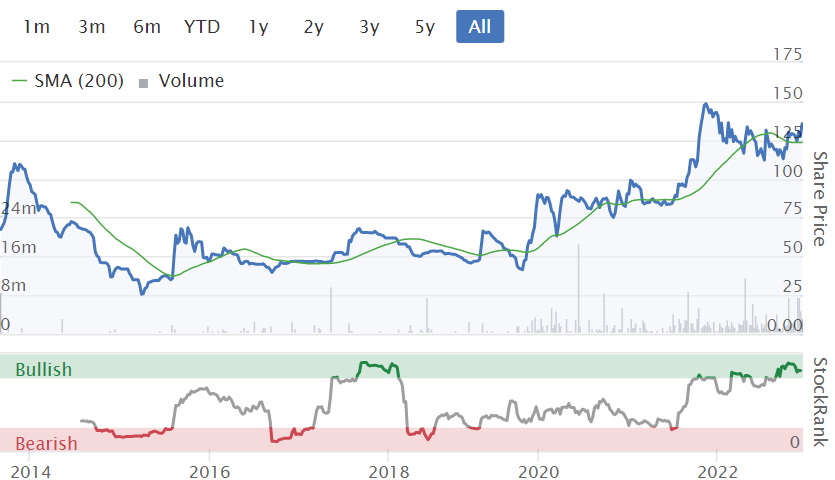
The long term chart below looks pretty decent to me - not too many gyrations, and moves up in steps, which seem to hold each time - which you often see at companies which are performing reliably well, without downside surprises -
.
Graham’s Section:
Argentex (LON:AGFX)
Share price: 130.44p (+10%)
Market cap: £148m
This FX broker’s stock was already enjoying excellent momentum prior to today’s trading update:
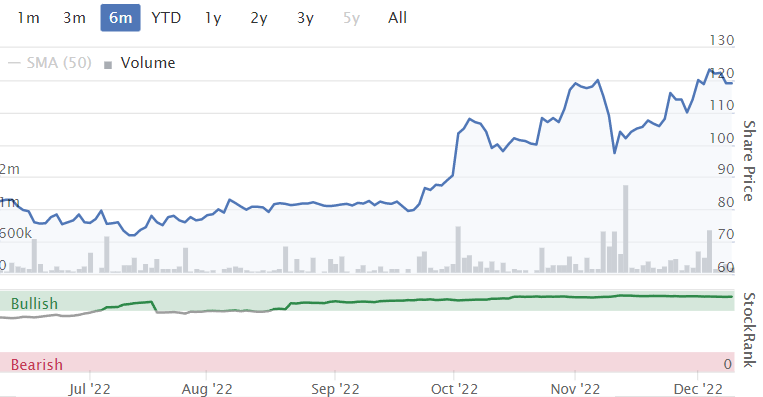
It has already raised full-year expectations in October, and followed that up with robust interim results in November.
Today we learn of “continued improvement to its trading”, as strong momentum has been maintained. Revenue and earnings for the current year will be ahead of current market expectations.(Note that the “year” is only nine months long, from March to December, after the company changed its reporting timeline.)
Everything is going according to plan:
The Group's growth strategy continues to deliver results with robust trading across all products and geographies. This includes our core FX offering benefiting from market tailwinds, sustained outperformance from our new Amsterdam office, continued optimisation of product mix including structured solutions and growth in client numbers in the online platform.
I would caution that the market tailwinds - unusual currency movements and unusually strong public interest in exchange rates - are beyond the company’s control and can’t be counted on as a permanent fixture.
However, the other factors cited as contributing to the company’s success are things that the company itself can take responsibility for: expanding to Amsterdam, selling more advanced, higher margin products such as options, and growing the number of clients on its online platform. All fine achievements!
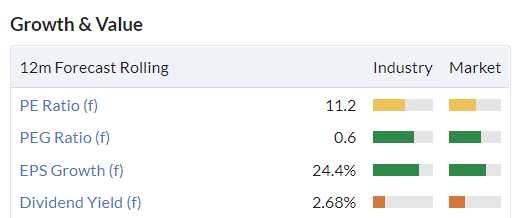
I continue to rate this stock currently as my favourite listed FX broker, and I also believe that it has grown into its IPO valuation and can potentially offer decent prospects from here.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

66 comments
An extraordinary statement from Argo Blockchain (LON:ARB) this evening:
...certain draft materials were inadvertently published as a test page on the Company's website. The inadvertently published materials, which implied that the Company was filing for Chapter 11 bankruptcy, led to the suspension of trading of the Company's securities on the London Stock Exchange and Nasdaq on Friday, 9 December 2022. Shareholders should note that the Company has not filed for bankruptcy at this time.
The Company has requested that the UK Financial Conduct Authority restore the listing of its ordinary shares and that is expected to happen as soon as practicable.
It's good to understand what lay behind the suspension, but the explanation hardly inspires confidence.
This was also notable on the StockReport page - ARB's peer group. All indicators flashing red.
Paul,
A busy day I realise, but if you can find the time to look at Coral Products (LON:CRU) this evening or tomorrow, I too would be grateful.
Sosandar (LON:SOS) is reporting tomorrow, I believe, so that will take priority, I expect!
(I hold both)
Just had a look at Coral Products (LON:CRU), under share holder activity it has directors have sold 7% of the shares, but I can't see any directors sales. Any ideas?
Hi Rusty2,
You are correct, there have been no director sales at Coral Products (LON:CRU) . I expect the issues arises from Stockopedia incorrectly attributing shares released from Treasury as director sales.
Volution (LON:FAN) - rumoured bid for this on Betaville apparently, hence the spike this afternoon. I bought this at the recent lows having missed out back in 2020. Good capital allocator producing strong ROICs and FCFs in a sector with strong regulatory drivers. Well diversified between UK, Europe and RoW.
I still see value if the rumour turns out to be just that and good upside if it proves well-founded.
Hi Paul,
Hope you're keeping well! Just a short note re CentralNic (LON:CNIC) (I hold) following your write-up; the large amortisation charges are I believe related to acquisitions and the CFO (now CEO) has explained them as spreading out of the purchase price(s) paid and do not correspond to cash/cash flow in the given period or any future period. So for example amortisation of customer databases and trademarks etc. These are not assets that would not need to be purchased again. They've said this is why they take EBITDA as a more useful metric to value the company. If you're interested there are several presentations on Investor Meet Company. They also go into what they term as organic and non-organic growth. The net debt position also seems resonable c. $63m at half year and most recent udpate and less than 1 x EBITDA. Cash conversion ususally over 100% and the graph looks encouraging. I'm sure as you mentioned that a cleaner set of accounts would make things easier for investors to see the business/metrics more clearly.
Best wishes,
Michael
in-line trading update buried an announcement by Accsys Technologies (LON:AXS) today that the CEO is stepping down. The CFO stepped down in summer, so it looks like a nice clean sweep out of the old management, who have presided over a factory construction fiasco.
Here's hoping new management now start to make good on Accsys potential and be able to ramp up manufacturing without any further issues!
Thanks for mentioning our last Mello Monday show of 2022. If any of you are Mello virgins and not watched a Monday virtual show before then you can get a FREE ticket for tonight’s event with the code NEWTOMELLO
https://tickettailor.com/events/melloeventslimited/795141
How on earth does ENGAGE XR Holdings (LON:EXR) get a 'High Flyer' Stock Rank style and an Altman Z2 score of 59.9 (ie 'safe' from bankruptcy risk) when its never made a profit and losses appear to have been increasing year on year?
Paul (or anybody) know why Invinity Energy LON:IES has doubled over last week. Perhaps you could include it in the next SCR. Thanks
Invinity Energy Systems (LON:IES): just read the RNS on the 1st of December, there are no secrets.
persistent selling by Fidelity & Amati. Everdura is largest award to date , 15MWh- grid resilience for Taiwan. Revenue forecast for 2023E fully covered by existing contracts. Some expectation about further awards before 12/22 Y/E & significant contact award anticipated by 1Q23( UK LODES competion) which Canaccord say likely to be larger than Everdura
The announcement of Ben Crawford leaving CentralNic (LON:CNIC) was a shock. He had built up quite a company and it looked like the business was about to finally throw up some positive statistics in the balance sheet and P&L pretax levels. (BTW I think a big element of the recently reported negative gap between EBITDA and pretax P&L was i) exchange difference against USD, which should not recur in the current period and ii) write off of costs incurred for the old finance arrangement that has now been replaced).
Not having any idea of the reason for his departure is a bit concerning, although the market seems fine with it. I wonder if the board wanted to reign-back on the expansion and let the numbers do the talking, as Paul notes, but that Ben could not reconcile himself to taking his foot off the accelerator.
I also note some suggestions on Twitter that Kestrel may have wanted to slow the acquisition trail and see the share price re-rate. Personally I would have been happy to see them continue as before - it is a large and rich market that is not easy to enter successfully. It seemed clear Ben was shooting for the stars and I was happy to sit and see what happened.
Equals (LON:EQLS) - an interesting share that we've been discussing here recently. Good news is that mgt has reached out to me, via an adviser, asking if I'd like a meeting. As it looks an interesting company, performing well, and I think there's a fair bit of subscriber interest in it here, I'll take them up on the offer. Will report back to you once I've met them, either in person, or by zoom.
Paul, I met these guys (cant remember the names) at Islington a few years ago (before COVID) and the impression I got was that they did not really care about retail investor engagement ie not even telling investors when results announcements were going to be- so reaching out to you must be a positive sign. I was a shareholder at the time but with that and probably a focus on top line and lack of control of overhead I exited. I haven't kicked myself yet
Good luck with the interview
Excellent news! I am a happy holder of CentralNic (LON:CNIC) (now!) having bought the share all the way from 116p down to 29p. Each time the price dropped I looked at the latest info and it seemed to be making great and steady progress. In particular I liked the move from retail to SME while most of their competitors remain very much in the retail space. I very much look forward to learning your views on this still small company as it hopefully continues its growth path. On a prospective PE of 14.7 and a PEG of 0.6 it still looks cheap to me on a platform of steady improvement over the last few years.
Interesting Velocys (LON:VLS) funding announcement this morning that bodes well for their Sustainable Aviation Fuel system. I am starting to smell the pie in the sky. I hold.
What to look at ??
Following the upcoming demise of Crestchic I find myself in the position of deciding where to re-deploy the funds (it was by far my biggest holding )
Good problem to have I guess .
Currently on the hit list
Avingtrans - already a big position but add on weakness (if falls back)
Sureserve - but again already a big position
Really needs to be an AIM share for the IHT cover .
I quite like Croma which has a cunning plan but already have plenty .
The definite one at current levels is Titon holdings which is a real deep value play albeit with headwinds, they are stuffed full of real estate which seems to aLmost cover market cap and have a Korean division that they could divest of for a high price . Reminds me a bit of Crestchic actually .
Current price is ludicrous but no liquidity and long term play.
Other than that open to suggestions and looking for inspiration ?
I took an opening position in Netcall (LON:NET) this morning, I get the feeling it's close to a breakout-rerate and just had a really good AGM trading update and a good broker write up on research tree. The forecasts are being upgraded and Revenue and Profit forecasts look good, with a steady growing profit margin. Plenty of cash and no debt.
It's expensive on a P/E basis, and pretty high on its chart (which would normally put me off) but looks like momentum is building, and Stocko's algorithms seem to agree. Goes X in a couple of days, but you won't be getting a holiday out of it! If it pulls back in January I will buy in again.
Good to see Sureserve (LON:SUR) on the move a bit today (I Hold)!
Good luck Planet. Maybe hold off for a January pullback....its a tough call (I have the same redeployment issue with K3C). If you go and visit Netcall (LON:NET) let me know before you go so I can triple my stake ;-D
I am also a holder in Netcall (Netcall (LON:NET)). I invested a few weeks back for the same reasons you mentioned. However, I like the fact that the chart is approaching a 20 year high. If the shares do break out and re-rate (fingers crossed), then from a technical point of view there is no overhead resistance; any buyers will be in profit and there won't be any frustrated sellers, who bought at a higher price, waiting to exit. As you say, it's not cheap on a PE ratio compared to the general market, however, it's not been this cheap for a while according to the StockReport. Did I mention I was a holder!
Avacta (LON:AVCT) Avacta may be worth a look. Currently on Phase 1 of a trial, involving proving that their AVA6000 can make Doxorubicin (Chemotherapy) more effective and lowering the side effects of the chemo. Nearly 500 days into the trial, currently on the 4th cohort of patients. Hopefully a RNS will drop soon with an update. Obviously highly speculative but worth a look. https://aimchaos.files.wordpre... investment note from Myles McNulty is quite an interesting readout. Best of luck.
I would have a look at Hargreaves Services (LON:HSP), one if Paul's mystery shares this week, looks very good value. Same sector. I hold.
Already have a big chunk of Hargreaves (2nd biggest holding ). Will add more of it falls back . Know it very well and the wind farm potential of circa 6 million isn’t factored in by my fag packet .
Hi Planetx,
Some ideas ( i hold some, but not all! )
iEnergizer (LON:IBPO)
ME International (LON:MEGP)
MS International (LON:MSI)
Ten Entertainment (LON:TEG)
Would have said Sure Ventures (LON:SURE), bit of a move up today which is welcomed!
Regards.
£SURESERVE even!!
Argentex (LON:AGFX) after todays announcement ? Still incredibly cheap even after todays rise.
Hold a big position in equals which is similar. I also know the CEO of argentex from long time ago and errr, well I prefer Equals .
Really needs to be an AIM share for the IHT cover
I really don’t follow your reasoning here. But firstly Let me express the hope your health is not such that IHT is an imminent concern.
My observation is that I don’t see deep value investing as being very compatible with inheritance planning. Typically, deep value stays unappreciated almost up the the point that its hidden value is realised - at which point it is time to sell and find the next prospect. But you can’t sell before your death if you are to enjoy the IHT exemption on the asset in question. The chances of finessing this opportunity in tune with one’s own demise are pretty slim, are they not?
Therefore, unless you have imminent and serious health concerns, would you not be better off widening your trawl and only narrowing your focus towards IHT-friendly Aim stocks at a later stage when stability of your wealth might be more important then capital appreciation, naturally steering you towards more stable names from within the index.
Trust me IHT cover is a top priority, do t really want to get into it too much, would require quite a lengthy explanation but it’s to do with EOT and deferred payment and IHT on deferred payment which is not guaranteed but inland revenue treat it as guaranteed .
Well actually I did get into it , but end result is my investments must have IHT cover .
Its an unusual circumstance not health related that makes it my top priority .
I also prefer some AIM companies especially ones that I understand and that engage as quite cranky that makes it more fun, and investing should be fun too !
I had 30 years owning a business so if I’m a shareholder I want to feel like and be treated like a company owner .
Just my mentality but equally I am not normal .
Surely planetx, if your heirs are looking for a windfall you might be prompting them to give you a new car and couple of foreign holidays to encourage you to chase after the IHT AIM Cos you worry about.
Morning planetX
I continue to hold Crestchic (LON:LOAD) as I feel that there is a real possibility of a counter offer. I also hold Avingtrans (LON:AVG) my second largest position that I added to on weakness at 347p a month or so ago.
Regarding potential candidates for future investment, I would suggest looking at Ricardo (LON:RCDO), which in my view has several tailwinds, but notably environmental consultancy. The shares have started to gain traction despite the depressed markets and the investment metrics remain reasonable. The new CEO, Graham Ritchie has set out his strategy for growth that appears very credible.
Talking of reasonable investment metrics I would also look at £PMP. Trading in line and very inexpensive on that basis. Also the newish management under CEO, Mike Raybould have a clear strategy for resurrecting margins and moving the company forward. See the webinar of the recent interims on
www.investormeetcompany.com
Extract from Portmeirion (LON:PMP) RNS of 3rd November
"As we continue through our key seasonal trading period, Group sales remain robust and further to our interim announcement on 15 September 2022 trading for the months of September and October have been in line with management expectations."
I hold both having bought Portmeirion (LON:PMP) at 300p and Ricardo (LON:RCDO) at an average of 399p.
Just my views I leave the decisions to you.
All the best
Portmerion I do like and will look again .
Ricardo is out as I’m not keen on consultants
Are you already a holder of Eneraqua Technologies (LON:ETP) ? Good, growth prospects with market tailwinds, winning contracts and management with significant skin in the game.
Are you already a holder of Eneraqua Technologies (LON:ETP) ? Good, growth prospects with market tailwinds, winning contracts and management with significant skin in the game.
I like the story and the valuation on this one but the liquidity (or lack of it) keeps me on the sideline.
Suspect we may see a secondary placing by management to improve liquidity. Only Slater with a disclosable interest ATM
Morning,
No sign of any Santa Rally as yet, should be imminent, if indeed there is one!
Positive news from CentralNic (LON:CNIC) this morning.
I think the three interest rate decisions this week will drive the markets along with the latest sanctions on Chinese officials by the US and the spreading of Covid across China, are all a headwind to Santa's Christmas Magic IMHO, but good pull back today so just maybe......On balance though I think I will sit blowing my brains out on indices to end this year, which lets face it, has been one to forget ;-)
i thought the run up from 6800 to 7600 from the start of november was the santa rally...it finished last week...hope there's more to come though !
Re Totally (LON:TLY) it is worth noting that the £66m contract for the next 5 years replaces a contract that Totally already has with the two Urgent Treatment Centres.
"The contract will replace an existing contract that Totally currently has in place for the two UTCs.
Following a full tender process, the NHS South East London Integrated Care Board ("ICB") awarded the contract to Greenbrook Healthcare Limited ("Greenbrook"). The contract will commence on 1 April 2023 and run for five years, with the option to extend by an additional three years."
So whilst it is great for recurring revenue visibility, there is no mention if this is on better terms, or worse, following the competitive tender. Does anyone have any insight as to the original contract?
Another contract for Kromek (LON:KMK) but it continues to be unprofitable. Perhaps it is approaching an inflexion point given the political instability in the world, and especially in Europe right now, where the contracts will continue to flow in at an increasing rate and the volumes for existing products will take off. Earlier contracts have been primarily US driven. This is from a European source, and perhaps that is significant. I am not nor have ever been a holder, but an interested bystander watching an apparently high tech company with a pitiable turnover which makes losses in such a sustained way over the years.
I wish I was an interested bystander - unfortunately I am a long term holder of LON:KMK who is not very good at deciding when to jump. I am however with you in your thinking. There seems to be a steady stream of positive news about orders in the last few weeks and the forecasts are for a 50% revenue growth which I suspect may be beaten. Unfortunately the forecast for Net profit is still -£3.5m and they seem to have burnt through £15m in the last few years. Even at this bombed out price it is at 2+* revenue so a lot of optimism baked in . Find it very difficult to recommend to others but I am starting to think cash burn will come to and end and if revenue growth gets repeated we may have lift off!
Good morning Paul and Graham, hope you both had a good weekend. I have recently stumbled on Coral Products Coral Products (LON:CRU) via some commentary in Investors Chronicle a couple of weeks ago. A small plastic extrusion manufacturer with a chequered history, that have dumped problem subsidiaries and have been on a bit of an acquisition trail. Results look promising today, but appreciate these might be too small, and I don't think they have been on your radar in the past.
Morning lefty99!
Thanks for flagging Coral Products (LON:CRU) interims, looks quite interesting. I'll have a look at it later this morning, after we've got a couple of larger company sections done.
Regards, Paul.
Thank you Paul
That would be great thanks Paul. I have been invested for quite a few years having first read some very positive stuff by Gervais Williams. (I note Premier Miton has since reduced their holding significantly but no idea if from his funds)
With this rising and other long term shres falling, this is now my largest holding (and I'm not selling any at this price).
K3C- trading update nicely pitched to keep potential bidder on side while not over exciting value expectations?
Sigmaroc (LON:SRC) impressive outturn for the year given the pervading economic gloom and in fairness the sector in which the company operates. Revenue ahead 20% year on year on a like for like for basis and underlying eps expected to be 10% ahead of market expectations.
As mentioned in previous posts I have met the management team headed by Max Vermoken, who come across as competent and very much 'switched on.' I had the good fortune to add to my holding significantly at 40p after attending the company's presentation for private investors at the Isokon building, Hampstead in October.
Also a reassuring update from K3 Capital (LON:K3C), comfortably in line with expectations. It will be interesting to see how the market reacts given the bid situation. I hold.
Morning !
We (wife & kid) went to Tenpin (Ten Entertainment (LON:TEG) ) at the weekend (the one in Nottm) and I was pleasantly surprised at how busy it was. Not just the bowling but the slot machines, pool etc. And people at the bar. Just a really nice atmosphere. I spoke to the manager and said I was a shareholder and he said trading has been very strong. We already knew that any way from the last trading update but still, worth noting...
Yes, also a happy shareholder here! Thanks for post.
Regards.
I had a very similar experience a couple of weeks ago, it was just so busy! Yet still single digit p/e and very generous dividend. Hollywood results are on Friday that should give a good read across but I will be surprised if it is anything other than record numbers.
I think the 10 pin bowlers have been helped by the fact that a lot of other family entertainment places have closed so less competion (just where I live the trampoline place and softplay both closed during the pandemic) . On top of that you obviously have fewer people going abroad and looking for cheap entertainment. I can see these tailwinds staying in place for some time. They also have relatively low staff costs, which is very helpful in current environment.
Both look good but for a Retail business faced with the well published headwinds (even if 10-pin entertainment is still decent value and very popular which I agree) isn't a high single digit P/E about right, i'd be wary of buying anything much over 9ish. Could be short term upside on positive trading updates though so good call.
Just don't think it's going to have a high % return potential unless takeover or holding for many many years.
bowling places also a nice place to stay in the warm for families rather than home bills.
CentralNic (LON:CNIC)
Change at the top announced. Perhaps in response to concern that the business is not as well understood as it should be due to pace of acquisitions and visibility of cash generation. Share buybacks in prospect. Looks sensible to me. Trading confirmed at least in line with latest upgrade. I hold.
Morning Paul,
Top pod as always - For the mystery shares, would it be possible for you record a mini-pod (just a couple of mins long) that only gets posted on Stockopedia? The mystery shares are the ones I want to hear about the most, but due to the format don't get that opportunity. I get a better feel for a stock when hearing you talk about it rather than just reading the write-up, not sure if that's just me though!? Very conscious of your workload, so no need to do a writeup just a quick audio recording would be amazing.
Maybe thumbs up from any readers who think its a worthy suggestion?
Thanks as always for the hard work Paul, Graham, Megan, Edumund, Mark and Roland.
It's a shame that people complained about giving too much info away and that mystery shares are needed in the first place. The best content is getting missed out as a result.
Podcasts are great, though. I look forward to them each week!
Personally I would be happy for Paul just to openly discuss the mystery shares in the free pod. As subscribers we have the advantage of 1) a few days (usually) head start if we read the daily SCVRs, 2) the fuller, detailed explanation of Paul's thoughts in the write up, and 3) the subscriber conversation that follows in the comments. That's enough IMO, though I appreciate others will differ.
Agree I would have no problems whatsoever with Paul just openly discussing the mystery shares. Realistically how many non subscribers will be listening to the podcast, and even if there are a couple of freeloaders then is it really such a big deal that we have to go to the hassle of having a separate podcast just for subscribers? Seems a bit over the top.
MJ Hudson (LON:MJH) shares suspended, CFO suspended, additional issues with the accounts, no audited results by end December. Oh dear, Mr Hudson.
What a disaster that one was. It actually looked an interesting business - seemed well placed to benefit from the mass of regulation in the fund management industry and the drive towards everything ESG. Hudson would supposedly take care of this side of things. I took a small position at one point, but something didn't feel quite right so thankfully got out. Felt far too acquisitive and the numbers had an awful lot of adjustments which I couldn't get my head around. Would be a good one to study in a bit more detail when time permits to figure out exactly what went wrong.
Sigmaroc (LON:SRC)
Cracking trading update today given all the gloom and pessimism. I hold.
"- Revenues to 30 November 2022 of £498m, up 20% year-on-year on a like-for-like basis;
- Demand conditions have evolved broadly as expected across market segments, with the Group benefitting from its broad end market and geographic diversification;
- Cost pressures managed through dynamic pricing, savings initiatives and performance improvement programmes;
- FY22 underlying EPS expected to be c.10% ahead of the market's expectations1;
- FY23 outlook remains unchanged;
- Active pipeline of acquisition and investment opportunities with potential to significantly develop the Group."
Top work this morning Mr C , on a cold snowy morning.
Good to know there are still things that can be relied upon.
R
I had to break off to clean up after our cat was sick on the carpet as well. What a rush. She usually only impedes me by sitting on my lap.
Loving the Casablanca vibe again! Here's lookin' at you...
Argentex (LON:AGFX) "ahead of expectations"...always nice ! Already on a low p/e with net cash so this should surely shoot up today...