Small Cap Value Report (Mon 12 Feb 2024) - JNEO, TPX, GOOD, DCTA

Good morning from Paul & Graham!
Here are Graham's latest thoughts, in an excellent & wide ranging interview with Paul Hill.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Quiet today -
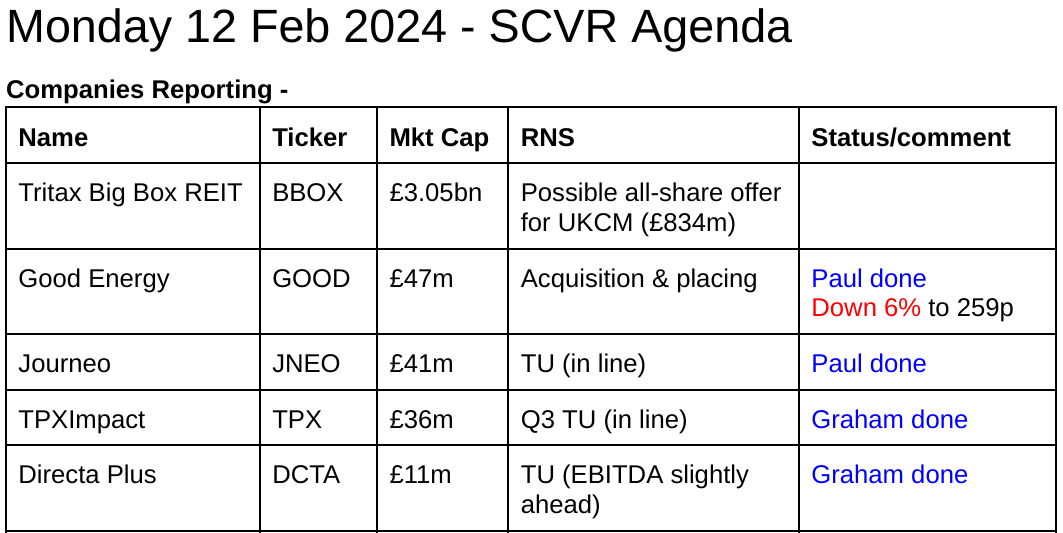
Journeo (LON:JNEO) - 249p (pre-market) £41m - Trading Update [in line] - Paul - GREEN
Trading update for FY 12/2023 is in line with expectations. Valuation still looks reasonable, providing it can keep winning contracts. Outlook comments are vague, but positive-sounding. JNEO seems to have transformed itself in the last year, so looking good, providing that momentum can be maintained.
Tpximpact Holdings (LON:TPX) - up 4% to 41p (£38m) - Q3 Trading Update - Graham - AMBER
This IT services company reports Q3 trading in line with expectations, and reiterates its targets for 2024/2025. These include like-for-like revenue growth of 15-20% next year. Net debt has reached a more manageable level, hopefully allowing for more stability in future.
Good Energy (LON:GOOD) - down 8% to 254p (£43m) - Acquisition & Placing - Paul - AMBER/GREEN
My first look at this energy supplier & services provider, which has announced a reasonable-sized, profitable acquisition today. Earnings seem very volatile, but I like the balance sheet strength, which makes me lean moderatively positively, purely based on an initial review.
Directa Plus (LON:DCTA) - unchanged at 17p (£11m) - Trading Update - Graham - RED
I don’t have a very good impression of graphene stocks up to this point, and Directa isn’t helping as it looks at risk of needing further funds in due course. The cash balance is €2.4m but net cash appears close to zero while the company remains loss-making.
Paul’s Section:
Journeo (LON:JNEO)
249p (pre-market) £41m - Trading Update - Paul - GREEN
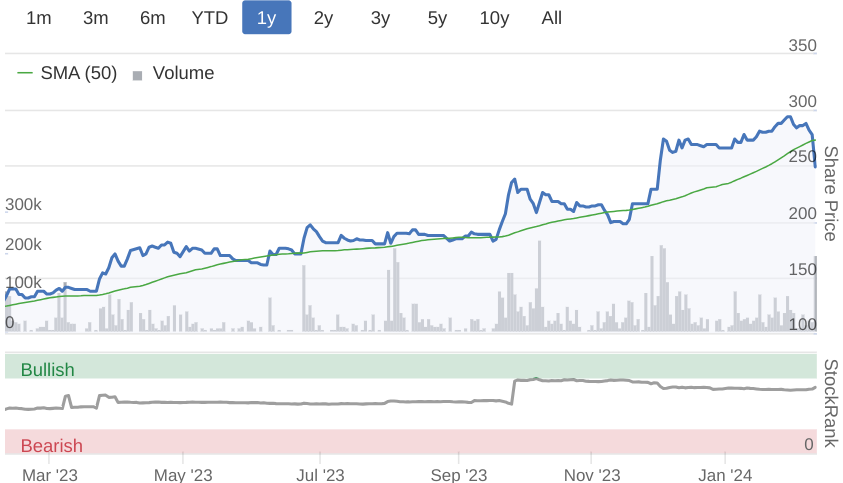
Erratic price movements last week rattled some investors -
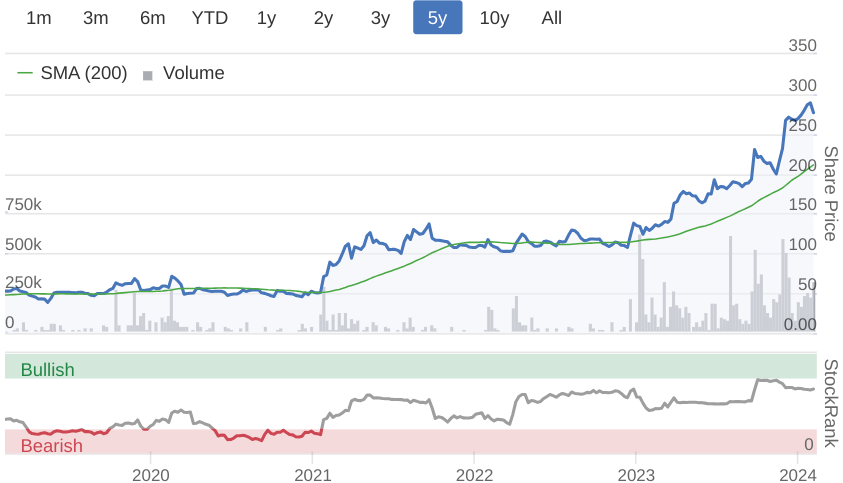
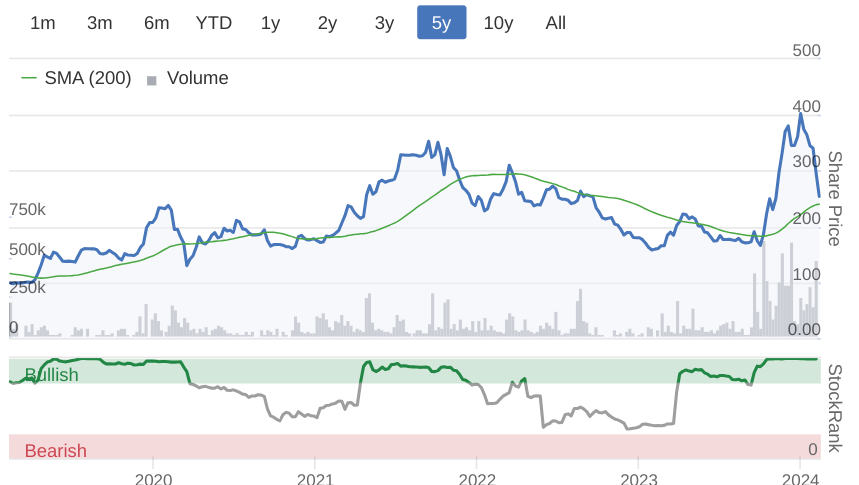
Although zooming out on the chart to 5-years, this has been a very successful investment for long-term holders, as new contracts and a seemingly very well-priced acquisition have transformed performance for the better -
Trading Update
Journeo plc (AIM: JNEO), a leading provider of information systems and technical services to transport operators and local authorities is pleased to provide an update on trading for the year to 31 December 2023.
Most importantly -
Adjusted profit before tax is anticipated to be in-line with market expectations.
Revenue up 118% to £46.0m (20% organic)
Acquisitions have been transformational -
The acquired businesses, Infotec and MultiQ, have performed well since joining the Group and contributed £21m in revenues during the year.
Cash sounds healthy -
Cash balances at the year-end were £8.1m, including payments in advance of £1.6m (2022: £0.5m). The Company invoice discounting facility of £2.75m was unutilised at the year end.
Outlook - light on specifics, but sounds positive -
Russ Singleton, Chief Executive of Journeo plc commented:
"I am very pleased with the progress we made in 2023, both organically and through two acquisitions. These developments are fuelling our strategy to broaden our customer base, extend our geographic reach, deepen our capabilities and provide us with access to thematically linked adjacent markets. We have strengthened our recurring revenue alongside our order book and pipeline, providing good forward earnings visibility and a solid base on which grow the business further. Together with significantly improved cash balances, we are investing in our people and technologies to develop innovative products and services that meet our customer requirements, as well as anticipating the future needs of the public transport sector. With a strong sense of momentum and an increasingly compelling customer offering, we look forward to further organic and acquisitive growth."
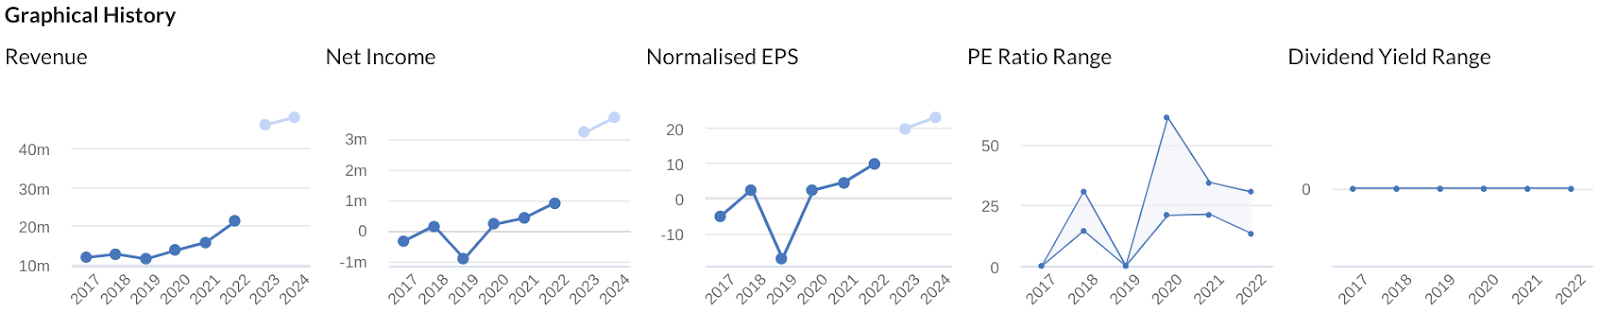
Forecasts - the StockReport shows 19.8p EPS for FY 12/2023.
On Research Tree the most recent note is from Cavendish, 28/11/2023, which says 20.6p adj EPS (raised 5% at the time).
At 249p/share, this gives a PER of 12.1x, which sounds reasonable, providing earnings can be maintained or increased further - that’s the key question.
A new note from Cavendish has just come through, saying it’s in line, and reiterating 20.6p EPS for this year. It mentions a large contract in New York, and cash being ahead of expectations.
A more modest rate of growth is pencilled in for FY 12/2024, to 23.1p EPS, a PER of 10.8x
Paul’s opinion - the numbers are very impressive, in particular the doubling of EPS from 2022 to 2023, mostly from what seems to have been a shrewd acquisition.
The main line of enquiry for research would be whether these are lumpy one-off type contracts, or whether momentum is building and growth will continue. I don’t have a view on that, but am just flagging its importance.
I was green when we last looked at JNEO, and based on the still-reasonable valuation, and strong progress in 2023, we have to stay at GREEN.
Good Energy (LON:GOOD)
Down 8% to 254p (£43m) - Acquisition & Placing - Paul - AMBER/GREEN
As it’s quiet for news today, I’ll spend some time acquainting myself with GOOD - something we haven’t covered here before. It’s been quite a rollercoaster ride for investors in the last 3 months particularly -
Today’s acquisition news also contains an in line trading update -
Good Energy has continued to trade in line with the Board's expectations following its last update to the market in November 2023.
What does GOOD do?
Good Energy Group PLC ("Good Energy" or the "Company") (AIM: GOOD), the 100 per cent. renewable electricity and energy services provider…
There seem to be several activities -
Electricity supply is by far the biggest, and only significantly profitable part of the business, as you can see from the H1 results segmental analysis table below -
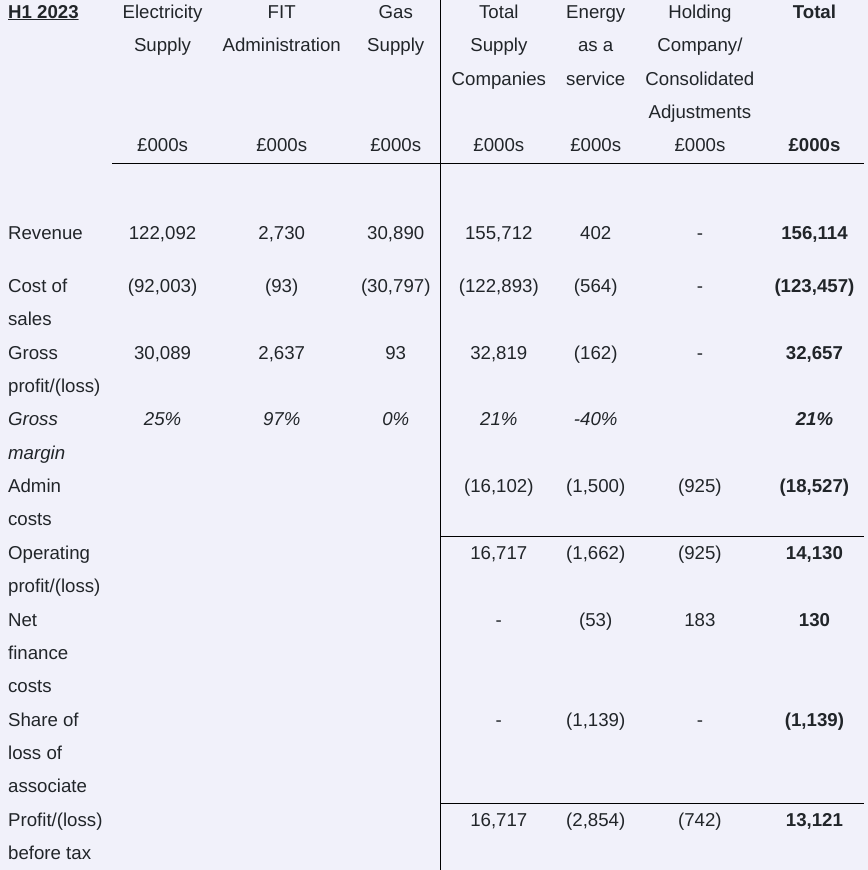
It owns 49.9% of Zap Map - an app for finding electric vehicle charging points. That seems to be loss-making, but might have some future potential maybe?
WessexECO Energy was acquired in June 2023, and is a small-scale installer of solar panels. It also acquired a small heat pump installation business. Neither look significant at this stage, so I’ll ignore them.
Smart meter installations - 44k so far, again this looks very small.
The main business seems to buy in renewable energy from solar and wind farms, then sell it on.
H1 (to June) 2023 was superbly profitable, but it sounds a one-off -
Gross profit increased due to a strong H1 2023 performance and cost advantages from our power purchase agreements. However, we anticipate a one-off loss in H2 2023 due to lagging commodity costs and tariff reductions.
· Operating profit of £14.1m (H1 2022: -£0.5m loss). Some of this is expected to unwind in H2 given the falling commodity cost environment since late last year.
It’s quickly becoming apparent that this share is impossible to value, because earnings are so volatile. This is why I tend to avoid energy suppliers, because there’s been so much disruption, many have gone bust, and they can’t fully control input or output prices.
Broker forecast - there’s a useful note from Canaccord available on Research Tree. This forecasts most of the H1 profit will be given back in H2, so FY 12/2023 is £264m revenues, and a PBT of only £4.5m, or 21.4p EPS - giving a PER of 11.9x. Note that H1 profit was 72p, so highly volatile earnings, and difficult to see any trend.
Note that on 28 Nov 2023, GOOD said -
"Following a strong first half of the year, the Company's trading to the end of October has been ahead of expectations. If seasonal normal weather and stable commodity market conditions continue for the remainder of the year, Good Energy expects to deliver earnings ahead of the Board's expectations for the full year seeing a profit before tax of at least £4m."
Bear in mind the 2023 forecast profit includes absorbing £3.0m losses from the energy services part of the business. So we could strip out those losses, and do a sum-of-the-parts valuation as an alternative to a PER-based valuation (which can give poor results when a group has some profitable bits, and other loss-making elements being developed).
2024 and 2025 forecasts show a sharp reduction in revenue, so it does look as if there’s been some energy crisis related volatility here. Who knows what normal will look like in future?
Balance sheet - given that I have no idea how to value this share based on erratic & unpredictable earnings, let’s see if there’s any balance sheet substance?
The last balance sheet was 30 June 2023, in the interim results here.
NAV was £50.6m at end June 2023. This included £5.5m intangible assets, so that reduces to £45.1m NTAV. That’s slightly higher than the £43m market cap, which is better than I was expecting.
Note there is an £11.4m asset for “equity investment in associate” - which is where a group owns 20-50% of another company, it appears as a single line being the amount invested, less any impairment (very subjective). I’m assuming this is ZapMap - which is the sort of thing that could either turn out to be worthless, or very valuable, we just don’t know which at this stage!
If we write that off (since it is loss-making), then NTAV drops to £31.6m, still not bad for a £43m market cap, and I am taking a very cautious approach by valuing Zapmap at zero.
Current assets were £113m, including £35m cash and £8.5m restricted cash.
Current liabilities were £80m, so there’s a decent surplus on net current assets, this looks healthy to me, although I’m not familiar with the sector dynamics, as in how much cash & liquidity electricity suppliers generally need to have.
Overall then my scrutiny of the balance sheet is positive, GOOD looks stable and quite well financed.
Latest acquisition - this is the news today.
This is a fair size acquisition for GOOD -
JPS Renewable Energy Ltd ("JPS") , a specialist solar and storage installation and distribution business, and its wholly owned subsidiary, Trust Solar Wholesale Limited ("Trust"), a standalone distribution and procurement business based in Maidstone, Kent (together "JPS Group" or the "Acquisition"). The Acquisition is on a debt-free, cash-free, basis for an initial consideration of £7.0 million (the "Initial Consideration") with further deferred consideration of up to £6.75 million, payable in cash over a two-year period (the "Deferred Consideration"), subject to certain performance conditions. Together, the total maximum consideration is £13.75 million (the "Total Consideration").
Payment of the £7.0m initial consideration is split -
Cash on completion is £3.7m,
New GOOD shares, 1,322,000 notionally priced at 250p = £3.3m (this is a 7.8% enlargement of the share capital)
Of these new shares, 842k are being sold by the vendors of JPS, presumably to institutions, at a discount of 9% to the market price. You might validly ask why the share price mysteriously fell sharply in the last fortnight?
The balance of 422k vendor shares will be subject to a 12-month lock-in.
The brief trading performance figures given for JPS look pretty good, it seems to be a proper business, making profits -
For the financial year ended 30 April 2023, JPS's solar and storage installation division reported revenue of £9.8 million and profit before tax of £0.5 million and is currently on track to deliver revenue of £9.7 million and profit before tax of £1.0 million for the year ending 30 April 2024.
Paul’s opinion - please bear in mind this is my first review of GOOD shares, so based on only limited knowledge.
I actually quite like it. The balance sheet support is key for me, because my main concern is that profitability seems so volatile - a large profit in H1, most of which is then being lost in H2 2023.
It’s a horrible sector too - trendy ideas tend to attract wild valuations, but often turn out to be completely unviable businesses - Pod Point group (LON:PODP) was a good example of this.
Also, electricity suppliers seem to operate in a boom or bust sector, where mistakes with hedging (or not) can be ruinous. The Government seems to be terrified of more suppliers going bust, hence might be allowing them to make super-normal profits in the short-term? Hence why I just think it’s impossible to work out (unless you’re a sector expert) which ones are worth backing, and which ones avoided?
Given its decent balance sheet though, I think GOOD is something that might be an interesting punt, so for risk-takers, I can see why this might appeal. Hence I’ll push the boat out a bit, and go AMBER/GREEN.
Graham’s Section:
Tpximpact Holdings (LON:TPX)
Share price: 41p (+4%)
Market cap: £38m
TPXimpact Holdings PLC (AIM: TPX), the technology-enabled services company focused on people-powered digital transformation, provides an update on trading for the three months ended 31 December 2023 ("Q3").
This trading update is in line with expectations.
Paul covered TPX in September, providing some remarks on a debt-reducing disposal (value: £7.5m).
In simple English, this is an IT consultancy serving the public sector, private sector and “third sector” (charities and NGOs).
Key points from today’s update:
Q3 like-for-like revenues up 32% to £20.2m, YTD up 25% to £61.8m.
Net debt further reduces from £12.8m to £10.7m.
Leverage multiple falls below 3x, and TPX “comfortably satisfied its banking covenants”.
3x is the magic number for the leverage multiple for most companies. Having crossed below that threshold, TPX’s lenders (HSBC) can hopefully breathe a little easier.
Outlook for FY March 2024: revenues of £80-85m (like-for-like revenue growth 15-20%), adj. EBITDA £4-5m.
Outlook for FY March 2025: like-for-like revenue growth 10-15%, with further margin improvement. TPX’s committed/backlog revenues for FY 2025 are already £65m. A year ago, the committed/backlog revenues for FY 2024 were only £50m.
CEO comment is upbeat:
"Although our budgeting process is still underway, the extent of committed revenues for next year provides a solid foundation for achieving next year's targets as they currently stand, building on our impressive new win rate this year and the successful execution of our strategy and three-year plan. The outlook remains positive, irrespective of the short-term uncertainty that may occur due to a general election, and I am grateful to all our people for their efforts and commitment to our goals and values."
Graham’s view
I tend to shy away from this sector (IT consultancies) due to low-ish margins and a sense that competition tends to keep it that way.
The forecasts at TPX reinforce this view for me, as £80m+ of revenues are set to produce less than £5m of adj. EBITDA - with real profits presumably lower than this.
The FY March 2025 forecasts are a little better with higher adj. EBITDA margins baked into estimates, but they still don’t come close to what I would consider to be a high-margin performance.
Valuation - adding on net debt, the enterprise value here is c. £50m, implying an EBITDA multiple of c. 10x for the current year and maybe 7x for next year.
I’m not sure that I would even be willing to pay that much in this sector, but perhaps TPX has some distinguishing features that could justify it?
Customer concentration - according to the 2023 annual report, TPX’s largest customer represented 6% of total revenue. It’s always worth checking for this, to understand the risk from particular contracts and customers. Customer concentration risk doesn’t seem too bad, but I’ll check it again in the 2024 annual report.
Overall, I’m neutral on this one, perhaps leaning slightly more towards a negative view than a positive one. But given the strong like-for-like revenue growth, I’ll take an AMBER stance on it.
Directa Plus (LON:DCTA)
Share price: 17p (unch.)
Market cap: £11m
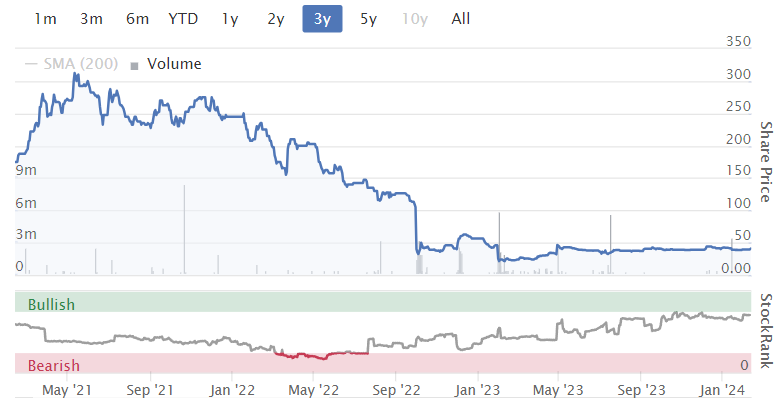
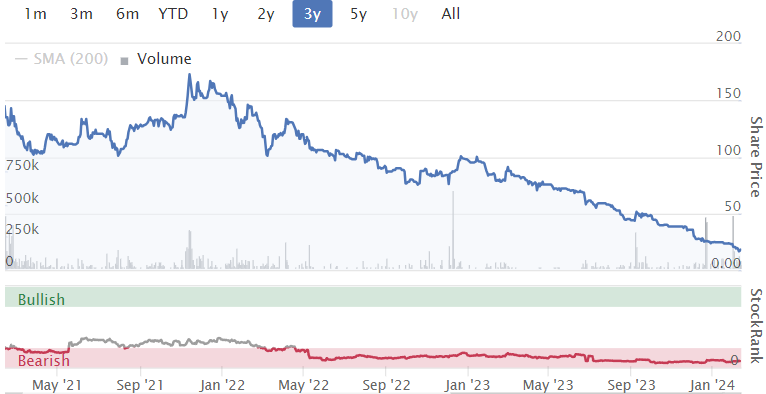
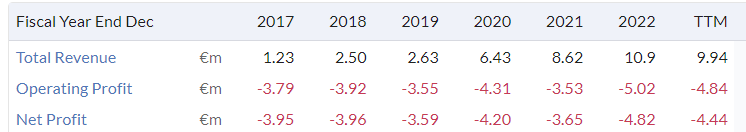
A quick look at the StockReport tells me I should probably be cautious with this one.
3-year chart:
Financial record:
StockRank:
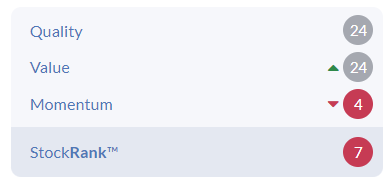
Paul covered this stock in September with the share price at 56p, giving it a RED.
It produces graphene products.The only other graphene company I previously studied in any depth was Versarien (LON:VRS). So I’m already very wary!
Let’s get into today’s trading update for 2023. Key points:
Revenues €11m (no mention of 2022 revenues, but it looks like they were about the same). This is below market expectations of €12m.
An improvement in the adjusted EBITDA loss of at least 20% from 2022, “slightly ahead of consensus market expectations”.
According to Singers this morning, their adjusted EBITDA forecast for 2023 is a €2.3m loss, improving to a €0.4m forecast loss in 2024.
Cash at the end of 2023 is expected to be €2.4m. However, this isn’t net cash. If you check the Singers note, net cash is expected to have finished 2023 around zero (€0.1m).
The company does have some impressive-sounding contracts:
Highlights in the year include a €5.5m three-year contract with LIBERTY Galati in the Group's Environmental division and, in Textiles, the Group agreed a significant expansion of its exclusive supply agreement with MC Armor in Latin America in addition to longstanding customer Grassi doubling its orders from the previous year.
And the near-future sounds promising:
With momentum and increased engagement across all verticals, and a strengthening pipeline of opportunities, the Board is also optimistic of delivering potential new material contracts in the short term. The current order book for delivery in 2024 stands at c. €7.8m, mostly made of recurring clients, further reinforcing the Board's confidence for increased traction in the year ahead.
That order book for delivery in 2024 covers just less than half of forecast 2024 revenues (€16.5m). Still a lot of work needed to hit those forecasts, then.
Graham’s view
I don’t need to spend any more time on this, as I already know that I’m going to give this stock the thumbs down. Sadly, without any meaningful net cash and with another adj. EBITDA loss pencilled in for the current year, the risk of another fundraising is simply too great to allow me to take any other stance.
It’s true that the adj. EBITDA loss is forecast at only €0.4m, implying that the company could be close to breakeven in terms of operating cash flow. But free cash flow is another matter.
Additionally, with the company missing its revenue forecast for 2023 and with the order book covering less than half of the 2024 forecast, I would be nervous about the company’s ability to hit its targets in 2024.
I’ll keep an open mind in case the situation improves during the current year. But for now I have to say that this one is a RED, in my view
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

91 comments
Does anyone know where you can get immediate notification of broker upgrades? For example, I've just spotted this on ADVFN
Jupiter Fund Management leapt 7% after receiving an upgraded rating to 'neutral' from BNP Paribas Exane. (I don't hold).
Glad to see that Poolbeg Pharma (LON:POLB) got a cold shoulder in price terms today after a ridiculous RNS saying this no profit/revenue company has a $10bn market opportunity today...
...if you fall for those lines then I've got a whole sector to sell you
Jupiter Fund Management (LON:JUP) Already mentioned and can't figure out how to delete.Re: Jupiter.A fluke or a premonition? Reiterating everyone else that we do need more fund liquidity.Otherwise noone holds much and sells on any movement higher.Come back Jupiter.All is forgiven.
I have never seen such a divergence in my 30+ years of investing/trading the US and the UK markets. It’s obvious that liquidity is very bad here and liquidity is more important than fundamentals in many occasions. But are things so bad here? Someone knows something that we don’t know?
But are things so bad here?
In a word: Yes. I only invest in the UK for diversification and currency reasons (and love of Stocko of course). To achieve over here the annual levels of return that have been typical buying and holding stateside since the GMC, you need to have very short term horizons that veer towards trading rather than investing. Or a VERY concentrated portfolio. There just aren't very many world-class companies. Meanwhile, the handling of the economy has been woeful since the 80s, and government has been downright incompetent. If you were looking in from outside, would you park your money here?
We never really had world class companies ; perhaps a few.
Personal opinions but It’s more than the handling of the economy as well-this divergence is liquidity driven-outflows from China all end up in the US and other European markets.
Hi BnB
On your point about where to park your money you might like this extensive research on global outperformers over the last c20 years.
https://www.jengaip.com/global...
Here's a snippet from slide 33 that may pique your interest:
"You may notice the five countries listed in green (India, Japan, Sweden, Germany and Israel).
These countries were the top five performing countries based on their representation on the subset list and their global stock market listing percentage.
Sweden, for example, had 20 companies that delivered a return of more than 1,000%. While Sweden's outperformers group is smaller than China's 34 companies, its stock market has only a twelfth of China's total listings, meaning it relatively outperforms China."
It's a fascinating read for those with the time.
A
Thank you abtan.
Redde Northgate (LON:REDD) Not sure if anyone follows this, but seen a few headlines about falling van prices. Not sure about badly this could affect them, but I believe around a third of their profits at the last interims came from disposal profits - could this profit stream vanish or even go into reverse, not to mention lead to a write-down in their stock? Looking at broker forecasts, I can see these have been quite steady, so just weighing up the risk of a profit warning, similar to what we saw with Vertu Motors (LON:VTU) late last year. Arguably this is all priced in given the very low valuation, but from my experience a low valuation doesn't offer much protection when profit warnings hit.
Glut of vans entering used market puts pressure on prices (fleetnews.co.uk)
Difficult to say precisely Bouden54 but if you look at analyst forecasts for Redde Northgate (LON:REDD) they are showing a 2024 drop in EPS of 11%. If you factor in the share buyback of 5% thats suggests a real 16% drop in profits. Given only a third of profitability is generated by sales it looks to me like 2nd hand van prices reverting to mean is built into the forecasts. Note also that of that £34m disposal profit only £16m was from the UK. The rest is Spain which has a different 2nd hand price market dynamic.
Some of the UK decline in 2nd hand van prices should be offset by demand for new vans which the same report shows was very strong in Q1. As Redde Northgate (LON:REDD) will have bought in advance the lease market for new vehicles looks like it should be good and pricing will reflect that. So margins up on new leases, margins down on disposals but feels like forecasts conservatively set.
Net net as long as there is good inventory management it doesn’t feel as though that should materially change forecasts.
As for balance sheet there is a surplus of about £500m net capital against the market cap of something over £700m so a lot of room for error there given the PER is also just 5*.
Redde Northgate (LON:REDD)
i think we are deffo finally starting to see fall in van prices now as evidenced by linked article - not sure how far we are towards bottoming out though - i suspect supply is probably still much tighter than for cars. anyone holding redde should have been well aware that they haev had mini windfall in this regard they should expect not to continue. Note link3ed article only suggested 6% fall in used prices so unless there are further falls imho thats still holding up quite well.
Note redde said in last annual report that they had carried on depreciating as normal - but now had to change tack slightly as vans had reached the point where it was obvious they were worth more that book value - this wording suggests they have still been conservative with regard to depreciation rate albeit that is changing - note per page 34 of annual report these changes are actually expected to benefit 2024 profits still factoring everything in - with that reversing in 2025 and 2026.
Note they also mitigated by leasing more as well - perhaps they may benfit from that plan if there is over supply in next 18 months - if they can swap from leased back to onwership if there is later over supply.
Personally i have always thought at some stage perhaps £30 mill may depart then bottom line and am probably still of the opinion there may be a hit at some stage that lowers the projections - in that regard they have been doing well to win new business so i think they are still in a very strong position unless the numbers go dramatically wrong ref vehincle prices. Board here seem ultra switched on too - i dont think they are the sort to bury their head in the sand. I suspect the market is factoring in fall in used prices at some stage anyway even if they are not forecast - so imho its semi in the price anyway - albeit with their current debt levels perhaps there are 2 reasons for lowly rating
Company does update periodically on their website and those numbers were updated 20/23/23 and consensus expectations then were £172 mill undelying pre tax profit.
In summary there could at any stage be hit withn normalisatioon of prices but imho thye have enough in the tank for that to not be an issue if it is happening about now and not already factored in.
- so easy cofmrtable hold for me (oopo time for egg on ones face ?)
hi rmillaree - Analyst forecasts for Redde Northgate (LON:REDD) look they have already factored in a fall in 2nd hand van prices - as I say the EPS next year comes down about 16% in EPS real terms so unless there is some other problem we are not seeing I actually expect the company to beat current forecasts.
Debt levels are moderate against Asset values £750m vs £1.23bn (so a whopping £500m capital surplus) and as you say the company depreciates conservatively. If the Accountants and auditors are telling the company depreciation is too conservative I'd be pretty comfortable that net capital is actually quite a bit higher than the £500m at half year as well.
Has Iofina (LON:IOF) found a bottom? I was struck by the bottom pattern and retest that Iofina (LON:IOF) seems to be making so I thought I'd look a bit further. Iofina (LON:IOF) doesn't meet my criteria for stock rank so I needed to read a good story to go with the price chart. Reading the most recent company guidance they are forecasting a 13 to 22% uplift in production volumes in H1 2024 compared to H1 2023. In addition the price of Iodine has stabilized at $65+ and is forecast to rise over the next few years. There are other potential positives in the update. On this basis I've decided to start a position today.
You can see from the chart that there have been 2 tests of a strong support line. It will be interesting to see if the retest of the breakout holds.
I know there are a few members in here who have been following the company for a while. I'm interested to hear any comments.
Interesting to see Jupiter Fund Management (LON:JUP) up a nice tick today, can't see any news updates and volume when I lasted checked wasn't above the daily average so can only put it down to the Graham Neary effect.
I posted on Augmentum Fintech (LON:AUGM) at 89p when they issued their results on November 28th. I also bought then but sold inJanuary on the fast 25% gain to 110p . Now, surprisingly, the share price is back to just 98p and I’ve used some of the proceeds from selling Good Energy (LON:GOOD) today for a second bite at the Augmentum Fintech (LON:AUGM) cherry.
AUGM issued their latest fact sheet today. Here it is:-
https://augmentum.vc/wp-conten...
All the plus points for AUGM in that November post still apply, but with the discount to NAV at 38% not quite as extremely crazy as the 41% discount then.
Worth the reminder as to why that 38% discount is crazy. While NAV has RISEN well over 30%. the share price has fallen over 30%! The top 3 holdings alone are worth more than the current Augmentum Fintech (LON:AUGM) market cap.
For any looking for a low risk but potentially quite a high reward investment opportunity then Augmentum Fintech (LON:AUGM) is WELL worth checking out. There’s also a good chance for those who prefer trading to buy and hold, of another quick 20% or so gain now the share has retreated from 110p to 89p. I’ll be more likely to hold this time in case of news ahead that sends the share price much higher. e.g a disposal above NAV or effective corporate action to try and reduce that far too wide discount. Other sectors like REITS are now seeing amalgamations.
Here’s the paste of my November 28th post.
“I bought Augmentum Fintech (LON:AUGM) at 89p today after their very encouraging results.
https://www.stockopedia.com/sh...
Since IPO in 2018 AUGM has had an unbroken run of NAV increases, though the latest increase to 160p is small. Yet the share price has gone from the biggest premium of any Investment Trust at one point to a now big 41% discount! And if stripping out the £58 million cash the Discount is 51%. So while NAV has gone up consistently the share price has gone down consistently.
Note that AUGM have £58 million in cash and no debt. Their top 3 holdings, TIDE, GROVER and ZOPA and the cash are above the current AUGM market cap, with no value at all attributed to their £125 million of other investments.
So far AUGM have had 5 realisations since IPO and all were above the holding value.
They have been buying back shares to try and reduce the discount. They can’t issue new shares while AUGM is at a discount but the bought back shares will be held in treasury to potentially be reissued if AUGM goes to a premium again. NO chance of that for a good while but very good chance of the discount narrowing from current undeserved extreme level.
This is yet another example of Investment Trusts being SO out of favour with discounts at near record levels. The tide will turn at some point, and AUGM looks yet another oversold Investment Trust worth checking out.
Good post - Chrysalis Investments (LON:CHRY) is another one, and not dissimilar in many ways - large discount, dominated by 2 or 3 large fintech holdings (Starling, Wefox, Klarna) which by themselves largely cover the market cap. Couple of good broker notes recently which outline the investment case.
Hi Ken (Kenmitch), although I've been a Stocko subscriber for several years, following on from Company Refs nobody will know me here other than yourself and sevenccc . Although on Stocko I'm george54 you will remember me as grecian from the MW site where for over 20 years or so we enjoyed many outperforming periods finding numerous winning growth shares
Anyway just to say that by total chance I also bought AUGM for more or less the same reasons you mentioned so was surprised when I found your post. Fwiw other recent purchases have been Paypoint, Future, Facilities by ADF, Serica Energy (after the recent price fall) SUPR and a top up on EBOX .
This post is just to introduce myself to you under a different name but as I don't want to bore everyone I won't say anymore other than agreeing that the Stocko facility is and always has been first class .
Great to see you here Grecian you were always top table on the old MW site with your pearls and investment track record look forward to some more rambles when time/ideas permit your end.
Grecian/George54.
Thanks for your post. Very pleased to see you are here too and hopefully posting from time to time if you find any tempting investments worth us checking out. You posted on plenty of big winners on Mike’s site, but I see that you’ve only posted twice on Stockopedia.
Guess you’re here more for the info similar to the old Company Refs and Sharepad like the brilliant imo stock pages. But there are also some excellent threads here (albeit much less user friendly than on Mike’s site).
e.g Charles Mitchell has started a new monthly Investment Trust thread that is beginning to see increased interest.Here’s the link for it.
https://www.stockopedia.com/co...
This thread follows on from an earlier one that saw 199 ofyen good quality posts.
I’ve also tried to get a BARGAIN thread going but so far with not much follow up.
And just this week Stockopedia staff writer (previously she was at Investors Chronicle) Megan Boxall has started a new thread for larger Companies. None of the threads here get the interest and follow up that the excellent Small Company Value thread does, but interest is growing.
I got called away and didn’t quite finish the previous post.
Here’s what would have been the final bit:-
George54 and anyone else reading this might well know all that! But it seemed worth posting it as none of the other Stockopedia threads get anywhere near the number of viewings or replies the Small Cap Value Report gets. So a bit more advertising (including by Stockopedia staff) might help other excellent threads get more recognition.
Hi Ken, good to hear from you and yes I will post from time to time when a promising early stage growth share comes to light. Also thanks for sending the Charles Mitchell new monthly investment trust link as well.
However it would be great if the BARGAIN thread gained interest as we all made very good money from it over the years on Mike's site. Although I'm an unknown here I'd definitely recommend that subscribers follow the/your thread as it certainly proved itself to be very profitable for many of the MW site members.
Filtronic (LON:FTC)
I just love these announcements from these small caps (although to be fair the company seems to be growing by the minute).
Filtronic (LON:FTC) announces that Mr and Mrs Dixon hold 38.5m shares.
Great , but you could have emphasised that basically they have sold about 3m shares!
Thanks Paul for the detailed Good Energy (LON:GOOD) analysis today. I was already dithering about selling and though I might regret it I have sold today. I realise few are interested in our individual trades but the reasoning why might be perhaps?
I bought Good Energy (LON:GOOD) after Small Company Sharewatch coverage last October. The key reason for buying as Investec’s forecasts of pre tax profits doubling is very year which if proved to be even passably accurate meant the share was s steal. The Investec forecast was £2.3 million this year, then £4.2 million, then £7.4 million and then £15.2 million.
The evidence from the two trading updates since, including today suggests that those forecasts could be pie in the sky. There are so many alternative shares and Investment Trusts to go for at present which when buying and holding I’m far more confident about prospects than I am for Good Energy (LON:GOOD) soGood Energy (LON:GOOD) went on my tactic that so often works.
I.e SELL if having doubts and SELL on a profits warning or disappointing update. That way the bulk of the portfolio contains winning investments and not too many losers.
Part of the Good Energy (LON:GOOD) proceeds I’ve used to buy Augmentum Fintech (LON:AUGM) again at 98p. . More on why later this afternoon.
Good Energy (LON:GOOD) £13.75m acquisition of solar parts distributor and installer JPS teaches this investor never to have a lie in – even at half term.
Growing solar and heat pump installation capacity is a core components of Good Energy (LON:GOOD) strategy to grow its energy services business - enabling households to take control of their energy generation, usage and cost. This in turn reduces Good Energy (LON:GOOD) relative exposure to energy price volatility compared to being a traditional energy supplier/broker.
Initial consideration of £7m with £6.75 deferred and contingent consideration to follow, for a business expected to generate PBT of £1.3min in the year to 30 April 2024 (PBT = £0.6m 2023).
Assuming a tax rate of 20%, this suggests a PE of around 13x for a business that has grown PBT by 116% this year.
Management state the solar market is booming with the solar installation market growing 38% in 2023.
Acquisition Positives
Acquisition Negatives
Cheers for the clear summary of positives and negatives.I've seen Good Energy (LON:GOOD) on the most viewed list a fair bit recently.Decided to buy from Ken today.A bit early this morning though it's a sell off nonetheless the last week.
Hopefully they can carry on buying great, little solar companies growing profits at speed.But not too small as i was wondering about the heat pump acquisition (although heat pumps do seem further away from mass adoption than ever currently) and the previous one as they seemed too tiny to be able to produce any meaningful revenue.
A lot of moving parts in this business though.Wil go with slightly larger Enphase Energy (NMQ:ENPH) solar inverter etc..manufactuer purchase for the solar section of the portfolio.Enphase Energy (NMQ:ENPH) CEO seemed to think the worst of the solar downturn wil be past for them with solar installation being so rate dependant.So i'm surprised Good Energy (LON:GOOD) 's new acquistion is doing so healthily currently.Perhaps due to them focussing on the 'higher end' installations and those folk who are much better off and can pay outright?Will be interesting to see if they turn out to be a bargain or not!
Liked the update from Journeo (LON:JNEO) this morning. Fridays move must have been some folk getting out ahead of the TU for whatever reason. Odd decision in my view as it is hardly expensive and trading momentum has been good so not really a “hot stock” where you might see a sell on news psychology.
Anyway all in-line with recently upgraded forecasts but the bit I like is the strengthening recurring revenue statement and the level of visibility that appears to be providing management. I’d like to know what that is in nominal terms mind you. Net cash almost 20% of market cap too with no debt so plenty of firepower.
Next 12 months for me is watching the Nordic region and any push into Germany/France, plus how well the US business grows. Forecasts look light to me, probably conservatively set but thats fine. With a 24p eps and net cash of 50p you’d like to think these can trade closer to 375p on 13* earnings + net cash so happy to hold here or maybe buy a few more if an opportunity arises.
I suspect you will find that Friday's fall was less to do with 'some folk getting out ahead of the TU and more to do with Downing selling down their stake prior to closing their fund.
There's a lot going for JNEO with organic and acquired growth, new products and markets, significant market opportunity, increasing recurring revenue and a management team capable of capitalising on all this.
didn't look like enough volume for that on Friday to me Charlie but let's see if Journeo (LON:JNEO) release an RNS showing them reducing. From memory I don't think there is any major time pressure on Downing so if I know Judith she will wait for an opportune time to offload to another institution if possible.
Good interview Paul and Graham.
A sea of green (European Markets)
And then we have a red - it’s the FTSE100!
From this week edition of the Economist. European main indices, past 10 years.
What do you expect from a market dominated by old economy stocks. I do remember the DAX being well below the FTSE 100 , and now it is over twice as that.
That's because the DAX is a total return index, whereas the FTSE 100, and most other indices, aren't. Adjust for that and the long term returns are very similar.
I am aware of that.
But a 3-4% dividend yield in 10 years it just cannot accumulate 150% return.
No, it’s not as much as 150%. I just pulled the two charts up in Bloomberg - DAX v TUKXG - and over the long term they track each other quite closely.
DAX 2011 6000
FTSE100 2011 6000
I don’t know which charts are you looking.
In the early 2000s was even below the FTSE100.
DAX has outperformed the FTSE100 in any way you look at it over the years.
FTSE100 is just an old economy stocks index that offers limited growth. Try to compare its performance as well with the SP500 , DOW and the NASDAQ over the years.
All the best,
Why has the FTSE100 been so bad. One possible reason is paying for the old legacy pension deficits. Reach for example have devoted most of their profits in the last year in paying down their pension liability. See BT as another example.
Why has the FTSE100 been so bad? Pension liabilities?
Pensions might be a handicap but they are a symptom, not the cause. The issue is that, with only a very small number of exceptions, the FTSE100 is made up of old economy, zero to low growth companies. Be that telecoms suppliers, listless retail banks, insurance dinosaurs, tobacco firms etc etc. Any high growth winners, eg ARM holdings, get snapped up by bigger international fish before they reach the main UK market. It's not the market's fault, you've got to look at government industrial and education policy over the last 40 years and ask why we have such a small presence in semiconductors, software, and now renewable energy. It's not as though we've arrived here in 2024 to be surprised that these industries are thriving. It's been obvious for decades.
Also and this was said by Nick Train in an audio interview somewhere around 4 months ago... the UK investors liking of s dividend makes it difficult for companies to proportionally reduce the divi which in turn reduces the ability to reinvest. Actually think this is a key point when you look at Buffet while he likes stocks that pay dividends he also wants growth and a moat and I Apple a large dividend is not necessarily needed.
So you don't have to go to twitter as well:
MrContrarian
No Smallcap Sweeps this week.
I'm in Prague,
Hope he has a nice time there.Never been myself, but it's on the list!
definitely recommend it, great place!
Bloomsbury v Avingtans v Bank Georgia
Any others .
Following bloodbath last week clearing the decks of smaller holdings sat on a bit of cash in pensio.n .
I’m at a short list of 3 to top up .
Any other suggestions
My 3
Bloomsbury - looks at top of its range and I wouldn’t normally buy at top of range but it looks ready to move up a level and it’s such a great company . News flow is all about it’s authors dominating the bestsellers plus Harry Potter plus education . I’ve a decent position already but sleep at night 10/10 factor .
Avingtrans - keeps dropping and it’s the wrong price but hard to see any catalyst unless they sell one of their companies . Market doesn’t know how to value it and the medical division is going to suck out cash for 2 years . Think it will be double this price in 3 years .
Bank of Georgia - has come off its highs, and Georgia capital is at its highs which is weird . Big dividend but don’t really like holding bank shares so probably doesn’t fit the bill .
other option is sit back and relax with a bit of firepower .
Must admit despite the highs I think Bloomsbury might break out into the 500s soon .
Morning planetX
As you may know Bloomsbury Publishing (LON:BMY) and Avingtrans (LON:AVG) are top 5 holdings for me. The other largest positions being Volex (LON:VLX) Sigmaroc (LON:SRC) Jet2 (LON:JET2) and Brickability (LON:BRCK.
Back to your question, I agree with your view on Avingtrans (LON:AVG) . It is not a share in my view that lends itself to being valued on earnings multiple or other conventional metrics. As you say the market views it is a bit of a conundrum and it is unlikely that the share price will progress until there is a disposal or positive news regarding its medical division or interest rates.
Regarding Bloomsbury Publishing (LON:BMY) I am of the view that there is likely to be a further upgrade prior to the prelims in May, just my opinion. I last added at 376p a month or so ago on the basis that it is not expensive even at the current valuation and it has £39m of cash looking for a home. Will Avingtrans (LON:AVG) and Bloomsbury Publishing (LON:BMY) be worth more in 12 months time, I think so, but I am biased.
As for me I am using dividends to build positions in Kitwave (LON:KITW) Hollywood Bowl (LON:BOWL) and Michelmersh Brick Holdings (LON:MBH) in a 26 share portfolio.
All the best
XPS Pensions (LON:XPS) - I would say is in a similar situation - having been sold off from its highs of 236p. Languishing, with c5 weeks to TU. Recent buys by management at 204p+. Mentioned favourably by Phil Oakley in a recent podcast on Twin Petes.
Kier (LON:KIE) and Afentra (LON:AET) are two of my latest buys. Both look very cheap and with experienced management.
Obviously DYOR.
All the best
Yiannos
Kier is uninvestable for anyone from t’posh side of Sheffield as they chopped all our trees down in the infamous tree cutting scandal few years ago .
Afentra I’ll look into buy oil exploration in Africa probably a bit out of my circle of competence .
Kitwave has been on my watch list for ages .
I might wait for Transense or even better do some hard yards and go take a look .
Hi planetx,
I tend to look at numbers and FCF growth in order to make my investment decision. Who is cutting trees and where is irrelevant for my financial analysis.
Kitwave (LON:KITW) and Transense Technologies (LON:TRT) cannot see where the growth is coming from. Transense Technologies (LON:TRT) is very small and illiquid .
All the best
Yiannos
It was tongue in cheek regarding kier cutting down all Sheffield trees .
It was quite a scandal made worldwide news and to be fair kier was pretty morally bankrupt in their dealings so not for me on a steel city principle (made in Sheffiekd)
Transense is tiny yes, It’s entire market cap is covered by an existing royalty agreement with Bridgestone and their other technology looks to “have legs” . Bit jam tomorrow maybe but so long as the Bridgestone royalty continues I have it down as totally underpinned on future earnings .
Afentra (LON:AET) interesting choice. Lots of investment going into Angolan O&G in the next 5 years.
Kier (LON:KIE) the Phoenix rising from the ashes then.
£KIER
It was quite a scandal made worldwide news and to be fair kier was pretty morally bankrupt in their dealings so not for me on a steel city principle (made in Sheffiekd)
with regard to any company that messes up - did they apologise and is it different management running the business now? would have thought thye would relish teh chance to throw old management under the bus if its new peeps in charge?
Must admit i was hoping for slight pullback on Kier price recently as i could potentially add subject to some fuerther research - price seems to be holding up too nicely though doh - it does look cheap albeit for companies like Kier over the years they have so often blown up at some stage when times get tough - so deffo invest at your own risk warning here with this kinda share however cheap it looks (looks like this has previously happened with this same share)
Err, I'm fairly sure that it wasn't Kier who cut down the trees in Sheffield. From memory it was either Mowlem or Amey I think - most likely Amey as I think Mowlem had hit the wall before those trees went.
In my defence it was planetx who said that - i simply asked my question based on the post planetx made - as ever with stuff like this its probably passy the parcel - i know Kier probably did take some stuff on from Amey - so perhaps they were left holding the tree stumps. Lets hope they didnt have the contract for nottingham !!! - quick look on googlke seems to have peeps blaming the council.
Afentra (LON:AET) has tickled a few fancies recently. Several people had it in their Top Five holdings going into 2024. High risk high reward with exponential increase in expected EPS.
Georgia Capital had lagged the rise of Bank of Georgia over recent months.
The facts: Bank of Georgia (LON:BGEO) -5% YTD, but Georgia Capital (LON:CGEO) +10% YTD.
For the longer period their share price is quiet similar way (beautiful uptrend).
Charles
I’ve held both for ages
Georgia capital at its highs past month
Bank of Georgia has retreated
So I see it differently, Georgia capital still playing catch up though .
Yes Georgia Capital (LON:CGEO) is just playing catch up Plantex.
TNAV will be around £20-£23 so it is still trading at a 50% discount to NAV which in my view is just way too high a discount for the quality of the investment businesses. None of it is “blue sky” they are all strong revenue generating utility type businesses that have real tangible value so there isn’t really any argument about whether NAV is real.
In more normal times the discount will be 20-25% so it can rise to anything up to £17 even with Bank of Georgia (LON:BGEO) treading water. Has been a nice slow rise upwards over last couple of months which is what I prefer to see in long term holdings.
I don’t hold many banks but I do own and still like Bank of Georgia (LON:BGEO) - been a long term holding for me which has done well. I think the dividend on invested capital is now around 35% which just shows the value of compounding over time! It has a very high level of “own capital” relative to share price and a much better ROTE than most.
I was looking at Bloomsbury Publishing (LON:BMY) this weekend, it has been a stock I've held from time to time, especially when my daughter was hooked on Harry Potter (unfortunately it's now Netflix, but she has been reading some Angie Thomas recently).
I really really want to buy in, especially given the sucess of Sarah J Mass, but my main concern is valuation. I can see in this market the price getting beaten up even on the back of an inline TU.
I've been buying Smiths News (LON:SNWS) for divis and I can see the price going up double? That would still yield around 5%.
Small positions in Supreme (LON:SUP) (I think the management here are looking to make this a much bigger company) and British American Tobacco (LON:BATS) for divis and I think a big bounce when people cotton on to the fact that without doing anything there's a massive generation of people getting hooked on nicotine via vapes (also think they will make bigger investments into the cannabis space).
Nexteq (LON:NXQ) I've held on and off and at the recent lows could not help myself at sub £1. Ditto with Card Factory (LON:CARD) 90p feels too cheap. But how long do we have to wait for the market to realise?
"how long do we have to wait for the market to realise". The answer to that is when Teleios decide to stop offloading into the market. Card made several concerted efforts to go through £1.10 but Teleios offloaded into the rise. I think they have traded it badly because investors take the view that there is easier money elsewhere. Until Teleios make it clear exactly how much they want to hold going forward it will be given a wide berth.
Also a big holder of Bloomsbury Publishing (LON:BMY, my second largest position only to Seplat Energy (LON:SEPL), a company id encouraged everyone to take a look at. Due to its geographical location in Nigeria it's often avoided by many investors and written off instantly.
For me it has a number of short to mid term catalysts that will very likely cause a significant re-rating of the share price. It currently trades at 143p, having made a healthy 27% gain over the past year before dividends. So what is going to cause the share price to move in my opinion:
A long standing dispute around the 1.3billion divestment of Exxon Mobil assets to Seplat Energy (LON:SEPL) appears to be on the brink of resolution. A government oil official claimed last week the deal was 98% resolved and would be completed in the coming days. They have stated this resolution could lead to a TRIPLING of turnover revenues.
The dividend is due a significant uplift following strong price movements in the past two years. It was previously 3cents per 1/4 but this could comfortably move to 4 or 5cents not to mention an overdue special dividend.
The Nigeria listing of seplat continues to see the share price increase at a much quicker rate than here in the UK, it is valued at 238p using the black market usd rate, a 60% upside to the UK listing. The gap here has widened a lot in the past two months. Are locals seeing something UK investors aren't?
The ANOH gas plant should be up and running this year adding some diversification and additional stability to the revenue stream.
Politically Nigeria seems stable enough at the moment, it's economy is doing well, boosted by huge population growth. Seplat are working with local communities to reduce theft and add jobs. It is of course still very corrupt compared to many western countries but I believe the geographical risk is already in the price.
Seplat Energy (LON:SEPL)
Is there any impact that the Nigerian currency has lost almost all its value against the GBP in the last year?
Thanks
Yiannos1 I was just thinking the same, given the reaction to PZ Cussons (LON:PZC) who operate heavily in Nigeria.
That said, if you believe that the currency issues are behind itself (or it probably won't go lower), is there a double bounce that might be had here?
Hi Yiannos,
In short, not really, as all oil sales and even divis are in USD, so the decline in the Naira hasn't been reflected in Seplat Energy (LON:SEPL) profits.
However, previously there had been a disparity between the actual exchange rate and black market rate for USD in Nigeria. As of last week the exchange rate now trades in line with the black market rate as the FX demand backlog has almost been cleared. I have read that this has been almost ten years in waiting and should mean FDI and portfolio flows should start to return, which can certainly be viewed as another bull signal for the share.
Thanks Ben interesting indeed.
The currency devaluation certainly had a serious effect on fast growing Airtel Africa (LON:AAF)
“Revenue in constant currency grew by 20.2%, with Q3'24 growth
accelerating to 21.0%. Reported currency revenues declined by 1.4% to $3,861m.
In Q3'24, reported currency revenues declined by 8.3% as currency devaluation
(primarily the Nigerian naira devaluation) continued to impact reported
revenue trends.”
Presumably Seplat Energy (LON:SEPL) sell in dollars rather than Naira?
That is correct.
Last time I checked the oil price was still in dollars.
But operating in a country where the currency lost almost all of its value against the pound I wanted to know if any implications can be foreseen ; taxes, payrolls , capex etc.
Life of assets? as well is important.
If you are aware of these I am very much interested as Seplat Energy (LON:SEPL) does look as an interesting investment.
All the best
Hi Yiannos, I would not wish to comment on the specifics of currency implications as i do not know for sure the answer. However, life of assets I can comment on
- SEPL's onshore assets have 25 years+ of life, which interestingly is multiples of many opportunities in the North Sea, and without the complexity. The new MPNU shallow water assets are admittedly shorter in reserve life. If you want some additional reading (it's paid for by seplat so account for that) then have a read of the link- https://www.seplatenergy.com/m...
The Nigeria listing of seplat continues to see the share price increase at a much quicker rate than here in the UK, it is valued at 238p
Seplat Energy (LON:SEPL) Hi Ben, this sounds like the shares are not fungible. I don't know much about these situations - I do remember a similar thing with Beximco shares. The idea being that if the shares are fungible, they will stay closely aligned. With Beximco it kind of sounded as though the UK listed share didn't have the same ownership rights (maybe no ownership rights, ie not actually considered to be a share holder) as the overseas listing. There was a big price difference, and as far as I'm aware the price difference has persisted. Do you know about the fungibility of the Seplat shares? or if this has any bearing on UK holders and the likelihood of it destroying any potential arbitrage between the prices?
cheers
Matt
Just to add - Can the currency movements cause them to move out of line?
Georgia Capital is my largest holding and I also hold Bank of Georgia. Bank of Geogia only represents 31.4% of Georgia Capital's portfolio which to an extent explains why the two stocks do not always move in line. The remaining investments of Georgia Capital are largely in defensive areas such retail pharmacies, hospitals and clinics and medical insurance. The net asset value per share of Georgia Capital is £23.40 so their shares stand at a massive 52% discount to NAV.
On a non related SCVR topic but I hope you don't mind me asking. Has anyone tried to deal ARM shares via any of the major platforms ? Seems $ARM won't settle via QUEST/CREST so punters cant access the stock. Any thoughts appreciated
Hi grout123
Yes that is the case with Arm Holdings (NSQ:ARM) , unfortunately.
HL tells me it is because 'there are additional charges levied beyond the normal dealing commission and foreign exchange charges.'
Regards
Howard
You cant trade via Hargreaves but apparently you can via AJ Bell. It seems ridiculous that a UK citizen cant trade in the countries biggest tech company via the countries biggest retail platform. Surely there must be away round this even if HL have to charge more to transact a trade. Is this another sign of the state of investing for UK citizens?
We've just published our latest instalment of the Week Ahead - our destination for large cap analysis, economic musings and international companies. Join the discussion via this link: https://www.stockopedia.com/co...
Excellent podcast again, Paul. Thanks for doing them in addition to the enormous SCVR output
Many thanks Paul.
In Graham's interview, there were a number of reasons why risk tolerant investors can be constructive on UK smallcaps, namely:
1) Cost of capital set to fall (re lower costs of borrowing & raising new equity/debt)
2) Institutional demand should rise as fund manager redemptions reverse to become inflows.
3) Today's smallcap M&A spurge will provide fresh capital for fund managers to reinvest (re flywheel effect)
4) Likewise, more & more companies are announcing stock buybacks - which again should lift investor cash balances for reinvestment.
5) Smallcap valuations are historically cheap - both in absolute terms & relatively vs largecaps.
6) Indeed there currently seems to be fewer director sells than normal - suggesting a positive risk/reward environment.
Many thanks Paul for posting this interview on here . Great to listen to Graham and his views on the market and stock ideas. A former stock analyst indeed !! Always enjoy listening to the Vox interviews as Paul Hill has much to add to any interview .
Another REIT merger announced this morning - Tritax Big Box REIT (LON:BBOX) and UK Commercial Property REIT (LON:UKCM) this time. It's a done deal with Phoenix and Investec on board.
Any thoughts on #good acquisition. Specifically a 9% discount placing for just 3% equity and why the £34m cash balance wasn’t used?
You are looking at last years results cash balance. Estimated cash balance for current financial year is £19m. Also they have used available cash for the acquisition.
[I hold] The Good Energy (LON:GOOD) acquisition works for me. The purpose of raising the companies whole market cap in cash by selling the generation assets was to allow the business to develop its clean energy service activity that was less regulated and potentially yielded (much) better margins. I bought on the basis it seemed to have a competent management team and would now be able to compete without the funding constraints of other small competitors (although I see Eenergy (LON:EAAS) has also cleared the decks by selling over half its business for cash, apparently with the same objective).
The earnings volatility is a concern but at least it landed the right way for once! I suspect the markets will be a bit less volatile over the next few years, provided no major wars break out (hmmm). I also suspect that as they are mostly contracting to buy and sell electricity it should be possible to hedge that ubiquitous commodity to match buy and sell obligations. As the business develops I imagine they may be better able to forecast the amounts to hedge.
I am also slightly concerned at the slightly woke appeal of the business because, personally, I would not be keen to buy a heat pump or solar panels, at least at this stage.
Finally I am delighted the SCVR team have included it in their commentary. It is indeed a difficult business for an outside shareholder to follow in detail and having their thoughts on developments will potentially be of great value. I expect it to be quite volatile but hopefully it will continue to make profits. If things go well it could be a multi-bagger.
Where is that from?
They are the consensus forecasts which you can get from the economic data calendars, eg: Trading Economics
Daily Mail
On the inflation side, Stay Humble, this is entirely because a very large deflationary figure of -0.6% was recorded last January and is falling out of the calculation. Chart below. The month-on-month forecast is actually -0.3% for this January. Over the last six months UK CPI is comfortably below 2% annualised. The two BOE MPC members who voted to increase the UK base rate the other week are lunatics, in my humble opinion.
Hi Chris where did you get the above bar chart out of interest ?
Hi this was from Trading Economics which summarises lots of good economic data across several countries