Small Cap Value Report (Mon 12 July 2021) - SAG, STB, QUIZ, ULS, PHTM

Good morning, it's Paul & Jack here with the SCVR for Monday.
Disclaimer -
A friendly reminder that we don’t recommend any stocks. We aim to cover notable trading updates & results of the day and offer our opinions on them as possible candidates for further research if they pique your interest. We tend to stick to companies that have news out on the day, and market caps up to about £700m. We avoid the smallest, blue sky type companies, and a few specialist sectors (e.g. resources, pharma/biotech).
A central assumption is that readers then DYOR (do your own research) and discuss in the comments below. The comments, incidentally, sometimes add just as much value as the articles. We welcome all rational views, whether bull or bear!
It's helpful if you include the company name or ticker within reader comments, otherwise some readers may not be aware of what company you are commenting on.
Mello Monday
Reminder that our favourite fortnightly online investor show is on again this evening. Full details here.
Agenda -
Paul's Section:
Science (LON:SAG) - another positive trading update from this interesting owner/managed technology group. I like it, valuation still looks reasonable, and all 3 divisions are trading strongly.
Quiz (LON:QUIZ) (I hold) - Q1 update shows strong growth against lockdown 1 last year comps. Gross margins high, and net cash has grown in the last quarter. Looks strikingly cheap to me, especially when compared with online-only ITS & SOS. Problem leases were ditched last summer in a pre-pack administration, so now QUIZ is only operating from cheap turnover rent sites on short leases. Illiquid share though, so it can be very difficult to buy or sell.
Photo-me International (LON:PHTM) - good performance in H1, driven by restructuring rather than much top line growth. Strong balance sheet. The big question mark is what the long-term profit outlook is going to be?
Jack's Section:
Secure Trust Bank (LON:STB) - impairments reduced once more and profits now expected to be materially ahead of expectations. The valuation currently looks undemanding given the positive news.
Uls Technology (LON:ULS) - residential conveyancing software provider has brought in some new senior hires and made a 'transformational' disposal that gives it net cash of £24m and an enterprise value of £28.2m on FY21 continuing revenue of £16.9m. Probably worth a closer look on valuation grounds but there's little to no mention of market position or the strength of competition.
Paul's Section
Science (LON:SAG)
400p (Friday’s night close) - mkt cap £165m
Science Group is an international, science-led services and product development organisation with a significant freehold property asset base. Following the Frontier acquisition in 2019 and the natural evolution of the services operations, the Group now comprises three divisions: R&D Consultancy; Regulatory & Compliance; and Frontier Smart Technologies ('Frontier').
[Paul: extracted from final results statement, issued 9 March 2021]
Background - as usual, I’m re-reading my previous notes on the company to get up to speed -
Here on 9 March 2021 I awarded the company a “looks interesting” view, on positive results for FY 12/2021.
Here on 19 May 2021 it got an upgrade to the coveted SCVR “thumbs up” view, on a positive trading update. Like many companies, it did mention supply chain issues, but despite that H1 profit guidance was +30% on the previous year’s H1 (a strong comparator).
Other key positives for SAG are: owner/managed business (lots of skin in the game), and freehold property on the balance sheet. No dilution during the pandemic, another key thing to check at the moment.
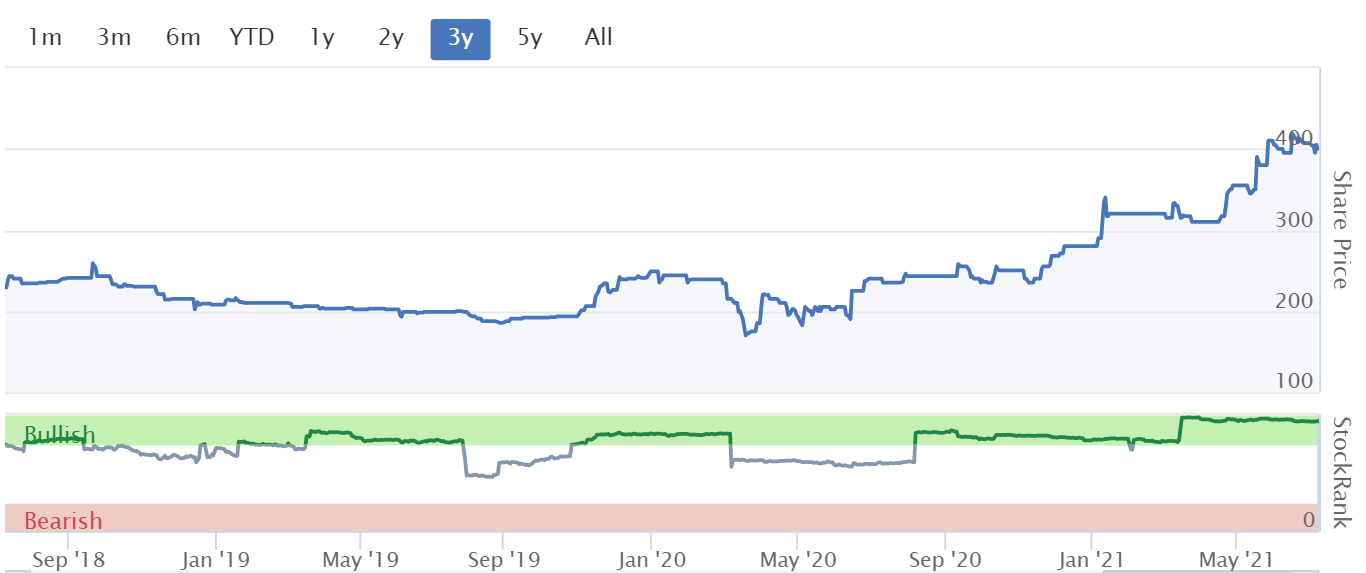
The share price is quite unusual, in that it’s had an excellent run (remember that shares doubling is normally quite unusual, we’ve been spoilt in the last year with a one-off powerful rally in practically everything). However, whereas many other small caps have succumbed to profit-taking, Science shares have remained buoyant. That seems to indicate shareholders are committed long-term, rather than short-term traders. The share’s probably too illiquid (with associated wide spread) to interest traders anyway.
.
Today’s update -
- Previously said on 19 May 2021 that all 3 divisions had a good start to the year
- “Momentum has continued” in remainder of H1
- Guidance H1 revised up again - revenue >£40m, and adj operating profit >£7m (over 40% up vs LY H1)
- “Excellent performance”, another upgrade from 19 May guidance
- Achieved despite currency exchange headwinds
- Diary date - H1 results due out in last week of July 2021
- CFO leaving at end July, “by mutual agreement”, appointed in Jan 2021, so clearly this hasn’t worked out. Unusually, we’re given a little colour on the CFO’s departure, which I like. Usually these things are hushed up -
Science Group's success is derived from its integrated organisation, with a hands-on operating management culture at all levels of the Group. After a career in significantly larger companies, it has become apparent that the role within Science Group is not aligned with Mr Vohra's aspirations.
The Group Financial Controller is taking over as CFO.
My opinion - Science Group looks to be on a roll, and still doesn’t look expensive, even on existing broker estimates. Hence increased forecasts after today’s trading update should keep the valuation reasonable.
I like it, a decent, entrepreneurial business, trading well, priced at a reasonable level. The departure of the CFO doesn't sound concerning, sometimes new appointees don't work out, as seems to be the case here.
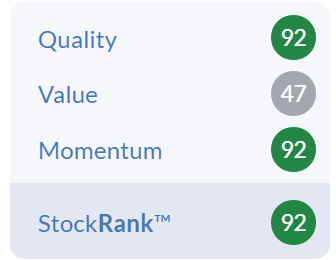
The high StockRank is reassuring -
.
Quiz (LON:QUIZ)
(I hold)
11.75p (up c.12%, at 08:48) - mkt cap £14m
QUIZ, the omni-channel fashion brand, announces an update on trading and its cash position for the period between 1 April 2021 to 30 June 2021 ("the Period").
Two factors have continued to impact sales -
- Closure of stores & concessions for some of the period, and
- QUIZ’s niche is special occasionwear - hit hard by covid restrictions
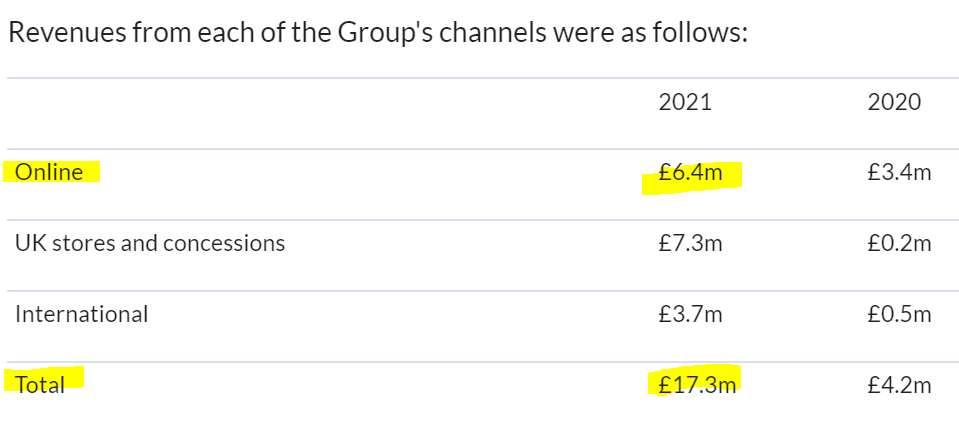
Despite this, Q1 total sales (incl or excl VAT?) were £17.3m - that’s not bad actually, and better than I was expecting. It’s a huge % increase on last year, not a meaningful comparison though, as lockdown 1 was so severe.
I’m encouraged by the near-doubling of online sales though, as that is near enough to a like-for-like comparison -
This is for quarter 1 -
Given that covid is still having an impact, particularly suppressing demand for special occasionwear, then I’m estimating that a more normal run rate might be nearer £25m per quarter, so c.£100m p.a., which assuming the sales numbers include VAT, dividing that by 1.2 to remove VAT (assuming everything standard rated), gets to c.£83m p.a. run rate of revenues. That’s a sensible sized business, doing a fair bit online, should be profitable at that level of revenues, and the market cap of £14m seems an anomaly (i.e. much too low) when you compare it with smaller online-only competitors In Style (LON:ITS) and Sosandar (LON:SOS) .
Sosandar (I hold) is growing fast, and is forecast to reach c.£24m revenues for FY 03/2022, a very aggressive forecast doubling of LY revenues. It’s been heavily loss-making in the past, would only reach around breakeven if forecasts hit this year, and is valued at £55m mkt cap.
InTheStyle is a recent float, currently valued at £117m, so has a newness premium. It’s also growing fast, and is forecast to hit c.£47m revenues this year, and make £2.5m PAT this year (also FY 03/2022). In my view ITS probably had a one-off benefit from lockdowns, hence the opportunistic float on AIM. It’s previous performance was lacklustre.
Finally we have QUIZ, valued at only £14m, yet likely to achieve revenues at least double of either ITS or SOS this year. Probably going to be profitable, given that all the store leases were ditched in a pre-pack administration last year. Hence the only physical sites it now operates are on turnover rents, and short duration (average 24 months), hence are not a millstone any more. Therefore with no problem leases any more, I think it's a reasonable thing to compare it with online-only competition, although using a lower valuation multiple to reflect sluggish/no growth.
QUIZ also has management that are more experienced rag traders than either SOS or ITS, but maybe lack the creative flair of those competitors? QUIZ isn't really a direct competitor with either SOS or ITS, but there is some overlap, hence I think it's interesting to compare their respective valuations.
Concessions - only 45 sites left, as the Debenhams ones have gone - they re-opened for long enough to clear most of the inventories held, which is pleasing. Personally I think the concessions (sections within a larger store, e.g. Dept Stores) are a bit of a distraction, but at least they get the brand out there into more locations, and are rarely loss-making.
Gross margins - good, and above both 2020 and 2019. Historically, QUIZ made strikingly high gross margins, so I’m encouraged by this. In H1 2020 the gross margin was 52%, and in H1 2019 it was 62% (pre pandemic). So being told today that both have been exceeded, is very encouraging indeed in my view.
Outlook - demand should increase further as lockdown restrictions ease. In particular I think weddings could be very useful for QUIZ, as it specialises in that area, and my thirty-something friends tell me they are inundated with wedding invitations from their friends. How long the restrictions are eased for though, is the big unknown.
Net cash - has actually gone up in Q1, from £1.5m at 31 March 2021, to £2.7m at 12 July 2021. Nothing is said about stretched creditors though, so I’m not sure how sustainable that cash balance is.
There is also an undrawn £3.5m bank facility, expiring 31 Oct 2021, but the company says it intends to renew it, which suggests the bank is comfortable with the situation (the founders are wealthy, having taken a substantial sum out in the original float).
Balance sheet - when last reported, as at 30 Sept 2020, was remarkably strong. Taking out the £3.9m intangible asset, resulted in NTAV of £18.7m, and a perfectly healthy working capital position, current ratio of 1.87 (anything above about 1.3 is strong for a retailer, the way I look at things). There’s no debt either, and the lease liabilities mostly disappeared in the pre-pack administration of June 2020.
My opinion - if you look at this share with fresh eyes, it’s an interesting special situation. Usually my investor friends just dismiss it as being rubbish, and won’t even look at the numbers! Therein lies the opportunity in my opinion.
It’s survived the pandemic, come out in better shape (problem store leases ditched), and with a strong balance sheet. There’s been no dilution since the original float, so theoretically the share price could get back to previous levels, if performance were to recover accordingly (probably very unlikely though!)
The main risk is if management decide to snatch away the upside by taking it private.
A return to decent, profitable trading maybe next year, could see this share double or triple from its £14m market cap now. It’s not even particularly high risk, due to the strong balance sheet and net cash position. The founding family still own about 50%, so I think are motivated to get things back on track, and it seems to be heading that way, given the encouraging update today.
Do be careful not to chase the price up, as it tends to have short-lived spikes upwards, which quickly reverse, and then people blame me for stoking buying interest. I’m only giving my honest opinions, and have no intention of selling any QUIZ for the foreseeable future.
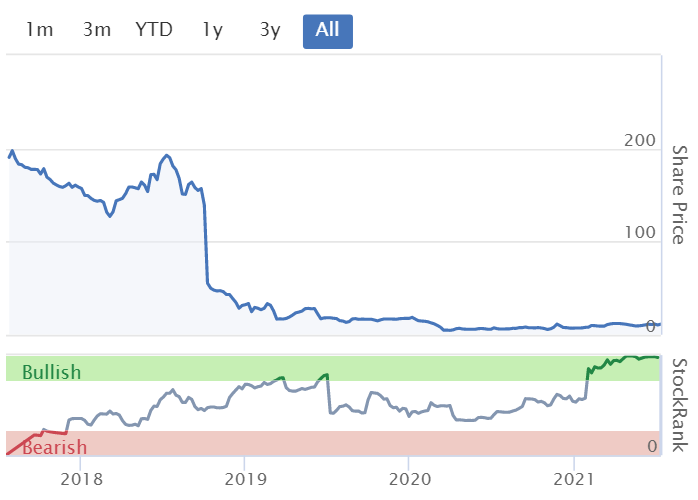
Terrible chart, but remember there's been no dilution, so the upside has not been curtailed since there have been no fundraisings, and none is needed in my opinion.
.
.
Photo-me International (LON:PHTM)
75p (up 5% at 11:03) - mkt cap £284m
Photo-Me International plc (PHTM.L), the instant-service equipment group, announces its results for the six months ended 30 April 2021 (the "Period").
Good half-year performance
H1 revenues up only 3.4% to £94.6m, although the prior year H1 figures would have only caught the start of lockdown 1
Adjusted profit before tax much improved from breakeven H1 LY, to £12.9m this year - driven mainly by restructuring cost-cutting, not top line growth
Net cash of £16.9m
Photobooths are still the main business, but self-service laundry machines are rising, and now 25% of total revenues
As in the past, no split is given of profitability by activity, so we have no meaningful way to analyse the business - i.e. declining vs growth areas
The CEO’s summary is quite useful -
"The Group has had a better initially expected start to the current financial year, with a promising return to pre-COVID business conditions. We have completed a multi-country restructuring programme which has radically reorganised our business areas and our country management. This includes a restructure of operations in the UK, which is expected to return to a cash positive position in the short-to-medium term.
"We are introducing new photo services and upgrading our photobooths. ID photos are proving to be a sustainable market, serviced through our established network and partnerships with site owners, including in the UK.
"We continue to have a great success in the rollout of our Revolution laundry machines in petrol forecourt locations, and our first 100 self-service apple juice machines have been delivered to the market alongside our 2,700 orange juice machines...
"Looking ahead, I am confident of a return to our fundamentals more quickly than previously expected, unless the COVID situation presents new difficulties."
Geographic split - as you can see below, most of the group profit comes from Continental Europe -

.
Balance sheet - looks solid, with a healthy cash position, which makes me wonder why they don’t pay off at least some of the outstanding bank debt, to save on interest costs?
My opinion - until the company discloses the split of where its profit comes from - i.e. the declining area of photobooths, vs the growing area of laundry machines & other activities, then it’s impossible to properly analyse the future outlook without having to guess key facts & figures.
I am impressed that covid triggered a restructuring, which conjured up significantly better profits. Which suggests to me that the group had a lot of fat in it, which was tolerated in the good times, but fairly easy to strip away in tougher times. That’s quite encouraging, as it suggests to me that deeper cuts could be made in future, if needed, to protect profitability.
The big question mark remains over the longevity of photobooths? They already seem an anachronism, and the group’s profits really seem to be dependent on the decisions of a few key Governments, over policy for photo ID required on official cards.
Capex is very high, so bear that in mind when admiring the buoyant EBITDA & cashflow numbers. On the plus side, note there was no dilution, since no fundraising was necessary during the pandemic.
Note that the low forward PER shown on the StockReport hinges on a large jump in EPS next year (latest Finncap forecast is 4.6p this year (10/2021) and 8.2p next year (10/2022).
Overall, I can see the attractions of this share, if you think profits are sustainable long-term. For me personally, there’s too much guesswork involved in this share, in terms of forecasting, so it’s not for me.
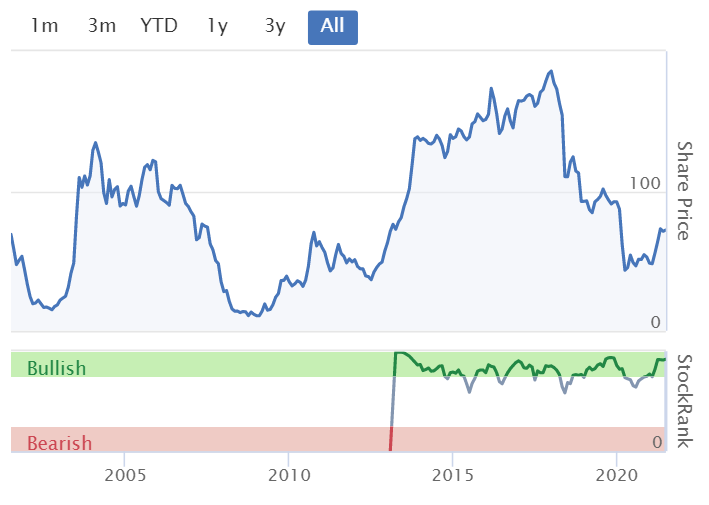
Here's the long-term chart, which is interesting as it shows how previously the market has gone through wild gyrations in sentiment towards the core photo booth business.
.
.
Jack’s section
Secure Trust Bank (LON:STB)
Share price: 1,140p (+9.62%)
Shares in issue: 18,638,372
Market cap: £212.5m
Secure Trust Bank is a UK retail bank based in Solihull. The group's lending portfolio currently focuses on two sectors: (i) Business Finance through its Real Estate Finance, Asset Finance and Commercial Finance divisions, and (ii) Consumer Finance through its Motor Finance, Retail Finance, Debt Management and Consumer Mortgages divisions.
Secure Trust uses a traditional savings and loan banking model. It takes savings from retail customers and makes loans to retail and business clients.
Banks can be complex and tricky to value, but Secure is well flagged by Stockopedia’s Ranks with a StockRank of 90 and appears modestly valued across multiple metrics. It trades at a discount to tangible book value.

And unlike the majority of stocks out there, this one has yet to return to pre-Covid levels despite a notable rerating so far.

Today the group issues a profit upgrade.
Trading statement
This is very brief but as noted above it’s an upgrade so worth flagging.
Secure says the positive trends experienced in the first quarter have continued into the second quarter.
IFRS 9 impairment provisions in the current financial year are expected to be significantly lower than the preceding year. As a result, profit before taxation for the full year ending 31 December 2021 should be materially ahead of current market expectations and be above the top end of the range of those expectations.
Those expectations were for an average profit before tax of c£29.5m within a range from c£26.4m to £36.8m.
Secure ‘remains cautious on the near to medium term UK economic outlook and will maintain a prudent provisioning policy, in case economic conditions worsen in the second half,’ however.
Conclusion
It’s not a stretch to see Secure Bank rerate closer to book value given its profitable operations and improving impairment forecasts.
Profits for the year will be ahead of £29.5m. Assuming the prior year’s tax rate and, say, £35m in PBT, we get £28.2m of net income or 151p of earnings per share. That makes for a forecast PE ratio of about 6.9x.
This is guesswork for now but it shows that today’s pre-open share price could prove to be undervaluing Secure’s prospects.
It has generated quite good operating margins in the past for a bank.

Returns on equity have also been comfortably ahead of larger peers like Lloyds in recent years, so it could be that Secure Bank is worth doing some more work on. The group looks to have a solid capital base and is capable of generating returns above its cost of equity. It’s quite possible that a blend of organic and acquisitive growth can propel the share price beyond a Covid bounce back.
This is not a part of the market I tend to get involved in though, and it’s only a brief update, so I’ll leave it there for now.
Uls Technology (LON:ULS)
Share price: 80.4p (-6.51%)
Shares in issue: 64,871,276
Market cap: £52.2m
ULS was founded in 2003 and provides a number of online services for consumers and intermediaries across the property, legal and financial services industries.
Services include its flagship eConveyancer, which is a fully automated online comparison platform that enables customers to obtain residential conveyancing quotations from ULS’s solicitor partners, then instruct their selected solicitor. This can be own brand or white label for the likes of BM Solutions, which is a division of Lloyds Bank.
Other services include estateagent4me, Property Searches, Energy Performance Certificates, and ID Checks.
The group has a clear mission to ‘revolutionise the home buying, selling and owning experience’ and to ‘make the process of moving home more efficient and a better experience for everyone’.
An important point here is the ‘transformational’ disposal of Conveyancing Alliance Limited ("CAL") for £27.4m. Net cash at the year end was some £24m, giving an enterprise value of just £28.2m. There have been a few changes at the senior management level too, so this could be a situation worth tracking.
According to the group’s chairman:
The [CAL] sale ensured that everyone at ULS was united in our desire to disrupt and transform the home moving process through a seamless digital journey, with the proceeds raised from the sale not only repaying all existing debts but also providing the funding for us to continue to invest in both people and innovation across the business, putting us in a much stronger position today than we were 12 months ago.
Final results
Highlights (from continuing operations):
- Revenue -18.4% to £16.9m, reflecting the COVID impact and market standstill in the first two months of the period and slower pick up of the first-time buyer market,
- Gross profit -20.7% to £6.9m,
- Underlying EBITDA £0.4m (FY 2020: £3.5m)
- Underlying loss before tax £0.8m (FY 2020: £2.4m profit) reflecting market dynamics and increased investment strategy
- Reported loss before tax £2.4m (FY 2020: £2.1m profit)
The first half was disrupted but the group has flagged improving conditions in the second half continuing into the new financial year. Conveyancing completions in the second half were 18,667 compared to 15,100 in H1, and there’s been a 21% increase in the number of active users in the group’s broker channel.
And while a loss is a loss, ULS really has been investing for growth - particularly in its DigitalMove offering, which has now handled more than 50,000 cases and has been moved to a cloud based third party environment to speed up the roll-out.
The underlying loss before tax on continuing operations was £0.8m against a profit in the previous year, with IFRS operating profit on continuing operations coming in at a loss of £2.4m, reflecting challenges in its core first-time buyer market and investment spend on DigitalMove. ULS is also working on a digital Rapid Remortgage proposition, which speeds the process of refinancing.
For the year ahead, the group expects to benefit from increasing demand and growing number of completions as the current year progresses. It aims to grow its routes to market for eConveyancer and develop the product suite, with substantial investment earmarked for DigitalMove.
Additional senior hires have also been made: Jesper With-Fogstrup joined as CEO in January 2021, and Ed Mardell and Simon McCulloch joining after the period end as chief technology officer and chief commercial and growth officer respectively.
Conclusion
The last time I wrote about ULS was to cover an ‘ahead of expectations’ announcement at 96p back in May.
So I’m surprised to see the shares down 5.5% to 81.31p less than two months later. Since then delays to the audited accounts have perhaps weighed on the price. Delays to accounts merit consideration but I’m not ruling ULS out on account of the large sale, resulting transformation of the balance sheet, new senior hires, and its desire to reinvest cash back into its product.
But just how good is that product, how much value is added, and how fierce is the competition? If similar product suites are being built by competitors then margins could fall over time. I’m sure the revamped management will look to communicate the investment case in more detail in the weeks and months ahead. It seems like a market ripe for disruption.
The company has a market cap of £52.2m, net cash of £24m, and an enterprise value of just £28.2m. Continuing operations generated revenue of £16.9m, so that’s 1.67x revenue, which could grow over the next year with a fair wind. It looks cheap compared to other software companies.
ULS says the housing market is in a ‘fluctuating’ state but notes the surge in completions approaching the first stamp duty deadline at the end of June might be repeated at the end of September.
Longer term, rising house prices and the shortage of supply continue to make it difficult for first-time buyers. At the same time potential buyers have been able to save more quickly towards deposits, higher LTVs are becoming available and the new Help to Buy scheme should also help.
Given the valuation, it’s worth taking a closer look at the group’s software and markets to gauge the strength of its position and the potential for growth, in my opinion.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

69 comments
On a more relevant (but still covid-related) note, it looks like other parts of the world are starting to increase restrictions again. Eg. France tonight. Given the recent market doldrums are partially due to inflation worries and global monetary tightening, could a reversal of reopenings etc (perversely) boost markets?
I guess readers will come to their own conclusion on that ....
Jack. thanks for the ULS Technology (LON:ULS) write up.
Anybody have any thoughts on the Primary Bid listing at 100p of Hydrogen One Capital Group?
Re. Hydrogen One IPO, I read through the prospectus and investor note this morning. There is also a useful write up on the Hydrogen sector in general - a good primer for anyone unfamiliar with the market. The IT itself is quite an interesting proposition offering a spread of investments in a „hot“ area of the market where it’s difficult for an outsider to differentiate the wheat from the chaff (while fully accepting it might all be chaff). In addition, the IT provides access to private as well as listed investments which wouldn’t otherwise be available to the retail punter. Fees and ongoing management expenses seem OK at a total of about 2.8% and there is comfort given by the fact that Ineos have agreed to be a cornerstone investor with a minimum position of £25m (of the target £250m). No financials as such given it’s a start up although it’s indicating an expected NAV cover at issue of 98%.
Overall can’t yet decide whether it’s a sensible play to get a diversified position in a sector that will be at the centre of moves to „green-ify“ future energy supply or a canary indicating that we’re at the top of the speculative market for Hydrogen based stocks. On balance thinking of rotating out of my residual holding in Itm Power (LON:ITM) (which has been up to a 40 bagger for me at its peak) and reinvesting the proceeds here. We have up to July 27th to make a decision.
Gus.
Thanks Gus.
In US there is $LIN Linde a large cap safer and diversified.
L&G Hydrogen Economy ETF (HTWG) an alternative. There's an ETF for everything it seems.
Hi GaryC.
Looks as though £HTWG is a (specialised) index tracker replicating a global portfolio of 32 stocks in the Solactive Hydrogen Economy Index as adjusted from time to time. No discretion in the selection - its holdings appear to be weighted on respective market caps.
https://fundcentres.lgim.com/u....
The Hydrogen One IT offers discretionary management from „sector specialists“ (as yet unproven) with its primary USP being its focus on private equity investments in tandem with Ineos as co-investor. The ETF has a much lower management charge (c.0.5% compared to the ITs c.2.8%). Although both are hydrogen economy focused I think they are qualitatively different.
Gus.
There is a clear case for continuing restrictions:
(1) Young unvaccinated people can still get long covid which a serious problem both at a national and personal level. This inconvenient fact has been ignored.
(2) Some people are unable to have the vaccine, such as under 16s and people with pre-existing health conditions. Is it right to sacrifice them?
(3) if you allow the virus to run riot amongst unvaccinated people then there is a risk of a new vaccine-resistant variant occcuring
(4) the call for abadoning restrictions has been led by libertarians types who have been consistently wrong at every stage throughout the pandemic. Why listen to them now?
(1) Vaccinated people can get 'long covid' as well.
(2) Sacrifice under 16s? Have you analysed their risk of hospitalisation or death? It's almost non-existent. You can calculate this at https://qcovid.org/Calculation
You sacrifice them by locking them up, masking them, testing them while healthy, and preventing them from having in-school education.
Pre-existing health conditions: perpetual lockdown then?
(3) the virus can only run riot amongst unvaccinated people endangering the vaccinated? Update Public Health England (page 16-17), 9 July, 2021, #18 shows in age group >=50, actually 88% of the 'Delta variant' were found in the vaccinated group. Why blame unvaccinated people for the failure to reduce transmission?
(4) tell that to Anders Tegnell in Sweden and tell that to Texas, Florida, South Dakota, etc.
Can we please stop this non-rational division (I can almost call it anger and disgust) towards unvaccinated people? Come with data, numbers and analysis instead of fear-based narratives.
And can we please rationally take into account side-effects of lockdowns too or do we just pretend that there is no collateral damage?
https://t.co/Riss32S8u7?amp=1
Martin,
Please stop posting continuous arguments about the vaccine. This is not a medical website - it is for serious investment discussion.
Lets please confine our discussions to investments and get back to talking about the pros and cons of companies.
Thanks
Kevin
Can you stop talking about exclusion and discrimination of people based on their medical status then?
LON:ULS. Excellent write up Jack. I don't hold but I like the profile. From what I see the upside heavily outweighs the downside risk - might take a small punt.
'Funny' old place the stock market, Avingtrans (LON:AVG) is awarded a £4.4M contract over 2 years, which is not insignificant given the market cap and the shares are marked down...hey ho.
I hold
Science (LON:SAG) (no position)
I liked the numbers the last time I looked at this one, but was put off by the lack of clarity on the increased cash generation vs the prior year.
Science (LON:SAG) bought a loss-making company, yet still somehow managed to go from generating £2.5m of cash to £10m in just one year - I just couldn't understand how they did it.
Not wanting to repeat myself, here is a link to my previous comment/concerns for any interested:
https://www.stockopedia.com/co...
No position yet, but I'm keeping an eye out on future results to see how that cash generation is coming along.
A
Science (LON:SAG)
abtan
yet still somehow managed to go from generating £2.5m of cash to £10m in just one year - I just couldn't understand how they did it.
If you look at the cash flow note they benefited £6 million this year (2020) and had adverse impact the previous year of £4 million on the following line item. Have yoiu factored in this change in working capital?
"Increase/(decrease) in payables excluding balances representing client registration fund"
This alone accounts for more than the entire difference so it seems that there is simply large variations in the payables line each of the last 2 years with last years cashflow being parciularly poor for the same reason this years is particularly good - the netted difference of £2 million over the two year peeriod being much less of an overall outlier of a number. Much better that cashflow is going in the right direction than wrong direction in this regard i must say - albeit the positive benefit this year may be expected to reverse back out partly or fully in 2021 onwards depending on where these numbers are trending - so i would tend to discount the positive element of cashflow benefit in any calcs i did.
Science (LON:SAG)
"If you look at the cash flow note they benefited £6 million this year (2020) and had adverse impact the previous year of £4 million on the following line item. Have yoiu factored in this change in working capital?"
Yes, I have factored this in.
I think it's also important to note other working capital movements (I've circled a few of the larger entries in red below), which made cash generation seem better than it was, especially the £1,033k for leases last year (which is then taken out further down the P&L).
So yes, I remain confused how they've done so well so quickly...and now the new CFO is leaving, which raised at least one of my eyebrows, though this could of course be a coincidence.
I'll wait for the interim figures to come out to research further - I'm certainly not discounting the possibility that there could indeed be an undervalued gem here.
A
Science (LON:SAG)
abtan
So yes, I remain confused how they've done so well so quickly...and now the new CFO is leaving, which raised at least one of my eyebrows, though this could of course be a coincidence.
I will bow out here - it looks like all the line entry adjusts too me are detailed though starting with the £6.4 mill profit ending up with the £17.6 mill cash from operating activities - so i am not sure what you are missing with all the differences between these two totals being listed in the acounts.
Thanks for the write-up on Uls Technology (LON:ULS), Jack. I've seen some weird reactions to announcements, but it's been a while since I've seen a stock report results as previously disclosed - which had put the share price through a £1 - fall 13% to circa 75p. Still the market must be seeing something I'm missing, perhaps it was expecting a further "ahead" statement.
Obviously I'm biased but I think the valuation makes little sense and is now (at the time of writing) covered in half by cash for a growing software business in a roaring property market. There's an investormeetcompany presentation at 4pm which should be interesting viewing.
Secure Trust Bank (LON:STB) was the Stock in Focus in May for Roland Head. It was positive, and he decided to buy it for the portfolio. After I DMOR on the Stocko metrics and their website, I bought, despite low Quality metrics (ROCE 0.8, GPA 0), pretending that it was a purely Spock/Hunter/NAPS-style purchase but knowing that I was also being soft 'cos I like the idea of a bank based in the Midlands. I've watched it go down since, wondering whether I should be cutting my losses quickly or whether that would make me a typical over-trading newbie. If it has turned a corner and is on the up, then doing nothing in particular but doing it very well has paid off.
If anyone has knowledge of the banking sector and can give a more meaningful analysis, then that would be of interest.
Secure Trust Bank (LON:STB) has consistently delivered mid teens return on equity with a very prudent approach, and well diversified across several specialist lending markets. I feel this warrants a decent 20-30% premium over book value, but currently trading on big discount so very happy to hold. Not sure if ROCE is especially relevant for banks so not too concerned about that metric.
Not sure if ROCE is especially relevant for banks so not too concerned about that metric
Thanks, Bouden54, that's useful. I've been aware through people's comments that not all metrics apply to Financials, but never been sure which ones.
Thanks for the info on Secure Trust Bank (LON:STB) - reassuring.
Yes I think ROE is key measure for banks. If not done so already, worth flicking through their results presentation, which has lots of useful charts showing their lending markets and historic returns. Very solid track record and well diversified so not too reliant on one type of lending.
Hi Paul
Would you have the time to pop over to my comment on Boohoo (LON:BOO) that I posted yesterday at
https://www.stockopedia.com/co...
Thx
Michael.
I thought this was interesting from The Times this morning. Susan Hopkins being the strategic director for COVID at Public Health England:
"Hopkins said that January’s peak of 4,000 admissions a day was “three doubling times away from where we are now, and that it was six to eight weeks potentially, unless things change, and unless we keep the transmission rate down”. Vaccination had more than halved the proportion of cases that end up in hospital but there was still a “direct relationship” between the number of cases and pressure on the NHS, she said."
Looking at Govt stats online the hospitalisations doubling time is every 2 weeks. So January peak we should reach at end of August if it doesn't slow down rapidly before then...
I'll be keeping well away from any "re-opening" stocks for now.
The key figure that doesn't seem to be publicised, is what proportion of the people being hospitalised due to covid are vaccinated, and what proportion are unvaccinated?
Comments in some recent articles from top medical people seemed to suggest that very few vaccinated people have ended up in hospital, let alone died. If that is the case, then there's no reasonable case for any further restrictions. If people refuse the vaccine, then end up sick or dead, that's their own fault, and it shouldn't be allowed to restrict the rest of us. Maybe fine them too, once they recover?! A stupidity/selfishness tax?
Regards, Paul.
I don't think there's data on that at the moment. AZ is about 92% effective and Pfizer 96% against hospitalisation after second dose if you catch COVID (which there's a reduced chance of) so you'd have thought this should make a difference at some point - see table below from Public Health England. But unfortunately 13% of population still unvaccinated and 33% haven't had second dose yet and we're not yet seeing any slow down in hospitalisations so I don't think this bodes well for summer at the moment.
and we're not yet seeing any slow down in hospitalisations so I don't think this bodes well for summer at the moment.
I have not seen many comments suggesting the current level of hospitalisations is trending in a direction where we will not be able to cope in this regard. From stats i have seen quoted 40% of covid hospitalisations are people hospitalised for other reasons who then test positive when there and also thankfully those that are vaccinated are much less ill on average else compared to the same cohort pre vaccination so less stress on the hospital system when they turn up . So the lack of any real panic from sage and and the authorities suggest that they think they are in a position where we can cope for now as things stand and generally they have been ultra cautious if there are signs things are heading out of control referfence with regard to what hospitals can cope with.
I think the issue with the figures you quote above re hospitalisation is that they are all pre delta variant, no worth nothing now, the delta variant is over 99% of all current UK cases, so its a new ball game, getting the data Paul is asking about is trivial, you know peoples names and nhs details when they go into hospitals, you can recall all their vaccine stats, it's trivial to work out, if they're not telling us, its for a reason, I suggest it's a bit like zaphod's sunglasses going pitch black to avoid him seeing anything that might alarm him.
if they're not telling us, its for a reason, I suggest it's a bit like zaphod's sunglasses going pitch black to avoid him seeing anything that might alarm him.
You can infer that the vaccines are working because the number of cases is growing rapidly while the number of people being hospitalised is only growing slowly. The last time we hit 30,000 cases a day (last December) we already had 20,000 people in hospital, now it's just over a tenth of that.
Of course, there could be some other hidden variable that's breaking the link between cases and hospitalisations but all things being equal the vaccination program would seem to be the most obvious cause.
So - even if everyone in hospital has been double vaccinated the vaccines are still reducing hospitalisations by 90%. Since we can reasonably assume that some people in hospital aren't double vaccinated the vaccine effectiveness will be better than that, and probably close to the trial numbers of 94% to 96% effective, even against the delta variant.
timarr
I completely agree, that is the key thing, I would also like to know what proportion have taken each vaccine. I suspect the figure is disappointingly high, which is why they don't publish it. If it were low they would be using it as a way to encourage people to get vaccinated. In the trials, the hospitalisation rate for the AZ vaccine was 0% I believe, however that was before the delta variant, which of course changes everything.
I can only find estimates based on studies like this one, which is a month old and suggests very high effectiveness against hospitalisations, but if this were true, hospitalisations wouldn't be on the rise so dramatically,
https://www.gov.uk/government/...
All we can hope is that cases flatten as the warmer weather comes, like it did last year, although with restrictions removed this is bound to put upward pressure on transmissions,
If we find that the issue is with young people getting it , what will we do ? offer to vaccinate them ? the balance of risk until now has seemed pretty good for young people although I did hear under 18s had died in the first 12 months, it didn't say how many of these had pre existing conditions. There's also the risk of long covid, I had speculated if it might make sense to just let the young kids get it , even hold covid parties and get it out of the way. But then there's the risk of long covid, my daughters school has a child in a wheel chair from long covid. Whats riskier the vaccine or having the disease ? which gives the best protection afterwards ?
In January less than 15% of over 35s had covid antibodies. That figure is now over 95% either as a result of vaccination or infection. It is reasonable to assume that nearly all vulnerable people have been vaccinated. I don't think that we will be able to reduce the risk of death from covid much lower than it is now in the UK, whatever we do.
I can only find estimates based on studies like this one, which is a month old and suggests very high effectiveness against hospitalisations, but if this were true, hospitalisations wouldn't be on the rise so dramatically
That conclusion isn't a safe one. If it was correct then double vaccinated people - primarily over 50 - would be the main growth area of infections. However, the most recent figures show that the biggest rise in infections is occuring in the under 50's - the group most likely not to be vaccinated:
https://www.ons.gov.uk/peoplep...
That low level of infection increase in over 50s is the key. But obviously the small number of unvaccinated people in that cohort are particularly vulnerable and likely to end up in hospital. A lot of the people who've chosen not to get vaccinated are convinced that CV-19 is a hoax and are therefore much more likely to engage in risky behaviours even as cases are rising. As noted in this article yesterday:
"A few patients we are caring for still deny Covid exists, even as we strap oxygen masks to their faces. That is perplexing. Staff find that particularly hard and I think it will be an interesting and difficult part of this next phase. I wonder if we’ll be caring for a select group of patients who think the very disorder we’re treating them for is a sham".
https://www.theguardian.com/so...
timarr
I would agree Paul. I think that there comes a point where if an individual refuses to take the vaccine for whatever reason then they have to take the consequences of this which should probably take the form of restricted liberty:
Then the rest of society who has taken the sensible course of action can get on with life.
Not sure why your comment has been red flagged.
Regards
Michael
I am personally very reluctant to put limitations on the non vaccinated, although I'm fully vaxed, I know people who don't want to be vaxinated, and are campaigning to stop vaccine passports, there's legal action going on in the EU, and they would love people to be forced to take the vaccine, which obviously won't happen. However the next best thing is making life difficult for the unvaccinated, so that they can claim they are being "forced" they would love that. I think the best solution is health passports where you need tests to do all the above, however if you are vaccinated, you are less likely to be carrying significant viral load, then you are exempt from some or all if you have no symptoms.
While the number of hospitalisations and deaths is clearly lower than in previous spikes, we have to remember that there are a lot of unvaccinated and half vaccinated people out there. Some of those will be hopsitalised, and those rates are rising. Many more of them will be incapacitated for some time by long covid, and that appears, so far as can be known at present, not to be strongly related to age as severe acute symptoms are.
More worryingly, allowing covid to rip amongst un and half vaccinated people maximises the chances of more dangerous variants arising. And allowing a lot of half vaccinated people to get covid is unfortunately the best possible condition for selection of variants that escape current vaccinations.
I can see no good reason for further major removal of restrictions until all adults, and ideally teenagers, are vaccinated. And no reason for removal of the requirement to wear a mask in places like public transport where people sit in close proximity for significant times.
Half price tickets for the Mello Monday show are available here....
https://www.stockopedia.com/content/we-are-back-mello-monday-is-tonight-835336/
Another solid quarterly update from Charles Stanley (LON:CAY) (I hold).
An increasingly attractive takeover play, with over £100 million of cash (>50% market cap) on the balance sheet?
Paul/Jack ULS Technology (LON:ULS) please, Final Results, is this an unexpected loss? Shares were down 7% but have recovered somewhat.
Not unexpected, the trading update in May made it clear they anticipated a loss for the year. They are heavily investing in DigitalMove which should be a game changer in the coming years. If this plan is executed well the share price will go through the roof based on their current market cap. With all that cash in the bank they have all the firepower they need. Very undervalued stock in my opinion. I see these moments as buying opportunities.
Completely agree here, I believe the market is missing what they are doing with DigitalMove, it's at early stage but the sector is crying out for a sector wide digital platform to manage property transactions and ownership.
I'm not at all sure. Growth depends a lot on the housing market, first time buyers in particular, and their spending big on staff and technology. I have a feeling they may be running quite a way above their prospects. Think it's a watch rather than a buy just now.
Well, regardless of the fundamentals today just shows what can happen to a small cap company with nervous investors. There is nothing new within this update to what was said in May and yet the share price is getting battered. The company has a slot on the Investor Meet platform today at 16:00 so hopefully they can provide clarity about growth projections and expectations over the coming year.
Re ULS. They are currently in the middle of webinar this morning. The results confirm the update on May 11th when the sp rose to £1.04. Since then after a boiling housing market, that market seems to be cooling off , that and the comment that there will be no dividend this year, even though I wasn't expecting one, tends to add a dampening effect.
There are only 65 million shares in circulation of which 77% are owned by institutions and 27% owned by Kestrel, a company that 'specialise in underperforming turnaround tech stock.' This stock has been pretty volatile this year, partly explained by the small number of shares and large institutional holding. I think at the moment its a question of faith in the management and confident backers such as Gresham house. Ultimately as with all these things the proof will be in the pudding. Be interesting to see how the webinar goes down.
My morning smallcap tweet:
Good Energy (LON:GOOD) Journeo (LON:JNEO) Mobile Streams (LON:MOS) Secure Trust Bank (LON:STB) Distil (LON:DIS) Science (LON:SAG) Charles Stanley (LON:CAY) Photo-Me International (LON:PHTM) Norman Broadbent (LON:NBB), QUIZ (LON:QUIZ), CPPGroup (LON:CPP)
Good Energy (GOOD) 340p offer (11% premium) from Ecotricity rejected. This is the third offer by Ecotricity. [SP=307.5 Cap=51m]
Journeo (JNEO) £0.5m order from Abellio within framework. [SP=100 Cap=9m]
Mobile Streams (MOS) £480k contract over 4 years for the use of Streams data platform. [SP=0.26 Cap=6m]
Secure Trust Bank (STB) guides FY(Dec) pretax materially ahead of market expectations of £26.4m to £36.8m, and above the top figure. [SP=1030 Cap=194m]
Distil (DIS) guides Q1 rev up 10%. "The figures are particularly encouraging as we are lapping the unprecedented first quarter in 2020." [SP=2.37 Cap=12m]
Science (SAG) ups H1(June) rev guidance to £40m and adj op profit to over £7m. [SP=401.55 Cap=165m]
Charles Stanley (CAY) FuM up 6% over recent Q. Rev up 8% yoy - "good forward momentum". [SP=351.67 Cap=183m]
Photo-Me (PHTM) H1(Apr) rev up 3.4%, EPS 2.49p (-5.64p). Co "confident of a return to our fundamentals more quickly than previously expected, unless the COVID situation presents new difficulties." [SP=71.6 Cap=271m]
Norman Broadbent (NBB) CEO leaves immediate effect. He is thanked. [SP=7 Cap=4m]
In line: QUIZ (LON:QUIZ) CPPGroup (LON:CPP)
Belvoir (LON:BLV) Investor webinar tomorrow at 1200 - registration link here:-
https://www.londonstockexchang...