Small Cap Value Report (Mon 12 Oct 2020) - CBOX, SAG, TPX

Good morning, it's Paul here with the SCVR for Monday.
It's very quiet for small cap trading updates and results again today.
Agenda -
Cake Box Holdings (LON:CBOX) - Trading update
Science (LON:SAG) - Trading update
Panoply Holdings (LON:TPX) - Trading update & significant contract wins
.
Cake Box Holdings (LON:CBOX)
Share price: 174p (up 5.5%, at 08:17)
No. shares: 40.0m
Market cap: £69.6m
Continued trading momentum in store and online
Cake Box Holdings plc, the specialist retailer of fresh cream cakes, today announces its half year trading update for the six months ended 30 September 2020.
I recall that this franchised cake shop retailer put out an impressive update after re-opening, which I reported about here on 1 Sept 2020. Re-reading my notes, it does look good. In particular a previously cancelled dividend of 3.2p was reinstated, as a special divi. LFL sales were up 14.1%, and online was up 74% - remarkably good, considering footfall is well down for retailers. This previous update covered the 5 months to end Aug 2020.
Update today - adds September to the reporting period, now 6 months for the half year to 30 Sept 2020. For the 6 month period, revenue was slightly down, at £8.6m (H1 LY: £8.8m). However, this includes 6 weeks of store closures at the start of the period, so the more meaningful comparison is LFL sales for the period after lockdown, being the 20 weeks to 30 Sept 2020;
Stores: LFL sales up 12.1% (very good, but down from 14.1% reported previously, so Sept has seen a slowing of the growth rate)
Online: up 81%, meaning that growth has accelerated further from the +74% figure previously reported. I would have liked to see the split of total sales between stores and online, because it's difficult to judge how important the online growth is, e.g. if it's coming from a low base.
Store rollout - given the chaotic circumstances of the last 6 months, I'm really impressed that CBOX has continued to roll out more store franchises. To open a cake shop right now, shows a lot of commitment from the franchisees, so they must find the offering compelling, which makes me sit up and take note.
Six new franchise stores were added to the Group's estate during the half year, bringing the total number of stores to 139. Recent store openings included Chatham, Swindon and Hemel Hempstead. In addition, after the period end, three new franchise stores are expected to open imminently.
A lot of the profits for franchise businesses come from up-front fees from selling new franchises. Hence continuing the rollout is important in that regard, to keep profits flowing. Then there's a long tail of franchise fees & service income in future, once a franchise is operating. It's a nice business model, but only works long term if there's a high enough gross margin to support both the franchisor and the franchisee's profitability. Cakes with quite high price points, are probably very high margin, I imagine.
I'm a little confused by this;
The Group has a very strong pipeline of new franchisees, driving confidence that the franchise store rollout programme will return to levels seen prior to the onset of COVID-19.
Currently, the Group has received and is holding deposits for 47 sites across the country.
It doesn't make it clear whether that is 47 new sites in the pipeline, or if it might include any existing stores? I might raise a query with the PR firm, to clarify that point, just to be sure.
Liquidity - £5.0m cash at period end, it's not stated whether this is net cash, or gross cash. I'll have to check the last balance sheet. This showed that there were bank borrowings of £1.6m at 31 Mar 2020. So I would have preferred the update today to give us the full picture, cash and debt.
Although I note that the last balance sheet also includes £4.6m of freehold property, and £1.0m of assets under construction. There was a £1.4m revaluation uplift on the freehold property, it looks like a new head office development. I adore freehold property on balance sheets, as it can hugely improve investment risk:reward, often with investors not even noticing it's there, so you get it free! So this more than offsets the incomplete disclosure about net cash.
For a franchising business, it's always worth checking receivables, in case financially distressed franchisees are building up unpaid invoices. There's no sign of that here.
Overall, the balance sheet is solid, so no problems that I can see here.
Dividends - we already knew that a 3.2p special divi was on the way, but another point has just occurred to me. Looking at CBOX's last year's cashflow statement, the business is generating enough cash to fund an expensive new freehold head office, plus paying divis. Therefore, once the capex programme is completed, there should be a lot more cashflow available to increase the divis. For that reason, whilst the 3.38% forecast divi yield may not look madly exciting, there should be scope for that to rise in future.
My opinion - I continue to be impressed with this company's performance. The share price looks about right for now, but I'm beginning to wonder if this could be a good long-term rollout. That it has managed to continue opening new stores, through franchisees, in these incredibly difficult times, tells me that the business must be pretty good. What sounds like a very strong pipeline of new stores, reinforces that.
Overall - looks potentially interesting, as a tuck away & forget type of long-term investment.
Note that the Directors have a lot of skin in the game here, but it looks as if a £6.4m sale occurred recently, raising a question mark. The downside of Directors holding lots of shares, is that liquidity can be a problem. The quoted market spread of 167p Bid, 180p Offer, is enough to put off many potential buyers. You can often get well inside the spread, but even so it's very off-putting.
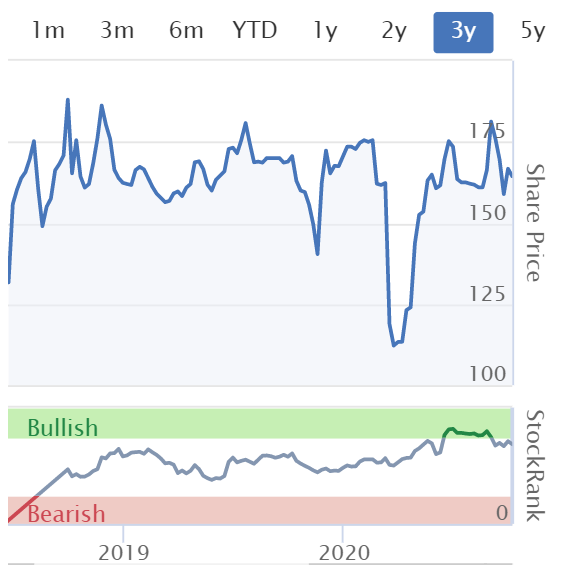
A sideways trending share price since listing. Note that the Stockopedia computers like it, with a high StockRank.
.
.
Science (LON:SAG)
Share price: 248p (up 5.5%, at 09:58)
No. shares: 41.77m
Market cap: £103.6m
It's helpful when companies give a short description of their business at the start of trading updates, which nearly everyone does. SAG seems to have forgotten to include that in today's update, so this is how it described itself in the recent interim results announcement;
Science Group is an international, science-led services and product development organisation with a significant freehold property asset base. Following the Frontier acquisition in 2019 and an organisation restructuring, the Group now comprises three operating divisions: R&D Consultancy; Regulatory & Compliance; and Frontier Smart Technologies.
Here is my review from the SCVR on 31 July 2020, of SAG's last interim results. I came away impressed. It's an unusual combination of businesses. Also noteworthy is that the long-standing Executive Chairman is still the largest shareholder, despite top-slicing his holding recently. Great to see so much skin in the game, but as with CBOX above, that does lead to poor market liquidity, with a small free float;
.
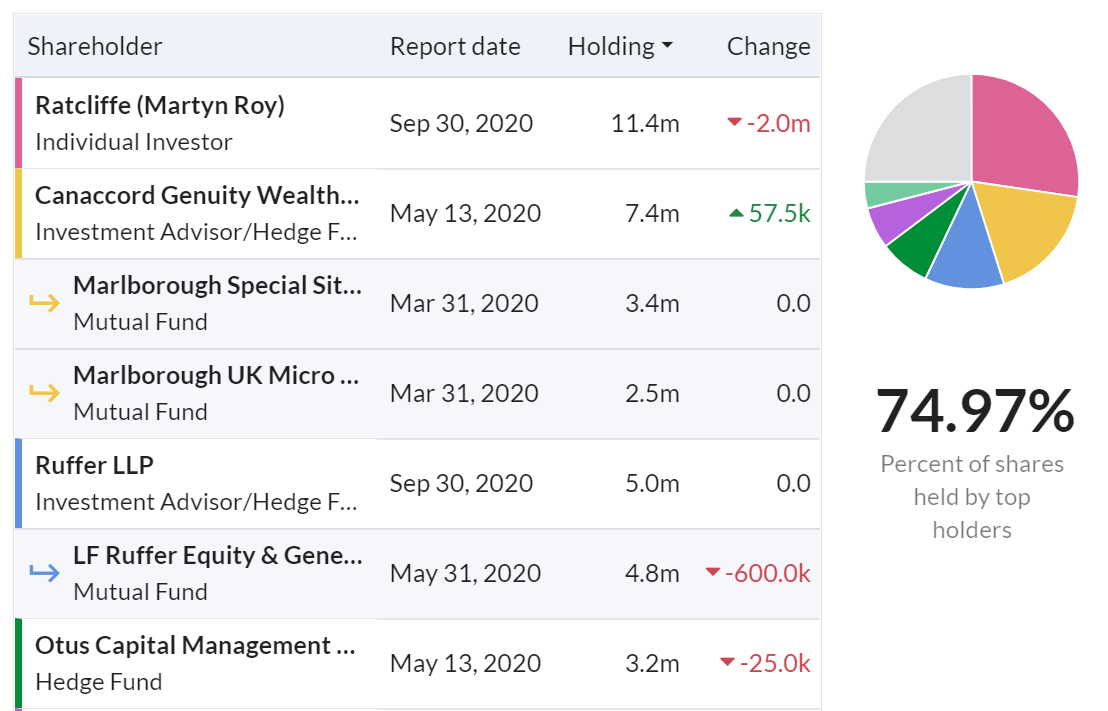
( see here for the full list, I've clipped this to make it fit into the article)
.
Today's update sounds very good during such a difficult year;
Science Group announces that, following its trading update on 10 September 2020, revenue across the Group has continued to be at the higher end of the Board's expectations. In particular, the performance of Frontier is noteworthy in terms of both revenue and, due to an enhanced product mix, an improved operating margin. While the Board is using the opportunity to increase investments in the operating businesses, it is now apparent that the Group's adjusted operating profit for the year ended 31 December 2020 will exceed the Group's expectations as set out at the start of the year.
That's particularly noteworthy because the beginning of this FY 12/2020 would have been pre-covid. So to be beating pre-covid expectations is a very strong performance. Plenty of other companies are beating market expectations, but often because the forecasts were slashed earlier this year. Not so here with SAG.
Frontier Smart Technologies - this acquisition has gone well. I won't repeat the detail here, but here's the summary;
... In summary, Frontier has exceeded the Board's expectations in its first year post-acquisition.
This was a turnaround acquisition, with costs cut, and it seems to have worked, so kudos to SAG management & their team.
Outlook - too uncertain, so concentrating on cashflow & prudence.
Science Group also benefits from its strong balance sheet including gross cash (excluding client held funds) at 30 September 2020 of £25.0 million and net funds of £8.2 million, with the debt secured on the Group's substantial freehold property (office and laboratory) assets. This capital base enables the Board to continue to explore acquisition opportunities although, as always, there can be no certainty that any acquisitions will be completed.
I reviewed the last balance sheet here. It's OK, but the cash position is flattered by high creditors. Overall NTAV is fairly modest at £8.5m. The freehold property could be worth more than book value though.
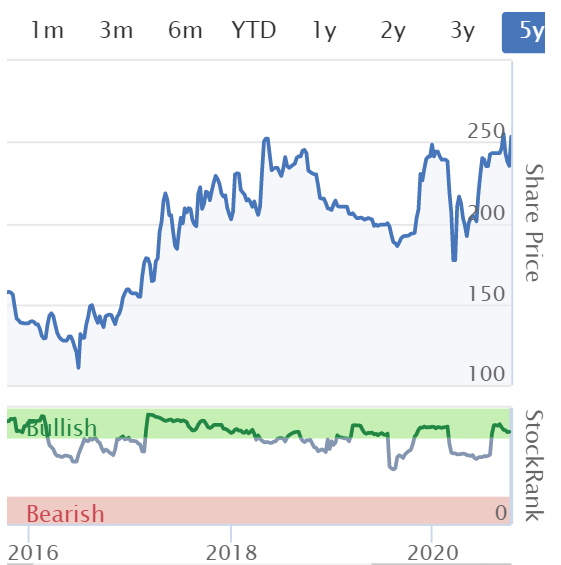
My opinion - remember that I only do a quick review in these articles, to look for good & bad things. Based on the solid interim results, and today's strong trading update, I think this looks a decent share for readers to spend some time taking a deeper look at yourselves. The valuation looks reasonable, and it's particularly impressive to find companies like this, that seem to have traded well in 2020, despite covid & lockdown.
Overall then, I like the look of this one.
.
.
Panoply Holdings (LON:TPX)
Share price: 137.5p (up 12%, at 10:44)
No. shares: 67.3m
Market cap: £92.5m
Pre-close trading update and significant contract wins
The Panoply Holdings PLC, the technology-enabled services group focused on digital transformation, provides an update on its trading for the six months ended 30 September 2020 ("H1 2021").
I last reviewed this share here on 14 Sept 2020. It sounds like an interesting, acquisitive group, in a sexy area. My main reservations are;
- Weak balance sheet - the most recent accounts show NAV of £27.3m, but deduct £44.3m goodwill/intangibles, and NTAV is negative, at £(17.0)m
- Sizeable deferred/contingent liabilities for acquisitions
- Rapid rise in share count
- Expanding too fast?
Those things might not matter in the long run, if the business trades well. I'm just flagging these things as potential concerns, which readers might want to dig deeper to form your own view.
Update today - some impressive-sounding growth here, but quite small numbers for a £92m mkt cap company;
- H1 revenues £20.5m (up 18% on a LFL basis )
- Adj EBITDA (oh dear) up c.25% to £2.4m
- "Strong balance sheet" (no it's not) with £6.4m cash, £1.0m net debt - which of course doesn't tell us the whole picture
- Two more acquisitions made
- Positive outlook comments, including that it expects an H2 weighting to profits
To save me typing more, here are the remaining bullet points, which sound upbeat;
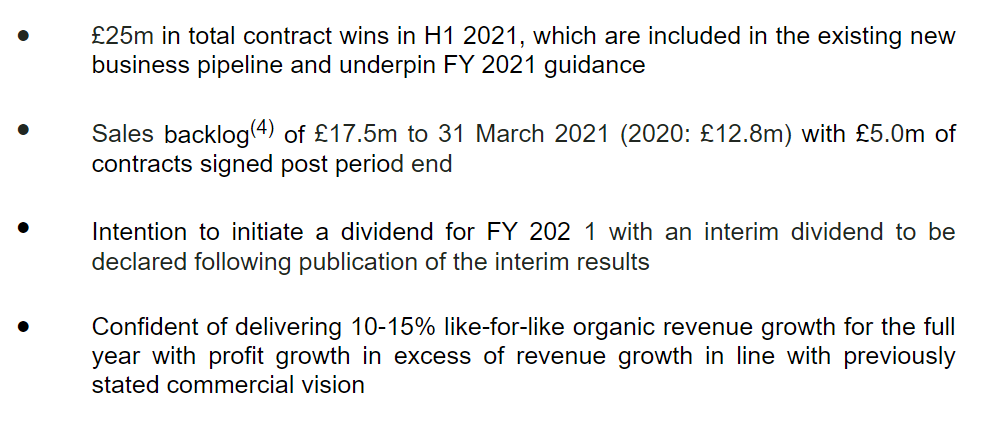
.
My opinion - neutral at the moment. There are enough negatives to make me want to steer clear at this stage, and the valuation is looking stretched to me.
However, I do recognise that growth sounds strong, and that management talk a great story about digital transformation for the public sector, and the extensive contacts that the various subsidiaries have, when combined, so cross-selling is easier.
Let's see how it develops. Not for me at this stage, as I'm generally not keen on rapid expansion through acquisitions, but I can see why some people might find the story interesting.
.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

62 comments
Online: up 81%, meaning that growth has accelerated further from the +74% figure previously reported. I would have liked to see the split of total sales between stores and online, because it's difficult to judge how important the online growth is, e.g. if it's coming from a low base.
Hi Paul
First ever comment on Stocko
Cake Box recently made available on Just Eat, Uber Eats and Deliveroo hence rapidly expanding on line sales - but yes from a low base?
Anyone tried to use the BigDish site?
Put in the location, no small restaurants signed up. Pizza Hut, Harvester and TGI Fridays are. Despite mentioning discounts, they are nowhere to be seen, and when you click 'book now' you are dumped on the booking page of the restaurant website, where you have to enter in your location again!
Reeks of a bit of a waste of cash to me, as long as they can keep on telling investors that that something is happening, they can keep drawing their salaries.
A back-end system is hardly proprietary. It sounds to me like they have been hanging around at the Google Cafe or something, trying to insert themselves into early stage startups for free.
The change of name thing means I wouldn't be surprised if they pulled out of food in the future. The idea of time-driven offers is actually a good one, so why is the progress so anaemic?
Intrigued about Cake Box. It doesn’t seem to be listed as a British Franchise Association member?
I would have thought that a quoted company would automatically want to be part of the BFA to help reassure both franchisees and Investors.
As it's a fairly quiet day and I know many here are either holders or followers, another RNS out today from Revolution Bars (LON:RBG) announcing yet another purchase of shares by Mark Ward. Now up to a 10% holding so even though the share price is close to being on the floor that's still quite a chunk of change and sign of commitment.
Anyone know who Mr Ward is and whether his history might shed some light on what he sees here that many don't?
I do hold and, unfortunately, have held for quite some time.
If it's the same chap, he seems to own a big chunk of Innovaderma (LON:IDP), too. That said, it's a fairly common name.
My best guess is that it's this chap:
https://www.linkedin.com/in/mm...
https://find-and-update.compan...
What does this tell us about his edge in Revolution Bars (LON:RBG)? No idea...
A lot of small cap stocks on the way up today; often on very little. They are going up because they are going up. A sign of froth at the end of a bull market? Or a huge influx of private traders trying to make a few £££? I have lost count of the number of individuals on social media saying they have lost their job so are going to become a full time trader. Robin Hood style "covid traders" I guess. Many of them might do fine in this time of extreme volatility and a few might just turn out to be naturals. Good luck to them all.
I do wonder though. I got a "tip" to buy All Asia Asset Capital (LON:AAA) recently. This is a tiny lossmaking investment company that is up 50 times from the lows and is valued at an amazing mkt cap. No thanks.....but it took me back to the 1980's where you had to phone and listen to a recorded message to get share tips. You never knew when they were being released so followers often phoned ten times a day. If you were lucky, you got the tip, phoned your broker and got in quick ....and then watched the price soar on ceefax or similar. Or phoned the FT line for "movers of the day". The key was to sell out before the next tip. Of course, now I realise that the tipsters had bought up a shed load of shares and it was just a form of bucket shop. Sometimes they had got wind of what was going to be printed in a publication ("red hot penny shares" or similar) and later on there was even a TV program where the contestants picked a stock for a week and the winner was the one that made the most money in that week. Of course, the picks soared the next morning so if you knew what was going to be tipped before the mkt closed that day.....leaky or what! Fun times....but not really that legal I guess. In those days though, without fast internet nobody seemed to be that bothered and insider trading was so rife that everyone knew of takeovers the week before. The first half of the movie Wall Street is so accurate for the times.
I thought Robin Hood announced they were pulling out of the UK market.
Robin Hood Energy have pulled out of the market, all companies using them e.g. Ebico, have transferred their clients to British Gas. Transfers are taking place now.
Different Robin Hood :)
https://www.telegraph.co.uk/technology/2020/07/21/stock-trading-app-robinhood-scraps-uk-launch/
Indeed, but barnetpeter referred to Robin Hood style "covid traders" I guess.
So it probably doesn't much matter which Robin Hood ;-)
It is though pretty disturbing if a significant people are using redundancy to earn easy money as traders.
Ah, I missed the style.
That happens a lot :)
Hello Paul. What are your thoughts on the Big Dish strategy change, announced in today's RNS?
I know that Paul does not do natural resources stocks in SCVR but in case anyone is interested, I have posted a note on the Discuss page entitled "Horses for Courses in Natural Resources - Jubilee Metals Group plc" £JLP
Any comments or feedback from the community most welcome.
Regards
Ricardo
Paul
Thoughts on change of strategy from Bigdish welcome, I've been watching since you covered the other week.
Hi Mike,
I wasn't going to mention Bigdish (LON:DISH) (I hold) as the frequency of updates is getting ridiculous! Plus it has such a small market cap, that it's now below my usual £10m cut-off. I think it's well into the territory of diminishing marginal returns, when it comes to these updates. Or even counter-productive.
The way I read today's update is a broadening of the strategy, and it seems sensible to find additional uses for the app, and getting some free stakes in startups could be interesting. It only takes one to hit the big time, and it could be transformational.
Investors in the US go crazy for this type of thing. The shares are a call option - tiny market cap, could fizzle out over time, or could 10-bag. Time will tell. As I always say, not for widows/orphans. I like the food tech sector very much, and am happy to take a punt on it, as a ground floor valuation type of share.
Regards, Paul.
I took a punt on it too, pretty small £5k, following your cover on SCVR. It is fair to say that short term price goes anywhere and everywhere, and it's kind of boring to track. I hope it gets somewhere in the end!!
Hi Paul,
Bigdish (LON:DISH) (I hold and I know maybe too much airtime) but just wanted to highlight that: I agree when say:
is a broadening of the strategy, and it seems sensible to find additional uses for the app, and getting some free stakes in startups could be interesting. It only takes one to hit the big time, and it could be transformational.
But my read is they will not be focused on food tech in particular (which in my view is frustrating) but anything that can try and utilise their platform ...
from the release "Looking ahead, BigDish is expected to grow into what is termed a Venture Builder and through this diversification, own stakes in companies across the technology spectrum. The Company will also consider a change of name as the Venture Builder model progresses."
As a tech firm offering sweat equity they will be in a crowded space...generally a start up looking for investment would normally gravitate to firms with expertise in their space, have a good track record and more importantly can open doors.
But here's hoping I'm wrong and they will find a diamond
Your comment has made me realise -
The platform offers discounts when restaurants are low volume right? I see no reason why this can't work really well for say, hairdressers, nailbars etc - anything that needs a booking really.
I still don't know how you get the potential customers to look at the app in the first place though. I mean, that's just GroupOn though.
Bigdish (LON:DISH) yes it could lend itself to other businesses which need bookings but I would ask why then not do it themselves, it would be an easy add on... as for using the app...a large marketing budget normally fixes that but for most early stage businesses they do not allow/have sufficient funds for marketing so you could have a great product that nobody knows about..
£DISH....TBH FatChance would be a better name. I am pretty sure roughly 99.99+% of both takeaway owners and takeaway customers have never heard of it, even directors are selling at any price......
and it's been bouncing around bankruptcy ville...seriously!
Just Eat Takeaway.com Nv (LON:JET) is the #1 by a mile and takeaway owners use it because it works. Forget the rest and choose (and invest) in the best.
Cake Box Holdings (LON:CBOX) - If six franchises opened in the half year to September then there is every chance they were signed up before the lockdown so I'd be interested to know how many of the (TBC) 47 pipeline are scheduled to open in the next six months?
I have to say, when I read that there was a pipeline of 47 franchisees my first thought was to wonder if this was because people who lost their income in the Covid crash were looking for another source of income rather than because the Cakebox business model was taking off.
Re Cake Box Holdings (LON:CBOX)
They'll need at least £135,000 plus VAT to buy a franchise. https://www.eggfreecake.co.uk/...
The FAQ's are interesting https://www.eggfreecake.co.uk/...
Q. I don't have any experience in managing a business, making or decorating cakes. Can I still open a franchise?
A. Of course you can. There is no baking involved and we provide all the training to make sure you have all the skills needed to operate our franchise through training on site and our tailored residential courses.
Q. I don't have the full capital. How do I fund my Eggfree Cakebox franchise?
A. We recommend you provide 50% of the capital and the remaining 50% through the bank. We have very good contacts with various banks and our Financial Director would advise you throughout the process.
Caveat emptor!
Edit - I'm not seeing them listed as a member of the BFA - the British Franchise Association. That would be a cross against my personal first checklist item if I was looking to buy a franchise. https://www.thebfa.org/
Also on Cake Box Holdings (LON:CBOX), why are the inventories (all said to be finished goods) so high and growing much faster than turnover? I assumed they were mostly sponges that should have a short shelf life.
That's an excellent question. A high and rising inventory was one of the warning signs with Patisserie Valerie. I've no idea if this is a red flag for Cake Box Holdings (LON:CBOX) but it's worth investigating.
I have no industry knowledge (wife is very capably in charge of the baking department), but in defence of Cake Box Holdings (LON:CBOX) the increase in inventory over the past four years, £0.87M is only a fraction of the increase in retained earnings, £7.09M.
Now FRASERS (LON:FRAS) has increased retained earnings of £383M and increased inventory of £681M - cost of sales have risen by 44%, inventory by 132%. That alone makes it a bargepole stock for me - but always DYOR.
Bonitabeach
No position
https://www.patplc.co.uk/sites... You might not have heard of Robin Angus or his investment trust Personal Assets Trust (LON:PNL) (Personal Assets Trust). Its goal is the preservation of capital (he calls it 'sacred capital) and beating RPI over the long term and it tends to achieve this objective (not that I have any shares in it). He's retiring and wrote his investment principles in the above report. It's a nice read over your morning coffee.
Thanks kgb1953 for drawing our attention to the latest thoughts from Robin Angus and Personal Assets Trust, which I have been reading for years. Although diametrically opposed to the approaches to stock selection underlying many articles on SCVR, it is apparent that both Personal Assets Trust and SCVR are successful ventures. Personal Assets Trust regards capital preservation as of paramount importance so it is perfectly designed for those who want a better return than leaving their money in a building society, but would have difficulty sleeping at night during market turbulence. My opinion is that Personal Assets Trust and its Investment Manager, Sebastion Lyon, are one of the best exponents of this "safety first" approach, using mixed asset investing. However, if you compare their returns to the best pure equity fund managers (who I believe you can identify) then the high cost of the "safety first" aspect is apparent from the lower returns. I also question whether Personal Assets often substantial investment in government bonds, (index-linked or otherwise) would prevent permanent loss of capital in the event of systemic failure of the financial system. In such a situation, I reckon selected blue-chip equities would eventually recover better than government bonds (which might be written off) after such a collapse.
PAT seems to me a little disingenuous in benchmarking against the FTSE All Share rather than a global index, given their main holdings are US stocks and bonds. Also 3 of their largest equity positions are sin stocks (drink and tobacco) which will grate with many prospective investors given the growing awareness of ESG principles.
Bigdish (LON:DISH) - (I hold) Interesting update to say the least! - Sweat equity is a good way to get stakes in start ups who may have good ideas but no resources to execute them. But It then makes me ask the question do they have too many staff with not much to do, which given they themselves are a start up is worrying....
Regarding Bigdish (LON:DISH) my take on this is that they have a good product which for whatever reason the market isn’t biting as they hoped. Straying into more product development when the first idea is still struggling is a danger signal to my eyes.
Well, maybe this is just me.....
But I wouldn't know how to download this app (is it an app?) and I'm aware that the solution exists. How do they gain traction across the population?
Generally, when I want to eat, I go eat. And then I use something like Vouchercloud as an afterthought once I've got the bill!
Why are Bigdish keen to go in so many directions at once, get the core product working 1st. Management seems all over the place, must be a nightmare company to work for, staff wouldn't know whether they're coming or going.
also, the largest shareholder is stepping down from the board?
and why do they keep telling us over and over they're not going to dilute the shares? is something on your mind you want to tell us
I brought this share for all the wrong reasons, I liked the price action and it attracted the gambler in me. Mental note to self, gambling is for when you're playing poker with your mates, max 30p big blind, not for when buying shares!
Since the covid start my kids ( 4 of varying ages uni, sixth for and school) have been hammering JustEat and recently they have been using UberEats (due to free money signing people up) instead of going out with mates. They now meet up and have a takeaway and drinks instead of going out for a meal.
Just been taking a look at Funding Circle Holdings (LON:FCH) again. An astonishing fall from the IPO price which was hugely inflated as it was listed as a tech company. This business has virtually no recurring income and is heavily reliant on marketing to generate new lending to generate fees.
I suspect we will se an upward blip in the short term on the back of CBILS. Then a fairly long and painful demise. I could see it been acquired by Starling Bank if it falls low enough.
Hi Paul,
What happened to your twitter account?
Twitter decided they could manage without my contributions, which has been a blessing in disguise for me. What a waste of time social media is. And extremely aggravating.
Ha, true that.
I’m a Twitter lurker mostly, there’s loads of great nuggets on there but also loads of muppets too. Thanks for responding :)
Appears, someone flagged my posts - I acknowledge I 'm not a great communicator and can be very blunt but I genuinely have no idea why this conversation was flagged. The question is meant to be asked in a friendly "how's it going" kind of way and my response is meant to convey a "yeah, social media is a double edged sword, it's great and bad at the same time" attitude. If that's not how it comes across then apologies.
I miss your funny comments Paul - but it has really turned into a cesspit of negativity recently.Tom Winnifrith is getting absolutely caned !!
Hi Paul - good morning. Any chance you could look AGFX (Argentex) please? Graham has covered it in the past, but would be great if you could give your opinion too.
Many thanks
P20
BigDish (LON:DISH) RNS:
"As part of this strategy the Company is making plans to bring in new experienced technology focused management to lead this initiative. The Company is also having talks with several potential Non-Executive Directors to add further substance to the Board".
and
"A Venture Builder model benefits from a leaner management team"
The whole RNS reminds me of Quindell - vague, ambitious and unfocussed.
BigDish (LON:DISH) RNS:
My experience tells me it's all about the quality rather than the quantity.
Bonitabeach
BigDish (LON:DISH) verbal diarrhea
Reading between the lines, the sector they are in is a barge pole sector at present, so they are looking at other sectors. They have a few sales leads, but none that have money to pay for the software.
Desperate stuff.
I'd be interested in other's thoughts on Argentex (LON:AGFX)
Obviously a poor trading statement, but it's what I believe to be a quality company who have ramped up sales capacity and are adding lots of new clients.
So is todays disappointment a covid related buying opportunity, or the start of a recently listed company starting to implode with increased costs and reduced sales?
If the former then it's a good opportunity. There is no threat to the business as the balance sheet is good with tons of cash and the rating is not challenging if it returns to former growth soon.
A respected tip sheet covers agfx and with remarkable prescience sold it last month 'although not recanting the story'.......
I agree with you this looks like a buying opportunity based on the good growth in customer numbers and strength of director commentary in today's statement.
I used to hold Alpha FX (LON:AFX) but sold in March after they warned of the bad debt. agfx is rightly proud of it's careful risk management in today's statement and on balance I now favour it vs afx.
Bigdish (LON:DISH) where to start! Since when has multiple customers and multiple code bases ever lead to a leaner management team? Major shareholder stepping down from the board so he has more time to work, hope he makes use of that extra hour. Guess we’ll find out soon enough more information as the RNS will be coming thick and fast from Zak.
That said it will be interesting to see the journey of Big Dish to either a multibag or a ramped bag of wishful thoughts that limps its way to a final delisting.
A cynic might thing Dish is serving up chaff and hope to distract from a failing business model.
Sweat equity? Sounds like they might license IP. That's not sweat, it's the product of sweat.
Anyway, for more salty excretions, sounds like Mir's your man.
Big Dish. RNS
What does this mean?
Ignore. Should have read Mr C first.
Investopedia has the definition
https://www.investopedia.com/t...
Essentially -
Plain English would have been better. Why do people have to revel in the use of impenetrable jargon?
Well, they’re hoping lots of people don’t understand it. My first reaction to the definition above was, as a techie if you deliberately ‘sweat’ me (unpaid labour) I’ll very quickly be looking for somewhere else to work.
It probably sounds better than "trying to get people to work for free"...
My morning smallcap tweet: DIsh takes the biscuit.
Cake Box Holdings (LON:CBOX) Camellia (LON:CAM) Yourgene Health (LON:YGEN) Scancell Holdings (LON:SCLP) OptiBiotix Health (LON:OPTI) Wilmington (LON:WIL) BigDish (LON:DISH) Eddie Stobart Logistics (LON:ESL) Science (LON:SAG) Panoply Holdings (LON:TPX) Seeing Machines (LON:SEE)
Cake Box (CBOX) guides H1(Sep) rev £8.6m (£8.8m), LFL up 12%. "We have received a record number of new store applications, giving us confidence that the momentum in our national rollout will return to pre-COVID levels." [SP=163.15 Cap=65m]
Camellia (CAM) Re: press report of legal case re violence by investee Kakuzi (avocado producer) - Kakuzi questions the case but does not seem to deny them outright. [SP=6850 Cap=187m]
Yourgene Health (YGEN) Elucigene DPYD cancer gene tests to be used routinely in Wales. [SP=20 Cap=144m]
Scancell (SCLP) proposed £12.1m subscription at 13p, a 19% discount. Also OO and issue of £17.9m convertibles. [SP=16 Cap=101m]
OptiBiotix Health (OPTI) launch in Australia and NZ of meal replacement shakes and bars containing OptiBiome weight management technology (sic). [SP=59 Cap=52m]
Wilmington (WIL) CFO leaves in Dec, new one found. [SP=125 Cap=111m]
BigDish (DISH) Developing a Venture Builder model to gain sweat equity stakes in a portfolio of assets with no cash outlay. Last time I saw 'sweat equity' was from Quindell's Rob Terry. Co to sign agreements with several 'significant' startups: BigDish will provide the technology in return for equity stakes. "Looking ahead, BigDish is expected to grow into what is termed a Venture Builder." Funding runway potentially further extended beyond Q2 2021. DISH's Digital Communications Officer is Zak Mir. Now where did I put those running shoes? [SP=1.62 Cap=6m]
Eddie Stobart Logistics (ESL) good trading at investee GreenWhiteStar (pallets and logistics): H1 rev down 1%, U/L EBITDA £16.6m (-£6.3m). [SP=6.63 Cap=25m]
Science (SAG) rev continued to be at higher end of mgmt expectations. Vague outlook "Board will therefore continue its prudent operating model, making investments when financial results permit, and maintaining its primary focus on cash flow.2 [SP=232.5 Cap=98m]
Panoply (TPX) guides H1(Sept) LFL rev up at least 18% and LFL adj EBITDA at least £2.4m (£0.9m). LFL = adj for acquisitions. £25m contract wins in H1, which are included in the existing new business pipeline and underpin FY 2021 guidance. "Confident of delivering 10-15% like-for-like organic revenue growth for the full year with profit growth in excess of revenue growth in line with previously stated commercial vision." [SP=122.5 Cap=83m]
Seeing Machines (SEE) expanding its driver monitoring system into an overall vehicle interior/occupant monitoring system (SEE).Will be available for automotive production programs starting as early as 2023. Market up to A$1.5 billion through to 2030. Beware tiny companies bandying about massive market sizes. [SP=4.65 Cap=156m]
Genedrive (LON:GDR)
No results or reports for Genedrive today so why ask about it in SCVR?
Synopsis available elsewhere...
https://www.stockopedia.com/co...
Readdin - I see that you joined yesterday and that this is your first post - welcome.
It is usual to say a bit about the share you would like to be discussed (e.g. results out today beat market expectations....) otherwise you are likely to get the dreaded 'thumbs down'. Also, as pointed out by Forbsy, this SCVR concentrates on current RNS announcements.
Morning, as sharw states below there's a fairly consistent way things are done on this blog, there are a few guidelines though.
Generally a company would need to have issued a trading update or set of results for the authors to add them into a main report. There are exceptions, they're only guidelines after all.
It's considered polite to state why you think a company is worth looking at, and it doesn't have to be for positive reasons - if you suspect some dodgy accounting or that management are overlooking something that's just as valid as saying "company doing amazing". We're here to share bull and bear cases. Paul is much more likely to respond if there's something interesting going on with the company that you can flag to him to look at.
There are some sectors that are much, much less likely to get looked at, basically anything that needs very specialist knowledge, so complicated financial institutions, miners and oilers, pharmaceutical trials and the like.
Finally if you want to discuss Genedrive and have some thoughts, you can always start your own discussion thread, I'm sure there are others who would like to hear what you think and would like to share their thoughts.
We could probably do with a pinned message somewhere explaining the etiquette of this blog, if you hit the green smiley face bottom right, Ed and the team are very friendly and helpful - I submitted a suggestion Saturday and got a quick personalised response that directly addressed the points raised.
As others have pointed out Paul has 100's of stocks in his small cap universe which he tries to cover and he excludes those where he feels he cannot add any value.
If it is Jack taking a turn on the SCVR he will often cover the likes of Genedrive (LON:GDR) but again only if there is news.
I don't hold Genedrive (LON:GDR) (but there has certainly been a lot of twittering about it since March) but I do hold Avacta (LON:AVCT) Novacyt Sa (LON:NCYT) 4d Pharma (LON:DDDD) Open Orphan (LON:ORPH) Synairgen (LON:SNG) Venture Life (LON:VLG) so it does interest me. Though none of these are my normal type of investment, we do not live in normal times. If you look at the Stockrank performance at https://www.stockopedia.com/le... you will see that the "dross" with a stockrank of between 1 and 10 has out performed significantly those companies with Stockranks with a rank above 80. I have no idea why or whether there is anything on the site from the Stockopedia team.
The most recent post on Novacyt Sa (LON:NCYT) is at:
https://www.stockopedia.com/co...
by Forbsy, so that might be of interest to you.
I think I personally have enough Covid punts though Genedrive (LON:GDR) is certainly tempting and I will start with Forbsy's post and go from there.
Finally welcome to this forum and don't worry about the thumbs down it doesnt mean a lot in most circumstances. BTW if you are using the new site you don't (annoyingly) get notifications of replies to posts so you have to keep checking back, which does tend to reduce engagement.
Regards
Michael
Make that 9 - 0
Your audience really appreciate you Paul, 8 Nil up while you are still warming up on the touchline this morning!