Small Cap Value Report (Mon 12 Sept 2022) - BKS, SRC, SPSY, MTEC, AXS, ARC

Good morning from Paul & Graham - suitably refreshed from his holidays! Today's report is now finished.
Normal service resumes here today, I'm pleased to say.
Weekend podcast went up as usual, or is available on podcast services (just search for "Paul Scott small caps").
Agenda -
Paul's Section -
Beeks Financial Cloud (LON:BKS) (I hold) - a reassuring, in line with (previously raised) expectations, trading update for FY 6/2022. Also BKS reveals the identity of an impressive recent client win. Outlook comments are buoyant, with a "record sales pipeline". This share is tricky to value, but the accelerating organic growth, mostly recurring revenues, and positive outlook, reinforce my belief that this share looks like a long-term winner for patient investors.
Spectra Systems (LON:SPSY) - I crunch the interim numbers, and come away impressed with the high profit margin, strong balance sheet, and generous divis. It's a very small company, but has numerous projects in the pipeline, any of which could be transformational if they scale up. Hence blue sky upside, on top of solid fundamentals - that's an attractive risk:reward stating point in my view. Worth a closer look I'd say.
Accsys Technologies (LON:AXS) - a catalogue of problems from this specialist wood products maker, which is struggling to ramp up production. Sluggish production in Holland, hampered by high gas prices as well as production gremlins. Its new Hull factory is also seeing delays & question marks over viability (due to gas, again). Only its US JV is progressing well, but won't be producing until mid-2024. Pity, as products are in demand. Overall, it looks too difficult to assess, and I'm worried about more dilution.
Graham's Section:
Sigmaroc (LON:SRC) (£310m) - this quarrying company announces interim results and also a JV with the industry giant ArcelorMittal. The deal is impressive in terms of the association that’s been formed, but I’m curious as to how the JV will negotiate pricing with its primary customer (ArcelorMittal) who will also be a 47.5% shareholder. As for the interim results, they show promise with good profitability and an upbeat trading statement, although the balance sheet has a significant degree of leverage. Overall I find this a perhaps risky and complicated, but nevertheless an interesting stock for us to keep under coverage, especially considering the inflation theme which exerts great influence over SigmaRoc’s revenues and costs.
Made Tech (LON:MTEC) (£44m) - this company focuses on digital transformation for the public sector. Revenues are growing at an excellent rate, approximately doubling each year, but statutory profits remain elusive. This looks to me like a labour-intensive, low-margin business that would be more appropriately owned by its employees, rather than external shareholders. However, external shareholders were happy to pay £70m for less than 50% of the shares at last year’s IPO. It wouldn’t surprise me if employees eventually bought it back for a pittance.
Arcontech (LON:ARC) (£11m) (+5.7%) - previously announced contract losses result in lower year-on-year revenues and profits at this software company, in line with expectations. PBT of £760k is generated from turnover of £2.8m. With over 90% of revenues being recurring in nature, the company has the confidence to increase its final dividend. Additionally, the Chairman says they are “well placed to make up some of the lost revenue during the current year”. It’s worth noting that Arcontech shows £6m of cash on its balance sheet, i.e. more than half of its market capitalisation. The underlying business does not appear to be going anywhere very quickly but it’s easy to argue that this is priced in at the current valuation. The shareholder register is also worth a look: insiders are well represented, plus some well-informed private investors. [No section below]
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section:
Beeks Financial Cloud (LON:BKS) (I hold)
143p (pre market open)
Market cap £94m
Beeks Financial Cloud Group plc (LSE: BKS), a cloud computing and connectivity provider for financial markets, is pleased to provide an update on trading for the year ended 30 June 2022…
Client win - this strikes me as significant, as a major reference customer - more detail is in the RNS -
…confirm that the first customer for its newly launched Exchange Cloud offering is ICE Global Network (IGN) part of ICE Data Services, a division of Intercontinental Exchange (NYSE: ICE), the world's largest exchange group and owner of the New York Stock Exchange.
Trading Update - this looks fine to me -
Beeks has delivered a record trading performance in the year, delivering growth on the prior year and in line with upwardly revised market expectations.
The Group has exited the year with Annualised Committed Monthly Recurring Revenue of over £19.3m, growth of 40% on the prior year, providing a strong basis for further growth in FY23.
I was discussing recurring revenue stats with another SaaS company the other day - PCI- PAL (LON:PCIP) - who explained the importance of annualised recurring revenues. For anyone not familiar, it’s a forward-looking indicator on revenues, that shows what the base level is (assuming no client churn, which is usually low at this type of business) for the coming year. Then there’s usually some additional growth on top of that, for new contracts won. Hence we can use ARR as a sense check for broker forecast revenues in the coming year. Stockopedia is showing £24.7m consensus forecast revenues for FY 6/2023, hence £19.3m ARR suggests that 78% of the new year’s revenues should already be in the bag. That’s appealing visibility for investors.
Results date - “early October”, for FY 6/2022 results.
Outlook - sounds encouraging -
"The success of Proximity Cloud and Exchange Cloud have contributed to a fantastic trading performance in FY22 and we enter the new year with a record sales pipeline and confidence in our ability to continue to capitalise on the significant opportunity ahead."
My opinion - this remains one of my favourite long-term holds. It’s tricky to value, because it’s a rapid growth company, not a value share. Hence I feel that over-analysing the historic numbers is missing the point. It’s the acceleration in growth, and the niche nature of what it does, that interests me.
For customers, security, and reliability, are absolutely key, and it’s taken Beeks c.10 years to develop its reputation and technical capabilities. Whilst that could be replicated by a well-funded competitor, it would probably take years before customers would be willing to trust it to deliver faultless service. Hence I see considerable intangible value in Beeks shares, and barriers to entry. Customers are very sticky, once signed up.
Management has spoken before about reaching a tipping point, where contracts are now scaling up. Large organisations tend to dip their toe in, with an initial contract, then once it’s proven, scale up to larger contracts.
Everything looks to be on track, and with a record pipeline, I reckon the forecast for FY 6/2023 looks set at a beatable level. Hence there should be little risk of a profit warning.
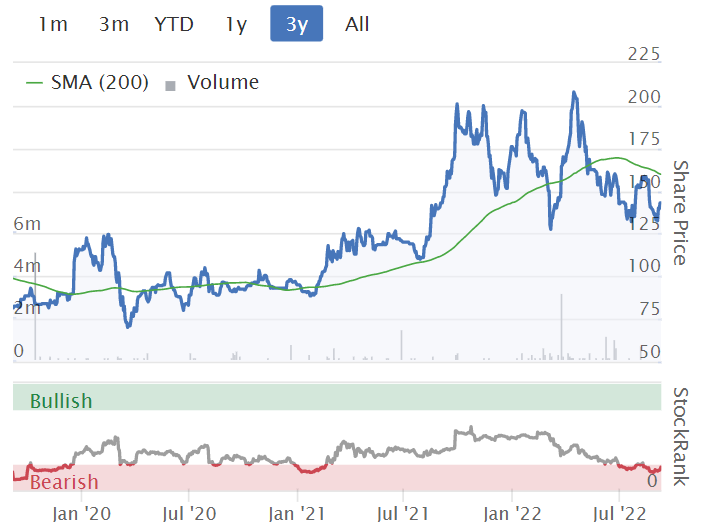
Beeks shares have held up relatively well in a nasty bear market for small caps. It seems to trade in a range between 125-200p. I’m more interested in the longer-term picture, as it seems obvious that Beeks is going to be a much larger, and more profitable company, in future. It just requires some patience, and nothing bad happening. So far, so good!
I’ve seen more bearish commentary on BKS shares, but think it misses the point, but it’s always good to consider bearish opinions, if only to double-check that the bull case holds water, which I think it does.
It's too early stage to have a decent StockRank. So the StockRank system asks us sternly, are you absolutely sure about this?!
.
Spectra Systems (LON:SPSY)
162.5p (up 2% at 08:59)
Market cap £62m
Spectra Systems Corporation (the "Company"), a leader in machine-readable high speed banknote authentication, brand protection technologies, and gaming security software, is pleased to announce its interim results for the six months ended 30 June 2022.
These interim numbers look good, and the company says that H1 figures are in line with its (previously raised) expectations.
Revenues were up 15% to $9.27m in H1.
It’s a high margin business, with adj PBT of $3.7m.
Overheads look strikingly small, so it looks as if SPSY is run on a shoestring, hence the high net profit margin.
Adj EPS fell 7% to 6.2 US cents, due to a much higher tax charge vs H1 LY.
Shares seem illiquid, often with a wide spread, e.g. only 13k shares traded so far today which seems unusually low for a £62m mkt cap company, on results day. So it could require patience to buy or sell in any size.
Balance sheet - is very good . $25m NAV turns into $18m NTAV. This includes $18m cash - boosted by a one-off large up-front cash receipt from a customer, of about $3.9m.
Cashflow statement - note the big divis being paid, plus smaller share buybacks. Again, cashflow was boosted by the $3.9m increase in deferred income (cash paid up-front by customers).
Outlook - sounds good -
"The Board therefore believes that the Company is on track to achieve record earnings and meet market expectations for the full year."
My opinion - the bumper 6.2% dividend yield may not necessarily be sustainable, given that some of the cashflow is one-off in nature. Although the $18m cash pile looks way more than necessary, so the company probably could continue paying big divis from cash reserves, if it wished to.
The most striking thing from reading these interim results is that SPSY seems to have lots of potentially interesting activities underway, including large contracts in the pipeline. Indeed, I know several shrewd investors in this share, who have told me that it’s a small company, where a number of development projects could prove transformational if they come off in scale.
In the meantime, it’s cash generative, and very soundly financed, so you get the best of both worlds - blue sky upside, but without the risks of cash burn, placings, etc.
I’d like to know how sustainable existing profits are? I.e. what proportion of earnings are repeating, and what are one-offs?
With its very low overheads, SPSY looks almost like a development company, where I imagine a team of boffins working on products & services in a lab, with a very lean overhead - e.g. sales & marketing costs were only $478k in H1. This is not a criticism, by the way! If it can throw off loads of profit & cash from a small team, then that’s attractive - although could be dependent on a few key people, possibly?
Overall, I’ve only scratched the surface of this share, but have seen enough to make me intrigued. I can see why several of my shrewd investor friends have congregated in SPSY shares, this looks an interesting company, so do have a read of the commentary with today’s results, which is the most interesting bit. There's also a note from WH Ireland available on Research Tree, thanks to them.
I’ve crunched the numbers, and am reassured that side of things looks OK. The PER is about 16, and the yield about 6%. Doesn’t look expensive, given all the interesting development projects in the pipeline.
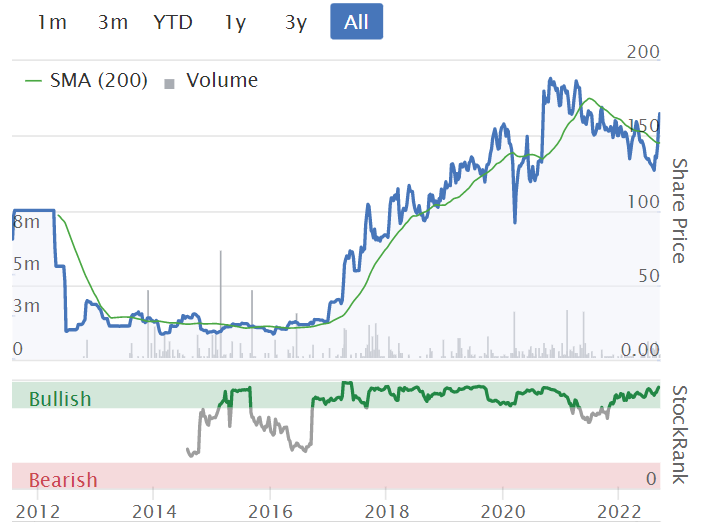
An amazing bull run began in 2016. StockRanks smile kindly on this share too -
.
Accsys Technologies (LON:AXS)
75p (down 16% at 11:03)
Market cap £155m
This update hasn’t gone down well, with a 16% drop in share price today.
This update covers the first 5 months (to 31 Aug 2022) of FY 3/2023.
Accsys, the fast-growing and eco-friendly company that combines chemistry and technology to create high performance, sustainable wood building products, provides the following update regarding recent trading and the status of its strategic growth projects further to its last update on 30 June 2022.
Key points -
Strong demand for Accoya wood product, above production capacity. Strong order book.
Revenues flat at 39m Euros - BUT this is volumes down 24% due to plant shutdown, offset by higher prices.
Energy (gas) price is an issue - adopted surcharge to “help the group manage the cost impact”.
Problems with 4th production line now resolved, but will take 2 years to reach full capacity (why?!)
New plant (Tricoya product) in Hull, being built with a consortium, is also over budget, and behind schedule. Gas prices also an issue. Funding issues. Evaluating all options.
USA JV plant construction - progressing well. Due to commence production mid-2024.
My opinion - I can see why the share price has been poorly performing.
The big problem with Accsys, is that it seems to be expensive, time-consuming, and problematic to scale up production.
On the plus side, the products seem genuinely good, with key advantages (e.g. longevity) over traditional wood, and are in demand.
If it can resolve the production issues, and get higher volumes flowing, then this share might do well. If not, then the share price could remain bogged down.
It’s also clearly leveraged to what happens with gas supplies - good upside if Russia backs down over its invasion of Ukraine, or potential big problems if the situation escalates.
AXS’s last reported balance sheet had good NAV, but it’s very top heavy with fixed assets - emphasising how capital-intensive this business is. A fundraise was done to top up the coffers with 20m Euros in May 2022. Reading that announcement, the funding structure looks complicated, with convertible debt, restricted cash, etc.
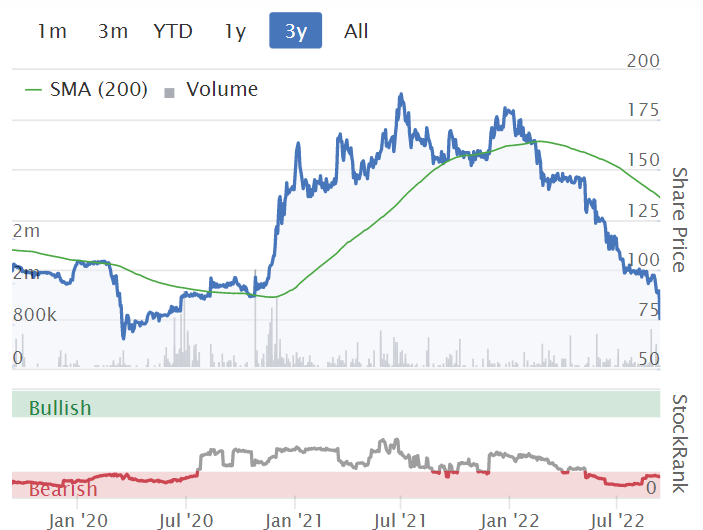
The share price is near the March 2020 pandemic lows, but the share count has risen from 118m in 2019, to 207m now. It’s vital to always check the number of shares in issue, before comparing points on the chart. I suspect that probably won’t have been the last fundraise.
Overall then, this is a complicated special situation. There are too many unknowns (e.g. price/availability of gas, production delays from new factories, funding for new factories, possible need for more equity placings) for me to be able to reach a conclusion on this share. Overall, I can see the potential for the product, but so far this share has been a frustrating example of how difficult it is to ramp up production of innovative, but complicated products. I think I’d rather stick to investments where revenue can be scaled up quickly, cheaply, and easily. AXS is very much the opposite of that. It could come good in the end though, who knows?
The StockRank system toyed with AXS when momentum was good, but has since gone cold on it -
Graham’s Section:
Sigmaroc (LON:SRC)
Share price: 48.6p (+2%)
Market cap: £310m
This acquisitive quarrying company announces a joint venture with steel manufacturing giant ArcelorMittal (you can find its StockReport here). SigmaRoc will invest around €20m and will own 47.5% of the newly-formed company, whose purpose will be to produce vast quantities of lime. The main customer of the new company will be ArcelorMittal, and it will also be supplied with heat energy recovered from a nearby ArcelorMittal plant.
This initiative looks to be an impressive sidebar as SigmaRoc collaborates with a vastly larger company on an apparently equal footing. However, ArcelorMittal will be a supplier, the primary customer and also a 47.5% shareholder of the new company, so I’m not sure how this new company is going to be able to negotiate pricing with ArcelorMittal, so as to ensure strong returns for SigmaRoc investors. I see a lot of potential for governance issues. But hopefully it works out well for SigmaRoc, which has been transformed by deals made over the past year and has an apparently insatiable appetite for more deals!
Interim results are also announced today, with key highlights being:
- Revenue £247.1m, +17% on a pro forma basis
- Underlying PBT £29.1m
- Actual PBT £18.6m
- Cash (30 June 2022): £46.4m
I’m not going to bother printing EBITDA here because it doesn’t make any sense to me as a metric in this case.
I also don’t think we need to concern ourselves with a direct comparison against 2021 figures, because the company has changed beyond recognition after a reverse takeover that occurred in 2021.
Let’s skip ahead to the upbeat outlook statement:
Trading in the early part of H2 2022 has started well, with the Group benefitting from its broad end market and geographical diversification. Demand remains good both for housing and infrastructure, as well as for industrial minerals. The Group has successfully dealt with various supply chain and inflationary headwinds in H1 2022 and has continued to do so into H2 2022, with particular focus on energy costs and continuous operational improvement initiatives.
My view
In summarising this company, I’m immediately drawn to the balance sheet where I find that it has total assets of £866m, or £511m if you exclude the intangible items. Against that it has total liabilities of £415m.
In other words, net tangible assets are less than £100m. That’s a deep discount to the latest market cap, but perhaps the valuation gap has been partially closed by inflation?
I’d also note that the credit facility led by Santander is not charging a very high interest margin, suggesting confidence from lenders, and that leverage ratios are said to be within Sigmaroc’s “target range”.
I suspect that management have many different moving parts to keep track of, both operationally and financially in terms of balance sheet management.
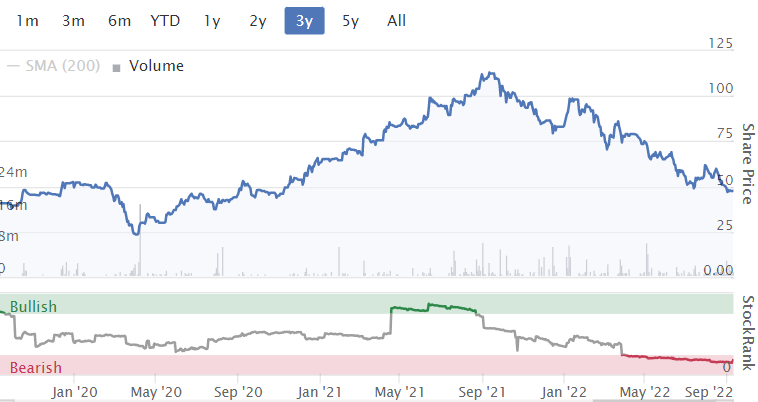
From an economic point of view, this is likely to be a good stock to monitor when it comes to inflation trends: can the sale prices for construction materials and other raw materials outpace input costs? The chart isn’t screaming bullishness yet:
Overall, as you can probably tell, I have mixed views on this one. But I’ll keep an eye on it for future developments.
Made Tech (LON:MTEC)
Share price: 29.9p (-2%)
Market cap: £44m
This is “a leading provider of digital, data and technology services to the UK public sector”. You can review its service offering here.
The company’s IPO was in September 2021, at 122p per share.
It has had a rotten share price performance so far, down by over 75%:
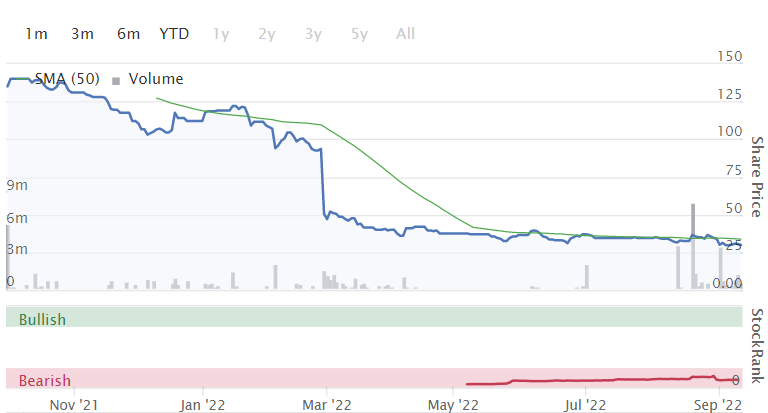
I’ve just looked up the prospectus, to find some details about how this one came to market. It turns out that of the 70 million shares which changed hands at the IPO, only 12 million of these were new shares (i.e. shares sold by the company to raise new funds).
The rest of the shares which changed hands - 58 million of them - were sold by existing shareholders.
This is definitely something to watch out for in an IPO: is the company raising funds for growth, or is the point of it to let existing shareholders get out?
In the case of Made Tech, it appears that the main point was to let existing shareholders get out, with gross proceeds for them of around £70 million, in exchange for less than half of the company. An impressive result, considering that Made Tech’s entire revenues for FY May 2021 added up to just £13m!
But it was sold as a growth story, with revenues approximately doubling each year.
Today’s annual results continue the theme:
- Revenues +120% to £29.3m.
- Gross Profit +125% to £11.3m.
- Adjusted PBT £2.3m (vs. a loss in FY 2021).
“Sales booking” and “contracted backlog” have also more than doubled, but these metrics are based on work carried out several years into the future so I wouldn’t get too bogged down in the details of numbers.
The main point, clearly, is that the story of a very high revenue CAGR (compound annual growth rate) is intact.
We also get a positive adjusted PBT, which is an improvement, but the statutory result is in fact a loss - there are “share based payment expense and related costs” of £2.4m, which wipe out all of the adjusted PBT.
Let’s check out revenue per employee, to see how efficient the company is at turning its headcount into sales.
At the beginning of the financial year, the company had a headcount of 235. At the end of the year, it had a headcount of 478. Let’s make a very rough guess that the average headcount was 350. By my calculations, that makes revenue per person for the year of around £85,000.
I have the impression that Made Tech’s employees are highly skilled (i.e. commanding good salaries). So with revenue per person of around £85k, it’s little wonder that there isn’t much money left over, after paying salaries and covering all the other costs of the business.
(To see how a high-quality company performs when you apply this metric, do it for Games Workshop (LON:GAW) and you’ll find that revenue per person is around £160k.)
It could be argued that the benefits of increased headcount at Made Tech haven’t been felt yet, and that the increased revenues to be delivered in future years will feed through to more positive financial results.
But the annualised revenue run rate is now reported to be around £40m, as of August 2022. If we apply the company’s year-end headcount to that figure, we again get revenue per person of around £85k. It looks like it might be difficult for the company to make big improvements to this metric.
Outlook
The company is purely focused on public sector work and is confident in its ability to steer through political change:
We are mindful of the recent changes within government and the potential impact of this may have on our public sector clients. However, our high level of order bookings, significant proportion of contracted revenues and the embedded and long-term nature of our client relationships and contracts give us confidence in our prospects for the coming year and beyond.
The “levelling up” agenda provides opportunities to expand regionally, and Made Tech has made new hires in Scotland, Newcastle and the Midlands.
My view
As you can probably tell, I’m not keen on this one as a potential investment.
It’s being sold as a play on the “digital transformation” industry, where there is secular long-term growth, but I’m not sure how investors are going to make much money here. As shown by the revenue per person metric, the work appears to be labour-intensive and from a shareholder perspective the overall margins look poor. At what scale would this company be able to earn meaningful profits?
I also note that the company’s employee retention rate collapsed to 73% from 86%, and no explanation for this was given. Given how crucial its employees are to the business, an explanation would have been helpful.
Finally, the company’s statutory loss would have been bigger if it hadn’t capitalised nearly £2m of product development costs.
Stockopedia’s algorithms describe this one as a “Sucker Stock” and I also can find few attractions here from an investment point of view. Some of the air has been taken out of the valuation, but I can see it deflating further:

Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

44 comments
Heiq (LON:HEIQ)
Early stage company with very interesting IP principally in textiles announces interims today. Milestone payment for HUGO BOSS stake very useful, deal with LYCRA company too. I'm hoping the price is at the bottom, I bought a small stake today. Worth a look.
Many thanks for another great podcast Paul. Like so many others - I really enjoy listening to your thoughts and catching up on the events of the week.
Although it is not a small cap, I was wondering if anyone had any opinions on Adidas shares. They seem good value to me at the current price for a quality business with very good management and an obviously strong brand / moat. Such a strong brand should be able to navigate the current inflationary pressures well. Being so global should also remove some risk when compared with more domestic businesses. I see the share price decline down to external factors that will not persist forever. I think as a buy and hold share this entry point is starting to look very attractive.
As I am not subscribed to Europe on Stocko I can't see the Adidas stock rank etc. I have subscribed to the UK and the US as I have a lot of holdings in both regions. However, I think it would be a great idea if Stocko allowed say 2 or 3 searches a month outside of your subscription region. I am sure there are others that would really benefit from this (say once you make your pick on your account - then the shares would be open for viewing throughout the month on your account). There are sometimes one or two stocks that I would like to be able to analyse on Stocko but it would not be worth the additional subscription fee for the extra region. Personally, I think this would make what is already a great service even better. Anyway, just a thought as I look at my locked-out page on Adidas shares.
cheers
Matt
Re Adidas - but would apply to Nike, Puma etc as well
The problem that faces these successful brands is that they are heavily dependent on China for growth and thereby are experiencing several problems, including:
Slowdown in the Chinese economy reducing discretionary spending
Lockdowns reducing footfall in physical stores
Consumer boycotts related to statements concerning Uyghur forced labour-derived cotton from brands trying to appease western consumer tastes
Consumer nationalism favouring local brands Anta and Li Ning (see boycotts)
These are all however powerful brands and prices today look like a good long term entry even if they might fall further if USA goes into recession. The trends driving their success are not going into reverse.
Some very good points BnB, many thanks.
You're quite right about China as its their largest growth market. It currently accounts for about 22% of sales. However, this also means they are well diversified elsewhere (the other 78% of their business is showing 'nearly' double-digit annual growth in every other region - North America being the lowest growth rate, but still at 9.1%). Also, many of the China related issues could be viewed as temporary with still very good future growth over the next decade. Especially for large established western brands as they seem to benefit hugely from natural demographic changes. The Chinese middle class will imo be far larger over the coming years and the thirst for western brands is part of their modern culture - I don't think the push back towards consumer nationalism will be too much of an issue. I suppose this is where one has to take a view. The last quarterly update showed a 16% decrease in revenue from China. In my opinion this decrease is down to external factors that are out of the control of the company and so this performance is reasonable imo given the huge number of headwinds in that region.
Great businesses can't always outperform every year. If we base our investments on all future revenues etc, then short term headwinds like these can create to a good entry point for the patient investor. I would rather take a view today and buy the shares while the revenues are down a bit and the pe ratio has come down a lot. I do not think these current global issues will last for many years and at some point I expect them to be back to record earnings and at that point when the numbers are better the fickle market will re-rate on a higher multiple. But one has to have the view that these Chinese and global issues won't last for many years.
One other point is what one's opinions are on athletic fashionwear; will this continue to grow in popularity (this is not guaranteed as fashion tastes are always changing).
I have not looked at Puma as I don't like the brand. I like Nike a lot but compared to Nike it appears you are getting a far 'cheaper' valuation with Adidas. Nike has 25% of the sports apparel market - while Adidas has about 15%. I don't know why Nike deserves such a large premium. From my research Adidas appears to be growing their margin and revenue better than Nike - and this appears to have been the trend for some years. Also, the direct to consumer model should increase margins in future years for both Nike and Adidas.
cheers
Matt
All good points and I would be a buyer of all three at these levels - instead I'm already a holder of the three as a basket of athletic stocks. Nike gets a premium rating because of its market leadership first and foremost and its more consistent track record of eps growth and higher ROCE and because, well, USA!
Adidas looks like the value option but it has underperformed peers so perhaps for a reason. My bank has recently moved to Hold and I note the CEO has been ejected.
Re Made Tech (LON:MTEC) - A more nuanced view (than Graham’s)
Time will tell on profits of course but gross margins are robust in the region of 38% and operating margins should eventually approach those of direct competitor Kainos (LON:KNOS) at around 18%. Given they operate in the same market and with a similar range of services why would it not - given solid execution?
Graham, I think you've overestimated the wage claims of a high proportion of the staff. Recruitment this year has a high proportion of "academy" hires, who are data gatherers rather than data analysts, trainee coders rather than experienced programmers - ie relatively cheap and with a higher margin per employee than you have assumed. But the question remains whether profits will emerge. If they are not visible today, then logically recruitment must be running well ahead of deployment, which bodes well for meeting FY23 objectives - you did acknowledge this possibility.
One of the keys to higher margins and profits is to develop their own IP - which is already underway and would account for the capitalised £2m development costs. So this is an area to watch.
I also believe there is a time lag in restoring margins per employee to pre-Great Resignation levels. An erosion of workforce that has been endured by all IT employers this year, and to which you alluded, means hiring replacements at higher wages to work on projects sold on a lower cost basis - this will reverse more profitably in due course.
The business is obviously still investing (in people) for growth and that will hit profitability. But the runway for expansion is considered by experts to be huge (>20% CAGR in DX through 2030). Whether Made Tech is a winner remains to be seen but I have channel checked their satisfaction levels and tested some of their work myself and been pleasantly surprised.
I used to outright own a competitor in this field (Government DX) for more than a decade and all I have further to say is that we found it deeply rewarding as a sector - as have investors in Kainos, or, on a totally different scale, Accenture. In the end, they are all software houses riding an unstoppable wave of technological progress. But Made Tech, reflecting its inherent uncertainties, is substantially cheaper on any measure!
Hi BnB,
Graham wrote the section on Made Tech (LON:MTEC)
Regards, Paul.
Sorry Paul. I’m multitasking watching the tennis from last night.
Made Tech (LON:MTEC)
BnB - thanks very much for sharing your perspective on this! You're right that MTEC has cheapened a lot already (e.g. it's cheap-ish on price to sales now, and a lot cheaper than something like Accenture). If margins per worker are better than I perceived, and if they further improve, then my concerns might already be priced in. Best of luck if you are a holder! Regards, G.
Thanks Graham. Time will tell if my faith is justified but Made tech’s profits are certainly lagging revenues today so I respect your concerns
Made Tech (LON:MTEC) Thanks for all the comments Graham and BnB. There is a management webinar today 16.9.22 at 12 noon for you to ask further questions and make your own judgement. Register here.
Spectra Systems (LON:SPSY) (I hold)
Hi Paul,
You asked: "I’d like to know how sustainable existing profits are? I.e. what proportion of earnings are repeating, and what are one-offs?"
I'm not sure about earnings, but there is definitely underlying repeat revenue. A few examples:
Within this segment revenues have fluctuated between $1.3m and $1.8m every year since 2017 and seem to be made up of a number of long term contracts.
Additionally there is a 10 year service contract in place for these sensor sales from 2024-2034 worth $14.8m i.e. on average $1.48m per year.
Note that this value has already increased twice this year (from $8.8m to $10.8m on 15th June 2022, and then again to $14.8m on 15th August 2022.)
$8.8m is being paid by this customer before 2024 for "the development of...new [sensor] capabilities."
The fact that 78% of the company's sales were within the USA last year implies to me that the big central bank customer is the FED. So if there are contracts in place until 2034, I'm inclined to believe that a lot of these future revenues are secure.
As you mentioned, there is a core cash generative business that's providing a foundation for the company to expand into other areas. In the meantime I don't understand why the dividend would not be secure and why growth would not continue.
---
Continuing my clearly bullish stance, I thought today's results were excellent.
The increase in cash was a nice surprise.
K-cups revenue is forecast to hit c$2m this year by my estimates. It was c$300k back in 2020, so that's decent growth for a new product in such a short period of time.
It was also nice to see gross margins edge higher, as forecast by the company at the full year results.
I remain a happy holder.
A
Thanks abtan, that's really excellent extra detail, thank you!
The sensors contract struck me as very large. Presumably that's likely to be lower margin?
Thanks again, Paul.
Spectra Systems (LON:SPSY)
"The sensors contract struck me as very large. Presumably that's likely to be lower margin?"
Highly likely, though hard to confirm.
I imagine with gross margins regularly in excess of 65%, there should still be a large enough buffer for a sizeable portion of the revenue to flow through to the bottom line, even at reduced margins.
Annual revenues are currently c$18m. That one contract, even though it's relatively short and possibly on a lower margin, should take revenues closer to $35m-$50m, at least for a couple of years.
A
Paul, please be aware that the Stockopedia numbers for SPSY are seriously messed up. (This bug is an old bugbear of mine which your colleagues never find time to prioritise). Check the market cap for a start (and EV) - just multiply the shares with the share price and see how accurate the Stockreport is.... (You may want to correct this error in your article, BTW). This error flows through to most valuation metrics (certainly the EV-based ones I like to use, possibly not PE to the same extent).
My hypothesis (from looking at this in the past) is that the error is caused by Stockopedia choosing to use the SPSC share price to "drive" metrics for both SPSY and SPSC. (SPSC last traded at 150p, and was stuck for months on 135p and very rarely trades, so a poor choice). Would you be brilliant if you could raise this...
So, warning to all: Do NOT trust the StockReport/Stockopedia metrics for SPSY!
I hold. Thanks for a good write-up and reader comments.
PS: Reporting my own post in case it helps the team think about / look at this again
vprt - thanks for pointing that out - stockopedia really should be on top of this or at least frame a reason why they show a divergence.
I notice that have still not changed £RDSB to Shell (LON:SHEL) in transactions.
Two more pieces of info over the weekend about French and German railways buying hydrogen powered trains. (Well, hybrid actually). It keeps coming up as a power source of the immediate future. Must be good for ITM. Anyone else interested in rhis area as an investment?
Hi Raleigh4343
I hold ITM Power (LON:ITM) AFC Energy (LON:AFC) and £CWR .... all are very volatile share prices so not for the faint hearted.
I have invested in them in their early extremely volatile days but exited (lost money) and kept away from them for quite a while.
It might interest some that ITM Power (LON:ITM) reports 14/9, Ceres Power Holdings (LON:CWR) 22/9.
I perceive that in the longer term there will be value in the Hydrogen market.
I also have invested in and watch some North American (US & Canada) Hydrogen companies $PLUG $FCEL $BLDP to list but three. As I do with some European companies Powercell Sweden AB (PCEL) and NEL ASA in Norway (NLLSF).
But, it is an emerging sector and although large government investments are being injected into it, share prices are really volatile.
For those interested in the UK Hydrogen space, ITM Power (LON:ITM) AFC Energy (LON:AFC) & Ceres Power Holdings (LON:CWR) do three quite different things. Which is why I hold a small amount in all three.
ITM Power (LON:ITM) is in effect building a Hydrogen power station as well as building and selling power cells.
Ceres Power Holdings (LON:CWR) is in effect a Hydrogen technology company, it form relationships with large organisation to partner with them to create Hydrogen technology based products whereby the big partners then distribute these products into their big customers bases.
AFC Energy (LON:AFC) has now began to focus on targeting Hydrogen technologies such that they aim to replace 'off grid' diesel/petrol generators. Such as the generators used on large building projects.
If any are interested to dig deeper I recommend searching YouTube and watching various vids. from these companies, and other sources, to gain an appreciation of the sector.
I sense the strength for this market will be supplying energy to big transportation, think ships, planes, large trucks and trucking fleets. Replacing off site fossil fuel generators, think data centers, building projects, emergency backup facilities. Pure play Hydrogen power plants supplying a defined campus, or feeding into a grid.
As you can see I am bullish on it, but think it will be a bumpy ride and probably requires a level of knowledge to have convictions to hold through volatility.
Regards
Howard
Hugely interesting and helpful. Thank you, Howard
Many thanks for such a great reply.
Thank you Howard, I agree with your last 3 paragraphs. I can't resist a small small cap and we hold Getech which is currently transitioning from solely supplying clever software programmes to mining and oil companies, to include Hydrogen storage and expertise. Japan and Germany seem more convinced about Hydrogen use but interest is growing here too now. I shall research the 3 you've mentioned with a view to investing.
I see Sanderson Design (LON:SDG) have appointed another broker. I know that's often a prelude to a fundraise but they have quite a bit of cash on their books so that doesn't feel likely, unless they're looking to make a big acquisition. Maybe this is just to attract shareholders given the depressed share price?
Hi PatrickL,
I also wondered about why Sanderson Design (LON:SDG) had appointed Singers as a new broker. It certainly doesn't need to raise cash, unless if a large acquisition was in the pipeline?
From my point of view, Singers are a friendly broker, that likes to get info out to private investors - e.g. short broker notes are available on Research Tree. Whereas Investec are not interested in us at all. Hence why any small cap would use Investec, Numis, Peel Hunt, etc, it a mystery to me. They actively try to stop us getting information & meetings with their clients! Yet we're the market for small caps. Crazy really.
Regards, Paul.
Beeks Financial Cloud (LON:BKS) has held its rising channel through a very tough few months. (Impressive for a growth share). IMO it’s trading at the bottom of its range and has significant headroom in the short term. (I hold).
What is also interesting about Beeks Financial Cloud (LON:BKS) is that Resistance has now become Support. It would appear that Support is forming around 130p and at 143p there is potentially plenty of upside going forwards. Also the Stochastic is approaching the lower level of 20 which represents a good point of entry. Also, the share has recently formed a double bottom which is another positive sign.
David (I don't hold - yet).
Morning Paul and thanks for the Beeks Financial Cloud (LON:BKS) write up - I have always been quite tempted here, my main concern is that Capex will always hold back actual earnings as they constantly spend to have the bestest, fastest, solution - Interesting to hover over the Capex per share line on the Stock Report to see how it is showing no signs of slowing at present. Have you considered this at all or is peak spend over perhaps?
I wouldn't expect it to be over for a long time if they continue to see revenue increasing at the current rates. They will however be able to generate economies of scale from purchasing ever increasing amounts of the same products and that should help.
I am honestly clutching at straws here but if you look at the history of companies like AWS you can see that there were around 10 years of no profits before they were able to grow out of the cost base. Beeks have a few advantages of being able to charge a higher price for the "niche market" but have that outweighed by higher costs.
To me this is about driving the revenue up and finding someone who can bolt it onto their business eventually through an acquisition. I would hope though before then Beeks can get the revenue up several fold from where it is today.
Hi matylda,
Yes, it's the capex at Beeks Financial Cloud (LON:BKS) that seems the main focus of bears. It doesn't worry me, as buying all the kit is necessary both to expand the range of markets that BKS offers connectivity to, and is necessary for new contract wins. I recall mgt saying that capex is typically 80% expansion, and 20% upgrades/replacement. Its just the nature of the business - capex has to be done first, then recurring revenues flow afterwards. As more customers sign up, then BKS gets increased business flowing through its fixed assets. So there's good leverage there.
The revenue line looks like it's going exponential, after years of slowly creeping up, that's the main thing that makes BKS looks so interesting right now. But the valuation is already c.£100m, so you could argue it's already priced in more growth.
Regards, Paul.
Thank you both, will keep a keener eye out for the next update, in particular the capex, which is still (perhaps rightly so, as they are still in expansion mode, as pointed out) rising more exponentially than Revenue, CAGR 50% vs 35% - Assuming this comes down, without further dilution, hopefully earnings will follow suit.
Thoughts on Spectra Systems (LON:SPSY) ints please.
Interims from Sigmaroc (LON:SRC) and Spectra Systems (LON:SPSY) both look positive on initial reading but need to re-read to get a better understanding of the detail. I have holdings in both.
Sigmaroc (LON:SRC) seems to have performed well given the nature of the business and European focus. Hopefully it will now use cash generated to fund expansion and avoid issuing new equity. The agreement with ArcelorMittal looks really interesting.
Thoughts on either welcome.
Does Stockopedia show which Index a company belongs to? e.g. £VOD.L is in FTSE100 but not classified as such anywhere.
on the stockreport page for Vodafone (LON:VOD) there is this:
in the "Profile Summary" section. Is that the info you are after?
Edit: sorry, it appears the image upload functionality is broken (or I am not using it correctly). In any event, the index membership appears to be listed in the "Profile Summary" section for Vodafone (LON:VOD)?
I'm using the mobile app and can't see a 'Profile Summary'. Will check on the desktop browser later. Thx
this is what I was on about (let's see if I can get it to work now):
(this is from a desktop)
Hi all,
Not one that's been covered much on the SCVR (yet!), but some of you might be interested in the below write-up of Assetco (LON:ASTO)
https://www.upsidedownsidecapi...
I think it's attractive at this point, with significant potential upside, and the downside quite well protected. The possible Parmenion transaction as reported by Sky (link in write-up) could really help to highlight value. Furthermore, it's still early days in an exciting journey to build an asset & wealth management company, led by people who were formerly in senior positions at Aberdeen Standard Life, which is a big deal for a small-cap like this.
Best regards & welcome questions if interested.
In my opinion, it's now at a place where it needs to consolidate and deliver on what it has acquired..
I know the directors of Assetco (LON:ASTO) are not short of a few bob, but interesting to see that Campbell Fleming has stuck his hand in his pocket for another £100,000 worth of shares. And this after the stock has risen by 15% on the back of the Sky/ Parmenion story.
I find this reassuring, as my reading of the Sky story seemed like it was a “leak” from the current owners’ side. Therefore my interpretation was that the £300-£400m valuation was AssetCo’s their PE partner’s estimated valuation, rather than the value that any potential buyer has indicated they were prepared to pay. (My interpretation of course could be wrong ).
If Parmenion is worth £300-£400m, then AssetCo’s 30% holding would be £90-120m. This is not far from the current market cap and there is net cash. (I hold).
Yes, it's an interesting one.
Year high is 177p and now at 71p to buy ( the year low is 58p)
Since June 2022 directors and associates have bought over £1.4m of shares ( Harwood Capital some £576,000 ) at around 73p - which is substantial and to me a buy signal.
Amongst the general doom and gloom, a really nice trading update from Beeks Financial Cloud (LON:BKS) :
"Beeks has delivered a record trading performance in the year, delivering
growth on the prior year and in line with upwardly revised market
expectations.
The Group has exited the year with Annualised Committed Monthly Recurring
Revenue of over £19.3m, growth of 40% on the prior year, providing a strong
basis for further growth in FY23."
"The success of Proximity Cloud and Exchange Cloud have contributed to a
fantastic trading performance in FY22 and we enter the new year with a record
sales pipeline and confidence in our ability to continue to capitalise on the
significant opportunity ahead."
It looks like Beeks Financial Cloud (LON:BKS) have really found their niche and are providing solutions for which there is a clear and growing demand?
Tier 1 customer looks good. I wonder what the exclusivity period is and will it help or hinder future sales?
Looking forward to any thoughts from Paul. (I hold)
I am super excited about £BKS and hope to be an holder long term (no takeover please) as it continues to both build out its capability and its customer base. Profitability will be limited as it invests in the infrastructure and I am more than ok with that until it gets to the scale it needs.
Longer term I expect it to have profitability of around 30% in line with other cloud serivce providers (AWS, Microsoft etc.)
"It's too early stage to have a decent StockRank. So the StockRank system asks us sternly, are you absolutely sure about this?!"
made my morning - thanks Paul! :-)