Small Cap Value Report (Mon 13 July 2020) - CMCX, GPH, YCA, NCYT, AVCT, MWG

Hi, Jack here - Paul is delayed in London so I'm taking over until he gets back.
With lockdown easing, I finally caught the train back from York to Oxford myself at the weekend. As much as it pains me to say it, the weather is a bit better down south…
Some quick news to kick off. CMC Markets (LON:CMCX) has appointed Brendan Foxen as its new chief technical officer. Foxen was previously CTO of Contino, a digital transformation consultancy, where he helped grow the consultancy from 16 to 400 employees. CMC says the appointment will ‘will support the accelerated development of the many opportunities that are in the pipeline’, which sounds promising.
Of course, the group’s shares have been tremendously strong given recent market volatility - but given the above, maybe there is more growth to come?
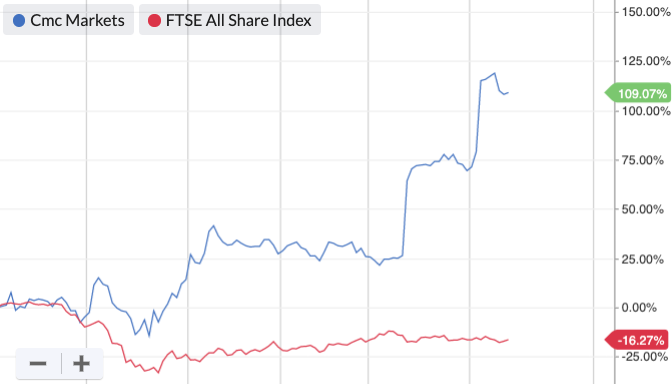
On 12.3x forecast earnings, that still looks like a modest valuation for a high quality, growing company. The question is if the company can replicate this year’s (probably) bumper results or if they will normalise in time towards a lower level.
Note that broker forecasts have nearly trebled for FY21 but FY22 estimates are anchored at around 16p.
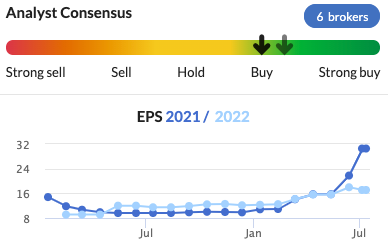
If you treat FY22 as a more ‘normal’ earnings level though that still puts shares on a forecast year 2 PE of just over 20x. So if there are good company-specific growth opportunities here, it could be worth a closer look.
Anyway, onto some results.
Global Ports Holding (LON:GPH)
Share price: 68.98p (-11%)
No. of shares: 62,826,963
Market cap: £48.75m
This is an absolute dive bomber of a share price chart. Global Ports Holding (LON:GPH) has been a bloodbath for shareholders unfortunately, and COVID has ruined recent trade.

Shares are down 11% today as GPH has abandoned its pursuit of a premium listing. This was an explicit ambition mentioned in the group’s IPO documents, so it’s a blow that three years later this has not materialised.
The group says:
These decisions have been taken in order to strengthen the Company's ability and provide flexibility to respond to challenges created by ongoing Covid-19 disruption to the global travel sector and the economies in which the Group operates.
A lot of this has been priced in. Back in March its shares tumbled from around 200p to its current levels.
It’s an unusual company. An independent cruise port operator with a presence in the Mediterranean, the Atlantic and Asia-Pacific regions and one large shareholder owning some 62.5% of the company.
In the group’s statement, GPH repeatedly reiterates its commitment to strong corporate governance. This has the ironic effect of making me wonder about the company’s corporate governance...
Even if that’s an unfair first take, the company has nearly ten times its equity in net debt and poor F and Z-Scores:

That said , the group does appear to be able to generate a good amount of cash flow in normal conditions. If it could get back to 2018 levels, that would put its shares on just over one times ‘normalised’ free cash flow…

In all though, there are plenty of warning signs to put me off any kind of contrarian bet. If there’s one thing we’ve been looking for in recent months regarding Leisure companies, it is balance sheet strength. It looks like Stockopedia is right to class this one as a Value Trap.
Yellow Cake (LON:YCA)
Share price: 224p (+0.45%)
No. of shares: 87,593,910
Market cap: £195.33m
Yellow Cake (LON:YCA) is an interesting company some subscribers have mentioned before that is worth bringing to attention. There’s no trading update today but there is another share buyback announcement.
This specialist operation was set up by the experienced and well connected investment banking team at Bacchus Capital as a ‘unique uranium commodity investment vehicle’. There really aren’t that many plays on the uranium price so YCA is worth flagging on that basis alone.
It’s recently listed and does not have much of an operating track record, so that is a risk. But this kind of stock can be hard to value, which should present opportunities from time to time. Management seems to think YCA’s shares offer good value as its news feed is littered with similar buyback announcements.
The team here looks financially savvy, with decades of experience in the markets. If they think YCA shares are attractive at current levels then it might be worth looking at in a little more detail.
The group has a VM Rank of 99 and strong relative momentum. There’s also been a lot of community buying recently:

The group operates almost like an ETF, buying and holding the physical commodity. There are no operating risks and no mines to run, so it’s a very low cost structure.
Here’s how it all works:
- Yellow Cake acquires uranium through its 10-year framework agreement with Kazatomprom (the world’s largest and lowest-cost producer)
- This gives it the right to purchase up to $100m of uranium per year from 2019 through to 2027, with the purchase price based on the spot price
- YCA has a storage contract with Cameco in Canada (the world’s second largest producer). YCA’s 9.7mmlb of uranium is stored here.
- YCA’s activity is informed by 308 Services’ uranium commodity market expertise.
Then you just sit back and bank on stronger uranium prices, if that’s your view.
The initial digging I’ve done into the uranium market suggests attractive fundamentals, with steady demand growth jutting up against supply cuts and restricted investments.
Market
After a couple of down months, the spot uranium price rose sharply during March, increasing 11% to US$27.40/lb. Transactional volumes increased markedly totalling 9.0m lbs with a monthly record number of transactions.
According to YCA, it is likely that the principal recommendation of a pending Nuclear Fuel Working Group report will support a uranium purchase programme by the US federal government.
Meanwhile forward uranium requirements remain substantial especially for nuclear utilities in the US and EU.
In March, Cameco announced that the world’s largest uranium mine would be placed on safe care and maintenance for an initial four weeks, subject to ongoing assessment. On 13 April Cameco announced that it would extend the temporary shutdown at Cigar Lake from four weeks to an indeterminate period.
Then in April, Kazatomprom announced that on-site staffing at its uranium mines would be reduced to minimum levels for a three-month period, resulting in the loss of production estimated at 4,000 tU (10.4 million lbs U3O8) for the year.
Similar shutdowns have occurred at other sites around the world - so might a supply freeze lead to a price hike? It seems like that has partially occurred, at least temporarily suspending a downtrend in uranium prices.

Source: Yellow Cake presentation
My view
In YCA’s recent quarterly trading update, management said:
Supply side pressures have been building in the uranium market for some time, as low prices have forced many producers to cut output. These have now been exacerbated by the effects of Covid-19, which has resulted in further downward pressure on uranium production, taking yet more supply out of the market.
We have already seen uranium prices respond with a strong uplift in March, and this has continued into April with the spot price exceeding 30 dollars per pound. Yellow Cake remains uniquely positioned to benefit from this supply side pressure and the resulting uranium price increases.
All in all YCA looks like an interesting and fairly unique company. It could offer portfolio diversification as well as good Value and Momentum. I don’t have a developed view on the uranium market, but the recent share buybacks and shareholder activity suggest that there could be something worth investigating here.
At current levels there could be scope for a rerating but it’s not one I know well so DYOR.
There is a recent interview with the CEO over at BRR Media (link here) for those that would like to get more of an insight into this company.
Novacyt (LON:NCYT)
Share price: 267p (-0.19%)
No. of shares: 58,094,754
Market cap: £156.29m
I’ve been slightly wary of looking into companies with business directly related to COVID-19 as there’s potential for stocks to get hyped up to unreasonable levels on little news flow.
Take Filta (LON:FLTA) for example - the deep fryer cleaner whose shares more than doubled in a week on the news that it was trialling a COVID-19 related sanitising service. Perhaps something like that might materially improve the group’s prospects - all I know is that since then, the group’s shares have retraced somewhat.
That said, somewhere in amongst all the COVID-related newsflow, there will be some real winners. Novacyt Sa (LON:NCYT) is one such contender after rapidly developing and launching one of the world's first molecular tests for COVID-19 back in January. This development, the group says, ‘established Novacyt as a pioneer and a leader in COVID-19 diagnostics’.
A bold claim - and one that looks to be backed up by some transformational half-year numbers...
Highlights
NCYT is firmly in Momentum Trap territory right now after a stratospheric first half of 2020 - just look at the relative strength on display here:

Shareholders are expecting big things - and NCYT begins this update with a bang: ‘Sales growth of more than 900%, debt-free and significantly cashflow positive’.
In terms of the actual (unaudited) figures, we have:
- A 900%+ increase in revenue from €7.2m (£6.3m) to €72.4m (£63.3m), with 91% of revenue coming in the second quarter,
- Anticipated EBITDA of over €45m (£41m),
- A cash position as at 30 June 2020 of €20m (£18m) compared to €1.8m (£1.6m) as at 31 December 2019.
- NCYT has achieved this even after significant investment to meet continued demand for the COVID-19 test expected in H2, and
- The group has paid down all outstanding debt, making Novacyt debt free for the first time in the Company's history.
That’s some pretty transformational trading momentum.
A big unknown is just how long this window of extremely high demand for COVD testing will last, but you can see that although Europe is no longer the eye of the storm, the number of global daily new cases continues to rise.

Some contracts for NCYT’s test have also been extended into the second half of 2020 and in some cases into 2021. Novacyt expects significant ongoing demand for COVID-19 testing well into the next calendar year.
In the US, the Company has signed a major distribution agreement for its COVID-19 test with a new global strategic partner. The US is delivering significant sales growth for Novacyt and a ‘major new agreement with a global strategic partner’ will help to further open up this market. Furthermore, the agreement can be expanded into new territories in time.
My view
NCYT’s test is being sold worldwide. The group is capitalising on the opportunity and has invested in a significant scale-up of operations, while paying down debt entirely. And even after all that, cash has piled up on the balance sheet.
Demand for the COVID-19 test remains strong, with June sales of €25.4m (£22.5m) showing the sixth consecutive month of growth. If you just linearly extrapolate that for the rest of H2, which might be conservative, you get £63m of revenue in the first half and an expected £135m of revenue in the second half (£198m total).
Heading over to the group’s 2019 Annual Report, it looks as though NCYT generated a gross margin of c64%. Applying that to my rough take on FY20 sales would give possible gross profit of nearly £127m.
That would make for a price to sales of 0.78x and a price to gross profit of 1.23x, which seems low to me given the trading momentum.
Alternatively, we can work out the group’s half-year EBITDA margin as 65%. Assuming that holds steady and using the above simple revenue forecast, we come to full year EBITDA of £128.7m. The company is now debt free with £18m of cash. This cash pile could build but let’s assume it stays the same. That makes for an updated enterprise value of around £138m. Put those two estimates together and it would make for an FY20 EV/EBITDA of just 1.07.
Maybe my assumptions are way off here, but this looks cheap given the prospects. If anybody has spent a little more time forecasting revenue it would be great to get a range of opinions on this point.
This is undoubtedly a transformational period for Novacyt and it looks to be seizing the opportunity with both hands. I wonder if the market has fully priced in its short term growth prospects. More importantly, what foundation for future long term value creation can NCYT develop with its rapidly escalating levels of revenue? And what in-house expertise can it leverage with all the cash?
The group’s CEO, Graham Mullis, commented:
The Company has rapidly established itself as one of the market leaders in COVID-19 PCR testing, with a significantly increased customer base, a recognised reputation for the performance of its products and established multiple significant strategic partnerships. This solid foundation, combined with a strong financial performance, will enable us to greatly enhance and accelerate our strategy for delivering long-term value to shareholders.’
To me that is the most promising part of the whole statement - perhaps NCYT can use current trading to power itself on to bigger and better things. It’s interesting to see the higher levels directors have bought stock at:

I’ve seen enough here to want to take a closer look - particularly since the share price is down nearly 50% from the April peak of 491p.
Avacta (LON:AVCT) and Modern Water (LON:MWG)
AVCT share price: 267p (-0.19%); MWG share price: 2.14p (+15.68%)
AVCT shares: 268,125,159; MWG shares: 524,693,214
AVCT market cap: £297.31m; MWG market cap: £9.71m
Rounding off the COVID-related newsflow today, we have the Avacta (LON:AVCT) collaboration with Integumen which will be facilitated by Modern Water (LON:MWG) ’s ‘award winning’ Microtox water contamination system.
All of these companies are low ranking Momentum Traps with blood red Financial Summaries - it’s not a part of the market I usually look at. Take Avacta for example:

But after reading through NCYT’s update above I did end up warming to the stock, at least enough to want to do a bit more research. So let’s look at this story too.
Avacta says its affimer agents can be used to detect coronavirus in waste water. Today’s announced collab with Integumen will see its affimers used in real-time bacteria alert systems developed by Integumen, which will then be integrated into Modern Water’s sensors.
Upon successful completion of an evaluation at a University of Aberdeen lab, AVCT and Integumen will enter into a supply agreement that will see the latter retrofit Modern Water’s microtox systems with the new sensors.
How material is this development, I wonder? It’s all quite early-stage. The proof is in the pudding, as they say - at least with NCYT we can now see the 900% increase in revenue.
My view
It’s too early for me. This isn’t my area so I will wait for more concrete financial information in Avacta’s first half trading update, which should be coming out soon judging by the group’s 31st December financial year end.
With NCYT at least we are seeing the early signs of the company graduating from loss-making story stock to something more profitable. Perhaps in AVCT’s next results we will see confirmation that it is following a similar trajectory.
As for Modern Water - highly speculative, loss-making micro caps that suck up cash are just not a part of the market I focus on. I’m particularly put off by MWG’s poor financial health scores:

You get the occasional big winner here, and some investors are presumably specialists in this space. I’m sure there are shareholders reading so if you have a more informed view of these companies’ prospects then leave a comment and let us know.
I wish AVCT and MWG good luck in this endeavour but it’s not something I can add value on at this stage.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

135 comments
Chatter on ADVFN suggests there has been a short report and attack on Manolete Partners (LON:MANO) today, which would explain the sharp fall. Has anyone here read the report?
manolete reads very badly take your loss sooner rather than later
any idea of how to stop my browser automatically uploading to the .app page - I like search old value reports but can’t in this web based app version
Interesting picks again Jack.Enjoyed the report and the comments. Thanks
It's about 36 hours from Burnley to Morocco, so even if low cost production in Leicester is shut down, I expect they could operate a fast fashion business sourcing there.
Assuming customs clearance is speedy.
Moving to Myanmar, Bangladesh or Cambodia would slow things down.
Anybody knows what the black candlesticks are in IG Volume indicator? Are these shorts?
Not enough body to add colour I would say
Might represent a day when the price closed at the open value ie no change?
No, this is a 1-min live chart screenshot. So those blacks are, as you can see from time stamp at the bottom, for the last 1 hour.
your chart covers 6 weeks
Regardless, whatever time period, it represents zero change in price. Green =price up, red=price down. Candlestick charts dont show ‘shorts’. They show trading range and open/closing price for that period.
It looks to me like a period of zero change from open to close. Which is interesting that a big volume spike gives no price movement (in this example).
£YCA Yellow Cake- based on the current spot price of circa $33/lb the NAV is £2.95. Today's share price is £2.25. The company is currently buying 90,000 shares/day in the open market. There is a uranium supply deficit, which is likely to increase, and spot price is expected to rise to $45 to $50 /lb in the next 12- 18 months. This share is a direct bet on the price of the commodity which in my opinion has asymmetric risk/reward.
Also, Geiger Counter Geiger Counter (LON:GCL) is an investment trust specialising in the commodity and associated miners. As then commodity price increases the equities should do very well.
As we've seen with Gold and the miners are breaking-out to new highs. The same formula should play out in the uranium market over the next three years.
Hi Aston,
Just looking at this myself. and get a slightly different NAV. Only thing I am unsure on is number of shares to use.
Regarding the supply deficit, could you point me in the direction of research in this area.
Cheers
El
My NAV calc
Number of shares 88,215,716
Uranium in storage 9,320,000
Spot price $33 per lb
£/$ 0.79
=(9,320,000*33)/88,215716 = $3.48*0.79= £2.75
Anyone knows what the BLACK candlesticks are in IG Volume indicator? See screenshot below for BOOHOO. Are these short positions entered into? Thanks.
Hi, my guess would be the black lines are where the system can't tell if the overall volume at the time aggregate shown was towards bids or offers i.e the price traded is midway / halfway between the offer and bid price for that time period.
Not sure but I think the black bars are days when opening price and closing price are the same i.e. neither up (green) or down (red)
Any views on the LUCECO results this morning, given you guys thought the last update was too good to be true?
Hi Jack,
I love the companies you choose to cover and the balanced view you put forward.Really like your information on £CMCX. It a reasonable way to value the company as you say. Valuation wise I continue to view Cmc Markets (LON:CMCX) undervalued.
I suspect the new level of revenue for spread betting firm will be higher for longer for a couple of reasons. (Cmc Markets (LON:CMCX), Ig Group (LON:IGG), Plus500 (LON:PLUS)).
I have no idea if that will play out this time, but the continued upgrading of the broker forecast makes me hopeful this is the case.
As always DYOR
BSV
Thanks BSV!
In everything we have seen and experienced over the past couple of months, my one real regret is selling Ig Group (LON:IGG) earlier in the year. Cmc Markets (LON:CMCX) could be an even better pick going forwards if it has some good company-specific growth projects lined up.
All the best,
Jack
The Boohoo (LON:BOO) scandal highlights a very interesting aspect of behaviour which is the difference between shared knowledge and common knowledge. You can have shared knowledge: where everyone knows the same thing, but this is not the same as common knowledge: where everyone knows that everyone knows the same thing.
I would argue that it was shared knowledge that Leicester had an issue with working conditions in the garment industry. There was a select committee report presented to the government on the issue.
What has changed is that the publicity surrounding the issue and in particular the role it may or may not have played on the Leicester lockdown, has shifted the issue from shared knowledge to common knowledge. And why we have government ministers suddenly declaring their "surprise" at the affair.
Shifts from shared to common knowledge can have profound effects since they force people to take action. The "cheating husbands puzzle" is a good example of how this leads to a rapid transition of an equilibrium state even though reality has not shifted in this time.
This is why ethical funds will sell down even though you may question how ethical their other holdings are and why we are seeing short term weakness.
Long term the impact will be determined less by supply & demand for shares but by valuation, and in particular, whether there will be lower growth due to boycotts (unlikely IMO) or margin compression due to higher costs (likely IMO.)
Fundamentally Boohoo (LON:BOO) business model is ripped to shreds. Their core USP, compared to other fast fashion brands, was Quick and Local and Small Batch supply chains. So they could produce small batches of the very latest styles, and get them on the shelves in weeks. Instead of the months and huge orders that is the requirement from ordering overseas from the likes of Vietnam or Bangladesh.
Other fast fashion retailers have similar "unfair labour" issues. But its easier to hide them, as the labour is in third world countries, where the local governments do their best to sweep it under the rug too.
Boohoo either need to do one of two things - start paying more for production in Leicester, and also spend more on supply chain monitoring. Two things that will hit margins badly, as well as sales, as they'll have to increase prices.
Or they need to move production overseas, but then lose their competitive USP, and become just another me-too fast fashion brand.
At the risk of going off on a tangent, this issue has some parallels with what Tesco (LON:TSCO) are up to. Last week it was reported Tesco has suddenly demanded "discounts" of 50% from their supplier base. How can smaller suppliers hope to get anywhere meeting that ridiculous demand unless they encourage their workforce to work shorter hours and claim welfare benefits to make up the difference, or other illegal ploys?
Tesco haven't asked for 50% as that would be a multiple of most suppliers existing profit margin. You have to be strong with the supermarkets and stick to your guns. If you have a good product at a fair price, deliver the variable quantities they ask for on time then you are usually OK.
I tend to agree with this. Apparently a lot of the so called slave labour at £3.00 per hour are also claiming unemployment. It may be a nod and wink situation between employer and employee to take advantage of stupid Western easy touch government. This may be irrelevant but if it turns out to be true makes BooHoo look even worse by association.
slightly off topic but can you anyone recomend a company for RNS "s i use investigate but have found that not all c/o rns are published there i recently missed LON:IBPO
Research Tree. You can set up RNS alerts with a free account.
thanks for taking the time to reply
I now use Stockopedia! If you set up a Watch (and perhaps Owned) list portfolio, then the RNSs are picked up and shown every day on your Home page. Now I see them and just pick out those I want to look at, reducing my email inbox vastly. While it bugs me that RNSs on investment trust NAVs sometimes leap to their US listing, it's another point of value of Stockopedia to me.
Do they come in as soon as they're released, or is there a delay?
Thank you for that I hadnt spotted it.
Hi , what is your views on Micro Focus International (LON:MCRO) ( Microfocus)
But at a Market Cap of £1 billion, Micro Focus International (LON:MCRO) is not yet a Small Cap. Possibly getting there. Historically the management has earned respect for its ability to sweat legacy software assets - a very reasonable business model. The HPS acquisition came with huge problems, now well publicised and not surprising to anyone with contact with any of those businesses. My own guess is that there is still value in the underlying business, but that an EV of over 4 billion is probably doing it justice. I don't hold.
thanks for the insight .
Srinivasan - welcome - I see that you have joined today.
Micro Focus International (LON:MCRO) may have micro in the name but when it comes to Mcap it is over £1bn so this "Small Cap" report is probably not the best place to discuss it.
That said I see that it had a big drop in price on a trading statement last August and another drop on results on Feb. 4th. this year so we have to look at it as a post profit warning situation so that is a chance to introduce you to one of the Stocko delights which is the occasional webinar and here is the one on Profit Warnings which I personally found very helpful:
https://www.youtube.com/watch?v=YayTZn4c7I0
thanks will have a look
I personally would not buy it at this point. The share price is in deep decline. I have found that stock picking is relatively easy but timing of buy and sell points, is not, but is critical to avoid losing money.
On one of the discussion boards (on the old ii site) which I followed and to which I contributed were several Technical Analysis enthusiasts. At first I was sceptical but eventually became converted. Their guru was Stan Weinstein and their Bible, his book "Secrets for profiting in Bull and Bear Markets". This is now out of print. However if you search Stockopedia you will find a series of articles which cover all the basics and which are downloadable. I was reading the last chapter in the book a few nights ago and have followed his system for several years now and so far have not, strayed from his principles and not lost any money as a result of Covid19.
My current project is writing a hand book on money and investing for my just 15 year old grandson. To this end I have been re-reading "The World's 99 Greatest Investors: The Secret of Success" by Magnus Anglefelt. Interestingly only one of these, Martin Zweig, was a Technical Analysis follower. The author rated him above Warren Buffet.
The characteristics they had in common was their emphasis on hard work, not using leverage or derivatives.
In conclusion you might want to buy at some point but not until the share price but be careful until the price rises above the 200 day and 30 day moving averages.
Hope this is helpful
Hi Interesting note Can you possibly provide a link to the articles on Stocko as i am struggling to find them.
Much appreciated
Hi ckidcurrie23
I entered the site and then clicked on today in the lt column and typed "Technical Analysis " in the search box; the reference is not at the top of the list so you need to scroll to find it.
I consider myself to be a long term investor not a trader, so the minutiae of the various signals are not so important to me as they are for a trader. When I am buying and selling I use Level2. and play with/use quite a lot of the indicators in my decision making, particularly volume, and Bollinger Bands..
So for the current situation you will will find some share price fluctuations on minimal volume even though there are a lot of shares in circulation. If this persists it tells me that most investors do not intend to sell I might then look who is buying and selling .If owners/insiders are not selling and particularly if they are buying I assume they have confidence in the company.
These high level successful investors keep it simple but their decision making is taken at at a very high level of abstraction. This is where all the work comes in, reaching that level of knowledge to be able to do this.
Best of luck. If you need some help let me know I will try to help you.
PS I am 80 years old; having contributed a huge amount to the school fees I am now working to contribute to University fees and educating my grandchildren as they are going to need more than one income stream in the future. If they learn to invest successfully they will not need to be wage slaves
Many Thanks 23jez for taking the time to reply.
Lots for me to learn in that stream.
Good Luck with your University Fees, totally agree if you can teach your children the benefits of investing they have the years to allow things to compound. I have ISA's set up for all 4 of my grandchildren to encourage that mindset.
Thanks Again
Lot of comments about £BOO. I don't own it and its not my cup of tea from a value investment perspective.
If you are thinking of it as a long term investment from a value investor point of view the last accounts show EPS of 5.88p which grew by 42% over the past year. Its Op profit is only £90m on sales of over £1.2bn, gross margins were down while administrative costs went up by £100m partly due to the consolidation of PLT - the accounts don't show the separate SG&A of PLT in 19/20.
At 240p the share price is 20% higher than a year ago and the PE is 40. 55% of the shares are owned by 10 shareholders and the Board is dominated by the founders. It is Aim rather than FTSE 100/250. Quite large amounts for share based payments and purchase of shares for the EBT are in the accounts.
So maybe one for the traders rather than a long term value investment. It reminds me, maybe unfairly, of Sports Direct Frasers (LON:FRAS) whose PE is 18.
Boo has taken another hit today, falling back below £2.30. QUIZ has also issued a statement today: "QUIZ is extremely concerned by information recently reported in the media regarding an alleged instance of non-compliance with National Living Wage requirements in a factory making QUIZ products in Leicester". This follows headlines in the Times newspaper that suggested that workers in Leicester had been offered as little as £3 an hour to make clothes for Quiz but only after working for free for two days.
My guess is that if this practice is actually more widespread than expected, police raids will follow. Possibly with Immigration investigators. I am sure the newspaper will have recorded everything so denials will be hollow.
Harriet Harman M.P. who chairs the Parliamentary Committee on Rights said: “It’s shameful that the big brand retailers are just turning a blind eye when they know there is a problem down the supply chain. It’s not good enough for brands to say they don’t know about it. It has to be their business to know about it.”
I am certain she will not let go of this subject very easily.
It also gives the opportunity for the Government to look at such issues as a tax on once used clothing which ends up as landfill.
No doubt this could be spun in such a way as to benefit the environment and fund fairtrade initiatives.
How do you know the clothing was only worn once to tax it?
You wouldn’t. The history of new taxation is that it uses a shotgun rather than a rifle. BooHoo/Quiz has given the Government the opportunity to use both barrels.
I think the local failure to investigate will probably end up a similar story to the Rotheram grooming scandals. It is easier to overlook a lot of these issues for the sake of local 'harmony'. The real losers are us taxpayers who foot the bill by loss of taxes as well as unemployment pay and tax credits - all to enable BooHoo to rip off everyone. Hope that they are not in any ESG funds!
Paul. I would welcome your analysis of today's RNS from AIRE. The rent collection figures look quite positive to my untrained eyes. I hold and I would like to add more assuming the divi can be held at a reasonable level.
For information only,
I recently took part in the Hipgnosis Songs Fund (LON:SONG) C share placing with PrimaryBid, once again having to use a debit card for payment. I sent a message to Hargreaves Lansdown asking them to initiate the transfer from the default Jarvis account setup by PrimaryBid and received the flowing message from HL this morning:
Whilst Hargreaves Lansdown is not affiliated with PrimaryBid, we are able to take orders through our platform for offers that they run. This means you are able to apply directly through one of your Hargreaves Lansdown accounts and use available cash in your account to fund the purchase.
Once an offer has been announced, please contact the dealing desk on 0117 980 9800 to place your instruction.
So, good news if you are with HL and want to take part in retail placings within ISAs and SIPPs - it is now possible! Hopefully other brokers will follow suit.
All the best, Si
Thank you simoan
That's very good to know.
Cheers, Martin
Bigdish (LON:DISH) - Has anyone any news or viewpoints on the share price movement. Only thing I can find is a drop of 650 ish active restaurants to present 60, though they have offered the platform completely free for the remainder of 2020 and BigDish has added a delivery beta.
The model still looks appealing long-term as the model of charging a fixed fee instead of % still makes sense from a catering perspective.
Sinking ship atm! Management really need to get a handle of it and start making progress quickly!
loads of potential but potential and talk only lasts for so long! Investors need to start seeing progress.
sub 1p wouldn’t surprise me on the current trend.
Don't see how they won't have to do a hugely dilutive equity placing in the next few months.
No revenue coming in, huge capex spend on Delivery and other features.
Then after that, they'll need to ramp up marketing and sales to acquire restaurants to the platform. Also customers to download the app.
If you were tempted by their business model, I'd rather wait till they get their financing sorted, and ensure they have at least 12 months runway for their bold ambition.
Personally, their strategy seems very me too. So many discount websites/apps out there for restaurants. So many delivery apps already. So many restaurant B2B SaaS platforms too. Where is the gap in the market?
Avation (LON:AVAP) investor presentation, July 2020, here.
Richard Wolanski, Finance Director, gives a comprehensive overview of Avation, how they’ve managed CV-19, and how he sees the outlook.
Separately, forthcoming piworld webinars, for your diary:
1. This Thursday 16th July, 1pm: An hour with Andy Brough. Head of the UK & European Small & Mid Cap team at Schroders
Andy will share his extensive experience of managing money, covering current markets, how he selects investments, reads accounts, and much more. Plus, your opportunity to ask questions. Register here.
2. Next Friday 24th July, 1pm: An hour with Mark Slater, Chairman & CIO, Slater Investments.
Mark will give us his wisdom on current markets, volatility, the macro backdrop, and how the retail investor can benefit. Plus of course the opportunity to ask your questions. Register here.
3. Friday 31st July, 12.30: Ig Design (LON:IGR) FY20 results webinar:
Paul Fineman, CEO & Giles Willets, CFO, will present Ig Design (LON:IGR) FY20 results, in a webinar, followed by Q&A. Register here.
With regard to Boohoo (LON:BOO) I am not going to comment on the what are currently alleged practices of Boohoo and or its suppliers. I simply don't have enough knowledge of what is going on.
However, I do feel the need to comment on what I consider to be SLA’s virtue signalling by “dumping” the stock. I am not an ESG investor per se though I will not invest in tobacco or gambling (though I hold Best Of The Best (LON:BOTB) so maybe it is just tobacco) and I do want to trust management if I can (so maybe I shouldn’t be in Boohoo?). If you take ESG to its logical conclusion very little is investable: Tesco they sell cigarettes, steel used to make missiles, big food/big ag destroyers of the environment, cars global warming, oil ditto, I could go on.
Turning to Standard Life Aberdeen who so publicly sold their holding in Boo on Friday I took a quick look at the documents available on their web site about the investments they hold and I can only come to the conclusion that their selling of Boohoo (LON:BOO) stock was nothing but a virtue signalling/PR exercise.
A quick (this was not a forensic study) examination of their holdings reveals:
Holdings of BVI companies (Tax avoidance?)
Holdings of Cayman Island companies (Tax avoidance?)
China metal recycling holding - I wonder what their employment practices are like
Las Vegas Sands - Gambling why are they in gambling companies
McDonald’s - Not exactly great for people’s health
Facebook - morally dubious monitoring of content
Tullow Oil - Climate change
Anheuser - Busch - Booze
GVC - Gambling
BAT - Cigarettes
Coco Cola Europe - Sugary drinks
Shell - Oil
I did some more digging this morning and in their ASI ex U.K. Ethical Fund
https://www.aberdeenstandard.c...
they have a holding in 349,000 British American Tobacco 6% 2034 bonds.
My point is not that I agree with (all) of the issues I sight but if you are going to dump #BOO you cannot hold Gvc Holdings (LON:GVC), £BAT Shell and companies in low tax districts and then make a song and dance about one particular company because it is in the news.
Boohoo (LON:BOO) is a 4% holding (was 5%) in my portfolio and so will not be topping up here but any further movement towards £2 will see me buy more.
Regards
Michael
What you are identifying is that the world is not placed to deal with many of the issues it faces Michael. When I was in investment in the early nineties we looked at ESG. The decisions required to come up with consistent investment is extremely subjective and that leads to difficulties for investors and hence it becomes purely a label, which is a shame given people want to do something good. I then went on to work with many pension funds in the Uk and again found they are not positioned for the changing world. Trustees have to get a return for investors in short time periods. The issues that need to be addressed are long term issues. I actually think PFs are the answer because there is a huge pot of money and we should be looking at intergenerational wealth rather than just our own. But I appreciate that is debatable and whilst our society measures success in money terms you will never crack the egg.
Hi Michael, I think you make a very important point about ethical investing.
I opened a conversation last year about this, asking for suggestions of ethical investments I should look at.
https://www.stockopedia.com/content/environmentally-friendly-investment-suggestions-497581/
One suggestion made by a contributor was the Royal London Sustainable World fund. On further investigation I discovered their top holdings were as follows:
Largest Holdings %
1 ROCHE HLDG AG 3.46
2 ADIDAS AG 3.09
3 ASTRAZENECA PLC 3.04
4 VISA INC CLASS A SHARES COMMON STOCK USD.0001 3.03
5 RENTOKIL INITIAL 3.03
6 MICROSOFT CORP 2.96
7 LONDON STOCK EXCHANGE GROUP 2.95
8 EXPERIAN GROUP CFD CS GBP 2.88
9 CSX COM USD1 2.88
10 ANSYS COM USD0.01 2.71
I simply couldn't see a link between their fund name and these holdings.
Cheers
Francis
Hi Francis
The contributor you refer to was me, if I remember correctly.
I think it’s important to distinguish between pure environmental funds, which I would consider to be those investing in renewable energy and that sort of thing and broader ESG funds, which are generally avoiding the worst sectors and in the sectors they do look at trying to find the companies that have a strong ESG performance.
Royal London Sustainable World is in the latter category.
I notice there is no fossil fuel, no arms, no mining, no tobacco in that top 10. No gambling or alcohol either but opinions vary on whether those are in the same category.
Why you would consider those top ten holdings objectionable on ethical grounds I don’t know. Why do you feel that these companies are not operating with a good sustainability performance?
All I can think is that you’re looking for something in the green tech or blue tech world rather than something ethical as such.
Hi Graham, it was indeed with you that I discussed this last year.
I think we are grappling with words and their meaning.
The ESG acronym leads with "Environmental" so for me at least, that should mean a positive effect on the environment whereas I think you interpret it as companies who do not harm the environment. Big difference.
However I never said I thought these firms were objectionable; I was merely questioning them based on my interpretation of what ESG means. As for their 'sustainability', I have no idea but again that word is open to much debate and interpretation.
cheers
Francis
Hi Francis
I hear what your saying.
During my career I had some involvement with environmental and sustainability issues and the terms are a bit vague sometimes. Companies also issue corporate social responsibility reports and so on.
But there are many measures that crop up regularly such as
Carbon footprint
Water footprint
VOC (volatile organic carbon) emissions
Heavy metal and hazardous chemical discharge
Amount of waste going to landfill
Amount of recycled paper and plastic used
Etc.
So, this is taken seriously by many of the major international companies. By improving their performance against these goals year on year they do indeed have a very positive effect on the environment. Some of them have made great progress.
So, this is the sort of thing that is generally meant by sustainability in the commercial world outside of finance. Fund and trust managers may take a different slant on it but I wouldn’t immediately poo poo it without looking under the bonnet.
I agree with all that Michael. Also some of the 3rd party sellers dumping BOO aren’t squeaky clean either. Pots and kettles.
And as the Sunday Times article yesterday pointed out. Some of the workers are complicit in this as they have worked out that they are better off working fewer hours for far less than the minimum wage and claiming benefits than working full time being paid the minimum wage.
Also so much of the comment on BOO sees the writers seeming to think this just a UK online retailer, and unaware of their huge and fast growing sales elsewhere. Customers outside the UK are not likely to stop buying clothes from BOO because of the current spat here.
As Paul Scott pointed out if BOO are now obliged to give up on Leicester they can easily switch to production elsewhere. That would be a blow both to those Leicester workers apparently working the system and to any illegal workers who would lose their jobs and would mean higher unemployment in Leicester.
And some so shocked (don’t know why as it been an open secret for years including decades ago when I lived in that area of Leicester) at the recent revelations seem to have double standards. They happily buy clothes and the shares sometimes of Companies whose clothes are produced in even worse conditions in deprived Countries while being disgusted that it happens here too. In an ideal world it wouldn’t happen anywhere.
How else are shops like Primark able to sell their clothes at such low prices? And the big brands too. Hidden away as far out of site as can be managed is the tiny label in tiny print showing (those willing to pay crazy prices to advertise that brand) that their shirt was also made in Bangladesh or similar Countries.
I regretted selling BOO ages ago and missed the chance to buy in the big March dip too. The recent dip gave a good chance to buy back a part stake at £2.15 and a dip back towards that price a chance to buy more.
And some so shocked (don’t know why as it been an open secret for years including decades ago when I lived in that area of Leicester) at the recent revelations seem to have double standards.
Just remember that there's now a National Crime Agency investigation underway into modern slavery in Leicester factories. Trading standards officials need permission to enter factories and inspect, the NCA can do pretty much whatever it wants.
If there is a link back to Boohoo (LON:BOO) then this is no longer simply a business issue. And if there isn't then it'll probably blow over.
timarr
HSE don't need permission to enter a factory and if the local authority is the regulator for a premises under HSWA 1974 then they don't need permission either.
HSE don't need permission to enter a factory and if the local authority is the regulator for a premises under HSWA 1974 then they don't need permission either.
The FT report in 2018 laid out what was happening in Leicester. Nothing was done about it:
https://www.ft.com/content/e42...
For textiles manufacturing, the enforcement approach has been “principally reactive”. There were 187 inspections of garment and textile factories last year, an increase on 103 inspections five years ago. But there were 136 workplace injuries reported in the sector last year — reportable injuries are those that necessitate more than a week off work or involve damage such as amputations, the crushing of internal organs or burns covering more than 10 per cent of the body. HSE investigated just five.
Boohoo (LON:BOO) are mentioned a few times ...
timarr
I don't really understand why £Boo has caused such an uproar. People want to buy Boohoo (clothes or shares), let them. Standard Life want to sell Boohoo, let them. Ethical investment funds want to be hypocritical, let them be. People want issues in the textile industry in Leicester resolved, good on them. The industry moves somewhere else, good for it.
Too many people passing too many judgements, often contradictory just makes everyone a hypocrite.
let those that haven't sinned cast the first stone and all that , and in the interests of hypocrisy, I am quoting the Bible (I think) even though I have never read it!
Also so much of the comment on BOO sees the writers seeming to think this just a UK online retailer, and unaware of their huge and fast growing sales elsewhere. Customers outside the UK are not likely to stop buying clothes from BOO because of the current spat here.
Perhaps not, but if they have to sort out other suppliers who pay minimum wage, or their existing suppliers are forced to start doing so, their costs wil go up. And that will impact sales and profits.
Re alleged Leicester sweatshops. I wonder about health and safety regulations.
Gold miners.
There was some excellent discussion on gold miners on Friday, and like many, each listed company represents risk due to the country they operate in. If like me you prefer to spread some of that risk but gain exposure to gold miners a fund or ETF would be useful.
LF Ruffer Gold Fund
Aims to provide capital growth by investing in gold and precious metal companies in the mining industry
https://www.ruffer.co.uk/Funds/Specialist-Funds/Gold
There are many other of course.
BSV
Blueskyventurer
Not sure why you are getting thumbs down as I think your comment is very valid. I hold Anglo Asian Mining (LON:AAZ) a 21% of portfolio position but you are right most miners have geographical/political risk. In AAZ I have accepted the risk in return for value, yield, potential growth, cash on th ebalance sheet and potential as a takeover target.
Regards
Michael
I think the thumbs down will for the very large font size which is pretty ‘rampy’ rather than the content of the post, which as you say is interesting.
Will try to do better next time.
BSV
Hi Paul,
I read an article this morning posted in the Guardian on Sunday which reported on some preliminary research from Kings College on the rate of antibody decline in recovered patients. It was quite sobering reading and if accurate its implications on the long term impact could be devastating.
I wonder if you could spare me your 2p on the impact of the research on say the pubs & clubs industry (I hold Revolution Bars (LON:RBG)), which presumably will only return to pre-covid trade on the back of herd immunity or a vaccine - both of which are challenged by this research?
Many thanks on your excellent SCVR's. Here is a link to the article: Immunity to Covid could be lost in months .
Best,
Otto
Thanks Noobinvestor for bringing this to our attention and depressing reading it makes, though a trial of 90 people is hardly conclusive. I don't hold retail or hospitality (I don't hold much mainly cash, gold and a large chunk in Anglo Asian Mining (LON:AAZ)) and certainly don't think now would be the time to be buying them.
It certainly makes me hope that:
It also raises the question as to whether if the fist time you contract the virus you only get mild symptoms, can it kill you the second time you catch.
Difficult times and a real challenge to our modern way of life.
regards
Michael
Noobvestor, I hope Kings College's worries turn out to be unfounded since I share the same. Imagine Covid-19 and the Common Cold being alike as regards to developing at least once a year and what it would do to the general health of the human race.
Silver Moon
Has anyone bothered to put Covid mortality into perspective? At present the mortality seems no worse/better than seasonal influenza which has killed up to 650,000 globally per annum. We don’t lockdown every winter for the flu do we? We don’t build temporary hospitals at the cost of hundreds of millions (which are not subsequently required)? How many people are fascinated by the development of a Covid vaccine but don’t bother getting a flu vaccine every year?
Can you please link to your study for the statement 'At present the mortality seems no worse/better than seasonal influenza'? As I understand it, transmission, hospitalisation and mortality rates for seasonal influenza and covid are vastly different.
All the studies I’ve read suggest Covid-19 has a cfr of 0.8 versus 0.1 for flu. So second call for evidence you have it’s no worse than flu.
Ref flu deaths (WHO) up to 650k/annum https://www.who.int/news-room/...
Covid deaths 571k globally. Google it-multiple sources.
Ref flu deaths (WHO) up to 650k/annum https://www.who.int/news-room/...
Covid deaths 571k globally. Google it-multiple sources.
That's not comparing like with like. This John Hopkins article gives a useful summary of the differences between flu and Covid-19:
https://www.hopkinsmedicine.or...
It's still early days but Covid-19 is more lethal than seasonal flu (there's lots of variation in numbers - at the top end estimates are as high as 50 to 100 times worse, but without full figures on asymmetric cases this is still finger in the air stuff, as far as I can tell). Implementing social distancing and hygene safety has reduced the spread so the total number of cases and deaths is not comparable with historic flu mortality.
Secondly flu doesn't generate anywhere near the same level of hospitalisations as Covid-19, which mostly means it's unlikely to cause us to run out of critical care beds. Additionally, if the latest evidence turns out to be true and Covid-19 immunity, like most coronaviruses, turns out to be short lived then it'll be possible to get it more than once a year.
Also the emerging evidence is that for some people who get infected by Covid-19 - including those that don't get it badly - there are longer term health conditions which aren't yet understood. For most people flu has no long lasting effects.
Remember also that the reported deaths are for Covid-19 confirmed deaths only. Excess deaths - either because of unreported Covid-19 conditions or because of related problems such as people not going to hospital with other illnesses out of fear - are probably quite a lot higher.
At this point Covid-19 is definitely more dangerous than seasonal flu. However, we are starting to see therapeutic treatments emerging, which will reduce mortality rates. The longer term impacts are, however, concerning.
timarr
timarr
Though covid cases are increasing fast in some Countries afaiaa the death rates are decreasing even in those Countries. . Whether that is because of improved ways of treating it or covid now being milder is not yet clear. THE big fear for our own health and from investment angle, is if (like Spanish flu) it comes back later this year in much more dangerous form and before an effective vaccine.
For now we know that in the UK and Europe deaths are now very low. Hope that continues. And on the number of reported cases, Trump is right in that far more, and more effective, testing means far more cases being found,
Note though that on that farm in Herefordshire most of the 73 employees testing positive did not even know they had got it. That could apply to millions of us, but unfortunately doesn’t remove the worry of the virus returning with a vengeance now that it’s clearer that immunity from it could be short lived.
It’s strange how UK citizens are the most worried in Europe about covid, yet the least willing to wear masks.
From investment angle the effect on markets and many of the shares that have recovered if the virus returns with a vengeance, seems predictable. They won’t like it either!
I'm sorry but:
And on the number of reported cases, Trump is right in that far more, and more effective, testing means far more cases being found,
This statement might be technically correct, but misses the big issue: the positivity rate. In Florida the rate of positive tests has increased from 5% to 19%, which means COVID is exploding down there.
The bright side is now we understand the disease course better and have rescue medications like dexamethasone to shave points off the mortality rate.
IncredibleMosesLeroy
This statement might be technically correct, but misses the big issue: the positivity rate. In Florida the rate of positive tests has increased from 5% to 19%, which means COVID is exploding down there.
Is it known though that the testing is on lfl basis ? if its not are you just assuming that its exploding when it could be asimilar quirk of the statistics?
for example say previously they limited tests to key workers and did not test most people who likely had covid that did not require hospital treatmment - i would expect this would be mostly a negative return result as testing was more rubber stamping someone was ok rather than testing due to the fact that they were presumed positive.
If the increase in testing is now down to the people who think they may have covid being tested in addition to the above sample then it seems pretty obvious to me that we would end up with a much higher % of positives from this new sample pool than the original sample pool and a higher overall % than was the case previously despite the fact the overall number of cases could be level/down or only verty slightly up.
I don't know if this could explain the higher rate alone or not but it seems a plausible scenario which would mean that some factoring in the types of test being conducted would be needed to work out what the heck is going on - really you need to do an ongoing blind trial of the general population to see what the real result is and i suspect that data does not exist for florida. Even then you have to be careful you are using a reasonable sample - i wander if the uk are continuing the trial they started some time back that looked at a random sample of the population each week or so.
Is it known though that the testing is on lfl basis ? if its not are you just assuming that its exploding when it could be asimilar quirk of the statistics?
Testing in Florida and elsewhere is subject to all sorts of inherent sampling biases, although mostly those would get rapidly called out if they were happening. However, hospitalisation rates aren't subject to sampling issues and as you can see from the raw data they're steadily growing. All things being equal that suggests quite strongly that the real underlying number of cases is also growing.
https://covidtracking.com/data...
It's highly likely that the data is pretty representative of the underlying situation - not good, and getting worse.
timarr
Though covid cases are increasing fast in some Countries afaiaa the death rates are decreasing even in those Countries. . Whether that is because of improved ways of treating it or covid now being milder is not yet clear.
Hi Ken
I would have thought the most obvious reason for decreasing death rates is that the people catching it are, on the whole, younger. That seems to be the issue in the US - young people are not obeying social distancing so more of them are catching it. That's led to a tick up in hospitalisation rates and, shortly, death rates - a few younger people will get ill and die but they'll end up passing it on to older generations.
There's a related issue around more testing, we're catching more asymptomic cases but that doesn't mean, as the Trump administration is insisting, that the reason for the increase is more testing. More testing doesn't mean more people end up in hospital.
Also, mortality rates are variable dependent on environmental conditions - i.e. if all the vulnerable people shield then the death rate will drop. What's more important is the lethality rate - if the virus is allowed to spread unchecked how dangerous is it?
The possibility that immunity is short-lived accompanied by the research suggesting that even younger people will get long-term issues is worrying. Increasingly I feel that waiting for the economy to "restart" is pointless. Lots of the economy has never stopped and much of that which is struggling is destined to fail anyway. No doubt governments will spend fortunes propping up failing enterprises, but I'd prefer to hedge my bets on likely survivors.
timarr
Thanks Tim. Great comment.
maillot has not run its course and therefore you are not comparing like with like.
I suspect that when C19 has run its course the deaths in a year will be approaching a million plus.
Further the health consequences for some survivors. One hospital in the US has had to remove the entire gut of five patients, there have been lung transplants.
You don’t want to get this disease at least until there is a better treatment or something like Avacta (LON:AVCT) ACE2 blocking Affimer.
No it is not the flu.
Kind regards
Michael
effectiveness is not great:
Seasonal influenza annually infects approximately 10-20% of the world’s population resulting in up to about five million cases of severe illness and 650,000 deaths. In addition, pandemic influenza, such as the H1N1 Swine Flu pandemic of 2009, is a constant global threat. However, current influenza vaccines, which target frequently mutating parts of the flu virus and therefore must be updated annually in the hope they will match the next flu season’s circulating strains, achieve on average only about 40% vaccine effectiveness in the general population and as low as 12% in older adults.
http://www.biondvax.com/2020/0...
Hi Noobvestor (and others on this mini-thread)
One alternative view developing about Cpvid-19 immunity is the role T-cells play in it.
Which has not been widely research to date, but is developing some traction.
This paragraph in an article about T-cells is but one example of the scientific discussions out there.
'In mid-April, work was published by the group of Andreas Thiel at the Charité Berlin. A paper with 30 authors, amongst them the virologist Christian Drosten. It showed that in 34 % of people in Berlin who had never been in contact with the Sars-CoV-2 virus showed nonetheless T-cell immunity against it (T-cell immunity is a different kind of immune reaction, see below). This means that our T-cells, i.e. white blood cells, detect common structures appearing on Sars-CoV-2 and regular cold viruses and therefore combat both of them.'
This is link to the article. It discusses CV19 and other Sars-related viruses (and the common cold).
https://medium.com/@vernunftundrichtigkeit/coronavirus-why-everyone-was-wrong-fce6db5ba809
I am NOT a medical person, just an interested layperson. I have followed these sorts of discussions closely though and know some respected medical people are endorsing how this part of the jigsaw seems to be evolving.
Regards
Howard
Thanks for the link Howard very informative. I am a retired medical doctor. What some of the references have highlighted is the opportunity costs of the huge resource diversion to COVID 19. These costs as is pointed out cause suffering and has been causing early deaths in some cases and are reducing longevity in others. A medical colleague's university friend had his chemotherapy stopped, was responding but died a couple of weeks later. Screening programmes have been halted with no indication as to when or if they will be resumed. This is in addition to the educational deficit and the increase in poverty and its health consequences.
We are very fortunate in this country in that we rarely suffer from natural disasters to add to our woes.
On the plus side there has been an outpouring of community spirit and kindness. My family live in London and I live in Yorkshire. I pride myself on being self sufficient and independent but my neighbours have been so kind and helpful with their unsolicited support. Our wonderful and cheap communication systems have mitigates many of the problems which would have occurred if this had happened 20 years ago.
#COVID
I was aware of the possible significance of the T-cell response, but not of that study from Berlin
" It showed that in 34 % of people in Berlin who had never been in contact with the Sars-CoV-2 virus showed nonetheless T-cell immunity against it"
If that figure is reliably represents a wider population, then it prompts me to wonder : Do people who quash he illness with the T-cell response : A - also start to develop antibodies whilst the T-cells are doing their job or B - not produce antibodies because the T-cell response is so rapid.
The scientists probably know this, but I don't!
The reason to ponder this is that if it is A - then these people would test positive to the antibody test and that might go some way to explain the large number of totally asymptomatic cases.
However if the answer is B - then there are potentially many more people that have been exposed to/ infected with the virus than revealed by the antibody testing. Which would mean we are somewhat closer to herd immunity - still not very close to be honest and if herd immunity is only a short term factor then it may not be very relevant.
In a similar vein I read some interesting speculation (I can only recount it, not validate or critique it) a few days ago as to why the Japanese seem to have faired so well.
To probably slightly mangle the scientific description :
As I say, just something I read, not sure if it is proven. But if it is it would be a positive for potential herd immunity supported by a vaccine.
Flipping back now to T-Cells. One of the tricks Covid has up it's sleeve is to suppress T-cell production and therefore some of the remedies being looked into are about boosting the T-cells.
With the Berlin study above in mind, I wonder if that only benefits "the 34%" (which could still provide clinically significant results) or everybody.
Anyway, meandering finally back to investing proper; I personally think it is a bit of a mugs game at the moment to try to second guess the science and position your portfolio accordingly.
However, I do now recall that during the period of the GFC, having stabilised the rest of my investments; I had great fun (and quite a lot of success - it was a bit like shooting fish in a barrel) working out whether "the market" would next be bullish or bearish on Barclays (LON:BARC) . At the time I did not have the confidence to play this for big money but at least I enjoyed it.
I have not worked out at this stage whether the market (or individual stocks) are reacting predictably to predictable news. It might be something to look for - one of my "Mello buddies" who likes to hide in the background may have the answer - If you are reading, you know who you are!
PMs still work for me ;-)
Yes, thanks Noobvestor for bringing this research to our attention. Reasons why some vaccines provide long-lasting protection and others relatively brief protection is poorly understood. It sounds as though a potential coronavirus vaccine might perform like influenza vaccines, providing reducing protection throughout a year and needing a repeat vaccination each year. This has been suggested by AstraZeneca which is working with the Oxford group on the most advanced vaccine against COVID-19. Even if the protection from an influenza vaccine wanes within a given season, it is likely to reduce the seriousness of the infection even if it fails to prevent the infection. From an investment perspective, a partially effective vaccine may well be more profitable than one providing long-lasting protection.
I sold out of Boohoo (LON:BOO) having seen it bounce. The valuation is high and sensitive to shocks, real or imagined. The Covid related issues give this story an extra potency for the time being.
If Paul is in Day Trader mode I suspect he will have taken some profits.
Paul,
Can you let us know if you have sold your Boohoo (LON:BOO) shares on the bounce or do you still believe it is a cracking buying opportunity? I know what you say here is merely your opinions and not trading advice.
Cheers.
How cynical are these times: that the consensus among city analysts and BooHoo shareholders is, the company being able to shrug off links to institutionalised slavery in Leicester, yet Gerald Ratner's careless remark at a 1991 conference destroyed the jewellery business he inherited.
Agreed. Indicative is MotleyFools' Matthew Dumigan yesterday stating that BooHoo has "stumbled upon difficult times recently regarding working conditions." Stumbled?
An awful trivialisation of a very serious issue.
Agreed. Indicative is MotleyFools' Matthew Dumigan yesterday stating that BooHoo has "stumbled upon difficult times recently regarding working conditions." Stumbled?
An awful trivialisation of a very serious issue.
Blimey! I didn't even know the Motley Fool still existed. Those were the days. To be fair, their editorial content has always been rubbish.
All the best, Si
Their US Motley Fool podcast is very good. Worth a listen on general market trends .
Their US Motley Fool podcast is very good. Worth a listen on general market trends .
I was referring to the UK site. It's where some of us here cut our teeth many years ago on the MF bulletin boards. All the best, Si
Motley were good in the early days - '99 /2000 - this is where Paul Scott became famous ! I remember his posts as Pauly Pilot and thinking crikey this guys switched on.
Motley now look like a parody account ..recent tip "Rolls Royce but have a minimum 10 year timescale " what! ??? COVID 20 something might have got me by then !
That is when the mission creep set in, after American management was parachuted in; the venture capitalists wanted to see a return. Cost cutting followed, community and writers were axed (just another cost). Monetization initiatives followed. However, internally there was general awareness that the prior business model wasn't working and something else needed to be tried. By any measure, that TMF(UK) encouraged be applied to assess other business models, we failed to measure up on. Everyone there should have been aware that they should keep an up to date CV, and most knew it was not a matter of if, but when.
In the mid 19th century the Royal Navy deployed 25 ships and 2,000 sailors to the West Africa Squadron to suppress the Atlantic slave trade. Now we don't do anything about modern slavery in the middle of England.
Re: Boohoo (LON:BOO) vs Ratner
There is a difference: Ratner stupidly and arrogantly insulted his customers, effectively calling them gullible and lacking any taste or sophistication. Boohoo (LON:BOO) hasn't condoned what has been going on in Leicester; they say they didn't know what was apparently happening and will work hard to stop what is an endemic problem across their industry, if any such is found in their supply chain - official or undeclared.
(No current position - I might buy BOO if the price falls enough.)
Boohoo (LON:BOO)
One additional comment with regard to boo is its current high valuation - if we take 2022 EPS of 10p and say 15 * multiple that gives up 150p reasonable valuation. So although price is way down from the peak the valuation here is still pretty lofty. Very hard to value company this company with anything between 100p and 350p possibly seeming reasonable value based on how you judge the buisness model's future sucess. I am happy to sit on the sidelines at present - i have held in the past and would possibly hold again if the price was right.
Morning everyone,
Any thoughts as why BOOHOO's shares are again shooting down after it reached c.310 last week? It's now c.240p again. Any ideas appreciated. Cheers.
There was a lot of bad publicity in the Weekend Media about the sweatshops in Leicester? BOO is on the point of my stop loss. Just watching to see if it recovers after the opening trading period. It has come back from 227.81 Early period always manic and I suspect panic sellers wanting out after bad news stories.
News in the guardian that the founders are connected to the factories that have been alleged to be paying below minimum wage. https://www.theguardian.com/business/2020/jul/10/boohoo-co-founder-jalal-kamani-linked-to-leicester-garment-factory
I don't believe things excreted through The Guardian. They love misleading headlines and spinning their leftie Islington agendas. What really happened? :)
Information is from companies house. Feel free to look at the source documents.
I don't think that is the issue, Is2g08.
The issue is the newspaper uses and manipulates facts selectively to promote its internal agendas.
"The Guardian" likes to present public service workers as "good", capitalist bastard business people and shareholders (which includes public sector pension funds) as "bad".
Morning newcomer,
Sunday newspapers stated that Aberdeen standard a major shareholder was not happy with the current situation and would start selling stock and this morning four major shareholders have reduced there holdings.
Northern Bear (LON:NTBR)
Very reassuring update from the company this morning, they held onto decent proitability ye 31/3/2020 despite march being a vital month and the comments about return to normailty and healthy order book give me confidence that presuming there is no matyerial lockdown 2 they will have passed through the whole covid issue without material issues - simply the costs associated with lockdown.
It's quite a good general sign particularly for the country that they feel positive about future workload - the 2008 recession removed for a considerable period of time a material amount of construction work once once financing ran out and everyone shut up shop. Hopefully the construction sector this time can get back to normality reasonably quikcly.
No specific comment on how they expect year end 31/3/2021 to pan out - not a surprise they don't really ever give much away this company. Can they breakeven ye 31/3/2021 - it will probably be a push but i would say yes. as long as they are back on track and reaonable normality is resumed then no biggie if there is too much ground lost.
It would be a great result though if they could squeek into profit to keep their unbroken record of profits going - sincfe teh 2008 recession - thats ignoring intangible w/offs mind !
If we look at the current buy price of 55p and the 2019 eps figure of 14p - thats ae of under 4 if they can return to pre covid profit levels.
I guess there is enough with this company to put most investors off but i am happy to continue to hold.
Whats not to like here?
construction sector and worry about recession?
micro cap
patchy history of growth - mostly kept alive by acquisitions
balance sheet not as stong as i would like.
some argue the structure of the business ensures too much of the crust earned goes to directors of operating subsiduries.
Mr Contrarian, just to say you do a fantastic job and thank you for it. Charles
Any thoughts on £boo today after the weekends activity anyone...?
Seems to be on a downward spiral. Considering adding more. Wondered what people thought. Where they stand.
PSQUARED Asset Management has placed bets worth more than £20 million that Boohoo’s #BOO shares would fall - the day after the fast fashion giant was accused of using sweatshop factories in Leicester. So basically, they are having a great Monday Morning start to this week.
I’ve added. In the long run I think it’ll come good. See them as online Primark. People have short memories when it comes to cheap goods.
But do we have a long term blind spot when it comes to ethical investing?
I did once suggest to Edward (Stockopedia) that it would be curious/interesting to have an equivalent "Ethical Rank" metric.
MichaelFBS hits the nail on the head very well.
The counter side to ethical piety is that it is consumers who decide what is and is not acceptable. We as investors provide cash/liquidity to companies, and companies only survive by adding value to a product/service/asset and fulfilling the demand of a consumer.
"Nobody ever went busy by underestimating consumer taste"
Any thoughts on £boo today after the weekends activity anyone...?
The media are now all over this, but the sweatshop conditions in Leicester have been known about forever. The potential difference is that with the factories a breeding ground for Covid they can no longer be ignored by regulators.
For Boohoo (LON:BOO) investors the questions seem to be:
I'd have thought the former was something interested investors could model. The latter is more in the realms of uncertainty - although nothing I've seen in the press so far appears to demonstrate a real link.
Overall, though, it's hard to see how you can source an £8 T-shirt from the UK when minimum wage is £8.72. As one of BOO's competitors noted at the weekend, they have better visibility of standards in Bangladeshi factories than they do of those in Leicester.
timarr
It is notable that the poor conditions in Leicester prevent the competitor placing their business there and that instead the work goes to Bangladesh. That’s an interesting counter to the usual cynical justification for turning a blind eye that if anything is done the people in Leicester will all be made unemployed. In fact work is going to Bangladesh because working conditions in the factories there are better.
John
Are they or is it a case of out of sight out of mind?
Regards
Michael
There is no excuse for the fashion companies not to inspect factories in this country and take responsibility. I have connections with a food manufacturer and apart from having to pay for an annual independent audit they have visits from time to time from the various supermarkets. Apart from looking at the food production they do a check on hours staff are working, the pay and holidays they get and even the breaks during the day. The manufacturer then often has to pay their supermarket customer for carrying out the check! Obviously, standards in food production are critical but checks could easily be carried out in clothing factories if Boohoo and their competitors had a mind to do so.
I have factory audit experience here and abroad, albeit in very different industries. I expect the main suppliers will have a nice clean shiny "Potemkin factory" ready to tick audit boxes. The trouble is if most of the actual work is done elsewhere. So the auditors need to drill down to understand whether what they are being shown is the whole picture. What is the turnover of this business - do the people and equipment they see credibly have the capacity to make that much product. What are they subcontracting, can we go see them too. What is being delivered to goods-in, where did those boxes come from, can we go there now please, yes straight away, etc.
I expect the customers that did audit thoroughly are the ones that decided they couldn't place their business in Leicester. Sky news is quoting a figure of up to 10,000 people there working in slave-like conditions.
https://news.sky.com/story/leicester-up-to-10-000-could-be-victims-of-modern-slavery-in-textile-factories-12027289
I would hope clothing factories are inspected and audited. There are nasty skin conditions, allergies, and concerns with the spread of infections with clothing too.
Good comment On:
"Overall, though, it's hard to see how you can source an £8 T-shirt from
the UK when minimum wage is £8.72. As one of BOO's competitors noted at
the weekend, they have better visibility of standards in Bangladeshi
factories than they do of those in Leicester."
The questions for me would be:
Regards
Michael
I was in garment manufacturing business for 40 years. When I first started in the 70s , a good seamstress was earning more than a legal secretary, they were able to buy a home and generally had a good standard of living. From the 90s onwards the downward spiral on wages began, I had factories overseas and in the UK. I got out in 2009 when it became impossible to meet the retilers demands on prices and lead times without exploiting the workforce.
Hi Andy, from your comments and experience of the industry, should we take that a cheap ‘made in the UK’ t-shirt bought anywhere is most likely made by an exploited workforce?
(Re: Boohoo. No position).
Boohoo (LON:BOO)
my thoutghts are
positive - QUIZ (LON:QUIZ) have been dragged into the scandal - that's great news for Boohoo (LON:BOO) - the less its about them and the more its about unscrupulous subcontractors or the indusrty in general the less its simply a boo only issue.
negative - daily mail article about Mahmud Kamani partying it up not so long ago with one of the sweat shop bosses. Not good news but being honest its probably to be expected that they would socialise in the same circles as those they trade with.Warning i read the mail online and took this article form there - i would say the mail online can be an unreliable source of info - publish now and worry about whether its true later
If there is any serioulsy bad news over the weekend i haven't seen it.
As Paddy once said if LUCE does not rise I'll eat my hat, thoughts welcomed
Hi Paul - any thoughts on Uls Technology (LON:ULS) and their latest update would be helpful. Many thanks!
Morning Paul,
Any thoughts on how you think Eurasia Mining (LON:EUA) might play out. Lots of activity at the moment....
Paul does not usually comment on resources stocks....
Nanoco (LON:NANO) morning Paul seem to remember you hold a few of these rns to say funding agreement in place with a US based firm re the case against Samsung. The not so good news mentions can take on average two years for a case to get to court.
At least it explains the jump in price a couple of weeks back on no news seems as ever someone was in the loop ahead of Joe Public.
I have watched this share for many years.in Stoko parlance I would call it a sucker sock
My morning smallcap tweet: 20 summaries today. QUIZ has questions to answer
Modern Water (LON:MWG) Global Ports Holding (LON:GPH) EQTEC (LON:EQT) Morses Club (LON:MCL) Ethernity Networks (LON:ENET) Deepmatter (LON:DMTR) Alternative Income REIT (LON:AIRE) Luceco (LON:LUCE) Image Scan Holdings (LON:IGE) Intelligent Ultrasound (LON:MED) QUIZ (LON:QUIZ) Corero Network Security (LON:CNS) Avacta (LON:AVCT) Integumen (LON:SKIN) Directa Plus (LON:DCTA) Novacyt SA (LON:NCYT) Remote Monitored Systems (LON:RMS) Nanoco (LON:NANO) Clinigen (LON:CLIN) Westminster (LON:WSG) Northern Bear (LON:NTBR)
Modern Water (MWG) Integumen and Avacta intend to enter into a supply agreement for the supply of Affimers into Integumen's sensors with the aim of integrating these sensors and retrofitting them into Modern Water's Microtox water contamination system units to detect covid. Awaits testing of Avacta Affimer reagents is completed over the next few weeks.
Global Ports Holding (GPH) has suspended its pursuit of a Premium Listing on the LSE. Also will terminate the Relationship Deed with its controlling shareholders, Global Ports Holding B.V. and Global Yatırım Holding to allow the co to benefit from more efficient sharing of its controlling shareholders' resources.
EQTEC (EQT) Aries Clean Energy filed a complaint in a Californian court against the co and others, alleging patent infringement through the use of the Group's advanced gasification technology in the North Fork Community Power project. Applies to USA only. Co says claim without merit.
Morses Club (MCL) launches remote lending process for new home collect credit customers.
Ethernity Networks (ENET) £780k placing at 12p, a discount of 37%, to keep the lights on.
DeepMatter (DMTR) £2.1m placing at 1.5p, a 19% discount, to strengthen the balance sheet and invest in sales, marketing, distribution and support.
Alternative Income REIT (AIRE) issues confusing set of nos for Q rent collection.
Luceco (LUCE) guides H1 rev down 14% but adj op profit up 25%. guides FY adj op profit at least flat and ahead of current analyst expectations. Co not making use of any government lending or tax deferral schemes.
Image Scan (IGE) partnership agreement with a major security technology company that will lead to the launch of a new range of security X-ray screening systems
Intelligent Ultrasound (MED) guides H1 rev £2.5m (£3.1m). Lockdown has dramatically constrained the Group's ability to demonstrate and therefore sell ultrasound training simulators to hospitals.
Quiz (QUIZ) fingered by press in Leicester rag trade scandal. "From our initial review, we believe that one of QUIZ's suppliers based in Leicester has used a sub-contractor in direct contravention of a previous instruction."
Corero Network Security (CNS) guides H1 rev up 48% and order intake up 58%. Co "continues to invest in sales and marketing, with progress achieved against its strategy to both augment its direct sales efforts and increase momentum through its channel partners in more regions."
Avacta (AVCT) see Modern Water announcement.
Integumen (SKIN) see Modern Water announcement.
Directa Plus (DCTA) wins contract to supply total waste management services to Cummins Generator Technologies in Romania. Worth $3m over 3 years starting Oct.
Novacyt (NCYT) guides H1 rev up over 900% to €72.4m. Demand for the Company's COVID-19 test remains strong with some extended into the second half of the year and in some cases into 2021. Guides H2 rev better than H1.
Remote Monitored Systems (RMS) £265k placing at 0.25p, an 11% premium, to keep the lights on.
Nanoco (NANO) gets litigation funding for patent case against Samsung. I'm short.
Clinigen (CLIN) Orphan Drug Designation for aldesleukin in the treatment of Amyotrophic Lateral Sclerosis, a severe neurodegenerative disease leading to progressive muscle weakness, paralysis and death within a median time of 2-4 years. Needs marketing approval for this indication.
Westminster Group (WSG) guides H1 rev up 24% and a move into profit.
Northern Bear (NTBR) FY(Mar) rev down 3%, adj EPS 8.7p down 36%. Passes div. Back to 75% of normal activity levels. Order book has continued to increase. I hold.
Jack, I would be interested in your view of Novacyt SA (LON:NCYT) please. This is, obviously, extremely volatile, but figures today seem to show concrete benefits of its Covid-19 products with (compared to some trading updates) clear guidance on massive revenue increases, EBITDA profitability over €45m (I'm wondering what adjustments there might be), and a cash position as at 30 June 2020 of €20m. Demand in the short-medium term sounds strong:
Demand for the Company's COVID-19 test remains strong, with June sales of €25.4 million (£22.5 million) showing the sixth consecutive month of growth. Certain contracts for the supply of the test have also been extended into the second half of the year and in some cases into 2021. With the daily global incidence of SARS-CoV-2 infections continuing to rise, Novacyt expects significant ongoing demand for COVID-19 testing well into 2021
The company seems to have finally got into the US market, saying "has signed a major distribution agreement for its COVID-19 test with a new global strategic partner. The US is delivering significant sales growth for Novacyt and this new agreement enables the Company to accelerate penetration of its COVID-19 test in this important market. This distribution agreement will focus initially on the US, with the potential to expand into further markets".
It also hints at acquisitive growth due to the expanding cash pile - 'there is expected to be greater cash generation in the second half of the year and the Company is reviewing its capital allocation policy to enhance and accelerate long-term value creation through its three-pillar strategy of organic, R&D and acquisitive growth.'
Thanks for the pointer, I've just done the write-up. It does look interesting to me and I think I'm going to take a closer look, but I'm a bit late to the party!
I'd like to get a feel for what life after COVID might look like for NCYT. In the meantime though the trading momentum is very strong and I see directors have bought at levels above today's share price in the recent past.