Small Cap Value Report (Mon 13 Mar 2023) - MCON

Good morning from Paul & Graham!
Breaking news! HSBC has bought SVB UK, in a deal that involves no taxpayer money. Details here.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Graham’s Section:
Mincon (LON:MCON)
Share price: 88.5p (pre-market)
Market cap: £188m / €212m
This is an Irish engineering group that designs, manufacturers, sells and services rock drilling equipment. Perhaps we can think of it as the “anti-Somero” (since the equipment from Somero Enterprises (LON:SOM) is designed to create perfectly smooth surfaces!). Like Somero, Mincon sells its own proprietary equipment, though Mincon also sells some 3rd-party gear.
Today, Mincon publishes its results for 2022, and here are the highlights:
Revenue +18% to €170m, with 19% growth in its own products vs. just 10% growth in 3rd party products. Own products are now responsible for 83% of total revenue.
Gross profit +11% to €54m.
Operating profit +9% to €19.7m
Net income +1% to €14.7m
Financial results
As you might notice from the above, there is a disappointing lack of progression as we go down the income statement: the percentage increases get smaller rather than larger!
This is worth investigating, as usually we want operational leverage to produce the opposite result.
First, the reduction in the gross profit margin: this is caused by two factors. 1) Input cost inflation, although the company says that cost increases were implemented in H2 to “largely” offset this. 2) There were significant new project costs and these are included in the calculation.
Mincon is one of those companies that applies zero adjustments to its numbers. While others might find a way to keep new project costs out of the “adjusted” profits, Mincon simply states what its actual results were. How refreshing!
This being the case, I think we have a reasonable explanation as to why gross margin dropped a few percentage points. It’s not reflective, in my view, of the company’s underlying pricing power.
Profitability was also held back by a c. 50% increase in borrowing costs. The company reports various bank loans adding up €31m and that have “a mixture of variable and fixed interest rates”. The average interest rate currently is 4.89%.
I calculate the company’s return on equity for the year as 10%, similar to the prior year.
2022 review / outlook
Mincon serves three industries and it was construction that stood out in 2022 with 45% revenue growth from this source as it won mid-to-large project contracts in North America. (Mining is the primary industry served by Mincon, and the other is geothermal.)
Supply chain / freight conditions- the difficulties experienced last year started to ease in H2 and Mincon has begun to “normalise” its shipping arrangements and unwind its working capital. Improved factory lead times will also reduce the need to use expensive air freight.
Order books are “strong”.
The Greenhammer project in Australia has run into some difficulties, but management remain confident in its potential:
We have been on site with the system drilling blastholes with our Mincon owned test rig. The Greenhammer system has performed to expectations when operating. However, it has been challenging to consistently deliver drilled metres due to reliability issues encountered with the drill rig. As a result, we had to carry out an extensive rebuild on the rig which we are confident will reliably support the system. While this delay has been frustrating in the short term, we remain confident in the long-term success of this project and believe that the system will be transformational for Mincon and the hard rock surface mining industry.
There is also a subsea project and it has seen “a number of significant milestones achieved”, but commercialisation is some time away.
The CEO says:
…we remain confident that we will deliver in the year ahead as well as make significant progress on our ambitious product development projects.
These ambitious projects challenge us, but they are essential to underpin our future, maintain our competitive advantages and to drive our profitability and return on capital employed.
My view
These results could have been a little more exciting for prospective Mincon investors. But 2022 was a difficult year, for reasons which affected many companies.
Additionally, the complications with Greenhammer in Australia are a slight worry, and Mincon’s increased use of bank loans are also not ideal for anyone who prefers investing in cash-rich smaller companies.
If I subtract Mincon’s bank loans from its cash position, net debt has increased to €15m, from only about €4m a year ago.
I’m still inclined to think that this is a company of above-average quality. Greenhammer continues to make progress, and the cash position should improve as the company unwinds the inventory it built up in 2022. There was a €13m increase in the inventory position last year, and this alone can account for its increase in net debt.
I’m on the fence, not sure if I should rate this stock positively or stay neutral. I think on balance I’ll stay neutral, looking for more certainty and a better cash flow performance before hopefully switching back to a positive stance.
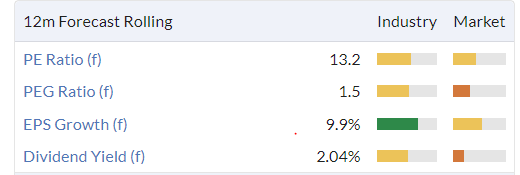
It’s finely balanced, because valuation does not look excessive to me:
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

61 comments
Hi Mr Boon. I was surprised to see the extent of the divergence in performance between (LON:X7PP) & (LON:X7PS) which I think is the Euro denominated version of your bank ETF.. I think I've decided that the recent falls are maybe not such good opportunities when you look at the huge increases in value that have already taken place since mid Octoberfor both these ETFs. I guess I am more nervous about future bad debt provisions rather than the recent SVB bank shenanigans. Anyway I hope it works out to be a very profitable investment for you. I always read your observations with great interest. In passing, I am surprised to see the extent of falls in Barclays Bank. Cheers.
Interesting observation about the two ETFs in different currencies and their diverging performance! That really shouldn't happen if the ETFs are the same underlying portfolio of shares. Both are full replication I believe.
I am cognisant of the potential for increase in bad debt provisioning. I have bought Invesco STOXX Europe 600 Optimised Banks ETF Acc (LON:X7PP) not as a long term hold, but more short term. I believe that within the next month or two, the markets will get the valuations of the big banks back to where they were pre-SVB. And then even go higher, because the big banks now have gotten more customer growth, deposit inflows (at low interest rates), allowing them lend more and also expand their NIM.
However, I do view the banking sector as being at the start of a boom cycle, now that rates have returned to normality. Therefore, I will be looking for longer term holds - specific bank stocks. Just need to find a way to get comfortable going through so many pages in each annual report :)
In a day like today, I only look at the fallers shares. It is a buy for me regardless what happens over the week. I pick up those I thought were good values last week, surely they are better value this week. Can they fall more? possible but I can not time the market. I buy some this week and some more in 2-3 weeks regardless what has happened to the share price.
I must say I've taken a similar approach and moved some money out of cash today and into US and UK equities that I've I had on the watchlist. Here's hoping it doesn't drop too much further. It's my personal view that this drop might be a bit overdone. We could see a climb back up with decent CPI data tomorrow and even a possible fed rate pause in the coming weeks. Here's hoping!
Interesting that Goldman Sachs now thinks UK inflation will fall below 2% target this year. That would suggest rates are too high if that turns out to be the case.
The UK market absolutely wet itself over SVB today whereas the US market appears a little more level headed. Perhaps party down to the awful liquidity in the UK markets these days.
Davidjhill. Thanks for posting Goldman Sachs forecast that UK inflation will fall below 2% this year. This is the most positive piece of economic forecasting that I have heard in the last year! If they are right, then this would be very positive for share prices.
The UK market absolutely wet itself over SVB today whereas the US market appears a little more level headed. Perhaps party down to the awful liquidity in the UK markets these days.
I'm seeing a dichotomy between a relief rally for tech (SVB depositors made good by regulators/Fed) and the recession trade exemplified by a flight to safety (bond yields slashed, healthcare and staples up) and away from cyclicals (industrials pummelled - esp Europe owing to the previous assumption that a recession had been averted)
I'm seeing minuscule liquidity in the UK
I'm seeing minuscule liquidity in the UK
Completely agree. Couldn't buy a full GBP10k of Treatt (LON:TET) this morning when markets were in full sell-off. Nevertheless, the behaviour I described (tech relief vs recession trade) is global. If anything, more pronounced in continental Europe than here.
Would this be the same Golden Sacks that was forecasting oil at $200? To be taken with a rather large pinch of salt.
all economic forecasting is to be taken with a large pinch of salt in its absolute
what is interesting is why they think that - not the actual number, and whether the direction of travel is there.
Correct. The UK market really is dreadful for the private investor
Quick Q - anyone know an LSE-listed ETF that gives exposure to only the major banks globally?
I am planning to take this opportunity to buy in. They have been hammered recently due to:
But looking for an ETF that tracks the biggest banks only, not a broad selection.
Found one - Invesco STOXX Europe 600 Optimised Banks ETF Acc (LON:X7PP)
Looks to be highly concentrated - top 10 holdings are 60%+
European (and UK) banks only, all the top names. LSE listed, GBP currency. Physical replication, no currency hedging.
I don’t know about ETFs but Polar Capital Global Financials Trust (LON:PCFT) might be worth a look
Full portfolio: https://www.polarcapitalglobal...
Interesting .... I am looking at the correlation between SP and bond yields. The higher the correlation and the more likely I am to buy puts. SVP is one of three banks to have gone down in the US and more will follow, the direct result of increasing FED rates and the banks having to invest excess liquidity (driven by COVID) into the bond market rather than loans. Good luck .... it takes two alternative views to make a market
I fully expect a few more banks to go under. Either USA, or in Europe. But I expect them to be smaller ones.
The catalyst for a collapse, in all three cases so far, has been depositors pulling deposits.
This is much less likely to happen with the big banks. For two reasons. The first is a diversified depositor base. The second is high regulation, meaning higher amount of regulatory capital buffers. And the third is that if a depositor is skittish, they will pull from small banks, but the money needs to go somewhere (eg big banks).
Hence why I think it is a good opportunity to buy into just the Big Banks (but not the wider banking index as a whole).
I have now taken a a sizeable position in Invesco STOXX Europe 600 Optimised Banks ETF Acc (LON:X7PP) !
Combined with my existing stake in Metro Bank (LON:MTRO) I'm now approximately 8% of the Boon Fund in banks.
I have now taken a a sizeable position in Invesco STOXX Europe 600 Optimised Banks ETF Acc (LON:X7PP) !
A decent call with European banks having deposited significant collateral with the ECB (= reduced need to liquidate bonds at a loss) and European depositors being very slow-reacting and primarily retail and small value.
For the bold, wouldn't iShares US Regional Banks ETF be the better bet - down 27% at one point today? My thinking is that one or more small banks might run into difficulties, fail even, but there are 38 holdings in the fund. Will Biden, facing re-election in 18 months, let depositors suffer across ALL of them? No way. And if matters were so bad that he, the Treasury and the Fed couldn't together avert a calamity, then our whole portfolios are toast for a while anyway!!
Ah, but if you see my comment above... I think small and regional banks are going to take more of a beating. I know the Feds are working on a liquidity line (giving cash for underwater bonds at the par price). But I think their recovery will lag the big banks.
If anything, the big banks will benefit out of this. Depositors will increasingly shift money from small to big banks, accepting low interest - perfect for the big banks NIM.
In a day or two, the narrative will be: "as expected, the Feds/BoE/ECB will do whatever it takes to secure the banking sector. Big banks are the last to be let to fall. Super secure, low PEs, good dividend yields (especially given the dropping rate expectations now) - lots to like."
I wouldn't be surprised if the big banks share prices eclipse the pre-SVB prices in the coming weeks.
I think small and regional banks are going to take more of a beating
My interpretation is they already have (in terms of SP) - thereby giving you a potentially better entry.
This is a purely academic discussion since I actually took the alternate course myself and bought a big U.S. bank today. I don’t like banks as investments usually - unless they have strong wealth management revenues - and I hate small ones!
One of the directors of Alphawave IP (LON:AWE) (Sutardja) has invested millions in AWE recently - or his family investment company has. Over the same period, broker forecasts have fallen somewhat, though growth is still forcast to be strong.
There's no recent discussion of AWE in SCVR. Is anyone here following them?
Looks like he has been buying for a while, big chunks bought in 2022 for example, and it’s not been much of a good investment so far. Interesting company though, I will follow it. Lots of good points about it aside from momentum.
Hi FREng. I recently bought Alphawave IP (LON:AWE) .
It has been discussed here: https://www.stockopedia.com/co...
I used to hold, sold last week, following what happened to WANdisco (LON:WAND) , I don't want to take the risk, something does not seem right.
Any reason why? Alphawave IP (LON:AWE) is a very different kettle of fish to WANdisco (LON:WAND) . The current SP is pricing in a big increase in revenue next year, but not unreasonably so. Real issues around a stock like this are how it stands vis a vis competitors. If you have any view on this we would all be interested. (I don't hold.)
Alphawave IP (LON:AWE) does appear (according to the FT article in a prior discussion) to have large related party issues. The brother of the wife of Sutardja is involved with a company with a large contract with Alphawave. Obviously he is buying stock which is significant, but pre-IPO he owned 17% and now owns 13%.
Also, in one of the slides it shows (something like) cumulative bookings for each year, I assume to mask the contraction in the current year.
It is probably best if you read the other post about Alphawave IP (LON:AWE).
Yes different type of companies. Shares are down from around 450p, seems the market does not trust this company. Forecasts have been reduced recently.
Thank you for your observations on Mincon Graham, we do not hold but I'd been hovering over the buy button ahead of today's results, I thought the Greenhammer update would be more positive. I'll wait and watch.
MelloMonday tonight.....In recognition of the fact that so many investors have been hit by various company frauds and other shenanigans at companies where we have invested it is worth looking at some of those in depth and also with the help of the audience so we have made tonight's show free to all with the code VIP13
https://melloevents.com/mm13ma...
Thanks! A good way to try it out.
Why does it start a 5 o'clock? Or are organisers assuming everyone works from home or is retired? I used to subscribe but the event starts too early, some presenters are not concise enough, so the whole thing goes on for too long. Any thoughts on revising MelloMondays?
We had complaints at one point last year that the show was finishing too close to the audience members bedtimes and in fairness it is a four hour show so can run late.
It is difficult to keep everyone happy and the show is recorded so everyone can watch it the next day too if they have registered.
Many watch on their phones whilst traveling home and you can just listen.
How would you propose to change it?
A lot of people are still at work at 5pm. Do people really go to bed before 10pm? Most I know go to bed later. Does not bother me as retired now.
Why do you require my mobile number?
I have little ones who are up 5am and during the night, so I go to bed at 9pm!
I'd start it at 6.30/7.00 ending it by 9.30/10.00 and restrict the time of some presentations. Some are not concise enough, which may well be sending your viewers to sleep, hence their earlier bed times!
We do not control or pre run through company presentations....it is their own work and they are all different lengths as some are new to Mello so we give a bit longer. Basically the Q&A tends to be longer with new companies whereas regulars need less time to get the message across. It is far from easy hosting these but I try to keep everyone awake
Prefer the earlier time as in South Africa and 2 hours ahead !
I have been attempting to 'run my winners'... It was working great until the last week...
Ditto.!!! What I had made in the first two months of 2023 has pretty much gone now. It just confirms we aren't out of the woods yet.
Yes, so much for the comments the charts, as so often the opposite happens.
Very quiet on here today with the market in freefall. It looks like everyone has shut down their devices and gone into hiding until it's safe to come out.
I know I have!
nope, just little to chat about. the opposite of shut down, sitting here watching and adjusting prices and alerts.. buying the odd starter position.
AKA masterly inactivity
I see it as a buying opportunity when Mr Market is in a manic depression & have been topping up my IT’s today.
Very worried that banks only invest in one sector any others?
https://www.investegate.co.uk/...
Fonix Mobile (LON:FNX)
Fonix interims out this morning read well,11% adj eps increase, continued steady growth, lots of growth possibilities, 99% customer retention and a 15% interim dividend increase.
I can't believe for one minute that HSBC had time to do its due diligence over the weekend and haven't secured some sort of government (=taxpayer) guarantee of its purchase...
Trusting Governments can be risky mjifgs, especially for banks persuaded to rescue other failing banks. HSBC shares look cheap (look at the dividend) but haven't reacted well so far.
This makes me wonder just how beholden to the BOE and the government UK banks are. Hopefully Standard Chartered (LON:STAN) which I hold will weather this SVB storm but I no longer hold HSBC Holdings (LON:HSBA) having sold on the last peak.
RE Polarean Imaging (LON:POLX), they have asked for suspension of shares until matters clear up.
Polarean Imaging plc (AIM: POLX), the medical imaging technology company, announces that the Company has sufficient cash outside of SVB to meet its immediate liquidity needs.Next Steps
The US Federal Reserve has issued a press release stating that it has created an emergency lending facility guaranteeing depositors access to their funds: federalreserve.gov/newsevents/pressreleases/monetary
20230312a.htm. The press release states that the funds will be made accessible from today.
The Company has requested that the listing of the Company's ordinary shares on AIM be temporarily suspended while it seeks further clarification.
The Company will update the market when appropriate.
This is the first company I have seen today to take suspension action.
Diaceutics (LON:DXRX) also suspended. Has all its cash balance with SVB UK and US.
Obviously to protect itself from a run on the share price. I hold.
Good news about HSBC and SVB UK.. The best!
Not sure that it means exactly 'business as usual' in all respects but hope so.
Hmmmm....
My morning smallcap tweet: Crash-a-banka: "We'll always have HSBC."
Global Ports Holding (LON:GPH) Nuformix (LON:NFX) Woodbois (LON:WBI) MTI Wireless Edge (LON:MWE), Nightcap (LON:NGHT)
◄Global Ports (GPH)► guides FY-Mar adj EBITDA over $65m. Q1-3 rev up 62%. Outlook for the cruise industry is very positive. [SP=159.5 Cap=100m]
◄Nuformix (NFX)► extends this FY from Mar to Sept. Doesn't even give a reason. Surely not kicking the going concern can down the road. [SP=0.32 Cap=2m]
◄Woodbois (WBI)► £3m placing at 1.2p, a 4% discount, for working capital. [SP=1.2 Cap=27m]
◄MTI Wireless Edge (MWE)► FY-Dec rev up 7%, EPS up 3%. Inline? There's been no FY trading stmt. Outlook in line. [SP=48.35 Cap=43m]
In line: NGHT
There'll always be a HSBC but wait, it's mostly Chinese!
Good morning! On your toes this morning Paul. I was relieved to read the SVB UK breaking news link you posted, and impressed with myself that I can still read the SCVR while in the 'Brace.. Brace.. Brace' position.
Lol... stand to, stand to, carry out blanket search!