Small Cap Value Report (Mon 13 May 2024) - CER, BBSN, TMG, MDZ, ACRM, HUD, JWNG, ZOO

Good morning from Paul & Graham!
Mello Monday tonight looks interesting, with one of our favourites Warpaint London (LON:W7L) presenting, plus Transense Technologies (LON:TRT) which we were discussing here last week. Also the author of Pigs Get Slaughtered will be on!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Companies Reporting
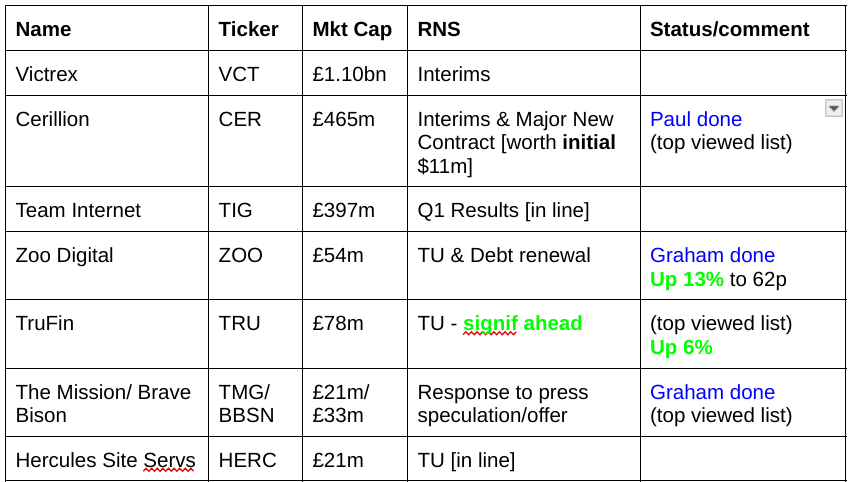
Other mid-morning movers (with news)
Mediazest (LON:MDZ) - up 67% to 0.1p (£2m) - Trading Update - Paul - AMBER/RED
Positive-sounding update, but a very quick look into the financial details shows a tiny business that averages around breakeven over the years. It can’t be economic to be listed, so de-listing risk looks high. Balance sheet is weak, running on fumes, and propped up with shareholder loans. Name drops big clients!
Acuity RM (LON:ACRM) - up 16% to 4.35p (£5m) - Contract Win - Paul - AMBER
Might be worth nanocap investors taking a look at this one, it seems to be winning contracts (upselling a renewal in this case) to big clients, including UK Govt. £500k over 3 years is a decent contract for a company this small. Looks like Acuity it was reversed into a cash shell in 2023. Too early to judge, but the flurry of contracts announced suggest there might be something interesting here, but proper research is needed - I’m just flagging interesting-sounding news.
Huddled (LON:HUD) - down 13% to 3.05p (£10m) - FY 12/2023 Results - Paul - AMBER
Trumpets a £13m profit, but it’s actually a loss from continuing operations, more than offset by profit on disposals, as the listed company changed its activities. The strategy is to build a portfolio of small eCommerce businesses - good luck with that, you’re about 25 years late!
Is the balance sheet any good? Actually yes, it is. NTAV of £6.4m, of which £4.3m is cash, and there’s no interest-bearing debt. Total creditors are only £0.75m, so it’s in a very comfortable position. I wonder if more small acquisitions will deplete that cash pile? Outlook comments indicate continuing losses in short & medium term, which rules it out for me.
I’m happy to watch from the sidelines for now, and we can see how it develops. So given the solid financial position, let’s go with AMBER for now. I recall this caused a flurry of interest last year, do any members want to update us with your current views?
Jaywing (LON:JWNG) - down 17% to 2.6p (£3m) - Update - Paul - RED
Trading is weak, in discussions with lenders to increase borrowing facility due to strain on working capital, CEO steps down, strategic review ended as presumably nobody wants to buy the company. Mentions stakeholders (always a red flag). Paul’s view - looking at the last balance sheet, it’s the lenders who’ve got the biggest problem here. Equity looks worthless, so it’s a bargepole I’m afraid.
Summaries of main sections
Cerillion (LON:CER) - 1,575p (pre-market) £464m - Interim Results, Major Contract Win - Paul -GREEN
Good H1 results (against tough LY comps) are slightly ahead of broker expectations. A major contract win announced today seems to further underpin seemingly modest FY 9/2024 expectations. I need to be better understand the nature of revenue/profits, since only about a third of revenues seem to be recurring - not that much for a SaaS business. So a few questions, but overall it's still very much one of my favourite UK growth companies.
Brave Bison (LON:BBSN) - down 3% to 2.45p (£31m) - Graham - GREEN
Mission (LON:TMG) - up 6% to 24p (£22m) - Graham - RED
These marketing agencies were in the weekend press: BBSN are interested in taking over TMG on an all-share basis, with TMG shareholders owning 45% of the combination. I leave our RED & GREEN stances unchanged but on the basis of their respective balance sheets, I do see merit in the BBSN proposal.
Zoo Digital (LON:ZOO) - up 14% to 62.8p (£61m) - Trading and Debt Facilities Update - Graham - AMBER
A very reassuring and positive update from ZOO as the company’s bank extends its (undrawn) facility for a year. Furthermore, its broker upgrades FY March 2025 EBITDA expectations thanks to a very strong Q1 performance with good visibility for the next few months. I can see both sides of the argument here.
Paul’s Section:
Cerillion (LON:CER)
1,575p (pre-market) £464m - Interim Results, Major Contract Win - Paul -GREEN
Cerillion, the billing, charging and customer relationship management software solutions provider…
H1 numbers look fairly good, but not spectacular. We have to be more picky now the valuation is so much higher than in previous years. Liberum reckons H1 is slightly ahead of expectations, and points out the tough prior year comparative.
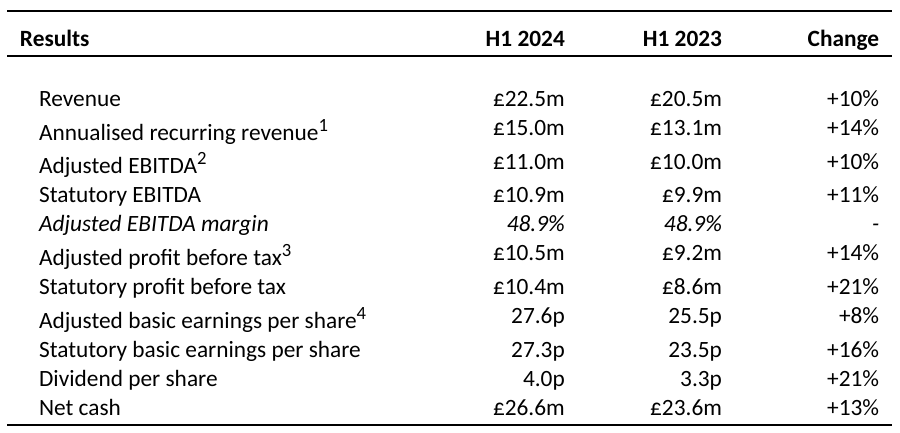
Outlook is confident -
"Cerillion's interim results again set new records for our key performance indicators in any six-month period and demonstrate the strong momentum in the business and the significant growth opportunities available.
"With an ever-growing sales pipeline, increasingly strong demand amongst telcos for digital transformation via SaaS solutions, and some exciting innovation in our product suite, we expect to continue to grow strongly. Given the Company's progress - including the major new contract announced today - and prospects, we believe it is well-placed to deliver market expectations for the full year and beyond, and we view the future with confidence."
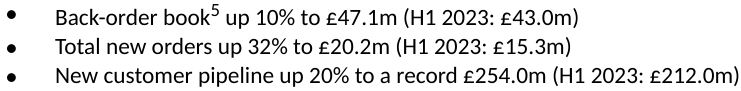
Order book & pipeline details also good -
Forecasts look modestly set, and it’s looking increasingly likely that CER should beat forecasts, which Liberum hints at in an update today. We have H1 actual of 27.6p (adj basic EPS above), and Liberum pencils in 47.6p (on a fully diluted basis) for FY 9/2024, which looks too low. Surely something like 60p might be more realistic?
Valuation (based on 1575p/share) -
Liberum’s 47.6p = PER 33x
My guess of 60p = PER 26x
So as we always say, CER shares are certainly not cheap on a PER basis, but I wouldn’t expect them to be, as it’s an exceptionally good growth company. If my guess on earnings is close to the outcome, then I think the valuation looks OK.
It all hinges on what future growth is like of course. I think the story here is very credible - that CER has the right software (standardised, hence high margins because it doesn’t need to be re-written for each client), and is clearly on a roll winning bigger contracts with each contract win providing another reference site to help win more customers. I find that a compelling investment case, that we can all understand without needing any technical expertise about the products - the numbers and contract wins do the talking.
Recurring revenues - this is my main area of questioning, and I hope we can get more colour from management on the webinar (details below). The £45m forecast revenues for FY 9/2024 (probably too low) compares with annualised recurring revenues of £15m at 31/3/2024. So only about a third of revenues seem to be contractually recurring.
From memory I seem to recall that CER is still heavily reliant on up-front licence fees from some contracts. So I need to better understand the mix of SaaS, and one-off licence fees. Ie does CER have to keep winning major contracts just to stand still? This could mean the risk of a profit warning if say a future year doesn’t get as many big contract wins as expected. Also it can be dangerous to chase up a valuation, based on not necessarily recurring very high margin profits.
I’m only asking the question, not expressing a view here. It’s absolutely key to the valuation to get this right.
Balance sheet - looks very strong, as usual. NAV £42.5m, less intangibles of only £4.5m (it hasn’t done much in acquisitions, and doesn’t capitalise much development spending, so nice clean numbers). Hence NTAV £38m, which is plenty for the size of company. Remember there are no inventories and little fixed assets at software companies, so NTAV can be quite small, or even modestly negative. Hence £38m NTAV is more than enough here. I think it needs that rock solid balance sheet though, to provide increasingly large customers with the confidence CER is at zero insolvency risk (vital when it’s entrusted with running business critical cloud-based systems). Hence paying out the cash in say a special divi would be a mistake I think, it's better to hoard a nice cash pile for any eventuality.
One query is note 5. This shows a big increase in long-term receivables, up to £9.3m, called “accounts recoverable on contracts”. I think the double entry here is CR: revenue/profit on the P&L, and DR: receivables on balance sheet - ie the profit has been booked, but the cash hasn’t yet been received. This is worth querying with management, as I don’t normally see receivables in the non-current section of assets. There’s another £12.6m of receivables in current assets, which again seems a lot.
I vaguely recall management previously saying that they sometimes sweeten deals by allowing customers deferred payment terms, given CER’s cash rich position.
The rest of the balance sheet looks OK, with a very comfortable cash pile of £26.6m, and no interest-bearing debt.
Cashflow statement - about a third of the positive cash generation is sucked into working capital again - mainly increased receivables. I suppose that’s to be expected at a high margin business growing sales quite fast, but links into my points about extended receivables above.
Only £560k capitalised development spend in H1 is nice and prudent accounting (in practice companies have tons of wiggle room to fit into the fairly loose accounting rules on this), so a low figure here shows they’re prudent I think.
Dividends paid are modest, and easily affordable - it has considerably greater dividend paying capacity I think. Hence the 0.8% yield could improve in future years, once the growth rate has slowed maybe.
Another big contract win today -
Cerillion, the billing, charging and customer relationship management software solutions provider, is pleased to announce it has agreed a major new contract, worth an initial $11.1 million, with a leading provider of connectivity solutions in Southern Africa. The contract is for an initial five years and has scope to develop further over time…
Under the terms of the agreement, Cerillion will be supplying, implementing and maintaining its flagship BSS/OSS solution on a SaaS basis.
I’m confused here. Does that mean the licensing revenues will be spread over 5 years (SaaS basis), or will some be up-front? Was this already in the forecasts for this year, or not?
Webinar - should be interesting and hopefully people might ask some of the questions I mention above -
Shareholders and potential investors can register to join the online presentation through this link: https://bit.ly/CER_H124_results_webinar
Paul’s opinion - this all looks good to me. I see the share price is up slightly +1.6% at 1,600p (09:00) which strikes me as about right. CER shares are already on a punchy valuation, and I think might have dropped a little today on the interims and only in line outlook. Once shares are richly valued, they have to keep out-performing. The $11m new contract win saved the day though, and who knows, could lay the groundwork for another upgrade in due course? I suspect it’s set up to beat existing forecasts, but it needs to be.
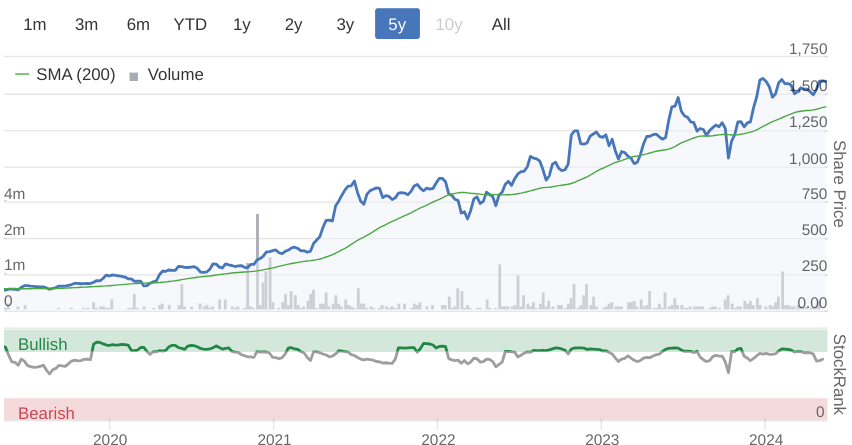
So long as CER can keep the contract wins rolling in, then I could see this share continuing a very impressive long-term up-trend. Things have to pause for breath, and retrace a bit in between of course.
I need to better understand some aspects of the business model, but from everything I’ve seen we have to stay GREEN here, maintaining my very positive comments previously on 16/10/2023, 2/1//2023, 20/11/2023, and 22/4/2024.
Graham’s Section:
Brave Bison (LON:BBSN) - down 3% to 2.45p (£31m) - Graham - GREEN
Mission (LON:TMG) - up 6% to 24p (£22m) - Graham - RED
Possible all-share offer for The Mission Group (RNS by BBSN)
Response to Press Speculation & Possible Offer (RNS by TMG)
An article in yesterday’s Sunday Times noted that these rival marketing and advertising agencies could potentially be set to merge, with Brave Bison taking interest in Mission.
Here at the SCVR, we last covered Mission in December when I took a RED stance on the basis of the company’s large debt balance and slim profitability.
Mission’s last-reported net debt balance (for end-Feb 2024) is £19.5m. “Headline” (i.e. adjusted) profits for last year translated into large actual operating losses after impairments.
The situation at Brave Bison is quite different with Paul taking a GREEN stance in January on the back of strong results with the company also reporting a net cash balance of nearly £7m.
All of which brings us to today’s news.
Possible all-share offer for Mission
Key points about the offer as outlined by Brave Bison:
Combined group would have 2023 revenues of £120m and adj. EBITDA c. £14m, before allowing for any synergies.
This larger size “would present a more attractive investment opportunity to institutional shareholders than either standalone company leading to the possibility of the enlarged Brave Bison trading at a higher multiple of earnings” (GN note: BBSN currently trades at 10x trailing adjusted earnings.)
They point out that according to the Dec 2023 results, Mission had gross obligations of around £30m (bank loans etc.), and that a combination with BBSN “would result in a strengthened balance sheet and improved debt and covenant ratios”.
Scrolling down through this RNS, I also find the following comment by BBSN on Mission’s debt load:
The Board of Brave Bison believes these debt levels are unsustainable based on the historical free cashflow generated by Mission in the past three years. Even with substantial improvements to operating cashflows, the Board of Brave Bison believes Mission will struggle to repay outstanding liabilities without a combination of asset sales, which would reduce the scale and may reduce attractiveness of an investment in Mission, or an equity fundraising, which would be dilutive to non-participating shareholders. The prospect of both asset sales and an equity fundraising were mentioned in Mission's final results announcement on 28 March 2024.
Response by Mission
Mission have revealed that at the end of April, they already received a conditional proposal of 11.5 BBSN shares for every Mission share, which translated to a value of 29p.
The bid was rejected on the basis that it undervalues Mission; here are the key points from their side of the story:
Mission shareholders would own 45% of the combined group, which “does not fully reflect the inherent value in Mission”. They argue that for 2023, Mission would have contributed 81% of revenues, 71% of adj. EBITDA and 54% of adj. PBT to the combined group.
They say that BBSN are considering a £10m fundraise, after the proposed merger, to strengthen the combined group’s balance sheet. This could result in further dilution for Mission shareholders.
The proposed Board of the combined group would only see one of Mission’s NEDs joining the Board.
In short, the proposal is not “transformational”, is “earnings dilutive” for Mission’s shareholders, and there is “no certainty” that it would result in a re-rating of the combined group’s shares.
Graham’s view
Here at the SCVR we tend to emphasise balance sheet strength, and clearly BBSN are in the much stronger position in that regard. In that sense, their offer could be considered “opportunistic”, but it might also make sense from the point of view of giving Mission shareholders a chance to resolve their debt problem.
Mission today have disclosed that their net debt as of 30 April 2024 increased to nearly £27m, mostly relating to bank loans but also HMRC and acquisition payments (some of which can be settled in shares rather than cash).
Let’s add on their net debt figures to their market caps to see what the rejected proposal from BBSN looks like in terms of enterprise values.
Mission: shareholders would get a total of 1.06 billion BBSN shares, at a value of 2.5p each that’s a total value (before any re-rating) of nearly £27m.
Add on the net debt figure and the enterprise value for Mission is £53m.
Brave Bison: at 2.5p, its market cap is £32m.
Deduct last-reported net cash and the enterprise value for BBSN is £25m.
Therefore, in terms of their enterprise values, the deal values Mission at about 68% of the total (£53m out of £78m total).
From that point of view, it seems about right if the companies are being valued on their adj. EBITDA (Mission would provide 71% of total adj. EBITDA for last year). If the companies are being valued on adj. PBT, then it’s generous to Mission (Mission would provide 54% of adj. PBT for last year).
If you think these companies should be run on a debt-free basis, then, I would say that this is a very reasonable offer from BBSN. The combination of BBSN’s existing cash plus an equity fundraise would wipe out most of Mission’s debts, leaving a manageable amount that could hopefully be paid off through the group’s combined cash flows.
On the other hand, if you are comfortable with these companies being run on debt, and if you think Mission can trade its way out of its net debt position, then you would naturally want to hold onto Mission’s shares and see its market cap improve as its debt load reduces.
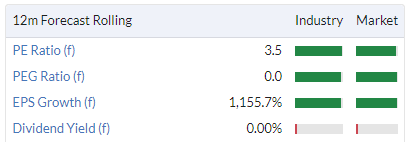
Mission’s valuation metrics are depressed, probably due to a combination of the debt load and the fact that its profits are very unclean with lots of adjustments needed to make them look good:
I am happy to maintain our existing stances on these shares:
BBSN: GREEN
TMG: RED
As for the deal, I would say it’s a reasonable offer because my view is that these companies should have a net cash balance (as they don’t have the quality or predictability of earnings to run on debt, in my view) and so I think the offer from BBSN is a reasonable solution to Mission’s predicament, that could ultimately benefit both companies. But at this stage, barring a shareholder rebellion, it seems likely that Mission will prefer to go it alone.
(Paul adds: Thanks Graham, a very interesting situation. I wonder what scale of cost savings could be achieved by combining the two small listed companies? A fair bit I would imagine, from clearing out duplicates from 2 sets of NEDs & advisers, and listing fees. Also after the merger of TPFG and BLV recently, I think there's a strong argument for forming a larger business with better liquidity in the shares. Institutions are apparently not interested in market caps below c.£250m, so getting a bit closer to that might help re-rate the shares of the combined entity onto a higher PER, which was a key rationale for the TPFG/BLV merger. Another key question is the relative skills of the top management? Absorbing a bigger business could be a challenge for BBSN management. Does anyone know much about their background, and whether they're likely to add value, or flounder under the difficulties of managing a much bigger group, and possible push-back against the deal? A risk is that key rainmakers at TMG might walk away and set up their own competing businesses, taking clients with them - a big risk at people businesses. I see that BBSN is 20% owned by Lord Ashcroft, which I think adds weight to the proposal in that it might be perceived as giving BBSN more clout. Usually when a minnow tries to bid for a larger company, it can look impertinent and foolish, but not if you have a billionaire backer. All interesting to ponder anyway! I'm not generally a fan of all-paper deals, as it can create indigestion with a lot of people holding shares that don't really want to. Although the TPFG/BLV deal has gone well - although that a merger of equals really, whereas BBSN is a good minnow swallowing a larger but troubled group.)
Zoo Digital (LON:ZOO)
Up 14% to 62.8p (£61m) - Trading and Debt Facilities Update - Graham - AMBER
ZOO Digital Group plc (AIM: ZOO), a leading provider of end-to-end cloud-based localisation and media services to the global entertainment industry, today provides an update on trading and its debt facilities.
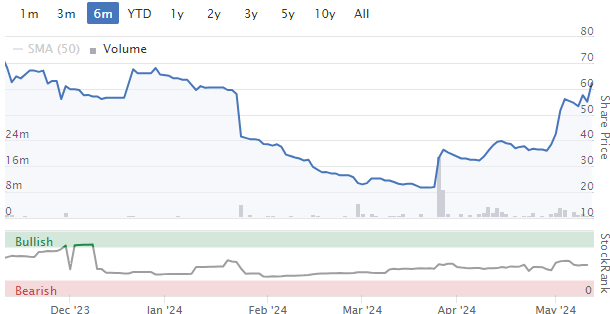
These shares have already almost trebled from their low in March. It was at nearly 200p last year, before a major collapse:
Here are the contents of today’s update:
Debt facility
The $3m facility with HSBC (currently undrawn) has been renewed for another 12 months, giving ZOO “enhanced financial flexibility for working capital purposes in an improving market environment”.
Net cash finished the financial year to March 2024 at $5.3m (vs. $3m expectations, according to Singers).
It’s a relief for shareholders who may have feared that the company was about to run out of liquidity: $5m of cash plus a $3m facility means $8m of headroom. However, that would surely be used up if the company had another terrible year; this brings us to the trading update.
Trading update
Firstly in relation to FY March 2024, ZOO says that they are “confident of at least meeting FY24 market expectations”.
Paul already commented on ZOO’s FY 2024 figures here with revenues expected to be down by more than 50% to around $40m and an adj. EBITDA loss of $13.5m.
As for FY March 2025, it has started well:
Customer demand has continued to recover with March 2024 invoicing the highest month since April 2023 following acceleration of the Company's pipeline. Work has continued to expand throughout March and April 2024 and visibility extends to September 2024. Revenues for FY25 Q1 are expected to be 36% up on FY24 Q4 which, together with recently implemented cost savings, is expected to result in EBITDA at break-even in Q1.
The broker’s EBITDA forecast for FY March 2025 is accordingly upgraded from $5.8m to $6.3m.
Graham’s view
This is excellent news and I think I can offer an improved stance of AMBER (vs. Paul’s AMBER/RED in March).
The company’s prospects of avoiding equity dilution appear to have greatly improved, following today’s news flow:
A better net cash balance than expected.
Extension of banking facilities for a year.
Upgrades to the adj. EBITDA forecast, implying that the company’s cash performance in the current financial year might be ok.
Ultimately I agree with Paul that this is probably not a very high-quality business from an investment perspective - how could a company build an enduring competitive advantage in dubbing/subtitling services? I also think it would be difficult for ZOO to have much bargaining power relative to its customers in the entertainment industry.
However, in normal conditions, it should be able to generate an acceptable level of profitability. FY March 2023 did see it generate an excellent financial performance, suggesting that its quality might be improving with its increasing scale, before it was hit by Hollywood strikes.
Now that it's in recovery mode, I do think it will get back to breakeven sooner or later, and it has a realistic chance of avoiding equity dilution. So I’m happy with a neutral stance.
(Paul adds: It's been a stunning % rebound from the lows in March 2024, for sure. Does that make it a good company though? The jury's still out on that, and I remain unconvinced, because even after the strong rebound (as expected from the ending of the Hollywood strikes), the March 2025 forecast is only now just below breakeven at adj PBT loss of £(0.1)m. Why pay £60m for a business that is only expected to improve to breakeven? That doesn't attract me at all. Clearly bulls must be betting that a much stronger recovery is in the offing (based on promising-sounding contract wins).
The big risk here was that it would run out of cash, after squandering the money raised for an acquisition on huge losses in FY 3/2024 (Why? Surely its costs should have been variable, hence scaled down when revenues dropped? This has not been adequately explained). Hence with insolvency risk apparently receding with enough cash headroom, I think it makes sense for Graham to move us up from amber/red to AMBER, as risk seems to have reduced - although I'd like to see what the full figures look like, to make sure the year-end cash figure hasn't just been window-dressed by locking up the chequebooks for a few weeks!).
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

77 comments
Dowlais (LON:DWL)
Inadvertently posted twice. See SCVR for 14 May.
thank you BnB for taking the time to write a reasoned and calm approach to a comment on Zoo Digital (LON:ZOO) . i'm delighted that the SCVR has given your post 120 thumbs up already as it so obviously reflects the views of the vast majority.
No-one is forced to read Paul and Grahams reviews.
Sending strength and calm to Paul and Graham - but hopefully the support of 120 outweighs irrational negativity from just one who appears to have a need to boast of just one success.
Twelve I think when I last looked!
145 now.
Tombholliday, I hope your comment doesn't upset/offend Paul or Graham. The majority of us on here really appreciate Paul and Graham's comments, and I for one, find them invaluable.
Hmm not sure invaluable is the right description here after the price of Zoo Digital has doubled, to repeat comments( without additional research) made when the business was trading at thirty pence is both arrogant and ignorant in the case of Zoo.
The market is making the investment case for Zoo Digital let’s leave it at that
Hmm not sure that you have properly read Paul and Graham's comments... even those of us who have no interest in Zoo observed that they have changed their stance to Amber and recognised that the risks have been reduced
Graham poses the question how could the company build a an enduring competitive advantage ? Assuming he is not being rhetorical then he does not know or understand Zoo studio software which the company has supplied to Disney, then he has not bothered to study the company in any depth may I ask a rhetorical question why does Disney channel a sizeable chunk of business through a South Yorkshire company unless that company gives Disney something that it cannot acquire closer to home?
Hope this helps
Assuming he is not being rhetorical then he does not know or understand Zoo studio software
You keep missing the point. It’s not Graham’s mission to understand Zoo’s software. It’s yours!
Grahams mission surely is to comment to the best of his ability on any company that he reviews when the market doubles the value of a business in six weeks and Graham merely repeats a colleagues negative commentary then he is coming up short surely
Where was that 'enduring competitive advantage' when Netflix stopped using Zoo and decided to do all dubbing/subtitling in house (i.e. very close to home).
Hope this helps.
Netflix do not use Zoo studio they have been a customer for other products and services
This is completely off topic but has anyone tried the 'copy a trader' function with eToro and would you recommend it or is it something to avoid?
It can work and I did it for a while with a reasonable return. However, with the help of Stockopedia I can now do it myself with often better results. Hope that helps
Dear Graham and Paul six weeks ago you wrote that you had commented on this business thirty six times and you were negative in tone, since then it has doubled. At the time it was suggested to you that a greater understanding around Zoo Studio and the relationship with Disney might clear up some of your fears around the quality of the business yet hear you are again making the same comments. - so I can only assume that the accounts remain unread the presentations ignored.
repetitive ignorant comment does not add value nor does enthusiastic endorsement - as emitted by you last February around the all time highs of Zoo. Your value on this seems to be that of a contra indicator
Your value on this seems to be that of a contra indicator
This is a pretty unpleasant comment. Paul and Graham are not tipsters. They are assessing companies based on their balance sheets and profit statements with particular emphasis on the risk of share dilution owing to cash difficulties. They came to a conclusion that, with the limited comprehension and depth of investigation that can be possible when you are reviewing over 600 companies a year, Zoo did not offer a good risk reward. The onus on this site is on subscribers to do their own research. If you have done so yourself, come to a different conclusion, and then made a good return on your analysis, well done to you. But it is quite inappropriate to come on here and inveigh against the analysts because they took a different view. They do a fantastic job. I commented last week that I've managed to prevail in my business and investing career at a high level without accountancy knowledge. That good fortune is in spite of my shortcomings and not because of it. And it does not in any way alter my admiration for their quickfire forensic dissections of a company's financial health.
Correct though when linked to the change in valuation of the company commented on
"repetitive ignorant comment"
Might be a good idea to edit rephrase in my view....
I agree with BnB. Graham's comments today on Zoo Digital (LON:ZOO) appear well balanced and fair to me. He has even upgraded from Amber/Red to Amber. The reality of this stock is that it has probably come out of the 'critical' ward and with a bit of luck doesn't need more funding. However it is still only running at about breakeven and has the long-term issue of too much customer concentration. The share price bounce might be encouraging but it doesn't add up to indefatigable proof that it is a quality stock.
If you listen to Paul's weekly podcast free on Spotify he addresses this issue as noone can predict the shorter term movements of a share price (in a different, still hiking rate environment, the share could equally have been marked down, even with a more encouraging outlook).And a lot of us aren't experts on each individual sector, nevermind individual businesses within them.Reviewing the accounts does help avoid some potential major red flags though and Paul and Graham's traffic light system refers to the latest accounts and no business or translation/ localisation market sector specific expertise in Zoo Digital (LON:ZOO) 's case.
On Beach group (LON:OTB) top mover today, up over 10%, can't see any news, any ideas?
On Beach group (LON:OTB)
Interims out tomorrow
On Beach group (LON:OTB) a bit leaky? Now up 15%.
Wow 17%, these interims had better be good. I hold.
a quick Stockopedia comparison of On Beach group (LON:OTB) and easyJet (LON:EZJ) (i hold) wins 26/40 so hopefully bodes well for easyJet (LON:EZJ) half year results this Thursday
Dont understand why anyone would use them they are so expensive compared to the likes of love holidays?
Their tv ads are hard to forget imo.Only ads i really remember apart from compare the market/meerkat and the opera singer.Could just be my bad memory though!
Well reading On Beach group (LON:OTB) reviews on Trustpilot, many say good value and easy to book on their website. Rating 4.2
Love Holidays same rating 4.2 but lots of bad reviews recently.
l never book these type of holidays.
Sold down a bit and wavered the wrong way for a while similarly to IG Design (LON:IGR) between TUs.Here's hoping it was just traders getting bored/worried recently and some buying back in/ or fomo'ing!!
If u see the trades - there was a big £300k sell - as soon as that went through - the entire book looked better.
Hi Paul,
Got some very reassuring feedback from an industry insider earlier on Cerillion (LON:CER) . The billing platform being best in class in competitive tender was the general overview. The licenses can be paid up front sometimes, for 5 years, annually or I guess outright. Some pay annually but its at a premium so good business for CER but also good if they are getting all that cash upfront I suppose. Most have implementation support and then pay for ongoing support, maintenance and other bolt on SaaS stuff, then there are future upgrades. I dont know the split but it sounds very sticky with ongoing revenue and future upsells. In terms of market size, I dont know the numbers, but its huge. So, all in all positive feedback.
Sigmaroc (LON:SRC) (I hold) buys cement-free concrete brand CemFree.
"Cement-free concrete brand CemFree has been acquired after materials specialist David Ball Group, which invented the product, went into administration earlier this year.
The product, which is an ultra-low carbon binder alternative to Ordinary Portland Cement (OPC), has been scooped up by SigmaRoc, an international heavy construction materials group.
CemFree’s new general manager Ian St.Hilaire says SigmaRoc sees a “promising future” for the brand, which will remain separate from the group’s Precase Product Group, retaining its own identity. It will encompass low-carbon cement-based technology GreenCem, also previously part of the D B Group."
Source: https://www.prolandscapermagaz...
CMC Markets (LON:CMCX)
apologies for straying off topic here , does anyone have thoughts on this companies prospects at present? I bought as a bit of a punt here as it wasnt really trading much above book value at the backend of last year. I see the price is up 150% in 6 months or so which is a nice problem to have. Looking at current pe stocky has it as being over 15 * earnings now and and price is now probably well over double the book value so it looks like the value has outed spectactularly well here - its a refreshing change for a share to make so much progress so quickly. Must admit i am tempted to sell up completely and move on - i think forward visibilty here is never the greatest at the best of times so must admit its not exactly one i want to tuck in my back pocket and forget about for 2 years. imho my own summary is that fair value is outed and on the basis i deffo wouldnt be buying at current price i think moving on may be the way to go
In H1 24 CMC Markets (LON:CMCX) was break even. In their last update H2 24 earning were c£50 - £60m.
If they can continue at H2 run rate then forecast PE for FY25 would be c6 - 7 and that doesn't include the £200m cash they hold or the stated efficiency gains from redundancies
CMC Markets (LON:CMCX)
cheers Kouremenous and Bouden54 - really helpful to know the splits ref profits and potential based on recent deliverance - that does evidence the decent potential here if they have hita purple patch - tricky one with such huge variability is numbers over time though. My decision is done here though i am happy with return here so its onto the next one - good luck to those that continue to hold here.
CMC Markets (LON:CMCX) based on some rough calculations I did a couple of months ago I think they can do 30p EPS if they continue to trade at their current rate - this would make them still good value in my view. Obviously earnings very volatile but they did manage 30p in 2020 (not to mention 60p in 2021, but that was clearly a one-off). They do seem to have momentum right now, with lots of good news recently, so I have sold about half of mine and keeping the rest.
CMC Markets (LON:CMCX) Intrinsic value based on my calculations is rounded to 400p, so the current price is still 68% of its value, imho. I hold
CMC Markets (LON:CMCX)
cheers QARPY - thanks for your comments. I wont argue with anyone that says this share is more - must admit due to fluctuations in fortunes its pretty hard for anyone really pin down a value. I am happy to take a bit less here than some may say its worth simply due to the unpredictability of earnings. Good news for holders is that shares i sell normally go up after i sell - so hopefully its onwwards and upwards for those who think it can regain former glories.
Real World Extortion
Still alive and well in the seafreight world .
Freight rates just doubled overnight for no obvious reason .
2k seafreight for a 20 foot last week
Wake up this morning it’s 4k despite us booking last week .
In my opinion probably the closest thing to racketeering around today .
Anyway just watch import costs not sure if these are new levels due to some spurious reason they trot out at every opportunity .
Nothing importers can do at all except smile that you’ve been shafted again and pay the bill , unless you are Jeff bozo in which case you go buy your own ships .
Real World Extortion - freight costs
Funny you should mention this because this morning I bought shares in Dsv A/S (CPH:DSV. High quality at a low valuation relative to history. Several recent upgrades to Buy.
I think they are just the freight agents in the middle so not the low life gangsters the world is saddled with and make no mistake hard to beat inflation when a must have supplier can just lift prices .
It’s the actual shipping lines that rule the seas .
Jack sparrow and Bluebeard in disguise centuries after the original pirates walked the plank .
New decently priced Cambridge based IPO).Must have a fair whack of institutional support.British technology firm Raspberry Pi is preparing for a £500m initial public offering (IPO) this month, it was reported on Sunday.
The Cambridge-based company is known for its affordable, credit-card-sized computers aimed at fostering coding skills among children.I still have my Raspberry Pi, although considerably older and you can potentially do a fair amount of cool stuff with them at any age (!) if you have the time and talent.Anyone else got one and used it to build anything cool?Will have to get it out of the bottom drawer sometime!
Financial data for 2022, disclosed in its latest filings with Companies
House, showed the company had 94 employees and an operating profit of $20m generated from $187m in revenue.
Where do readers find the best source(s) in advance of upcoming RNS's for UK companies in the coming week or two please, especially but not exclusively, smaller companies. Thanks for information/help
ShareCast.com is a good source for what you are looking for providing as well dividend payment dates and EX dividend dates.
All the best
I use Investegate. It did go down in quality but has improved recently. You get an email on Sunday with all the scheduled updates and AGMs, in the next week. Also get daily updates on stocks you select.
Enjoyed listening to Paul's latest podcast this morning. I thought the comments about a mind shift change at this stage in a market recovery/early stages of a bull market were thought provoking. Likely that a rising tide lifts all boats so there could be some good trading opportunities and even a chance to exit from those lagards with a little increased volume.
Enjoyed the podcast(s) as always this week Paul. In particular it was interesting to hear you discuss how some out of favour (typically Red/Amber) companies might be moving into focus, especially as short term trades.
I have read a number of people on twitter who have already achieved 10-20% portfolio gains YTD, and once the money comes in, confidence grows and so does appetite for risk. I am sitting on 13% gain, which considering I have had no takeovers and sold CMC Markets (LON:CMCX) waaaay too early, I am more than content with. My mindset is certainly now more open to a few higher risk trades, in the hope of getting in before others - which also means others are likely to be feeling the same.
We all know that the market is a voting machine rather than a weighing machine, however, less discussed and also important to consider is - what type of investor currently holds a stock and what are they most likely to do with it in the coming months? More specifically, are they going to sell? For example, the average private investor holding dividend stalwarts such as National Grid (LON:NG.) is likely quite different in mentality to those holding speculative biotech or junior miners.
Those who already hold debt hungry companies with recent poor performance have had a lot of opportunity to sell out. Are we therefore at a point where almost all the sellers are gone... probably. Paul mentioned Mobico (LON:MCG) and S4 Capital (LON:SFOR) as companies where he felt there could be good short term upside provided there are no catastrophes in the upcoming results.
I am really interested to hear the thoughts of the Stocko community on what they think might be the unexpected winners over the next 3-6 months?
My pick is 888 Holdings (LON:888). Of course the debt is simply ridiculous, but we all know that and I am not planning on holding for any duration. The upsides and reason for my selection:
- The 3 year chart shows that it has just broken the 200day after bouncing off it twice previously
- A nice long term bowl forming on a 3 year chart
- Lots of director buying in 2023 at or around the current sp, no sells
- After the recent update stocko has moved it back into the green zone, the stockrank is 78
- The April pay rises benefit their primary customers, typically working class younger males
- The Euros are taking place this year which will drive profits, especially if we get good weather, beers and gambling on the football means profit for 888 Holdings (LON:888)
- Olympic games also taking place this summer which offer lots of gambling markets.
- Euros and Olympics will offset the usual quiet period over the Summer months where there are no football markets.
Really interested to hear the thoughts of others on what would be their pick for shares with high potential upside in the coming months.
Hi BenHazz,
I think 888 Holdings (LON:888) could be a good shout for a trading share, but just wanted to point out it's not hit the 200ma yet. The below is from Stocko's chart, the 200ma being the grey line on top. It's above the 10ma and the 50ma, so going in the right direction.
Cheers
Chris
888 Holdings (LON:888) Thanks for pointing this out - I got thrown off because when you shift between the 3 year view and 1 month view on charts, it changes from 200day to 50day moving averages. I saw it was above the green line and assumed it was still showing 200day. Slightly reduces the upside story for now, lets hope it can push through it in the next few weeks!
Good post Ben. I already own some Rank (LON:RNK) as I think offers better R/R than 888 Holdings (LON:888) , though i can see the attraction having held in the past.
For recent buy, I’ve just taken a position in Coats (LON:COA) . Breakout >77p from multiple year consolidation, currently moving nicely towards the next breakout level at 92p. Historical pension issues look to be much improved, top ups turned off late 2023. Improving FCF to invest in growth, global leader in its markets, sporting summer events should give a boost to the apparel markets. As ever DYOR but one to watch imo.
CPICapita (LON:CPI) Hi Ben. Capita is languishing. If they can achieve the cost savings they've been promising recently then there might be a reasonable bounce. RGBPRBG Holdings (LON:RBGP) I agree with Paul that they look like they've kitchen-sinked absolutely everything over the last 6 months and could well show some signs of life over the next couple of updates now they've gone back to basics and concentrating on purely the legal work.
On Capita (LON:CPI)
From memory there is an investor presentation in June. I expect they hope to declare they are trading at cashflow breakeven. They may manage it.
This may give a bit of a pop to the sp in the short term.
In the long term capita is a collection of business units that provide services under contract. They have long stated that they want to leverage the fact they are possibly the uks largest employer of it staff and move to selling higher margin knowledge based services. That is a good ambition but will take many years as they are in the middle of many multi year contracts where there is little opportunity to increase profits. There is also no guarantee of success (stating the obvs).
Not exactly unexpected as Paul I know is a fan, but Jet2 (LON:JET2) is likely to benefit from the built up demand for holidays overseas and is due for a correction having dropped 13% in last month or so.
Also will the lack of delivery of new craft by Boeing help prices as per Michael O'Leary!
Good Morning Paul, as always I enjoyed listening to your weekend podcast. I hope that you will be able to let me know your view on my thoughts below.
I was very interested to hear your thoughts on being able to shift your mindset at the very start of a new Bull Market when that pivotal shift happens, that if we as investors can take on a bit more calculated risk in companies that are good established profitable companies but are carrying just a bit too much debt (best avoided in the depths of a bear market) we may be able to enjoy some spectacular rebound percentage gains, and you gave a few recent examples.
So with that in mind I got thinking and I came up with Saga (LON:SAGA) which I think may fit the criteria. It is a good company, and the debt maturities are quite long term and they do have a bit of wiggle room and other options to get out of jail like sale and lease back.
I think that Saga (LON:SAGA) could fit the criteria as a company that is a bit riskier and we should not be put off by the debt for a possible strong rebound trade. It is on a PE of just 3.5, so if the multiple doubles and we enjoy a 100% gain Saga (LON:SAGA) would still be in the single digit PE club, hopefully plenty of room for a rebound, what do you think Paul ?
Best regards Neville
Neville, Just wrote a lengthy post and only afterwards read your post... it seems like we are both on the same wavelength today!
13 May 2024
Saga (LON:SAGA)
2024 Bond repayment
Saga plc (Saga or the Group), the UK's specialist in products and services for people over 50, confirms that it has repaid in full the £150.0m 3.375% senior secured bond. This bond redemption was funded from Available Cash resources, including a draw down on the £85.0m facility with Roger De Haan maturing in April 2026.
Saga (LON:SAGA)
nevilleaustin
It is a good company, and the debt maturities are quite long term and they do have a bit of wiggle room and other options to get out of jail like sale and lease back.
huh they have specifically advised they wont have the money to settle the April and July 2026 debt that is due. Ok we are talking 23 months away but that really is in focus now imho rather than being in the "long term". Note going concern notes rules will mean that they cant really leave this till the last minute without probably spooking the market if they get to being close to 12 months out. the danger here is that they need to raise funds from shareholders at depressed shareprice - large duilution would reduce the upside potential. Ok you may be confident they have a rabbit in the hat - but imho the text below is very clear warning they need to find a rabbit from somewhere ! - note to be clear i dont have particualr concerns about solvency - just that if the rabbit doesnt do the job its likely it will be at the expense of shareholders.
Note this is twice in one month they have explicitly advised Roger wants his money back in less than 24 months and they have today confirmed that its his money that has has been used to settle the current bond repayment that has just been paid down.
per company just last month
The Directors have considered the resilience of the Group, taking account of its current position, the principal risks facing the business in severe but plausible scenarios and the effect of any mitigating actions. Under all scenarios modelled, the Directors have identified a need for additional mitigating action beyond the scope of normal trading to manage the solvency of the Group at key pressure points over the five-year period. These points include the maturity of the £85.0m loan facility with Roger De Haan in April 2026, and the maturity of the Group's £250.0m unsecured bond in July 2026. A range of options are currently being explored, including potential partnership arrangements, which would release capital and enable the Group to restructure its debt; new liquidity facilities; and an evaluation of corporate refinancing.
Hi rmillaree, Thank you for taking the trouble to express your view and concerns regarding Saga (LON:SAGA) as a candidate for a rebound trade.
What you have drawn attention to does cause me more concern than I had originally considered, especially the danger that they may need to raise funds from shareholders at a depressed shareprice, but on the other hand I think that diluting shareholders should not be on Rogers mind as he happens to own 26% of the Company and would not be in his best interest.
I think they do have a rabbit in the hat which is the sale and lease back option, and I think that they are softening up shareholders to this possibility with their recent communications. And if the sale and lease back went ahead that may even get the share price moving ?
Saga (LON:SAGA)
And if the sale and lease back went ahead that may even get the share price moving ?
Certainly if they realise excess cash that could cover 2026 bond requirements (and Roger) whilst being left with a capital light cruise business that is still decently profitable then yes.
but on the other hand I think that diluting shareholders should not be on Rogers mind as he happens to own 26% of the Company and would not be in his best interest.
that would normally go without saying , obviously as of last month they have had to face te facts of where they are though so imho the moving to capital light model is not being done from position of strength.
Note if shareprice was to half again from here - then for less than 25% of the loan proceeds he would be receiving back he could participate in a rights issue if that raised say £85 mill simply to pay him down (say double the current shares in isue to do that). So he could be happy picking up some more shares on the cheap anhd ending up with business that has £85 mill less debt with other shareholders picking up the balance of the tab. To be fair to him he has given the company time heer so presumably we should expect his patience may wear thin eventually. The danger here is that to me the company and Roger are clearly not in control of the shareprice as things stand and we shareholders are completely in the dark as to whether there isa rabbit in the hat or not and if there is whether its of any use - all i do know is that the real big money that is probably dictating things ref shareprice will certainly be better informed than us !
In the meantime they kinda need to show the insurance side is bouncing back somewhat too !
I have added a few Sanderson Design (LON:SDG) and Michelmersh Brick Holdings (LON:MBH) this morning. On the basis that both:
Have lagged the recent upturn in small caps and remain cheap on several metrics.
Have cash on the balance sheet
Will benefit from a fall in interest rates, and the resulting uptick in house building
Are in my opinion good companies with good management
Also Sanderson Design (LON:SDG) trades below book value with Michelmersh Brick Holdings (LON:MBH) trading close to par and both are still to go ex-dividend.
The funds were provided by the sale of Ultimate Products (LON:ULTP) at a minimal loss. I still like the company and management, but feel that the above provide better opportunities in the medium term.
As always just my views.
All the best
Jonno
I’m with you on SDG but surely you can pick up on the lows it’s just bouncing between 1.00 and 1.08
I bought more at 1.01 last week , almost up to a full position and just adding on the days mr market is depressed
Only other think I’m buying is titon every time I can get 80p but that’s not a bounce trade
Other than that can’t see any reason to sell anything and switch , jumping in and out never works that well .
I’m watching the Georgia situation , bank of Georgia results out this week , if bank of Georgia jumps reckon Georgia capital will take a few days to catch up .
possibly playing with fire on Georgia but for example if Putin invaded all bets are off with the stock market rise anyway
Sanderson Design (LON:SDG)
Hi planetX
You will probably be proved right in that I will be able to pick up the shares at. closer to 100p. Paid 106p today for a modest addition to my holding.
However I don’t think that a few pence here or there will matter much in the grand scale of things, once rates start to fall and small cap/AIM redemptions finally end.
I like to buy as cheap as I am able, but am also cognisant of Peter Lynch’s saying that if one likes a stock, one shouldn’t attempt to ‘nickel and dime’ it.
I think that Sanderson Design (LON:SDG) is a prime bid candidate and that an offer of at least 200p would be required, which is around twice my blended purchase price.
All the best.
Jonno
Agreed , only thing with SDG is it doesn’t half jump around almost on a weekly basis .
I’ve been topping up for 6 weeks now and it’s up and down like Billy o
If I do a decent chunk the price spikes
Seems to be a consistent seller
I keep looking at Sanderson Design (LON:SDG) , but I just can’t see where the growth is going to come from. It looks to be well managed, and its operations trot along nicely, but it’s market is niche with, I suspect, little room for expansion as it has no moat to speak of and doesn’t generate the cash or margins to become a serial acquirer on a grand scale.
The share price girations seem to be more a product of investor whim that systemic groth prospects. For a business of that type a or of 10 or 11 feels about right.
I’m playing devil’s advocate to a degree so if anyone has a any substantive points, I might have missed, feel free to shout.
As it happens I have just finished reading Pigs Get Slaughtered. It’s very good and certainly very relatable for the private investor community. You might even recognise the odd character or two - Phil Carmen for example.
Oh heck well spotted....I must ask him about that when I interview him tonight. It will be good to have comments from those who have read it and all those who attend tonight can download the book for just 99p
Here is the post and links if any have missed it Stockopedia | Mello this Monday with a popular fund manager & a financial crime thriller | By carmensfella
M&A bids continue to roll in.
According to the FT, the value of bids for UK stocks has hit the highest (re $78bn YTD'24 Dealogic) since 2018 - with the majority coming from overseas buyers. Recent targets include miner Anglo American and IDS, the owner of Royal Mail.
Another indicator perhaps to "Buy in May, as BULL market is here to stay"?
Finally ...
"Shein suppliers still work 75-hour weeks - report
Workers for some suppliers of Chinese fast fashion giant Shein are still working 75 hours a week, despite the company promising to improve conditions, a report suggests.
A new investigation by Swiss advocacy group Public Eye has followed up on its 2021 report, external, which found a number of staff across six sites in Guangzhou were doing excessive overtime.
According to the group, who interviewed 13 employees from six factories in China supplying Shein for its latest investigation, excessive overtime was still common for many workers."
Source BBC Sunday 12 May 2024: https://www.bbc.co.uk/news/art...
And yet, nothing will happen on any Shein alleged violations because the UK is desperate to get a big name IPO this year...
More pain for Boohoo (LON:BOO) and ASOS (LON:ASC) to come...
Wonder if TMG's management would be unanimously rejecting BBSN's offer if they were to run the enlarged entity instead? My guess is no!
Cerillion #CER H124 results in line for the full year (with scope for upside I suspect especially on margin.)
New contract worth $11m
New bus pipeline +20%; back order book +10%
Management webinar & Q&A next Monday 20th May, 2.30pm. Register here.
Top quality granted not cheap.
Cerillion (LON:CER)
My morning smallcap tweet: The picture of wealth
Trufin (LON:TRU) Mission (LON:TMG) Brave Bison (LON:BBSN) Netscientific (LON:NSCI) Jaywing (LON:JWNG) Active Energy (LON:AEG) Zoo Digital (LON:ZOO) Acuity RM (LON:ACRM) Mediazest (LON:MDZ), Hercules Site Services (LON:HERC), Team Internet (LON:TIG)
◄TruFin (TRU)► guides FY-Dec significantly ahead of market expectations with EBITDA positive. [SP=73 Cap=78m]
◄Mission Group (TMG)► rejects all share offer from Brave Bison: 11.5 shares or about 29p, a 28% premium. [SP=22.7 Cap=21m]
◄Brave Bison (BBSN)► positive spin on its rejected offer for Mission: "Brave Bison is currently engaging in conversations with Mission's Board and major institutional shareholders to solicit support for the Possible Offer". [SP=2.5 Cap=32m]
◄NetScientific (NSCI)► wins investment management mandate with Martlet Capital and has acquired the operational venture capital business of Martlet, excluding the Martlet Portfolio. Adds c.£23.3m of funds under management. [SP=63.5 Cap=15m]
◄Jaywing (JWNG)► guides FY-Mar rev flat in const currency and down slightly in real terms. UK Consulting division had weak Q4 which has continued. Talks with lenders on increasing the existing facilities. Ends sale process. CEO scarpers. [SP=3.1 Cap=3m]
◄Active Energy (AEG)► has received a number of proposals re trategic opportunities and the potential sale of the Company's CoalSwitch assets. If it's not sold co will have to consider a members voluntary liquidation. Holders might get zip. [SP=0.35 Cap=1m]
◄ZOO Digital (ZOO)► confident of at least meeting FY-Mar market expectations of rev $39.7m and EBITDA adjusted for share based payments -$14m. $3m debt facility renewed for a year. [SP=55 Cap=54m]
◄Acuity RM (ACRM)► wins 3 year contract worth more than £500k all of which is payable this FY. [SP=3.99 Cap=5m]
◄MediaZest (MDZ)► guides H1-Mar rev up and improved EBITDA. Strong trading momentum continued into H2. [SP=0.07 Cap=1m]
In line: HERC, TIG
Hercules Site Services (LON:HERC) - Further good growth in H1, in line with expectations (note here: https://www.equitydevelopment....)
Hercules’ H1 trading update confirms another period of strong growth, in line with expectations. Revenue in H1’24 is expected to be over £47m, an increase of c.27% over H1’23. This represents c.50% of our FY’24 forecast (£94.7m), suggesting the Group is well on track at the half year stage.
All income streams grew, underpinned by substantial demand from the infrastructure sector, as well as the Group’s own growth initiatives. Contract momentum remains positive, and we note an encouraging trend in recent industry data.
Recent contract successes included over £5m in civil projects and the significant new framework agreement with Costain. UK Construction industry data (PMI) was also positive in April for the second month running, suggesting a more supportive environment overall.
We look forward to further details in the interims on 3rd June and retain our Fair Value / share estimate of 55p.
Gulf Keystone Petroleum (LON:GKP) buyback and cancellation programme started. All the rage but should give the shares an upward nudge.