Small Cap Value Report (Mon 13 Nov 2023) - FDM, BLND, XPP

Good morning from Paul & Graham!
Mello Monday is tonight from 17:00 - a couple of interesting companies that we follow here are presenting, namely Solid State (LON:SOLI) and Sosandar (LON:SOS) (I hold).
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Agenda for today - at the moment Graham and I are scratching around, trying to find anything interesting to write about, so we can avoid having to spend any time on Team Internet! ;-)
Summaries
FDM (Holdings) (LON:FDM) - down 12% at 411p (at 08:08) £451m - Trading Update (2024 profit warning) - Paul - BLACK / AMBER
Profit warning, slightly below for 2023, but warns for 2024. Big (18%) drop in consultants currently hired out. Strong balance sheet confirmed by me, and generous dividend yield, since all earnings are paid out to shareholders. Could be an interesting one for a cyclical recovery at some point (maybe not yet though?). Nice quality business. (Edited below to include new forecasts from Shore).
British Land (LON:BLND) - up 6% to 333.4p (£3.1 billion) - Half-year report (strong rental growth) - Graham - GREEN
Rental growth is expected at the top end of previous guidance as BLND continues to sign up tenants at very strong prices across its portfolio of campuses, retail parks and urban logistics. At a hefty discount to official NAV and a divi yield of 7%, I like the look of BLND.
XP Power (LON:XPP) - 1,217p (£293m) - Fundraising - Paul - AMBER/RED
I'm pleasantly surprised by the generosity of shareholders, injecting fresh equity at an impressive premium from the recent lows. That triggers the bank slightly relaxing covenants, although debt remains uncomfortably high. An excellent rebound from the recent lows, but there are still questions hanging over this company - mainly, what caused profits to plunge? Is that just a one-off, or sign of a deeper malaise? I don't know, so am keeping clear for now.
Paul’s Section:
FDM (Holdings) (LON:FDM)
Down 12% at 411p (at 08:08) £451m - Trading Update (2024 profit warning) - Paul - BLACK for spreadsheet / AMBER on fundamentals
FDM Group, a global professional services provider with a focus on Information Technology, today provides the following trading update.
Tricky one this. Is it a profit warning? I’d say yes - a slight miss (“broadly in line”) for FY 12/2023, but performance for FY 12/2024 will be “impacted” by “lower than previously anticipated” number of consultants assigned to clients.
The numbers have fallen a lot - this is down 18% for Oct 23 vs Oct 22 -
Consultants assigned to clients at the end of October 2023 were 4,136 (end of October 2022: 5,014), (30 June 2023: 4,602).
Reasons given - client caution (which we’re hearing from quite a few B2B companies at present) -
Since the publication of our Interim Results announcement on 26 July 2023, macro-economic and geo-political uncertainty has continued to cause clients to delay and defer decisions around project commencements and Consultant placements.
Nonetheless, levels of client engagement continue to give us encouragement and there are some signs that confidence is slowly beginning to return, albeit varying by geography.
Balance sheet - it says this today -
The Group has a robust balance sheet, with £35.3 million cash at 31 October 2023 (31 October 2022: £34.4 million), (30 June 2023: £38.1 million), and no debt. An interim dividend of £0.17 per share, amounting to £18.5 million, was paid on 13 October 2023.
I always have to check balance sheets myself, as you simply cannot rely on what companies say about their own balance sheets. Often it can be a contrary sign when management claim to have a strong balance sheet!
The good news here is that FDM does have a healthy balance sheet, with minimal fixed assets, and plenty of working capital, with £38m net cash at June 2023.
Paul’s opinion - this looks a very nice business. It makes a good strong profit margin, from training and hiring out IT consultants. It's a glorified specialist staffing company really.
It has a clean, capital-light balance sheet with ample cash and working capital.
The cashflow statements are also very impressive - lots of cash generated, which is pretty much all paid out in divis, because there’s negligible capex required.
Stockopedia shows a forecast divi yield of 7.9% based on a share price of 467p (Friday’s close). I imagine the share price is likely to take a tumble today, as lower earnings are now expected for 2024. This means probably a lower divi, as all earnings are paid out in divis.
There has been a sharp fall in activity recently, which is going to hurt profits in 2023 a little, and more in 2024.
I haven’t yet seen any broker notes available, but Shore Capital normally covers it. EDIT: see below for updated Shore figures.
It’s maybe too early to start thinking about bottom-fishing here for a bargain.
Note that FDM shares have already crashed a lot, and once sellers have done their worst today, it’s probably going to be not much above the 2014 main listing float.
Although note that it was previously listed on AIM, but management nicked it off us (I was a shareholder at the time), taking it private with Inflexion Private Equity for a song (£33m) in 2010, then re-floating it 4 years later for £200m! So they very much look after themselves first and foremost, although that’s probably true of management at pretty much all listed companies.
At some stage though, I would say FDM shares would be a nice recovery share, as it’s a fundamentally decent business.
So for now, and with incomplete information, I’ll go with AMBER.
EDIT: an update note has just come through from Shore Capital, via Research Tree, many thanks to both. Revised forecasts are now -
FY 12/2023: adj EPS revised down 6% to 33.2p
FY 12/2024: adj EPS revised down 25% to 26.6p
That’s quite a sizeable reduction in forecast earnings. What multiple should we value the company on? I would say 12x 2024 forecast should be a fairly safe base case valuation, so that’s 319p. The current share price is 397p (at 10:05), a PER of 14.9x the reduced 2024 forecast. Not exactly a bargain, but that depends on whether you see 2024 as a one-off bad year, and recovery to come in 2025 (or 2024 itself might surprise on the upside).
Since the macro outlook is very uncertain at present, I remain of the view that it feels too early to jump in here, hoping for a recovery. So I’ll stick with AMBER, as above.
XP Power (LON:XPP)
1,217p (£293m) - Fundraising - Paul - AMBER/RED
This is an international group, making electrical power converters - examples of its products are here.
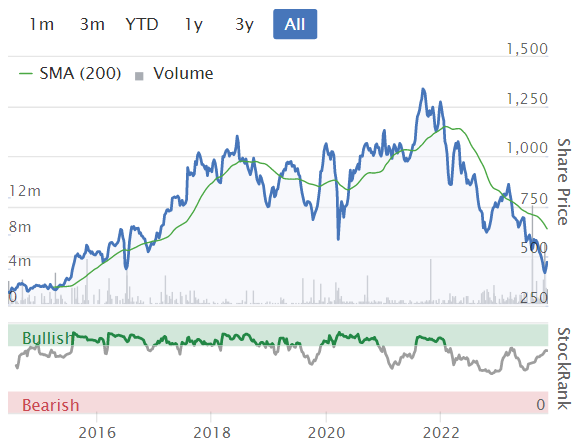
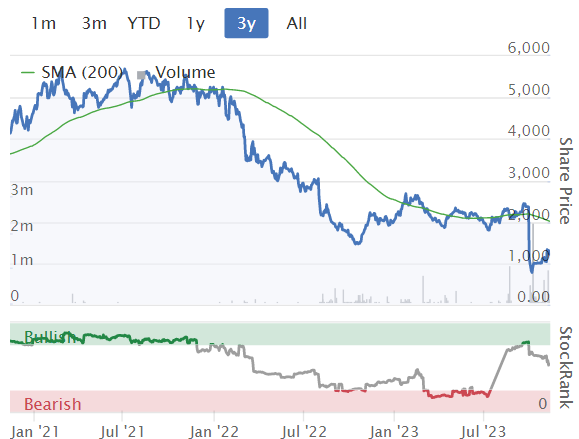
After a long bull run, which saw it roughly 40-bag from 2008 to 2021, the wheels have really come off in the last 2 years -
Our coverage here quickly summarises recent events -
2/8/2023 - AMBER 1950p - Roland worried about high debt. But saw it as possible value, and a turnaround.
2/10/2023 - RED - Profit warning crashes shares 46% to 1286p. Possible covenant breach.
6/10/2023 - RED - Lurches down another 10% to 730p on divi canx. Looks high risk.
27/10/2023 - RED - 1094p - Q3 trading stabilising. Hints at a placing.
We had no choice but to stick with RED, until it managed to refinance. Remember our traffic lights are not intended to predict the future! We’re just flagging risk, and you can make up your own mind if the reward outweighs the risks or not.
Investors who held their nerve have been nicely rewarded, with a c.57% rebound from the 776p recent low to today’s 1,217p - good to see!
Refinancing - this is the news I want to look at today. A placing of £44m and small retail offer up to £1.5m was announced on 6/11/2023. This is a 20% enlargement of the share count. Price was noteworthy, at 1150p per share, a premium of 6% on a share price that had already bounced strongly from the lows.
Note that net debt was £163m on 2 Oct 2023, so this placing is only dealing with about a quarter of the debt.
Debt will remain high -
The Funding Plan is expected to leave the Group's leverage broadly at the top end of the Company's previously stated target range by year end 2024.
Borrowing facilities amended, to slightly relax the covenants, dependent on completion of the fundraise.
Opportunistic bid approaches rejected -
Since the trading update of 2 October 2023, a small number of parties have expressed indicative, non binding interest in acquiring the Company at prices which the Board considers fundamentally undervalue the Company and its long-term prospects. Having considered each of these unsolicited expressions of interest, with its advisers, the Board does not believe that any of them are at a value which merits further engagement with any of those parties and has had no hesitation in unequivocally rejecting them.
Outlook -
While, as previously announced, 2023 will not deliver the financial progress the Company had forecast earlier in the year, it is expected to result in a trading performance similar to the prior year in what have become increasingly challenging end market conditions.
While it is too early to provide specific guidance for 2024, the Board expects to enter the new financial year with a sizeable order book, largely for delivery in the year. The Group will also benefit from the recent significant action taken on costs and cash.
Longer term, the Group has a strong pipeline of potential design wins, and existing product, combined with end markets that have excellent through the cycle growth drivers. The Board therefore expects, on average, to grow ahead of its markets while returning margins and cash to historic levels.
Revised forecasts - nothing detailed is available I’m afraid. But we have got broker consensus numbers, showing c.115p EPS for both FY 12/2023 and FY 12/2024 - very much lower than previous forecasts -
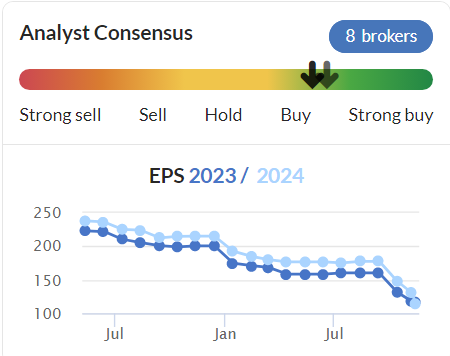
Valuation - on the latest forecasts, and at 1217p/share, the PER is about 10.6x.
That doesn’t strike me as a particular bargain, given that XPP will still have a heavy debt burden.
Paul’s opinion - what an interesting situation, where it seems likely that existing shareholders strongly supported the company with fresh cash for new equity, to protect the value of their existing holdings. Management must have delivered some impressive investor presentations to get this degree of support, with a placing at a 6% premium on an already strongly rebounded price. That’s a surprising outcome for sure in a bear market.
Well done to anyone who caught the bounce, but I don’t see anything attractive in the current price. It’s still not clear why earnings plummeted from previous expectations.
I see this fundraise as a case of avoiding disaster, rather than a comprehensive solution to XPP’s problems.
Further upside could come from a recovery to historic margins, which management talks about. I wouldn’t want to bet on that happening, when I’ve not had it properly explained why margins crashed in the first place.
So it’s not for me.
Although to reflect the reduced risk from the placing, I’ll move from RED to AMBER/RED.
Graham’s Section:
British Land (LON:BLND)
Share price: 333.4p (+6%)
Market cap: £3.1 billion
This is one of the largest UK REITs. For an overview of the sector, I recommend Roland’s article from July.
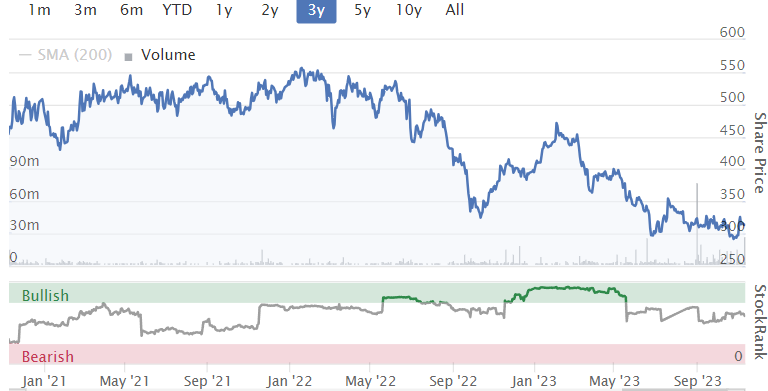
As interest rates rose from 2022 until now, the BLND share price has responded as you might expect, down by nearly 50% from peak to trough:
Let’s take a look at today’s interim results.
Headlines:
Underlying profit growth 3.4% to £142m
Underlying EPS growth 3.4%, to 15.2p
Dividend per share growth 4.8%, to 12.16p
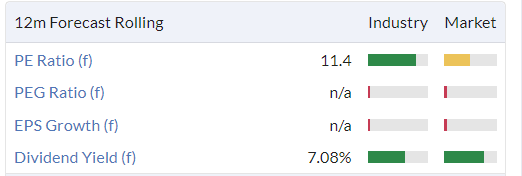
The StockReport suggests an EPS forecast for the current year (FY March 2024) of 27.4p, putting this on a PER of about 11x, or perhaps more like 12x after this morning’s share price increase.
Balance sheet highlights are quite interesting:
Net tangible assets per share (calculated using EPRA methods) are 565p, nearly 70% above the current share price. Among other things, this calculation excludes the taxes that would be payable if properties were sold.
Loan to value 36.9%; looking at this figure in isolation it suggests to me that leverage is modest.
Net debt to EBITDA 6x; this would be high for a normal operating business but real estate companies can be treated differently.
Other key points around the balance sheet: the company has an investment-grade “A” credit rating from Fitch, enormous liquidity of £1.7 billion in undrawn facilities and cash, and another £350m of new loans since H1 ended.
Occupancy is excellent at 96%. New deals with tenants have been signed at an average 12% premium to the estimated rental value used in portfolio valuations.
Valuation is down 2.5%, with the main driver being a 4% fall in the estimated value of campuses. Of course the stock market is going to be more pessimistic than this (e.g. BLND share price down 20% year-to-date). It’s noteworthy that rents are going up even as valuations are going down.
Outlook is positive with estimated rental value growth at the top end of previously guided ranges for FY March 2024. So that means rental growth of about 4%-5% in each category.
Additionally, BLND are “comfortable with current market expectations”.
Graham’s view
We don’t cover REITs very often in this report, and we have never covered BLND. However, on a quiet news day, there is no harm in taking a quick look.
Should small-cap investors take an interest in these? Well, given that valuations are so beaten up at the bottom end of the market, I would be more interested in the higher-risk, higher-reward situations available down there.
That said, anyone who is looking to de-risk while still enjoying a decent return might find that large REITs are a reasonable proposition. Of course it’s still necessary to diversify and to research the individual REITs that you are investing in.
My own view on BLND is that it’s offering investors a pretty good deal right now. The disparity between the company’s balance sheet value (around £5.4 billion) and market cap (£3.1 billion) could probably be explained by a combination of economic concerns - exposure to retail - and a demand for higher rates of return than the BLND property valuation implies.
Investors might also be concerned about the office portfolio, although BLND insists that demand and occupancy remain high. The typical tenant of its prime London office portfolio is the UK headquarters of a large corporate.
At its current official valuation, the yield on BLND’s portfolio is just over 6% (the “Net Equivalent Yield”).
But with inflation still at 6.7%, and with low-risk fixed rates of 6% available, perhaps it makes sense that investors aren’t willing to mark the BLND portfolio at its official fair value.
Instead, the BLND share price is discounted low enough that the dividend yield on the shares gets up to 7%. The underlying earnings yield on the shares is another step higher again.
While I think there are many bargains in the market right now, I do think that BLND is probably one of them. If I was looking to park some money in a lower-risk way than the small-cap end of the market, I’d certainly consider this.
So I’ll give this one the thumbs up.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

96 comments
I have added to my holding in Pressure Technologies (LON:PRES) prompted by price weakness, the recent news on refinancing by major shareholders, Harwood Capital and Peter Gyllenhammer and today's update from BAE Systems (LON:BA.) that included the £3.9billion funding for the next phase of SSN-AUKUS submarine programme. Pressure Technologies (LON:PRES) through its CSC division should be a significant beneficiary of the latter.
The refinancing (£1.5m loan) comes at a cost, but Chris Mills and Peter Gyllenhammer aren't going to shoot what they consider to be the potential golden goose. Both supported the open offer in December 2022 to raise £2m after expenses in subscribing for shares at 30p. See extract from relevant RNS below
'Schroders Investment Management ("Schroders"), Harwood Capital ("Harwood") and Peter Gyllenhammar AB ("Gyllenhammar"), each a substantial shareholder of the Company (as defined in the AIM Rules), have conditionally subscribed for 2,333,333, 3,333,333 and 1,000,000 Placing Shares at the Issue Price, respectively.'
Richard Staveley, manager of Rockwood Strategic (LON:RKW) sits on the board of Pressure Technologies (LON:PRES). Given the recent share price weakness Pressure Technologies (LON:PRES) is around 6% of Rockwood's NAV. It trades at a significant discount to NAV of around 33p and from memory owns a large site close to the M1 in South Yorkshire. Mr Staveley likens the opportunity in Pressure Technologies (LON:PRES) to that of Crestchic, which was eventually sold at a substantial premium to Harwood's cost of investment.
Pressure Technologies (LON:PRES) has put its PMC (Precision Machined Components) division, which is trading well, up or sale. PMC makes specialist precision castings for use in the oil and gas industries. it intends to use some of the proceeds once sold to pay back the £1.5m loan to Harwood and Gyllenhammer. This parallels the disposal of Tasmin Tools by Crestchic.
The share price should respond positively to the sale of PMC and/or the anticipated fall in inflation and consequently interest rates.
Hopefully the investment thesis plays out over the next few years.
Hi Jonno
I know Pressure Technologies (LON:PRES) reasonably well…& held the shares many moons ago..I’ve also visited them & seen what they do first hand…I’d be cautious about ascribing too much value to PMC…they don’t produce castings..they machine them with great skill & some v impressive kit but that’s an important difference to consider in terms of the value add imho
Best of luck with your investment…I like the company & wish it well
Cheers Rhomboid,
Thank you for the feedback. I shall revisit the company website and make sure that I get my ducks in a row. It will be interesting to see how it pans out.
I need to listen to Paul's Podcast - massive respect for his honesty. I only use my SB accounts to short (with guaranteed stops) to hedge against stocks I own ,and also act instantly on a multitude of mis -priced assets .......BUT my discipline and education came after many losing trades involving £thousands and thinking that I could predict the short term movement of indices, Fortunately my losses were nowhere near as large as Pauls .
For what it’s worth….UBS have come out and said they think the Fed will cut rates by 275bps in 2024
That’s a big outlier to what the market in general is pricing so interesting to see. If more houses come out with anything similar then market expectations on rates will change down and stocks will rerate upwards. One to watch even if not particularly relevant yet.
If more houses come out with anything similar then market expectations on rates will change down and stocks will rerate upwards.
But if this happens too soon, financial conditions will loosen prematurely and the Fed will respond by raising rates!!
I think what UBS are arguing (rightly or wrongly) is that inflation is under control, the economy in the U.S. is under enough pressure to warrant some pretty significant rate cuts next year to keep the economy moving forward and they think 2.75% worth, which is huge.
I’m not saying I agree with that analysis but it is interesting as UBS are the first big inv bank to come out as such a big outlier vs market expectations.
If they’re going to do this, they can’t wait too long in to 2024 as there is an embargo on changing rates in the run up to an election due to it being viewed as politically influencing the outcome
Jarvis Securities (LON:JIM) . Shares have dropped 21% on a market update after midday 1. No dividend for Q4 declared and 2. FCA further review required. Graham gave this the thumbs up in August so would appreciate a comment if possible. Thank you , and keep up the great work!
Ouch! and more ouch! Glad I sold out at £1. The part of the RNS that really bites you in the backside is the cancellation of the dividend!
Ouch, I sold Jarvis Securities (LON:JIM) at £3 and it was only 2 years ago.
If I look at my ex-holdings, some of them had huge drops - lesson: don't be shy to sell!
It would be interesting to get a comment as i didn't get the wording of the review at all and what it's basically all about.It didn't do a great job of explaining it to the lay person in my opnion.
Dear Graham
In respect of British Land, the company converted to REIT status in January 2007, paying around £300 million to HMRC to achieve the conversion. If I am right, therefore, I believe this means that the company does not pay capital gains on subsequent property disposals so the NAV figure quoted is accurate. I am sure there are other subscribers who will understand this much better than I do and correct me if I am wrong.
Kind regards
Phillip
You are right. A well-managed REIT will not pay CGT on property sales. ChatGPT says this, and I checked it here :- In the UK, REITs are generally exempt from corporation tax on the profits and gains from their property rental business, provided that they meet certain conditions. These conditions include distributing at least 90% of their property rental income as dividends to shareholders and meeting other regulatory requirements.
In the world of smallcap REITs I am currently studying Regional REIT (LON:RGL) because all the evidence I have collected suggests that the portfolio is worth more than the valuation and it is trading at a discount of over 60%.
Personally think there are much better options in the REIT space - Regional REIT (LON:RGL) I'm not surprised discount is high as they carry a lot of debt (50% LTV is far too high) and given its focus on regional offices suspect they could face major headwinds over the coming years (occupancy is only 81% which isn't great) . The most obvious bargain for me is Tritax EuroBox (LON:EBOX) - this is on a c45% discount but holds quality assets where there is a structural demand.
In same sector and equally unloved is the smaller abrdn European Logistics Income (LON:ASLI) (I hold). Share price down 50% since 2017 IPO, Discount to NAV close to 50%, Dividend close to 9% (albeit not fully covered), Gearing at 35% (at all in cost of 2%). Recent interims didn't scream disaster with respect to the well diversified logistics assets which appear to be on decent length leases with inflation linkages but the market just doesn't want to know. Can only hope that if/when interest rates are cut (and gilt yields fall) property REITs in sectors with structural demand return to favour.
Just on spread betting- I believe its doesn't attract CGT, which looks like an upside. But if punters are more often than not losing money on spread betting, surely you also cannot also offset your losses against any realised financial capital gains if you have activities in other non spread betting trading accounts-if you have any? So it looks like a double loss from my naïve investors perspective.
I have never used spread betting, so may have got that all wrong.
I heard wrt CFDs (not sure how that differs from spreadbets) that the Inland Revenue doesn't attract CGT for precisely the reason you mentioned: most lose money.
Mark, I think that's wrong (unless the rules have changed recently).
Spread bets are exempt from capital gains tax, but CFDs do attract CGT in the same way as owning physical shares. CFDs were invented to avoid Stamp Duty, and to enable leverage to be used.
I would agree with Paul "normally" per current hmrc guidance spread bets highly likely to to be "tax free gambling" and cfd's subject to cgt (might be different if companies holds em?)
Logic and worked example ref cfd's detailed below
https://www.gov.uk/hmrc-intern...
https://www.gov.uk/hmrc-intern...
https://www.gov.uk/hmrc-intern...
Note tax rules often have quirky situation where the general rules that normally apply may not apply - so i would only ever speak generally here , it is possible if there is evidence of an organised trade type activity going on ref spead bets for example that this could be a trade and subject to income tax/ni - even the hmrc manual here point away from that being the case mostly whilst covering their backs and saying "it could be" in BIM 22020.
https://www.gov.uk/hmrc-intern...
So do most shares accounts.
Our the years I think I have almost started a tradition of disagreeing with Paul on Team Internet (LON:TIG) (formerly Centralnic) and so far the share price clearly shows the result, Paul 1: Aislabie 0
And yet.....the results today for 9mths support my general thesis that this oiss a cash generation machine that is no danger of having to rely on its balance sheet asset values, where, as Paul correctly notes, the Negative Tangible Net Worth remains substantial. Relying on cash flow always assumes that there actually is real cash flow and not some sleight of hand and for TIG I am now a believer that their cash generation is real. The allocation of that cash is also where comments diverge. The company clearly has (because of its acquisition style) a need to pay to former owners for deferred acquisition cost. After that, it has this year decided to buy back stock and start paying a small dividend, the alternative, of paying down debt as fast as possible might be more market friendly (even if the market is not necessarily right).
I do not feel the same level of concern as Paul that TIG is a scammy internet advertiser, maybe my expectations for internet advertising are not that high to start with (though I have got a concern re gambling). For those looking for management comment and a chance for questions there is an online discussion at Investor Meet Company at 13.00
I agree 100% with Paul on this one and it clear that there is something wrong as the price is not going anywhere.
Management loaded the company with enormous debt buying back their shares.
While I concede that TIG has substantial debt ($168mm), it also has $83mm of cash and the debt load originally was not taken to buy back shares but to purchase the companies which brought it to its current size. The buy backs stared in this period and cost $30mm in a company that generated $54mm of operational cash flow. $17.9mm was spent on deferred consideration for the aforementioned purchases (not being a recurring cost), and of course higher interest took $9mm in the period. They borrowed an additional $15mm bringing debt up to a level they have previously held. So is it imprudent for a company to run debt at a net $80mm level when it generates $54mm in 9months?
If these operational cash generation numbers are correct I think it is taking a risk well within its capability, but I understand the concerns of those who just want to see debt reduced even though its tax cost is low.
Same tactics with Tremor one that I have tried on many occasions to warn readers in the past. The two companies were as well rather related some years ago.
Similar management behaviour in TIG and I expect them in the near future to raise more money for supposedly another acquisition.
Good luck to all holders.
Paul Can you put the link back for weekly podcast I cant see it, perhaps my fault but others seem to find it ?
If you search and find your old quality small cap page and click on "new home" you are taken to Happy Family Store and I'm not after Viagra. I'll leave this one for you to solve !
Here you go Mike - listening to it now! https://shows.acast.com/paulsc...
Thanks
Honest his old page links to a heathcare site weird
Mike
Leading proxy shareholder agencies have recommended investors in Victoria (LON:VCP) vote against accepting the royal carpet maker’s annual report and accounts at its meeting today. After accountants issued a qualified audit opinion and raised fraud risk concerns Glass Lewis and Institutional Shareholder Services have advised shareholders in the 128-year-old company to oppose the resolution. - The Times [ADVFN Newsdesk]
I held and sold out on original announcement.
Morning Paul
Have ever tried to find out how much was your loss if you haven’t averaged down on losing positions in your spread betting account?
Perhaps £1m-£1.5m less?
Paul I was astounded when in your Superb Podcast on Saturday you disclosed you lost £2 million last year on Spreadbetting.
I recently closed my Spreadbet Account because I decided the odds were rigged against me. I was slightly up due to one win on Burford Capital.
Having read your SCVR for several years now I think your honesty in admitting your own mistakes is rare but very refreshing in an age when many even find it difficult to apologise.
Keep up the good work.
Ouch! A testament to strength of character that Paul continued (and continues) to do the same high quality analysis despite that cloud hanging over him. I'm assuming that was a significant chunk of the portfolio.
But if spread betting is too dangerous even for someone like Paul, how on earth can PIs go short? I have seen more opportunities to be short than long in the last 2 years but despite reading the Naked Trader guide I never tried it. Robbie Burns points out that it's pure gambling and my wife would probably cash in her marriage chips if she thought I'd turned into a gambler. She already thinks investing in shares is akin to gambling!
Id say as long as you're not going nuts placing huge trades spreadbetting is very useful. I trade indexes/commodities (maybe a couple of trades a week) and the odd short. Theres been some good opportunities lately to short on the opening bell and take 5%+ . Not for everyone but when longs were so bad Aug-Oct just have to go with the flow.
I read a piece of analysis on spread betting that looked at those who were successful at it. It concluded that positions were generally only held for short periods of time and often accounts had zero positions for periods at a time. So basically very much a tool to be used sparingly and in a very disciplined manner. Not well suited to longer term holdings/investments it seems tho I’m sure there are exceptions to the rule.
I think where they can be useful is in pairs trades - ie where you short one stock and go long another. But you still need strong discipline there as short squeezes can hurt if you don’t close quickly.
The Volkswagen AG (ETR:VOW) short squeeze should be required reading for anyone before they venture into pairs trading.
https://internationalbanker.com/history-of-financial-crises/the-volkswagen-short-squeeze-2008/
And if you are spreadbetting you should be very aware of the embedded financing rate. This eats you alive if you hold a position open for for too long.
With spreadbetting you need to be right AND get the timing right. With shares you can get away with waiting until you are right.
Nevertheless, spreadbetting can have its uses if you are sensible - for managing currency exposure over the short term, or for reducing CGT exposure for a high conviction approach etc.
Interesting. Do you have a link for this?
The problem with pairs trading is you are paying the finance spread on both sides of the trade. Hedge funds get an offset , private investors usually don't.
You are actually credited with short interest on FX positions in IG Index.
It's not as much as their daily admin fee on the position though!
Spreadbetting is not just for shorts.
People in long trousers just use it less
;-)
She's right but I don't tell the missus too much.
Silver
Good Energy (LON:GOOD) the 100% renewable electricity supplier and energy services provider, has launched a number of new innovative products as it continues to scale its offering.
https://www.investegate.co.uk/...
Nigel Pocklington, Chief Executive Officer of Good Energy, said: "Today's update illustrates the hard work we have been doing to develop a new suite of services that can enable, incentivise and accelerate the UK's transition to clean energy.
"Good Energy is providing industry-leading products across solar, EV and smart tariffs, in addition to our end-to-end hassle free heat pump installation services. We have recently confirmed that we are the top rated Which? Eco Provider for the third year running and are retaining our five star customer service rating on TrustPilot. This is confirmation that Good Energy provides the greenest products with excellent service at prices that are market leading, truly helping our customers cut their carbon."
Mtk cap £45m, 12m rolling fcst:
P/E 10.7, PEG 0.2, eps growth 130%
Taken a position last week. Good Energy (LON:GOOD) is a tiddler in comparison to Yu (LON:YU.) which has gone up 4x in 1 year.
eParo
Surprised your post on Good Energy (LON:GOOD) after their update today hasn’t seen much response.
Like you I bought recently at just over £2 following a write up in Small Company Share Watch last month. I hadn’t bought any of their tips for ages as much prefer the better quality (imo) analysis and balance sheet coverage on smaller Companies from Graham and Paul.
But based on these forecasts from Investec, Good Energy (LON:GOOD) looked a too good opportunity to miss!
18.3p to end 2024
33.2p to end 2025
69.2p to end 2026.
SCSW were previously very keen on Telecom Plus (LON:TEP) which they highlighted at inception at just 50p and now 28 times higher with dividends more than covering the buy price then. Ditto with Yu (LON:YU.) more recently with big 268% one year share price gain and further upgrades.
Big share price gain for Good Energy (LON:GOOD) today. Still worth checking out.
I recently added TEP after the SCVR article. Good income and growth potential in the utility sector.
A couple of observations:
Downing Strategic Micro-Cap Investment Trust (LON:DSM) I have a reasonable holding and think that there are several good companies in the portfolio that I also hold individually, all within an ISA. For example Volex (LON:VLX) is my largest holding. I also hold Hargreaves Services (LON:HSP) that in my view is chronically undervalued and Flowtech Fluidpower (LON:FLO) an excellent turnaround opportunity, under new and very experienced CEO, Mike England.
I think that Judith Mackenzie and her team have made some good investments, other than the above, such as Ramsdens Holdings (LON:RFX) , but have in my view continued to support some poor management teams, Fireangel Safety Technology (LON:FA.) for me being the obvious example. There won't be a fire sale. This makes no sense and there is no need to do so. I shall be sorry to see Downing Strategic Micro-Cap Investment Trust (LON:DSM) go as once the gloom lifts most of its holding will I believe do well and the NAV close. As for Downing Strategic Micro-Cap Investment Trust (LON:DSM) being subsumed into Harwood, this is a possibility, but Chris Mills and his team already hold close to 30% of Hargreaves Services (LON:HSP) and I believe Flowtech Fluidpower (LON:FLO) . Still I suspect that there will be a twist in the tail yet.
Avingtrans (LON:AVG) This is my second largest holding and I fully agree with planetX. The company has an excellent management team and well thought out strategy. Chris Mills (Harwood) holds around 12% I believe. The medical division that currently makes no contribution to profits has significant upside and is the potential cherry on the cake.
Downing Strategic Micro-Cap Investment Trust (LON:DSM) I will be v interested to see how the involvements with Real Good Food (LON:RGD) turn out. The loan notes are, I believe, the largest holding in their portfolio and look a v precarious holding - Downing Strategic Micro-Cap Investment Trust (LON:DSM) supported what appeared to be a "keep the lights on" funding earlier in the year.
Yes. Real Good Foods was another investment that struck me as not of the best. However the AGM statement/trading update of 31 October was positive .
Christopher Mills is a keynote speaker at the Mello London conference at the end of this month as is Judith MacKenzie so you may be interested in attending.
There is a separate post on Stocko by me all about the two day show
www.melloevents.com
Kainos (LON:KNOS) I see Graham will cover this company ( I hold) . They have dropped nearly 13% but report:
KAINOS FIRST-HALF PROFITS, REVENUES GROW
(Sharecast News) - Kainos posted a jump in first-half profit and revenue on Monday as it hailed continued strong growth across its key business areas.
In the six months to 30 September, pre-tax profit rose 12% to £30.9m, on revenue of £193.2m, up 7% on the same period a year earlier.
Revenues in Digital Services nudged down 1% to £109.2m. The company said strong public sector revenue growth of 17% was offset by the expected drop in healthcare and project scope reductions in some commercial sector engagements.
Meanwhile, the Workday Services division saw revenue growth of 18% to £57.3m and Workday Products revenues were up 28% at £26.7m.
Chief executive Russell Sloan said: "In the last six months, our Digital Services division has been fuelled by public sector clients continuing to invest strongly in digital transformation projects. Meanwhile, there has been strong growth in our Workday Services division where we continue to be the leading Workday partner in Europe and are enjoying a growing status in the US and Canada.
"Progress within our Workday Products division continues to gain momentum. In addition to our three established Smart Suite products, we are delighted to have launched our latest product, Employee Document Management, which already has nine international clients signed up. We are confident that we will have further opportunities to develop new, innovative products as we continue to help ambitious clients deploy Workday."
Anyone any ideas as to why such a large fall in the SP?
Kainos (LON:KNOS) muted eps perhaps? Dividend is up though which shows management still positive on future
Possible read across from FDM.
IT projects are much easier to cancel/defer/mothball than physical asset projects.
I hold Kainos (LON:KNOS) and Softcat (LON:SCT) - which suffered a similar fate on recent announcement of its results. With operating margins of 14% (both) together with ROCE of 44% and 58% respectively, I will be topping up my holdings.
Hi The skier,
Looking forward to Graham's review of Kainos (LON:KNOS) .
In the meantime I would suggest that the share price slump of circa 20% is down to a bit of a re-rating. A p/e of over 24 is not warranted given revenue growth of 7% (noting the business sector increases and decreases within) and a flat EPS. The fact that the H1 bookings are down 9% is also a headwind. If the bookings do not pick up in H2 then next FY will be a challenge. I don't currently hold Kainos (LON:KNOS) but am keeping a close watch. Cheers.
Both Kainos (LON:KNOS) and FDM (Holdings) (LON:FDM) are two of my largest holding, so feeling the pain today.
Good morning,
I know there’s a lot of interest on here for Vertu Motors (LON:VTU) , I myself am a holder and of course it got a mention in Paul’s enjoyable podcast this weeknd. I read the following article this weekend from the website AM online (Automotive Management), it had been posted on X in the latter part of past week, it’s a useful round up of , and potential future of the merger activity in the sector.
https://www.am-online.com/deal...
That was an excellent link to read, thank you The Ox 2906. We no longer hold Vertu although I am a firm believer in it's management's ability to grow the company, we sold as I believe current trading will make it difficult for UK motor groups in general to hit forecasts. My timing was awful as Cinch revealed their interest. Marshalls profits have halved within the Constellation group but perhaps much of that is down to shedding Toyota dealerships under pressure from Toyota, as mentioned in your link. As most cars used and new are sold under lease type agreements, customers are facing much higher replacement costs, with no equity in the returned vehicle, as used car prices in general revert to more normal patterns. This has become very evident in America and I expect the same to happen here. Finance houses insist on finance recourse agreements with dealers, they can pull back commission already paid as returned cars fail to reach the forecast values. I was hoping to buy back into Vertu as this scenario played out but the Cinch move and positive publicity around that has turned my plan into a very bad one! Good luck to you and all other Vertu shareholders.
Thank you The Ox-interesting read.
Strong move up on the S&P last 10 days. Tho Moody's downgraded its outlook on US debt to negative from stable after the close.
Latest analyst forecasts
FDM looking like a warn for 2024.
JSE reads well but not kept up with the story. No position in either at the moment.
I've also created a video on a sector I think will outperform. Could be wrong and often am!
Hi Michael(I detect a faint Teesside accent?)
Thanks for the video which sets out the bull case for uranium - the demand for clean energy being greater than its supply.
I hold Centrus Energy (ASQ:LEU) which last week made its first delivery of HALEU to US Department of Energy. A volatile SP but one I see as a long term hold.
Hopefully this shortfall means 24 is the year - u can argue the mkt will stay strong for longer but clearly the 2027 outlook for supply growth can and probably will improve. For 24 is the crunch….. I hold Yellow Cake (LON:YCA) and Geiger Counter (LON:GCL).
Do you know why the broker forecasts for Yellow Cake (LON:YCA) are so low for 2024? I hold Geiger Counter (LON:GCL) and various others in the US markets.
It’s an NAV stock - I pay little attention to the P&L although I have reviewed their costs and the salaries of the board are v competitive. I think the big risk at Yellow Cake (LON:YCA) would be a storage issue at Cameco or some sort of fraud.
YCA stores its uranium in Canadian and French warehouses so I'd say the storage risk is reasonably low.
I had a tour of Orano's Tricastin U3O8 storage facility once in France. Pretty secure I would say.
Hi SCI20 - yes, that's correct. I'm originally from the mighty town of Hartlepool. I'm unfamiliar with other countries' stocks - there are likely to be better explorers than Aura and further advanced but I have exposure to this sector through YCA.
You can take the boy out of Hartlepool …..
Suprised you are not trading US stocks Michael. AMD six years ago was a penny stock at $1.59, and has since 100 bagged to $164 in 2021. Even though the risk was high that AMD wasn't going to make it, the technicals did improve considerably at $3(still a 50 bagger) ora gap up at $4, where all the MA's had crossed upwards. and if one had scaled up their position at each base thereafter, that would have reduced the risk much instead of going all in at $3.
FDM (Holdings) (LON:FDM) Just to repeat something I mentioned last week, I have very little personal confidence in the current senior management team. Opinion rather than fact of course but based on a number of recent interactions. In addition, there are other companies in the same niche who are doing it better and are far more pleasant to engage with.
Centrus Energy (ASQ:LEU) is one of my longest held positions. I too am a Uranium bull with 20% allocation to U equities. I hold Yellow Cake (LON:YCA) , Geiger Counter (LON:GCL) and Cameco (NYQ:CCJ) . It is a frustrating and volatile sector to hold and I was undoubtedly early, but the future looks pretty bullish.
Apart from Kirkland Gold (now part of AgniCo Eagle Mines (TSE:AEM) ), Centrus Energy (ASQ:LEU) has been one of my most successful investments. I am a chemist and accountant by training - turned dilettante farmer - and I think a lot of the IP they hold is not reflected in the price. The positioning of Centrus Energy (ASQ:LEU) in the current geopolitical environment is compelling, but they have historically been very dependant on the Russians.
I also like Silex Systems (ASX:SLX) and their laser approach to seperation of the two main isotopes of U - 238 and 235 (only U-235 is fissible and very high speed centrifugation of U in the form of a gas - UF6 - has been the method used in the past). I am keen to go and see them next year as I have never been to Australia.
If you don't want to go down the rabbit hole of geology and chemistry, your best bet is probably just to buy Geiger Counter (LON:GCL) which is on a deep discount.
Excellent thread. More evidence that the SCVR is where useful discussions can be found.
An interesting observation to start the week....
Did you know that the 573 companies in the FTSE-All Share Index combined are now worth less than each of the top two Magnificent 7?
The FTSE-All Share is worth £2.2 trillion versus Apple US$2.8 trillion and Microsoft US$2.7 trillion.
The FTSE-AIM All Share is only worth £49bn, so only 2% of the small FTSE-All Share.
A sobering thought of just how far things have stretched in one direction...hopefully there will be a bounce back at some point!
Hopefully, there are 573x less investors looking at FTSE All-Shares than each of the Magnificent 7... and this throws up opportunities.
I'd rather compete with say 100,000 other investors than 57,300,000 other investors given that I am neither a star investor nor able to dedicate a full working week.
My morning smallcap tweet: The Tills are Alive with the Sound of Moolah
Saietta (LON:SED) Sondrel (Holdings) (LON:SND) Cellular Goods (LON:CBX) Develop North (LON:DVNO) Avingtrans (LON:AVG) Harworth (LON:HWG) Brave Bison (LON:BBSN) Biome Technologies (LON:BIOM) Cordel (LON:CRDL) Good Energy (LON:GOOD)
◄Saietta (SED)► Indian JV (50% owned) wins £106k order for pilot production over the next 3 months. "Target volumes indicated by the client, subject to further purchase orders, are expected to commence in Q2 2024 generating revenue for Saietta VNA of approximately £12.7 million in the first year of production, with an expected minimum of 60,000 orders over a 5 year period." [SP=20.47 Cap=20m]
◄Sondrel (SND)► wins maiden production order for an ASIC chip. No £££. Included in FY23 F/C. [SP=15.58 Cap=14m]
◄Cellular Goods (CBX)► successful creation of kelp-derived biochar. "Paves the way for carbon dioxide removal credit production and a range of applications in agriculture, environmental restoration and industry." [SP=0.46 Cap=3m]
◄Develop North (DVNO)► starts £500k (max) buyback. [SP=75 Cap=22m]
◄Avingtrans (AVG)► wins 3-4 yr multi-phased order starting this month. Initial value c.$10m. [SP=367.9 Cap=118m]
◄Harworth (HWG)► get planning permission for 800,000 sq. ft of industrial & logistics space at its Skelton Grange site in Leeds. [SP=100 Cap=324m]
◄Brave Bison (BBSN)► c.£4m in new contract wins and renewals over periods up to 24 months. [SP=1.6 Cap=20m]
◄Biome Technologies (BIOM)► risk of two RF div contracts slipping into FY24-Dec. Q1-3 in line. [SP=128.9 Cap=5m]
◄Cordel (CRDL)► boasts that the National Gauging Database contract with Network Rail went live on-time and on-budget. [SP=4.81 Cap=9m]
◄Good Energy (GOOD)► info on launches of new products. [SP=267 Cap=45m]
◄Notes► SP & cap are 20m delayed
Downing fund
Read somewhere last week that Judith Mackenzie fund is being wound up and cash returned to shareholders .
Simon Thompson article I think, so 2 things to consider
- as suggested by Thompson probably an opportunity to buy into downing as it’s sell below NAV and make a % when cash returned
- watch out for selling pressure on the holdings as they are sold .
Be interesting which of the Downing holdings get snapped up by Harwood /Mills / Rockwood .
planetx - yes, I also did think Harwood could be taking a look at the Downing vehicle. There is some overlap in key holdings. Harwood may be talking to them about Flowtech, Hargreaves etc. or just bid for the company at some point. Would be a good add-on for Rockwood to increase its critical mass.
I don't think there is immediate selling pressure like an open ended fund though. They will probably be winding up the investment trust gradually, not over weeks and months.
Hopefully not the 3 or 4 years I think Crystal Amber Fund (LON:CRS) will end up taking!
Downing Strategic Micro-Cap Investment Trust (LON:DSM) Planetx - You probably read it here, on Thursday, a really good thread. Should have pleased those who have been complaining that we don't discuss UK small caps enough!
The cautious view was expressed here by Wolf of Small Street -' I'm getting a cold sweat just looking at the list' - but the contrary view is by Jonno here this morning.
The full RNS is essential reading, this is the key line, [the board] 'has concluded that it would advantage all shareholders equally and fairly to commence a managed wind down of the company's investment portfolio in an orderly manner'. No firesale. My take is that not many of the portfolio are dogs, that even the dogs can be worth something (I'm looking at Fireangel Safety Technology (LON:FA.) ), that this situation might be a catalyst for a takeover of at least one of the shares in the portfolio, and the current discount of 14% is sufficient cushion for any decline in the underlying during the wind-down.
The price of DSM increased by 7% after the announcement and the discount narrowed (the portfolio increased in value slightly). But it's down this morning. I don't hold but am watching.
(Note: an early post in the thread on Thursday refers to the wrong fund).
Bit late in the day but for the sake of completeness I have taken Downing Strategic Micro-Cap Investment Trust (LON:DSM) off my watch list. The loan notes from Real Good Food (LON:RGD) are 12.5% of the portfolio and the discount on DSM today is only 14.6%. There's a note against the loans: 'Unquoted. Stated inclusive of the fair value of unpaid interest income.' Are RGD not paying the interest on time? RGD FY23 (published in September): Sales down 19.8% , EBITDA loss of £4.8 million, Loss before tax £9.0 million, total net debt increased to £31.2m (2022: £25.5m). You couldn't rule out RGD going "Pop!" and I'd want to see a bigger discount on DSM before buying. Much better to watch the better individual holdings and buy selectively if the overhang drags them down.
Thx for that planetx .... I'll go and have a trawl through their holdings.
Looks like only Volex (LON:VLX) held in common at around 6% of a £35 m fund. Not particualrly material.
Aving trans
Lovely contract win of 10 million usd over 4 years for design and development of a new pump .
This does not include the actual order that they will be in prime position to get.
Been sold off recently and easy to buy at 370 level occasionally 367 which is a great entry point .
I’m almost maxed out on Avingtrans which is an excellent company with superb management .
Seems to be a big selller around .
Hi Planetx
I think eps was heavily downgraded for next year wasn’t it. Ie down to around 5p which would explain why there are sellers about as it nominally looks like it is in a high PER. Long term prospects might be good and I agree it is a very well run company but investor appetite very short term at the moment.
Hello Planetx. What am I missing with Avingtrans (LON:AVG) I wonder. SP flat for 3 years, down 11% this year, stock rank 40 etc etc. Please persuade me!
- Sun of the parts vakuation of the individual businesses is above market cap .
- this excludes the new investment in imaging which is in their for free and in 24 months could be worth more than market cap
- huge nuclear contracts coming up in next years
- plenty of cash (think it was 17 million)
Management excellent
Proven track record of buy build and exit .
Isn't that Purchase, Improve, Exit? I believe Roger McD likes his pies!! Avingtrans (LON:AVG)
Excellent podcast at the weekend Paul - good to hear your summary of the wider view and market context at the start.
Thanks TJ! Much appreciated, it's good to get some feedback on my podcasts, as often it feels like I'm shouting into the wilderness. But the listens are climbing, to almost 2k per week, which is pretty good in a savage bear market I reckon, for very niche content.
For me the podcast is just the right balance between company news, macro, personal experience, rambling (I mean that in a good way) and humour.
Similar podcasts can be far too dry, and I quickly lose interest.
Thanks Wolfie! Shares, and finance can be a very dry subject, so I try to keep my podcasts fast-moving, and a little bit quirky! Everyone's got their own style haven't they.
I love listening to podcasts about shares/economics, and wish more people would do them, providing they broadly know what they're talking about of course!!
Yes it's a very good podcast. Topical, interesting with good well reasoned content.
My thoughts echo the other respondents. Just didn't get there early enough to say so!
Thank you for informative podcasts, listen while on exercise bike, seems to make the punishment go quicker!
Card Factory (LON:CARD) recovering well from recent lows with looking like the shares of former large holder cleared and possibly in anticipation of a TU.