Small Cap Value Report (Mon 13 Sep 2021) - TST, GMR, STEM, SCE, XPD, BIRD, LUCE, WATR

Good morning, it's Paul & Jack here with the SCVR for Monday.
Agenda -
Paul's Section:
Touchstar (LON:TST) (I hold) interims. Brief comment, as it's very small.
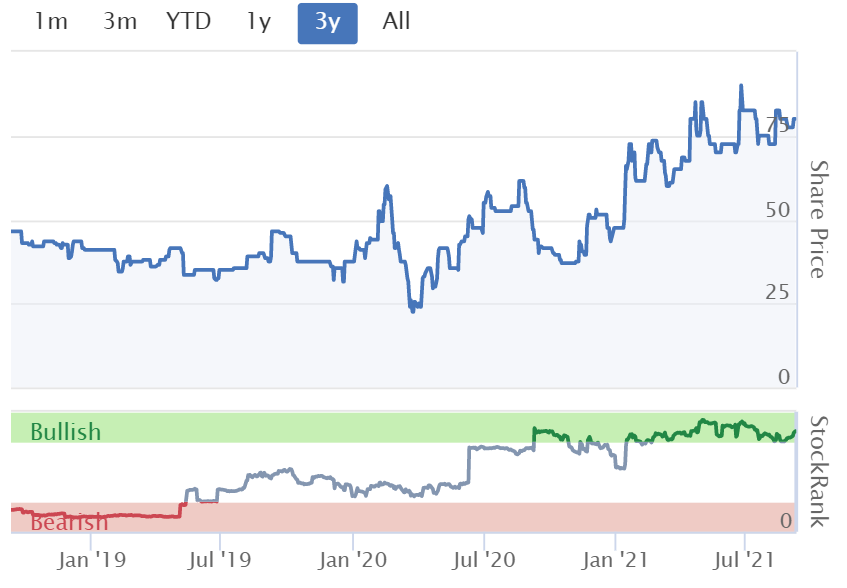
Gaming Realms (LON:GMR) - strong interim results, moving into profit. Potentially interesting, could be worth readers taking a closer look. 2021 outlook is in line with expectations If forecast growth in 2022 happens, then the shares could end up looking cheap. I don't know enough about the business model to be sure either way, so am neutral.
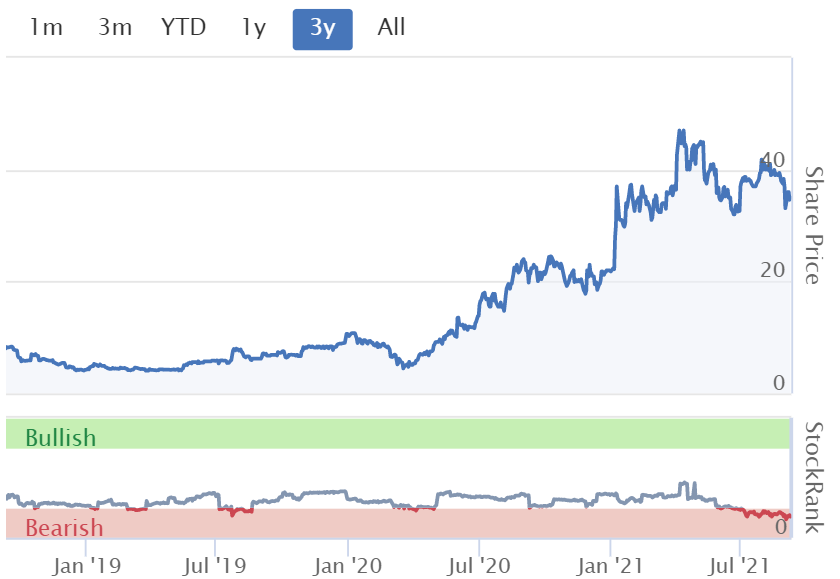
Surface Transforms (LON:SCE) - another set of poor results, to add to a 20 year track record of poor results. However, big orders in the pipeline mean things look set to dramatically improve in 2021 and 2022.
Blackbird (LON:BIRD) - interim results don't impress at all. It's still loss-making, and needs to at least double revenues just to reach breakeven. There's enough cash to keep going for several years. I've no idea why the market cap is so high.
Luceco (LON:LUCE) (I hold) - my notes from today's interim results webinar on InvestorMeetCompany. I've taken a small opening stake, because the share price has fallen 30% on worries about supply chain problems. That might be a reasonable entry point maybe?
Water Intelligence (LON:WATR) - strong interim results, but the top dollar valuation & lack of divis rules it out for me.
Jack's Section:
Sthree (LON:STEM) - strong trading continues and FY profit is expected to be significantly ahead of consensus. The shares have been strong recently so there's a question around valuation and also around how long the market remains buoyant, but the group is investing in headcount and it's not hard to envisage continued strong trading.
Xpediator (LON:XPD) - recently upgraded guidance for at least £8.5m of FY profit before tax is maintained. Big increase in receivables and swing to net debt due to restructuring and Brexit complications. It's a buoyant market for logistics, but it's also low margin and costs could rise to so overall I'm neutral.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to cover trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul's Section
Touchstar (LON:TST) (I hold)
Too small to report on here properly, as only £7m market cap. However, interim results today (c. breakeven) show some signs of life. In particular, I like the outlook comments -
-- H2 2021 started well and expect strong result
-- FY 2021 we now expect to be above market expectations despite continued uncertainty
-- Current prospects give us confidence that 2022 will be an even better year
-- Order book as of the 10 September 2021, stood at GBP836,000.
The balance sheet is just about OK (net cash of £1.3m, unchanged), and the order book has been growing, now at £836k.
My opinion - it’s a tiny business, not sure why it’s listed really. However, I’ve always thought there might be something potentially interesting here, so have held a small position for several years. The new “Podstar” product (software for transportation) is being rolled out in 2022, after trials this year. Very illiquid, so won’t interest many people.
.
.
Gaming Realms (LON:GMR)
35p (Friday night close) - mkt cap £101m
Gaming Realms plc (AIM: GMR), the developer and licensor of mobile focused gaming content, is pleased to announce its interim results for the six months to 30 June 2021 (the "Period" or "H1'21").
Headlines -
Revenue growth of 50% generates adjusted EBITDA[1] of £3.1m[2], up 144%
Continued U.S. expansion post period end with content launched in Pennsylvania
Strong revenue growth to £7.7m in H1
Adj EBITDA of £2.7m (after share option charge) is best ignored, because it’s not reality - the company capitalised £1.6m of development spend onto the balance sheet
Profit before tax is a more meaningful number, and has moved from a loss of £(693)k in H1 LY, to a profit of £804k H1 this year - an impressive turnaround
Balance sheet looks adequate
Cashflow has benefited from a one-off receipt of £973k deferred consideration, plus £362k sale of something - GMR did look like it was scraping the barrel for cash last year, but I’m impressed it has pushed through without needing to dilute shareholders with a placing.
Note there is a convertible loan of £3.5m due for payment at end 2022 - it would be worth checking the terms, to see if conversion might occur, and cause dilution or not.
Outlook - the commentary sounds generally positive, and concludes that it’s trading in line with expectations -
With a strong game development pipeline, a clear strategy to continue expanding its distribution internationally and with demand from the Group's customers expected to continue, the Board expects trading for FY21 to be in line with market expectations and remains confident in the strategic outlook for the business.
My opinion - an interesting company, which has clearly made good progress this year, moving into profit.
I’ve never managed to get to the bottom of exactly how the business model works. In particular, how much of the revenues are recurring, and how much one-offs? Previous management webinars & results statements have been a bit vague on this, in my view, more clarity is needed.
Is GMR worth just over £100m? Not to me it isn’t, because I’m not sure how likely it is to deliver profit growth.
On the upside, current year forecast is for 0.9p EPS, rising to 1.8p in FY 12/2022. If the FY22 forecast is achieved, then the PER would only be about 19 times - which looks too low for a fast growing software business, with products that look popular with gaming companies, internationally.
Overall then, GMR looks potentially interesting, and this could be worth readers spending some more time doing the detailed research. If you can get to the bottom of how the revenues work, recurring/one-offs, then do please let me know!
.
.
Surface Transforms (LON:SCE)
66.5p (up 2% at 08:27) - mkt cap £133m
Surface Transforms (AIM: SCE) manufacturers of carbon fibre reinforced ceramic brake discs, announces its half-year financial results for the six months ended 30 June 2021.
There’s very little for me to say here, because this share is all about future growth which seems to be in the pipeline. The interim numbers have not yet seen that growth coming through.
Tiny revenues of £1.2m in H1
Strong gross margin of 62% - I like that, because it shows that there’s good operational gearing once revenues really start to rise strongly. Bulls in this share say that it has special expertise in ceramic brakes which gives it a defensible moat. That’s the key issue to research.
Cash is strong at £17.2m, from a placing.
Outlook -
The Company now expects to enter a period of high growth, partially, but not solely based on a lifetime value OEM order book of circa £70m. Indeed, we repeat the statement made by the Chief Executive in the manufacturing strategy announcement of 1 September "at the time of the fundraising we said that we thought there could be sufficient demand to fill the Knowsley factory by 2025 (£75m sales), albeit these projections are still uncontracted…we have now concluded that we may want this capacity by 2024."
It goes on to say that the timing of orders is uncertain for 2021, and some might be pushed into 2022. I don’t think that matters particularly, because the value in this share will be all about what revenues/profits it makes in several years’ time, hence the timing of short term production isn’t significant, but could possibly cause some volatility in the share price maybe? Although in my experience, when people buy into a share like this, they tend to be “believers” and hold tight through any short term disruption.
However, we reiterate our previous statements, that we expect to be profitable in 2022.
My opinion - neutral, because this type of share doesn’t generally interest me. I’ve had lots of bad experiences with loss-making companies on the cusp of great things, as something nearly always seems to go wrong.
That said, SCE seems to have a genuinely impressive order book, and looks on the cusp of strong growth, and imminent profitability.
How to value it though? That’s the tricky bit, because there are no existing profits, we have to forecast what it might make in future, or rely on inherently uncertain broker forecasts. There's also the question of competition which might crop up, if SCE starts making big money.
Good luck to holders! It would be good to see SCE finally come good, after about 20 years as a listed company producing dismal numbers every year. It does look like that’s about to change for the better!
.
.
Blackbird (LON:BIRD)
34p (down 12% at 10:53) - mkt cap £115m
I’m amazed the market cap is £115m, given the track record of negligible revenues, continuous losses, and fundraisings. Although as SCE has shown above, occasionally jam tomorrow stocks do actually look set to serve up some jam - nearly always years late, and after burning through a lot more cash than originally planned. I wonder what Blackbird shareholders will be spreading on their crumpets? Jam, or regurgitated worms?! Let’s have a look.
.

.
Blackbird plc (AIM: BIRD; OTCQX: BBRDF), the developer and seller of the market-leading, patented cloud native video editing platform Blackbird®, announces its interim results for the six months ended 30 June 2021.
Revenues are still tiny, but up somewhat - is this growth enough?
record revenues for the six-month period of £867k, up 21% year on year
A similar amount of revenue is secured for H2.
It’s still loss-making, and cash-burning, and this is just a half year remember -
Net loss before tax £1,168k (6 months to 30 June 2020: £942k)
Cash of £5.7m, so looks financially secure for the time being.
Outlook -
By the end of August 2021, we had grown 2021 secured revenue to £1,763k (2020 comparative: £1,453k) and had £893k of contracted revenue for 2022 which is up 18% versus the 2020 comparative for 2021 (£756k).
More excitingly, our recently announced first technology licensing deal opens up both a quicker expansion opportunity in our existing market and further potential in new markets outside the Broadcast sector. This deal clearly demonstrates the adaptability of our technology and significantly increases the Company's TAM. The next few years will be most interesting for the Company as our markets recognize and respond to the flexibility, resilience and sustainability of our core technology…
The future prospects for the Company continue to be very bright and I look forward to working with the team to deliver these.
US Listing - shares are to be listed in the US, on the OTCQX Best Market - doing a bit of googling reveals this to be a junior market, where shares are traded by dealers, rather than having orders matched as on the main US markets.
Will this lead to a re-rate of Blackbird shares? It might do, who knows? Maybe it will get ramped on Reddit?!!
Balance sheet- looks OK for now.
My opinion - sales need to double from here, just to reach breakeven. The growth rate isn’t anywhere near fast enough as yet.
The market cap of £115m looks incredibly generous, considering performance to date.
I’d want to see a large acceleration in growth, before even considering an investment here, because performance to date simply doesn’t justify a market cap anything like this high. So investors must be very confident about the company’s future, because they’re paying a lot up-front for commercial success that has not as yet been achieved.
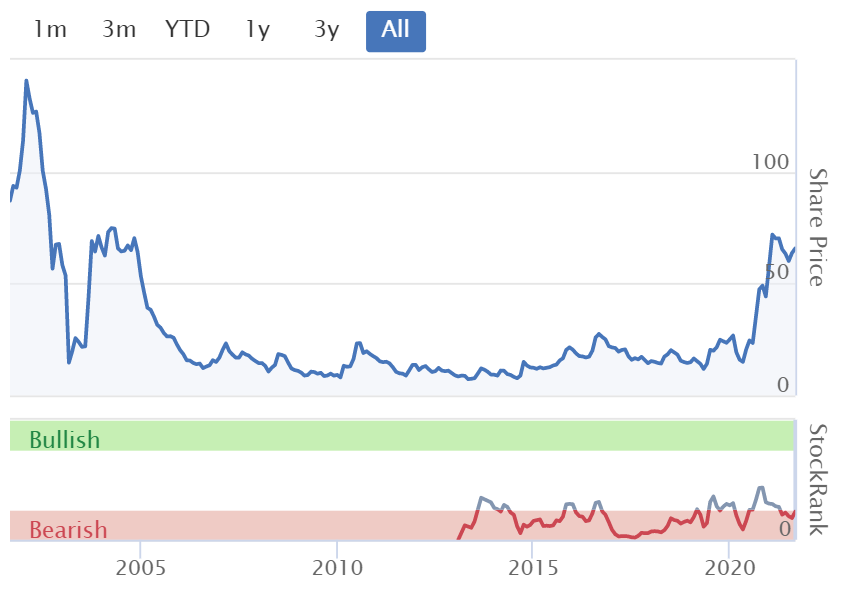
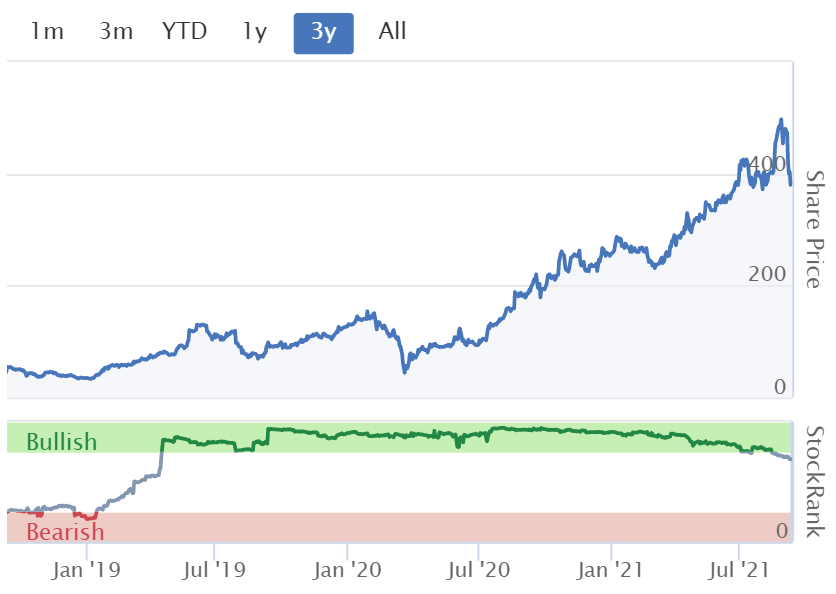
It's surprising to see the share chart below looking so positive, when it is not supported by positive financial results. If it was me, I'd be banking my profits with grateful thanks to the buyer. Although we are in a bull market for tech shares, and valuations don't necessarily need to make sense to value investors.
.
.
Luceco (LON:LUCE) (I hold)
384p (up 1% at 11:54) - mkt cap £617m
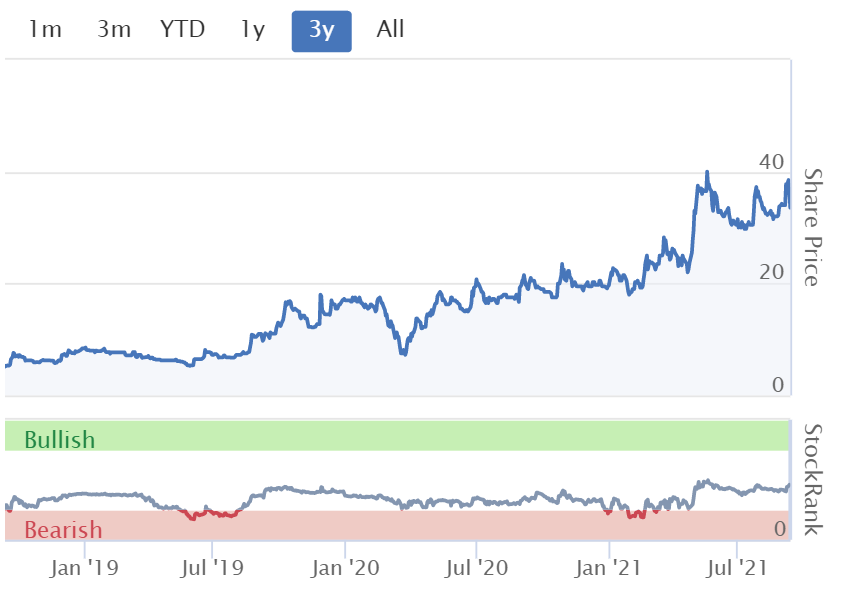
I last looked at this company on 7 Sept here, on publication of superb interim results. With the share price at 474p, I commented that top-slicing looked a good idea, after a great run. I didn’t expect the price to fall as far as it has, down around 100p since then, although it showed signs of finding a floor this morning, so I did pick up a little scrap for my small punting account. At under 400p, the valuation looks more reasonable to me, in the high teens PER.
There’s just been a results webinar on InvestorMeetCompany (recording now available here), so here are my notes - as usual, this is not comprehensive, I tend to just jot down key points. So apologies for anything I missed.
Management pronounced the company name as “Loo-see-co”
Very clear explanation of what the company does -
Wiring accessories (50% of revenues, and bulk of profits)
LED lighting (25% of revenues) - newest part of the group
Portable power - e.g. electrical extension leads & reels
Customers - two thirds sold to electricians, the rest to end users (mainly power leads)
Markets - mostly UK, 80%
Demand is driven by construction, repair & remodelling markets, which are growing faster than GDP, stable market growth
R&D and manufacturing have been done in China for last 12 years, half of what we sell is made in our own factory in China, competitors don’t tend to have their own factories, so this is a competitive advantage.
LUCE products have long-established, respected brands. Priced in mid-market, but with above average design & quality.
Good relationships with distributors.
Very successful recent interim results - more than doubled profits.
Driven by new business wins, and high product availability - production has risen 50% during pandemic
Favourable market conditions, plus market share gains.
Gross margin is coming under temporary pressure from cost price increases, but these are being passed on to customers, albeit with a time lag. Expected to continue in H2, then be sorted out by 2022.
Longer lead times out of China, have compensated by increasing inventories - which does make me wonder if supply chain problems could be a vicious circle - i.e. shortages & delays, so everyone increases inventories, thus making the problems worse!
Brands & pricing power mean cost price rises can be passed on to customers, but it takes a while for all customers to accept price rises.
Automating its factory, with 2 year payback on investments.
H2 will be a little softer - e.g. construction materials shortages are causing delays to some projects, out of Luceco’s control.
Inflation & supply delays are the major challenges at the moment. Don’t know when they will be resolved.
Q&A
How much of market share gains are temporary due to competitor supply difficulties? Not much, mayabe 4%? Difficult to know. Growth is slowing at e.g. Screwfix, but not likely to go backwards. Shipping costs are the big unknown. It got to $12k per container, we thought it couldn’t go any higher, then it went up again to $15k. Can’t last forever. Taking twice as long to get product in from China. Ports congested (anecdotally - I noticed that in Malta where I am currently residing, the horizon is dominated by long lines of static freight ships, at least 20 of them, not moving at all seemingly. They’re pointing north, towards Italy/Europe).
CFO chipped in that LUCE sells half its products FOB - i.e. the customer takes the goods from its factory in China, so shipping issues are the customer’s problem.
High hopes for new electric vehicle products, launching later this year.
China factory is running at c.80% capacity, but with further automation capacity could be extended, so maybe 60-70% capacity after those improvements.
Acquisitions - we can spend £80-90m without dilution. Working on 3 deals currently, totalling £70-80m, expect 1 or 2 to succeed in the near future.
My opinion - a good, clear briefing, which I found very useful. This is a good business, and the recent correction has I think provided a reasonable buying opportunity. It depends if demand remains robust, and of course the supply chain difficulties won’t help short term sentiment. I’ve bought a small opening position at 380p, initially as a punt, but after the webinar, think I might transition my holding into my long-term account, possibly buying more on any further share price weakness - but I’ve not decided yet, am still pondering things.
Management seem switched-on (geddit?!). Checking the last annual report, the long-serving CEO has a huge personal shareholding, of 31.5m shares. This is one of several striking similarities with electrical cable group Volex (LON:VLX) (I hold).
Overall, I’m braced for a bumpy ride over the autumn/winter, as supply chain problems could worsen, who knows? But the recent c.30% fall in share price from an admittedly rather toppy peak of c.500p, looks a fair entry point in my view.
.
.
Water Intelligence (LON:WATR)
1265p (up 1%, at 12:38) - mkt cap £207m
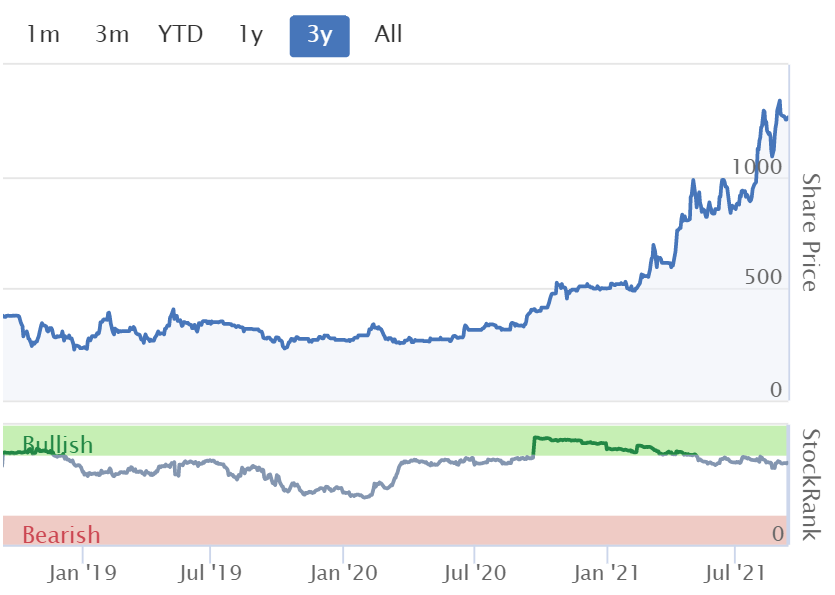
H1 results look good, with revenues up 44% to $24.7m, and adj profit before tax up 77% to $4.2m.
The trouble is that the market cap is so high, at £207m.
For me, a far more attractive US share is Somero Enterprises Inc (LON:SOM) (I hold) which is valued at £303m, yet looks set to make 3-4 times as much profit this year as WATR. True, WATR is growing fast, and being a small business still, can achieve a higher growth rate. SOM is also a cash generation machine, and pays out generous normal & special divis. That suits me better than a highly rated growth share such as WATR, so it's just horses for courses, depending on your investment approach00.
Valuation rules out WATR for me, but good luck to holders. There’s no denying the company is performing consistently well, and has interesting growth potential.
5-bagging in the last year and a bit, it must be very tempting to bank some profits.
.
.
Jack’s section
Sthree (LON:STEM)
Share price: 595p (+8.38%)
Shares in issue: 133,510,532
Market cap: £794.4m
SThree is a recruiter with ten brands across the Science, Technology, Engineering, and Mathematics (STEM) industries. It was founded in 1986 as an IT-focused specialist staffing agency but since then, there’s been an organic push into new geographies and sectors.
Most of its business comes through Computer Futures, Progressive, Huxley and Real.
As with certain other sectors, recruiters have proven to be post-lockdown winners and the SThree share price chart shows as much, with a six-month relative strength figure of +49.6%.

The group now qualifies for the Value Momentum Screen and today’s short update confirms that trading remains robust.
Full year profit performance expected to be significantly ahead of consensus
Highlights:
- Net fees +29%, with strong growth in Germany (+35%), USA (+31%), and Netherlands (+24%),
- Contract and permanent fees up 27% and 36% year-on-year respectively,
- Contractor order book +41%,
- Net cash up y-o-y from £39m to £51m,
- PBT to be significantly above market consensus (of £51.4m) due strong trading and delays to investment spending - this follows the upwards revision provided in June 2021.
Credit to SThree for including the market consensus figures. These look like strong results.
Importantly, performance versus 2019 is also positive: Q3 net fees are up 11% on a two-year basis, with Germany up 22%, the US up 28%, and Netherlands up 8%, while the contractor order book has risen by 20%.
The top five countries represent 87% of revenue, with Germany at 33% of the total and the US at 26%. Contract net fees represents 76% of Group net fees, more or less stable year-on-year (Q3 2020: 77%).
The strong order book reflecting strong ongoing high demand and a positive outlook
Group average headcount was down 2% year-on-year by the end of the period but SThree is hiring and expects a further increase in Q4 and FY22.
The Group plans to issue a trading update for the year ended 30 November 2021 on 13 December 2021.
Conclusion
Obviously the share price performance shows that investors understand trading is strong here. Are the shares attractive even after this steep rise?
Significantly ahead of £51.4m, so let’s say £55m-£60m. Let’s assume a tax rate of 28% (roughly equivalent to FY18 and FY19 tax rates). That would be £39.6m-£43.2m of profit after tax and 29.7p-32.4p of earnings per share, way up on FY20’s 17p and the forecast FY21 figure of 25.3p, and would equate to a PE ratio of 16.9-18.5x. The group has net cash of £51m, so we can also adjust for that.
It’s not obviously cheap to me given that this is a sector whose profitability can vary across the business cycle.

But you could argue that it’s fairly valued on near-term growth prospects, with scope to surprise further on the upside. Particularly if there’s a degree of operational gearing at play.
We have the uncommonly buoyant conditions, the fact that SThree is attractively positioned in structural growth areas, and the fact that it already benefits from a unified global database of clients and customers (so there are presumably fewer IT headaches than one might find in a company cobbled together via disparate acquisitions).
SThree appears confident and expects to continue increasing headcount over the next year, which suggests it expects to remain busy for a while yet. Revenue has increased steadily over the years in spite of choppier profits.

The group’s exposure to contracting presumably means it is well-placed for a more flexible working environment as well. This looks like a good company - one of the better listed recruitment companies out there so I’d happily spend more time on it. My concern is purely valuation for now - perhaps the easy money has been made and holders will now be looking at less substantial share price gains and even then, assuming a lot of things go right.
On the other hand, I certainly wouldn’t bet against this kind of momentum. When conditions are this strong there’s always scope for ongoing earnings beats. The group’s largest markets are robust and a more inflationary environment should feed through into higher wages. So I wouldn’t be surprised to see further positive developments here.

.
EDIT from Paul - this PIWorld recording has just come through, thanks to Tamzin & Tim -
Xpediator (LON:XPD)
Share price: 69.4p (-4.69%)
Shares in issue: 141,688,425
Market cap: £98.3m
Xpediator is an international freight management company providing logistics and transport support solutions. The group works across the UK and Europe with a particular expertise in Central and Eastern Europe (CEE) countries. These markets are growing at faster rates than the rest of Europe, while logistics itself tends to grow in excess of GDP.
Established in 1988, the group has an international network of offices providing road, sea and air freight services, together with logistics and warehousing in the UK and Romania. The three main areas are freight forwarding, logistics & warehousing, and transport services.
This can be a tough part of the market to operate in, but supply chain logistics and fulfilment are essential services for most companies and in the current environment, with Covid lockdowns leaving all sorts of supply chain disruption, there is high demand for these services.
But there are other investment candidates in this industry: Clipper Logistics (LON:CLG) is doing an exceptional job in e-fulfilment, and Wincanton is now making similar moves. Xpediator (LON:XPD) differentiates itself with its CEE exposure, but is this the right way to play supply chain disruption?
Whilst market conditions remain highly competitive, demand for the Company's freight management services has remained strong.
Highlights:
- Revenue +27.1% to £126.6m,
- Adjusted profit before tax +71.4% to £3.6m,
- Adjusted earnings per share +53.4% to 1.58p; basic EPS up from loss of 0.25p to positive 0.66p,
- Interim dividend up 11% to 0.5p.
Adjusted profit before tax of £3.6m reflects growth within key CEE markets, incremental revenue generated from customs clearance, and a full recovery from a COVID-19 affected market.
That figure adjusts for restructuring costs of £398,000, amortisation of acquisition related intangibles of £742,000 , and an additional interest charge of £167,000 (H1 2020: £171,000) resulting from IFRS 16. So that’s a material level of adjustments, about £1.3m.
Freight Forwarding specialises in moving freight, primarily internationally by road, rail, air and sea. The division accounts for 79.6% of group revenue. Sales increased 28.5% to £100.8m (2020: £78.4m) generating operating profit of £4.1m (H1 2020: £2.6m), driven primarily by growth in CEE, enhanced sea freight rates and successful implementation of a UK customs clearance department.
Logistics and Warehousing includes businesses in the UK and Romania under the Delamode and Pallex brands. revenue increased by 22.0% to £22.9m (H1 2020: £18.7m) giving an operating profit of £0.4m (2020: £0.6m). The Romania Pallex business was strong but was offset by start-up costs linked to the UK new build 200,000 sqft facility in Southampton and the UK Braintree facility turnaround.
Transport Support Services, trading principally under the Affinity brand, provides bundled fuel and toll cards, financial and support services for hauliers in Southern Europe. Revenue increased by £0.5m to £3.0m (2020: £2.5.m) and operating profit to £1.3m (2020: £0.9m). Note this is higher margin than the other two.
Balance sheet - Net debt excluding right-of-use assets debt at 30 June 2021 was £1.6m (31 December 2020: net cash £6.8m). This primarily reflects considerable advance supplier payments required in line with market supplier availability, increased freight rates, delays in client payments linked to acceptance of Brexit related charges and some delays in collecting UK receivables following a restructuring in UK freight forwarding finance and shared service teams.
The group says that ‘this item is receiving significant focus, has already improved and is expected to be fully unwound by the year end,’ so we can presumably look forward to an improving net debt position and hopefully a return to net cash.
Post period - UK strategic partnership with e-fulfilment leader Synergy Retail Support, opening of 200,000 sqft new build warehouse extension in Southampton, and further recruitment of key senior personnel to enhance and strengthen leadership.
The group says it is well placed to achieve an improved performance in the second half of 2021 with adjusted profit before tax for the full year expected to be in excess of £8.5m and a healthy pipeline of potential acquisitions.
Conclusion
With net debt of £1.6m, it’s not a hugely concerning level but I’d perhaps want to see Xpediator embarking on a more concerted acquisition strategy from a position of greater financial strength. The group does say it is managing this so progress here would be good. Receivables is a huge line item in the cash flow statement at £16m that turns an otherwise cash generative six months into a cash reducing one. It’s something to keep an eye on.
The group has a useful mix of geographies and freight management services and it is looking to grow. Management says it continues to review a number of acquisition opportunities. The group is maintaining its recently upgraded target of at least £8.5m of profit before tax.
Using a notional 20% tax rate, I make that out to be at least around 4.8p of earnings per share and a forecast PE ratio of around 14.4x. I think that’s towards the upper end of what I might pay though for this type of business.
Current conditions across a range of sectors continue to be affected by unusual post-lockdown dynamics. It’s net positive for Xpediator, but it’s also causing some complications as well, such as the increase in receivables. And who knows how long it all lasts for. These businesses are generally not that high quality insofar as margins and barriers to entry tend to be low, so I wouldn’t want to pay too high a multiple of earnings. Costs could increase as well, with papers recently flagging the shortage of drivers around.
It’s not dissimilar to the car dealers in some ways: exceptional current conditions, but for how long, and what happens when/if the tailwinds unwind in a year or two? It seems like brokers are also struggling to get a handle on the near term outlook.

It’s quite possible that the group is in for a period of exceptional trading but longer term this is a tough industry. With the right strategy Xpediator can certainly grow, but on the whole I’m neutral here.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

37 comments
Relatively big (more or less doubles the company’s size) after hours acquisition of ExpressVPN and equity raise announced by online security specialist Kape Technologies (LON:KAPE) . Includes a retail offer via PrimaryBid.
https://www.stockopedia.com/sh....
It has been acquisitive in the recent past and did a substantial fund raise last October at par so this seems a pretty aggressive buy and build company. Presumably it’s current 60%+ shareholder is onside* and will take their share/potentially underwrite the whole thing. No position but looking.
Gus.
* Edit: Reading into the RNS, the equity raise is fully underwritten by the lead shareholder.
Ig Group (LON:IGG) up 20% on no news??
Just a blip it seems, ignore me.
Paul - thanks for looking at Surface Transforms (LON:SCE)
I did some research on this last week following the Stockslam when David Thornton of SCSW talked of Richard Sneller being a shrewd investor (in relation to Totally). I looked him up and he holds 12.45% of SCE.
There is a useful talk with an analyst about what he calls the transformation from R&D House to volume supplier here.
I think that you, Paul, would be a good person to check out the product (carbon ceramic disc brakes). Perhaps you would like to start with this model which has them fitted.
I enjoyed the Aston Martin video, thank you.
Hi Paul, very interesting reading regarding your comments on freight costs. I wonder how much they will affect SCS figures on 5th Oct? I decided to taken some profits on SCS and leave a few on the table just in case of a shock! I am sure I read somewhere in a previous report from SCS that they were looking at setting up some manufacturing in the UK to combat the issues with high transport costs? We will see...
I shall be looking out for DFS' results soon, to get some idea of the potential direction of SCS' share price...
Dunelm (LON:DNLM) reported good figures recently and few supply issues.
Hi Dieselhead2,
I've got mixed feelings on the current supply chain issues, freight costs & delays, and input cost inflation - these are issues that are now absolutely widespread, even ubiquitous. Also very widely known.
The question is how (if at all) should we be reacting?
These seem temporary issues, that will get resolved, but nobody knows how long. So logically, it shouldn't really affect the valuation of shares very much if at all. The trouble is, so many market participants these days are short-termist, that they do move in & out of shares (thus moving the prices) on short term factors.
So what are we meant to do? Mostly I want to sit tight, and just ride out short term volatility. But the other part of me wants to take some money off the table, so that I have a pot of cash to buy bargains. After all, you can't buy if you're fully invested. Luceco (LON:LUCE) was a good example - I was able to buy a few today around 380p, when it was nearer 500p just a couple of months ago, despite superb interim results. Wobbles over supply chain issues seemed to cause a stampede for the exit amongst short term traders presumably? Or people (understandably) wanting to bank profits on a price that had clearly become over-extended in the circumstances.
I think Volex (LON:VLX) might have seem some read-across selling recently too, maybe?
The other question, is whether companies benefit from, or are hurt from these issues? Car dealers, and James Latham (LON:LTHM) for example, are raking in the profits from supply constraints - if the customer can't buy the product anywhere else, then they'll complain but pay up, if the price rises by 20%, say. There must be other companies in a similar situation - able to raise prices, as smaller, weaker competitors suffer from supply constraints.
It's all very confusing, and difficult to predict. I suspect this could be a time when scuttlebutt could be very useful. So if you have specific industry expertise, do let us know what's going on in your sector here.
Best wishes, Paul.
Paul - on the subject of shortages there is an article worth reading here on the building industry:
https://www.bbc.co.uk/news/uk-...
Paul, I agree about Volex (LON:VLX) Which is similar to Luceco (LON:LUCE), I have sold most of mine and will back if it falls some more. I was thinking of taking some profits in both of those anyway as they were looking a bit high. I’ve also sold out of a few others which have had a good run. I think these supply issues will be around for at least a few months. Halfords (LON:HFD) is another one that has fallen back because of these issues.
Hi Paul, thanks very much for your indepth reply. I believe that at some stage shipping costs will lower, especially if companies start looking for cheaper options such as air freight (if indeed they are cheaper, although air freight companies may well see this as an opportunity to raise their prices too and have a 'piece of the action'. I find it very interesting to try and work out who on the stock market are the beneficiaries of these types of change. It's trying to get there before the 'herd arrives'. On the subject again of SCS and other retailers and in other industries, they won't be able to pass on cost increases immediately to those who have paid deposits I wouldn't have thought, but will probably look to as soon as possible on future orders by adjusting their ticket prices and protecting their margins. Sometimes I have held a share for too long and not taken profits and others I have sold too soon. Hindsight is great of course and it will continue to happen to us all....
All the best Paul.
DH2.
Anyone know why RBG has bounced 6% today on no apparent news please?
Revolution Bars (LON:RBG) (I hold)
I would guess that it's something to do with confirmation over the weekend that no vaccine passports will be required in the near future.
Thanks for covering Sthree (LON:STEM), Jack. I admit to some professional insights within this sector and these results come as no surprise.
Following every economic crash, we see major capital investment in technology, which feeds through into widespread demand for tech expertise, of which there is a structural shortage, both locally and worldwide. Meanwhile the nature of industry’s response to Covid (WFH, automation) has applied a multiplier effect to this already powerful shift. Resource shortages then create spiralling wage inflation - 25% is not unusual for in-demand sectors - and an imperative to increase the proportion of flexible (contract) resources vs permanent hires. To those businesses, like Sthree (LON:STEM), with a relatively high proportion of earnings from contract, this is a powerful driver.
What is misunderstood about technology recruiters is that their business isn’t particularly cyclical. This isn’t Pagegroup (LON:PAGE) or £HAYS where turnover closely mirrors the economic cycle. There’s always a shortage of tech resources everywhere! Always. Rain or shine.
The second point that is misunderstood is that recruiters with a high proportion of contract income are operating with a relatively high degree of visibility of future revenues. Not only is income contracted usually at least 6-12 months into the future, but it comes to resemble (more highly valued) subscription earnings, as contracts are regularly renewed for contract workers for whom there is no alternative resource and who have become “sticky” to client companies as they develop into reservoirs of company know-how. A renewal rate of 70% is typical - without significant additional sales effort.
Sthree (LON:STEM) is far from the “best” technology recruiter. Smaller, more focused boutiques do a better job and have higher margins. But it is the best investment proposition in the sector for the buy and hold investor - by some margin. So the only question is: what is the fair valuation and is there more upside?
Here I would defer to those with more experience in fundamental analysis and the “wisdom” of the market. However, the latter has, I feel, misunderstood the fundamental advantages of Sthree (LON:STEM) over its listed counterparts, and continues to value the shares in line with counterparts - when it should command a premium - but I offer no guarantees that the market will ever wise up. What I can say with confidence is that tech hiring accelerations following economic crashes tend to be 5-10 year affairs, so I would not hesitate to buy at these levels, particularly with the possibility in mind that the market finally wakes up to the superiority of the tech + contract combination.
Thanks BnB - very insightful
I've now parsed this morning's report from Liberum with its 12% upgrade to the price objective. I find their upgraded revenue and EBIT numbers for FY22 and FY23 far too conservative. The broker is modelling growth in gross profit of only 3% pa over the period when I would confidently expect, and the company's own history in the recovery from the GFC points to, sustained growth in double figures for some years. On a less bullish note, I do not count on, and the broker does not anticipate, a material increase in operating leverage. It's simply not part of the business model.
Final point. I should have noted earlier that I am a long-term holder of Sthree (LON:STEM) and Robert Walters (LON:RWA) and backed up the truck for plenty more in March 2020. Despite the healthy gains I am not trimming either. They are no longer a true value proposition but, as my picks from the secular growth market of recruitment, they have potential to run for some time, paying a growing dividend to boot.
Good looking interims from Water Intelligence (LON:WATR) Revenue up 44%
Announcement that one time micro cap “fizz stock” Mobile Streams (LON:MOS) has launched its LiveScore service into Argentina, one of its main revenue sourcing countries during its earlier incarnation under previous management.
https://www.stockopedia.com/sh....
New management seem to be putting a decent business together and have learned several lessons from the past (remittances from this service will come into a U.K. rather than Argentinian bank accounts hopefully avoiding previous problems with exchange controls etc.). Definitely not one for widows and orphans but there are probably worse places to have a speculative mad money punt.
Gus.
Mobile Streams (LON:MOS) I agree. It is definitely not one for widows or orphans but the Live Streams product looks interesting, has been growing quite rapidly and looks like it may just be a decent long term business. This new Live Scores product appears to me to be an entrepreneurial use of previous tech and recent partnerships and if they can do £1m a year on that across Mexico and Argentina then worth having, particularly if there is no currency risk.
At a £7m market cap it is tiny and will be relatively illiquid. I did buy some around .23p but as you say a bit of a mad money punt so quite small size. Not one I'd usually go for but strikes me that the turnaround by the new management and new product appears to have momentum.
Henry Boot (LON:BOOT)
Interims out and they are ahead of expectations. They deliver £18.7mil of profit from continuing operations (£30 mill bottom line after factoring in pension actuarial gain). Per stocky year end expected profit 23 mill.
EPS of 14.1p compared to stocyy year expectations of 16.5p - no idea on weighting here but it looks like they are on for good beat. Note expectations were very modest year so kinda looks like they have been sandbagging - they averaged 30 EPS 2017-2019 so more of a return to the normal that
Net asset value up from 235p to 256p (help by positive pension gaiin)
What i like most about this company is that they seem very conservatively run.
Other points of note.
they have gone from net cash to net debt - i see that as positive for this company as they need to be investing to make their dosh.
ROCE is low - deffo room for improvement here - not sure if its covid related blues in that regard - or whether they simply they arent the fastest at getting a quick bang for their buck - i have them down more as reliable plodders which aint all bad.
· Increased ROCE¹ of 6.3% (June 2020: 2.1%) +4.2% for the six months to 30 June 2021 and EPS grew significantly to 14.1p (June 2020: 4.1p) up 243.9%
Bango (LON:BGO)
Bango have this morning confirmed that the Tier 1 North American customer they mentioned on 7th September is non other than Verizon. Don't know practicably speaking how much revenue and or profits this may help pull in but if nothing else it's a nice tick in the box with regard to the quality of companies they are making deals with - with Verizon i think being top dogs when it comes to wireless telecommunications in the US.
Signed a new, multi-year platform deal with a "Tier1" North American telecommunications company. Under this agreement, the telecoms company will deliver all its third-party subscription offers through the Bango Platform.
13 September, 2021 - Bango (AIM: BGO), the global platform for data-driven
commerce, announces it has signed a platform agreement with US
telecommunications giant Verizon (NYSE: VZ) to power its third-party services,
after a competitive bid process.(1)
Note: Having to post on 'new' Stocko site where my markup doesn't work. So here's the new simplified format for now:
Mgc Pharmaceuticals (LON:MXC) Cambria Automobiles (LON:CAMB) Audioboom (LON:BOOM) Bank Of Georgia (LON:BGEO) Surface Transforms (LON:SCE) Nuformix (LON:NFX) 1spatial (LON:SPA) Diurnal (LON:DNL) Big Technologies (LON:BIG) Batm Advanced Communications (LON:BVC) Diaceutics (LON:DXRX) Tricorn (LON:TCN) Toople (LON:TOOP) Image Scan Holdings (LON:IGE), Iqgeo (LON:IQG), Gaming Realms (LON:GMR)
Thanks for going to the effort - your morning summaries are always appreciated!
Many thanks MrC.
Hopefully the Stocko IT people can resolve this. If they were able to speed the site up to the speed of the old site too that would be great but I won’t hold my breath.
Also many thanks MrC.
Since apparently the old site was unavailable to newer subscribers, there are likely to be many who are unaware how good the old site was. It’s done now but I much preferred the old site and wonder if it was a mistake ditching it and starting a new one (presumably expensive and time consuming) instead of further improving the old site. Not that it needed much improving!
"It’s done now but I much preferred the old site and wonder if it was a mistake ditching it and starting a new one (presumably expensive and time consuming) instead of further improving the old site. Not that it needed much improving!"
I suspect this has been done to death - i think the fans of the old site have been pretty vocal in their opinions so i think its unlikely that the change has been made without realising the full consequences and implications (Ie some bods may stop subscribing or suffer what they percieve is less good service) . I for one was a fan of old site personally but i am aware that running different versions for an over extended period of time probably aint practical - the new site does have some plus points over the old site so i suspect a decent proportion of fans of the old version will accept the change its not as if the powers that be arent trying to improve the service overall on an ongoing basis here.
“I suspect this has been done to death - i think the fans of the old site have been pretty vocal in their opinions…”
Agree, it has been done to death! I imagine they expected people to get used to the new site over time, and eventually prefer it. Well, nearly a year later I still think back to how good the old version was, compared to this. I avoid all the data pages and stockreports now, and get my data and screening elsewhere. The SCVR is the only reason I’m here.
rmillaree
I largely agree with your reply and agree that it’s time to move on and also that the new site is OK overall, and I make use of it and not just the Small Company Reports. Those using Stockopedia only for the SCVR are missing out on a wealth of information. I also realise that Stockopedia made the change with the best of intentions. My problem is that I find it much harder to navigate which probably reflects my competence rather than failings on the new site.
I posted because of the problem superb poster Mr Contrarian had today after having to switch from the old site. Stockopedia staff are incredibly helpful so no doubt will help him sort whatever the problem is.
ken mitchell:
" My problem is that I find it much harder to navigate which probably reflects my competence rather than failings on the new site".
No, it is not just you. There are some better features on the new site but it is the dreadful navigation that has kept me on the old to the bitter end.
I am taking my last look around today at those lovely drop down menus from the top bar. Hover the cursor over and you get a list of your portfolios to choose from. In the new it automatically goes to your first alphabetically and you have o wait for that to load before you can choose the one you want. I'm going to have to rename my main and most-used tomorrow with a 1 in front of it.
As for screens they are no longer in one place - now it is yours in one, gurus in another and when you call up the latter you can't get the complete list in order of performance with an option to look at different time frames.
For newer readers who have been denied access to the old site and for the rest of us for whom this will be just a happy memory from tomorrow this is what I have just described:
I agree about the old site. On folios on the new site you can move them up and down just by dragging into the order you want, on a pc, just left click with the mouse, so the one you want to show first is your main one.
Many simple things missing from the new site and it's much slower.
Xpediator (LON:XPD) run of good form continues I am pleased to read this morning. They've benefitted from Brexit and they seem to have a really good niche in the supply chain with Eastern Europe in particular. Interim results show turnover up to £126.6m (2020 £99.6m) and PBT of £3.6m (2020 £2.1m). Not big margins but EPS up to .66p from H1 loss of 0.25p. I've commented here before that someone will surely acquire them in the future (Wincanton (LON:WIN) announces an acquisition today - its a lot about scale). Can Paul please have a look today if time permits? I hold.
I hold too and would welcome a review from Paul or Jack
Stonking set of results from palm oil producer M P Evans (LON:MPE) this morning.
https://www.investegate.co.uk/...
Double benefit of significant increase in production from recent overhaul of facilities and a significant increase in the underlying commodity price. Also helps that its plantations tend to be pretty remote so COVID doesn’t appear to have been a direct disrupter. Not the wokiest of industries but the company would appear to be at the more progressive end of the palm oil ESG spectrum (if that’s not an oxymoron). Recent holding.
Gus.
Good results out of CLIG, I think, I hold.
In summary EPS 38.8p v 29.5p. Underlying EPS around 48p, eliminating acquisition related costs. Divi 22p v 20p, full year divi 33p. Excellent yield.
Fair value at this price, P/E of 12 puts fair value at £5.75 ish.
A continued Hold for me. Exposure to market height, emerging markets, and inflation (bond investor).
Agree, these are attractive results. The net outflows are a slight worry and hard to disaggregate how of this is pandemic related or due to the merger in some way (e.g. existing clients not liking the merger) - anyone look at fund managers generally and have a feel for whether most of them have had outflows due to pandemic?
The underlying calculation looks OK other than quite a big adjustment of £3.2m for amortisation of acquired intangibles - anyone more knowledgeable on accounts have a view on that one? Is that basically removing from statutory results the wipe out of the previous brand value of the Karpus Investment Management company?
As you say GreyInvestor City Of London Investment (LON:CLIG) is good value: trading around a forward p/e of 10-11 with a 6.3% yield. This is a large holding for me as it's been pretty reliable and the company is very transparent publishing monthly fund under management figures on its website.
Good looking interims from Gaming Realms (LON:GMR)
They appear to now be generating positive free cash flow and profits from operating activities. There should also be more to come as their business expands in the North America.