Small Cap Value Report (Mon 14 Mar 2022) - MORE, CBOX, FNX

Good morning, it's just Paul here today, as Jack's taking some well deserved time off!
Agenda -
Paul's Section:
Hostmore (LON:MORE) (I hold) - my review of the in line figures. Everything looks fine to me, apart from a slightly soft current trading update (LFLs down 3% in first 8 weeks). Forecasts have already factored in increased costs, and there should be good profits coming from new site openings on very attractive rental deals. Looks fully funded to expand with 3 different formats. Very cheap in my opinion. But households might rein in discretionary spending as inflation bites.
Cake Box Holdings (LON:CBOX) - an in line trading update, and sensible management changes are announced. Will shareholders put the accounting/audit problems behind them now, or could the new CFO want to kitchen sink the next numbers? How will institutions (selling) react? Is this going to reassure them, or do they just want out?
Fonix Mobile (LON:FNX) - excellent interim results, with simple, clean numbers, that I can't find any fault in. This looks a decent GARP share, so gets a thumbs up from me. Cash generative, paying decent divis, and growing nicely, with a solid outlook. Also has very sticky, repeating business from established clients. There's lots to like here, as a long-term hold.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Hostmore (LON:MORE) (I hold)
83p (down 10% at 09:10) - market cap £105m
Hostmore plc (the "Company" and, together with its subsidiaries, being the "Group"), the hospitality business focused on American-themed casual dining brand, 'Fridays', and the cocktail-led bar and restaurant brand, '63rd+1st', is pleased to announce its unaudited results for the 53 weeks ended 2 January 2022 ("FY21").
We’ve followed this share closely here at the SCVR, after it demerged from Electra Private Equity. So far, the demerger has been a complete flop. Not because anything is wrong with the company, but because the broker seems to have completely failed to drum up any buying interest in the shares. The £8.1m cost of listing fees look outrageous to me, given the poor result.
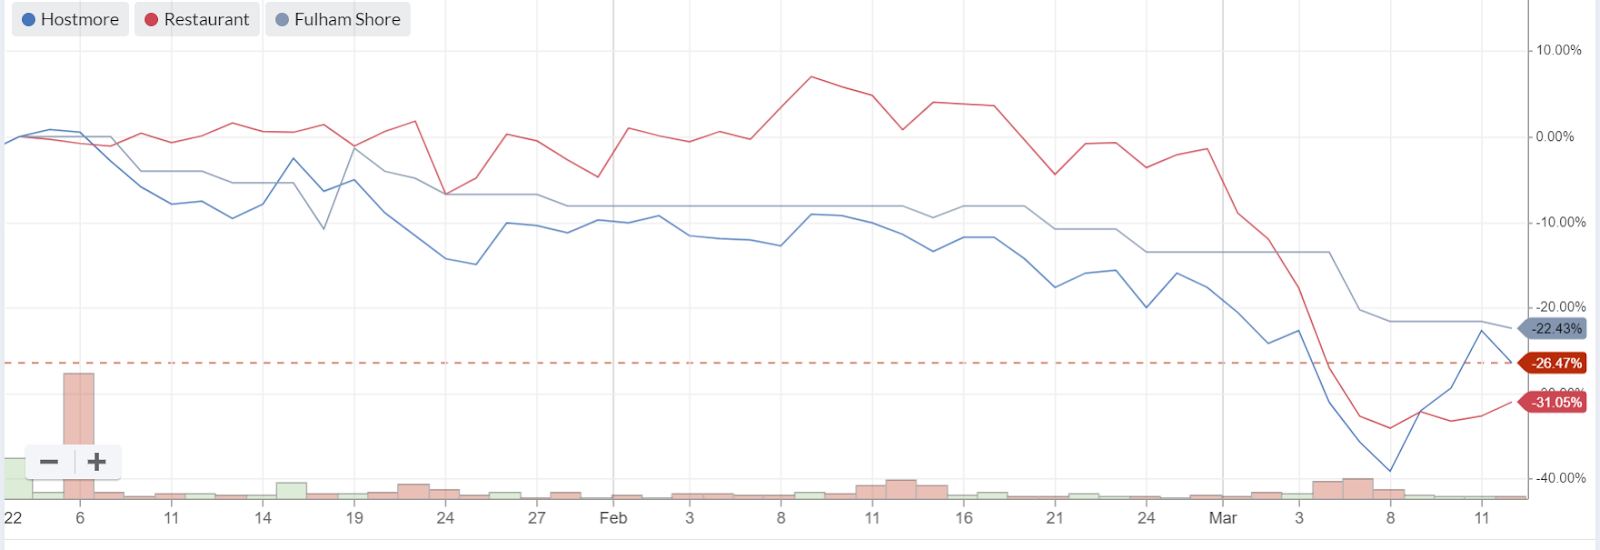
Also to be fair, recent inflation shocks, events in Ukraine, and tightening household budgets/sentiment have hit the sector hard - see comparison chart below with Restaurant (LON:RTN) , Fulham Shore (LON:FUL) , and Various Eateries (LON:VARE) - it’s a little difficult to distinguish the lines, as they cross over, but MORE is the worst, down 31% year-to-date, followed by RTN down 26% YTD, and FUL down 22% YTD.
.
I can see why investors would cool on restaurants at the moment, because it’s discretionary spending for customers. However, we’re not just buying this year’s earnings. We’re buying all future earnings, and consumer discretionary spending goes up & down, but over the long term should rise. So this sell-off could be presenting us with a longer term buying opportunity. I certainly think so, MORE looks very attractively priced to me. Particularly as there's a lot less competition now, and a lot more look set to close down later this year, as Govt support measures end.
I’m trying to type this at the same time as listening to the analyst webinar, which is a struggle!
FY 12/2021 was a highly disrupted year, due to the pandemic - little to no trading in the 4-5 months up to May 2021, partially offset with Govt support measures, e.g. furlough, reduced VAT, business rates relief, and negotiated landlord support.
Some numbers -
Revenues £159m (similar to Edison forecast of £160m). Important to note that revenue is forecast to rise to £242m in FY 12/2022, assuming restaurants can trade normally.
Adj EBITDA (pre IFRS 16) is £21.5m, which seems to be £1m ahead of the Edison forecast I’m looking at of £20.5m
Adj EPS is 6.4p. Edison doesn’t seem to have worked out an adj EPS forecast, so I’m not sure how that compares.
Net debt of £12.2m is much lower than I was expecting, and has risen a bit to £13.2m by 27 Feb 2022.
Like-for-like revenues were up 4% on pre-pandemic (2019) trading, from re-opening in May 2021
Current trading - a bit disappointing, down 3% on pre-pandemic, for first 8 weeks of 2022
New sites - 4 opened in 2021, 6 targeted in 2022. Lots of opportunities, especially when rent moratorium ends shortly (total sites currently 88 operating)
Substantial bank facility of £65m agreed in July 2021 through to Oct 2023 - loads of headroom, with net debt at only £12.2m
Free cashflow strikingly high at £31m
Growth to come from new sites, and potentially small acquisitions (small disrupter brands, which don’t have capital to expand on their own - seeing opportunities here)
Positive outlook despite cost headwinds
Energy costs hedged, and food/beverage largely contracted for 2022 - so should cope better with cost increases than competition. Not planning to raise prices much when VAT returns to 20% - good, because I think the prices are too high already.
Edison forecast is 10.7p for FY 12/2022 - giving a PER of only 7.8 - seems abnormally low, maybe the market doesn’t believe the current forecast? Mgt confirmed in analyst call today that the increased costs are already factored into forecasts
InvestorMeetCompany webinar is at noon today
Fridays & Go - a new concept being trialled (small site, takeaway, a bit like a posh MacDonalds) - first site opens this week in Dundee - one to watch
Intention to pay divis in future
One-off stock market listing fees of £8.1m, main reason for a statutory loss of £1.6m in FY 12/2021
Balance sheet - management keep saying how strong it is, but I would say it’s OK, rather than strong. NAV £125m, less goodwill of £146m, gives negative NTAV of £(21)m. This deficit is caused by the lease entries, which are net £(34.6)m. It’s the usual IFRS 16 nonsense, to I tend to remove these entries, which moves NTAV positive, to £13.6m - not much, but adequate.
A couple of useful points from the analyst call -
£5m of the RCF paid off today from the substantial cash pile
New sites - deals have to be good. Expecting lots more new sites from end March when multiple negatives hit the sector: rent moratorium ends, VAT & Business Rates return to normal, Living Wage increases. All factored into existing forecasts.
New site deals agreed for FY22 so far have rents of 4.9% of expected revenues. Compares very well with >10% pre-pandemic. Not paying lease premiums either, and expect a significant landlord contribution towards fit-out, plus a rent-free. Landlords favour TGIs as a new tenant because of the collaborative way they handled the pandemic. So in a very strong position, and have loads of liquidity available for expansion.
Net debt has reduced due to strong cashflows. Expect it to come down modestly, but main focus now on capex/expansion, and also some remaining stretched creditors re rents will be paid.
My opinion - the fundamentals look excellent to me. This is a good business, generating strong cashflows, and has very good expansion opportunities ahead, and the funding in place to do it.
Hence if we look beyond the poor sentiment around this share, and the very modest valuation, I remain of the opinion that it’s an excellent buying opportunity.
We all have our views on the brand, etc, but the fact is that the business is strongly cash generative, so our views don't really matter. It's money in the till that matters.
Who knows how long it will take for the stock market to digest the overhang of shares? As long as the fundamentals remain strong, it’s just a question of waiting.
The downside risks are obviously sector-wide macro risks of consumers reining in discretionary spending as higher heating bills, and general price inflation take a chunk out of household real incomes, in the short term.
.
Cake Box Holdings (LON:CBOX)
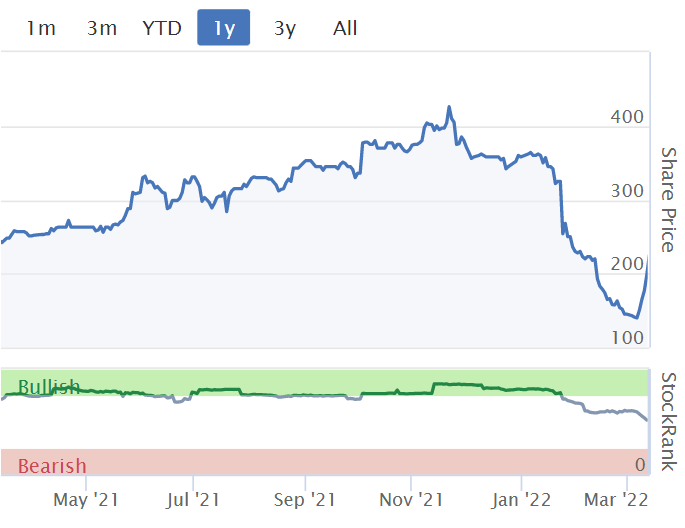
225p (up c.13%, at 10:45) - market cap £90m
Management Changes & Trading Update
Cake Box, the specialist retailer of fresh cream cakes, today announces various Board and executive management changes, alongside a short trading update ahead of the end of its financial year to 31 March 2022.
Trading update - this sounds reassuring -
Trading has continued strongly throughout the second half of the financial year to date, and the Board expects performance for the full year to be in line with expectations.
It sounds like the company is taking positive steps to repair its reputation, after some pretty disastrous negatives last year - leading to the auditor resigning, and departing with a scathing resignation letter. Amazingly, the market didn’t seem to notice, until Maynard Paton wrote an excellent article flagging this and other issues.
There was also the matter of the co-founder/CFO disposing of a large personal shareholding just before the auditor resigned.
Anyway, he’s (Pardip Dass) gone now, and not before time.
David Firth becomes Interim CFO - I’ve not come across him before, but his potted CV looks impressive. Have any readers come across him?
A new COO is also appointed.
Previously announced, BDO was appointed internal auditor to improve processes, in Aug 2021 (that won’t be cheap).
My opinion - these steps look very good, and should start to improve the company’s shattered reputation.
I’ve got 2 worries - firstly that the institutional shareholders, most of whom seem to be sellers, might use the share price recovery to accelerate their exit. Or they might be reassured, and stop selling. We don’t know.
Secondly, that the new finance head might discover a can of worms, and want to do a kitchen sink job on the next set of numbers.
Or it might all blow over, and the shares recover. Who knows?
Prior to the accounting issues emerging, I did like this business, but thought it got too expensive.
Now it looks cheap, but I’m scared off by the accounting problems!
.
.
Fonix Mobile (LON:FNX)
155p (up 4% at 14:13) - market cap £154m
Fonix, the UK focused mobile payments and messaging company, is pleased to announce its unaudited interim results for the six months to 31 December 2021 (the "Period").
Strong gross profit and earnings growth, in line with recently upgraded expectations
I’m impressed with these numbers. Fonix floated on AIM in Oct 2020, and amazingly for a fairly recent float, it has not collapsed after a profit warning, nor run out of money!
I remember having a video call with the CEO around the time it floated, and thinking what an impressive business this is - dominating a niche of payments/votes for reality and charity TV shows (e.g. X-Factor, Children In Need), Fonix has the infrastructure for taking those payments/votes, and the customers tend to be very sticky, coming back year after year - on the basis of if it ain’t broke, don’t fix it.
That results in a cash generative business, with high margins, which is able to pay out decent divis, with a yield of c.4%.
I was a bit worried about the longevity of its services, but the commentary today talks about good new contract wins. The figures show a strongly convincing growth track record too.
EPS has progressed as follows (June year ends) -
H1 2020: 2.9p
H1 2021: 3.6p
H1 2022: 4.4p
Can’t argue with that.
Revenues in H1 2022 are up 16.2% to £28.6m
Adj Profit Before Tax is up 20.3% to £5.2m. Very nice numbers.
Amazingly it says over 99% of income is of a repeating nature.
100% platform uptime is claimed, absolutely vital for a business of this kind - if its systems fall over at peak times, then it wouldn’t be long before customers leave.
Divis - there’s a 2p interim divi, with a policy to pay out 75% of adjusted earnings, with a forecast yield of about 4.4%
Outlook comments sound confident -
We have continued to make great progress on our strategic goals in the period, with growth ahead of management's initial expectations and the business is showing strong momentum going into the second half of the year. As was the case last year, we're expecting the first half of the financial year to be slightly larger due to some seasonality in the trade of our customers, however the underlying run-rate remains strong.
In line with our growth strategy, we continue to invest more in future growth, with increased spend on sales and marketing, along with further investment in both product and international reach, as we look to deliver sustainable, highly profitable growth for our shareholders.
The company's new business pipeline continues to grow strongly, including several significant enterprise deals in the UK and internationally, which provide the Board with confidence in the ongoing success of the business.
Ukraine - no specific risks for Fonix, other than impact on the UK economy generally.
Balance sheet - capital-light with only £5.2m NTAV, and hardly any fixed assets.
An unusual feature is very high receivables, and offsetting high trade payables. From memory, I queried this with management a while ago, and it’s something to do with being owed large amounts from payment processors, which are then passed on to customers by settling the payables. It might be worth someone querying that with the company again, just to be sure I remembered correctly.
There’s a very healthy net cash float of £23.6m, and no debt. The cash is mostly customers’ cash, which is passing through.
My opinion - what a smashing set of numbers, I’ve enjoyed reviewing this, so thank you to the readers who gave me a prompt to look at it.
I’d classify this as a GARP share (growth at reasonable price).
The talk about international growth is encouraging too, giving much larger total addressable market size.
Overall, Fonix gets a thumbs up from me, delivering decent interims, with a solid outlook, and at a price that I think can be justified.
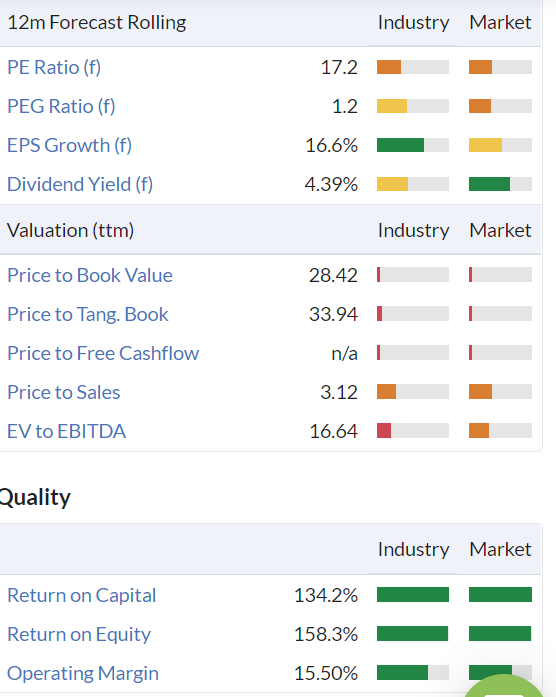
It seems to me that the StockRank system is being a bit stingy with a rating of 57 -

.
Very high quality scores on the growth & value section, as you can see -
.
.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

77 comments
Just for clarity, I bought a small initial holding this morning. I've been watching Tracsis for some time, but looking for reduction in the share price, given the wide spread.
Tracsis announced the purchase of US rail tech firm RailComm which is in the same tech space as the company. Probably outside your preferred area Paul, but any thoughts would be welcome.
Covid rates in Hong Kong are something else.
If this spreads, and China is sticking with zero covid then this could have far reaching consequences. Numerous cycles of absolute lockdown/reopening are bound to effect supply chains/inflation.
I listened to the Investor Meet Presentation today with Hostmore (LON:MORE) and I thought the CEO and CFO did a good job and I felt they were both very much on the ball.
Some points I picked up in no particular order.
Rent to Revenue in 2022 on New Sites 4.9% compared to 11.9% on Old Sites.
Table Top Order & Pay at Table a big success. Driving up spend per customer.
Outdoor Dining could be very popular if we get a good Summer and CEO thinks this strategy will prove popular.
100% Tips go to Staff. I like that.
Head Chefs have all been on Training Course with good results.
The Estate is very new overall so no major CAPEX.
Net Debt to EBITDA 0.3X
April will mark bail out time for many operators as Paul has mentioned.
I hold but 44% down!
thanks for the summary. I like the look of hostmore but the trust pilot reviews are awful.
would be great to hear from the company how they are addressing , was maybe covered on investor meet ?
Hostmore (LON:MORE)
Would love some clarification from Paul or anyone cleverer than me ref the quoted free cashflow number of £31 mill.
Seems clear to me that to arrive at the £30.6 mill quoted free cashflow they need to add back £13.6 mill of "finance expenses" as if they dont exist.
If these finance payments are quasi "lease related costs " as appears to be the case for the majority of the total (£10.1 mill of £13.6 mill) - it just seems plain silly to quote a number than ignores this cost with out caveating up that fact. Ref EBITDA Paul has sensibly used the lower pre IFRS number here so as not to confuse.
Must admit though i have a low expectation that the £13 mill should taken back out as its all as clear as mud but i am defaulting to that being the case until someone can evidence its not a real "rent related cost to the business" .
Shanghai authorities starting various inner district lockdowns where Omicron cases pop up. Lockdowns last for 14 days.
As if war, soaring inflation, sky high energy prices, large food price increases and supply chain problems arent enough our old friend covid seems to be popping up again in Europe and China.
Shenzhen lockdown until March 20th - population 17.5m- huge container port and export hub. Zero covid looks a dead end for China.
So many moving parts just now its difficult to keep a clear head and tip toe through the potential land mines everywhere. One thing im definitely not doing is buying anything for the long term and ignoring price declines, can easily see a scenario where Europe slips into recession and 30-50% more wiped off already flattened prices. A real savage bear market will come back to maul investors a second or third time, so for me personally any buys need an escape plan just to be safe.
Same boat....only spread betting at moment taking a very short term view and locking profits with a tight stop loss...cant look beyond today IMO.
Whilst not running to invest more I am keeping everything I have today on the basis they are companies growing and heading in the right direction. I do not want to try and time the market as I will inevitably fail. whilst you scenario is very possible there's also one which Putin - Ukraine find some middle path they can both live with, supply issues improve and COVID continues to become milder and we see a few years of steady but unspectacular growth.
I am not as pessimistic as you, but I agree it’s nuts at the moment to invest in any stock with poor liquidity . Have cut my portfolio by half and all now are easy to trade
I agree Caper. I have some long term holds but anything new has a stop on it, and only liquid shares.
I was buying a few showing momentum/volume changes at the end of last week, think the US markets are forming a base for a rally in the short term. Just my gut feeling based on sentiment and fear, so who knows. There does at last seem to be some institutions stepping in and buying on selected companies in the UK.
If a rally does come I'll use it to rejig my portfolio and move to more cash, not get sucked in. Dont want to spend the summer lull (tho maybe not this year?) fully invested.
The market is starting to think this latest COVID "wave" in China might be more serious than previous ones. Vaccine shares like Moderna are up quite a bit today, and CSI300 Index down quite a bit.
Hostmore (LON:MORE)
I would take that free cash flow figure with a great big dollop of salt and other condiments - may at least make the food taste better.
Free cash flow apparently - £31m
Change in Net Debt - £16.6m
£15m seems the number to me vs £31m pretended! Let them off for their ridiculous IPO costs, but 13m raised at IPO.
My simple brain makes that free cash flow of 2m (or 10m allowing for IPO costs), which was about as overpriced as their food. Oh & free cash flow should deduct more than just maintenance CapEx, but I am one of those have fun staying poor types!
Don't hold - cheap for a reason as far as I am concerned and management either don't know what free cash flow is or choose to fudge.
Much better ways to lose my money I think
You need to read accounts a bit more carefully ;)
Irrespective of whether someone thinks the shares are good value or not they reduced net debt by £16m, spent £5m on new store capex and reduced lease liabilities by £11m
This is the FCF use of £32m
It looks like their free cash flow figure is excluding lease payments - i.e., the rent on restaurants.
If so, while being technically correct, it is meaningless number. This FCF figure is like a 'free cash flow to enterprise' figure, from which you need to take out lease payments and other finance payments to end up to a 'free cash flow to equity' figure, which is the only figure any of us will actually care about.
Not to mention the use of 'maintenance capex' to determine free cash flow. A more or less aggressive management team, depending on how they want to present the numbers, can say whatever they want about what is 'maintenance' and what is 'growth'. It's highly discretionary.
As is often the case, when a company makes a statutory loss but quotes an incredibly high FCF number, it is the statutory loss figure which (in my view) paints a fairer picture of reality.
So you agree that the free cash flow is not £32m ;)
I should perhaps read more carefully but tired numbers on a tired brand - have better things to do with my time.
If the "real" free cash is anywhere near 32m, I am happy to be corrected. If holders (potential holders) take a 2nd look on the back of my comment and find that this trendy, fast growing chain with positive competitive backdrop is available at 3x free cash, by all means back the truck up.
Wish you all the very best!
Heavens above you lot don't do much research do you?
£MORE
In this regard thats 3 separate posters as far as i can see - being me , Vsihv and ExpectingValue who seem to think the £32 mill is simply an illusion as it seems to exlude what is practicably speaking some (or all?) of the rent payments - which would make quoting the figure as useful fact nonsensical. Are you still standing by the fact that the £31 mill is real cashflow and includes a fair deduction for "rent due" for the year ?
I am happy to email the company for clarification if you are sticking to your guns on this one.
There is the thought that perhaps recent IPO's should be given a wide berth till a few results under their belt, maybe even a year or two.
Personally eating out will take some time to readjust - not scared of the bug but just happier cooking at home and not having to go out in the cold. The youf however are of a different disposition - as long as getting funded.
Hi Paul, I'm a big mystery shopper of Friday's and I really think they are getting most things right. The new shop model which is quite different from the old traditional one is a big plus in my opinion and the last few visits by us Milton Keynes and now Speke they were very full and staff are generally excellent and cheerful.
Somewhat surprised by the muted reaction on Alphawave Ip (LON:AWE) this morning. Bought OpenFive business unit in US for $210m expanding their customer base from 20 to 75 (mainly in North America) and earnings accretive.
Revenues for 23 are now expected at $325m-360m with ebitda margins of 32-26%
move out a year and they expect $500m at 40-45% ebitda margins.
So for an IP business generating say $200m of ebitda in 18 months time we currently have a market cap of £1bn which seems eyewateringly low as a valuation (given they have a bout $200m left in net cash too). These IP type businesses normally trade on 20 to 40* earnings. The customer base is now well diversified with much of it in North America and South Korea so the whole debate/short attack re potential for connected party sales in the China JV seems pretty moot.
Share price still trading at lows though so market obviously doesn't believe either the story or the numbers I guess.
I think long only investors view Alphawave Ip (LON:AWE) as a "show me" stock since the short report. It's been very profitable for traders in the 160 - 200 channel. Time for everyone to buy is when I "turn trader" and sell at 200 - that'll be the cue for a positive re-rating. Alternatively we have to wait for the next release of numbers which cannot be far off.
One point to note, reading the RNS carefully, £500m revenues are due in FY25, not FY24, which has potential to close at that run rate, ie not the same as achieving it within the year. Even so, price would prove very attractive today if those levels are met.
yes - agreed. Annualised run rate of $500m for FY24 but nonetheless price looks bizarre. Even on this years earnings it's about 8 or 9* earnings cash adjusted. Let's see the numbers I guess.
I agree with BnB. Alphawave Ip (LON:AWE) is on my bargepole list until we can see a clear refutation of the short report accusations. In particular we needs some clarity on how much of their revenue is genuine and not derived from related party transactions.
I don't mean to be rude but if you had listened to any of the presentations since the short report you would know this. At H1 stage none of the revenue was attributed to Verisilicon or CPP. You have clarity, you just haven't listened.
One of the things I quite admire (in a perverse way) of short attacks is their ability to convince investors there is something wrong without offering any real proof. It is highly effective for the shorter and quite long lived. It's probably manipulation but it's clever.
Btw there is also nothing necessarily wrong with a JV where directors have some connection to each other as long as it is disclosed. Particularly when the JV is with another business that is well known in the market in which they operate and has several billion in revenues already. It doesn't make the revenue less genuine! But these days throw mud and it will stick.
I agree with BnB. Alphawave Ip (LON:AWE) is on my bargepole list
To be clear - I own AWE. I just recognise that the market is waiting for more data. Possibly with good reason.
The conference call today has added more colour and FY21 results are due out within a month or so.
Alphawave Ip (LON:AWE)
Somewhat surprised by the muted reaction on Alphawave Ip (LON:AWE) this morning.
Is it me or have they provided no details of the financials of the buisness being acquired - i can expect the market reaction to be somewhat muted AT BEST if they are splashing out $210 mill cash without providing any financial info for what they are buying - apologies if info is there and i have missed it.,
As a company that has been accused directly of being somewhat less than kosher in the past i would have expected they would go out the way to provide some flesh on the bones ref history of what they are buying !!!!
I think Restaurant Group issue finals on Wednesday, they may have some interesting input.
"I can see why investors would cool on restaurants at the moment, because it’s discretionary spending for customers. However, we’re not just buying this year’s earnings. We’re buying all future earnings, and consumer discretionary spending goes up & down, but over the long term should rise."
I think historically this is correct Paul but a question mark does arise around food inflation depending on the outcome of the Russia / Ukraine debacle. They both account for around 30% of wheat production. Food service outlets will have to focus on prices closely if this is a prolonged war, and even if it isn't it is possible that Putin realises he is sitting on a significant amount of the worlds food (which might be why he invaded in the first place). So costs may remain high longer term, but definately there will be a shortage this year. So that is the supply side add your demand side concern and I think this sector will struggle. Just my thoughts and concerns.
Not only wheat is going to be more expensive but fertilizer has jumped up in price by 3x according to some reports, so food prices will all be increasing plus there is the gas price rise which some producers use for food production. There are still shortages of workers in farming and abattoirs, apparently it is just as bad as last year, this is partly due to Brexit, many workers went back to Eastern Europe but now can't return due to immigration rules. Haulage drivers also still an issue. Of course the Govt. could allow more Ukrainians in, which may help with some staff shortages.
If there is a recession, which I think is likely, then I would not want to be invested in restaurants, some of those won't survive a recession after Covid.
Hi Camtab,
Fair points, thanks.
In the analyst call, management said food price inflation is currently rising 5-6%, and they mentioned additional pressures re wheat & cooking oil, as you mentioned. Shouldn't be a problem in 2022, because they've got contractually agreed pricing on most food. Also the hedging energy prices is looking very smart.
Another point to consider is that the gross margin is very high, reported at 80% for FY 12/2021. So higher costs for food ingredients doesn't make a great deal of difference to the bottom line.
I wonder what choices households will make this year? The TV news always focus on the element of the population who live hand to mouth. However, about 60% of the population are middle class, and have much more liquidity than this - with savings, and credit cards, who therefore have considerable flexibility with disposable income. That type of household might be perfectly happy to continue existing spending patterns, and accept that they might have less surplus at the end of the month, and run down savings somewhat, or put some spending onto credit cards.
Also this year's high inflation could become next year's reduced inflation, once it annualises. That's what's happened before, e.g. after the Brexit vote triggered a jump to 5% inflation, which then subsided when it annualised. I don't think we should necessarily take temporary factors now, and extrapolate them out indefinitely.
There are so many moving parts, nobody knows what's going to happen, but it's looking very likely that high inflation is likely to be around until some point in 2023, when it might moderate as supply chains improve in many areas, which is what the shipping companies are saying is likely.
Who knows what the oil/energy prices are going to do? They're so volatile.
Also, with real wages now declining, surely that reduces the need for central banks to hike interest rates as aggressively as they might have planned? If demand is already coming out of the economy due to inflation, then they could argue the case to moderate interest rate rises, anticipating reduced demand and hence prices on many things normalising (as supply chains settle down).
Who knows?!
Regards, Paul.
P.S. Thinking about the (known) sledgehammers that are about to hit retailers/hospitality, it's likely that we'll see an imminent, very large, reduction in capacity - as zombie companies finally throw in the towel. There must be thousands of smaller restaurant operators who won't be able to cope with this lot - all hitting them simultaneously in just over 2 weeks -
Business rates going up
Reduced VAT going up from 12.5% to 20.0% on food & soft drinks
Minimum Wage going up c.6.5% (from memory)
Rent moratorium ending - this has effectively made it optional for companies to pay rent on commercial properties. I wonder how many premises will now be repossessed by landlords?
MORE reckon that something like 10-15% of the restaurant market has disappeared during the pandemic. It seems to me that the above list could push large numbers of restaurants out of business.
That then leaves well-financed, expanding operators like MORE with many opportunities to take on new sites, often fitted out already (so less capex than a shell), and on highly attractive rents (as mentioned above).
Hence tough macro conditions, but much more market share potentially for the operators that survive & can expand.
In previous recessions I've noticed that the retail/hospitality chains that can expand in a recession, often end up the big winners when conditions improve afterwards. That's one of the reasons I like MORE - looking beyond just the next say 12 months. Stock markets seem currently to focus entirely on the short term, which could be presenting us with some smashing longer term value.
Thanks Paul, whilst not totally agreeing I can see the points you make and appreciate of course none of us really know how it will work out anyway. The only question mark I would raise is I wonder how much wheat will be produced if any this year in Ukraine? Seeing how indiscriminate the bombing is I suspect very little which will lead to a real issue come September/October time. I sometimes think in the West we get it the wrong way round. We have money ergo all will be well, but if that money can't buy food, minerals etc it becomes pretty useless and in that sense Putin is in quite a strong position. Not a complete argument, because there is not the time nor the inclination but I hope it makes a point for thought for some.
Ive eaten out a fair bit the last week in Manchester and Leicester. None of the eateries covered here. I've been impressed with the professionalism of the various restraints we've visited - but maybe you have to be professional to survive. What is a shock is the cost - eating out is no longer cheap, especially if you want a bottle of wine or a few beers too.
I never eat in any restaurant unless they accept corkage as my wine is better than the restaurant and a hell of a lot cheaper, including any corkage charge !!
SCVR seems very quiet at the moment. Has everyone given up?
Give me a chance to get some sections up, to stimulate debate hopefully! My keyboard is glowing red hot as we speak :-)
No criticism Paul - the content here is excellent. My vibe is that a lot of folks have thrown in the towel after recent losses. Long termers should stick to their knitting IMHO and wait for the recovery; although there's plenty of scope for things to get worse before they get better, they will get better at some point.
Things seeming quiet is healthy given the volatile state of the market. Most seasoned (ie old) investors know that during turmoil the best thing to do is sit on your hands and stop staring at your computer screen.
Hostmore (LON:MORE)
Very interested to the read Paul's take on these results as they look good to me from an initial review.
I may well have misinterpreted this, but it seems that IRFS16 has actually resulted in a favourable outcome for Hostmore - they made a profit but were pushed into a statutory loss due to IRFS16, which in turn has resulted in a tax credit.
That's a good point, I forgot to mention that Hostmore (LON:MORE) (I hold) had an abnormally low tax charge, but didn't look into why. It might also be due to the £8.1m listing costs being tax deductible, but a one-off?
Skimming through the results this morning for £MORE I felt that everything was looking good until I got to the 3% drop in LFL compared to 2019. It seems this may have spooked some people as my take having listened to a couple of interviews with new management is that they are highly experienced, very capable and have an excellent track-record in this type of business. Some of their ideas for the future look to be very interesting.
Hopefully the LFL is a temp and easily recoverable position, but a slow down in the economy is a concern as obviously eating out is a discretionary choice and with inflation reaching highs, with the knock-on to food and fuel bills you can easily see the brakes coming on the economy in the next few months.
I remain optimistic though and hope for a short-term end to the Ukraine issues and a recovery in markets with the inflation issues washing through quicker than anticipated. Might be wishful thinking, but I remain positive. I hold.
£MORE Getting a tax credit due to a loss is NOT a favourable outcome! Profit would be better!
Morning Paul, hope you had a good and stress free weekend. Two shares on the radar this morning.
The first Fonix Mobile (LON:FNX) which is a mobile payments and messaging service. Its shown 16% increase in revenue for the last 6 months with bullish comments around new customers and international expansion. I hold and continue to feel this company has room to grow.
The next one Hostmore (LON:MORE) which I am sure is on your radar to take a look at today. It seems to be recovering nicely from the pandemic with strong cash generation. I hold and expect a re-rating over time.
Fonix Mobile (LON:FNX) tipped at the weekend in SCSW.
The author claims they have never lost a customer and that expansion into Europe is to commence soon.
Hi Brookeda,
Yes indeed, I'm focusing on Hostmore (LON:MORE) (I hold) at the moment, just about to start typing up my notes.
After that, I'll look briefly at Cake Box Holdings (LON:CBOX) , then Fonix Mobile (LON:FNX)
Nightcap & Craneware are possibilities after that.
Regards, Paul.
Had an interesting talk yesterday with a friend of mine who owns one of Sheffield’s design agencies who also have their own workshop for their hotel / restaurant / shop fit projects .
He was telling me many of the basic materials are simply not available , or if they are prices are currently so high that projects now cannot proceed .
Example birch ply (cones from Russia ?) is no longer available , basic plasterboard is on 2 month leadtime with a 5 fold increase in price and suppliers insisting on payment on order and huge MOQ .
This is starting to cause sone real issues and any company with aggressive rollout / shop fits / building work is going to have their build costs escalate and fall behind schedule .
Said he had never seen anything like it except in the frenzy that was early days procurement of PPE .
Not sure how the likes of Howdens / Travis Perkins etc will be affected , maybe some spike in short term profits as margins of current inventory spikes ?
I did not know that birch ply came from Russia, I thought most was from Finland.
Not sure myself but it’s certainly hard to get !
google is your friend
“Baltic Birch Plywood is a plywood built using a specific method. It comes from Russia and the nearby Baltic states. “
Am more concerned about everyday essentials - wheat and fuels. Birch ply is top end stuff that's always been expensive - four times more than 'ordinary' ply.
I thought finland / latvia / estonia.
and there were reports of a strike in Finland - UPM one of the biggest wood cos is on strike.
I was looking at UPM, I did not know about the strike.
I was at the supermarket yesterday and saw that there was a limit on sunflower oil to two bottles per shopper due to reduced supplies due to the Ukraine war.
I didn't realise they harvested sunflowers seeds in March.
I assume people are panic buying ahead of what they feel will be shortages in the future? Or with modern supply chains a lot of the stock is kept over there?
There are shortages of some foods, I went to Aldi and Morrisons last week, no frozen Salmon or Tuna in Aldi, I got the last Salmon packet in Morrisons. Morrison none of their own brand of wholemeal bread. Not sure why frozen fish is out of stock. I thought there maybe shortages of flour but ok at the moment.
A lot of breaded fish comes from Russia - even if that’s not the stuff we eat in the UK, substitution effect in other countries will cause a shortage here
I see but it’s not breaded, just salmon and Tuna. white fish which is used in processed food is normal supply.
I’m reading it could be to do the recent storms and staff shortages.
Your focus on two types of fish is you trying to force data out of an anecdote. Any given week of the year something will be in short supply. It just so happens the thing this week is something you want to buy. You're making a mountain out of molehill.
If the products in short supply become widespread then it'll be obvious there is a wider problem.
No hard data from me either, but it has seemed clear to me for quite a few months that there are continually some (changing) gaps on the the supermarket shelves. Presumably more a general supply chain. border delays, Brexit, lorry driver shortage issues rather than specific Russian problems. But that's another one so things aren't likely to improve. Let's not feel sorry for ourselves though - it's going to be far worse in many other countries.
Who is making a mountain? I'm just reporting my experience, if anyone is making mountains it is you. Salmon has been an issue for some time now, over a month, I had to buy another product a month ago. Supply chain has been pretty good for over a year until recently, I'm finding stock missing and I expect this to get worse once sanctions have an effect on Russian supplies and prices.
Never mind salmon - I'm struggling to get hold of the beluga caviar that I like to have for breakfast each morning!
My Aunt was v. posh. She would have canapes at 11 on christmas day. The first plate was beluga with a bottle of pol roger wrapped in a cold wet tea towel that I (aged 7) poured out. One year I looked at the label on the third bottle (wrapped in a tea towel) - it was a Cremant. She said "after 3 glasses they never notice and the caviar is just ordinary after the first plate". She was right.
Morning planetx,
Interesting comments from you about building products in short supply.
Last week Sig (LON:SHI) said things were easing -
In the near-term we are anticipating some remaining impact from material shortages, but these are gradually abating...
They seem to focus on selling insulation & roofing products.
Also, I wonder if shortages of products such as the birch ply you mention, could be adapted by substitution for a different product that doesn't come from Russia/Baltics?
People & companies tend to find workarounds for any supply shortages, over time. But as you say, this could be another thing that causes short term disruption.
Anyway, interesting scuttlebutt, thanks for posting!
Regards, Paul.
Paul, but was the Sig (LON:SHI), statement based on information before the Ukraine invasion? China is locking quite a few areas due to Covid which may have effects on supplies.
"Paul, but was the Sig (LON:SHI), statement based on information before the Ukraine invasion?"
No, it was a statement released last Friday, so 11 March 2022.
P.
OK but that may well change in the next few months.
Paul
Your probably right but on a 0-6 month timescale I don’t see how new supply can come online , he also said he had a similar conversation with a leading Sheffield developer who had simply decided to mothball all projects for 12 months .
I’m also not sure if there are credible alternatives for birch ply (his preferred fabrication material ) and standard
I think 2 things will happen
- projects already started will fall behind and have increased cost in materials and increased costs in delays (guys stood around waiting for materials is a nightmare )
- new projects unless absolutely gut busting essential will get put on the back burner .
From an investment perspective you have probably hit the mail on the head , the company that can produce the product or already produces the product that can fix the issue takes the biscuit (or something like that ) .
I’ll ask him just out of interest what are the actual alternatives .
Interesting. I think the second order of these effects will be contractors going bust (where they can't pass on price increases or win new work) and reduced client budgets where the increases can be passed on. In that vein and given the current ever increasing and persistent nature of construction material inflation I'd envision that total construction material volume could take a bit of a hit over the next few years. For example if a social housing body had a budget of £10m for 33 houses and material, labour and plant increases add 10-20% to costs then we could see a scenario where 27 -30 houses are built instead.
Building supplies (and cooking) are essentially commodities - not just oil gas gold nickel etc, always in the news - now we hear about vegetable oils, grains, plywood, gypsum, cement - all the boring cheap as chips reliable easily available or were - steel a big one (reinforcement, beams, most of construction has something even your house).
Let's hope this is the 'toilet roll' issue from early days but costs will rise across the board for commodities. Revenue does not always equal earnings unless they can pass it on = inflation. Cost to build the house, cost to buy the house, increased mortgage deposit and higher interest rate to buy the house. Back to property as the hedge on inflation, unfortunately likely to become a societal issue at some point.
I'm thinking Berkshire Hatherway and Amazon (before they split the share). Construction, food, cake etc will watch with interest.
"Back to property as the hedge on inflation, unfortunately likely to become a societal issue at some point."
Already is an issue. Rent+utilities is close to 50% of income for young adults add food inflation greatest for basics, NI charges etc and who would want to be in their 20s (financially speaking!!). I have a 19 and 21 year old and see their coping mechanisms - I think gyms will do OK as for £25/mnth you have a place to go and activity to get you out from your tiny room share/parents house! It is a shame we cannot invest in food banks as these will be another "winner' in the next year
In contrast, the best situated are the top 50% rich, elderly on inflation adjusted pensions who have paid for their houses and are seeing rapid capital appreciation. Even energy inflation is less of an issue for them in truth since they can afford to pay for/already have good insulation and solar panels etc. At worst, they can choose to downsize, pocketing a huge capital amount. Unlike the young they have also saved over P2Yr because Covid has kept them home. We need businesses whose core audience are the affluent over 70s.
So go Saga (LON:SAGA) and £UBG (Disc I hold)
Amusing that Cake Box Holdings CBOX is replacing its CFO despite largely dismissing the accounts' critique by Maynard Paton, whom it described as a "retail blogger".
Maynard's blog (on his portfolio etc) is very good and well worth reading. I took a look at the weekend.