Small Cap Value Report (Mon 15 April 2024) - SAA, RNO, ASHM, KRM, IES, POLR, MTO, EXR, HZM

Good morning from Paul & Graham!
Today's report is now finished.
The Week Ahead series - today's article is from Mark.
Mello Monday is tonight - details here.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
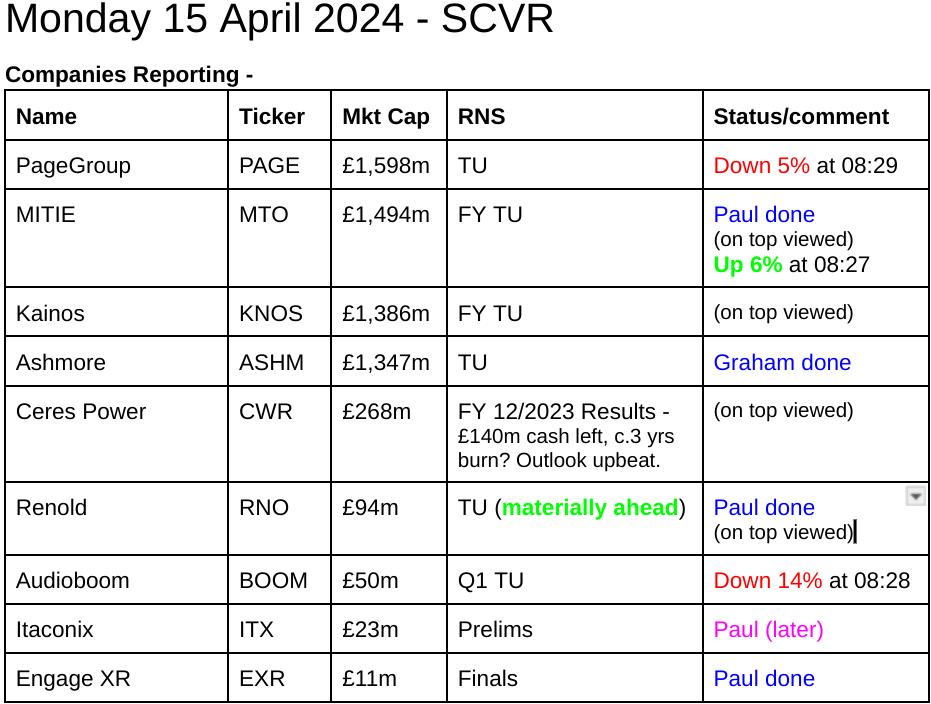
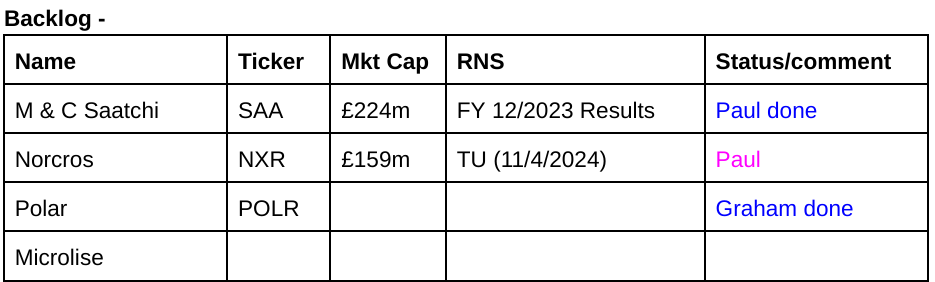
List of companies reporting - some of which we'll report on, focusing on over/under performers, and what we think are the better value/GARP shares. Also we prioritise your favourites, by looking at what readers are reading, on the top viewed list from the home page. Please remember that on busy days we cannot cover everything.
Other mid-morning movers (with news) -
KRM22 (LON:KRM) - up 24% to 23.5p (£8m) - New Customer Contract - Paul - RED
Niche risk management software minnow. Sounds like it’s making progress with growing ARR, and cost-cutting. However, its balance sheet is very weak c.£(6)m negative NTAV. Propped up with loan from major shareholder. Kestrel is second largest shareholder. I see high risk of this share de-listing, therefore I have to mark it red as currently structured. Pity, because if it had been properly funded with net cash, then it might have been an interesting punt here.
Invinity Energy Systems (LON:IES) - up 8% to 23.75p (£45m) - Update on Stretegic Investors - Paul - RED
Teases us by saying the negotiations with multiple large investors are going well, but nothing actually agreed as yet. I flagged here in Feb 2024 that it’s clearly running out of cash, and needs another refinancing. So personally I’ll wait to see if it successfully refinances, before being tempted to have a punt. Given the heavily cash burning history, I have to mark it as high risk for now, hence a continuing RED. The battery storage products do sound interesting though, and very much of the moment. I just need more proof, and more secure finances first.
Horizonte Minerals (LON:HZM) - down 82% to 0.425p (£1m) - Corporate Update -
Says it’s struggling to raise more cash, and that alternative options won’t leave any value for shareholders. That’s it then, looks like it’s a zero. Obviously we don’t cover the resources section here in the SCVRs, but an 82% share price drop today caught my eye and meant I had to do a spot of rubber-necking. It’s been around a long time, listed on AIM since 2006. Tried to develop nickel projects in Brazil.
Summaries of main sections
M&C Saatchi (LON:SAA) - 184p (£224m) - FY 12/2023 Results - Paul - AMBER
A 5-year turnaround still hasn't delivered convincing results. The famous PR agency has seen shares up 50% since last autumn. I'm underwhelmed by its complicated accounts, and poor cashflow, with legacy issues still cash-hungry. Hence why it pays negligible dividends. Weak balance sheet isn't good, but not a particular issue for a capital-light business. Maybe I'm missing a trick, but I can't see anything to get excited about here at the moment.
Renold (LON:RNO) - 40.3p (£91m) - Trading Update [ahead] - Paul - GREEN
"Materially ahead" of market expectations for FY 3/2024, with Cavendish raising adj PBT forecast by 13%. Also a larger increase in its FY 3/2025 (previously very cautious) forecast. The profit growth is coming from margin improvements. Net debt is quite modest, and more acquisitions are planned. I remain keen on this under-priced acquisitive group. Don't forget the pension deficit though, although this is waning in importance as the group grows.
Ashmore (LON:ASHM) - down 1.4% to 185.3p (£1.32b) - Trading Statement - Graham - GREEN
The Q3 update from this emerging markets asset manager describes a £2 billion outflow, blamed on institutional investor risk aversion. But I think the overall story here remains intact. If the dollar ever stops strengthening, Ashmore should see headwinds turn into tailwinds.
Polar Capital Holdings (LON:POLR) - 530.4p (£537m) - AuM Update - Graham - GREEN
An excellent update from Polar last week saw estimates getting revised higher and was warmly welcomed by investors. Small net inflows in Q4 interrupted the stream of outflows. This stock remains expensive relative to AuM but the earnings multiple is undemanding.
MITIE (LON:MTO) - up 8% to 120p (£1.60bn) - Trading Update (FY 3/2024) - Paul - AMBER
Shares up 8% on a decent-sounding FY 3/2024 trading update. I'm not sure how much more upside there is to be had here, after a very strong run of late. Facilities management companies tend to be ascribed quite low multiples by the market. This share has basically gone sideways for 20 years, so I'm not sure it's the best investment opportunity out there.
ENGAGE XR Holdings (LON:EXR) - unch 2.0p (£11m) - Final Results [FY 12/2023] - Paul - AMBER
Lousy numbers from this serial loss-maker. Why amber then? I've probably been too generous, but the main reason is that it has a 2-year cash runway after a fundraise in 2023, and has won a few impressive contracts. Losses are reducing too. As a fun money punt, I'd be tempted if the price came down a fair bit more. Risk:reward doesn't feel quite right yet. It probably should be amber/red actually. Let me have a think, I might edit this later.
M&C Saatchi (LON:SAA)
184p (£224m) - FY 12/2023 Results - Paul - AMBER
It’s getting a little late to be publishing 2023 results, and they’re not even audited.
Inevitably at a communications company, its results statements are going to be scrutinised carefully. The headlines don’t impress me, with the last two sounding too vague -
Material profit improvement in H2 and encouraging Q1 like-for-like momentum
Significant progress on transformation programme
Strengthened foundations for future growth
Going back a few years, SAA got itself into a big mess, and had various accounting problems, including some complicated options scheme that was used in acquisitions, that got into a tangle - see our archive where it’s all documented. It seems to have mostly sorted itself out now, but is still a big drain on cashflow.
More recently, the “Queen of tech” Vin Murria tried to take over SAA, but that didn’t work out. She’s still the biggest shareholder with 12.5%, and her listed tech acquisition business AdvancedAdvT (LON:ADVT) holds a further 9.8%.
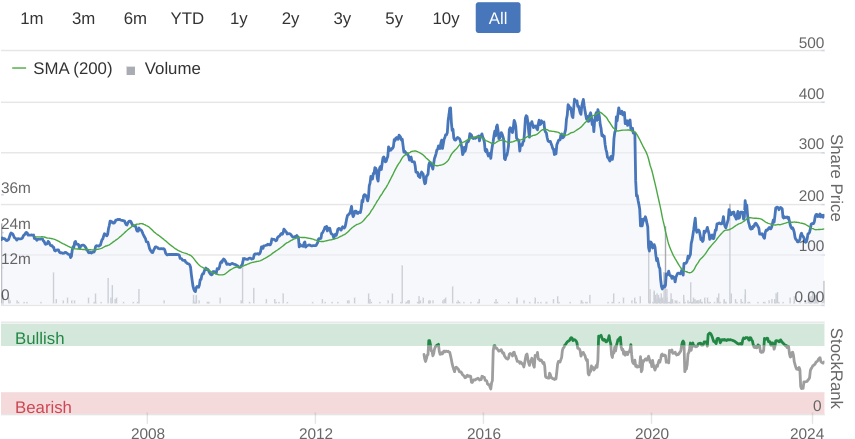
SAA shares have risen c.50% from last autumn’s lows.
Note that the biggest drop in SAA shares happened in summer 2019, before the pandemic began in Feb 2020 -
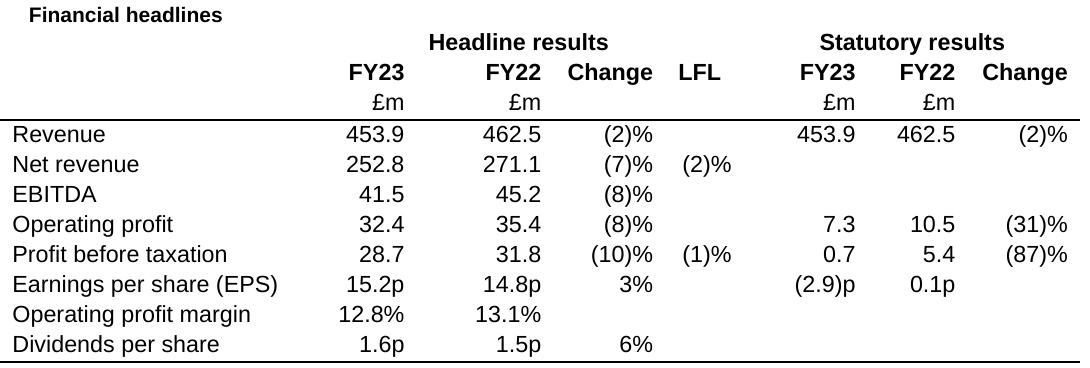
The headlines section below raises some obvious questions - why is there a gulf between adjusted, and statutory profits, in both 2023 and 2022? Why is adjusted PBT down 10%, but adj EPS is up 3%? Why are dividends so mean, at little more than 10% of profit? -
New CEO is joining soon - I wonder why the old one left? -
"I am delighted that Zaid Al-Qassab joins as CEO in May to lead M&C Saatchi on its next phase of growth, building on a simplified operating model and supported by our exceptional leaders.
It’s an international group, with 40% of revenues UK, Asia and Americas being the next two largest markets.
Adjustments - here’s the reconciliation from small statutory profit, to large “headline” PBT. I see the dreaded put options still seem to be muddying the water -
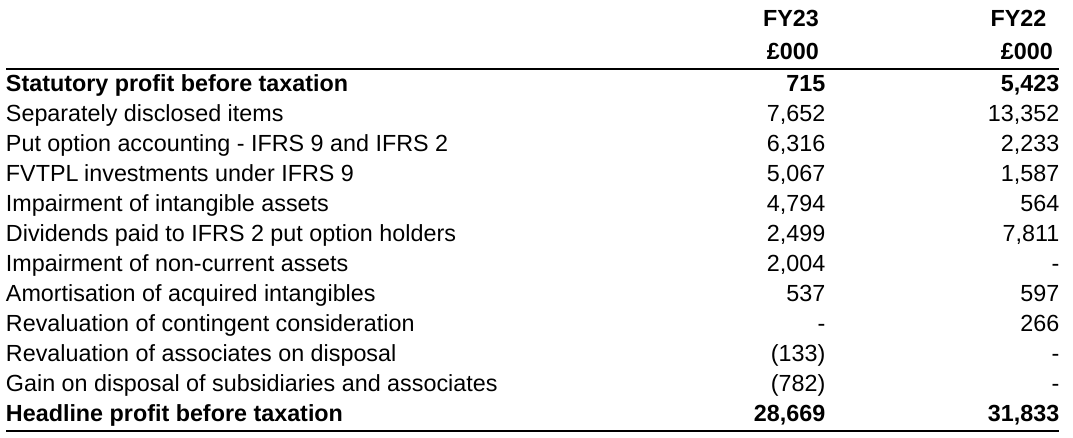
What on earth is FVTPL above? It’s “fair value through profit & loss” - which means the change (downwards) in value of some unlisted investments in other companies that SAA has made. That sounds subjective valuations of investments. They’ve now written off just over half of the £15m total (not very good) investments, in the last two years. Maybe SAA should stick to its core activities in future, instead of trying to be an incubator investor in multiple startups?
Outlook - is it just me, or is this (below) mainly waffle? I would have expected something more concise, and impactful from a communications group -
“Over the last 12 months, there have been many changes at M&C Saatchi against a background of significant market volatility. The Board has materially changed, including the appointment of a new Chair and Chief Executive Officer designate while our markets have been challenging, particularly in the technology sector. As such, we have taken the decision to no longer provide long-term targets and will, instead, provide nearer-term guidance.
2024 has started with renewed energy and focus and encouraging first quarter momentum. While our end markets continue to be affected by macro-economic uncertainty, we expect Headline profit before tax for 2024 to be in line with expectations. We are confident that the structural changes we are making to our cost base alongside our new operating model are increasing our operational leverage potential which will help support future margin expansion.
We have evolved the senior leadership team increasing capabilities and alignment. Zaid Al-Qassab's arrival as our new Chief Executive Officer is at the core of this process and sets the scene for our delivery over the coming years.
We are well progressed on building a simplified operating model which places our regional focus and global specialist expertise at the heart of everything we do. This will ensure we can continue to be unashamedly bold, creative, entrepreneurial and fearless in the work we do with our clients.
Our focus is on growing returns for our shareholders by investing in capabilities and driving the Group forward with renewed purpose. We have a marked advantage in being able to operate at scale with the agility of a start-up, allowing us to move at pace.”
Balance sheet - isn’t great. NAV is £29.5m. Deduct £34.6m intangible assets, and NTAV is negative at £(5.1)m. So there’s no asset backing. However, a people business like this probably doesn’t need much in the way of tangible assets, so it’s not necessarily a problem, I’m just reporting the facts.
Lease liabilities exceed right of use lease assets by £15.7m, so that raises the question of whether it is committed to any onerous leases? I can imagine that a big name PR firm like this might have signed some expensive leases on fancy London offices in the past, that it might now find expensive, what with more people working from home, etc. Anyway it’s a question to ask management.
“Minority shareholder put option liabilities” have fallen a lot in 2023, but are still material, at £9.9m in current liabilities, plus £3.5m in non-current liabilities.
Ah! It’s coming back to me. I remember now - the plunging share price a few years ago meant that some payments it had to make in shares would have caused big dilution. So it renegotiated them, to pay out in cash instead. I see the share count seems to have stabilised at about 122m in issue. See note 26 for the details of equity related liabilities, which increase with the rising share price. This shows that £25-34m liabilities (total over the next 5 years) are payable between a share price of 200-300p. That’s a fairly hefty amount, and I suggest we should probably discount the valuation of this share by about 10% to allow for this.
Net cash was £8.3m at end 2023, down from £30.0m at end 2022.
Going concern note looks clean, saying it can operate within banking covenants even in a severe but plausible scenarios.
Cashflow statement - given that the P&L is full of adjustments, and the balance sheet is weakish, and complicated, then cashflow might give us a better idea of whether this business is any good or not.
Operating cashflow in 2023 was about £30m, but “Exercise of put options” saw a cash outflow of £14.6m - so half the cash generated was burned on this. There was also a £14m adverse working capital movement. Put those two things together, plus £4.2m cash paid out for corporation tax, and cash generation was actually negative £(3.6)m.
This is all before lease-related cash outflows too, of £(6.2)m. So about £(10)m cash outflows. Capex is modest at £1.8m.
Cash fell from £37m to £24m in the year, and it raised an additional £9m from increased bank borrowings.
Overall then, the cash generation is negative, and looks very poor to me in 2023 and 2022.
Paul’s opinion - as a value/GARP investor, I’m mainly looking for cash generative companies, that can pay out surplus cash in big dividends. SAA looks almost the opposite of that. Its accounts are far too complicated for a company of this size.
If you’re prepared to ignore a load of real world costs, then the adjusted numbers look OK. However, cashflow is reality, and it’s really poor, in both 2022 and 2023. That’s why SAA is only paying token dividends. The historic issues are not fully resolved, and are still a major burden on cashflows. Bulls might argue these are only temporary though, and they could be right, who knows what the future holds? The outlook does say that 2024 should see better cash generation.
SAA has been seemingly in permanent turnaround mode for about 5 years now. Admittedly we have had the pandemic in that time, but its problems pre-date that.
I was expecting to like this share, but rummaging through the accounts has put me off. It looks superficially cheap, on a forward PER of 9.9x, but the weak balance sheet, poor cashflows, and negligible dividend yield don’t suggest to me that this is a great opportunity. That’s just based on historical numbers though. Vin Murria seems to think it has great potential, and she’s a lot smarter than me, so maybe I’m missing a trick here? That said, we’re not trying to predict the future in the SCVRs, we’re just analysing the facts & figures as of now, and SAA doesn’t impress on that basis.
Renold (LON:RNO)
40.3p (£91m) - Trading Update [ahead] - Paul - GREEN
Renold, a leading international supplier of industrial chains and related power transmission products, is pleased to provide a trading update for the year ended 31 March 2024 ("FY24" or the "Year"), ahead of the announcement of the Company's preliminary results for the Year.
Trading is ahead of expectations -
The strong momentum in the Group's performance in the first half of the Year continued throughout the second half of FY24. The results for the full year are now expected to be materially ahead of current market expectations1, with adjusted operating profit approximately 20% higher than the prior year, driven by a further improvement in margin.
1 Company compiled analyst consensus for FY24 is for revenue of £244.3m, and for underlying operating profit of £26.5m.
Broker update - Cavendish helps us with updated numbers (many thanks) -
FY 3/2024: raises adj PBT forecast by 13% from £19.2m to £21.7m.
EPS is raised from 6.0p to 6.6p.
FY 3/2025: previously soft forecasts are raised a lot, with adj EPS up 28% from 5.3p to 6.8p (still only a slight increase on FY 3/2024 - are they leaving things cautious, to allow for further upgrades in future?)
Valuation - at 40.3p (like to rise today) the PER is only 6.1x revised forecast FY 3/2024.
Remember that the PER is low partly because of the cash-hungry pension deficit.
Profit growth is being driven by margin improvement, not top line growth.
Net debt is £24.9m, which looks fine to me relative to profitability.
Order book sounds fine -
Order intake in the second half increased over the first six months by 7.5%, or 8.2% at constant exchange rates. The closing order book at 31 March 2024 of £83.6m remains close to record levels and was in line with the half year position (30 September 2023: £83.6m).
Acquisitions - sounds like more are planned. Renold is proving adept at these, and it’s a good strategy because acquisitions are gradually diluting the pension deficit -
The Group continues to strengthen its financial position, which provides funding capacity to support its strategic growth objectives. These include both investment to further enhance operational capabilities as well as value-accretive acquisitions, from a developing pipeline of opportunities.
Paul’s opinion - very positive still, this is one of my favourite value/GARP shares, and has been for several years. I think the valuation is too low, and over-compensates for the pension deficit, which has proven a manageable and diminishing problem as the group grows.
At some stage, there’s possible scope for this share to re-rate, both from diluting the pension scheme in a larger group (enlarged via acquisitions), and eventual recognition that it is self-funding these acquisitions, and seems to be pretty good at it.
So it’s a thumbs up from me again, GREEN. Expect a rise in share price today (written just before 8am).
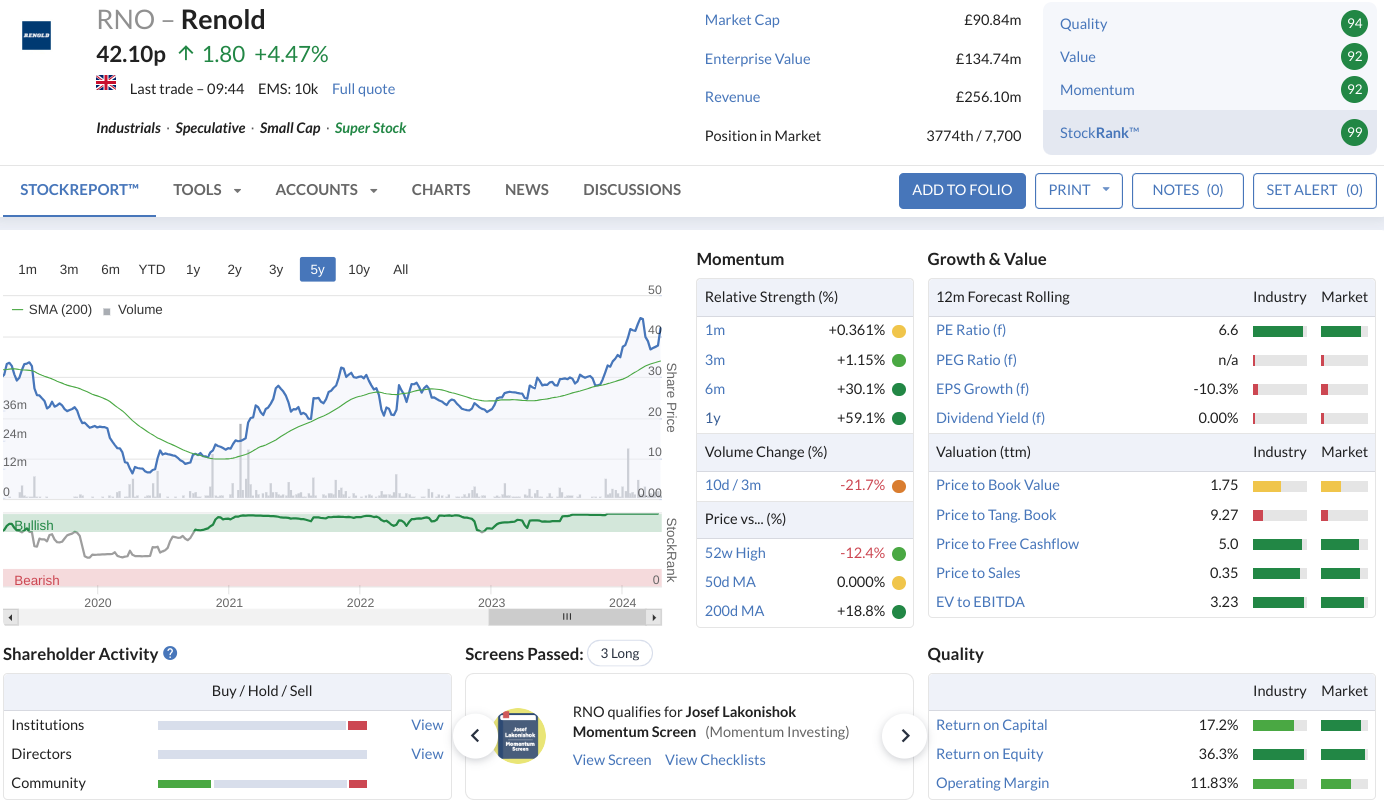
RNO shares are close to its recent 5-year high. Consistently high StockRank in recent years -
MITIE (LON:MTO)
Up 8% to 120p (£1.60bn) - Trading Update (FY 3/2024) - Paul - AMBER
Continuing our push into selected mid caps, I’m attracted to Mitie by the excellent 5-year chart, high StockRank, and positive market reaction (up 8%) to today’s news.
I last looked at MTO in 2020 and 2016, so we seem to be on a 4-year reporting cycle!

I would have preferred a clearer explanation of what the company does - this seems a bit vague -
Mitie Group plc ("Mitie" / "the Group") (LSE: MTO), the UK's leading facilities transformation company, today provides a trading update for the year ended 31 March 2024 ("FY24").
Going through the H1 results, this was the divisional breakdown, which gives a better idea as to what it does (half year figures remember!). It’s facilities management basically - with most profitable division at the top -
Business Services: £719m revs, £42m op profit, 84% of revenue is security & cleaning.
Central Govt & Defence: £406m revs, £35m op profit
Technical Services: £636m revs, £20m op profit, mostly maintenance & project work.
Local authorities, education, health, prisons, etc: £371m revs, £14m op profit.
The FY 3/2024 headlines today are -
Record revenue of at least £4,500m (11% increase yoy)
Operating profit increased to at least £200m (4.5% margin)
Share buybacks continue with next £50m programme launched
That suggests H2 improved on H1 (since operating profit was £85m in H1, it must be £115m in H2). I’m not sure if this is a usual seasonal pattern, or out-performance? There are no broker notes available to me, so I’ve had to estimate my own figures for FY 3/2024. I’ve come up with 10.6p adj EPS, which is a bit ahead of the broker consensus shown on the StockReport of 10.3p. So this looks like a beat against expectations, which is what an 8% share price rise today suggests too.
I don’t like the current trend for presenting operating profit as the main profit measure, we’re seeing this with more & more companies. We’re trying to wean the city off EBITDA, but they seem to have tried to dig in at operating profit, instead of presenting proper profits (adj PBT and adj EPS are the measures I need to see, to take into account all costs).
In this case though, adj operating profit was £85m in H1, and this became adj PBT of £80m, so that’s quite close together, since finance costs are not high for the size of business.
Note that profit adjustments are significant each year. Note 3 to the H1 results shows that it adjusted out £15m of acquisition-related costs, and £10m restructuring.
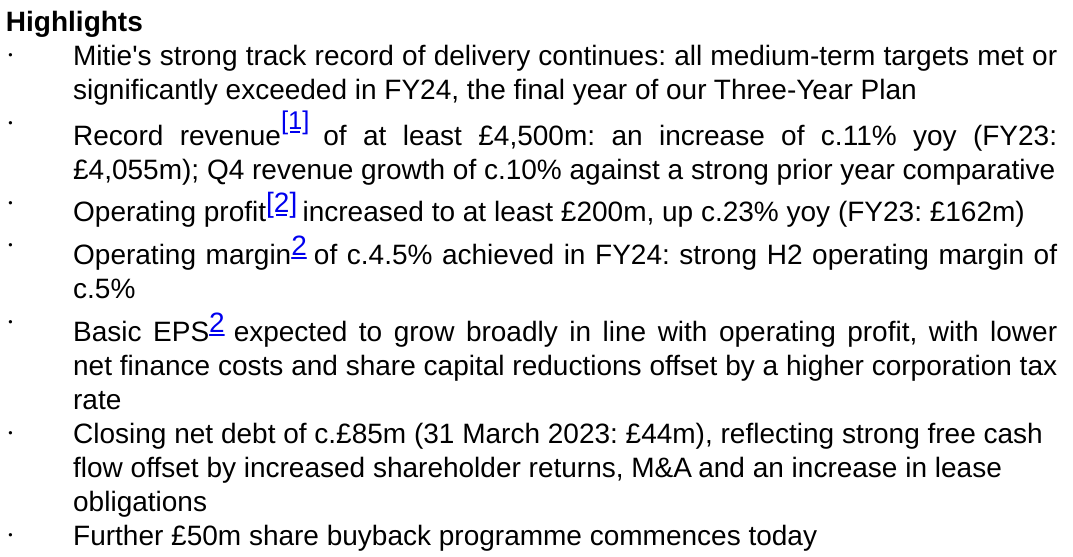
The highlights section below reads positively - and note the share buybacks at Mitie have been substantial, with issued shares peaking c.1,539m in 2022, now down to 1,335m. Another £50m share buyback is announced today, about 3% of the total in issue.
Note the significant increase in profit vs last year of 23% - impressive -
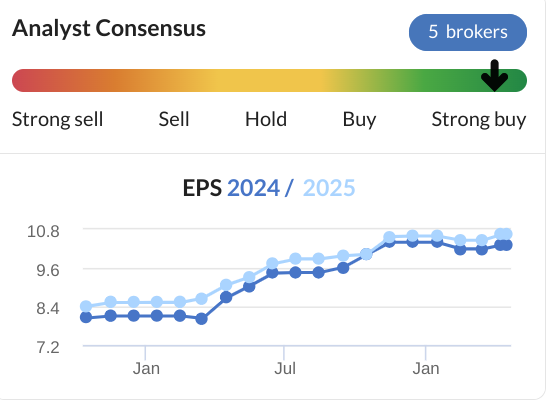
Broker consensus forecasts had been steadily rising -
So we’ve established that the group is performing well. What about its finances?
Balance sheet - excellent to see Mitie reporting average daily net debt, we need to keep the pressure on for all companies to report this key figure -
FY24 average daily net debt is expected to be c.£160m (FY23: £84m).
Overall, the balance sheet is loaded up with intangible assets, relating to the many acquisitions it has done. NAV is £412m, less intangibles of £606m, gives a weak overall NTAV of negative £(194)m.
Normally that would make me nervous, but in this case it actually looks OK. Why? Mainly because this is a services business, so it has negligible inventories. Not having to carry inventories which would be hundreds of millions, if this were selling physical goods, means the balance sheet can be negative overall without causing any problems.
There is some debt, but this is structured very well. It has £150m in private placement notes, with long maturities and low interest rate of 2.9%. So this looks an inspired move during the zero interest rate phase to lock in cheap debt.
An undrawn £250m bank facility is also available.
Both trade debtors and creditors are big numbers, at around £800m each. These would need careful scrutiny when the annual report comes out. In particular I’d be interested in what the c.£500m of accruals contains?
So even though it looks weak on paper, this balance sheet actually looks OK to me in practice.
Cashflow statement - going by the H1 figures, it seems to be spending more than it has coming in, with spending mostly on making acquisitions, paying divis, and doing buybacks. All of which seems to be depleting the cash pile.
Since I’m happy with the overall net debt position, which isn’t excessive at the moment, then it’s probably OK. It would be worth closely scrutinising the cashflow statement when the full year figures come out.
My opinion - it’s a fresh look for the first time in 4 years, so I’ve not looked at everything.
My impression is that this seems a well-run business, performing well. Facilities management is fairly low margin work, and Mitie makes about a 5% operating margin, and I imagine with little to scope to meaningfully raise that.
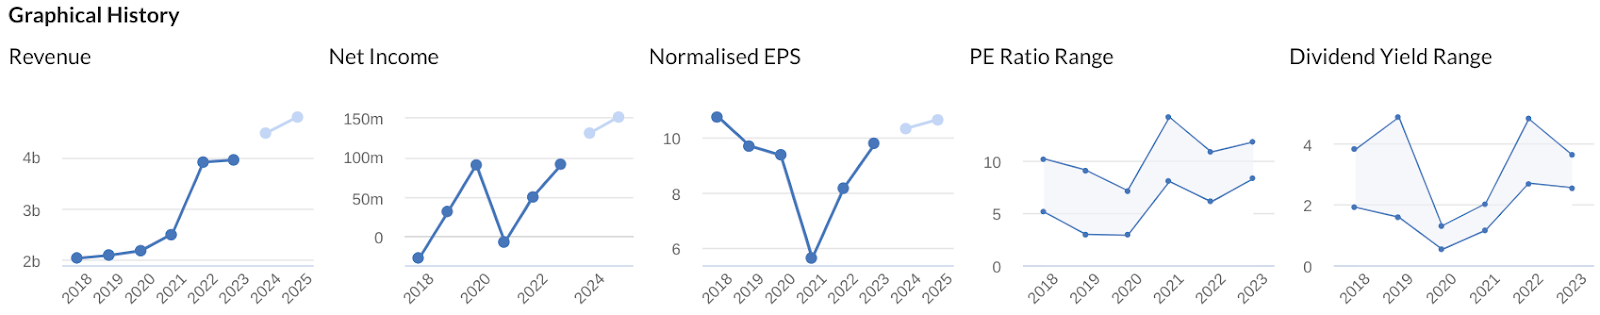
Obviously it had a rough time in the pandemic, but has now recovered. My main question mark from the graphs below, is whether all these acquisitions are really adding value? Revenue & profit growth look good, but it more than doubled the share count between 2019-2022. So EPS has essentially been static around 10p, and the PER is typically low - this makes me question how much more upside there is likely to be now that the shares have had a good run? I think MTO shares look OK, but there doesn’t seem to be exciting upside here. Whereas we’re finding numerous other shares that look obviously under-priced, and with cyclical upside in for free, whereas MTO shares look up with events, and probably don’t have much cyclical upside. So I would worry that tying up money here could have an opportunity cost.
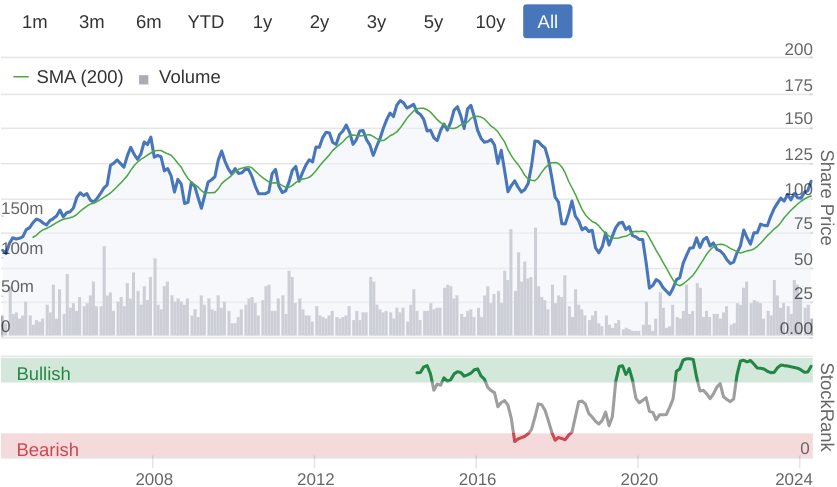
Zooming out, and the 20-year chart has basically gone sideways (below). AMBER feels right to me.
ENGAGE XR Holdings (LON:EXR) - unch 2.0p (£11m) - Final Results [FY 12/2023] - Paul - AMBER
ENGAGE XR Holdings Plc (AIM: EXR), a leading spatial computing and metaverse technology company, is pleased to announce its audited results for the 12 months ended 31 December 2023.
I’ve previously been negative on this jam tomorrow cash burner. However, looking at today’s accounts, I’m happy with the cash position, and reduced cash burn, which gives it a 2-year cash runway not having to worry about any more dilution or a cash crunch.
It warned on profit last autumn, and 2023 revenues show no progress at E3.7m (down from E3.9m in 2022).
EBITDA loss reduced from E5.8m in 2022, to E4.0m in 2023. It’s an own goal quoting EBITDA, as there is no capitalisation of costs (nothing in intangibles on the balance sheet), so LBT is the same number, of E4.0m.
Net cash is the key number, which is healthy at E7.9m (EXR raised E9.9m fresh equity in Feb 2023).
Outlook - seems mixed. It says Q1 2024 was a record quarter, but then seems to quote revenue bookings, not actual revenue recognised, of E2m - it’s ambiguous. Mentions that some corporate clients have not renewed, or scaled down contracts, as workers come back into offices. That’s a concern for a growth company. Business seems to be focused on the educational & training sectors, globally, where EXR reckons it’s in “prime position” to become the global leader in this niche. It also expected many competitors to fail this year, an unusual statement! The worry is that they might be failing because it’s impossible to make any money from this area maybe?
Paul’s opinion - speculative, but EXR has won a few impressive contracts, and it has plenty of cash to give it a 2-year opportunity to crack this space. Shares look a long shot, but I’d be tempted to have a little punt if they drift down to 1.0p per share (half the current level).
Graham’s Section:
Ashmore (LON:ASHM)
Down 1.4% to 185.3p (£1.32b) - Trading Statement - Graham - GREEN
This is a Q3 update:
Ashmore Group plc ("Ashmore", "the Group"), the specialist Emerging Markets asset manager, announces the following update to its assets under management ("AuM") in respect of the quarter ended 31 March 2024.
Assets under management fell by 4%, including a 5% fall in the broad “Fixed Income” category that is Ashmore’s core business:

All told, it’s a $2.1 billion fall in AUM, made up of a $2.0 billion net outflow along with a small decline due to investment performance. Institutional clients were “continuing to reduce risk”.
Despite the overall sense of risk aversion, equities did see a small net inflow.
Performance was affected by the strong US dollar, which reduces the value of bonds denominated in other currencies (especially. the “local currency” theme in the table above).
Marc Coombs is the founder and largest shareholder, in addition to being the CEO:
"Emerging Markets delivered a mixed performance over the quarter as stronger than expected economic data pushed back expectations of rate cuts by the US Fed. Looking beyond the short-term, macroeconomic stability in emerging countries underpins superior GDP growth compared with the developed world, and many central banks continue to cut rates in response to lower inflation. An easing of US monetary policy will further boost hard currency bonds and, with the US dollar at or close to its cyclical peak, a weaker dollar will underpin returns from local currency bonds and equities. Ashmore remains well-positioned to benefit from the capital flows that should follow these positive market trends."
Graham’s view
While I do value Ashmore’s commentary, it’s worth repeating that in my experience, they will always argue that they are well-positioned, and they will always argue that investors are underweight emerging markets.
Long-term, I think they have a point that institutional investors will want more emerging markets exposure, and it’s a valuable niche in which to have specialist expertise, so I tend to view ASHM shares as attractive.
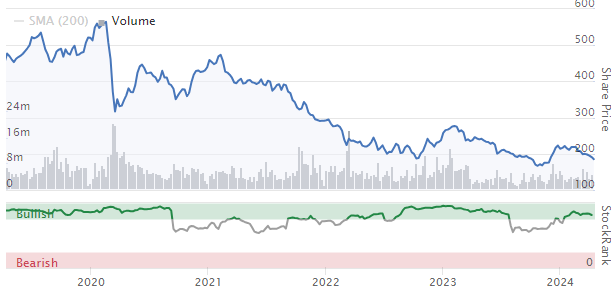
They’ve been getting cheaper in recent years:
As a result, they tend to offer a very generous yield:
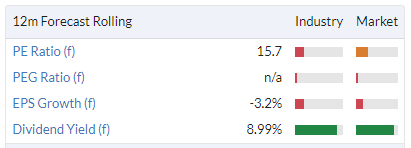
The PE Ratio may seem expensive, but the company has a very strong balance sheet that includes a seed portfolio worth nearly £300m. So the PE Ratio is not the only factor to be considered here. See our comments in February.
Despite the outflows in Q3, I’ll continue to give this share the thumbs up.
Polar Capital Holdings (LON:POLR)
530.4p (£537m) - AuM Update - Graham - GREEN
News from Polar last week was a little better, and the market reacted positively to this update.
In the case of Polar, the quarter to March is its Q4. So the update published last week was its full-year update.
In great news, Q4 saw net inflows at Polar. They were very small inflows (£56m), but inflows nonetheless!
The underlying assets - e.g. healthcare and technology stocks - were a good place in which to be invested during the quarter, and so AuM rose by an impressive £2.3 billion, or 12%, to £21.9 billion.
It means that the financial year had a very positive result, in the end. The final result for FY March 2024 is:
Outflows £1.6 billion
Investment returns £4.3 billion
Total change in AuM: £2.7 billion, up 14%.
Of course it would be best if AuM growth was driven by inflows rather than by investment returns, but maybe the good result in Q4 is a sign that Polar has turned the corner?
Estimates: Paul Bryant at Equity Development upgraded his revenue forecast for FY March 2025 from £178.6m to £197.1m, and his EPS forecast from 35.3p to 43.4p.
Some snippets from the CEO comment:
Given the backdrop of challenging conditions for the asset management industry, and following a number of quarters of net outflows, it is pleasing to be able to report net inflows
With interest rates having potentially peaked, global equity markets continued to rise during the quarter…
While the outlook for fund flows remains uncertain, positive momentum has continued into April 2024…
Whilst global financial markets remain exposed to several headwinds, the potential of interest rates peaking and central banks beginning to consider the possibility of rate cuts bodes well for equities in general and investors will, we believe, continue to seek additional exposure to the asset class.
Graham’s view
This stock made it onto my best ideas list. There were many fund managers I could have chosen, and there are still many fund managers I am bullish on. However, I decided to go for one of them consider to be “best in class”, and that is Polar.
It’s a mainstream fund manager but I am betting that it can resist the flight to passives due to known specialisms in particular sectors.
Like Ashmore, this one also appears to offer good value, especially in terms of the dividend yield. As consensus estimates are upgraded, the PE Ratio should fall, too:
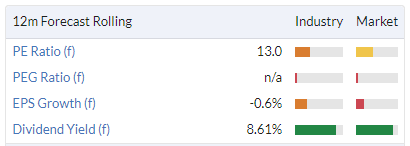
Of course, it’s not the cheapest fund manager. At the current valuation, it offers only £41 of AuM for every £1 invested in the stock.
By contrast, something like Jupiter Fund Management (LON:JUP) currently offers £107 of AuM for every £1 invested in the stock. I like the risk/reward there too (e.g. see our report in January), but that one has almost become a special situation due to the extremely long series of outflows.
For investors who are willing to pay a higher valuation to get a fund manager with a better chance of defeating the passives and retaining its independence, I think Polar is a great candidate.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

84 comments
Billington Holdings (LON:BILN) .... Shout out to Yiannos1 who pointed this one out in February.... 20-25 % rise since then , but results and investor presentation tomorrow morning... I know that the group collectively has different ideas on style and communication, but as Paul said at the weekend, it's a team game.... Great spot Yiannos1...
The consensus view from Wall Street economists is that the US is heading for a 'No' landing (see below).
Sounds great....
Until of course, one realises that the optimism has already been priced into equity markets.
With the #SP500 trading at >20x PER & there apparently being only a 29% chance of a recession in the next 12 months.
Will be great when we the us markets can finally make up their mind and get past all this uncertainty and get through a recession or no recession (!) as the US market sentiment can still move and affect global markets naturally.J!Although historically the data always pointed towards a probable recession.Just pull off the plaster already US investors!
Burford Capital (LON:BUR) now down 127p nearly 10%.
It seems to stem from a request by the New Argentinian Government to Judge Preska re the YPF Case.
A larger than normal drop today in Burford Capital (LON:BUR) of 6% 83p.
My largest position. Far from a Small Cap at £2.85 Bn but I just wondered if any holders had an opinion.
Not sure but Burford Capital (LON:BUR) had quite a fall on Friday on the US markets, presume that was after we closed here. So it could be an adjustment for that. I see Burford Capital (NYQ:BUR) is up slightly today, over there.
Not a holder of Burford Capital (LON:BUR) - don’t see how Argentina can or will want to afford any settlement. Likely to kick the can down the road and water down any resolution significantly in my opinion. Only got to look at Argentinas debt history to see this.
This is not new - I’ve said this consistently when Burford Capital (LON:BUR) comes up. I see any actual monetary recovery at cents in the $ if anything. I could be completely wrong of course but I’d say the indicators are more consistent with this view.
I have no view on Burford Capital (LON:BUR) valuation per se if this settlement were stripped out as haven’t looked in any detail, just that if I were a holder I would want a high risk premium to compensate for the low recovery probability from the YPF case. Is this factored in?
I quite like the space but opted for Litigation Capital Management (LON:LIT) as I feel it is exposed to much less lumpy risks and now has the benefit of a litigation fund management business and associated regular mgmt fees.
At a MCap of 1.6bn Kainos (LON:KNOS) is a bit above the scope of SCVR but it is clearly a popular stock judging by "Most Viewed" table. I am surprised that it has moved up today given the modest update and forecast revenue drop (although earnings will be "in line"). The review by Canaccord Genuity is headed "soft growth patch" and their general circumspection would seem to emphasize the "Falling Star" category given by Stocko. Being now 32% below its 52Week high it has much to prove. It is disappointing for a company which until recently had looked to be strong a contender for long term success.
Are there any on here who deal with them and can throw some light on their current drift as a business?
Kainos (LON:KNOS) I hold. In my opinion this is a quality operation which I understand is highly regarded by its clients. I note that Baillie Gifford added to their holding last week.
Kainos (LON:KNOS) There's a temporary bear market in IT consultancy and this was not a bad warning, hence the relief rally. Good time to buy IMO even if future growth won't be as dynamic as during the pandemic. Best to average in over the next couple of TUs.
I think what is encouraging about Kainos is the growing proportion of it's revenue that is coming from the Workday products. This has been growing steadily as they expand their suite of products. These should provide a growing recurring revenue stream going forward, with higher margin, and help provide a buffer during times, such as currently when demand for IT services are weaker. Eventually the demand for IT services should start to pick up again when long term confidence in the economy returns. So, even though revenue was a little off, I think the future looks bright.
Off topic question - does anyone know if there is a way to track individual UK gilts (eg TR25) in a Stockopedia folio?
If not, are there any work-arounds as I'd like to keep my individual folio's reconciled to the trading accounts that they relate to. Thanks.
RE: GILT TR25 in folio
A good question. I have tried but it would appear that Stocko does not subscribe to most fixed income data. Some prefs, but that seems to be about the limit of what is on offer here.
I don't think you can track it on Stockopedia, I hold TR25 also.
I suppose you can use google sheets or excel to track the overall performance.
Funds are also missing from Stockopedia. Dividends have to been entered manually.
Maybe Sharepad does all these things?
OK, thanks both - at least I know I'm not missing something!
I watched Paul Hill's recent interview with Richard Crow that piqued my interest in Dowlais (LON:DWL). As a result I did a little research, although their is much more to do. The shares are absolutely cheap on an optical view perhaps too cheap? The company was demerged from Melrose Industries (LON:MRO) 12 months ago, or thereabouts, since which time the share price has tanked, not helped by a substantial goodwill impairment in respect of its Powder Metallurgy division.
'A full review of the medium-term trading prospects of Powder Metallurgy, after our first year of ownership, has resulted in a non-cash goodwill impairment charge of £449 million contributing to a Group statutory operating loss of 450 (LON:450) million.'
The share price has been further depressed by the Capital Group , the largest shareholder selling down its position, which in the last month has reduced from 14.7% to 4.6%.
Based on present estimates the current PE is 5.4 falling to 4.35 with a yield of 5.1% rising to 6.3%. There has been a significant director buying with the CEO and CFO collectively buying close to 500,000 shares at a shade over 81p last month.
The company has also just announced a £50 million share buy back with the acquired shares to be cancelled. This strikes me as a good use of capital given the depressed share price. In addition there is a final dividend of 2.8p that goes ex this Thursday.
To conclude with an extract from the the outlook statement taken from the recent prelims, which appears a little at odds with the depressed share price.
As we look forward, current industry forecasts imply a slight decline in global light vehicle production in 2024. Based on these external forecasts and our current order book, we anticipate Group revenues will be similar to the prior year, at constant currency, with a modest reduction in the first half offset by an improvement in the second half due to the expected timing of several new programme launches. On this basis, and with our strong continued focus on operational efficiencies, we expect to further expand operating margins and grow free cash flow in 2024. We remain confident of achieving our margin target of 10%+ in Automotive over the medium-term, largely underpinned by announced restructuring."
I have a fair bit more homework to do, but the portents look enticing given the present share price.
To paraphrase Howard Marks, in my view one of the great investment minds, along with Charlie Munger and Peter Lynch, it is not what you buy but what you pay that determines the success or otherwise of an investment.
I have therefore purchased an opening position in Dowlais (LON:DWL) at 82p.
All the best
Is there a pension deficit at Dowlais (LON:DWL) ?
I did look at it, seems high risk, the debt is too high for me. But CR is a pretty shrewd investor, although I thought his recent purchases were higher risk than usual.
Re Dowlais (LON:DWL) there most certainly is a pension deficit https://www.dowlais.com/files/...
I’d also suggest the statutory loss is of considerable importance to the investment case as it reflects a poorer outlook for the powdered metallurgy division …still looks cheap but not without issues
Thanks for your response on Dowlais (LON:DWL), too many issues for me.
Cheers Rhom
Dowlais (LON:DWL) is certainly not without risk, but much is already priced in I would suggest Need to delve further into the detail of which there is much.
At present it is a small position and may well stay that way. But the amount of director buying is encouraging, Spending close to £400,000 of their own money by the CEO and CFO, who should, fingers crossed, have a good handle on the finances and order book is a bit more than beer money, even for the wealthy
Time will tell.
Re Dowlais (LON:DWL) director share purchases are non meaningful…as both CEO & CFO are required to make them…
Good spot Rhom. Highlights my need for additional research.
Dowlais (LON:DWL)
"But CR is a pretty shrewd investor, although I thought his recent purchases were higher risk than usual."
It was not one of CR's picks - Paul Hill mentioned it during the conversation.
CR has since invested last week
He bought last week. His recent buys were not on that video, because it was about the 1st quarter. He sold half of his Rolls-Royce Holdings (LON:RR.) and Marks and Spencer (LON:MKS) and bought Dowlais (LON:DWL), Frontier Developments (LON:FDEV) and Synthomer (LON:SYNT, maybe some others as well.
"He bought last week. His recent buys were not on that video, because it was about the 1st quarter"
Ah, OK, thanks for the clarification.
I'm no saint but I find the repeat ego-off in here tedious (TBF I'll have a fight with anyone who wants to - absolute character flaw and not an innocent)
IMO there's a lot of dross and spiv posted in comments. Unless the bar is made very high and 'professional' with coherent arguments and facts AND NOT 'I own and it went up' -> I mutter f-off to every post that has 'I hold' in it fyi...what's the effing point in saying that after you've just waxed lyrical about why xyz quality/sh1tco (delete as appropriate) is great and its gone up loads to prove it.
Stocko cannot police this. They need to let it run and short of threats or very direct personal abuse they just need to let comments run and play out. If people pay their £££s to sh1tpost then so be it. I'm amazed at some of the fragile egos...eg looking at a poster beginning with Y dishing out, crying, etc but not taking and claiming they are bullied if someone disagrees with them!
Otherwise close down comments and concentrate on the data and analysis from a few verified people (like Paul, Graham etc....not things like Paul hill that just feeds the spivvy angst and ego stuff that underlies a lot of PI stuff)
I find Ken's posts uninteresting now so I just don't read. If you too find it the same then don't read them. Others will like them...and as this is an open space that's fine. Ken is providing a service to some...and to call him Trumpian is just silly...you may as well say the same about my daughter when she posts some CAPITALISED social media bs!
I'm letting my membership roll off later this month as, despite liking a bit of an argument now and then, the whining and red flagging along with spivving of stocks in the comments is tedious and a distraction
Stocks go up and down. Investing is a fraught business and it triggers our emotions. If you are going talk about your precious (we are all like that with stocks) then be prepared to be hurt by the rejection etc...or embarrassed by Mr Market playing games with you. And if someone beefs you its as they have been triggered...don't clutch your pearls and run to daddy aka the red flag. Ie grow up!
PS I fully expect this post to be deleted...
It will be a shame to see you go mojo!
Also be sorry to see you ship out Mojo there have been times when I have thought your crazy as a box of frogs but you clearly know your way around the macro and individual stocks way better than most (including me) good luck with whatever you decide.
Its a shame that some of the really knowledgeable posters seem to be going quite even the momentum masters Robbie Burns got flagged a few weeks back and we should be trying to get him to post more here not less.
Will be a loss to this forum if you decide to leave Mojo. I for one find your comments useful, researched and interestingly put across in your own unique style of expression.
Perhaps we can develop thicker skins to help bypass comments that do not serve the intended purpose of this forum...?
haha...didn't realised it duplicated in weird way when I edited. I would red flag my repeat post myself...but I'll leave some pearl clutcher the joy
There is a #MelloMonday investor show this evening with six companies covered including three doing presentations and Q&A Stockopedia | Mello on Monday...three companies, supply chain issues uncovered & a BASH | By carmensfella
#SEED not the long term share for investment imo, but has some interesting investments in cannibis stocks that is pending some huge regulatory change in the US, which could be a major catalyst. Aside from that, what peeks my interest is after the £2.4m receipt today they have £6m in available cash vs. mc of £4m.
Ashmore (LON:ASHM)
I've got a strategic eye on this. I like a combo of their niche EM debt capabilities (one of the few that offer it) and successful seeding and growth of local operation in market (Columbia, Saudi, India and Indonesia), growth of alternatives/infrastructure and improving equity capability. EM has been largely a dead asset class since 2012.
Ashmore's recent woes trace particularly to a mistaken move into already distressed Russian, Ukrainian, Venezuelan and Chinese Real Estate prior to covid/Russian invasion (can't remember exact timings). I believe they may have been the biggest foreign holders of some now deeply distressed Venezuelan (oil company) and Chinese RE (Evergrande) assets. TBH there's a hint of hubris around this...founder Coombs being a bit gung-ho contrary in his moves.
Dividends are high and an important part of senior team ongoing remuneration. In the past Ashmore could be accused of being miserly with their payout and not raising with earnings growth. Ashmore's issue now is that with AUM loss operating earnings no longer cover dividends...and that keeps deteriorating. Obvs they have the cash on balance sheet to see themselves through that for a long while yet. But I don't see them running that position very long and its notable in interim guidance they talked about upping the share of earnings going to remuneration significantly above historic norms...I take this as a hint that they may be preparing the ground for a div cut.
Anyway. I took a small position early Nov 23 (at lows - not normally that good at timing!). I felt at that point I was getting a free hit at a pro cyclical risk position. Its paid out c.10% in div since then and gained c.10% as of open today...and I sold. In Oct/Nov 23 it was clear they were going to maintain dividends for this year and there was a decent chance that the shift in risk sentiments would work into their AUM via performance and flows. However, that hasn't pulled through and we are now into the final quarter of the year...
My view on pro cyclical risk opp and good timing might pull through but now that outcome is all condensed into what happens internally (flows) and externally (markets) in this final quarter. It needs to be pretty decent to be confident they look through on the div. That's a gamble with much poorer odds now. I think they will cut...
...and that will be a very interesting point where I may get the chance to load up and look for what I think will be a good strategic entry and tailwind point. Of course, they may cut the share price rise around that as clouds clear and they rebase a bit! Who knows? I think the sp likely falls
I also went into Ashmore (LON:ASHM) last year, although earlier at a much worse price point than you, in June 2023. So am underwater, even with the dividend paid out.
I have a different view on the dividend - I think they will keep it for FY24, as they have had a record of increasing or flat dividends for over 17 years now:
However, you're right that it can't go on forever, and there's no immutable law that says investment capital must cycle back into EM again soon.
However, my macro view is also that inflation in developed economies (eg USA) will be more stubborn than expected, which inevitably leads to a view that rates will remain high, when then leads to a view that no more investments will flow into EM (when you can get such high risk free rates in the USA, and also strong USD).
So I also have my finger hovering over the sell button. Will digest and re-do my calcs later this week; don't think the SP will drift further down in the short term, sentiment is already so bearish.
(I hold in the Boon Fund - that reminds me I should shortlist this as an article to write in the next few weeks)
I agree re Ashmore (LON:ASHM) ...I think its a sensible long term risk to take and I like the EM exposure. I just can't help see the div risk in front of me right now revolving around how Q4 AUM pans out.
I have an added concern re the long in the tooth founder. I feel this is his last hurrah. I don't think he survives another year of this. This is speculation from me (and he'll probably be wheeled out in his coffin or strapped to a chair for his own safety etc at a much later date) and quite probably wrong. I've worked in investment businesses (and also 'professionally' analysed them) and I just think he knows, the board knows and the senior sales people know (the most important people!) that the situation can't run-> and that means change, flux. They got to present to existing clients and new that something has changed for the positive. Its unhelpful for business that he focuses so much on macro in his comments...doesn't matter if what he says is true, clients just get tired hearing that they are waiting for the Fed, rates, NVIDIA (NSQ:NVDA) to take a dive, etc
On Friday I posted a comment on the significant move in Renold (LON:RNO) . Looks like the market was ahead of the game. (I hold).
Could be leaks or insider dealing. I hold Renold (LON:RNO) also.
As a holder of Renold (LON:RNO) since 2001 I can safely say it takes very little volume to move the share price.
M&C Saatchi (LON:SAA) I really can’t see the appeal when WPP (LON:WPP) it’s a better company on a lower multiple with an obvious catalyst for rerating in the near future when big tech advertising budgets are revived. I recommended this on the “shares that have fallen “thread, since when they have begun a moderate but steady recovery. Still some way to go in my opinion.
I wonder if any readers might be interested in Conduit Holdings (LON:CRE) ?
I used to have really major holdings in London underwriters, but lost interest when rock bottom interest rates and tidal waves of easy money destroyed their business case. I became interested in Conduit Holdings (LON:CRE) when I saw some interesting people from the industry join up there. Up until now I have felt that the company has been too early stage, but it's latest results looked terrific to me. I don't expect them to be repeated, and Baltimore bridge problems may have an impact, but they look very sensible value to me with a substantial yield and are priced close to NTA.
Comments appreciated.....
Interesting opening Mr Grey. Having held Beazley (LON:BEZ) for more years than i care to remember i have always looked for a "companion" stock, remembering how a number of firms got taken out privately in the mid last decade. First coming across Conduit Holdings (LON:CRE) last autumn and was impressed by the experience of the main players during a webinar (recommended watching - last oct/nov i think). This was compunded by the renewals RNS in early january. What impresses me is that not only has it a 'tailless' liability but their ability and knowledge to choose which class to insure. Have spent the 2 or so years since IPO building their position in the reinsurance market, this could go on to strengthen always assuming their ability to pick risk is not impaired by left fiels disasters
I hold both i mention
I have held cat reinsurers on and off and used to cover them a bit. I bought conduit when they were well below 1x P/TNAV and sold in early 2023 as a trade. It looked like the right time in the cycle and the right price. I also bought and sold LRE around the same time but have held onto a few since they have an underwriting track record which Conduit currently lacks. Like other cyclicals I don't see them as buy and hold stocks and timing is critical; in fact I always feel a bit like I am holding a ticking bomb since black swan events are more common than one assumes and it seems that they are getting increasingly common. They feel a bit like airline stocks in that respect - after a shock event they can look cheap but what is to prevent another shock event when the balance sheet buffer has already been eroded? For what it is worth, for me at 1x P/TNAV and capable of high returns on capital Conduit looks cheapish but I prefer to buy when they look really cheap and the risk reward is more skewered.
Conduit Holdings - A J Bell Shares Magazine made a compelling case for investing in CRE, in their. edition dated 21.12.23. They considered that CRE five year target had almost been reached at the 3 year mark, and their impressive new business taken on board recently will show in bottom line profits in about 18 months time. Such is the nature of the underwriting business. I bought then and they’re up about 5% since.
M&C Saatchi (LON:SAA) Paul, thank-you for your review this morning which really helped clarify SAA for me.
I think M&C Saatchi (LON:SAA) is a superior car crash, burned my fingers on it years ago and no longer hold.
Morning Paul Scott.
Like many others, I just wanted to say, I really enjoy your weekend podcasts. Your delivery is clear, interesting and you always manage to make me smile at least once. Sound was really good this week and I'd never noticed you say 'um' a lot. Don't worry about that. Your podcasts are an excellent precis of small cap market news from the perspective of Paul Scott
Michael
Agreed MichaelT. Scotty's weekend podcasts are a must listen for any serious smallcap investor
Fully agree. That goes for traders too!
Hi Paul I’d like to echo those comments except I found the volume levels quite low, even on my highest volume setting I was struggling to hear clearly…wanted to point out as you’re in Gozo so things will be different for the next few weeks I guess…enjoy the sun!
I agree, podcasts are brilliant. Please don't worry about saying 'um' alot, I never even noticed. Just my opinion, but I wouldn't worry about trying to be too polished. Your natural, genuine delivery style is what makes the pods so good, unique and must listen.
Thank you to everyone for the super feedback on my podcasts, much appreciated! It motivates me to keep doing them, when I hear that people find them useful and/or hopefully a bit of fun too, with what can be a very dry subject.
Discusion posts.
Stocko's Alex posted last Wednesday about dividend charts which turned into a wider discussion, with Ed and Keelan commenting, about a number of things including the whole setup of posts. One aspect was the relation of SCVR posts to others and there was (IMHO) a very good post by ken mitchell to which I replied. One of the things I mentioned was the dropping out of sight of the post for (usually small and less liquid companies) that have had a change in price. My example was Shoe Zone (LON:SHOE) which had 8 posts in the SCVR on Thurs. and another 6 on Friday. The right place would have been at the "shares that have drifted down in price recently for no reason (or have not risen)" post:
https://www.stockopedia.com/co...
So please have a look at the post mentioned earlier, that is outside the SCVR - you can start with Ken's comment and replies:
https://www.stockopedia.com/pr...
or look at the whole post:
https://www.stockopedia.com/pr...
Even if you take nothing else away please come in to the SCVR via:
https://www.stockopedia.com/di...
so that you are aware of what else is around.
I have wondered aloud a few times about an official thread for each stock?
The problem is, if you post on older threads then hardly anyone sees it. I have posted on older SCVR and not got any replies, even if it was the day before.
Rusty2: indeed - that is why I advocate coming here via https://www.stockopedia.com/di... - that way I can see I have 9 comments to catch up on Thursday's SCVR:
I think members would soon get fed up, if the SCVR reports gets littered with posts with links to other posts. I'm surprised how dead SCVRs go after the current day.
I always do go in that way, but seems many, just go straight to SVCR.
I think members would soon get fed up, if the SCVR reports gets littered with posts with links to other posts
This. I had a grumble last week about it. Posters wishing to draw attention to their alternative threads should credit us with a little more intelligence and assume that we know there are other options via the Discuss > All Posts option.
In fact I put in a request to tech support to simplify that navigation with an All Posts button.
Trouble is, like time, the SCVR is the essence.
THE key point in sharw’s post was simply this. Too many subscribers seem totally unaware of all the other (often excellent) bulletin boards here, including those initiated by Stockopedia staff!
Here’s the link again that if used to access this site will bring up all the threads and NOT just this excellent thread.
https://www.stockopedia.com/di...
This Small Cap Value Report thread is deservedly very very popular, but replies suggesting everyone knows about all the other threads are wrong.
e.g I’ve written posts on other threads and got just 1 or 2 thumbs up and NO replies. Occasionally I’ve also gone on to post it here. AND instead of one or two ticks, on a couple of occasions the posts got well over 100 and replies well in to double figures AND some of those replies were superb and also got heavily recommended . That strongly suggests lack of awareness among Stockopedia subscribers of all the other threads here.
AND if only more people did read and post on and reply on those threads, then there would be FAR fewer off topic posts here too.
What’s happening now is that this excellent bb is getting swamped by more off topic posts and so much so on some days that shares analysed in detail by Paul and Graham sometimes don’t get the response they deserve as we gravitate to other topics.
That’s unfair to them and annoying to those who know about all the other threads but who are only interested in this one.
EDIT.
IN response to a surprisingly hostile reply from BnB I’ve just removed the paragraph and link to an Investment Trust thread, and have switched to this thread started by Megan Boxall a few weeks ago:-
https://www.stockopedia.com/co...
It’s hardly thriving is it?
I was one of those who posted on Shoe Zone (LON:SHOE) in response to a query about the price fall. I was aware of one potential reason for the drop and thought it was relevant to that time & day.
I’ve had a look at the discussion board you would prefer me to post on. It does have interesting posts but as an ongoing board each post is relevant to the time & day posted and can become less so as time elapses. The SCVR is (as someone else also noted) the essence of time.
I would hope that so long as what each of us posts is constructive and polite it is still perfectly ok to post on here
I posted the initial post about Shoe Zone (LON:SHOE) it was down over 10% on the day, looked like within an hour, l got an alert in the afternoon, it was not a gradual drift down. The link you suggest is not the right place IMO,
there was a profit warning some weeks ago and this was a sudden drop on the day.
If I had posted there, doubt there would have been any response. Last post was 6 weeks ago.
https://www.voxmarkets.co.uk/r...
Renold (LON:RNO)
A very upbeat Trading Uodate from Renold. FY24 expected to be materially ahead of current expectations. As revenue was flattish this would seem a great result.
I think Paul usually looks at this so maybe if he has time he will comment.
Without the YUK acquisition (conveniently not mentioned, yet again!), revenue growth would have been even more negative though? Excluding price increases (surely they have them), acquisitions and currency effects, volumes must be significantly down. I’d really have hoped for a better top line result to have any hope Renold (LON:RNO) can medium term grow its way out of its debt/pension deficit issues.
And the order book is down. It's at £83.6m versus £99.5m last year and £84.1m at the end of FY22. On the plus side it does talk about acquisitions and I see the broker is penciling in a dividend for the first time in memory as well.
Renold (LON:RNO)
I'm with you on this one M48. On the face of it a really nice announcement;
The strong momentum in the Group's performance in the first half of the Year
continued throughout the second half of FY24. The results for the full year
are now expected to be materially ahead of current market expectations(1),
with adjusted operating profit approximately 20% higher than the prior year,
driven by a further improvement in margin.
However, at the 6 month stage revenue increased from £116m to £125m. This means second half revenue is a decrease, back down to £116m - I'm not seeing this as strong momentum.
Secondly, the net debt figure has not reduced that significantly given the EBITDA/Net profit figures mentioned - indeed Cavendish say the extra £2m of debt reduction over forecasts comes from favourable working capital changes and some receivables paying early.
So in summary we have flat/falling turnover despite acquisitions, we have one off improvements in net debt due to favourable wc movements and we have a cash hungry pension fund deficit.
On the plus side we have improved efficiency leading to margin gains (but this can't go on forever?) and a full order book which clearly helps with visibility.
Also surely talk of paying a dividend is premature, isn't it?
I am a holder but I'm not convinced this trading update is as good as it first appears??
Thanks Norfolk. Although I've not read the broker report something doesn't stack up in my eyes - declining underlying volumes in a business with high operating leverage is normally not conducive to margin improvement - unless they've built up year end inventory and loaded the balance sheet with overhead costs to offset, or there's significant product mix variations or something else they've chosen not to highlight. CEO been there a while so doubt there's still low hanging fruit to easily drive margin. Suspect until we get the full Renold (LON:RNO) results statement we won't know but I'm going to stick my neck out and say they'll show something important that's not been fairly explained today.
Edit: and referring to Paul's remark that the broker forecast for next year might leave room for an upgrade, a contrarian position is that this year's number includes something unrepeatable.
I seem to remember the order book and revenues for Renold (LON:RNO) by lumpy military contracts. Wasn't there an 8.9mm one for H1?
This sounds familiar to me as well, also after the recent news of UK defence spending increasing to 2.5% this can only put wind in its sails for Renold (LON:RNO) surely?
M48 good point on Revenues for Renold (LON:RNO) . I'm sure many here have worked in businesses where increasing profitability can be achieved for a couple of years without growing the topline. If this is happening even with acquisitions which should be adding revenue how competitive is their offer? And how sustainable is this growth in profitability?
Probably still deserves a higher PE ratio than current but no more than 8 -10 times?
Seems to me revenue is not regarded here, in the same way as in the US markets. Here revenue is so not relevant, it is more about profit and eps. In the US the 2 key figures on quarterly report days, are revenue and profit. If a company misses on revenue forecasts, it can have quite effect the share price.
Morning Helvellyn,
I'm on the case re Renold (LON:RNO) - first on my list as it's a "materially ahead" update.
P.
Good update on Renold (LON:RNO) Paul. But surely with its valuation so low, despite its pension issues, it too should be on a list of UK targets? Must be some US engineerin giants that might welcome its expertise/European positioning?
A good trading update from Renold (LON:RNO) with adjusted operating profit approx 20% ahead of previous year.
Renold (LON:RNO) Always nice reading "The results for the full year are now expected to be materially ahead of current market expectations" in a trading statement. (I hold)
Despite the awful headlines wrt the Middle East - it appears early bird investors have decided to buy on the 'sound of cannons' this morning.
With most equity futures up at the bell. That is from where they closed at 9pm Friday (12th) evening - not when the FTSE100 ended trading at 4.30pm (which was slightly higher).
I thought oil prices were up last night but it is the opposite this morning. Misleading BBC news or what? Shares are generally up apart from oil.