Small Cap Value Report (Mon 15 Jan 2024) - IQG, ASHM, CRST, RFX, BAKK

Good morning from Paul & Graham!
Today's report is now finished.
Updating my SCVR summary spreadsheet, would you believe, we've already looked at 60 unique companies so far in 2024 - a flying start, I'd say! Although 11 of those were just quick comments, not full sections. Even so.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
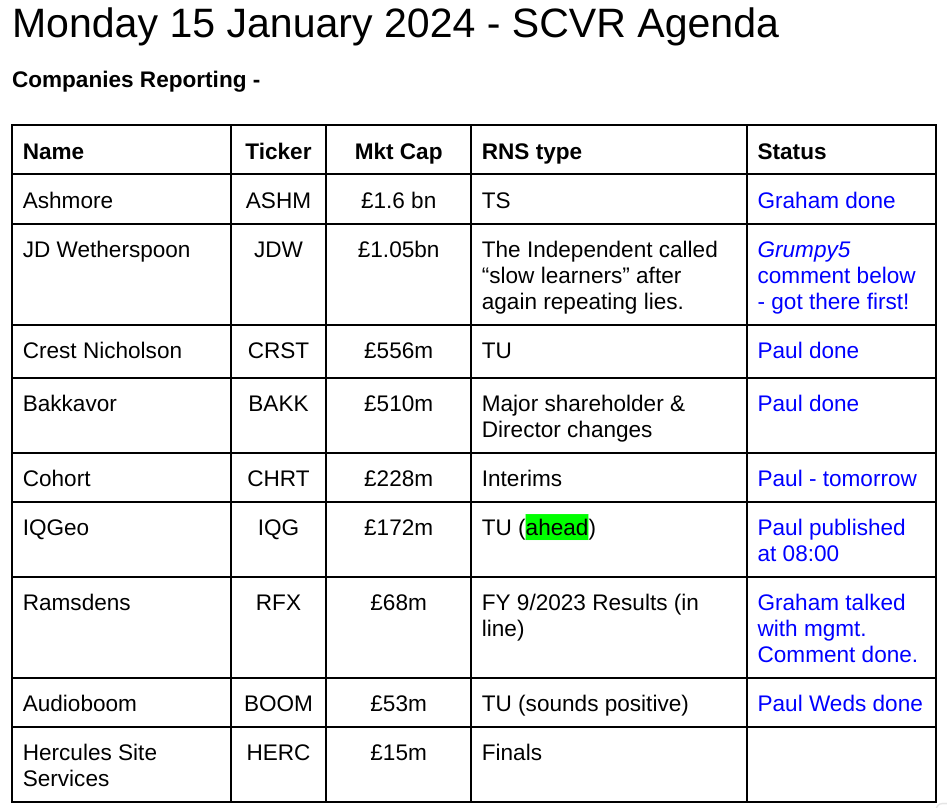
Summaries
IQGeo (LON:IQG) - up 17% to 325p at 08:19 (£201m) - Trading Update (ahead) - Paul - AMBER/GREEN
Excellent update, ahead expectations for FY 12/2023. The outlook comments look really encouraging too. I'm very much warming to this high growth, niche software company. Shares are expensive on PER, but that's a clumsy measure for a rapid growth company. Looks good to me, but beware risk to valuation if growth slows down. Possibly a risk worth taking, I'm increasingly thinking.
Ashmore (LON:ASHM) - unch 223.5p (£1.6bn) - Trading Statement - Graham - AMBER
This emerging markets fund manager reports further outflows in Q2 but at a slower pace than Q1 and slower than the average quarterly decline last year. Perhaps significantly, equities saw an inflow. Could we be about to see the long-awaited turn in EM sentiment?
Crest Nicholson Holdings (LON:CRST) - down 5% to 206p (£528m) - Trading Update (profit warning) - Paul - BLACK (pw), GREEN on fundamentals.
It's a mild profit warning, due to more legacy problems/costs, making CRST look a bit accident- prone. The large discount to NTAV remains a big attraction, and I continue to wonder if it might attract a bidder?
Ramsdens Holdings (LON:RFX) - down 5% to 205p - Annual Results - Graham - GREEN
The market seems disappointed with a muted Q1 trading update, but the PBT estimates for the current financial year are unchanged. I remain a big fan of this company - offering net cash, a good yield, store expansion, and a proven business model at a cheap P/E multiple.
Bakkavor (LON:BAKK) - up 4% to 88.2p (£510m) - Major Shareholder & Director Changes - Paul - AMBER/RED
A 20% stake has changed hands, making me wonder if it might become a bid target? I crunch the H1 numbers from a few months ago, but the weak, overly indebted balance sheet puts me off. Still, I've upped my view from red last time (which was a bit too harsh) to AMBER/RED, to reflect the low margins, heavy bank debt, and higher finance costs.
Paul’s Section:
IQGeo (LON:IQG)
Up 17% to 325p at 08:19 (£2101m) - Trading Update (ahead) - Paul - AMBER/GREEN
IQGeo Group plc (AIM: IQG), a leading developer of geospatial productivity and collaboration software for telecoms and utility network operators, is pleased to announce an update on the Group's trading for the year ended 31 December 2023, ahead of the release of its audited final results in March 2024.
We had an almost 5-year gap in reviewing this share from 2018 to Sept 2023 when it cropped up on my radar here on 26/9/2023 - with very strong revenue growth, and the prospect of a long awaited breakthrough into profitability. The high valuation, and balance sheet queries put me off a bit at the time.
That was resolved here on 20/10/2023 with my notes from a call with management, who explained credibly I thought, why receivables were unusually high. Having resolved queries, I felt much happier about IQG shares, turning amber.
IQG looks a very interesting niche software company, with large, sticky clients, and very strong growth.
FY 12/2023 strong trading, ahead of expectations - excellent news today -
The Group is pleased to report that it expects results to be ahead of expectations, demonstrating sustained and strong growth and momentum across all key metrics, underpinning confidence in further improvement and growth in the current financial year and beyond.
Summary of the key points, with my comments -
5-12% broker upgrades today.
FY 12/2023 revenues £44.2m (organic growth +56%, total +66%) - exceptional growth.
Exit ARR (annualised recurring revenue) £21.1m, up 40% (+50% at constant currency) - note this is slightly less than half revenues, so not as high a % as some other software cos.
Order intake of £56.9m is above revenues, but over what periods? This is usually a multi-year figure, so not that meaningful without more detail of the timescales. Ideally we need a table, showing orders itemised over each of the next 5 years.
Adj EBITDA up a very impressive 237% to £6.4m+
Net cash £11.0m end Dec 2023.
Outlook - strong pipeline, gross margin to rise, “megatrends” over next 10 years in its market, where it claims to be the market leader - that has certainly caught my attention!
Valuation - for a software company, adj EBITDA is meaningless. They need to give us real world profit measures, of adj PBT and adj EPS (providing adjs are sensible).
Cavendish helps out with more detailed numbers in an update this morning -
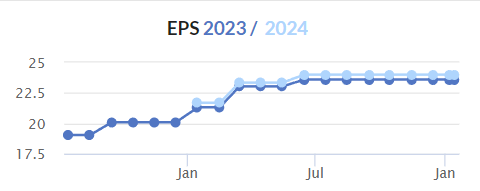
FY 12/2023 adj EBITDA of £6.4m becomes adj PBT of £3.4m, and adj EPS of 4.7p
FY 12/2024 forecast rises to £5.5m adj PBT and 8.1p EPS.
PER is a clumsy measure for rapid growth companies, so I would expect it to be high, which it is - 59x (2023) and 34x (2024) - expensive, and dangerously so if growth doesn’t meet the big forecast increase. Or cheap, if growth is strong, or stronger than forecast, and continues in future years. Someone might bid for the company, lofty valuations for software companies are commonplace.
Paul’s opinion - this seems a really impressive growth company, so despite the very full valuation, I’ll go up from amber to AMBER/GREEN. Well done to holders who kept your nerve during the sell-off last year.
Sometimes when you find an exceptional growth company, we need to just pay up. This might be one such situation, it looks like it to me. Although if growth disappoints, it has a long way to fall from a high valuation.
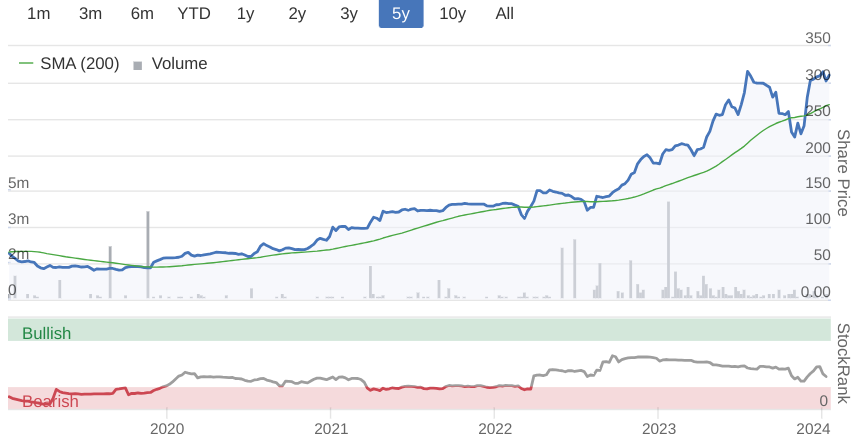
Even I can see that this is a super 5-year chart -
Crest Nicholson Holdings (LON:CRST)
Down 5% to 206p (£528m) - Trading Update (profit warning) - Paul - BLACK (pw), GREEN on fundamentals.
A pattern seems to be emerging of the largest housebuilders doing quite well in tough market conditions (reported so far: Persimmon (LON:PSN) , Taylor Wimpey (LON:TW.) , and Vistry (LON:VTY) - all reviewed in last week’s SCVRs), and the smaller ones struggling more - eg MJ GLEESON (LON:GLE) and now Crest Nicholson Holdings (LON:CRST) issuing profit warnings due to legacy issues.
Today CRST mentions some more problems, on top of the issues announced leading to its profit warning that I covered here on 16/11/2023. It’s looking rather accident-prone -
… comprehensive review of the costs associated with the work required on this project as well as our other legacy sites. Consequently, further additional costs have been identified which will impact FY23 and the Group now expects the Adjusted Profit Before Tax to be £41m for FY23.
In addition, the Group expects to recognise an exceptional charge of £13m (which is not cash in FY23) in respect of a legal claim that it has recently received relating to a low rise apartment scheme built by the Group which was damaged by fire in 2021. The Group is addressing this claim diligently and efficiently and will provide further details in our preliminary results. This is unrelated to the general fire remediation programme that the Group is currently delivering.
Outlook - this is the same thing the other housebuilders have said recently -
The recent reduction in mortgage rates has provided a more constructive backdrop for house buyers and the wider housing market. Although it is too early to gauge customer behaviour, we have been encouraged by an increase in customer interest levels and inquiries this calendar year.
Valuation - no broker updates available to me. Looking at my notes from 16/11/2023, I see previous guidance (lowered range) was adj PBT of £45-50m. So today’s updated £41m figure isn’t too bad, and seems to be due to one-offs rather than general trading deteriorating further. I can live with that.
The main attraction of CRST in particular is the still large discount to NTAV - Stockopedia has it at 0.66, and the 5% fall in share price today will reduce it further. That’s very attractive valuation territory, especially after the whole sector has had such a remarkable surge in the last 3 months. Many others are now at premiums to NTAV.
Paul’s opinion - this is a mild disappointment today from CRST, so a 5% trimmed share price feels about right to me.
The big discount to NTAV strongly appeals to me here, so on fundamentals I still think this is an attractively valued share, so GREEN. Although it has to be marked BLACK for my spreadsheet, in order to flag that it is a profit warning.
Bakkavor (LON:BAKK)
Up 4% to 88.2p (£510m) - Major Shareholder & Director Changes - Paul - AMBER/RED
This company makes ready meals for supermarkets, and operates on a low PBT profit margin of about 3%, after hefty finance costs.
This announcement may or may not be significant, time will tell. It’s unusual though, so thought I’d flag it, and also gives me a reason to briefly review BAKK shares.
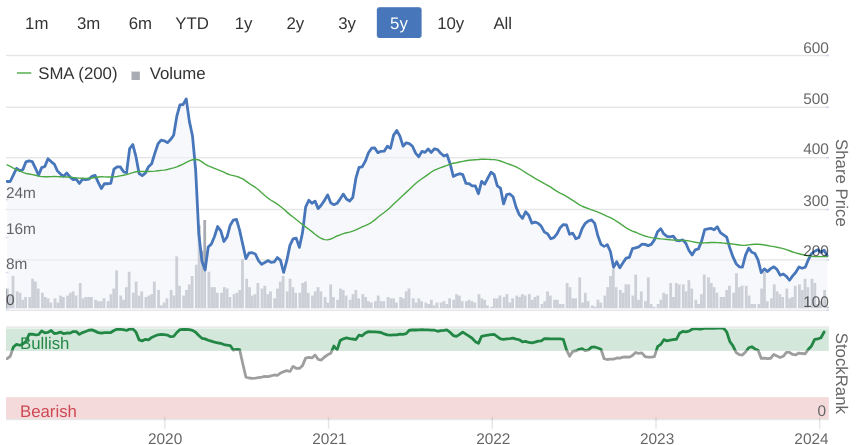
BAKK floated in Nov 2017, shares have done poorly, just over halving over the last 6 years. Although it’s paid out about 26p in divis since floating, softening the losses from the shares.
I only looked at it once in 2023, here on 1/6/2023, where I flagged the weak balance sheet with negative NTAV, and heavy debt. Thus I didn’t see the generous dividend yield as being well supported.
Today’s news is that Baupost, a big US hedge fund, has disposed of its entire 20.1% stake in BAKK to LongRange Capital Fund, which doing some googling is described as a “buyout fund”. Which makes me wonder if it might try to buy all of BAKK, for a potential premium, I’m just guessing there. Today’s RNS says LongRange has $1.5bn under management, not huge compared with BAKK’s £510m market cap. Could it be too large for them to takeover, possibly? Not necessarily, if debt was involved in funding a deal, but BAKK already has a lot of debt.
Baupost’s Board representative will be standing down, understandably.
A relationship agreement means LongRange also gets a non-independent Board seat, through a former NED called Bob Berlin, who knows BAKK well, it says.
So, are BAKK shares any good? I’ve had a quick look at its interim results here H1 6/2023 -
It claims that H1 was “strong”, but H1 adj EPS was down, from 4.6p to 3.9p.
Smaller operations in the USA (breakeven) and China (loss-making) look uninspiring. The main business is UK.
Big increase in finance costs, so adj PBT fell about 10% in H1.
Balance sheet is weak, NTAV negative about £(56)m - the heavy fixed assets are being funded by negative working capital and bank debt. Combining that with paying out almost all earnings as divis doesn’t look a comfortable situation to me. I like “inefficient”, asset-laden balance sheets, not accidents waiting to happen, with all the associated risks of dilution - although to be fair it got through the pandemic without having to raise equity - probably because lockdowns would have helped it sell more ready meals, as restaurants closed.
Supermarkets are notorious for squeezing out the profits from their suppliers eventually, so I don’t see this ever becoming a high margin business.
Paul’s opinion - it’s definitely not the sort of share I would want to invest in, but good luck to any holders. Maybe RED was a bit harsh last time, so I’ll edge up a bit to AMBER/RED, mainly reflecting the weak balance sheet with too much debt, and low margin business model.
Speculative upside could come if the new 20% owner intends bidding for the rest of the company, so a potential trade maybe? Who's right, the 20% seller, or the 20% buyer?! No idea!
Graham’s Section:
Ashmore (LON:ASHM)
Share price: 223.5p (unch.)
Market cap: £1.6 billion
It has been nearly a year since we last covered Ashmore, but I thought this morning’s trading statement deserved a brief mention.
As you may know, Ashmore is an emerging markets fund manager, with particular expertise in fixed income. I like this specialisation as I believe it’s an asset class which many investors might wish to access but where they may feel unable to do so themselves.
Today brings a Q2 update from Sep to Dec (year-end is in June).
Over the quarter AuM increased from £51.7 billion to £54.0 billion.
Comparing market cap to funds under management, I see that we have a multiple of £34, i..e you get £34 of AuM for every £1 invested in Ashmore stock at the current valuation. This is a much more expensive rating than you get at the other fund managers.
Ashmore is also expensive relative to earnings:
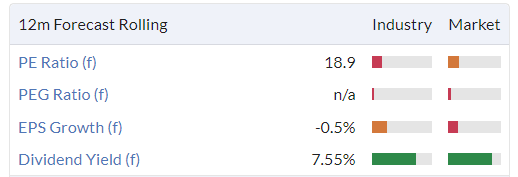
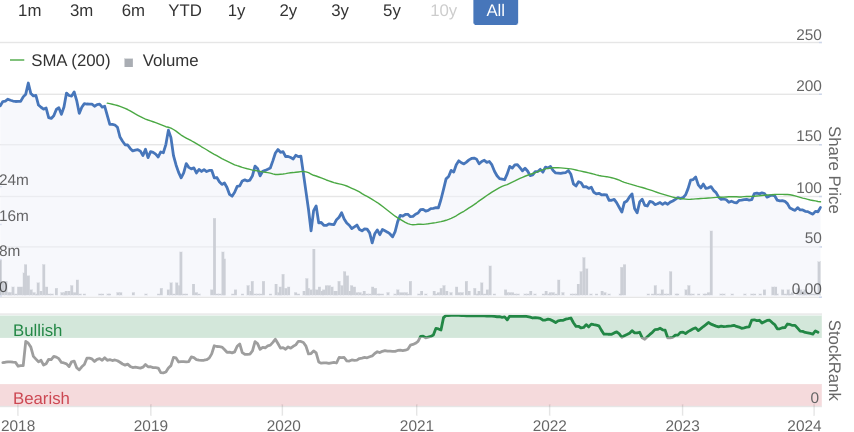
In share price terms, the stock is still lower than it was a year ago, but it has made a nice recovery since December:
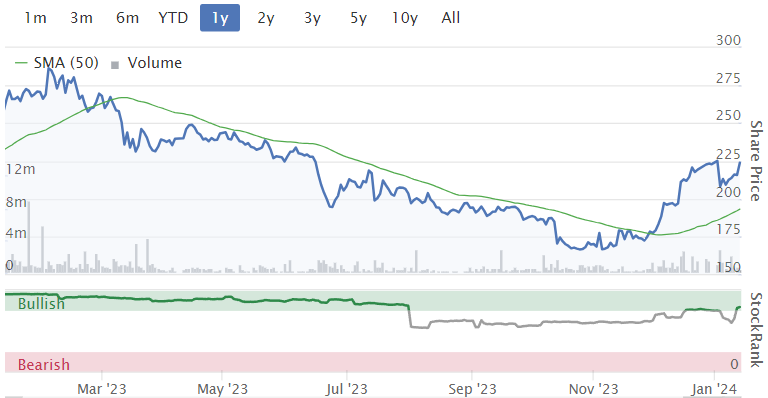
But let’s continue with this morning’s update.
Key points from this Q2 update:
Net outflows $1.6 billion
Positive investment performance $3.9 billion (so again, AuM is growing despite outflows).
Comment:
The Group's net outflows reduced from prior quarters as, while there continues to be some risk aversion among certain investors, clients responded to the improving global macro environment. Equities delivered a net inflow and, within the fixed income themes, the outflows were broadly spread with no significant patterns.
Could there be light at the end of the tunnel? Equities are only a small part (12%) of Ashmore’s total AuM but it seems significant that this segment has seen an inflow.
Checking the Q1 statement, total net outflows then were $2.9 billion.
In the previous financial year (FY June 2023), net outflows were $11.5 billion, or an average of $2.9 billion / quarter.
So a reduction to $1.6 billion in a quarter might be seen as cause for relief, possibly?
Further commentary by the company:
The Fed's signalling of the end of its rate hiking cycle and continued economic stability in many emerging countries delivered strong performance across Emerging Markets over the three months. Fixed income indices rose by 6% to 9% and equities increased by 8%, and the majority of Ashmore's strategies outperformed over the quarter.
Graham’s view
I’m a long-term fan of this company and perhaps have a blind spot when it comes to the bear case against it. But as Ashmore itself says, and I agree, the likely imminent turn in the interest rate cycle and a resumption of “risk-on” could see a big swing in sentiment in favour of emerging markets.
The S&P 500 and the US dollar have been so strong for so long - both before and during the tightening of interest rates - that they have seemed to almost swallow up the demand for other equity markets and more exotic currencies. But could that be about to change?
We should bear in mind that Ashmore always says that investors are underweight in their allocations to emerging markets. But personally, I’m inclined to agree with them.
While I do lean towards taking a positive stance on this stock, I’ll moderate it and take a neutral position this morning. Its earnings multiple is much more aggressive than other fund managers and perhaps already prices in a recovery.
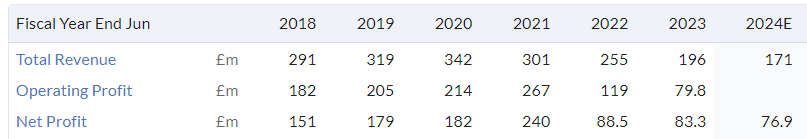
Ramsdens Holdings (LON:RFX)
Share price: 205p (-5%)
Market cap: 64.6m
I just came off a quick call this morning with Ramsdens management, so many thanks to them for taking the time out to speak with me.
Before getting into the contents of the call, let’s review today’s full-year results for the year ended September 2023.
We have strong growth in the key measures of profitability, along with growth in net assets:
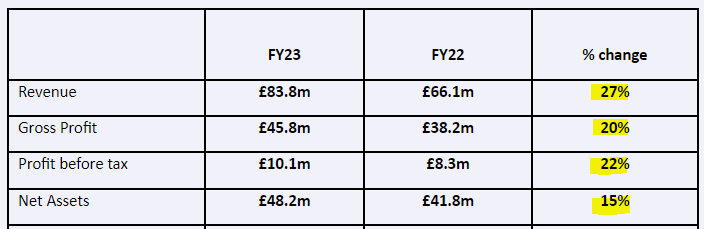
The result “was driven by strong performances across all four income streams” (pawnbroking, foreign exchange, retailing, and gold purchasing).
Foreign currency: gross profit up 7% year-on-year to £13.6m, ahead of pre-Covid levels thanks to larger transactions with customers and higher margins than pre-Covid.
However, “the key summer period was slower than originally anticipated”.
The company points out that more than 50% of purchases in Portugal, Italy, Greece and Spain use cash, which suggests that cash will remain in demand from UK holidaymakers.
Ramsdens did launch a new multi-currency card in September, to capture non-cash transactions, but it only generated minimal revenues before the financial year-end.
Jewellery retail: revenue up 23%.
Pawnbroking: active loan book up almost 20% to £10.3m. The company is not expecting to achieve the same level of growth in FY 2024. Repayment rates are in line with the long run averages.
Precious metals buying: revenue up almost 50% to £23.5m.
Net cash falls to £5m (£8.8m a year ago) due to the expansion of pawnbroking and jewellery retailing operations.
CEO’s review: describes it as “a great year”, delivering record profits.
Store expansion: eight new stores were opened during the year, including 5 in Yorkshire and the North West, and 3 in the South East. This has thankfully gone very well:
We are pleased to say that all new stores are trading well, with several well ahead of expectations. We ended the year with 160 stores and two franchised stores.
Q1 trading update
We also have an update for October to December 2023 which is in line with expectations:
Foreign currency: gross profit flat on the prior year. Comment:
While we are encouraged by growing sales of FX, purchases of FX from returning holiday makers are still subdued, indicating they are keeping their leftover FX cash for another trip or have spent their cash while abroad.
Jewellery retail: revenue is “broadly flat”, though gross profit is up 5%.
Pawnbroking: the loan book is already up by a few percentage points in the quarter to £10.6m.
Precious metals buying: gross profit up more than 10%, “due to growing awareness of the service offered by Ramsdens and the continued high gold price”.
Management call
I had a brief call with Peter Kenyon, CEO of Ramsdens this morning.
My questions were:
1. Store expansion. Is the company finding that there is more competition in the South East? I was thinking in particular of competition from H & T (LON:HAT) who have 270 stores and are very strong in the South East.
Answer: Mr Kenyon said that staff training was the biggest challenge with opening new stores as you have new staff who have to handle increasing amounts of business as the store matures. He said that competition was not a problem with these store openings, and the company planned to continue expanding in the South East.
2. Gold price risk. How does the company manage this?
Answer: Mr Kenyon said that gold was about 15% of pawnbroking items and that the company’s pawnbroking policies were very conservative, i.e. for gold with a value of £19 the company would only lend £12.50. He also mentioned that their prices for buying and selling gold are adjusted every single day.
I mentioned Albemarle Bond; it’s worth noting - and Mr Kenyon reminded me - that he has been with Ramsdens for many years (since 2001) and that he was with the company when it went through the 2013 gold price volatility.
Ramsdens subsequently went through a private-equity backed management buyout led by Mr Kenyon.
3. The company is valued on a P/E multiple of only 9x despite showing strong growth. How does the company explain this valuation, or how it would argue for a higher valuation?
Mr Kenyon rightly replied that he can’t control the share price and that he can only focus on making the company as cash generative as possible, pay the dividend, and keep making the company as strong as possible, but naturally he agreed that this valuation seemed low.
4. Cash policy. The company has £5m of cash. If it wanted to borrow to invest, it probably could but does the company prefer to keep a net cash balance long-term?
Mr Kenyon said that the cash balance was important e.g. in terms of managing the gold price risk, having a cash balance means that the company would have a buffer to protect it.
Estimates at Liberum for underlying PBT are unchanged for the current year, FY 2024. They raise their revenue estimate but reduce their margin estimate due to a greater emphasis on jewellery retailing. The net result is no change in the underlying PBT estimate, which they see increasing from £10.1m to £10.5m.
Graham’s view
I’m remaining positive on this stock. In my view, little has changed since we last looked at this one (in October). The main development is that we now have further confirmation that the store opening programme is going well.
It seems that the market is big enough to allow for the expansion of Ramsdens into the South East. Remember that its mix of services is different to H&T, who are far more heavily focused on pawnbroking.
Having spoken with Peter Kenyon, I have the impression that the company is in fact quite risk-averse, despite its growth ambitions. I think they are very aware of the dangers of over-extending either physically (through store openings) or financially (through leveraging up its balance sheet).
I think the best argument for the current share price is that the company’s growth expectations for FY 2024 are quite modest: revenue growth of 6% and underlying PBT growth of 4%.
Higher costs are expected to bite this year, including higher energy costs (£0.4m higher in FY 2024 due to the expiry of a fixed price energy deal) and a 10% increase in the real living wage.
However, I see these as minor short-term issues, not as problems that should detract from the long-term investment case.
The company has previously under-promised and over-delivered. I wouldn’t count on that happening again, but it’s something to be aware of:
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

82 comments
On Graham's comments on Ashmore just looking at MCAP/AUM, then concluding this is expensive misses an important point.
Ashmore has c £750m seed funds invested, or about half the market cap, adjust for this and the valuation is much much cheaper...
Hi Rob, thanks for the comment. Ashmore's June 2023 report shows £291.5m of seed capital investments (Note 20). Do you mind if I ask where does the £750m figure come from? G
Hercules Site Services (LON:HERC) - "Strong conclusion to FY23, positive start to FY24" (link to research report here: https://www.equitydevelopment....
Hercules has reported strong full year results, with profits well ahead of our expectations. Against a supportive backdrop for infrastructure investment, we believe momentum is building and a positive outlook statement anticipates another year of growth in FY24. We reflect this in our revenue forecasts, whilst noting that an increasing interest charge will reduce profits in the short term.
All three divisions contributed to the strong growth in FY23, but Labour Supply remains, by some distance, the largest element of the Group. This division accounted for 75% of Group revenue and 65% of gross profit whilst also delivering the strongest revenue growth in FY23 (+92%). This was driven in particular by additional demand under the Balfour Vinci JV contract on HS2 (London to Birmingham), which still has several years to run.
The outlook statement strikes a positive tone, highlighting new revenue streams which should make a positive impact in FY24. Further organic progress therefore looks well underpinned and November’s Future Build acquisition (Hercules’ first deal) adds another leg to the growth story.
Hercules trades on a FY25 P/E rating of c.16x and a dividend yield of 7% with scope for good earnings growth over the medium term. Our new Fair Value / share estimate is 55p (from 60p), representing a FY25 EV/EBITDA rating of 11.5x
Interestingly I had tried to trade Filtronic (LON:FTC) today through IG but it was only accepting Sells.
Is Michelmersh Brick Holdings (LON:MBH) finally braking out? Broken recent high, but still slightly below previous highs. Looks like its broken up out of the downward channel and possible a golden cross about to happen.
Paul Hill of Vox, largest holding
React
Slightly strange lunge downwards of 6-10% from 145 to 135. For an RNS announcing Dowgate as joint broker
Some forum comments meaning a placing is coming .
Easy to sell
hard to buy
So I think it’s heading straight back up .
Ramsdens Holdings (LON:RFX) Thanks for the review on this and sharing those questions with Peter Kenyon. I do think he is very risk adverse but also likes to under state. Very much like Archie Norman from M&S, but then he did work under Archie many years ago. I have met him a few times and I would say he is very astute. I no not hold.
SCSW (scsw.co.uk) published their 2024 NAPS in the latest issue which came out on Saturday. Gone are the days when their tips used to move prices by 10-20% on Monday morning!
Their 2023 NAPS gained a meagre 2.4%.
Did any of their NAPS crossover with Pauls? They've had Volex several years in a row when I used to subscribe
Sorry, wrong NAPs.
Ramsdens Holdings (LON:RFX)
The company points out that more than 50% of purchases in Portugal, Italy, Greece and Spain use cash, which suggests that cash will remain in demand from UK holidaymakers.
Ramsdens did launch a new multi-currency card in September, to capture non-cash transactions, but it only generated minimal revenues before the financial year-end.
wowsers - i don't doubt that cash will remain material - but should we not be expecting material or accelerating move away from cash? as far as uk holiday akers are concerned ?. How much cash should we be expecting in 5 years time ? - deffo seen peeps in this country who were big cash fans are now nearly entierely onto electronic where possible. I have noticed that those that i know that used cash traditionally use starling/revolut/nationwide etc - can Ramsdens hope to compete with other methods of paying for overeas expenses at same levels?
If overheads ref curency is fixed is any expected continual decline not going to hit them hard? ie if that gross profit dries up will the overhead costs not stay stubbornly high if staff are needed on site anyway.
I am far from predicting the death of fx income buit in soem respects i would feel much more comfortable if it was already much lower element of gross profit. Do holderes think the fx is sound as a pound medium term?
Ramsdens Holdings (LON:RFX) - I suspect we might need to differentiate between the general trend towards increasing card use abroad and the trend as it applies more specifically to Ramsdens customers. I reckon they know their customer base very well and know that these are people who have to budget their holiday spending, which is why they take cash rather than hitting the resort with their debit card. It will be interesting to see how extensively their new currency card, which has similar attributes to cash, is adopted by their customers over time.
I do agree with other comments regarding the management's instinctively cautious outlook. The outlook comments accompanying the previous year's results were strikingly similar - "some bits doing well in Q1, some bits not so much, too early to say how the year will play out" - the positivity appeared further into the year. I suspect they will continue to do just fine.
Having cycled through Austria in the summer. We found we did not take enough cash. Most small cafes wouldn't take card. Signs everywhere cash only, even in Vienna. Restaurants generally took cards 30 -40 euros minimum spend on one card only. Wouldn't accept two cards payments from two couples. Had similar experience in Majorca. Can only assume the card company fees are excessive. Cash seems in some places, is still king.
Yes it is the same in many Asian countries, cash only or if you pay by card, they charge you a fee, around 3%. Even fairly developed countries such as Thailand. Even in Japan, a major chain Hotel, was charging fees, if paying by credit card.
cheers for that - i remember the same used to be the case here. perhaps the law change in 2018 was the impetus needed here for the change to take place - retailers here cant charge extra now so that probably did the job of getting fees down to reasonable levels perhaps as volumes grew. Perhaps the change wil take waaaay longer than i fear then - i do kinda think once you are used to tapping with phone it is more convenient so i must admit so it all seems strange that other countries are not modernising - hey ho if they aint they aint.
Thank you very much for your comments on RFX Graham, I dont mind investing where management are cautious yet still growing the company. We'll add to what is now in our top 5 investments by valuation.
little bit of news on CMC Markets (LON:CMCX) Haven't seen any new numbers from Peel Hunt or Numis.
Consensus figures seem to be March 2024 PBT 12m.> 2025 34m > 2026 49m.
With EPS of 3.3p>. 9.2p. >13p
If Shore are expecting 41m that's between 2025-26 consensus. Maybe around 11p?
Another bullish update in a month or two would certainly help.
"CMC's surprise and brief statement last week portrayed how sharply fortunes can turn in terms of quarterly trading momentum," Shore analysts commented.
The London-based firm lifted guidance for full-year net operating income to between GBP290 million and GBP310 million from GBP250 million to GBP280 million. This will be up from GBP288.4 million in financial 2023. The financial year for CMC ends on March 31.
The company reported a "strong performance" in its financial third quarter, amid improved market conditions and led by an increased contribution from its institutional business.
Shore predicts CMC will achieve a pretax profit of GBP41 million for the current financial, a much more bullish prediction than the GBP15 million it previously had.
"This is the first upgrade we put through in the last one and a half years, following an extended period of downgrades after successive revenue and cost disappointments. These upgrades entirely reflect Trading division revenue," Shore said.
Shore added: "The balance of risks to forecasts feels to the upside now, which motivates our change in recommendation to 'hold'. Interims on November 16 hinted at scope for cost savings, which we expect CMC to confirm later this year. Furthermore, if the drivers of revenue improvement in CMC's January 8 update are sustainable, we could take a more constructive view on CMC shares."
I really do think Paul and Graham do a fantastic job with this report and their podcasts. They are so full of enthusiasm for investing and sharing information. Without a shadow of doubt the best 2 originators out there
I also like the way it evolves with little tweeks to its format
Paul you deserve a beer, but sorry you cant is dry January
Thanks Alex! Beer is the devil's urine! :-D
Devil’s Urine? must be a craft beer in the Bournemouth area…
I thought some was K9P?
Whiteadder reference!
To go back to Filtronic (LON:FTC) I think it worth looking at some of the figures there. The basic stock report figures are, frankly, poor. Who would invest in a company like this?
And yet. In 2021 there was a change in management, with a new CEO in February 21 and a new chair in November. The following 12-18 months were difficult, as supply chains meant that fulfilling orders was not straightforward.
In a recent update they have said that results are going to be in line with expectations, so nothing exciting is expected in the results to be announced next month. The FY ends on 31 May, so the next results will, if I understand correctly, be HY 24.
What has changed is the new contracts being agreed that have yet to find their way into the figures. I'm going to set out the contract wins announced over the last couple of years:
October 21: $0.8m for pilot phase 5G, expected to mainly be billed in 2023
June 22: follow-on contract for the above, now expected to be $0.9m, again, mainly in 2023
June 22: new filters contract, £350k, expected to be recognised in 2023
July 22: filters with existing client, £400k, expected during FY23 with follow-on potential
July 22: defence client, £500k, expected to be delivered in 23
Jan23: low earth orbit (LEO) satellite contract worth £2m expected to be recognised in 23. At the same time the trading update said supply chain shortages meant:
"Revenue in H1 FY2023 was £8.4m (FY2022: £8.0m) representing 5% growth, with
£1.0m of adjusted EBITDA. Strong demand has carried through to H2 which is
reflected by the current order book of £17m but we are currently experiencing
a shortage on a number of unique semiconductor components which is impacting
our ability to meet customer schedules in the second half. Our efforts to find
the components from alternative sources in the secondary market have so far
been unsuccessful. Consequently, this near-term timing issue will result in
weaker trading in FY2023 than current market expectation. As these temporary
shortages unwind, we expect an uplift in revenue and a resumption to plan in
FY2024."
So, we are being flagged up, 12 months ago, to expect 24 to be better than 23.
April 23: defence contract, $0.8m, in FY24
July 23: EUR3.7m contract from European Space Agency, part of FY24 forecast
Sept 23: £3.4m LEO win, expected in FY24
Dec 23: £4.5m RF contract win starting Q4 CY 2024
Dec 23: £4.8m LEO win with revenue to be recognised in CY 24
Today: £2.m RF win with Qinetic, phase 1 only, to be recognised over next 2 years
In other words, quite suddenly, around a year ago, the size of contracts increased markedly. In 22, 4 contracts were announced, worth around £2m. In 23, over £15m were announced. None of these are likely to have found their way into the first half figures to be reported next month. In addition, we were told that a lot of the "business as usual" from financial year 23 will be rolled over into 24.
It seems to me, based on the information that we do know, that Filtronic are going to issue results that show very significant growth very soon. And from the frequency of sizeable contracts being announced, the momentum seems very strong.
Am I missing something?
Filtronic (LON:FTC) Am I missing something?
The obvious question is whether a PER of 36x for FY25 doesn’t already discount the strong likelihood of outperformance arising from all those contract wins. Frankly, I haven’t a clue!
Even at 12p the price I started to buy at seemed expensive looking back, but you do need to look forward. The IP as planetx stated needs to be worth something right? A friend of mine who worked at Toumaz and Frontier Silicon spoke to me last year about this. He 'heard' on the grapevine that the semiconductor area that Filtronic (LON:FTC) operate in is off the chart in terms of new technology, and as this was his area of expertise, I did have to listen.
There's all kind of government involvement which generally speaking cannot be discussed, but he's not an investor, although said he would recommend 'I have a couple of quid on it', so I have bought in tranches and this is a full position of mine now, I may have to slice just in case the bears come rolling in.
Perhaps the risk is just 'extrapolation'. As with most small caps it is difficult to predict longer term earnings and trends.
So now Filtronic are performing much better - could this be an inflection point? Or could this just be a short term period of good performance?
To extrapolate out these contract wins and to assume they will now keep growing at this clip is risky - after all the stock does not look cheap on conventional metrics - so it is priced for continued improved performance.
So the way I see it, you could be entering at the perfect moment, just as the company is turning the corner after years of difficult trading. But at the same time, the good news flow could slow and the growth story could stumble and fall heavily on a single update - as I have had the misfortune of experiencing on many a small cap with a great growth story. Basically what I am trying to say, is that positive trading doesn't always last forever - and this type of business perhaps could go either way as it is in what appears to be a specialist niche area that is perhaps difficult to predict.
I don't hold or know anything about Filtronic. So I have no idea the strength of their product / offerings or the potential for increased competition. I just think it is a dangerous thing to extrapolate to much when dealing with UK small caps (as I have found to my own pain), and perhaps the market also agrees and is generally cautious when extrapolating to far out.
Long term trend for LEO , hard to see a reversal given the current position and the need to increase coverage .
Suffice to say and of course DYOR that being a supplier to the company rolling out the below then for me it’s a relatively low risk , PLUS importantly there is an intrinsic asset value in their business not reflected on balance sheet as explained earlier
Just think the sweet spot isn’t going to go away and they just lucky that the product they developped previously is becoming a key component in a new worldwide program .
“As of early January 2024, it consists of over 5,289 mass-produced small satellites in low Earth orbit (LEO)[5] that communicate with designated ground transceivers. Nearly 12,000 satellites are planned to be deployed, with a possible later extension to 42,000. “
It’s been coming for about 12 months and let’s see if any new orders pop through in the next weeks / months .
Hi planetx
I do not hold Filtronic (LON:FTC) but are you absolutely correct about their IP. Special situation; same as Nanoco (LON:NANO) IP.
All the best
Of course I meant that you are absolutely correct.
Sorry it’s Monday!
Pendragon
All moving parts here .
Big “special situation” evolving here that posh bloke Christopher Mills explained in great eloquent detail in a recent interview .
In a nutshell
After sale goes through a big chunk of cash retorted to shareholders (by memory Circa 25p)
Resulting business he rates as very valuable way in excess of the 7/8p differential share price
So you can’t buy on trading account as exposed to CGT on your 25p
But if you bought in pension it’s a nice arbitrage easy win .
Two big RNS today Newton gone from 5 to 12% and UBS in at 5%
Felt like a no brainer but you need cash to make it happen but if you have cash in pension sat there this is a good looking opportunity
Hi PlanetX, is there any indication of when this might go through? I plan to take advantage but don't want to lock cash into Pendragon (LON:PDG) until as late as possible as I can be utilising it elsewhere in the meantime. I remember listening to the podcast thinking I didn't want to be locked in with nothing to show for 6months or so.
Hi Planetx
You def don’t want to be buying Pendragon (LON:PDG) outside of a tax shelter such as an ISA as the 24p returned in cash is by way of a dividend so would be taxed at your marginal rate - ie 7.5% up to 32.5%.
I am considering a purchase but the real question is this. The bid was at 35p so there is a 2p differential (theoretical arbitrage) by buying now. But once the dividend is returned will the residual share price of c. 8p just shoot up to 10p+ on sudden buyer demand as the rump of the business is released or will it flatline or maybe even drop if there are sellers about? I think Mills’ rationale is that the shares will rally as investors who want to buy currently can’t because of the tax implications of the deal structure (or at least only in a certain size).
But you could tie up a chunk of money of which 3/4 you will get back in x months time and the rump will be a buy of the sexy remaining business at 8p. That may appeal depending on time to completion and your view on lost opportunity cost. At just 5% that equates to 1.7p or almost the entire difference between the offer price and current price.
I’m a bit torn between buying soonish and waiting until the completion and hopefully picking up sub 10p. I am waiting on proceeds from the Ten Entertainment (LON:TEG) takeover which should be this month so that may swing it for me.
Pendragon (LON:PDG)
My guess is that there'll be a lot of churn in the shareholder register post the deal so the 'stub' could be quite volatile, but this will provide an opportunity.
Funds that are Pendragon (LON:PDG) holders may not fancy an undersize position in a tech business and so will look to liquidate their holdings. Other funds taking an interest will not be able to value the business in a 'clean' manner, nor easily acquire a sizeable position in the de-merged business and so will unlikely be day-one buyers.
In summary, I think the price could go either way but a further dip on those re-sizing portfolios will present a further opportunity once the shake-out subsides.
I've bought for the ISA / SIPP expecting a deal in Q1. I'll top up my position on the residual business if an opportunity presents itself but need to do a bit more research.
ie 7.5% up to 32.5%.
If only the rates were still that low - sigh
Lol yes of course - 8.75% up to 39.35% these days. Wishful thinking on my part……also ridiculous imo
also ridiculous imo
they have to raise taxes somewhere - its our many years of folly adding to our national debt to blame (14k each is it??) bearing in mind the lack of recession between 2008 and 2019 they were golden times of stability when we should have been tackling the debt issue. we the people have only ourselves to blame for voting in these muppets (i would quite happily have a random selection of dinner ladies running the country on old skool values if that was a voting option)
I dont have any answers other than those earning over 50k are more able to pay more than those earning less and those with dividend income have genrally being paying less than employees / sole traders . HMRC provide very generous tax mitigation options that aid the frugal amongst us that are lucky to earn a decent packet. So my sympathy for the better off who choose to spend is limited , albeit perosnally i wouldt ever want to charge more than 40% overall (39.35% on top of copr tax is certainly over that !!) - that would be the case whether i am impacted or not.
really that's my point. Once you get close to 50% tax you provide a significant disincentive around tax collection. I have more than 1 friend that went abroad when tax rates hit 45%. They were happy to pay 40% - even 42% (given the sneaky NI) but that was the proverbial straw....... and so now other countries get their tax pounds and the UK doesn't.
Financial services (mainly London) accounts for a disproportionate amount of GDP right across the country. Many people don't realise the impact its health has on their standard of living. They think that because they live in say Lincoln (random town) it's all irrelevant to them......it isn't! The media doesn't help.....
So when the stock market is pretty much on its knees; when the US and Asia gets to play on a much more favourable playing field and the EU are chuckling away because they managed to slide in rules that didn't really harm their non existent financial markets but damaged London's standing......well, to disincentivise investing through over taxing is, imo at least......negligent!
David
I agree 100%
I’ve just taken a small position with what little funds I have in my pension .
Maybe post transaction the share price will be pinned down by the churn of shareholders
But mills made a pretty compelling case that the residual business was worth way more than 7-10p a share
Taking a small interest always means you pay more attention than having watch list at least in my case
Thank you for covering CRST Paul, we hold and can live with the modest fall so far today. Much more disappointing is the response to Ramsdens results so far today, we hold and I thought they were good results with a decent dividend rise. I'd appreciate any comments from this community pointing out why my confidence in RFX is misplaced. I am tempted to add at this level.
Hi JASVFS. Re. Ramsdens Holdings (LON:RFX) I'm not an expert in the company, but I think it was the rather soft wording on current trading that has made the market react with a slight sell-off. FX section mentions "flat" and "subdued". Jewellery revenue is "broadly flat" i.e. slightly below. "Mixed performance" within categories and channels.
Then the CEO's section added a layer of negativity in my mind. This is almost a litany of excuses for potential poor performance later in the year (even if the factors are real): "While we are very conscious of the tough economic conditions and the cost pressures of energy pricing, increased interest rates, and paying the RLW, we have confidence that our long-term strategy, which remains unchanged, will deliver long-term benefits for all stakeholders."
The confidence in "long-term strategy" rather than "this year's forecasts" is telling I think.
Ramsdens Holdings (LON:RFX) I hold.
The outlook statement is cautious, but this is perhaps with a view to underpromising and (modestly) overdelivering.
Marks and Spencer (LON:MKS) (I hold)
Not a small cap but despite a rather muted response to their Christmas trading update I note multiple recent f/c PBT upgrades on Sharepad for FY'24 (to 31/3/24) as follows;
13/12/23 f/c PBT increased from £610m to £617m
18/12/23 upped to £629m
8/1/24 upped to £636m
10/1/24 upped to £644m
12/1/24 upped to £655m
15/1/24 upped to £674m
That's an increase of 10.5% in 4 weeks!
Snazzy
Not todays news as such but it does appear that MS International (LON:MSI) selling has stopped. Looking like relatively small buys now pushing up the price as little offered on the other side.
Was thinking about the business case over the weekend and it feels to me as though drone warfare is now pretty extensive, so anti-drone guns should inevitably do well. I see there is an Aussie competitor that has a jammer called drone shield that is also doing well. Feels like these are somewhat complementary products rather than competitive but I’m no expert. In the defence space it is all about credibility and reputation and MS International (LON:MSI) have bucketloads of strong references here. Despite the rise from 200p over last couple of years I’m surprised they are still so lowly valued. Feels like 80-100p eps isn’t far away and with the net cash position they are really a single digit PER business with huge blue chip clients like the US military, providing innovative solutions into an expanding market.
I’m probably just talking my own book and therefore inevitably biased but just struck me over the weekend and noticed the price movement this morning. Very little chatter on it which I def prefer as certainly not overbought with hot money either. Any other interesting insight on the market landscape I’d be keen to hear.
MS Int
A good friend of mine and ex special forces (still trains then) was down last week and was saying the use of drones in Ukraine has changed the landscape of how the battles are fought .
Agree on MS valuation and they should start spitting out cash as can be seen by the cash increase
As my old FR used to say
“Cash in the bank doesn’t lie”
MSI has several negatives though: almost two thirds of the business (probably a shrinking proportion) is petrol forecourts, branding and forgings. How that fits with the other part (anti-drone weapons) is not clear. The weaponry is where the growth is.
About two thirds of the shares are owned by the directors - a positive, but it makes the shares illiquid and prone to lumpy share price movements. No brokers cover the stock.
Yes - agree with both of those points : MS International (LON:MSI) is a bit of a conglomerate though those areas of the business seem to also be growing. I suspect they will become much less material in years to come but may be why they are not rated as highly.
They are now of a size that brokers really should be covering them - a question for management I think. Some research would help a bit.
MS International (LON:MSI) (I hold).
David, since you asked. Though not sure how insightful this will be. The landscape is complicated and very different for Naval and Landbased systems - as is MSI's place in the market. Even so I'll try to keep it short and simple. Probably over-simplified.
But first a general observation. For decades many national defence strategies have pursued a 'missile only' air defence programme. The UK has been a leading advocate. Gun's have been regarded as effectively obsolete. It's this approach by the UK that led MSI to focus upon the US market over a decade ago. Quite correctly in my opinion. But now the game is up and there is going to be quite some chaos in many overspent defence ministries as they try to spin having invested in the wrong strategy? It will also be quite an opportunity, but politics and big-industry lobbies can lead to strange decision making in a crisis? The sniff of budgets and contracts has all the pigs at the trough? There are a lot of options for weapon systems, ammunition types, calibres, mounts etc all being pushed hard by all these industry players and comparing apples with oranges is not easy.
Naval Systems. There is plenty of established competition in the Naval market and new entrants arriving. Nexter (France), Aselsan (Turkey) Leonardo (Italy), Northrop Grumman (US - mainly turret mounts) and amongst new entrants EOS (Australia) and Rheinmetall (Germany). And both Russia and China. Opportunities like the US fleet roll-out of the mark38 mod4 come around about once in a generation. BAE (owns Bofors) was the incumbent for the Mark38 mod3 but lost out to MSI the 'new' kid on the block. BAE don't seem to be giving up and are marketing their losing upgraded mark38 mod3 as an anti-drone solution.
As you rightly say MSI has quite a pedigree in naval systems. They've been making firecontrol systems and mounts for over a century (not as Mining Supplies International but as Lawrence Scott of Norwich which MSI bought several decades ago). Winning the mark38 mod4 as sole source provider across the US fleet (initially CVN, DDG and USCG polar cutters) is a game-changer for MSI. Partly for the prestige, partly for the base-load of work of work it provides stretching into the future, partly for the support, spares, maintenance and repairs that stetches even further, and also because the USN have written a new module for the AEGIS combat system which fully integrates the mark38 mod4 into the vessels combat system. No longer out in the cold. In my view it makes modern small-calibre remote weapon systems a formidable part of the combat system. Proper Star Wars if you like. Here's a link to a twitter discussion on the likely role played by MSI's older DS-30B weapon system on HMS diamond when used recently https://twitter.com/R_P_one/st...
Land systems. MSI are a new entrant to land systems. Plenty of competition, same list as Naval and add a few more. But the market is growing very fast and likely to be enormous. Successful entry to this market is likely to be transformational. Again. It seems that MSI had been developing a system specifically for the counter drone role and defence of critical infrastructure prior to the Ukraine war and had supplied an earlier version to a middle eastern country. Paladin (the DROPS-based truck transportable system) is at least v2. Which is why its gone into service in Ukraine so fast. Almost all of the competition have taken existing mobile or transportable anti-aircraft systems and added the counter-drone role. Generally a compromise solution. Most of the existing systems are much more expensive. Some of the mobile ones are probably cheaper, but likely not as capable nor effective. MSI has a relatively unique position in the defence of critical infrastructure - which is now suddenly seen to be extremly important. And a price to performance and reliability point which is quite possibly well ahead of the competition. Link to Rheinmetall Skynex video
Reputedly it uses a lot less ammunition to achieve this. With swarms of drones now attacking the old 'wall of lead' approach is no longer viable. The definition of effective performance is the fastest ability to down the target and move to the next. We can now add - with the least use of ammunition. How is this achieved? That is MSI's magic. There is no silver bullet, just constant improvement in every piece of the system, and not just on day one but through the life-cycle. I think this will be an important selling point in the future.
Anyway. I've droned on enough! Sorry! Really. This is the short version and you did ask. I think you pressed the...
For my money - and it is around 45% of my portfolio - the Naval systems market, the other 3 divisions and the mounting cash pile justifies a market cap significantly above the current price. For what its worth, the prospects for the other 3 divisions also look good, with forging (benefitting from reshoring of supply chains and growth in the forks market) and superstructures (benefitting from repurposing and change in ownership of forecourts) well invested in recent years and likely to continue the trend of growth. Branding now on the mend and has ability to scale up rapidly with high margin work and operational leverage if it can capture the opportunity.
Which makes the landsystems market the icing on the cake for me. The opportunity is enormous. I am not yet convinced that they have traction in this market. The competition is ugly and doesn't play fair. I'd like to see another landsystems contract in the next few months - if that happens - then it potentially doubles the value of the company again in my view.
cheers
Mark (believe it or not I am not a big fan of guns. But then I'm not a big fan of drones. Especially not killer drones).
Mark
super commentary on MS International (LON:MSI) and really well written. I knew some of that but far from all so I find the level of info you've added here really helpful, particularly around the competition landscape, so thanks for taking the time to put "pen to paper".
I can't quite work out given what they've achieved with the US and coupled with the other 3 divisions firing (no pun intended) why they trade down here. As another reader noted maybe the complete lack of broker research doesn't help. I'm relatively patient with it though having held from 200p and I, like you, can see it worth well more than double the existing price. Real success in the land based anti drone warfare would be transformational though. This is a market cap of £150m and almost a third of it is in net cash.
Thank you Michael for your Stock Picks for 2024. I always enjoy your videos but I cannot understand the modern idea of playing background music to the tape. So irritating. Must be my age!!
The Cohort (LON:CHRT) Interum results look good to me. You can see the summary at https://www.cohortplc.com/investors/results-reports-presentations. Worth a read. Looking forward to Paul's review on it.
I watched the royal institute Christmas lectures over the weekend. Obviously it’s aimed at children, but it was a surprisingly good introduction to the current state of AI.
Filtronic
Seems to divide opinion on here .
Not my normal cup and f tea but have listened to the CEO was pretty down to earth and solid .
Category Low Orbital Earth satellites is seemingly red hot and with customers such as Tesla and Amazon seemingly forced to buy their products due to their IP hard to see them not doing well .
Bear case is they’ve never made much money and are low margin and have promised before .
If I was buying this company outright I would buy it based on the value I’d the IP which is really the “sweat labour” the company has put in with the past years of non delivery of profits .
But great IP and established production sector in a red hot sector that forces the players to buy from them is what is seeing this influx of orders and rerating .
Plus I liked the CEO and FD they were grounded . Humble and looked like they cared about their investors
Excellent podcast at the weekend Paul - always much appreciated.
Listeners will be relieved to learn nothing sinister underlies your unproductive cough (other than perhaps some subliminal podcast "stage fright"?)!
As for the associated "lifestyle factors" which aggravate a range of conditions, including your latent acid reflux, the old adage which applies is that the greater the pleasure afforded by any recreation or consumption, the more likely that it is: illegal, or immoral or fattening or a full house! (Note: the fattening being a proxy for the broad range of health impacts gleefully exaggerated by the puritanical food and drink police).
J D Wetherspoon (LON:JDW) this morning: "We are glad to be able to help slow learners at the Independent." Priceless - I wish we had more CEOs like Tim Martin!
Ah! You've stolen my thunder, I was just about to flag that LOL! Absolute classic isn't it :-)
Good old Tim. You can always rely on him to come out with great statements, unlike newspapers who you can't rely on for accurate news!
J D Wetherspoon (LON:JDW)
its beyond annoying really - its only 9 days ago since other newspapers apologised for spreading the same/similar lies yet again - presumably it was some syndicated story that keeps getting rehashed. It portrays the press in a very bad light that its clear they print owt and take no responsibility to quickly correct things when they get it wrong and when they do get wrong not repeat their crapola - and they are happy to keep repeating. One would think when they keep repeating the same lies after being told it would amount to slander. Fair play to the company for holding the press to account to soem degree - shame the press regulators dont take stuff like this more seriously , if they can act like this with companies like wetherspoons what chance does your average bod have ensuring they aint being slandered in the name of making a quick buck - sigh.
Could you tell me please when the U.K. press, or media was ever seen in a good light ? Certainly not in the last decade or so . Absolute shambles
The reputation of the UK press is long established. 90 years ago Humbert Wolfe famously wrote :
You cannot hope
to bribe or twist,
thank God! the
British journalist.
But, seeing what
the man will do
unbribed, there's
no occasion to.
You obviously don’t read The Guardian.
"Tell a lie often enough, it becomes the truth"
Has been used as propaganda for generations. Media are doing it on purpose so it becomes subconscious when the average Joe thinks about him. They'll repeat the lie again in future I've no doubt.
Having been directly involved in many news worthy events over the last 35 years I can unequivocally say that the printed press rarely report sincerely about a situation. They do whatever is required to see their products. I don’t believed anything I read in them - DYOR ….
My morning smallcap tweet: The goldfish bowl of news
Avon Protection (LON:AVON) Audioboom (LON:BOOM) Iofina (LON:IOF) IQGeo (LON:IQG) Filtronic (LON:FTC) Kanabo (LON:KNB) Futura Medical (LON:FUM) OptiBiotix Health (LON:OPTI) Oracle Power (LON:ORCP) Hercules Site Services (LON:HERC), Ramsdens Holdings (LON:RFX)
◄Avon Protection (AVON)► wins multi-million € order to supply its Multi-Role Rebreather for military diving operations. [SP=899 Cap=272m]
◄Audioboom (BOOM)► guides Q4-Dec rev up 5% and 27% on Q3. Adj EBITDA turns positive at $0.2m. Expects record rev in FY24 and a return to adjusted EBITDA profitability. [SP=325 Cap=53m]
◄Iofina (IOF)► missed H2 production guidance of 325-350MT with output of 318MT. "The iodine spot price softened by circa five percent over H2 2023 towards mid-to-upper sixties dollars per kilogram as prices have settled from historically high levels." [SP=25.34 Cap=50m]
◄IQGeo (IQG)► guides FY-Dec ahead of expectations with rev over £44.2m up 66%, adj EBITDA over £6.4m. Bullish. [SP=290 Cap=179m]
◄Filtronic (FTC)► wins contract from QinetiQ. Phase 1 worth £2m over 2 yrs. [SP=21 Cap=45m]
◄Kanabo (KNB)► has signed a partnership with City Dock Pharmacy in London, to launch a walk-in pain clinic which will use Kanabo's Treat It online platform. [SP=2.58 Cap=15m]
◄Futura Medical (FUM)► has extended until Jan 2029 its exclusive licensing agreement with Cooper Consumer Health for Eroxon rights in the European Economic Area, UK and Switzerland. [Stick your innuendo in here]. [SP=34 Cap=102m]
◄OptiBiotix Health (OPTI)► to launch LeanBiome in Muscletech, one of the leading sports nutrition brands in the industry. LeanBiome will be incorporated in Muscletech Nitro Tech Ripped range. I don't use that myself. Or go to the gym for that matter, as is clear if you meet me. [SP=24.5 Cap=22m]
◄Oracle Power (ORCP)► general update. [SP=0.03 Cap=1m]
◄Hercules Site Services (HERC)► FY-Sep rev up 71% above exp. Pretax £641k is below Stockopedia F/C of £772k. Outlook - Q1 'has been successful'. [SP=25 Cap=15m]
In line: RFX
Morning Paul
Excellent update from IQGeo (LON:IQG) . Ahead of expectations revenue and profit. Cash generation good as are outlook comments. May be worth a look.
Thanks as always for the podcast . Cheers rh
Morning richardho!
Excellent update from IQGeo (LON:IQG) . Ahead of expectations revenue and profit. Cash generation good as are outlook comments. May be worth a look.
I'm on the case, that's my first port of call, as it's ahead exps. Section up soon!
Regards, Paul.
Excellent update from IQGeo (LON:IQG)
It is a very good update. And the company is exposed to interesting drivers. My concern is that the level of recurring revenue is relatively low at just under 50%, although the recurring revenue retention rates are outstanding at 132% - lots of upselling going on. More expensive than obvious comparison Cerillion (LON:CER) on profit multiples and much lower quality on operating numbers. But this is not unusual at an earlier stage on the growth curve. And the lower price to sales despite faster growth in revenues is interesting. Overall, if you can stomach Cerillion’s valuation - and long term holders are very glad they did - then you should find this one quite interesting. Cavendish updated forecasts of “only” 13% and 11% revenue growth in FY24 and FY25 seem to leave ample room for upgrades. I’m maxed out on Tech and nibbling at beaten up cyclicals at the moment but I will be watching this one for a pullback to maybe swap in from one of my mistakes (that I just haven’t recognised yet). If only I’d been alert to the November dip!!
Nice contract win at Filtronic (LON:FTC) where they announce a deal with Qinetiq (LON:QQ.) worth £2m for phase 1. They’ve been knocking it out the park recently
I have heard a lot of people more clever than me mention Filtronic (LON:FTC) here, personally I can't get excited. You have to win a lot of big contracts when you only make 1% operating margin! Apologies if Stocko stats are not accurate on this one!
Isn't that the point of Filtronic (LON:FTC) as an investment currently? Market Cap of £45m, winning contracts a few million here and there (where the liklehood will be recurring revenue) together with barriers for competitors, higher visibility, higher margins due to scale, rinse and repeat?
I recall that the historic problem with Filtronic (LON:FTC) is that its products seem to have a shortish lifespan. Hence why it innovates, has a burst of excitement and rising profits, then it all withers away as competitors presumably match/undercut its products. You can see that from the long-term chart - bursts of excitement, which always fizzle out. Maybe it's different this time?!
Still, it might be a nice one to trade, rather than invest in? Looks like it's in a nice uptrend (for now anyway).
Paul
Think you haven’t understood the evolution of the Filtronic product range over the past years and it’s correlation with the Requiremehts of the LEO
There is very strong barrier to entry and this is effectively a new market
In short there is a huge barrier to entry in a strong market
Ask yourself why are Tesla buying their product instead of developing their own, because it’s a protected IP product made by an established company .
There is pretty close to zero chance in my opinion of anyone working on a LEO programme is going to switch to a new supplier who can undercut .
It just is not going to happen in this market
That’s why the strength of this company as I said in another post is in its IP and patents and ability to produce for this new market .
Elon Musk is not going to switch supplier to save a few 100k on a 3-5 million contract where they have a supplier of trust .
So I think historic comparisons don’t apply at all. In any way shape or form .
Interesting, thanks planetx.
Elon Musk is not going to switch supplier to save a few 100k on a 3-5 million contract where they have a supplier of trust .
I'm not necessarily disagreeing with you, but if you read the Ashlee Vance or Walter Isaacson biographies you'll soon come to realise that he very rarely works in the way most people would (take the Twitter server move as an example!).
And just to be pedantic, it would be SpaceX buying equipment for LEO satellites, not Tesla (NSQ:TSLA) :-)
OF course
The point is no self respecting company sending satellites into orbit are going to change from an established supplier with proven manufacturing ability and reliability and history .
Not a chance in hell for my money .
Point taken!
It's probably worth pointing out that a number of the Starlink satellites will deorbit each year, so even when SpaceX have launched whatever amount is needed to get their constellation to the desired size, they will have a continual churn rate that needs replacing. Which obviously bodes well for future recurring revenues here.
Technically 5 years, but lower expected lifespan given the low orbits and the increased gravity by earth.