Small Cap Value Report (Mon 15 July 2024) - RWA, CAV, MEGP, BRBY Movers: DEST, SBDS

Good morning from Paul & Graham!
We've run out of time today, so that has to be it.
"Profitable growth" survey
A bugbear of mine, we're seeing this arguably meaningless phrase appearing in many results & trading updates. I wanted to survey your opinions on this, so we can give some feedback to the PRs and brokers I talk to. Unfortunately, my survey last week went wrong, as I didn't realise Survey Monkey start charging extortionate fees once 25 people have replied, so I had to bin that.
This weekend I set up a new survey through google forms. So I invite you to give your views on the increasing use of the vague phrase "profitable growth". Even if you replied to the old survey, please do reply again, as this is a new survey. It doesn't capture any of your personal information, or have any commercial angle on it at all. I'm just interested to hear your views. Thanks in advance.
Click here to reply to my survey
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia.
Companies Reporting
Other mid-morning movers (with news)
Silver Bullet Data Services (LON:SBDS) - up 27% to 95p (£17m) - Contract Wins & Working Capital Facility- Paul - AMBER/RED
“Silverbullet (AIM: SBDS), a leading provider of AI-driven digital transformation services and products, is pleased to announce significant new contract wins and a new working capital facility.”
20 contract wins, but totalling only £1.2m total. Says it now has c.70% visibility for (not stated) FY 12/2024 revenue target. Mentions “worldwide mandate for its data strategy” with global confectionery company - presumably Mars, which it has previously mentioned a contract renewal for FY 12/2024 of $2.3m, on 27 Feb 2024 - I’m assuming the £1.2m new contract wins are additional to that Mars contract?
New borrowing facility of $1m is a receivables discounting facility. Again, very small, and reminds us how tight cash must be.
Outlook - confident it can meet FY 12/2024 expectations. Reckons it can achieve positive EBITDA & cashflow in H2.
Paul’s view - I’m surprised punters have chased this share up 27% on relatively minor news today.
I should remind readers that SBDS has a weak balance sheet, and 2023 results contained a material uncertainty going concern. So you’re going to get diluted sooner or later, on unknown terms, is my view. That’s why I have to flag the risk with a continuing AMBER/RED - but NB some riskier shares go on to do very well, so don’t let this necessarily put you off - it’s just a risk flag, so you can weigh up the options armed with the full facts.
It’s an interesting-sounding company, demonstrating good revenue growth. Key question - what does it have that’s special, compared with any number of similar consultancies talking about AI? The repeat business with Mars looks intriguing though. Very volatile share, is telling us the market doesn’t know how to value it.
I’ll move up to amber once it gets proper financing. The existing balance sheet is clearly stretched, and badly needs a proper equity injection. Losses in 2023 greatly reduced, and if it does achieve positive cashflow in H2 this year, then investors could get lucky here, who knows?!
I recall there was a fair bit of reader interest in this share previously, so what do you think?
Destiny Pharma (LON:DEST) - down 74% to 2.25p (£2m) - Proposed De-listing - Paul - GREY (delisting)
AIM is not the right place for zero revenues, serial loss-makers, so I’m pleased to see another one is departing.
This has been listed since 2017, and burned through a lot of cash. We’ve never reported on it here at the SCVR, because there’s nothing we can say on zero revenues speculative shares. They’re just punts, and they nearly all fail. I’m flagging it to try to keep track of delistings for my spreadsheet.
Summaries
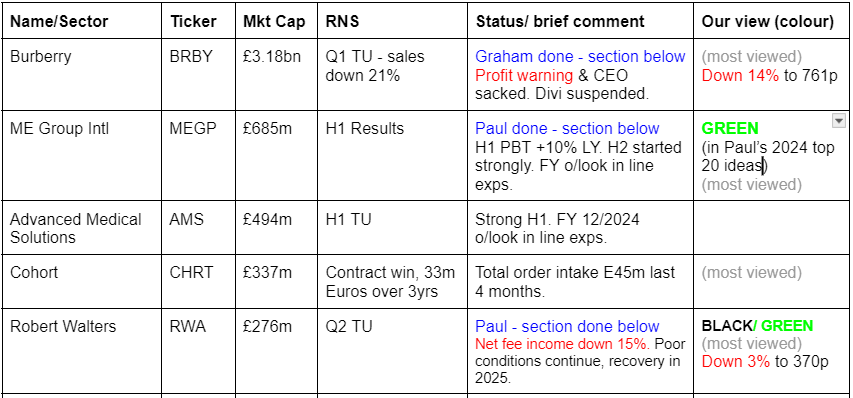
Robert Walters (LON:RWA) - down 3% to 370p (08:48) £268m - Q2 Trading Update (profit warning) - Paul - BLACK (pw) - GREEN (on fundamentals)
RWA follows larger sector peers, PAGE and HAS, saying that current trading is depressed, with fee income down c.15%, and no sign of green shoots yet, now expected in 2025. Crunching the numbers, I still view RWA as fundamentally attractive, safe (strong balance sheet), generous divis, and a cyclical recovery to come in 2025 probably. It's GREEN for me.
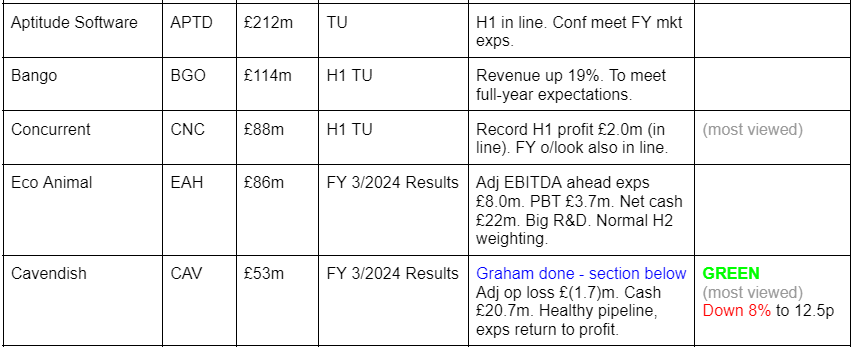
Cavendish Financial (LON:CAV) - down 5% to 12.99p (£50m) - 2024 Full Year Results - Graham - GREEN
These results aren’t too exciting when you look at the numbers. Despite much higher revenues on a combined basis, and post-merger cost synergies delivered as planned, the company failed to avoid posting a loss for the year. It has paid out generous staff bonuses which I think can be justified in these special circumstances, but it must tighten up its FY 2025 payments if market conditions don’t improve.
ME International (LON:MEGP) - Up 1% to 183p (£692m) -H1 Results - Paul - GREEN
Pleasing H1 results, and a confident (in line) outlook. Everything looks good to me, including balance sheet and cashflow. The self-funded roll-out of more laundry machines continues at a record pace, together with next generation replacement photo booths. Despite rising c.46% in 2024 YTD, this top 20 share idea of mine still looks attractive value, so I'm sticking at GREEN. High StockRank too.
Burberry (LON:BRBY) - down 16% to 747p (£2.7 billion) - First Quarter trading update - Graham holds BRBY - BLACK (PW) - AMBER on fundamentals
Tough news for BRBY shareholders (myself included) as the company reports a very poor quarter with a 20% decline in revenues at constant exchange rates. The CEO leaves and is immediately replaced. Due to the inherent leverage of retailing, the company is now loss-making and the stock is a risky recovery play. Solvency seems ok for now but I can’t take a positive stance on this in the short or medium term.
Paul’s Section:
Robert Walters (LON:RWA)
Down 3% to 370p (08:48) £268m - Q2 Trading Update (profit warning) - Paul - BLACK (pw) - GREEN (on fundamentals)
Focused on being optimally positioned amidst muted client and candidate confidence
This is now the third international recruitment group which has told us that trading is difficult. We covered Pagegroup (LON:PAGE) profit warning here last week, and similar news from Hays (LON:HAS) here last week. Both said that conditions are tough in nearly all geographies, so this is not a UK-specific problem. Both have similar market caps at £1.4bn to £1.5bn, and in both cases there was little impact on their share prices, which had already seemingly anticipated slower trading, with the rally in May completely reversing in June/July.
Hence it shouldn’t have come as a surprise to anyone that smaller rival RWA is also today announcing slow trading. We’ve only so far seen a very modest 3% drop in RWA’s share price today, indicating the bad news was expected, and already factored into its valuation. I find it encouraging when share prices barely budge on a profit warning, as that’s telling me we could be at or near a bottom.
RWA reports today that Q2 (Apr, May, June 2024) Net Fee Income was down 15%. That’s exactly the same figure that PAGE gave us last week for Q2.
The trend seems to be worsening within Q2, with June down 18%. Definitely no green shoots in the staffing sector, yet.
RWA’s own staff headcount has fallen 15% Y-on-Y, so it’s scaling down staff overheads at the same rate as revenue falls.
Net cash of £49m (excl lease liabilities) at end June 2024 is healthy.
Balance sheet overall is very good, with NTAV of £130m, almost half the market cap. So you get proportionately more balance sheet support with RWA than with the larger staffing groups. Plus a lower PER, and a higher dividend yield, so I think RWA looks more attractive than PAGE and HAYS in terms of the valuation numbers.
UK - interesting to note that London is performing better (-6%) than elsewhere (-21%).
CEO comments below (in full, as they’re interesting) -
"Fee income for the first half of 2024 continued to reflect the rebasing in market conditions relative to the post-pandemic peak. This period of market adjustment is now longer in duration than previously expected, with macroeconomic turbulence and political uncertainty restraining client and candidate confidence in certain geographies.
Our near-term planning now assumes that any material improvement in confidence levels will be gradual, and likely not occur before 2025. In this environment, we remain focused on being positioned to deliver the best outcomes for our clients and candidates, whilst maintaining tight cost discipline. These actions do not fully offset the first-half fee income reduction, but they position us well going into the second half of the year.
Though current market conditions suggest a wider range of potential outcomes for the full-year than seen historically, I have high confidence in our experienced leadership team, which has successfully navigated many challenging market cycles. We are committed to our medium-term plan to further strengthen the business, details of which will be shared at our capital markets event in September."
Broker updates - I don’t have access to anything as yet. Given the tone of the above, I imagine brokers are likely to trim their estimates for FY 12/2024 and FY 12/2025, which is what has already happened with PAGE and HAYS. Not drastic cuts, but significant - eg broker consensus estimate for FY 12/2025 at PAGE has just dropped from 29.5p to 25.7p after last week’s profit warning. Hence I imagine something similar might happen with the existing consensus for 2025 at RWA, currently 30.1p. Let’s assume that also drops by 13%, then we get to c.26p for 2025.
Valuation - at 370p I make that a 2025 PER of 14.2x - not exactly a bargain, but the hope would be that 2025 forecasts are beaten once recovery begins.
The question is how much are earnings likely to recover in future? I’m starting to wonder if the bumper profits immediately after the pandemic in this sector might not necessarily be the normal level we’re likely to return to. As hinted at by RWA above, maybe that was a temporary boom? So perhaps we should be adjusting down our expectations of a cyclical recovery, which RWA says will only be gradual, and in 2025 (not this year)?
Paul’s opinion - I see better value at RWA than its larger rivals, and I particularly like its balance sheet strength with net cash, and only about 2x NTAV. It seems to me that dividend expectations might be too high, so I wouldn’t be surprised to see brokers trim not only profit, but also dividend forecasts. That said, RWA clearly has the financial strength (hefty net cash) to continue paying good divis.
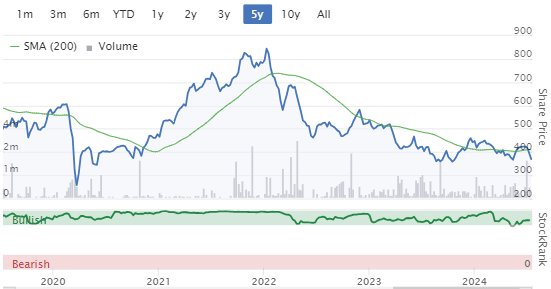
Looking at the 5-year chart below, RWA shares are at a low, not much above the initial pandemic panic sell-off. Note also there’s been no dilution, in fact the share count has shrunk a bit over this 5-year period, from c.78m to c.72m, so buybacks, on top of generous divis which have totalled 98p in the last 5 years - during the chaos of the pandemic & energy crisis. That’s impressive.
Is today’s update actually a profit warning? It doesn’t specifically say that expectations have been lowered, but it dances around the issue talking about a “wider range of potential outcomes”, and it does say fee income is lower than expected. So I think this is effectively a profit warning (trading slower than expected) and I bet broker forecasts will be reduced. So that’s close enough to a profit warning to have a BLACK flag on my spreadsheet. Incidentally, this is not a negative view on any share. It’s just flagging that a profit warning has happened.
As I recently posted, the BLACK shares on my spreadsheet have in many cases subsequently recovered, and quite a lot have attracted takeover bids. So I challenge the idea that companies which warn on profits should be avoided. My data shows that, in the last year anyway, many profit warnings have actually been decent buying opportunities. But mainly for previously good quality companies, not the tiny market cap junk ones, which tend to keep warning on profits time & time again. So let’s keep an open mind.
I see RWA as a fundamentally good company, and hence for me this delay to recovery is disappointing, but expected. If there’s another lurch down in share price later this year, it would become too attractive to resist. Good fundamentals mean I’m ignoring this recent soft patch of trading, which is sector-wide, and remaining at GREEN for the inevitable trading recovery (seemingly now in 2025). That seems to be the market’s view too, with sector prices holding firm despite soft current trading.
ME International (LON:MEGP)
Up 1% to 183p (£692m) - H1 Results - Paul - GREEN
ME Group International plc (LSE: MEGP), the instant-service equipment group, announces its results for the six months ended 30 April 2024 (the "Period" or "H1 2024").
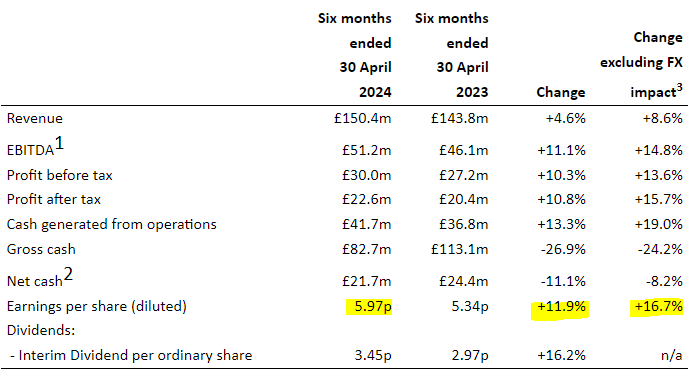
Good H1 figures, with profit rising faster than revenues, net cash similar to last year, H1 divi up 16% -
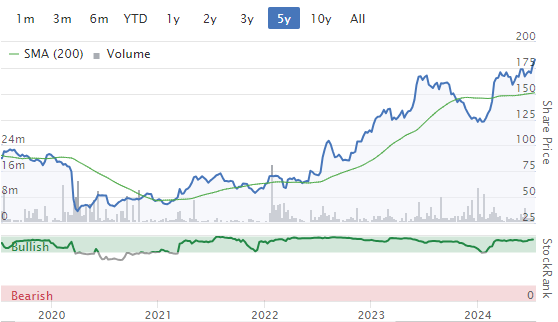
Growth is coming from both the core photo booths, but also the increasingly important laundry machines, typically sited in car parks and filling station forecourts. I think the market has woken up to the roll-out potential of this high margin laundry business. We got there first here at the SCVR, spotting the valuation anomaly of this GARP share, which I included in my top 20 share ideas for 2024, which is now up a decent 46% from the 126p starting price.
Seasonality - note there is a usual H2 weighting, so the numbers above are consistent with full year forecast of c.14p
Outlook - sounds good, and is in line. What I like about this, is that we don’t have to worry about large, lumpy contract wins or the like. This is a self-funding roll-out of proven, successful, niche machines/services. Surely it should be rated on a PER that reflects these pretty dependable, recurring revenues, and the growth (but it isn't)?
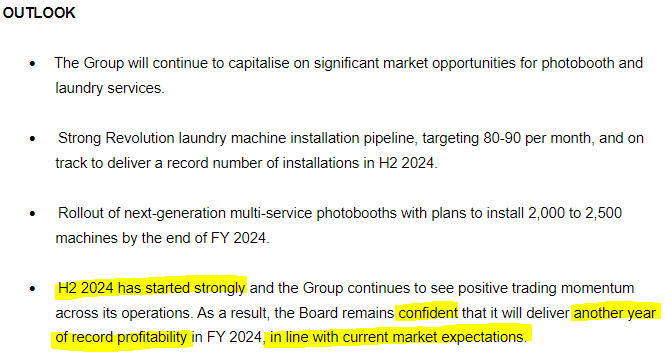
This bit below appeals. It reminds us that MEGP is not standing still, and has deep expertise & experience in self-service booths of all kinds. Who knows what it might come up with next?!
"Additionally, the Group's R&D team has devised new production techniques to reduce the cost of the next-generation photobooths by 28% (effective immediately) and the Revolution laundry machine by 13% (effective FY 2025). A new generation solar panel, which delivers twice the power generation of the current model, is also in development and will be utilised by the Group's Revolution machines"
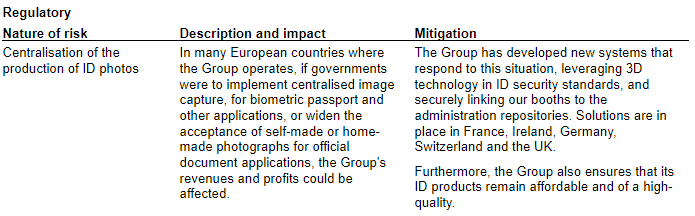
Key risk for the main photo booth business seems well-addressed in the risk section -
Valuation - the StockReport shows broker consensus of 14.1p FY 10/2024, and 15.4p FY 10/2025.
I would rate this share on a PER of 15-20x, to reflect its quality, recurring earnings, and self-funding expansion. So I get to a theoretical share price of 231p to 308p. The current price is 183p, so in my opinion this share remains undervalued. Although historically the market has tended to apply quite a low PER to MEGP, seeing it as old technology that is likely to decline sooner or later. That seems fundamentally wrong to me, but nobody can look into the future with certainty.
The quality of the business is shown by the fact that it can self-fund the roll-out of many new machines, at an accelerating pace with laundry, without using any net debt, and still throw off enough surplus cash to pay out a 4.6% dividend yield.
This is what a proper cash generating roll-out looks like! Compare the figures here with the weak numbers at GYM - there’s no comparison, MEGP is streets ahead.
Pizzas! - readers discussed this a while ago, and one subscriber even mystery shopped a pizza machine. We were then told by someone that MEGP had sold off the food/drink machines division. Today’s commentary seems to be saying this is still a live area, but maybe just selling the machines, rather than operating them? -
“In addition, the Group sells pizza vending equipment in Continental Europe and the UK, albeit on a small scale. The Group expects this will remain a small financial contributor to the Group going forward.”
As an aside, apparently Japan is the place to go for vending machines. I’ve never been (high on the wish list though) but saw a travel documentary recently, which said that Tokyo has vending machines everywhere, for all sorts of things, literally every few yards.
Balance sheet - absolutely fine, I don’t need to go into detail.
Cashflow statement - remarkable, the business throws off lots of cash, which it uses for capex and decent divis.
Paul’s opinion - I remain very positive on this share. It’s a high quality share, priced as a value share. That just doesn’t make sense to me, so I think with patience, it could & should do another leg up. And you're paid well whilst you wait, with those attractive divis.
Stockopedia likes it too, with a StockRank of 94.
So it's another GREEN from me.
Graham’s Section:
Cavendish Financial (LON:CAV)
Down 5% to 12.99p (£50m) - 2024 Full Year Results - Graham - GREEN
These are the first full-year results since the merger of Finncap and Cenkos.
Important to bear in mind that the merger didn’t take place until half-way through the financial year (FY March 2024).
Key bullet points:
H2 revenue +80% on a combined basis to £35m
£7m annualised cost synergies delivered on schedule
Net cash £20.7m at year end.
There is unfortunately a pre-tax loss of £4.3m. Normally I look for brokerages/investment banks to slash bonuses in the bad years, so that they never need to post a loss - their staff are very well paid in the good years, after all.
Cavendish explains the loss as follows:
The reported loss for the year reflects the decision we made to pay bonuses to reward and retain staff following a strong post-merger performance.
Balance sheet: there is tangible equity of £26m, including the cash figure mentioned above, and a large pile of receivables (£23m).
Outlook sounds more positive than negative, with a good start to FY March 2025:
The business is performing well in the new financial year, with deal flow balanced across ECM, Public and Private M&A, Debt Advisory and Private Growth Capital. As we look ahead, we see many reasons to be positive, including continued equity issuance, private and public M&A, further client wins and a number of emerging IPO opportunities as companies seek to join the UK markets. Clearly there remain uncertainties and macro issues which impact market sentiment, but with our well diversified offering and robust platform we look forward to returning to a profitable year as the merger synergies are fully realised and with that the compensation ratio returning to normal levels.
Graham’s view
As I’ve said, I normally want companies in this sector to slash bonuses in the bad years. If they do that, it shouldn’t be necessary for them to ever post a substantial loss.
But this is a special case: a transformational merger of equals has taken place. Many staff have had to change where they work and how they work. Others have been let go. In these circumstances, I think it’s reasonable for the company to maintain bonuses in the short-term, even if the financial results for the year don’t justify it.
In the long-term and starting straight away, shareholders will benefit from the £7m of annualised cost synergies that have been delivered.
Now if it turns out that FY March 2025 is another poor year and if the company fails to adjust its bonus payments sufficiently to avoid posting a loss, I’d certainly have to rethink my positive stance here.
Cavendish has announced a dividend of 0.25p, which I think has a gross value of less than £1m. Total employee costs, including bonuses, were £35m. For FY 2025, the company needs to try to get the balance right again between employee and shareholder rewards.
I am going to maintain my positive stance here for all the reasons I’ve described before. The enterprise value is £30m for a business that is going to deliver profits more efficiently (due to economies of scale) and more easily (due to less competition) whenever AIM conditions improve. For me, this still looks like an exciting way to bet on a market recovery. This is why it is on my list of best ideas for 2024.
Burberry (LON:BRBY)
Down 16% to 747p (£2.7 billion) - First Quarter trading update - Graham - AMBER
(Graham has a long position in BRBY at the time of writing.)
This is not a small-cap but seeing as I am a long-term (i.e. long-suffering) shareholder here, I thought I could add a few words on it.
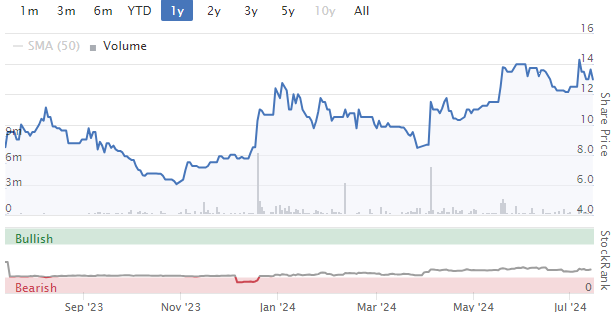
Firstly, while today’s news is clearly very bad, the market has at least been attempting to price it in before today. Share price performance year-to-date:
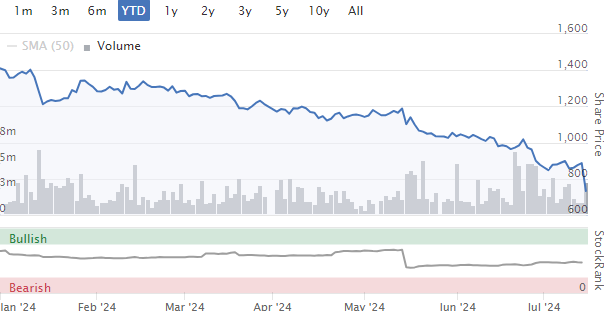
Here are the numbers:
Q1 revenue down 20% at constant exchange rates.
Comparable store sales down 21%.
Comparable store sales: down 23% Asia Pacific, down 16% EMEIA (includes India, Africa), down 23% Americas.
Chair comment:
Our Q1 FY25 performance is disappointing. We moved quickly with our creative transition in a luxury market that is proving more challenging than expected. The weakness we highlighted coming into FY25 has deepened and if the current trend persists through our Q2, we expect to report an operating loss for our first half
Dividend payments are suspended as the company tries to “rebalance our offer to be more familiar to Burberry's core customers whilst delivering relevant newness”.
Various initiatives are underway, e.g. better functionality online with a website refresh, and a new outerwear campaign to be launched in October.
Outlook: profit warning for FY March 2025 based on current trends.
In addition to declining underlying revenues, the company is also suffering from currency movements and is forecasting a £20m hit to operating profit based on current exchange rates.
CEO replaced: the CEO unceremoniously leaves “with immediate effect by mutual agreement”, and is replaced straight away by the former CEO of Michael Kors and Coach. It’s a radical change without any transition period and with little warning. I suppose we can applaud the Board for their decisiveness.
Graham’s view
This stock has been part of my long-term portfolio for years. I’ve had many opportunities to cash in, but I always felt that it was worth holding on as the brand seemed to have an evergreen appeal to luxury consumers, especially in Asia, and I expected LMVH or someone else to eventually come knocking for it.
However, Burberry is currently suffering badly in a very tough market. Gucci (owned by Kering) provides a good comparison and in April it reported Q1 revenues down 21%, “attributed to a sharp decline in the Asia Pacific region”.
Given that Gucci had such a bad start to the year, I’m inclined to think it’s too soon to say that Burberry is doing much worse than its direct peers. Other luxury brands such as LVMH haven’t done as poorly, but they include brands which are not Burberry’s direct competitors.
As for my stance on this one? With the company now loss-making, I don’t think I can give this stock the thumbs up, as recovery plays are inherently risky. So I prefer to be neutral.
Personally, I don’t have any plans to sell my BRBY stock at this time, as I tend not to tinker with this portfolio - I know that some of the stocks in the portfolio will be losers, but I also expect that some of them will be big winners.
A note on solvency: the company reported net debt of £1.1 billion as of March 2024, but this included nearly £1.2 billion of leases. Excluding leases, the company still had a small net cash position. Cancelling the dividend will be a big help in maintaining solvency.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

69 comments
Hi Paul
Silver Bullet Data Services (LON:SBDS) - not sure why you’re quite so certain they need any particular size of raise.
1) since that going concern statement they raised cash
2) they have clearly had no problem getting a £1m RCF which means lenders appear quite willing
3) management have shown no particular desire to dilute. minimal dilution since IPO
4) cashflow positive this year
So whilst balance sheet is by no means flush with cash I’d say any equity raise they might do is likely to be minimal.and as such any discount likely to be small to zero. The last raise was taken by 1 investor (who I believe is pretty smart).
This is a company with a superb client list where they very clearly have strong repeat relationships and are “landing and expanding”. They have a product that in the cookie free world (hopefully digital only or I’m screwed :-) ) should do extremely well.
So I get an Amber status or an Amber/Green but Amber/Red feels pretty harsh. This is not a serial dissapointer or a jam tomorrow. It hasn’t had a regular begging bowl out and has grown its revenues and invested in product very well. Now on the cusp of cash profits.
Good points well made, thanks David! Re Silver Bullet Data Services (LON:SBDS)
AMBER/RED is just flagging risk remember, not predicting the future. It definitely needs an equity raise, in my view. That would be a good thing, as big clients want to see solid balance sheets from suppliers.
Previous tiny equity raise, and tiny invoice discounting facility just reinforce the need for proper funding. I'll happily go AMBER if it raises say £5-10m equity so it can operate properly, not hand to mouth.
Agree there are interesting speculative aspects to the share, I thought my piece was quite well balanced.
Good luck with it!
Regards, Paul.
Silver Bullet Data Services (LON:SBDS)
I'm interested in this company, and have been watching but I don't think that I have a good enough understanding of the business model/related parties/finances to invest.
Who was it said 'Don't invest in companies where you don't understand what they do'?
Going Concern - The last raise I can see is the RNS November 29th - placing to raise £1m. The placing is accounted for in the AR - and the Material Uncertainty statement in the same accounts is after accounting for that raise? Still applies unless I've missed something?
Working Capital Facility - if it was an RCF it would be stated as such? The wording makes me think it's an factoring/invoice discounting facility. Little or no risk taken by the bank on these facilities as they take ownership of the invoice for collection?
I'm not surprised to see the working capital facility. In the AR one thing I don't understand is the relatively low gross margin of the 4D platform - with revenue rising an impressive 170% the gross margin is 38%. Before all staff/overhead/central/finance costs. It doesn't smell like SaaS? To be fair I don't think that they say it is? Makes me suspect its a video adtech platform running marketing campaign for clients - with some clever proprietary software including machine learning in the backend. Which would basically be a video playout platform, potentially costly content to host and it's not clear to me what the monthly billing basis is? It's not licence, or the software? It's billing against the advertising campaign in some way? Is there a success/performance element based upon improved campaign performance?
I can see potential risks here that I don't understand? I may have completely misunderstood?
Not detracting in any way from the impressive growth figures that are very attractive. I just don't think I understand the business model? And how the revenue converts to a high level of profitability? Perhaps someone with a lot more knowledge of Martech and Adtech can help me understand what is being provided to customers and what they are likely to be paying for?
Given the - current - relatively low gross margin in the 4D platform I can see that rapid increases in winning revenue can lead to rapid increases in working capital - a typical problem of success. I can see that they will try to avoid another raise, but they already have quite a lot of small loans and an expensive convertible loan - so I guess it will all depend upon the relationship between rate of growth or revenue and working capital?
cheers
Mark
Journeo (LON:JNEO)
Sell or add?
Unloved and unwanted. Is the market right in terms of the falling share price that suggests something is awry or have investors just got bored at the absence of news? Trading update expected at the beginning of August?
Unsure whether Downing Strategic Micro-Cap Investment Trust (LON:DSM) retains a holding.
I have a modest holding.
All views welcome.
Was watching the Synetics IMC video today, interesting response to the question of Downing Micro-cap - I thought there was a EGM in August raised by Milkwood on this topic.. ? (question @ 42:00)
(link : https://www.youtube.com/watch?...)
I was wondering myself why Journeo (LON:JNEO) had been battered last few days - a 20% fall on news that I can see. I guess maybe it is a Downing overhang but need to check that out. Any insights would be useful.
Like this medium term a lot and can see it considerably higher so maybe another opportunity to top up if this continues any further
I think time is on your side with this one Jonno. Personally with a month until the update I'd be holding on a little longer to see what happens to the share price. A chartist would probably sell, although in this case Journeo (LON:JNEO) thats maybe a bit rash. Personally I wouldn't be buying right now, nobody want to catch a knife. But with any luck the sp will settle in the coming weeks and if it starts to move up as we move to results then maybe that's the time to add. I don't hold but am keeping a close eye.
Journeo (LON:JNEO) I remember picking up from a Ricard Staveley interview recently that one of his stocks was held by a fund that was selling down a number of positions. Journeo was owned by that fund (sorry but can't remember which one). I, following my rules, have since sold down to the sleeping level (ie it won't kill me if this is something more substantial). I'm fully expecting to be proven wrong in this, but safety first.
VP (LON:VP.)
Further to my recent posts on Van Elle Holdings (LON:VANL), VP (LON:VP.) is another share that in my view is too cheap based on the fundamentals and Government's positive narrative on infrastructure and house building. I have posted on VP (LON:VP.) previously. It is in my opinion that it is the pick of the equipment hire companies by some distance.
My investment thesis in no particular order:
Whilst some economic uncertainty remains, the Group has made a solid start to the new financial year, which we expect to be in line with the Board's expectations: Infrastructure market remains supportive with a clear pipeline of projects. Prospects in Energy market provide confidence.
General Construction market remains challenging. Brandon Hire Station action plan underway with confidence in medium-term prospects
Headwinds remain in Housebuilding market, with a slight drop in activity levels.
Commenting on the Final Results, Anna Bielby, Chief Executive of Vp plc, said:
"The Group has again delivered sector-leading returns, led by a strong performance in Infrastructure. Whilst some economic uncertainty remains, particularly in Construction and Housebuilding, we remain confident in our ability to react to changes in end markets and take advantage of economic improvements.
"We have made considerable progress in FY24 with new leadership and a refreshed strategy. We are excited about the future and have confidence in our ability to both grow the business and drive value through simplifying the way we work."
"The Company has been notified that, on 3 July 2024, Jonathan James Jones, a Person Closely Associated with Sarah (Sally) Jones, Company Secretary of the Company and a Person Discharging Managerial Responsibilities, purchased a total of 35,565 ordinary shares in the Company at a price of 708.54p per share"
I could ramble on but would recommend that anyone interested visits the company website where the diverse range of the company's activities is explained. The recent investor meet company webinar is also worth a watch. For what its worth I have added a few today at 689p. My average in price is around 600p.
The bug bear is that the spread on the shares is an absolute pain, but when the housing construction market awakens I am of opinion that one will be paying significantly more for the shares.
"It is likely that the housing/construction sectors are close to the bottom", I agree but it will take a helluva lot of money to reignite it don't you think jonno? I hold Barratt Developments (LON:BDEV) , Taylor Wimpey (LON:TW.) and Persimmon (LON:PSN) so am a patient hopeful.
Hi Silver Moon,
I have taken more of a picks and shovels approach and hold Van Elle Holdings (LON:VANL) Brickability (LON:BRCK) Michelmersh Brick Holdings (LON:MBH) Sigmaroc (LON:SRC) and VP (LON:VP.) and more tenuously but directly related to the health of the housing market Property Franchise (LON:TPFG)
Good luck with your house builders.
Re: Burberry (LON:BRBY)
A note on solvency: the company reported net debt of £1.1 billion as of March 2024, but this included nearly £1.2 billion of leases. Excluding leases, the company still had a small net cash position. Cancelling the dividend will be a big help in maintaining solvency.
Graham,
I think you’ll find they announced a £300m bond issue with a 5.75% coupon last month. So the solvency situation is worse than stated above currently, with a further £19m in coupon payments going out the door per annum.
All the best, Si
Burberry (LON:BRBY)
simoan
I think you’ll find they announced a £300m bond issue with a 5.75% coupon last month. So the solvency situation is worse than stated above currently, with a further £19m in coupon payments going out the door per annum.
Huh - if they raise £300 mill will that not mostly be neutral ref net debt - ignoring fees as they benefit from the cash inflow ref bond issue.
Not sure why solvency is even being questioned here if ignoring leases they have NO net debt (ie net cash) and they are still expected to make well over £100 mill of profits this year presumably even after todays downgrades? - ok if trends continue to worsen could be a worry if they have large payables perhaps but cant see how company with no real net debt making £100 mill plus profit should have any worries as things stand. Cancelling dividend is obviously sensible if there is worse to come perhaps so fair play to them being proactive in that regard.
Huh - if they raise £300 mill will that not mostly be neutral ref net debt - ignoring fees as they benefit from the cash inflow ref bond issue.
In the very short term, yes, of course, but they stated the purpose as “general corporate purposes” i.e. keeping the lights on. You also need to be careful using the free cash flow figure shown by Stockopedia because it does not include lease payments. I expect the free cash flow will be strongly negative for FY25 as things stand and it remains to be seen how necessary the bond issue was.
Hi Paul
I suspect I am the someone as per...
"We were then told by someone that MEGP had sold off the food/drink machines division. Today’s commentary seems to be saying this is still a live area, but maybe just selling the machines, rather than operating them? -"
Anyway this is the not terribly clear RNS...
https://www.investegate.co.uk/...
Best wishes, Martin
Thanks for the write-up on Cavendish Financial (LON:CAV) Graham.
To aid my understanding of today's results I've done a bit of work to compare previous years KPIs which I have copied below with a couple of points about methodology. I have done this quickly during my lunch hour so feedback welcome and I apologise if I have made any errors. The equivalent EPS figure is likely to be imperfect but it's hopefully a quick rule of thumb - what I haven't done in the time available is compare average share numbers among Cenkos and Finncap to check they didn't wildly differ from year-to-year. Hopefully the EPS figure looks OK - again please challenge if you think I've done anything wrong.
What I take from this is:
We have had cumulative inflation of 30% since 2019, so perhaps the new high water mark in a bumper year for might be 100m revenue for Cavendish Financial (LON:CAV)
Cavendish Financial (LON:CAV)
Tortoise,
The FY24 numbers include 7 months of Cenko’s contribution and 12 months from FCAP. You may need to adjust your figures to get an accurate comparison.
Cenkos didn’t command a high PE at the top of the cycle. I recall something around a PE of 5 or 7. Perhaps others have a better memory or some real data.
My valuation has to include the Share Incentive Plan and Co-investment Plan which gives 15% of the company to management/employees over the next three years. (RNS 19.ii.24) The same RNS states that there was an intention to extend the plan in March. It is complicated.
I still own some.
Join us for a jam-packed MelloMonday tonight from 5:00pm with Stockopedia favourites Paul Scott and Mark Simpson both joining us on the BASH. The programme for the evening is as follows:
5:00pm Interview with Investor and Ex-Schroders Fund Manager, Iain Staples
5:30pm Company presentation from TEAM plc
6:00pm Company presentation from Velocity Composites
6:30pm Trading update from Time Finance
6:45pm Educational Presentation
7:00pm Company presentation from Coral Products
7:40pm BASH (Buy, Avoid, Sell, Hold) Panel featuring Iain Staples, Paul Scott (GMS) and Mark Simpson (CAU)
For more information, click here: https://melloevents.com/mm150724/
There are lots of interesting sessions and all annual pass holders and individual ticket holders will be sent a recording of the show within 48 hours of registering. For half price tickets, use code MMSTOCKO50. https://www.tickettailor.com/events/melloeventslimited/1093812
Burberry (LON:BRBY)
I understand the temptation to bottom fish here - but with retailers/fashion brands is the obvious safe thing when there is clear downward trend in performance , to simply stay clear until the trend is clearly in the right direction. I understand some companies will always have swings and roundabouts due to external factors (eg halfords) but with fashion and the like is it not much simpler to wait till the company starts delivering real positive performance?. I understand long term holders who are happy to tough it out will not necessarily sell out but seems to me its too hard to call then bottom here if one is sat on the sidelines looking for "reasonable" entry point. Note its easy to say this sat on the sidlines whilst watching not having got suckered in - the trying to time the bottom thing and being clever can be highly tempting - i dont really blame anyone who got suckered in here - i have been known to try and time the bottom myself when i think companies are decent.
Totally agree, why catch falling knives? Tops are spikey and bottoms are usually rounded so there’s usually plenty of time to accumulate later. I much prefer to pay a little more (although probably less in this case!) later on when evidence of a turnaround is manifesting. Buying too early while stocks are tanking is something I can’t personally make a successful strategy of because I can’t handle watching holdings decline by 50% plus hoping for an eventual recovery.
Begbies Traynor (LON:BEG) - our Investor Presentation webinar with management starts in 15 minutes for any interested parties: https://www.equitydevelopment....
On Cavendish Financial (LON:CAV), Graham you said:
"Now if it turns out that FY March 2025 is another poor year and if the company fails to adjust its bonus payments sufficiently to avoid posting a loss, I’d certainly have to rethink my positive stance here."
In the outlook statement, it says:
"...we look forward to returning to a profitable year as the merger synergies are fully realised and with that the compensation ratio returning to normal levels."
So should be alright. I'm going to keep holding and trying to buy more.
Cheers
Chris
Yea, I called that one wrong, sucked into the blurb....
Missed this bit entirely... Poor show letting it go into a loss to pay out bonuses...
"The reported loss for the year reflects the decision we made to pay bonuses to reward and retain staff following a strong post-merger performance."
still holding though.
Cavendish Financial (LON:CAV)
Well thought out update from Graham
The problem for Cavendish Financial (LON:CAV) and other financial services is that bonuses are part of comp. Whilst they are technically variable they aren’t really. Pay someone a zero bonus is managing them out - anyone getting that will leave. So if you want to protect your business you have to pay semi competitively.
So bonuses should Not be viewed as variable at all. They should be viewed as having some variability. Ie in a bad year you can reduce the pool 20% and in a good year you’ll increase it a bit but don’t be fooled by the rhetoric. To pay nothing is to effectively kill your business.
It's a wonder the CEO ofBurberry (LON:BRBY) hadn't been sacked long ago, China's relations with the West his, and the company's, downfall.
Not just China - revenues are down by huge percentages across the board except in Japan.
The fundamental problem with Burberry (LON:BRBY) is it is a mediocre quality brand. A sizeable percentage of total sales - and I cannot find the exact figure right now - is sold through discount outlets at up to 70% off. You do not see LVMH Moet Hennessy Louis Vuitton SE (EPA:MC) or Hermes International SCA (EPA:RMS) having to do that, although Kering SA (EPA:KER) is also struggling.
The Marketing Chief, Rod Manley has departed after 6 years of non-performance, and I think there will more blood on the carpet yet. Burberry have started formal consultations with staff which must mean several hundred are in danger of being laid off. I would argue the problem is not the cost structure but a weak brand which has failed to find much traction in a weaker Chinese market. It looks increasingly likely Burberry will exit the FOOTSIE 100 leading to further SP declines as the ETFs rebalance. It would not surprise me in the least if Burberry is now in play and it will be interesting to see if the irrepressible Mike Ashley enters the arena.
Still, I am just a semi-retired dilettante farmer who sells potatoes and grain ... so take my post accordingly.
Wouldn't disagree with your comments and would add think the mistake Burberry made was moving upmarket into the same space as LVMH ....Louis Vuitton ...Hermes when as you say the brand is of 'mediocre quality' when, personally speaking, they should have stayed in the Armani...Hugo Boss space. Nearly fell off my chair when I had a quick look at their website and the prices they were charging . No wonder they've been left with excess stock !
Yes it also sounds from BRBY's update that they just got the fashion designs wrong, which haven't appealed to customers. Sounds like it's going back to being a one-trick pony of its check-patterned raincoats, etc.
Anyone fancy some budgie-smugglers, which The Times tells me are this season's must-haves? A mere snip at £320 -
Wow £320 ... quite incredible.
Rather go commando and save myself the money.
Too many ticks up here to go commando, but I admire your resilience.
I need albatross smugglers
Speaking for myself life is too short to spend any time on Burberry (LON:BRBY) Silver Moon,. There has to be better than this out there and so there is. Van Elle Holdings (LON:VANL) up another 7.5% today for instance.
Speaking for myself life is too short, which is something all too real for myself Peter T, sometimes I move too fast and at other times too slow in attending to my portfolio. Take your Van Elle Holdings (LON:VANL) , I held it against the odds for 4 years then sold as soon as my holding came into profit last year and as for Burberry (LON:BRBY) I am left holding the baby :-(
Good review of weatherspoon's menu in last week's podcast :)
Lol, I agree, my wife walked in on me at exactly that point and queried what the hell was I listening to, it was funny….
ME International (LON:MEGP)
Positive results, confident outlook, driven by the growth of its Wash Me division. Much to like in my view.
ME International (LON:MEGP)
I agree much to like and much to process.
I particularly like the margins:
Ebitda margin of photo booths of 34%
Evitda margin of laundry machines 48%
Eventually capex should tail off in 2026 and that should reflect in even greater cash flows.
Coffee Can stock for me, buy, hold and revisit in a few years….
ME International (LON:MEGP) Will be down today given the run up last week
ME International (LON:MEGP) I would like to see these washing machines rolled out all over the world. For those who love or need to travel, the biggest bugbear is laundry. There are very few laundrettes, and you have to catch them within sociable hours which is not always convenient. I paid precisely £70 for just a handful of T-shirts and boxers to be washed the other week in a hotel. So cost also comes into it.
BRBY Early morning is 783p down nearly 12%. Ouch. As Paul notes, sales are down ~20% in its quarter just reported.
It's a total falling knife at the moment. I've said this a few times before, but I'll reiterate. Analysts are continually downgrading their forecasts, and Stockopedia gives it a Momentum score of 4. anything at or below 10 is a huge warning.
Brands don't necessarily last forever, although we're not at that stage yet. Brands can struggle, though, and it won't be the first time that BRBY has faced such struggle. So you shouldn't necessarily expect the recovery to be quick. Working capital is down and net debt is up, which isn't so great. If the debt increases and profits decrease significantly from this point, they're heading for trouble.
I watch developments with interest, but I'm not tempted at this stage. Just my 2c.
BRBY. For balance, , I've been looking at the BBs and a number of bullish points were mentioned:
New CEO and strategy. The dividend cut should help finances. possible FX headwinds. So, maybe.
I did look at Burberry online. Everything is hellishly expensive. For example, I bought some sandals from Next at less than 10% of the price that I saw sandals sold for on Burberry. How much of a premium can they realistically charge? They seem to be in the price category of tailored goods.
I did see a documentary where they talked about luxury brands. Remember, a lot of this stuff is mass-produced, so companies are walking a fine line between "aspirational" and "true" luxury for rich people. The quality is likely good, but there's considerable psychology to it.
I suspect that the Chinese economy is a little more buoyant than people are generally making out, although I do think there are many many problems that China faces for which there are no easy solutions.The comments on Burberry (LON:BRBY) prompted me to look at their web site. They want £590 for a nice pair of sneakers. How many folks other than the mentally deranged will pay that? Not many I suspect.
Burberry (LON:BRBY) - I have a nice Burberry jacket that I purchased a few years ago for about £1k so maybe I was a bit deranged.... but some people like buying the best clothes. I've stopped this as I worked out that I had a lifetime supply of luxury brands and maybe not enough opportunity to wear them all! The jacket is nice enough, but nothing special....not even slightly waterproof...I wouldn't buy another as it's a lot of money for an average coat!
Anyway, I've always been sceptical on Nick Train's comments about Burberry. It is undoubtedly an iconic brand, but maybe it would fit better as part of the LVMH portfolio? Fashion brands have a tendency to out-perform for many years and then do the opposite.
The issue now with Burberry is that the press headlines are counter-productive. People buy Burberry because of its brand positioning and quality. Once the world knows its not as popular as it once was, customers will go elsewhere. One to avoid in my view. Another blow-up for Nick Train unfortunately.
Burberry is going to have the same destination of Ted Baker which dropped from £20 to less than £1.
The brand name is worth something and some big names topvest mentioned can easily afford it.
I am tempted at catching this falling knife!
Nice end of year results from Cavendish Financial (LON:CAV) reintroducing dividend with probably more coming this year.
Thanks to Graham for great analysis on this one, very glad I did a bit of my own research and built a position around 9p after being highlighted on the daily SCVR
What does nice end of year results actually mean?
What did your own research unravel?
All the best
It means in a tough market they are still re introducing dividends, one off merger costs are out the way so they should be profitable now .
I'm not a financial analyst, just a casual investor.
I take it you're not a fan of? Cavendish Financial (LON:CAV)
I have a sizeable holding in Cavendish Financial (LON:CAV) . My main worry, after reading and re-reading the April full-year trading update, had always been the lack of PBT figures. The suspicion was they would be negative, as has turned out to be the case. Ironically, I had decided over the weekend to sell a chunk of Cavendish Financial (LON:CAV) and buy Capita (LON:CPI). A bit late with my decision as is often the case. Adjusted PBT is -£1.7 mill, which is not bad given their net cash, although we do not know if cash has reduced since 31 March. The market also can’t make its mind up yet…
Cavendish Financial (LON:CAV)
I, too, own some Cavendish, but slightly less than I owned at 8 am.
It would have been more helpful if pro forma numbers were issued so that comparisons could be made without the use of a calculator and a few vague guesses. Negative goodwill from the Cenkos merger causes big distortions, too, as does the cash on Cenkos’s balance sheet at merger masquerading as cashflow in the headline numbers. Although presumably correct from the perspective of accounting rules, I feel that these numbers have been polished to shine as brightly as possible rather than state the true position of the business.
I own because the time will come when this business will boom, but I feel uncomfortable with what I feel is an attempt to obscure rather than illuminate. The LTIP (etc.) doesn’t help with this feeling of disquiet upon reading the results.
Graham, I would appreciate your perception in this matter.
I don't own Cavendish Financial (LON:CAV) although it is on my list. Had a brief skim (with a slightly sore head) and I can see:
Post merger performance is indicated, but as above, be nice to see some real comparables.
Cost synergies have been exceuted, although I think we were already aware of this.
Cash in bank and divis to be resumed.
BUT - It's making a loss! £3.8m spent on merger etc..
Despite the merger, adminsitrative costs are high, together with share based payments.
There's talk of an improved market conditions and more synergies to come, but on balance I don't think I'll be rushing in just yet. Especially when there are far bigger divs on offer from say Liontrust Asset Management (LON:LIO)
Edit - I was on auto pilot, I didn't mean to put in Liontrust Asset Management (LON:LIO) as a direct comparitor, still a bit hazy! I have been looking at Tavistock Investments (LON:TAVI) though, no view yet.
Hi Laurie
Excellent post on Cavendish Financial (LON:CAV)
I have sold as well.
All the best
I'm quite bullish on Cavendish Financial (LON:CAV) - probably more so than the majority of other Stockopedia users commenting today.
I started buying a few weeks ago, but liquidity meant I wasn't able to get my full position I wanted. Today, I've managed to fill my boots at 11.5 to 12p.
Why have I bought?
It is because there is huge operational gearing. The % going to employee renumeration is 73% in FY24. But if you break it out, it is only 68% in H2.
And management say that FY25, will "trend back to normalised levels".
What is a normalised comp ratio? Going back the last few years, in both Finncap and Cenkos, it is 60%.
My calculations show, with some revenue growth to come in FY25, as well as employee compensation normalising, that 3p EPS is possible.
On a 12p share price and £21m in cash, and solid NTAV, that's a bargain in my eyes. And you have thrown in for free, the possibility of an IPO market revival later this year.
Now that I've built my position, I'm in the midst of writing up a more detailed article on Cavendish - will be published in the next few days.
(I hold in the Boon Fund)
Note: the shares are terribly illiquid. Hard to buy anything more than 20k to 40k shares at a time within 2% of the mid-point.
Very helpful post Boon - I've set out what their staff comp was in previous years in a separate post below too. Looking forward to your detailed article. I agree on the bull case; this is the only share in my portfolio where I think there is a short-term (12-24m) chance the shares could multibag.
Multi-bag in 6-12 months would be amazing for Cavendish Financial (LON:CAV) !
Personally, my target valuation for within 12 months is around 25-30p, so just over a double-bag potential. However, I think if the IPO market comes back strongly and the UK markets are seen positively again, it really could multi-bag I think...
The great thing is this option (IPO + market positivity) is essentially given as a free option at the current SP. Even if the markets stay in the doldrums, and revenue growth is meagre (single 5-10% yearly), I can still see close to 3p EPS in 12 months time.
(I hold in the Boon Fund)
ME International (LON:MEGP)
Interim 6 month results out today
ME International (LON:MEGP)
I also liked the sound of this in CEO Serge Crasnianski's comments;
"Additionally, the Group's R&D team has devised new production techniques to reduce the cost of the next-generation photobooths by 28% (effective immediately) and the Revolution laundry machine by 13% (effective FY 2025). A new generation solar panel, which delivers twice the power generation of the current model, is also in development and will be utilised by the Group's Revolution machines
My morning smallcap tweet: Bargain/Runt
Genedrive (LON:GDR) Destiny Pharma (LON:DEST) EnSilica (LON:ENSI) Cohort (LON:CHRT) Robert Walters (LON:RWA) Silver Bullet Data Services (LON:SBDS) Mediazest (LON:MDZ) Harland & Wolff group (LON:HARL) Spectra Systems (LON:SPSY), Bango (LON:BGO), Aptitude Software (LON:APTD), Concurrent Technologies (LON:CNC)
◄Genedrive (GDR)► FDA assigns Breakthrough Device Designation for the Genedrive MT-RNR1 ID Kit. [SP=2.85 Cap=15m]
◄Destiny Pharma (DEST)► proposes de-listing to give a realistic chance of securing the capital required to progress XF-73 Nasal through clinical trials having failed to raise funds for far. [SP=8.64 Cap=8m]
◄EnSilica (ENSI)► wins $7m order for an edge AI processing chip. Expects $5m in this FY. Has alos won over $2m of services and NRE bookings. [SP=46.81 Cap=46m]
◄Cohort (CHRT)► wins €33m three year contract with NATO Communications and Information Agency. [SP=810 Cap=337m]
◄Robert Walters (RWA)► warns that any material improvement in confidence levels will be gradual, and likely not occur before 2025. Q2 net fee income down 12% at const currency. [SP=382 Cap=276m]
◄Silver Bullet Data Services (SBDS)► has won 20 contracts in H1 worth £1.2m. These "contribute to committed revenues in FY 2024 representing nearly 70% of the full-year revenue target." [SP=74.45 Cap=13m]
◄MediaZest (MDZ)► has won £500k orders in last 2 months. [SP=0.08 Cap=1m]
◄Harland & Wolff (HARL)► the late FY audit is now undergoing final audit partner reviews. [SP=8.38 Cap=14m]
◄Spectra Systems (SPSY)► wins 5 year lottery gaming software contract renewal worth $636k. [SP=239 Cap=111m]. I hold.
In line: BGO, APTD, CNC
I bought GDR last week on the unexplained huge trading volume. Having looked into it they managed to pull off the £6m raise (including a big bit from REX) and now have a market cap of £15m with £6m of cash, and two very promising tests each with large (£100m+) market opportunities and no real competition. The stroke test has been recommended by NICE (final approval letter pending) and today they’ve announced the hearing loss test is joining the FDA fasttrack evaluaiton program. This is encouraging because it shows they have managed to successfully work with the FDA, which could be helpful for the stroke device. The platform itself I don’t understand well, but if they’ve developed two genomic tests to address gaps where no alternative exists, the technology may have substantial value. I think this may well be a genuine multimeter in the making. It’s certainly rare to see a biotech with advanced technology so close to commercialisation, addressing unmet needs, at a such a modest market cap. I will be holding onto mine to see what happens next.
Robert Walters (RWA)► warns that any material improvement in confidence levels will be gradual, and likely not occur before 2025
I would observe that recruiters, operating on the leading edge of economic sentiment, have no more a clue when recovery will occur than the average economist, ie their management have no inherent predictive skills at all, but are a reliable bellweather when the turnaround actually occurs.
Suggests to me the leading edge is indicating that unemployment is going to keep rising and wage growth is going to keep falling , so expect some rate cuts
ECO Animal Health (LON:EAH) - Strong FY24 results: 11% underlying growth (new note available here: https://www.equitydevelopment....)
For the year ended 31st March 2024, ECO Animal Health Group reported revenue +5%YoY at £89.4m, which on a currency-adjusted basis was +11%YoY, and (adj.) EBITDA of £8.0m, +11.2%YoY which was ahead of market consensus on an improvement in margin from 8.5% to 9.0%. The impact of currency volatility was evident in gross profitability at 42.1% compared to 45.0% a year earlier; H2 recovered to 43.1%. (Adj.) EBIT was 14%YoY lower at £4.6m, a 5.1% margin compared to 6.3% in FY23.
Having rallied 30%YoY, EAH shares are trading 7% off its recent year high. We have derived a Fair Value per share range of 137p-146p based on the initial, medium-term, valuation of the pipeline of products under development.
I had a chance to read through Ed Croft's latest PDF on "Investing with the StockRanks." I have also read Roland Head's recent article on Quality Investing.
It got me to wondering if I could come up with my own simple rules of building a portfolio of quality shares.
I decided that there should be a combination of quality, safety, growth, and value. Here's a list I came up with:
* Quality: Look for a Q score of at least 80. That's simple enough.
* Safety: Look for Interest Coverage of at least 7. 10 would be better, and net cash even better still.
* Growth: Look for OCFPS (operating cashflow per share) growing at least 7% annually. In fact, take the lower figure of FCFPS (Free cashflow per share). You still want at least 7% CAGR.
* Value: If you want to keep it simple, just apply a maximum Fwd PE of 19. If you want to get fancier, use a kind of "Terry Smith bond-like rate". To do this, take the rate of inflation and add 1%. This is the minimum FCFY (Free cashflow yield) you'd be prepared to pay. Inflation is 2.5%. So I want a yield of 3.5%. Stockopedia doesn't give you a FCFY, it gives you a P/FCF (Price to free cashflow). It is easy to convert, though. P/FCF = 100/FCFY. So based on a required yield of 3.5%, I'd want to pay a maximum P/FCF of 100/3.5 = 28.
You might want to add in a few sanity checks to confirm that you're not being misled by the numbers. The company should have a fairly good ROCE, say > 12%. It shouldn't be a heavily cyclical industry, which will distort the numbers. It shouldn't be issuing shares like crazy (Stockopedia give you an average share count CAGR rate). Probably stick to less than 3. Net debt should be less than 5 X Net Profit. Beware if Capex per share is rising substantially less than operating cashflow. It could a sign of them underinvesting.
I'm just going to pick a few shares at random as examples for illustration purposes.
MACF. I know that this is one of Ed's favourites, so I thought I'd mention it. It's been growing operational cashflows by 22% pa. Imagine that! It has interest cover of nearly 10, and ROCE has been averaging 14%. Its Q score is 67, which doesn't meet my quality criterion as I've described it, but I'd still say it's a good quality share.
BNZL. A large-cap, so perhaps not everyone's cup of tea. It has a Q-score of 87, ROCE 14%, and its cashflows have been growing by by 13% pa. It has an IC (Interest Coverage) of 8. It trades on a fwd PE of 16.
BA. Another large cap. Q=89, its operating cashflows have been compounding at 26% pa. IC is nearly 10. Fwd PE is 17.6.
GAMA. This is a company that I practically never hear mentioned. It has a Q score of 98, ROCE 23%. Cashflows have been growing 23% pa. It has net cash. It has a fwd PE of 17. I bought this share earlier this year, and reckon this could turn into a live one.
There'll be tons more out there waiting for you to pick over. Now let's look at some of the nastier stuff.
VOD Someone recommended this to me as a good long-term hold. I have known for a long time of its appalling ROCE and debt levels. Its 5-year share price performance has been terrible, going from 128p to 70p. Yikes. It has a Q score of 56, and operating cashflows have been growing by about 5% pa. Its IC is low, though, at less than 2. I would put it in a long-term portfolio. Analysts do anticipate significantly improved earnings over the next couple of years (although worryingly they've been revising them downwards), and the shares are pretty cheap. So, meh, maybe it will be an OK value pick. But not a long-term quality pick, which is what I'm focussing on.
WPP is another large-cap that has been struggling. Cashflows have been declining, which isn't a good sign. The Q score is 54. Its ROCE is 4%, which is meagre. As you might expect, its share price performance over 5 years has been lacking, going from 938p to 734p. Like VOD, analysts are expecting improved earning over the next couple of years, but their forecasts keep declining.
BRBY I thought I'd mention this as this is a well-known Nick Train favourite. Its Q-score is 77, so a little under my threshold. Its free cashflow has only been increasing by about 2% pa, which explains why its shares might have been struggling. Interest coverage is 13, which is fine, although I do notice that it has really upped its net debt from £460m to £1125m. They'll need to be a little careful about that. Its momentum score of 4 puts me off rather. But hey, Nick Train, so what would I know? Oh, and analysts have been constantly downgrading forecasts.
PS I see BRBY released its trading statement today. It looks a bit of a stinker.
Mark, I’m sorry to introduce a negative tone, but I think your screen is too leaky on ROCE and too tight on valuation. You also haven’t given margins the prominence they deserve. Consequently, you have a list of mostly cyclical and commoditised businesses. They are not necessarily bad companies, I own WPP for a short term cyclical recovery, bought below today’s levels. I also own Burberry for the eventual recovery and take over potential, but this time I was in too early. MACF is one I like and hope to own for the long-term. But my enthusiasm is based on management’s competence rather than any outstanding characteristics of the intrinsic business. A greater focus on ROCE and high margins with a tolerance for paying up for the highest quality would deliver a superior set of businesses that you could be far more confident of owning for a very long time. Here are a few examples, all of which I own, and many of them for more than half a decade. Needless to say, none were cheap when I bought them, yet every one of them has delivered great returns and a good night’s sleep:
Alpha International (LON:ALPH)
4imprint (LON:FOUR)
Ashtead (LON:AHT)
AstraZeneca (LON:AZN)
Auto Trader (LON:AUTO)
Cerillion (LON:CER)
Diploma (LON:DPLM)
Experian (LON:EXPN)
Games Workshop (LON:GAW)
Halma (LON:HLMA)
Howden Joinery (LON:HWDN)
Judges Scientific (LON:JDG)
London Stock Exchange (LON:LSEG)
Relx (LON:REL)
Rightmove (LON:RMV)
Sage (LON:SGE)
Volution (LON:FAN)
Wilmington (LON:WIL)
And if you’re looking for cheap with high ROCE, then surely ME International (LON:MEGP) , whose results today look much better when you adjust for currency.
Thanks. I'm always interested in hearing about people's Quality/GARP/QARP ideas.
Obviously investment strategy is a huge topic. For me the the two most important points are:
1. Everyone is different, ensure your strategy matches your personality.
2. Time horizon and holding period is probably the biggest difference between people.
Value needs a lot of time to manifest. Quality usually less time. And momentum is fairly short term. I am impatient and don't want to hold for more than 6 months, so i tend to look for momentum type stocks and special situations. But as per 1. above everyone is different. Comments welcome, tell me if i am wrong.
Hi Epitychia. I agree with you that the typical holding period is an important part of the strategy. My holdings are mostly Growth and or Quality at a reasonable price. But they must have good Momentum. My typical holding period would be about 6m and I sell everything everything if the general market conditions are not supportive enough. At the moment I am quite highly invested.