Small Cap Value Report (Mon 15 Nov 2021) - CARD, BILN, NGHT, TLY

Good morning, it's Paul & Jack here with the SCVR for Monday.
Agenda -
Paul's Section:
Card Factory (LON:CARD) - a meaningful Director buy (of £107k) reinforces my view that things seem to be improving for this greetings card retailer, following a sound recent trading update. Although bank debt remains a concern, due to the risk of an equity raise being required.
Billington Holdings (LON:BILN) - profit warning for FY 12/2021, due to contract delays, and supply chain issues. WH Ireland halves profit forecast for 2021. On the upside, outlook for 2022 is good, and balance sheet is strong. Overall though, I see little attraction to this share.
Nightcap (LON:NGHT) - awful results for FY 06/2021, mainly due to massive £3.8m share option charge (how can that be justified at this early stage?), and IPO costs. Balance sheet looks quite weak - the big cash pile seems to be offset by bank borrowings + stretched creditors. Overall, I think this looks significantly over-valued, having a premium for newness and roll-out potential.
Totally (LON:TLY) - low margin healthcare outsourcing company, has produced decent interim results. This share looks quite interesting, with over £5m annualised EBITDA, a number which survives my close inspection! The cash on the balance sheet has come from favourable payment terms with the NHS, so shouldn't be seen as surplus cash. Overall, I quite like this share, looks an interesting business that's now performing well.
Jack's Section:
to follow
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section
Card Factory (LON:CARD)
54p (pre market open) - £185m mkt cap
Nathan (Tripp) Lane, a Non-Executive Director of the Company, purchased, in aggregate, 200,000 ordinary shares of 1 pence each in the capital of the Company ("Ordinary Shares") at an average price of 53.5 pence per share.
Investors have to be so careful interpreting Director buys, as they’re often cynically used for PR purposes, in an attempt to prop up a falling share price.
However, I’ve found that Director buys of over £100k in value are often worth taking note of in small caps, because that’s a meaningful amount of money, showing that the Director concerned is not mucking about, and clearly sees the outlook as good. The main risk is that they’re delusional, which does happen sometimes. We also have to take into account the personal financial circumstances of the Director, often unknown.
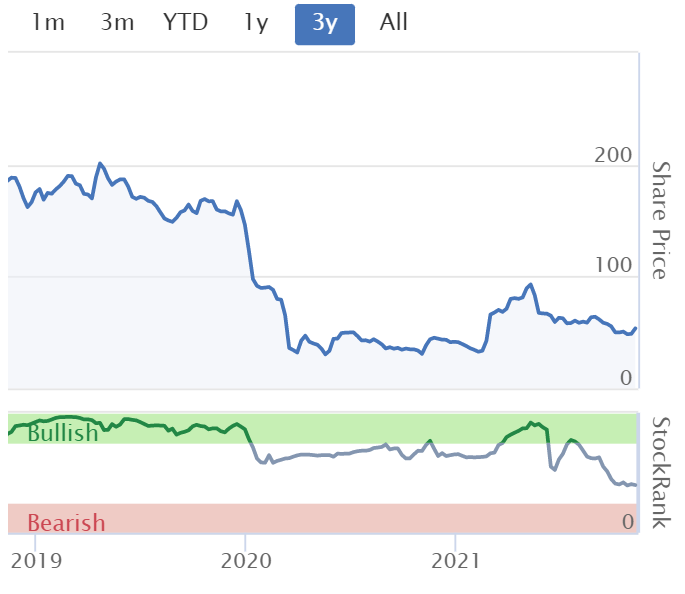
My opinion - CARD is particularly interesting, because it’s been in a precarious financial position since the pandemic began, with far too much bank debt, and strengthening internet-only competitors such as Moonpig (LON:MOON) .
However, CARD’s most recent trading update was good - with reduced footfall almost offset by increased average basket value. Together with cost-cutting, this should mean the business is generating decent cashflows again.
It’s got through the worst part of the pandemic without being forced by the bank lenders to dilute shareholders. An improving situation now, should mean that if/when the equity raise is done, it’s likely to be at a higher price, and have more institutional support, because the company will be able to demonstrate stronger trading. The golden scenario would be if CARD is able to persuade the banks to continue supporting it without having to do an equity raise.
A NED spending £107k buying shares last week, at 53.5p seems to me a further indicator that things should be on the mend.
It’s still quite high risk, due to the weak, overly indebted balance sheet, but all the signs seem to be pointing towards the fundamentals improving. A Director spending £107k buying shares is another reason to start viewing this share a bit more positively, if you’re prepared to take on the risk of its weak balance sheet & high debt.
Management has probably been focused on fire fighting over the past 2 years, as CARD was struggling even before the pandemic hit.
.
Billington Holdings (LON:BILN)
260p (pre market open) - mkt cap £34m
Full Year Trading Update (profit warning)
Billington Holdings Plc (AIM: BILN), one of the UK's leading structural steel and construction safety solutions specialists, provides the following trading update for the year ending 31 December 2021.
Shareholders here should brace for a nasty day.
What’s gone wrong? - delays to key projects means that delivery (and hence booked profits) of product will slip from 2021 into 2022.
The outlook for 2022 sounds encouraging, which may limit the damage to the share price, possibly? It’s such a small, illiquid share, that anything could happen.
Outlook - is better for 2022, which may cushion the impact of the profit warning maybe? -
As a result, market expectations of the anticipated Group profit before tax will not now be met for the year ending 31 December 2021.
However, the delayed profit recognition, in combination with the Group's strong order book and project pipeline provides greater confidence in meeting current market expectations for the year to 31 December 2022.
WH Ireland has usefully issued updated forecasts this morning, many thanks for that.
It reduces FY 12/2021 from 15.0p to 7.6p, thus making a share price of 260p very difficult to justify.
FY 12/2022 forecast is left unchanged at 20.3p, which doesn’t make a lot of sense to me, given that 2022 should benefit from the delayed contract deliveries, so should surely be raised?
The hope must be that the 2022 forecast can be beaten?
Is the company financially distressed? - absolutely not. I’ve had a look at the last reported balance sheet, and it’s very secure, so no issues about solvency here at all.
Graphical history - this is interesting, see below. Pre-pandemic, BILN showed a lovely up-trend in profits & EPS, but that ended abruptly in 2019. If the business can recover to pre-pandemic trading, maybe in 2022, then the shares might be of interest. It also pays divis.
However, looking at graph no.4 below, we can see that the market only awared BILN a low PER of between about 8 & 12, which seems sensible for this type of capital-intensive, lowish margin, cyclical business. Hence it’s difficult to see much upside from the current price.

.
My opinion - I would imagine a share price of 200p or lower would be more appropriate than the current 260p.
It’s not just contract delays either. BILN also mentions material & labour supply constraints, and cost inflation.
On the upside, it sounds confident about the outlook for 2022, has a strong balance sheet, and pays divis.
Overall, I feel this share would need to be crushingly cheap to interest me, which it isn’t.
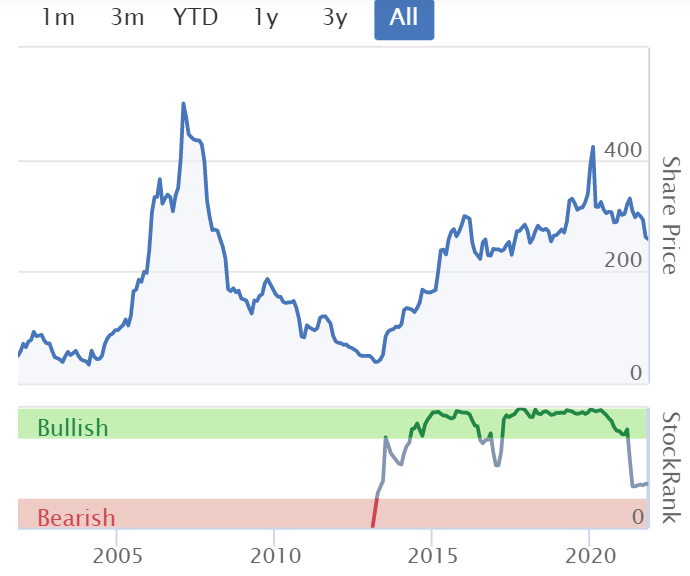
Looking at the long-term chart below, this looks like a company that is subject to considerable cyclical swings, hence is maybe one to buy in recessions, for a recovery, then bail out when it's trading well. Easier said than done!
.
Nightcap (LON:NGHT)
20.5p (down 5%, at 10:03) - mkt cap £38m
The commentary is more interesting than the numbers here, with some interesting points made which have read-across for the whole hospitality sector. In particular, NGHT says that difficulty & hence cost of recruiting staff is its main challenge.
NGHT is an acquisitive bars group, run by Sarah Willingham (CEO) who appeared on TV’s Dragons Den.
The P&L numbers for FY 06/2021 reinforce just how small this company is. Although several factors have exacerbated that - enforced closures due to lockdowns, other trading restrictions during the period (e.g. social distancing limiting capacity).
The group is acquiring small bars chains, hence FY 06/2021 does not represent a full year’s trading for all of them.
Plus there are many more sites planned to be opened in future. Put all that together, and it’s a particularly difficult share to value, where all the value in the share is based on future expectations, rather than historic results. I’m not at all keen on that type of investment, as they often become over-valued on hopes for stellar growth. £38m market cap looks very inflated to me, given where the company has currently got to, in terms of fundamentals, and that we don’t really know how profitable it might be on a normalised basis, because there are no historic numbers to refer back to.
The pipeline for new sites looks very ambitious, for a small business. There must be execution risk with growing this fast. But equally, it makes sense to take advantage of exceptionally good conditions in the property market (lots of good sites available on attractive terms) -
In addition to the three new sites we have a further 23 sites in legal negotiations or under offer across the Group's brands. I am very happy with the rate at which we are progressing our organic growth.
Profit & loss account numbers for FY 06/2021 look dreadful to me -
Revenues only £6.0m
EBITDA £958k
Loss before tax £(5.3)m!
The main culprits for the hefty loss are £3.8m in share-based payments - an astonishingly large figure, for a newly created group. This certainly raises a big question mark over who benefits from this group being set up? Investors generally don’t mind management being rewarded once they’ve created a highly profitable, dividend paying business, but getting £3.8m for what is a start-up, seems highly questionable to me. That would need investigating before buying this share, to make sure you’re not being stitched up by greedy management.
There’s also £714k in IPO & fundraising fees, which given some of the crazy numbers we’re seeing at other companies, doesn’t actually seem too bad!
Balance sheet - this is far weaker than I expected.
In particular, the £13.2m in gross cash is largely offset by £4.7m borrowings, plus an unusually large £8.6m in trade payables. That looks very much as if there could be substantial stretched creditors (e.g. rent arrears, VAT/PAYE arrears, etc). Which begs the question, what would net cash look like once creditors have normalised? Much lower, I suspect.
With lots of expensive fit-outs needed on future new sites, then there could be another equity placing needed at some stage.
NAV is £13.2m, but there’s £9.7m of intangible assets, leaving only £3.5m of NTAV - adequate for a small bars group, but not enough to fund an ambitious roll-out plan, in my view. Although new sites are likely to come with reverse premiums & rent-free periods, which helps reduce the cash outlay.
My opinion - I’ve heard good things about NGHT management from a sector expert, so I’m keeping an eye on this share. It’s in a sweet spot right now, because younger people are much more willing to go into bars as normal, than older people. Wetherspoons said something about that in its recent update - with ales sales down heavily, but cocktails & other drinks that appeal more to younger people up.
Anecdotally, I was out and about last week in N1 London, and was amazed at how busy the pubs are - particularly the ones with younger clientelle, which were absolutely rammed. No social distancing whatsoever was in evidence from what I saw. I'm not casting judgement on that, just reporting what I observed, which backs up recent strong trading from Revolution Bars (LON:RBG) (I hold), and positive current trading from NGHT.
However the numbers today from NGHT (especially the modest balance sheet) reinforce my view that the market cap seems way ahead of reality, and I don’t like paying up-front for what might become a decently profitable business in future.
It seems to me that there’s little to differentiate NGHT’s brands. Bars are bars. They’re trendy when they’re new & exciting. Then after a few years, the interior becomes tatty, the branding stale, and customers move on to the latest new bar nearby. Do I want to pay a big premium for newness? Not in this sector, no.
Revenues are strong at the moment, due to pent-up demand, so bars targeting younger drinkers are doing really well. That won’t last forever, and the danger of yet another lockdown hasn’t completely gone away.
Overall then, NGHT seems an ambitious growth company, but for my money, the market cap looks too far ahead of reality to make it worth considering. That's just one person's personal opinion though, as always here. Other investors might be happy to pay up for apparently good management, and an ambitious expansion strategy at the right time.
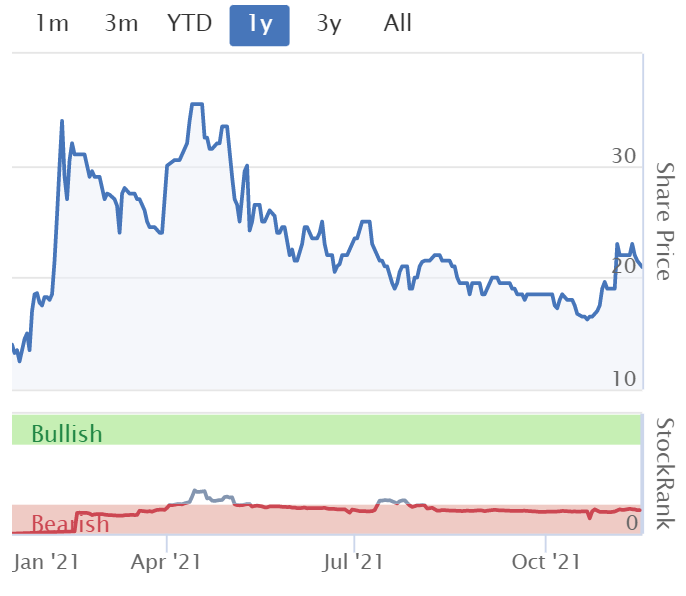
As you can see from the chart below, the initial IPO euphoria has abated somewhat, but it's still far from cheap on fundamentals.
Many thanks to Allenby for publishing forecasts. The valuation doesn't look as high if you believe the company can achieve forecasts. E.g. FY 06/2022 is £30.4m revenues, and £2.9m EBITDA, both forecast to rise strongly in subsequent years. If NGHT does achieve forecast numbers, then in 2 years' time, it would have growth into the current valuation.
.
Totally (LON:TLY)
34.5p (down 1%, at 13:38) - mkt cap £63m
Totally plc (AIM: TLY), a leading provider of a range of healthcare services across the UK and Ireland, is pleased to announce its unaudited interim results for the six months ended 30 September 2021.
Strong Performance and Continued Success
There are some pleasing numbers in here -

Profit before tax of £0.9m is a very small number, on H1 revenue of £61.6m - this is my main concern with Totally - the company is busy, but only eking out a tiny profit margin.
EBITDA of £3.3m is more interesting though. The main difference between £3.3m H1 EBITDA and £0.9m H1 PBT is the £2.3m depreciation & amortisation charge. Very little of this is depreciation of physical fixed assets, because the balance sheet shows only £1.0m of property, plant and equipment - showing that this is a capital-light business model. That’s probably made up mostly of computers, and office furniture, I imagine.
Intangible fixed assets have dropped by £2.1m, to £36.6m. Digging for more information, note 14 from the last annual report shows that almost all the intangible assets are acquisition-related. That’s excellent news, because we can safely ignore these intangibles, and the amortisation of them, because it’s just book entries relating to previous acquisitions - i.e. there’s no ongoing real world cash impact from the amortisation charges.
Totally is not capitalising development spend, I’m pleased to report. There was a small amount (under £1m) but that was fully written off to nil in previous accounting periods. The only remaining intangible asset at March 2021 was a trivial £689k of computer software, that originally cost £2.9m, which is fine.
What all of this shows, is that the £3.3m H1 EBITDA number is a meaningful figure, not an inflated number. The only adjustment I would make is to deduct £553k in H1 lease finance charges, so my adjusted EBITDA for H1 is £2.75m, doubling that to annualise it, and we’re at £5.5m - not too shabby at all, for a £63m market cap that is growing both organically, and from bolt on acquisitions.
Balance sheet - the impressive £18.3m cash pile has been growing from genuine cash generation, but a fair bit of that has also come from favourable working capital movements - see the cashflow statement.
Totally is also a beneficiary of the NHS being prompt payers, I recall management confirming this on a previous webinar. So it’s important to remember that its cash pile isn’t really surplus cash. It’s offset by creditors - so the cash pile occurs by virtue of a favourable working capital cycle - i.e. getting paid before suppliers have to be paid.
For this reason, I’d be interested in finding out what the average daily cash balance is throughout the year, rather than a snapshot on a particular day. That would be a good question to ask on the InvestorMeetCompany webinar at 10am tomorrow.
Current assets (including the cash pile) total £26.9m
Current liabilities total £28.7m.
So there’s actually a deficit on working capital, with the current ratio being an unimpressive 0.94. Does this matter? Not if the NHS keeps paying promptly. But if that were to change, then the cash pile could easily evaporate. Hence it would be unwise for the company to spend the cash on acquisitions for example, which it does mention in the commentary as being in the pipeline.
Overall, NAV is £34.7m, if we deduct intangible assets of £36.6m, then NTAV is negative, at £(1.9)m. That’s not in itself a problem, but I’m flagging this because Enterprise Value (taking the cash pile off the market cap) would give you an unrealistically low number, and could result in the shares being over-valued.
To summarise then, I don’t have any particular balance sheet concerns, I just want to flag that it’s a fairly flimsy balance sheet, which happens to benefit from having the main customer being very generous with prompt payments of Totally’s invoices. That’s very different from having a pile of cash which the company owns outright, which is not the case here, the way I view the numbers.
Outlook - these comments are scattered throughout the commentary, rather than having a separate outlook section.
Yet against a backdrop of continued uncertainty, the Group's performance has been strong, with growth in revenue, earnings and cash. During the period we performed ahead of management expectations, positioning us well for a strong full year despite a more uncertain second half. We are now undertaking advanced planning to prepare for the increased demands of winter alongside rising levels of COVID-19 and the onset of seasonal flu.
My opinion - I’m warming to this share. If the improved performance can be maintained, with possible further growth, then this could be a decent share to own, long-term.
I do worry a bit about the complexity of the contracts, and reliance on various parts of the NHS as the main customer. But that could also be Totally’s strength, in that it seems to be building good relationships with the NHS, and could therefore squeeze out competitors and become the partner of choice?
My main worry in the past was that Totally seemed to be very busy, but not really making any money. Digging into the figures today has reassured me on this issue, with good H1 numbers once the amortisation charge is adjusted out (a valid treatment, in my view).
Overall then, Totally shares look potentially interesting.
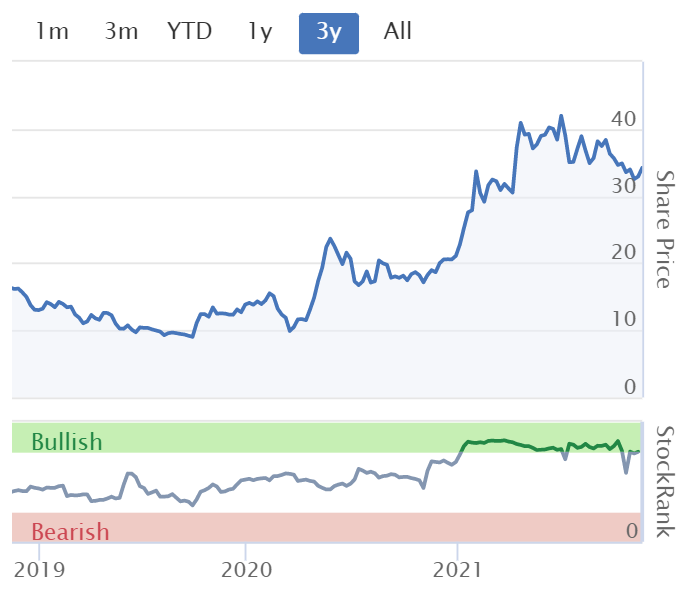
As you can see from the 3-year chart below, the share price has been strong, and the StockRank has also strongly improved..
 .
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

30 comments
Totally (LON:TLY) Interview of CEO with VOX.
Many thanks for the excellent write up on Totally (LON:TLY) (I hold) Paul.
The customer concentration risk is both a strength and a weakness, as you have alluded to. There is good visibility of revenue/earnings through contracts awarded, but Co is very much dependent upon the NHS.
The Board is made up of ex NHS employees and their knowledge of the internal workings of the NHS both from a practical, working point of view, as well as a winning new business and contracts point of view, must be a significant barrier to entry.
Of course, in the current climate the NHS will need all the help it can get, especially in reducing waiting lists, especially from a known, reliable and trusted partner such as Totally. (There has been a recent shift away from competitive tendering with contracts now awarded to known and trusted 'Preferred Partners' of which Totally (LON:TLY) is a well proven one).
Also in this regard, the relatively new area of insourcing i.e the supply and sourcing of skilled staff for out of hours use of NHS facilities, is expected to be a significant growth area for the business.
I hadn't quite figured out the cash pile vs market cap conundrum which you have shone a light on and so an average daily cash balance is certainly worth finding out tomorrow, if possible.
Thanks for the write up on Totally (LON:TLY) Paul. It looks very interesting.
I must find out much more about what they actually do, given the true level of profitability you uncovered.
Plus I love businesses who get paid by customers quicker than they have to pay suppliers. It means their growth is self financing rather than the other way round, as it is for the majority of businesses who will see increases to their working capital as they get busier.
I agree they are at risk of, and dependant upon, one principle business for this payment benefit, but hopefully the NHS being a public body is not going to be changing its policies any time soon.
Hi Paul - just wondering if you can share your view on what has happened at LON:ELTA the share price seems to have come off sharply following demerger - I was expecting it to go the other way as value gets realised?
Having worked through the numbers following Paul's analysis of the Electra Private Equity (LON:ELTA) situation (DYOR as the SCVR emphasises) I also would have expected the demerger to unlock value rather than destroy it! It is difficult to understand how a business valued c. £5.50 a share can suddenly be valued at c. £4.40 a share (based on Paul's spreadsheet model at today's prices) - a 20% fall - with no fundamental change in the underlying businesses and no negative news flow. It would seem that the whole demerger process and the role of the advisors has been, and continues to be, the major problem. It is hard to continue to hold the two businesses when they are being sold off so badly but I guess we have to wait and see and hope that they recover to a more reasonable valuation.
RE: Electra Private Equity (LON:ELTA)
It would seem that the whole demerger process and the role of the advisors has been, and continues to be, the major problem
And maybe, also, there were a lot of private shareholders on board who had unreasonable expectations of how quickly the value could be unlocked and who jumped overboard when they discovered they couldn't stag the stock for the expected profit after demerger?
It'll probably take some time for the shareholder register to sort itself out but if the underlying value thesis is correct then this will sort itself out eventually. Classic voting machine versus weighing machine type stuff.
timarr
I’m not a holder here so apologies for my lack of knowledge of the fundamentals, but might it not be a case of the “buy on the rumour, sell on the news” ie buyers rode the wave on the way up to the float and then cashed in? If so, if the value is truly there then the price will drift back up.
rambutan on advfn made this comment in relation to Hostmore (LON:MORE) to the effect that there's up to 25% of shareholding possibly to be ditched over time ''I think that a lot of the shares need to change hands.
Crown Sigma is a UCITS fund of PE funds, so will have to sell.
Witan IT, another fund of funds, albeit with a bit more flexibility, will also be a seller.
Likewise the M&G stake.
So plenty of work for the brokers to be getting on with. imho''
"It is hard to continue to hold the two businesses when they are being sold off so badly."
Eh?
If everything in the grocery store was on sale at 20% off, you wouldn't turn around and say 'I don't trust this, I'm going to come back when the prices are much higher'. People would think you are insane. So why is it ok when it comes to our money?
B.Ritholz
My read of the Billington Holdings (LON:BILN) profit warning is that not only is the revenue slipping into next year, but the profitability of those slipped revenues will be lower due to the slippage.
Maybe hence why broker forecast of EPS is lower this FY, and unchanged next FY?
I was wondering whether Paul or Jack could have a look at Totally (LON:TLY) totally results today ?
I'm more optimistic on £BILN. The demand side has been transformed by the huge demand for warehouse space for online sales and data centres. 1.5bn sq ft needed globally just to keep pace with predicted online retail penetration. If we really build all the giga factories which we need for EV then the UK will struggle to supply all the fabricated steel required. See Somero Enterprises Inc (LON:SOM) for how this can play out. Margins have been messed up by COVID and soaring steel prices but if they can get back to the 6% or so they made in 17, 18, and 19 then 40p of earnings is a realistic possibility perhaps in 2023. Add that to the EV only being around GBP20mn (assuming those delayed contracts convert to cash in the new year) then you have a very cheap business. TNAV 230p last seen. Great management team who have been flagging this risk of delay all year hence the muted price reaction.
You're certainly right about the balance sheet (pension fund surplus as well) and it being small and illiquid.
Hi Paul
Did you have any joy with the enquires into Hostmore (LON:MORE) & Electra Private Equity (LON:ELTA) (I Hold both)? I am particularly keen to understand the relative net cash/debt positions & where the Sentinel sale proceeds reside.
Best wishes Steve
Cloudcoco (LON:CLCO)
News of a £3M 3yr contract for this company which is what was salvaged from the wreckage of PINN Pinnacle Technology which bought a lot of companies with paper but forgot to lock in the sellers who cashed in and ran. Last reviewed by Paul about 2016 when he said they appeared to be going bust. Many new shares later and still clinging on. I was going to print out the stock report but I ran out of red ink. I worked in IT support from 1970's onwards and one thing that customers need to know is that when there is trouble their support company will be there for them. Why a company would risk a contract with a supplier with such shaky finances I don't know, maybe connected in some way. Being cynical I suspect another fundraising, they often follow publishing of good news to dress up the company for a party. Still a big risk of going private too. Their financial adviser MXCP did that.
Kainos (LON:KNOS) down 10% currently after an excellent report even though profits were only up 3% Hopefully a sign of more sanity is returning to the market
I agree that the price needed to deflate a little. Indeed, I sold half my stake a while back for £20 in anticipation of a correction. However, analyst estimates for Kainos (LON:KNOS) over the next couple of years look seriously conservative. Is turnover really going to stay flat in 2023? Track record and the ever-growing demand for IT services suggest otherwise.
Interesting to see the Cmc Markets (LON:CMCX) strategic review, which may lead to a proposal to split the business into two: leveraged and non-leveraged, to maximise returns to shareholders. I bought these at the recent low point with a long term view. The market has marked the shares up 10% at the time of writing but of course this is still very beaten down v ATHs. Not due to conclude the review until June next year.
Cmc Markets (LON:CMCX) sold off very sharply recently on what seems to have been a quiet couple of months trading activity. Pretty ridiculous as everyone knows revenues are very lumpy from month to month, but on a longer term view the upward trend is pretty clear. Seems extremely cheap even after this morning's rise.
I hope Paul or Jack can comment on the statement from Cmc Markets (LON:CMCX) today.
What seems to come across is that they think the shares are woefully undervalued. Interim results are this Wednesday and these might confirm that.
Apparently IG Market Cap/Revenues is x4. Plus500 x 2.6 and CMC just 1.8.
CMC share price is down about 50% since April peak last year, and look at a bargain price. I’ve added today, but share was up 10% and that’s now down to 7%. That’s another reason for hoping Paul or Jack can comment, in case there are negatives I haven’t spotted!
Bouden54
The problems at Cmc Markets (LON:CMCX) are largely company specific rather than the result of 'a quiet couple of months trading activity'.
This can be seen by comparing how analysts forecasts have evolved this Summer - Ig Group (LON:IGG) have a very different profile to Cmc Markets (LON:CMCX) .
Cmc Markets (LON:CMCX)
Ig Group (LON:IGG)
Since mid 2019, Cmc Markets (LON:CMCX) have been taking on client risk rather than fully hedging it as Ig Group (LON:IGG) do. The result this Summer was that Net Operating Income guidance fell 20% in the 6 weeks to the start of September. Basically £VMCX failed to correctly identify which risks to hedge.
Going forwards therefore, the Quarterly results of Cmc Markets (LON:CMCX) will largely be a function of hedging/not hedging, & hence will be lumpier than those of Ig Group (LON:IGG) .
I don't think we know for sure that the downturn in Cmc Markets (LON:CMCX) earnings was due to hedging related issues as opposed just to quieter trading - unless I missed this I don't recall the trading updates going into that level of detail. In any case, the broader point is that revenues will be uneven from month to month (whatever the reason) and you just need to look through this to a certain extent. Obviously both IG and PLUS reported decent trading recently so that is an anomaly, but these are very different businesses with different clients so I don't think this is necessarily the start of a trend.
I don't think we know for sure that the downturn in Cmc Markets (LON:CMCX) earnings was due to hedging related issues as opposed just to quieter trading
That's true, but the change in hedging policy will inevitably make things lumpier. But really CMC is just another example of a stock that got ahead of itself as investors interpreted excess earnings driven by lockdown as a permanent state of affairs. Despite that the business looks in rude good health.
But really, the underlying point here is that the stake held by Peter Cruddas means there are no agency problems with management. The business is managed for the long term, and decisions are made on that basis. Investors who are looking to make a quick turn need to be aware of this because they may not get the results they expect in the short-term.
timarr
I hold £cmcx sitting on a loss but think it's still undervalued so happy to hold. But this morning's announcement seems short on detail, personally I'd rather Paul or Jack spend time looking at the results later in the week than this.
Any chance of a review of Gfinity (LON:GFIN) full year results today? Revenues seem slightly above expectation but market does not seem to have taken kindly
Excellent results for both Mti Wireless Edge (LON:MWE) and Totally (LON:TLY) today, (I hold x 2 )
Been an holder of Mti Wireless Edge (LON:MWE) for 4 years now and seen a nice 300% return and its in my coffee jar list of holdings. It continues to make steady rather than spectacular progress in all of its three divisions. For some reason (and maybe I am being greedy) I almost expect growth to be higher than 10% of so when I look they are in 5G and water scarcity projects I am always a little disappointed at their results. Cash generation continues to be strong and I suspect we'll see another good increase in dividends next year so maybe I should be happy.
I hold both too, but whilst regarding Mti Wireless Edge (LON:MWE) as coffee can, I was underwhelmed by the £TLY statement, particularly the outlook aspects.
Mti Wireless Edge (LON:MWE) Increase in profitability up 11% seems quite good to me, esp' when "...By far the majority of industry's investment in 5G is still to come and so the opportunity remains significant for us and we continue to be well placed with the antenna division being a key supplier to the major mobile network radio manufacturers."
One of my largest holdings having been in since 26p and 22p. I'm not particularly comfortable about military aspects but on the other hand - "One fifth of the world's population live under conditions of water scarcity and the issue is getting worse. Governments globally are responding and solutions like Mottech's, which typically save 35% of the volume of water previously used, are gaining traction across all of our target markets."
[deleted]